Daily Stock Market Report (Fri 24th Oct 2025) - Was Treatt successful? - TAP, ALU, REC, GROW

Good morning!
I've finally managed to publish my interview with the CFO of PPHE Hotel (LON:PPH) in article format, which I hope you'll find interesting.
Was Treatt successful?
Congratulations to Lord Lee on his successful Treatt (LON:TET) investment over many years, where he has now crystallised the profits.
There is a good question in the comments, asking how Lord Lee's Treatt investment was successful.
It does look like a rubbish investment, to be fair:
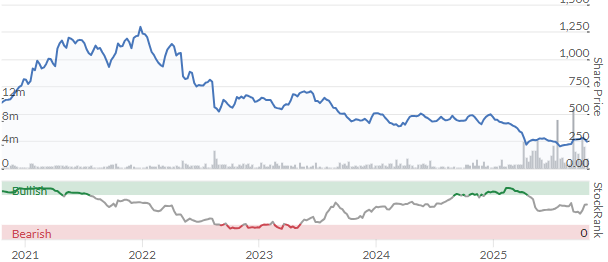
That is, until you zoom out:
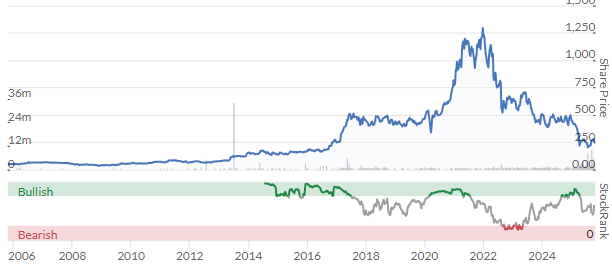
This chart does not even capture Lord Lee's entire timeframe. He said that he first invested in it in 1999, when the share price was £1.50 - and that was before a 5:1 stock split (each old share was "split" into five new shares). On an equivalent basis, the share price in 1999 was only 30p.
The annual dividend alone is now worth 8p, and the takeover offer is 290p.
I accept that 26 years is a long time in investing. I accept that Lord Lee will have paid more than 30p per share for his follow-on investments in Treatt. And I accept that the S&P 500 has also done very well over this timeframe. But there is no universe in which this share has been an unsuccessful investment since 1999.
To me, this is what extremely successful investing can look like: when dividends are a double-digit (even better, a triple-digit) return on your initial investment. When the stock moves in a month (or even in a day) by as much as your initial investment. When you can sell a tiny portion of your stake and get all of your initial investment back.
This might sound fantastical, but I've seen plenty of people do it. Lord Lee did it with Treatt. The Tesla believers, for all their faults, have done it. I'd be shocked if Ian Cassel hadn't done it on multiple occasions. Holding onto shares for very long periods of time is not the only way to invest - but it's not bad! And it's working out pretty well for me, where my own current portfolio is worth about twice what I paid for it.
Spreadsheet accompanying this report: link (last updated to: 7th October).
All finished for the day and for the week. Thanks everyone.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£66.9bn | SR88) | DREAMM-7 showed a 51% reduction in the risk of death and tripled median progression-free survival. | ||
Natwest (LON:NWG) (£48.2bn | SR81) | “We have upgraded our income and returns guidance for 2025… We now expect income excluding notable items to be around £16.3 billion for 2025 and to achieve a Return on Tangible Equity of greater than 18.0%.” | ||
CVS (LON:CVSG) (£1.02bn | SR65) | Intends to move from AIM to Main Market. Rationale: access deeper pools of capital, index inclusion, etc. £20m share buyback. | ||
Treatt (LON:TET) (£145m | SR59) | Lord Lee said he had an intention to vote for the takeover, but has now sold all of his Treatt shares. The number of shares which have been promised to vote for the takeover reduces from 8.1% to 6.9%. | PINK | |
Alumasc (LON:ALU) (£123m | SR78) | Conditions have become more challenging in Q1, exacerbated by uncertainty re: Autumn Budget. The board believes it prudent to adopt a cautious approach for H1; still expects a second-half weighting. | BLACK (AMBER) (Graham) Downgrading our stance to neutral, to be consistent with our normal procedure after a profit warning and also consistent with Alumasc’s declining StockRank. The earnings multiple on next year’s EPS forecast (FY June 2027) is 9x and I would struggle to argue that it deserves to be rated more highly than that. | |
Record (LON:REC) (£112m | SR81) | Net flows marginally positive, AUM reaches new high. £0.5m performance fees. Fee rates “broadly unchanged”. | AMBER/GREEN I’m a long-term fan of this one, and my instinct is always to be GREEN on it. But I note Roland moderated our stance to AMBER/GREEN in July. And I can’t really argue with that given that net flows are neutral, fee rates are probably nudging lower long-term, and performance fees are fairly modest. | |
Orosur Mining (LON:OMI) (£87m | SR26) | Latest cash balance $17.2m following private placement. Will focus investment in Columbia and Argentina. Exploration-stage, zero revenues. | ||
Rentguarantor Holdings (LON:RGG) (£28m| SR12) | Winner of the 'Best Professional Guarantor' award at the ESTAS Awards 2025. Award judged off customer satisfaction. | ||
Tap Global (LON:TAP) (£19m | SR16) | Institutional Bitcoin Treasury as a Service ("BTaaS") platform has successfully onboarded London BTC Company Limited (LSE: BTC) ("London BTC Company") as a client for its BTaaS platform. | RED (Graham) [no section below] If Bitcoin Treasury companies are rat poison, then this is rat poison-squared. |
Backlog
Molten Ventures (LON:GROW)
Up 15% yesterday, now at 489p (£868m) - Half Year Trading Update - Graham - GREEN
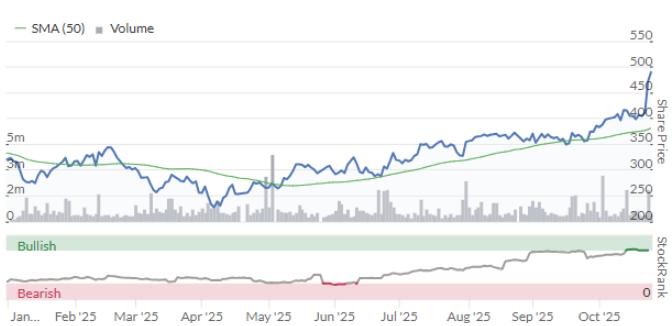
Thank you to Jim for suggesting we cover this one today. The company formerly known as Draper Esprit put out a strong statement yesterday and saw a very nice share price reaction. It has been on an upward trajectory in recent months:
Molten Ventures is a European tech-focused venture capital firm. If so inclined, you can peruse its investment portfolio here - it includes some names you’ll definitely have heard of.
This is what they achieved in H1 (to September):
HY26 demonstrated further growth in both GPV (5.5%) and NAV per share (7.2%), supported by a combination of hands-on portfolio management, improved market comparables, and the ongoing share buyback programme.
(GPV = gross portfolio value.)
NAV is expected at 719p (current share price: 489p, so that’s a 32% discount). That’s up from 671p at the end of the previous financial year (FY March 2025).
Gross portfolio value is £1,425m, benefiting from a £75m uplift. Of course true portfolio value for a business like this is a matter of opinion to some extent, but the valuations of their companies at recent funding rounds can be used to provide reasonable estimates.
The company has an annual target when it comes to realisations: 10% of gross portfolio value. H1 saw 4.5% of the portfolio converting into cash, which is pretty much in line with that target, and there are “further potential realisations during FY26 being actively worked on”.
It looks like Molten Ventures must have been a fairly late investor at Freetrade, as they only made 1.5x their money on that one (it was bought by IG group (LON:IGG), in which I have a long position).
They made 20x their money on Revolut.
Buyback: £38m has been returned through buybacks since July 2024.
Cash: still very substantial at £76m, and they have access to a £60m RCF.
CEO comment: very positive.
“We have had a strong first half of the financial year continuing the recent upward trends in portfolio value and NAV per share, supported by our focus on portfolio management and development, and our balanced capital allocation policy.
“We are also pleased that we have been able to deliver an ongoing strong level of realisations following on from last year, which reflects the maturity, depth and breadth of our portfolio.
“We invest at the forefront of a generational shift in technology, with Molten’s portfolio covering key subsectors such as Fintech, Space, Cyber, AI, Climate, Quantum, Digital Health, and Crypto & Blockchain. The portfolio offers considerable potential to deliver some of the category winners of the future.
Graham’s view
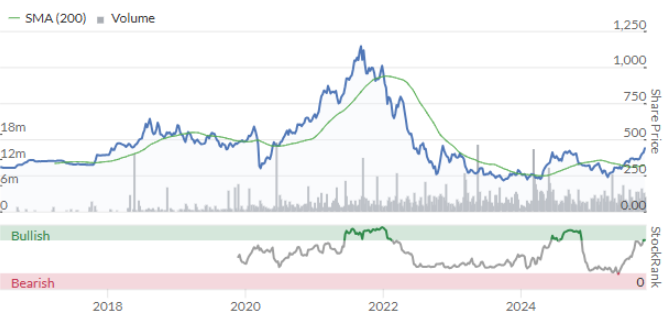
I like listed investment vehicles with good track records, and Draper Esprit has done ok for investors over the years - although given the risk involved in VC investing, you might have expected more capital appreciation than what the long-term chart shows below. They have never paid a dividend.
Checking the presentation at their full-year results, I see that they claim to have delivered a 15% average return since IPO.
I can't verify that figure but I can see that their NAV per share has grown from 343p (March 2017) to its current level of 719p.
I guess they don’t have that much control over their share price: they couldn’t stop it trading at a massive premium to NAV in 2021, and I’m sure they wish it wasn’t trading at a discount now.
Here’s a snapshot of their “Core portfolio”, which includes their largest, most mature holdings. It might be tricky to read but it does show Revolut, Freetrade (now sold) and N26.
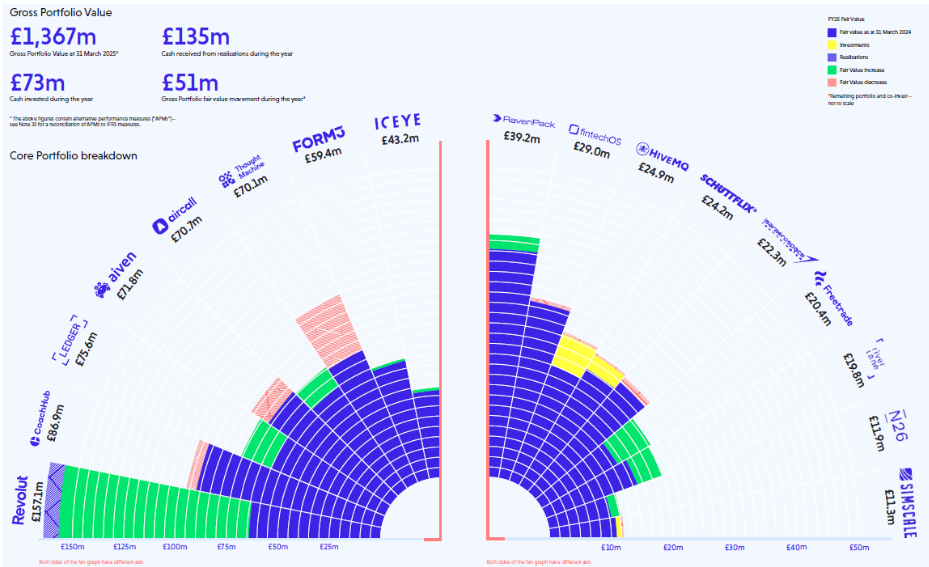
I’m inclined to put a GREEN on this: I like the risk:reward of reputable investment vehicles at a 30%+ discount to NAV. Of course, there is some risk, but I'd wager that a 30%+ discount prices in plenty of bad news, and the company is addressing the discount with buybacks (these buybacks themselves being a further boost to NAV, on top of the company’s own investment returns).
Portfolio diversification could be a little better, but I note that they have been selling off bits of their Revolut position, to open up new positions elsewhere. Sounds sensible.
So I'm GREEN on this - I'd definitely be up for researching this in more detail, and putting it on a "buy" watchlist.
Graham's Section
Alumasc (LON:ALU)
Down 11% to 302p (£123m) - AGM Trading Update - Graham - AMBER
A pretty poor AGM update from this “premium sustainable building products, systems and solutions Group”.
The situation has worsened in the Q1 period (July to September), with the blame going to pre-Budget uncertainty:
As announced at the FY24/25 full year results, conditions in the Group's core UK residential and commercial markets have been volatile, with demand in a number of sub-sectors at subdued levels. Conditions in a number of these markets have become more challenging through the period, exacerbated by short-term uncertainty surrounding the UK Government's upcoming Autumn Budget. While the Housebuilding Products division has continued its positive momentum over the period, a number of delays in larger new build and RMI projects have constrained UK revenues in the Building Envelope and Water Management divisions, despite a healthy order book and a growing pipeline of opportunities.
Alumasc says it is outperforming the wider market, and still sees “encouraging demand in its export markets”, although export revenues this year will not match last year’s success.
Looking ahead to a possible recovery in UK construction activity:
The timing and pace of this recovery remains difficult to predict, and consequently the Board believes it prudent to adopt a cautious approach for the first half of FY25/26, as conditions remain uncertain. The Board still expects a second-half weighting to FY25/26, as announced at the FY24/25 full year results.
Estimates: as is typical, the job of providing fresh forecasts goes to the Nomad (in this case Cavendish), and forecasts are not shown in the RNS.
So let’s switch over to this morning’s Cavendish report to find the new estimates.
FY June 2026: revenue forecast cut by £4m to £113.4m, adj. PBT forecast cut by £0.9m to £14.4m. Adj. EPS forecast cut by 5.9% to 29.1p.
FY June 2027: revenue forecast cut by £1m to £119m, adj. PBT forecast cut by £0.3m to £16.2m. Adj. EPS forecast cut by 1.9% to 32.8p.
Graham’s view
For those who don’t study this company regularly (like me), this is what Alumasc provides: water management solutions, building envelopes and house building products (vents, access panels, etc.).
Roland struck a cautious tone on this one in September (share price at the time: 337p). He kept our AMBER/GREEN positioning, but noted that an H2 weighting for the company was unusual.
There are good reasons to be careful about unplanned or unusual H2 weightings. They often come after a poor first half where management are unwilling to admit defeat yet and allow full-year forecasts to get cut. Clearly, this means there is an elevated risk of a profit warning.
At least today’s profit warning is not all that bad: EPS cuts of less than 6% for the current year, and less than 2% for the next year.
But I’m not going to trust that the 2% cut to next year’s forecast is sufficient - it seems to price in a turnaround that is far from certain. There is no order book figure provided, for example, to give us confidence that FY27 will see higher revenues and profits. We can only hope that construction activity picks up soon, perhaps after the Autumn Budget.
CEO - some important context that the CEO is retiring in March 2026, after 25 years with the company and 23 years as CEO. According to the announcement last month, the search for his replacement is “well progressed”. Whoever they are, it seems that they will walk into a challenging environment.
Conclusion - I don't have any desire to be especially critical of this company. It’s still profitable, it’s still paying a dividend, and it’s not financially levered. When dealing with mature micro-caps, that’s already impressive.
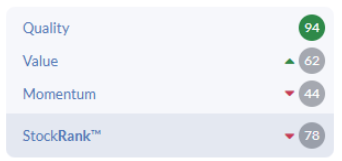
However, I am going to downgrade our stance to neutral, to be consistent with our normal procedure after a profit warning and also consistent with Alumasc’s declining StockRank. The earnings multiple on next year’s EPS forecast (FY June 2027) is 9x and I would struggle to argue that it deserves to be rated more highly than that.
Record (LON:REC)
Up 4% to 58.4p (£116m) - Second Quarter Trading Update - Graham - GREEN
The market likes this. Let’s pick out some bullet points:
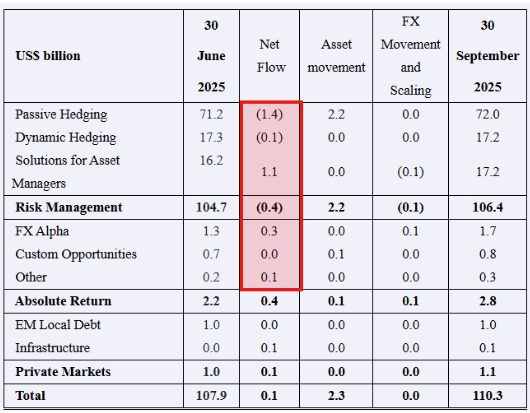
Q2 net inflows of $0.1 billion: a rounding error, but positive!
Positive market movements $2.3 billion, so AUM rises to $110.3 billion.
An important but highly unpredictable number is performance fees: these come in at £0.5m (Q2 last year: zero). A helpful profit boost and it means that performance fees so far this year (£0.9m, after adding in the Q1 result) are meaningful, although it looks like they will struggle to match the £3.2m achieved in FY25. Those in turn were lower than FY24’s performance fees.
Average fee rates are “broadly unchanged” (i.e. slightly lower). I would expect continued gradual downward pressure on fees that can be charged for passive hedging services, but Record also provides value to customers with “Dynamic Hedging”, “Solutions for Asset Managers”, and return-seeking products.
The table shows clients taking a little money out of Passive Hedging, but adding to several other categories:
Infrastructure Equity Fund: this gets off the ground, with €100 million deployed. There were previously said to be €1.1 billion of commitments to this fund, so plenty more to go.
Graham’s view
I’m a long-term fan of this one, and my instinct is always to be GREEN on it. But I note Roland moderated our stance to AMBER/GREEN in July. And I can’t really argue with that given that net flows are neutral, fee rates are probably nudging lower long-term, and performance fees are fairly modest.
It still has wonderful investment characteristics, in my view - including an enormous yield - but I should accept that when growth is limited, I should also limit my enthusiasm a little.
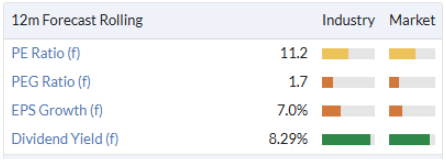
Stockopedia captures this nicely with the PEG ratio: growth is lower than the P/E ratio, making for an expensive PEG.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
On the subject of Bitcoin
Citywire are reporting (along with many others) that JP Morgan are allowing institutional investors to use Bitcoin and Ether holdings as lending collateral from the end of 2025. Link below..
https://www.cityam.com/jp-morg...
For those unfamiliar with US banking, JP Morgan is the largest bank in the US. Another step in the process of Bitcoin being slowly integrated into the financial Establishment of the US.
As stated on various occasions, I dont personally think that Bitcoin is either Ponzi (scam) or a Tulip Bulb (mania) it doesn't seem to fit the profile of either. Intrigued as to why these arguments are still being put forward.
Munger is often quoted on the subject, but he has passed away and does not have the opportunity to change his mind. If he was still here, he might have softened his view on this one.
Graham, did you do a any numbers on JLs Treatt return? My simplistic calculation is that a purchase of 30p returning 250p in 26 years is 8.5% cagr. Add 3% yield pa would give 11.5%
In 2016 John Lee's ISA portfolio was reported as being worth £4.5 million:
https://www.cityam.com/how-to-...
On Treatt (LON:TET) he started buying at 31p in 1999 and he bought on at least 34 different occasions. We don't know what the total cost of his stake was, but the highest he's ever been reported as buying them at is 251p this year.
In 2021 Lee reported that his Treatt (LON:TET) stake was worth 35% of his ISA. That was probably its peak, as the price touched £13.
https://www.telegraph.co.uk/mo...
We also know Lee sold about 20% of his Treatt stake at over £10. He's just sold 730,000 shares at somewhere around £2.50. Even assuming no other sales that's around £2.5 million that he's recovered from Treatt alone. If he was holding over 800,000 shares at its peak that stake would have been worth over £10 million (I'm pretty sure I heard a figure in excess of that mentioned at a Mello event, but I don't think that was on the record). If roughly correct his Treatt dividends would have been around £60,000 a year. What a terrible investment ...
We also know from the above article that he's rebuilt his ISA to a new peak, despite the fall in Treatt and other stocks. So we can assume that his ISA is currently worth well in excess of £10 million. His CAGR over the lifetimes of ISAs and PEPs must be over 10%, probably over 12%.
As others have noted, if he'd sold his Treatt (LON:TET) stake at its peak then he'd be much richer. Of course, none of these people have noted that it's Lee's willingness to hold stocks to the bitter end of his convictions that has driven his excellent returns. For every Treatt there have been multiple takeovers at very high prices - Lok'n'Store, Fenner, Delcam, Tarsus, Air Partner ... and many more.
If that's not a successful approach to investing I don't know what is!timarr
Thanks for the Molten Ventures (LON:GROW) write up Graham.
Jim. GROW is often mentioned on the monthly Investment Trust thread. Maybe have a look from time to time. Along with other PE trusts and the rest.https://www.stockopedia.com/co...
It was a great suggestion, Jim! You're welcome.
Megan Boxall is raising money for the Samaritans.
Not sure if this has already been mentioned here.
Please anyone that can afford to can go to justgiving.com and help this effort.
Close friend of mine has spoken to them in the past-Great cause and money not wasted.
All the best
#ZTF - new Rezorce LinkedIn page started last week and the post below suggests the project is now restarting. Surely this should have warranted an RNS from Zotefoams? Does anyone have more colour?
https://www.linkedin.com/posts...
Zotefoams (LON:ZTF)
I assume from the following that reZorce has been sold to ANTHONY NEIL COURT-JOHNSTON, who ran the project at Zotefoam, and two others who were also involved with the project.
https://rezorce.co.uk/ is the new company website.
https://find-and-update.company-information.service.gov.uk/company/16545474/officers is the info at Companies House for a private limited co incorporated on 27 June 2025.
Why do you say that? I don't think Zotefoams (LON:ZTF) has sold Rezorce.
Zotefoams (LON:ZTF) Check the second link in my post. It is for a company called reZorce run by the chap who ran the project at Zotefoams. Three individuals own the company's share capital; Zotefoams does not. (Check the filings tab on the Companies House website for confirmation.) The website (also linked above) rezorce.co.uk displays the same company number as the private limited co. JoshWood found a LinkedIn post (c. 1 week old) telling the world that reZorce is back and/or available:
We’re delighted to announce that development of multi-award-winning ReZorce Circular Packaging is now continuing as part of a new partnership, which nevertheless retains key members of the original team.
I don't know if reZorce was sold or licensed, or some other arrangement (e.g. royalties) has been put in place. I have emailed Zotefoams asking for clarification, and will share any response, but there may be a reason why this needs to be RNSed. There is a scheduled trading update on the 30th, according to the Stockreport; perhaps we will find out more then.
info@rezorce.co.uk is the new company's email address. Those running the project now may provide information more quickly than Zotefoams.
Thank you for that, Laurie. I suspect that Zotefoams have retained the intellectual property here and this company has been set up to see if they can commercialise it i.e. profits would be shared between the two. A sensible compromise by Zotefoams if they don't want to sink any more capital into it. Lower returns but lower risk too.
Given the tone of the Alumasc (LON:ALU) "AGM Trading Update", I expected far greater reductions in the forecasts than those provided by Cavendish. It seems very likely to me that the H1 results in February, or an unscheduled TS before then, will highlight the adverse trading conditions detailed in today's update and result in a far larger downgrade in FY26 and FY27 expectations.
The mismatch between today's RNS and Cavendish's new numbers seems completely delusional to me... ...but then perhaps RR will provide them with lots of help in the Budget... ...or perhaps not.
You may well be proved right, shanklin, in that a slow start to the year doesn't bode well for a year that was already flagged as 2nd half weighted. However the Cavendish numbers will be where Alumasc (LON:ALU) have steered them to today, so that will still be the Company's own best guess. Perhaps they expect some overseas wins in H2?
The modest rating and solid balance sheet should be enough to support the share price at these levels, especially if the small trim to numbers proves sufficient. I can't quite see the argument for thinking that the new forecasts are "delusional". The trading backdrop hasn't been particularly favourable for some time and yet Alumasc (LON:ALU) has managed to outperform the building industry as a business so far.
Slightly unusual Daily Report today?
I didn't quite understand the bit about about Treatt as its difficult to establish exactly how well Lord Lee has done since only Lord Lee knows when he has bought and sold here.
I get the general premise of long term investment as I am long term investor myself, but not sure that Treatt was a strong enough case or if the start of the DSMR was the correct place to discuss.
Like most of us, I have concerns about Bitcoin Treasury companies but thought the rat poison squared was an unusually strong comment on a discussion board. If someone described me or one of my ventures in such a way, I think that a solicitors letter would be in the post.
I have to say that recently the DSMR has been going from strength to strength in terms of coverage and quality. Today has started a bit off balance in my view.
Nice one Intuitive6191.
A writer calling someone a rat poison……..squared as well!
As for the Treatt (LON:TET) performance-who knows? If it’s what it looks like it was a waist of time in my opinion holding this for so many years.
All the best
Fair enough, intuitive6191! Fridays can be a bit dull - I'm working by myself, and there isn't much news. So I try to inject a little extra colour into the report. It won't be to everyone's tastes, and I probably could do better.
"only Lord Lee knows when he has bought and sold here." - that's true, but he has claimed his initial entry point here and his exit has been outlined in an RNS today, both of which are public.
"Rat poison" is how Charlie Munger referred to Bitcoin. He can't call it that anymore, so I'm doing it for him. I guess it is probably a little offensive - but it's less offensive than what I originally wanted to call it. Have a great weekend!
Obviously you don’t get the opportunity!
All the best
I liked the opinion piece, good to have views on different asset classes. The generally defensive nature of the cryptocurrency holders is somewhat cult like and good to see it challenged.
Cult is not accepting this new financial world we are entering to.
BTC-ETH-STABLECOINS
Mentioning Munger and his negative opinion on the best performance asset of the last 2 decades-that’s cult with blinkers on!
And the reason just because people did not get involved and lost the opportunity of a life time.
That’s cult!
All the best
I'd just note that Bitcoin and Ethereum are very different from stablecoins, albeit all are forms of cryptocurrency.
The former are essentially free floating technocurrencies whose value is driven by supply and demand, while the latter is essentially a digital representation of fiat currency, and are pegged to the latter. Bitcoin is essentially a (very volatile) store of value while Ethereum is primarily functional, allowing the execution of applications against Ether.
Bitcoin is often described as digital gold - it has no functional purpose beyond being money. Ethereum is digital silver - it has practical uses which can drive its value, dependent on demand.
Note also that not all stablecoins are the same - some claim one to one backing with fiat (evidence for this is hard to find and if true means they're simply a transfer mechanism) while others are algorithmically linked. There have been challenges with maintaining pegs under both models.
Many cryptocurrencies are scams, but not all. Any crypto not backed by real assets or by an irrepudiatable blockchain is probably suspect.
Crypto is now a genuine asset, although it's likely to a very volatile one due to how decoupled it is from acual underlying physical assets.
timarr
Thanks timarr
Although all well known to most that follow the path of this kind of investment.
Yes 100% most cryptocurrencies are a scam but BTC and ETH are here to stay.
People (investors) forget that many listed companies are a scam too!
BTC will be linked to US treasuries during this administration.
All the best
Hi yiannos
Although all well known to most that follow the path of this kind of investment.
I hope so, this is cryptocurrency 101, but not fully understood on this thread I think.
The idea of Bitcoin enhanced Treasuries is fascinating, but I do worry when commentators use phrases like "even if Bitcoin only grows at 30% a year" - I mean, everything has a limit. To make this work the US government needs to prefund their Bitcoin purchases - and then hope Bitcoin continues its ascent.
Ultimately the value of Bitcoin and other cryptocurrencies rests on the security of the technology they're built on. That's a risk, and not one that the proponents fully acknowledge while being full on supporters of AI and quantum cryptography, as clear a case of cognitive dissonance as you could find.
But in the meantime, the music plays on and we must dance ...
timarr
regarding Treatt and the offer, it should be noted that Doehler has bought a c. 25% blocking stake. There is therefore no guarantee that the offer at 290p will be voted through.
Could that be why Lord Lee chose to sell? In case the share price falls back towards 200p if the bid is taken off the table...
could be, current price is well below offer price, suggesting that its by no means certain to go through...
I sold a few weeks ago @ 280ish, as i had other use for the cash...but thought even 290p was an opportunistic offer, although I did ok as bought @ 215p only a few weeks earlier!
I did think a takeover was quite likely but thought it would go for 300-325p
I think the 25% stake means that the current offer for Treatt (LON:TET) , which is in the form of a Scheme of Arrangement, is bound to fail. Not 100% sure, but that's my understanding.
I wonder if this means the current bidders would be allowed to come back with a higher price in the form of a conventional takeover offer. Does anyone know the answer to that?
Either way, it's fair to assume that the recent share price more or less discounts the near certainty that the current Scheme of Arrangement will fall.
The current offer is by way of a scheme of arrangement. They reserve the right (if this is voted down) to move to a standard takeover offer. Then it is up to the bidder to specify his conditions, which I imagine would be a minimum of 50% acceptance (as 75% would be impossible without Doehler agreeing).
Off topic from the main report….
I really enjoyed the webinar last night but was too busy to give it my full attention and therefore ask a question or two. Is there any way the video can be added within the discussion tab where further questions can be added? The replay has no comment section (that I can see). Thanks!
Loved the Rat poison-squared remark for Tap Global. What a pity cryptocurrency is gaining any foothold anywhere.
Be careful with your metaphors! BTC holders treat being called 'rats' as a badge of honour. (The Rat vs the Bubbleboy was a key speech by Antonopolous...where being a sewer rat gave them extra resilience) They also like the honey badger metaphor ...because honey badger doesnt care. But everyone should care about BTC ponzi treasuries...Seems amazing anyone would invest (Especially when you can just buy BTC yourself)
Careful what you wish for especially about things you don’t fully understand or have made no effort to do so (BTC).
I do agree with Fire Juggler that there is no need to get involved with all these BTC treasury companies as you can buy the actual BTC with no premium!
BTC linked to stablecoins and US treasuries before year end. Another halving (2028) around the corner.
I still find it hard to believe that most people regard this as a bubble. Bubbles burst quick-they do not progress for 15 years!
Take some time to read about the gold rush over the weekend and how gold progressed over the next 175 years.
Can’t imagine when BTC mining stops in 2042 what will happen to the price……….even before that and in every halving event.
All the best
Understanding it and scratching my head at why anybody would buy into a Ponzi scheme, selling a Ponzi scheme, under the auspice of a " mining venture " leaves me thankful that we still have some investor friendly financial regulation in the UK.
Investor friendly financial regulation is the last thing we have here (for reference look at AIM! and the shitcos).
One can buy these shitcos in an ISA but they cannot buy the most popular ETF that has trebled since its listing!!
Agreed though that most of them are just ponzi schemes (have mentioned this on so many occasions).
ISA limitations should be lifted-if we have paid our tax on our earnings and there is proof of that and signed by a certified accountant/tax professional.
Why £20,000 and not £100,000 if these are earnings already taxed.
All the best
ETF's, arghh another form of investment needing my unwary protection from (:-)
2040 that is!
All the best
How about some great news for a UK producer Chapel Down (LON:CDGP) the sparkling wines are simply fabulous, todays RNS below. Just remember to buy 2025 in a few years time !
Chapel Down Group Plc
('CDG' or 'the Company')
EPIC: CDGP
2025 Harvest Update
Chapel Down's Board is pleased to announce the completion of a strong 2025 harvest with good yields and exceptional grape quality.
Chapel Down has 1,018 acres of vineyards of which 777 are fully productive, an increase of +30% productive vineyards since 2022. This year's yield is expected to be 2,882 tonnes (2024: 1,852 tonnes), at an average yield of 3.7 tonnes per acre (2024: 2.5 tonnes per acre), which is +15% higher than the historic 5-year average yield per tonne.
The warm and consistent summer of 2025 created optimal conditions for fruit development, resulting in grapes with a good balance of ripe fruit flavours for complexity and texture with the natural acidity that will add a fresh, crisp backbone to our wines. As more of our vineyard estate becomes fully productive, Chapel Down is able to create a higher mix of Traditional Method sparkling (TMS) wines which are the Company's core strategic focus. This vintage is expected to enable a higher mix of TMS than in any of the previous five harvests.
The Board remains confident in underlying trading conditions and therefore achieving market expectations for 2025 FY. Finalisation of the (non-cash) Fair Value Adjustment to Biological Produce calculation will be progressed over the coming weeks.
Josh Donahay-Spire, head winemaker, commented: "2025 has been one of those rare years that winemakers dream of. Excellent growing conditions throughout the season combined with a relatively settled weather pattern during the harvest itself has resulted in good yields and exceptional fruit quality. The wines we will make from the 2025 vintage will help Chapel Down to continue to change the way the world thinks about English wines."
James Pennefather, CEO, added: "It is clear that 2025 will be seen as one of England's great vintages for Chapel Down, and is testament to the quality of the vineyards we have planted and the relentless attention to detail from our viticulture teams. I would like to thank all the members of our viticulture and winery team who have worked tirelessly to deliver such good quality and yield. This harvest was the second highest yield ever for Chapel Down and takes us one step closer to achieving our ambition of winning an equivalent 1% share of the global Champagne market by 2035."
We are also delighted to share our Harvest Report which provides more detailed information about the vintage and growing conditions for 2025 harvest. You can find the report here:
https://chapeldown.com/pages/results-centre
Mike, I mentioned the harvest yesterday and had a bit of derision about English wines !. I have held shares for a year, Chapel Downs wines are excellent the Kit Coty at the premium end. The Albarino is as good as many Spanish. The future for English wine making looks very promising. Sure you have seen this Chapel Down NY video released today.
How was Treatt successful?!
Not sure Dogon. Looking at the chart it seems like a rollercoaster that was optimally exited in Dec 2021. But from a satisficing point of view - if LordLee bought at 31p in 1999 and sold for 270p in 2025 that's a 771% gain of 8.7% annualised CAGR...
Fire - great answer! And there are dividends too.
Treatt (LON:TET) But that is only based on his original investment, what about subsequent investments? Did he buy any over 270p? Of course if he had sold around 1250p, would have been much better. This is the problem, with long term investing, you can hold on too long. I did it with Burford Capital (LON:BUR) went up to 2000p then right down.
I've answered you in the main report, Dogon!
I’m not making any judgements here, but are we saying that 8.7%pa, or perhaps 10-11% if one includes dividends, represents successful investing (given the risks involved in buying into smallish companies)?
It's a fair question, Rare Bird. The S&P 500 has also done very well since 1999, as I mentioned in the main report. But so has TET. If you earn 10% annualised over 26 years, you get 12x your money back at the end. I think that's successful investing, even for small-caps. The FTSE-100 might compound at 6-8% long-term, depending on your source.
Hi Graham, the Alumasc (LON:ALU) comments seem to be a copy/paste from REC. Although the market has spoken, down ~10% on open....
that's fixed, thanks Tim.
Graham, Several of the comments are attached to the wrong companies. e.g. ALU, REC
sorry, those two got mixed up. Fixed now.
Graham
If you get time you could have a look at the Molten Ventures (LON:GROW) trading update from yesterday. The SP ended up 14% and with an SR of 75 the only missing words were 'ahead of expectations'. [I hold].
Comments on record !!!!!
Judging by your exclamation marks I thought something very serious had happened! REC share price is up 0.6%.
no graham comments were mixed up !!!!!! exclamation marks just for you
I think the paragraph included which says "marginally positive" probably about sums it up
I sold my REC in 2021 after a good run and moved on. I'd forgotten all about them until I read a column in the Telegraph by the REC founder Neil Record. He still owns 25% and writes a good article on macro economics every week. He's an ex BoE economist but don't let that put you off, he seems to know how many beans make 5 which is more than some.