Daily Stock Market Report (Fri 27th February 2026) - RMV, BBOX, SNR, RGG, HAS

Good morning - it's the last trading day of the week, and the month!
Calling it there, thanks everyone. Have a fine weekend. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
International Consolidated Airlines SA (LON:IAG) (£20.9bn | SR89) | Revenue +3.5%, operating profit before exceptional items +13.1% (€5,024m). ROIC 18.5%. “Positive outlook for 2026 supported by compelling market dynamics and secular long-term demand.” | ||
Flutter Entertainment (LON:FLTR) (£16.0bn | SR22) | FY2025 revenue +17% benefiting from M&A. Adjusted EBITDA +21%. Net loss $407m due to $556m impairment charge. 2026 guidance: revenue +12%, adjusted EBITDA +4%. “US current trading largely reflects the impact on our customer base of the very high gross revenue margins achieved in the second half of Q4, driving lower levels of customer engagement into 2026.” | ||
Melrose Industries (LON:MRO) (£8.0bn | SR46) | Revenue +8%, adjusted operating profit +23% (£647m). New £175m buyback. Dividend up 20%. 2026 guidance: adjusted operating profit of £700 million to £750 million. | ||
Intertek (LON:ITRK) (£7.2bn | SR68) | Expanded its footprint in Colombia with agreement to acquire QTEST, “a market-leading provider of high-quality electrical testing and certification services”. 2025 revenues £2m. | ||
Pearson (LON:PSON) (£6.1bn | SR73) | 2025 sales +4%, adjusted operating profit +6% (£614m). “Confident in outlook, guiding to mid-single digit sales growth for 2026 and beyond. Strong financial position, with £350m share buyback well underway.” Medium term guidance reiterated. | ||
Tritax Big Box REIT (LON:BBOX) (£4.6bn | SR65) | Net rental income +10.6%. EPRA net tangible assets per share 187.76p (last night’s close: 170.3p). LTV 33.2%. “We enter 2026 very well positioned with a clear strategy, multiple organic growth drivers, a supportive market backdrop and a strong balance sheet.” Anticipating acceleration in adjusted EPS growth in FY26. | AMBER/GREEN = (Graham) The discount to NAV has narrowed to only 9%, compared to 20% a year ago. But I think I can stay AMBER/GREEN on the basis that trading remains very solid, with stable vacancies and gradually rising rents, and with an interesting growth opportunity in data centres. Perhaps the discount can narrow even a little more and approach the NAV? | |
Rightmove (LON:RMV) (£3.3bn | SR35) | All 2025 metrics in line with guidance. Revenue +9%, underlying operating profit +9%. “Property end-market trends remain supportive for our partners' businesses.” H2 weighting expected in 2026, H1 impacted by “fewer developments coming into the year and the strong mortgage comparator last year”. | GREEN ↑ (Graham holds) I’m going to upgrade this back to GREEN today, on the grounds that this is a very strong results statement, with a confident outlook, and the market has reacted positively to it (potentially signalling a positive change in sentiment). | |
Rathbones (LON:RAT) (£2.4bn | SR79) | FUMA £115.6 billion (Dec 2024: £109.2bn). PBT +53.5% (£152.9m), underlying PBT +4.6% (£238m). “We remain confident in achieving our 30% underlying operating margin target by the fourth quarter of 2026, assuming FUMA growth of 3% in 2026, stable inflation and interest rates in line with current market expectations.” | ||
Just (LON:JUST) (£2.3bn | SR41) | Planning to be acquired by Brookfield Wealth Solutions in H1 2026. | PINK | |
Senior (LON:SNR) (£1.08bn | SR65) | SP +18% Following three proposals, the Board appointed Lazard and Jefferies to initiate discussions with third parties. The company confirms it has received two further, superior all-cash proposals from other potential offerors. Discussions with potential offerors remain ongoing. £40m buyback postponed. | PINK (Graham) [no section below] Clearly I got this one wrong, as I thought it was full-priced last August when the market cap was merely £814m. The market cap is now pushing £1.3 billion and I calculate that the P/E multiple has today reached a remarkable 32x. This has always seemed to be a rather dependable defence stock but with rather average ROE and ROCE metrics and single-digit growth forecasts, I simply don't understand the attraction to a buyer at this sort of price. The Board are surely doing right by shareholders if they negotiate a sale price anywhere around this level? | |
Hays (LON:HAS) (£717m | SR30) | SP -10% Net fees down 9%, operating profit before exceptional items down 25%. “Continued macroeconomic and political uncertainty.” “New Year Temp & Contracting Return to Work volumes are building in line with prior year and our expectations. Perm remains tough but stable overall, with activity returning to pre-Christmas levels.” The CEO also steps down with immediate effect, "for personal reasons". | AMBER/RED = (Graham) [no section below] We've been AMBER/RED on this (e.g. see here) which appears to have been the correct call as both the company and its share price continue to suffer. The company blames macroeconomic and political uncertainty, but I don't buy it at this stage - there is something structurally broken with many recruitment companies, in my view. Economic challenges may be a factor, with employees reluctant to switch jobs and employers reluctant to expand, but I don't see how this can explain the consistent underperformance of the sector for a few years now. I think that another explanation - disintermediation by LinkedIn, for example - is needed. The Hays share price has been broadly declining for about five years now and on these reduced earnings, it does not even appear cheap to me yet. | |
Castelnau (LON:CGL) (£315m | SR33) | Hornby agrees sale of Scalextric & CEO departure and succession plan | Portfolio company Hornby Hobbies Ltd has agreed to sell Scalextric for £20m. £8.5m upfront, the remainder deferred and payable out of free-cash flow. | |
SRT Marine Systems (LON:SRT) (£209m | SR38) | Follow-on contract with an existing sovereign customer to expand the scope of the system. | ||
Gooch & Housego (LON:GHH) (£207m | SR63) | The order book has grown strongly and is currently at £168.3m (30 September 2025: £142.3m). “The Board's expectations for the current year remain unchanged, and are underpinned by the order book, self-help measures and new business pipeline…” | ||
Jubilee Metals (LON:JLP) (£137m | SR38) | The sale of the chrome and PGM Operations in South Africa has now been completed. Now focused on operations in Zambia. Discussions well advanced with a range of shareholders to ascertain views on future distributions (dividends/buybacks). A High Court process is needed to create distributable reserves. | ||
Rentguarantor Holdings (LON:RGG) (£42m | SR25) | RentGuarantor has developed AI-powered tools capable of automatically reading and analysing tenant documents. | RED = (Graham) [no section below] I was hopeful that this might prove itself to be a quality AIM stock, but since joining the exchange it has unfortunately proven itself to be rather promotional with a steady stream of RNS announcements, not all of which seem to be RNS-worthy. February alone has seen five announcements of this nature, and they seem to be increasing in their frequency. There have been four in the past week alone: if they keep going at this rate, they will soon be releasing multiple announcements per day. | |
Directa Plus (LON:DCTA) (£14m | SR40) | The Board is in advanced discussions with its long-standing substantial shareholder, Nant Capital, LLC, regarding a €4 million potential loan. |
Graham's Section
Rightmove (LON:RMV)
Up 5% to 448.9p (£3.42bn) - Annual Financial Report - Graham - GREEN ↑
(At the time of writing, Graham has a long position in RMV.)
Rightmove plc, the UK's largest property portal, today announces its audited results for the year ended 31 December 2025
Rightmove has been under pressure for most of the past year, as the market digests the potential impact of AI. The share price is down by 45% from the peak last summer:
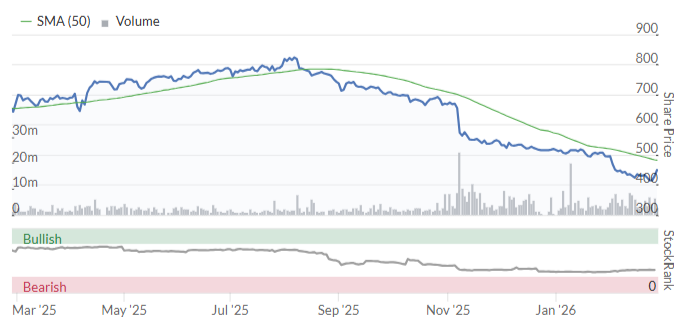
Thankfully, these results read well.
The highlights table:
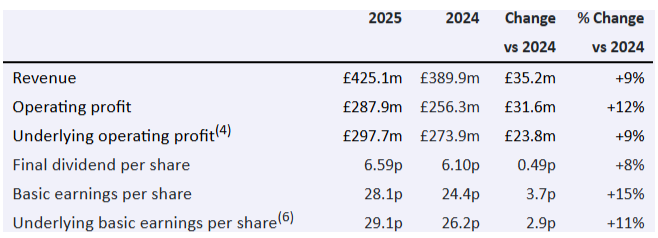
If you didn’t know that sentiment around this stock was so poor, it would be hard to guess it from these numbers.
Market share: this stands out to me.
Record share of time spent on Rightmove at year-end (89% Comscore; 75% SimilarWeb/data.ai/Sensor Tower)(1) with over 85% of traffic direct and organic(2); strong usage of a range of new consumer features, with several powered by AI
My reason for involvement in Rightmove - and the reason it’s such a controversial company at times - is the natural monopoly (or duopoly with Zoopla) which it appears to enjoy.
And with its share of time now apparently at a record, this monopoly is as strong as ever.
The fact that 85% of traffic is “direct and organic” is also key: everybody who is interested in property knows that Rightmove is there and will visit it without any need for an ad to prompt them. This is a serious competitive advantage.
OnTheMarket, now owned by CoStar Group, does not appear to be having any detectable impact on Rightmove’s market share.
AI: the market has been concerned by the threat of AI to existing internet platforms, and was also spooked by Rightmove’s intention to spend big on its own AI tools. Here is the latest on that topic.
Let’s quote extensively from Rightmove’s comment on its data and AI tools, as I think this is key to the story. I’ve highlighted some snippets that strike me as important:
Rightmove benefits from 4 petabytes (PB) of historic and live data - all stored on its unified and cloud enabled data platform - with over 90% proprietary to Rightmove. This data is processed by c.200 proprietary models to create differentiated outcomes to both consumers and partners
o Highest ever delivery of technology releases from our product teams - more than 6,000 during the year - leveraging Rightmove's data and technology, along with insights from c.20,000 minutes of user testing, over 85,000 surveys, and c.500,000 recorded web and app sessions
o Examples of new products for partners included Online Agent Valuation and AI-enhanced Opportunity Manager for Estate Agents, Direct Appointment Booking for New Homes, a new data API and property details pages for Commercial partners, and upgrades to Rightmove Plus and the Rightmove Hub
o Examples of new features for consumers included MyPlaces, Style with AI, AI Keywords within the app, a global-first Property Checker within Mortgages, and a Renters Checklist within MyRightmove
o A multi-year collaboration with Google Cloud enables Rightmove to lead digital innovation in the property ecosystem, leveraging its extensive datasets and accelerate products that deliver value to consumers and partners
Personally, I think it makes sense for Rightmove to spend big on innovation during a period in which there is a lot of change in how business is being done online.
There is no question in my mind that they can afford it, given their profit margins:
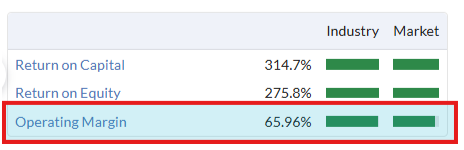
Of course it’s hard to say in advance if all of this AI/product spending is going to generate an attractive return, but I have no problem with them taking that risk.
My main priority is that Rightmove remains the #1 place to research properties, and anything that ensures this happens is fine with me. I am happy for profits to not be maximised for a couple of years, if that’s what it takes. For me, the bigger risk is that they don't spend enough, and then lose out to superior products at other platforms.
Average revenue per advertiser
The number of estate agent/developer customers is very stable (only up 1%), but they continue to spend more each year. The key ARPA metric just keeps rising:
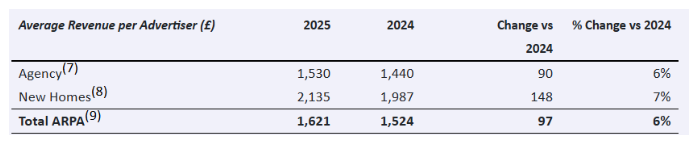
End-market trends: the property market is “supportive” for Rightmove’s customers, with more Bank of England rate cuts expected in 2026 and mortgage rates down year-on-year.
Current trading: Rightmove has entered 2026 “with strong momentum”. The outlook sounds strong although it does have an H2 weighting.
In line with our guidance set in November, we continue to expect 2026 revenue growth of 8-10%...
We expect year-on-year growth in the second half of 2026 to be stronger than the first half. First half growth is impacted by fewer developments coming into the year and the strong mortgage comparator last year.
We anticipate c.1% growth in membership and ARPA growth of £110-120 across Agency and New Homes.
CEO comment: contained within his very confident statement, he says “we will introduce a Rightmove app-in-GPT on OpenAI in the near future.” Interesting!
Dividend: the final dividend increases from 6.1p to 6.59p. There is also going to be a £90m share buyback (reduces the share count by less than 3% at the current market cap).
Graham’s view
Without wishing to get too philosophical on you, I do think the share price movement here over the past year is consistent with the Mr. Market metaphor: the one where he is an emotional neighbour, shouting house prices at you every day.
Rightmove hasn’t changed all that much over the past year, and yet the share price has been cut nearly in half.
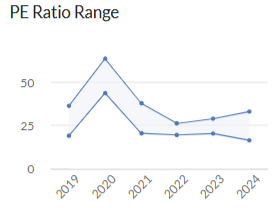
The P/E multiple has often been in the mid-20s and high 30s:
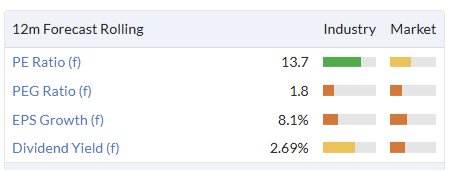
And then it fell to less than 14x:
If you didn’t know any better, you’d assume that the earnings outlook had dramatically changed. And maybe it has in the long-term, if AI disrupts it. But that’s not reflected in short-term forecasts:
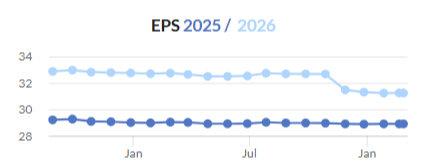
The cut to the FY26 EPS forecast was from 32.7p to 31.5p. That does not seem of great significance to me.
I’m going to upgrade this back to GREEN today, on the grounds that this is a very strong results statement, with a confident outlook, and the market has reacted positively to it (potentially signalling a positive change in sentiment).
Granted that as a shareholder, I may be biased.
I also acknowledge that the StockRanks don’t like it yet:
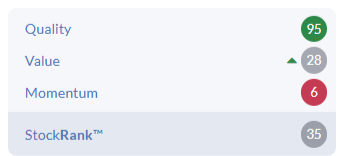
I don’t like to disagree with the StockRanks very often, but in this case the main area of disagreement is Momentum - the StockRanks are wary of momentum, and I'm willing to look past that.
However, with the share price rising on the back of today’s results, I think we have a genuine piece of evidence that momentum and sentiment might be about to change.
I also note that the other area of StockRank weakness, the ValueRank, has been increasing. This is a stock that has rarely offered much fundamental "value".
So I’m taking a contrarian stance here by upgrading this back to GREEN, and I may be in a small minority with this view. But I hope you can understand my reasons, whether or not they prove to be valid.
Finally, checking shorttracker.co.uk to see how active the short-sellers are here, I see that disclosed short interest is about 2% of total shares outstanding. That’s a meaningful figure, but not too alarming. For context, there are 70 other UK companies where the disclosed short interest is higher than 2%.
Rightmove is 3% of my personal portfolio and if I didn’t have any other good ideas, I’d even consider topping up my position here!
Tritax Big Box REIT (LON:BBOX)
Unch. at 170.35p (£4.6bn) - Results for the year ended 31 December 2025 - Graham - AMBER/GREEN =
Tritax owns “the UK’s largest logistics investment and land development portfolio”.
Some very decent figures here, until we get to the official earnings per share figure (“IFRS earnings per share”). More on that at the end.
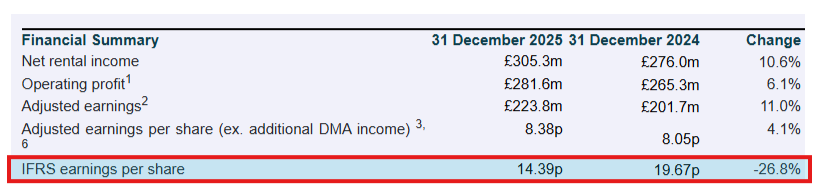
Do bear in mind that the growth in net rental income has been boosted by an acquisition, so it’s not “like-for-like”.
Like-for-like rents grew 4.2%, while the portfolio’s like-for-like estimated rental value grew 4%. So the real growth in rents is clearly running at around 4%.
Vacancies are stable at 5.6%.
We get some interesting comments from the Chair:
"Over the past year, Tritax Big Box has taken important strategic steps that reinforce both the capabilities of our platform and our growth drivers. The successful integration of the UKCM logistics assets, together with the portfolio acquisition from Blackstone, has created a meaningful c.20% exposure to urban logistics, strengthening our end-to-end offer and further cementing our leadership position across the UK supply-chain spectrum.
"In parallel, we have launched our data centre programme, pioneering an innovative 'power-first' approach that unlocks opportunities in digital infrastructure. In just 12 months, we have assembled a high-quality pipeline and made significant progress, positioning the company to generate exceptional returns for Big Box shareholders from the most compelling structural growth opportunity in real estate.
The company’s stated growth drivers are 1) rental reversion (new leases at higher rates after old leases expire), 2) developing best-in-class logistics assets, 3) data centres. The data centres are “targeting exceptional risk-adjusted returns”.
Balance sheet: net debt is £2.6 billion and the loan-to-value is 33% which is pretty standard and safe for most REITs in my view. Indeed, a REIT with an LTV much lower than that might even make me suspicious - why not borrow more to maximise returns?
LTV last year was 29%, with the increase being due to the acquisition of a portfolio from Blackstone.
The weighted average cost of debt is a moderate 3.6%, although this is up from 3.1% a year ago. A £400m RCF has been refinanced along with a £300m 7-year bond. Average maturity is 4.3 years. Nothing out of the ordinary here, as far as I can tell.
Graham’s view
As always, the key metric for me when examining a REIT is net asset value vs. the share price.
NAV per share is calculated under normal accounting rules and under EPRA’s rules for real estate. In both cases, the result at BBOX is about 187p - 188p. So the current share price offers about a 9% discount to that figure.
When I looked at BBOX a year ago, the discount was 20% and I took a moderately positive stance.
The shares are up by 18% since then, and a useful dividend yield has also been paid:
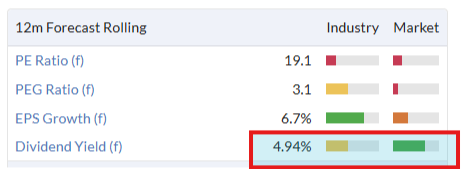
So perhaps I should have been more positive on this a year ago.
At the new, higher valuation, I think I’ll keep us moderately positive, as there is still some level of discount that could be narrowed, and the company appears to be trading very solidly.
The only issue I needed to investigate was the year-on-year decline in earnings per share under accounting rules. There were two main reasons for this, that I can find on the income statement.
Change in fair value of properties. Last year, there was a £244m gain in fair value. This year, there was “only” a £199m gain. This doesn’t concern me.
Impairments: last year, there were barely any impairments. This year, there were £29m of impairments. Checking footnotes, I find that it was due to a site where BBOX’s “expectation on the possible likelihood and timing of achieving planning consent changed in the period.” In the context of a multi-billion pound portfolio, this does not strike me as terribly important.
Neither of these factors require me to change my stance. So I’m staying where I was on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Hello All,
On the back of Funderstruck post below,
Currently awaiting transfer of ISA, in that time MHA (LON:MHA) has decided to tank, anything I can do? Desperate to sell. I know that nothing can be done until finalised.
Thanks
I did see this as a potential problem Spider but was forced into a change. Possibly if you have a second platform you might take avoiding action if you see this happening again to another holding.
Could someone please update as to the colours on Grahams spreadsheet. Thanks
There is a legend in the spreadsheet itself Paul, if you're not sure what they mean. Just scroll to the right. G
Thank you
Rightmove (LON:RMV) At 15x fcf valuation and mid single earnings growth, it is not a steal at the current price. The investment case at today’s is somewhat based on the stability / maintenance of its competitive positioning, which is potentially more precarious than it was 3 years ago. Is there a mid teen earnings growth story here to get the PEG up? (No position in this stock)
Does anyone know a reason for the share price of Watkin Jones (WJG) going up over the last few days?
Bowl
Watkin Jones (LON:WJG) there has been good volume printed most days for the last two weeks before the 'bowl' started to turn up. Also the order book is well bid even now so it may be that someone is building a position here. there has been some discussion over on the 2026 Trade/Chart Ideas thread https://www.stockopedia.com/co...
Thank you ,everyone, who answered my call on Weds for advice on selecting a replacement Platform Broker . I finally added AJ. Bell as the ease of contact and excellent response to Support calls was more of a priority for me. And that proved itself whilst yesterday i smoothly transferred a Trading and Equity ISA from the existing user.
Well at least i have done all the Admin and received confirmation but i now have an agonising long wait for the transfer to complete.
I am thinking of following you (from HL). Have they told you how long you will be unable to operate your accounts?
Hi Conistons, They indicated a 4-5 week period for equities & after that the Cash would follow.
I have two other accounts one of which is HL which although a bit more expensive even though the trading cost has recently been considerably reduced, I like the actual platform & ease of use although the speed of telephone answering is slower than AJB. at least they have that service; some of the low cost platforms cannot of course afford that luxury.
Changes like this do require a lot of research, switches need to be speeded up like bank accounts but probably not the same mass of the public behind the call.
Thanks Funderstruck. Eek 4-5 weeks without my daily stock market buzz...I think I may reconsider. I am peeved that HL are going to charge me a lot more - I don't deal often so won't recoup much on the lower dealing fees - but being locked out for so long might cost a lot more. Familiarity with their system and access to real time prices is probably worth something. Thanks for your information. Good luck with the transfer!
Augmentum Fintech (LON:AUGM)
Can I urge other shareholders dissatisfied (as I am) with the proposed sale of the company at a 30% discount to its NAV to write to them and say so.
Address is info@augmentum.vc
This is the text of my letter:
“I am a long-term and quite substantial shareholder in Augmentum Fintech via my and my family’s ISAs and SIPPs held through Halifax Share Dealing and Stocktrade.
I am writing to complain about the deal to sell the company at a discount of 30% to the Net Asset Value – this is an outrage, and in my view is a serious breach of your directors’ duties. I will be voting against.
If you do not want to run the company – as you plainly do not – then you should resign and make way way for people who are willing to run the company for the benefit of the shareholders.
I look forward to hearing from you that the deal has been pulled.
Yours sincerely”
Ricardow, I have sent the below
Attention the Board
I am a long-term shareholder in Augmentum Fintech.
I am writing to complain about the deal to sell the company at a 30% discount to its Net Asset Value. This is disappointing given the patience many of us have had over the years by considering the manager's comments at various presentations and continuing to have faith.
It appears you are now selling the company cheaply, just as the portfolio is reaching a point where real value may be achieved—no wonder the buyer is keen to grab this at a 30% discount.
Personally, I would have thought you are in breach of your fiduciary duty to act in the best interest of the shareholders. The Board's role is surely to monitor the manager and the performance of the assets, not to decide that due to a large market discount, you should seek a buyer at almost any price. That hardly maximizes value for shareholders.
If you feel the business cannot continue as it is, and I accept that maybe the initial flotation failed to raise enough funds, then surely a merger with another similar trust would make more sense.
I find this comment insulting to us shareholders- you are letting another body benefit from our intial investment in what were early stage fintech companies. ( I am not even sure we were aware a strategic review was under way. Did you advise shareholders?)
"Consequently, Verdane and BidCo believe that Augmentum will be better able to achieve its growth and valuation aspirations with better access to capital under BidCo's ownership. Verdane and BidCo believe that under private ownership there will be greater flexibility to execute and accelerate Augmentum's investment strategy with a supportive owner which can help unlock the potential of the Portfolio. Verdane is very experienced in creating value in technology growth investments (including in portfolios of investments), has access to material financial and other resources and, accordingly, is well placed to support, finance and positively influence Augmentum and the Portfolio going forward.
Verdane and BidCo consider that the Acquisition provides a compelling and immediate liquidity opportunity for all Augmentum Shareholders to realise their investment in full for cash at a material premium to the current traded price of an Augmentum Share."
I strongly suggest you withdraw from this low offer unless Verdane dramatically increases the terms; a 10% discount might be acceptable. Why not speak to other Trusts and see if they would make a paper offer which at least means us shareholders could still benefit from the patience we have shown.
I look forward to hearing from you that the deal current has been pulled.
Perhaps consider a comment on Tritax Big Box REIT (LON:BBOX) [I hold] as flagged by Tortoise. I am a lay investor and understand little about the implications of it being a Reit, and also their corporate structure. but it does seem they are in a more exciting niche (huge data centre near Heathrow etc) than many Reits. What finally got me to invest was the list of director purchases. I have never seen anything like it!
BBOX - The long list of director purchase a few months was related to the management agreement whereby 25% of the management fee is used to purchase shares for directors, so wouldn't reading too much into that.
many thanks. Very helpful to know that. I had been massively impressed! This is good example of how this Discussion group can be so useful.
Nettle- https://www.stockopedia.com/co...- I just added a comment about the Heathrow data centre on the Trust thread. A slight question mark but not a worry to me, bought more today.
International Consolidated Airlines SA (LON:IAG) solid results. EPS up 20% with some jiggling. Stock down 5% so some profit-taking? Would be interested in team view.
Tritax Big Box REIT (LON:BBOX), which reported today, continue to looks good to me with a 10% discount to NAV per share. I hold. It is also a potential AI beneficiary from data centres - it is expecting planning permission to be granted by 17 March for its first data centre.
Does anyone have a bear case against it? The valuation of some REITS has now caught up with NAV but there remains a discount here. We're likely now near the low point in the cycle with interest rates coming down although, of course, some REITs might still be seeing rising costs as they replace loans acquired during the pandemic and pre-pandemic interest rate lows.
The only current bear is the Secretary of State reviewing the Heathrow Data centre - March 17th expected date. More added on the Trust Thread. Joins FTSE100 March 2nd. A long term holding of mine and bought more today.
Thanks Graham for looking at this today :)
Most welcome, Tortoise! It was a good suggestion :)
MELROSE
The report reads well, all the numbers are up and increasing. Still the shares are down 10% and Stocko ranking agrees with the market.
Clearly I am missing something big here! Maybe someone wiser can tell me.
You and me both Yadi. Profits up, dividend up and a share buy back.! Not usually a trigger for a fall.
Wish I had some spare cash - Maybe the Market disappointed that they are not moving into combat drone production
re Melrose Industries (LON:MRO)
Not an expert or holder but think as you would expect the guidance is actually weaker at revenue level.... I also thought they sounded ok but as we know the devil is in the detail.... as a rule I always let US open before trying to fish for a bounce.
Good point RDH - especially I guess with stocks like CRH (LON:CRH) and Ashtead (LON:AHT) now with primary listing in NY
Could it be that Melrose Industries (LON:MRO) is one of the potential suitors for Senior (LON:SNR)? - I hold both. That could cause a nervous exit from some ‘lucky’ insiders, but not me, yet.
Melrose set a 2026 adjusted operating profit range of £700–£750 million, which UBS noted sits just below the £754 million consensus estimate. After a very strong 2025, investors had been positioned for further upside, so even a modest shortfall versus expectations weighed heavily on sentiment.
Operationally, Melrose is strong with expanding margins, improving cash flow , and engines and defence divisions performing well. However, the valuation was rich, and the market was positioned for another guidance beat.
Even a small guidance miss relative to consensus can trigger a large move when expectations are high and the stock has recently outperformed. This is a classic case of “great results, disappointing guidance”.
I hold and will continue to do so. Might even add a few.
Life goes on ... certainly does when you are in the middle of lambing.
Thanks James - I guess I am not the only one with a few 'hiccups 'like this recently. The Market can be very hard on the slightest excuse - thankfully the portfolio is holding up with the recent addition of precious metals - Gold / silver and copper which I would never have entertained previously but for this bulletin board. And good luck with the lambing - you must be a bit early this year for The Highlands !
Benefits of a lambing shed and a gambling attitude to climate change. 35 years ago, we would have six feet of snow at this time of the year; we now have sunshine and the grass is growing! Unlike the rest of the country, we have had a pretty dry winter, but little snow.
I am planning to do a deep dive on Melrose as there is an annuity nature to their income going forward which I am not sure is fully appreciated. The shares currently look cheap to me.
Engines is the core of Melrose’s business and the main profit driver with revenue of £1,632 million in 2025 accounting for £520 million of adjusted operating profit, or about 80.4% of group operating profits,
Engines is therefore the dominant earnings contributor, with very high margins (31.9%).
Airframes, on the other hand, is smaller with revenues of £1,957 million and adjusted operating profits of £156 million. So Airframes account for 54% of sales and 24.1% of operating profit. Airframe margins remain weak at around 8% and has to be a focus for management moving forwards.
I am fairly sure the two business lines can operate independently of each other. I have written to them to ask because some analysts have wondered if Melrose might divest the airframes business. I doubt it: Melrose has not announced any plan to sell its Airframes division, and nothing in the latest results or news flow indicates an active disposal process. The available evidence instead points to continued ownership, with management focused on improving margins and resolving operational issues rather than preparing the business for sale.
On a personal note, I am happy to continue holding, although today's SP action was undoubtedly unwelcome. I am thinking of adding tomorrow as I regard Melrose, Rolls Royce and Babcock as long term holds.
Melrose Industries (LON:MRO). An explanation. Interesting last line. Shares of aerospace components supplier Melrose Industries MRON.L fall 14% to 548p; top loser on FTSE 100 index .FTSE
** Flags softer-than-expected revenue for 2026 as sector-wide supply chain constraints persist
** Sees 2026 group revenue of 3.75 billion pounds ($5.06 billion) to 3.95 billion pounds vs analysts' estimate of $4.01 billion pounds, according to data compiled by LSEG
** Says U.S. tariffs and ongoing supply chain bottlenecks continue to add complexity, contributing to its downbeat revenue forecast
** Brokerage JP Morgan says "2026 EBITA guidance below consensus but entirely due to FX"
Just had word from Stocko there is a system problem which they are working hard to resolve.
Burford Capital (LON:BUR) I hold
Any chance you could cover yesterday's Annual results which were released in the afternoon?
Thanks. I had battered my iPad for 10 minutes blaming Apple - then realised it was the site!
Stocko pages taking a long time to load for me - anyone else?
Yes, very slow.
Yes was wondering whats going on
same
Just pleased to hear it is not only me !
Thanks 'The Raven' rebooted my laptop already this morning thinking it was me ;-((
At least I now have a chance to read all the famous quotes!
Intertek (LON:ITRK) - I'm surprised that an acquisition of a company with £2m of revenues actually merits an RNS for a business with £3.4bn of revenues and a £7.2bn market cap!
I couldn't believe it when I saw the £2m figure!
SRT Marine Systems (LON:SRT) Good new contract with existing client - But do we know the contract period?
SRT Marine Systems (LON:SRT) I hold
Hi bohenie, the announcement says "The new contract is a follow-on contract to expand the scope of the system." SRT contracts for systems is not like a manufacturer supplying physical widgets where the contract ends when the last widget is supplied. SRT systems remain operational until the customer decides they don't need it or have an alternative supplier. In practice that's very unlikely as these are highly embedded into their national security or fisheries programs. It is expected that such systems will grow and be maintained over long periods along with a charge for the data imported resulting in continued revenues for SRT.
Of course there is a period during which the system or an enhancement is being delivered for which SRT receive revenue, in this case $20.5m. This particular contract does not specify how quickly the expansion of scope will take . Given the size of the contract I suspect it will be a fairly short period. My guess is it is an extension of the Kuwait contract as they have been very ambitious and in a hurry to fully establish their system.
This expansion could be to analyse data from a new type of sensor or the supply of physical equipment or both. For example, the customer may want airborn drones or subsurface vessels to be added to the existing sources of data. SRT would also have to add the relevant analysis to its GeoVs software.
I hope this answers your question.