Daily Stock Market Report (Fri 28 Mar 2025) - SMWH, RCDO, SNWS, EVPL, INPP, BAG, LTHM, JHD

Good morning,
Happy Friday! Today I'm hoping to look at some backlog items that were requested by readers or are otherwise interesting. So far I have EVPL, INPP and BAG on the list.
Today's Agenda is now complete (added RCDO and SMWH).
I'll be adding some Backlog items through the afternoon - please continue to check back.
4pm: all done, and hope you're happy with the brief coverage of various backlog items. Have a nice weekend!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| WH Smith (LON:SMWH) (£1.4bn) | Sale of High Street Business | SP -4% Gross cash proceeds £52m, net cash £25m. Creates pure play global travel retailer. Trading in line. Background notes: The High Street division generated “trading profit” of £32m on revenues of £452m in FY August 2024. With 500 stores being sold, the average store is valued at £150k. | AMBER/GREEN (Graham) [no section below] This sale price strikes me as underwhelming. Perhaps the loss of the name WH Smith from this division (to be rebranded “TG Jones”) is a major reason for the discounted sale? I leave our mildly positive stance unchanged as 85% of SMWH’s trading profit is from the Travel business which will now have management’s undivided attention. |
BBGI Global Infrastructure SA (LON:BBGI) (£1.0bn) | Full Year Results | Nav per share 142.7p. On 6th February, announced a Board-recommended offer at 147p. General meeting on 10th April. | PINK (under offer). |
| Ricardo (LON:RCDO) (£160m) | Strategy Update | Response to Science (LON:SAG) . Says SAG wants to control RCDO without paying a takeover premium. Trading in line. | AMBER/RED (Graham) One good outcome from Science Group's involvement is that it has prompted Ricardo to promise a business and strategy update for next month, which may contain more info than Ricardo would otherwise have felt obliged to publish. |
Smiths News (LON:SNWS) (£129m) | TU | Solid performance, on track to deliver results in line with expectations. | GREEN (Graham) The company reminds us that at least 91% of revenue is contractually secured through to 2029. The collapse might come in 2030 but I'll keep my optimistic stance on this for now. |
Good Energy (LON:GOOD) (£90m) | Un-audited Results | 2024 profit in line. PBT +16% (£6.6m). Revenue fell with energy costs, but gross margin improved. | PINK |
LMS Capital (LON:LMS) (£18m) | Full Year Results | NAV £36.2m, NAV per share 44.8p vs. share price 21.3p. Year-end cash balances £13.5m (including cash at subsidiaries). | PINK (“Managed Realisation”) The Board have signalled their intention to pursue an orderly realisation of the portfolio and return capital to shareholders. |
Roebuck Food (LON:RFG) (17m) | Full Year Results | Revenue £11.6m, operating loss from continuing operations £1.7m includes acquisition costs £1.1m. | |
Parkmead (LON:PMG) (£14m) | Interim Results | Cash £6.8m. Disposal to generate £14m plus contingent consideration of up to £120m. | |
Plexus Holdings (LON:POS) (£12m) | Interim Results | Sales -43% (£2.9m). Pre-tax loss £1.3m. Cash £1.4m. Exc. a one-off deal, organic revenue up £1.9m. | N.B. has conditionally raised £3.5m subject to approval at a general meeting on April 7th. |
Westminster (LON:WSG) (£9m) | Interim Results | Revenues +26% (£3.7m). Gross margin falls to 33%. Pre-tax loss £1m. Raised £1.2m recently. |
Ricardo (LON:RCDO)
Up 1% to 261p (£162m) - Strategy Update - Graham - AMBER/RED
The friction between SAG Holdings (NAQ:SAG) and Ricardo leads to another RNS.
Science Group has demanded the removal of Ricardo's Chairman. It is the Board's understanding that, if this demand is met, Science Group will seek to replace him with the Executive Chairman of Science Group. This would give Science Group effective control of the Board without paying a premium for that control.
The Board believes Science Group's actions are being taken solely for the benefit of Science Group and its own shareholders and are contrary to the interests of Ricardo's other shareholders.
Even though I have a moderately negative stance on Ricardo, I have some sympathy for their position. They didn’t seek out this conflict. And unless Science Group can get a much bigger stake than 16% - or convince other Ricardo shareholders of the correctness of their position - then Science Group isn’t entitled to demand major board changes.
Ricardo notes that thanks to the disposal of its defence subsidiary and various acquisitions it made (and perhaps overpaid for?), its Environmental & Energy businesses now account for c. 85% of operating profits.
One positive effect of Science Group’s agitation is that it has prompted Ricardo to produce a “Business and Strategy Update” for publication in mid-April. This will include:
YTD 2024/25 trading and outlook;
Actions the Company is taking to further reduce costs and improve cash generation in the near and medium term; and
Greater detail on the Company's plans to focus on environmental and energy transition solutions.
Graham’s view
See my comments in January to see why I turned AMBER/RED on Ricardo: a significant debt load, a major profit warning, and a moderately high earnings multiple for an average-quality business even if it hits downgraded forecasts.
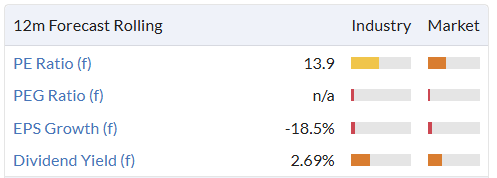
The big question for me is what Science Group sees in it. The most logical explanation I can find is the one given by Ricardo itself: a potential opportunity for Science to control a £160m market cap business in the consulting sector, even though Science doesn’t have the funds to buy the business outright.
Smiths News (LON:SNWS)
Down 1% to 52.8p (£131m) - Graham - GREEN
Mark has been AMBER/GREEN on this newspaper/magazine delivery business, while I've been GREEN on it.
Today the company has reiterated a very interesting fact: that I remember it saying before:
Smiths News has officially secured long-term contracts covering 91% of its newspaper and magazine revenues through to at least 2029, providing a solid foundation to support its medium-term growth ambitions. Smiths News continues to maximise its market-leading early-morning, end-to-end supply chain capabilities
I remember being a little sceptical of this but the company clearly wants the market to take it to heart!
If that puts a floor on revenues through 2029, is it possible that the revenue decline might be less than the 9% shrinkage implied? If revenue falls by only mid-single digits by 2029 that should mean several more years of big dividends that are well covered by earnings:
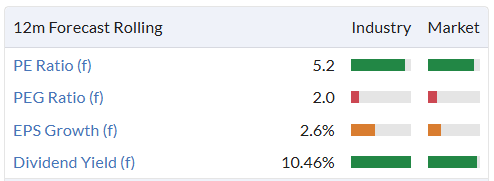
The question is whether we see some kind of final collapse in newspaper and magazine readership. Or - and this may be wishful thinking - could we see it actually hit a trough at some point?
Today's update from Smiths News describes a "solid trading performance across H1" with the full-year performance tracking in line with expectations.
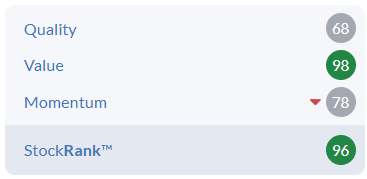
It is categorised as a Super Stock:
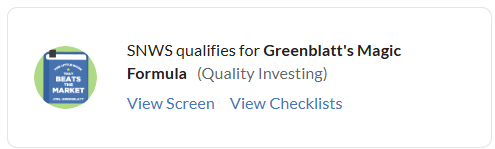
And it passes my favourite stock screen:
So where does it go from here? As with the likes of Reach (LON:RCH), I'm attracted to contrarian "cigar butt" stocks like this, where there is the prospect of a few more puffs of profitability to justify the current market cap.
At the most recent full year results, it reported average net bank debt of £12m which was down by over 50% on the previous year.
I think a very large part of the future value here rests in management's investing capabilities, as the core business may ultimately be in a terminal decline but the company will have available cash flow to invest in bolt-on acquisitions and other "adjacent growth initiatives". This is perhaps riskier than the average stock I might go GREEN on, but I remain comfortable with this stance for now.
Backlog items (please check back through the afternoon as I work on this).
- EVPL done
- INPP done
- BAG done
- LTHM done
- JHD done
Everplay (LON:EVPL)
Up 18% this week to 271p (£395m) - Final Results - Graham - GREEN
everplay group plc, a leading global independent ("indie") games developer and publisher of premium video games, working simulation games and children's edutainment apps, is pleased to announce its unaudited final results for the year ended 31 December 2024
This is the renamed Team17, creator of the Worms games franchise.
I was reasonably positive about it at the interim results last year.
This week we had full-year results with the following highlights which on their face seem to justify my positive stance:
Revenue +5% (£166.6m)
Adj. EBITDA +46% (£43.5m)
PBT £25.3m (last year: £1.1m loss)
Cash improves to an impressive £63m (from £43m).
The back catalogue is key to performance at this Group, which arguably reduces the risk as it doesn’t rely on new blockbuster performances every 6-12 months. The back catalogue generated 86% of group revenues in 2024, higher than its six-year average of 76%.
Consider this review of performance at the subsidiary which still carries the original name of the group:
Team17 revenues fell by 5% as some new titles failed to meet management expectations and some titles were moved into FY2025. There was, on the other hand, strong double-digit growth in the back catalogue. More than 80 titles contributed towards back catalogue revenues in period, encompassing over 1,200 Digital Revenue Lines (up from over 900 in FY 2023)
Away from Team17, the other subsidiaries delivered much better revenue growth, up 22% and 25% respectively.
Dividend: we have a maiden dividend of 2.7p.
Outlook:
The Group has made a good start to FY 2025, supported by the momentum from the festive season promotions. As a result, the Board remains confident that the Group can deliver an improved trading performance in FY 2025, marginally ahead of current market expectations, and remains well positioned for continued growth over the medium to long term.
Market expectations are not included in the announcement.
Graham’s view
“Indie” games are an interesting investment idea. They lack the enormous resources that go into flagship games titles, and in general they can sometimes look unimpressive, but they often still command a loyal following.
With Team17/everplay, I think we have probably my favourite example of an indie games developer. Worms launched an “Anniversary Edition” 25 years after the original which I played as a teenager (how to make me feel old!) and continues to attract a following.
Despite being an indie games company, I actually think this business might be less risky than some developers of flagship titles, due to its diversification and thriving back catalogue.
With rising momentum and a near-perfect QualityRank, I’m happy to upgrade my stance on this to GREEN.
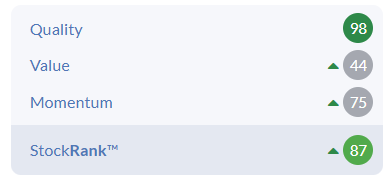
I see that the dividend forecast on the StockReport was only 1.4p, with the actual proposed dividend being nearly twice as high. The ValueRank might get a boost when this is updated:
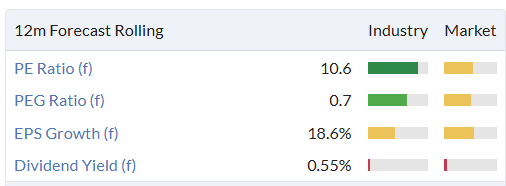
I should add a gentle reminder that the largest shareholder Debbie Bestwick (with 18%) is currently a NED. She sold 10% of her stake back in November at 210p and it wouldn't surprise me in the least if she continued to diversify out of the business over time.
International Public Partnerships (LON:INPP)
Unch. at 110.9p (£2.1bn) - Full Year Results - Graham - AMBER/GREEN
This investment trust was suggested by a reader. It's FTSE-250 listed and invests in offshore energy infrastructure ("OFTOs"), various public-private partnerships, and other businesses in the infrastructure theme.
From its homepage I see that it has a 72% UK weighting with other important weightings in Belgium, Australia and Germany.
Yesterday it published full-year results with the following key points:
- NAV decreased to £2.7 billion (Dec 2023: £2.9bn), "primarily driven by an increase in interest rates".
- PBT was around breakeven
A low correlation with FTSE All-Share of 0.4 is mentioned - they are clearly targeting a certain type of risk-averse institutional investor by mentioning this.
I note that fee changes have been agreed with the investment manager so that they will be partially incentivised by the market cap of the company, not just its NAV. In other words, they will be motivated to try to close the discount to NAV!
The Board aren't satisfied with this discount at all:
"The Company's portfolio continued to show resilience during the year with strong underlying performance, despite a persistently challenging market environment for listed investment companies."
"The Board continues to believe the share price at which the Company is currently trading relative to the NAV materially undervalues the Company. Reallocating capital to enhance value for shareholders continues to be the primary focus for the Board and Investment Adviser, having realised c.£260 million through asset recycling in the 18 months to 31 December 2024. The realisation proceeds achieved were in line with the last published valuations. The Company is continuing its divestment programme in order to increase the quantum of capital able to be returned to shareholders with an enhanced target of returning up to £200 million."
Outlook: they are again targeting risk-averse institutions with this message (where I have added the bold).
Despite the persistent challenges facing the sector, which are contributing to sustained upward pressure on discount rates and consequent valuation challenges, listed infrastructure continues to represent an attractive long-term investment.
The Board believes that the implied projected net returns of 10.7% on an investment in the Company's shares, with a current dividend yield of 7.6%, represents an attractive 5.6% premium to that offered by a 30-year UK government bond.
Graham's view
I'm happy to give this an AMBER/GREEN. I've not studied it in detail but the sector in general is cheap. With a NAV per share pf 144.7p, this trades at a 23% discount. Or looking at it another way, investors would make a return of 30%+ from the current level, purely from a narrowing of the discount to zero (on top of the underlying return).
We've seen so much corporate activity in the trusts area recently, with many of them going private, my working assumption is that they are all undervalued until proven otherwise!
In fact, I've recently bought a trust for my personal portfolio for the first time. I've bought Pantheon International (LON:PIN) and look forward to writing up some analysis of it for you at some point in the not-too-distant future.
INPP is targeted at investors with a low risk tolerance and personally it doesn't match up with my risk appetite, so it's not something I'd consider investing in personally. But for those who match up well with its risk levels I can see that it might be be attractive. I'm AMBER/GREEN on this.
A G Barr (LON:BAG)
Unch. at 623p (£697m) - Full Year Results - Graham - GREEN
This Glasgow-based drinks group was previously on my small-cap watchlist. I rather meanly removed it due to its recruitment last year of an unlucky CEO.
I do still view it as a fabulous company.
Here are some headlines from its results for FY Jan 2025. And kudos to the company for getting these out in March!
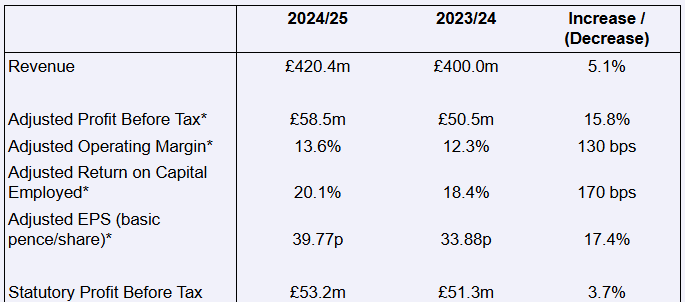
The adjusted PBT result is higher than the estimates published in January.
Let's explore why statutory PBT failed to grow; here are the adjusting items.
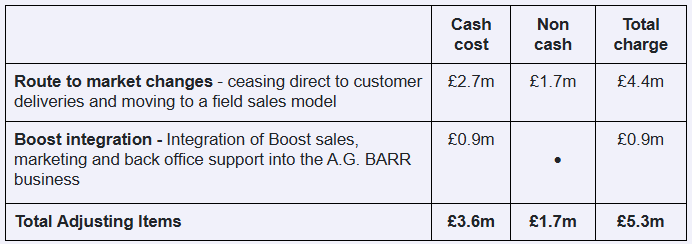
The adjusting items "comprise costs associated with our business change programme to improve efficiency and unlock growth".
I tend to not allow these types of adjustments, or to only partially allow them. It's too easy for sneaky CEOs to put a range of inconvenient costs into the adjusting items bucket. An optimist will argue that they are non-recurring costs. A pessimist like me will argue that non-recurring costs are a fact of life!
The company offers guidance that it's planning to spend £1m this year to simplify and integrate the business into a single organisation. So hopefully that will be the main adjustment and we'll see a cleaner result for FY January 2026.
The main brand is IRN-Bru and it's great to hear that it continues to do well. Rubicon also had a "standout performance". I note that the 3 core soft drinks brands - IRN-BRU, Rubicon, Boost - generated 66% of total revenue, and collectively grew 8.4% year-on-year.
Outlook - in line.
CEO comment:
"2024/25 was a successful year for the Company. I would like to take the opportunity to thank my colleagues across the business who delivered these excellent financial results.
Looking forward, we have a refreshed strategy centred on growth and are committed to our long-term financial targets. I am confident that successful execution of our plans will see another year of positive progress towards our long-term goals."
Graham's view
This is still a fabulous company in my view. Stockopedia calculates it as a High Flyer (high Quality and high Momentum) but the Value on offer doesn't seem too bad either:
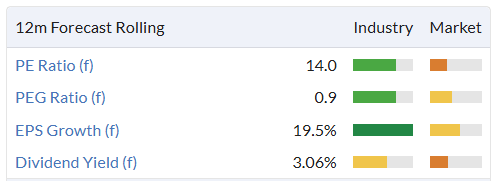
Their core drinks brands appear to be as strong as ever. I'm happy to leave my positive stance unchanged.
James Latham (LON:LTHM)
Up 4% this week to £10.87 (£219m) - Trading Statement - Graham - AMBER/GREEN
We had a brief update yesterday from this trade distributor of timber, panels, and decorative surfaces.
Revenue for the year to 31 March 2025 remains in line with market expectations, with volumes slightly up on last year. Cost prices have remained stable throughout the year, but the market for timber and panel products remains competitive.
We continue to invest in order to keep improving our service levels. We anticipate that our profit before tax will be in line with market expectations. The Company's balance sheet and cash balances remain strong.
I'm happy to leave our prior stance unchanged - AMBER/GREEN by Mark in November.
Checking SP Angel's December note, I see that they "marginally" reduced their forecasts for FY March 2025 to revenues of £359m and net income of £19m (and it's nice to see no difference at all between net income and "adjusted" net income.
I also note a net cash forecast of £74m which helps to takes the sting out of fears that this might be trading expensively:
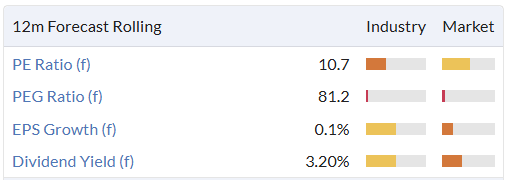
Growth is minimal - revenues are expected to fall slightly - so I expect that the main reason to hold this would be a high level of bullishness on the macro outlook.
James Halstead (LON:JHD)
Down 1% this week to 146p (£608m) - Interim Results - Graham - GREEN
James Halstead plc, the AIM listed manufacturer and international distributor of floor coverings, announces its results for the six months ended 31 December 2024.
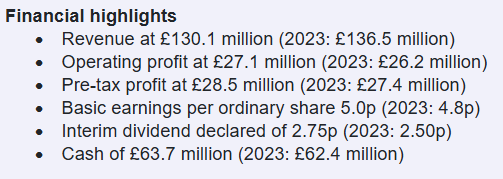
Floor coverings are one of the trickiest sectors in my experience. But James Halstead has pumped out some decent results in a tough year:
Exec Chairman comment:
"Against the backdrop of difficult markets, we are pleased to have raised profits underpinned by improved margins and reductions in overheads. We remain confident of the Group's medium-term prospects, despite short-term confidence weakness in Europe, and anticipate another year of progress.''
The decline in revenue is attributed primarily to "restrictions on government spending in several key markets".
In the UK (43% of turnover), sales were flat. By contrast, central Europe was down 8% and Australia was down 12%. North America was up 7%.
The accounts are presented cleanly and the company records cash inflow from operations of £25m, although this is down on the prior year due to increased inventories.
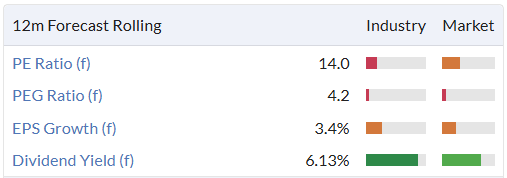
Cash stands at £63.7m and the dividend increases 10%.
There's an impressive yield:
Outlook excerpt:
[Restricted government spending] will change, we believe, over the course of 2025 and we would expect to see a stimulation to sales. Additionally, the UK housing sector has continued to be subdued but the reform of planning and mandatory targets should pave the way to push through the acute housing crisis again giving us confidence in improved demand.
We are pleased to see that H2 has started well and in January 2025 UK sales, which are the bedrock of the Group, were 9% ahead of the comparative.
Graham's view
The note re: inventories has caught my attention and I see that inventories finished H1 at £87m. Revenues in the prior year were £274m to give some context; it's worth bearing in mind that inventories are a significant drain on cash but I wouldn't yet be concerned by this factor. The company cites shipping delays and launch stocks being needed for new ranges and these strike me as reasonable explanations for a relatively small year-on-year increase in inventories.
Paul was GREEN on this last October and I do respect Halstead's solid track record, the strong balance sheet, the clean accounts and the family-based ownership with family members still running the company.
If its growth prospects were similar to LTHM I'd probably be AMBER/GREEN on this one too, but given that Halstead's UK sales are up 9% in H2 and earnings forecasts on the StockReport do suggest some growth is on the cards, I'm happy to leave the GREEN stance unchanged.
With that said, I end the report here. Cheers!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Thanks for covering James Halstead (LON:JHD) Graham. Just to let you know in title of the review you have it as amber/green but in conclusion you have it as green.
Fixed it Barbara, thanks for letting me know! G
Great to see a balanced and positive write up on Everplay (LON:EVPL) . Onwards and upwards me hopes. Such low P/E and PEG ratings agqinst others in the sector.
Just noticed Spire Healthcare (LON:SPI) up 4% on a grant of options award seems a bit odd to be up a tad on such an rns anyone brighter than me have any thoughts ?
Thank you Graham for taking your time looking over inpp,.
It's very much appreciated especially with the amount of companies that you all have to cover .
Graham: for some reason, BAG and EVPL are not included in the "Securities Mentioned" side-bar
Martyn
they should be there now Martyn!
hi Graham,
A G Barr (LON:BAG)
This Glasgow-based drinks group was previously on my small-cap watchlist. I rather meanly removed it due to its recruitment last year of an unlucky CEO.
I can think of a few more appropriate adjectives than 'unlucky'.
Snazzy
such as?!
I couldn't spell that out on here but I'm sure you would have a good idea.
It's difficult to understand how he manages to keep getting high profile jobs with his dismal track record.
AIM up 9 days of the last 13. Could the worm be turning....?
Certainly not reflected in my portfolio
Norges Bank goes over 3% in CARD ahead of results next month
Which platform do you find the most uptodate and accurate for values of what Norway's oil fund is investing in?
Quite amused this morning to see the Ricardo (LON:RCDO) RNS include ”The Board believes Science Group's actions are being taken solely for the benefit of Science Group and its own shareholders…”
As a business, that’s exactly what Science (LON:SAG) should be doing!!
If the Ricardo (LON:RCDO) management had successfully pursued the same goal, they wouldn’t be in their current mess.
National World (LON:NWOR), who last month agreed to a takeover offer from a unit of media company Media Concierge (Holdings) Ltd, have confirmed today that they have now received an approach from Eldridge Media Holdings (EMH), owned by soccer club Chelsea's co-owner Todd Boehly, regarding a possible takeover offer. A bit late in the day I would suggest but interesting none the less (I hold)
I may as well throw in requests for LSL Property Services (LON:LSL) and James Latham (LON:LTHM) which posted FY results and a trading update respectively this week.
I continue to be amazed by the seemingly low valuation of the former, which has:
All divisions are profitable.
Am I missing something?
ref a comparison of the formerwith Mortgage Advice Bureau (Holdings) (LON:MAB1), Momentum perhaps? I do hold MAB and it's a Mid Cap versus a Small Cap.
James Latham (LON:LTHM)
Thanks for the write-up Graham.
Have a nice weekend.
A
James Halstead (LON:JHD)
I second BnB's request, if you have time. I opened a position yesterday for the reasons explained in my previous post.
I’ll third that. They haven’t been this cheap for 11 years.
JHD - They certainly look cheap versus where they normally trade, but not sure they look especially cheap on an absolute basis - looks to be around 13-14 time earnings.
JHD if you can find some time please Graham.
JHD if you can find some time please Graham.
The last time JHD was priced these levels, EPS was 25% lower and the dividend only half the size. It wasn’t growing appreciably back then either, so I guess you could say it is cheaper now. And much cheaper relative to interest rates which were lower back in the middle of the last decade, ie on an even playing field the valuation would be much higher today. It certainly seems to be just an income play, albeit a solid one. Some commentators are wondering about a cyclical rebound, but there’s nothing in the company’s forecasts to suggest they expect one.
Hi Bnb
James Halstead (LON:JHD) I think brokers forecast might be somewhat on the conservative side. Given the company's reference to delayed spending.
"Despite this, the backlog of refurbishment and increased capacity of hospitals, schools, prisons and other government buildings is well reported and it can only be delayed not cancelled. Demand for aged care (a core sector for our flooring) is expanding with demand for places outstripping supply with new capacity likely to follow. Our ongoing expectations are for increased sales in the UK."
It is also likely to be a beneficiary of the recent decision of the German government to launch a 500 billion euros infrastructure fund, although such benefits are a few years down the line. Also it appears that the majority of capex has already been accounted for.
"Completed previously announced capital expenditure programmes across our Teesside and Radcliffe sites to upgrade production capabilities"
South America looks to be a promising market for expansion. So all in all I am happy with my initial purchase.
WH Smith (LON:SMWH)
Morning Graham, I am surprised that there is no mention of the agreed sale of the High St business to Modella Captial. Gross cash proceeds of £52m appears modest, but in the current climate it is a monkey off the company's back, allowing management to focus on the successful travel division.
It would be lovely if the team could use this as an opportunity to take a look at WH Smith (LON:SMWH). I haven't had a chance to properly digest today's news but some general points on the business:
- The travel business offers good growth at a modest p/e (in both historic and absolute terms). Last year the travel business had like-for-like revenue growth at constant currency of 12%
- Removing the highstreet business will have removed the equivalent of 15% profits in the last recent financial year so today's sale needs to be seen in that context. (Although it was representing an ever decreasing percentage of overall revenue and profits).
- More negatively, I thought the interest rate they're paying on the new debt looked unfavourable.
Just a short note on SMWH from me today Tortoise, see the table above. For more background see our coverage in January.
Naked Wines has ‘turned a corner’, says Panmure Liberum
Panmure Liberum has upgraded Naked Wines (LON:WINE) on the back of a ‘sound’ new strategy.
Analyst Wayne Brown moved his recommendation from ‘hold’ to ‘buy’ and increased his target price from 50p to 150p on the online retailer.
‘Investors need to pay attention – Naked Wines has turned a corner,’ he said.
Brown noted that it is now free cashflow positive and the company has a plan to achieve three things: significantly build cash on the balance sheet to more than £100m over the next five years; return the business to 5-10% revenue growth while underpinning earnings at £10m in the near-term; and commit to distributing this cash to shareholders.
‘All this is being achieved while improving returns, and deploying a new marketing plan that offers the opportunity to deliver sustainable growth,’ said Brown.
‘With cash much greater than the current market cap of £45m we see huge upside to the share price.’
The shares were trading up 28% at 80.5p on Thursday afternoon, and have risen 40% over one year.
Interesting view eParo. I see the strategic review includes "liquidating £40M of excess stock". Sounds like a big night out. They also trimmed £28M last year.
I'm no expert, but it feels like maybe people are buying less wine? Liquidating replacing selling to more customers & customers drinking more?
Or are Naked getting better at turning it over, while turnover declines? The commitment to shareholder returns is nice. But what happens when the excess stock runs dry?
I don't see this being covered in the daily report today or yesterday. Was there a reason, or was it just missed out?