Daily Stock Market Report (Fri 28th August 2026) - WJG, GDWN, SOM, EMAN, SYS1/BBSN

Good morning and happy Friday!
News has been quiet overnight, but one interesting piece of corporate news is that Stripe and private equity firm Advent have reportedly given up on their planned takeover of PayPal Holdings (NSQ:PYPL).
Paypal shares are lower by 14.6% in overnight trading, but still higher than they were before the proposal was officially announced in July.
Stripe is valued at about $159 billion in the private market, c. three times PayPal’s market cap. I imagine that it envied PayPal in its early years - but it's now a far more successful business.
Overnight market movements:
The FTSE is up 0.1% at 10,810
S&P 500 is down 0.1% at 7,720
Brent crude (November) is down 0.4% at $88.20/bbl
Gold is down 0.6% at $4,575/oz
Bitcoin is down 0.5% at $79,700
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
HUTCHMED (China) (LON:HCM) (£1.62bn | SR16) | New Drug Application for fanregratinib has been granted conditional approval by the China National Medical Products Administration for the treatment of adult patients with intrahepatic cholangiocarcinoma. | ||
Goodwin (LON:GDWN) (£1.37bn | SR32) | Revenue £280m (2025: £220m). Operating profit £78.6m (2025: £37.1m). Dividend to increase 18% to 330p. “The proposed disposal includes Goodwin Steel Castings Limited, Goodwin International Limited, Noreva GmbH, Easat Group and Pumps. The sale process is progressing well…” | AMBER = (Graham) | |
Caledonia Mining (LON:CMCL) (£363m | SR61) | Blanket Mine M&I Resources Increases by 22% & Maiden Mineral Resource Estimate at Motapa | Blanket: 22% increase to the underground measured and indicated mineral resource estimates to 2.178 million ounces of gold. Motapa: Maiden measured and indicated mineral resource estimate of 7.8 million tonnes at a grade of 1.51 g/t, containing 379,000 ounces of gold at a cut-off grade of 0.5 g/t. | |
Halo Minerals (LON:HALO) (£358m | SR8) | AIM admission raised £4m. Continued advancement of the Company's flagship Playa Verde copper and gold tailings reprocessing project in Chile. | ||
McBride (LON:MCB) (£291m | SR84) | Strategic partnership securing two long-term contract manufacturing agreements with E.H. Group B.V. ("Vestacy"), the global home care company behind brands including Air Wick, Calgon, Cillit Bang and Mortein. Transaction to be materially earnings accretive. | ||
Andrada Mining (LON:ATM) (£139m | SR30) | Financial Results For Year Ended 28 Feb 2026 & Board Changes | Revenue up 34%. Operating loss improved to £2.6 million (FY2025: loss of £3.9 million). Operating Cash Flow increased by £8.7m to £4.7m (FY2025: loss £4.0m). “Andrada enters the next phase of its development from a materially stronger position.” Changes to NEDs on the Board. | |
Somero Enterprises (LON:SOM) (£124m | SR94) | SP +6% Amendments to the company’s bylaws (bringing them closer to UK standards). Search ongoing for a new NED. Executive Vice President of Sales will transition from the Board and assume the title of Chief Commercial Officer. | AMBER/GREEN = (Graham) [no section below] I'm leaving Roland's AMBER/GREEN stance from July unchanged. But it's worth noting the scale of investor dissent here, after all resolutions at the June AGM saw a majority of votes against them. As Somero is a Delaware company, some of these resolutions managed to get passed anyway (the resolutions for the re-election of Directors). Somero said that the other resolutions, such as those ratifying the Annual Report, did not need to be passed under Delaware law anyway. Today's announcement helps to bring Somero in line with some UK governance standards, which means that future nominees will need a majority of votes rather than merely a plurality. I continue to have doubts about Somero's competitive positioning, but I don't see any need to adjust our stance on the back of today's update. | |
Borders & Southern Petroleum (LON:BOR) (£109m | SR60) | Welcomes the recent news from Navitas and Rockhopper regarding the accelerated development of Sea Lion. | ||
Everyman Media (LON:EMAN) (£51m | SR56) | New NED as another steps back for health reasons. “The Board continues to engage with stakeholders regarding the potential cancellation of trading in the Company's ordinary shares on AIM… A further announcement in relation to a Delisting is expected to be made in due course.” | RED = (Graham) I continue to view this as a "Heads we win, tails you lose" situation, with the threat of a delisting looming over small shareholders. We first learned of the desire of several board members to delist the company in June. What's odd is that the company might finally be about to post some good results, e.g. the H1 update in July showed admissions up by over 20% and adjusted EBITDA up by 32%. The statutory numbers at Everyman have always been poor but I'm wondering if that might be about to change - and if there could be some connection between that and the timing of the delisting proposal. Whatever the truth of the matter, I think it's generally the right call to avoid a stock where the directors and the major shareholders no longer want it to be listed, unless we are truly content to own unlisted shares. So my RED remains in force. | |
Watkin Jones (LON:WJG) (£46m | SR38) | SP -8% “…the Group has been engaged with investors on a small number of transactions with the potential to conclude in Q4… the Board has concluded that it is now unlikely that all of these transactions will be finalised by the year end. As a result, the Group is expected to deliver adjusted operating profit for the full year at a similar level to H1.” | PROFIT WARNING (AMBER/GREEN=) (Graham) | |
System1 (LON:SYS1) (£43m | SR67) | “The Board does not see the Revised Offer or the Alternative Offer as representing an acceptable fair value for all shareholders and, as a result, the Board of System1 continues to unanimously and unequivocally reject the Cash and Share Offer and the Alternative Offer.” | TAKEOVER (rejected by the Board) (Graham) [no section below] | |
Kr1 (LON:KR1) (£24m | SR15) | Aggregate infrastructure income (year-to-date, unaudited): £587,625. NAV £31.4m, NAV per share 17.7p as of July 2026. | ||
FIH (LON:FIH) (£23m | SR52) | Revenue from continuing operations of £37.4 million (up £0.8m). Pre-tax loss from continuing operations was £2.9 million (2025: £7.2 million loss) including non-trading items. Underlying pre-tax loss £0.3m. Post-year end, announced a £7.6m disposal. | ||
Power Metal Resources (LON:POW) (£14m | SR40) | On-site work has now commenced at POW’s 100% owned Tati Gold Project located on the Tati Greenstone Belt near Francistown, Botswana. | ||
Tekcapital (LON:TEK) (£9m | SR45) | Guident CORP, a leader in autonomous vehicle remote monitoring and human-in-the-loop operations, has announced a strategic collaboration with Florida State College at Jacksonville. | Reach announcement - non regulatory press release. |
Graham's Section
Watkin Jones (LON:WJG)
Down 8% at 16.55p (£43m) - Graham - PROFIT WARNING (AMBER/GREEN =)
I already looked at this at the end of July, saying (if you can forgive me for quoting myself):
Despite my lack of confidence in the ability of the company to hit forecasts, I’m inclined to leave our AMBER/GREEN stance unchanged here. My reasoning is simple: our AMBER/GREEN stance, at least as far as I’m concerned, is a view on the balance sheet, not earnings.
The share price that day was 18.2p.
The company said then that it was working on “a small number of transactions”, and that these would have to conclude in Q4 (i.e. by the end of September) in order for the company to grow its operating profit in H2. This seemed highly uncertain, and I assumed there was “at least a 50% chance of a profit warning”.
Surprise, surprise: today we have that profit warning.
As set out in the Q3 trading update, the Group has been engaged with investors on a small number of transactions with the potential to conclude in Q4. Whilst investor engagement in each of these schemes remains active, the Board has concluded that it is now unlikely that all of these transactions will be finalised by the year end. As a result, the Group is expected to deliver adjusted operating profit for the full year at a similar level to H1.
Adjusted operating profit in H1 was only £0.4m, and so the company is not going to generate very material profits this year.
(One bright spot in the H1 report was the lack of any adjustments - hopefully we’ll see the same in the full year?)
You could be forgiven for thinking that the delayed transactions will go straight into the FY27 result, and that FY27 forecasts should therefore be raised on the back of this update. This rarely happens in practice - but I'd still hope that FY27 would be slightly more resilient.
Estimates at Progressive have been reduced. Revenue gets cut all the way from £272m to £223m, and adj. operating profit gets cut from £6m to around breakeven.
A few other titbits from today’s update:
Provisions:
We have made further progress on our building safety rectification obligations with four projects currently on site of which two buildings are expected to be completed in FY26. The Group's provision will continue to be kept under review, reflecting ongoing building investigations and discussions with owners and supply chain.
The company’s building safety provision was £38m at the interim result, after being discounted to its present value. It’s expected to be incurred over four years. This is a legitimate source of uncertainty. WJG said it was “in discussions with a number of property owners whereby the legal responsibility or confirmation of fire safety remediation requirements remains uncertain”.
Cash: year-end net cash is expected to end FY26 above the £61m figure at the half-year report. Progressive had a £76m forecast, which they have today reduced to £63m.
Graham’s view
At a market cap of only £43m today, I’m going to ignore the profit warning as far as our colour rating is concerned.
I very rarely do this. Here at Stockopedia, we respect PEAD (post-earnings announcement drift). Positive surprises lead to positive drift, and negative surprises lead to negative drift.
But as I said one month ago, I no longer think that earnings are particularly relevant for Watkin Jones, at least not in the short-term.
It’s true that eventually, it will need to either earn a real profit or return capital to shareholders.
But as far its fundamental value is concerned, this is primarily a balance sheet play, in my view.
Net cash exceeds the market cap. If we deduct the present value of the building safety provision from the cash forecast, we are still left with a “net net” cash figure of £25m.
But cash is not the only asset on the balance sheet. The March 2026 figures showed the company having equity of £125m, of which only £10m was intangible. Indeed, most of the company’s assets are considered "current" and have real, easily measurable value: there's £92m of inventory/work-in-progress, £28m of "contract assets", £29m of receivables, etc.
Therefore, I’m going to leave this stubbornly on AMBER/GREEN. I’m not fully GREEN because any deep value investment can require a lot of patience, and it’s not clear to me what the catalyst might be for the share price to start reflecting fundamental value here.
There’s also some uncertainty around building safety provisions, which could eat into a chunk of value.
But overall, I continue to like this as a deep value play. Today’s profit warning doesn’t come as a surprise, so I don’t see why I should have to change stance.
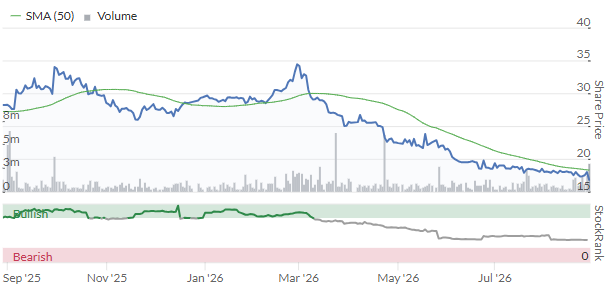
It's an ugly chart, which goes with the territory when it comes to deep value investments:
Goodwin (LON:GDWN)
Up 7% at £194 (£1.46bn) - Graham - AMBER =
There are some excellent comments today from readers, including from John Smith who points out the slightly bizarre sequence of events here in terms of news flow.
Goodwin is a family-owned engineering business. Many value investors (including myself) love family businesses. We like businesses where the founders, or their descendants, continue to own and run it. This can help to create a wonderful alignment between management, the Board and external shareholders. Everybody is in it for long-term success rather than short-term gains.
But there are downsides to this, and I think Goodwin helps to highlight one or two of them.
There is no question that it has been a roaring success for its shareholders over the long-term.
But over the last year, strange communication has created an (unnecessarily?) volatile share price chart:
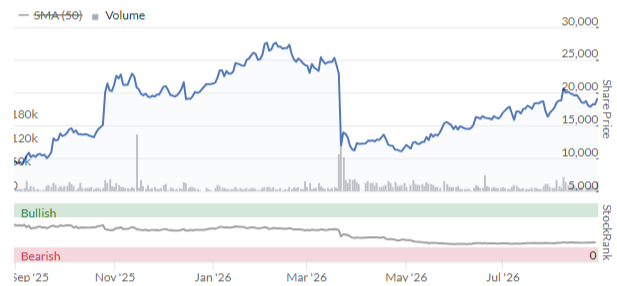
“Buy-and-forget” investors won’t have worried about this too much. But most of us feel like we want to have some idea about how our investments are doing. And in the case of Goodwin, unorthodox communication created an information vacuum in which confusion reigned.
This is a business which eschews providing investors with normal forecasts:
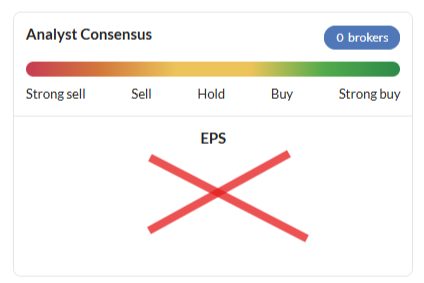
Personally, I don’t have a big problem with that. But it does mean that anybody getting involved here needs to accept that neither the company itself, nor the City, might help you very much to understand what results might look like from one year to the next.
The announcements to the LSE are all we are given, and anything else you need to work out for yourself.
And if these announcements are all you rely on, you could be forgiven for being confused.
In March, the company announced a horrible profit warning. The share price crashed 35%, to £150 per share - given that this company’s worth is now measured in the billions, it was a pretty significant financial event!
Maybe TJW Goodwin got up on the wrong side of bed the day he wrote that trading update, but there was barely even a sliver of good news to be found in that update. The Iran war was not even a month old at the time - maybe he was particularly worried about that? He even suggested cutting the dividend policy, “given the escalating Gulf situation and the broader economic environment.”
Fast forward to today’s results for FY26, and we get the following:
Revenue up 27% to £280m
Trading profit up 118% to £77.5m (the company did previously tell us that this would be in excess of £71m).
Dividend up 18% to 330p.
And everything is rosy in the garden:
Whilst there has been growth in all our manufacturing companies, the Mechanical Engineering division in particular has continued to experience a substantial increase in customers' demand for precision-machined, high-integrity castings into mission critical defence and nuclear applications… Goodwin has positioned itself to be a leading supplier on many UK and US Navy frigate and submarine programmes.
Disposal: the company acknowledged earlier this month that it was looking at options including “the potential sale of a substantial part of the Mechanical Engineering Division".
There’s an important update on that front today:
The significant improvement in the performance of the Mechanical Engineering division… has substantially enhanced its strategic value and generated considerable external interest… the Board committed to pursuing a potential disposal of a substantial part of the Mechanical Engineering Division and appointed Rothschild & Co as its financial adviser to initiate an active sale process of its constituent business units… The proposed disposal includes Goodwin Steel Castings Limited, Goodwin International Limited, Noreva GmbH, Easat Group and Pumps.
This looks to be the majority of the entire group.
With Mechanical now classified as a “discontinued operation” (because it’s up for sale), the company breaks out its FY26 performance as follows.
Continuing operations (Refractory & Technological): revenue £69m, trading profit £10m.
Mechanical: revenue £211m, trading profit £67m.
As you can see, without Mechanical, Goodwin would be left with a much smaller and less profitable group. They say that they would have “a simpler, more focused portfolio of specialist businesses with strong market positions and attractive long-term growth prospects”.
Net debt: £29m, after paying out a £40m dividend.
Outlook: no outlook statement, as usual.
Estimates: no estimates. Shore Capital provides some coverage, but not in a forward-looking manner.
Graham’s view
I raised our stance on this to AMBER when news of the potential disposal was confirmed. They have a target to complete this transaction in the next 12 months. I'm guessing there could be some large, well known defence/industrial concerns examining this opportunity.
As far as my stance goes, I don’t think I can do better than AMBER on this again today.
Earnings per share for FY26 are 738p, which puts the shares on a trailing P/E multiple of 26x.
The FY27 outlook presumably remains clouded by the issues raised in the March update.
The wildcard is the potential disposal price for the Mechanical division. What might a suitor pay for this? Presumably quite a lot, if external interest has motivated the company to sell. But I don’t really believe in buying shares just because a takeover is considered likely, especially when any potential takeover price is still a mystery.
So for me, the picture here remains as cloudy as ever, and the colour is AMBER.
The StockRank takes a harsher view, calling it a Falling Star:
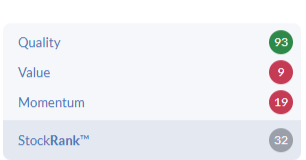
Goodwin may reward detailed research, and it has rewarded its long-term shareholders handsomely for many years. But for me, I’m afraid that it remains inscrutable.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Goodwin (LON:GDWN)
Majority shareholders (that’s the people running the company) have realised that they cannot sell all their shares.
They want an exit and this is the only way possible……
Crystal clear!
All the best
Re Goodwin (LON:GDWN) I’d point out a few things that may help render it more scrutable
Firstly when a business has just reported profits that have increased 118% it doesn’t make the Stockopedia definition of value (which are on a trailing twelve month basis) and thus yet to reflect today’s results at all the obvious yardstick to use….and especially so as there are no f’casts either.
Secondly I’d suggest confusing cause and effect if you’re characterising the March TU as a profit warning….it literally started out by confirming that expectations would be met…before descending into a laundry list of things that ultimately never happened or didn’t impact at all or were frankly immaterial. Bizarre IR but decidedly not a PW …just a curiosity of an RNS.
Thirdly this business has a long history of re-inventing itself and thus the likely disposal of GI & GSC is this writ large. I would add that for the family to be doing this the price must be highly attractive and the opportunity set they’ve pivoted towards equally compelling….and in particular Matthew & Bernard Goodwin will be free to spend more time scaling Duvelco around the world. This has long been identified by the company as the largest market niche they’ve entered and also a niche where their offering has some uniquely compelling properties that they see offering even higher margins than defence/nuclear . Building commercial scale Duvelco plants is obviously not straightforward…but equally obvious is that they believe they will get there.
AVD has always looked like a patented product where a combination of efficacy and insurance company stipulations will deliver an impressive global business over time…they’ve already got some 65 distributors all over the world signed up. The product is 90% water so it isn’t hard to believe that margins will be somewhat satisfactory. The narrative today around Soluform was also encouraging as it was for the wider refractory group.
We will only be able to judge this pivot through the price achieved & what comes to fruition in the years ahead. It is by far my largest holding so my bias is off the chart but I see no more interesting company in the U.K. listed company arena.
Brilliant Rhom..
I know you're an expert analysing this company. What do you think the sales proceeds could be?
I wouldn’t want pull a number out of thin air because it would look a touch too toppy to be real…not least because next year is a nailed on humdinger for them
Thank you Graham for your coverage of WJG, I feared it might drop a notch from Amber Green. I'd noticed Octopus Investments sold 3 million shares before the HY update which is rarely a good sign. Nice to see the Non Exec Chair put £33,000 in this morning at 16.86p per share, I should have waited, I bought a lot less but paid 17.50 p for ours. I've learned enough on here to stop doing what I've just done but before the brickbats come, we've also had some good profits using the traffic lights and stock ranks, of which Ramsdens is currently close to payout time.
Hi Graham et al,
As always, a big thank you for the excellent analysis and commentary — it’s really valuable and much appreciated.
One small suggestion that I think would make the daily report even more useful would be to include a little more information in the initial agenda before the market opens. For example, it would be helpful to know, against each company, whether commentary is planned for that day (and perhaps whether it is expected to be brief or more detailed), together with an indication of when the full updates are likely to be published.
I completely appreciate that the analysis takes time and that timings can inevitably change during the day. It would simply be useful to have an indication of what is planned so that I can:
Even a simple indication such as “commentary planned — expected this afternoon” would be really helpful in managing expectations.
Thanks again for all the work that goes into these reports — this is intended as a small usability suggestion to make an already excellent daily resource even better.
Have a great weekend!
Fair point I think.
I quite often wonder whether there will be an analysis or a comment on a company on the early doors spreadsheet .
It’s not a deal breaker or anything as I usually check back at lunchtime anyway and in the end we get what we get.
Comes under nice to know I suppose, and I wouldn’t want to add to workload of the analysis team who do an amazing job in such a short time span.
Great idea TS23. I'll implement that from next week! Cheers. G
Goodwin (Goodwin (LON:GDWN) has reinvented itself several times over the last century and a half as Alex Sweet explains in his excellent substack (https://sweetstocks.substack.com/p/goodwin-plc-breaking-good) . Nevertheless, it is sad that the bulk of a great British engineering success story, is now likely to end up either owned by a foreign buyer or a p/e firm with a short term time horizon. Hard to believe a UK trade buyer will step in to buy a company whose heavy casting products are critical to the UK and US defence industries.
Lord Lee, in his latest Investor Chronicle podcast, also notes that 3-4 members of the Goodwin family went offshore some time ago, presumably for tax reasons. They will be far better placed than the rest of Goodwin’s private shareholders who will face a hefty CGT bill, especially if the Labour Governments bows to the pressure to bring CGT rates in line with income tax rates.
Yes, interesting. Jersey x 2, Italy and Switzerland notified to Companies House in April.
I would like to make a scathing comment but they are just doing what I do with my ISA's, albeit on a far grander scale.
How to explain the bizarre contradictions between the March update from Goodwin (LON:GDWN) and the commentary provided in today's results announcement?:
Dividends:
In March, the Board said it was weighing whether to revert to the old policy (38% of post-tax profit plus D&A) "or to a lower level should this be considered appropriate given the escalating Gulf situation and the broader economic environment" — explicitly floating a cut, citing geopolitical risk. Today's statement announces a 330p dividend, up 18% on the prior year, with no acknowledgment that a lower payout was ever on the table. The "prudent," risk-conscious framing simply vanishes.
The tender losses are framed as damaging in March, then simply disappear. March calls Goodwin International's loss of the £45m Sellafield bid and Easat's loss of the ~€18m Estonian radar contract "disappointing" and "unexpected," specifically flagging pressure on the Mechanical Engineering Division. Today's results describe that same division's year as "excellent," with "substantial increase in customers' demand" for defence/nuclear work and Easat's profit jumping from breakeven to £4.5m — with no reference at all to how those lost tenders affected the numbers, positive or negative.
Refractory Division tone reverses entirely. March: "trading conditions remain broadly unchanged," gold/silver prices "weigh on confidence," and there's a vague warning about "the lack of confidence by the general public starting to colour their spending habits" — a soft, cautious framing. Today: trading profits up 15%, driven by a "wear once" consumer shift to low-cost brass jewellery that the March update never mentioned, plus a major win (largest US jewellery caster adopting X-SIL) that would have taken "many years" to land and can't have appeared from nowhere in six weeks, plus Hoben's "excellent year" and Soluform growth of 50%+. None of this positive momentum was signaled in March; instead consumer caution was framed as a headwind, not the driver of a growth story.
The scale of outperformance is hard to reconcile with the March narrative built around lost tenders, subdued consumer confidence, and a possible dividend cut.
The uber-positive trading update from last October precipitated a share price rise of over 30% followed a week later by massive share placings by various family members. The subsequent handbrake turn of an update in March which contradicted just about everything previously said in the October update, caused a precipitous collapse in the share price of almost 50% and then today's results are another remarkably contradictory framing of the trading situation. It's almost like the staid, old family firm has taken to Trumpian tactics of manipulation. With so much of the business up for sale, so little insight from the board and such inconsistency of presentation, it's pretty much impossible to value.
Yes, critical UK defence components are in the hands of off shore share price manipulators, allegedly. I'm shocked and stunned.
Have any Goodwin (LON:GDWN) experts come up with a plausible valuation for the mechanical division? It's beyond my abilities!
£69m operating profit assigned to it, almost doubling year on year. Assuming further growth this year could be looking at comfortably north of £1bn valuation assuming a PE of around 15.
An 18–22× Mechanical operating-profit valuation implies gross equity proceeds of roughly £1.19–1.47bn after the disposal-group net debt, equivalent to around £159–195 per current Goodwin share. If, illustratively, 75–85% were ultimately returned, that could mean approximately £119–166 per share in capital returns.
Vain hope I suppose that Smiths (LON:SMIN) will take on GDWN’s Mechanical. They’ve just sold a few bits and have cash, but also what is important they remain British with top class management. Would seem a fair fit with their GKN Engineering. But wdik. I hold both.
Mark Slater the renowned fund manager has just agreed to be one of our headline keynote speakers and Ed Croft will be giving us an all new presentation for the conference
There is a Bank Holiday Weekend offer with 25% off ticket prices for one or both days of MelloLondon
Just apply the code ML26Aug25 and it will reduce https://www.melloevents.com/mellolondon2026
Mark Slater - Renowned he may be - but his funds have produced disastrous results in recent years
bohenie, i just checked your comment. Slater Growth down 17.7% over 5 years, the FTAllsh up nearly 69%.
Worth listening to him to find out what not to do!
For many years his fund was one one of the top performing out there. Just shows how cyclical fund management is - you can have a great few years and then really struggle for the next few years. Usually because the type of shares they hold go in or out of style rather than because of any particular skill.
I think the real skill in being a fund manager is learning to adapt as the world changes.
This requires open mindedness and humility.
Difficult when you’ve had five good years, been paid a fortune and believe your a genius!
Well then there is probably something to learn from him.
Great minds think alike Chris.
He got some right...
Based on an interview with him during Covid I bought Hollywood Bowl (LON:BOWL) and Ten Entertainment Group. Did nicely!
Andrada Mining (LON:ATM) There's a new Zeus Note out this morning, which IMO is not unreasonably calling the "Turning Point" as they call it. No PT's or anything in this one athough I'm sure others will follow with theirs in due course.
Good morning Graham. What are you thoughts on McBride? They say this deal is transformational adding 15% to revenues and earnings enhancing.
I don't hold but am intrigued by the reaction.
Welcome a look at FIH after disposals ahead of first oil what are prospects and is valuation correct has been volatile
Does it still have some Rockhopper Stock? I thought it sold it some years ago. I guess trading conditions may change on the Island when drilling gets going though.
Thanks JASVFS and Crusty. Those do look like two of the more interesting announcements today for sure!
Would be grateful for opinions on Goodwin (LON:GDWN) . Seems a very positive update, but are they selling the golden goose? I hold a few.
Share your concerns re golden goose, but presume they know what they are doing (fingers crossed)… hard to reconcile this update with the alarmist one earlier in the year.
I would also like a review of their results
It would be interesting to know a range for the payment to shareholderers on sale, it could be worthwhile adding to recieve the sale proceeds?
I expect they will get a full price for mech eng and then concentrate their endeavours on Avd and Duvelco both of which have huge markets and both yet to fly.
very interesting times especially if they get £1.5bn or north for ME
Good morning Graham if WJG's FY update creeps onto your radar today I'd be interested to know if it keeps the Amber Green you left it with on its Q3 update 30/726? Nothing's really changed since your reasoning then, H2 is going to be the same as H1 but cash will be a bit higher than expected. This means its discount to net cash is higher too. I'm minded to add a few more to a losing holding at 8.00am on that basis.
Do you know how much of the net cash is spoken for by cladding provisions? When I last looked at Watkin Jones (LON:WJG) I was a bit put off that provisions seemed to keep increasing and made the net cash position look less rosy.
The last numbers I saw Tortoise were H1 26, where they reduced their provision to £38m from £46.4m as at FY 25. It is running though and therefore can change as investigations progress but also pursuing recovery claims against some of the cladding manufacturers which could offset. So I guess market will remain reluctant until more clarity comes due.