Daily Stock Market Report (Fri 2nd Oct 2026) - TPT, IGG, JDW

Good morning, we have a section Mark wrote yesterday on Topps Tiles (LON:TPT) to get us started today. Thank you so much for all your kind wishes and your patience. I'm sure I'll be back to normal next week!
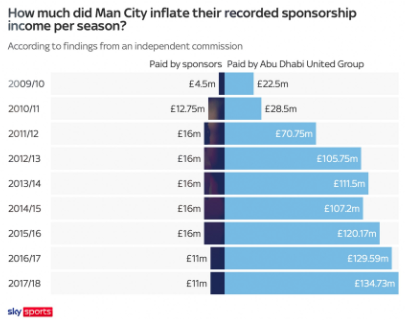
Man City scandal: I know some people don't like us discussing sport here, but the Man City situation appears to be a genuine financial scandal with over £900m of sham revenues and artificially reduced expenses, according to an independent commission. Man City will appeal all charges. But the bit that I find most interesting is that the auditors were fooled along with everyone else (except for the man on the street). Sky News published this graphic:
If a highly regulated and highly scrutinised organisation like a football club can get away with this sort of thing for so long, it does make you wonder what much smaller and less scrutinised organisations might be able to get away with.
Overnight market movements:
The FTSE is up 0.4% at 10,470
S&P 500 is up 0.3% at 7,690
Brent crude (December) is down 0.7% at $101.70/bbl
Gold is up 0.3% at $4,190/oz
Bitcoin is up 1.6% at $86,000
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£186bn | SR53) | AZ & DS collaboration with Summit for Datroway | AstraZeneca and Daiichi Sankyo have entered into a clinical collaboration agreement with Summit Therapeutics Inc. to evaluate Datroway in combination with ivonescimab across multiple tumour types including lung and breast cancers. | |
IG group (LON:IGG) (£4.25bn | SR83) | SP -27% Q3 2026 total revenue expected to be approximately £240 million, down approximately 14% year-on-year, reflecting lower OTC revenue retention. “The Board remains confident of meeting its medium-term guidance beyond 2026. | PROFIT WARNING (AMBER ↓) (Graham) At a market cap of £3.3 billion, I’m likely to continue holding this one. It’s a flaw: I can’t seem to sell any positions that I own. But I do think that a net income result well in excess of £400m is still very possible for 2027 (the forecast on the StockReport is £476m), assuming that revenue retention recovers. That is a big assumption, of course. But if it’s true, the forward earnings multiple is in the region of 8x. At this sort of earnings multiple, mishaps are to be expected. Super high-quality businesses with strong visibility don’t trade at 8x or 9x earnings (it was at 9x last night). I’m going to continue holding this one. But it’s not pleasant at times like this. | |
J D Wetherspoon (LON:JDW) (£858m | SR37) | SP +10% FY July 2026: LfL sales +4.2%. PBT -28% (£58.6m). Full-year dividend unchanged at 12p. Trading update: “In the last nine weeks, to 27 September 2026, like-for-like sales increased by 8.6%, helped, no doubt, by exceptional weather... At this early stage, we continue to anticipate profit before tax and separately disclosed items in line with current market expectations.” | AMBER/RED ↑ (Graham) [no section below] | |
Costain (LON:COST) (£675m | SR92) | Costain has been appointed on to Pagabo's Civil Engineering and Infrastructure Framework which carries an estimated total value of £4.29bn and will run for a term of four years to 2030. | ||
Capita (LON:CPI) (£273m | SR18) | Statement regarding the National Audit Office review of Civil Service Pension Scheme administration | "Capita has a long-standing record of cooperating with Parliamentary and regulatory investigations and will continue to engage fully and transparently with the NAO, Cabinet Office and relevant stakeholders... Capita accepts that performance remains below the standards that scheme members and the Government rightly expect. The remediation of CSPS remains the Group’s top priority." | |
Eco (Atlantic) Oil & Gas (LON:ECO) (£147m | SR15) | Ministerial Approval - Namibia Licences Farm-down | On 1 October 2026, ECO received formal Ministerial approval for the transfer and assignment, relating to the Company's previously announced farm down of a 60% Participating interest in all three of its Petroleum Exploration Licenses offshore Namibia to BP. | |
Bezant Resources (LON:BZT) (£31m | SR24) | Mine and processing plant construction completed ahead of schedule and within internal budgets. Commercial concentrate production has now commenced. Phase II expansion planning which is already underway focussed on a tandem processing plant with the capacity to increase throughput by up to 40%. | ||
Critical Metals (LON:CRTM) (£26m | SR32) | CRTM announces the start of its 2026 field programme at Molulu, following programme authorisation, funding release and mobilisation. | ||
Manolete Partners (LON:MANO) (£18m | SR53) | Successful completion of a large case in late September 2026, which was settled for £3 million. This settlement forms part of the Company’s expected realised revenues for the current financial year alongside realisations from its portfolio of other cases. The Board’s expectations remain unchanged. | ||
Pathos Communications (LON:NEWS) (£17m | SR28) | Pathos has been recognised in the Financial Times as one of the UK’s fastest growing companies, and the fastest growing British company in its sector. |
Backlog
Topps Tiles (LON:TPT) (by Mark Simpson)
Down 2% at 35p (£70.5m) - Full Year Trading Update - Mark - AMBER/RED =
Revenue is down slightly here, but as they are keen to point out, there are good reasons for that:
Group revenue, including CTD, was c.£292 million for the year, down c.1.3% year on year, reflecting the annualisation of prior-year CTD store closures and the previously announced closure of underperforming Topps Tiles stores.
LFL revenue is largely flat, but this should probably be considered a good result, given the market backdrop:
Group revenue, excluding CTD, was c.£267 million, up c.0.7% year on year despite challenging market conditions. Topps Tiles delivered resilient like-for-like revenue3 down c.0.1%, with fourth-quarter trading affected by periods of extreme heat. Like-for-like sales improved in September and Topps Tiles continued to outperform the wider market4, which declined by approximately 1.7% over the financial year.
Pro Tiler Tools, the company’s online specialist supplier of tiling tools, consumables and equipment, aimed mainly at professional tilers, was the bright spot, growing revenue 18%.
Overall, the company expects Adjusted PBT for the full year to be in line with current market expectations and helpfully gives these as £6.6m, with a fairly tight range of £6.5 - £6.7m. This looks to be from two brokers: Zeus at £6.7m and Edison at £6.5m. As an aside, it is good to be able to see the notes here. I was previously critical that the company chose a broker where individual investors couldn’t see the numbers. This looks to have been corrected, with two notes now available to all investors.
This isn’t particularly impressive, as it comes in significantly below last year’s £9.2m adjusted PBT, but again context is everything. This represents a bottoming of the recent downgrade cycle:
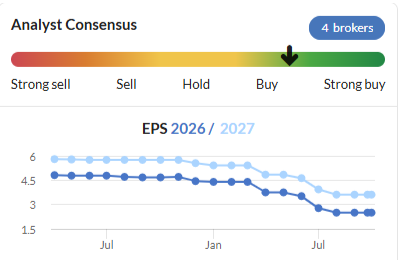
The company makes no statement about FY27, meaning that we are left to judge for ourselves how likely the modest forecast recovery is. Their broker, Zeus, mention the possible positive impact from the new help-to-buy style scheme, but don’t expect any short-term benefit.
Valuation:
Zeus sum up where the company finds themselves quite well:
The shares look expensive on depressed FY26E earnings, trading on 14.2x P/E, falling to 9.5x on FY27E, versus a sector average of 12.4x. FY27E growth is underpinned by self-help, though persistent input cost pressure is a risk and the market is unlikely to see significant volume growth until late 2027. We remain positive on Topps and our medium-term view is unchanged, with policy-led volume growth a potential upside rather than part of our base case.
The Stock Ranks largely back up that view:
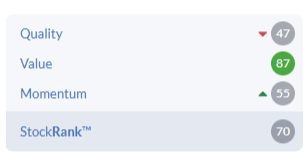
However, it is worth noting that the Value Rank is backwards-looking and may not look as strong when these reduced FY26 numbers are released and processed by the algorithms.
Mark’s view
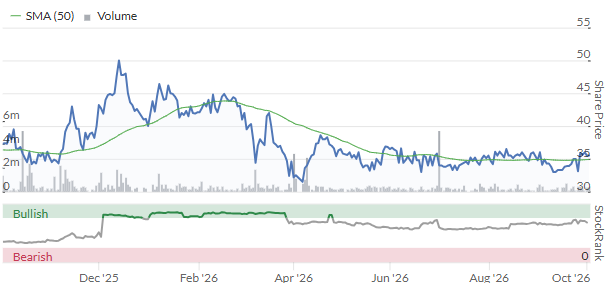
Like many building supplies companies, there is a strong argument that the company will look cheap whenever a cyclical recovery in the sector occurs. I have always viewed Topps as one of the best-run companies in the sector, and its niche gives it specific strengths. However, the market seems to have translated that into a near-term rating that is much higher than similarly struggling companies.
However, any short-term housing market recovery seems to have been largely derailed by rising bond yields that feed directly into the interest rates homeowners pay for fixed mortgages. Without this headwind, I may have been more comfortable suggesting that a recovery was more likely than a further decline. Now it seems that could go either way. I don’t see an as-yet-unconfirmed first-time buyer scheme for new builds having a huge impact on the market, beyond shoring up some shaky housebuilders.
Our previously slightly negative AMBER/RED view was shaped by two profit warnings this year. While this is not the third warning, and gives some confidence that trading may have bottomed, the lack of FY27 commentary leaves too many outcomes available for me to feel comfortable changing our view at this point.
Graham's Section
IG group (LON:IGG)
Down 22% @993p (£3.3bn) - Q3 Trading Update - Graham - AMBER ↓
[At the time of publication, Graham has a long position in IGG.]
I woke up a little poorer this morning, as one of my largest holdings was about to issue a serious profit warning.
The CEO opens the Q3 trading update like this (emphasis added):
Growth in first trades and active customers remained strong in Q3 2026. Lower Q3 revenue reflected reduced OTC revenue retention in less supportive market conditions, and I remain confident in meeting our medium-term guidance.
Lower OTC revenue retention means that spread betting was less profitable than it was previously: “Within OTC derivatives, revenue retention in Q3 2026 was approximately 70%, below the approximately 80% averaged since the introduction of market-making optimisation measures in H2 2025 to the end of Q3 2026.”
These “market-making optimisation measures”, in layman’s terms, I take this to mean that IG have been hedging less than they did before. They've described it as "Flexing OTC spreads to reflect changes in underlying market liquidity", "Increasing market risk limits for the most liquid instruments", and "Upgrading algorithms to lower hedging costs".
I’ve had a look through their 2025 annual report this morning to find an update on the amount of market risk that IG is exposed to. Historically, I seem to remember that the amount of risk it was exposed to was much less than 1% of the notional value of customer trades.
In a 184-page document, there is exactly one page focused on market risk (which I consider to be the key risk that the company has to manage). And this singular page doesn’t tell me anything very useful - only that IG has “predetermined, Board-approved, market risk limits” and that “scenario-based stress tests are performed on an hourly basis”. But I’m not left with any real understanding of how much market risk the company faces.
In a document of this size, which goes into great detail on all manner of things (including a 12-page “Sustainability Report”), I’m disappointed that there is so little information on market risk. Unless I’ve missed it somehow - please do let me know in the comments.
The reason I’m labouring this point is that the company’s exposure to market risk is exactly what seems to have triggered the drop-off in profitability in Q3.
Here are key points from today’s update:
- Q3 revenue is c. £240m (of which trading revenue is about £210m), down 14% year-on-year, due to lower OTC revenue retention. OTC trading revenue is down 18% year-on-year due to the lower revenue retention mentioned above.
- 2026 total revenue growth now expected to be in a mid-single-digit per cent range year-on-year
- Q3 organic first trades up 25% year-on-year, organic active customers up around 17%
And Underdog traded strongly with net revenue up >100% year-on-year to approx. $105m.
Looking ahead, they remain confident in their market-making optimisation measures:
As previously guided, the Board remains confident that these measures will structurally increase OTC revenue retention over the medium to long term, albeit with greater expected short-term variability.
Estimates
Total revenue had been expected to grow from £1,090m (2025) to £1,253m (2026), an increase of 15%.
If this now only grows by 5%, that’s nearly £110m of lower revenue than they had previously been expected.
There will also be significant non-recurring costs: £30m to do with redomiciling and restructuring, and more to do with the acquisition of Underdog. So I don’t expect a good statutory result.
Graham’s view
This profit warning has been caused, in my mind, by the company’s voluntary decision to take a riskier path when it comes to hedging.
I have managed to find this chart in the company’s FY25 results presentation:
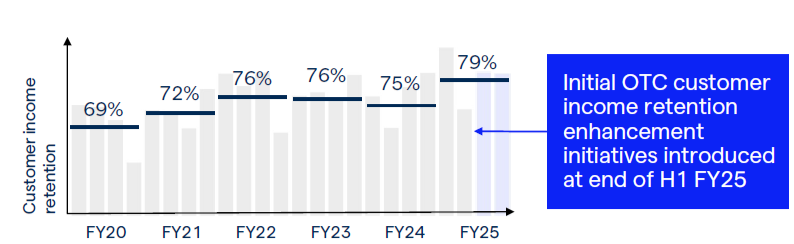
As you can see, OTC revenue retention was 69% to 76% (or even higher) before the changes were implemented.
It then rose to 80% in H2 FY25 and H1 FY26, before dropping back to 70% in the most recent quarter.
This chart shows how they expect higher retention on average with their new policies, but with fatter tails:
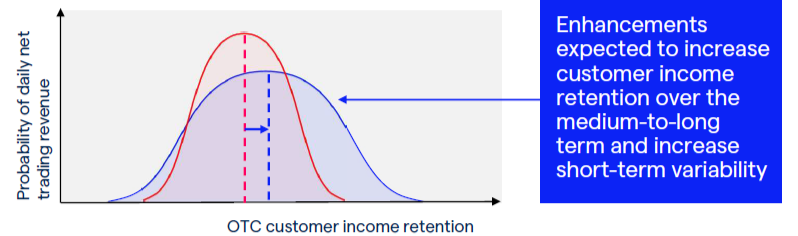
I actually don’t have a problem with this, if it turns out to be an accurate model over the long-run. But it’s a little difficult to have faith in it when it has helped to bring about such a serious profit warning, only about a year after implementation.
Roland took us down to AMBER/GREEN after the acquisition of Underdog. I’ve already stated this, but I do not approve of that acquisition. And so I agree with Roland’s decision that day.
Today I’m taking us down to a neutral stance.
The critics of this industry have always maintained that they suffer from a lack of visibility: that customer churn and volatile trading patterns make it impossible to predict results with confidence.
I’ve never thought that was incorrect. But I’ve been happy to invest for the long-term, on the grounds that the long-term trajectory for companies like IG will be upwards.
Unfortunately, more patience is going to be required. With (I think) £100m+ dropping off the revenue forecast, along with various non-recurring costs, the 2026 net income result will be dramatically lower than the £424m forecast that is visible on the StockReport.
At a market cap of £3.3 billion, I’m likely to continue holding this one. It’s a flaw: I can’t seem to sell any positions that I own. But I do think that a net income result well in excess of £400m is still very possible for 2027 (the forecast on the StockReport is £476m), assuming that revenue retention recovers. That is a big assumption, of course. But if it’s true, the forward earnings multiple is in the region of 8x.
At this sort of earnings multiple, mishaps are to be expected. Super high-quality businesses with strong visibility don’t trade at 8x or 9x earnings (it was at 9x last night). I’m going to continue holding this one. But it’s not pleasant at times like this.
Adding insult to injury, IG announced a £125m buyback programme in March. Thankfully, they only spent £33m before it was cancelled to save cash for the £1 billion purchase of Underdog. But I’m concerned that both that proposed buyback and the purchase of Underdog were not very good uses of cash. With market risk then coincidentally turning against them soon after these decisions, it is becoming harder to keep faith in current management.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Sold my CMC Markets (LON:CMCX) shares yesterday when they briefly came back to only a 5% loss on the day.
They were a NAPS holding, and I know Ed says you need to hold for the full 12 months, but with only 2 months to go, and the Stockrank falling to close to another of Ed's suggestions, sell when it falls below 70, I decided to bank my one bigger gains and wait until a new Naps starts (for me) in December.
I may miss out on a bounce, but would I buy them today based on the NAPS criteria, no.
I think this is a great way to think about these things. The quant part gives you a baseline for the type of stocks you should be looking at, then the discretionary part allows you to choose a diversified selection to avoid undue concentration. Then a quant/discretionary process allows you to exit, either when things go very wrong, very right or when it reaches a set time period. You get the best of both worlds.
lnteresting debate over holding period. Some of the top rated stocks have been hammered lately, IG group (LON:IGG) and Tullow Oil (LON:TLW) are just 2, this has wiped out quite a bit of profit in some folios. CMC Markets (LON:CMCX) l did top up yesterday at 600p, l see 2 directors also bought reasonable amounts.
Directors were selling a while ago.
‘Opinionated’ or not Tim Martin runs the most efficient pub business in the U.K. which what an investor wants
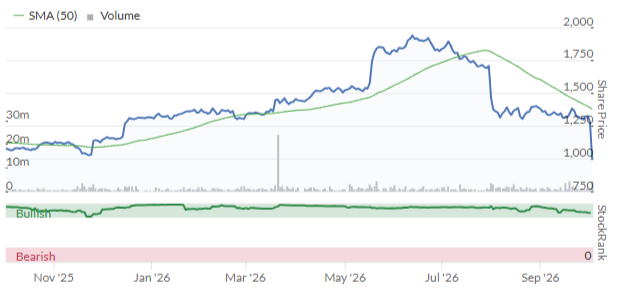
IG group (LON:IGG) don't have time to study but a well flagged warning around early July and fell to maybe a support at 1700. Next day boom to 1300. Ok bad is over let's be cool and hold. Boom now 990.
This is not some speculative basket blue sky share. I hold in IG ISA and spread bet account (which probably colours my thoughts as heavily underwater on silver duh).
Was thinking of getting into CMC Markets (LON:CMCX) who seem to be more 'modern', but sure my personal choices do not move the market. So what does.
Joins Vistry (LON:VTY) in the "Coffee Can" and perhaps remove from my watchlists.
The mistake may be that this is now 'cheap' a 'cigar butt' and 'pile in there' 'back up the truck'. Clearly something wrong that Mr Market very well knows and we don't.
The climb back to relevance (SP) will be long and hard. Boohoo (LON:DEBS) anybody.
Unless snapped up by someone - Who and Why.
Sorry to rant but there is also much market competition here now and AI Agents will do much of what these services can provide over time.
Price leads the news (nice topic for conversation).
Thanks for the helpful commentary on IG group (LON:IGG) . I had top sliced my shareholding a few months ago after the unwelcome announcement of the group's acquistion of Underdog and strategic statement outlining the possibility of further aquisitions.
I find it hard to know what how to act when faced with unexpected bad news like this morning's profit warning. Dazzled in the headlights! Anyway, the user comments and Stockpedia commentary help me make a decision.
Recalling Stockpedia's past research on how to act on profit warnings, I decided to sell the rest of my holdings. The decision process being the research that markets on average do not reflect the full future impact of a PW until days or weeks later. That combined with the commentary that IG group (LON:IGG) may possibly have been taking on more risk than we thought , and not being candid about it, nailed the decision.
No fun taking a 21% loss on the day, but to quote a line from Abigail's Party - better out than in.
If it’s any help, I always sell on the first iffy news like an acquisition where commentary and the share price reaction on the day shows serious questions about the wisdom of that buy. That certainly applied to IG group (LON:IGG) with their Underdog acquisition. The share price fell to around £14.50 that day.
I also always sell on the first profits warning. It works very well overall as I’m out ahead of further falls for the share price.
I don’t follow IGG closely but the problem with selling now around £10 is that the bad news might be almost priced in now, making it the time to consider buying again rather than selling after the big share price fall.
Cheers ken i have been looking at my Nichols (LON:NICL) share and their recent 70m vithit acquisition share price not gone down well on that news. So i might sell.
I have wondered the same DA regarding Nichols (LON:NICL)
Thats a chunky acquisition, uses up all their cash reserves and I cannot see anywhere any recent experience within the business of making acquisitions of any size, let alone a relatively large, overseas one like this.
Yep nicl never makes acquisition it seem the new cfo ex thg not a great performance there share price wise. Only ROI but can they get vimto in Roi and vise versa cant see a profjt warning coming as Africa looks good.
I agree that it seems like Nichols (LON:NICL) taken on too much than they can chew with VitHit.
But I'm holding still as think recent Vimto trade would be spectacular (amazing summer), OOH also in growth (cinemas footfall doing well), and Africa growth continuing. Plus, I suspect, Middle East distributors ordering more than usual to mitigate risk of logistics disruption in coming months if further war escalation. Lots of positive catalysts, needs only a few to land to exceed broker forecasts for FY.
very good points
Hi ken
Generally agree with you. Spreadbetters are a gamble on volatility: I've seen them swing both ways without warning on many occasions. The trick is to take profits on the upswing and then re-invest on the fall.
Here, with IG group (LON:IGG) we have the combination of a badly received acquisition and a profit warning which appears to be largely the result of a change in their hedging policy. The management have a lot to prove but you'd think this is nearer the bottom than the top.
Anyway, I will ride the downswing, although I await with interest news of the Underdog deal - if it turns out the deal can be repriced due to the fall in the IGG share price I will exit. That would be confirmation that the management have lost the plot.
Otherwise, I'd say the fall in CMC Markets (LON:CMCX) today is probably a minor buying opportunity. Their business model is now very different to IGG's.
timarr
The hook to catch a fish.
CMC Markets (LON:CMCX) Lord Cruddas just bought 23,000 shares in CMC markets at 600p .
CMC Markets (LON:CMCX) another director buy today, David Fineberg, just under £140,000
Here is Dan Neidle’s (tax expert) take on the Manchester City situation and whether there might be an issue with HMRC
https://taxpolicy.org.uk/2026/10/01/manchester-city-unpaid-tax/
Well worth a read for those interested in this saga.
according to the FT there may be directors of Man City who can protect themselves using diplomatic immunity.
IG group (LON:IGG) getting clobbered, I see. I hold. Ouch. I'm beginning to think that the problem here is that these platforms earn enormous returns on capital, which is an open invite to competition, especially from the Americans.
I also think that although platforms are a somewhat sticky business, they may not be sticky enough.
I have been hearing grumblings about IG and some of the changes it made recently. It's a way to lose customers.
I personally have moved off of Hargreaves Lansdown because of their monthly custody charges. I split it between IB (Interactive Brokers), Lightyear, and Trading 212. I like T212 the most, IB the least, with Lightyear in the middle. Lightyear seems like a new immature entrant at the moment. They seem to be trying to improve their offering, though, and I expect it to be more credible as time progresses. It's one to tune in later for those unhappy with their current arrangements.
There seem to be similarities with the high street banks. There used to be 4 banks in our town. The banks per capita must have been through the roof compared to other places. Maybe it was all the farmers that were an excellent demographic for the banks.
So, that all fell one by one, and we were left with no bank on the high street. Fairly recently the town opened up a banking hub. I'm not sure if you've heard of those, but they provide general banking facilities with a guest from each bank on allotted days to deal with any queries customers might have.
So my dad went along on the Virgin Money day to talk to them, only the guy didn't turn up for whatever reason. No doubt there were legit reasons, but come on, could they try any less?
I realised the futility of all this, and switched to a so-called challenger bank a couple of years ago. I opted for First Direct because their telephone support was excellent and they gave me a cheque book. If I want to pay in a cheque I can take a pic of it and they'll do the rest. Marvellous.
There are plenty of other online banks out there, all hungry to get your money, and provide good service, So if you like your Monzo, Revolut, Chase or whatever, then fine. I'm just saying what tipped the scales for me. Your mileage will be different.
This is one of the good things to emerge from the GFC (Global Financial Crisis). In a rare moment of actual clarity and insight, the gov't recognised the problem of "too big to fail", and hence encouraged new entrants. As the saying goes, never let a good crisis go to waste.
It's difficult to know how I compare with the majority of folks. I tend to stick with what I know, but I don't know, maybe I'm more willing to explore than most. Certainly with the banks, it has opened my eyes a little and encouraged me to be more open-minded and vote with my feet.
I guess that banking relations are stickier than stockbroking. Their systems are newer and not as rigid as the incumbents. They are built on what is relevant today, not what was relevant 20 years ago. I've seen Trading 212 advertised quite a lot on GB News (?) (It's what my dad watches a lot, which gives our political leanings away, not that they were that difficult to guess in the first place). So they're obviously having a marketing push.
Not forgetting the fact that younger investors might be stuck on an old provider, so advertising is likely to work on them. And I must say, I do think that T212 is more appealing to the younger generation than the more traditional brokers. Or maybe I read too much WallStreetBets over on Reddit. They're too into their Robinhoods and, what's the other one, Freetrade (?) which are very gamified.
So anyway, that's just some things for folks to think about.
It takes a while for new entrants to build momentum in financial services. For a while you think the incumbents are doing ok. Then whoosh!
All the providers have differing websites, mobile offerings. IG is poor imo, clunky too many button presses and no overview analysis which IBKR are very good at and fantastic liquidity (ok on small orders - I'm not rich).
AJB ok but high security firewalls have to jump over but actually not a bad thing. Security is paramount for your savings. Until OpenAi opens the er door.
Stocko ok for the weekend long view analysis and TradeView for the chartists ('tea leaf' readers - if I was an acolyte then IGG would have been dumped, but I did not - do I learn a lesson?).
Nobody said investing was easy but take the time worthwhile 100%.
My mate wants to put his wad into 4% stuff, earns income for the bills ok no problems. But the wad needs to work for you, not the actuary or bank. They get fees you get a static investment. But not interested.
Competition open - what will be higher in July 2027. Depends on what the WEF wants not our Local Government puppet.
I'll start -
Gold - and any UK mining such as Cornwall tin etc
Alternative energy - Small Nuclear Reactors (Rolls-Royce Holdings (LON:RR.) should do, had long enough at the game.
Pharma - we are good at this for some reason. Biotech. Data to collect information from every surgery and outcome to inform what works and what doesn't. AI can crunch the data which no 1000s of humans can put together.
We call it IT, now called AI. Forget the robots taking over the world. Maybe one day but "this is not that day" (Independence Day).
IG 23% down in one day. But warnings were there on the chart. Reason is unclear but holders are along for the ride.
Can you explain in a bit more detail what you meant by getting a chequebook and paying in cheques ?
I’m pretty sure all banks now offer a facility to bank received cheques online rather than visiting a branch . Which is one reason that far fewer people need to visit a branch - hence the bank closures
FD issues a cheque book so that you can write cheques. Not all banks do this nowadays, AFAIK.
You can pay physical cheques into your account by taking a webcam snapshot of them. That's probably quite standard with online accounts these days, but it is new to me. I couldn't see an ability to do this in my RBS account, for example.
what should i do with IG group sell out today accepting 20 % loss or hold on hoping there will be chaos and volatility in future? will it fall further Thanks
Have a read of the profit warning survival guide from the Stocko Team: https://www.stockopedia.com/academy/reports/the-profit-warning-survival-guide/
Would appreciate a summary. Like one warning, two warning, three warning - too late sucker.
I use Ichimoko Kumo Clouds with a cup of tea leaves. The problem is I don't follow my own highly developed back tested and robust systems developed over many years.
And if I did still would not capture IG group (LON:IGG) - this is on the ED ucation course please.
IG might also face another headwind if rates are now near peak and start to fall as they will earn less interest on client deposits (which have flattered earnings in the recent past). If equity markets fall or go sideways that also tends to reduce trading activity. This did look a bit toppy at near 2000 but the rapid reversal was a bit shocking. The stinky Underdog acquisition is the main culprit here tho.
Man City scandal - very inyeresting points Graham. I really wouldn't want to be the BDO audit partner who signed off those accounts if it’s confirmed there has been such wrongdoing !
I suppose I should start with a declaration of total bias. A life time of supporting the blue half of Manchester made me this way.
Nevertheless, I do think we need to question some of the “evidence” being chucked out there to demonize my beloved club. Frankly, some of the reaction from pundits and YouTubers is totally overblown. I do get it though. It’s irresistible click bait for the people who make their living from it.
Anyway, back to the evidence. The chart that Graham has attached above from Sky Sports is a classic example. It purports to show the amount that City have inflated their sponsorship over the years. The dark blue, we are led to believe, is the “real” sponsorship and the light blue is the “sham” sponsorship. However. if we are to believe this then we must also believe that the “real” sponsorship in 2017/18 was less than the sponsorship in 2010/11, after the club had won 3 league titles, 3 league cups and an FA cup.
i wouldn’t want to have to defend that position in the High Court.
” It purports to show the amount that City have inflated their sponsorship over the years”
It doesnt. It shows the amount of sponsorship paid for by Abu Dhabi United Group and Other Sponsors .
The title for the table is, “How much did Man City inflate their recorded sponsorship income per season.”
Happy to debate this all privately with you Gnome2 but as graham said would get into a football discussion which isnt really appropriate for here. I do have a lot of sympathy with City fans who appear to me to to fall into one of two camps :
Only know a handful of city fans personally - all fall into the latter category
My scion is a Manchester United fan so very happy to see this discussion. This site needs some oomph (ED).
I give a flying football over anything er soccer but did once buy into MU just a quick trade but puts emphasis on the word volatile.
Football is not an investment (me said not Mr Buffett).
It could be but impropriety is not a good look.
Anyone with finance from the Middle East where trust has different rules. Do business there for the dollar then don't cry when get shafted.
If this the base of City’s defence then this is a joke as there is a good excuse for the lower amounts.
Must have read this 30 times today on different forums and it’s obviously something that the dodgy owners are trying to sell to the media now!
The worst ever scandal in football’s history. The club will have to be dissolved and the owners banned from football.
All the best
I suggest you spend less time on social media Yiannos :-)
Lately that’s the answer you get in this forum from people that can never come back with a solid answer to support their original arguments.
Sad indeed!
All the best
I finally agree with Yiannos about something ! Hurrah !
Where else to get some sort of fact.
The pilots, co-pilots, passengers, seems to change by the hour. Except if some conclusion which is common sense from the start.
This is not a forum for chat but it does give colour to investment strategies. Hard to ignore (Ed did warn long time ago about focusing on the 'news').
Get the hell out of Dodge - is simplistic but be very fast on the draw other wise move away.
Totally agree
MELLO LONDON
Stockopedia will be well represented at this two day show and ED is one of the Keynote speakers plus everyone enjoys the BASH sessions
Five more companies announced today....we are rapidly heading towards our 60 target which will be an all time record for a two day event ( previous record 47) Just announced
FRP
IP Group
Manx Financial
S&U
Renalytix
It is going to be an amazing two days and 87% of the investors already booked have tickets for both days. The networking will be amazing
use code Stocko25 for 25% off General Sale & Final Release tickets: https://www.melloevents.com/mellolondon2026
Really important tip; If you hasve never attended a Mello conference before this is perfect timing to start as we still have 17 taster tickets for those 'New to Mello' just enter the code NEWBIE when registering and it will be a huge discount to just £30 and you can use it for both days.
See you in November for Mello London, it is going to be an excellent two days for investors - Mello really is a very open and welcoming investor community so do join us!
Kingfisher (LON:KGF) Kingfisher KGF.L: Peel Hunt raises target price to 370p from 350p
Vodafone (LON:VOD) Vodafone VOD.L: Berenberg raises target price to 140p from 123p
Like others I've been trying to make sense of what all the bond market tensions mean for my portfolio. I have zero expertise on economics and only vaguely understand the bond market.
In the spirit of trying to help others crystallise their own thoughts here are some of mine below. Again I stress this might be total rubbish - please challenge me! I'd also like to flag a very helpful FT Q&A yesterday with two of their analysts trying to answer similar reader questions: https://www.ft.com/content/db266f36-c6d3-4368-8633-290e2c35e54d
1. I think the honest answer is no-one really knows where this ends up. I'm also mindful that every crisis has a new angle no-one saw coming or underestimated. One potential scenario is a new sovereign debt crisis.
2. Governments are not taking meaningful long-term action to address their debt costs. They'll continue to pursue short-term piecemeal attempts to balance budgets and I suspect many Western countries with high debt costs will continue to have constrained budgets and public expenditure which might limit the upside for those companies with a public sector focus.
3. Most of the news focus has been on the impact on governments. However, I've also been thinking about how companies and individuals are now facing increasing debt costs whether that's mortgage costs or borrowing costs. Now more than ever it probably pays to stay away from indebted companies. Conversely, those with large cash balances might get a boost to their interest earnings. However, debt is often used for growth so higher debt costs could have an overall dampening effect on economic activity.
4. A key question for me is to what extent this results in a 2008 style crisis - disastrous for our portfolios - or is a slow burn of gradually increasing pressure on governments the most likely scenario? So far equity markets have held up surprisingly well despite bond yields. Also, large spikes in bond yields only feed into government debt burdens gradually and the financial system in many Western countries is now more robust. But again I come back to point 1: there might be a sudden unexpected event that might lead to panic selling and a vicious downward spiral.
5. Potentially the biggest threat to equity markets in the short-term is the AI trade unwinding. I saw an article about how much US households have invested on the stock market: a sharp fall in the NASDAQ could be quite nasty for the US consumer. How much the AI trade unwinding affects UK-focused small caps I am not sure but there are plenty of shares with some AI driven benefit that would probably sell off.
6. More positively, an FT analyst pointed out that debt-to-GDP ratios are actually pretty stable currently - partly due to inflation - and the share of GDP they spend on interest costs is actually lower over the last decade. And again, equity markets have held up well this year.
7. I am also mindful that the 2022 Russian invasion, and subsequent inflationary increases, was very damaging for equities and was my worst year on the stock market. It's taken 3-4 years for markets to bounce back properly.
So what to do?
We've been worrying about bond yields for some time now. If I had sat out the market this year I would have missed out on some fantastic gains.
That said, I am becoming more, not less, worried. Plus there's no end in sight to the Iran war and Russia is reportedly this morning saying there are now no rules governing the conflict in Ukraine as we head into a winter with higher energy prices. And we're probably well into AI bubble territory which will burst at some point.
If there is a sudden crash or big lurch down I also want some cash on the sidelines as that's often when you make the most money. I know quite a few private investors like to remain fully invested on the basis they can't predict the markets - but none of us would really want to be holding on going into a 2008 style crisis.
On balance I think I am going to try and protect some of my gains this year and reduce - ideally halve - holdings which have probably got limited upside in the next 6-12 months. I.e. remain maybe up to 50-75% invested but with a decent amount of cash on the sidelines to take advantage of any big lurch down in the markets. Of course, I will probably be selling the shares that will bounce back the strongest if there is a sudden drop in yields but, having had a decent year, I think I fear losing my gains more than missing out on an upwards spike in the markets.
I hope this is vaguely helpful to share!
I read an interesting piece this year that said a 2008 crash will likely never happen again as we now have so much private pension invested that can't be removed and governments have shown they will just print money to avoid one like they did with Lockdown. In that scenario, cash would be eroded by the inflation caused by the money printing.
Personally I don't think anything can be called anymore, it's not a free and open market, lot's of intervention, global planning, tax money funnelled into corps, insider trading etc, etc. Numbers and data make sense but people flip the script often.
Whenever you hear variations on the theme that this time is different be very sceptical. Although I agree that governments and central banks will do pretty much everything they can to prop up equity markets given that the economy today is so heavily dependant on the stock market.
A good analysis Tortoise investor. A good time to be c40-50% on the sidelines in my view. We must be nearer the end than the beginning of this bull market which has lasted since 2009. To me it all looks a bit like 2008, albeit for different reasons.
Hi Tortoise
You are describing the wall of worry and the more you gain the more you want to protect those gains. Here are some positives posibilities (all speculation - none of which might happen):
Iran's currency is experiencing hyperinflation and the Iranian gov't are rapidly running out of funds and ability to fund/feed their army and population. They had 80 million barrels of oil parked off China which was being drawn down apparently. This supply is now gone. Therefore, US just need to keep up the blockade which they have signalled they can do for a long time (3rd carrier going to the region). The regime might sound tough but they need the support of the army and population.
So the situation will resolve at some point and then the market bounce could be akin to the announcement of the covid vaccine. Yields will plummet and confidence will soar. You don't want to miss that day/week.
6% bond yields are in themselves a reason to buy bonds. If you believe in the very long term average rate of inflation 2 to 3% then a 6% yield is adequate to provide a very comfortable retirement. Right now it appears that inflation and yields are going to spiral out of control. However, if that does happen then borrowing and spending will stop and a recession is almost guaranteed. At which point yields and interest rates plummet.
My point is that the market will be self regulating/correcting (even if we have to reach an extreme before correction takes place).
In 1998 yields were approx 6%. If you had bought the 30yr bond back them you would have been in a wonderful position for 30 years (who could have foreseen near zero interest rates when yields were at 6% in 1998).
I'm not starting an argument here. Just pointing out some of the counter possibilities.
Personally, I am adding some bonds to my portfolio for the guaranteed income whilst using equities for the potential longer term higher returns.
Thank you very much. I've also bought some bonds - even 3 and 6 month T-Bills are quite attractively priced.
Hi Tortoise,
Your thoughts and concerns very much echo my own. This last month or two I have been selectively moving in to cash and am now 80% cash.
I recognise that this is super defensive and whilst I am not trying to time the market, I just feel a lot more comfortable currently having a substantial amount of risk off the table.
It may well be I miss out on some profits but I can live with that and I am content that when I personally feel more comfortable about the markets and macro issues then I can begin drip feeding back funds back in at a pace that suits me.
Each to their own, as they say.
I suppose you have to consider what does a sovereign bond crisis really mean - on the face of it a worry about significant fiscal restraint aka austerity which reduces GDP etc but having said that, austerity didn't really work last time and although it could be forced on a country its probably not the immediate answer. So more likely is some restraint and some changing the rules : that allows governments and markets to ignore certain liabilities which brings about some calm. Ie a technical debt reduction rather than an actual one. Net net some combination of this could work especially if inflation also retreats ....which it should in a recession. While all this could be unpleasant I don't think it recreates 2008 because the system soldiers on and the cards are reshuffled .... so whilst I don't discourage taking some profit and holding cash ... I would caution against thinking 2008 is imminent tbh .... Sterling would be my concern for the UK but it's actually holding up rather well at the moment .... and the UK only really needs a few tweaks here and there to be in a sustainable position. Society everywhere needs to cut the welfare bill, which isn't going to be popular but that is where we are.
Excellent post!
Goldman Sachs group (NYQ:GS) and Blackstone (NYQ:BX) recent share price movements speak volumes.
The US has no other option but to take interest rates below 2%. Something will soon break out there in the market and we will experience a deep recession.
Not sure if we are there yet, but iShares 20+ Year Treasury Bond ETF (NMQ:TLT) will be an option for making money as rates will soon (2027) be dropping.
Big gains have already been made over the US.
All the best
You've covered it well Tortoise investor. I've been a bear and of course wrong (on and off) since 2016. Stockopedia and the FT are where I live, for me red lights have been flashing on the American market for over a year. Did you note Bill Gross's advice in his piece in the FT a couple of days ago on Bonds and equities? He's not infallible but he has a lot of knowledge and experience -- Shun bonds unless very short term (he was the Bond King) and beware highly valued tech companies.
We currently have more in cash than shares, a ratio which has paid off quite well ahead of all the sell-offs since 1987, when I learned a lot of unforgettable lessons. Good luck in successful investing to all those who responded to your message.
Thanks for this Ti - really excellent
As a long term and happy holder of Saga (LON:SAGA) I note that Stockopedia still rates the share a Momentum Trap.
I listened to the Company Presentation on Investor Meet yesterday and I am very confident that the Company is in a very sweet spot and as debt is falling rapidly it will not be too long before a Dividend is paid.
I know Cockney Rebel is a big fan of Saga and you only have to look at the UK demographics to see that business should continue to boom.
What has surprised me is the hugely successful link to Nat West and the inspired decision to sell off the Insurance Section to Ageas.
IG group (LON:IGG) - Not all convinced that 'less supportive market conditions' are the key driver for the downgrade - peers such as CMC and PLUS (as well as larger US peers) all reported good trading, while volatility indices still look reasonably supportive. Definitely seems more company specific, in which case possibly a good opportunity to buy CMC or PLUS both of which have fallen sharply in sympathy.
The director buying in CMCX, although meaningless really in £££, suggests that there is no market sensitive statement coming.....
Man City, IG group (LON:IGG) Capita (LON:CPI) our Friday is starting to form a pattern today ladies and gentlemen. Charlatans.
In further cheery news we have Capita (LON:CPI) admitting that the National Audit Office is reviewing their Civil Service pension scheme administration. Not a good look either (did somebody say 'Crapita'. Not me!)
I'll say it!
Awful company. Despite continuous failings and poor execution, governments still employ these charlatans. Terrible value for the taxpayer.
What an appallingly unsatisfactory 3rd quarter update from IG group (LON:IGG) . Clearly a profit warning, but all they talk about is the revenue decline and how they are reiterating their medium term prospects. This is no way for a large cap company to behave - please just tell investors what the downgrade to earnings is so that we all know the situation, rather than presumably dripping it out to institutions via their broker.
Also thought it read poorly - blowing my trading will be fine theory out of the water - not an expert on their numbers but guess this all sounds like you can nudge down 5-10%. Not what the Breon fans would have been looking for.... company obviously trying hard to hold it all together so the house probably limits the downgrade today.... but the share price chart isn't looking good and weakness today a new breakdown. Disappointing although I hadn't got involved yet.... I did pick some TP Icap (LON:TCAP) yesterday on weakness which may also be poor timing. We see.
let's see if Corky or any of the rest of the board buy shares at this level....
IG group (LON:IGG)
Seems like its an increasing trend of companies to just spout complete gibberish - todays from igg is a doozy of complete nonsense. As ever when it’s not straight taking honesty it’s rarely good news. Can’t make any sense of it - that is one thing with this company and sector there can be pretty large variability in some of their core stuff - I am not minded to over worry with short term bad news - as soon as company start reassuring about the medium term though well that likely wont be good for either this year or next year ref forecasts.
My best guess is Revenue is kind of inline (+14% ) unless you thought they would be nearer 18% H1 or higher and margin weaker than 44% H1 ...nearer 40% .... which all sounds a bit like -10% to me but maybe im wrong.
IG group (LON:IGG)
First up I want to know how on target ref year end profits they are and if there is any change next year - simply have to wait for broker updates I can’t even begin to guess
RE: IG group (LON:IGG)
Markets were calmer so traders placed less bets and lost less money.
Underlying metrics all up. Basically a classic spreadbetter trading update - lower volatility = lower revenues.
All they need is increased market volatility to pump earnings. Now where can we find an agent of chaos to inject that into the markets? Hmm ...
timarr
Knock on effect on CMC Markets (LON:CMCX) as well.
CMC Markets (LON:CMCX) Crikey. You're right. Plus500 (LON:PLUS) took a pummelling this morning too. Down around 10% but has since eased off.
Plus500 (LON:PLUS) issued a trading in-line RNS around 10.00am, obviously in response to the pullback in its share price, which had the desired effect. Also Lord Cruddas, as I posted very recently, purchased 23,000 shares in CMC Markets (LON:CMCX, he already had a majority holding in excess of 60% IIRC.
Sold all my IG shares since their system update. It’s terrible. Can’t see open positions on charts anymore, most US stocks now show 24h prices with spreads of 80%, so my p/l is meaningless until the US opens. Deal ticket doesn’t show value or how many shares you have. No RSP prices, just fills at your limit. Awful. Seems they’ve turned into a betting company and have lost their UK customers. I, like most, are looking to move their ISAs and spread bet accs.
to where thought?
cmc
I used them decades ago - worth another try - also good for diversity of funds.
Trading 212?
Already with them - it isn't a great platform to use (from my perspective). Also see a lot of "it takes ages to get a buy in", implying they are looking for matched transactions on there own site before reluctantly going to market.
Unfortunately I cannot recommend Hargreaves Lansdown. They originally had a great customer service and website, but since being taken over by private equity both have nosedived. I do not think that they have a single employee maintaining their website. It is barely functional and there have been no fixes for months.
And hargreaves charges you a yearly maintenance fee of your equity!!
Hargreaves Lansdown changes to website are terrible and charges are up the private equity firm are just wanting to increase profits and reduce service Who should one change to
Yep - I left a company pension scheme with them - costs were completely uncompetitive - I assumed they spend a chunk of that schmoozing FDs to put their company pension schemes with them. I'd never go there for their lack of morals (ripping off a captive audience).
A number on X have been posting evidence of how even market orders seem to be bought at worse prices than when they try them in other accounts.
I would expect them to lose customers and maybe those Q4 numbers will look even uglier.
To wolfspirit's question about where to move - AJBell still offer real time quotes and I know some also like ii's functionality.
So both IG group (LON:IGG) and Hargreaves Lansdown have "fixed" things that werent broken and are losing clients over it, but who is picking them up AJ Bell (LON:AJB) or Aberdeen (LON:ABDN) through interactive investor?
Both are probably benefitting, both reported increase in customers in July TU's, and that was before AJB and HL started to tinker with their platforms.
I use AJBell and ATM I am content. If I switch it will be to ii (Aberdeen). From reading the various grumbles on here I think you have hit on the 2 best options for PI's with SIPPs and ISAs.
ATM Capital?
Indeed. IG filled my Limit order at a worse price than the RFQ fixed quote I dummy-tried at the same time on AJ Bell!
This was for a small cap share in the UK.
I'm probably going to move to Interactive Investor.
After doing loads of research, there's only really a few options for small and mid cap investors. AJ Bell, Hargreaves, Barclays, Interactive Investors, Interactive Brokers.
However, IB is what IG are using for their share dealing back-end, so I don't have faith it will be better...
I would choose AJ Bell, except that I already have my SIPP with them, so reluctant to put my ISA eggs into the same basket.
So Interactive Investors it is then!
Check out the ii platform first - I find it 'pre-historic' in comparison to IG's graphing view. Maybe AJ Bell need another try! :-)
I must be missing something about the appeal of ii. I hate their interface - the graphs are awful. SIPP with them for cost - but customer service is abysmal, although did get a cash payment for a mess up they did.
I left AJBell for the cost (went to ii) - partner still with them with lower sized pot. I still own shares in them! :-)
I think they have 2 different systems - I'm still on the old one. Open positions on charts get removed if there is a corporate action. e.g. just happened to Christie Group. They lose the original cost (you can add back in, although that isn't a great excuse!). I've also heard that they don't take limit orders - but I still get them. I've not bought USA shares throguh them though.