Daily Stock Market Report (Wed 22nd July 2026) - BMY, HDD, JHD, LIO, RCH, GNC, BOOT, JDW, MUL

There’s little overnight news to report, apart from one that you’re very familiar with by now: strikes being exchanged between the US and Iran, as mediators attempt to get negotiations started again (I feel like Bill Murray in Groundhog Day).
As there isn’t much overnight news to comment on, I thought I’d mention this article which has been on the BBC Business website for the past few days:
Focused on investors in Korea, Singapore and Australia, it attempts to capture the current sentiment in the tech sector. Most of the comments from the young investors it interviews are quite sensible. But then it’s always fun when you get comments like this in mainstream media:
"I could maybe count with my hands the number of people who aren't investing today," South Korean investor U Chan Lee says. "Even stay-at-home mothers, like my mum, who has never been interested in the stock market, are now interested."
The “shoeshine boy” indicator doesn’t exist anymore, because shoeshine boys don’t exist in the same numbers as they used to. But the principle is still as true as ever: that when those who have never shown much interest in the stock market before are suddenly keen investors, then it’s time for everyone else to be cautious.
The FTSE is up 0.2% at 10,600
S&P 500 is down 0.1% at 7,500
Brent crude (October) is up 0.7% at $89.10/bbl
Gold is up 1.2% at $4,130/oz
Bitcoin is down 0.7% at $66,000
Leaving it there for today, have a good evening! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Fresnillo (LON:FRES) (£19bn | SR82) | Q2 attributable silver production down 1.7% to 10.9moz vs Q1 26. Q2 attributable gold production +13.8% to 154.8oz vs Q1 26. Outlook: remains on track to meet full-year production guidance. | ||
Hochschild Mining (LON:HOC) (£2.29bn | SR53) | H1 gold equivalent production -6% to 180.64koz. Solid performance from Inmaculada and San Jose with a continuing turnaround at Mara Rosa. Outlook: on track to meet 2026 attributable production target of 300-328koz gold equiv. | ||
Greencore (LON:GNC) (£1.78bn | SR36) | SP +12% Revenue +3.2% (pro forma) to £1,024.3m with “a fast start on synergy delivery” following the Bakkavor acquisition. Outlook: upgraded FY26 adj operating profit guidance - now expects £234-242m, vs consensus of £219-231m. Shore Capital upgraded broker estimates: - FY26E adj EPS: 19.3p (prev. 18.0p) - FY27E adj EPS: 23.1p (prev. 22.7p) | AMBER/GREEN = (Roland) [no section below] We last looked at this sandwich and ready meal business in October 2025, shortly before its merger with Bakkavor was due to complete. At the time I took a broadly positive view, but said I’d wait until after the acquisition completed before considering an investment. We’ve now reached that point and the shares have roundtripped from 233p down to c.190p and back up to 247p today – albeit with an enlarged sharecount. On balance I’m happy to leave my previous view unchanged. While I wouldn’t pay a high multiple for this low-margin business, momentum looks strong and Greencore has a respectable track record in this sector. With a FY27E P/E of 11, I don’t think the valuation looks overheated yet. | |
Sirius Real Estate (LON:SRE) (£1.55bn | SR69) | Acquired a “defence-supported business park in Fulda for €49.8 million”. Currently fully let with an annual rent roll of €3.93m, 5.1yr WAULT and EPRA net initial yield of 7.8%. | ||
Energean (LON:ENOG) (£1.44bn | SR40) | Commissioning of second oil train on FPSO was completed on 13 July, expanding liquid processing capacity from 18 kbbl/d to 31 kbbl/d. Liquids production is expected to average 17-21 kbbl/d in H2, in line with 2026 guidance following H1 suspension. | ||
Sigmaroc (LON:SRC) (£1.35bn | SR85) | Revenue +2.5%, EBIT +3.9% to £89.5m. H1 EPS +12.2% to 5.23p, with covenant leverage reduced to 1.66x (H1 25: 2.04x). Outlook: FY26 expectations unchanged. | ||
Resolute Mining (LON:RSG) (£1.08bn | SR59) | Additional drilling of over 31,000m delivers an expanded Inferred MRE of 133 Mt grading 0.71 g/t Au for 3.0 Moz (at 0.3 g/t cut off, US$3,250/oz Au pit shell). Planned $15-25 million work programme to drill out deposits and to progress feasibility studies and mining application by the end of 2027. | ||
M P Evans (LON:MPE) (£883m | SR99) | Group harvested FFB +14% to 705.4kt in H1 26. CPO production +11% to 192.3kt, with Palm Kernel production +11T to 42.1kt. Average prices realised in H1 of $873/t (CPO) and $813/t (PK). | ||
J D Wetherspoon (LON:JDW) (£804m | SR29) | LFL sales +4% for the 12 weeks to 19 July, with year-to-date LFL sales +4.2%. Outlook: “profits for the year are likely to be below market expectations” due to lower Q4 sales and higher costs. | BLACK (RED ↓) (Graham) The central problem here is that profits are the difference between two large numbers - and one of those numbers in particular (costs) is subject to many forces outside of JDW’s control. Changes in cost inflation and taxes have not been particularly favourable in recent times. Long-term, I would expect this stock to enjoy good balance sheet support, as 70% of pubs are owned freehold. So in the bigger picture, I’m not very negative on JDW. However, I am going to respect the downward trend in earnings forecasts and therefore take a fully negative stance in the short-term. | |
James Halstead (LON:JHD) (£545m | SR82) | UK sales increased “modestly” vs last year. Seen headwinds against sales of luxury vinyl tiles in EU and Australia. Also chose to absorb some cost inflation relating to the Iran conflict to protect relationships with contractors and seek opportunities to gain share. Outlook: sales will be marginally below 2025 with profit approx. 10-15% below that of last year. Panmure Liberum cuts FY26E EPS to 8.7p (prev. 9.9p). | BLACK (AMBER/GREEN ↓) (Roland - I hold) I think the company’s decision to defer price rises in order to support ongoing projects is a sign of its quality and durability – and could support market share gains. The mountain of net cash on Halstead’s balance sheet means this decision is readily affordable. Reflecting this, today’s updated broker forecasts do not suggest any change in the dividend outlook for this year, even though the payout is no longer likely to be fully covered by earnings. On the other hand, I recognise that this business is exposed to external headwinds and has a poor record of growth in recent years. Until this situation improves, the upside on the stock may be limited. I’ve moved our view down by one notch today to reflect this risk, even though I continue to believe this stock offers value on a longer-term view. | |
Bloomsbury Publishing (LON:BMY) (£524m | SR89) | Bloomsbury is among the beneficiaries of a class action settlement (Bartz et al vs Anthropic) and expects to receive c.$3,000 for each of 14,087 titles, less costs. This will be divided equally between the author and the publisher. | GREEN = (Roland) [no section below] I’m not sure if the company has mentioned this class action before, but my number crunching suggests Bloomsbury’s share of this windfall might be c.$21m before costs. Checking the court document shows attorney fees have been capped at 25%, plus expenses. So I would guess that Bloomsbury could receive c.$15m as a result of this class action. This cash will be used in line with the group’s capital allocation policy. I upgraded our view on Bloomsbury to GREEN in May after reviewing its full-year results. These numbers also prompted a significant StockRank Jump. With the market cap broadly unchanged since then, I think it’s fair to leave my positive view intact today. | |
Frp Advisory (LON:FRP) (£294m | SR69) | Revenue +16% to £177m, with adj pre-tax profit +12% to £41.4m. Adj EPS +11% to 11.92p. Demand in the insolvency and restructuring market “remained robust” last year. Outlook: trading so far in FY27 has been in line with the board’s expectations. | ||
Capita (LON:CPI) (£291m | SR19) | Issued $55m (£41m) of unsecured senior notes with a three-year maturity and 7.54% annual coupon. Has also amended the interest cover ratio on its existing US Private Placement notes to 3.0-3.5x. | ||
Norcros (LON:NXR) (£286m | SR61) | The Group's trading performance for the first quarter of our financial year continued to be solid, with revenue +3.1% on a LFL basis. Outlook: expectations for the full year are unchanged. | ||
Boku (LON:BOKU) (£285m | SR42) | Peter Klein appointed as Chief Commercial Officer. He joins from Mastercard and has over 25 years experience in payments, fintech and financial infrastructure businesses. | ||
Seeing Machines (LON:SEE) (£224m | SR24) | Secured a new Driver & Occupant Monitoring System (DMS/OMS) program with a European automotive manufacturer, through an existing Tier 1 customer. Production is expected to start in 2028 and the award is expected to generate c.$5m in lifetime revenue. | ||
Henry Boot (LON:BOOT) (£223m | SR54) | Market conditions remain uncertain and a number of housebuilders have slowed land acquisition activity. Plot sales are expected to be “materially below the prior year”. Outlook: pre-tax profit is expected to be “significantly below current market expectations” (previous consensus: £20.4m). | BLACK (AMBER =) (Roland) [no section below] I’ve previously concluded that one function of this business is to effectively provide free credit for housebuilders, who can delay or suspend land purchases (from BOOT) depending on market conditions. We’re seeing that again today, with plot sales down sharply. The company’s own home completions were also lower. The attraction here is the c.50% discount to tangible book value – Henry Boot does own a lot of land and I’m confident this will deliver some value over time. The problem is that the company isn’t getting paid to hold this land and is consequently generating low returns on its asset base. We don’t have access to updated broker forecasts today, but I would guess we will see FY26 EPS estimates cut by at least 10%. Graham moved to a neutral view on BOOT in January. I’m going to take a chance and leave this unchanged today. The company still expects a reduction in net debt by year end and the shares are trading at post-2013 lows. I think a degree of patience is justified. | |
Liontrust Asset Management (LON:LIO) (£210m | SR96) | AUM increases from £19.6bn (March 2026) to £24.3bn (June 2026). Net outflows £357m. River Global acquisition added £3bn to AUMA. | GREEN = (Graham) | |
Reach (LON:RCH) (£188m | SR66) | On track to deliver on market expectations for the year. Revenue down 9%. Adjusted operating profit down 4.1% (£43m). Statutory operating loss £43.5m driven by impairments. | BLACK (AMBER/RED ↓) (Roland) [no section below] Today’s in line guidance for the current year masks substantial cuts to broker forecasts for FY27 and FY28 (see left). There’s also a nasty (but sensible) dividend cut, with the interim payout halved to 1.44p per share. Operationally, the business suffered in H1 from declining print circulation and a 40% drop in page views due to Google algorithm changes. This dependence on organic search traffic points to the low quality of the business (in my opinion), but I note the company is gradually targeting a shift from volume to quality – and this could pay off over time. Perhaps more importantly, pension deficit contributions are currently running at £57m (17p per share), but will fall to £15m in FY28 and are expected to end after that. This could transform Reach’s cash flow – assuming its business holds up in the meantime. At face value the stock now looks very cheap, on a FY27E P/E of 3 with an 8% dividend yield. However, I think there are potentially good reasons for this, so I’m cutting our previous neutral view by one notch today. At this time, I see Reach as a special situation requiring further research. | |
Tristel (LON:TSTL) (£185m | SR77) | Revenues up 10%. Adjusted PBT +10%, expected to be no less than £11.5m, marginally above market expectations. | ||
Dialight (LON:DIA) (£163m | SR89) | Strong sales growth in Q1 comfortably exceeding the Group's stated expectations of 3-5% plus sales growth. Profit for the financial year ending 31 March 2027 is likely to be ahead of its previous expectations. | ||
Personal group (LON:PGH) (£126m | SR79) | Revenue +10%. Adjusted EBITDA +22%. Cash £29.4m. Confidence that trading remains in line with market expectations for the full year. | ||
EnSilica (LON:ENSI) (£102m | SR51) | Follow-on chip orders worth €1.1 million from a European satellite communications customer. | ||
Mulberry (LON:MUL) (£97m | SR52) | Group revenue for the year was up 4% to £125.5m (+11% in H2). Gross margin 72% (2025: 67%). Reported loss before tax £8.9m (2025: loss of £32.2m). Outlook: Trading in the current year has started positively, with momentum from the second half of FY26 continuing into FY27. Performance in line with the Board's expectations. | AMBER ↑ (Graham) [no section below] I've been moderately negative on this one, but I must acknowledge that there are plenty of green shoots of positivity. Fristly, these full-year results are H2-weighted: H1 saw an underlying loss of £7.4m on declining revenues. But the full-year loss was only £8m, meaning that the underlying result in H2 was close to breakeven, and with rising year-on-year H2 revenues. The dreaded EBITDA loss has been eliminated, even if that is a fairly low bar. Current trading is impressive too, with a 23% revenue increase in Q1 including a 21% like-for-like increase in Retail & Digital revenue, and with broad-based geographic growth. Gross margin, the basis of financial success in this sector, has also improved to nearly 72% (from 66.8%). Finally, I note that there are no major adjustments to the numbers, so that the statutory loss is close to the underlying loss. The major and obvious negative point is that Mulberry is still loss-making and is expected to remain loss-making until FY28, when a small profit is expected. However, with so many positives to hold onto, I think it's worth being neutral on the stock at this point. I still believe that it could be of strategic interest to a trade buyer, who might value the potential of the brand significantly higher than £100m. | |
Hardide (LON:HDD) (£59m | SR56) | Revenues for the third quarter to 30 June were £4.1m in the period, such that revenues for the year to that date total £8.9m. Also achieving operating profit margins higher than anticipated. The Board now expects that full year financial performance will be materially ahead of its previous expectations. | GREEN = (Roland) Revenue is on track to double this year, driven by new business wins. The resulting improvement in manufacturing capacity utilisation plus good cost management has catapulted the group to a very respectable level of profitability. Earnings are now expected to rise from 0.2p in FY25 to 5.4p for FY26. Looking ahead, the valuation still seems relatively reasonable to me, with FY26E P/E of 18 and FY27E P/E of 12. With six earnings upgrades in 18 months, I’m not betting against momentum here and will leave our positive view unchanged ahead today. | |
Orosur Mining (LON:OMI) (£58m | SR10) | CEO comment: "Starting exploration from scratch is never easy, but the work carried out by our team support our initial view of the extraordinary prospectivity of El Pantano. We now own the project 100%, and so have many options available to us". | ||
Ariana Resources (LON:AAU) (£41m | SR37) | Tavşan operations have completed ramp-up and ore is currently being loaded onto the heap-leach pads at the required rate of 4,000 tonnes per day. | ||
Skillcast (LON:SKL) (£40m | SR38) | Continues to trade in line with market expectations for the full year. Revenues of £8.2 million for H1 2026 (up 10%). ARR +5% since the start of the year to £14.5m. | ||
ImmuPharma (LON:IMM) (£28m | SR4) | IMM has selected Thermo Fisher Scientific as its drug product and contract development and manufacturing organisation for its Kapiglucagon program. | ||
Great Southern Copper (LON:GSCU) (£19m | SR2) | Results from 20 channel traverses, representing 409 metres of sampled outcrop and 214 samples, confirm broad zones of highly anomalous copper-silver mineralisation associated with quartz veining within the silica-clay altered dacite dome. | ||
NAHL (LON:NAH) (£18m | SR84) | Continues to trade in line with management's expectations for the full year. Revenues for the Period are expected to be approximately £19.7m, 3% ahead of the previous year, while underlying operating profit is expected to have increased by c. 8% to £3.4m (H1 2025: £3.2m). | ||
Oriole Resources (LON:ORR) (£17m | SR30) | Oriole is pleased to announce that a maiden drilling programme has been completed at its 85%-owned Wapouzé limestone project in north-eastern Cameroon. | ||
Potter & Moore (LON:PAM) (£16m | SR65) | CFO has informed the Board of his intention to step down from his role. Expected to work his six-month notice period to ensure a smooth transition. He is thanked. | ||
Sealand Capital Galaxy (LON:SCGL) (£15m | SR3) | Conditional agreement to acquire Brilliant Glow Group Co., a privately held company incorporated in Hong Kong, which owns Shenzhen Brilliant Glow Consulting Services Co. Total consideration £6.6m. BGG focuses on advising small and medium-sized enterprises across a range of industries in APAC. | ||
Harena Rare Earths (LON:HREE) (£13m | SR11) | Signed a Project Development Funding Agreement with the United States International Development Finance Corporation. DFC has committed up to US$4.84 million towards the agreed project development budget for the Ampasindava Project. |
Graham's Section
Liontrust Asset Management (LON:LIO)
Down 3% at 322.5p (£203m) - Trading Update - Graham - GREEN =
This one has built up a nice head of steam in real months:
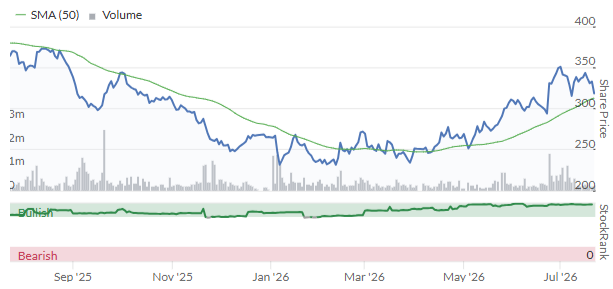
While I’ve not been entirely enthused by the company’s fund performance, competitive positioning, nor its outflows, I’ve held to the view that “profits are profits”, turning GREEN (from AMBER/GREEN) last month.
The Stockopedia calculations have taken a similar view, calling it a “Super Stock”.
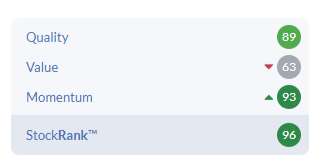
Note the attractive P/E multiple, EPS growth rate and dividend yield:
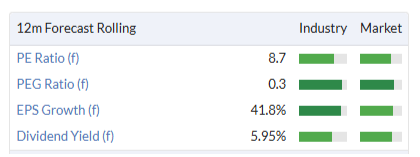
It’s worth mentioning that the EPS growth rate is based on recovery after a severe downturn:
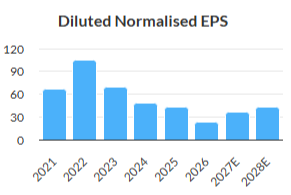
In a similar vein, the dividend yield is after a big cut to the payout:
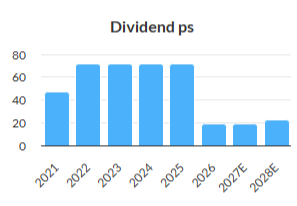
Checking in on today’s update, we have a familiar theme: outflows continuing, but AUM increasing as a rising market tide lifts all boats.
Net outflows in Q1 (April to June) of £357m
AUM rises from £19.6bn to £24.3bn, helped by the £3bn acquisition of River Global.
CEO comment:
The acquisition of River Global has increased AuMA by £3 billion, taking AuMA to over £24 billion, and expanded our investment capabilities and styles, while enhancing the breadth and depth of our investment professionals. River Global has also added several strongly performing funds to the Group, including eight ranked in the first or second quartile of their respective sectors over three years.
Graham’s view
Net outflows were £0.8 billion in the prior quarter (Q4 of FY26).
For FY26 as a whole, net outflows were £4.2 billion.
For FY25, they were £4.9 billion.
In this context, a £357m quarterly outflow is not bad at all - one might almost say “good”! It’s the sort of level where if markets are performing reasonably well, then it could be offset by returns. (the latest quarterly outflow, if annualised, would equate to about 6% of AUM).
I’m therefore going to stay GREEN on this one.
It’s not my most comfortable GREEN by any means, but I perceive value and the StockRanks are very positive, too.
J D Wetherspoon (LON:JDW)
Down 7% at 702.58p (£749m) - Pre-close trading update Graham - RED ↓
We’ve been pretty nervous about this one, with our most recent coverage being Roland’s AMBER/RED in May.
That May update was a profit warning (“slightly below expectations”).
But the share price has actually risen since then:
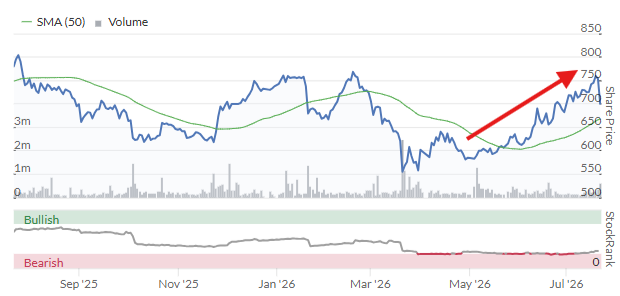
Today, however, we get another profit warning.
Key points:
Like-for-like sales up 4% in the 12 weeks to 19th July 2026 (NB. financial year-end is the end of July).
Year-to-date like-for-like sales up 4.2%
Year-to-date, JDW has opened 8 pubs, sold nine. 15 franchised pubs have opened, bringing the total to 23..
Net debt is expected to end the year at £720m, same as last year.
Chairman comment from Tim Martin:
"Profits for the year are likely to be below market expectations, with marginally lower sales than anticipated in the final quarter, combined with higher costs in the areas of food, labour, repairs, energy and business rates."
Graham’s view
The central problem here is that profits are the difference between two large numbers - and one of those numbers in particular (costs) is subject to many forces outside of JDW’s control. Changes in cost inflation and taxes have not been particularly favourable in recent times.
We were already AMBER/RED on this. Do I dare go fully RED?
I think I will, to be consistent with our philosophy that profit warnings are often followed by more profit warnings.
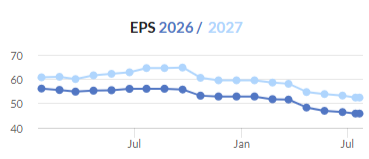
EPS forecasts are gliding downwards:
Long-term, I would expect this stock to enjoy good balance sheet support, as 70% of pubs are owned freehold. And in the words of the most recent interim statement:
The company's freehold assets have not been revalued for over 25 years.
So in the bigger picture, I’m not very negative on JDW. However, I am going to respect the downward trend in earnings forecasts and therefore take a fully negative stance in the short-term.
Roland's Section
Hardide (LON:HDD)
Up 21% at 90p (£69m) - Trading Update - Roland - GREEN =
Hardide provides tungsten-based coatings that help prevent corrosion and erosion of on engineering components. Graham upgraded our view on this business in May, recognising its strong momentum. This has proved to be a good call.
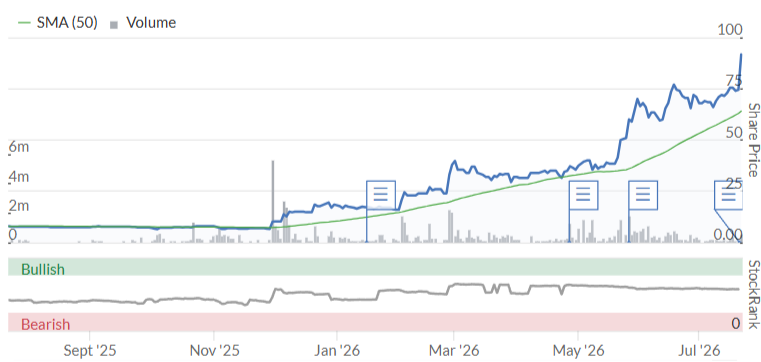
Hardide shares had already risen by 26% since then, before today’s stonking upgrade. This has seen broker Cavendish lift its FY26 earnings estimates by 33%, prompting a 20%+ share price surge:
Let’s take a look at what’s new..
Trading update: key points
The strong momentum in the business continues.
Q3 revenue of £4.1m - this compares to revenue of £4.8m for the whole of H1.
Growth has been driven by new contract winds and improved operational performance supporting higher output rates.
Operating profit margins “higher than anticipated”, reflecting successful management of costs. This mainly refers to supplies of tungsten gas, where the company has diversified its sources of supply, forward purchased 50% of requirements for 2027 and is maintaining higher inventories to offset commodity market volatility.
Confident in doubling revenue this year and then doubling revenue again over the next two to three years.
To support growth the Board has approved £4.5m of capital investment in three new coating reactors, to be funded through internal cash and debt as required.
Outlook
As a result, the Board now expects that full year financial performance will be materially ahead of its previous expectations [for the year ending 30 Sept 26].
Hardide helpfully includes details of previous consensus forecasts (revenue: £13.4m, EBITDA: £4.3m).
With thanks to broker Cavendish and Research Tree, we have access to a full set of updated forecasts today. These show impressive upgrades to FY26 forecasts – with less than three months until the end of the year, I would expect a high level of confidence in the new FY26 estimate:
FY26E adj EPS: 5.4p (+33% vs 4.0p previously)
FY27E adj EPS: 7.7p (+43% vs FY26)
At the last-seen share price this morning of 90p, these forecasts put Hardide on a FY26E P/E of 17, falling to a P/E of 12 in FY27.
Roland’s view
I don’t know this business especially well, but what seems to have happened here is that revenue growth (through new business) has led to improved capacity utilisation and generated powerful operating leverage. This means that fixed costs have shrunk relative to revenue, catapulting the group into profitability:
FY24: 48% gross margin / operating loss
H1 25: 54% gross margin / operating loss
FY25: 57% gross margin / 4.3% operating margin
H1 26: 65% gross margin / 26.8% operating margin
FY26E: 62% gross margin / 35.2% operating margin
This explains why a 125% increase in revenue this year is expected to translate into a 2,600% increase in earnings (from 0.2p per share in FY25 to 5.4p per share in FY26).
The result is that investors have had to rapidly re-evaluate the valuation of this business. It’s worth noting that according to our data, this is the sixth earnings upgrade in the last 18 months:
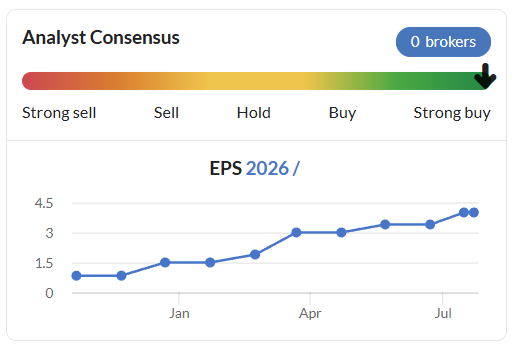
My impression is that the market is still catching up – a FY27 P/E of 12 doesn’t seem excessive, although it’s worth remembering that the company is now investing in significant new manufacturing capacity. If demand from new orders doesn’t keep pace with this, profitability could worsen again.
Management commentary on the outlook for new business sounds broadly reassuring to me today, although I don’t have the in-depth knowledge of the business needed to evaluate these prospects:
The growth is anticipated to be achieved by diversifying the customer base, growing existing key accounts, including progressing ongoing supply arrangements with its major energy sector customer in North America, and developing the potential for significant revenues in the Middle East from a similar end use application. In addition, the Company has a growing pipeline of new business opportunities that it is seeking to convert in the short to medium term, including in new end use sectors such as semi-conductors.
I would guess that today’s upgrade and the introduction of FY27 forecasts will result in an improvement to Hardide’s StockRank – possibly even a Jump.
With such strong momentum and a seemingly reasonable valuation, I am going to leave our positive GREEN view unchanged today.
James Halstead (LON:JHD)
Down 4.5% at 120p (£501m) - Trading Update - Roland - BLACK (AMBER/GREEN ↓)
(At the time of writing, Roland has a long position in JHD.)
I don’t think anyone would really dispute the financial quality or balance sheet strength of this family-controlled vinyl flooring business. Nor could we really argue about its long-term focus and consistency. But I think the company’s recent record on growth is probably open to debate.
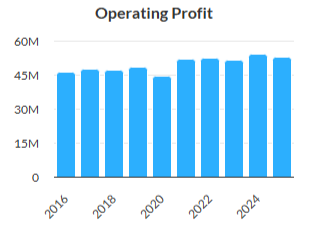
James Halstead’s operating profit has only risen by 15% over the last 10 years – that’s an annualised growth rate of 1.5%:
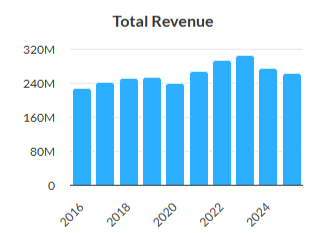
Perhaps worse is that revenue has been shrinking from the record high set in FY23. The group’s top line has grown at an annualised rate of just 1.7% since 2016:
In fairness, there are plenty of good reasons for this. Even ignoring pandemic disruption, many of the company’s end markets (commercial vinyl flooring and luxury vinyl tiles) have been subdued. Supply chain conditions and cost inflation have put additional pressure on the business.
Despite these mitigating circumstances, we need to consider growth – historic and prospective – in our assessment of any business. This is especially true when it comes to valuation.
I’m on record as suggesting James Halstead could be cheap, but today’s update is the second profit warning in four months. Does my positive view still hold?
Headwinds: we’ve got ‘em
All of this brings me to today’s trading update, which covers the year ended 30 June 2026.
Halstead’s commentary is generally brief, but it’s also transparent and detailed. Here are some of the key points:
Market conditions: gained UK market share, with modest increase in sales. The company’s presence in the UK market is mainly through repair and refurbishment in education, healthcare and hospitality. As we regularly see in the DSMR, these are sectors where many end user budgets are under pressure.
Elsewhere, Europe remained “solid but muted”. However, North America and the Middle East were 54% ahead of comparatives, with South Africa 25% ahead of comparative figures. These are smaller markets for the company, but this level of growth suggests Halstead is gaining share and establishing a reputation.
Profitability & Pricing: the Iran conflict caused many suppliers to “immediately” add surcharges to their pricing. Halstead opted for a different approach:
As a manufacturer with many end contractors committed to projects, we felt this was a situation to absorb some of this cost and to buffer the effects to the end contractors, at least for the short term.
Management explains that while much of their business is through distributors, “our connections to end projects are strong, especially overseas”. In markets where demand was already “fragile”, the company decided that maintaining previously agreed pricing was the “responsible course of action”.
While I wouldn’t question this company’s long-term commitment to its customers, the decision to hold prices wasn’t entirely selfless:
Furthermore, James Halstead carries significant stock and with many competitors not as well placed, we saw it as an opportunity to take some extra volume as those competitors raised prices.
Ultimately, this comes back to the strength of the group’s balance sheet, which allows Halstead to provide superior service and availability, even in disrupted markets.
June trading: UK sales were strong last month, but the company admits this may have been due to contractors buying ahead of July’s planned price rises. This raises the risk that ‘pull-forward’ could adversely affect FY27 results.
Outlook
Halstead provides clear guidance relative to last year’s results – so anyone can see the numbers and work them out quite easily.
In summary, the Company anticipates that sales will be marginally below the 2025 comparative with profit approximately 10-15% below that of last year.
FY25 revenue and profit after tax were £262m and £40.6m respectively.
Applying the mid-point of today’s guidance gives me the following FY26 estimates:
FY26E revenue: c.£260m
FY26E profit after tax: c.£36m
With thanks to the company’s joint brokers, Zeus and Panmure Liberum, I can see confirmation of my estimates today and revised EPS forecasts:
Panmure Liberum:
FY26E EPS: 8.7p (prev. 9.9p)
FY27E EPS: 9.8p (prev. 10.4p)
Zeus:
FY26E EPS: 8.7p (prev. 9.4p)
FY27E EPS: 9.4p (prev. 9.7p)
Both brokers have converged on an FY26 EPS estimate of 8.7p. Given that the year has ended, I guess we can be fairly confident the real figure will be close to this.
This puts James Halstead on a FY26E P/E of 14, with a prospective dividend yield of 8%.
Interestingly, both brokers expect the company’s strong cash generation to have continued despite last year’s headwinds. Net cash is expected to have been over £70m at the year end.
It’s this balance sheet strength that allows Halstead to maintain high levels of stock availability and defer price rises to support existing projects. Having plenty of cash also allows the company to maintain a near-100% dividend payout ratio.
Roland’s view
I am a James Halstead shareholder, so I’m talking my own book and am naturally biased.
To me, the fact that James Halstead can navigate through periods of external turbulence without needing to compromise its strategy or risk its balance sheet is a sign of the quality and likely durability of this business (which has been trading since 1915).
Polyflor has an international reputation as a high quality product and is used in many major public facilities and large commercial installations. The group’s strategy of supporting its customer base in recent years has not led to any noticeable reduction in profitability and quality metrics remain excellent.
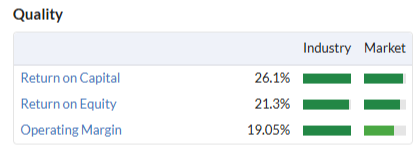
This approach also feels right to me. After all, which of us wants to deal with a counterparty who pulls the rug out on previous pricing at the drop of a hat?
On the other hand, I recognise that this business is to some extent at the mercy of external conditions. There’s a risk James Halstead will remain stuck in a low-growth scenario for some time. Holding the shares in this scenario may carry an opportunity cost.
Over the longer term, the worst case might be that pricing power and profitability will be gradually eroded as the company scrabbles to hold onto market share.
Fortunately, I don’t see any sign of this at the moment. As far as I can see, the company is likely to be gaining share in a difficult market and is well positioned for any upturn.
For me, this is an income holding. I am more likely to top up than sell following today’s update.
However, I have to recognise the lack of momentum here and consider valuation.
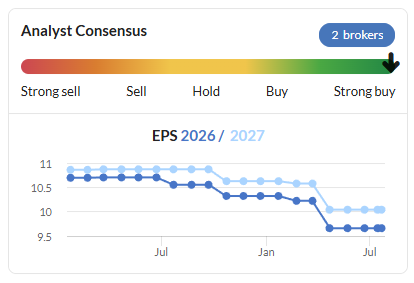
While the 8% yield is certainly attractive, this year’s forecast dividend of 9.1p is no longer expected to be covered by earnings. The group’s strong cash position should mean the payout remains safe, but an uncovered dividend is never ideal.
Valuing the business relative to earnings also suggests to me that a share price recovery may hinge on a return to growth. Despite the strong quality metrics, the FY27E P/E of 13 is not necessarily cheap if EPS forecasts flatline or even fall further.
On a long-term view, I remain fairly confident this stock should remain an income compounder, but I have to respect the lack of momentum at present.
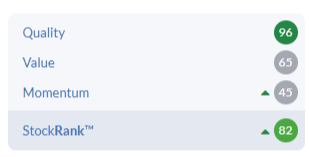
For this reason, I’m going to move our view down by one notch to AMBER/GREEN today to reflect near-term uncertainty.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Graham / Roland
it would look like you meant to do a report on the Greencore (LON:GNC) Q3 TU released this morning, it's ticker is included in the DSMR title but there is no section for them apart from the usual RNS notification. Did one of you forget to attach it? Looking forward to reading it if there is one.
TIA
That's in there now, Helvellyn!
Great thanks Graham .
EasyJet deal may be off due to EU legislation. Down 10%. Tried to sell my holdings. I cannot get a quote.
I see Mortgage Advice Bureau (Holdings) (LON:MAB1) has jumped 34% today to around 750p. Sounds like a takeover in the wings.
Anybody know anything???
I thought it was down 1-2% today?
I wish!
looks like a fat finger trade recorded @ 748 and not 548
Mortgage Advice Bureau (Holdings) (LON:MAB1)
But easyJet (LON:EZJ) down 8% is not a FF, but I dont see any news of the recent offer being withdrawn. !!
Two exciting updates from Mello this afternoon...
MelloMonday 27th July from 5pm https://www.melloevents.com/mm270726
Legendary figure in UK fund management, Gervais Williams of Premier Miton (LON:PMI), joins us to share his latest insights on the market in a fireside chat. Last but (we hope) definitely not least, the BASH returns with John (aka The Oak Bloke) and Jamie Ward (aka Wonder Stocks). John covers Audioboom (LON:BOOM) & Jamie will be covering ROSEBANK INDUSTRIES (LON:ROSE). Between these sessions will be company presentations from Frp Advisory (LON:FRP) ECO Animal Health (LON:EAH) who both had results recently. Use code MMSTOCKO50 for 50% off. If you are a shareholder in any of the presenting companies, you are eligible for a free ticket for this webinar with code SHMM26. Hope to see you on zoom this Monday.
Mello London 17th & 18th November https://www.melloevents.com/mellolondon2026
Our headline in-person event returns to Chiswick with tickets now live. You can secure an early bird one or two day ticket for £69 or £99 respectively saving you up to £100 by registering early (available for just two weeks). Plenty more updates to follow here but to whet your appetite, Lord John Lee and Richard Staveley will both be with us and on our main stage.
“fireside chat” is an import from the USA that should be immediately deported.
In that case, let's go with... Interview with Gervais Williams, Premier Miton. Not sure you would want to be "fireside" in these recent temperatures anyway.
M P Evans (LON:MPE) reports H1 production and unit realisations and share price up 8.75% to 1840p. This is only two months since the price crashed from 1900p to 1370p - a near 30% fall following declared intervention on palm oil exports by Indonesian government. Previously held in my version of Ed’s QVM Naps approach but sold as a consequence of this news and consequent fall. Just about broke even but clearly a mistake - what did I miss?
There was early reaction to the declared intervention but as the scenario was to cover exports (and related fiddles) and M P Evans (LON:MPE) and AEP Plantations (LON:AEP) sell locally the proposals don't affect them - both issued statements to that effect.
I continue to hold AEP and only have to worry about el nino, crop damage and related price increases.
Be interested to hear what Ed and the team think about this article by Edward Chancellor (source: Moneymakers). If it turns out to be accurate also possible implications for Phil Hoffer’s strategy though guess the need for high quality ranking alongside momentum may provide a bit of support if the worst happens! May only be available to subscribers but could be published elsewhere.
https://money-makers.co/2026/0...
First of all I'm no investing expert.
Second my QM Growth blueprint integrates Quality & Growth alongside momentum.
Every strategy has some downsides. The downside of the High QM Growth approach I use is the drawdown during wider market weakenss. it is challenging (maybe too challenging for some). I hold high quality stocks that are exhibiting strong growth through this downturn. In my experience these stocks rebound shaprly. I also strive to zoom out and I keep looking at this chart. The S&P 500 since 1930's. This is a logarithmic chart.
For me the drawdowns are only a problem if I need the money in the next 3 years ... and I peronally don't. I've recently had on average ~20% drawdowns across my portfolios but I also had that in March only for them to recover and set new highs.
The same happened in a sharp drawndown in Jan 2025 and again in April 2025.
For the whole of 2022 I sat on my hands, no selling, no buying ... just waiting.
It's not for everyone but it's better that people understand and are prepared.
Best of luck
Yesterday we had a brief conversation in the comments section about Rentguarantor Holdings (LON:RGG). I wasn't sure what the potential market is but I've now looked at this.
There's a Cavendish note out today that's very helpful - see their site or research tree. The forecasts are stretching but they put this on a 2.8p EPS next year and 5p in FY25. I imagine if those forecasts can be hit this will be on a p/e of at least 20 meaning a share price of 56p in the next 12-18 months is possible from the current 35p.
The company has a useful investor hub: https://investorhub.rentguaran... which includes a recent corporate presentation with some detail on market size. Looking at the addressable market size, if they can get say 10% of the tenancy contracts signed per year you could be looking at revenue of maybe £140m. In reality this might be higher as in yesterday's update they noted their average contract size is now £915. Plus, a tenant has to pay annually to guarantee that year's rent - so the market isn't just limited to the number of new contracts being signed but existing ones as well.
£140m might not sound huge but it offers reasonable upside from the current market share and in their original IPO document from 2021 (they were originally on Aquis) they noted an intention to look at international expansion or offering complementary services.
One of the biggest risks for the company seems to be regulatory. If a court deemed their product to be an insurance product then they would need to get FCA and PRU approval - which could cause them to suspend or withdraw their product. I have no idea of the likelihood of it being challenged as an insurance product
I have opened a small position.
Is there a two edge sword in terms of risk with Rentguarantor Holdings (LON:RGG)
As their gross margins are 70%, that's really attractive. What's to stop someone else setting up a competing service? There are surely others in the industry looking at them and saying "wow, they make so much, that's a fab business model". Especially as there's no regulatory hurdle, etc.
And if regulatory hurdles do come in, that might slow future growth, negative for profit margins (eg insurance-like capital requirements, etc).
Sounds a bit damned if you do, damned if you don't type scenario going forwards for RGG?
Is there a two edge sword in terms of risk with Rentguarantor Holdings (LON:RGG)
It's really interesting but also, I suspect, quite risky. Property Franchise (LON:TPFG) already offer a tenant guarantor service via Let Alliance but they don't have the depth of the RGG data who support non-traditional renters like students, universal benefit recipients and overseas workers. It's a data driven AI approach that so far has allowed them to take on higher risk clients and make a significant margin. This, along with deep integration into rental agencies, has driven their business.
Right now the student market is booming: 600,000 overseas students who have no choice but to use a professional tenant guarantor service. And success there has driven RGG's explosive growth because they were smart enough to see the opportunity. Whereas previous most overseas students paid upfront that's been made illegal (mad, I know, but there you go ...) and RGG spotted the opportunity and adjusted faster than everyone else. They've somewhat insulated themselves for the next three years with three year cover contracts, but competitors will have adapted for next year's student cohort.
The Renter's Act makes it illegal for the agents to push RGG's product over others. They must present multiple options. Success for RGG going forward will depend as much on marketing to consumers as to agencies.
RGG has the best technology, and the fastest underwriting. So far that's worked. The current boom is probably a one off (albeit possibly an extended one) but it won't be simple to compete with their extended data set and AI capabilities (although that's a black box, as with all AI offerings).
Overall I think this is a worth a dabble, but if I were them I'd be aiming to drive growth as hard as possible and sell out as high as possible rather than waiting for the market to settle over the next few years.
timarr
Thanks for the detailed comment, timarr!
Historical performance data on guarantees would be a moat as a first mover... so that's interesting.
I guess the key risk is whether management have relaxed "underwriting" standards to drive growth... will take a closer look to see if I can get comfortable.
Hi
Google Finance has forced me to use the new Beta version on my lap top. It takes some getting used to and its latency is slow. But the integration with AI tools to explore why things are changing in stocks is pretty good. As is its ability to examine my own watch lists and pick out moves and news.
Regards
Howard
A report in Money Mail may be of interest to the not yet retired, it says "LSE 24 will operate separately from the Main Market, which will continue to operate its existing trading hours of 8am to 4.30pm." On trials this year, if successful it will be operational in 2027.
Bloomsbury Publishing (LON:BMY) gets a mention today, I see.
I hold on account of its QGARP qualities. Fwd PE is 14.6, putting it in the buy-zone. ROE is OK, though not spectacular. Perhaps ROE should be taken with a pinch of salt to some extent. Some companies do well even without mighty ROEs and without getting themselves into all kinds of overexpansion troubles.
BMY has net cash, which is nice. It's been growing its dividends at a rate of 13% pa over the last 5 years. Imagine that.
Looking out over 10 years, revenues and EPS has more than doubled without tapping the market, which I like to see for growth purposes.
BMY has a lot of interesting stuff that looks to be coming out, too.
So yeah, have at is what I'm saying.
I personally don't pay too much attention to ROE unless it's an asset based company (eg banks or REITs). Worth noting that companies with weak balance sheets can often have high ROE since they don't have a lot of equity - BMY is the opposite of that with a net cash position which may partly account for the modest ROE. The key thing for me is EPS and dividends which have both been growing very consistently over the past few years.
ROE
It’s exactly the opposite on what you said-:)
All the best
The point is that companies with really strong balance sheets - such as BMY - can often have relatively low ROEs. Because they don't take on much debt, they rely heavily on shareholder equity—and that huge equity base ends up watering down their ROE.
That’s correct!
But for the banks can be very manipulative and it’s something I have personally experienced just before the financial crisis.
All the best
Well, most bank equity was wiped out after the financial crisis because of very high leverage and poor quality loans. I'd say bank metrics look much more secure today, although I personally don't hold any as most are now trading on a large premium to book value after the recent strong run.
Personal group (LON:PGH) solid if unspectacular, double digit growth, both divisions doing well, 90% retetiin rate. 29m cash no debt
Retention can't spell!
James Halstead (LON:JHD) (I hold)
Hi Graham, would you be able to cover James Halstead today please?
I have a small position only (down 10%) and am debating whether to add to it, holding on for the yield, and awaiting recovery.
The Stock Rank has risen over the last few months and Lord Lee is a holder too.
Got that request, Richard! Cheers.
Thanks for covering James Halstead (LON:JHD) Graham I had been musing it as an income stock for my retirement portfolio, they have loads of cash on the balance sheet but the constant downwards direction of the share chart has put me off.
They do look a quality stock but equally they are another one who's fate is most likely tied to the housing market which is showing no signs of life currently.
Sigmaroc (LON:SRC) I hold
Lots to like in this trading update. All numbers moving in the right direction and positive outlook comments. SRC holds a strong position in its market not yet reflected in the share price in my opinion. Would appreciate the teams view today.
Wow yet another upgrade at Hardide (LON:HDD). Cavendish raised EPS estimates by 16.5% last time and today they've raised them by another 33%! New 2027 forecasts (year beginning this September) show a further 43% upgrade and a EPS of 7.7p. Based on an opening price this puts them on a p/e of around 10 for FY27 despite the momentum. I've lost track of how many times this share has bagged this year!
(Disclosure: I've decided to open an initial position this morning based on the Cavendish note and will do some proper research today or tomorrow)
Thanks for this. I am fortunate in having a small position and a tad less fortunate in it not being a lot larger.... Do Cavendish give a revised TP by any chance?
Charlie - Cavendish are one of a handful of 'free to investor' research houses. As such you can sign up for free and see all of their research. Worth noting that the material from these brokers can be a bit like promotional stuff issued by the companies who pay for it so be aware of that and also that the notes are often a bit brief unless an 'initiation of coverage' piece. Nevertheless you do still get forecasts for revenue and profit so they can provide a useful yardstick on progress.
If you hold a number of small caps, it is well worth your time getting acquainted with these brokers (others include Edison, Equity Development, Progressive and Zeus). Start with Cavendish and you will find their TP for Hardide!
Careful of the marketing angle to these notes
Anthropic to pay $1.5 bil for training it's AI models on Bloomsbury Publishing (LON:BMY) books. Would've been a hell of a lot cheaper if they just bought the books!
I hope this will set the precedent for more suits against this form of plagiarism.
Why are Bloomsbury Publishing (LON:BMY) stating in their RNS
Bloomsbury had £29.2m net cash as at 28 February 2026. Bloomsbury's capital allocation priorities are organic investment, debt repayment to reduce interest costs, dividend payments and bolt-on acquisition opportunities.
Seems out of place, as well as out of date. ?
Probably just want to make the point that they should now have net cash of at least £40m
Here are the specific details of the Bartz v. Anthropic settlement: [1, 2]