Daily Stock Market Report (Wed 27th May 2026) - ZTF, BPM, CHRT, BOWL, HDD, PETS, HICL, SMT

I wrote last week about Chinese, Indian and Korean vessels making it through the Strait of Hormuz.
Yesterday, two more supertankers made it through the Strait: one from Singapore and one from Greece. A few Iranian oil tankers also passed through without incident.
According to Bloomberg, tankers are travelling together in small groups - safety in numbers, I guess. They are crossing through a diplomatic grey area, without a US escort but likely having some sort of agreement with Iran.
It’s possible that other vessels have also made it through, but have not been detected due to signal interference.
I find this one of the most intriguing elements of the conflict: commercial vessels floating through waters where jet and drone attacks are also occasionally taking place, and (allegedly) where mines are being placed!
The best-case scenario is that a deal is announced in the next few days. I’ve trained myself to be an optimist - it feels necessary as an equity investor - so I’m going to hope this happens very soon, that commodity prices go back to normal, and our focus can then move on to something else. Negotiations between the Trump administration and Tehran continue.
Overnight market movements:
The FTSE is set to open down 0.1% at 10,490
S&P 500 is unchanged at 7,525
Brent crude (July delivery) is down 2% at $97.90
Gold is unchanged at $4,530
Bitcoin is down 0.5% at $75,700
Finished for the afternoon, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£217bn | SR75) | FDA has extended PDUFA date to review additional data requested to support the NDA for camizestrant in combination with a cyclin-dependent kinase (CDK) 4/6 inhibitor for the treatment of patients with HR-positive, HER2-negative advanced breast cancer whose tumours have an emergent ESR1 mutation. | ||
Scottish Mortgage Investment Trust (LON:SMT) (£16.8bn | SR N/A) | NAV +27.4% for the year to 31 March 2026. “A notable contributor … was SpaceX, where continued strong operational execution has led to a significant upward revaluation, increasing its position as the Company's largest holding by some margin.” SpaceX is reported as 19.3% of the portfolio at 31 March. | AMBER = (Graham) [no section below] Flagging this primarily because it will be a popular way for UK investors to access SpaceX. In the past, SMT made a fortune investing in Tesla, and the long-term record remains excellent. The total return over ten years is 435%, beating the FTSE All-World Index (234%) by a wide margin, and FY March 2026 marked a return to form. At the end of the year, SpaceX accounted for 19% of the Trust's assets, "a degree of concentration which is highly unusual for us". SMT say that we should think of SpaceX as "a dual monopoly: the world's dominant launch provider and a global connectivity utility with the potential for software-like margins". The Trust will be subject to a lock-up at the forthcoming IPO, and so it will not be able to immediately reduce its holding in Musk's space venture even if it wanted to. The Trust's other top holdings can be reviewed here , including many names with which you'll be familiar, and seven of the world's top ten most valuable private companies. As for valuation, SMT's NAV per share is 1403.58p according to an RNS published yesterday. SMT's share price, however, is over 1500p. The Trust has been regularly issuing shares at a premium to NAV, "owing to demand in the market". I would not wish to pay a premium to NAV in order to buy into a trust, but demand for SpaceX exposure is clearly very high. While I personally believe that SpaceX's planned IPO valuation is absurd, I'm happy for us to take a neutral stance on SMT. | |
HICL Infrastructure (LON:HICL) (£2.4bn | SR86) | NAV per share up 4.6% to 160.2p, NAV Total Return of 10.3%. 12.2% portfolio return, “significantly ahead of expectations”. Dividend of 8.35p with cash cover, FY27 target reiterated at 8.50p, with 8.65p for FY28. | AMBER = (Roland) [no section below] The discount to NAV has narrowed in recent weeks, but shares in this infrastructure investment trust still offer a useful 16% discount to today’s reported NAV. A key priority for shareholders is the sustainability of the dividend. Today’s results seem positive in this regard, with cash cover of 1.1x from continuing assets. Cover increased to 2.4x when disposals are included, but I’d prefer to see cash from asset sales used to fund new investments (or buybacks). One challenge facing HICL is the growing maturity of its portfolio of UK Public-Private Partnership assets. Replacing these with assets that can support long-term growth and attractive income streams is a key priority. I think the company is making progress and am encouraged to see HICL join the growing number of trusts where management fees are linked to market cap. This means that if the stock is at a discount to NAV, its managers get paid less. Following this strategy last year would have cut management fees by 11%. On balance, I’m positive on HICL as a high yield choice, but I think the stock’s forecast dividend yield of 6.3% is probably up with events. I’m going to take a neutral view today, noting that earnings are expected to remain flat this year. | |
Greencore (LON:GNC) (£1.9bn | SR80) | “… strong half year results for the new Greencore, having acquired Bakkavor in mid-January.” Pro Forma revenue +3.2%, pro forma adj op profit +15.3% to £73.3m. Outlook: expect to deliver FY26 adj operating profit in line with current expectations. | ||
Bodycote (LON:BOY) (£1.43bn | SR84) | Year-to-date revenue +1.9%, with core revenue +9% and strong growth in Aerospace & Defence and Industrial Gas Turbines. FY outlook maintained, expect core revenue growth to moderate in H2. | ||
Pets at Home (LON:PETS) (£830m | SR87) | Revenue -0.8%, pre-tax profit -28.3% to £86.5m. Adj EPS -29.7% to 14.8p. Dividend of 7.4p plus further £50m buyback. FY27 outlook: “we are comfortable with consensus expectations” for adj pre-tax profit of £98m. | GREEN ↑ (Roland) [no section below] I was positive about Pets at Home in a Stock Pitch in April and today’s results don’t change that view. While the pet sector is currently exposed to consumer spending headwinds and post-pandemic pet demographics (many are enjoying a healthy mid-life), both factors should normalise over time. On a medium-term view, I think PETS’ full-service business model and c.25% market share remain attractive. I’d also note the excellent cash generation last year – free cash flow of £62m gives a yield of 7% at current levels. Cost inflation was also well controlled, at under 2% last year – a contrast to some other consumer businesses. My working assumption is that the experienced new CEO will improve the performance of the retail division (including online) while delivering incremental growth in vet. Improvements to retail could boost cash generation and profitability, lifting ROCE above the c.8% achieved last year. In that scenario, I think the shares might deserve a higher rating than the current forward P/E of 12. I’m going to stick my neck out and upgrade to a positive view following these results. | |
Cohort (LON:CHRT) (£580m | SR29) | FY26 revenue +12% to £303m, adj operating profit +31% to c.£36m, ahead of market expectations. Closing order book of c.£620m (FY25: £615m, includes 80% cover for FY27 revenue forecasts: “confidence in a strong 2026/27”. | AMBER/GREEN ↑ (Graham)
We’ve been a little cautious on this one, worried about the H2 weighting it needed to hit full-year forecasts and the high valuation. We were wrong on the first count, although I think there is still an argument to be made that the valuation here is punchy. The ValueRank is only 19, and Stockopedia categorises it as a Falling Star. But when the facts change we should change our minds, and it turns out that there was nothing to fear about the H2 weighting - the company has more than fully delivered on what was expected in H2. So I’ll nudge us up to AMBER/GREEN today. | |
Hollywood Bowl (LON:BOWL) (£436m | SR66) | SP +15% Revenue +9.5%, UK LFL +1.3%, Canada LFL -3.2%. Adj pre-tax profit +8.1% to £32.1m, adj EPS +11.3% to 14.5p. Outlook: confident in delivering on FY26 expectations. | AMBER/GREEN = (Roland) Today’s results are in line but have been met with a response that suggests to me investors were expecting much worse. The macro environment is certainly not easy – BOWL’s centre staffing costs rose by 18.5% in H1, but its ability to increase prices was constrained by lower games volumes and pressure on consumer disposable income. I’m going to give the company the benefit of the doubt today and leave our view unchanged – I do still think this is a well-run business with some attractive qualities. But with the earnings outlook flat this year, I’m not far from the point at which I might consider switching to neutral. | |
B.P. Marsh & Partners (LON:BPM) (£243m | SR90) | Final Results for the year to 31 Jan 26 & Directorate Change | NAV +10.3% to £360.2m (959.8pps), total shareholder return of £41.7m (12.8%). Brian Marsh moves from chairman to “Founder and Life President”. New chair appointed. | GREEN = (Graham - I hold)
I’m very glad to be a shareholder here again, but there are a few details worth ironing out. I estimate current NAV as 937.5p, implying a discount to NAV today of 26%. I’d also like to reiterate that the diversification of the portfolio is limited, due to some large positions - the level of concentration of BPM’s portfolio is equivalent to holding 7 or 8 different positions. Just something to be aware of, in case you are treating this like some sort of mutual fund - it’s more concentrated than that. I wrote a Stock Pitch on this company in March: here's the link. |
Sovereign Metals (LON:SVML) (£218m | SR19) | Monazite concentrate containing the most critical and highly valuable heavy rare earth elements Dysprosium (Dy), Terbium (Tb) and Yttrium recovered from four planned pits in the Kasiya DFS mine plan, including pits scheduled for Year 1 production. | ||
Zotefoams (LON:ZTF) (£198m | SR76) | Year-to-date revenue +26% to £64.1m, led by EMEA. Footwear growth moderated but Transport & Smart Technologies continued to grow. 2026 outlook: full-year expectations remain unchanged. | AMBER/GREEN = (Roland) I am tempted to upgrade to be fully positive on Zotefoams, as I think the business is improving and the forward P/E of 10 looks undemanding. However, the group’s continued heavy exposure to Nike (where earnings forecasts were cut recently) and last year’s changes to segmental reporting mean it’s a little hard to be sure about the profitability and scale of the group’s other main division. While it’s possible that I’m being too cautious, I’m going to mirror the falling StockRank and leave my moderately positive view unchanged following today’s in-line update. | |
Afentra (LON:AET) (£168m | SR65) | Afentra has been awarded a 35% operated interest in KON4 alongside Angolan partners. The signing of the contract is expected at a later date. KON4 is situated in a historically productive area, including the Quenguela Norte field where production peaked at 12,000 bopd before being shut in in 1999. | ||
Aptitude Software (LON:APTD) (£119m | SR38) | Two new Fynapse enterprise wins so far in FY26. Rationalising wider product lines. Strategic review remains ongoing with a range of options under consideration. | ||
Andrada Mining (LON:ATM) (£86m | SR22) | Approval for conditional funding of NAD98 million (c. £4.4 million) Bank Windhoek and the Development Bank of Namibia. The expanded diamond drilling programme at its Lithium Ridge project has now been completed. Assay results confirm extensive, high-grade lithium mineralisation, up to 3.02% Li₂O over 5m. | ||
Arrow Exploration (LON:AXL) (£72m | SR69) | Average corporate production of 4,715 boe/d (Q1 2025: 4,085 boe/d). Adjusted EBITDA up 22% ($14.1 million). Net income of $5.2 million. Cash $24m. "The focus for the remainder of 2026 will be to drill additional wells at the Icaco pad, drilling development wells on the Alberta Llanos and Carrizales Norte pads and numerous well recompletions to improve productivity in our currently most prolific fields." | ||
Watkin Jones (LON:WJG) (£59m | SR53) | Revenue down 22% to £100.2m. PBT £0.0m (HY 2025: £0.2m). Adjusted net cash £61.3m. “We have achieved a resilient performance in the first half… While market conditions remain challenging and continue to impact the pace of recovery, the long-term fundamentals of our end markets remain attractive…” | ||
Hardide (LON:HDD) (£40m | SR59) | Orders received from its large North American energy customer to cover the remainder of FY Sep 2026. Value £2.4m is greater than the Board's previous expectations for this current financial year. This will have the effect of materially improving revenue and overall financial performance expectations for FY26. “We expect these orders to continue…. developing a mutually beneficial schedule for orders and deliveries which will underpin FY27.” | GREEN ↑ (Graham)
I’m going to respect the momentum here and turn fully GREEN for now. Long-term, I don’t know if this is a quality business. It has been listed for over 20 years and for most of this time has been loss-making and not very impressive. The company's recent success has been driven by a small number of customers, making this a rather double-edged situation. That said, I won’t argue against the momentum this share is currently enjoying. Recent results have genuinely been excellent and if they hit the latest Cavendish forecasts, they are on track to achieve spectacular ROE and ROCE this year of c. 47%. | |
Abingdon Health (LON:ABDX) (£30m | SR24) | Abingdon Health USA, Inc. has been certified as eligible to earn up to US$370,000 in performance-based Wisconsin tax credits over a three-year period. | ||
Kendrick Resources (LON:KEN) (£31m | SR21) | Completes internal review and analysis of historic and current work, resulting in targets consistent with expectations for the Company's flagship rare earth projects at Teufelskuppe and Kieshöhe in SW Namibia. These projects are subject of a 70% earn-in interest by the Company. | ||
ImmuPharma (LON:IMM) (£28m | SR4) | Loss for the period £1.8m (2024: £2.5m). Cash £1.4m at Dec 2025. Subsequently raised £6.5m. CEO: "ImmuPharma is entering a pivotal phase, focused on securing a commercial partnership for P140 in 2026 while continuing to develop its broader portfolio, with a key focus on fast tracking Kapiglucgaon over the next two years.” | ||
Europa Oil & Gas (Holdings) (LON:EOG) (£21m | SR19) | 17 months: revenue £3.9m (12 months to July 2024: £3.6m). Pre-tax loss £2.7m. Cash balance £0.3m. Subsequently raised £4.1m. Outlook: well placed to capitalise on momentum, with “EG-08 Farm-out Agreement and anticipated drilling of Barracuda later in the year in particular providing further certainty for the Company's short-term outlook.” | ||
Tekcapital (LON:TEK) (£16m | SR55) | Loss after tax $17.1m caused by the unrealised depreciation of its portfolio. Net assets $55.1m (2024: $70.1m). NAV per share $0.23. | ||
RTC (LON:RTC) (£15m | SR99) | Q2: high fuel costs have impacted margins in Rail and Energy. Materially lower demand for temporary labour. Permanent vacancies at lowest point since 2021, and resignation rate at lowest level since Covid. | ||
Nanoco (LON:NANO) (£13m | SR51) | Proposed cancellation in order to further reduce operating costs. Annual savings of £0.7m. Cash balance £10.1m as at 19th May 2026. Cost savings will extend the Group's cash runway, with a view to being break even in the medium term. | ||
Jangada Mines (LON:JAN) (£12m | SR15) | Ongoing exploration at the Molly Gold Project in Brazil. Molly 1: High-Grade Gold Confirmed, drill holes 3A and 3B intercept significant gold, silver and copper mineralisation. Molly 2: Discovery Confirmed: Maiden Discovery Hole 7A demonstrates previously undrilled deposit related to the Molly 1 system. |
Graham's Section
B.P. Marsh & Partners (LON:BPM)
Up 2% at 688.55p (£248m) - Final Results for the Year to 31 January 2026 - Graham - GREEN =
(At the time of writing, Graham has a long position in BPM.)
I’ve been consistently positive on this insurance investor, and I don’t think today’s results are going to change my stance. So let’s review it quickly.
Key points:
NAV increases 10% to £360m
Total shareholder return (including £8m of dividends) of 12.8%
NAV per share 1,009.9p, or 959.8p fully diluted.
The equity portfolio generated a return of 21.4%
Following £8m of dividends paid in FY January 2026, BPM is planning to pay £13m in FY January 2027 and £7m in FY January 2028. This follows some very successful investments and disposals, which gave rise to an unnecessarily large cash balance. The cash balance is currently £29.6m.
Board changes: Founder and Life President Brian Marsh OBE stepped down from the Board yesterday, after 25 years as Executive Chairman and then a brief period as non-Executive Chairman.
On the topic of Brian Marsh, it has been rumoured that COO Alice Foulk is his daughter. I contacted the company’s PR representatives back in March about this and they informed me that Brian and Alice are not related. So the accusations of “nepotism” don’t seem to have any factual foundation.
He is still the largest shareholder, owning 39% of the business:
When I founded B.P. Marsh my belief was simple: that patient, partnership-led investment alongside talented entrepreneurial management teams could create exceptional long-term value. More than three decades on, with Net Asset Value having grown to £360.2m and a portfolio spanning international insurance and financial services markets, I believe that philosophy continues to be valid…
What gives me greatest pride, however, is not simply the financial performance, but the culture and reputation that the business has built over many years, one based on integrity, long-term thinking and genuine partnership.
The company has a new non-Executive Chair, Rebecca Shelley, with a background primarily in corporate communications (e.g. Group Communications Director at Tesco and Prudential).
CEO Dan Topping summarises the year in review:
The year was characterised by disciplined capital allocation and the continued expansion of the Group's international specialty finance and insurance distribution portfolio. B.P. Marsh increased exposure to several of its strongest-performing investments, including Pantheon, XPT and ATC, whilst also deploying capital into a new generation of high-growth insurance intermediaries, underwriting agencies and complementary financial services businesses.
And discussing how the business is handling a weaker insurance market:
Whilst commercial insurance pricing softened across certain markets during the year, the Board believes the Group's portfolio remains comparatively well insulated from broader market cycles. A significant proportion of the Group's investments are early-stage or recently established businesses focused predominantly on generating new business opportunities, rather than relying heavily on the renewal of historically priced insurance portfolios. As a result, many portfolio companies are driven more by entrepreneurial growth, talent acquisition, product development and market share expansion than by prevailing premium rate conditions alone.
Graham’s view
I’m very glad to be a shareholder here again, but there are a few details worth ironing out.
Firstly, the NAV per share as of year-end is before a 22.3p dividend that was paid in March. So I reduce the current NAV per share to 937.5p.
This gives a discount to NAV today of 26% according to my calculations.
I’d also like to reiterate that the diversification of the portfolio is limited, due to some large positions:
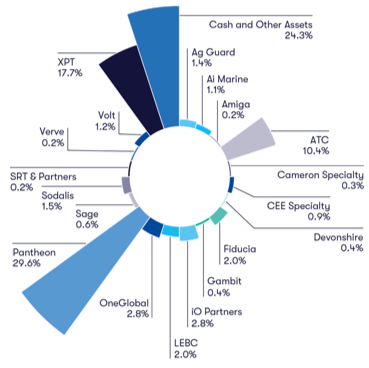
The company has even continued to increase its stake in Pantheon in the new financial year, as noted here.
To help quantify the concentration, I’ve calculated the Herfindahl-Hirschman Index for the portfolio. I get an HHI of 1300 which is actually better than I expected.
The effective number of holdings is given by dividing HHI into 10,000. In this case, I get 7.5 holdings - so the level of concentration is equivalent to holding 7 or 8 different positions. Just something to be aware of, in case you are treating this like some sort of mutual fund - it’s more concentrated than that.
Personally, I’m not worried by this level of concentration. My own portfolio is far more concentrated, and BPM is just a small slice of that. I would even be open to owning more BPM at the current valuation. But before closing, I should mention a few more of the risks:
Brian Marsh’s holding - what might he plan to do with it?
The next generation of managers - they are all very highly experienced and trustworthy, but they also have very big shoes to fill. Very similar to the Warren Buffett question (disclosure: I’m long BRK.A).
Similar to Judges Scientific (LON:JDG), they may find it challenging to source good deals that move the needle and that they understand, now that they have a larger pool of capital to invest.
As I said, I am comfortable with all of these risks and would be happy to own more BPM. But I’m open to any counter-arguments!
Cohort (LON:CHRT)
Up 8% at £13.34 (£627m) - Full Year Trading Update - Graham - AMBER/GREEN ↑
Great news here - revenue and adjusted operating profit are ahead of expectations.
FY April 2026:
Revenue £303m (consensus expectations: £293.9m)
Adjusted operating profit of c. £36m (expectations: £34.7m)
Order intake £313m which the company points out is ahead of revenues
The closing order book therefore grows to a new record c. £620m, although only 1% higher than last year’s £615m order book.
Cohort has therefore beaten revenue expectations by 3% and operating profit expectations by almost 4%.
Visibility is excellent:
The order book underpins c.£253m of current market revenue expectations for the new financial year (30 April 2025: £230m) or c.80% cover.
This is the same percentage of cover that the company enjoyed at the time of last year’s trading update, also near the end of May.
Cash: net funds ended that year at around £3m, much improved from the £32.5m of net debt at H1. They expected net funds to be even stronger, but some expected receipts slipped into Q1 of the new financial year.
CEO Comment:
"I'm particularly pleased with the strong maiden full year contribution from EM Solutions. The business has made good progress in capturing opportunities for growth and collaboration with other Cohort subsidiaries.
"Our strong balance sheet and liquidity provides a robust platform from which to continue to invest in the business while considering further targeted acquisitions.
"The high level of order cover provides confidence in a strong 2026/27 financial year."
Graham’s view
We’ve been a little cautious on this one, worried about the H2 weighting it needed to hit full-year forecasts and the high valuation.
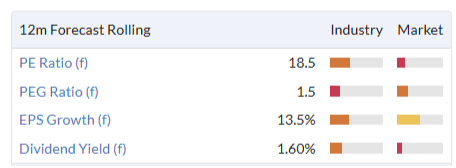
We were wrong on the first count, although I think there is still an argument to be made that the valuation here is punchy. The ValueRank is only 19, and Stockopedia categorises it as a Falling Star.
But when the facts change we should change our minds, and it turns out that there was nothing to fear about the H2 weighting - the company has more than fully delivered on what was expected in H2.
Defence has been a great sector in which to invest, given the unfortunate geopolitical trends of recent years. Cohort provides a wide variety of surveillance, communications, sonar and underwater systems. With the company continuously enjoying robust demand, and demonstrating sturdy earnings forecasts, I’ll nudge us up to AMBER/GREEN today.
Hardide (LON:HDD)
Up 16% at 59.2p (£47m) - Significant further order intake North America - Graham - GREEN ↑
Hardide provides “advanced coatings that solve performance challenges in abrasion, erosion and corrosion resistance”.
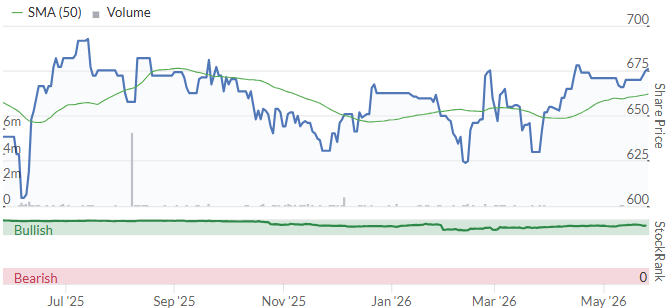
The share price is up by nearly 70% since I looked at only last month. The 1-year chart is quite amazing:
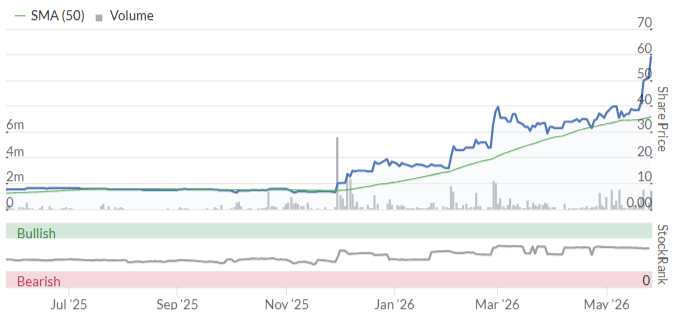
Interim results for the company posted a week ago showed revenues up 71% (to £4.8m) and operating profit jumping to £1.3m (from breakeven).
Today’s update is as follows:
Hardide plc (AIM: HDD), the provider of advanced surface coating technology, is pleased to announce that it has received orders from its large North American energy sector customer to cover the remainder of that client's anticipated requirements for the course of financial year ending 30 September 2026... The value of the contract is £2.4m and is greater than the Board's previous expectations for this current financial year. This will have the effect of materially improving revenue and overall financial performance expectations for FY26.
The company also says that “Operational improvements delivered in recent months have enabled Hardide to deliver its existing order book at a faster rate than previously anticipated.”
CEO comment:
We expect these orders to continue into the next financial years and, as we work more closely with the customer, are developing a mutually beneficial schedule for orders and deliveries which will underpin FY27.
Estimates: Cavendish have increased their FY September 2026 forecasts as follows.
FY26 revenue forecast increased by 8% from £12.4m to £13.4m
FY26 adjusted PBT increased by 17% from £2.9m to £3.4m
The net cash estimate also gets a boost, from £3m to £3.3m.
The new EPS forecast is 4p, so the shares are trading on 15x earnings at the current share price, already reaching close to Cavendish’s target price of 60p in this morning’s session.
There aren’t yet any forecasts for FY September 2027. Cavendish say: “We expect further trading momentum will drive earnings and anticipate FY27E will show a robust advance.”
Graham’s view
I’m going to respect the momentum here and turn fully GREEN for now.
Long-term, I don’t know if this is a quality business. It has been listed for over 20 years and for most of this time has been loss-making and not very impressive.
Suspecting that its fortunes may ride on demand from a small number of customers, I've checked last year's annual report. The Risks section of the report confirms that the company’s top six customers accounted for c. 70% of total sales last year. The report also notes that revenue growth in FY25 was “driven particularly by two large new customers” (from the US and the Middle East respectively).
Therefore, we can say confidently that the company's success is driven by a very small number of customers. Which makes this a rather double-edged situation.
That said, I won’t argue against the momentum this share is currently enjoying. Recent results have genuinely been excellent and if they hit the latest Cavendish forecasts, they are on track to achieve spectacular ROE and ROCE this year of c. 47%.
Last year’s result was already excellent, according to Stockopedia:
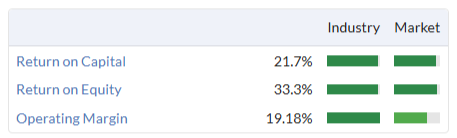
So to my eyes, this share is offering a little bit of everything: quality, growth and momentum. And I don’t think that the value on offer is all that bad against the latest, upgraded FY26 forecasts, with FY27 having the clear potential to be even stronger than the current year. Customer concentration is probably the main source of risk.
Roland's Section
Zotefoams (LON:ZTF)
Up 7% at 426p (£211m) - Trading Update - Roland - AMBER/GREEN =
Today’s trading update from high-performance foam specialist Zotefoams covers the four months to 30 April 2026. It’s short but mostly positive.
Key points:
Group revenue rose by 26% year-to-date to £64.1m, or by +7.1% on an organic basis.
This result reflects a flat organic performance in the group’s largest region, aided by growth in smaller markets and a contribution from a recent acquisition:
EMEA: revenue +24% to £50.1m, although this was boosted by a £9.8m contribution from Spanish firm OKC, which was acquired in November. Excluding this, EMEA revenue was flat at £40.3m (FY25: £40.4m). Management says this reflects lower footwear revenue, but continued growth in Transport & Smart Technologies.
North America: revenue up 30% organically to £12.1m. Reflects increased manufacturing capacity from “our second low-pressure vessel” and good demand in Consumer & Lifestyle and Transport & Smart Technologies.
Asia: revenue of £1.9m (FY24: £1.0m), showing “good growth”. Continuing to invest in new facilities in Vietnam and South Korea which are expected to be operational “towards the end of the year”.
As a reminder, Zotefoams now reports revenue according to the markets in which the group generates revenue, rather than by product type. The downside of this approach, in my view, is that it obscures the performance of the company’s various product verticals and makes it difficult for us to gauge revenue growth or margins in different areas, beyond what the company chooses to disclose.
Financial performance for the period is said to have been in line with expectations, reflecting operational improvements and cost savings.
The integration of OKC (Overseas Konstellation Company) is also progressing to plan. Zotefoams paid up to €36m for OKC last year, which represented a 7.4x multiple of EBITDA. It’s said to be a leading specialist foam producer in Europe, with particular expertise in applications for “protective components, acoustic insulation and specialty packaging”.
In other words, OKC is mainly additive to the Transport & Smart Technologies side of the business, which should aid further diversification.
2026 Outlook - there is no change to guidance today:
The Board is encouraged by the solid start to 2026 and its full-year expectations remain unchanged. Whilst mindful of elevated uncertainty in the macroeconomic backdrop, we continue to expect demand in key target markets, together with the contribution from OKC, to more than offset the moderation in Footwear.
Roland’s view
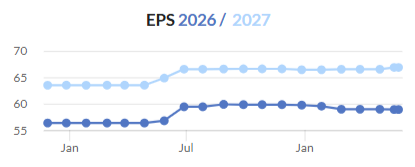
I have been encouraged by the changes made by CEO Ronan Fox, who has curtailed speculative investment and focused on growth opportunities in the group’s core lines of business. This has led to several earnings upgrades over the last 12 months:
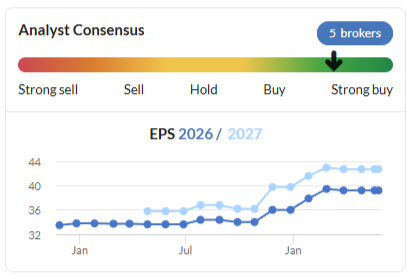
The result of these changes – so far – has been an improvement in quality metrics and and respectable revenue growth:
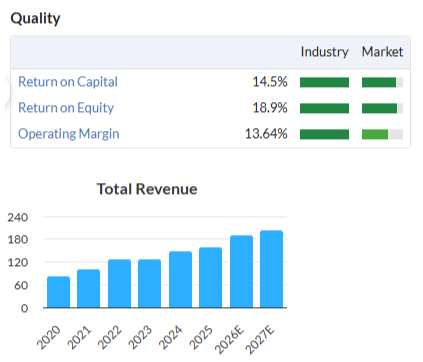
The Normalised EPS figure on the StockReport suggests Zotefoams’ adjusted earnings are expected to fall this year, but that’s not actually the case.
Last year’s results and forecasts from house broker Singer Capital in March show that the following progression is expected:
FY25 actual adj EPS: 38.0p
FY26E adj EPS: 40.8p (+7.4% vs prior year)
FY27E adj EPS: 43.5p (+6.6% vs prior year)
FY28E adj EPS: 47.3p (+8.7% vs prior year)
In other words, earnings are expected to continue growing at c.7% per year over the next few years.
One catalyst for this is expected to be the company’s new manufacturing and design facilities in Asia, which should come on stream later this year. Strong growth in markets such as aerospace and space is also helping to drive growth.
The expansion of the Transport & Smart Technologies business should also provide a second benefit for shareholders by reducing Zotefoams’ dependency on core customer Nike (NYQ:NKE), which I believe may have generated around half the group’s revenue in 2025.
If Zotefoams can continue to deliver on current forecasts then the shares might be too cheap at current levels.
However, by way of caveat I would note that the StockRank has fallen steadily since March, from 93 to 76:
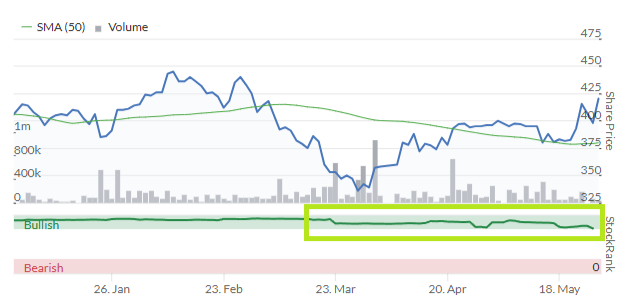
There is clearly still some risk of macro disruption and perhaps more importantly, of further weakness in Footwear.
I’m fairly sure Zotefoams’ fortunes remain quite closely-linked to demand from Nike, whose earnings forecasts were recently downgraded (again):
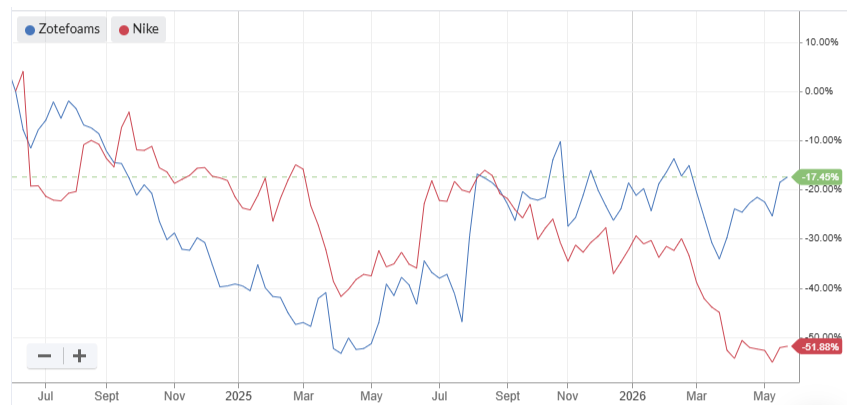
I would speculate that one reason for the change in Zotefoams’ reporting might be to make it harder for shareholders to gauge the group’s exposure to Nike, which wasn’t disclosed last year (previously, it had been).
For this reason as much as anything else, I am going to resist the temptation to upgrade to be fully positive today and retain my previous AMBER/GREEN view.
Hollywood Bowl (LON:BOWL)
Up 14.5% at 298p (£500m) - Half-Year Results - Roland - AMBER/GREEN =
Today’s half-year results have received a warm welcome from investors, despite the company’s unchanged full-year guidance.
Given that FY26 forecasts are for broadly flat earnings, today’s double-digit share price gain suggests to me that investors may have expected bad news. Indeed, BOWL shares remain below the 300p level last seen a year ago:
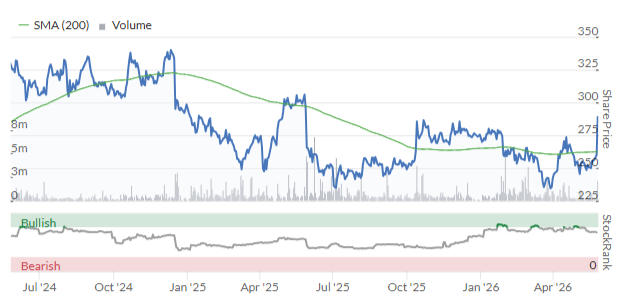
The main risk here seems to be that profitability has been under pressure from inflation and stagnant consumer spending – my reading of today’s results suggest activity levels may have fallen slightly in the company’s venues.
Operating margins have fallen steadily over the last few years:
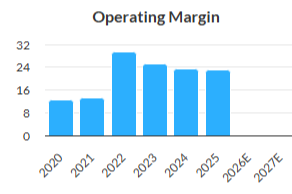
Let’s see whether today’s results show any change to this trend.
Half-year results summary
Today’s headline figures look strong at first glance:
Revenue up 9.5% to £141.5m
Adjusted pre-tax profit up 8.1% to £32.1m
Adjusted earnings up 11.3% to 14.51p per share
Interim dividend up 10.2% to 4.52p
Net cash up 14.3% to £26m
However, I think there are a few niggles to consider:
Like-for-like revenue growth 2.3%
UK LFL +2.6%
Canada LFL +0.5%
Reported pre-tax profit down 3.9% to £27.2m
Revenue growth: fewer games?
The contrasting performance metrics provided today make it clear that customers played fewer games at Hollywood Bowl venues during the first half of this year.
UK:
LFL revenue +2.6%
Average Spend per Game +7.6% to £12.77
Canada:
LFL revenue +0.5%
Average Spend per Game +9.7% to CA$19.10
Hollywood Bowl says LFL performance in Canada was affected by snowstorms that caused some centres to close for several days. But there are no such excuses for the UK business, where the company admits to “a modest reduction in game volumes”.
Management says that the impact of lower volumes was offset by “modest inflationary price increases” and continued progress using dynamic pricing to maximise yields at peak times. There was also improved uptake of add-ons such as VIP lanes and “a strong amusements mix”.
I would suggest this model of charging more for fewer games can work for a while, but probably not indefinitely given the current pressure on disposable income from higher energy costs.
Hollywood Bowl’s performance over the next 6-12 months may depend on whether other pressures on consumer spending ease.
Soaring costs eat margins
The company itself also has exposure to rising costs. While management is keen to emphasise that UK staffing costs remain under 20% of revenue, this ratio is 26% in Canada and these costs are still rising fast.
Total centre staff costs rose by 18.5% during the half year, while administrative expenses and corporate costs rose by 12.2% and 18.6% respectively.
The end result was that the group’s H1 operating margin fell to 24.0% (H1 25: 27.0%). There’s a seasonal H1 weighting to profits here, so my assumption is that H2 margins will be lower, reducing the group average for the year.
New centres - diminishing returns?
With group LFL revenue growth of just 2.3% in H1, we can deduce that total revenue growth of 9.5% was driven by new openings. The company confirms this:
UK: rebuilt Liverpool centre and new Reading centre opened, with two more openings planned for H2 and four for FY27 and FY28. A further 20 potential locations have been identified and the company is targeting 95 UK centres by 2035.
Canada: 1 new centre opened in H1 with a further planned for H2 and five planned in FY27. Now targeting 35 centres by 2032, bringing forward this target from 2035 previously.
I see Hollywood Bowl as a strong operator with a leading brand in the sector. But it’s a competitive business and I am not certain how strong the group’s competitive advantage might be against some other large chains.
Today’s results include a reminder of this: the company has reported a £2.8m impairment on a UK centre opened less than three years ago - this is the main reason for the fall in reported profits today:
It was the second to open in its local market and faces intense competition. While the centre is still cash generative on a CGU basis, it is not performing at the level we had originally anticipated.
Today’s impairment includes a £0.8m charge to the right-of-use assets (lease) for this centre, presumably suggesting that it is no longer expected to generate enough cash to justify its original lease cost.
This underperforming centre may be the exception to the rule. Hollywood Bowl may well be able to continue expanding profitably for many more years yet.
However, many consumer rollout models eventually reach a point where new locations offer diminishing returns. This is often because the market has become saturated or because the company has started to pay too much for new locations.
I think it’s worth noting today’s impairment and watching for any further such events.
Outlook
Broker Cavendish notes that today’s results cover 58% of its full-year EBITDA estimate, highlighting the H1 weighting I mentioned earlier.
Cavendish forecasts are unchanged today, reflecting the company’s in-line guidance:
The Group remains confident in delivering on expectations for FY26
The StockReport shows us that consensus figures drifted lower lower year and were downgraded in January, but have remained stable since then:
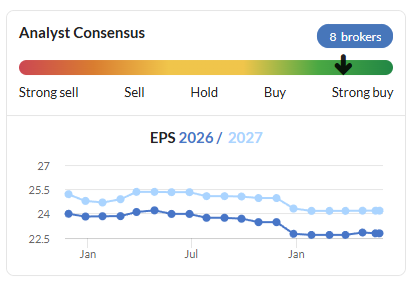
However, this morning’s share price rise (+15% at the time of writing) means that the P/E multiples shown in the StockReport this morning are now stale.
Based on FY26 adjusted EPS estimates of 23p (FY25: 23.6p), Hollywood Bowl is now trading on a forward P/E of 13.
Roland’s view
The group’s improved half-year net cash position and strong quality metrics are a reminder that this business does have some attractive characteristics:
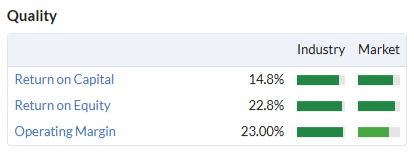
However, pressure on consumer spending means the group’s earnings are currently expected to be flat, at best, this year despite the contribution from new centres.
Today’s impairment charge on a recently-opened centre is also an example of how expansion could put pressure on profits if the group ends up locked into leases on centres performing below original expectations.
The company’s current financial year ends on 30 September and profits are expected to return to growth in FY27. I think that much may depend on whether pressure on consumer spending eases. That’s linked, at least partly, to the situation in the Middle East – Ofgem has announced this morning that the standard domestic energy price cap will rise by 13% from July.
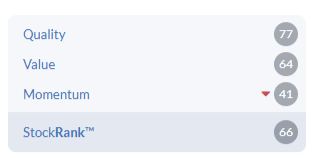
I’m going to give Hollywood Bowl the benefit of the doubt today and leave our AMBER/GREEN view unchanged. But I think the valuation is close to the point at which I’d mirror the StockRanks and switch to neutral in the current environment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
It struck me the other day when looking at Coats (LON:COA) that Zotefoams (LON:ZTF) might be a really good fit into Coats.
And Coats do have an appetite to grow their Footwear division inorganically, having made a decent sized acquisition in the past year here.
For feedback I’ve just unsubscribed from the Daily Stockmarket Report emails. I prefer facts not flannel. Someone at Stockopedia has decided you need more hype in your emails. I don’t like it. Hype is what gets PI’s to make poor decisions.
Please don’t go down the route of our mainstream media channels where every windy or hot day has to be declared a national emergency. Where every headline has to be a disaster or an imminent disaster
Some of the articles don’t even say which company they refer to in an attempt to get readers to click through!
Just give me numerical facts and unbiased opinions please.
While I get some of your gripes, it is in the nature of opinion that it is always biased ( see your Hollywood Bowl note above). Opinions supported by the facts still rely on which facts you select and how we rate their influence on the future. So I am happy to ride through opinions/analysis of differing quality and pull up the names for doing my own (probably, no certainly, biased ) research
Hi Aislabie. I think you miss the point of this gripe. It’s not related to the Hollywood bowl comment. The daily stock report appears to have had a marketing work over to try to add mystery and intrigue with jingoistic headlines. I’m not a fan of this presentation.
I agree it’s not possible to be completely unbiased. We can only admit that we are naturally biased and declare our bias for the reader.
That appears to be a very cautious take on Hollywood Bowl (LON:BOWL) Roland.
I hold Hollywood Bowl (LON:BOWL) so I am positively biased. The market reaction suggests you are being too negative and surely the Stockranks are now out of date as they won’t have updated on today’s news or share price change (momentum). The idea you were thinking of downgrading to Amber when the market says the opposite should possibly make you revisit your assumptions about the future?
In a tough market they have shown that the business can still grow. They would not be accelerating new openings if they had concerns. They’ve hedged some of their biggest costs and now offer some of the best value family entertainment.
When times are tough the strongest, best run operators have room to tighten their belt and offer better deals. The competition needs to be at least as efficient or they’ll go out of business. All of them have increasing costs but not all of them will be making money with a solid balance sheet.
There will probably be some profit taking after today’s price action but the chart suggests that the price may heads higher in the medium term.
I hold Hollywood Bowl (LON:BOWL) and Zotefoams (LON:ZTF) and as one might expect am pleased with this morning's announcements and the positive market reaction, which is not always the case to good news.
I am obviously biased but both shares continue to look good value after this morning's share price rise. Both are financially sound and have good runways for growth. Hollywood Bowl (LON:BOWL) in Canada and Zotefoams (LON:ZTF) with its investment in Vietnam, which should receive a tailwind once realism and rationality dawns for the idiots in America and Iran, to put it politely.
Hi Graham, thanks for the above analysis of BPM. Just wanted to note the above present day NAV estimate is probably understated due to post YE deferred contingent consideration of £9.5m received for a prior disposal.
Recent strength of markets continuing. I try not to second-guess anything!
Fair few shares not partaking in recent rally
Journeo (LON:JNEO)
Fonix (LON:FNX)
Restore (LON:RST) did but selling off after update, which I thought was decent
Watching with interest
Also add Frp Advisory (LON:FRP)
Fonix (LON:FNX) is an interesting one for sure. It has some amazing quality metrics but I feel like the market is pricing in some kind of erosion of the business model? I need to do more research - but if you have any thoughts let me know! Last time at Fonix (LON:FNX) was in the DSMR was July 2025.
Pets at Home (LON:PETS) Some thoughts on the FY26 Prelims:
IMO Pets at Home (LON:PETS) is at an attractive valuation. The vet group’s strong cash generation protects the downside while the new insurance division offers long-term upside, however, I accept that short-term performance relies entirely on the management's ability to improve the retail side of the business.
What did you make of the tepid outlook for revenue growth in the Vets business going forwards? As this is the crown jewel in the Pets at Home (LON:PETS) group, and the one driving all the profits and cashflows at the moment...
"sales growth of low single digit with momentum likely to build through the [FY27] year against a market backdrop which we expect to remain subdued"
I'm a bit perplexed as it does say momentum likely to build, but then caveats that markets expected to remain subdued. Are we then expecting them to aggressively take market share? But that hasn't been articulated well in the strategy sections.
Hi Boon,
The pandemic animal cohort has entered its "healthy mid-life" years and require fewer routine clinic visits. The vet sector is also suffering from an acute shortage of qualified clinical staff and therefore I think growth has hit a hard ceiling dictated by clinical headcount rather than market demand.
The large pandemic pet cohort will begin entering its senior years starting around late 2027 and 2028. Older animals naturally require significantly higher levels of veterinary care, chronic disease management, and medication, so growth should naturally return. The new PMS and pet insurance should also help drive efficiencies and top line growth.
Just as an aside - A German friend of mine drives her dog back to Germany to have treatment because it is cheaper than the vet costs in the UK....
I agree with you on the medium term growth driver you described above.
Just trying to make sense of the conflicting statement about FY27 from the company.
Markets now liking today's results at the end of the day.... was down at the start!
I know you are a keen follower of B.P. Marsh & Partners (LON:BPM) Graham, will you be reviewing the results today? I'm already a shareholder and am considering making B.P. Marsh & Partners (LON:BPM) a core long term portfolio holding. It has a strong track record, an attractive NAV discount and a handy dividend too.
Ive never really looked or followed it - surprised the shares aren't a little better for a steady 11% compound story - they do seem to follow the fortunes of Hiscox (LON:HSX) a little which is probably an awful comp so apologies..... having said that the sector has had a decent run pre recent rate weakness.
B.P. Marsh & Partners (LON:BPM)
Brian Marsh has finally hung up his boots and been moved over to the "Alex Ferguson Role" - job done by him at 85 he lasted even longer than Fergie before going into complete retirement - other than the fact they will no doubt wheel him out for stuff he can stil tolerate.
There may be high level of nepotism here but seems like he has done a good job creating very stable platofm for the buisness to simple rinse wash and repeat withn inestments - i suspect its some time since he had teh day to day hassles anyway.
over to the ye numbers - fully diluted nav is what its all about here - we really dont need to look much beyond that really - thats now 959.8p per share at 31/1/2026 - that was 909.8 at 31/7/2026 and 847.3p at 31/1/2025. we should expect straightlin progress here - numbers are perfectly pleasing to me - if this churns out average of 10% pa on and on thats great. Some years we should expect little material progess too - being honest i was expecting 2026 to be such a year - they banked huge 35% uplift in value ye 31/1/2025 so its pleasing that they have continued to up thn=e numbers after such a chomping year (2025) that kinda delivered 3 years of profits - thats the nature of the beast - there may be years where the fairly chunky core costs result in little to no increase.
discount to NTAV here is currently 29% - churning out 10% pa bottom line consistently perhaps deserves soemthing better than 29% disocunt ? the future profits need to be made though - one might argue as they grow it is perhaps gettinmg harder to find obvious compelling no brainer investments - they dont seem short of options here even if they are slightly branching out. To me they could be buying back bucketloads of shares - if they ideally want to remain nimble - they seem happy to grow though and thats probably the way of the world with corporate entities - you dont want to say - well we will keep asset base as it is - delver 10% compounded and buy back 7% of shares per year. shareholders would be very rich quite quickly if that was the acheivable plan - that would do me but to most it may seem like they are taking money for old rope ref salaries.
happy content holder here.
£BPM Also worth noting that they have net cash of around £50m - this would make the cash-adjusted discount closer to 35%, which seems very high given their track record.
B.P. Marsh & Partners (LON:BPM)
great point ref cash - personally i tend to ignore this on the basis that they have had huge inflows from successful exits the last couple of years levels well above what you would expect in an average times. It makes sense they havent "rushed" to invest it all immediately - but i kinda presume that anyone investing now may find that the cash "excess" dwindles over the next 24 moves as it goes into further investments. If we take the viewpoint that cash is "here today" gone tomorrow - then practicably speaking its only a temporary benefit at these levels. dont get me wrong they have larger market cap now - and i guess they must (if they dont want to gamble) hold adequate cash for overheads divis and buybacks over the next 24 months - remember overheads are getting on for £15 mill pa here - so cashflow can easily benegative if they have no "exits" in a particular year. Me personally i would love more buybacks at current price as that gets instant boost to ntav - but facts are here - they ned cash buffer and the rest will probably be spent on investments. would i have preferred they keep cap on costs and pay more out to shareholders on the basis small and nimble is better than big and lumpy perhaps? but they have done so well with investments made that i understand their core ethos of "ploughing as much as possible back into new investments" - one minor item here is that there will be some chunky "bonuses" turning up for managemnt that might partly be in form of shares issued? - in that regard at least if we concentrate on diltuted ntav at least stuff thats issued will always be factored in - does anyone know if all fiture possible awards are factored into that number too ? i am not over worried like some ref director remuneration as they are looking at 10% returns pa before handing out big wonga - if management get 10-15% of excess well at least its minor % of bigger pot - albeit it may look "uber generous"
I holdWatkin Jones (LON:WJG) , have done so for a long time. The 6-months results are out today.
Alex Pease, Chief Executive Officer of Watkin Jones, said:
"We have achieved a resilient performance in the first half, underpinned by strong operational delivery and a proactive approach to cost and cash management.
I read this as saying 'we are in the wrong business' .
It's just corporate waffle
Reading on in Mail Online latertoday, this what the article says:
Researchers say employees who are impressed by corporate 'waffle' score lower on tests of analytical thinking and problem solving.
I'm guessing someone set the CEO up.
From a quick scan of the morning news I think Hardide (LON:HDD) looks interesting. Small market cap but decent looking growth with a big upgrade this morning. I have never looked at. Would welcome your expert eyes Graham and team!
check out Oak Bloke on this one too
Thanks for flagging that - useful.
Such a shame I didn't spot this company when it was 7p just a few months ago!!!
Thanks for the Oak Bloke shout. Very.informative and also entertaining. HDD now on my watchlist…..but is it too late!!
Cannot trade it on T212 ( sad face)
Thanks for covering this today :) Interesting to read and nice to see a small cap turning around and doing well.
You're most welcome, Tortoise! It was a really interesting suggestion!
Request for your analysis on Hollywood Bowl (LON:BOWL) and Zotefoams (LON:ZTF) please. Always appreciated.
acknowledged Revs8!