Daily Stock Market Report (Wed 8th October 2025) - SQZ, GNC, IPX, MARS, RFX

Good morning and welcome to today's report!
The agenda is now complete.
Today's report is now complete.
Spreadsheet accompanying this report: link (last updated to: 5th September).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view |
|---|---|---|---|
Lloyds Banking (LON:LLOY) (£49bn) | Notes recent FCA announcement on industry-wide redress scheme and is assessing its impact on current provision for this issue. | ||
Anglo American (LON:AAL) (£33bn) | Supportive of Teck’s revised approach to QB. Says outcome of Teck’s review is “broadly consistent” with own due diligence. | ||
Bunzl (LON:BNZL) (£8.0bn) | Bolt-on acquisitions in Ireland and Spain in September. Holding webinar today on acquisition strategy. | ||
Unite (LON:UTG) (£3.5bn) | 95.2% beds sold for 25/26 (24/25: 97.5%). 4% rental growth YTD. FY25 EPS exps unch: 47.5 - 48.25p | ||
Greencore (LON:GNC) (£1.0bn) | FY25 rev +8%, food to go esp. strong. Now exp FY25 adj op profit c.£125m, ahead of exps (prev. £118-121m). | PINK (AMBER/GREEN) (Roland) | |
Serica Energy (LON:SQZ) (£832m) | SP -10% Production suspended from 30/9 due to flare problems. Expected to restart shortly at “severely limited” rates until the root cause of the problem has been identified and resolved. FY production to be below previous exps of 29,000 - 32,000 boepd. Auctus Advisors has cut its FY25 production forecast to 27.5k boepd (prev. 30.8k). | AMBER (Roland) [no section below] I’m starting to lose count of the number of times I’ve seen this RNS title from Serica. While the company’s recent acquisition looks attractive, as Mark discussed here, today’s news is a reminder that nearly half the group’s (pre-acquisition) production depends on flaky, ageing infrastructure that’s controlled by someone else. Serica has cut production guidance again today but isn’t in a position to provide definitive new guidance until some clarity emerges on the timeline for repairs. CEO Chris Cox describes the news as “incredibly frustrating” and I imagine shareholders will agree. But it’s not clear to me that he has much power to influence the situation. I’m going to maintain our neutral view today on the grounds that the recent acquisition should help to dilute the impact of Triton production, while Serica’s overall valuation continues to look reasonable to me. However, my view remains that these North Sea consolidators probably deserve to be cheap, given the limited lifespan of many assets and the potential decommissioning costs they will face in the future. | |
Foresight group (LON:FSG) (£542m) | H1 EBITDA is in line with current FY26 consensus. AUM +3% to £13.6bn, FUM +1% to £9.6bn. | ||
IP (LON:IPO) (£472m) | IP has 12.3% holding in Monolith, an AI software company. No financial terms disclosed. | ||
Pantheon Resources (LON:PANR) (£332m) | 25 frac stages completed in 8 days. Operations underway for clean-up and production testing. | ||
Kenmare Resources (LON:KMR) (£273m) | Commissioning started on 2 Oct. Expected to take 3-4 weeks. On track for 2025 production guidance. | ||
Impax Asset Management (LON:IPX) (£250m) | Q4 AUM flat at £26.1bn with positive market performance offsetting £1.4bn of net outflows. "Material inflows" from EU/NAm clients. | AMBER/GREEN (Graham holds) [no section below] I’ve been AMBER/GREEN on the fund management sector in general, to reflect their cheapness but also that current trends are against them. As with Liontrust yesterday, Impax continues to report net outflows, and these have ticked up to £1.4bn (previous quarter: £1.3bn net outflows). As with Liontrust, Impax argues that things are actually looking up, despite higher net outflows: “there is solid evidence that flows are stabilising, including in our wholesale channel”. Unfortunately, that solid evidence is not visible yet when it comes to actual flows, but as with Liontrust I do think that pessimism is sufficiently priced in here. This stock qualifies for the “Ben Graham Deep Value Checklist” and the “Ben Graham Defensive Investor Screen”, and I’m happy with my currently small (and underwater) position in it - with no intention to add to it unless there are tangible signs of improvement. | |
Marston's (LON:MARS) (£246m) | Underlying PBT to be ahead of expectations. LfL sales +1.6%. Year-end net debt (pre-IFRS 16) to EBITDA now below 5x. | AMBER (Roland) Today’s upgrade is positive and my number crunching suggests management commentary could imply a c.6% increase to underlying PBT guidance for FY25 (y/e 27 Sept 25). However, debt services costs and capex remain high, while a sluggish economy appears to be limiting sales growth. Despite the tempting discount to book value, I would prefer to wait for the full-year results to learn whether Marston’s debt repayment capacity has improved and to be able to review updated guidance for the current year. For these reasons, I’ve left our neutral view unchanged today. | |
Riverstone Energy (LON:RSE) (£223m) | Managed wind-down: compulsory redemption of 70% of shares at £11.01. | PINK (managed wind-down). | |
Netcall (LON:NET) (£202m) | Rev +23%, adj. PBT +8% (£8.3m). Enters the new financial year with strong momentum and a record pipeline. | ||
Vertu Motors (LON:VTU) (£191m) | JLR cyber-attack: one-off impact on FY26 adj. profit before tax of up to £5.5m. Excluding this impact, underlying PBT expected in line. | ||
Seeing Machines (LON:SEE) (£153m) | Additional Purchase Order valued at c. $1.8m to “a world-leading North American self-driving car company.” | ||
Ramsdens Holdings (LON:RFX) (£125m) | SP -5% Updated forecasts from Panmure Liberum: | AMBER/GREEN (Roland) [no section below] With gold topping $4,000/oz for the first time yesterday, I’m surprised to see Ramsdens’ share price fall following today’s ahead-of-expectations trading update. The company’s commentary highlights a strong full-year performance across the business, in particular from gold purchasing. However, I think there are a couple of other factors worth considering. Firstly, this business is unusually exposed to the price of gold. Gross profit from precious metals totalled nearly 30% of the group total in H1, slightly ahead of pawnbroking gross profit. This weighting is likely to have increased in H2 – today’s note from Panmure Liberum suggests precious metal GP will be the largest contributor to group profits in FY25. CEO Peter admits that “we have benefited from the sustained high gold price”. He believes the group’s diversified income stream provides some protection, but I suspect that in a gold downturn there might also be knock-on effects on jewellery sales and pawnbroking – the overall impact on Ramsdens’ profits could be significant. Of course, there’s no guarantee the gold price will fall. It could stay high or rise further, in which case Ramsdens could continue to outperform over the coming year. We are generally positive on Ramsdens and I believe there’s plenty to like about this business. But I think the rising valuation and growing level of commodity price exposure means that to some extent, the near-term outlook for profit is more speculative and less under the company’s control. To reflect this risk, I’ve moved our view down by one notch today. | |
Fiinu (LON:BANK) (£42m) | Has now fully drawn down £2m convertible loan facility. New joint broker. | ||
Aptamer (LON:APTA) (£26m) | New £360,000 contract. Visibility of £1.03 million in value for current period, with nine months remaining. Company not providing formal guidance at this time | ||
Fusion Antibodies (LON:FAB) (£17m) | Work is expected to be completed within the current financial year and generate revenues of not less than £175,000. | ||
Velocity Composites (LON:VEL) (£12m) | 10-year contract extension. Expected to generate approximately $2.5 million in revenue in FY26. | ||
Oxford Biodynamics (LON:OBD) (£10m) | Development of a new highly accurate blood test to diagnose Chronic Fatigue Syndrome (CFS), also known as Myalgic Encephalomyelitis (ME). |
Roland's Section
Greencore (LON:GNC)
Up 0.5% at 233p (£1.03bn) - Trading Update - Roland - PINK (AMBER/GREEN)
Convenience food producer Greencore has upgraded its full-year guidance for the year ended 30 September 2025 today, extending a run of upgrades over the last 18 months:
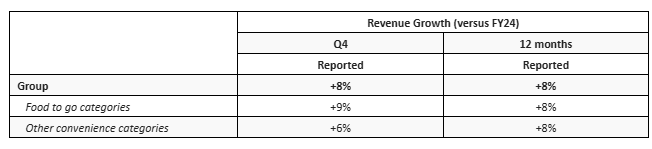
Today’s commentary sounds positive. Q4 revenue rose by 8%, consistent with growth over the last 12 months. Food to Go has been particularly strong recently, which management says has been driven by categories such as sandwiches and sushi.
Cash conversion has remained good, supporting a further reduction in net debt to £70m from £136m at the end of March 2025. Leverage is said to be “well below” the target range of 1.0x-1.5x, presumably leaving plenty of capacity for the cash outflows required when its acquisition of Bakkavor completes later this year.
Outlook
FY25 adjusted operating profit is now expected to be “approximately £125m”.
Previous guidance in July was for £118-£121m, which itself was an upgrade from £114-117m. So we can see that management has been inching up guidance as trading has evolved over the year.
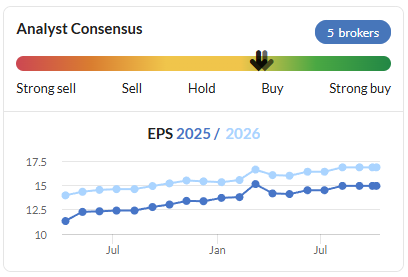
I estimate that today’s upgrade could drop out to give an adjusted EPS figure of around 15.5p for FY25, leaving the stock on a P/E of around 15x.
Roland’s view
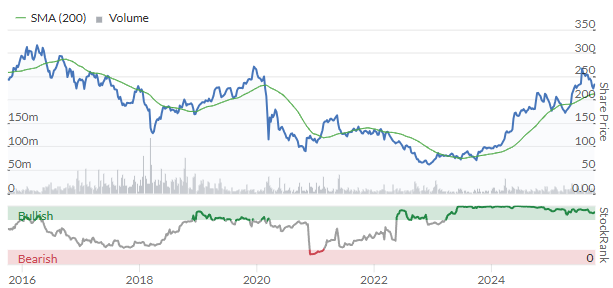
Greencore’s share price is now back at pre-pandemic levels and no longer obviously cheap, in my view, for what remains a low-margin and somewhat cyclical business:
From here, I’d argue outlook is increasingly dependent on the success of the Bakkavor acquisition/merger. This cash/shares deal is expected to complete later this year and will see Bakkavor shareholders own 44% of the expanded company.
Combining two £1bn+ companies is not without risk and complexity. Greencore will be paying out c.£500m on the cash element of this deal, so any subsequent setbacks or cash flow problems could leave the group with an uncomfortable level of leverage.
I’m going to maintain our AMBER/GREEN view today out of respect for the company’s seemingly strong momentum and repeated upgrades. But at current levels, I would personally be inclined to wait for the merger to complete before considering an investment. The lack of any share price reaction to today’s news suggests to me that the market may share this view.
Marston's (LON:MARS)
Up 6.7% at 41.4p (£261m) - Trading Update for 52 weeks to 27 Sept 25 - Roland - AMBER
Checking back in the archives, we last covered this heavily indebted pub chain in October 2024 and then in December 2024, when Graham reviewed last year’s results.
The share price has hardly changed since then, but trading (and profitability) seem to have improved – at least that seems to be the implication of today’s upgrade to FY25 profit guidance.
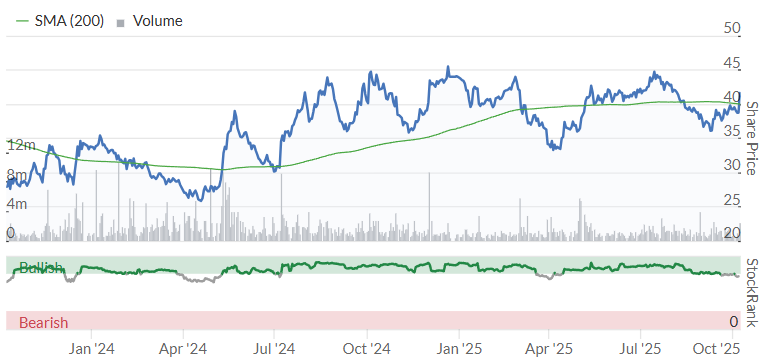
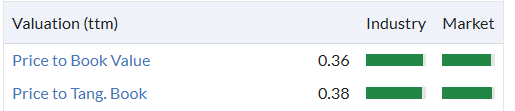
I’m interested to see if an opportunity might be emerging. After all, these shares currently trade at a c.60% discount to book value, according to Stockopedia – although we should remember that this is potentially a fair reflection of high indebtedness and low returns on assets.
FY25 trading summary
This update is fairly light on detail, in my view.
We aren’t given a full-year revenue figure, but are told that like-for-like sales rose by 1.6% during the year to 27 September. This result is said to have outpaced the market.
However, as some of you have suggested below in the comments, this low level of LFL growth may well imply a reduction in volumes, when inflation is taken into account.
One interesting point is that recently refurbished pubs are said to be performing much better, with “average initial revenue uplifts” of 23%. Leaving aside the heavy lifting done by the word “initial” here, I think this just highlights the capital-intensive nature of this business. Pubs need regular refurbishment – Marston’s capex is currently running at 7%-8% of revenue and is expected to have been c.£60m in FY25. If profitability isn’t sufficient, what can happen is that businesses of this kind end up running to stand still.
Fortunately, profitability does seem to have taken a further step forward over the last year, thanks to a variety of efficiency-type measures:
Step-change in profitability underpinned by sustained margin expansion through our market-leading pub operating model, including revenue management, labour efficiency and procurement initiatives
We aren’t told anything about operating margins, but Marstons says that underlying EBITDA margins have improved by more than 1% over the year. This margin was 21.4% last year, so it seems reasonable to assume a figure of c.22.5% this year.
This seems cautiously encouraging to me, given the impact of higher employment costs since April.
Applying this margin estimate to Stockopedia’s consensus revenue forecast of £917m suggests a FY25 EBITDA figure of £206m. That would imply a slightly lower H2 weighting than in 2024, so perhaps it’s slightly low (or perhaps market conditions were weaker this summer than in 2024).
The other key point is that the company confirms year-end net debt/EBITDA leverage is expected to remain below 5.0x, as was reported at the half-year mark (4.9x). Unfortunately there is no detail provided on net debt, so we don’t know if this reduction is due to debt repayment or simply the deleveraging effect of rising profits.
Outlook & Upgraded Guidance
Unfortunately we are left guessing about the exact scope of the improvement to FY25 expectations today. Marston’s management are not as forthcoming as that of Greencore (see above) and have not provided explicit new profit guidance.
This is what we get instead:
“Underlying profit before tax expected to be ahead of market expectations”
Previous market forecasts were for underlying PBT of £67.2m, with a range of £64.6m to £69.2m, according to company-compiled figures
I don’t have access to any updated broker forecasts today, so I’ve used my EBITDA guesstimate above as the starting point for a new estimate of underlying PBT:
Underlying EBITDA: £206m
Depreciation and amortisation: -£45m (in line with FY24 and FY23)
Finance charges: -£90m (annualised from H1)
Underlying PBT: £71m
This estimate suggests a c.6% increase in underlying PBT versus previous expectations, which is consistent with the share price movement this morning. So I’m happy to use this as a working assumption (although of course I could be wrong).
Applying a similar increase to forecast EPS suggests a figure of 8.25p, leaving the stock on a FY25E P/E of 5.
There’s no update on FY26 guidance today, except to note that an accelerated capex plan is in place for pub refurbishments next year.
Roland’s view
Marston’s underlying pre-tax profit in FY24 was £42.1m, so the FY25 results look likely to show growth of 60%+.
This sounds impressive, but I think it’s worth remembering that this business is still primarily being run to service its debt burden – H1 reported net debt was £1,252m, including lease liabilities, dwarfing the £261m market cap. Interest payments are likely to be c.2x reported net profit and there is no dividend currently.
Today’s update seems broadly positive to me, but it leaves several questions unanswered, notably whether Marston’s has been able to make any meaningful debt repayments this year. Remember that last year’s big reduction was funded with the proceeds of the sale of the company’s brewing business.
A bullish view here would be that if Marston’s can maintain higher levels of profitability, it should be able to repay debt and reduce the discount to book value, potentially supporting a share price re-rating.
However, the business is currently faced with a sluggish UK economy, persistent inflation and demanding levels of capex and debt service.
Graham upgraded to neutral after reviewing last year’s results and I am happy to maintain that view today, reflecting the StockRanks. However, I would prefer to wait for the full-year accounts and updated FY26 guidance before considering whether to turn positive.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Triton just seems to be the rake Serica Energy (LON:SQZ) keep stepping on.
Excellent analysis, I was hoping there would be additional commentary on Ramsdens Holdings (LON:RFX) but the summary covered most of it. It's no longer a cheap business - more a an alternative way to bet on Gold. There are cheaper ways to get leverage gold exposure - futures for one!
x
For anyone who subscribes to Paul Scotts blog there's a good write up on Foresight group (LON:FSG) by one of his team today.
Marston's (LON:MARS) Not a business I have looked at but having had the misfortune to stay in a Youngs pub that had been bought from Martson's and not yet re-furbished (Thought in 2 years it should have been given the price was £170 including shareholders discount )I am unlikely to. Youngs refunded me for the cost of the room, which gives you an idea of how poor it was. Just had a look at a Marston pub with rooms. B&B £92.50 is 50% less than I paid in any pub during a weeks stay in Kent (owned by various -Fullers, Shepherds Neame etc). T ath e base price of £62.10 for a room no wonder Marston's are struggling to repay their debt mountain. Just my view but would not touch the business on my limited experience of them.
Marston's (LON:MARS)
you have lost me are you saying price is too cheap for them to make money?
i am guesing pricing reflects realities of staying above a pub - which probably isnt for everyone. I suspect people who do stay may spend a but in the associated pubs.
i would guess like spoons there will be huge variability in quality of offering.
ref the debt - its really just akin to long term mortgage here (freehold backed) - figures pimped up by article today and sotcky - excluding lease liabilities its 881 million - and is mostly long dates debt.
the key here is whether they now have freecashflow that can be used to pay down debt.
even if they chipped away at debt at £30 mill per year it wouldnt take long for the double benefit that the chunky interets payments would start to come down and that would increase profits and (less interest) and allow faster reductions later.
today they have said
Recurring free cash flow expected to be in excess of the Capital Markets Day target of £50 million, achieving this milestone ahead of schedule.
Note i second Roland caution here ref debt reduction - the proof of the pudding is in the numbers - and until i see real material reduction in debt - or i see that funds are being spent elsewhere that explains why debt is not coming down (eg capital expansion).
So as aholder i would say jury is very much out but i very much think if they can be disciplined and keep purple patch going there is some chance the debt mountain issue may start to be actively addressed on ongoing basis.
deffo safer on the sidelines for sure though - albeit with tangible book value at over double the shareprice - whilst its making decent profits and interest rates are not too high one would like to think that there is value here - just a shame i can ever imagine PIF wanting to buy out pub chains !!
I am saying the rooms are too cheap. And if anything like the one in the Pub Young's had bought need some work on and then maybe get £130 or so. I am exposed to the sector as it happens through Fuller Smith & Turner (LON:FSTA) and Young & Co's Brewery (LON:YNGA) so would not buy any other anyway.
Marston's (LON:MARS)
cheers Charles - and least with cheap and cheery expectations are NOT amazing perfect for your contractors and people on a budget.
https://www.proactiveinvestors...
as an aside proactive investors seem to be saying that - Shore capital may be saying that net debt might come down by £50 mill - from £890 to £840 mill. Not sure i believe it until i see it - but if that is anything like true and repeatedable each year that woudl be game changer. In4 years debt could down from £890 mill to £690 mill - stuff like that would take all the strain of financing and the like. I wont perosnally believe it until the company updates actual numbers though - the keep repeating the £50 mill fcf every update its getting a bit boring.
Free cash flow exceeded the pub group's £50 million target, and net debt is expected to fall below £840 million, pushing the ND/EBITDA ratio below 5.0 times.
But you can stay in a Hotel from around £42. I avoid pubs now as too expensive and noisy, rooms are often dated and not sound proofed.
I am sure it is possible and I guess that means Pubs need a USP for the rooms
"UK Treasury Gilt 5.25% 2041, maturing 31 January 2041, new issue. This offer will remain open until 2.30pm on Monday 13 October 2025. " Aimed at Retail Investors as well. BoE having to issue bonds with this coupon
Thanks HL, love the personal touch!
BOE sounds alarm over AI Bubble?
Surely that’s bullish enough and more to come!
All the best
The BOE are doing a great job. My US portfolio is up 3% today.
Netcall (LON:NET) I hold
Would appreciate the team taking time to look at the final results. Lots of growth but profit down.
The challenge with the update was there was really no reference as to why the profit was down despite the strong revenue growth. I assume based on the underlying EPS growing that quite a chunk of it was going on shares to employees (a non cash but dilutive cost.)
The fact that a fast growing software type company is profitable in the first place is commendable and at this point I am quite happy holding Netcall (LON:NET) as a growth stock and given the AI/Process improvement area is very fast growing see this as a potential muti-bagger longer term. The fact they don't need to raise more money is the important one for me
Re Netcall (LON:NET) ,Statutory profit was down due to 1.5mm acquisition related costs (amortisation of goodwill, post-completion earnouts and transaction costs) and 0.2mm increase in share based payments. Adjusted PBT was 8.3mm +8% which lagged behind revenue growth due to reduced interest income (from utilising part of the cash pile for the acquisitions) and the 1.5mm investment in their CCaaS offering (now complete) which reduced EBITDA margins to 20.5% from 21.6%. New cloud business has an EBITDA margin of 30% so that should start rising this year.
EPS growth this year is forecast to increase to +14% and they usually beat that by a bit.
Netcall (LON:NET) many thanks for the explanation
Hi Graham would be great if you have a chance to have a ramble of Foresight group (LON:FSG) its a bit of an under the radar financial company.
Its heavy into renewables and woodland, from memory the founder spent a million plus on shares not long back.
He's early 70's also so one would think he will be looking for an exit at some point, like most things they have had a decent run up since April but don't look expensive plus they have a north of 6% dividend covered (just but predicted for the cover ratio to improve next two years).
Foresight group (LON:FSG) - the is indeed a niche company and I don't know of another to compare. Maybe this is a major factor in their success. They were big in forestry but I believe have sold out of this sector a couple of years ago and probably a well timed decision as so much greenwashing is out there even the 'goodies' face criticism. See factsheet from their website
https://media.umbraco.io/fores...
Hi Phoenix - You make an interesting point about age and looking for an exit - I take the opposite view nowadays - Look around, there are loads of 'elderly' entrepreneurs who have no intention of exiting - I reckon its the impatient younger ones seeking a buyout!
Look around, there are loads of 'elderly' entrepreneurs who have no intention of exiting - I reckon its the impatient younger ones seeking a buyout
Very good point. This was me 30 years ago! In your early entrepreneurial phase, you’re in a hurry to bank that first big payout in cash.
Foresight group (LON:FSG)
not looked at this company before - all the numbers look very pleasant here.
So review would be nice.
I am not generally a fan of fund managers who provide tracker type investments and take an overly large cut.
I think this is perhaps more niche company ?
does the main man here keep remuneration costs under control ? - i have it whne management take big cut of the profits when there is a purple patch.
Its not so clear to me why eps number have been so strong teh last couple of years - is this level of profit generation sustainable - or have they simply hita purple patch with prior investments showing good uplifts in value.
i definately think therte is a niche for solid companies investing in stuff that isnt simply tracking the stockmarket primarily.
not unexpectedley with the nice looking numbers this company seems to tick plenty of boxes ref screens that would give on comfort - my one worry with companies like this is if they are a black box ref future earnings. book value seems non existent here per stock - so looks like they need to be maikng £50 milliom plus profit pa to support shareprice - so doenst seem to be same tnav backing that a company like B.P. Marsh & Partners (LON:BPM) has.
B.P. Marsh & Partners (LON:BPM) - Another company run very well by an older generation person - with his family now taking a considerable interest. I can never weave my way through all the tech figs but there is cash on the Foresight group (LON:FSG) balance sheet and £50m profit pencilled in for 2026 so think it does indeed tick the boxes!
Ariana's second Tavsan mine is now in operation. It will be transformational for the company! Market is still asleep https://www.londonstockexchang...
Ariana Resources (LON:AAU)
Transformational indeed...
Taken from LSE release
"Gold production from the heap-leach is expected to start in the current quarter, once sufficient ore is loaded and leaching has commenced."
"Approximately 800,000 tonnes of ore is currently stockpiled and awaiting loading, with crushing having been underway since August."
Shouldn't have long to wait to hit the bank.
Thanks for highlighting
For those interested in Trusts and Vietnam, the Vietnam stock market has been granted emerging market status by FTSE Russell. Hopefully MSCI will follow suit at some stage. This will lead to more investment in the market from funds who use those indexes.
Just as Serica Energy (LON:SQZ) started to take off!
Agree - most frustrating - let’s hope a catalyst for positive change.
Triton - what a nightmare this is becoming. Like keeping an old banger on the road, fix one thing and something else drops off. Thank heavens for the latest Prax acquisition - without that diversification I'm sure the SP would have collapsed further still. They've 2 basic options -
1. Directly confronting the Triton issue by evaluating a) a change of operator, b) replacement of the FPSO, or c) significant life-extension upgrades.
I hope they manage a) and c).
2. Strategically reducing its exposure to Triton's reliability by building a more diverse portfolio centered around its other major, often-operated, hubs like Bruce and the newly acquired Shetland Gas Plant (SGP).
Timely Prax acquisition helping to propel this forward.
I hope they can successfully navigate a path for both 1. & 2. Redevelopment of the Kyle field would add further to the economics of further investment in Triton. I think the current team led by Chris Cox are very capable and proactive and I'm happy to continue to hold.
Bloomsbury Publishing (LON:BMY) - news of a Disney film deal on K.Rundell book
https://www.londonstockexchang...
Marston's (LON:MARS) Like-for-like sales growth of 1.6%, once food and drink price inflation is taken into account, seemingly implies a fairly steep reduction in customer numbers and/or spending per customer. This appears to follow the trend of other retail hospitality companies.
Marston's (LON:MARS)
More spin than you would get from your average Jenny here.
100% agreed that the lfl numbers are not impressive.
They have magically managed to beat market expectations despite these tepid numbers and they are also outperforming the sector as a whole - cross reference their preferred third party stat provider.
As a holder I am content with hitting targets - in current environment that’s fine -and hopefully decent growth still pencilled in for next year.
Let’s not pretend they have shot the lights out here - seems like they have simply left a bit in the tank ref ye numbers.
If we want meaningful comparison on sales spoons managed 5% lfl growth - so their outperformance stats source seems somewhat sketchy - they may be outperforming struggling local independent pubs but not spoons.
Let’s see how quickly debt is coming down per te numbers - I suspect not to quick. Overall though upping profits this year nand next is still positive progress - if they don’t need to have over excessive cap ex - in that regard they are clearly splashing the cash on refurbs.
Hmmmm do they exclude Thurber pubs from lfl comparisons - if they do these figures might be materially better than the quoted 1.6% increase - if that’s the case comments above may be slightly harsh
I am avoiding the consumer discretionary sector in this environment. Who knows what extra taxes Ms Reeves has up her sleeve.