Daily Stock Market Report (Mon 10 Feb 2025) - LIFS, SYME, FTC, PRV, BP., LIKE, ZIN, ENSI

Good morning! Let's see what's in store for us today.
11:30: wrapping this up here, thanks everyone! Another clean sweep!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| BP (LON:BP.) (£69bn) | None | Noted activist investor Elliott Management has built a stake in BP, according to press reports. | AMBER/GREEN (Roland) |
Porvair (LON:PRV) (£316m) | Final Results | Revenue +9% to £192.6m, op profit +8% to £22.8m. Trading mixed, 2025 outlook optimistic. | AMBER/GREEN (Graham) Not too much has changed since my last review. Underlying sales growth is now positive and a new CEO will take charge in 2025. A nice company, valuation somewhat full. |
Filtronic (LON:FTC) (£203m) | Further contract win with SpaceX | £16.8m contract for FY25 and FY26. Both years now expected to exceed current market exps. | AMBER (Roland) |
Likewise (LON:LIKE) (£48m) | TU & Acquisition of Logistics Centre | Positive start to 2025, revenue +8.4%. £1.2m acquisition near Plymouth completes UK coverage. | AMBER (Roland) |
EnSilica (LON:ENSI) (£47m) | Interim Results | “Solid” H1? Rev fell slightly (£9.3m) and negative EBITDA (£0.2m). H2 weighting expected | AMBER/RED (Graham) I'm not RED on this because I presume that ENSI's customers would not be awarding contracts and funding to a supplier that was in danger of going bust. |
Zinc Media (LON:ZIN) (£15m) | TU | Rev below exps, but adj. EBITDA +50% to £1.5m, in line. Excellent momentum into the new year. | AMBER/RED (Graham) Taking a more lenient view on this as it does not seem to be distressed currently, but the net cash balance is thin and the long-term financial track record is terrible. |
| LifeSafe Holdings (LON:LIFS) (£3.5m) | Business Outlook | The fire safety tech business is hoping for an €800k order in “coming months” and £800k contract over next two years. But no certainty of either yet. | RED (Roland) [no section below]. Shares down 90% since 2022 float. Appears subscale and loss-making. Some hope of a transformative deal but looks speculative and risky to me. |
| Supply@Me Capital (LON:SYME) (£2m) | Funding Update | “Given the cash flow pressure…the Board is actively exploring alternative funding options”. Waiting on related party loan funds from CEO’s other company which itself needs restructuring. | RED (Graham) [no section below] |
Graham's Section
Porvair (LON:PRV)
Up 2% to 692p (£322m) - Full Year Results - Graham - AMBER/GREEN
Porvair plc ("Porvair" or the "Group"), the specialist filtration, laboratory and environmental technology group, announces its results for the year ended 30 November 2024.
This looks a solid set of results from PRV. The headlines:
Rev +9% to £193m, +13% at constant currencies.
Adj. op profit +8% to £24.5m.
Op profit +8% to £22.8m
The adjustments to the profit figures are reassuringly light.
Even statutory PBT comes out at £20.9m, not far off the adj. PBT figure.
I think these results are slightly above consensus estimates, although the announcement does not confirm this.
Please note that acquisitions have boosted performance and so none of these figures are organic or “underlying”.
As we saw the last time I covered PRV, the company doesn’t mention underlying sales growth in its headlines.
You have to get into the footnotes of today’s report to find PRV’s underlying revenue at constant currencies. It turns out that growth according to this metric is just below 4% (£166.5m vs. £160.3m last year).
So once again I have to observe that underlying sales growth was limited. The company emphasises that trading conditions were “mixed” with “some end-market inconsistency”.
Then again, if the company can afford to make acquisitions and if growth is more attractive as long as those acquisitions are included in the results, should investors really care about weak organic growth? Perhaps not! But I think it’s good to understand where the headline growth is really coming from.
Final dividend gets a small increase to 4.2p, total dividend for the year 6.3p.
CEO comment:
"Trading conditions were mixed, with strength in aerospace and petrochemical markets offsetting weakness in laboratory and industrial consumables. The Group's strategy, unchanged since 2004, continues to deliver consistent results despite some end-market inconsistency. The Group focuses on markets with long-term secular growth drivers: tightening environmental regulation; the growth of analytical science; the need for clean water; the development of carbon-efficient transportation; the replacement of plastic and steel by aluminium; and the drive for manufacturing process quality and efficiency.
I note that the CEO is retiring this year; he has been in this position since 1998! But true to form, PRV is well set up with a “Chief Executive Designate” who has already joined the Board. The Designate’s most recent role is COO at Hill & Smith (LON:HILS).
In a review of the past 20 years, the retiring CEO highlights PRV’s achievements including compound growth in EPS of 13% and growth in the share count of less than 1% p.a.
It doesn’t happen often enough that companies use low growth in their share count as a metric of success! A stable or declining share count is one of the first things I look for when I’m making an initial assessment of any company. Bravo to PRV for keeping its share count stable over the long-term and for pointing this out.
Net cash: finishes the year very slightly lower than last year, just below £14m.
Checking the cash flow statement to confirm PRV’s explanation for the lack of growth in net cash, I see the following items:
£10m spent on acquisitions
£5m on capex (my impression is that this is mostly replacement capex, not growth capex)
£3m on dividends
£2m on pensions
It seems to me that most of these items could be classified as voluntary, except for the capex, so I would see true cash generation as c. £15m.
Contributions to the pension scheme are temporary, as the deficit is v. low at around £6m.
Also, the company's cash balance was held back by a large (£7m) growth in receivables - perhaps this might reverse in 2025?
Outlook: the CEO reiterates his belief in the company’s long-term strategy, and has this to say about the current year:
In the nearer term there is much to look forward to in 2025: new product introductions in aerospace, Seal Analytical and Kbiosystems; the installation of a new manufacturing line for aluminium filtration; industrial demand recovery in the US; and increased Laboratory in-house manufacturing through Hungary.
Graham’s view
I was AMBER/GREEN on this last July at a share price of 676p.
At 692p today, I think I can leave my stance unchanged.
I do admire PRV’s consistency and its stable share count over the long term.
It has an admirable track record of paying progressive dividends for many years.
The strategy of focusing on particular filtration/environmental markets has worked and continues to work.
Given all of its positive characteristics, I’m inclined to keep my positive stance on the share. However, I have to dock it some points for a) the limited organic growth, and b) the fact that the valuation does a good job of reflecting its past success.
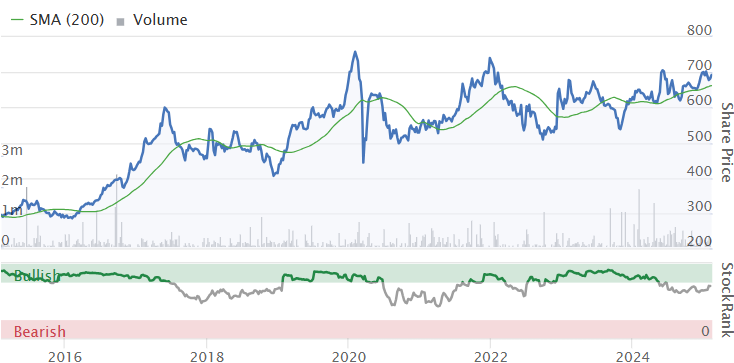
Perhaps if its end-markets can recover, we could finally see it breaking higher out of this 500p-700p range?
Zinc Media (LON:ZIN)
Up 7% to 66.25p (£16m) - Trading Update - Graham - AMBER/RED
Zinc Media Group plc (AIM: ZIN), the award-winning television, brand and audio production group, is pleased to announce a trading update for the period ending December 2024, subject to audit.
We very rarely cover this one. Paul gave it a scathing review last year on the basis that the messaging from management simply didn’t match up with reality.
It has a long history which goes back to Ten Alps (TAL), co-founded by Bob Geldof, that produced shows like Panorama and Dispatches.
Today we learn that 2024 EBITDA is £1.5m, in line with expectations.
However, revenue has apparently missed expectations at £32m, vs. £40m last year and a Singers forecast for £34m.
The fall in revenues reflects a disposal, business closures and “some opportunities moving into the new financial year which have now been commissioned”.
There is gross cash of £6.3m and net cash of £1.3m. The net cash figure is very slightly below forecast (£1.5m). Most of the debt seems to be in the form of shareholder loans, without covenants.
CEO comment:
The Group has undergone an exceptional transformation in recent years… focused the Group on its higher margin television and content production, whilst broadening its offering in this sector; positioning the Group for further growth.
The start of the new financial year has been excellent, with a slew of new, high-profile commissions and launches including the BBC documentary Israel and the Palestinians and a new multimillion pound primetime quiz show, The Inner Circle, hosted by Amanda Holden. Forward bookings for the current year are well ahead of the same time last year, and we have a strong pipeline for the year ahead…
Outlook: ZIN has won £16m of work in the last five months, and has £21m of revenue secured for FY25, up 24% compared to last year.
Graham’s view
Checking the forecasts again (with thanks to Singers), I see that adj. PBT for 2024 is expected to come in close to breakeven (£0.2m), so it’s only marginally profitable in real terms.
For 2025, adj. PBT is expected at less than £1m, which in my book is still not a meaningful level of profitability for a listed company.
And this is a concern because if it does generate £40m+ of revenues, as forecast, then I’d like to think that some of this might be left over for shareholders after all costs. Especially if the company is now focused on “higher margin” work.
But TV production is a people business. ZIN’s staff must be paid for their efforts. I doubt that trying to save on staff costs in order to leave a profit for external shareholders would be a winning strategy.
And it’s not a strategy that they’ve tried before:
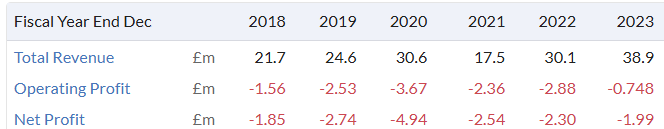
The company has raised new equity from time to time but at this stage it looks to have been a case of throwing good money after bad.
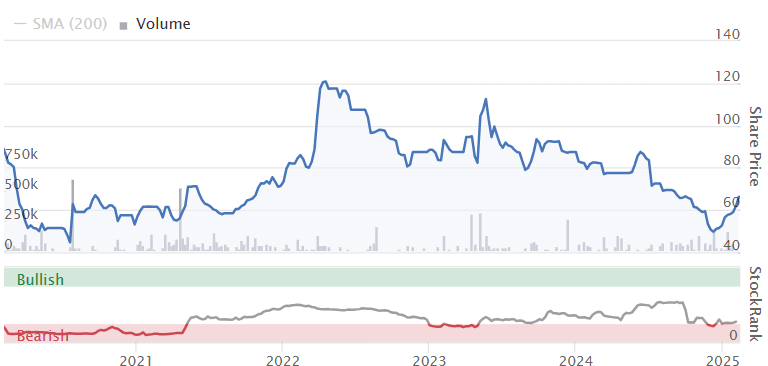
I’m toying between RED and AMBER/RED on this.
Why be RED:
A long history of unprofitability, and no meaningful profitability expected soon.
Doesn’t look like it owns any intellectual property. A people business.
A very thin net cash balance
Assuming that the net cash balance fluctuates from time to time, the company would be unable to repay its shareholder loans without finding another form of finance elsewhere. At least until profits and cash generation improve.
Why be AMBER/RED:
The new strategy is supposed to be more focused
The recent acquisition might improve performance possibly?
Revenues are supposed to increase 20%+ this year and the order book seems to support this.
Does not seem to be distressed currently.
I think I’ll go AMBER/RED on this, but it’s a really close call. I like to reserve RED for cases where there is current financial distress or a serious fundamental problem. It seems to me that ZIN is just a poor-quality business with a weak balance sheet. Maybe its performance can improve a little this year and it could give us a positive surprise at last. AMBER/RED it is.
EnSilica (LON:ENSI)
Down 11% to 43.5p (£42m) - Unaudited Half Year Results - Graham - AMBER/RED
EnSilica (AIM: ENSI), a leading chip maker of mixed-signal ASICs (Application Specific Integrated Circuits), announce its unaudited results for the six months ended 30 November 2024…
We already looked at this a week ago, on a contract award, and it’s back today with interim results.
This is another stock I upgraded from RED to AMBER/RED, as I figured that ENSI’s customers (such as the UK Space Agency) must have done some due diligence on their supplier’s ability to execute contracts. Even though the company did not appear to be financially very strong to me, its customers must have faith.
Today’s interim results show revenues of just £9.3m (H1 last year: £9.6m) which leaves the company with a mountain to climb in order to hit full-year forecasts. Singers had previously pencilled in £30m of revenue for FY May 2025. They have today cut this forecast to £28.2m.
Similarly, the adj. EBITDA forecast gets a shave from £4.8m to £4.1m, and the adj. PBT forecast gets lowered from £2.5m to £1.8m.
The CEO describes H1 as a “solid start”, which I’m not sure I totally agree with. He points to progress on contracts and highlights the potential SpaceX opportunity:
"We have made a solid start to 2025, securing a further five design and supply ASICs contracts, and we remain confident of securing additional mandates across the remainder of the financial year. Our NRE and chip supply revenues from these new contracts alone are expected to generate a further £100 million of revenues over their lifetime, starting from 2027 onwards, further cementing our growing financial base…
Our ongoing progress has been further highlighted by the recently announced £10.4 million of funding from the UK Space Agency… This funding will enable our team to advance our position and competitiveness as a key supplier of silicon chips for user terminals across the various new satellite constellations, offering an alternative to SpaceX's Starlink service."
Chasing SpaceX contracts seems to be a good strategy for listed companies!
Net debt: the company doesn’t make its financial position obvious in the commentary, you have to get into the footnotes to find the details.
Net debt is £4.9m, up by about £1m year-on-year.
The value of loans outstanding is up by £2m, and this is not matched by an increase in cash. The lender is the Bank of Scotland.
So again it looks financially shaky to me. But its customers don’t seem to mind, and hopefully their funding will enable ENSI to carry on without interruption?
We get a going concern analysis, which concludes with the Directors (not the auditors) saying that they are happy with the company's ability to continue as a going concern. But I note that one of the reasons this give for this point of view is “the Company's history of being able to access capital markets as evidenced by the raising of £5.2 million gross equity in May 2024”. So I certainly wouldn’t rule out another equity fundraise.
Graham’s view
I was AMBER/RED on this very recently and I’m not inclined to change my view today, although make no mistake: this is a poor set of results and is effectively a profit warning. But I’ll stay AMBER/RED on ENSI for now.
Roland's Section
Filtronic (LON:FTC)
Up 11% to 103p (£225m) - Further Contract Win with SpaceX - Roland - AMBER
Results from this radio technology business have been transformed by its relationship with Elon Musk’s firm SpaceX. Today we have news of a further contract win and an upgrade to expectations.
Filtronic plc (AIM: FTC), the designer and manufacturer of products for the aerospace, defence, space and telecoms infrastructure markets, is pleased to announce a significant new contract win with SpaceX valued at $20.9m (£16.8m), to be fulfilled in both FY2025 and FY2026.
As a result, expectations are being upgraded for both FY2025 and FY2026:
the Board is now confident the business will exceed current market expectations for revenue and profit in both FY2025 and FY2026.
Estimates: Filtronic’s financial year ends on 31 May, so FY25 is around three quarters complete.
Reading the RNS, my initial thought was that adding £16.8m to the next 16 months would be a very significant upgrade for a business with annual revenue under £50m. However, I had to question whether any of today’s contract news might already have been factored into forecasts.
Filtronic has not provided any information on revised expectations today. However, investors with access to broker notes are able to get more insight. With thanks to Cavendish, updated forecasts are available today on Research Tree.
Cavendish’s analysts have increased revenue forecasts for FY25 and FY26 by 4.1% and 4.9% respectively. They’ve left their price target unchanged at 110p.
Forecasts for adjusted earnings per share have been increased as follows:
FY25E: 5.0p per share (+4.2% from 4.8p previously)
FY26E: 3.2p per share (+6.7% from 3.0p previously)
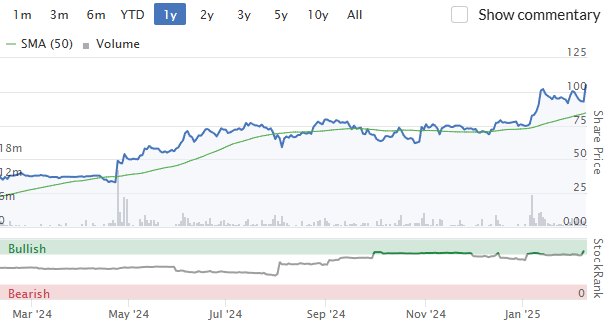
The shares have risen by 11% this morning at 08.30, meaning that Filtronics shares have become more expensive relative to expected earnings. I calculate a FY25E P/E of 21.5, rising to FY26E P/E of 32.
Roland’s view
Today’s news is certainly positive for Filtronic and its shareholders. But objectively it only appears to be a modest beat of existing forecasts.
My sums suggest the following revisions to Cavendish’s revenue forecasts today:
FY25E: £50.4m (previously £48.4m)
FY26E: £43.0m (previously £41.0m)
In total, this represents a £4m increase in forecast revenue. This seems to suggest that £12.8m (c.75%) of today’s contract award was already factored into analysts’ forecasts, prior to today.
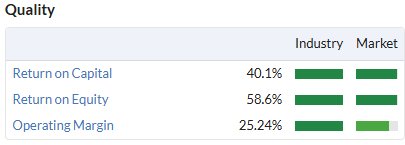
Filtronic is undoubtedly trading well and boasts excellent quality metrics. But the concerns around forward visibility and customer concentration that I raised in my last comment (4 Feb 25) are unchanged for me.
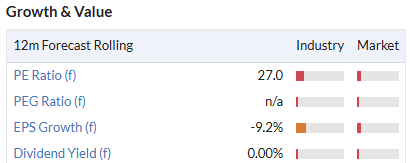
This may be an unpopular choice, but I continue to think that the share price is largely up with events for now. I’m going to maintain my view at AMBER today.
BP (LON:BP.)
Up 8% to 468p (£75bn) - Elliott Management stake - Roland - AMBER/GREEN
Shares in FTSE 100 oil major BP are up by around 8% this morning, after press reports over the weekend revealed that well-known US activist investor Elliott Management has taken a stake in the business.
The size of the stake has not been disclosed, but a source quoted in Bloomberg suggested it was “significant”. Newswire items like this are available on the News tab of the StockReport - e.g. here.
There’s no official comment on Elliott’s objectives but it’s suggested that Elliott sees BP as “undervalued” and will urge the company to “consider transformative measures”.
BP’s challenges have been much discussed in the press recently, together with its potential to become a takeover target. Even The Guardian had a piece over the weekend.
Some analysts suggest the business is trading below its fair value, on a sum-of-the-parts business. A greater focus on the upstream division (oil and gas production) might improve both valuation and profitability.
The company’s 2024 results are due to be published tomorrow (11 Feb) and BP is hosting a Capital Markets Day on 26 February. This was postponed from the 11th to allow CEO Murray Auchincloss to recover from a planned medical procedure.
BP has already talked about the potential for further disposals – I imagine we’ll learn more on 26 February.
Roland’s view
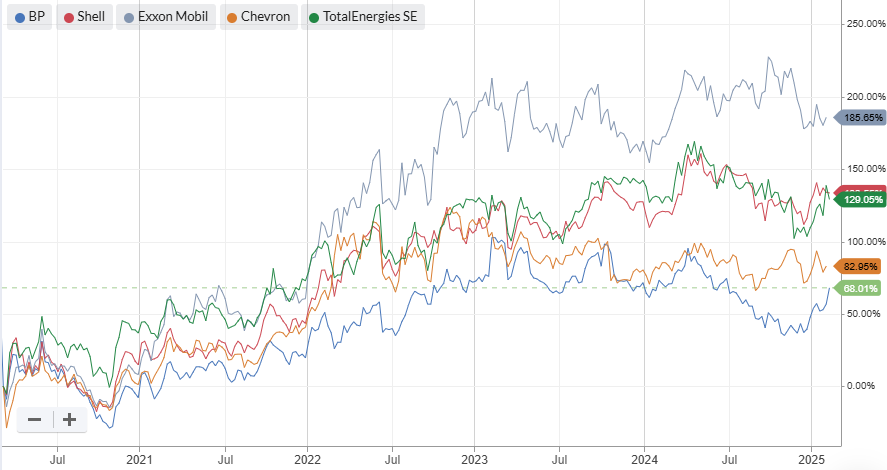
BP’s share price has certainly underperformed key rivals over the last five years:
One metric I like to use with these large, cyclical companies is the CAPE ratio, or Price/10yr average earnings. This can be useful to see through the variability in profits from commodity production and gain a more objective view on valuation.
Stockopedia provides this measure in its Value table view. We can see that BP is trading at a significant discount to key rivals:
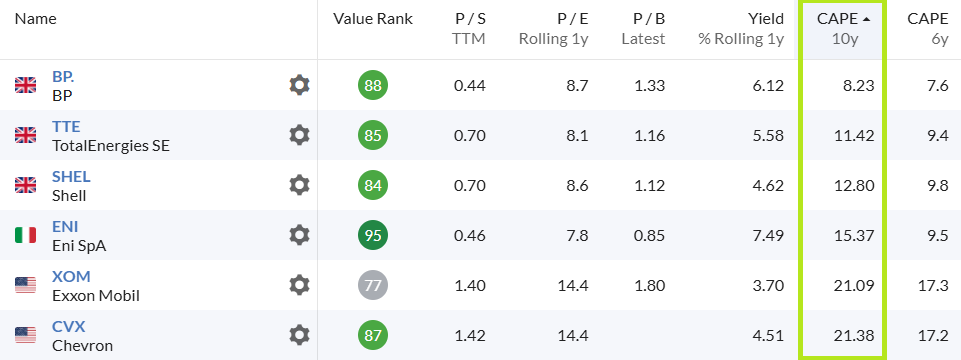
BP’s CAPE 10y of 8.7 (prior to today) suggests possible value, in my view.
However, the group’s falling profits and relatively high leverage have led some analysts to speculate that BP’s current share buyback and dividend programme might become unsustainable over the coming year.
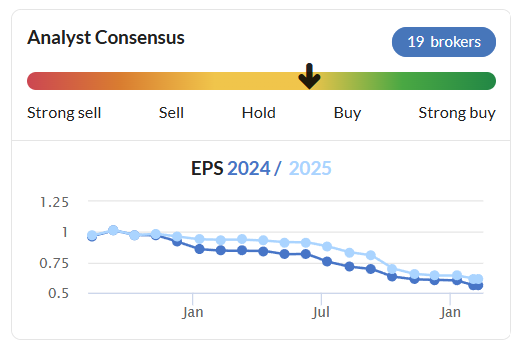
BP is large and complex and faces the additional challenges of geopolitical risks and the energy transition. However, I would be inclined to share Elliott’s view that the company could be undervalued, given the underlying quality and profitability of its core units.
This isn’t a detailed review, but on balance my view is that BP shares are probably quite reasonably valued at current levels. AMBER/GREEN.
Likewise (LON:LIKE)
Unch. at 19.3p (£48m) - Trading Update & Acquisition of Logistics Centre - Roland - AMBER
This fast-growing flooring distributor has issued its second trading update in just over a month today. Graham covered January’s full-year update here. Today we learn that 2025 has got off to a relatively strong start:
Likewise has made a positive start to 2025, with total sales revenue increasing by 8.4% in January and Likewise Branded businesses increasing by 13.6%.
For context, total sales revenue rose by 7.5% in 2024.
Likewise has also completed its geographic coverage of the UK, with the acquisition of a new warehouse for £1.2m near Plymouth. This purchase was funded from internal cash resources.
The new Logistics Centre will both establish Likewise South West and also enable Valley Wholesale Carpets to develop business with customers in Devon and Cornwall.
This purchase takes the reported value of the group’s freehold property portfolio to £23.3m. A focus on freehold property is one factor CEO Tony Brewer appears to be determined to replicate from his former employer Headlam.
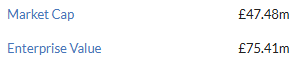
Likewise’s £23m property portfolio provides asset backing for half its market cap and just under one-third of its £75m enterprise value:
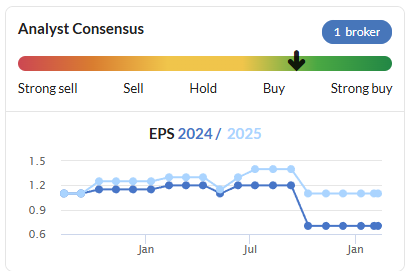
Outlook: 2025 forecasts are unchanged today, according to an updated note from house broker Zeus.
Revenue is expected to rise by 6.1% to £160m in 2025, supporting a 57% increase in net profit to £3m, or adjusted earnings of 1.1p per share.
In today’s update, the company says it has “extensive product launches planned for Q1 and Q2”. It’s aiming to “materially increase market presence in independent flooring retailers and contractors”.
CEO Tony Brewer continues to sound excited about the prospects for his business:
The momentum developed in H2 2024 has continued in the early part of 2025 providing the Group with confidence in an exciting future and further progress towards our medium term objectives
Roland’s view
Likewise is led by an ex-Headlam manager. His strategy appears to be to try and eat Headlam’s lunch. Recent share price action has certainly favoured the fast-growing upstart over the incumbent:
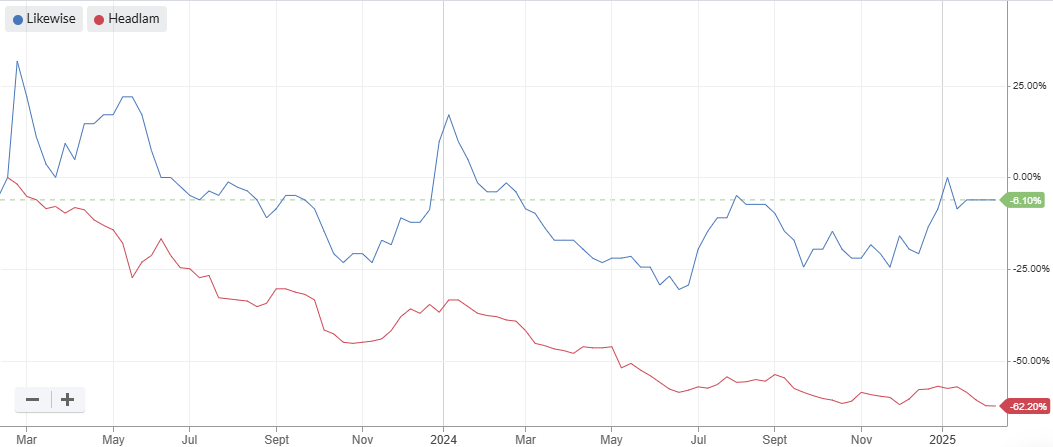
However, everything has its price. This sector is not exactly booming at the moment. I think it’s worth noting that Likewise’s Valley wholesale division – an established business it acquired – saw sales fall by 3% last year.
Low profit margins and (so far) very low returns on capital suggest to me that Likewise shares are probably up with events at current levels:
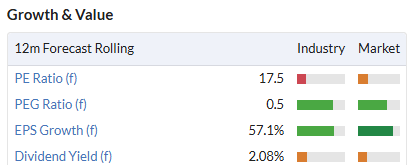
Graham took an AMBER view on Likewise in January. I see no reason to change this today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
In case you missed it, here is Zinc Media CEO Mark Browning discussing the Group’s current progress and prospects on the Engage Investor platform - https://www.engageinvestor.com/event/4d371385476c
Interesting to note your views on ENSI, which I think are basically fair enough.
I'd disagree though on your view that they have a mountain to climb on the full year revenue numbers.
As, if you look at the last year split it was heavily weighted to the second half and this time round they have the Siemens chips being supplied now coming through. They also have the big Italian contract contributing, so I don't see those revenues as being difficult to hit.
With four chips now in production and twelve more following through in the 2-3 year design phase, then there looks like some real growth prospects on offer if they can deliver over the next 12-18 months.
Certainly it looks like it could do with a decent raise, but I suspect that they have enough visibility from these large contracts that have been sealed and as you point out, I doubt that these big customers would entertain them if they were likely to go out of business, given the nature of what ENSI is providing.
If they announce further contract wins in the coming months as I expect, then this could well prove to be a big winner. Highly speculative of course and it could do with a much strengthened balance sheet.
I see Pan African Resources (LON:PAF) put out a trading update today, around 9am. Does not look very good to me but it is not very clear, shares are down 9%.
Likely a bit of a profit taking today on a day where gold miners did stonkingly well. I guess the grass was greener on this Monday
Pan African Resources (LON:PAF) Looks way below the forecasts, so much about rates of exchange. Gold sold was18% down.
I don't understand this: "The opportunity cost associated with the synthetic forward transaction of US$17.4 million (2023: US$1.7 million)."
I haven't looked into this at all Rusty, nor do I know the company, but would it be an increased cost ( less profit ) due to more aggressive gold price movements upwards in 2024 compared to 2023 ... i.e. the downside gold price hedges lost more money as the gold price moved up more aggressively... causing bigger accounting entry losses ... ?
Thanks for the write up on BP (LON:BP.) The team have produced some great research articles recently on stocko analysing performance after events such as 'ahead of expectations' and 'director dealings'- I would be keen to see something similar on activist involvement and whether that precedes outperformance.
Join us for MelloMonday on tonight at 5.30pm.
The programme for the evening is as follows:
5:30pm Company Presentation from Time Finance plc
6pm Company Presentation from React Group plc
6:30pm Educational Presentation
6:45pm Company Presentation from Hercules Site Services plc
7:15pm BASH (Buy, Avoid, Sell, Hold) Panel featuring Mark Simpson (OMG) and Damian Cannon (SAAS)
For more information, click here: https://melloevents.com/mm100225/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1485401
FTSE 100 hits another high. The MSM are all over it! (Not)
As a shareholder in LifeSafe Holdings (LON:LIFS) , I cannot disagree with your view that the company is subscale, loss-making, speculative and risky. It also has a history of doing cash raises at lower prices. But at a £3.5m market cap what can one expect?
Why do I hold, other than the lowly valuation?
I bought Lifesafe’s small (hairspray can size) extinguisher product on-line a while ago and I noticed how immediately the rest of the family bought in to the concept. They had previously argued against having an extinguisher which was heavy, unsightly and no-one would be capable of using in the panic of an emergency. They saw it was useful to have a small easy to use extinguisher which can tackle all types of fires before they grow too big We have 3 at home - so if a fire started we would have one close at hand . Fortunately we have not yet had to use the product .
This is the company’s consumer product - which is largely sold in the US. Effectively the same underlying product is sold in the industrial products.
The company’s fire extinguisher product is flourine-free, works on multiple types of fires (including lithium ion) and has a low environmental impact, which is particularly useful in the forest fire, where I understand older products like LC95 are being withddrawn. I am not a fire extinguisher expert but I have been reassured that some of the other shareholders I have come across work in the industry. I also am told that the Lifesafe product is less toxic than other competitor lithiun ion extinguisher products based on vermiculite.
The company pivoted to a B2B2C and B2B strategy in early 2024. Manufacturing and consumer customer fulfilment is effectively outsourced. This simplification should make the company much easier to scale. So to me the post-2023 business model makes sense. The last four six-monthly periods have seen declining cash burn. The key to reaching profitability revolves about its ability to convert interest into contracts. Today’s RNS offers hope that significant additional contracts may now be coming into view.
Interesting post…but I think you may have been misinformed re vermiculite ..the principal competitor is AVD from Goodwin (LON:GDWN) …I hold btw…which is completely benign and industry standard certified for fighting Lithium Ion fires https://www.avdfire.com/what-i...
I’d be interested to know what certification Lifesafe products have for a comparison
I’d say the RNS is more likely plumping the cushions for one final fund raise to avert collapse
Thanks. Your link to the properties of AVD is very helpful.
Zenova (LON:ZED) did you take part in today’s £250k raise?
No
ITV (LON:ITV) has risen 4% today on no news as far as I can see. There was a news item out on 30th Jan about a possible studio merger with with Redbird IMI's production arm, but no official RNS followed. Perhaps this is progressing?
I hold.
Filtronic (LON:FTC)
Surely it's a good thing to have a independent observer like Roland show some scepticism and highlight the risks? Even if you are a shareholder, you don't want everyone to be parroting the same view that this is going to the moon, and that everyone should HODL come what may? We've seen how that ends up, many times over.
That is all, carry on.
Chris
Roland, you say BP (LON:BP.) is better value than its peers. Shell (LON:SHEL) is probably are the nearest, hardly any discount and the quality according to Stockopedia is much lower. Their debt levels are also relatively higher.
As Roland points out, BP does look cheaper based on CAPE (i.e average earnings over the past 10y ) - earnings are quite volatile on a year-to-year basis and tend to mean revert over time so CAPE is arguably a better measure than standard PE ratios.
I was looking the Stockopedia value as well. Does CAPE take into account the debt? Management has not been good either in the past, probably why the quality score is low.
Filtronic
I remember a pretty negative view on filtronic from Paul when we discussed it when it was sub 20p
There was some healthy debate both then and has been all the way up with a lot of naysayers
Hopefully DYOR and come to your own conclusions.
If you take a big position on a company I think we individually should know more than any writers who by definition have to cover literally thiusands of stocks
I only cover 30 companies so my knowledge and understanding by definition has to be better .
Hence whilst stocko writers are worth reading it should always be for reference only and start a seed on potential new interesting companies
Im not into any of this large cap and US market “new look” either so find less useful stuff on here .
Agree with you Planetx. I have been a holder for many years since it was 8p.I too read many things, I only use Stocko and other writers as a guide and as you said DYOR. I sometimes find what some of them say about stocks goes completely the opposite way. Glad I went with my own gut instincts :)
I totally agree with you PlanetX regarding Filtronic (LON:FTC. I have been a holder for many years since it was 12p drifting to 8p but followed my gut instinct rather than brokers. I too only use Stocko writers and other analyst as guides. Best policy is DYOR I find that a lot of the time the shares go completely opposite to what they predict.
BP (LON:BP.) it’s mad how much impact an activist investor buying can have on a share price of such big companies 7% for BP this morning. Can’t see mention of how many shares they have acquired but suspect it’s under the reporting threshold.
Market Makers making the market? Otherwise it is down to proactive investors sentiment.
It made more of an impact than a few ahead of expectations announcements made recently. Given the size of BP find it hard to see how much impact an activist can actually have without owning a significant % of the company. The same thing happened with Uber in the US in the last few days.
suspect your right market makers setting the price on the news.
I hope the team are going to take a look at Porvair (LON:PRV) today. A long-term core holding of mine that might not set the world on fire but delivers consistent revenue, earnings and cashflow growth from a selection of businesses that have promising secular growth drivers.
I'm sorry Roland, amber on Filtronic (LON:FTC) given they have already stated they will exceed market expectation a week after their last update?
Do you not see a pattern here? Do you want them to put all their cards on the table and guide you to exactly what is in the pipeline?
I note not too long ago you rated Beeks Financial Cloud (LON:BKS) amber/green, with "Exciting growth potential."
I hold both for a considerable amount of time - I can tell you what growth I'm more excited about and it's not Beeks!
Given the share price is roughly where it was last week without the forward looking visibility, I'd argue this is even better priced than it ever has been!
You might well be right, Viz, but let's not forget that Filtronic (LON:FTC) has been a bit of a basket case for the last ten years barely breaking even whilst it occasionally boasted of strong order growth and then disappointed again. This time could well be different and they clearly have (in SpaceX) a giant customer at the cutting edge of their industry. However, I would need to be very sure that the Filtronic technology behind the sales to SpaceX was applicable elsewhere and that we were going to see a widening out of the customer base at some point before I got too excited from here.
Hi Viz,
Thanks for your comment. I do recognise there's a risk I'm behind the curve on Filtronic (LON:FTC), or that my view is too short-sighted.
However, from what I understand, earnings are forecast to fall sharply next year and some technical milestones must be met to trigger the next phase of SpaceX growth.
I don't know how much uncertainty is attached to this, but it seems a potential risk to me.
So too is the level of customer concentration. Checking last year's annual report, SpaceX contributed 48% of revenue last year, while the company's three largest customers generated 84% of turnover.
If something goes wrong with one of these key relationships, profits could fall very sharply.
Today's upgrade from Cavendish is also relatively modest and the shares are now close to the house broker's (unchanged) target price of 110p.
My comments only reflect my personal view. I don't have the in-depth knowledge of the company that a long-term shareholder might have. For prudence and balance, I have to consider valuation and downside risk, as well as the scale of the potential opportunity.
I think Filtronic does look like a good business that's performing well. My amber view is not intended to be critical, but to reflect a variety of possible factors, including valuation.
I hope this comment helps to add some context to decision to stay with amber.
Roland
Thanks for your response Roland - and I do understand your concerns - I shared similar here last week. That said over the weekend I revisited these concerns with a friend who works with the RF space (and is even more keen than me on Filtronic (LON:FTC). While your concerns regarding earnings volatility and customer concentration are valid, there are several key growth drivers that could support Filtronic’s long-term trajectory.
1 - Expansion of the space sector - this was mentioned last week by them when they stated "overall market size growing to $310bn USD by 2031"
Filtronic has established itself as a key supplier of high-frequency RF technology, particularly in E-band and mmWave products for LEO satellite constellations. The demand for high-speed satellite connectivity is increasing, with SpaceX's Starlink, Amazon’s Project Kuiper, and other emerging players requiring high-performance gateway and backhaul solutions. The ongoing commercialisation of space-based internet presents a strong market tailwind.
Moreover, Filtronic’s role in supplying high-power amplifiers for ground stations means it benefits not only from SpaceX’s expansion but also from the broader ecosystem of satellite operators. While technical milestones must be met for further SpaceX contracts, Filtronic's expertise in mmWave technology positions it well for continued engagement.
2 - Beyond space:
Customer concentration is a consideration, as I set out last week but Filtronic has actively pursued diversification. Notably:
3 - mmWave being used in space
Last week's update indicate that Filtronic's mmWave technology is now being deployed in space applications, an important milestone that could open doors to new contracts. The successful operational use of E-band in orbit would reinforce Filtronic’s market leadership in this niche.
Value? While Cavendish's upgrade may seem modest, their share price targets are often conservative with Filtronic (as mentioned on this thread - perhaps guided by management) in the face of emerging opportunities. If Filtronic secures further contracts beyond SpaceX, or if its technology gains wider adoption in LEO and 6G infrastructure, the valuation outlook could shift - and let's face it, they have literally a year to smash those targets.
Caution is understandable, but Filtronic has significant upside potential through its exposure to the rapidly growing space communications market, the expansion of high-frequency backhaul solutions, and its ability to diversify revenue streams. The next 12–24 months will be key in determining how effectively it can capitalise on these opportunities.
I hold, obviously :D
Liking against Filtronic (LON:FTC) there are certain similarities with Novacyt SA (LON:NCYT) , the diagnostics company which went from nanocap to borderline midcap on the basis of manufacturing the best Covid diagnostic kit on the market. It had a mountain of cash and the prospect of expanding into all manner of neighbouring fields of medical endeavour. It then fell out with it main client, the DHSC, and sank without trace. I still hold my stake which is currently showing a 93% loss (having once been some 250% up) partly as a reminder to be wary of investing in companies like Filtronic (LON:FTC).
I think what everyone forgets is that buyers, holders and sellers can all be right at the same time. It's often just a question of timeframes.
My view on Filtronic (LON:FTC) has been pretty consistent, and data driven over recent months, as follows:
My view is that FTC will see accumulation and post-earnings-announcement drift in the direction of these surprises for the next 6 months+ (with the caveat that this is based on the base rates).
Roland's view is likely based on a longer timeframe than my analysis. He's right to call out the very high weighting towards a single SpaceX customer.
Different views and timeframes make a market. There is a world in which the share price does very well in the shorter term, but the single customer weighting hits FTC's share price at some point!
If you want to read up on "Ahead" announcements, first day share price jumps and the ensuing "Drift" in share prices - catch up on the following resources.
Ed, thanks for stepping in, your input is that valuable. I'm becoming increasingly focussed on short termism and high dividends, don't hold Filtronic.
It’s difficult to think in probabilities. That’s natural and human.
Excellent debate this. Thanks everyone for their comments on Filtronic (LON:FTC)
Gulf Marine Services (LON:GMS) summary (posted on advfn) from Panmure Liberum note:
"Since 2021, the primary focus for GMS has been around deleveraging. This has now largely been accomplished due to favourable markets with the net debt projected to be US$160m (net debt/EBITDA ratio of 1.5x) by December 2025 - it was US$406m and 8.1x in 2020. Accordingly, the narrative has evolved such that GMS, having regained the trust of the banks can consider payment of a dividend, share buybacks or possible expansion in the fleet by way of buying or leasing further vessels. In effect, its recovery story has moved on which has yet to be fully realised in the share price. We maintain our BUY recommendation and target price of 30p.
Demand outstrips supply for vessels – FCF yield of over 20% GMS is benefitting from a favourable macro-backdrop of improving demand for its vessels both in the Gulf region and the North Sea coupled with a tight supply of vessels. This has led to a potent combination of increased backlog, day-rates, utilisation and cashflow. We see this positive scenario playing out for, at least, the next three years given the lead time in supplying new vessels and the upbeat outlook for Oil &Gas and Offshore Wind Projects.
Capital allocation – what happens now? The priority in 2025 remains deleveraging but options are materialising: 1) pay a dividend 2) engage in share buy-backs, or 3) expand the fleet by buying or leasing another vessel. All three options are feasible and to highlight how attractive a dividend payout of 25% would be – it would imply a dividend yield of c.5% which would be 3.8x covered and cost only US$11m in cash terms in 2026."
Gulf Marine Services (LON:GMS) - could memories of the NMC fraud be holding this back? Perhaps some scepticism about the quality of audits in that part of the world (NMC was audited by EY since its IPO in 2012).
I hold.
Filtronic (LON:FTC) - Another SpaceX contract win
"Consequently, the Board is now confident the business will exceed current market expectations for revenue and profit in both FY2025 and FY2026."
As upgrades go, that's as good as it is going to get in a week. Never a doubt.
Filtronic (LON:FTC)
Uncertainty over FY2026 revenue now removed at Filtronic (LON:FTC) (LON:FTC). That was the only remaining brake.
Cavendish forecasts for 2026 dil EPS moved from 3.0 to 3.2p. Still looks conservative to me.
The brokers have been WAY behind the curve on FTC for over a year now. Makes it an easy game for the patient GARP investor. The value is astonishing to me but I'm very biased!
As a former analyst I can tell you the Cavendish analysts will be doing precisely what they are told!
Interesting insight. I have often wondered just how much independence sell-side analysts have when it comes to their forecasts and opinions on clients. Are broker forecasts that deviate from the company's optimistic ones allowed? Can they be vaguely negative in terms of outlook? Or does it more depend on the value of the client relationship, how long they are likely to remain a client, or the personalities involved?
I was referring to analysts at the corporate broker; other analysts can do whatever they want (usually). More pusilanimous ones, including ones at the big US banks, rarely tread outside company so-called guidance.
Interesting. So you think FTC management are simply lowballing the analysts?
Having met the management at a Mello, they are very sensible, and therefore want to under-promise and over-deliver.