Daily Stock Market Report (Mon 11 Nov 2024) - CYAN, CAV, IPF, AQX, SAG, TIG

Good morning! Welcome to Monday's report.
And we're all done (1pm).
Cheers!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Companies Reporting
Summaries
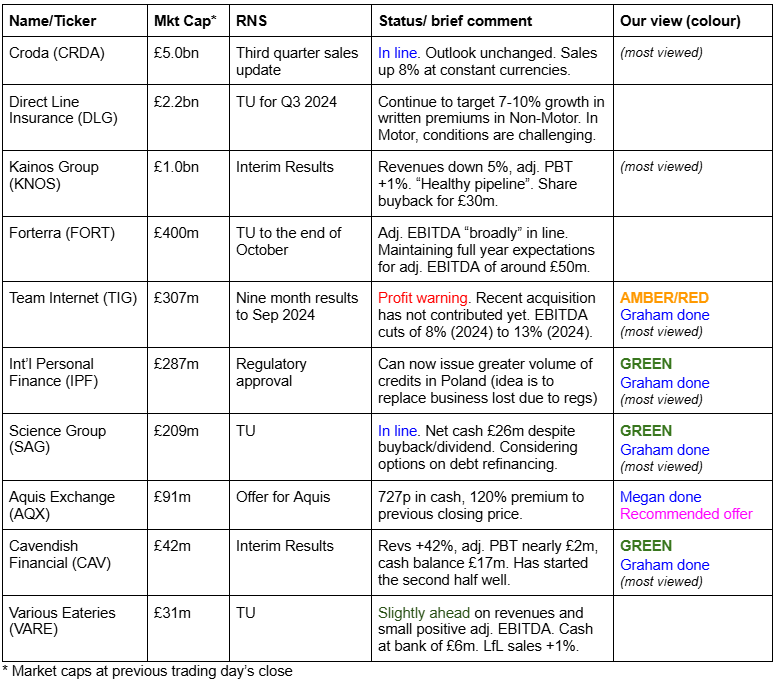
Cavendish Financial (LON:CAV) - up 7% to 11.8p (£46m) - 2025 Interim Results - Graham - GREEN
H1 revenues are up by over 40% year-on-year at this investment bank. Profitability remains weak with a result that’s only around breakeven. I’m happy to stay positive as I do think AIM can continue to strengthen from here.
Aquis Exchange (LON:AQX) - up 115% to 708p (£91m) - Offer for Aquis Exchange - Megan - PINK
Swiss stock exchange operator SIX has made an all cash bid for AQX which values the shares at a 120% premium to the previous day’s closing price. The bid has been recommended by the company’s directors and a cohort of its major shareholders, so this looks like a done-deal, which releases value for private investors after a lacklustre five years as a listed company.
Team Internet (LON:TIG) - down 16% to 99.7p (£308m / $397m) - Nine month results - Graham - AMBER/RED
It’s a profit warning with cuts to EPS forecasts of 13% and 18% for 2024 and 2025, respectively. A cheap valuation gets even cheaper. With $100m of net debt lingering, I’m reluctant to go back to neutral just yet despite some very low valuation multiples.
Short Sections
Cyanconnode Holdings (LON:CYAN)
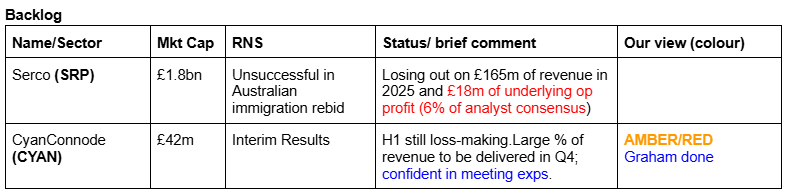
Down 12% on Friday to 10.3p (£37m) - Interim Results - Graham - AMBER/RED
CyanConnode (AIM: CYAN), a world leader in narrowband radio frequency (RF) mesh networks, announces its unaudited interim results for the six months ended 30 September 2024…
Paul was unimpressed with this company’s full-year results (for FY March 2024), discussed here.
As predicted, it did need to raise new funds and it did so in September, issuing 60 million new shares at a price of 9p. This brought the share count up to nearly 360 million in order to raise £5.4m for the company before expenses.
The jump to nearly 360 million shares is not yet reflected this chart:
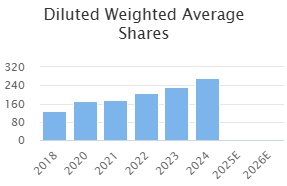
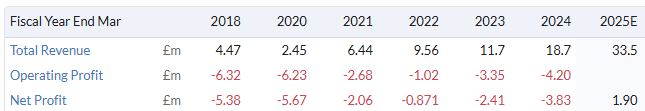
The most recent interim results show a decline in revenue (from £5.8m to £5.6m) and another operating loss of £2.1m, about the same as H1 last year.
Despite this poor outturn, the company says it is on track to meet ambitious expectations for the year that imply a radical change in fortunes: it is forecast to generate full-year revenues of £33m (!) and a pre-tax profit of £1.3m.
The reason for this optimism is an enormous increase in the company’s order backlog, with a large chunk due for delivery in H2.
The units in the order backlog are “Omnimesh RF Modules and associated products”, for use in Indian electricity smart meters (explanation here)
The track record here is truly awful but in light of the fact that it has recently raised funds (cash balance nearly £4m as of the end of September) and is apparently on track to deliver these orders in H2, I’m happy to upgrade my stance on this a little, up to AMBER/RED for now.
International Personal Finance (LON:IPF)
Up 1% to 133.7p (£290m) - Regulatory Approval - Graham - GREEN
We covered the Q3 update from IPF last month with news that the business had stabilised in Poland in terms of its year-on-year numbers.
This follows a traumatic period for IPF in Poland where new legislation reduced the cap on the non-interest cost of credit for consumer loans. The cap was reduced from 100% to 45%, with the result that IPF’s home credit business was forced to evolve very quickly - but job losses and a shrinkage of the business were inevitable.
Today’s news is that IPF has been granted a full payment institution licence in Poland, which means that it can expand its credit card business. CEO comment:
The customer response to our new credit card offering has been fantastic. With this new licence, we will be able to expand access to even more customers, allowing them to shop online, in retail stores or access cash through their customer representative or an ATM. Based on the success we have seen so far, we believe there's strong potential to introduce this credit card product to our other markets in the future."
Graham’s view - I had no reason to doubt that IPF would get this licence but the news is to be welcomed and provides a slight boost to my existing positive view on this stock. The company is exposed to a broad range of risks, which I believe are likely to be priced in at this valuation:
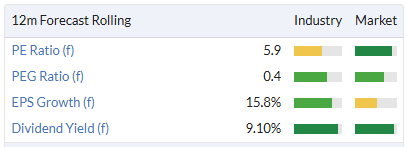
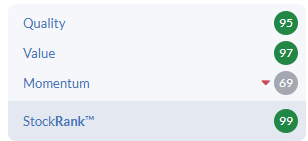
I also note that it carries a perfect StockRank of 99.
Please see here for my interview with the management team earlier this year.
Science (LON:SAG)
Up 1% to 469.5p (£211m) - Trading Update - Graham - GREEN
SAG is “an international science & technology consultancy and systems organisation”.
It provides “products and services to clients in the key vertical markets of defence, industrial, medical and consumer”.
Its year-end is in December, and we get the following trading update:
Trading in line with expectations for 2024.
NI contributions will go up by £0.7m; the company is planning how to mitigate this.
Net cash is £26m as of the end of October. It was £18m at the start of 2024 and the company has returned £7m to shareholders during the year (divis + buybacks), so net cash generation must have been robust year-to-date.
Loans: despite the large net cash position, the company has a term loan expiring in 2026 and a (currently unused) RCF. There was £13m outstanding on the term loan at the start of this year. SAG discusses in today’s trading update how it plans to refinance/renew these. It doesn’t sound to me as if it should have any difficulty at all refinancing, given its net cash position and solid trading.
The update finishes with a vaguely-worded hint of activity:
If concluded on satisfactory terms, these new, increased facilities with extended commitment periods, combined with the Group's existing cash resources, would strengthen Science Group's ability to continue to consider corporate opportunities which may arise.
Graham’s view
Back in March, Paul speculated on what deals SAG might be considering or working on behind the scenes.
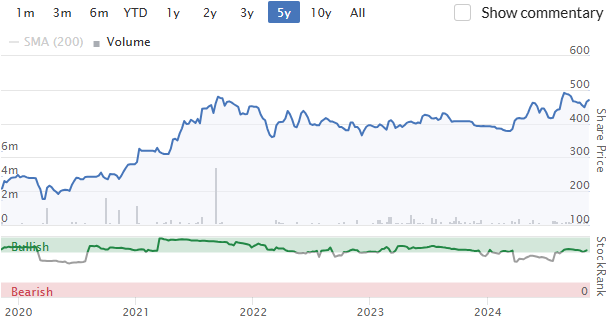
This isn’t a sector I love but I’m happy to leave the GREEN stance unchanged for now given the company’s resilient trading, strong balance sheet, and murmurs of potential activity coming down the tracks. A £5m share buyback is ongoing.
Graham's Section
Cavendish Financial (LON:CAV)
Up 7% to 11.8p (£46m) - 2025 Interim Results - Graham - GREEN
This is a stock from my best ideas list that hasn’t done very well: it’s still down 7% year-to-date. But despite the lacklustre share price performance, there are signs that the bull thesis may play out.
From today’s interim results to September:
Revenues +42% year-on-year to £28m
Adj. PBT £1.8m (H1 last year: adjusted LBT £3.6m)
Cash of £18m
Unfortunately, share-based payments to management of £1.6m eat up nearly all of the adj. PBT.
Other adjusting items eat up the rest of it, so that the unadjusted result is only around breakeven.
Interim dividend increases slightly to 0.3p (H1 last year: 0.25) but this will only cost £1.1m so it’s not a huge commitment given the existing cash balance .
Outlook: H2 has started well, with the revenue run rate continuing at the same pace as H1.
As the leading broker on AIM, Cavendish’s comments on the state of the market are worth quoting extensively (emphasis added):
In the recent UK Budget, the Chancellor's announcement that shares in companies quoted on AIM will be afforded 50% inheritance tax relief from 5 April 2026 recognises the vital role played by this market in the UK's economic growth and removes any uncertainty about its future.
We believe this relief, coupled with the inclusion from 2027 of unused pension funds within inheritance tax, means AIM shares will become particularly attractive from a tax planning perspective.
Makes sense to me: with more investments subject to inheritance tax, even 50% relief is valuable. So there is still a good case to be made for AIM from an inheritance tax perspective.
They continue:
UK small and mid-cap markets are trading at historically high multi-decade discounts to their global peers. With interest rates reducing, a positive agenda for pension fund reforms, a stable political landscape and the uncertainty around AIM now resolved, we see the attraction of investing in the UK increasing and expect the headwinds that have been constraining our markets to abate, narrowing this discount. Furthermore, we do not expect that the modest increases to capital gains tax will impact levels of activity for public or private company transactions.
Graham’s view
I agree with Cavendish that taxes are not a hurdle to investing in AIM and that AIM is still attractive from a tax point of view.
While the recent changes do involve paying more tax on AIM shares, it remains advantageous to invest here vs. other exchanges.
And we should now be able to enjoy this clarity for the foreseeable future: it would be unthinkable for the new government to tinker with the rules around pensions and inheritance on an ongoing basis.
I don’t think taxes and political uncertainty have been the problem with AIM. I think AIM-listed companies themselves have been the problem: see the long-term AIM All-Share Index chart for proof.
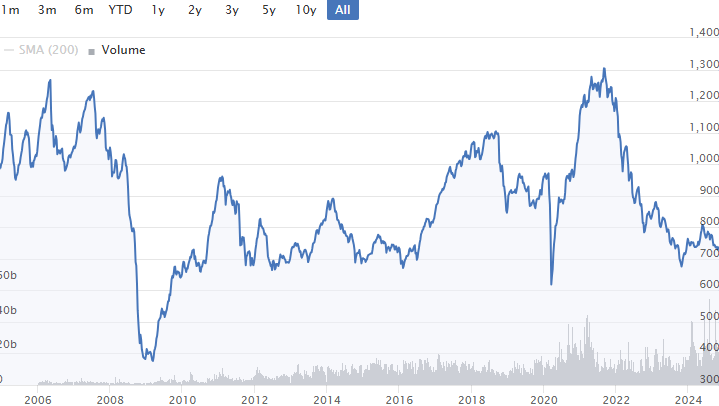
If readers are aware of any other stock market indexes with a performance like this, please do share them.
While this chart does not include the positive effect of reinvested dividends, it does show an index that has failed to grow in value over a considerable period of time.
The last time that the market achieved a high valuation, in 2021, the brokers responded by dumping a wave of poor-quality IPOs onto investors, with the result that “2021 IPO” has become almost synonymous with “junk”.
What we’ve seen since then: another crash in the overall value of this index.
Of course interest rates also had something to do with the crash, but higher rates did not prevent the FTSE All Share Index and the FTSE 100 from making new all-time highs in 2024.
In my view, the biggest hurdle to investing in AIM is that the overall index can’t be trusted to generate a good return. It’s difficult enough to carry on investing in the UK when the US has provided such wonderfully high returns, but it’s made more difficult on AIM when the overall index is almost guaranteed to do badly.
That’s where the power of intelligent stock-picking comes in. Hopefully on Stockopedia, we’ve helped to demonstrate that it’s possible to create good portfolios and pick good stocks, even in difficult periods such as the last few years.
As for Cavendish itself, I remain GREEN as I wait patiently for the tide to turn.
Team Internet (LON:TIG)
Down 16% to 99.7p (£308m / $397m) - Nine month results - Graham - AMBER/RED
TIG is “the global internet company that generates recurring revenue from creating meaningful and successful connections: businesses to domains, brands to consumers, publishers to advertisers”.
It previously had the name “Centralnic” with the ticker “CNIC”.
See its wide range of services here - everything from domain name sales and digital advertising to consumer-focused product comparison websites (in French and German).
Its main online marketing products are from TONIC and ParkingCrew. Earlier this year it bought Shinez for $43m.
Today it publishes a profit warning with its interim results.
An overview:
For the nine-month period, revenue is up 1% to $615m, and adj. EBITDA is up 2% to $70m. There are slight increases in its gross profit margin and adj. EBITDA margin.
However, higher finance costs have taken a lump out of PBT, which falls 8.5% to £18.3m.
Net debt is close to $100m, which is up from $74m at the start of the year.
The leverage multiple is still ok at 1.2x.
I’m saddened to see that the company has been buying back its own shares despite its net debt position. Paul queried TIG’s buybacks here.
Outlook section is long, but I think this is the main point (emphasis added):
The Directors are pleased to report that Team Internet Group's core businesses remain strong and resilient. While our recent acquisition of Shinez has yet to contribute to EBITDA, we are actively adjusting its operating model and cost base to improve performance…
The Group remains on track to produce record profits in 2024 and 2025, albeit at more moderate growth rates than originally anticipated. The Group now expects to deliver approximately USD 97m adjusted EBITDA for 2024.
Estimates: thanks to Edison Research for publishing a note today that is freely available.
They argue that TIG’s core business has “performed creditably” in a difficult advertising market, but that Shinez has “significantly underperformed”.
Changes in forecasts:
For FY24, Edison cut the revenue forecast by 8% and cut EPS by 13%.
For FY25, they cut revenue by 21% and EPS by 18%.
Their new EPS estimates are in the region of 23p for both 2024 and 2025.
Graham’s view
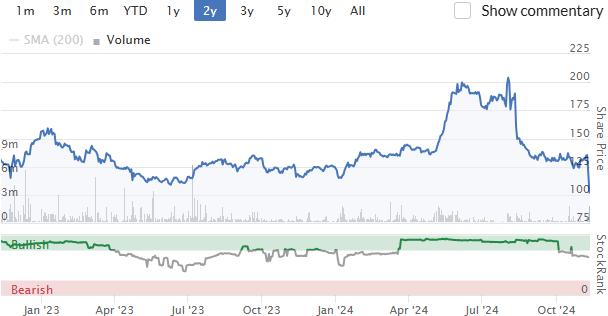
The main reason that has prevented TIG from falling further today is probably the fact that it was already trading very cheaply on a PER basis.
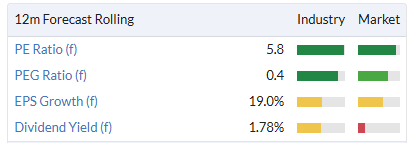
However, I’m not sure I would be in a rush to buy here, even at the current lower levels.
TIG is complicated: it has some core assets which don’t seem to be growing very fast, it has an acquisition that is significantly underperforming vs. expectations, and then it has a wide range of non-core assets that are difficult to assess. The whole does not appear to be greater than the sum of its parts, and indeed it seems to have too many parts to make for a sensible investment.
The Board are aware that the stock market is sceptical, saying that they believe “the market does not fully recognise the value of this diverse asset mix and is committed to providing greater information…”
In addition to providing more information, one of their proposed solutions is “balance sheet optimisation”, i.e. more dividends and buybacks. But given given the large debt load, is that wise? At least the net debt position is forecast to reduce over the next year, according to Edison’s forecasts.
After today’s profit warning, I think a healthy dose of scepticism remains appropriate here and so I’ll leave the AMBER/RED stance unchanged. It might be very cheap but I’d like to see some stability and debt reduction before going back to neutral.
Megan's Section
Aquis Exchange (LON:AQX)
Up 115% to 708p (£91m) - Offer for Aquis Exchange - Megan - PINK
Swiss stock exchange operator SIX has made an offer to acquire London’s Aquis Exchange (LON:AQX) for an all-cash offer that values the company at £207m, or £225m on a fully diluted basis. The offer, which has been recommended by the group’s directors, will see shareholders receive 727p per share, a 120% premium to the closing price on Friday.
Aquis was founded in 2012 and listed on the London Stock Exchange in 2019, where its shares have never really gained much traction. The offer represents a slight premium to the highest price the company’s shares have ever achieved on the stock market of 720p per share back in September 2021.
That doesn’t mean the company has been an all-out disappointment. Over the last ten years it has grown to support the daily trading of about €2bn worth of European equities (a total of €40bn is traded on stock exchanges across Europe on a daily basis) through its four operating subsidiaries. British investors are perhaps most familiar with the Aquis Stock Exchange (AQSE), a growth market which hosts the likes of Shepherd Neame and Adnams. But the company operates order books covering over 6,500 European stocks across 16 markets.
Sales have risen by almost 500% since the IPO and the company has become increasingly profitable, last year reporting net profits of £5.2m, compared to a £3.4m loss the year before it joined the market.
But continuing to grow in the competitive world of trading has proven challenging. The directors have pointed to this as one of the reasons for recommending the offer, commenting today that: “the terms of the offer provide Aquis shareholders with an attractive opportunity to accelerate and de-risk future value creation and realise certain value of their holdings today in cash”.
SIX and Aquis have already received approval from shareholders representing just over a third of the share count, but the remainder of the shareholders will now also have the opportunity to vote. The takeover is expected to complete in the second quarter of 2025, at which point shareholders will receive cash in exchange for their shares.
Megan’s view: This looks like it’s pretty much a done deal. With the directors and major shareholders already bought in, it’s likely that the rest of the shareholders will follow and the takeover should be completed by the first half of next year.
Does it represent good value? An enterprise value of £194m is equivalent to 8 times sales and 37 times operating profits delivered in the last 12 months. That’s not far off the current valuation of the London Stock Exchange and a premium to the valuation the LSE placed on Refinitiv in its 2021 acquisition.
More significantly, this looks like a sensible strategic move for Aquis, which has grown from a minnow into a meaningful operator in the European exchange network, but is likely to struggle to make further inroads.
In our recent webinar, Ed and I suggested that a good way to respond to a takeover offer is often to sell half of one's holding, while awaiting potential further offers. As this is a recommended offer, it’s unlikely we’ll see higher bids at this stage. Therefore, selling out at 710p might be sensible for those shareholders who wish to free up some cash to be deployed elsewhere, if they don't wish to wait for the proposed 727p payout next year.
The big question really is why the company’s shares were trading so much lower than what has now been deemed fair value. London’s markets remain at a deep discount to other major global exchanges and there are value opportunities to be had.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Today is a bit of a milestone for me, up 100% TY on Tesla (NSQ:TSLA) - I'm so glad as my UK stock picking has been pitiful! :)
Congrats to any other holders - just the start hopefully!
And don't worry Bears, I know all the bear arguments....
Thanks for the write-up on Science (LON:SAG) .
I totally agree tthat the company is indicating that it has considerable firepower for an acquisition (at least once its renews its current facilities, which are with Lloyds.). Martyn Ratcliffe (Chair and largest shareholder) has emphasised in the past that he views the company as a holding company (not as a consultancy business.). Therefore I think that any future acquisition could be sizeable and in any sector.
Hi group this is a questionbim sure you will be able yo answer ..the question is about the recent hikes in employer NI contributions and profit my point is that these extra payments will be mitigated against the amount of corporation tax they would have had to pay.. or am I wrong in this assumption
You are correct - thats possibly already factored in by everyone that matters though.
Ie its standard practice that if ones cost go up ones tax go down - thats knows and will be factored into the equation ref bottom line.
So its just the same as everyone else who say cost will go up £5 mill - their tax will come down by approx 25% of that - thats a given that may or may not be specifically mentioned.
Either way they are paying 75% of the increased costs minimum probably - it could be worse though if they have losses and dont get tax credit !
For any particular company you need to look at the exact detail of what they are saying ref botttom line totals wehn they update us. If thats £6 mill adverse impact on net profit they have factored in the tax credit - if they say thats £6 mill hit to underling profit (before tax) - then the tax benefit will kick in so that £6 mill less profits (pre tax) means tax will be £1.5 less leaving net profit worse off by £4.5 mill.
as ever the devil is alwasys in the detail of what is exactly being said by wheoever as there is no real standard metric here !
Any ideas why MJ GLEESON (LON:GLE) are so weak today?
Your question rather sums up the issue highlighted in the previous post. I’ve already answered the very same query on Paul’s Substack. I’m going to stick to a rule of avoiding duplication where I can.
MJ GLEESON (LON:GLE)
i suspect the market is starting to mark down companies saying nothing on the basis that the next news will be bad (ers ni increase and inflationary increases in building sector) and in the absence of formal update to the contrary we will give them a kicking ref that uncertainty. To be fair to listed companies i doubt its practical for them to all sit down with advisors and update immediately after then budget.
The specific update from Vistry on Friday wont have helped too when they said the following on friday.
the Group is expecting to see some overall pressure on build costs in FY25.
When shares are in obvious downtrend too i always think everyone is in to give that share a kicking till the bottom is reached - so those with stoplosses may be exiting the building too.
Note Taylor Wimpey updated Thursday and their update was much more positive than Vistry - but their trend is similarly down so it looks like the sector is under pressure - albeit Tw aint down 5% today !
RE:M J GLEESON
" inflationary increases in building sector"
Agreed. Since Covid there has been more difficulty in getting trades. Some now work a 4 day week and increase prices to make up the difference.
Slightly different for new build contracting - but the shortage of labour will feed through.
If Angela Raynor tries to buid the number of houses she hopes to, it will be interesting to see where she gets the labour and what it costs to do so.
My sector pick for the greatest wage inflation.
Just saying the interaction here is important, obviously a lot of conversation has moved over to Paul's subdtack, it would be a shame to lose the quality posters here. Good to talk!
Agreed. I often get alot from the conversations on these daily posts. It would be a shame if it died a death, as the discussions here are are a big reason why I pay to subscribe!
Although I will add, I think the team are doing a fantastic job since Paul left.
Agreed but most of the top table posters like RD, Wolf, Yiannos , the two Mitchells, the two Mark's, Abtam, Boon( just a smattering of the quality) are still knocking about here.
This investment board is the equivalent of the Man City squad even the reserve team is ten times the quality of any other board on the web.
I would put myself in the top 1% of knowledge in the UK but on this board I'm mopping the top boys changing room floor at half time.
See what happens I think both Stock and Paul's new venture will go from strength to strength.
Can’t we get the Donald to draw up a peace treaty and we revert to how things were a week ago!!!
Serco (LON:SRP) I had a look over the weekend. Serco 2024 outcome is H2 weighted which isn't good but this was forecast pre losing the Australian contract. Valuation is in your favour.... if the company can grow. Contracting businesses you don't really want to be anywhere near when they go backwards because already low margins go South quickly.
On growth, the US business is healthy with strongest margins and predominantly defence. The book to bill is 1.3x.... so this division should not disappoint and this helps secure forecasts. This is where the good news stops however and win ratio in the UK/EU has slipped such that book to bill is only 0.7x. It's the largest division by revenue but with structurally lower margins than the US. This is most likely to disappoint. If you believe the co. has just had a bad run and the win ratio reasserts itself then the order book will be healthier at the year end... and then by and large nos are done. The Asia business is in recovery / disarray and the Mid East is interesting but not that meaningful.
The company believe benchmark/industry growth remains 4-6% and without slippage due to overseas problems or poor win rates ....this would be enough on a rating of 10x. In a recession this could even be attractive. The balance sheet debt looks fine within the target range of 1-2x EBITDA and the co have been buying back stock. If the Slater boys are right and the Co is in much better shape then the Australian contract loss is a useful entry point.
On balance Id say it looks ok but don't bet the house until you have some more contracts announcements that secure 2025 and confidence 2024 is in the bag.
V interesting. Thanks, RDHOWARTH.
Glad to see Cavendish doing well today after the retirement of the Manx Missile yesterday! A true British great!
International Personal Finance (LON:IPF) has a quality rating of 95 but the numbers don't look fantasic as below.
How can the quality rank be so high - are there other metrics considered?
International Personal Finance (LON:IPF)
with pe of 6 and your quoted metrics it looks great value - what do you expect with a p/e of 6 ? - note free cashflow looks good too. You can have a great business with craploa return on capital - the trick is to ensure its someone else thats sunk the capital previously and you are getting the reward now of that sunken cost.
Debt is high, as is often the case with good looking uk value stocks.
Morning Graham. In the Cavendish Financial (LON:CAV) piece you say
'And we should now be able to enjoy this clarity for the foreseeable
future: it would be unthinkable for the new government to tinker with
the rules around pensions and inheritance on an ongoing basis.'
I agree with your view that it would be poor for a government to do this but I am not so confident they won't. As the Institute for Fiscal Studies have pointed out, it is extremely likely that the government are going to have to come back with further tax rises (in the absence of economic growth more significant than OBR anticipate). This is because a lot of departments will be unprotected from cuts after 25/26 based on the current settlement. It's unlikely Rachel Reeves will try to hold the line on that one! Plus we will have further Budgets before Labour leaves office - they're not going to announce nothing in those are they - and they have already said they will stick to not raising employee NI, income tax, or VAT which only really leaves employer based taxes (which they have probably milked as much as possible) and other taxes like those on pensions and inheritance. See Paul Johnson's comment this morning for example: https://www.thetimes.com/busin...
None of this means we should change what we're doing immediately but I think we should just be on our guard for further tax rises of some sort.
Absolute cracker of a show tonight and Paul will be on the BASH Stockopedia | Mello Monday with Blue Whale, Rockwood, Smiths News & Paul Scott on the BASH | By carmensfella
Good morning, can you please review YouGov (LON:YOU)?
Hi! YOU was covered here and here. Thanks. G
Good morning All, Can anyone please suggest good websites for Broker/Analysts updates/forecasts. Thank you.
Good morning. Try Research Tree. It's a paid service and not all brokers contribute but still good value in my view.
https://www.research-tree.com/
Thank you very much!
Just a quick heads up, Hargreaves Lansdown have IT issues this morning affecting trades and the display of information. I need to move brokers.
HL are working fine for me.
HL did 'planned maintenance ' on their site over the weekend. Often a time to put the tin hat on! Portfolio Analysis on their website not working for me this morning.
Their website is very tired compared to some of the more modern competitors.
I do feel that they have become complacent, relying on customer loyalty and huge fees.
Just a quick heads up, Hargreaves Lansdown have IT issues this morning affecting trades and the display of information. I need to move brokers.
That’s strange because I topped up MONY (LON:MONY) shortly after the time of your post using the app,
$BTC at $80,000 is the main headline in the FT:
https://x.com/FT/status/185571...
Kr1 (OFEX:KR1) is the best digital asset play imo as the Trump administration seen to be very supportive of Crypto currencies.
Not a small cap. Coinbase Global (NSQ:COIN) might be a better bet. The Levis Strauss of the crypto gold rush. But be warned - I predict it will all end badly! Crypto is like a zero coupon perpetual bond. No use case since 2009... ( I hold since 2017)
Unless of course Musk convinces Trump to switch the dollar for DOGE . Which could happen.. Then again there's a lot of Trump NFT bagholders out there. Down just the 90% which for crypto is pretty good.
Aquis Exchange (LON:AQX) - offer at 120% premium. Further recognition that the UK is cheap - Temple Bar estimating 40% discount to world peers versus 50-year average of 20% discount.
I hold.
well done, mammyoko!
Cavendish Financial (LON:CAV) interims look good to me within the doom and gloom of Aim, they seem upbeat about market opportunities!
"UK small and mid-cap markets are trading at historically high multi-decade discounts to their global peers. With interest rates reducing, a positive agenda for pension fund reforms, a stable political landscape and the uncertainty around AIM now resolved, we see the attraction of investing in the UK increasing and expect the headwinds that have been constraining our markets to abate, narrowing this discount. Furthermore, we do not expect that the modest increases to capital gains tax will impact levels of activity for public or private company transactions"
Yes I'll definitely be covering this one. Thanks NewInvestor1972!
Cavendish Financial (LON:CAV) looks stunning value at under 12p to buy. I already had my maximum stake but broke that rule that I rarely break, and added a few more today.
Market cap is £42 million. Yet Cavendish Financial (LON:CAV) back up their “strongly cash generous claim” with figures to show it. .i.e cash balances up 40% to £17.2 million and now further up to £23.3 million.
Now profitable too, and starting dividend payments. These could well increase fast as they did previously in the good years when I held Cenkos. (Cavendish Financial (LON:CAV) was the merging of Finn Cap and Cenkos).
I can’t fathom the low stock ranks on Stockopedia, nor the muted share price response to these Results whenCavendish Financial (LON:CAV) could well be making substantial profits soon, so maybe there are negatives I’ve missed? Looking forward to reading Graham’s analysis.
Hi Ken, I'm staying GREEN on this... shares up 7%. Needs more real profits to start to get really exciting IMHO but a good start with this bounce in revenues. UK extreme undervaluation can't last forever surely? Best of luck. G
Thanks Graham. I agree about the need for real profits but isn’t there strong evidence now that these could soon be a reality? If that proves to be the case by then the share price will have priced that in.
I’ve just found a Cenkos 2021 update at what turned out to be just after the AIM index peaked at 6500 before falling heavily and it’s still only about half that peak at 3700. Note the increased dividend but the update is also interesting for the warnings in it too.
I nearly always sell on any hints in an update of disappointing news ahead and that iffy update was when I would if still holding, have probably sold Cenkos.
Conversely I look to buy on strong hints or evidence of improved prospects. Good chance that applies to Cavendish Financial (LON:CAV) now. This tactic has worked so well over many years. It minimises our losses and maximises our gains
Here’s that Cenkos 2021 update. (Readers might well be thinking why on earth should I read that now? Mainly to see the obvious hints after a very good update of problems ahead. The update from Cavendish Financial (LON:CAV) today provides the mirror opposite of equally strong hints of better times ahead).
https://www.morningstar.co.uk/...
Hi Ken
The share based payments charge is a red flag here. Any SBP charge that exceed 10% of FCF is too much and Cavendish Financial (LON:CAV) is just a company for the benefit of its employees and directors. Year after year you will be diluted here. Shouldn’t be listed really.
Good balance sheet though.
All the best
Valid points as usual yiannos. I dislike Director greed and Cavendish Financial (LON:CAV) is yet another example. I don’t agree re the year after year of dilution. Cavendish Financial (LON:CAV) could rake in the profits and cash (as Cenkos which I held at the time, did in the good times) that could swamp the Director greed. This sort of thing (and I dislike the window dressing and hiding of negatives too) is priced in with market cap so low.
There’s always a bull and bear case. I’m strongly swayed by the positives but it’s good to see the negatives put too. Time will tell.
I worry about Cavendish Financial (LON:CAV) being a lifestyle company, the old companies certainly have form from what I have read.
But still 2.7% interim divi, say the same or a bit more for final - not bad, it still seems cheap even if they are a bit greedy...
What happened to the Cavendish Financial (LON:CAV) £7m expected cost synergies post-merger? Or did they find £7m and then hand it back to themselves?
As always, trumpeted cost synergies never quite deliver!
Bigger picture, for me the story here is threefold. I wrote a longer Note on this on Substack, here's the TL;DR:
(I hold in the Boon Fund)
Not sure you should be linking to Substack really Boon, may be considered rude.
Especially when it's purely to try and move traffic over there.
Substack and Stockopedia are very different- I don’t think it’s rude. Is mentioning Research Tree rude too by that logic?
Other sites get promoted on here, all the time, so why not another one?
Hi Boon. I have subscribed to your Substack publications. Not sure that "publications" is the correct term as I am just getting to grips with using Substack! Anyway your work on there is very interesting and well worth reading.