Daily Stock Market Report (Mon 20 Jan 2025) - RCH, SDG, JDG, CAPD, CLIG, VANL

Good morning!
11.10am: wrapping up the report there for now, thank you.
Spreadsheet accompanying this report (updated to 10/1/2025)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
ME International (LON:MEGP) | Extension with Morrisons | Contract extension for photo booths and laundry machines. | GN’s view: this was issued through REACH, so it’s not material. |
PRS Reit (LON:PRSR) (£606m) | Q2 Update | 5,437 new homes (LY 5,264). 99% rent collection. LfL rent up 11%. Strategic Review/Sale Process. | |
M P Evans (LON:MPE) (£501m) | Crop & Production update | 1.6m tonnes in 2024 at an avg mill-gate CPO price of $823/tonne | |
Judges Scientific (LON:JDG) (£489m) | TU | 2024 results expected to be in line with expectations. | AMBER (Graham) Remain cautious on this. SDI more interesting right now. |
Cerillion (LON:CER) (£466m) | Major contract | “Supports” existing market guidance. | |
Midwich (LON:MIDW) (£299m) | TU | Adj PBT “slightly below” market expectations. | |
Reach (LON:RCH) (£229m) | TU | Strong Q4. FY results to be ahead of expectations. | GREEN (Graham) |
City of London Investment (LON:CLIG) (£192m) | TU | Net outflows of $564m in HY to Dec 24, AUM of £9.9bn. | AMBER/GREEN (Roland - I hold) |
Capital (LON:CAPD) (£162m) | TU | FY24 revenue of $348m, “marginally below” guidance of $355m-$375m. | AMBER (Roland) Teething problems in N. America have caused revenue to miss exps. |
Bango (LON:BGO) (£83m) | TU | 2024 rev $53m. EBITDA >$15.2m. Exps not mentioned; broker’s EBITDA forecast was $15.8m. | |
Van Elle Holdings (LON:VANL) (£42m) | Contract | 8yr/£30m electricity transmission schemes contract award. | GREEN (Graham) No change to f/cs at Progressive, no change to our stance. |
Sanderson Design (LON:SDG) (£38m) | TU | Profit warning. Adj PBT now expected to be £4.0m-£4.8m vs c.£7.5m previously. | BLACK / AMBER/GREEN (Roland) The shares could be entering value territory. |
Pod Point group (LON:PODP) (£26m) | TU | Adj EBITDA loss in line with guidance at c.£(14m). FY25 results will be below expectations. | |
XLMedia (LON:XLM) (£25m) | Tender offer | £16m will be returned to shareholders at 11.5p per share (24% premium). | |
Checkit (LON:CKT) (£19m) | Contract renewals and wins | No description given of any changes to earnings expectations. | |
Croma Security Solutions (LON:CSSG) (£12m) | TU | “Firmly on track to meet expectations.” H1 rev +8% (£4.6m). Cash £4.1m. |
Graham's Section
Reach (LON:RCH)
Up 19% to 85.9p (£273m) - Trading Update - Graham - GREEN
It’s a very short update from Reach:
Trading in Q4 was strong. As a result, we now expect to deliver results ahead of current market expectations for the full year.
Of course it’s churlish to complain about an “ahead of expectations” update, but perhaps they might have added some colour to this announcement, as the saying goes, and said something about where the outperformance came from?
They do helpfully disclose that they consider market expectations to be for an adj. operating profit of £97.8m.
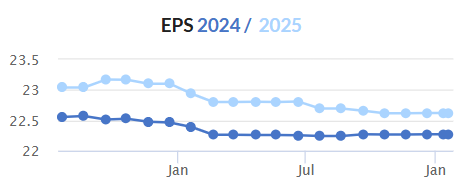
Earnings expectations have been stable for a while, which I think is reassuring as the stock is priced for disaster:
Pension warning: a £5m error was discovered in a pension scheme calculation, resulting in red faces for whoever was in charge of those spreadsheets. RCH will pay this additional £5m in 2025. RCH’s other pension schemes have been reviewed for the same error, and nothing material has been found.
Refinancing: RCH’s banking facilities have been refinanced. It’s a £145m RCF for four years, plus potentially another £72.5m. RCH must keep its leverage multiple below 1.75x to comply with covenants.
Graham’s view
I’ve been positive on this one, e.g. at 97p here. I’ve argued that the bear points - the long-term secular decline of newspapers, and RCH’s large pension liabilities - may already be priced in, leaving an opportunity for a pleasant surprise if/when things don’t work out as badly as feared.
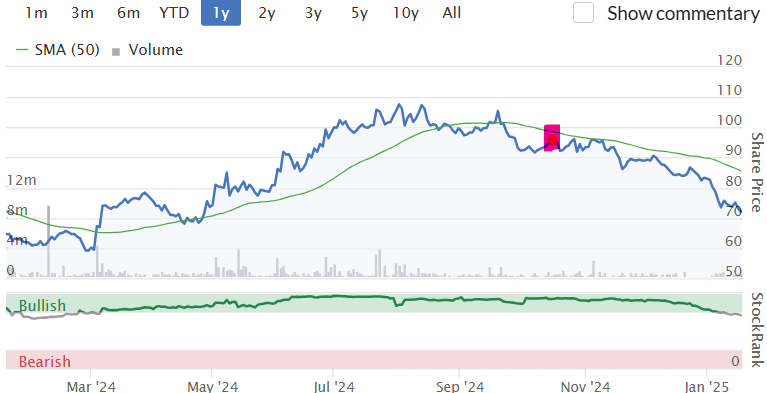
However, the market is slow to agree with me. Even after the bounce in the share price we are seeing this morning, the share price is still lower than it was when I covered it last (marked in pink below):
It will cost over £200m to clear the pension fund debts, and this issue won’t go away until c. 2028.
Revenue is currently falling at about 4-5% p.a.
The arguments here have something in common with the debate over Smiths News (LON:SNWS) (covered last Thursday), where SNWS is the distributor rather than the owner of print publications. Both companies must struggle with the ongoing shift away from print, and in that sense they both face uncertain futures.
But both companies are also being run to maximise current profitability, and are generating very impressive profits relative to their market caps.
Here were RCH’s value metrics as of last night:
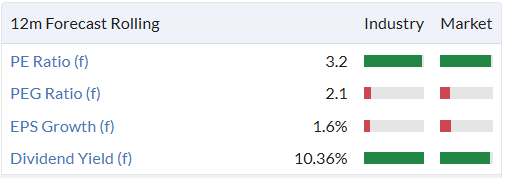
It’s traditionally considered to be a sign of extreme value if a dividend yield exceeds a company’s PE ratio. In the case of RCH, its dividend yield was more than three times the size of its PE ratio! And this for a company where its bankers are relaxed about the situation and have just extended their facility to the company for another four years.
I could be completely wrong about this but I continue to view RCH as a very interesting candidate for investment, though I admit that it’s in the “cigar butt” style.
Judges Scientific (LON:JDG)
Up 2% to £75.38 (£500m) - Graham - AMBER
I’ve been neutral on this one - see my coverage of November’s profit warning here (share price at the time: £88).
Today’s update confirms that 2024 was difficult, affected by Geotek’s lumpy revenue profile and Chinese weakness.
Fortunately there is no further downgrade since November and the full-year result for 2024 will be in line with new expectations for adj. EPS of 276.8p, although this is in the bottom half of the 270p-300p range that we were previously given.
Prior to the profit warning, the EPS estimate was c. 349p.
Review of 2024:
The challenging trading environment resulted in mixed trading across our Group and, as the year developed, the prospect of a 2024 Geotek coring expedition evaporated, resulting in no recognisable revenue in the year. Other headwinds affected our businesses to varying degrees, including a large reduction in orders from China, together with a general weakness in order intake and some customers delaying orders and deliveries.
Order intake: up 2.2%, excluding a large contract at Geotek. With these large contracts having a big effect on the numbers and as they are unlikely to repeat in a predictable way each year, I think it makes sense to exclude them where possible.
Organic revenues: down 5.8% excluding coring.
Outlook: 2025 is off to a good start.
The current year is starting more encouragingly, with Geotek's coring expedition having commenced and a number of the deferred projects from 2024 are now anticipated to contribute to H1 earnings. The Board remains confident in the long-term growth drivers of the business…
Graham’s view
I remain cautious on this for reasons I’ve expressed before. Also see my coverage in September. To summarise, I’m concerned by:
Geotek reducing the quality of JDG (unpredictable revenues and overall quality metrics likely to fall).
The difficulty of finding large acquisition targets that will do better than Geotek, putting a question mark over JDG’s ability to continue to make progress as it did in the past.
Weak orders and revenues across JDG as a whole, particularly from China. Have Chinese customers found Chinese-made substitutes?
The fact that the stock continued to trade a high earnings multiple (over 20x) despite these concerns.
With the share price having been broadly on the decline over the past year, valuation is approaching more reasonable territory:
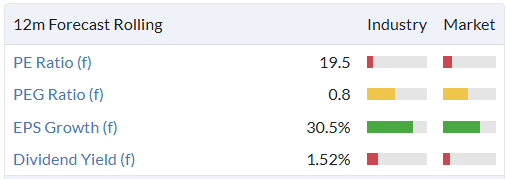
However, I note that smaller peer SDI is only trading at 8x earnings (last covered by Mark here). At that sort of price, SDI could be a more tantalising prospect right now.
Van Elle Holdings (LON:VANL)
Up 9% to 42.5p (£46m) - Eight-year electricity transmission agreement - Graham - GREEN
Another brief update for us to look at today. VANL announces that it has signed:
…an eight-year partnering agreement with Wood Transmission & Distribution Limited ("Wood") to deliver ground investigation, design and construction activities for piling and foundations across several transmission schemes as part of Ofgem's Accelerated Strategic Transmission Investment (ASTI) programme. Subject to performance, the partnership is expected to be worth in excess of £30m to Van Elle over that period.
The CEO notes that the recent acquisition of Stirling-based Albion Drilling will help to provide “a local resource base and specialist skills needed to deliver these important commitments, often in remote and challenging locations”.
Estimates: thanks to Progressive for publishing a note on VANL today. The forecasts they’ve put out are identical to the ones they published last time, including FY April 2025 revenue of £159.1m, and PBT of £6.1m. PBT is forecast to rise to £8.1m next year.
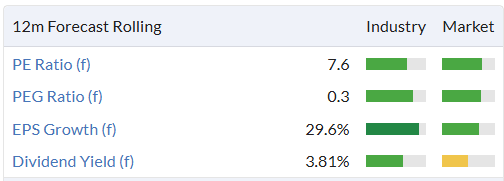
Graham’s view: it would have been more helpful if this RNS acknowledged that there should be no change in earnings expectations as a result of this agreement, or else clarified that the company did think that an upgrade was warranted. Either way I’m going to leave the previous GREEN stance unchanged here, noting a StockRank of over 90 and some cheap valuation metrics:
Roland's Section
Sanderson Design (LON:SDG)
Down 18% to 44p (£32m) - Trading update - Roland - BLACK / AMBER/GREEN
Graham last covered this luxury interior furnishings business in October, when it issued a profit warning. Unfortunately we have another profit warning today. It looks like a big one, too.
As a result of the factors outlined above the Board now expects underlying pre-tax profits for the year ending 31 January 2025 to be in the region of £4.0 million to £4.8 million.
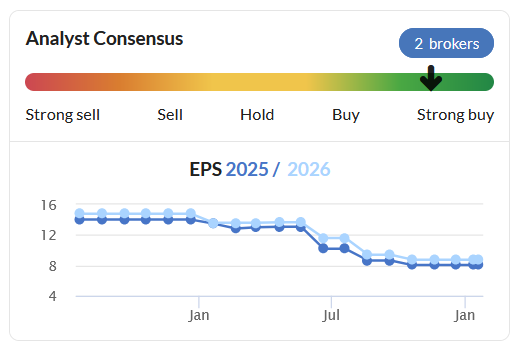
To put this in context, broker Progressive was previously forecasting adjusted pre-tax profit of £7.6m. So today’s warning represents a reduction in around 40% in 2024 profit expectations, on the back of significant cuts to forecasts over the last year:
Let’s take a look to see what has gone wrong.
2024 H2 shortfall: in its October update, Sanderson warned investors that H2 trading would need to improve for the company to hit expectations. Unfortunately, this did not happen.
The company says that full-year sales will be 5% below expectations, at £101m (FY24: £108.6m).
As a quick reminder, H1 sales fell by 11% to £50.5m. This implies that H2 sales are also expected to be £50.5m, versus £51.9m in FY24.
This doesn’t seem like a big fall. Indeed, the numbers suggest H2 revenue was stronger than H1, in terms of the prior year comparison.
However, the company says that an altered sales mix means the hit to margins and profits will be significantly greater than the sales shortfall.
Looking at the detail, performance across the group’s revenue lines appears to have been volatile and soft in some areas:
Brand product sales: retail sales rose by 5% in Dec 2024 and then fell by 13% in the first two weeks of January. Overall brand sales down 9% for the year, at c.£71.7m (FY24: £78.8m). Consumer confidence weakest in the UK, SDG’s largest market
Increased inventory provisions: softer demand, particularly for fabric, is expected to result in an increase in provisions. This reflects accounting charges for stock that may be difficult to sell without discounting. However, the company also says that inventory is expected to unwind in the coming months, so perhaps we’ll have more clarity on this with April’s FY results.
Licensing: good momentum in H2, with FY revenue expected to be £10.1m-£10.9m (FY24: £10.9m).
Manufacturing (3rd party orders): “high margin repeat orders” have declined, while recent new business has been for “smaller print runs” resulting in lower margins due to initial set up costs being spread across lower volumes..
Net cash: expected to be c.£5m at year end (H1 25: £9.6m), reflecting recent capex of £3m and raised inventory levels. Borrowing facilities remain undrawn.
Outlook: Progressive has cut its earnings forecasts by almost 50% today and has also pencilled in a cut to the dividend (this wasn’t mentioned by the company):
FY25 adj eps: 4.6p (previously 8.3p)
FY25 dividend: 1.2p per share (previously 2.4pps)
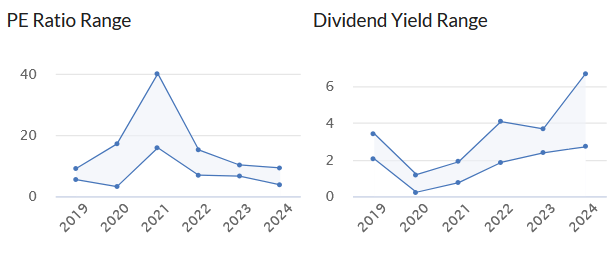
Based on the last-seen share price of 44p, these estimates price Sanderson shares on a P/E of 9.5 with a 2.7% dividend yield.
As Stockopedia’s handy trend charts illustrate, this valuation is not out of keeping with the company’s historical rating, if we exclude the pandemic boom period:
In a situation like this, my main concerns are cash generation and the balance sheet.
Cash generation: net cash has now fallen from £16.3m at the end of January 2024 to just £5m. The fall reported for the last six months is £4.6m, of which £3m is said to have related to one-off expenditure, classed as capex by brokers Progressive.
The company’s comments suggest the remaining £1.6m may have been absorbed into inventories and working capital. An increase of this size relative to half-year inventory of £27.2m does not seem too alarming to me.
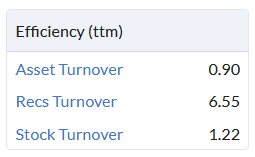
However, it may be worth pointing out that stock turnover is already very slow in this business – Stockopedia shows a figure of 1.2x on the StockReport, in line with my own calculations. This implies Sanderson takes around 10 months, on average, to shift stock.
Balance sheet: Sanderson continues to have net cash with no drawn debt. Lease liabilities also seem manageable at c.£12m, based on the interim accounts.
Checking back to the half-year accounts, Sanderson reported a tangible net asset value of £59.8m and a net asset value of £86m. The stock was already trading at a significant discount to book value ahead of today’s warning:
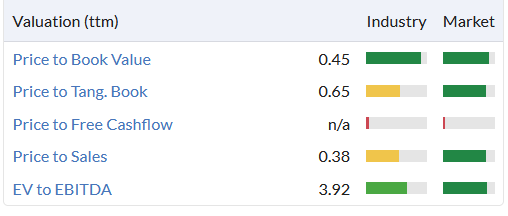
I estimate that the discount to tangible book value is now approaching 50%. That looks potentially cheap to me.
Roland’s view
My feeling is that today’s update represents – broadly – a continuation of H1 performance. H2 revenue appears to be level with H1 and today’s guidance implies H2 adjusted PBT of £1.8m-£2.6m, versus an H1 figure of £2.2m.
The impression I get is that the company may be suffering primarily from a nasty case of reverse operating leverage, with lower volumes and slower stock turnover causing a geared reduction in profits.
I do not know a lot about Sanderson’s products, but I would guess that demand from affluent customers will recover over time.
These shares have now fallen by around 80% from their 2021 highs and are heading towards micro cap territory, with a market cap of just £32m.
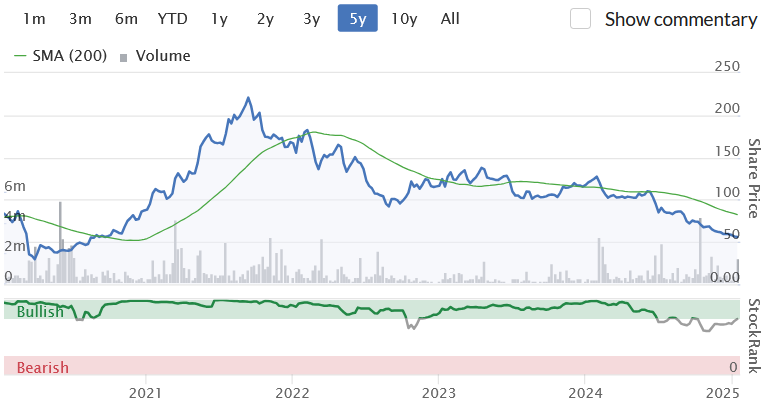
However, I don’t see any fundamental problems with the business and I’m intrigued to see the shares trading at a steep discount to their tangible book value. I share Graham’s October view that this stock is potentially in deep value territory.
While it’s possible that problems will continue to emerge, the shares look affordable to me even reflecting the impact of today’s downgrade. I think it’s worth remembering that this business has some attractive qualities, including high-margin licensing income and some valuable brands.
On balance, I would be inclined to take a closer interest in Sanderson after today. I’m going to maintain our previous view of AMBER/GREEN ahead of April’s results.
Capital (LON:CAPD)
Down 11% to 74p (£145m) - Trading and Operational Update - Roland - AMBER
Today’s full-year update from this gold mining services business includes a revenue warning and has been poorly received by the market (my bold):
As detailed below, FY 2024 revenue was $348.0 million, up 9.3% on FY 2023 ($318.4 million) but marginally below our guidance of $355-375 million.
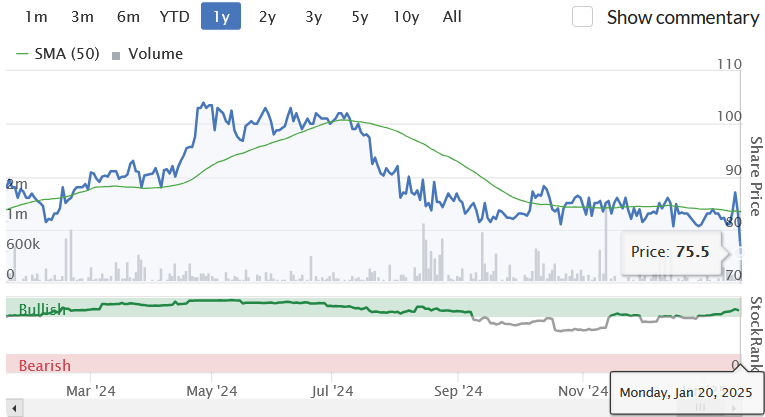
Today’s revenue shortfall seems to have been driven by two specific issues, while broader operating metrics look more positive.
Drilling business: this is Capital’s core business. Revenue rose by 11% to $239.1m last year. The main problem area appears to be the group’s US business – it has been diversifying away from Africa over the last couple of years, perhaps prudently.
Nevada Gold Mines: this major drilling contract has suffered delays in ramping up. As a result, “contract revenues are not yet supporting the cost base”. Not ideal, but Capital is an experienced drilling contractor and says management have now spent “significant time on the ground” to move things forward.
NGM was originally expected to generate $35m/yr for three years from 2025. There’s no statement on actual NGM revenue in today’s update.
Elsewhere, a number of new drilling contracts are announced at mines in Africa, together with an extension of the scope of work for industry leader Barrick at a mine in Pakistan.
MSALABS assaying business: Capital’s other arm is MSALABs, which runs a chain of laboratories used by mining clients to test and analyse their output.
Results have fallen slightly below guidance due to lower utilisation levels in some labs, including work relating to the Nevada Gold Mine project.
FY2024 revenue of $43.6 million was broadly in line with our revised guidance of ~$45 million
Once again, changes have been made to management to improve performance, including the appointment of a new chief operating office for MSALABS.
Investments: one unusual aspect of Capital is that it takes equity stakes in companies as investments, leveraging its industry knowledge. Sometimes the investees are also clients.
This carries some risk, but is also a potential source of value creation. Recent performance appears good, as we might expect in such a strong gold market.
Capital sold its stake in Predictive Discovery to Perseus Mining (a client) for $31.2m in August 2024
Total investment gains (realised and unrealised) in H2 were $12.4m
Investments were valued at $30.3m at the end of 2024 ($47.8m at June 2024), including the impact of the Predictive sale.
Financial & Operating performance: despite the individual disappointments listed above, Capital’s overall performance appears to have been positive last year:
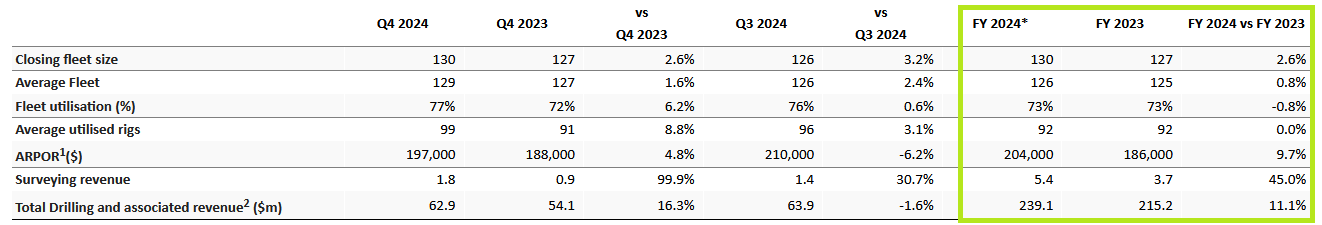
From this we can see that fleet size increased slightly, fleet utilisation was stable and average revenue per operating rig (ARPOR) rose by almost 10% to $204k per month. This doesn’t seem like a bad performance to me.
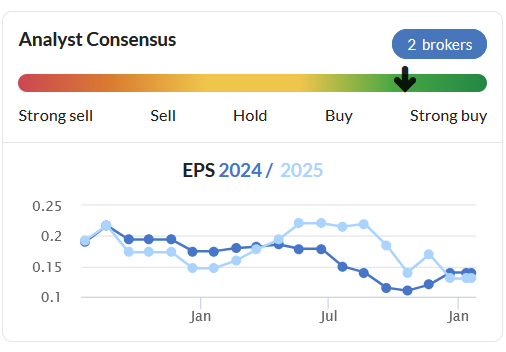
Outlook: There’s no update on profit guidance in today’s statement, but broker Tamesis Partners (available on Research Tree) has left its forecasts unchanged. Unfortunately today’s note does not include explicit earnings forecasts, but seems to imply a figure of $0.134 per share for 2024, similar to the $0.14 consensus shown on the StockReport.
Earnings forecasts for Capital have been relatively volatile over the last 18 months:
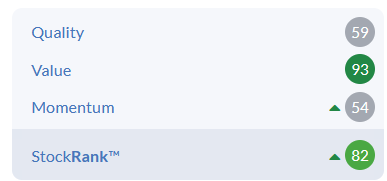
But the StockRanks suggest value and improving momentum:
Roland’s view
Capital appears to be suffering from growing pains in its US business, but this diversification may prove prudent given the increasingly uncertain political environment in some West African countries. I would imagine the incoming US administration is also likely to be supportive of the mining sector.
The shares now trade at a c.25% discount to their last-reported book value and my impression is that net debt should have fallen to a more comfortable level from the H1 figure of $86.4m.
Cash generation may also improve in 2025 as capex falls from $70-80m in 2024 to a new guidance range of $45-55m.
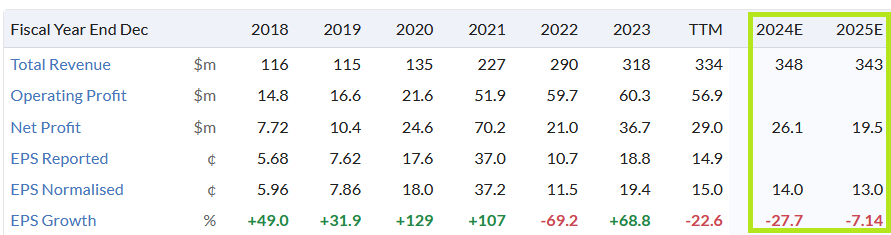
Today’s update did not include any revenue guidance for 2025, but existing consensus forecasts on Stockopedia suggest a further decline in earnings in 2025.
While I think that value could be emerging here, I feel the uncertain outlook means that it’s sensible for me to remain neutral ahead of Capital’s full-year results in March. AMBER.
City of London Investment (LON:CLIG)
Down 9% to 345p (£178m) - Six months to 31 Dec 24 Trading Update - Roland (I hold) - AMBER/GREEN
This niche fund manager focuses on fixed income and equity strategies that involve buying investment trusts at a discount. CLIG reports in USD and the majority of its client base is also in the US.
CLIG shares have performed well over the last year, but have given up some gains today after the company reported (yet another) quarterly net outflow.
Funds under Management (FuM) were $9.9 billion at 31 December 2024, a decrease of 2.9% as compared to $10.2 billion at 30 June 2024.
The company provides a breakdown of flows by strategy:
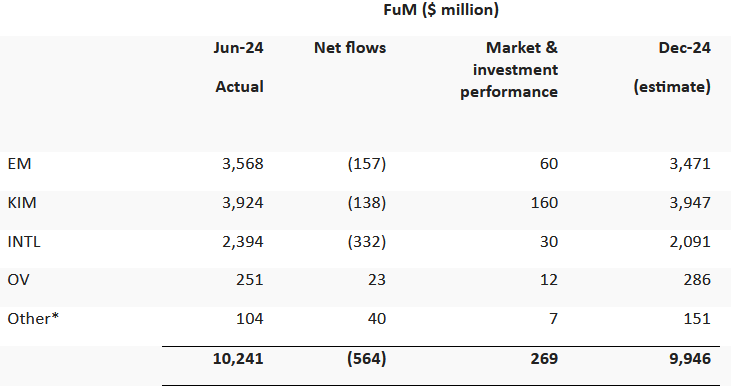
CLIG reported net outflows of £195m in Q1 FY25 and positive market performance of £687m. Comparing these with today’s half-year numbers suggests to me that overall performance weakened during the second quarter of the company’s financial year (y/e 30 June):
Q2 FY25 net flows: £(369m)
Q2 FY25 market & investment performance: £(418m)
Despite this disappointment, the company says its main strategies performed ahead of benchmarks during the six-month period:
Investment performance for the rolling six months ending 31 December 2024 and calendar year 2024 were both ahead of benchmarks for the majority of CLIM & KIM core strategies. Strategy returns were in the first or second quartile vs peers over the same periods.
Roland’s view
CLIG’s continued outflows do not make it unusual among UK fund managers. Only a minority are reporting net inflows.
The attractions of this business for me (as a shareholder) are its 30%+ operating margin, strong cash generation, 9% dividend yield and founder ownership.
My perception is that pressure from 31% shareholder and KIM founder George Karpus has helped to give management a much-needed prod over the last year or so.
Higher interest rates are also a meaningful source of income for a business with c.$30m of net cash and I believe the dividend is likely to remain safe for now.
On the other hand, there’s a risk CLIG could continue to struggle to generate positive flows and may eventually become a classic value trap.
I’d like to go GREEN here, but I think it’s probably more prudent to choose AMBER/GREEN, reflecting the risk of continued stagnation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Van Elle Holdings (LON:VANL) contract win; progress in the energy sector:
"Van Elle Holdings plc (AIM: VANL), the UK's largest ground engineering contractor, announces that it has signed an eight-year partnering agreement with Wood Transmission & Distribution Limited ("Wood") to deliver ground investigation, design and construction activities for piling and foundations across several transmission schemes as part of Ofgem's Accelerated Strategic Transmission Investment (ASTI) programme1. Subject to performance, the partnership is expected to be worth in excess of £30m to Van Elle over that period.
Works have commenced on initial projects in New Cumnock, Argyll and most recently at Beauly-Loch Buidhe where ground investigation works are mobilising throughout January for 240 towers to be constructed in 2026-27."
The shares continue to look cheap on a range of metrics. the presence of some savvy investors on the share register reinforce this view. Rockwood Strategic (LON:RKW) has significantly increased its holding since mid December and Peter Gyllenhammer has very recently taken a 4.2% holding.
I am biased and have a full size position.
Hi Jonno. I don't normally consider coys under £100m MC but this is of interest. The list of major shareholders shows that 4 significant holders sold a chunk on 23rd July a day before results issued. Any significance here ?
City of London Investment (LON:CLIG) the latest fund manager to report outflows of around 5.5% at the half year vs the full year FuM figure of $10.2bn. Between Q1 and Q2 FuM fell from $10.7bn to $9.95bn. Not good.
What worries me is that it has a lot of US based clients - aren't US investors supposed to be more positive right now or am I getting blinded by the Mag 7 performance? Has anyone looked at fund manager performance in the US and have a sense of whether CLIG is an outlier?
Juicy dividend and US dollar strength should help in the meantime. I hold.
Not looked at City of London Investment (LON:CLIG) for a while but they have quite a niche strategy focusing on closed-ended emerging market funds (essentially looking for funds trading on wide discounts). For me it doesn't look the most exciting strategy and returns don't look anything special so not suspired they're seeing outflows. I believe there is now also another division following an acquisition a few years ago. I must admit I stopped looking at it a while ago as struggled to get excited by it, but looks decent enough business.
Hi Tortoise Investor,
I missed your comment on City of London Investment (LON:CLIG) yesterday but you highlight a good point -- the performance of the Mag 7/S&P 500 has made CLIG's products harder to sell. The company has acknowledged this in its commentary.
How long we will have to wait for CLIG's value-led strategy to deliver superior results is the million-dollar question.
Roland
Disclosure: I hold CLIG.
Morning Graham,
Would it be possible for you to comment on Intuitive Investments Group (IIG)?
I know it's a bit left field but has some credible people involved like Nigel Rudd and Rob Naylor.
Interesting announcement this morning.
Not one for the faint-hearted though.
Thanks.
Hi Ian, thanks for the request but it looks like IIG would be more suitable for discussion with Investment Trusts or other funds? G
Ok, thanks.
Totally agree Yiannos, Every time the NASDAQ Hits another ATH the press are all over it, giving it “USA USA USA”
here the FTSE 100 hits an an ATH and MSM just say oh, it’s just due to the weakness in the pound….
if we don’t stop talking ourselves down the cloud over the uk markets will never clear.
Spot on
Couldn't agree with you more, negativity is hugely debilitating, it's difficult to see clear sky's with our mainstream media and inept government acting as prophets of doom. At least companies long dollars in will have an uplift
Reach (LON:RCH) good news (above expectations) although brief today mixed with an oversight. This share looks too cheap.
Market likes the news 23% up…….…
Cerillion (LON:CER)
SIGNS $11.4M CONTRACT WITH NATIONAL TELECOMS OPERATOR
Seems to be a new 5 year contract.
Journeo (LON:JNEO) £1.1m purchase order from Cardiff Council. Small yes, but a good indication of the direction of travel (no pun intended) with the government intent on promoting public transport,, especially bus travel
JNEO is going very well. I expect to see a number of announcements such as this as we move towards the end of the government fiscal year and underspent budgets are used. A rather ridiculous paradigm to run business, but that is the way things in government are.
Sold out of #JNEO last week knowing I might regret it as whilst I see these announcements a lot of it is replacing old deals as they don’t have repetitive deals more lumpy contracts and the overall growth last financial was small. It’s well run though and In a nice space . I made 140% on it so no complaints from me
£JNO
i dont blame anyone for giving companies like Journeo a miss as there is no doubt sales can be lumpy and that always has the "potential" to cause issues - particularly if the exit price is sound. I have only held for under 6 months and was a bit nervous ref last year as they had the large us subway contract ending and not only did they have to hit ye targets but reassure about the future too whilst bedding in acquisitions.
Personally i am happy they managed to deliver numbers that were huge step change up on the past . To me this is a completley different beast now from the company that was entering 2023 with poor track record - when they had alot still to deliver to provde business was viable - they seem to have done the hard job of hitting targets and delvering decent level of profits (numbers prior to 2023 look a bit of a joke type business)
ref the current price - the shareprice is up 25% since i purchased , often if i make a quick decent gain i might just bank that and move on if i think the share price is getting ahead of itself or the discount to fair value has outed - so the easy choice here is to bank quick profit (with other cheap stuff on offer) and move on.
Looking into 2025 we have only had near flat expectations (profits up up £0.2 mill) prior to recent update ref the current year - thats not really brilliant i must admit. In that regard i need to decide if management here are advising that things might be tough - of if they are starting off being very conservative with forecasts. With a lumpy revenue business i want forecasts to be conservative - the last thing i want to do is be worrying about last minute contracts not being signed or not being delivered as that can cause carange.
Lets look at what they said ref new year in the recent update.
On the basis of recent trading and strong order intake, the Group is continuing to perform ahead of management's expectations and FY2025 is viewed with confidence. We expect FY2025 adjusted PBT to be slightly ahead of market expectations** after accounting for the taxation changes in the 2024 Autumn budget.
Up to now i have had no reason to doubt the board and i am pretty happy them having delivered as promised ref last year. They seem to be on the ball and grounded. Looking at this statement - i take positive from the fact they are telling us at the outset that they are slightly ahead of the curve. If one is only slightly ahead looking at 12 month numbers with high degree of uncertainty - i think i would simply be minded to say we are on track only but confident. I take this as quite confidence here that they have even used teh term "ahead" this early . Hey ho we will only find out the reality later in the year.
Note the p/e here is only 11.6 - so we arent exactly paying much of a premium rating here for this share - to be fair with minial growth we shoudlnt expect much more. what i dont really know if how "mission critical" the tech is on the stuff they sell. I would like to think if its most sales have some associated sofware needs then i am presuming inherently their sales should be steicky. So my thesis is that this stuff should almost sell itself if it works and its easier to come back to them for more of the same than go elsewhere. Plus if the stuff is good and does work well it sells itself so others as they can easily see that it does what it says on then tin - they seem to be getting enough diverse contracts that all seems on plan to me. Does anyone have a viewpoint on how high tech most of their current stuff is ? do this still sell high volume of stuff without much added value ?
so to me at present the fact they are quietly confident and the current and future stuff is level above what they delivered previously i think the jump in shareprice is simply reflecting the fact this is a much better (and less risky) company than it was entering 2023 - with some decent real profits delivered now. Hopefully the are placing themselves to perhaps upgare numbers in year - i dont mind most companies starting that was lets hope that is teh case here.
The buy point for me was that Journeo (LON:JNEO) said that they were looking for European certification/ authorisation ( don't know the right word) that would enable them to bid for contracts in Europe. Then they said it had been granted. I'm now waiting for their first contract
I hold
Hi rmillaree
For what its worth I see Journeo (LON:JNEO) as a multi year compounder so wouldn’t confuse next years analyst estimates with long term growth prospects.
When the old management decided to get out (lack of vision in my view) and new team bought in it took them about 3 years to get the business and technology on the right footing again. Then they added scale with some canny acquisitions and now we are seeing a period of stabilisation again. The Nordics needs a bit of time to expand into other European jurisdictions but this offers some great growth opportunities. Current mgmt talk about getting to £100m of revenues c. Double existing levels. This is of course aspirational but having followed this mgmt team for a while now I have confidence in them.
In the meantime we are at a PER of 11 which isn’t expensive but cash adjust that and it’s more like 8 so hardly a rich rating. I note that they have an increasing ARR component to the business as well now so as this grows I’d expect a bit of a multiple re-rate as well.
Personally I’m not expecting fireworks this year although I do anticipate a beat, but this stock tends to move in steps rather than gradual moves up so I’m not particularly minded to sell and re-purchase either as I will probably miss it. I’ve held since 100p so good compounding return and I can see it doubling or more again over the next few years so meets my target criteria.
Baffled (not really!) by the fact there was no TV coverage (headlines) over the weekend about the FTSE100 making a new ATH!
All the best
Good news doesn't sell, yiannos!
Pound has collapsed the last 30 years!
Especially if the aim is to push other political parties………….one actually!
All the best
Hi yiannos1 Please can you accept my request to follow you on X. I was following you before but then had problems with X related to authentication of my account. I'm @apozniak381 and have sent a follow request. Cheers! Andrew
same with me please - im @patstrutt1
Does it show confidence in the UK or just dollar earners benefitting fron collapse of the £? FTSE100
I don't really watch TV news these days but every newspaper I read reported it alongside the IMF saying UK will be fastest growing European economy during 2025.
As we know, it might be more a reflection on dollar strength and FTSE100's exposure to global companies. I'll get more excited when the FTSE250 hits a new ATH!
Cable is stronger than what it was exactly two years ago!
UK economy is not bad as commentators and media and platforms (especially X) TRY to make it. Liquidity though and innovation still behind.
All the best
Good spot. Guess it doesn't fit the narrative about the labour budget totally killing UK business.
Exactly!
Trump ignites the crypto space by launching a meme coin which has rocketed to billions in mkt cap. Melania followed with her own coin. Easy money for them!
BITCOIN all time high at $108,000 too as Trump likely to deregulate crypto. It's going to be a wild Digital ride next few years!
So anyone can release a coin and it's instantly worth a lot of money, I must be missing something. Will probably lose millions but sleep easy at night.
I agree feels like you're missing out big time but I think these just provide an easy vehicle for fraud, tax evasion and organised crime.
There are genuine use cases for btc:
You live in a country where you do not trust the local currency (India Africa China s america)
You want to make a large cash like payment. $10M weighs 100kg in $100 bills. Won't fit in a carrier bag. Thumb drive fits in a pocket. (russia etc)
You want to receive blackmail
You are concerned about your local currency being debased. (Possibly most countries outside Switzerland)
But yes mostly not legal.
All it takes is for a number of govts to clamp down and the value will crater.
Btc has a large negative intrinsic value and a much larger positive money value (what other people think it is worth)
Obviously Blackrock don't agree with you about Btc, or they wouldn't have launched a massive ETF?
do Blackrock simply not dabble in everything that is legal and can make them some fees ?
Probably correct, but remember most money laundering is done through the system. The whole argument about Btc and illegality is a red herring spread by the likes of Mr Dimon etc. I wonder why.
But not with their money.
Can I interest anyone in some rather pretty tulips?
This has been around longer than the tulip thing and not going away anytime soon. Annoyed that so difficult for us UK'ers to join the party. Of course highly speculative - it's knowing when to get out - to tame the greedy demon on your shoulder with the mini-Buffett on the other.
Trump and Elon are going to cash out of this at the end of the next four years in multi billions nice work if you can get it.
It's expensive to buy a condo on Mars.
I'm sorry - looking at the Judges Scientific chart on the right hand side of my screen. This was a big thing on this site top of the tree. Bit like Games Workshop but they bounced the downtrend. Toy soldiers over cutting edge tech.
Bitcoin is a Ponzi scheme.
I don't disagree but like the out of control western debts in the trillions these stories/situations can run for many more years than one would think possible.
I've generally found liquidity drives markets theres £677 billion in the tga waiting to be drawn down, fed is cutting rates even though inflation not beaten, i'm more leaning that 2025 will be another decent year for most major asset classes 2026 possibly not so much we will know the answer in 24 months.
Cheap Card Factory offers ‘significant upside’, says Berenberg
Shares in Card Factory (LON:CARD) remain ‘too cheap’ and offer significant upside given the confident outlook from the greeting card and gift retailer, says Berenberg.
Analyst Adam Tomlinson retained his ‘buy’ recommendation and target price of 154p on the stock, which was trading down 1.5% at 94.3p on Friday morning.
Management has delivered ‘exactly as promised’ in the second half after a profit decline in the first half, including ‘continued robust revenue growth, and with cost/efficiency benefits materialising as planned’, the analyst said of the recent update.
‘It reaffirms our confidence that the group can deliver on its strategic, operational, and financial targets as it progresses towards its full-year 2027 ambitions,’ said Tomlinson.
The shares, however, remain ‘too cheap’ on a price/earnings multiple of 6.4 times and a dividend yield of 5.2% and Tomlinson said there is ‘significant upside from here’.