Daily Stock Market Report (Mon 20th July 2026) - CRW, GKP, CSSG, DPP

The UK gets its fifth Prime Minister in four years today, with Sir Keir Starmer to make his final speech as PM this morning before handing over the reins of power to new Labour leader Andy Burnham.
Burnham will then speak outside No. 10, with an outline of his speech having already been leaked to the media.
The BBC reports that Burnham “is expected to argue that political stability must deliver "tangible" improvements along with "giving people more breathing room" on the cost of living.”
Precise details of his policy plans are scarce, but they include dropping plans for a government-issued digital ID, honouring existing licences for new oil and gas drilling in the North Sea, and greater public control of water and energy companies.
Overnight market movements:
- The FTSE is down 0.3% at 10,550
- S&P 500 is unchanged at 7,460
- Brent crude (September) is up 2.9% at $90.60/bbl
- Gold is down 0.2% at $4,010/oz
- Bitcoin is down 0.7% at $64,100
Roland Head joins me today.
The Agenda is complete. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£76bn | SR88) | European Medicines Agency accepts submission to update Bexsero label for 1-dose Meningitis B booster in 10+ year olds. If approved, a single booster dose could help protect individuals who were previously vaccinated with Bexsero. | ||
Prologis (NYQ:PLD) (£106bn | SR52) (re. SEGRO (LON:SGRO) (£12bn | SR74)) | Prologis has made two further proposals to the board of SEGRO since 24 June. SEGRO’s board has rejected both of these. Prologis is now sharing details of its latest offer: 0.089 new Prologis shares for each SEGRO share, with a partial cash alternative of up to £2.7bn at a fixed price of 1,000p per SEGRO share. Based on Prologis’ closing price of $149.79 on 17 July, this values each SEGRO share at 993p, a 33.8% premium to the undisturbed price on 23 June 2025. | TAKEOVER | |
South32 (LON:S32) (£9.1bn | SR68) | All assets met or exceeded FY26 production guidance except Worsley Alumina, where production was 99% of FY26 guidance. FY27 outlook: all FY27 production guidance is unchanged except for Australia Manganese, where work is underway to handle elevated waste volumes. | ||
Big Yellow (LON:BYG) (£1.73bn | SR48) | Revenue +3%, LFL revenue +2%. Maximum lettable area +5% with closing occupancy -2.8% to 76.6% and LFL occupancy -0.2% to 79.2%. Average rent per sq ft +3%. Outlook: “operating environment may continue to be challenging”. | ||
Advanced Medical Solutions (LON:AMS) (£616m | SR53) | Half Year 2026 Trading Update & Publication of Scheme Document | Expect H1 revenue of c.£115.2m (H1 25: £110.8m) despite some H1 orders shipping later than planned in July. FY26 EBITDA expectations are unchanged. | TAKEOVER (under offer) |
Craneware (LON:CRW) (£416m | SR39) | The company reports an incident of “unauthorised access to a subset of its data environment”. Incident response is underway. Initial investigation suggests “a significant volume of file names were viewed and exfiltrated”. Data involved appears to have included employee, customer and partner records, although “a large element” of this is said to be “non-sensitive or already public regulatory data”. Further updates will be provided as appropriate. | AMBER/RED ↓ (Roland) This cyber attack comes less than a month after Craneware issued a profit warning. While there is no reason to link the two events, the coincidence of multiple problems leaves me feeling uncertain about the near-term outlook. In addition, there seems to be some risk that regulatory changes could prompt changes to the company’s core business model. With the scope and impact of today’s cyber attack still to be confirmed, I’m moving our view down by one notch today to reflect a more uncertain picture overall. | |
Gulf Keystone Petroleum (LON:GKP) (£380m | SR77) | Has temporarily shut-in Shaikan production as a safety precaution “due to the developing regional security environment”. The company’s assets have not been affected and latest gross production from Shaikan was “above 45,000 bopd”. | AMBER/RED = (Roland) [no section below] As a single-asset producer in a volatile region of the world, GKP will always carry some additional risk. Production was shut-in from 28 February until 24 June and has now been suspended again, seemingly following the death of a US soldier in northern Iraq. While there is no doubt of the latent value and cash-generative potential of the large Shaikan field, reliably realising this value has proved difficult throughout much of GKP’s operating history. With violence seeming escalating rather than abating and no meaningful financial forecasts available, I’m going to leave Mark’s previous cautious view unchanged today. The shares don’t seem cheap enough to me to justify taking a neutral view. | |
Caledonia Mining (LON:CMCL) (£244m | SR60) | Gold production +18% to 17,360oz (vs Q1 26), reflecting improving access to higher-grade areas. The average Q2 grade was 2.88g/t, rising to 3.05g/t in July. Outlook: confident in FY26 production guidance of 72k - 76.5koz. | ||
Helical (LON:HLCL) (£231m | SR40) | The allotment and issue of 122,320,093 B shares relating to the £12m capital return will take place today. The B shares will then be redeemed tomorrow for 9.72p per B share. This will effect a return of 9.72p per ordinary share. | ||
Concurrent Technologies (LON:CNC) (£218m | SR45) | Emily Ciechan appointed CFO. She joins from DS Smith and was previously at Guardian Media Group, News UK and Kantar. Ciechan will join on 5 October 2026. | ||
Savannah Resources (LON:SAV) (£162m | SR37) | “Debt process advancing” with various advisers appointed. Has received initial non-binding lending offers. Savannah is negotiating with further offtake partners and is assessing a dual stock market listing on another unnamed market outside the UK. | ||
Jadestone Energy (LON:JSE) (£159m | SR45) | Second well in Malaysia infill drilling campaign has been completed 13% below budget and brought online at 2,800 bopd. Drilling and completion on the third well have recently been concluded, with results to be reported in due course. | ||
Residential Secure Income (LON:RESI) (£103m | SR63) | An aggregate of 66,103,233 newly issued LIVE shares have been allocated to RESI and will be distributed to RESI shareholders at 6pm on 22 July. The exchange ratio of the LIVE ordinary shares is approx. 0.3570 LIVE shares for each RESI share. Cash proceeds of £45m also received from LIVE will be returned to shareholders through a B share issue that’s expected to take place in Q3 2026. | ||
DP Poland (LON:DPP) (£68m | SR24) | Existing CEO steps down after four years. Łukasz Ostrowski is appointed CEO, effective 3rd August 2026. He was Deputy CEO of OTCF S.A. (owner of the 4F brand), one of Poland's leading sports and apparel businesses. | AMBER = (Graham) I’m still hopeful that this might turn into an attractive investment opportunity at some point. There’s one big difference between where the company is now and where it was a year ago: it’s increasingly franchised, rather than running its own corporate-owned stores. Franchisee-owned stores are 38% of the estate. This is a genuine and (probably) positive change in the business model. | |
Helix Exploration (LON:HEX) (£67m | SR8) | The Company's jumbo tube trailer contains approximately 160 Mcf of compressed high-grade helium. The Company's own tube trailer is now starting regular transit to the industrial gases customer pursuant to the short-term spot sales arrangement announced in May with prices reflecting current spot market rates. | ||
Alternative Income REIT (LON:AIRE) (£57m | SR47) | “…a possible offer from AEWU has the potential to deliver a more attractive outcome for AIRE shareholders than the offer currently being proposed by Glenstone REIT plc… both from a price and corporate governance perspective… the Board welcomes AEWU's renewed interest and intends to engage with AEWU to determine whether the AEWU Possible Offer can be developed into a firm offer capable of recommendation.” | TAKEOVER | |
Pulsar (LON:PULS) (£47m | SR30) | Revenue +10% (£33m). ARR £67.2m (Nov 2025: £64.5m). Continues to trade in line with the Board's expectations. | ||
Sareum Holdings (LON:SAR) (£33m | SR23) | Dosing has been completed in the Phase 2-enabling toxicology programme for SDC-1801, a selective oral TYK2/JAK1 inhibitor being developed as a potential treatment for a range of autoimmune diseases, with an initial focus on psoriasis. | ||
Emmerson (LON:EML) (£25m | SR15) | In May 2026, Morocco applied to the Tribunal to have certain jurisdictional objections bifurcated (addressed by the Tribunal in a separate, preliminary phase). The Tribunal has rejected Morocco's application. | ||
Insig Ai (LON:INSG) (£19m | SR0) | Insig AI has committed to invest an immediate €300,000 in ATM Labs B.V., trading as 4Mica, a Belgium based, early-stage AI agent micropayments solutions provider. | ||
Inspiration Healthcare (LON:IHC) (£16m | SR56) | The Board has withdrawn Resolutions 10 and 11 (disapplication of pre-emption rights) from the agenda of the AGM, following feedback received from a significant shareholder in the Company. | ||
Kazera Global (LON:KZG) (£16m | SR12) | Has received the initial advance payment of US$750,000 from South Africa AT Investments under their long-term Mining Cooperation and Production Sharing Agreement. A further advance payment of US$1.75 million is payable by SAI upon the grant of the 2A Project Mining Right. | ||
Medpal AI (LON:MPAL) (£15m | SR0) | Buys Solid State Technologies Ltd, trading as eMARx, a UK provider of electronic medication administration record software to care homes and pharmacies. Initial consideration c. £0.38m: £133,066 in cash and 7,272,834 new shares. Total consideration c. £0.47m. | ||
Croma Security Solutions (LON:CSSG) (£9m | SR59) | Expects to report revenues of c. £11m, slightly ahead of market expectations and up 15%. EBITDA also marginally ahead of expectations at around £1m, reflecting the planned increased investment in the business (FY 2025: £1.1 million). Broker Zeus cuts FY26E adj EPS estimate to 3.5p (prev. 4.0p) | BLACK (AMBER =) (Roland) This small cap appears to be cash rich but not very profitable or fast growing. Today’s updated broker note indicates a cut to full-year earnings forecasts, so I’m viewing this as a profit warning despite revenue and EBITDA being ahead of previous expectations. There are currently no forecasts in the market for the current (FY27) financial year, it’s impossible to know what’s expected to happen next. I’m retaining my neutral view to reflect Croma’s strong balance sheet, owner-management and some apparent progress with its locksmith roll-up strategy. From what I can see, the share price is covered by tangible net assets, so there could be some value here. High cash levels also provide optionality for the business, assuming suitable acquisition opportunities can be found. However, given Croma’s small size and lack of coverage, I think this is a situation where private investors have to do their own research and modelling to form a conviction view either way. |
Graham's Section
DP Poland (LON:DPP)
Down 1% at 7.2p (£68m) - CEO Succession - Graham - AMBER =
We didn’t cover DPP’s recent trading update, so I’ll do that now along with news of a CEO change.
DPP is a business that has never made much (anything?) by way of profits, but we continue to monitor it, just in case:
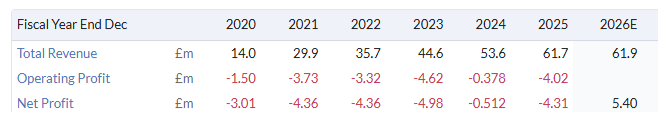
Today’s news is simple enough: the incumbent CEO “has decided to step down”. He is thanked and his achievements are lauded. It’s impossible to tell for sure, but my sense is that he has jumped rather than being pushed.
Indeed, his successor has already been chosen: a Polish national with experience at the polish sportswear business OTCF, where he has been deputy CEO. Before that, he spent 7 years at IKEA. Sounds like a reasonable appointment.
Let’s scroll back to the H1 and Q2 update, issued last week, to see what the new CEO is walking into.
Key points for Poland (there are also a few stores in Croatia):
Like-for-like system sales up 3.7% in Q2, and up 6.2% in H1 as a whole.
Like-for-like delivery sales growing well, while non-delivery sales shrank.
Due to network expansion, total system sales were up 16.4% in H1. It seems that this growth calculation is based on the conversion of “Pizzera 105” stores over to the Domino’s brand. Pizzeria 105 was bought last September.
Some numbers to demonstrate the impact of this large acquisition: at the end of H1, the DPP network had 208 stores, comprising 139 Domino’s stores and 69 “Pizzeria 105” stores.
At the H1 update last year, they had 207 stores, but this was made up of 117 Domino’s stores and 90 “Pizzeria 105” stores.
CEO comment (the outgoing CEO):
Whilst conversion activity has progressed more cautiously than anticipated, the Group is applying insights gained from completed conversions to refine the process and is now focused on accelerating the pace of future conversions.
The operational benefits of our commissary consolidation, completed in Q1 2026, are beginning to flow through the business, supporting improved cost efficiency, labour productivity and long-term scalability across the network."
On the topic of H2 like-for-likes being lower than H1 like-for-likes:
Whilst Group system sales and orders continued to deliver double-digit growth during H1 2026, like-for-like trading moderated in the second quarter against a strong comparative period, following a significant marketing and promotional campaign in Q2 2025.
The Group recognises the softer like-for-like order performance in Q2 and remains focused on initiatives to improve order growth while continuing to drive profitable system sales growth
Outlook:
The Board is pleased with H1 2026 performance and remains confident in the full-year outlook. The Group anticipates continued double-digit system sales growth in H2 2026, underpinned by ongoing network expansion and the continuing Pizzeria 105 conversion programme.
Graham’s view
I’m still hopeful that this might turn into an attractive investment opportunity at some point.
There’s one big difference between where the company is now and where it was a year ago, that I haven’t mentioned yet: it’s increasingly franchised, rather than running its own corporate-owned stores.
Last year, only 15% of its 117 Domino’s stores in Poland and Croatia were franchised.
This year, franchisee-owned stores are 38% of the estate.
They are “focused on continued franchise transition to a franchise-led, capital-light operating model, which is expected to deliver system sales growth, margin expansion and improved long-term returns for shareholders”.
This is a genuine and (probably) positive change in the business model.
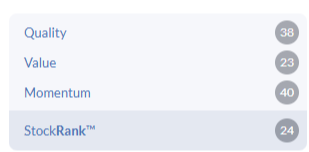
So while the stock doesn’t offer much in terms of quality or value yet, or indeed momentum, I think it’s worth continuing to check for progress!
I was neutral on it at this year’s full-year results, and will leave us neutral on it today.
Roland's Section
Craneware (LON:CRW)
Down 9% at 1,110p (£381m) - Notice of Cyber Security Incident - Roland - AMBER/RED ↓
It’s unfortunate for Craneware that this cyber attack comes less than a month after the company issued a profit warning in what could be an early sign of regulatory headwinds.
While there is unlikely to be any connection between the two events, my experience is that it often pays to be cautious when companies are experiencing multiple problems at the same time. That’s especially true in a case like this, where both problems could end up being more serious and longer-lasting than they first appear.
Craneware cyber attack - key points
Today’s announcement has left me with a mixed view on the likely severity of this cyber attack. On the one hand, everything seems to have been contained and business operations are continuing without issue:
Craneware has suffered “unauthorised access to a subset of its data environment”.
The company’s incident response plan has been activated and an investigation is underway.
The “incident has been contained and there has been no disruption to customer services or to the Company’s operations”.
Retained cyber security service providers have been supplemented by “external cyber security and forensic specialists”. These external specialists have confirmed there are “no residual indicators of compromise” in the company’s systems.
The relevant authorities have been notified in the UK and US.
Data breach: “significant volume” stolen
On the other hand, the company’s description of the extent of the data breach sounds less reassuring to me:
Investigations so far have established that a significant volume of file names were viewed and exfiltrated. The current assessment is that a large element of the data involved is non-sensitive or already public regulatory data. A percentage of Craneware employee data as well as a subset of customer and partner records have been accessed and exfiltrated.
The way I read this, Craneware is saying that a lot of data was stolen, but most of it wasn’t very important or confidential.
This claim seems to be slightly at odds with the idea that the attackers have gained access to employee, customer and partner data.
I wonder if the people and organisations whose data has been stolen share Craneware’s view that it’s largely “non-sensitive or already public”.
Impact assessment is still underway
In any case, it sounds like it’s too soon for a definitive assessment of the data that’s been lost and the commercial or legal consequences:
The Company is continuing to assess the precise nature and scope of all the data involved and is working with its advisers to identify affected parties and prepare appropriate notifications, including any required further notifications to relevant authorities, in each case in accordance with applicable regulatory obligations.
Outlook
Further updates are promised “as appropriate”.
We are told there has been no impact on operations, so I assume existing guidance for FY26 and FY27 remains unchanged at this time, barring perhaps some additional costs relating to the incident.
Roland’s view
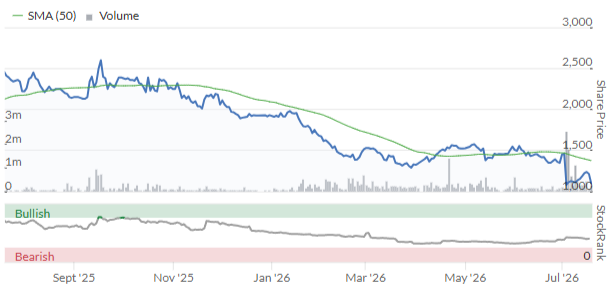
The market reaction to today’s news has been relatively muted, with the shares down by 9% at the time of writing. One reason for this may be that Craneware has already suffered a fairly dramatic de-rating over the last year – the stock has fallen by 50% since July 2025:
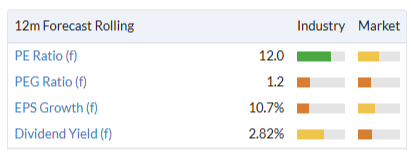
This decline has left the shares trading at an unusually low valuation for this business:
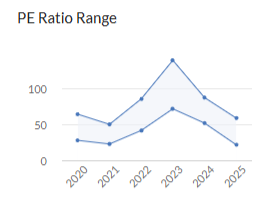
For some context, the P/E has generally been above 20x in recent years:
This low rating appears to be at least partly due to concerns about the future of the US 340b programme, which allows hospitals and clinics to make discounted drug purchases. As Graham mentioned recently, Craneware’s core product appears to have been built around the US 340b programme, but there now seems some uncertainty about the future prospects for 340b.
If Craneware can adapt to changing conditions and maintain the relevance of its product offering, then I think this low rating might be an opportunity.
Recent CEO share buying could also be a positive indicator – Craneware CEO Keith Neilson spent £100k on shares at 1,102p following the recent profit warning, adding to his existing holding of 3.2m shares (with a 9.4% interest, he is Craneware’s largest shareholder).
However, I’m less positive about this purchase than I’d normally be for a CEO buy. After all, the amount Neilson spent was around only one-tenth of his annual dividend income of c.£1m from Craneware.
The combination of a profit warning, a business model that may need to change and a cyber attack means my confidence in the outlook for this business is lower than I’d like.
To reflect this view I’m going to move our view down one notch to AMBER/RED today.
Croma Security Solutions (LON:CSSG)
Up 6.5% at 73p (£10.0m) - FY26 Trading Statement - Roland - BLACK (AMBER =)
Checking back in the archives, the last time we looked at this UK locksmith and security solutions business was in November 2025. Croma’s strategy is to expand through bolt-on acquisitions to act as a consolidator in these sectors.
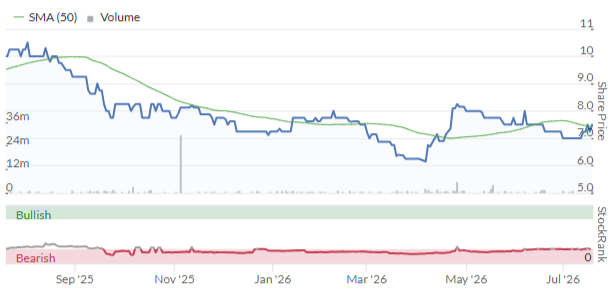
At the time of my last review I noted that without significant earnings upgrades, FY26 profits were likely to be substantially below FY25 levels. The shares have trended lower since then:
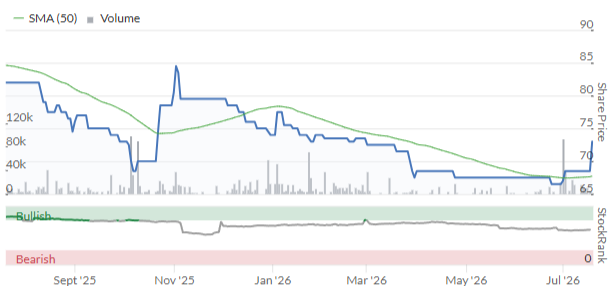
Today we have a full-year trading update for FY26 and updated broker note, so it seems a good time for a fresh look.
FY26 trading update (y/e 30 June 26)
Revenue to be +15% at c.£11.0m (FY25: £9.6m)
EBITDA to be down by approximately 15% at c.£1m (FY25: £1.17m)
Net cash of £4.9m, up from £4.4m at 31 Dec 25
Profits are certainly going to be lower than in FY25, but both revenue and EBITDA are said to be slightly ahead of expectations, according to the company.
The net cash balance is also impressive – net cash now appears to cover half of Croma’s market cap.
Checking the half-year accounts and adding today’s additional cash suggests to me that Croma’s tangible net asset value could be around £10.8m or 79p per share. On that basis, it looks like the current share price is slightly below the group’s tangible net asset value – potentially a value indicator.
Unfortunately, one reason for this may be Croma’s poor profitability:
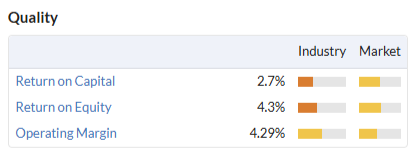
Without achieving higher returns on capital and equity, this business seems unlikely to generate sustainable value for its shareholders or justify a higher rating.
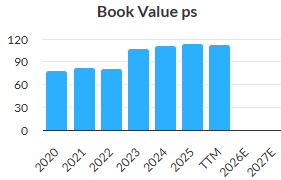
I note that book value per share has been pretty flat since the bump generated by the Vigilant disposal in 2023:
Updated forecasts: is this actually a profit warning?
There’s also some bad news today, although this is certainly not obvious from reading the RNS.
With thanks to broker Zeus and Research Tree, we have access to updated FY26 estimates.
These suggest to me that today’s update should actually be seen as a profit warning.
While Zeus has increased its FY26 revenue and EBITDA estimates in line with today’s trading update, the broker has cut estimates for FY26 pre-tax profit and earnings per share:
FY26E revenue: £11.0m (+3.5% vs £10.6m previously)
FY26E adj EBITDA: £1.0m (+8.7% vs £0.9m previously)
FY26E adj pre-tax profit: £0.6m (-13% vs £0.7m previously)
FY26E adj EPS: 3.5p (-12% vs 4.0p previously)
Checking the details of Zeus’s model, it seems that there are two reasons for this divergence between EBITDA and real profits:
Rising costs: Croma’s overhead costs are expected to have risen by 22% to £4.4m this year as the company invests in new operational capacity.
Normalised tax charge: it seems that the company benefited from an abnormally low tax charge last year. Checking Croma’s FY25 accounts, this is flagged as being linked to “adjustments for prior years”. I don’t know the details of this, but Zeus forecasts show the tax rate rising to 25% for FY26, from just 4.3% in FY25.
Higher costs put a dent in pre-tax profit and the impact of this is compounded by the effect of a higher tax rate on earnings per share.
The end result is that Croma’s adjusted earnings per share are expected to fall by 44% to 3.5p per share for FY26, according to Zeus.
Trading commentary
While today’s profit warning is disappointing, today’s commentary does suggest to me that Croma is continuing to make some progress:
Two acquisitions completed in H2 - presumably these will contribute to earnings in FY27
During H2, Croma completed the acquisition of TLS Security Systems, an established locksmith and security business based in Taunton, Somerset, in January 2026, followed by the acquisition of Southern Security Services Limited, an established electronic security and specialist locksmith business based in Poole, Dorset, in March 2026. Both businesses have been successfully integrated and are trading in line with management's expectations.
Outlook
There’s no financial guidance or trading commentary for FY27 today, but Croma does make encouraging noises about the prospects for further acquisitions:
The Company has a healthy pipeline of acquisition opportunities and is actively progressing a number of discussions, providing a strong platform for further acquisitive growth.
Roland’s view
Zeus has opted not to provide FY27 forecasts today, so there are no forecasts in the market yet for the current year. I guess these will be provided with the FY26 results, but last year’s these weren’t published until November – so visibility for investors is limited.
To some extent this goes with the territory when investing in micro-cap stocks. Croma’s £10m market cap means it’s never going to justify much coverage. CEO Roberto Fiorentino also controls almost 30% of the stock, so (probably) has effective control and is presumably focused on his own strategy for building longer-term value.
None of this is necessarily bad news. Without studying this business in detail, my general feeling is that progress is being made with the group’s targeted roll-up strategy, but more slowly than expected.
In terms of valuation, the situation seems interesting.
Based on today’s forecast for FY26 EPS of 3.5p, Croma shares trade on a lofty P/E of 21.
However, stripping out £4.9m of net cash from the £10m market cap brings this P/E down to around 10x. There’s also expected to be a 2.5p per share dividend, giving a useful 3% yield.
As I mentioned earlier, I also estimate a tangible net asset value of c.79p, above the current share price.
Do Croma shares offer value at current levels? Based on the information available to me from today’s updates, I think the answer is maybe.
Taking a positive or negative view would require a greater understanding of the acquisition opportunities available to Croma and some modelling of the potential economics of an enlarged business.
If this business can become more profitable and/or faster-growing, then the shares could be cheap. On the other hand, it’s possible that this situation could morph into a value trap, with management unable to leverage the strong balance sheet into genuine growth.
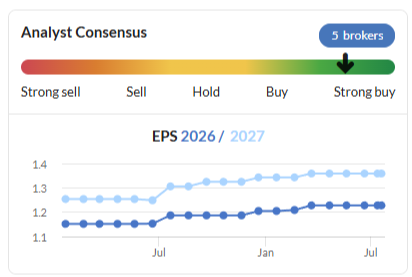
I think the StockRanks’ Contrarian styling is very fair here:
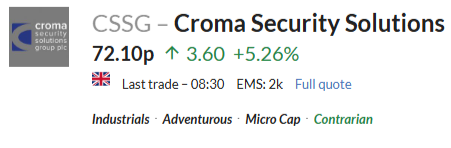
In my opinion, this is a good example of a small company where private investors might be able to gain an edge through careful research. I can’t do that today, so I’m going to leave my previous neutral view unchanged.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
John Healey as chancellor then. Bit of a surprise.
I asked social media:
This is a very fresh appointment — some questioning his economic experience (he has a background in trade unions and local government/housing rather than high finance), while others note his Treasury experience earlier in his career.
So has kept under the radar - local government bureaucrat - safe - as opposed to the other suggestions, we dodged a bullet.
Plus500- the Board stated that 2026 trading was in line with expectations. I don’t see this a a profit warning but after the CmC results people might have expected more…..
Plus500 (LON:PLUS) not helped by the massive directors's selling, this year.
Starting to feel like a buying opportunity tbh (I don’t hold)
Thank you for taking the time to look at CSSG Roland, much appreciated. It's why I pay my subscription, to have points made I've missed. We'll stick with Roberto Forentino until November and see if his optimism was justified.
Croma Security Solutions (LON:CSSG) Am I the only one to enjoy reading of a locksmith and security solutions business making bolt-on acquisitions. Thanks Roland.
Graham, do you have any views on the precipitate drop in Plus500? There was no read across from CmC in the recent results; perhaps they need to be more forthcoming on what the new businesses might hold for shareholders!
Plus500 (LON:PLUS) Graham covered the profit warning last month.
Hi Rhodie
Yes that is one of the big points made in the vid. I watch with interest to try to see what, if any, catalysts might emerge to stimulate the UK stocks.
Regards
Howard
Roland you covered Croma Security Solutions on Nov 3rd 25 and gave it Amber. We hold and as the shares have dropped from 82p to 68.50 we bought a few more last week. Net cash is up which must now be almost 50% of the it's market cap. As it's on today's list I hope you have time to comment on today's TU. Planet X late of this parish was a strong advocate and I followed him into this small company years ago.
Morning Jasvfs,
Thanks for the suggestion. Croma Security Solutions (LON:CSSG) is next on my list!
Roland
it may be worthwhile to do a recent article on which companies are likely takeover targets
Haven't had one for couple of years now
I've had a few this year. Advanced Medical Solutions (LON:AMS) and Ramsdens Holdings (LON:RFX) are the latest ones.
I bought a few REITs over the last couple of years because 1. they're nice REITs and 2. they seem like obvious potential takeover situations due to trading beneath NAV despite being high quality, and the weakness of the pound / huge strength of the dollar makes it a double pleasant opportunity for US buyers. From my portfolio, Care REIT and Warehouse REIT already disappeared to takeovers, but I still hold two more that I am happy to hold and would not surprise me whatsoever if a takeover bid came in
- Tritax Big Box REIT (LON:BBOX)
- Supermarket Income REIT (LON:SUPR)
I did top slice them just recently so currently small positions for me, because the discount to NAV is not as attractive as it was and I feel there are regular chances every year to top these positions up caused by brief issues in the bond markets.
Hi
This vid crossed my YT yesterday. It examines why the valuations of the UK stock market are so cheap in contrast to the US and other markets (even emerging markets).
It picks out why so many UK listed companies have recently been the subjects of twenty eight takeover bids (worth some £60 billion). In contrast to only seven new listings this year (raising £600 million approx). A stark 27 to 1 ratio.
The vid digs into some history of why UK valuations are low, then assesses if the UK seems to be a value trap or an opportunity.
It is 33 mins. Might interest some. Neil Woodford is interviewed.
Regards
Howard
This is actually a Neil Woodford PR piece. Very slow and repetitive and seems to miss that a lot of current m&a are trade buyers. For reasons unknown or un said international fund and pension buyers are ignoring the UK despite CAPE and despite others seeing the value. It is a failure of UK based banks, not the Government?
Woodford has a good point on one aspect which has definitely contributed to the stagnation of the UK equity market, compared, to say, the US. This is that around 20 years ago, the government introduced a requirement for final salary pension schemes to move to a position of matched liabilities. It was a nonsense that in simple terms, made final salary schemes have sufficient assets to be able to pay claims if every member died on the same day, obviously, something that would never happen. At that time, these pension funds held over 70% of the UK equity market. To achieve a matched liability position, they had to ditch equities and buy gilts (quelle surprise that the government, who benefits from selling debt, introduced this requirement). Its taken them 20 years to get to this position but the upshot is that final salary schemes now only hold 2% of the UK equity market. That’s been such a drag on rising share prices, as pension schemes have consistently been reducing their UK equity weighting by dripping stock into the market, holding prices down for decades. With barely nothing left to sell now, the UK equity market should do much better going forward, assuming positive drivers exist. Now, I’m only paraphrasing what Woodford has said, it it could be incorrect, but if it is true, it is a very interesting thesis.
I hear what you are saying BUT in 20 years the rest of the worlds professionals, apart from Canada pensions have not spotted the bargains??
Thanks, this is important. The pension funds also lost a huge amount money in the last few years when the price of gilts fell by matching duration of their liabilities.
The main reason that the Liz Truss / Kwasi Kwateng budget nearly sank UK. financial markets.
Surely it hardly matters as the underlying cause remains - the dying out of that type of pension scheme in general and the overall vast superiority of the US market in terms of liquidity, EPS growth etc
Neil Woodford is self interested in the things he says and does not actually care what is better for UK pensioners. He wants policies & opinion to form around things that will make him more money. Pretty transparent and uninteresting IMO.
This could be the reason so many pension schemes have been sold to the likes of Legal & General (LON:LGEN) and Chesnara (LON:CSN) - Gets rid of the liability and of course makes an easier target for takeover
Snowdrop - Retaining Stamp Duty is entirely within the control of the Govt. Stubbornly persisting with it when almost no one else does (and particularly when it raises only limited revenue in the context of the wider govt pot) is just negligent. It is to our advantage to have a thriving and deep equity capital market.
The point that Rhodie makes is correct. The obsession with Defined Benefit schemes to liability match has been a massive drag. As these schemes have almost all now closed and are in run off things should improve. However, our Defined Contribution schemes also shun UK equities to an extent which is unique in the developed world. Even Australian schemes which were pioneers in terms of global investing and alternatives still retain a much higher percentage of their assets in Australian markets. Given the signifiant tax breaks that pension money enjoys on the way in I don’t think it’s unreasonable to demand a higher domestic allocation. Ultimately a thriving domestic market and economy is good for pensioners assuming they want to remain citizens of said society. Instead we seem to have a self-hating cadre of portfolio managers who think that, in simplified terms, the best protection for their clients is to send UK tax shielded funds to lower US cost of capital. And when done collectively that is disastrous for our future economy. Our local cost of funding is higher. And eventually it’s not a question of local firms, especially cutting edge, not listing in London. It’s them being set up in the US from the get go. For UK society as a whole this is sub-optimal as it will ultimately make everyone poorer. But I don’t think it’s something our politicians or the ever short termist City understands