Daily Stock Market Report (Mon 20th October 2025) - BME, CLIG, STB, HSP, GFRD, PLUS, DPP, VARE

Good morning! Judging by Mark's Week Ahead article on Friday, this could be a pretty interesting week. I hope you're all doing well!
All done for today, thank you!
Spreadsheet accompanying this report: link (last updated to: 23rd September).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£195bn) | Positive CHMP opinion for subcutaneous Saphnelo & US FDA Approves Tezspire in CRSwNP | Saphnelo: recommended for approval in EU for systematic lupus erythematosus, which affects 3.4m globally. Tezspire: approval broadens indication to a second disease, affecting up to 320m globally. | |
Plus500 (LON:PLUS) (£2.23bn) | 9M revenue +2%, customer income +8% to $536.7m, EBITDA +1% to $267.8m. FY26 revenue and EBITDA guidance unch. Market expectations: revenue and EBITDA of $749.5m and $343.0m | GREEN (Graham) [no section below] With Plus500 reiterating guidance, I have no reason to change my positive stance on this incredible share - the best-performing UK share since it IPO'd in 2013. The US futures business (us.plus500.com) is a key growth driver currently and segregated customer funds in this business have now crossed over the $1 billion mark. For the group as a whole, revenue growth for the first nine months of the year is now growing as quickly as I might have hoped, given the tariff tantrum that got markets moving in April. Revenue from spreads, commissions, overnight charges, etc. (collectively referred to as "customer income") rose 8% but performance was held back by "customer trading performance", i.e. customers made smaller losses this year than last year! I've criticised Plus500 for a long time for not hedging customer trades - it is happy to profit when they trade badly, and to take the risk of losses if they trade well. For the first nine months of 2025, customer trading activity lost $10.4m directly to Plus500, versus $46.6m in the same period last year. Regardless of my criticisms, there is no question that the company has been exceptionally profitable, year-in year-out. And it is now trying to be more selective when it comes to customer acquisition: new customers were down slightly compared to last year, but the average deposit per active customer doubled. This reflects the US futures business and the overarching strategy to find higher-value customers. With a very healthy balance sheet ($815m cash) and an ongoing focus on shareholder returns through dividends and buybacks, I see little option but to stay positive on this. The rolling P/E is 11x, without adjusting for the cash balance. | |
B&M European Value Retail SA (LON:BME) (£2.18bn) | PW: Found £7m of costs not recognised. H1 adj EBITDA now £191m (prev. £198m). FY26 adj EBITDA exp £470-520m (prev £510-560m). CFO leaves. | BLACK (RED) (Roland) | |
Sirius Real Estate (LON:SRE) (£1.49bn) | Near Munich, 27,180sqm lettable area. €3.4m rent roll, 7.8% yield. 94% occupied w/ 7.8yr WAULT. | ||
GlobalData (LON:DATA) (£924m) | PW: FY25 revenue to be in line with exps, but FY25 adj EBITDA margin now to be lower than expected. | ||
Galliford Try Holdings (LON:GFRD) (£525m) | Appointed to £3bn affordable homes 5yr framework by Hyde Group. Confirmed on all seven lots, targeting 1,500 homes/yr. | AMBER/GREEN (Roland) [no section below] This was a long-term holding for my SIF folio that I seem to have sold far too soon. While my reservations about this sector are unchanged (see here), Galliford appears to be continuing to win new work to support further growth. There’s no commentary on expectations today, suggesting to me that this new contract win may already be reflected in market forecasts. Personally, I wouldn’t be brave enough to buy into this business on a forward P/E of 15. But Galliford does seem in good health, with last year’s results showing a decent net cash position and improving margins. If the business continues to hit forecasts, I accept the shares could still be reasonably valued at current levels. The StockRanks are certainly positive, with a score of 97 and Super Stock styling. I don’t see any reason to change my previous AMBER/GREEN view today. | |
Avacta (LON:AVCT) (£284m) | Demonstrated favourable safety and tolerability, with lower toxicity compared to conventional therapy and “exciting efficacy”. | ||
Hargreaves Services (LON:HSP) (£218m) | Sale of land generating rent from wind farms/access agreements. £8.8m cash upfront plus £3.8m contingent amount due by Sept 2029. | AMBER/GREEN (Roland) [no section below] I’m a long-term fan of this business. Longserving CEO and 8% shareholder Gordon Banham has a strong track record of delivering on his promises over time, in my view. The shares have certainly been a profitable investment for patient investors who’ve taken the opportunity to buy below at a discount to book value at various times over the last decade – most recently in 2022/23. Today’s disposal is at a premium to balance sheet value of £7.4m, presumably based on historic cost. However, the sale price is in line with a more recent independent valuation of £12.6m, if we’re willing to include the expected £3.8m of deferred consideration. This will be contingent on future wind yields – these can be uncertain, as investors in TRIG (disc: I hold) and UKW have found over the last two years. Commentary from other renewable operators has suggested the market for asset sales has become more difficult over the last year, so I’m encouraged by this deal, which seems to suggest the company’s target of £27m of renewable asset disposals is realistic. Hargreaves has been gradually monetising its extensive land assets for some years, while developing its continuing businesses in Services (bulk earthworks for infrastructure projects) and raw material trading. Shareholders have benefited through some generous dividends. The current valuation looks reasonable to me, especially given forecast net cash of £32.7m at the year end. This should comfortably support the near-6% dividend yield. Although the stock now trades at a premium to book value, I’m happy to maintain a positive view today. | |
Seraphim Space Investment Trust (LON:SSIT) (£192m) | Portfolio valuation up by £58.3m (28.9%) to £259.8m. NAV per share +23.2%. 66% of the portfolio has robust cash runway. | ||
City of London Investment (LON:CLIG) (£188m) | Funds under Management +4% to $11.2 billion. Net outflows $419m. | AMBER/GREEN (Roland - I hold) As a long-term shareholder I am happy to see higher FUM, as it should generate additional fee income to improve cover for the 9% dividend yield. I’m also encouraged by the strong investment performance against (most) benchmarks, as it suggests CLIG’s teams are finding attractive opportunities and executing on them successfully. The remaining issue – as for so long – is the lack of inflows from new or existing clients. Gains in FUM during the quarter were entirely driven by $861m of investment gains, which offset net outflows of $419m. Unless this situation improves, I suspect the shares will remain fairly valued at current levels. Despite this, I think there’s enough value on offer to leave our moderately positive view unchanged today. | |
Secure Trust Bank (LON:STB) (£169m) | FCA proposed redress scheme is towards the extreme end of outcomes. STB to increase provision by approximately £16 million to a total of £21 million. | AMBER (Graham) Downgrading this to neutral has been a really difficult decision as I still believe in the value on offer here for patient, long-term shareholders. However, long-term may also mean long-suffering as the accounts are likely to be messy for the time being as the bank digests the costs of shutting down its vehicle finance businesses, while also complying with the FCA's redress scheme for motor finance customers. I agree with the stock's very high ValueRank and would like to upgrade my stance on this again as soon as possible - perhaps when we get a little bit more clarity and a sign that trading has stabilised. STB's "core" business is doing ok but arrears in the non-core segment haven't improved as anticipated. This is one I'm going to be watching very closely for a buying opportunity. | |
DP Poland (LON:DPP) (£78m) | Renewed agreement for 10 years to 31 August 2035. A further 10 year renewal option would extend it to 2045. | AMBER (Graham) [no section below] This is really just a box-ticking exercise as it essentially allows the company to continue operating for another ten years, and legally it looks set up to continue for another 20 years. Recent interim results (to June) showed that the company remains loss-making as it has been for many years. Fortunately, the losses are small (£460k in H1) and there is £3.5m in the bank. With 117 operated stores plus another 90 franchised stores trading as “Pizzeria 105”, the market cap is potentially cheap against 200+ pizza outlets, but the lack of a decent track record would keep me cautious. | |
Defence Holdings (LON:ALRT) (£54m) | ”...continues to execute its strategy with financial discipline, maintaining a robust balance sheet and significant headroom to support ongoing delivery.” | ||
Various Eateries (LON:VARE) (£18m) | SP +25% Rev +6% (£52.4m), ahead of exps (£50.7m). Adj. EBITDA at least £1.1m versus market expectations £0.4m. Momentum has continued into FY September 2026. Cash at bank of £8m. New Zeus forecasts: FY5 adj. LBT £2.9m (previously LBT £3.6m). FY26 adj. LBT £2/5m (previously LBT £4m). | AMBER (Graham) [no section below] A huge share price reaction today but please bear in mind that Hugh Osmond owns 64% of this company, so the free float is only worth about £8m even after today’s gains. Revenues are 3% ahead of expectations and these expectations must have been quite modest, given that full-year like-for-likes are only 2%. This is said to be ahead of the wider market. The really good news is that greater efficiency has had a remarkable impact on the bottom line, even despite higher min wage and NICs. The strong cash position is worth highlighting but I can’t turn positive on this on the basis of positive EBITDA. Checking forecasts from Zeus (with thanks to them for publishing today), I note that the company is expected to remain loss-making in the current financial year in terms of the pre-tax result. | |
Prospex Energy (LON:PXEN) (£18m) | Gas production has resumed after detection of a leak in April. Prospex owns 7.24% of the field. | ||
Zenith Energy (LON:ZEN) (£15m) | Italian subsidiary agrees to acquire solar energy projects with combined capacity of 22 MWp. Total portfolio 98.5MWp. | ||
ARC Minerals (LON:ARCM) (£15m) | Zambian JV between subsidiary Unico Minerals and Anglo subsidiary has by mutual agreement been terminated. |
Graham's Section
Secure Trust Bank (LON:STB)
Down 5% to 844p (£161m) - FCA Consultation on Motor Finance Redress - Graham - AMBER
The STB share price has already been under a lot of pressure this month:
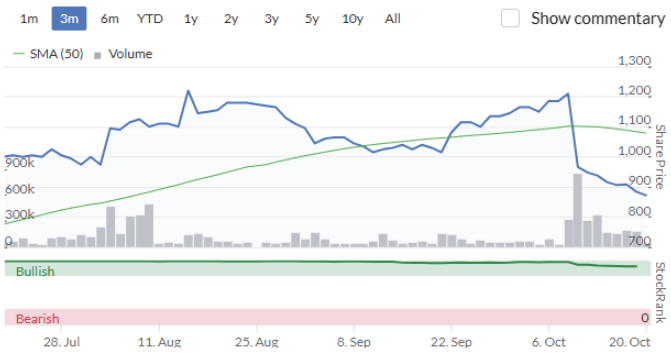
On October 9th, the shares fell 20% after a profit warning. As we didn’t get to look at it that day, here are the details of that warning:
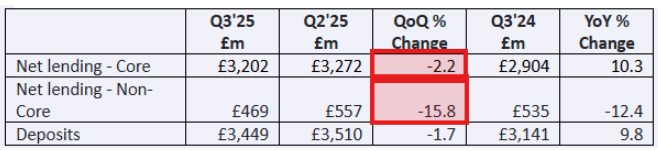
The overall net lending book declined 4.1% in Q3 due to the “run-off” of Vehicle Finance, a market that it is exiting and that it now describes as “Non-Core”.
“Core” net lending grew by 10.3% (Retail Finance 9.1%, Real Estate Finance 12.6%).
The vehicle finance book is shrinking faster than STB expected - but remember that it’s no longer making loans under this heading. Surely there can’t be that much variance in how quickly customers are repaying?
This table shows that the Vehicle Finance book fell 15.8% in the quarter, and even the “Core” book fell by a few percent:
As far as the profit outlook is concerned, this strikes me as even more important:
The Vehicle Finance business also incurred higher than anticipated impairment charges for the year-to-date with expected improvements in probability of default rates not yet being fully reflected in the IFRS9 accounting models. Underlying arrears and default rates in the portfolio remained stable but have not improved on H1 2025 to the extent anticipated.
The first sentence makes it sound like an accounting issue, but actually there is a real problem: arrears and default rates not improving.
It’s always very disconcerting when I see this sort of two-pronged failure: the loan book is shrinking faster than expected (which I guess includes car loan refinancings/early payments), and at the same time arrears and default rates aren’t improving as anticipated. So there’s less interest being received both from good borrowers and bad borrowers
On top of the above, “management also expects that the exit from Vehicle Finance may require additional provisions for onerous supplier contracts associated with new business originations”.
So that makes for a trifecta of bad news from Vehicle Finance. At least we know these aren’t going to be ongoing problems!
The “Core” business was reported to be still trading in line.
Profit outlook:
Whilst the Board now expects the Group's underlying profit before tax for FY25 to fall below market expectations by up to £9 million, due to the performance of Vehicle Finance, it remains confident of c. 30% year-on-year growth in underlying profit before tax.
View on the profit warning: we’ve been AMBER/GREEN on STB, and I’d be reluctant to downgrade to neutral on the back of this warning, as all of the bad news warning relates solely to a segment that is in wind-down.
For context, adjusted PBT at STB last year was £39m. And that was after taking a £62m special impairment charge related to the FCA’s “Borrowers in Financial Difficulty” review, which affected many companies in the sector. For a company with a market cap (today) of £161m, these are enormous profit figures.
I suppose the problem is that it’s all so complicated: do investors need to focus on the “Core” business only, or should they look at the overall “Adjusted profit before tax pre impairments” (which the company highlights), including vehicle finance?
Or how about adjusted profit before tax?
Or (the worst options) actual profit before tax, or actual net income!
I guess I’ve talked my way into downgrading this to a neutral stance, due to the complications.
Personally, I still see an enormous amount of value at the current market cap. But here at the DSMR we are trying to be disciplined, which typically means downgrading stocks when they issue bad news.
And the statutory result could be poor here, after all provisions and impairments.
Speaking of which, here is today’s news:
FCA consultation paper on its proposed redress scheme is towards the extreme end of outcomes previously expected from the Supreme Court judgment
STB expects to increase its motor finance redress commission provision by approximately £16 million to a total of £21 million
£16m is about 10% of the current market cap, after today’s share price fall; it’s a material amount, but it doesn’t fundamentally change the investment story here, in my view.
Checking last year’s full-year results again, I find tier 1 capital of £350m, and balance sheet equity of £360m (almost fully tangible).
So an additional £16m charge isn’t a game-changer, in my opinion.
The company’s calculations say the same thing:
On a pro forma basis, as at 30 September 2025 STB had a Common Equity Tier 1 ("CET1") ratio of 13.3%1. STB estimates that the additional expected provision of £16 million1 will reduce CET1 ratio by c. 50 basis points to 12.8%1, significantly above the Group's regulatory requirement of 9.6%.
Also worth noting that the FCA’s current proposed redress scheme (which I view as a worst-case scenario for the industry) would only result in an additional £6m provision, according to STB. There is still time for the consultation to soften the redress scheme.
Graham’s view: I’m going AMBER on this today, for two main reasons:
Discipline: we tend to downgrade stocks that issue profit warnings, because bad news tends to be followed by more bad news. Ed has written about this for years, e.g. see here.
Complexity: even though my personal view is that this stock offers excellent value, I acknowledge that the results are going to be highly complex, with a range of provisions, impairments and one-off costs. The motor finance compensation is not responsible for all of this complexity - the company’s own decisions and the manner of presentation also play a role.
I do hope to take a positive view on this again before too long, but for now I’m neutral.
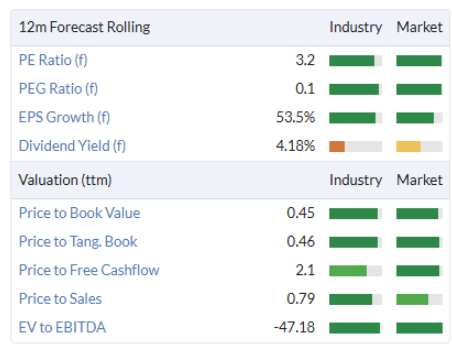
The ValueRank is 97, but it’s not easy to buy against the type of news flow that STB has produced
Roland's Section
B&M European Value Retail SA (LON:BME)
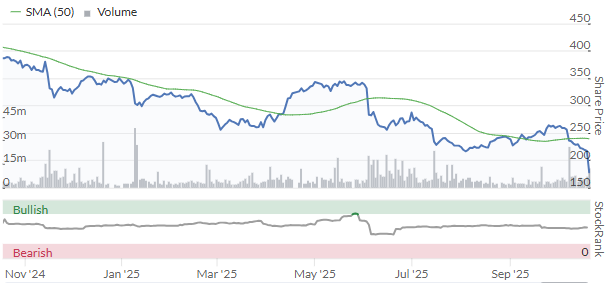
Down 18% at 179p (£1.8bn) - Update on FY26 Guidance and Directorate Change - Roland - BLACK (RED)
Commiserations to shareholders here – today’s update from the value retailer is B&M’s second profit warning in three weeks. I covered the previous update here on 7 October.
The short version of today’s update is that the company has cut its full-year profit guidance range by c.7.5% after discovering a £7m accounting error in its H1 accounts.
The company is commissioning a third-party review of this issue and CFO Mike Schmidt intends to step down, although he will stay with the company until a successor has been appointed.
Let’s step through the news.
Accounting error: while preparing its half-year accounts, B&M discovered “approximately £7m” of overseas freight costs that had not been correctly recognised in cost of goods sold. This error followed a computer system update earlier this year.
The issue has been resolved but the company warns the impact on the outlook for FY26 is “material”.
Impact: H1 adjusted EBITDA is now expected to be £191m, instead of £198m previously – a reduction of £7m. This implies an H1 EBITDA margin of 6.9%, versus 7.2% previously.
Revised FY26 outlook: as a result, B&M has cut its FY26 adj EBITDA guidance to £470-520m. This is a reduction of around 7.5% from the previous guidance of £510-560m.
However, in numerical terms EBITDA guidance has been cut by £40m, versus a £7m reduction to H1 EBITDA. Intuitively, this seems like a bigger cut than we might expect to see for the issue described.
The company doesn’t highlight any other issues today but says the FY outlook has been recalculated based on “revised second-quarter margin run rates” (my bold).
I wonder if this suggests that the extra costs only apply to Q2 trading, not to H1 as a whole. If so, that would magnify the potential impact on H2, especially given B&M’s typical H2 seasonality.
Working through the numbers gives me:
Seasonality: today’s revised EBITDA guidance suggests a 40/60 H1/H2 split, taking the mid-point of guidance. This would be a similar H2 weighting to last year. Applying the extra £7m of costs pro rata to the increased revenue expected in H2 would give me c.£16m of additional costs.
Q2 + H2: adding £16m to £7m gets me to about £23m of additional costs/margin impact
That’s still a long way short of the £40m cut to today’s FY26 EBITDA guidance. I wonder if the £7m of unrecognised costs actually applied to a timeframe that was shorter than one quarter; that would magnify the FY impact.
The problem here is that I don’t know the margin assumptions being used for H2 or the timeframe over which costs were not being recognised. The company didn’t split out quarterly EBITDA in its H1 update and hasn’t been explicit today about the timeline.
Another issue that’s likely to have a big impact on FY EBITDA and earnings is the potential range of revenue outcomes for the year – the company reiterates this guidance today:
As previously disclosed, B&M UK's like-for-like ("LFL") sales are expected to be the principal driver of the outcome within this range, for which we reaffirm our assumption of a second half UK LFL percentage growth rate of between low-single-digit negative and low-single-digit positive levels.
A performance at the upper end of the range could drive positive operating leverage, boosting profits and operating margins – whereas a weaker result will have the opposite effect.
Roland’s view
Today’s profit warning extends a fairly dire run of downgrade for B&M over the last 18 months:
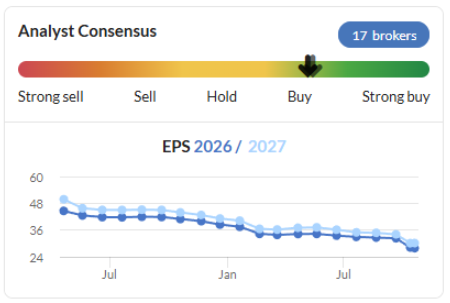
I’d previously turned neutral here on the basis that B&M’s problems seemed like they should be fixable by the highly-experienced new CEO, Tjeerd Jegen
However, I don’t have enough information to make the numbers add up in today’s update.
I’m also concerned by how low the group’s margin expectations appear to have fallen:
FY24 EBITDA margin: 11.5%
FY25 EBITDA margin: 11.1%
FY26 revised EBITDA margin guidance (mid-point, consensus revenue): 8.5% (prev. 9.2%)
More broadly, I’m worried about the risk that trading in H2 could still end up falling below revised guidance.
In today’s RNS, the new CEO seems to suggest that returning to historic levels of profitability might be a medium term goal:
The Group continues to expect that with LFL growth, future adjusted EBITDA margins for B&M UK can stabilise at low-double-digit percentage levels over the medium term.
As Mark has commented in the past, when a company talks about the medium term, it often means the short term outlook is not very good!
Today’s update has left questions unanswered, at least for me. It also highlights a sharp fall in margin expectations – and says nothing about leverage, which will presumably now be higher than expected at the end of the year.
My previous move to a neutral view appears to have been premature. I am going to drop down to RED ahead of B&M’s H1 results being published (due 13 Nov). As things stand, I wouldn’t want to invest here without more information.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Supreme (LON:SUP)
There is a good interview between Paul H and Sandy giving details of today's acquisition here: https://www.voxmarkets.co.uk/a...
Shore has raised adj. eps to 3/26 and 3/27 from 16.7 and 16.7 to 17.1 and 18.8. Zeus has raised the same from 17.4 and 19.4 to 18.0 and 20.6.
For those worried about vaping Shore has this category as 46% of revenue and 50% of gross profit to 3/27.
Supreme (LON:SUP)
cheers sharw - useful info - thats good if they have it as down to 50% of gross profit come ye 31/3/2027 - i might have feared it might still be higher than that (trending down is good for me - as i dont like that sector)
with upcoming budget and what not i think for those not invested t present remaining on the sidelines for now is slightly less risky than jumping in if the powers that be need to raise more money "from all sources" -next month. Hey ho this might get a bounce perhaps post budget if there is no bad news.
ref slimming world
interesting that back in the day slimming world was worth £2.5 billion at one stage - so £20 mill seems cheap - £9 million gross profit. Payback in 3 years.
Does anyone else find it ludicrous that an institution of Lloyds Bank’s weight ( with Halifax and Bank of Scotland) relies entirely on on a third party server company such as AWS? Banks, of all companies, should have a switchover mirror site and preferably both sites under their exclusive control, with different geographic locations of course.
If this is the area where they believe they can cut costs, then I see them as being cruelly deceived.
B&M European Value Retail SA (LON:BME)
I decided to test AI yesterday and asked it what shares I should buy now. This was one of its suggestions.
Perhaps it knew they would be much cheaper today ;-)
Is this a new measure of frothy markets - AI buying the dip!
Thanks all! If you have the time please could you look Fiske (LON:FKE) ? Thanks
The work behind the scenes continues at Mello, as we hope to create another excellent investor fest for any of the Stockopedia community that will be joining us on the 18th & 19th November at #MelloLondon: https://www.melloevents.com/mellolondon2025
If you missed out on early bird, do not worry, as you can still get 25% off general sale tickets with this discount code: Stocko25
Confirmed exhibiting & presenting companies:
B.P. Marsh & Partners (LON:BPM) EJF Investments (LON:EJFI), Inspiration Healthcare (LON:IHC) IP (LON:IPO) Manx Financial (LON:MFX) Mercia Asset Management (LON:MERC) Mortgage Advice Bureau (Holdings) (LON:MAB1) Newmark Security (LON:NWT) Oxford Technology 2 Venture Capital Trust (LON:OXH) Personal group (LON:PGH) Polar Capital Holdings (LON:POLR) Rockwood Strategic (LON:RKW) Serabi Gold (LON:SRB) Seraphim Space Investment Trust (LON:SSIT) Shearwater (LON:SWG) Skillcast (LON:SKL) Smithson Investment Trust (LON:SSON) Theracryf (LON:TCF) Time Finance (LON:TIME) Wise Funds PCI Pal (LON:PCIP)
Keynotes include:
Richard Staveley, Rockwood Strategic (LON:RKW) Tom Dorner, Polar Capital Global Financials Trust (LON:PCFT) Judith MacKenzie, Downing & Lord John Lee. More to be announced.
Panel Sessions & Educational Talks:
We will of course have our popular BASH (buy, avoid, sell, hold) panels as our BASHers put forward their stock picks.
We will also have talks on Crypto, Investment themes that become Bubbles and so much more!
Hopefully as many of you can join us in Chiswick on the 18th & 19th November.
David
Supreme (LON:SUP) has made another acquisition, Slimfast UK and Europe for £20m. The company appears to be making lots of acquisitions as it pivots away from vaping to other fast moving consumer goods. Good leadership with plenty of opportunities. Appreciate any views you may have Graham or anyone following this Co
Supreme (LON:SUP)
i think the jury is out here - they are splashing the cash for future stuff. Looking at expectations for 2026 and 2027 - both have been clearly trending downwards ref expectations.
As things stand they expext ye 31/3/2027 to have same similar of eps as they returned ye 31/3/2024.
Its not clear whether vapes easy profits are exiting the building and not being replaced by new stuff - or whether new stuff simply isnt generating material profits. I suspect that its probably mixture of "both"
Note i am guesing vapes is still the vast majority of profits and more regulation may be on the way - so i would say possible headionds too if the powers that be rightly cmap down further on children vaping - its clear to me the recent changes have probably changed very little in that regard (once its endemic its so much harder to cut out).
Personally i find vapers worse than smokers as they are so often so keen to vape they will do so before they have actually left a building or public transport facility - it would be nice if they had the courtesey to at least get clerar of place where others dont get the fumes wafted in their mouth - before taking their "hit". I ssuepct many are clueless that they even do it - just evidenced how addictive vapes are though.
If the expectations are lower for vape profits and other stuff is coming on stream making positive progree - then perhaps the worst may be over. But it does seem that they arent making any meaningful progress and still have vaping risks medium term.
Does anyone have any splits ref future profits from different segments - if other stuff is trending up and vapes is trending below 50% and worst is over i could perhaps buy in here. I aint gonna do it whilst its making over 50% of profits from vaping supplies though - imho thats a risky segment to be making over 50% of profits from.
Vaping was 55.8% of revenue in FY2024.
Supreme (LON:SUP)
Vaping was 55.8% of revenue in FY2024.
I am more interseted in profits than revenues.
Looking at the year end update it also appears new vape taxes turn up from Next October - i have asksed copilot what it thinks effect will be on pricing and looks like price could be doubling to trebling on refills. Thats a chunky increase in price for your average teen vaper
That could perhaps materially impact things i would guess - thats even without posible further tightening ref legislation above and beyond what is already planned. imho we cant get enough of that.
Impact on Prices
Example:
Current 10ml bottle: £3 → After tax: ~£5.64 (including VAT).
Current 100ml shortfill: £10 → After tax: ~£32+ (including VAT and margins
Regulation with Tobacco companies made it more difficult for new entrants to enter the market and this could be the case here. That they also have diversified into different product categories and purchased well known brands should bode them well
Allegedly Vaping is not as dangerous as smoking and not all Vapes used are laced with nicotine, I think they will around for a long time to come. I do agree with you when its come to inconsiderate vaping in public places.
Supreme (LON:SUP)
Allegedly Vaping is not as dangerous as smoking
i think its a very proven fact that vaping is by far the lesser of two evils here - vaping is brilliant starting point for anyone who cant give up smoking via other means.
Facts are though smoking has been in long term "terminal" decline for decades now - that trend would have continued as it was without vaping coming along.
So the real issue is that half of the people using vapes are not ex smokers (and that % will grow) - and a decent % of "ex smokers" would have been ex smokers anyway without vapes.
It would have been super easy to make vapes available on prescription for ex smokers only - job done.
Note twice as many youngsters vape as smoke - so what should have been a sub 10% 18-24 smoking rate with next to no vapes - is now something like 1/3 of all 18-24 years partaking in one of the two very very addictive activities both of which are clearly not healthy.
pure craziness we have allowed vapes to get out there without prespcription when we have done an amazingly fantastic job in ensuring that less people smoke yoy every year independant of vapes.
B&M European Value Retail SA (LON:BME) is yet another share where it paid off when I sold after the first hints of trouble around £5. The share price fell that day……and for the first time they were vague about the Outlook.Time and again it pays to sell on the first profits warning.
Does anyone have thoughts on what is going on with the Treatt share price, now well below the bid offer of 290p? Although Dohler have built a 22 percent stake they have said that they do intend to bid. Is it a “spoiler” holding with the intention of hoping to buy at a lower price when the current offer fails ? I hold.
Does anyone have thoughts on what is going on with the Treatt (LON:TET) share price, now well below the bid offer of 290p? Although Dohler have built a 22 percent stake they have said that they do not intend to bid.
(My bold).
The view is that Dohler's stake is a blocker and the bid will fail. The recent update from the company suggested their woes are not behind them.
Longer term Dohler's stake is probably a good thing, but in the short term the price will likely fall back below where it was pre-bid given that the company performance has deteriorated and Dohler's involvement prevents a bid.
At lower prices there may be value here given the assets.
I sold on the improved bid.
timarr
Treatt (LON:TET) Thanks for correcting my typo error timarr. As you say, Dohler do not intend to bid. My feeling at the moment is that I should take my small profit and sell.
B&M European Value Retail SA (LON:BME) Are the wheels coming off the wagon on this one? I did own some time ago, and sold at a loss. Just as well.
BME has a momentum score of 3. Anything below 20 I take as a serious red flag. If you go back a year. The M seems to have been below 20 since around Dec 2024 (let's say at about 337p), so we'd have plenty of time to sell out, which would have been the right decision.
Amazon Web Services us-east-1 region is down today and absolute Armageddon on the internet as usual, with many businesses you wouldn't expect to have a dependency on a US data centre being totally broken with little they can do about it in a hurry.
My Xero accounts has just come back !
There's no good reason to have all your critical tech infrastructure dependent on one region these days. It all depends on how the management team view risk vs cost to mitigate. And that tells me something about how they run the rest of their business too.
Today's small issue at B&M European Value Retail SA (LON:BME) has reminded me of a retail mystery. I have failed to understand the previous success of this company and that of the one owned by 3i (LON:III) (is it called Action Group?) I thought that the failure of Woolworth many years ago indicated that any 'value retailer' of low ticket items would struggle on the high street with such challenging overheads as we have in the UK. I must be missing something?
Agree, B&M European Value Retail SA (LON:BME) also has other competitors that are too similar (eg Home Bargains).
I wouldn't like to be in the CEO's boots today, having bought £.5 million+ of stock at around 245p in September. Ouch....
And yet there's The Range which is privately run and profitable (?)
Yes. Near me we have a large B&M store, it is like a DIY shed and just about 200m away there a Range shop, quite large but not a shed. The Range seems busy, maybe because it is smaller but the till area is usually quite busy. Their prices are often lower than B&M. The tills at B&M, often only 2 open and queues usually not more than a few people. The Range have taken over from Wilko, in fact they stock some Wilko products.
Always think it's odd that you never get company accounting errors where they FIND £7million they didn't know they had.....It's always usually the negative.
RE: B&M
"I thought that the failure of Woolworth many years ago indicated that
any 'value retailer' of low ticket items would struggle on the high
street with such challenging overheads as we have in the UK"
More nuanced than this I think. If you follow the value retail market you will see some companies making a success of the value segment, whilst others like B&M appear to be struggling.
The Corporate website of Home Bargains gives some useful information on how a value retailer can grow. Worth noting that HB has recently been ranked by Which at No 6 in the top 100 stores. Also worth noting is HB credit of 5A1 which is difficult to beat.
https://corporate.homebargains...
I think that key difference between B&M and HB is the shopping experience. The B&M store nearest to myself is in quite a poor state of repair and it looks like you are going into a cheap store, whilst the Home Bargains is extremely well fitted out and it looks like a premium shopping experience.
It would seem that most shoppers want a value store with a premium instore experience. This isnt rocket science, but something a natural and intuitive retailer will deliver.
I have been quite bearish about B&M as I cant see how it will restore its former glory. The turnaround quoted by the new CEO seems quite slow and during that time competitors will be growing. HB has stated previously that its objective is to open 800 to1000 stores up from its current base of circa 650 stores. Some of these will no doubt pile more pressure on B&M.
No connection to either HB or B&M.
To use my old Works Managers expression when exhorting to make big improvements; "you can't sell tyres off the top of a dunghill".
Probably worth noting that Action does not operate in the UK, having said publicly that it has so far not viewed the UK as an attractive market to enter due to high operating costs, competitive environment etc.
I think the rise of Temu must be impacting sales at bargain retailers like b&m too
They sell the same products at a fraction of the price
Hargreaves Services (LON:HSP)
Disposal of first tranche of renewable energy land assets for £8.8m plus top up payment of £3.8m, possibly up to £5m depending on wind yields. Looks good to me.
Cavendish has a sum of the parts value at 930p; who knows but worth a fair bit more than the current share price in my view. Debt free, excepting that for the leasing of earth moving machinery and a 5.5% yield.
I hold.
Reassuring TU from CLIG, we hold. FUM up 4% - solid performance against Bloomberg benchmarks and total dividend at 33p the same as last year. As we've been raising cash I'd be interested in comments about parking some of it in CLIG. I'm also hoping there might be a read across to LTIT which we also hold.
Net outflows still look pretty high, although the funds seem to be performing well with market movements offsetting outflows from an AUM perspective. I would personally like outflows to stop or at least slow before getting involved here.
I hold Clig and good to see FuM holding steady and Div maintained, however I am not a fan of asset managers at the moment, others I hold (Pmi) are doing poorly. I personally feel more inclined to focus on Reits for dividend income, especially in an Isa wrapper.