Daily Stock Market Report (Tue 7th October 2025) - IMB, BME, ANG, TEP, LIO, CHRT

Good morning! Let's see what's in store for us today.
We've run out of time now - thanks for dropping in.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view |
|---|---|---|---|
AstraZeneca (LON:AZN) (£197bn) | Baxdrostat demonstrated a statistically significant and highly clinically meaningful reduction in 24-hour ambulatory systolic blood pressure compared with placebo. | ||
Shell (LON:SHEL) (£159bn) | Q2 adjusted earnings -$0.5 billion. Q3 outlook: -$0.5 billion to -$0.3 billion. | ||
Rio Tinto (LON:RIO) (£81bn) | Rio Tinto, Mitsui and Nippon Steel will invest $733 million (Rio Tinto’s share $389 million), extending mining activity for years to come. | ||
Imperial Brands (LON:IMB) (£24bn) | On track to deliver full year guidance, announces further £1.45bn share buyback.
“High-single-digit adjusted EPS growth” expected in line with forecasts (Stocko consensus 312p) | AMBER (Roland - I hold) [no section below] Today’s full-year update covers the year to 30 September and looks reassuring to me. Recently-departed CEO Stefan Bomhard appears to have followed the tobacco industry playbook successfully last year, with price rises “more than offsetting” the expected decline in volumes. In addition, Imperial says it gained market share in the US, Germany and Australia – three of its top five markets. The company continues to prioritise shareholder returns through dividends and buybacks, with an increased buyback of £1.45bn (FY25: £1.25bn) planned for the year ahead. I can’t fault the logic of this strategy in this context, but after a strong run, I don’t think the valuation is as compelling as it was even six months ago. Earnings forecasts have trended slightly lower over the last 18 months, too. While I currently hold Imperial Brands for income in SIF and my personal portfolio, I’m not inclined to buy more at current levels. I’m also a little wary about the recent change of CEO. I’m going to leave Megan’s previous neutral view unchanged today and await the full-year results to revisit the investment case here. | |
Londonmetric Property (LON:LMP) (£4.3bn) | Founder/investment director retires. £7.4bn portfolio has continued to perform strongly. Q1 dividend +7% to 3.05p. | ||
B&M European Value Retail SA (LON:BME) (£2.6bn) | H1 revenue +4%. B&M UK LfL sales +0.1%. Expects full-year adj. EBITDA of £510-560m (FY25: £620m). | BLACK (AMBER) (Roland) New CEO Tjeerd Jegen has completed his initial review of the business and makes some damning comments about operational failings, including prioritising “the look of a full shelf over actual stock availability”. However Jegen is an experienced retailer and I don’t see why these issues can’t be fixed. In the short term, the company must show it can return to positive LFL sales in the core UK business after a flat H1 LFL result. Today’s profit warning equates to c.12% cut to EBITDA guidance at the midpoint, with the actual outcome still highly dependent on H2 trading, especially the peak festive period. I am going to take a chance and maintain a neutral view today, as I estimate B&M now trades on c.8x earnings and could still enjoy many of the advantages that made it so successful (and cash generative) previously. While this situation isn’t without risk, I share the StockRanks view on this stock as a possible Contrarian opportunity. | |
| Greatland Resources (LON:GGP) (£2.5bn) | September 2025 Quarter Production Update | Quarterly production of 80,890 oz. AISC to be around the lower end of FY26 guidance. FY26 guidance remains 260,000 - 310,000 oz at AISC $2,400 - $2,800/oz. | |
Telecom Plus (LON:TEP) (£1.46bn) | Customer numbers up c. 19% in H1. “We remain confident in our previous guidance for both customer growth and adjusted pre-tax profits for the full year.” | GREEN (Roland) [no section below] I covered this utility reseller in more depth in June, when I reviewed the group’s FY25 results. The shares have drifted lower since then but today’s trading update seems fine to me and highlights continued strong customer growth. This business has consistently generated double-digit returns on equity and enjoys strong cash generation. I see it as an attractive alternative to traditional utility stocks and believe the shares look quite reasonably priced, on a forecast P/E of 14 with a well-supported 5.6% dividend yield. | |
Great Portland Estates (LON:GPE) (£1.33bn) | Whistleblower review finds no unlawful conduct & Q2 business update | “We reiterate our rental growth guidance… with portfolio-wide growth of 4.0% to 7.0%.”NEDs investigated whistleblower allegations; concluded historical bonuses were correctly calculated. | |
CVS (LON:CVSG) (£897m) | Continuing PBT -7.4% to £32.6m on an increase in finance expense and depreciation. New financial year off to a strong start. | ||
Oxford BioMedica (LON:OXB) (£766m) | Pays $4.5m for FDA-approved, commercial-scale viral vector manufacturing facility. Supports existing financial guidance. | ||
Cohort (LON:CHRT) (£643m) | 4yr contract for airborne countermeasures and related services for UK prime contractor & international end customer. | AMBER (Graham) [no section below] I’ve been neutral on this defence stock - e.g. see here - with a large anticipated H2 weighting creating a risk of a profit warning, in my view, which could be dangerous as the stock is quite highly rated. Today’s announcement only covers about 2% of annual revenues and I don’t think it makes any difference to forecasts, but as the CEO says it does help to “enhance the visibility” of revenues. I maintain my previous concerns and neutral stance. | |
PRS Reit (LON:PRSR) (£615m) | Rev +14%, adj EPRA EPS +19% to 4.4p, in line. NAVps +7% to 143p. Portfolio completed at 5,478 homes. | PINK (under offer) | |
Funding Circle Holdings (LON:FCH) (£373m) | Defaulted loans previously sold to Azzurro Associates have been settled by guarantors. | ||
Victorian Plumbing (LON:VIC) (£256m) | Rev +5%, in line with exps, adj PBT -5.6% to c.£21.8m, at top end of exps. Market share gains. | ||
Liontrust Asset Management (LON:LIO) (£209m) | Q3 net outflows of £1.2bn, AuMA £22.0bn at 30/9. Seeing signs of increased demand, but progress “slower than we had hoped”. | AMBER/GREEN (Graham) Everything has its price and I think Liontrust shares are cheap enough. The bear arguments are easy to make, but at a P/E of 7x and with over £100 of AUM for every £1 invested in the shares at this level, I think the bear arguments are priced in. | |
M&C Saatchi (LON:SAA) (£172m) | WSG is a specialist advisory and media rights consultancy. Deal funded with cash, no value provided. | ||
Gooch & Housego (LON:GHH) (£164m) | FY25 results to be broadly in line with exps. Y/E order book £142.3m (FY24: £104.5m). | ||
Orosur Mining (LON:OMI) (£77m) | Results from recent holes “consistent with expectations”. Targeting MRE by end of year. | ||
Angling Direct (LON:ANG) (£39m) | Rev +17% w/ UK LFL +14.2%. Adj PBT +34.7% to £3.0m. FY26 to be ahead of exps: revenue >£102m and adj EBITDA >£4.35m. (prev. £3.8m) | AMBER/GREEN (Roland) Today’s results show decent levels of growth and improving profitability. While this remains a low-margin retailer that needs to carry a lot of stock, the numbers seem to be moving in the right direction and today’s c.16% upgrade to FY26 EBITDA guidance is a respectable result. The share price looks up with events to me on a near-term view, especially given management’s cautious view of the outlook for FY27. But I think this business has the potential to become larger over time, especially if its European operations can scale up profitably. I’ve left our moderately positive view unchanged today. | |
Inspiration Healthcare (LON:IHC) (£20m) | Rev +41%, adj EBITDA £1.3m (H1 25: £3.2m loss). Strong order backlog. Confident of meeting FY26 expectations. | ||
Tan Delta Systems (LON:TAND) (£15m) | Order for oil analysis sensors to be used on commercial shipping. Small order but will be valuable as a user reference to aid sales. | ||
Cordel (LON:CRDL) (£14m) | Extended this Australian contract to 31 Aug 26. Includes LiDAR, Video and Clearance Assessments. |
Graham's Section
Liontrust Asset Management (LON:LIO)
Down 2% to 320.16p (£204m) - Trading statement - Graham - AMBER/GREEN
Liontrust Asset Management Plc, the specialist independent fund management group, today issues its trading update for the three months ended 30 September 2025.
We should be hearing from all the fund managers soon, with their quarterly updates.
Here’s the latest news from Liontrust.
Key points:
Net outflows £1.2 billion (previous quarter outflow was £1.1 billion, and the outflow in the corresponding quarter last year was also £1.1 billion)
Assets under management down 2.7% over the quarter to £22 billion
CEO comment:
"Over the past few quarters, we have written about our belief that the market environment going forward will be more favourable for active managers. We are now seeing clients seeking to diversify away from the US and towards active management, and this is shown in an acceleration of interest in Liontrust strategies.
It scarcely needs to be said, but the acceleration of interest is not yet translating to an acceleration of net flows.
He continues with an explanation:
We are having success among institutional investors and wealth managers, notably internationally. This includes new mandates as yet unfunded and being added to clients' buy lists. This progress has been slower than as we had hoped, however, leading to £1.2 billion of net outflows in the last quarter, which were spread across wealth manager, adviser and retail clients in the UK.
Unfunded mandates are a concrete achievement which should lead to imminent inflows, but being added to buy lists is a less tangible achievement - Liontrust funds will be just one set of options among many alternatives.
This comment from the CEO on active management is relevant for everyone, so I’ll quote it in full - I think fund management companies are very useful for macro comments like this:
The Magnificent 7 are still heavily influencing market performance; their earnings and valuations dominate the S&P, exposing the market to volatility. But, at the same time, we have seen increased dispersion among these mega cap stocks and currency movements have been a positive tailwind this year for investors in non-US markets such as the DAX, Nikkei and FTSE 100.
Geographical diversification, therefore, is becoming more important, as is stock selection outside the very biggest companies in the world. We expect to see greater dispersion of returns generally going forward highlighting the value that active management brings to client portfolios.
In other words: buying the Mega-caps/Mag 7 is no longer proving to be guaranteed easy money for investors.
He says Liontrust are “confident about the outlook” for their business - impressive, given that it has been years since the company reported net inflows!
Fund performance: looking through their table, I count that 39 funds are in the 3rd or 4th quartile over 1 year, while only 14 funds are in the 1st or 2nd quartile.
Granted that 1 year should not be a very significant timeframe for investors, but I think in practice that retail investors (who account for the overwhelming majority of Liontrust’s AUM) do care about 1-year performance, and it’s uninspiring to see so many funds in the bottom half of performers.
Graham’s view
The very latest AUM figure is £22.2 billion. At a £204m market cap, that’s £109 of AUM for every £1 invested in Liontrust shares, up from £92 in July. I was AMBER/GREEN in July.
At this even cheaper valuation, I’m inclined to leave AMBER/GREEN unchanged, once again on the basis of sheer cheapness against AUM.
The bear argument is easy to make: net outflows are continuing uninterrupted, despite management’s confidence, and the addition to “buy lists” may or may not make a meaningful difference to this trend. Fund performance, meanwhile, remains uninspiring - and that’s compared to other funds, not even the more difficult benchmark which is given by stock market indexes!
I’ve also been a little critical of management’s M&A strategy here - remember the GAM fiasco?
But everything has its price and I do like the risk:reward here.
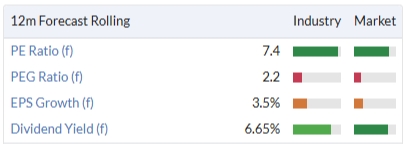
Stockopedia considers this a Contrarian stock - accurate.
Roland's Section
B&M European Value Retail SA (LON:BME)
Down 8% at 236p (£2.4bn) - FY26 H1 Trading and Operational Update - Roland - BLACK (AMBER)
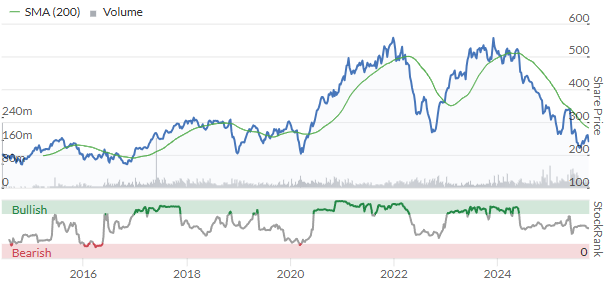
Unfortunately today’s update from value retailer B&M is a(nother) profit warning. This business was a FTSE 100 member not so long ago, but its share price chart now suggests it has now become either a contrarian bargain or a structurally-challenged business:
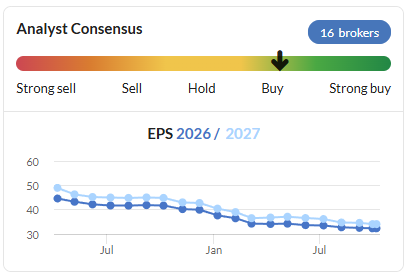
Earnings expectations have also collapsed, falling by more than a quarter over the last year, prior to today’s downgrade:
Clearly we need to be a little wary here – and it’s possible I haven’t been cautious enough. In my last review of B&M in June I concluded the FY26 outlook was probably in line and upgraded my view to AMBER.
With hindsight, I should probably have waited until new CEO Tjeerd Jegen – who only started work in June – had had more time to review the situation.
Let’s take a look at the main points from today’s update.
H1 trading: headline revenue figures for H1 show revenue up 4% to £2,749m, with growth in the core UK business and faster-growing French unit:
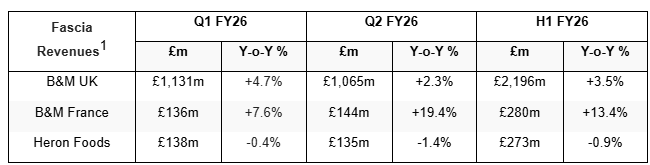
However, this growth was almost entirely driven by new store openings, which totalled 15 net new stores across the group (+9 UK, +5 France and +1 Heron).
Like-for-like sales in the core B&M UK business rose by just 0.1% in H1, as weaker FMCG sales offset growth in General Merchandise. This appears to reflect poor operational execution as much as weaker demand, according to Mr Jegen’s comments today.
Back to basics: Jegen is a highly-experienced retail exec and today’s update suggests to me that he is pinning the blame for B&M’s problems on a decline in operational execution in recent years. My reading of this is that the problems may have begun to emerge following the retirement of longtime CEO and co-owner Simon Arora in 2022.
In today’s update Jegen highlights four key actions being taken to improve the performance of B&M UK following his initial review:
Cutting prices on key FMCG items: while B&M pricing is said to have remained competitive at a basket level, some individual lines had become less competitive. Prices have been cut on 35% of “key value items”, lowering the average KVI price by 1.8%. Price rises elsewhere are expected to limit the impact on overall margins.
Rebooting ‘Managers Specials’ promotions: these are said to have become “static and duplicative”. To bring “excitement and great value back to our front-of-store bays”, store managers will be allowed significantly more discretion to choose the best lines to offer to meet local demand.
Refocusing our ranges: a material increase in SKUs (product lines) in recent years has “introduced complexity for our customers and our operations”. Plans are underway to reduce line count and accelerate the clearance of discontinued ranges.
Restorying product on-shelf availability: this made me sit up - “we found that our emphasis on store presentation prioritised the look of a full shelf over actual stock availability of products customers want”. As a result, availability of best-selling FMCG items fell to 86%, well below best practice standards of 98%. B&M is now planning to improve replenishment processes and simplify its ranges to ensure “our most popular products are always available”.
Retail is detail, as the saying goes, and the list above suggests to me that operational management has weakened since Simon Arora stepped down.
Historically, B&M’s core customer proposition was built around keen pricing, good availability of well-chosen ranges and fresh offers. The business seems to have been underperforming in all of these areas. I think it’s remarkable for a major retailer to admit that it has been pretending to have full shelves while disregarding actual stock availability.
I don’t mean to reflect unkindly on Jegen’s predecessor as CEO, Alex Russo, who took over from Simon Arora. But Mr Russo was promoted from CFO and perhaps didn’t have the operational experience needed for this role.
Outlook & revised FY26 profit guidance: we already know that gross margins were impacted at the start of the year by price deflation on some products. These changes are now starting to annualise, but some one-off cost headwinds remain:
Annual Extended Producer Responsibility tax costs of £14m
Higher wage costs of £30m in H1, before mitigation
H1 adjusted EBITDA is expected to be £198m, 27% below the £274m reported for the same period last year.
Leverage is expected to be above the group’s target range of 1.0x-1.5x at the half-year mark.
FY26 adjusted EBITDA is now expected to be £510m to £560m, versus a previously-reported consensus range of £569m to £646m. Taking the midpoint of each range, this represents a cut of c.12%.
The eventual outcome is expected to be highly dependent on B&M UK sales trends:
Given the visibility available on operating costs and trading margins, we expect B&M UK's LFL sales will be the principal driver of the outcome within this range, for which we assume a second-half UK LFL percentage growth rate of between low-single-digit negative and low-single-digit positive levels.
I don’t have access to updated EPS forecasts today, but I would guesstimate that B&M is probably now trading on a FY26E P/E of about eight after today’s share price fall.
There’s no mention of the dividend in today’s update, but my guess is that a more conservative payout may be likely, until leverage comes under control and LFL sales return to growth.
Roland’s view
After falling by nearly 20% at the open, B&M’s share price has recovered somewhat and is currently down by around 8% on last night’s close.
I can see why investors may be choosing to buy into this morning’s weakness. While I think today’s update gives a fairly damning view on the group’s operational management in recent years, my previous view that these issues are all fixable is unchanged.
Based on his comments so far, I am inclined to think Jegen could be a good fit for this role and has a decent chance of delivering a recovery.
The business doesn’t look too expensive to me, either. While profitability will clearly be lower this year, historically B&M’s quality metrics have been much stronger than those of the big supermarket groups:
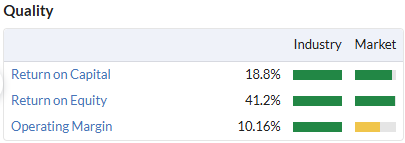
If these advantages can be restored in the future, I think profits could recover strongly over time.
I can’t take a positive view on a company that has just issued a profit warning. But I am going to take a risk today and maintain my AMBER view on B&M. Stockopedia’s algorithms rated this as a Contrarian stock prior to today. I believe that remains a fair view of the situation.
Angling Direct (LON:ANG)
Up 5% at 56p (£41m) - Half Year Results - Roland - AMBER/GREEN
I’m happy to see that I upgraded our view on this fishing equipment retailer to AMBER/GREEN following its H1 trading update in August, noting “the potential for an upgrade if H2 trading is strong”.
The shares have continued to rise since then, extending a strong trajectory over the last year:
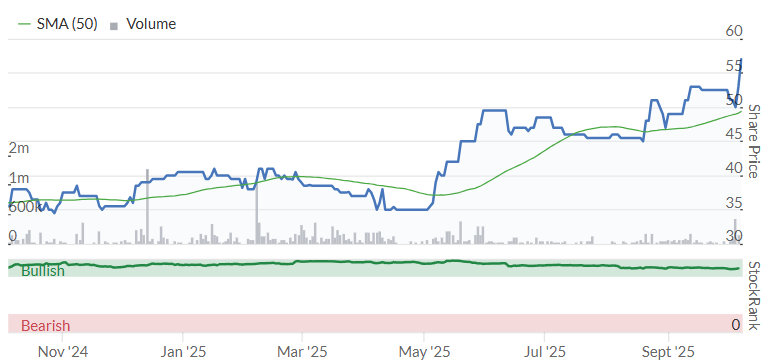
Today we have the actual results for H1 FY26 – and an upgrade to full-year FY26 guidance.
Sales growth has been consistently strong at this business, but (real) profitability has been very poor in the post-pandemic period, so I’m interested to see if this is improving.
H1 results summary
Here are the main headline figures from today’s results:
Revenue up 17% to £53.6m
Gross profit up 21.3% to £20.4m
Gross margin: 38.0% (H1 25: 36.7%)
Adjusted pre-tax profit up 34.7% to £3.0m
Reported EPS up 29.9% to 2.91p
Net cash down 26.5% to £12.5m
The company says retail sales in its UK business rose by 15.4% to £30.5m in H1, with like-for-like store sales up by a creditable 9.8%. Two new stores have been opened so far this year, taking the total to 55 UK stores.
Online sales rose by 21.2% to £20.6m, with customer numbers up by 17.9%.
Online growth is said to have been helped by the company’s loyalty scheme, MyAD – which now has almost half a million members – and by social media activity, with AD’s YouTube channel attracting 3.9m viewers during the half year.
In the nascent European business, trading improved but operations remained loss-making, with an adjusted EBITDA loss of £0.2m.
Profitability: operating costs rose by 20% during the period as cost and wage inflation added pressure to margins.
Even so, the increase in sales appears to have provided some operating leverage benefit, with an increase in operating margin to 6.1% (H1 25: 5.8%).
I estimate this translates into a return on capital employed of 5.9%, on a trailing 12-month basis.
These figures are an improvement on last year’s result, but ROCE is still likely to be below the group’s cost of capital:
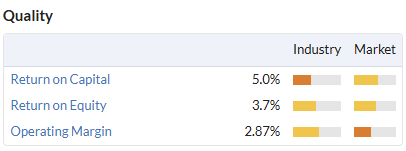
Looking at the accounts, my feeling is that the main reason for the low returns is the level of stock Angling Direct carries and the slow stock turnover it achieves.
Today’s report shows £26.2m of inventory at the end of July. That’s 20% above the levels reported at both H1 25 and FY25 – which seems to rule out seasonal shifts. Inventory seems to have risen faster than sales over the last year, which doesn’t seem ideal.
In addition, stock seems to move quite slowly. I estimate it’s taken around 140 days to turnover stock over the last 12 months. That’s consistent with the stock turnover ratio of 2.7x shown on the stock report, which implies a figure of 135 days.
If the business needs to hold stock for c.3.5 months and then only achieves a mid-single-digit margin, overall returns are likely to be constrained.
Fortunately, the negative working capital model of the business – where customers pay up front and Angling Direct benefits from supplier credit – does help to offset this somewhat, improving cash generation.
While net cash reduced during the period, the £12.5m net cash position still represents over 30% of the market cap, a margin of safety and some optionality on future plans.
Outlook & revised profit guidance
As a result of the strong trading over the first half and now that we have traded the final two months of the key trading season, the Board believes the Company will exceed current market expectations
Helpfully, the company provides specific guidance on this today for the FY26 year that ends in January:
Revenue: “not less than £102.0m” (prev. £97.7m)
Adjusted EBITDA: “not less than £4.35m” (prev. £3.75m)
This is a 16% increase on previous consensus EBITDA expectations, but it still translates to a somewhat sad EBITDA margin of 4.3%, below the H1 operating (EBIT) margin of 6.1%. This is a useful reminder that profits are heavily weighted to the first half of the year in this business. H2 has been loss-making or breakeven in recent years:
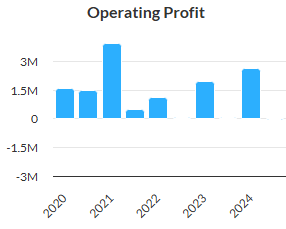
Perhaps a greater concern is the lack of guidance for the following year, with the company citing headwinds relating to “inflation pressures and consumer spending capacity”:
This ongoing wider uncertainty means that the Board will continue to adopt a prudent approach to planning for the next financial year.
Roland’s view
Angling Direct’s share price has only moved by around 5% today, despite the 16% increase to FY26 EBITDA guidance. I can see a couple of potential reasons for this.
First of all, the shares were already trading on a rolling P/E of 20 ahead of today. Not cheap, for a low-margin retailer:
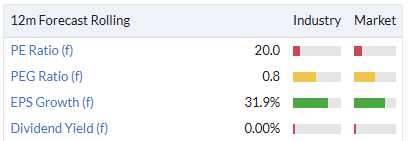
Secondly, the cautious tone on guidance for FY27 doesn’t necessarily suggest to me that the pace of growth and improvements in profitability seen this year will be maintained.
On the other hand, the company does seem to be trading well, gaining share and improving its financial performance. If the company can make its European operations work profitably, there could be scope for considerable further growth in years to come.
While I can see some risks, this is the second upgrade in six months. I think it's appropriate to maintain my AMBER/GREEN view on Angling Direct today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
I dont hold Liontrust Asset Management (LON:LIO) , preferring Polar Capital Holdings (LON:POLR) at the moment, but I remember when I was working in the industry it could take a number of years for a mandate to come to fruition from the initial inquiry. After all, you don't just drop $250m or whatever amount at the drop of a hat! A 2 year process wasn't uncommon for a big mandate.
I am surprised that Liontrust Asset Management (LON:LIO) haven't announced any acquisitions, I know at one point they had a team dedicated to it, not sure if they still do, and one of their justifications for updating their systems lat year was too make future integrations easier.
Thank you for covering Angling Direct Roland, I agree it's not cheap, and it's not exciting, I'll wait for the inevitable drift back in the share price before contemplating adding to our holding.
We hold Angling Direct and it makes a welcome change to see an above expectations forecast! I'm usually asking for comments on averaging down but maybe we've hooked a winner for once. Roland covered AD on the 20-08-25 and nudged Stockopedia's rating up a notch while mentioning their sub 3% margins. They've managed to squeeze them slightly higher with more AD brand sales, smart shelves, and better buying. Apologies for being late with this comment but observations appreciated as I'm tempted to add more.
After a great MelloMonday last night, we are back for another one next Monday 13th October. We will be joined by the very popular Richard Staveley of Rockwood Strategic who will then be followed by three company presentations.
We have a special guest with Lord John Lee joining us to discuss the merits or not of the latest price announced for the takeover of Treatt plc where John is a significant shareholder and has been for many years of course. As ever, the webinar will be rounded off with our popular BASH (buy, avoid, sell, hold) panel. We may also have a couple more sessions which are tbc...
This will be a popular MelloMonday so secure your ticket early as we have a limited capacity on the webinar.
Full details here: https://www.melloevents.com/mm131025
Schedule (subject to some minor change):
5:00pm.... Richard Staveley, Rockwood Strategic (LON:RKW)
5:30pm.... Company Presentation from DSW Capital (LON:DSW)
6:10pm..... Lord John Lee looks at the Treatt bid
6.25pm......Company Presentation from Quartix Technologies (LON:QTX)
6:45pm.... Company Presentation from Nexus Infrastructure (LON:NEXS)
7:15pm.... BASH (Buy, Avoid, Sell, Hold) Panel
Please note, if you are a shareholder of any presenting company above, you can secure a free ticket.
If not, use code MMSTOCKO50 for 50% off tickets: https://www.tickettailor.com/events/melloeventslimited/1738556
Good morning, can I repeat my continued requests for the summary table to have each box formatted to top left alignment. IMB is virtually unreadable on a phone. Would appreciate an acknowledgement of my request with either reason why it can't be done or estimate when you can accommodate a reasonable customer request. (Sorry if my tone doesn't come across well, not intended. Just sick of this for months and my request not being acknowledged).
Wildshot, you would have a slightly higher chance of progress with this by using the green button at the bottom right of the screen. That way you will at least get some form of response.
"Wildshot, you would have a slightly higher chance of progress with this by using the green button at the bottom right of the screen. That way you will at least get some form of response."
Perhaps. I think it all depends on what question you ask on the green button. Some questions like the accuracy of the data are difficult to answer.
From some of the discussion posts, it would appear that a number of subscribers have been trying to raise issues via the green button and given up. There is the cynical view that the green button purely exists to avoid public discussion on points which are difficult to resolve.
Some times you don't any response. I did raise this issue about format, as it is rubbish on my iPad. They said use it in landscape, it already is in landscape, after that nothing. This issue is nearly half the scene is taken up by sticks in the right hand side. Yesterday on the table, the comments on one stock was 45 lines long, SpeedyHire below it must have been nearly a 100 lines long. There should be an option to not show the tagged stocks on the right hand side.
This has been discussed numerous times before, unless enough people complain, then nothing happens.
I used to wonder what all of the fuss was about (using PC screen). Today I find that not only has the info on the right grown to take up about half of the width but also the green button is missing. So how do I do anything about it?
OK. Sometimes people have good reason why they don't use the green button. So they have to raise issues in this DSMR. Fair enough.
My experience of using the green button is that you get an acknowledgement "We'll pass that on to our developers", then nothing. No way of seeing if they did, or if there is any follow-up. Perhaps there should be a public 'suggestions' forum to avoid replication and also make it a two-way street.
I wanted an option for the Stock Report and the Accounts tables to be in reverse chronological order so that the most relevant data are on the left by the row headings, not something from 2016. Suggested a year or so ago, nothing heard back since.
This has been suggested before about suggestions or airing of site problems, Stockopedia were opposed to it.
Not quite sure what the issue is as I have no problem reading the table on my phone. Perhaps better to raise direct with team rather than cluttering up the comments section with this repeated request.
Works fine for me
Hi wildshot, I agree that top-left formatting would make it much easier to follow, rather than having to scroll up and down, and I agree with WarrantStar that the green Support button is the place to go rather than this chat. . If you’re on a phone, the’ green button’ is called Support and you find it by clicking on your avatar, top-right of the screen. Good luck!
Wildshot: I use an iPhone 13 mini and i can read the IMB write up easily on that small screen by scrolling. Both in portrait and landscape. What exactly is the problem you want fixed?
How many words per line can you see, in the comments.
About 7 in landscspe
I see 1-3, in landscape.
Do you have the stocks on the right of the screen?
Shrink your font size.
Thanks for the suggestion but this would make it unreadable without a magnifying glass.
Or a pair of near vision specs.
Hopefully these screenshots load. Appreciate some people may not have a problem but judging on responses some of us do. Formatting is something that can be managed by editors when they write articles. Hopefully some of us will be able to appreciate more the great value of the written content when it is easier to read. All other things considered, keep up the great work
Same issue
Wildshot, are you using the internet to access or the Stocko app?
I'm not sure that your suggestion would make things better... if aligned top-left, would you not create the same need to scroll, but from a different starting point?
Regards, Jon
You would have to scroll less because the table would be wider. Comments on my screen can be 100 lines long, because each line is only about 15 characters wide.
Rusty and John F, my point is that with the name of the company in the centre of the left box, rather than at the top of the box I often am reading the writers views before I know what company they are talking about purely due to the layout which I think is not helpful. This is very bad on a phone and still not ideal on a computer or monitor.
OK, slightly different issue then from mine. Yes the name is in the centre, not at the top, so on my screen can be about 50 lines down.
I suggest long comments, are not put in full in the table, but below it. We used to have short comments before.
CFO of Made Tech (LON:MTEC) is departing after less than two years in the role. Numbers looked to be improving at the company, so shareholders will be hoping that this isn't an ominous sign of trouble down the road.
6 month handover, doesn't appear that ominous. Seller in the market currently too it seems to my annoyance
Chair reminding us of trading in line was helpful. Also CFO gone after they just published results and audit, so cannot be anything financial related.
Small order for real time oil analysis sensors from Shell Marine Products. Whilst the value is small, I believe the fact that Shell will use the sensors to monitor the quality of oil in their engines is significant. It is an endorsement that the product works and is able to reduce costs by basing maintenance on the condition of the oil, not an arbitrary time period. Given the number of engines in the world, there is ample opportunity to grow the business.
Here we have a small UK company based in Sheffield who have created a suite of products that is also being trialled by the likes of Amazon in the gearboxes and motors of conveyors in their huge warehouses. This again affirms the potential for a significant future IMO
Inspiration Healthcare (LON:IHC) I hold
Good start to 2026 following the change to "back to basics". Revenue up, gross profit up, margin up, debt down. Would be good to have the team cast an eye over this one.
Inspiration Healthcare (LON:IHC) be careful, have read elsewhere that brokers have lowered the forecasts quite a bit this morning. Not able to verify this though, can anyone confirm?
B&M European Value Retail SA (LON:BME) H1 26 report reads well. Weaknesses acknowledged and being put right. New CEO has bought about 1£million in shares. I think the bottom is in and the market will warm to this report. +5%.
B&M European Value Retail SA (LON:BME) The price has been moving back up from recent lows around £2.20 following the new CEO's confident purchases in the market. Margins are still under pressure. I don't remember them mentioning the problems keeping shelves stocked before. We could see this test recent lows again. The CEO's back to basics plan isn't retail rocket science, that's normal jogging isn't it, getting the basics right. Pricing and keeping shelves stocked.
Looking through the list of key initiatives at B&M European Value Retail SA (LON:BME) , think they are all sensible.... but the context is that they are sensible for moving the medium-term and long-term needle for them, but short-term looks negative.
There's a reason why they tried to maximise margin on certain line items as part of the basket, incrementally increased SKUs over time, and economised on stock replenishment frequency. These are all decisions made by management over the years, not blindly, but probably because they delivered incremental short term gain.
New CEO, rightfully so, focused on medium-term delivery as he knows he's being judged on a 2-4 year timeframe. Not 6-12 months.
So I think there's probably soft trading still to come for another 6-12 months. No hurry to buy IMO.
B&M European Value Retail SA (LON:BME) H1 26 report reads well. Weaknesses acknowledged and being put right. New CEO has bought about 1£million in shares. I think the bottom is in and the market will warm to this report. +5%
Have you read the numbers or just the words? I predicted a near 20% drop over on Paul’s site. SP is still uncrossing but I’m pretty certain this will eventuate.
Update - opened 18.6% down.
B&M European Value Retail SA (LON:BME) Could be a nice short term trade if it touches £2 or a good entry point for longer term investors.
Fair enough. My prediction hit rate is quite low!! I didn't think the numbers were so much below what was expected. And the words were guarded anyway. Traders may have been expecting better (hence 18% drop) but it is probably too soon to see that in the numbers. Will likely recover a bit during the day. I hold and expect the new CEO to do well with getting the simple things right. He is certainly invested.
Price is recovering a little now. Perhaps it will hit +5% by the end of the day and you’ll be the one laughing!
B&M European Value Retail SA (LON:BME) haha I doubt it. To be fair I did miss the numbers in the text lower down and just saw the ones in the box. Should have read the whole thing before commenting!!
B&M European Value Retail SA (LON:BME) actually by the end you were out by 12.2% and I was out by 12.8%!! Honours even I would say!
B&M European Value Retail SA (LON:BME) Maybe the new CEO is also "setting a new baseline" by getting all the bad news out at the start of his reign?
B&M European Value Retail SA (LON:BME)
Maybe the new CEO is also "setting a new baseline" by getting all the bad news out at the start of his reign?
I would wholeheartedly agree - either that or they are in a rut that has no possible positive narrative (sometimes i simply accept the honesty that times are tough and rising prices to cover increased costs and maintain margins is not possible always possible short term).
I wasnt expecting any more downgrades here after chunky purchase by new bod - but here we are and him setting the bar low makes sense unless they are ruderless without a paddle.
It can be tough for retail to gey mojo back when things go wrong - look at companies like boohoo and superdry (oj they are online) - tesco made zero progress for a few years after their accounting scandles back in the day.
its tricky when momentum is turning and the broker forecasts have bottomed out and the share price is starting to rise - everything can look promising here - but when on the sidelies i alwasy think that an uptick in future prospects is the safest sign of all that there isnt more bad news to come. I think many companies (building and construction particularly) - have ben biggie caught out here honestly thinking things look like they might get better - only for that pssoible betterness to not turn up.
Are many companies going to jump the gun with slight upgrade if they arent confident that there is actual improvement - probably not. Its
Note imho here its just a question of level of profits here - funamentally this company is still very much a money making machine.
Appreciate the new ceo has invested about £1m recently but I really don’t think b&m are that competitive price wise. debt levels are also too high
Home Bargains much better to shop in according to my better half.
The Range also.
Home Bargains is a formidable company. Privately owned with what appears to be a rather flat organisation where the staff have a direct route of communication with the senior management.
I had an interesting conversation with one of the managers a while back on the ability to keep shelves filled - he quickly responded that you cant sell fresh air.
Inconceivable to me that Home Bargains would let themselves get into a B&M situation and if they did, I doubt that it would take 12-18months to resolve.
My experience is that where Home Bargains are going head to head with B&M - there is only one clear winner.
I too prefer Home Bargains even though I have shares in BME. Just wish I could buy shares in Home Bargains as it seems like a great company. I always pass loads of their lorries on the motorway when I head North.
On the M4 between England and Wales too.
Good morning Graham.
If you have time, I'd be very interested in your thoughts on the latest production update from Greatland Resources (LON:GGP) posted this morning. It's been a very busy and transformative year for this company, transitioning from being a junior gold and metals explorer, into a fully fledged owner operator of one of the biggest gold mines in Aus. It was previously called Greatland Gold, and changed its name to more accurately reflect its future. Earlier this year, it cross-listed onto the ASX, and is now in the ASX200.
It has today published its update for the last quarter, and I believe it's a beat on forecast. The 'old' company was listed as a Sucker stock for many years, (justifiably in pure stat terms) with stock rank in the teens. The 'new' company now has a neutral rating, and a stock rank of 56. Unfortunately, owing to the cross listing, the 'old' company info no longer appears on Stocko, and 'new' company shows up on here as a 'recently listed company'. I've tried searching for the stats on the 'old' version, but they seem to have disappeared off this site. I've asked support about this.
Anyway, as big a fan as I am of Greatland Resources (LON:GGP), I'm always grateful for any feedback/analysis that might give me pause for thought as regards my investment, be that from yourselves or my fellow subscribers.
Edit: I see it's not on your list.
Thanks
Greatland Resources (LON:GGP) - thanks for highlighting this stock - Must be one of the largest MktCap listings on AIM. Wonder why they are not on the main LSE listing?
Hi bohenie,
I think based on what they've had on their plates over the last couple of years; the reorganisation of the company, the transition from a small explorer to a mid miner/producer/explorer, their recent move to the ASX, coupled with the cost and legal complexities of moving from AIM to Main, makes such a move quite a low priority, if indeed it even appears on their 'wish list'. I also think their priority, as an Aussie company, is the ASX.(Imho)