Daily Stock Market Report (Mon 21st September) - CRW, AAZ, ELIX, AXS

Good morning, the news flow over the weekend was fairly quiet from a UK perspective. Just a couple of political headlines worth noting:
The US and China have been holding talks on AI, trade and investment ahead of a summit this week between Donald Trump and Xi Jinping. For a preview of this summit, please see Mark’s Week Ahead article on Friday.
In Germany, the ruling Christian Democratic Union had another terrible state election and is projected to win less than 5% of the vote in Mecklenburg-Western Pomerania (a north-eastern state). Most votes were shared between the AfD and SPD.
Right, let’s get on with today’s company news!
Overnight market movements:
The FTSE is up 0.3% at 10,685
S&P 500 is up 0.5% at 7,680
Brent crude (November) is down 1.5% at $99.10/bbl
Gold is down 0.6% at $4,355/oz
Bitcoin is up 0.7% at $81,650
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£194bn | SR55) | Klygefa recommended for EU approval by CHMP & Enhertu recommended for approval in EU in early BC | Klygefa (gefurulimab) recommended for approval for the treatment of adults with generalised myasthenia gravis (gMG). | |
JD Sports Fashion (LON:JD.). (£3.5bn | SR92) | JD has agreed a franchise partnership with Mexican retail distributor Grupo Axo. Beginning in 2027, Axo will operate more than 140 JD stores and provide ecommerce trading. | ||
Resolute Mining (LON:RSG) (£1.53bn | SR79) | Production at Syama remains below plan due to the “challenging operating environment in Mali”. 2026 group production guidance has been cut to 205-225 koz at an AISC of $2,250-2,350/oz. | ||
Syncona (LON:SYNC) (£688m | SR59) | Portfolio company Beacon Therapeutic’s gene therapy, laru-zova, has met its FDA-endorsed primary endpoint, demonstrating statistically significant low luminesce visual acuity (LLVA)1 in patients. Beacon will now initiate pre-submission discussions with global regulatory authorities. | ||
Craneware (LON:CRW) (£459m | SR37) | Revenue flat at $206m with ARR flat at $185m. Adj EBITDA +3% to $67.1m with adj EPS of 116.8c (FY25: 116.1c). FY27 Outlook: "taking a prudent view of its revenue expectations in FY27, resetting them to... c. $185m." (StockReport revenue forecast for FY27 was $222m.) Financial impact of the recent cyber incident not yet quantified. | PROFIT WARNING (AMBER/RED =) (Roland) Today’s profit warning comes less than three months after the company’s last. Management warns that changing 340B regulations are hitting revenue and admits that the recent cyber attack could affect future customer engagement following the loss of some customer data. I think an interesting opportunity could emerge from this situation at some point, but I think it’s too soon to moderate our view just yet. Earnings visibility feels poor to me and I fear there’s still the potential for further downgrades. | |
Anglo Asian Mining (LON:AAZ) (£422m | SR56) | H1 revenue +245% to $141.2m with pre-tax profit of $68.5m (H1 25: $7.1m). Net cash of $57.7m. Outlook: FY copper production guidance unchanged at 20-25 kt. Silver guidance unchanged at 170-210 koz. Gold production guidance cut to 26-30 koz (prev. 28-33 koz). FY AISC guidance for copper reduced to $6,000-7,000/t. | AMBER ↓ (Roland) The main takeaway from today’s update is the cut to cost guidance for copper production. I estimate this could equate to a c.$18m cost saving in 2026. Although this could be partially offset by lower-than-expected gold production, I estimate today’s updated guidance could still support a c.8% EPS upgrade. While the shares appear cheap in P/E terms, Anglo Asian is a relatively high cost producer. I’d argue that further upside is largely dependent on commodity prices, making this a speculative situation. With the stock up 100% in six months, I think it’s prudent to move to a neutral position. | |
Guardian Metal Resources (LON:GMET) (£322m | SR9) | On the strength of the results for the first four Phase II holes, together with visual observations from a further 24 drillholes awaiting assay, the Company has decided to commence a rehabilitation program to safely access the underground historical workings. | ||
Elixirr International (LON:ELIX) (£316m | SR56) | H1 revenue +25% to £89m with adj pre-tax profit +25% to £25.1m. Adj EPS +18% to 34.2p. Strong growth in AI-related work. Outlook: confident FY26 adj EBITDA will be in line with expectations, with revenue broadly in line. | PROFIT WARNING (sort of!) (AMBER ↓) (Graham) Technically this is not a profit warning, but it’s very close to one. I’m going to record it as a profit warning for the purposes of our record-keeping. I’m also going to reduce our stance on this to neutral, as an organic growth rate of 5% - which is now baked into Cavendish forecasts - doesn’t scream to me that this is a company fully benefitting from the AI trend. As I’ve said before, there’s a ceiling on what I’d be willing to pay for a consultancy business. At the latest share price and EPS forecasts, I calculate the current-year P/E as 8x, falling to 7.6x for next year. That does potentially offer some value, but perhaps not so much when you consider the hollowed-out balance sheet. | |
S4 Capital (LON:SFOR) (£306m | SR91) | Non-exec Nirvik Singh is taking up a full-time role as part of the company’s executive leadership, so will step down from his non-exec role. | ||
Serabi Gold (LON:SRB) (£206m | SR94) | During H1-2026 20,831 metres of diamond drilling were completed, comprising 11,522 metres across 37 holes at Palito and 9,309 metres across 42 holes at Coringa. Results obtained to date have supported a number of new prospective models and reinterpretations. | ||
Accsys Technologies (LON:AXS) (£177m | SR51) | SP -12% Revenue -6% to €56.9m with group sales volumes -11% to 22,186 for the give months to 31 August 2026. Slower trading than expected due to macro conditions. Outlook: expect lower revenue in FY27, with adj EBITDA of €21m to €23m (previous consensus €28.8m). | PROFIT WARNING (RED) (Graham) We don't cover this one often. It's "the world’s leading supplier of premium, high-performance and sustainable wood building materials", and yet its financial track record is anything but premium: it has been listed for about 20 years and profits have been sporadic at best. Today's profit warning refers to inflation and interest rates having prompted customer destocking: that might very well be true, and it makes sense that the demand for building materials will be volatile and sensitive to economic indicators. But at the same time, it's hard to shake off the assumption that these wood products are heavily commoditised, given the overall lack of profitability. The note from Panmure Liberum today cuts the PBT forecast from €7.7m to €2.4m, a much more severe percentage cut than the EBITDA forecast has received. With such marginal profitability on volatile demand, and a poor historical track record, I'm inclined to take a negative stance on this today. There's also net debt of over €40m to be taken into account here. | |
Savannah Resources (LON:SAV) (£150m | SR32) | Shares suspended this morning as Savannah intends to undertake an equity capital raise to support the continued development of the Barroso Lithium Project. | ||
Pulsar Helium (LON:PLSR) (£144m | SR16) | David T Young joins Pulsar as Chief Financial Officer from 21 September 2026. He was previously at The Carlyle Group. | ||
Somero Enterprises (LON:SOM) (£136m | SR98) | Two additional NEDs have been appointed and Larry Horsch will retire. Howard Hohmann has left the board to become Chief Commercial Officer. Following the changes, Somero will have two Executive Directors and five NEDs. | ||
Invinity Energy Systems (LON:IES) (£113m | SR23) | Revenue and grant income of £1.7m with net loss increased by 14% to £12.1m, reflecting R&D expense. Net cash of £10.5m. Customer orders increased to 34.2 MWh (H1 25: 11.7 MWh). FY26 outlook: trading in line with management expectations. | ||
Iofina (LON:IOF) (£98m | SR77) | H1 revenue +7% to $31.3m with adj pre-tax profit +196% to $4.9m and net cash of $7.2m. FY26 outlook: on track to meet market expectations for the full year. | ||
Borders & Southern Petroleum (LON:BOR) (£95m | SR46) | Operating loss for the period of $726k, with cash of $1.02m at 30 June 2026. Continues to engage with third parties re. Farm-out process, with “significant progress being made”. | ||
Cora Gold (LON:CORA) (£78m | SR32) | FEED process advancing well with many workflows, including 3D plant modelling and all field work, now concluded. “This work is progressing in tandem with our resource expansion work, which has yielded highly positive initial results.” | ||
UPL (LON:UPLL) (£55m | SR21) | Phase Two of the LSOG development programme has started with the third well, GMF-5, spudded on 18th September 2026. Drilling and well operations are expected to take approximately 60 days. Potential resources of up to 5-6 trillion cubic feet (Tcf) of gas. | ||
Coiled Therapeutics (LON:COIL) (£34m | SR0) | COIL has successfully enrolled patients across two distinct escalation cohorts for its lipid-based formulation of AO-252 as the trial advances towards Phase I/II planned dose-expansion cohorts in ovarian and prostate cancer. | ||
Manx Financial (LON:MFX) (£31m | SR38) | PBT £3.4m (H1 last year: £4.1m), “the normalisation of profitability following the absence of some one-off benefits we enjoyed in prior periods”. Loan book £423m (2025: £393m). Total equity £45.5m. “The disconnect between the Group’s market valuation and its underlying performance remains stark.” | ||
Blencowe Resources (LON:BRES) (£29m | SR14) | COO becomes Interim CEO. Board looking for permanent CEO. Project financing: capex of $45m is estimated for Phase 1. Financing discussions are ongoing with a number of strategic investment partners and are progressing in parallel. “...current cash is sufficient to support the corporate overheads, ongoing product qualification and the Phase 1 project financing process.” | ||
Medpal AI (LON:MPAL) (£27m | SR5) | Conditionally raised £5m gross by issuing 10 million shares at 5p. Last night’s close: 6p. Trading update for September to date: annualised revenue now rate now over £35m, up from £28m for August. “Trading at current levels would be sustainable using the Company's current cash balances, but additional funds are necessary to sustain the anticipated growth trajectory of the Group.” Bank funding is being explored. | ||
Cleantech Lithium (LON:CTL) (£25m | SR15) | No revenues, £1.5m operating loss. Pre-tax loss £3m. CEO: “our focus is firmly on execution: advancing the remaining technical work to move towards the Definitive Feasibility Study… commence the environmental impact assessment… and permitting work, and selecting the right strategic partner.” Australian listing targeted for completion in Q4 2026. | ||
B90 Holdings (LON:B90) (£21m | SR42) | Revenue +38% to €3.3m. Net loss €0.02m (H1 last year: loss of €0.04m). Cash €1.47m. Board “remains confident in the Group's prospects for the remainder of the year and, based on current trading, expects the Group to deliver results in line with management expectations for the full year.” | ||
ARC Minerals (LON:ARCM) (£16m | SR10) | No revenues, operating loss £965k. Cash £1.9m. | ||
Pennant International (LON:PEN) (£14m | SR46) | Short-term unsecured shareholder loan agreement with Brett Gordon, an existing major shareholder, for a loan of up to £600,000. Enables PEN to reduce its bank overdraft to £1.0m. Interest rate 10%, payable monthly. Repayable in full after 180 days. | ||
Block Energy (LON:BLOE) (£14m | SR16) | 3D seismic acquisition over the Martkopi Terrace prospect in Georgia: approx. 70% of the survey has now been acquired and it is expected to complete by mid October. | ||
Eco Buildings (LON:ECOB) (£14m | SR3) | Framework agreement with Lumen, a cosignatory, and with the Republic of The Gambia, for establishment of the ECO Buildings West Africa AI-Powered Centre of Excellence. Minimum 10,000-home housing programme, including an initial phase and minimum order of 1,000 homes. Parties to negotiate the definitive agreements required for implementation. | ||
Powerhouse Energy (LON:PHE) (£10m | SR1) | Revenues £437.1k (H1 2025: £474.9k). Pretax loss £910k. £1.42m cash. Outlook: “Acceleration of the development of commercial applications for PHE’s technology through site visits and providing waste testing.” |
Graham's Section
Elixirr International (LON:ELIX)
Down 12% at 547p (£278m) - Interim Results - Graham - PROFIT WARNING (sort of!) (AMBER ↓)
Exlixirr is “an established, global award-winning, challenger consultancy”.
I was moderately positive on it back in April, saying that a P/E of about 10x was about as high as I’d be willing to pay for a consultancy.
Some weakness since then has seen the rating fall back to 9x, and it’s lower again today:
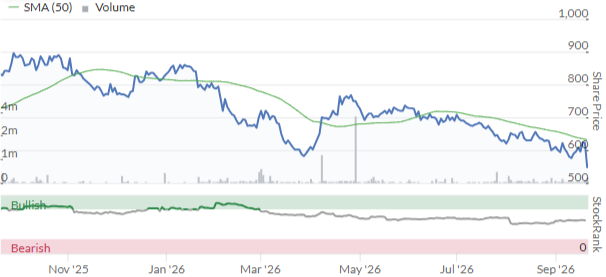
Highlights today:
Organic growth is 5%, lower than it was in FY 2025 (15.3%) and massively lower than the headline revenue growth rate of 25%.
Adjusted EBITDA is up 29%, with of course the majority of this growth being inorganic.
Adjusted PBT also rises strongly, up 26% to £25.1m.
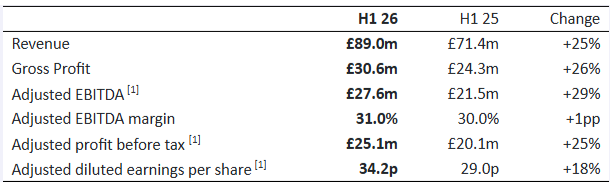
I note that adjusted EPS increases at the lower rate of 18%, hinting at some equity dilution.
Turning to the unadjusted (statutory) figures, I see that actual PBT comes in at £18m, nearly 30% lower than the adjusted figure. There are £7m of adjustments:
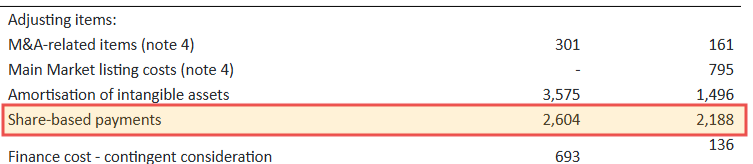
My main objection here is to share-based payments (SBPs), which were £2.2m in H1 last year and £2.6m in H1 this year.
So for me, the real PBT figure is £22.5m (adjusted PBT of £25.1m, minus SBPs of £2.6m).
Some might argue that the “M&A related items” are a feature of the strategy, and are therefore recurring, but I’m happy to treat them as a voluntary growth expense rather than a real cost of the underlying business.
Balance sheet: negative tangible equity to the tune of some £58m. A year ago, tangible equity was close to zero, so there’s been an enormous shift over the last 12 months.
Working capital: A year ago, working capital (current assets minus current liabilities) was minus £6m. In this report, it’s minus £10m.
Net debt: this has soared from £11m in June 2025 to £61m in this report. Even excluding leases, the company calculates a net debt figure of £56.5m.
The company says that its leverage ratio (net debt divided by annual EBITDA) is only 1.1x, which is a modest ratio and well within covenants. But for people businesses such as consultancies, I don’t consider this to be ideal. When I looked at Elixirr in April, net debt was only £24m.
Let’s check the outlook now:
Our scalable business model supported by an increasingly diversified platform spanning capabilities, geographies and industry verticals provides multiple avenues for growth. This, combined with our focus on quality of earnings and higher margin work, gives the Board confidence that total adjusted EBITDA for FY 26 will be in line with market expectations and revenue will be broadly in line.
This sounds to me like we should expect a slight revenue miss but with higher-margin work hopefully keeping earnings in line with expectations.
Estimates: thanks to Cavendish for publishing on this today. The leave EPS forecasts unchanged: adj. EPS of 67.5p this year, rising to 71.5p next year.
But they’ve also materially cut their revenue forecasts, by about 4% for each year. So for example, the new 2026 revenue forecast is £180m (previously £187m).
Interestingly they also cut their PBT forecasts by 2-4%. This doesn’t translate into lower EPS because they don’t expect the share price to rise by as much as they did before (could be because of lower expected SBPs or less acquisition-related dilution). Without knowing their exact reasoning, it seems to me that a slight reduction in the EPS forecast might have made more sense?
CEO comment focuses on AI, naturally enough:
“AI is changing what our clients need from us. Businesses are moving quickly from asking what AI can do to working out how they can use it to transform the way they operate and grow. We have built a powerful combination of consulting, technology, data and AI expertise to help them do that, with AI-related revenue increasing by 185% in the first half.
“The scale of the opportunity ahead is significant. Industry research estimates that agentic AI alone could create up to $200 billion of new demand for technology services over the next five years. We have spent the last six years deliberately building our consulting, AI, data and technology capabilities to benefit from this shift.
Graham’s view
Technically this is not a profit warning, but it’s very close to one. I’m going to record it as a profit warning for the purposes of our record-keeping.
I’m also going to reduce our stance on this to neutral, as an organic growth rate of 5% - which is now baked into Cavendish forecasts - doesn’t scream to me that this is a company fully benefitting from the AI trend.
As I’ve said before, there’s a ceiling on what I’d be willing to pay for a consultancy business. At the latest share price and EPS forecasts, I calculate the current-year P/E as 8x, falling to 7.6x for next year.
That does potentially offer some value, but perhaps not so much when you consider the hollowed-out balance sheet.
So for me, this is an AMBER, with the potential for us to take it back to AMBER/GREEN when there’s better news.
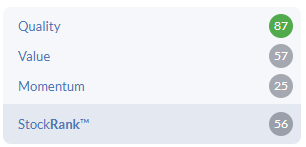
The StockRanks arrived at a neutral score before I did:
Roland's Section
Craneware (LON:CRW)
Down 24% at 1,020p (£259m) - FY26 Final Results - Roland - PROFIT WARNING (AMBER/RED =)
We’ve been on a downgrade cycle for this US-focused healthcare financial software business.
Graham cut our view to neutral in early July, when Craneware warned on profits regulatory headwinds in its 340B activities.
I followed this by cutting our view to AMBER/RED in late July, when the company suffered a cyber attack.
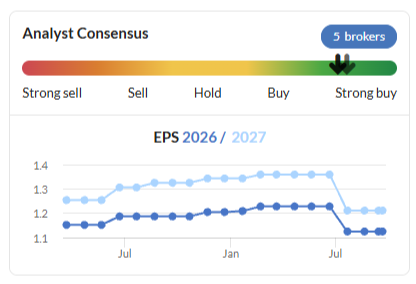
While today’s FY26 results are in line with July’s revised forecasts, management’s outlook commentary appears to include a further profit warning for FY27. Updated analyst forecasts that I can see this morning have cut FY27 EPS forecasts by 20%.
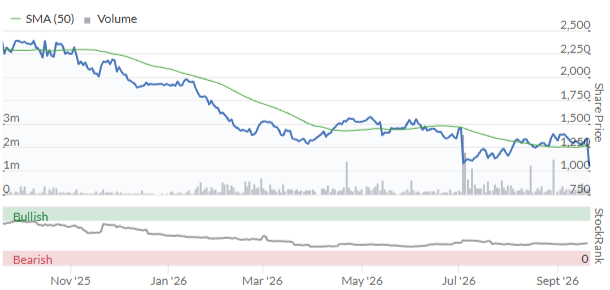
Craneware shares have now fallen by more than 50% over the last year:
FY26 results summary
Today’s results are in line with July’s revised forecasts but do not provide a very encouraging picture, with all key numbers largely flat versus last year.
These figures cover the year to 30 June 2026, so don’t include the period affected by July’s cyber attack:
Revenue unchanged at $206.0m (FY25: $205.7m)
Annual Recurring Revenue (ARR) of $185m (FY25: $184m)
Adjusted EBITDA up 3% to $67.1m
Reported pre-tax profit up 7% to $25.8m
Adjusted EPS up 0.6% to 116.8 cents
Net cash down 60% to $11.3m (following a $25m buyback)
These results need to be seen against the unexpected developments in the 340B market over the last year. 340B is a US federal scheme that allows hospitals to buy outpatient medicines at a discount for supply to low-income patients.
Craneware’s exposure to 340B increased significantly in 2021 when it acquired Sentry Data Systems for $400m ($312.5m cash & $87.5m in new CRW shares) – equivalent to a pricey 17x 2020 EBITDA.
Unfortunately the goal posts have started to move for the 340B program over the last year:
The program continues to evolve as manufacturers seek to unilaterally control the 340B program, introducing more stringent data submission requirements, and the legislature attempts to clarify regulations, proposing trialing the use of rebate-based processes rather than discounts applied at the point of purchase. Under these more stringent data requirements and rebate model, eligible US hospitals and clinics would pay a higher initial price and then submit validated transaction data to receive the 340B benefit. This would increase working capital, data, reconciliation and compliance requirements for providers.
As a result, customers have been understandably reluctant to commit new spending to Craneware’s 340B products:
While our software identified a considerable amount of available 340B opportunity for our customers in H2, and activity levels with customers remained high, the uncertainty in the market meant that this did not translate into revenue, and we did not see the expected growth in our 340B related transaction revenue as a result.
The good news seems to be that when the dust settles, the 340B program is still likely to offer an opportunity for Craneware, whose c.40% market penetration in the US makes it an important incumbent software supplier.
The company also has other irons in the fire as well and believes that AI is likely to be an opportunity rather than a risk for the business. Today’s results highlight a number of new contract wins, with an increased proportion of business with new customers:
We are pleased to see sales to new customers increase as a proportion of total new sales, to 10% from 2% a year ago, following an increased level of competitive takeouts and new wins, reflecting the increased strength of our Revenue Integrity offerings. Bringing new customers into the Group provides for further expansion opportunities that support revenue growth in future years.
Outlook & Updated Guidance
Craneware expects the 340B situation to stabilise as the year progresses, with tailwinds “expected to build in H2 FY27”. However, my impression is that the timing of any recovery is still somewhat uncertain – changes to 340B have not yet been finalised.
The impact of the recent cyber attack is expected to be a further drag on performance this year:
While the immediate impact of the security incident has been contained, the full financial outcomes are yet to be quantified, including the impact of future customer engagement.\
This sounds slightly ominous to me – will customers be reluctant to sign new contracts with Craneware due to security concerns?
Management has confirmed today that the data accessed in the attack included “Craneware employee data and a subset of customer and partner records”.
A profit warning isn’t all that surprising in the circumstances, but penalty points go to Craneware for the unnecessarily complicated wording of today’s FY27 guidance:
Therefore, while the Board remains confident in the long-term outlook for the Group and the growth opportunities, it is taking a prudent view of its revenue expectations in FY27, resetting them to the equivalent of the Company’s Annual Recurring Revenue of c.$185m.
The upshot is that revenue guidance for the year has been cut to c.$185m, 17% below previous consensus of $222m (according to the StockReport).
With thanks to Capital Access and Research Tree, I have access to updated forecasts this morning. Earnings estimates have been cut by 20%:
FY27E adj EPS: $1.00 (-20% vs $1.25 previously)
FY28E adj EPS: $1.12 (-20% vs $1.40 previously)
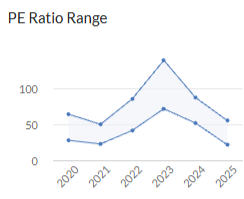
After this morning’s share price fall, these forecasts put Craneware on a FY27E P/E of 14x. That’s unusually low for this business:
Roland’s view
Craneware is a founder-led business with a large market share and a long track record. It’s an example of the type of business I often like to invest in.
However, I am generally cautious when I see multiple problems converging on a business at the same time. The reason for this is that even a well-run and strongly capitalised business (as I think Craneware probably is) can suffer in these circumstances.
The impression I get from today’s results is that earnings visibility for the year ahead could still be quite limited. I think it’s fair to assume there will be additional costs and a more difficult sales environment than usual.
Despite this, I’m inclined to keep an eye on this situation as a possible turnaround buy at some point. In my view, the valuation has fallen to a level where it could be quite interesting, while the longer-term growth prospects still seem significant.
I’m leaving our view at AMBER/RED today, but I think this is a situation that could be worthy of further research.
Anglo Asian Mining (LON:AAZ)
Up 13% at 417p (£480m) - Interim Results - Roland - AMBER ↓
I’m not surprised to see shares in this copper, gold and silver miner rising today. Leaving aside the company’s very strong financial performance in H1, AAZ has also cut full-year cost guidance for copper after costs came in below guidance in H1.
Let’s take a look.
Half-year results summary
Anglo Asian has a portfolio of mining assets in Azerbaijan. As Graham has commented previously, it’s a relatively high cost producer.
The resulting operating leverage from higher commodity prices over the last 12 months has driven a spectacular increase in profitability and cash generation. Half-year performance was also helped by the first six-month contribution from the group’s Gilar and Demirli mines:
Revenue up 245% to $114.2m
Pre-tax profit up 865% to $68.5m
Net cash of $57.7m (Dec 25: $2.6m)
Interim dividend of 6 US cents per share
An ongoing ramp-up in copper production means the red metal is expected to be the company’s primary output from 2026 onwards. Progress towards this goal was positive in H1:
Copper production up 644% to 8,840 tonnes
Gold production up 2% to 12,329 ounces
Silver production up 49% to 92,855 ounces
Half-year costs were below expectations for both gold and copper:
Gold: $1,224 per ounce
Copper: $5,158 per tonne
Outlook & Updated Guidance
The growth in copper means today’s cut to cost guidance is particularly significant – likely outweighing an expected shortfall in gold production:
Copper: full-year production guidance unchanged at 20,000 to 25,000 tones with reduced All-In-Sustaining-Cost (AISC) guidance of $6,000 to $7,000 per tonne (previously $6,800 to $7,800)
Using the mid-points of these guidance figures, I estimate this could equate to a c.$18m cost saving on copper production this year.
Gold: full-year production guidance reduced to 26,000 to 30,000 ounces (previously 28-33 koz) due to lower-than-expected recoveries in H1.
Silver: full-year production guidance of 170-210 koz is unchanged.
At current gold prices (c.$4,300/oz), this reduction to gold production could cost c.$10m in lost revenue, so perhaps c.$7m in lost operating profit, offsetting some of the additional profit expected from copper.
I don’t have access to updated broker forecasts today. But some guesstimates on my part suggest the net impact of these changes could be to lift expected 2026 operating profit by c.$10m, or perhaps c.$7m after tax.
That would equate to a c.8% upgrade to the consensus net profit figure of $90m shown on the StockReport. That’s broadly consistent with the 13% share price rise at the time of writing.
Of course, these estimates could quickly become (even more) inaccurate if gold and copper prices change significantly in either direction.
Roland’s view
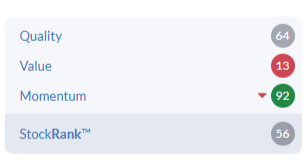
Anglo Asian shares continue to look superficially cheap, on around 6.5x forward earnings. However, this is a common characteristic of miners during periods of high commodity prices and not necessarily an indicator of fundamental value:
If prices remain high or climb further, then the bull case here could remain intact. Even so, I think it’s probably prudent to consider some of the risk factors.
Anglo Asian is quite a high cost producer, especially in copper. Although the current copper price of $14,650/t leaves ample room for profit, it’s worth remembering that the price was less than $10,000/t a year ago.
With costs running at $6,000-7,000 per tonne, a move back towards that level – for any reason – could quickly wipe out much of the company’s profit.
Political risk in Azerbaijan may also be worth considering. The company’s website notes that its current mining rights at Gedabek only extend until March 2027 and reminds us that the Azerbaijan Government “restored its sovereignty” over the Karabakh region containing the Demirli mine in 2023.
I don’t know anything about Azerbaijani politics or the company’s relationship with the local government. But I think it’s worth considering the risk that the fiscal or operating environment could become less favourable at some point in the future.
Graham was AMBER/GREEN on Anglo Asian in May, to reflect the StockRanks’ High Flyer styling.
The High Flyer styling remains, but the stock has doubled over the last six months without any corresponding increases to earnings forecasts. Indeed recently introduced broker forecasts suggest earnings could fall next year:
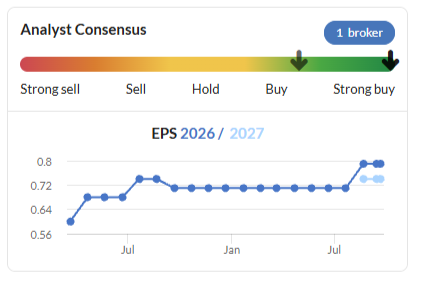
Although today’s cut to copper cost guidance has further improved the economics of the business, I would argue that any further upside here is likely to be dependent on commodity prices, making this a highly speculative situation.
While I’m not a chartist, I also wonder if the technical picture is also weakening. Volumes have fallen steadily since the stock’s re-rating in June/July:
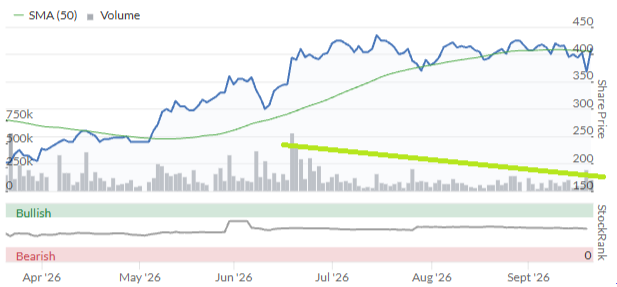
On balance, I think it’s prudent to move to a neutral view today to reflect the speculative nature of this situation. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
have held Anglo Asian Mining (LON:AAZ) since September 2018 and it is currently 33% of my portfolio. This means today has been a good day at the office.
It has had its moments (war with Armenia, dividend suspension) but overall, I have liked it as a counterweight to my other 13 holdings (mainly MAG7, Brooks Macdonald (LON:BRK) Games Workshop (LON:GAW) and Sylvania Platinum (LON:SLP)). The gain on the holding represents about a 1/4 of the value of my portfolio.
Mohammad Reza owns about 29% of the company and is very well connected politically. So, I am not worried on that front vis a vis the expiry of the concessions.
As for the price of copper my understanding is that there is a shortage in supply and that demand is likely to increase, thereby supporting the price.
I should and probably will cut my holding, but I have been saying that for a few years now. Then there would be the question of what I do with the proceeds. Answers on a postcard please.
But I continue to think that on a pe(f) of 6.5, PEG of 0.4 and a yield of around 1% (I think that will increase in the short term) Anglo Asian Mining (LON:AAZ) still strikes me as a good investment.
Regards
Michael
Anglo Asian Mining (LON:AAZ) is a strange beast. There are only 114m shares in issue, and it very rarely issues new shares - that figure has been unchanged for years. The company is 40% owned by the board, and both of the senior directors are political heavyweights (John Sununu used to be George W Bush's Chief of Staff) who have appointed their sons to senior positions in the company. In other words, it is very much run like a family company. It has no need to promote itself and so tends not to. But its AGMs are very well attended (usually there are 30-40 PIs there) and I know of 8-10 PIs who own another 10% of the company between them. In other words, the free float is very low.
They have brought 2 new mines into production in the last 12 months - Gilar and Demirli - without any dilution. They have countless other prospects but in particular a very large mine - Garadagh - due to come into production in 2028. It is true that there is jurisdictional risk. Azerbaijan is stable, but it clearly isn't as stable as Australia or Canada. Nor is it a basket case when it comes to civil violence like many African states or likely to experience sudden windfall taxes like the UK.
They have pivoted from being a gold miner to a copper producer very professionally, are building back the dividend, and have a track record of bringing new projects into production without dilution. If you think copper is at the start of its bull market rather than nearing the end of it, AAZ will do very well.
Disclaimer: this has been my largest holding for several years.
Thank you Donald. Very informative. You and I seem to have similar feelings on Anglo Asian Mining (LON:AAZ) . See my post here.
Thanks Michael - I think I bought Anglo Asian Mining (LON:AAZ) mainly in 2017, so even before you, and yes, we've been through the mill with the war and the mine suspension. But the board have always shown they are fully aligned with shareholders and the geology team, led by Stephen Westhead, is first class. They are simply a well run company with a trustworthy team, and if you are bullish on copper (which I am) they have a growing portfolio and are able to self-fund it.
Any thoughts on reviving your podcasts Donald that you did with your Scottish friend ?
I’d love to but I’m the founder of a start up that’s in the middle of a seed fundraise and it’s all hands to the pump for the next 12 months, but never say never!
Iofina (LON:IOF) H1 today looks like a textbook case of operational gearing. Its plants carry a largely fixed cost base, so much of each extra tonne of iodine produced drops to profit. Even with the iodine price flat, gross margin jumped from 22% to 33% and EBITDA doubled, helped further by a milder winter and reduced costs.
Iofina is one of those few companies on the LSE which you can continue holding long term trusting management to keep delivering.
Iofina (LON:IOF) at the interims last year the SR leapt from 72 to 94, predominantly driven by the VR & also to a lesser extent by the QR. The market failed to notice; the share price, ca.24p at the time, went nowhere until the finals at the end of April, at which point it broke out- another example of the market missing a positive change in the operating performance of the business a good few months before. The SR has drifted down since then- presumably as a result of bored holders selling out- but if you had applied the "90/80" rule to the letter then you would have been out at around the recent high at 59p- not a bad return if you can get it.
Apologies for going off topic
Zotefoams (LON:ZTF) . I've only just got round to watching their interim results presentation from last month, where the company expressed full confidence in the strategy/future.
Its interesting that neither the CEO or CFO appear to have purchased any shares in the company and hold only negligible options.
For me, although I like the business, this is the single reason why I haven't yet invested
Hi Lochinver, I think that the key management may have options under the company LTIP scheme even if they don't hold a significant number of shares right now.
Zotefoams (LON:ZTF) Thanks TS. I will have a delve into the recent accounts to check out the quantum.
Just had a look at last interims. CEO has an award of 171,000 shares under the LTIP scheme which could be doubled if the company hits its targets under the scheme ( runs to end 2028) . The CFO has 212,000 under the scheme plus another 93,000 if targets hit.
Well spotted TS. At least that means they are well incentivised to improve shareholder returns. It still would have been nice to see them put their hands in their pockets, as the rest of us are obliged to do ! When I was an FD of private equity owned manufacturing businesses in a previous life, there was an expectation that a Director would invest personally in cash an amount in the order of their annual salary. Strange that concept doesnt appear to be in place at the plc level !
Sylvania Platinum (LON:SLP) was a SR jumper on Friday so bought back in. Interested to see where this one goes.
As a medium-term holder of Sylvania Platinum (LON:SLP), with the odd topslice, its good to see. Back to 130p would be nice! Decent divis ahead too.
As a medium-term holder of Sylvania Platinum (LON:SLP), with the odd topslice, its good to see. Back to 130p would be nice! Decent divis ahead too.
Kistos Holdings (LON:KIST) SR jumped hugely into the 90s today. Any views?
Bit dated but Alyx discusses Kistos briefly in this podcast at the 22 minute mark: https://open.spotify.com/episo...
Thanks, Nurzel. That's a good spot. There's been a fair amount of institutional investment in Kistos Holdings (LON:KIST) this year, it seems and Kernow Asset Management's comment on Merryn's podcast was very positive.
Kistos
There's a rebellious cockney out there that may say there's a nice bowl forming.
The Mello show is back tonight and is a cracking line up. We have #IPO, # GTC & #TPFG presenting plus Stuart Widdowson #OIT joins us for an interview and the BASH (Buy, Avoid, Sell, Hold) rounds off the show. Lots to cover and plenty for investors to enjoy.
MelloMonday 21st September from 5pm: https://www.melloevents.com/mm210926
Use code MMSTOCKO50 for 50% off. If you are a shareholder in any of the presenting companies, you are eligible for a free ticket for this webinar with code SHMM26
Full MelloMonday agenda (subject to minor change):
5:00pm Company Presentation from IP (LON:IPO)
5:30pm Company Presentation from Property Franchise (LON:TPFG)
6:10pm Interview with Stuart Widdowson Odyssean Investment Trust (LON:OIT)
6:40pm Company Presentation from Getech (LON:GTC)
7:10pm Mello BASH (buy, avoid, sell, hold) panel with Bruce Packard covering Manolete Partners (LON:MANO) & Richard Crow aka Cockney Rebel covering James Cropper (LON:CRPR)
Hope to see you tonight. If you cannot join LIVE, please feel free to register and the recording will be distributed to you within 48 hours.
David
Manx Finance. Looks undervalued. Any thoughts on this would be much appreciated.
STCM – Steppe Cement. Does anyone else hold it or have any views? Decent yield, a 100 Stock score, and improving fundamentals.
We are long time holders grout123, at last on profit and watching this rally with interest. It's been covered well in discussions recently which you're probably aware of.
With a market cap of £4.96 million I'm not surprised Getech isn't on the Agenda but if anyone here follows penny shares it might be worth reading their HY results today. We are long term holders who should have taken the loss years ago but there are definite signs of life here with growing ARR, positive EBITDA, revenue up 22% and enjoying positive trading momentum.
And you forgot the most exciting recent development at Getech (LON:GTC) ... a potential trade bidder has popped up on the share register! Having bought at like c3p per share I believe?
We bought a few more this morning The Boon Fund, I would think their patents on the Globe for example could be worth more than the current market cap. good luck with your holding, you'll see profit well before we do!
I haven't done the maths The Boon Fund but three individual investors bought in August 2.1 million shares, 1.8 million and 1.4 million. I misread your comment as you being a holder!
Sadly I was dithering on the buy button on Getech (LON:GTC). Thought 2.14p was a bit too high to buy, so waited..... Lesson learnt!
Will be analysing these fresh numbers to see if it makes sense to buy now. I do like the medium term story here.
Looks like a warning from Craneware (LON:CRW) on 2027 revenues to me. Thoughts from Graham et al would be welcome.
I'm afraid it just goes to show how misguided the Board's use of the term "the proposal fundamentally undervalues the company and its prospects" was when Bain proposed a 2650p bid just over a year ago! Shares now more than 60% below that level. Pretty sure the advisers won't be refunding their fees.
Elixrr if you have time pls team
Not sure what this company has to do to impress the market - down over 10% today
Peel Hunt downgraded from Buy to Reduce, cut EPS forecast by 7% and target price moved from 1,100p to 570p due to slowing organic growth to 5% and execution risk re buy and build strategy.
Thank you! Good to know what’s driving this madness.
I can’t justify their figure, without ignoring other financials or completely undermining the management (which are one of the key strengths for me). Looks like an opportunity.
Elixirr International (LON:ELIX) Not sure if the sell off today is justified or not. But perhaps the Peel Hunt downgrade was timed to cause max pain. They were the house broker before basically being fired (Hired in Jan 2025 and let go in August 2026 being replaced by Canccord). Now at the first opportunity Peel Hunt have released a rather aggressive downgrade - would they be saying this if they were still the house broker?
The outlook statement isn’t great either ‘revenue broadly in line’
Well, i am out, took a large haircut here, lessons to be learned
Elixirr International (LON:ELIX)
I put these on my watch list on friday. Took them off today !
There is something else going on here. ....17% down on a 2-4% PBT cut does not make sense. Bad comms in the results release as well. Bad guidance. Who advises these people?!
I'm a holder, my initial reaction was to buy some more until I looked a bit more deeply into the interims. Personally didn't like the trajectory of cash, which for me is one of the most important things in a business like this. It looks like they're trying to buy growth without controlling spending, at the moment it doesn't look out of control but it could easily go that way if they don't take a step back. For the moment I'm holding, still think it's fairly cheap on a risk / profit basis. Not that bothered about minor changes in profit forecasts, frankly the difference is effectively lost in rounding, but if debt continues to rise in any significant manner then I'll probably sell.
Quite a bit to unpack with the proft warning from Craneware (LON:CRW) ! Cyber attack potential regulatory liability, why sales are slowing down so much, and the 340B uncertainty.
Also a profit warning from Accsys Technologies (LON:AXS) . Big u-turn from a year or two ago of "It is a supply constraint issue not a demand issue... to increase sales" to now having reached the supply/demand equilibrium? Which leaves the high rating very exposed.
Accsys Technologies (LON:AXS) Another jam tomorrow story - its never made a profit yet has a momentum score of 72 and overall of 51 - should be way down with a red marker