Daily Stock Market Report (Mon 23 Dec 2024) - DLG/AV, BOO/FRAS, SEE, QUIZ

Good morning! News flow remains very limited and so I will attempt to wrap up this report quickly, as I did on Friday!
Podcast: in case you missed it, our weekly podcast was published by Lawrence on Friday.
You can find Takeovers, £100m whisky, and decoding stock market jargon on:
11am: as there is no other earth-shattering news today, I'll wrap this up here. The daily report will be published tomorrow, but not by me, so let me take this opportunity to wish you all a very pleasant Christmas break. All the best!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet). Updated to 19/12/2024.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Direct Line Insurance (LON:DLG) (£3.2bn) | Offer for DLG | The preliminary agreement (6th Dec) becomes a recommended cash and share offer worth 275p. | PINK (Graham) |
Boohoo (LON:BOO) (£463m) | Results of General Meeting, Sale of London Office | Mike Ashley and his colleague fail to join the Boohoo board. Boohoo sells its London office for £49.5m. | RED (Graham) |
Seeing Machines (LON:SEE) (£184m) | £26m strategic investment from Mitsubishi | Collaboration agreement includes £26m subscription. Mitsubishi to have a 19.9% holding. | AMBER (Graham) |
Quiz (LON:QUIZ) (£3m) | Proposed cancellation of trading on AIM | 67% of shares already support a delisting, as benefits of being listed no longer outweigh the cost. | RED (Graham) [no section below. Needs more funding and therefore existing equity looks close to worthless.] Down 57%. |
Direct Line Insurance (LON:DLG)
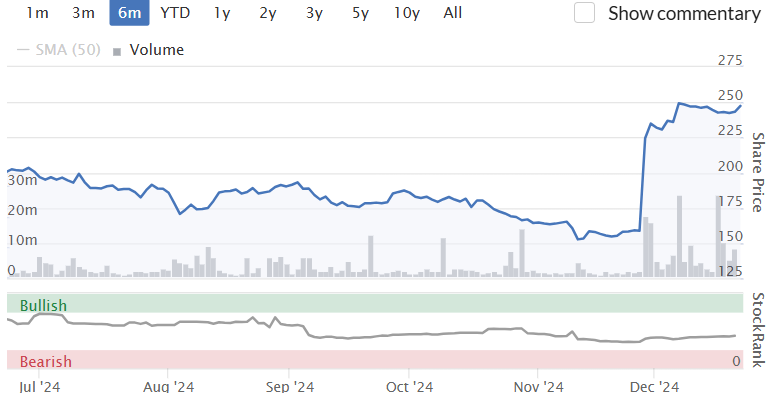
Up 3% to 251p (£3.2bn) - Offer for Direct Line Insurance Group - Graham - PINK
Aviva (LON:AV.) and Direct Line have firmed up their preliminary agreement in time for Christmas. Today we have the formal announcement of an offer worth 275p, nearly half of which is in cash and the rest comes in the form of Aviva shares. The proposal is at an enormous 73% premium to the undisturbed price at which DLG shares were trading before we learned that Aviva was interested.
An interesting context for the deal is that Aviva’s former CEO of UK & Ireland General Insurance, Adam Winslow, left Aviva to become the new DLG CEO this year.
Before long he had stolen two of his former Aviva colleagues to become DLG’s new CFO and Chief Risk Officer.
Media reports suggest that Mr. Winslow privately attempted to persuade DLG investors to give him more time to turn things around, rather than accepting Aviva's bid. We noted earlier this month that the recommendation from DLG to accept Aviva’s offer seemed to come only after shareholders were consulted on their views.
The reunion of former colleagues who jumped ship may be slightly awkward but I doubt that DLG shareholders will be worrying too much about that.
Boohoo (LON:BOO)
Unch. at 33p (£462m) - Frasers notes outcome of boohoo shareholder vote / Sale of London Office - Graham - RED
The Boohoo board won the contest at the general meeting held on Friday, as both Mike Ashley and his insolvency expert failed to win board seats. It wasn’t particularly close in the end as nearly 64% of votes went against Ashley & co. Ashley went into the event facing some tough obstacles including rejection by both the existing Boohoo board and the main proxy advisory services.
Today, Frasers (LON:FRAS) says that it “respects the views of the independent shareholders”, but that it will take up Boohoo’s invitation to propose another Board candidate. So the drama will continue. But I think Boohoo’s position on this is reasonable - as Frasers is their largest shareholder (25%), they are right to offer Frasers one board seat. But I don’t think they should feel under any obligation to accept Mike Ashley as the candidate.
Remember that Frasers officially operates under the claim that Ashley “has no day-to-day involvement or responsibility for the strategic direction of the Group or any Board matters”. If that was believable and true, then why should he represent Frasers on the Boohoo board?
In other news, Boohoo has sold its office in Soho for £49.5m. This lets it pay down its term loan in full and leaves it with a £125m RCF which it says “is sufficient for its needs going forward”. After this latest action to address the company’s net debt, I’m open to the possibility that I may need to upgrade this one to AMBER/RED - but not yet.
Seeing Machines (LON:SEE)
Up 8% to 4.8p (£204m) - £26.2m strategic investment from Mitsubishi - Graham - AMBER
I was a sceptical voice on this one for a long time, and I think it was the right call as the company has remained loss-making, its share count is up, and the share price has made little long-term progress.

Today, it has announced a collaboration with Mitsubishi Electric Mobility, a subsidiary of Mitsubishi Electric, to “pursue joint growth opportunities” in driver and occupant monitoring systems (DMS/OMS). As part of the agreement, Mitsubishi invests £26m in SEE at a price of 4.09p.
SEE touts this price as being “at a premium of 12% to the 30-day VWAP” (volume weighted average price) but I think they should also have conceded that it’s an 8% discount to Friday’s close. There’s no mention of that anywhere in the RNS. It means dilution of 15% for existing shareholders.
I continue to view this as a “jam-tomorrow” share and I dislike how it communicates with investors. For example, take its full-year results announcement to the stock exchange this year. Instead of giving this a normal title such as “Final Results”, like every other company, the RNS was titled “Global regulatory momentum drives revenue growth”. Revenues did indeed grow by 17%, but the EBITDA loss nearly doubled.
Paul was AMBER/GREEN on this and the tie-up with Mitsubishi does add credibility to the story, so I’m not going to follow my instincts and take this all the way down to a negative stance straight away. Neutral for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
As we approach Christmas and a new year, I would just like to comment about two balancing areas; holidays and carpets. The current score in football parlance is overseas hols 30, new carpets nil. In all the comments in detail I have read on these sectors over the last many months, I have never seen that bald statement clearly made. It makes complete sense. So many family havent had a hol abroad for years, and on the other hand, you can live with the carpets you have for quite a long time, and there is very little new residential build to support that market.
Recently, the biggest carpet share, Headlam (LON:HEAD) has made a small recovery but only by selling the family silver, albeit to a profit versus balance sheet valuation. Surprise, surprise.
Where have most of the new wage increases following Labour's great victory gone? My guess is all inclusive foreign hols have been the magnet - On Beach group (LON:OTB), Jet2 (LON:JET2), Tui Ag (LON:TUID), easyJet (LON:EZJ) all reporting buoyant business- which wont do much for the UK's growth figures etc.
How many years will this pattern last? Cant see carpets recovering until well into the big Labour's building programme, and the timing for that is disappearing into the mist -'by the end of the parliament'!
As interesting is what will the holiday company's performance at this time next year, versus the 'tough competitors' that this year is building. Cockney Rebel seems to think On Beach group (LON:OTB) will double by this time next year. That's a big call. and will make the calendar 26 forecast even more interesting!
Just a few thoughts. Happy Christmas, and a very interesting new year to all. Looking forward to trawling through everyone's great tips for 25.
Could we have a post from the team discussing UK listed stocks most exposed to the USA and in particular the changes Trump will likely bring?
Think that would be very useful, especially pre his inauguration.
Thanks!
Could we have a post from the team discussing UK listed stocks most exposed to the USA and in particular the changes Trump will likely bring?
If that’s what you want to see, then write it and post it. I’m sure there will be willing contributors. Personally, I think it is mostly noise, and just a little bit of signal. It’s not possible to manufacture, for example, cheap but decent quality cosmetics in the US at anything like the cost achievable in China or Southeast Asia. So all that tariffs on such products will achieve is to stoke inflation without reshoring any jobs. And inflation will cost Trump his job. He knows this.
I think it's an exaggeration to say that inflation will cost Trump his job. He's in for 4 years, impeachment permitting, and no president is allowed to serve more than two terms. Which is not to say that I disagree with the rest of your comments.
Great podcast not concentrated on the commentators buys/sells and their biggest holdings. An informative podcast for the week’s events and to be honest I never thought I will enjoy an English market podcast like I enjoy the US ones (On the Tape Podcast, Acquirers Podcast).
Keep it up.
All the best
Hi Yiannos - really good to hear you enjoyed it!
Markets trying to rally, could be another damp squib.
Merry Xmas to all!
Boohoo (LON:BOO)
Sells its London offices for £49.5m but they forget to mention how much they have bought this and the big loss incurred. Boohoo (LON:BOO) has always been a very bad run company for the benefit of the family involved.
This sale is a big worry for shares like Osb (LON:OSB) and one should have a proper look on how they evaluate their stage1, stage2 and stage3 loans. Osb (LON:OSB) is a big concern and I am amazed this has not fallen today.
All the best
Not sure why there would be much (or any) read across to OSB - nearly all their loans are residential properties to professional BTL investors. Valuations should be pretty accurate here. I don't think they have much exposure to large offices.
Osb (LON:OSB)
Not al all.
If you have the knowledge and expertise on how loans should be evaluated, have a proper and extensive research on how they report their COMMERCIAL MORTGAGES and how other major banks do it. This is destined for a big fall. Their stage loans reporting does not make any sense.
All the best
OSB - Commercial property only makes up 4% of their loan book according to the last accounts - therefore I can't see how this exposure could have a significant impact. For full disclosure, I do not currently hold OSB, but that's mainly because the share price is incredibly volatile and been known to crater 25-30% on relatively minor newsflow. Would probably look to get back in at the 350-360p level.
Have a look at the different stage loans and how these are structured and showed in their accounts.
Also explain to me why the difference for example the HSBC Holdings (NYQ:HSBC) ones?
Also explain the credit impairments in a bad economy!
I definitely do not hold and I do not short shares.
This will go down.
All the best
Isn't HSBC a very different situation? OSB is almost entirely BTL to professional landlords with loans secured against the properties, and subsequently incredibly low default rates.
Osb (LON:OSB)
Yes it is in some ways!
But I am talking about the difference in the stages : from 2 to stage 3 loans. Osb (LON:OSB) are showing about £5B in stage 2 loans but only AT THE MOMENT a figure of £200m in stage 3.
Bonkers accounting.
All the best
OSB could perhaps help reduce volatility with a little more information about key metrics such as the net interest margin.
In March this was 251 bps and forecast to be stable. In November, this had appeared to slip to 230/240 .
In the meantime Paragon had reported a slight increase to 316bps - quite a difference from OSB.
Also they need to define "professional" when referring to Landlords. Does this mean the Landlord is full time, or holds a certain number of properties, or something else?
Instinct tells me to be careful here - especially if the sector takes a hit.
Dont hold
Osb (LON:OSB)
Thanks intuitive6191 for explaining some more details.
No need to discus this further. I always try to comment after hours of research. If commentators on this thread do not want to acknowledge the fact that this is a company with a loan book of £24B showing an increase in stage3 of only £200m, that’s fine by me!
All the best
Osb (LON:OSB)
"a loan book of £24B showing an increase in stage3 of only £200m"
Stage 3 % of the loan book (3.6%) is higher relative to what I can see from previous years e.g. it was 3.1% and 2.3% in 2018 and 2019 respectively.
For context the Stage 3 Loan % for Paragon Banking (LON:PAG) (on their Mortgage Loan Book only) is currently 1.35%.
Osb (LON:OSB) Paragon Banking (LON:PAG)
Hi intuitive6191
OSB NIM for H1 was 2.37%.
Paragon's NIM at their year end (September) on their Mortgage Loan Book only was 2.15%
For completeness Paragon's NIM at their year end (September) on their Commercial Loan Book only was 5.86% (which explains the overall 3.16% NIM that you mentioned), but I don't think it makes sense to look at this if we're comparing with OSB.
Deleted.
What are you on about?
Honestly guys!
Hold OSB at moment and just interested how stage one, two and three loans will impact them, never heard the terms before, calafornian is it?
Hold OSB at moment and just interested how stage one, two and three loans will impact them, never heard the terms before, calafornian is it?
It's IFRS 9.
https://www.bis.org/fsi/fsisum...
timarr
Yiannos,
I believe they bought the office for appox. £72m three years ago.
A great piece of business by them!
I would also be a little wary of OSB. When I last looked they appaered to be putting any second charge business into run off which would de-risk the loan book - but its a business sector which I think might have problems ahead.
Osb (LON:OSB)
They are boosting their earnings by registering credit impairments!
Good luck to all shareholders.
All the best
Osb (LON:OSB)
"They are boosting their earnings by registering credit impairments!"
Does this refer to the one-off £5.2m credit booked in H1?
I agree that it looks off, but in fairness they rationalise this in the H1 report:
"The impairment credit was due to updated macroeconomic scenarios, particularly house price improvement."
I think it's fair to challenge this explanation, but it could make sense as Osb (LON:OSB) booked much higher impairment charges in the prior 2 years (£30m and £50m respectively). Perhaps they were previously over-conservative and they are now simply clawing back some prior provisions?
When a serial loss making jam tomorrow stock trading at 5% of its all time high makes a product sale announcement the audience here is entitled to be underwhelmed. But it is just possible that something big may now (at last) be happening to ITM Power (LON:ITM) .
The announcement today is for 3 Neptune V electrolysers which have a stated price of £4.3mm each, for a company projecting £28mm for the year to April 25 this is not trivial and follows bigger orders noted recently. Losses are still projected ( although forecasted at a slightly lower level), but with £200mm in cash they are well set to be able to afford what looks like, and is projected to be, a real ramp up in sales. Directors made some useful share buys in October and there is still time to see how things roll out, but I am putting this firmly on my watch list .
I don't understand the ITM Power (LON:ITM) comment of 'trading at 5% of its all time high'. It has traded at over £6, did you mean all time low?
It’s all time high was about £7. 5% of its all time high is 35p - which is where it is now.
Thanks for clarifying. Thought you meant it was just 5% below it's all time high, ha ha
Been out celebrating have we?
Yeah, it's that time of year.
From someone who is apolitical.
Perhaps, just perhaps the democratic pendulum is starting to swing in a positive direction
The loathsome Assad regime is gone. Hopefully the west will support, but not interfere in Syria’s rebuilding and move towards financial and political stability.
Democracy has prevailed in South Korea with the removal of Marshall Law and impeachment of the president.
Hopefully 2025 will see a resolution of the Ukraine conflict and peace in the Middle East. Naïve perhaps. Donald Trump is not on my Christmas list, but he is unpredictable and one never knows what he might do?
We will certainly be shaken in 2025 with the volatility Trump carries with him!
All the best
Trump will try and possibly succeed in dismantling democracy in the US.
And how exactly will he do that?
Democracy in Chains - Nancy MacLean. It's quite heavy going, but worth a read
Stealth War - by Robert Spalding, Ray Porter, et al. Not so heavy and easily understood.
he'd need to take America's god, guns n' guts away first - can't see that happening ;-)
All I want for Christmas is
- a Santa rally
- UK to return to growth
- peace on earth (but let me know when, so I can sell my defence stocks first)
There is an interesting interview in the Daily Telegraph with Sir Don Mccullin yesterday and he is extremely pessimistic about the future of Syria. Given his 60-year coverage of wars, sadly I can imagine his assessment will be correct.
As for vice president elect Trump ... who knows, but the tea leafs do not look good. Maybe Mandy with the assistance of Farage will sort everything out with President Musk?
I do like how the press are quoting "President Musk" to wind the old goat up.
Yes Farage will save the planet and solve all problems!
I have just seen that on 19 December, Smith & Nephew (LON:SN.) CFO John Rogers bought around £700k worth of stock. That's a large insider buy. (I hold)
For those interested in Smith & Nephew, I came across this snippet recently - where Michael Ulrich (J Hambro Asset Management) discussed the company and its prospects - as viewed in May this year - with Paul Hill :
https://www.stockopedia.com/co...
This big director purchase (thanks for pointing this out, Edward) shows that someone believes this giant will awake from its slumbers...
Also prescient was Michael's comment that National Grid (NG.) wad probably paying too much out in dividends as it needed tons for capital investment : this was May 20th. Three days later, a major 2 for 7 rights issue was announced for just this purpose - underlined by NG's announcement this week.
Enjoyed the podcast published Friday last week - particularly as centered around three different themes rather than just company results (life blood as they are).
Enjoy the break all.
Geoff
Hi Geoff - thanks for the kind words on the pod, I'm keen to make sure we're adding something of a unique perspective on the week!
On Stocko the operating margin for 2023 & TTM (I am ignoring the COVID years 2020-2022 as presumably it was affected by reduced elective surgical activity) is significantly down on 2018 & 2019. Why is that? I haven't researched before but if it can meet the 2025 broker estimates I appreciate this could look cheap for what's been regarded as a quality stock.
NAHL (LON:NAH) confirm that in final discussions with multiple bidders for their critical care business
Interesting development with Seeing Machines (LON:SEE) following an investment of £26.2m investment by Mitsubishi representing 15% holding bring its total holding to just over 19%.
Are we now finally going to see improved shareholder value over the next 5 years?
Tin hats on! UK economy heading for 'worst of all worlds'
https://news.sky.com/story/uk-...
Great podcast last week, the sound volume has been fixed and I could listen to it without changing the volume every time Lawrence or Graham talked
Thank you - really glad you enjoyed it!