Daily Stock Market Report (Mon 27 Jan 2025) - SMWH, GOOD, VLX, COST, SRAD, DOCS

Good morning!
It's another positive set of announcements with lots of updates but possibly no profit warnings, with everything either in line or ahead of expectations. This happened several times last week, too. [EDIT: we also have another takeover offer!]
Could it be that economic worries, for the time being at least, have been fully priced into consensus forecasts for most companies?
I doubt this will last come April and the planned tax increases, but let's enjoy it while it lasts!
With the markets we cover arguably offering both a) historically cheap valuations, and b) forecasts that almost all companies are now able to meet or beat, surely the outlook for overall performance can't be bad!
11.30am: wrapping it up there for now, thank you.
Spreadsheet accompanying this report (updated to 17/1/2025)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Johnson Matthey (LON:JMAT) (£2.3bn) | Strategy update | Maintaining focus on PGM, scaling back hydrogen tech, committee to consider capital allocation. | |
WH Smith (LON:SMWH) (£1.5bn) | Response to press speculation | Confirms w/end press reports that the company is exploring options to sell its High Street business. | AMBER/GREEN (Graham) A positive announcement as this is primarily a travel business now. |
Dr Martens (LON:DOCS) (£704m) | Q3 TU | Q3 trading was as expected and FY25 outlook is unchanged. Q3 revenue +3% at constant FX. | AMBER/RED (Graham) Upgrading this as a recovery now seems more achievable although debt and inventories may remain challenging. |
Volex (LON:VLX) (£521m) | TU | 9M revenue up 21.8% to $789m, inc 9.6% org growth. FY profit exps remain in line with forecasts. | GREEN (Roland) |
Pensionbee (LON:PBEE) (£373m) | AUM update | AUA has reached “over £6 billion” representing >265k customers. | |
Costain (LON:COST) (£231m) | TU | FY24 in line (adj. op profit £41.9 - 43.4m, net cash £160m. “Forward work” rises by £1.5bn to £5.4bn. | GREEN (Graham) Very impressive growth in the forward work position. If they execute this at expected margins then shareholders should do well. |
Stelrad (LON:SRAD) (£180m) | TU | 2024 revenue -6% to £290m, but adj op profit marginally ahead of exps at c.£31.5m. | AMBER/GREEN (Roland) |
Genel Energy (LON:GENL) (£175m) | Trading & Operations update | FY24 free cash flow of $19m and net cash $131m. FY25 cash gen expected to cover org costs. | |
Concurrent Technologies (LON:CNC) (£152m) | £3.4m contract award | “Significant order” for VME-based 6u boards from existing European customer, delivered 2025-27. | |
Good Energy (LON:GOOD) (£73m) | Recommended cash takeover at 490p | Cash offer at 24% premium to Friday’s close. Buyer is energy transition tech group Esyasoft. | PINK (Roland) |
Synectics (LON:SNX) (£57m) | $2.2m contract award | Synergy upgrade and expansion at a major gaming resort in SE Asia, delivery in current financial year. | |
PCI- PAL (LON:PCIP) (£51m) | TU | H1 revenue up 26% (up 13% normalised) and in line. ARR up 21% year-on-year to £16.8m. | |
Renalytix (LON:RENX) (£37m) | TU | On track to deliver expectations for FY26 and FY26, which assume average 20% quarterly growth. | |
Lendinvest (LON:LINV) (£33m) | FUM update | FUM crosses over $5bn, after a series of major funding uplifts. | |
Brave Bison (LON:BBSN) (£28m) | TU | FY24 adj. PBT £3.9m ahead of exps (£3.7m). Board “remains comfortable” with FY25 forecasts. | |
Fadel Partners (LON:FADL) (£13m) | FY24 TU& FY25 outlook | FY24 rev/LBITDA in line? Net cash $2.4m ahead of exps. O/look: big improvement in LBITDA. |
Graham's Section
WH Smith (LON:SMWH)
£11.48 (pre-market) (£1.49bn) - Response to press speculation - Graham - AMBER/GREEN
A brief acknowledgement from WH Smith:
WH Smith PLC ("WHSmith", or the "Group") notes the recent press speculation regarding its High Street business.
WHSmith confirms that it is exploring potential strategic options for this profitable and cash generative part of the Group, including a possible sale.
Over the past decade, WHSmith has become a focused global travel retailer. The Group's Travel business has over 1,200 stores across 32 countries, and three-quarters of the Group's revenue and 85% of its trading profit comes from the Travel business.
Sky News had the scoop, revealing on Saturday that the company was in secret (not for long!) talks to sell its entire high street business. According to Sky, SMWH “has been in negotiations with a number of prospective buyers for several weeks”.
Graham’s view: I’ve always had a fairly positive impression of SMWH and I think that the disposal of its High Street business could only improve its quality. I expect that most investors would share this view, as High Street competition is considered to be intense while airport competition is much less so.
Checking the most recent annual results, I see that most of SMWH’s official “debt” is the the form of leases; debt excluding leases is a more modest £370m, which looks manageable against adj. PBT of £166m.
In any case, a sale of the High Street business could be expected to wipe out that debt.
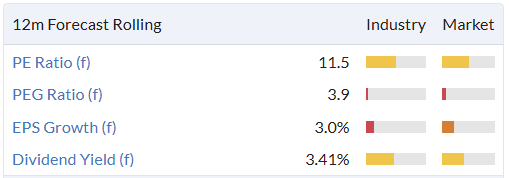
I’ll take an AMBER/GREEN stance on this as I see today’s announcement as positive news from a stock I’ve always liked. Valuation is not outrageous:
Costain (LON:COST)
Up 6% to 90.9p (£244m) - Trading Update with Strong Forward Work Position - Graham - GREEN
A nice full-year update from this contractor:
Trading for FY 24 has been positive with Group adjusted operating profit expected to be in line with market expectations and net cash at the end of the year in line with market consensus.
Consensus figures: adj. operating profit £41.9 - 43.3m, net cash £160m.
The stand-out figure provided is the £1.5bn year-on-year increase in the company’s “high-quality forward work position”, to £5.4bn.
This is not exactly the same thing as the order book. The definition:
Forward work is the total of order book and preferred bidder book which includes revenue from contracts which are partially or fully unsatisfied and probable revenue from Water and other frameworks included at allocated volume.
Including the “preferred bidder book” within this metric means including projects there is an increased risk of delay and possibly some uncertainty over the final price, as my understanding is that negotiations may not have been fully concluded. But these are projects where Costain has been selected and should get the job.
Having said that, £1.5bn is still a huge year-on-year increase. Annual revenues are only around £1.3bn, so more than an entire year’s worth of revenues have been added on.
Graham’s view
As we’ve said before, contractor businesses are problematic for investors due to the small and vulnerable profit margins they generate.
Costain today says that it has “increasing confidence in its ability to deliver further growth in operating profits and margins”, as it works towards its >5% operating margin target.
It is expected to generate a run-rate margin of 3.5% in FY24 and then a run-rate margin of 4.5% in FY25.
The most recent balance sheet was strong (net assets £230m, although this includes £48m of intangibles and a £55m pension surplus). It has been carrying out a £10m share buyback due to a strong cash position.
All things considered, I’m inclined to leave our GREEN stance unchanged. The shares are cheaply priced if you think the company is likely to make further progress on margins.
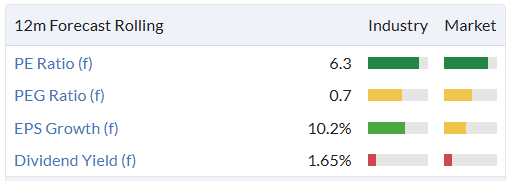
I also note a StockRank of 97.
Let me just emphasise that I don’t view any stock in this sector as offering much in terms of quality. But if I did have to invest in this sector I’d make sure I picked something that offered a strong balance sheet, a management team who placed great emphasis on improving and maintaining their profit margins, and a cheap earnings multiple.
COST offers all of these, so I’ll stay GREEN. Let’s hope that they stay disciplined as they execute the projects in their much-enlarged “forward work” position.
Dr Martens (LON:DOCS)
Down 3% to 70.4p (£679m) - Graham - Q3 FY25 Trading Statement - AMBER/RED
It’s an in line update from Dr. Martens that leaves the FY March 2025 guidance unchanged.
Headlines (everything is measured at constant FX rates except where mentioned otherwise):
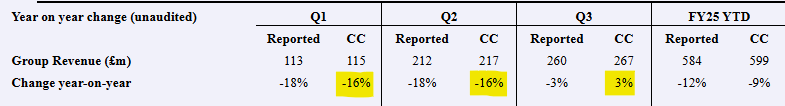
Q3 revenue +3% to £267m (or down 3% at actual FX rates)
Wholesale revenue up 9%, but direct-to-consumer revenue only up 1%
Within direct-to-consumer, e-commerce grew 2% while retail revenue fell 1%.
Direct-to-consumer revenue grew very well in APAC (+17%). Americas was up 4% while Europe/Middle East/Africa fell by 5%, “impacted by the deep promotional nature of several markets, especially in December”.
Dr. Martens are currently running an end of season sale. Paul previously (e.g. here) flagged the company’s very high inventories as a problem; the company today says they are ON Semiconductor (NSQ:ON) track to meet our inventory reduction target for FY25@
Here’s a summary table. Q1 and Q2 were very poor year-on-year, but Q3 has greatly helped the year-to-date performance:
Estimates: this stock is covered by 7 brokers although none of them are currently posting research for this company on Research Tree.
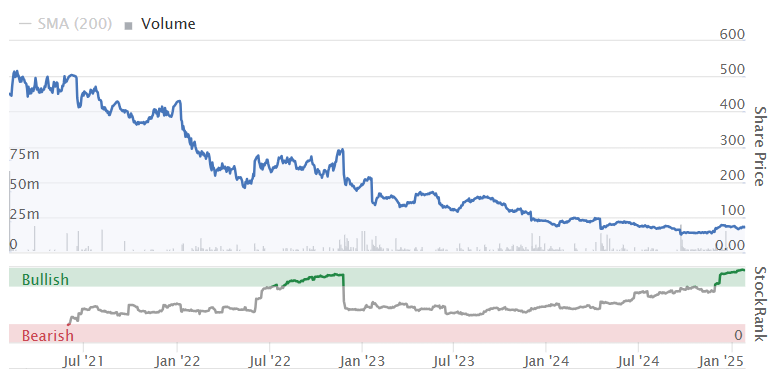
Dr. Martens was supposed to be a much more influential stock, having originally achieved a valuation of £3.7bn at its IPO price (370p) and quickly racing higher to over 500p, before reversing.
It has now become one of the best examples of a 2021 IPO flop.
Consensus forecasts suggest revenue for this year (FY March 2025) of £818m and net profit of £28.8m.
Graham’s view: I’m happy to upgrade this to AMBER/RED on the basis that the company reduced its inventory by £69m (year-on-year) according to the interim results, published in November. Inventory fell from £314m (Sep 2023) to £245m (Sep 2024). With another season finished and an end-of-season sale, I’m expecting more progress on this front by the full-year results.
Net debt is also a concern with the company publishing a leverage multiple of 2.3x at the end of H1. The company did not provide an update on that in today’s announcement, but we can presume there is no change in the outlook there.
Overall, it’s not a pretty picture but the company did enjoy a period of bumper profits immediately before and after its IPO. To reflect the possibility that it achieves some form of recovery, I think I have to upgrade it today, although personally I would not yet be tempted to buy in.
Roland's Section
Good Energy (LON:GOOD)
395p (pre-market) (£73m) - Recommended Cash Acquisition - Roland - PINK (takeover)
This fast-growing energy supply and services group first disclosed takeover interest on 28 October 2024. Today we have the outcome – Good Energy has received a 490p per share cash offer from energy transition technology specialist Esyasoft Holding Limited.
This offer values the business at £99.4m and is being recommended by the board. It represents a 66% premium to the closing price on 25 October 2024 and a 24% premium to Friday’s close. I think it’s likely to proceed unless a competing buyer emerges.
The valuation represents a multiple of 18x 2024 forecast earnings and 11x 2025 forecast earnings.
The high multiple of 2024 earnings reflects its current dependence on profits from low-margin energy supply.
Good Energy is in the process of switching its strategy to focus on high-margin energy services, using an acquisitive approach. Services generated an operating loss of £2.2m in H1 2024, but the profit contribution from services is expected to outweigh energy supply in 2026.
Depending on your point of view, Esyasoft is paying a high price for the legacy business or a low price for the faster-growing but currently less profitable services business.
On balance, I think today’s offer looks reasonable, given the risks of the group’s acquisitive growth strategy and its current dependency on a slow-growing energy supply business.
While some shareholders may be disappointed, I think it’s worth remembering that this offer provides a guaranteed profit and removes the risk of disappointment if the services transition doesn’t go smoothly.
Volex (LON:VLX)
Up 0.5% 284p (£524m) - Trading Update - Roland - GREEN
Today’s trading update from this AIM-listed cabling specialist (“integrated manufacturer of critical power and data transmission products”) covers the 39 weeks ended 29 December 2024.
The Group's underlying operating profit expectations for the full year remain unchanged and are in line with market forecasts.
Trading summary: Volex says that revenue for the financial year to date rose by 21.8% to $789.4m. Within this, 9.6% was organic growth while 13.1% was contributed by acquisitions. Foreign exchange had “a small adverse impact”.
The company separates its business into five customer segments:
Electric Vehicles: demand is driving “significant organic growth”
Consumer Electricals: “continued to perform strongly”
Medical: softened slightly, normalising from a strong comparative last year
Complex Industrial Technology: improved relative to first half
Off-Highway: growth rates normalised with some markets showing “subdued demand”
The breadth of Volex’s customer base is in part a reflection of its regular acquisition activity, which has driven more than half its revenue growth over the last nine months.
Operating profit margins are said to be “within our target range” of 9%-10%.
Net debt at the end of the quarter was $151m excluding lease liabilities, representing 1.3x EBITDA, unchanged from H1.
Growth investments have continued, adding capacity in countries including India and Indonesia during the year. The company also reports recent increased demand from a major data centre customer in North America.
Outlook: the company says its confident customer demand will sustain “high single-digit organic growth for the full year” while maintaining margins in their target range.
Volex expects to report underlying operating profit in line with current market expectations. These are helpfully included in the footnotes to today' s release – the averages provided are:
Revenue: $1,031.4m
Underlying operating profit: $96.7m
These estimates price the shares on a forward P/E of 11 and would represent growth of 13.0% and 7.8% respectively versus FY24 results. This suggests slightly lower margins versus last year’s figure of 9.8%.
Roland’s view
Executive Chairman (and 25% shareholder) Nat Rothschild appears to be continuing to deliver attractive growth at reasonable margins.
This business is relatively capital intensive, so quality metrics are only modestly above average:
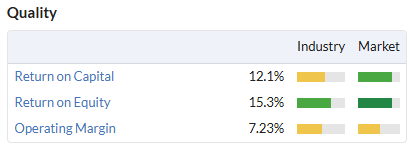
For this reason I wouldn’t personally want to pay a high multiple. However, Volex operates in a number of attractive long-term growth segments and seems to be performing well.
The current valuation looks very reasonable to me. I’m happy to maintain our GREEN view.
Stelrad (LON:SRAD)
Unch. at 142p (£181m) - Trading Update - Roland - AMBER/GREEN
the Board expects to deliver an adjusted operating profit of c.£31.5m, marginally ahead of expectations
Stelrad is a leading manufacturer of central heating radiators in the UK, Europe and Turkey. This business was one of the class of 2021 IPOs, but unlike many flotations from that year has subsequently proved to be a decent business.
Today’s full-year update appears to be slightly ahead of expectations and contains some points I think are worth highlighting.
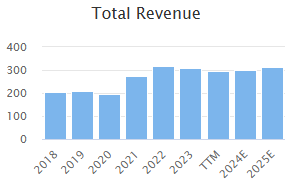
Trading update: Stelrad says revenue fell by 9% to c.£290m last year as “ongoing high interest rates and inflation” held back activity in both new build and RMI markets (repair, maintenance and improvement).
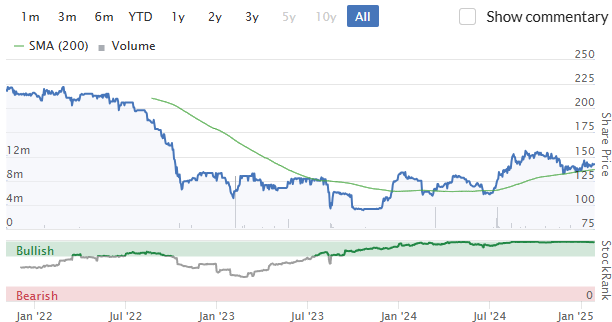
As a result, full-year revenue fell by 6% to c. £290m. Although H2 volumes benefited from some new business wins, overall volumes remained below 2023 levels. Indeed, revenue peaked in 2022:
However, while volumes were down, profitability rose sharply. Stelrad says it achieved an 11% increase in contribution (profit) per radiator during the year. This was achieved through “proactive margin and cost management” but also due to “the price benefit of further increases in average radiator size”.
Impressively, in my view, Stelrad says this is the seventh consecutive annual increase in contribution per radiator.
It’s because of this that the company expects to report an adjusted operating profit of c.£31.5m (2023: £29.3m) at an operating margin of 10.8% (2023: 9.5%).
Outlook: no broker forecasts are available on Research Tree for Stelrad but consensus forecasts on Stockopedia prior to today suggested 2024 earnings of 12.6p per share. I suspect the impact of today’s upgrade will be relatively small, so I’d estimate an updated figure of c.13p, pricing the shares on 11x 2024 earnings.
There’s also a useful 5.4% dividend yield:
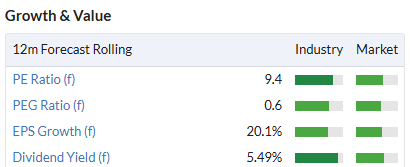
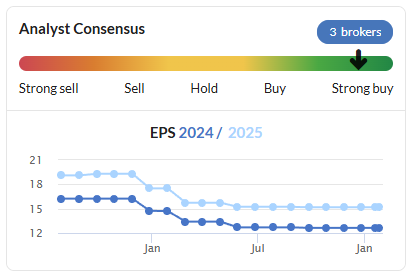
Looking ahead to 2025, Stelrad is expected to deliver further earnings growth, with consensus estimates suggesting earnings could rise by 20% to 15.2p per share.
In today’s statement, Stelrad says it expects “continued softness in market conditions” but is starting to see a recovery in volumes in some core European markets. I get the feeling European markets are a little ahead of the UK in terms of demand – the company cites:
strong embedded replacement demand across Europe, product premiumisation upside and long-term regulatory tailwinds for decarbonised energy efficient heating systems continue to underpin the Group's confidence in the future
We’ll have to see if any updated broker forecasts filter through to Stockopedia over the coming days. My impression from today’s update is that current 2025 expectations are largely unchanged.
Roland’s view
Stelrad appears to be benefiting from two factors, premiumisation and decarbonisation – heat pumps require larger radiators than fossil fuel systems. In the UK at least, I think there’s also the potential for a cyclical recovery at some point.
I am not sure how far Stelrad can go with premiumisation, but I expect the decarbonisation trend to remain a structural driver for the fitment of larger radiators for many years. I know if I was buying radiators today, I would consider the spec likely to be needed for a heat pump, even though I’ve no immediate plans to replace my boiler.
Stelrad shares have lost their IPO froth and now look quite reasonably valued to me, given continuing progress:
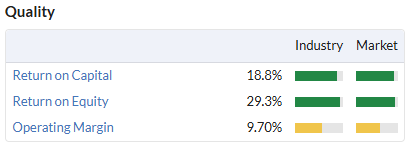
The company’s quality metrics are also above average:
However, there are a couple of points that I think are worth watching.
As Paul has commented previously, debt levels are relatively high. The interim results showed net bank debt of £64m with cash interest paid of £3.8m, or perhaps c.£7.6m annualised. That would be roughly a quarter of FY24 adjusted operating profit.
Today’s update reports year-end leverage of 1.4x EBITDA. This sounds reasonable and is comfortably within covenants, but I think it understates the level of indebtedness here, given that interest payments are deducted from EBITDA.
I prefer to compare net debt to net profit to get an idea of how quickly a company might repay its debt. The interim net debt figure of £64m represents 4x 2024 forecast net profit of £16.2m. This is at the upper end of my comfort zone.
Much as I like receiving big dividends, Stelrad’s dividend payout of c.60% of earnings also looks a little generous to me. I think it would be sensible to reduce the payout and use some additional cash to repay debt.
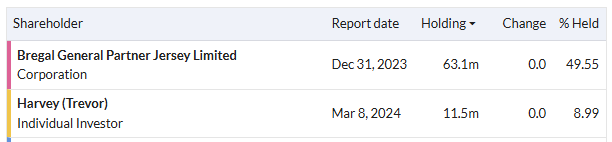
However, I’d speculate that one possible reason for the company’s dividend policy is CEO Trevor Harvey’s 9% shareholding. I estimate he is receiving over £880k per year in dividends!
Similarly, the company’s former private equity owner is receiving around £5m.
On a related note, these two shareholders effectively control the company – there’s not much liquidity:
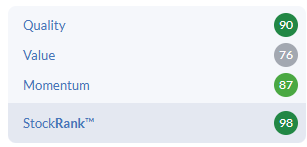
Despite these comments, I’m positive about Stelrad and am hopeful of seeing volumes and revenue stabilise this year. The StockRanks are also positive:
On balance, I think the shares are probably decent value at current levels. AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Pretty much all etfs I follow have been hit massively, couldn't understand it, even so called World or Global, energy too IESU for example. Not supposed to happen.
Why is gold down, thought it would go up. Lots of non AI stocks really down as well.
My main issue with Stelrad (LON:SRAD) is there is little to no moat. The technical aspects of a radiator are pretty simple, and one radiator manufacturer is much like the next. Not much pricing power there from what I can see.
Very intriguing LinkedIn post by Smiths News (LON:SNWS) :
“In just a matter of days, we can FINALLY share about our exciting new collaboration with a HUGE, household brand. Keep an eye out for an announcement coming very soon…”
Surely if that’s genuine eParo, Smiths News (LON:SNWS) had to announce it via an RNS. Telling investors to look out for “exciting new collaboration with a HUGE household brand” is against the rules. Also the share price is unchanged which also questions the validity of that LinkedIn post.
It's a great idea to follow a company you invest in on LinkedIn. You do get to hear about new business or hints new business is possibly being worked on. Last year I recall one company I invested in posting on LinkedIn about a large team trip out to the Middle East, two weeks later a new contract was announced in that region.
Summarised from todays FT article:
Tech stocks tumbled on Monday as Chinese AI start-up DeepSeek released a groundbreaking language AI model rivalling US giants OpenAI and Meta, using fewer Nvidia chips. This sparked fears over the sustainability of the US’s AI leadership and sent Nvidia’s market value plummeting by over $300bn, marking the largest single-company drop in history.
DeepSeek’s advancements triggered significant market losses, with Nvidia shares down 11% pre-market, ASML down 10%, Microsoft falling 6%, and Meta dropping 5%. Broader impacts were felt, with Nasdaq futures pointing to a 4.2% decline and Siemens Energy plunging 22%, reflecting concerns over future AI hardware spending.
While some analysts warned of overreaction, others noted the vulnerability of US tech’s dominance in AI. DeepSeek founder Liang Wenfeng emphasised the efficiency of their model, and Barclays’ Mitul Kotecha highlighted China’s persistence despite US chip export restrictions.
Some optimism emerged as analysts like Dylan Patel suggested lower AI costs could boost long-term adoption, benefiting chipmakers. Chinese stocks such as Baidu and Alibaba rose, signaling excitement over DeepSeek’s success, even as broader Chinese indices saw slight declines.
Finally had a chance to dig into DeepSeek’s r1…
Let me break down why DeepSeek's AI innovations are blowing people's minds (and possibly threatening Nvidia's $2T market cap) in simple terms...
https://x.com/morganb/status/1...
Deepseeks view of Google Gemini as a competitor "In conclusion, DeepSeek could be better than Gemini AI in specific scenarios, such as niche applications, cost-effectiveness, or customization. However, Gemini AI remains a formidable competitor due to its state-of-the-art capabilities and integration with Google's ecosystem. The choice between the two would depend on the specific needs and priorities of the user or organization.
I find it hard to believe that supposed ‘disruptive’ software changes have impacted processing and consumption by the magnitudes implied. I can pretty much guarantee that there will be significant compromises and we aren’t comparing apples with apples. Worst case scenario is that work throughput is looked to increase which still requires the targeted compute and power as previously forecast. That said, those AI stocks were looking frothy so any excuse to give them a haircut.
One of the articles that I read about this suggested that DeepSeek’s future might be as a targeted AI system working from a specific large language model built to answer legal or medical questions rather than as a single massive model designed to function across the whole of human knowledge. It seems very credible to me that this could be done with less hardware. Moreover, rather than breaking words down into syllables it has been built to function with entire words.
DeepSeek Day
Huge important and thanks for flagging here.
All my nuclear trades have been whacked (Centrus Energy (ASQ:LEU) Oklo (NYQ:OKLO) Nano One Materials (TSE:NANO) Lightbridge (NAQ:LTBR) and one on my watchlist Micron Technology (NSQ:MU) Broadcom (NSQ:AVGO) (-18% good lord) ASML Holding NV (NSQ:ASML.
What changed? - some "out of the blue" Chinese knockoff - is the North American AI foundations so built on silicon. I've avoided the MAGS for the 'picks and shovels' were looking at data centre fit-out suppliers but now not so sure.
Over-reactions can give good buying opportunities - good companies on sale - but Mr Market is certainly playing a game.
NVIDIA (NSQ:NVDA) apparently has lost $560bn the largest in Stockmarket history. Meta Platforms (NSQ:META) oddly unaffected.
Has anyone any thoughts on the Johnson Matthey (LON:JMAT) announcement? It seems to have three messages. One - no more investment in hydrogen. I am waiting in vain for the hydrogen market to take off, so this might make sense. Two - somehow increasing cash efficiency. Should it (wasn't it) doing this already? Three - forming an investment committee. I thought this was the job of the board.
Health care stocks will be the winners if the AI spending starts slowing down.
All the best
Hi Yiannos, do you mean from the rotation of funds invested? Thanks, Mike
Hi MIK
Nothing to do with rotation of funds. Cheaper AI is good news for everyone except the Mag7.
All the best
Nothing to do with rotation of funds. Cheaper AI is good news for everyone except the Mag7.
Correct, especially as the code is open source. Although it looks like DeepSeek is running on now banned NVIDIA GPUs so it may be hard for them to maintain this kind of progress. Also - $6.5m is a joke, there's no way this was done on that kind of budget. And where did they get their data from ...
But still, a salient reminder that tech eats tech.
timarr
Llama from Meta is also Open source: OpenAI (clue is in the name) was supposed to be but that changed mid- flight/funding rounds. Deepseek is very different from an architecture and orchestration PoV - it is very clever and efficient (and powerful, - I had a few goes over the weekend but it seems busy today ;0)
. It's more the nature of disruptive innovation, incumbents get disrupted . this challenges the assumption that huge compute hyperscaler DCs are a must for AI - they may not be .
it's very bullish the broader adoption of AI and its embedding more widely but for example, Nvidia's enormous margins are likely to be pressured: this looks more like a moat shrinking /evaporating from the power of the very thing it was predicated on.... but time will tell .
Meanwhile the market has some discounting to do.. EMH anyone ?
Though I wouldn't rule out the potential for state actors.... not like we haven't seen that already without too much, em Star gazing ;-)
Why? because we will all be drinking more :) but agree after today the bubble hasn't burst but dissipated somewhat.
Regarding Good Energy (LON:GOOD) the offer encapsulates the whole idea of investing in equities, I've stuck with Good Energy sometimes wanting to sell and at other times wanting to buy. Perhaps I should have followed my hunches and been better off for it but I'm happy with this result.
Good Energy (LON:GOOD)
Yes, agree.
It’s a shame that this had been taken off the market as I didn’t see it had a rival (that was listed).
However I’m around ~80% up in 23 months and there are other opportunities.
Thank the community for their insight and onward and upward!
Yes, sold my Good Energy (LON:GOOD) shares, this morning, up over 60% in under a year, l can't complain, think it is a fair price.
Nice to see Good Energy receiving a bid at a significant premium. They were on the Mello Monday show last year
Join us for MelloMonday tonight at the slightly earlier time of 4:30pm.
The programme for the evening is as follows:
4:30pm Interview with Fund Manager, Katen Patel
5:00pm Company presentation from Helios Underwriting plc
5:40pm Company presentation from Solvonis Therapeutics (formerly Graft Polymer)
6:20pm Educational session
6:35pm Company presentation from Cohort plc
7:20pm BASH (Buy, Avoid, Sell, Hold) Panel featuring Kevin Taylor and Mark Simpson
For more information, click here: https://melloevents.com/mm270125/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1485400
More Upcoming Events:
Mello Farnham on Tuesday 28th January 2025, 7.30pm https://melloevents.com/mellofarnham/
Mello returns to its roots by re-introducing the much-loved investor dinners which, for 15 years, took place in Beckenham Kent. In 2025, Mello has found a new home…. The Wheatsheaf Pub in Farnham, Surrey. This pub will host an investor dinner where a successful CEO of an AIM listed company will present their business and will answer questions.
The evening runs from 7pm – 10.30/11pm, with plenty of opportunity to network with like-minded serious private investors, many of whom you may have seen at one of our Mello in-person conferences.
Any thoughts on Deepseek released over the weekend?
For those who don’t know, it is a Chinese AI tool in competition with Open AI, Google’s Gemini etc. more concerning that it doesn’t require NVIDIA (NSQ:NVDA) chips and costs are much lower than its US competitors.
The initial feedback of the product has been impressive if not too impressive. However, this will impact on SP of NVIDIA (NSQ:NVDA) ,Microsoft (NSQ:MSFT) and Alphabet (NSQ:GOOGL) . Maybe time to top slice.
Having missed out on both the AI and fat drug moonrockets I’m probably not best qualified to comment, but these do remind me of the dotcom era, with dangerous projections of compound growth. Yes, the internet changed the world forever, as will AI and the obesity drugs, but those benefits and profits will be widely distributed, often to players yet to emerge. In AI the big US players have advantages in cultural, regulatory and innovation, and it appears they still have the better product, but these are early days and the pace of advances made by the Chinese, if correct, in the face of restricted chip supply and at a fraction of the cost do not bode well. I think this may be a bubble pricking moment and good luck to holders, if I were fortunate to be one I would certainly be taking some money off the table.
Black swan event!
"In an interview with CNBC, Alexandr Wang, CEO of Scale AI, described the AI race between the U.S. and China as an "AI war." Wang believes China has substantially more Nvidia (NASDAQ:NVDA) H100 GPUs than people may think."
That suggest that it does use Nvidia GPU's, where does it say it doesn't use Nvidia?
My understanding was that they were using older generation Nvidia chips, as Nvidia are banned from exporting later generation chips to China. Just another example of sanctions backfiring, as it just ends up driving further innovation.
Thought I ask Deepseek!
Experiencing high traffic so can’t give me a reply. So their servers can’t cope.
Apparently some news sources are saying that the Chinese may have a stack of older versions on NVIDIA (NSQ:NVDA) chips and/or using other methods which require less energy/power to work. https://www.bbc.co.uk/news/art...
It is also possible that Deepseek are using “in-house” built chips to overcome the export restrictions imposed by the US.
Whichever way you look at it, there is another competitor in this space and in such short space of time has started a disruptive effect.
There was an article in the Economist about Chinese AI https://www.economist.com/lead...
In summary it says that in spite of the chip problems, they are doing remarkably well.
Polar Cap Tech Trust ( LN:PCT) I hold ( for 10 years )
I would love to know the managers take on this news over the weekend as last time I saw them present at Mello they said they were 100% in on AI, 6 months previously I recall they said 75%
They know the space , companies and understand the material better than most
If anyone spots any reaction from them, I think most valuable
Nasdaq futures down 4.40% so the market is certainly taking it seriously. That would be a whopping big daily move if it holds.
I recommend this article in The Register for a comparison of DeepSeek with its rivals:
https://www.theregister.com/20...
What is quite amusing is how relatively simple tasks still trip up all of the LLMs....such as asking how many "r"s there are in the word "strawberry".
Which may add some context to the other news out today - that the use of AI at the DWP isn't going terribly well!
https://www.theguardian.com/te...
I asked Chat GPT this question and it answered it perfectly, first time ..?
the problem was 3 months ago it couldnt answer the question without really having full on 6 pints in argument with it till it got bored and agreed for the quiet life - that was despite the fact it was a meme at the time. as it was so well known obviosuly it would be fixed sooner rather than later - the issue is that probably took manual intervention to get fixed - not a great sign that its ultimately "reliable" at anything despite the fact it can do unbelievable amazing complicated stuff - its super clever with zero attention to detail which should be a bit scary
From the Telegraph...
DeepSeek said it had spent only $5.6m (£4.5m) developing its model - peanuts when compared with the billions US tech giants have poured into AI.
Maybe Chinese government chucking in billions behind the scenes ?
I would guess so. Quoting a ridiculous number though is a great opportunity to crash the US markets.
Ask DeepSeek about Tianamen Square in China or Taiwan. DeepSeek won't be able to give you an answer because the Chinese have wiped Tianamen Square & Taiwan from its memory/search. DeepSeek just ìnforms you that it is a friendly AI product and the subjects are beyond its current scope.
David.
That's if you can ask it anything at all, seems to down most of the time.
So many AI answers are incorrect. AI software is very hit and miss.
My current view of AI is like a trip to your GP. If you can describe your symptoms clearly, they are good at listening and can hone in and ask good follow ups. You may get the right diagnosis!
The answers are wrong. I don't know why AI is used anyway for basic questions. AI probably gets it's answers from the internet, many are incorrect as out of date or just plain wrong.
Just go on a travel forum, see the confusion because people look at answers on goggle or social media.
I was looking the frequency of car ferries from one port to another port, l know there are car ferries, AI butts in and states no car ferries from that port, totally wrong.
From the Telegraph today
"A Reddit user managed to persuade DeepSeek to give answers about the Tiananmen Square protests in 1989."
According to the Telegraph, the user substituted numbers in place of some letters and eventually found a description of how the Unknown Rebel became a symbol of resistance.
However, deepseek is open source. I'm no expert here, but there is a report, I can't now find, that says that the censorship regarding eg Tianamen is down to the platform it's running on, not the system. I've also had to leave ExTwitter recently as thanks to the actions of it's billionaire owner it's become an ususable cess pit. Problems online come from many sources
The "aheads" from Brave Bison (LON:BBSN) are becomming a regular feature at this business. New Cavendish Note this morning TP 4.7p, valuation "highly compelling" and Brave Bison (LON:BBSN) "one of the few in the sector not to warn".
I've seen the Green Bros at Mello several times now, and concluded that they are the real thing: capable, ambitious but firmly grounded, and cognisant of (& alligned with) shareholder returns. At c£20m EV (Cavendish have £18m, net cash is £7.5m), whilst this may still be too small for some, I think a much bigger business is in the making, with a now limited window to hop on this journey at an early stage.
The share price of many good quality UK small caps seems bonkers to me and at times incomprehensible. It will change, but as to when, perhaps when the ever present air of negativity that the media seem to dote on ends.
Anyway enough of the philosophising. I will be sorry to see WH Smith (LON:SMWH) disappear from the high street, which looks as if it will happen, but should it, it removes a competitor for items such as greeting cards, wrapping paper, stationery etc. From where I sit this should be a positive for Card Factory (LON:CARD) which like many small/mid caps no one can be bothered with and continuing with my opening theme is bonkers cheap. I have therefore added a fair few this morning.
Just my thoughts.
I am confused, Jonno. Why do you assume that the buyer of the WH Smith high street stores will not continue selling the same product range as before?
More to the point - will anyone offer to buy WHS. Just near me the Halstead branch which also houses the only Post Office and where there are no longer any banks - is due to close in April. Maybe CARD or another similar coy will change tactics and broaden their offering to fill the gap without the cost of buying out WHS
Yes l was wondering who would want it, with staff costs soaring and the high street in decline, l can see why they want to sell it. My one in the nearest town has closed already, now a charity shop. The 2 banks, one of which closed about 4 years ago, are still vacant. All building societies closed many years ago.
Jonno, it depends what the buyer does with the high street shops. If it continues in a similar line of business, and does it better, it could increase competition.
Richard
Fair point Sparkler and Richard, and admittedly an assumption on my behalf, but WH Smith (LON:SMWH) wouldn't in my view be considering the sale of its high street business if it thought it had a successful future. LFL revenue in its high street division declined 2% last year and I just can't see a buyer successfully replicating a business in which the present owner has had over a century of experience and continues to struggle.
"During the year, High Street delivered a performance in line with our expectations with Headline trading profit1 of £32m (2023: £32m), and revenue of £452m (2023: £469m). We managed the business tightly, keeping focused on costs and cash generation. LFL revenue was down 2% on last year."
As far as Card Factory (LON:CARD) is concerned, it has an integrated operating model and great cash flow. Even without any benefit from the demise of Smith's high street business, the valuation is compelling at the current price and it has in my opinion an excellent management team.
Card Factory - Outlook
· The Board expects to deliver FY25 adjusted profit before tax (excluding one-off items) in line with current market expectations5, reflecting robust revenue growth and the benefits of our previously announced productivity and efficiency programme.
· The changes to National Living Wage and Employer National Insurance Contributions will result in annual cost inflation of c.£14 million in FY26. We expect to offset this through our proven approach which includes our ongoing productivity and efficiency programme, as well as range development and pricing, while continuing to invest in our future growth. Despite these inflationary pressures, we currently expect to deliver a mid-to-high single digit percentage increase in adjusted profit before tax in FY26.
· We will provide a further update on our strategic and financial progress at our Preliminary Results on 7th May 2025.
As always just my view.
All the best
Good trading update from Volex (LON:VLX) today. I am unsure why the share price has failed to recover since they withdrew their bid for TT Electronics (and demonstrated their ability not to overpay for acquisitions). I would be interested to hear your views.
Hi Steve, I hold a fair few Volex (LON:VLX) and have done so for 2 or 3 years. The share price action reinforces my view of the irrational prices of many good quality UK small/mid caps.
Regarding Volex (LON:VLX) , the share price drop was over concerns regarding possible tariffs on imports from it's Mexican factory production.
No, it dropped on 15th November, when the takeover of TT electronics (LON:TTG) was announced. Volex (LON:VLX) share price dropped and TT electronics (LON:TTG) shot up.
Tariffs I suspect.
I dug through past results this morning and it looks like in H1 19 they benefited from stockpiling ahead of potential tariffs - so might be worth us probing whether the current organic growth performance is being partly driven by that. They also made a point about (at least some of) their competitors being more exposed to China back in 2018/19 but I also took from this that they expected to be impacted too.
CTRL+F 'tariffs' here: https://volex.com/wp-content/u...
Dr Martens (LON:DOCS) maybe starting to look interesting as the -16% constant currency revenue loss at the Half Year is now a +3% at Q3 - a bit like what we have seen at Burberry (LON:BRBY). I know DOCS is not at the luxury end like BRBY but their price point is still higher than average so maybe they have been experiencing similar trends?
This only makes it in line with expectations because of (what previously seemed optimistic) H2 assumptions but maybe they are now on track.
The problem is that given the debt and past record I am not sure this looks particularly good value yet. In year ending 3/20 and 3/24 (ignoring '21 and '22 affected by COVID) they made c.7p EPS and it's trading this morning at 72p.