Daily Stock Market Report (Mon 3 Feb 2025) - ULTP, SDY, SRC, ENSI, CHH, SSTY, FEN

Good morning!
I'm afraid we have a few profit warnings in the mix today.
12pm: It's a clean sweep of the RNS lineup today. See you tomorrow!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Sigmaroc (LON:SRC) (£814m) | FY TU | 2024 earnings “modestly ahead” of consensus, improved margins. FY25 outlook unchanged. | AMBER (Roland) |
Speedy Hire (LON:SDY) (£124m) | TU | Profit warning. Challenging start to Q4 (Jan-March), ongoing macro uncertainty. Net debt £123m. | BLACK (AMBER) (Graham) The economy and CP7 are singled out as reasons for this severe profit warning. Long-term it might still be a winner but I'd prefer to be neutral as we saw a similar profit warning in early 2024. Too accident-prone. |
Ultimate Products | TU | Profit warning. PBT estimate cut by 36% for FY25 to £11m, cut by 27% for FY26 to £13.7m (Zeus). | BLACK (AMBER/GREEN) (Roland) |
Churchill China (LON:CHH) (£68m) | TU | Year-end trading was in line with exps. No change to Nov 24 guidance. Markets remain challenging. | AMBER/GREEN (Roland holds) |
Frenkel Topping (LON:FEN) (£45m) | TU | 2024 adj EBITDA flat at £8m. FUM +17% to £1,560m. FY results to be in line, outlook confident. | AMBER (Graham) My initial take is that this is at fair value. An argument could be made for cheapness (forward PER 8.5x), but it’s not jumping out at me. |
EnSilica (LON:ENSI) (£41m) | £10m funding award | £10.4m award from UK Space Agency to develop components for mass market satellite broadband. | AMBER/RED (Graham) |
Safestay (LON:SSTY) (£15m) | TU | Rev +2% to £23m in 2024, adj EBITDA -4.4% to £6.5m. Fwd bookings +27% at 1 Jan 25, confident in adj EBITDA growth. | AMBER (Roland) |
Graham's Section
Speedy Hire (LON:SDY)
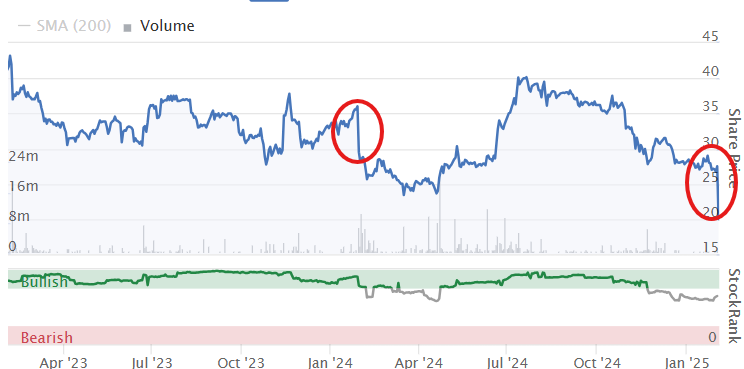
Down 28% to 19.75p (£92m) - Trading Statement - Graham - BLACK (profit warning) / AMBER
Speedy’s year-end is in March:
Speedy, the UK's leading tools and equipment hire services company, operating across the construction, infrastructure and industrial markets, provides the following trading update for the ten months to 31 January 2025.
Unfortunately, it turns out that January has been a difficult month for the company.
Several factors are mentioned.
Firstly, due to the “widely reported economic downturn”, there has been a “slower post December shutdown recovery across the majority of our customer base”.
Renew Holdings (LON:RNWH) said that Network Rail’s delays relating to its “Control Period 7” were responsible for its recent profit warning, and Speedy also gives this a mention. It sounds like there is no room for complacency for any investor who might be affected by CP7.
Trade & Retail channel: Speedy has re-engineered this small part of its business (only 1% of revenue last year), but “it is taking longer to achieve the expected levels of hire revenue which we now anticipate achieving during first quarter FY2026”.
Joint venture in Kazakhstan: a significant downturn in performance due to the early shutdown of major contracts.
Net debt rises year-on-year to £123m.
A note on this: it’s normal for equipment hire companies to use a moderate amount of leverage and in this case of Speedy it targets a leverage multiple of 1.5x (leverage is defined as net debt to EBITDA, where EBITDA is calculated the old-fashioned way, i.e. pre-IFRS 16).
Speedy’s net debt should reduce from its current level by year-end but it’s still higher than last year and so the company acknowledges that its interest charge will be higher than last year. The interest charge last year was nearly £13m.
Outlook
We remain committed to the delivery of our Velocity strategy providing benefits for Speedy for the long term. We are focused on what we can control, and we will continue to manage our cost base and balance our investment decisions in response to the current economic climate.
The Group has a promising pipeline of growth opportunities with new and existing customers, and should benefit from increased government spending on infrastructure projects. Nevertheless, with the challenging start to our final quarter and ongoing macroeconomic uncertainty, the Board expects lower than anticipated profitability for the full year.
Estimates
Thanks to Panmure for getting fresh estimates out this morning.
They have reduced their FY25 EPS forecast by 42% to 2.1p (last year 2.3p).
They have reduced their FY26 EPS forecast by 28% to 3.3p.
Net debt (excluding leases) was supposed to finish the current financial year at £98m, but it is now forecast at £115m.
Panmure says that 9.2p of EPS is still achievable “eventually” when operational gearing works in Speedy’s favour, but they do not have 9.2p of EPS in any of their forecasts out to FY27.
One other observation I might make is that while today's trading update does not mention Speedy's dividend policy, the current rate of annual dividend - 2.6p per share - will not be fully covered by this year's EPS, based on the new forecast.
Graham’s view
We haven’t expressed a view on this one since AMBER/GREEN last April.
Scroll back to this time last year - Jan 30th 2024, to be precise - and I see that Paul explained that “Forecasts are slashed as a variety of fairly minor-sounding problems combine to cause a 35% drop in broker forecast earnings for FY 3/2024.”
Here we are a year later and we see forecasts getting slashed again, for a variety of reasons.
Last year, among the reasons, the company blamed “weakness in some of our end markets and seasonal product lines”, i.e. macro was blamed last year, too.
This year, I think many other companies will agree that the economy is not providing a supportive backdrop for trading.
But the bottom line is that, as an investment, Speedy is highly accident-prone. Even if the myriad of factors that drive these profit warnings are entirely beyond the company’s control, I don’t think it matters - I can’t have faith in this company’s financial progress. I’d rather invest in something where less can go wrong.
On that basis I don’t think I can maintain our moderately positive stance on this one, even at a cheap valuation.
After the share price fall this morning, the shares now trade at a PER of 6x FY March 2026 forecasts.
That sort of earnings multiple seems reasonable to me. Hopefully the company can kick on and achieve the operational gearing that is envisaged for it, eventually producing annual EPS of 9p. But I don’t think anyone can assume this will happen soon, after the second major profit warning in a year here.
So while I agree that there is speculative upside, I think the market is right to price this share as if it won't materialise for a long time.
As an American President once said: “Fool me once, shame on you. Fool me - you can't get fooled again.”
EnSilica (LON:ENSI)
Up 5% to 44p (£43m) - £10.38m UK Space Agency Award - Graham - AMBER/RED
EnSilica (AIM: ENSI), a leading chip maker of mixed signal ASICs (Application Specific Integrated Circuits), is pleased to announce that it has been awarded £10.38 million funding over the next three years from the UK Space Agency for a development project under its Connectivity in Low Earth Orbit ("C-LEO") programme…
ENSI will “develop a family of semiconductor chips to support future generations of best-in-class, highly integrated, mass market satellite broadband user terminals. The terminals will be capable of connecting with various satellite constellations and will leverage advanced semiconductor technology.”
The UK Space Agancy will fund up to half of the cost of the overall project.
ENSI has a £9m debt facility (announced in Nov to refinance existing facilities). Perhaps it can fund some/most of the remaining cost itself? Although its finances have been under some pressure - more on this in a moment.
CEO comment:
We are honoured and proud to have won this highly significant award from the UK Space Agency under the C-LEO programme, as we believe satellite communications is an incredibly important sector for EnSilica and one that is fast expanding globally.
This funding will enable us to advance our technology and bring innovative solutions to the satellite broadband market, with the project expected to be hugely beneficial to society, offering resilient internet connectivity in times of crisis, as well as providing high speed internet connectivity in remote communities not well served by terrestrial networks.
Estimates
I don’t see any change to the estimates at Allenby, but they point out that if Ensilica wins a supply deal for its chips relating to Starlink terminals, that would be material.
Singers have taken a slightly different approach, estimating higher costs in the short-term and therefore making some modest adjustments to EBITDA and free cash flow forecasts for the next two years.
For context, their new adj. EBITDA forecasts are £4.8m (FY May 2025) and £8.6m (FY May 2026).
Consistent with Allenby’s message, they say that “long-term opportunities should more than compensate” for marginally lower cash flows in the short-term.
Graham’s view
I was RED on this at the full-year results published in November (share price at the time: 44p), as the going concern note stated that the company would not be able to survive the new financial year without additional financing and the receipt of expected revenues from existing customers. This was even after taking into account the refinancing of the company’s debt facilities.
Since then, we’ve had an “in line” trading statement at the AGM, a $30m 10-year contract, and today’s UK Space Agency news.
I’m therefore happy to upgrade this to AMBER/RED as I must presume that ENSI’s counterparties including the UK Space Agency have done the due diligence required to ensure that ENSI is not very likely to collapse over the next 12 months.
If ENSI hits its forecasts for the financial year that starts soon - FY May 2026 - then I expect investors to do extremely well. These forecasts include £38.1m of revenue and adj. PBT of £5.5m. Throw in a Starlink-related contract and this could be a huge winner.
But I need to keep my feet on the ground. At the moment there seems to be a great deal of latent potential, but the value is highly uncertain. I think AMBER/RED is fair for now.
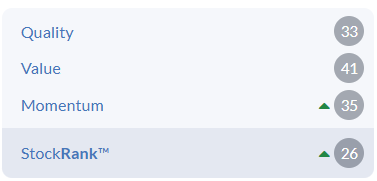
ENSI's risk classification on the StockReport is "Highly Speculative" and the StockRank is only 26. At least Momentum is recovering:
Frenkel Topping (LON:FEN)
Unch. at 35.4p (£45m) - Trading Update - Graham - AMBER
FEN is “a specialist financial and professional services firm operating within the personal injury and clinical negligence marketplace”.
2024 is in line with management expectations.
While there is no growth in adj. EBITDA for the year (flat at £8m), and the company has moved into a net debt position, there has been nice growth in funds under management:

Within funds under management, the “discretionary” funds (which I presume involve higher fees) are up by an impressive 26%.
The company made a small, bolt-on acquisition in April 2024 (price £3m). It has also announced various partnerships and joint ventures over the past two years. My point is that I think the growth numbers shown above are mostly organic.
Cost of higher NICs/NMW: the cost is estimated at £500k p.a. The Board “will work hard to mitigate this external headwind as far as possible through pricing and technology efficiencies”.
Outlook: continued positive momentum in January, and confidence for the start of the new financial year.
Estimates: Cavendish have reduced their 2025 EBITDA forecast by £0.2m to reflect the impact of higher NICs/NMW that can’t be mitigated this year. The new EBITDA forecast for this year is £9m, converting to adj. PBT of £7.6m.
Graham’s view
My initial take is that this is fairly valued for a professional services firm:

I note the argument from Cavendish that this is cheap for the sector, if you compare FEN vs. a group of IFAs, Legal Services and Business Consultants. They suggest that the cheap rating is due to concerns around a FEN subsidiary that have now been resolved (“Partners in Costs”), and regulatory risk to do with the FCA’s new standard, “Consumer Duty”.
As I don’t study this one regularly, I’ll accept the risk of splinters and sit on the fence with a neutral stance. Maybe there is an opportunity here, but I’m not sure. I was neutral when I looked at FEN back in 2023, when the share price was 56p. It has fallen by more than a third since then, so if anything I should have been more sceptical the last time I checked it out. On the other hand, after falling steadily for some time, perhaps it now offers some value?

Roland's Section
Ultimate Products (LON:ULTP)
Down 21% 79.8p (£68.9m) - H1 2025 Trading Update - Roland - BLACK (AMBER/GREEN)
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), announces its trading update for the six months ended 31 January 2025 ("H1 2025").
Unfortunately today’s update is a profit warning. Brokers Shore Capital and Cavendish have both cut their FY25 earnings estimates by 36%. FY26 estimates have also been cut.
Let’s take a look.
Weaker than expected trading: Ultimate Products says it’s still suffering from tough air fryer comparatives (this boom is now fading) and has seen subdued market conditions in the UK.
H1 revenue fell by 4.7% to £79.4m, although within this international sales rose by 12% to £29.1m. This seems to indicate that UK revenue fell from £58.2m to £50.3m in H1, a fall of 13.6%.
This effect was most notable in Q1, when Group sales were down 9.3% year-on-year. However, trading improved in Q2, with sales down by a more moderate 2.2%.
Ultimate also notes a number of cost pressures, including £2m of additional shipping costs in H1 due to higher rates.
Order book: the company entered calendar year 2025 with an H2 order book up “an encouraging” 24% year-on-year.
However, just one month later, the H2 2025 order book is now up only 13% year-on-year. Demand from some retail customers is said to have eased – I get the impression there has been a sharp drop in new orders.
International performance remains stronger, with forward orders up 20% year-on-year.
Outlook: revenue guidance for the year ending 31 July 2025 has been cut:
Therefore, the Board believes that the Group's full year revenues will now be broadly flat compared with the prior year.
For context, last year’s revenue was £155m. Prior to today, Stockopedia consensus showed group revenue rising by 10% to £171m this year.
The company says full-year EBITDA is now expected to be £14-£16m, around 25% below previous consensus of £20.6m.
Updated estimates: Shore Capital and Cavendish have both issued updates through Research Tree today, translating Ultimate’s comments into updated earnings estimates. Many thanks.
Cavendish: FY25 EPS cut by 36% to 9.3p (previously 14.6p)
Shore Capital: FY25 EPS cut by 36% to 9.5p (previously 14.8p)
Both brokers have also cut their FY26 forecasts by around a quarter.
Roland’s view
Today’s profit warning is Ultimate’s second in 12 months, following a cut to guidance in May last year:

However, even before today’s big drop, Ultimate’s share price had fallen by nearly 30% since the Autumn Budget:

My feeling is that the market has been pricing in further weakness and a likely dividend cut. While today’s update confirms the company intends to maintain its 50% payout ratio, this suggests the payout could fall by 36% to around 4.7p per share this year (FY24: 7.38p).
Personally, I’ve admired the longer-term progress of this business and am encouraged by the apparent progress on international growth.

Ultimate has some well-known brands and has seemed well managed to me, with strong quality metrics and good cash generation:

My main concern is probably that the value positioning of the company’s brands could leave it open to intense competition on price.
Today’s drop leaves Ultimate Products trading on around eight times 2025 forecast earnings, with a c.6% dividend yield (based on revised estimates).
The company has said today that it intends to maintain leverage at 1x EBITDA, as in the past, so it doesn’t look like the balance sheet is becoming unduly risky.
I would imagine there’s still some risk of one further profit warning. But on balance, I think these shares could now be at a level where they are starting to offer value. I’m going to maintain our AMBER/GREEN view.
Sigmaroc (LON:SRC)
Down 1.4% 72p (£810m) - Year-end Trading Update - Roland - AMBER
This lime and minerals group (building materials) is notable for the buy-and-build strategy it’s pursued since listing, in particular last year’s £1bn acquisition of European lime assets from industry heavyweight CRH.
These deals have left a burden of integration work and debt, but SigmaRoc appears to be handling these successfully and trading well:
2024 underlying earnings and EPS modestly ahead of consensus expectations, driven by transformational investment to create a leading European lime and minerals platform.
Today’s update covers calendar 2024. Helpfully, the company has included like-for-like (LFL) figures as well as headline numbers reflecting last year’s acquisitions:
Revenue expected to be up 72% to c.£998m
Pro forma revenue down 2% LFL
Underlying EBITDA expected to be up 90%, exceeding £222m
Pro format EBITDA up 2% LFL, reflecting integration progress
Today’s upgrade appears to be driven by improved profit margins rather than underlying sales growth.
Underlying EBITDA margins improved to 22.3%, increasing 220bps YoY
Updated estimates: helpfully, SigmaRoc have also provided an updated earnings per share estimate in today’s update. This ensures that investors without access to broker notes are not left at a disadvantage:
Underlying EPS expected to be around 8.3p, approximately 10% ahead of consensus [specified as 7.6p] and 3% ahead of prior year
I can’t fault the clarity of guidance here. Personally, I find that encouraging, as it suggests to me the company has good financial controls and has a clear story to communicate to shareholders.
Operating commentary: management says that pro forma LFL volumes fell by 4% last year, reflecting weaker market conditions in residential construction and some industrial markets.
However, the company has continued to make progress integrating the CRH assets and streamlining its portfolio. A number of non-core Belgian and French assets were sold for €49.5m (7x EBITDA).
Talks are also underway to replace the bridging finance facility used for the CRH transaction with a lower-cost long-term loan.
Encouragingly, net debt leverage on a covenant basis is expected to have closed the year “below 2.1x”, down from 2.3x at 30 June 2024. Half-year net debt was reported at just over £500m.
While I feel this level of gearing is relatively high for a business of this kind, the numbers are moving in the right direction.
Outlook: there’s no change to guidance for the current year. Based on current consensus numbers, this suggests SigmaRoc’s earnings could rise by 12.6% to 9.4p per share in 2025.
That puts the stock on a 2025 forecast P/E of eight, which could be quite reasonable if deleveraging continues:

Roland’s view
There’s clearly a cyclical element to demand and pricing for the kind of products SigmaRoc sells. But at the same time, in general this type of business will only have limited competition in any given geographic area, as long-distance transport is generally not economically attractive.
This is also a capital intensive business – SigmaRoc’s profitability metrics are consistently low:

Today’s update suggests the company is making good progress with what I see as the riskiest part of its strategy – integrating large acquisitions and reducing debt to a safer level.
However, given the relatively high level of debt and low profitability I am going to stay neutral for now, at least until the company’s full accounts are published. AMBER.
Churchill China (LON:CHH)
Down 6.5% to 575p (£63m) - Full Year Trading Update - Roland holds - AMBER/GREEN
At the time of publication, Roland has a long position in CHH.
Churchill China shares are down as I write, but I would argue today’s brief update from this leading manufacturing of crockery for the hospitality trade is broadly positive.
The business finished 2024 trading in line with revised expectations, after November’s nasty profit warning:
The Company is pleased to confirm that trading in the final two months of the year met the Company and market's expectations and that there is no change to the guidance issued in November 2024.
Market expectations are cited as being for a pre-tax profit of £8.5m.
This looks consistent to me with Stockopedia’s consensus earnings figure of 57.9p per share, pricing Churchill on just over 10x 2024 forecast earnings, with a covered 6% dividend yield.
Outlook: Chairman Robin Williams says that conditions remain “challenging” but the company is continuing to make improvements to productivity and yield in its factory.
Mr. Williams says the business remains well positioned to capture a recovery in demand:
with an unparalleled service offering and an innovative and differentiated performance product.
Roland’s view
Graham covered Churchill China in more depth in November. He noted that he thought the shares were “possibly not far off deep value territory”.

My view is similar and I recently bought some shares. I believe Churchill’s differentiated product, strong balance sheet and long track record should support an eventual recovery.
I’m going to maintain our view at AMBER/GREEN, reflecting the uncertain near-term outlook.
Safestay (LON:SSTY)
Down 1.5% to 23.2p (£15m) - Trading Update - Roland - AMBER
We last covered this European hostel operator at the end of February 2023, when Graham took a look. The shares have not done much since then, but the operating environment has evolved as the impact of the pandemic has moved further into the background.

I thought it might be interesting to update our coverage today and see how the situation has changed over the last two years. This stock has traded much higher in the past and trades at a significant discount to its June 24 book value:

2024 trading update: today’s update covers the 12 months to 31 December 2024. Revenue is in line with the broker consensus shown on Stockopedia:
Revenue up by 2% to “a record” £23m in 2024
Adjusted EBITDA down 4.4% to £6.5m
Forward bookings at 1 Jan 25 of £4.7m, 27% higher than at the start of 2024
Debt refinancing into a new £16m 5yr term loan with £2.5m RCF
The top two numbers suggest to me that Safestay’s pricing or its cost base came under pressure last year. It seems pricing was the issue.
Safestay’s operating metrics show the company selling more beds and improving occupancy in 2024, but at lower price points:
Total Bed Nights rose by 10% to 931,688, with 37% booked direct or without commission payments (2023: 32%);
Occupancy rose by 3.8% to 75.2%;
Average Bed Rate down 10% to £21.40
Total Revenue per Available Bed (Total RevPAB) down 2% to £18.56
Revenue from ancillary sales helped to cushion the decline in bed rate, but this still suggests a tough trading environment.
We can get some context on this by looking at the recent update from Hostelworld, which is a large online travel agent specialising in hostels. It recently reported “an 8% decrease in net average booking values year-on-year”.
This seems to suggest that falling bed rates are a sector headwind and that Safestay’s performance is broadly in line with the wider market.
Current trading & Outlook: Safestay expects the macro backdrop to “remain challenging” this year.
The company cites the 27% YoY increase in forward bookings as evidence that its marketing and brand-building efforts are delivering results.
Management says the international hostel market remains large and fragmented and that Safestay will continue to look for expansion opportunities, including “less capital-intensive routes to market such as franchising partnerships and management contracts”
Financial guidance is limited but suggests some headline growth in 2025:
The Board is confident of achieving further strategic progress as well as revenue and adjusted EBITDA growth in 2025.
Roland’s view
When Graham covered Safestay in 2023 he suggested that it would be good to see occupancy returning to pre-Covid levels of c.75%. This has now happened.
He also noted the company had previously said it would be self-funding when it had 20 sites – this should happen shortly. Safestay had 17 sites in operation at the end of last year and three in development.
Today’s refinancing news and the company’s mention of capital-light growth options certainly suggest to me that Safestay’s management expects further expansion to be self-funding.
Unfortunately, there’s clearly some weakness in the hostel market at the moment that’s limiting pricing (but not necessarily demand). We don’t know how long this might last.
In addition, I’d have to note that EBITDA is not necessarily an ideal metric to use for a business where the depreciation charge reflects the need for regular building maintenance and lease expenditure. In 2023, EBITDA of £6.8m translated into operating profit of £2.5m, for example.
At a balance sheet level, I can see some value here. The latest accounts (June 2024) showed net tangible assets of £21.5m, versus today’s market cap of £15m.
On the other hand, profitability is relatively low and I’m not sure Safestay is generating enough real profit to justify trading much closer to book value.
I’m going to remain neutral for now until the company’s 2025 results are published and/or more detailed outlook commentary becomes available. AMBER.Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
His Dad was German but he doesn't seem to want to cut them any slack.....I don't know the reason but it will be revealed in time
I noticed today that 3 Pennant International (LON:PEN) directors had bought shares. Small total cost but PENN is illiquid. I hold.
I listened to the Eenergy (LON:EAAS) webinar this morning and was impressed with the progress they have made - excellent revenue and np growth and zero debt. Forecasts look good too. I am a long term holder.
I'm wondering if anyone with an accountancy background has cast their eye over the trading update from Eenergy (LON:EAAS) last Thursday. There was an Investors Meets the Company presentation this morning. I don't hold but I was interested because they claim they are on the verge of great growth. But they have declared a bunch of accountancy adjustments for 2023 which reduces the revenue by £4.8m. Are these adjustments reasonable? Should I trust the figures going forward?
Nice director buy for easyJet (LON:EZJ)
Bodes well £100k - not small potatoes
The Company announces that it received notification on 3 February 2025 that Julie Chakraverty, Non-Executive Director, acquired 20,083 ordinary shares of 27 2/7 pence each in the Company (“Shares”) at a price of £4.9792 per share, in London.
easyJet (LON:EZJ) "Julie was appointed to the Board on 27 January 2025" so probably part of her contract and not significant.
Rockwood Strategic (LON:RKW) Eurocell (LON:ECEL) Card Factory (LON:CARD)
The above shares are held in family portfolios, all of which are in ISAs. Given the unremitting gloom, added to by Donald's tantrums I have opened positions in my wife's ISA in all three.
Rockwood Strategic (LON:RKW) I am an admirer of Richard Staveley he is clearly passionate about investing and tells it as it is, including not always getting the investment thesis right Rockwood trades at a small premium to NAV, which in my view is worth paying. I have individual holdings in RM (LON:RM.) and Van Elle Holdings (LON:VANL) .
Card Factory (LON:CARD) and Eurocell (LON:ECEL) both are very cheap based on forecasts and unsurprisingly share a number of investment characteristics. I especially like that both exhibit really good free cashflow The trading update from Eurocell (LON:ECEL) was downbeat and you can't accuse the management lead by Derek Mapp of buffing up prospects, despite this the company expects to achieve forecasts. As for Card Factory (LON:CARD) I like the management team who have achieved a significant turnaround without issuing equity and are using cash generated for acquisitions and to expand partnerships.
A reduction in UK interest rates should in particular benefit small caps and hopefully all three shares will be trading at much improved prices in the next 12 months.
The difference with Rockwood Strategic (LON:RKW) and other Harwood funds, is they are actively involved with the business, not like most funds which just buy and sell shares.
The difference with Rockwood Strategic (LON:RKW) and other Harwood funds, is they are actively involved with the business, not like most funds which just buy and sell shares.
There’s two sides to this situation, however. Any competent management team is likely to tell a meddling (and likely only temporary) minority shareholder own to “ go and do one!” If that’s not happening, the company is not in great shape.
But are they minority shareholders? They often have quite a large share of the business and a director.
For example: Hargreaves Services (LON:HSP) they have 27% share and one director.
EKF Diagnostics Holdings (LON:EKF) 29% share and 1 director.
RM (LON:RM.) 15% share and no director?
Yes many companies, they are involved in, do need some turning around.
And Mills has been on the Board at MJ GLEESON (LON:GLE) for a number of years. Harwood are the biggest shareholder there though only 10%.
Might CARD suffer from Trump’s sanctions?
Card Factory (LON:CARD) why would they be affected by Trump's tariffs?
Factory outside the USA. Now selling in the USA? So presumably importing
Yes they acquired Garven recently but only paid $25m for it, so it must be a small exposure. Looks like they import some products from China. No tariffs on the UK yet.
Exporting to USA following the recent purchase of distribution companies over there.
Gulf Keystone Petroleum (LON:GKP) which I hold is nothing to do with Tariffs snowdrop and everything to do with some major news today that the IRAQ Government has approved a Compensation Plan to Resolve the Oil Dispute with the KRG. Kurdistan Regioal Government.
Could this mean the Pipeline closed for nearly 2 years will be opening soon?
From where I posted on another thread:
The decision by Iraq's parliament to resolve the payment dispute over Kurdish oil is a significant step forward, but it does not automatically mean exports will resume immediately. The hurdle removed—agreement on production costs and payments—was a major barrier, but it does not equate to an immediate reopening of exports. While it increases the likelihood of resumption, political and logistical challenges remain. If Baghdad, Erbil, and the IOCs can finalise agreements, and if Turkey cooperates, exports could restart in 2025.
Other players in the regions will be pushing for this and bit by bit the barriers are being removed. Let's not forget, even without this, the local supplies are doing well and providing a decent income.
7% fall in Zotefoams (LON:ZTF) anyone know why?
No clue. Only bought middle of last week as well. Not the best timing!
Zotefoams (LON:ZTF) is this particularly exposed to US trariffs? Not sure how much business they do with the US
I thought this would have a minimal impact if any but perhaps the markets opinion differs?
Zotefoams (LON:ZTF) supply Nike, it is a major contract. But most of Nike's products are made in Asia, l thought. Not sure if it will impact them. I suppose it will push up prices if they imported to the US. May mean switching manufacturing from say China to Vietnam or Indonesia.
Zotefoams (LON:ZTF) has a manufacturing facility in Kentucky, so I would assume they are fine.
And mid way through investing £10m in additional piece of expensive production machinery to create foam.
US market a big customer eg Nike, maybe, shoes also made in Mexico. Hard to say, trumps trade tariffs bound to impact manufacturers. But I can’t see shoe manufacturing moving to US changing their economy! I Hold and am equally disappointed. Trump could cause a lot of damage don’t understand why people trust him.
Zotefoams (LON:ZTF) is reverting to it's trend line after the breakout from the last results didn't hold. Note it fell heavily on Friday also. There's price support at £2.75 and £2.50:
Last week Schroders announced that they had reduced their holding in ZTF from 16% to 15%. Perhaps with the change of strategy announced by the board a couple of months ago, to shelve Rezorce, Schroders may no longer be interested in holding a stake or such a large stake. ZTF is pretty illiquid so without another fund steppng in to take up the slack it is possible that the share price will continue to slide till the point where the value is such that buyers come in in size? Either that or Schroders will have a price lower than which they will not be prepared to sell and they will just drip shares into the market until they are done.
Interesting article in the Telegraph re Shein float According to the Telegraph..
"Stop Uyghur Genocide has kickstarted a judicial review process to block the Chinese fast fashion empire’s planned float amid concerns over alleged abuses in the company’s supply chain."
The Telegraph goes onto to say that the Labour Government is reportedly in support of the deal
Full article behind a paywall.
As I stated here before - if the UK gov simply stopped allowing imports under £130 VAT free that would have an immediate impact on shein and others who seem to make their money not only on cheap labour but tax free pricing.
I don't have any special knowledge of the situation but would suspect that if this was proposed Shein would simply not float here.
As I have mentioned before, I don't think that the Government has much of a bargaining hand on this one.
I don't have any special knowledge of the situation but would suspect that if this was proposed Shein would simply not float here.
I would presume the opposite - my logic being if they want to be legit , they wouldnt want to have an accusation being thrown at them that they still had an artificial advantage over uk based firms unless its simply down to uk powers that be that make it so. I could be totally wrong here and i wouldnt like to wage too much at odds of 50/50 -but i would have small wager that the £130 import limit is something they will have active contingencies for and would probably just suffer if tehy still beenfit and that is withdrawn. Hey ho when it come to plugging these obvious tax loopholes it never quite seems to be the priority of the current incumbents of office to take on these big firms - so perhaps teh fact they are listing means chances of loophole being plugged are very low wink nudge wink - brown paper bag on the books . Presumably sheins plans are such that uk sales will end up only being minor % of overall sales - so i suspect they will accept what any country throws at them within reason.
"my logic being if they want to be legit"
There is no possibility of them being legit whilst the forced labour allegations remain unanswered.
Gulf Keystone Petroleum (LON:GKP) Is today's leap up (+9%) an UPSIDE to tariff mayhem?
Sipan Sherwani, a member of the Kurdistan Democratic Party’s (KDP) parliamentary bloc, confirmed to Kurdistan24 correspondent Dilan Barzan that this legislative move eliminates all legal obstacles preventing the Kurdistan Region from exporting its oil. So NO it's other GOOD news
Probably because I sold my holdings last week :/
Hi Snowdrop - please see the link I posted earlier on with the info
sadly SPM your post was not on the site when I posted mine. I just noted that my own holding had lept and then pasted a section of your article link when I discovered the actuality.
No, I don't believe so. More likely it's a continuation of last week's rise as the possibility that talks about reopening the pipeline seemsto be getting somewhere.
Hi Graham. Thanks for the analysis on £UTP (I hold)
They are maintaining their capital allocation policy which includes dividends and buybacks? However, based on a 50% of profits this suggests a flat or downward movement for ye '26.
In respect of buy backs I think when they reference buybacks these are shares bought for the Employee Benefit Trust. So in effect this reduces future dilution of share options being crystalised as a real increase in the share register, but it could also mean increasing rewards to staff and directors if more options are issued.
Personally, I think generally they have taken a balanced view of both sides but with a slight nervousness on how much further buy backs have to go on backing share option awards.
We have been here before with dips on performance, and I agree there is some underlying growth, and the management are quite sensible overall.
Hi Trident, thank you very much for the comment but Roland has covered this, not me. I'll let him know. G
Hi Trident,
Thanks for your comments on Ultimate Products (LON:ULTP) .
I didn't mention buybacks in the interests of brevity but you're correct, according to today's update they are planning to continue these. In fact, I've just seen they issued a second RNS today around 8am, specifically about buybacks. This was too late for our 7am sweep.
Ultimate's buyback policy is to maintain leverage at 1x EBITDA after paying dividends at 50% of earnings. So in effect, the company seems to say that anytime there is additional surplus cash beyond the dividend, it will be funnelled into buybacks.
The current buyback programme was announced in May 2024 and is continuing, with a further £2m tranche beginning today.
Checking back to the announcement last May, the company says all shares repurchased will be cancelled (not kept for the Employee Benefit Trust):
"Any Ordinary Shares purchased under the Share Buyback Programme will be cancelled and the number of Ordinary Shares in issue reduced accordingly."
I am not generally a fan of leverage targets. But at current levels I do think that buybacks could provide good value for money, assuming trading recovers in the not-too-distant future.
Roland
Thanks Roland. I hear what you are saying about the Buybacks. I think in the past they have had certain purchases for their Employee Trust, but maybe this is outside the formal BuyBack programme.
Ultimate Products (LON:ULTP) is yet another example supporting the ruthless tactic I use of selling on the first signs of bad news and when there’s a profits warning. Selling then is often ahead of further falls and ahead of the next profits warning.
Another thing to bear in mind when finding excuses to hang on to our shares after profits warnings is that there are plenty of alternatives issuing regular “better than expected” updates that are far more likely to see significant share price gains.
Here’s the trading update Ultimate Products (LON:ULTP) issued last May that saw the share price fall heavily to 140p. The price did recover for a while but today is down to 83p. Note “revenue down……trading impacted by slowdown in near-term sales…..these conditions likely to continue throughout Q4.”………and perhaps beyond too?
“Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), announces its Q3 trading update for the period from 1 February 2024 to 30 April 2024.
In the Group's interim results, it reported total revenue down 4% with Adjusted EBITDA broadly flat on the prior year. Since that time, trading has been impacted by a slowdown in near-term sales from landed stocks (call off, regular stock and online sales), typically at higher gross margin, reflecting the broader slowdown seen in retail sales to consumers. This has resulted in revenue being down 7% year-on-year for Q3. The Directors believe it is sensible to assume that these trading conditions will continue throughout Q4. Therefore, the Directors expect FY24 revenues to be at least £156m, with gross margin being in line with last year, and Adjusted EBITDA to be in a range of £17.5-18.5m.
As the year progresses, we are continuing to see the gradual resumption of normal ordering patterns from our retailer customers as the overstocking issues brought about by the pandemic subside. The increase in forward ordering by retailers has primarily been benefitting our forward order book for FY25, and as a result we are already seeing significant growth over the FY24 order book. The Directors therefore have confidence in the Group's prospects for FY25.
Commenting on the update, Andrew Gossage, Chief Executive of Ultimate Products, said:
"It is disappointing that Spring has seen continued poor demand from consumers, which has adversely affected sales in the current quarter. Our assumption is that these challenging conditions will persist in the short-term and so impact our FY24 outcome. In contrast, the order book for FY25, at this early stage, is significantly ahead of FY24 as retailers continue to increase their forward orders as the overstocking issues brought about by the pandemic subside and consumer confidence builds as we see a return to real wage growth. As such, we remain confident in the Group's medium-term prospects."
* Consensus market expectations for the financial year ending 31 July 2024 are currently revenues of £166.7m, adjusted EBITDA of £21.5m and adjusted EPS of 15.6p”
Ken, you have guided us on this point, SELL at first warning, a few times as have the Stoko team and their stats. I thank you all, it is beginning to sink in even with a thicko like me. But to encourage us could you guide further on: there are plenty of alternatives issuing regular “better than expected” updates that are far more likely to see significant share price gains.
Ed Croft covered “better than expected” updates in this superb article. It’s a must read.
https://www.stockopedia.com/co...
One very good place to find those “better than expected” updates is this very thread.
A few of the many examples include Next (LON:NXT) share price doubled since Oct 2022 low and from about 10p many years ago.
Marks and Spencer (LON:MKS) share price recently quadrupled from 2022 low when it was a screaming buy.
Games Workshop (LON:GAW) share price is up from £56 this time 3 years ago to £144. I bought only a few years ago at just £4.60. I sold far too soon for a modest profit. I’m more sensible now in running winners all the while updates are good instead of selling on a whim possibly because something else appealed that day!
Gulf Keystone Petroleum (LON:GKP) share price has doubled in the past year including another 12% today. Somehow they managed to do well despite pipe line closure and to pay significant dividends again. The pipeline dispute might be at the endgame too.
TP Icap (LON:TCAP) has risen from £1 to £2.70 in 3 years.
The above are just a very few examples of shares I either hold or have held and still monitor. There are many more!
In contrast look at updates from Asos (LON:ASC) Boohoo (LON:BOO) QUIZ, JOULES and REVOLUTION BARS (before the name change). All have proved to be disastrous investments or gone bust. Update after update provided warnings but pundits and those of us holding, too often tried to find excuses when covering and/or holding them.
I held all these big losers except ASOS and lost on all of them, and heavily on Boohoo (LON:BOO). That’s why now I’ve become ruthless in selling at first signs of bad news. It’s working very well….whereas holding on and finding supposed excuses for bad news, didn’t!
Yes don't listen to pundits or tipsters, making out the profit warning, is not so bad, get out. Some people can't admit they got it wrong.
Can't have any ego investing
Ken,
Very wise words indeed. There is a saying that covers this and it is one I follow.
" you don't have to get your money back the same way you lost it !"
excellent and thanks again. Of the goodies quoted, next is the only one missing from my stack. It's selling the duds fast that makes the difference!
Just to comment a bit on £UTP when I first invested in them I did so because of some large Director buys. Unfortunately they then had a trading blip, and the shares went down quite a bit. In due course trading improved, and shareholder rewards via dividends etc were also good, so against my usual policy I significantly added more, and was rewarded with a pretty good return medium term. That said, sell on a profit warning is not a bad philosophy for an investor, and I have hugged and held some underperforming stocks way way too long, but am working to cure that tendency.
If Trump is going to put tariffs on EU trade but not on UK then this would bode well for UK. The EU would have to shift some manufacturing to UK
We don’t want to be Trumps dog, our weak politicians will probably have sign up to their factory farm produce amongst other horrors. Plus he flip flops no manufacturer is going to move here, they’ll sit out his term.
Also if there is any wiff that the UK are benefiting from this over USA. Trump will quickly slam it on to us. The best we can hope for is flying under the radar and try keep some normality while he is in power.
Trade in goods between US and UK is fairly balanced (services UK is in large surplus but hard to put tariffs on). Am not sure why he is being flexible with UK unless he wants to divide us from EU further or indeed flog us agricultural produce. He is a real estate guy so he'll want his pound of flesh. A good trade deal would bolster Reform Party so that could be a possibility. Stanmer is in weak position with UK close to it's credit card limit (and Labour are at idealogical odds with his philosophy) so I can't fathom why Trump is being civil with him but am convinced he has a, as yet unknown, cunning plan. It might be good for UK markets in short term though.
...Am not sure why he [Trump] is being flexible with the UK unless he wants to divide us from EU further or indeed flog us agricultural produce. ...Starmer is in weak position...so I can't fathom why Trump is being civil with him but am convinced he has a, as yet unknown, cunning plan.
Perhaps vaguely relevant:
Trump's mother was British. He spent time in Scotland when he was younger and he has real estate interests here. If requested, Britain would be obliged to grant citizenship and residency. What is the cost of keeping an escape route open?
On the other hand, perhaps the reason behind the current attitude is that many large defence companies are both British and American.
-But I expect we will get the Trump treatment eventually.
Surely the idea of Trump having a "cunning plan" seems pretty unlikely, and looking less so by the day.
I would say it’s an oxymoron (no pun intended)
not if Stammer continues to cosy up EU.
It will be interesting to see how things go. I think there are elections to Congress are in 2 years time, and any narrow majorities for Trump may increase or decline in that time.
I don't think Trump could be ever accused of having a 'strategy', other than to tear up whatever the previous President has tried to do. But I wonder if his tariff war is a two part effort to balance the under investment of Europe in defence spending, with bringing back more dollars to the US through a tariff war in addition to pressure for defence spending.
China & Europe has been using Mexico as a means of getting their goods into the US below the tariff barrier, by setting up factories there, so plugging the holes caused by Trumps policies is a moveable feast and the UK may become a better target depending on how trade talks go. Biden wasn't that friendly to us.
I don't think Trump could be ever accused of having a 'strategy', other than to tear up whatever the previous President has tried to do
But Musk has, in spades, and he has the president's ear (for now at least)
How does Trump's policies align with EVs?
He doesn't like them. Haven't seen a policy but it will come. Musk's long term goal is to get to Mars and he needs the support of government to achieve this so he can trade off Tesla and Mars
Good morning. News out over the weekend onGulf Keystone Petroleum (LON:GKP) , as per the attached link https://www.kurdistan24.net/en.... Explains why the stock is up another 8% or so this morning.
Just when you thought markets were stabilising...
Re; Ultimate Products
It would be interesting to know who a the "larger customers" of Ultimate Products and to see if there is any read across into a retail slow down.
I assumed that B&M was a major customer - but a recent visit to the store suggested only a couple of UP product lines.
A key concern with UP is that as a small supplier it possibly has limited bargaining power with its larger customers. If customers dictate price and delivery schedules then it is difficult to see what UP can do other than to accept.
Ultimate Products (LON:ULTP) I've never understood the attraction of this stock, we have been using the same bathroom scales for over 25 years and we're not rushing out to replace our air fryer anytime soon either....so many attractively priced, growing, recurring revenue companies out there, why bother with this?
All these new houses need kitting out but hey, we're investors in equities and I moved on from Ultimate Products around a year ago.
Re; Ultimate Products
It's not a company with a moat - that's for sure.
One other point which might be significant for holders is Home Bargains and the Pifco brand.
Recent visit to HB had nearly two aisles of PIfco brands looking to me like it is now hitting UP head on in this respect.
Given the torrid economic backdrop, not helped by the clueless Trump, Sigmaroc (LON:SRC) has delivered a positive outcome for the full year.
I have a good sized position having held and added since pre-pandemic. I have meet the management team lead by CEO, Max Vermoken and admire their ambition and entrepreneurial approach. Once the residential house building gains traction, whenever that may be I expect the shares to do likewise.
I hold also and agree with you, they just need that lift in the housing market and infrastructure to move from "blah blah" to action.
Oh for the days of the clueless Biden NOT. Thank heavens we haven't got the hapless Harris in office.
Are we in for a protracted tariff driven pullback then? Tariffs are far outside my experience, it feels more like the steam age!
Look at charts from Jan 2018, when Trump last announced tariffs on the 22/1.
Looks like a similar pattern.
Hi Paul2148 - Yep same behaviour - I don't wish to get small p political here, but Methinks more politicians show signs of being GRIFTERS. Not standing for office to serve
My badly made point here is - Money is made when markets move unexpectedly
(Depends who thinks its unexpected?)
Personally I find this article alarming - Reports suggest members of Musk-led Department of Government Efficiency (Doge) - which is not a government department, but a team within the administration - have been granted access to sensitive personal information of millions of Americans. thttps://www.bbc.co.uk/news/art...
How is the use of this data being regulated?
PS
Personally I find this article alarming
who are then grifters though - those dishing out the money of others or those trying to minimise that spend?
As far as i am aware doge exists due to an executive order of the newly elected president and was based on comment he made pre election that he would tackle government spending . How on earth is this department meant to cut spedning without have suitable overview of how the money is being spent.
Do free and fair elections worry you ? america pretty much got what it voted for.
You 100% got my point America pretty much got what it voted for.
AND a free hand for their president and his choice of advisor to disrupt
He's going to clean the swamp better than he did in his first term with far more able and trusted people in all the key positions. While he shakes up America he will also shake up the World, and boy do we need it.
Shake it up to suit himself and his cronies. We dont need that.
His cronies will go to Mars - yours will live on them.
A country ruled by business people with common sense, entrepreneurialism and pride in their country.
Who wants that?
I prefer low productivity, no growth, socialist, woke, crime ridden, open border, no identity - er Grate Britain.
Apologies this is an investment site and got suckered.
Just dipped into Credo Technology Holding (NSQ:CRDO) despite DeepNowt other than NVIDIA (NSQ:NVDA) everyone else doing fine.