Daily Stock Market Report (Mon 6th October 2025) - QTX, Beauty Tech IPO, SDY, AML, BKS, TET, DIA, BBSN

Good morning! And welcome back to Roland from his holiday.
Apologies for the lateness of today's report - I lost internet connection this afternoon for the first time in years! Will add a few more sections to finish off. All finished for today.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view |
|---|---|---|---|
Mondi (LON:MNDI) (£4.6bn) | Adj EBITDA -19% to €223m vs Q2. “Challenging trading” with oversupply. Current prices below Q3 average prices. | ||
Sirius Real Estate (LON:SRE) (£1.47bn) | YoY rent roll +15.2% (+5.2% LFL), with €300m acquisitions YTD. On track to deliver FY results in line with exps. | ||
Aston Martin Lagonda Global Holdings (LON:AML) (£823m) | PW: FY vols to decline by “mid-high single digit” %. FY25 adj EBIT to be below bottom end of exps (<£110m). | BLACK (RED) (Graham) [no section below] Some may argue that there is no point in my covering this, as I am only ever going to be RED on it. However, I think that in order to fully appreciate what makes good companies “good”, it helps to be aware of what makes bad companies “bad”. In the case of AML, the investment case hasn’t matched the elegance of the cars, as the company has been consistently loss-making ever since it floated, and earnings forecasts have a strong tendency to be downgraded. Car manufacturing is a highly capital-intensive process at the best of times, where the largest operators struggle to generate an attractive profit margin, and where small brands such as AML require very strong margins to turn a profit at all. AML has been unable to do this and has also (consequently) suffered from a very weak balance sheet, requiring regular fundraisings. The most recent interim results to June showed net debt of £1.4 billion; the company is rated B- by Fitch, which is at the lower end of “highly speculative”, and its outlook was changed to negative earlier this year. Of course I’ll keep our RED on this stock after today’s latest profit warning. | |
ITM Power (LON:ITM) (£488m) | Project shortlisted in UK HAR2 round, expects to be operational in 2028. No value provided. | ||
Ferrexpo (LON:FXPO) (£316m) | Commercial production +3% to 1.51mt vs Q2, but -29% vs Q1. Withheld VAT now $47m, production down to one line. | ||
Treatt (LON:TET) (£161m) | Final cash offer from Natara of 290p per share; 29.5% premium to 5/9 close. (Previous offer was 260p.) | PINK (under offer) (Graham) [no section below] | |
Beeks Financial Cloud (LON:BKS) (£148m) | Rev +26%, adj PBT +41% to £5.5m. Recurring revenue +5% to £29.5m. FY26 outlook in line with exps. | AMBER (Roland) | |
Quartix Technologies (LON:QTX) (£138m) | Q3 “very strong”. FY25 rev and profit to “slightly exceed” latest market forecasts. FY26 outlook “improved”. | GREEN (Roland) Today’s Q3 update reads well and contains the sixth upgrade to guidance since July 2024. Founder Andrew Walters has done an excellent job since returning to the business two years ago and it’s hard to fault recent performance, in my view. International growth is encouraging with nearly half the group’s revenue now generated outside its core UK market. I can see some risk that pricing power or growth could falter as Quartix competes against rivals backed by big corporate owners. But I’m happy to remain positive given excellent quality metrics and strong cash generation. While the P/E of 22 isn’t cheap, I don’t think it’s unreasonable given expected double-digit EPS growth. | |
Speedy Hire (LON:SDY) (£111m) | Agreed supply deal with HSS ProService, will take 10% equity stake and purchase some assets for £35m. | AMBER (Roland) [no section below] The market has reacted well to today’s news that Speedy will become the first-choice supplier to ProService (HSS’s digital sales channel). Speedy will also take a 10% stake in the restructured ProService business and acquire certain assets, listed as “three distribution centres, motor vehicles and hire equipment”. Without any details it’s hard for us to gauge if this is likely to represent an attractive investment for £35m. Speedy expects “a full payback” through operating cash flow in “two to three years”. However, today’s note from Panmure Liberum suggests leverage will rise to 2.1x by March 26 as a result of this deal (FY25: 1.9x). To support deleveraging over the next two years, Speedy’s dividend is being cut by 61% to 1p for FY26, although management hopes to reinstate the payout to current levels in FY29. The obvious attraction here is that Speedy Hire will gain additional volumes and market share in a competitive and somewhat commoditised sector. That’s not a bad thing and today’s broker note suggests it could drive a meaningful recovery in earnings. However, Speedy Hire warned on profits in February and has historically generated low returns. It’s also been somewhat accident prone. I would like to see concrete evidence of the benefits of this deal with HSS (also a poor quality business, in my view) before turning positive, so I’m going to mirror the StockRanks and leave Graham’s previous neutral view unchanged today. | |
Avation (LON:AVAP) (£109m) | Appointed advisors to arrange investor meetings for new $300-400m credit offering. | ||
Jubilee Metals (LON:JLP) (£104m) | Now received first tranche of $15m sale proceeds. Progressing 3-stage plan to develop Zambia copper assets. | ||
Dialight (LON:DIA) (£97m) | Sales are marginally down but margin improvement, cost reduction and cash generation continued to improve. “Expects to significantly exceed Adjusted Operating Profit expectations.” But also: “the Group remains cautious on the sales outlook for the full financial year to 31 March 2026 due to this continuing uncertainty.” | AMBER/RED (Graham) [no section below] My existing RED stance on this - as explained here - is to do with balance sheet safety, and therefore I can give it an upgrade by one notch today on the news that net debt has improved significantly to $10.2m (March 2025: $17.8m), helped by $3m of credits from the IRS. That debt level is less than £8m, i.e. less than 10% of the market cap. Therefore, even if the company still had any risk of breaching covenants, and there was a short-term emergency, one might expect that the company could fill the gap with a small fundraise. So hopefully the balance sheet concerns are no longer valid here - more will undoubtedly be revealed at the interim results. Looking at the company more broadly, I remain very careful when it comes to stocks in the lighting sector, due to volatile demand, and I note that the company’s messages today are very mixed: they are beating operating profit expectations, but accompanying that with an extremely cautious sales outlook. So I’d still be inclined to view this as a high-risk play, and not particularly cheap at a c. £100m market cap. | |
Brave Bison (LON:BBSN) (£91m) | GM convened on behalf of Lord Ashcroft to appoint a new NED. 51% of shares have indicated they support Board’s opposition to this. | AMBER/GREEN (Graham) [no section below] It sounds like Lord Ashcroft's attempt to get the CEO of Impellam, Julia Robertson, onto the board of Brave Bison is now doomed to failure. Shareholders owning the majority of the shares have now indicated they support the Board on this. I do find it a little surprising that the Conservative peer is unable to get a NED appointed, seeing as he owns 24% of the company. The level of opposition is impressive, with two thirds of the entire shareholder register (excluding Lord Ashcroft) providing written indications of support. Incidents like this often lead to escalation of some sort - perhaps we will see him increase his stake further? For our most recent coverage of this stock, please see here (Sep 11th). | |
Batm Advanced Communications (LON:BVC) (£79m) | Sells A.M.S 2000 Trading Impex to Dr. Zvi Marom in exchange for his shareholding in BATM, c. 22% of the company. Transaction values AMS at £17.6m. | ||
Alternative Income REIT (LON:AIRE) (£58m) | NAVps +3.4% (83.64p). Year-end discount falls from 18.4% to 11.5%. Dividend resets lower due to increased financing costs. | ||
Hemogenyx Pharmaceuticals (LON:HEMO) (£58m) | Institutional Review Board at MD Anderson Cancer Center has allowed children and adolescents in Phase 1 trial of HG-CT-1. | ||
1Spatial (LON:SPA) (£53m) | Signed £1m, 15-month contract with UK Power Networks for 1Streetworks platform, with a one-year extension option. | ||
HSS Hire (LON:HSS) (£52m) (suspended) | Final Results & ProService Supply Agreement with Speedy Hire | 15-month period to March 2025: £130m loss, underlying PBT minus £8.4m. Material uncertainty. Suspension is lifted. | |
Skinbiotherapeutics (LON:SBTX) (£38m) | SBTX received a list of participating Superdrug Stores for 1st phase of AxisBiotix™ launch. | ||
Manx Financial (LON:MFX) (£33m) | Neil Jeffery, consultant with subsidiary Payment Assist Limited, has been retained by Manx Ventures Limited until 2023. | ||
Litigation Capital Management (LON:LIT) (£13m) | Funded party unsuccessful in seeking to appeal arbitration loss, Investment held at a value of £1.4 million to be written off. |
Graham's Section
Beauty Tech (LON:TBTG)
Down 2% to 281.55 (£312m) - IPO (Announcement of Pricing and Offer Size) - Graham - AMBER
Last week saw the first major IPO in London of 2025: Beauty Tech (LON:TBTG).
It looks to be the biggest IPO since Applied Nutrition (LON:APN) and Raspberry PI Holdings (LON:RPI), which both took place last year.
Some of the key facts:
39 million shares sold at 271p
Implied gross proceeds: £106.5m
Net proceeds: £101m, of which £28m is receivable by the company, while £73m goes to selling shareholders.
As a general rule of thumb, I like to see IPOs where more money is being raised by the company (presumably to fund growth) rather than by selling shareholders.
On Friday, the shares closed at 288p, up 6%: a sign of a well-run IPO where there was more demand than supply at the IPO price.
Berenberg and Rothschild managed the IPO with the help of RetailBook (owned by Peel Hunt, Hargreaves Lansdown and others).
What it does:
What began in 2009 with the launch of CurrentBody has since evolved into a portfolio of category-leading brands, including CurrentBody Skin, ZIIP Beauty and Tria Laser. Together, they give us product excellence across the four core clinic based technologies of LED, radio-frequency, microcurrent and laser.
The “signature devices” from CurrentBody are an LED Red Light Therapy Mask (costs £499) and a Radio Frequency Skin Tightening Device (costs £299).
Red Light Therapy Mask:
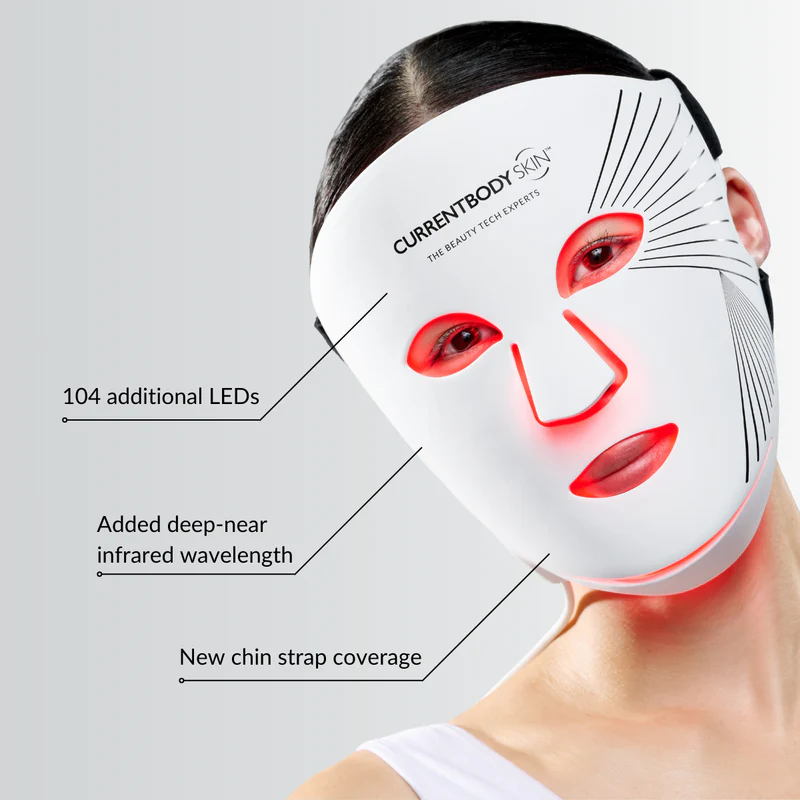
I’m not familiar with this technology - and I would not presume that any of our readers need any of these devices!
The Therapy Mask provides “advanced skin brightening, clearing and anti-ageing”.
Historical financial information - FY December 2024
Digging through documents on the IPO website, I find the following information:
FY 2024 revenue: £101m
Gross profit £57m
Operating profit £12.6m before the impact of IPO-related costs of £7.2m.
Firstly, I would say that the high gross profit/gross margin of over 50% is a good start - an initial indicator that we are looking at a high-quality business, with pricing power.
Secondly, I agree with excluding IPO-related costs, so I am happy to use the £12.6m operating profit figure.
Moving further down the income statement, there was a large interest bill (“finance costs” are £8.6m).
But the footnotes tell us that using the IPO proceeds, the company is to pay off £22.5m of bank loans. They are also converting loan notes and preference shares into shares, and will have a “debt-free position at IPO”.
With bank loans, loan notes and preference shares all eliminated, £8.6m of finance costs would have been drastically reduced.
So in summary: 2024 saw over £100m of revenue, a >50% gross profit margin, and an operating profit of £12.6m.
Interim financials to June 2025
We also get interim results to June 2025.
Key points:
Revenue £55m (up 27%)
Gross profit £33.6m (61% gross margin)
Operating profit £9.3m, up more than 100% against the previous H1.
Finance costs are £4m but this includes interest on loan notes and preference shares - and as we just mentioned, these costs should not be continuing.
I note also that the operating profit figure is after charging “exceptional administrative expenses” of £1.5m, with “deal fees” (relating to exploring a private equity acquisition, and IPO-related costs) of over £1m.
27% revenue growth in H1 is very impressive, but dig beneath the surface and there are a lot of moving parts. The main driver was 56% growth in the main brand Currentbody, while at the same time the company discontinued reselling Third Party products, which resulted in a loss of revenue.
Shareholders after IPO
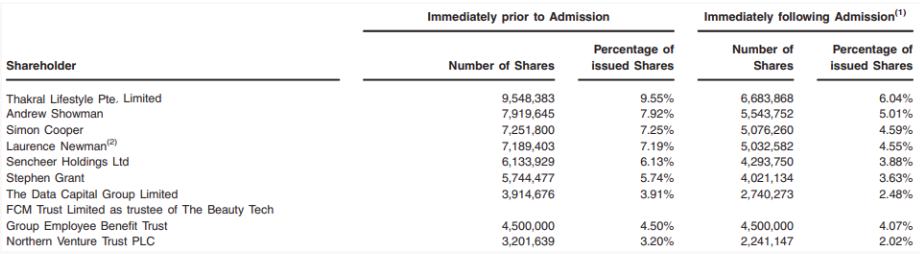
Some key points here: this is clearly a liquidity event for existing shareholders, but it looks like they are all keeping most of their existing stakes.
Laurence Newman is the founder and CEO: his stake reduces from 7.2% to 4.6%.
As an aside, I note that Northern Venture Trust PLC is managed by Mercia Asset Management (LON:MERC). Beauty Tech’s headquarters are in Manchester.
Comment by Laurence Newman:
"I am incredibly proud of everything The Beauty Tech Group has achieved since we launched CurrentBody in 2009. From establishing ourselves as a global leader in the fast growing at-home beauty technology market to successfully completing this milestone listing on the London Stock Exchange, the Group continues to go from strength to strength.
"As we enter the next stage of our growth journey, this IPO provides the perfect platform to increase awareness of our three distinct, premium brands and take the Group to the next level, while delivering sustained and profitable growth. The continued momentum within the business and strong support from investors during our roadshow, gives us the confidence and financial firepower to fully capitalise on the significant opportunities that lie before us.”
Graham’s view
I’m still getting familiar with this company, so I’m not going to express a very strong opinion on this today.
Some positive points:
Founder-led, and the founder-CEO still has a position in the shares after the IPO.
The balance sheet should be fine - not cash-rich, but not carrying excessive debt either.
While I don’t know much about the company’s products, it seems that this sector - beauty technology at home - ought to be a growth sector for the foreseeable future, due to the technology involved becoming gradually more affordable and effective.
Some risks and negative points:
While some of the IPO money has gone to the company, most of it has gone to selling shareholders.
The money that has been received by the company is mostly being used to repair the balance sheet, rather than directly funding growth.
Is there a risk of LEDs/laser products becoming more strictly regulated? And do these products actually work? I don’t know!
As usual, I’ll apply my IPO rule, which says that the stock is likely to remain overvalued after IPO for at least two years, or until the share price has fallen by 50%.
A price to sales multiple of 6x is certainly quite adventurous, although with strong margins the P/E multiple for the current year might actually turn out to be reasonable for a high-growth consumer-facing company.
For example, operating profit should be well over £20m, considering that the seasonally most important Q4 period has not happened yet. Then adjusted net income after 25% tax should be over £15m, which would put the P/E on less than 20x.
On seasonality:
The Group experiences a significant degree of seasonality, with a substantial portion of its annual revenue generated during the fourth quarter of the year. In particular, sales volumes peak in November and December, driven primarily by increased consumer spending associated with Black Friday, Cyber Monday, and the holiday shopping season leading up to Christmas.
A cynic might argue that it’s suspicious that the company would get its IPO away just before sales volumes are forecast to peak for the year. Will this become one of those IPOs that issues a disgraceful profit warning very shortly after listing - I hope not!
Overall, I’m going AMBER on this. I’m delighted to have a big IPO to look at, as they are necessary for the long-term health of the market. And it will be a bonus if these shares turn out to be a decent investment.
Roland's Section
Quartix Technologies (LON:QTX)
+12% at 318p (£154m) - Trading Statement - Roland - GREEN
The Company now expects to slightly exceed the most-recently updated market estimates for revenue and profit for the full year.
This fleet telematics specialist has staged a strong recovery over the last year. The stock has double-bagged since founder Andrew Walters returned to take charge of the business in October 2023.
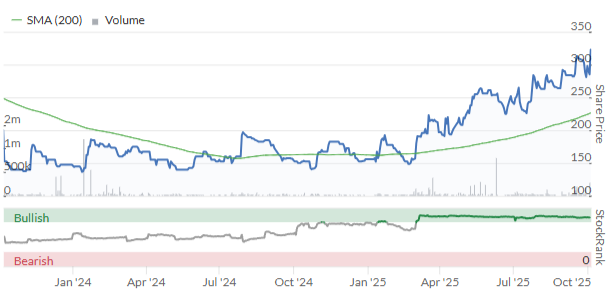
This has been mirrored by a series of broker upgrades – today’s upgrade is the sixth since July 2024, according to today’s note from house broker Cavendish. This is reflected by the broker trend chart on the StockReport:
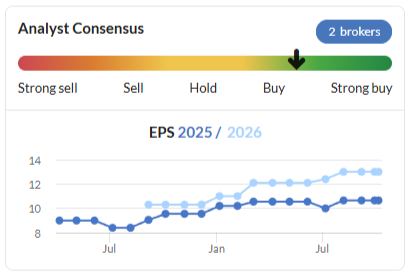
Let’s take a look at today’s update to see what’s changed.
Q3 trading - FY upgrade: financial performance during the most recent quarter is described as “very strong”.
During the first nine months of 2025, Quartix’s annualised recurring revenue (ARR) rose by £3.5m (+11%) to £36.1m. In value terms, that’s equal to the ARR growth achieved during the whole of last year.
As a result, both sales and profits for the full year are now expected to be ahead of previous market forecasts for revenue of £36m and adjusted PBT of £7.1m:
One factor driving these gains was the implementation of the company’s second annual price increase earlier this year. I think this is important. Telematics services are relatively cheap on a per-vehicle basis and costs have come down in cost over the years, as might be expected. For these reasons I’m encouraged to see that Quartix’s services have sufficient appeal to support both price increases and growth.
A greater focus on subscriptions should also help support visibility and margins. The company says hardware now accounts for under 3% of sales, with 94% of revenue coming from subscriptions.
Cash generation was further boosted in Q3 as production of the company’s latest, lower-cost tracking system TCSV17 reached full production, allowing stocks of the previous TCSV15 to be run down. Going forward, this transition is expected to support higher gross margins. Cash costs from 4G upgrades are also expected to taper.
Management says free cash flow for the first nine months of 2025 was £4.3m, exceeding previous full-year forecasts of £4.1m.
Outlook & Updated Estimates
Executive chairman Walters sounds confident about the prospects for the next 15 months:
"We have made substantial progress in many key aspects of our business during the first 9 months of 2025. Over the past 12 months our annualised subscription revenues have risen by a record £4.3m, or 14%, to £36.0m; we look forward to the remainder of the year and 2026 with confidence."
With thanks to broker Cavendish, we have access to updated forecasts today showing the scale of today’s upgrade:
Revenue | EPS | |
FY25E | £36.1m (prev. £36.0m) | 11.5p (prev. 11.2p) |
FY26E | £40.3m (prev. £39.9m) | 14.6p (prev. 13.8p) |
While changes to revenue growth forecasts are minimal, these new forecasts increase FY25 EPS by 2.7% and FY26E EPS by 5.8% – useful increases.
Taking into account this morning’s double-digit share price gain, I estimate this leaves Quartix on a FY26E P/E of 22.
Roland’s view
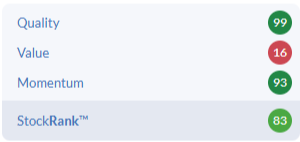
Quartix has been a good example of a turnaround with good fundamentals where investors have been able to ride the momentum and benefit from a significant re-rating. Momentum remains strong but the stock’s value rating has declined, leaving it in High Flyer territory.
The company’s focus on expanding its fleet and international businesses is paying off and seems to be allowing it to gain scale outside its core UK market. I’ve reproduced the charts below from today’s Cavendish note:
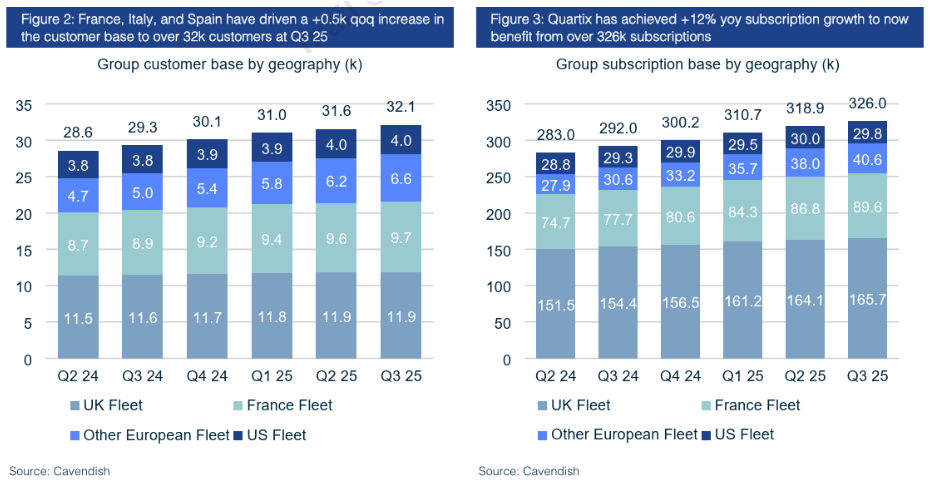
Around 46% of recurring revenue now comes from customers outside the UK, suggesting there could be significant further growth potential.
One point I’ve noticed when I’ve looked at this business before is that Quartix’s customers tend to have small fleets. Or at least, they use telematics on relatively small numbers of vehicles. Crunching the numbers from the Cavendish graphics above give me the following average number of subscriptions [vehicles] per customer:
UK 13.9
France: 9.2
Other European: 6.2
US: 7.5
I guess these averages may mask a small number of larger customers and a long tail of small operators. But I’d see this both as a growth opportunity and perhaps a constraint on long-term growth, depending on whether Quartix can win business from more larger customers or not.
When I looked at this business in depth elsewhere a few years ago, my impression was that a number of key competitors were owned by larger companies. For example, tyre giant Michelin and US mobile operator Verizon both own telematics providers.
At the time I wondered if competitive pressures could limit Quartix’s pricing power and growth potential. I can’t help feeling this remains a medium-term risk, but it certainly doesn’t seem to be a significant problem at the moment.
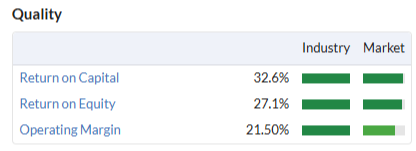
While the stock’s ValueRank of 16 is now at a level that might suggest some caution, quality metrics are excellent here:
As we’ve seen today, momentum also appears to remain strong. Based on today’s forecasts from Cavendish, adjusted earnings are expected to rise by 17% in 2025 and by 27% in 2026.
I took a GREEN view on Quartix in April, but the shares have risen by nearly 50% since then.
I might normally moderate my view to AMBER/GREEN at this point, but I’ve decided to stay positive.
On balance, I don’t think the stock looks too expensive for a business with this level of quality and momentum. Quartix’s strong balance sheet and excellent quality metrics also suggest to me that cash generation could remain very strong as various one-off costs recede, perhaps supporting additional shareholder returns. GREEN
Beeks Financial Cloud (LON:BKS)
Down 9% at 200p (£148m) - Final Results for y/e 30 June 2025 - Roland - AMBER
Our tracking spreadsheet shows that we have been consistently neutral on Beeks this year, most recently in September when Mark reviewed a recent contract announcement.
Beeks provides low-latency computing and connectivity for financial sector customers. For me, the problem is that this business is priced like a high-flying software company but seems to have more of the characteristics of an equipment leasing business. Beeks has consistently reported low profitability and must often fund new customer deployments upfront before receiving ongoing revenue. As a result, strong revenue growth has not been matched by profit growth and profitability has been poor, at least on a statutory basis.
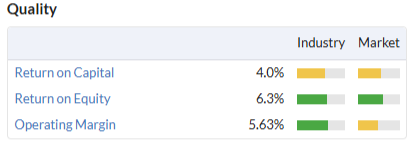
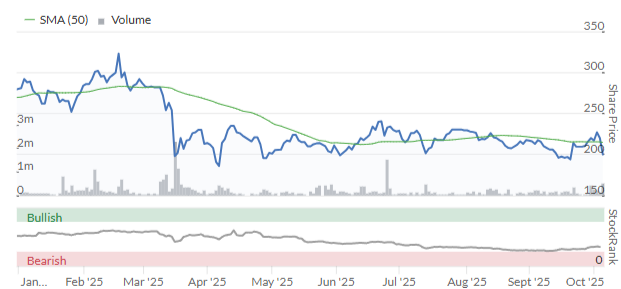
I’m open to the idea that this situation could improve over time as Beeks scales up and transitions to new revenue models. But the shares are down again today, extending a trend that’s seen the shares fall by over 25% so far in 2025:
FY25 results summary
Turning to today’s results, revenue of £35.9m and adjusted earnings of 7.6p per share both appear to be in line with consensus expectations, according to the StockReport.
The company is one of the more talkative members of the market and has kept investors updated with regular RNS releases covering contract wins and other developments. Here are some of the highlights from the past year:
Exchange Cloud contract wins secured with clients including the Australian and Mexican stock exchanges, crypto group Kraken and post-period end, a division of the TMX Group (which owns the Toronto Stock Exchange);
Continued expansion with existing customers, including an Exchange Cloud contract extension with the Johannesburg Stock Exchange;
Proximity Cloud contracts signed including renewals and wins “across brokerage and fintech firms”, including “a leading global FX broker”.
Turning to the accounts, there are some fairly large movements reported for both revenue and profit:
Revenue up 26% to £35.9m
Gross profit up 30% to £14.7m
Gross margin: 40.9% (FY24: 39.8%)
Underlying pre-tax profit up 41% to £5.5m
Reported pre-tax profit up 91% to £2.8m
Net cash of £7.9m (FY24: £6.6m)
Revenue: the company is keen to flag up growth in its newer Exchange and Proximity Cloud services, but these still only account for a minority of revenue. The core Public/Private Cloud business still generates the majority of sales, albeit with minimal growth last year:
Public/Private Cloud revenue up 2.4% to £25.6m
Proximity/Exchange Cloud revenue up 196% to £10.3m
Note: as I understand it, Public/Private Cloud respectively allow customers access to shared or dedicated infrastructure located in Beeks’ own data centres.
Exchange and Proximity Clouds provide customers with similar connectivity stacks deployed into customers’ own data centres. Exchange Cloud is a reseller package designed to allow exchanges to offer white-label services to their own clients, while Proximity Cloud provides dedicated cloud computing infrastructure directly to a single end-user.
These different services have different revenue recognition/payment structures. I’m not familiar with all of the details but Proximity/Exchange Cloud are said to have an upfront revenue element, resulting in a lower level of recurring revenue. Growth in these newer services led to a fall in the proportion of recurring revenue last year:
Annualised Committed Monthly Recurring Revenue up 5% to £29.5m;
Recurring revenue fell to 71% of the total, from 84% in FY24
Profits & margins: depreciation and amortisation charges (on hardware and software) are significant and recurring for a business of this type, due to the need for regular upgrades.
Beeks’ FY25 underlying EBITDA of £13.7m drops down to a reported operating profit of £2.8m when these costs are included.
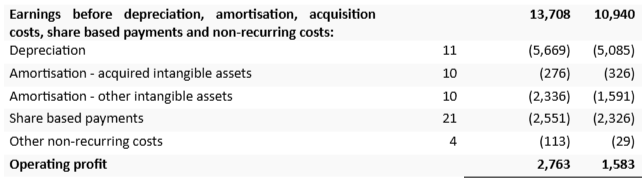
For this reason I am inclined to ignore EBITDA and focus on operating profit (EBIT).
Last year’s increase shows a welcome increase in operating margin at 7.7%, from 5.6% in FY24.
Return on capital employed: this useful improvement in margins translates into a FY25 return on capital employed (ROCE) of 5.9%, according to my sums. That’s better than the 4.1% achieved in FY24, but is of course still a very poor figure that is likely to be below the group’s cost of capital.
In fairness, using average assets over the year lifts ROCE a little higher, as capital employed rose by 20% to £46.7m last year. Last year’s new assets will presumably generate higher returns when they contribute a full year of income (i.e. over the coming year).
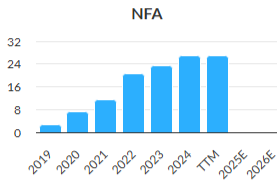
However, this continual growth in capital employed is par for the course with this business, as highlighted on the StockReport by long-term growth in fixed assets:
A review of the historic accounts in Stockopedia suggests to me that there’s limited evidence so far that Beeks’ growth is generating attractive returns:
Capital employed rose by £37.8m to £43.1m between FY18 and FY24;
Over the same period, operating profit rose by 78% to £1.6m;
Thus, the additional capital employed only generated £0.7m of additional operating profit – equivalent to a 1.9% return on the additional capital employed.
Cash generation: net cash rose by £400k to £7m last year, suggesting the group roughly broke even in terms of free cash flow.
Checking the free cash flow statement confirms this, showing that additional cash generated last year was absorbed by working capital outflows and higher capex, both needed to support new business.
Outlook
CEO Gordon McArthur describes FY25 as “another landmark year”. He says that after “two years of market education”, the company is now a “well-established and highly regarded player” in its sector.
Growth prospects are said to be positive, but today’s outlook statement appears to be in line or even slightly below – broker Canaccord Genuity has trimmed its FY26 EPS estimates slightly today, while also introducing FY27 forecasts:
FY26E EPS: 8.9p (prev. 9.1p)
FY27E EPS: 10.5p (new forecast)
These estimates put Beeks on a FY26E P/E of 22.5, falling to 19.0x for FY27.
Roland’s view
Today’s results don’t really change my view on Beeks. While I can see the potential for greater scale and consistent high utilisation to drive improved profitability, the reality is that this remains a relatively low margin and low ROCE business.
Even after today’s share price drop, the shares still look too expensive to me, on a P/E of c.20.
Ahead of today’s results, the Stocko algorithms were rating Beeks as a Falling Star with a low StockRank.
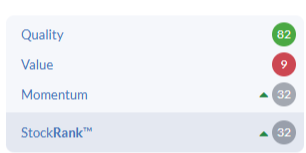
I think this is probably fair. If there was any more leverage here I would probably turn negative, but the group’s net cash position is just about enough for me to leave our neutral view unchanged today. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Thanks for the write up on Quartix Technologies (LON:QTX) I used to be a long term shareholder but sadly due to a professional conflict of interest I had to sell. Since which I have been watching from afar and knew when Walters came back it could be a great turnaround story. I have mixed feelings with it doing so well and what my holding could now be.
BTW can I repeat my polite request of a few months ago. For the results summary table can each box be top left aligned in the format (like you do in excel)? At the moment the format is terrible to read on screen, especially a phone as you have to constantly scroll down and up to know which company results/statement you are referring to.
It is no better on an iPad, each line in the comments, is 1 to 3 words wide. Quartix Technologies (LON:QTX) comment is 45 lines long. I reported this several times to no avail. I'm viewing landscape before anyone suggests that.
If you got rid or reduced the stocks, taking up about 40% of the right hand of the screen, it would solve that. If l turn it to portrait then the stocks disappear. QTX is then only 15 lines long.
Speedy Hire (LON:SDY) is even worse, can't be bothered to count the lines, must be nearly 100.
Hi Gra(nt)ham,
All the best
Beauty Tech (LON:TBTG) looks a decent short to me
Hi Roland
Are the guys doing a piece on Beeks Financial Cloud (LON:BKS) ??
FY results today
yes Threepeat, we are!
Alas no BKS piece :-(
Yes there is, see above.
It arrived very late, but this was due to broadband issues with Graham's providers - very grateful he still came through.
Everybody in my neighbourhood lost their broadband at the same time... I'm using an alternative solution to finish the report! Apologies.
Where is the link to the DSMR archive?
Perhaps better to have it as a permanent link on the home page?
Hi lemming (nice username!) - here is a link to all DSMRs. https://www.stockopedia.com/ed...
Join us tonight from 5pm for another excellent MelloMonday with three company presentations followed by an excellent BASH (Buy, Avoid, Sell, Hold) panel.
The line up for tonight is as follows:
5:00pm John Goold, CEO of Kelso group (LON:KLSO)
5:30pm Company Presentation from Orchard Funding (LON:ORCH)
5:50pm Company Presentation from Eleco (LON:ELCO)
6:20pm BASH (Buy, Avoid, Sell, Hold) Panel featuring Damian Cannon covering Cairn Homes (LON:CRN), Nicholas Cotton covering Seeing Machines (LON:SEE) & Jamie Ward covering Focusrite (LON:TUNE)
Tickets available here: https://www.melloevents.com/mm061025
Please note, if you are a shareholder of any presenting company tonight, you can secure a free ticket using code: MMSHComp25
If not, use code MMSTOCKO50 for 50% off tickets.
Beeks Financial Cloud (LON:BKS)
There is always so much upbeat bullishness in their broker notes and then I look at earnings and cash flow forecasts and I'm so underwhelmed....
Beeks Financial Cloud (LON:BKS)
i think what company like this needs is transparency ref broker notes or paid for reserach - do we have detailed projections for this company for example something along the lines of what equity developments does for Norcros (LON:NXR) - for Norcros (LON:NXR) for example via their website we can see income/cashflow and balance sheet right through to 2028 - so one can see whats planned and one can monitor updates over time. As you say if we get no detail and they concentrate on underlying numbers and ebitda there is so much scope for stuff to be capitalised or extracted by directors - so there is not much left.
Balance sheet here doesnt seem too bad and they are cashflow positive now - share based payments seem very high but preumbaly shouldnt materially increase.
I was always of the presumption here that they were still investing capital wise at present annd that the benefits wouldnt really flow through to teh future.
I would say growth at less than 10% is less than what i would have hoped for - albeit with reduced growth hopefully the figures would be much cleaner ref less capitalised costs and cashflow at or above profits.
I havent looked closely at this one to see how things are trending - one would be hoping if they arent investing for future growth above 10% that they would be trending towards £10 pa free cashflow this year or very soon after - not sure if there is any sign of that after todays update?
Yes always with Beeks Financial Cloud (LON:BKS) the results are underwhelming compared to the rhetoric. Its down around 10% today as they have slipped out that the NASDAQ contract has churned before it ever got started (apparently based on pressure from AWS.)
When there's good news its blasted out for all to see (there were three separate announcements on the winning of this deal) and then slipped into year end results when its lost. It gives us a feeling of what else is hidden.
Revenue growth continues to be strong and the business is gaining traction (they mention they have 6 of the top 30 markets and are talking to 4 more) and so there's no reason to doubt this business won't be significantly bigger in the few years time.
The challenge is it costs a lot up front the Beeks to set them up and therefore cash flow is tough. It has stopped bleeding cash though and is using its cash flow to generate further growth.
I continue to hold and see a day when Gordon cashes in on this through a PE sale but its taking longer than people expected to get there and its probably still a few years off year as we need to get to probably $100-$150m in revenue. I do wish though they would be a bit more open with people. If this was a retail business and they were using cash flow to roll out more shops no one would have an issue which is in effect what they are trying to do.
Thanks for your comments here, I have been a long term holder and must admit I expected better progress than we have seen over the last couple of years. Given their PE ratio I’m sure people are expecting more growth than current forecast. I often think uk tech companies don’t charge enough for their services. Their profit margins aren’t great considering the perceived benefit of their systems, etc.
Beeks Financial Cloud (LON:BKS)
. Given their PE ratio I’m sure people are expecting more growth than current forecast.
I wouldnt necessarily presume that is the case - if one has saas type income (sticky customers who will pay monthly and retention rates are high) some will pay a premium.
Their profit margins aren’t great considering the perceived benefit of their systems, etc.
one would like to hope operational gearing would kick in at some stage.
Imho thought its up to the company to lay out simply the future propsects in that regard that slap us in the face ref prospects - so something like detailed numbers ED do for norcros would be really useful.
Avation (LON:AVAP) News this morning on RNS about them having appointed advisors to refinance their unsecured notes due October 2026. This is a very sensible move despite seeming to be very early for three reasons:
1. Most non investment grade bonds have non call protection that becomes less onerous each year prior to their maturity date, with the call premium falling to zero in the final year. They would therefore be able to call the existing notes at par (i.e. 100 cash price) rather than having to pay a premium to holders.
2. Right now corporate credit spreads are very tight by historical standards for both investment and non investment grade debt. Credit rating agency Moodys have given AVAP a corporate rating of B1 and an issuer rating of B2; looking at the comparables in the US high yield index this would imply a coupon on the new issue of around 6.75 - 7%. This is clearly going to be issuer specific, so the caveat will always be that there’s no guarantee that this particular issuer will price there, but it’s at least a benchmark. On the downside, transportation has historically had the single highest default rate since records began in the High Yield market, but on the upside, institutional investors should like the relatively benign loan to book ratio given the value of their assets.
3. Finally, this gives them a long runway on the refi. In my many decades in fixed income I have seen too many companies wait until the last moment before refinancing their maturing bonds, only to find that there’s a sudden deterioration in risk appetite and they have to pay a much higher coupon - or in a few cases ended up ignominiously submitting to a debt for equity swap with shareholders suffering major dilution. At least this gives them time to try again if credit market conditions deteriorate as October goes by.
I hold.
HSS Hire (LON:HSS) - Not sure I understand the complexities of today’s announcement of deal with Speedy Hire (LON:SDY) but I do know that it has returned from suspension with 43.6% increase in stock price!! This was inevitable after I sold following the announcement of impending suspension caused a 17% crash in the price to add to some further slippage in previous days. Where is insider information when you need it!! No doubt next time I decide ‘no smoke without fire’ I should do just the opposite and then see any share involved crash & burn. The joys of stock market investment.
You did the right thing, it is what it is.
I did the same as I'm sure many did. It is swings and roundabouts.
Was no "week ahead" posted on Friday or did I miss it?
https://www.stockopedia.com/co...
Go to Discuss then All Posts. It's about fifth down.
It must have been as I looked at it during the w/end.
Yes there is but not much on it.
Shawbrook intention to list announced. Presumably very good news and PR for Pollen Street (LON:POLN) if it proceeds successfully.
Excellent news for Pollen. I can't find exact split between Pollen and BC but likely to own between 30 - 50%. Float estimated at £2bn +. Strange though, directors of Pollen selling shares recently.
Better offer in for Treatt (LON:TET) ?
Better offer in for Treatt (LON:TET) ?
Final offer too. Still derisory (in my opinion).
Given Döhler have bought 10% but aren't making an offer and Natara have so far got irrevocable undertakings for just 2.99% of the company it's not at all clear how this will play out. Presumably Döhler would be happy for the bid to fail and would then want to develop the relationship further, which couldn't be bad for Treatt.
While Treatt has its issues - largely being subscale in the industry - a bid at what is probably not much more than net asset value really doesn't deserve to succeed.
timarr
Treatt (LON:TET) Surprising that Rockwood also thought that 260p was derisory but now think that 290p isn't!
It looks as though this will fail and the price fall back to perhaps 240p. The question then is what happens to management who embraced the original offer so enthusiastically - surely their position will be compromised and have to resign?
I note also that Lord Lee has given an indicative offer of support. Again, surprising given that he must be heavily underwater at this price.
I note also that Lord Lee has given an indicative offer of support. Again, surprising given that he must be heavily underwater at this price.
From memory he bought below £1, originally.
timarr
Treatt (LON:TET) Yes, I can see you're probably right that he may not be underwater. According to an article in the FT he started buying in 1999 when the share price was around 35p. He has repeatedly added subsequently according to articles that I have seen. Incredible to think, however, that, on this share alone, his opportunity loss is in the order of GBP7m!
Treatt (LON:TET) And, I hasten to add, his opportunity gain from not selling at the bottom, around GBP500k! I've got several 'round-trippers' in my portfolio but some consolation to see that it can happen to anyone!
Lord Lee also said that he top-sliced when the price was much higher
Yes but he was equally derisive of the bid price on a recent podcast …not giving the impression that a 10% bump was really satisfactory, but although he’s accepted he isn’t tied in like Harwood are.
There is an * next to the word “final” which allows them to increase their offer in the event of a third party offer, so that’s not quite final! All eyes turn to the Fatherland for their thoughts!