Daily Stock Market Report (Thur 10 July 2025) - MACF, HSW, POLR, JUP, KETL, TRI, PIN, LIO, CAR, CML, PEBB, ENQ

Good morning!
Yesterday evening I published the H1 review of my 2025 watchlist, so feel free to check that out!
Today's Agenda is complete.
Spreadsheet accompanying this report: link.
We're finished for today, cheers!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Severn Trent (LON:SVT) (£8.0bn) | Expects to perform in line with guidance, including £25m in “ODI reward” in FY26. | ||
DCC (LON:DCC) (£4.69bn) | Q1 op profit in line, modestly behind last year. Outlook: good op profit growth, strategic progress. | ||
Pennon (LON:PNN) (£2.23bn) | Ofwat accepts SW Water’s enforcement package. No financial penalty but £24m of undertakings. | ||
Vistry (LON:VTY) (£2.04bn) | H1 profits in line (adj. PBT £ 80m), underpins confidence in outlook. Net debt £295m better than exps. | ||
Grafton (LON:GFTU) (£1.93bn) | H1 in line. Revenue +10%. Includes benefit of acquisitions. Many markets remain challenging. | ||
Pantheon International (LON:PIN) (£1.39bn) | £23.7m of buybacks in May at 40% discount to NAV. Another £20m allocated (on top of £10m). | GREEN (Graham - I hold) [no section below] | |
Pagegroup (LON:PAGE) (£881m) | Q2 gross profit -10.5% (cc). 2025 operating profit to be broadly in line with consensus c. £22m. | ||
Dr Martens (LON:DOCS) (£736m) | Trading since the start of the year is in line with exps, all guidance unchanged. Healthy order books. | ||
Rank (LON:RNK) (£644m) | LfL net gaming revenue +11% to c. £795m. Full year adj. LfL operating profit ≥ £63m, ahead of exps. | ||
Johnson Service (LON:JSG) (£617m) | H1 rev +5.5%. HORECA saw “slower than anticipated start to summer months”. Debt £99m. | ||
Jupiter Fund Management (LON:JUP) (£575m) | £15bn of AUM bought in. Price £100m, funded from existing cash. Targets £16m annual synergies. | AMBER/GREEN (Graham) I give this acquisition two thumbs up as the price paid seems very reasonable and it sounds like it should be a strategic success. Jupiter is a fund manager I've been quite positive on - its shares have staged a tremendous turnaround since April, not far off doubling from their lows. | |
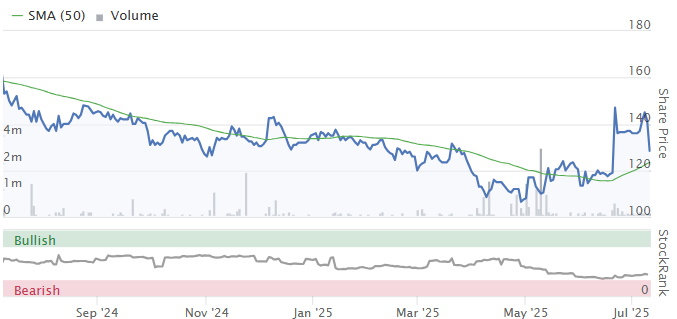
Polar Capital Holdings (LON:POLR) (£495m) | AUM 30 Jun +8.2% in the quarter to £23.2bn. Net Flows -£632m. | AMBER/GREEN (Graham) Leaving my moderately positive stance on this unchanged after some modest outflows in the quarter, which are uncharacteristic of the company. I can't predict the future but I'm hopeful that this is not the start of a new negative trend. Positive market movements have more than made up for the negative quarterly flows. | |
Griffin Mining (LON:GFM) (£356m) | Fully recovered from 2024 suspension of operations. Zinc conc prodn +61% vs prior quarter, Gold conc +157%, Silver conc +174%, Lead conc +82%. | ||
Brooks Macdonald (LON:BRK) (£286m) | Q4 FUM +3.2% to £19.2bn. Q4 net outflows £5m vs £129m outflow in Q3.Anticipates the full year performance to be in line with market expectations. | ||
Pantheon Resources (LON:PANR) (£247m) | Nabors 105AC rig is contracted and is currently mobilising to the Dubhe-1 pad for an well is an appraisal well targeting the Ahpun Topset. | ||
Enquest (LON:ENQ) (£235m) | Completed the acquisition of Harbour Energy's business in Vietnam for $85.1 million. Net of interim period cash flows consideration paid by EnQuest was $25.7 million. Adds net 2P reserves and 2C resources of 7.5 million boe and 4.9 million boe, respectively. | AMBER/GREEN (Mark) [no section below] | |
Liontrust Asset Management (LON:LIO) (£231m) | SP +6% AUM £22.6bn, unchanged over 3mo, £1.2bn net outflows, almost entirely from UK Retail funds. Confident sentiment: “We have now begun to see investors, led by institutional clients, turn more towards actively managed funds and diversify geographically, with Europe and the UK outperforming the US stock market over the first half of 2025”. | AMBER/GREEN (Graham) [no section below] | |
Macfarlane (LON:MACF) (£186m) | SP down 11% | (BLACK) AMBER (Mark - I held) | |
Hostelworld (LON:HSW) (£179m) | SP down 9% Net bookings and revenue flat. H1 Adj. EBITDA down 23% to €7.4m. FY 2025 adjusted EBITDA in line with market consensus | AMBER/GREEN (Graham - I hold) It's a quasi-profit warning as although the company still says it's on track, the market doesn't seem to believe it. The company has a lot to do in H2, with a larger H2 weighting than last year needed to meet full-year adj. EBITDA forecasts. I'm still a fan of the overall story here, but I downgrade our stance by one notch to reflect the heightened risk that the company fails to meet full-year forecasts. | |
DP Poland (LON:DPP) (£97m) | “...marked improvement in sales trends resulted in record monthly system sales for both months, contributing to a 4.9% year-to-date system sales increase.” | ||
Strix (LON:KETL) (£96.2m) | “The Group confirms that a competitive refinancing process will be formally initiated in the coming weeks to provide cost effective and flexible funding to support the Company's medium-term investment-driven growth aspirations.” | AMBER (Mark) [no section below] | |
Trifast (LON:TRI) (£92.6m) | Rev -2.7% to £227.4m. U/L EBIT at CCY +31% to £15.6m. U/L PBT £11m. Slightly ahead of consensus. Statutory PBT £4.9m (FY24 £0.8m loss). “Trading headwinds have continued to persist into Q1 FY26 “ | BLACK (AMBER) (Mark) | |
Pebble (LON:PEBB) (£78m) | Revenue and Adj. EBITDA for HY 25 in line with management's expectations despite currency headwinds, slightly behind prior year. | AMBER (Mark) [no section below] | |
Creo Medical (LON:CREO) (£51m) | MicroBlate™ Flex begins lung tumour post-market clinical studyt the Amsterdam University Medical Centre in the Netherlands and at the Royal Brompton Hospital in the UK. | ||
CML Microsystems (LON:CML) (£45m) | 12-year design and supply agreement with leading manufacturer of industrial Global Navigation Satellite System (GNSS) equipment valued at over $30m. | AMBER/RED (Mark) [no section below] | |
Carclo (LON:CAR) (£35.2m) | Will be temporarily suspended from listing and trading from 1 August 2025 until the audit is completed. Highlights previously announced ahead of expectations. | AMBER/RED (Mark) [no section below] |
Graham's Section
Hostelworld (LON:HSW)
Down 9% to 129p/€1.50 (£164m/€190m) - Trading Statement - Graham - AMBER/GREEN
(At the time of publication, Graham has a long position in HSW.)
I pitched this at Mello recently, and also bought a few shares in it myself.
Today’s trading statement has gone down like a lead balloon, even though it reiterates FY25 adjusted EBITDA guidance (the consensus forecast is €19.9m, as compiled by the company).
Key points from this update:
H1 net revenue +0% (€46.7m), net bookings +0% (3.7 million), net average booking value -1% (€13.40).
Direct marketing 51% of revenues (H1 last year: 45%).
H1 adj. EBITDA €7.4m (H1 last year: €9.6m).
The company is still benefiting from some positive cash generation: net cash was €2m as of December 2024, and this has increased to €6m.
And as signalled previously, dividends are back on the agenda with 20-40% of adjusted PBT to be paid, starting in H2 this year.
That’s on top of a £5m share buyback which began recently.
CEO comment:
"Trading over the last six months has been in line with expectations as outlined at our Capital Markets Day in April. Although trading in the first half showed mixed results across regions and channels, we are encouraged by the positive trends observed in June. This included growth in both booking volumes and average booking value (ABV), alongside an improvement in marketing as a percentage of net revenue…
Marketing as a percentage of revenue increased year-on-year, primarily driven by cost inflation in the first few months (which has since moderated) and the growth of paid channels as a proportion of total web channels….
As part of our broader growth strategy, the Group continues to evaluate acquisition opportunities….
Graham’s view
I think I can understand why the market might be underwhelmed with this update.
For a start, 0% growth in top-line indicators (revenue, bookings, etc.) is not exciting.
Customer demand for cheaper Asian destinations has been a long-running reason given for slow top-line growth, and now the company is also talking about bed price deflation in Europe. If the product they are providing is getting cheaper everywhere, that doesn’t bode well for their growth prospects.
Then there is the increase in marketing costs - Hostelworld’s main vulnerability is these costs, which it can’t control (it can control how much it spends, but has no control over their price!).
On a personal note, I am put off by their interest in M&A, which I view as a distraction. I want their core business to prosper, and I don’t see why it can’t! I also don’t want them to drain their cash balance, as they’ve worked so hard to return it to a healthy position. And with buybacks and dividends planned, I don’t see that they are likely to have all that much surplus cash lying around.
Incidentally, I see very little value in the company paying dividends at this stage in its development. It should be an exciting growth story, not a stock that investors are buying into for the yield! But at the same time I understand that LSE investors tend to appreciate some income. Hopefully the dividend will be at the lower end of the 20-40% range.
I’m inclined to keep my positive stance on this share (indeed I’ve slightly increased my exposure to it this morning), but I’m also mindful that today’s update could be interpreted as a profit warning, given the share price reaction.
The company has only generated 37% of its full-year adj. EBITDA forecast in H1, leaving it a lot to do in H2 to meet forecasts.
Last year, the company generated 44% of full-year adj. EBITDA in H1. So the H2 weighting is going to have to be more extreme this year, if forecasts are to be met.
As this is a quasi-profit warning, I’ll downgrade our stance on this by one notch, from GREEN to AMBER/GREEN. Based on existing forecasts, the shares are trading at a PER of about 12x. Given the latent potential of the company, and even if the company will probably miss its forecast, I still think this one is quite interesting.
Polar Capital Holdings (LON:POLR)
Down 4% to 466p (£473m) (includes the effect of 32p ex-dividend) - AuM Update - Graham - AMBER/GREEN
There is a pleasant 8% increase in Polar’s AuM in Q1 (April to June), although this is thanks to market movements rather than flows.
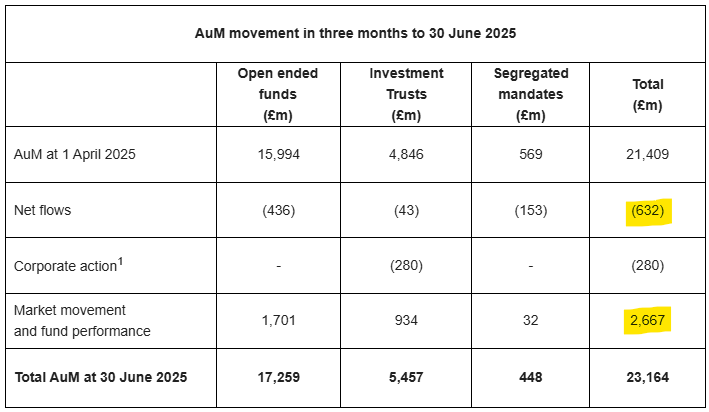
As the table above shows, flows were negative (£0.6bn), while market movements pushed up assets by £2.7bn.
As a rule of thumb, flows are far more important than market movements when it comes to assessing fund manager performance. Flows represent customer demand, while market movements do not!
CEO comment:
"There has been continued demand for a broad range of our funds during the quarter…
During the quarter, the open-ended Technology fund saw net outflows of £162m, an improvement on the £200m of net outflows seen in the previous quarter. Over the calendar year to 30 June 2025, as global indices broadened out, this actively managed fund was 8.5% ahead of its benchmark. Elsewhere, the remaining net outflows this quarter were primarily from the closure of an institutional mandate managed by the Healthcare team and an asset allocation change by a single Emerging Markets Stars client. Despite near-term market volatility, the new business pipeline for the Emerging Markets and Asia team remains strong.
Graham’s view
It’s unfortunate that Polar is now experiencing outflows, as it was one of the very few in the sector that somehow managed to avoid this.
But it is still possible to write off these flows as being rather small and inconsequential.
The Technology fund may have a better time attracting funds in the year ahead, now that it’s outperforming its benchmark.
And the other outflows can be classified as one-off changes that aren’t necessarily indicative of a broader change in client sentiment.
Furthermore, positive market movements can easily overwhelm and offset these outflows, as demonstrated by the overall quarterly AuM movement.
So I’m not panicking here. Bear in mind that I already moderated my stance on this to AMBER/GREEN, as I acknowledge that it’s possible to construct bearish arguments on all active fund managers, including Polar. I do still view this as a manager of the highest quality, and it remains one of the managers where I’m most optimistic about their future. Hopefully these quarterly outflows are just a bump in the road.
Jupiter Fund Management (LON:JUP)
Up 12% to 121.88p (£648m) - Graham - AMBER/GREEN
This is another fund manager where I’ve been quite positive - see my coverage of its Q1 trading update in April, where I thought flow performance was much improved compared to the prior year.
It has also offered exceptional value (much more than Polar),although recent share price gains have erased some of this exceptional value:
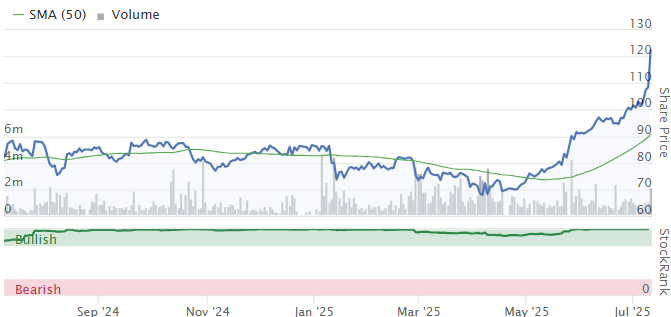
For context, in April, Jupiter stock was offering £114 of AuM for every £1 invested in it.
Today’s news is that Jupiter is buying CCLA Investment Management Limited, the asset manager for the non-profit sector, for £100 million.
CCLA has over £15 billion in AuM, so this is a step-change in Jupiter’s overall scale (Jupiter had £44 billion of AuM at the end of Q1).
It’s also a very attractive price being paid in terms of the sheer scale of the assets being bought in. Jupiter is getting £150 of AuM for every £1 it is spending on this deal.
That’s much cheaper than Jupiter itself was trading at, in the April doldrums.
Strategically, Jupiter are very happy with the transaction:
The Acquisition is highly compelling from strategic, cultural and financial perspectives, delivering progress against multiple objectives.
As well as the highly recognised and respected CCLA brand, the investment teams and client engagement model will be preserved, to ensure their clients continue to receive the consistent, high quality client service that they expect.
The Acquisition marks a significant step forward in delivering on Jupiter's key strategic objective of increasing scale, specifically within its home market of the UK. It also opens up a new client channel and provides complementary investment expertise with a high degree of cultural alignment.
Capital allocation framework - in separate news, Jupiter announces that it going to not just pay out 50% of pre-performance fee earnings in an ordinary, but it will also pay out 50% of performance fee earnings in the form of a special dividend or buyback (or both).
Graham’s view
In relation to the CCLA deal, I’m left wondering “what’s the catch”? CCLA is said to have generated “net inflows into long-term funds each of the last 15 calendar years”, which is not what I would have expected, at least for the last few years.
CCLA’s underlying operating earnings were “just under £13m million” in the most recent financial year, which also suggests a reasonable earnings multiple being paid after taxes are accounted for.
Jupiter are targeting “run-rate cost synergies of at least £16 million”, which should further boost profitability and reduce the effective multiple paid (although one-off costs to achieve this will be c. £17m after tax, to be incurred over several years).
I’m tempted to upgrade my stance on this to GREEN but I’ll stay calm for now. There is still a major negative trend facing this sector, and there may be a catch that I’m unaware of. But based on what I know so far, I’m giving this acquisition two thumbs up
Mark's Section
Macfarlane (LON:MACF)
Down 11% to 103p - Trading Update - Mark (I held) - BLACK/AMBER
It is bad news from this straight-talking packaging manufacturer and distributor:
In a year of challenge and economic uncertainty, we currently expect full year 2025 Adjusted Operating Profit to be approximately 10% below 2024.
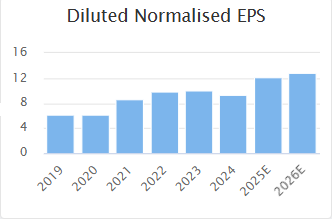
They don’t make many adjustments (just amortisation and deferred contingent consideration changes) and don’t attempt to sugar-coat it, which is nice to see. However, there is no getting around that this is a miss versus expectations, which were for a strong recovery in EPS:
Their broker, Shore, reveals what this means:
Our revenue line for FY25F reduces by £3m to £307m, EBIT by £4.7m to £24.7 (-16%), with adj. PBT at £21.1m (-18%) and adj. EPS at 9.8p (-19%). We also cautiously reduce our expectations for FY26F, revenues falling by just £1m to £320m, with EBIT reducing by £4.7m to £25.9m (-15%), with adj. PBT at £22.4m (-15%) and adj. EPS at 10.4p (-15%). The balance sheet remains robust with net debt well within facilities. We retain our prior dividend forecasts, and the company confirms the continuation of its share buy-back programme.
As is usual with companies that have net debt, the scale of the miss increases as you go down the income statement, leading to a 19% reduction in FY25 EPS. More worryingly, Shore reduce FY26 expectations by 15% showing they think this is more than a one-off. This is especially disappointing as the company mentions a specific focus on increased cost-cutting which should be feeding through by then. These are the reasons given for the miss:
Distribution is experiencing weaker than expected demand, delays in new business decision making, pressure on gross margin due to the competitive environment, rising input prices and slower than anticipated recovery of labour and property-related cost increases.
Manufacturing Operations is performing robustly with good momentum with our aerospace and defence related customers and the benefit of the Polyformes acquisition, marginally offset by the slowdown in those sectors where customers are being impacted by uncertainty over US tariffs.
Sounds like a perfect storm of delays, margin and cost pressures. As a distributor, there is no escaping the end market conditions in which they operate. At the time of their AGM statement, they said that Q2 had started with strong momentum, and they specifically reference this today:
We highlighted in our AGM statement that market conditions in 2025 were challenging. It is disappointing that the momentum increase we experienced early in Q2 2025 has not been maintained and as a result will impact our full year performance.
I don’t think there was any attempt to mislead investors, and market conditions have simply not been as they expected. This is perhaps a canary in the coal mine for other businesses that rose on what appeared to be a recovery in trading in early Q2.
Macfarlane are keen to point out that they are comfortable enough with debt levels (and presumably so is their bank) for them to continue to buy back shares. This may provide some short-term share price support. However, Shore increase their estimate for net debt at the end of 2025 from £16m to £22.8m on this update. This may well start to limit the company’s ability to make acquisitions, which has historically been the main source fo their growth. And it occurs at a time where they may want to take advantage of weak market conditions to strike good deals.
Mark’s view
I held shares here this morning, so this warning was a bit of a surprise. This was a relatively modestly priced high-quality business that has a history of compounding earnings at a reasonable rate (although mainly through acquisition) and was forecast to return to growth this year. The Stockopedia algorithms liked it too, rating it a Super Stock, and the share price was recovering. However, none of this precludes a profits warning, as today has proven.
It was hard to know how to react this morning. This warning doesn’t change the long-term story of a quality company compounding earnings. However, a multi-year warning means the near-term rating is around 20% higher (assuming no price change), and this didn’t look as good value. These things aren’t exact, though, and if I thought it was sufficiently undervalued on a 2026 P/E of 9, surely it isn’t a sell at a P/E of say 10 (after a drop in share price). There is also the tendency for companies to take longer to turn around than expected, which can lead to further warnings. Even without another warning, forecasts are now for little growth over the next few years, making the investment case weaker - perhaps this will never return to previous levels of EPS growth.
Weighing all this up, I let price be the determining factor in my decision. After all, value investing is about capitalising on perceived differences in value and price. If the price has dropped more than the decline in value, it is a buy. If the price hasn’t dropped enough to provide a margin of safety between price and value, it's a sell. The price has been volatile today (perhaps due to the company continuing to buy back shares), making it difficult to form a personal view, as it changes by the minute. I took the opportunity to sell my shares today when the price hadn’t fallen as much as the drop in 2026 EPS forecasts. It remains on my watchlist and I’d probably be a buyer again if it dropped to 7-8x the now reduced EPS, despite the risk of a further warning. That probably makes it an AMBER for me.
Trifast (LON:TRI)
Up 1% to 70p - Final Results - Mark - BLACK (AMBER)
This fastenings company is undergoing a transformation program in an attempt to return to its previous operating margins. Their “ambition“ is medium-term EBIT margins greater than 10%. They have made some progress against this aim in FY25. However, this isn’t helped by a revenue decline:
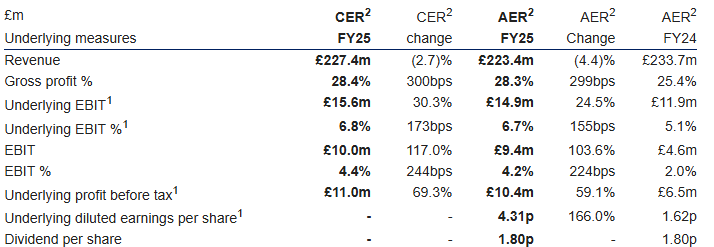
The company say this is partly due to a strategic decision to exit some low margin business. Overall, it is a little difficult to work out exactly how these line up versus expectations. On the surface these appear to be a slight miss on revenue, beat on adjusted Net Profit, but a miss on EPS:
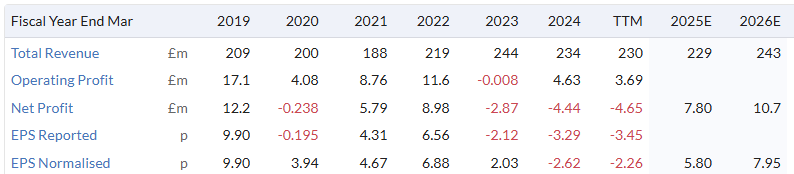
Cavendish say these were in line with their expectations. Zeus say:
The operational improvement in margins means operating and pre-tax profit were marginally ahead of Zeus estimates despite revenue being slightly lower.
They appear to gloss over the fact that their previous EPS forecast was for 5.8p of adj. EPS and this figure came in at 4.3p! Dividend being held at 1.8p is below their expectations of a small increase to 1.9p. Perhaps the best that can be said is that these results are mixed.
This is also a company that reports a significant gap between adjusted and statutory results. Here’s the breakdown:
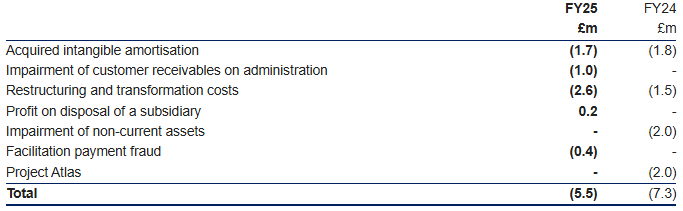
Most of these look one-off, but they are not all non-cash. They also don’t appear to have credit insurance in place for all customers, making this an ongoing risk in weak economic conditions. I think we have to conclude that this is the type of business where restructuring costs will be an ongoing recurring cost for the foreseeable future. Excluding these when the current focus of the business is transformation through cost-cutting and operational improvements looks like a bit of having your cake and eating it to me!
Regional Breakdown:
UK & Ireland remains a weak spot, and EBIT margins here are both lower than the group average and declining:
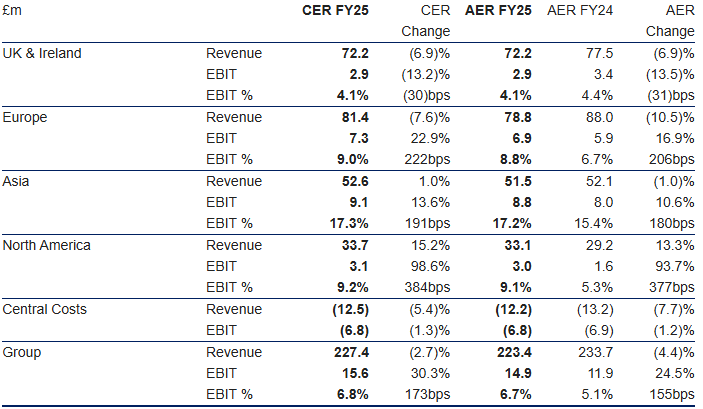
The company say part of this is due to a warehouse move and consolidation in the UK at the end of the year. However, this can’t be the full story, and on the IMC call, they confirm that the weak UK automotive sector is largely driving this. Other regions appear to be performing well, although there is little revenue growth anywhere.
Balance Sheet:
The company have done well reducing their inventories, although this is no doubt helped by reduced revenue:
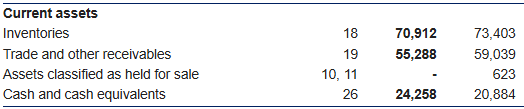
Net debt reduced and is now below 1x EBITDA:

This gives them the possibility of considering bolt-on acquisitions again. Although the static gross debt and lack of dividend growth suggests they don’t feel as comfortable with the debt level as they may first appear. This could be due to working capital swings during the year.
Net assets have declined slightly:

Mainly due to a drop in intangible assets:

Meaning net tangible assets have only declined by £0.2m to £87.7m.
Outlook:
This is quite a weak sounding outlook statement:
Trading headwinds have continued to persist into Q1 FY26 due to:
· Macroeconomic headwinds impacting a number of industrial markets, with particular Automotive sector softness
· US tariffs on steel and aluminium, disrupting sourcing and costs
· The weakening USD.
While there was some doubt as to how the FY25 results stacked up with expectations, there is no doubt here that this outlook is disappointing. Cavendish say:
Forecasts: We are reducing our FY26E forecasts, with a 4.3% YoY cut in revenues to £214m, down 13.4%. Lower volume drop-though and further operational performance initiatives result in an adj EBIT of £16.1m, a YoY increase of £1.2m, with margins progressing to 7.5%. This gives adj PBT of £11.7m, with adj EPS at 6.5p, down 22.0%. We reduce our dividend due to the FY25 held dividend, and lower FY26E expectations, with a YoY uplift to 1.9p. Cash generation reflects the profit downgrade, albeit still with a YoY improvement, but also good working capital management, with net debt of £8.8m
Zeus:
…weaker volumes lead Zeus to reduce FY26 revenue by 11% to £214.0m, which, when accounting for unchanged EBIT margin expectations of 7.4% (+70bps yoy), mean adj. EBIT falls 11% to £15.8m (prior: £17.7m). Adj. PBT falls 13% to £11.5m but is still 15% higher yoy.
Zeus’ EPS estimates drop by a similar amount to Adj. PBT.
Valuation:
Making my own updated consensus I get 6.55p EPS for FY26, with £10.4m net debt ex-IFRS16. Zeus expect EPS to grow to 8.7p in FY27 and then 10.8p in FY28, with net debt further declining. Cavendish don’t appear willing to make forecasts beyond FY26 so future years should probably be viewed with a pinch of salt at this time. At the current 71p to buy this makes the forward multiple 10.8x, or around 12x if you debt adjust it.
This isn’t unreasonable if you assume that the transformation program will deliver the results the company say they will. However, that delivery has taken a step backwards with today’s results, and in particular the FY26 outlook, making a dent in confidence.
This trades on a P/TBV of 1.14, which shows that this is modestly rated if they can make those assets productive again, but that this isn’t necessarily a buy on assets alone. This could provide some downside protection, though.
Mark’s view
The cuts to FY26 revenue and EPS with a static share price mean that the forward valuation multiple has increased here today. While the long-term recovery story looks intact, market conditions mean that this moves further into the future. This effect doesn’t look severe enough to change my previous AMBER stance here, though.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Gold bugs out there are for sure watching the Mali government and Barrick Mining (TSE:ABX) confiscation of resources. The price rises the grift increases at government state levels.
Any companies in Africa - well just put capital letters onto jurisdictional risk. Good night.
Yes - wasn't it Mali that stung Resolute Mining (LON:RSG) for 160 million in 'unpaid taxes' in 2024? Payment of the amount 'owing' was encouraged by detaining the CEO until the cash was stumped up. The government have clearly learnt that this is a great business model, so are trying it again. Reeks...
Maybe socialism works for mining - slavery in basic terms. Capitalism have those nasty er capitalists sucking the resources and destroying our environment - so may as well do it ourselves.
Lets forget 'cards', fripperies, kettles, footwear and 'blue sky' health miracles and anything under 100m - the world is energy, weaponry and natural resources inc water, which is reflected in some of the companies covered above.
Liontrust Asset Management (LON:LIO) decent bounce on the SP today, good news after this went ex div last week!
Surprised that Rank (LON:RNK) isn't on the radar today.
Beats the forecast, good double-digit top line growth momentum.
Also brokers have an additional 3p, 4p to add to FY26+ forecasts now that the new laws have come in allowing more slot machines in existing casinos. This is a massive boost on the 9p EPS for the FY Jun25 just ended.
If taking 12p EPS for FY26 (and that assumes no growth next year, which there will be) and applying the usual 17-20x bottom of the PE range for gambling companies, that would be a 200p share price. From the current 140p.
AND the biggest risk - regulatory/legislation - is now removed for the next 12 months at least, given the government just passed their massive Gambling Act reforms.
(I hold in the Boon Fund)
Be great if the team have time to run the rule over Brooks Macdonald (LON:BRK) they are moving from aim to main market and have a slightly different angle from other fund managers in that they are buying IFA firms up.
With a view I'm guessing to then telling them they have to use their internal models/funds so you would hope that the money once invested would prove reasonably sticky against outflows.
Just a couple of weeks ago Elixirr International (LON:ELIX) moved across - so far it hasnt moved them - they continue to yo-yo up and down every day
Anyone know why Alumasc (LON:ALU) as fallen from about £3,90 to £3.30 in recent days without any apparent news? Is this a good entry or top up point? I hold.
Alumasc (LON:ALU) Profit taking before imminent trading/operational update (July 18 last year)?
Alumasc (LON:ALU) Results not until September, there could be trading update soon.
Well, I bought in this morning. Should be update next week.
Alumasc rose on the indiscriminate buying of UK small caps back in May and June during which period the company gave no updates on trading. There has since been some profit taking to which the firm has been vulnerable. The price is roughly where it was at the time of the last update and the spike up to 390p struck me at the time as unjustified. Unless of course we see a big upgrade when they report.
I believe there is a trading update due next week, so maybe there are some people in the know getting out early or there is some profit taking before the update. I hold here, but I might be tempted to sell.
Market seems undecided about today’s results from Trifast (LON:TRI) . Quite heavy volume but direction unclear. It does appear that the Harwood inspired margin recovery program is gaining traction but I suppose global macro is not going to favour high volume, low margin widget makers / price takers.
Would appreciate if Graham or Mark have a chance to cast their eyes over this one.
Here is the operations update:
https://x.com/CamlMetals/statu...
https://www.londonstockexchang...
Does anyone have a link to this? I cannot find any information.
Thank you for your comments on Macfarlane Mark, especially your final paragraph. It's a share we held with some modest success previously and will now go back onto my monitoring list to buy into again.
MACF I'm a holder, and obviously not a happy one.
"This warning doesn’t change the long-term story of a quality company compounding earnings." This is what I also believe, which is why I'm sticking with it. There is an element of doubt in my mind, so I'm not topping up.
Diversification is my friend.
I'm joining the Macfarlane (LON:MACF) commiserations club...
I guess the writing was on the wall in some of the warnings they gave in the last two updates.
Very brutal cuts to EPS forecasts for FY25, FY26 by brokers.
And that probably means no more acquisitions this year, as they get their core house in shape. Unless its out of administration or a bargain price (which maybe there will be more of this year if the market is also suffering).
Acquisitions was the main thesis that I bought in for - that they will be able to bolt on struggling smaller players. But it looks like they themselves are now struggling.
Haven't properly gone through the numbers yet, will do so within the next week, to take emotion out of it. But I'm looking to hold if its sub-10x PE.
Interesting that the price had risen over the last few weeks. At least you know the company runs a tight ship, not any leaks?
Valterra Platinum (LON:VALT) - Ive 'inherited' a few shares of this company spun out of AngloAmerican. Cannot decide whether to hold sell or top up - There does not seem to be any coverage anywhere. Any thoughts please ?
Platinum squeeze underway ... I would hold. Shitco in Shitcountry ... so just a trade.
Jupiter Fund Management (LON:JUP) - fantastic deal announced today to buy CCLA which has an excellent reputation in the charity sector. I'm confused as to why they were able to pick this highly respected provider on such a low multiple / why CCLA are attracted towards Jupiter. Maybe its the unstoppable trend of wealth managers getting bigger like Rathbones etc. CCLA has a stronger brand than Jupiter, that's for sure!
Buying CCLA for 100 million pounds and adding 15 billion pounds of assets under management sounds cheap
Vistry (LON:VTY)
i have had a dabble here as a trading punt - there isnt rellly much to recommend here based on events of last 18 months.
the share does trade below book value p/e is under 10 and at some stage one would think that the bad news would be over - they must be sick of updating further woes every time they update so makes sense at some stage to face realities and reset goals at conservative levels - not convinced some boards have that ability in their locker - todays update seems acceptable though so some hope here.
this company was flagged up on the trading ideas board - i think basically the dowtrend in shareprice and earnings updates seems to have very much bottomed out for now - share is bumbling along the green line chartists like to use and the stock rank is very decent and trending up (perhaps surprisingly)
todays update seemed absent of any specific bad news which is really good news - other than perhaps a very poor update ref development opportunities that stuff must be somewhat lumpy though in nature. dont know detail but i think recent government changes may have help back such stuff in last 9 months perhaps ?
The Group secured attractive land and development opportunities in the period totalling 3,113 (2024: 8,225) plots, across 14 (2024: 32) developments. Whilst we expect the rate of land acquisition to increase in the second half, we are targeting a reduction in the length of our owned landbank in the medium term in line with our capital light Partnerships strategy.
on the plus side they seem to be in control of debt and seem to want to keep it simple - at presenent that makes sense and is fully applauded by me.
so i would guess the main worry here would be if they cant deliver volume if land oportunities dont present themselves or struggle ref margins (seems to be issues for many housebuilders) . I dont like any business where the government needs to do their job - but no one cant deny (other than zero emission hardcore people and nimby idiots) that we need lots of new affordable housing.
Nothing to recommend here - my position is already underwater having bought at slightly higher level - but the main bad news does seem to be mostly in the rear view mirror here.
With my trading shares i plan to exit asap if there is specific bad news upcoming - there enough here for me to carry on holding - hopefully the discount to ntav provides support even if actual earnings at exepcted levels might be tough to come by. With profit they are making and lack of dividend basic maths says the debt should reduce and the discount to ntav should increase if shareprice goes nohwhere - well thats as long as there are no exceptionals taken of teh current stocky forecasts s- in that regard i offer no assurances and suspect there may be prior flagged items perhaps?
VTY I heard earlier in the year that a fund manager was quite keen on VTY. He seemed to think that it would be able to generate high returns on capital. (Just, um, maybe not today or next week.) The phrase here is "capital light Partnerships strategy."
It is on a PBV of 0.63, which is usually regarded as "hella cheap". Give it 5 years. I found that with my Standard Chartered (LON:STAN) shares. I bought in Jul 2022, faffed around for a couple of years, and then got their mojo working. Now doubled.
Central Asia Metals (LON:CAML) down 7.5% this morning on no news?
Operations update. Slightly lower output estimates.
Seems to be error on News feeds as links to an item to similar epic Camelia CAM
Polar Capital Holdings (LON:POLR)
This morning's announcement confirms my view that Polar Capital Holdings (LON:POLR) is the pick of the bunch amongst the listed assets managers. I hope that Graham is able to do a compare and contrast with this morning's announcement from Liontrust Asset Management (LON:LIO) , which in fairness suggests that the situation is starting to stabilise.
I hold Polar Capital Holdings (LON:POLR) so am somewhat biased.
Jet2 (LON:JET2) for what its worth I thought that the 10% mark down yesterday was unjustified. Again I hold.
Jupiter Fund Management (LON:JUP) is the one that is flying, up another 9% today.
Polar reported FY las Monday, 30 June. Good to see strong progress in Q1 AUM. SP dropped this morning as shares xd today. (I hold)
Polar Capital Holdings (LON:POLR) Thanks for the reminder - Yes its Thursday!
Would be an idea if Stocko were to list the main exDIVI stocks each Thursday !
www.dividenddata.co.uk
Only UK ords, no prefs, so if you hold LLPD etc they don't show up, otherwise it's a very useful site.
Comparing POLR and JUP is like chalk and cheese. Stocko comparison tool shows them neck and neck but one income and one growth
Maybe Jet2 (LON:JET2) need to move out of AIM to reduce volatility, more funds will invest and they will likely gain in value also. Perhaps shareholders should start to put them under pressure on this!
Yes JET2 need to get off AIM and also start paying a reasonable dividend (around 4%) as they have plenty of cash - I think that would give the share price a bit of a lift.
You could be right but the boss has a significant holding and probably wants to keep the reduced IHT benefit in place.
£JET
i dont mind the volatilty personally - i ama big fan of Jet2 - probably could buy more - but could also possible sell some if price spiked up - so does volatility not sometimes offer options for nimble minor holders?
hmmm comparing 2 year chart to easyjet i dont see alot of difference ref volatility other than confirmation i have held the right company.
I’d appreciate the team’s thoughts on Johnson Service (LON:JSG) please. I hold.
Johnson Service (LON:JSG)
todays update didnt seem terrible - but yet another company that says didly squat as to how todays update relates to current year end expectations. Seems endemic now that companies are providing zero useful info in their updates and having behind the scenes discussions with brokers who then do the dirty job of saying thats slight downgrade for this year and next.
We really need some campaign to take board to task in this regard when other similar and smaller companies have the courtesey to so - we are still on course ref ye profits - we are broadly on course - or this is minor profit warning.
not good not clever and not really acceptable - i bet the brokers and advisors love it though as it makes their job seem more important - it is clearly creating a false market though if multiple brokers all make the same downgrades today.
The market has rightly acted like an investor reading this update - well are we on taregt or not your update has gioven us concerns and i am worried its not as good as you told us yesterday - but you havent confirmed that.
The bizarre aspect is that the market is, in my experience, never fooled by attempts to obfuscate the extent of the damage. It only corrodes faith in management and therefore the share.
The lawyer in me is very suspicious of the words 'to date' in the Carclo (LON:CAR) update. Suspect this audit issue ends badly...
Carclo (LON:CAR) As an ex auditor, delays in the audit usually mean problems with the accounts, even the possibility of a fraud. A large red flag.
Ftse 100, DOW and S&P at 52 wk highs I believe. Bullish or overheated?!
Sorry NASDAQ not DOW
Q2 earnings season about to ramp up so time will tell
BTC and ETH ripping too. Very bullish.
Stocko has a breakdown of the FT100 here: https://www.stockopedia.com/in...
Using TTM the PE is 15,5, which is about average. I calculated a median PE (ex ITs), which came out the same.
S&P500 is at highly elevated PE ... or is it? Prof Damodaran recommended using median PEs rather than mean PEs. The latter tend to get distorted by "fat tails". More specifically, the Mag 7 is on high valuations and makes up the bulk of the index. So the results are highly skewed. Earlier this year the Prof did a median calculation, and it was about its historical norms. So, surprise!
One of my favourite charts is the growth vs value stocks chart, which is only for US. I've not found a good UK equivalent. https://www.longtermtrends.net...
It shows that growth vs value is (nearly) at the highest relative value to growth. The implication is that (US) value stocks are in a good position to outperform growth stocks. Just don't hold your breath.
I explored some UK indices. In the FT100, all companies had a G (Stocko Growth rank) over 30. If you define a G less than 30 to be a "slow grower", then there aren't any slow-growers in large caps. If you take G>70 to be "fast growers", then the majority qualify.
Perhaps the definitions might be regarded as "highly dubious", though. Games Workshop (LON:GAW) has a G score of 69, for example. I don't think anyone is going to say it isn't a growth share, though.
Perhaps one might choose OCF 5yr growth. On that basis, GAW has compounded by 22% pa. So yeah, growth company. BAE Systems (LON:BA.) is just a little below it, at 20%.
The leader is Tesco (LON:TSCO) at 127%. I doubt anyone would call that a growth share, though.
So "growth" is difficult to pin down.
Could it be the stocko defn that is worth looking at?
The eternal question!
Agree as we are dealing with historical data. All good fun though.
To me Stocko is a safety net - if want to pick a dud then your fundamental eyes are open so take the punt. Thats where charts come into play imo. The Market / Street knows more than you or me so the SP tells the story - the news catches up afterwards.
Wise words.