Daily Stock Market Report (Thur 11th June 2026) - RWS, HLMA, PAY, SRB, WIZZ, NXR, CNC

SpaceX is reported to be massively oversubscribed, with more than four times the demand than the quantity of shares that are actually available.
Official pricing is today (at the fixed price of $135 per share) and trading in the shares should begin tomorrow.
At a $1.8 trillion valuation, it will be more valuable than Tesla (NSQ:TSLA) and Meta Platforms (NSQ:META) but not quite as valuable as the likes of Amazon.com (NSQ:AMZN) and Microsoft (NSQ:MSFT). It will be a top 10 stock in the US by market cap.
In terms of its historical importance, it’s a truly landmark event. Alibaba Holding (NYQ:BABA) had a market cap of $169 billion at its IPO price, which seemed enormous at the time (this was in 2014). Saudi Aramco was valued at $1.7 trillion at its 2019 IPO, although they only raised $29 billion.
SpaceX, by contrast, is raising $75 billion - and apparently could have raised a lot more.
If you want my opinion, we have moved into a stage of the long-term bull market where prices for popular shares are now entirely unmoored from the fundamentals. I’ve mentioned recently the price to sales multiples for SpaceX, which do not fit with any standard method of valuation. But maybe this time is different?
Overnight market movements:
The FTSE is set to open down 0.3% at 10,220
S&P 500 is up 0.4% at 7,300
Brent crude is up 0.4% at $93.30
Gold is up 0.6% at $4,100
Bitcoin is up 1.5% at $62,700
Leaving it there for now, cheers!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Halma (LON:HLMA) (£17.6bn | SR69) | Revenue +15% to £2.58bn, Adj. EPS +21% to 114p, dividend +&% to 24.74p. Outlook: Positive start to the 2027 financial year, strong order book and order intake ahead of revenue and last year. Economic and geopolitical environment remains uncertain. Expect low double-digit percentage organic CCY revenue growth. Adj. EBIT margin in line with 2026. | AMBER ↓ (Graham) | |
Derwent London (LON:DLN) (£2.08bn | SR67) | Jonathan Murphy appointed as Chief Executive. Most recently Chief Executive Officer of Assura plc. | ||
Grafton (LON:GFTU) (£1.58bn | SR85) | Targets for 2030: Adjusted EPS CAGR 10%+ over the period 2025 to 2030. Cumulative FCF £850m+ over the five year period 2026 to 2030. ROCE 13%. Lease-adjusted net debt to EBITDA ratio of 1.0x to 2.0x. Dividend cover in 2.0x to 3.0x range. | ||
Sirius Real Estate (LON:SRE) (£1.54bn | SR88) | Placed €185.1 million nominal value of notes through taps of two of its existing corporate bonds, taking each bond to a total outstanding nominal amount of €500.0 million. | ||
Safestore Holdings (LON:SAFE) (£1.38bn | SR55) | H1 Revenue +5.6% to £120.6 (LFL +5%), u/l PBT +2% to £44.6m, Adj. EPRA EPS +2% to 19.4p. EPRA NTA ps -0.8% to 1,120p. FY 2026 outlook: Return to earnings growth with projected EPS at the lower end of consensus range largely reflecting the expected impact of higher interest rates in H2. | BLACK (lower end of consensus) | |
Great Portland Estates (LON:GPE) (£1.28bn | SR30) | Secures 12 new Fully Managed leasing deals totalling over 41,000 sq ft and delivering £8.0 million of annual rent at an average of £195 per sq ft. | ||
Serica Energy (LON:SQZ) (£1.06bn | SR92) | Acquisition from ONE-Dyas of a 10% interest in the Catcher Field and a 5.21% interest in the Golden Eagle Area Development has now completed. Adds around 2,500 boepd, and net 2P reserves of 3.0 mmboe. | ||
Wizz Air Holdings (LON:WIZZ) (£1bn | SR62) | Fleet +13% to 262, Revenue +8% to €5.691bn, EBITDA +16% to €1.318bn, Net profit -99% to €1.3m, Net debt flat at €4.941bn. “Not giving guidance for F27 at this time of the year given the lack of visibility across our trading seasons, uncertainty related to the ongoing conflict in Iran and the closure of the Strait of Hormuz.” | AMBER/RED (Mark) There doesn’t appear to be signs of the immediate solvency concerns raised by competitors, which is perhaps why the market liked these results. However, with no forward guidance and brokers forecasting EPS losses for the foreseeable future, I struggle to make the investment case here, versus something like Jet2, which is forecast to be profitable and on a lower P/TBV rating. As such, a broadly negative view versus sector peers would seem to make sense. | |
International Personal Finance (LON:IPF) (£552m | SR88) | All conditions satisfied apart from Poland. IPF and Bidco currently expect the Polish Regulatory Condition to be satisfied before the Sanction Hearing, which is now expected to take place in late July 2026. | ||
Foresight group (LON:FSG) (£488m | SR89) | Agreed to sell its public markets investment division, Foresight Capital Management, to Guinness Global Investors, totalling £1.0bn AUM (7% of Group AUM) and 16 employees. No price given. | ||
Origin Enterprises (LON:OGN) (£407m | SR93) | YTD Revenue +2.7% (+5% CCY), FY adj. EPS guidance €0.52-0.55. | ||
NCC (LON:NCC) (£401m | SR73) | Unaudited interim results & Conclusion of the Cyber Strategic Review | Escode sale completed on 29 May 2026, and NCC is now a pure-play Cyber business. Strategic review of the Cyber business is now complete. £170m tender offer + £15m share buy-back. H1 Revenue +5% to £151.3m, Adj. EPS +200% to 4.5p, Net debt excl. Leases at 31 Mar £10.2m. £230m net cash at 1 June following Escode disposal. | |
RWS Holdings (LON:RWS) (£381m | SR93) | FY26 Revenue +5%, Adj. EBITDA +20% to £45.7m, Adj. PBT +33% to £24m, reported LBT £9.5m. Interim dividend -29% to 1.75p. Net debt £32.5m (FY25: £25.4m). Good start to the second half; continue to trade in line with expectations for the full year. FX hit of £2.0m + £1.0m hit from Obviously acquisition. | AMBER/GREEN ↓ (Mark) On the surface, these are reasonable in-line results. However, the more I look into them, the less I like them. The single-digit P/E is based on heavily adjusted figures. Plus the dividend looks like it may come in a little below analysts’ consensus for the full year. With these in mind I think we should take a slightly more cautious view, at least until the gap between adjusted and statutory figures is narrower and the strategy concerns are shown to be overblown. | |
PayPoint (LON:PAY) (£335m | SR72) | FY26 Net Revenue +1.7% to £190.8m, u/l EBITDA +2.2% to £92.0m, u/l PBT +1.5% to £69.0m. Net debt £132.5m (FY25: £97.4m). “Overall, the Board remains confident in delivering further progress, exceeding the underlying profits achieved in FY26 and achieving results in line with market expectations.” | GREEN = (Mark) | |
Forterra (LON:FORT) (£281m | SR64) | CFO leaving the group after 20 years with Forterra and its predecessor organisations to pursue new challenges. Will remain as CFO until October to assist with an orderly transition. | ||
Social Housing REIT (LON:SOHO) (£279m | SR63) | Inclusion Housing Community Interest Company has received a compliant G2 V2 regulatory grading by the Regulator of Social Housing. Inclusion is SOHO's largest lessee, representing approximately 30% of its annual rental income. “…a positive development for the sector, providing further evidence that well-managed, lease-based providers can operate successfully within the regulatory framework while continuing to deliver high-quality homes and services for vulnerable residents.” | ||
Empire Metals (LON:EEE) (£250m | SR7) | Completed an integrated metallurgical processing flowsheet for the Pitfield Titanium Project in Western Australia. | ||
Serabi Gold (LON:SRB) (£239m | SR99) | NI 43-101 Technical Report for the Palito Complex and Coringa Mine | Publicly filed its detailed technical reports of its updated Mineral Reserve estimates and Mineral Resource estimates for its 100% owned Palito Complex. | AMBER/GREEN (Mark) [no section below] |
Norcros (LON:NXR) (£237m | SR89) | Revenue +10.6%. Underlying operating profit +7.9%. Outlook: “Market conditions are likely to remain subdued, with the pace of any recovery in the new build sector still unclear. The mid-premium RMI sector currently remains more resilient and the Board's expectations for FY27 are unchanged.” | AMBER/GREEN = (Graham)
The lack of organic growth is pretty unsettling. Combine that with the very competitive markets in which Norcros operates - bathroom and kitchen products - and we are left to conclude that this should trade on a very cheap valuation. That’s what the market is giving us. I think Norcros shares do still offer value, but for good reasons. At least the story has improved in recent years, with the pension deficit and South African exposure no longer being very relevant. | |
Concurrent Technologies (LON:CNC) (£218m | SR43) | SP +9% Four-year order worth c. £17 million from a major European defence equipment prime contractor. "More broadly, demand across our defence markets remains encouraging.” | AMBER = (Graham) [no section below] This is a fabulous announcement in many ways - a very large multi-year order from a longstanding customer - but once again CNC's approach to communication leaves a few questions unanswered. There is zero reference to the impact of this contract on expected future profits or o existing market expectations. They do say that the contract gives them "enhanced multi year visibility", but do no spell it out. An additional c. £4.25m of annual revenue, if it was not already baked into forecasts, would boost FY27 turnover by 7%. With the company enjoying a P/E multiple of over 30x as of last night, I'm going to leave our neutral stance unchanged. This is the type of situation where I would follow the momentum and upgrade our stance, if the message was clearer. | |
M&C Saatchi (LON:SAA) (£172m | SR63) | Like-for-like net revenue is in line with expectations and supportive of the market's full year outlook. | ||
Strix (LON:KETL) (£75.5m | SR92) | The new CEO was previously Group Chief Commercial Officer at A-SAFE Ltd, which makes traffic barriers and bollards. Was also Managing Director and Group Commercial Lead at AIM quoted Grosvenor Technology / Newmark Security Plc. | ||
Zephyr Energy (LON:ZPHR) (£63m | SR26) | Q1 production averaged 918 boepd net to Zephyr (vs 983 boepd in Q4). Q1 “exceeded management's forecast and reflects the expected natural decline rates of the portfolio.” | ||
Poolbeg Pharma (LON:POLB) (£53.3m | SR27) | The first site activation for the first-in-patient POLB 001 TOPICAL clinical trial has occurred. | ||
Palace Capital (LON:PCA) (£33m | SR52) | Adjusted loss before tax £0.1m. Actual loss before tax £5.4m. NAV per share falls 14% in H1 to 210p. | ||
Predator Oil & Gas Holdings (LON:PRD) (£30.8m | SR8) | Snowcap-3 long-lead well inventory build progressing on track. Oil storage tanks (capacity 1,200 barrels) to move to Snowcap-3 production facilities site. Various other updates. “We are very pleased with current progress given the unpredictable impact of the Middle East conflict on the global logistical supply chain.” | ||
Bezant Resources (LON:BZT) (£27.3m | SR32) | Definitive documentation for the US$7 million secured prepayment facility and offtake agreements with Hartree Metals LLC. | ||
Haydale (LON:HAYD) (£25.3m | SR-) | Expansion of its agreement with Lloyds Bank through its SaveMoneyCutCarbon platform. National launch targeted for June 2026. | ||
Panther Metals (LON:PALM) (£12.9m | SR22) | The first drill hole at the Awkward Conduit Target has completed successfully and drilling has now commenced at the Wishbone Prospect. | ||
Rockfire Resources (LON:ROCK) (£11.4m | SR16) | Appraisal of the historical underground mining access at the Molaoi project in Greece: “…The current condition of the underground, which was only observed from the entrance, did not exhibit visible deterioration of the existing support system.” |
Graham's Section
Halma (LON:HLMA)
Down 15% at £39.38 (£14.97bn) - Full Year Results - Graham - AMBER ↓
These 2026 results look good against expectations, but it’s the FY27 outlook that is more questionable.
Firstly, a brief overview of FY March 2026. (By the way, I find it easiest to read them on Halma’s website as the RNS itself is empty.)
Revenue +15% to £2,582m (StockReport forecast: £2,559m)
Organic revenue growth of 16%, far above their long-term target of 7% thanks to high growth in their photonics business.
Adjusted EPS +21% to 114.05p (StockReport forecast: £113p)
Halma’s US-based photonics business designs, develops and manufactures photonics equipment out of Philadelphia.
The results are clean with statutory EPS of 98.57p (up 26%).
The company calculates an “adjusted Return on Total Invested Capital” of 16.2%, up from 15% last year, which is also very encouraging.
The full-year dividend gets a 7% increase to 24.74p, which is covered several times over by EPS.
Leverage is modest at 1.16x, “well within operating range of up to two times”.
So what’s the catch?
Outlook:
We have made a positive start to the 2027 financial year, with a strong order book and order intake ahead of revenue and last year.
But…?
While the economic and geopolitical environment remains uncertain and our companies continue to experience varied conditions in their end markets, we currently expect to deliver low double-digit percentage organic constant currency revenue growth in this financial year, including premium growth of approximately five percentage points from our photonics business.
Adjusted EBIT margin is expected to be in line with the 2026 financial year (excluding the one-off from the Nuvonic transaction).
Graham’s view
Checking forecasts, I can see a £2.87 billion revenue forecast on the StockReport for 2027.
Granted that this number is not organic, but that’s an increase of 11% over the 2026 figure.
This seems to match well with the outlook provided today of “low double-digit percentage organic” growth.
Indeed, low double-digit organic growth, plus some inorganic growth from the 2025 acquisitions, perhaps could help to boost FY27 revenue over that £2.87 billion forecast?
None of this seems to justify a 15% fall in the share price.
I’ve also checked the forecast EBIT margins and can’t detect any major disappointment in the outlook on that front, either. The market already expected FY27 margins to match FY26 margins.
But I think I can put together some post hoc reasons for today’s fall in the share price.
1. FY27 EPS forecasts have been on a rising trend, and the market may have expected a continuation of that trend, with scope for another upgrade. Today’s outlook doesn’t provide that.
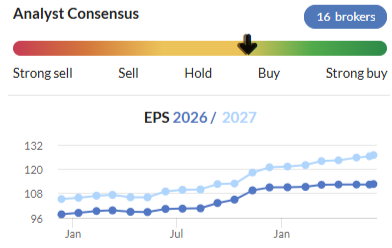
2. Instead, today’s outlook raises the spectre of a potential profit warning with talk of "uncertainty" and "varied conditions" in end markets.
3. Halma’s share price has been on a terrific run in 2026, up over 30% year-to-date. As I’ve stated several times recently, “selling the news” is a common tactic on the day of results or trading updates, after a run like this.
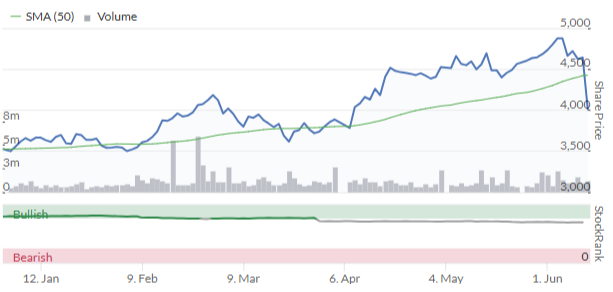
4. The P/E multiple going into these results of 36x is at a level that tends to be especially fragile to any negative change or uncertainty around the outlook. The ValueRank here is only 5.
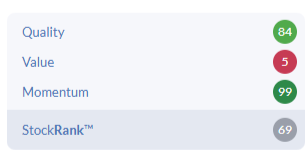
I believe that the new forward P/E multiple is about 31x, after today’s fall.
With photonics growth expected to recede, the total organic growth rate will shrink from 15% to maybe c. 11%, and the long-term target growth rate is only 7%. Personally, I expect higher growth rates than this, from a business trading at this sort of earnings multiple.
In December, I said that I wanted to find “any excuse” to downgrade our stance on Halma from AMBER/GREEN to neutral. The market cap today is higher now than it was in December, and I think I now have enough reasons to justify a neutral stance on this High Flyer. So I’m AMBER on this today.
Norcros (LON:NXR)
Up 3% at 270p (£243m) - Results for the 53 weeks ended 5 April 2026 - Graham - AMBER/GREEN =
I was praising Norcros last summer for simplifying its operations, at 268p.
Fast forward to 2026 and the share price has barely moved since then, although the company has continued to evolve.
It has closed its tile manufacturing operations in South Africa (Johnson Tiles South Africa), having already sold Johnson Tiles UK.
It also recently announced that it was exploring the sale of the remainder of its South African businesses.
But on the other hand, it bought a Norwegian supplier of wall panels for £45m.
All of these changes “reflect the Group's continuing focus on both simplifying the portfolio and increasing exposure to more resilient mid-premium product segments and geographies” (according to the update last month).
Turning to today’s results:
Revenue +10.6% includes the Norwegian acquisition of Fibo.
Organic growth of 0.7% is much more modest but is described as being “ahead of the market”.
Underlying operating profit +7.9% to £48m
Actual operating profit is only £22m, less than half of the massaged number that includes £26m of adjustments.
These adjustments include:
£13m of “acquisition and disposal related costs”. Amortisation is included here (nearly £8m).
£3m IAS19 administrative costs, which are to do with administering the pension scheme.
£10m of exceptional items, the largest of which is £7m of impairment but there are another £3m of miscellaneous costs lumped in here.
I’m willing to look past the acquisition and disposal related costs, and the impairment, but I’m not inclined to look past the other items.
However, after checking the pension scheme notes, I find that there’s an agreement to reduce NXR’s contributions to its running costs to max £1m.
So in this case, I’m willing to agree with the company’s interpretation and to look past the vast majority of the items they highlighted. I therefore estimate the real profit figure as about £45m (close to their £48m figure).
That’s a measure of operating profit, stated before the impact of net financial debt (£66m) and leases (£31m).
Outlook
Group revenue in the two months to the end of May 2026 was 3.1% ahead of the prior year on a constant currency like for like basis, adjusting for Johnson Tiles SA and the acquisition of Fibo. Market conditions are likely to remain subdued, with the pace of any recovery in the new build sector still unclear. The mid-premium RMI sector currently remains more resilient and the Board's expectations for FY27 are unchanged.
Graham’s view
The lack of organic growth is pretty unsettling. Combine that with the very competitive markets in which Norcros operates - bathroom and kitchen products - and we are left to conclude that this should trade on a very cheap valuation.
That’s what the market is giving us:
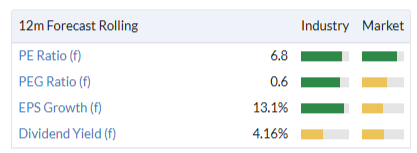
If I attempt to value it on an EV/EBIT basis, I have:
Market cap = £243m
Debts (including leases in our calculation, since EBIT excludes some lease costs these days) = £97m
Enterprise value = £340m
EBIT (operating profit) we estimated above at around £45m.
That gives an EV/EBIT multiple of 7.5x, only a little higher than Stockopedia’s estimate of the P/E multiple.
So I think Norcros shares do still offer value, but for good reasons.
At least the story has improved in recent years. We used to bang on in this report about its pension scheme and its South African exposure. The pension deficit is not really an issue now (it was £12m as of March 2024, and the company has been making annual contributions of nearly £4m). And they are leaving South Africa.
So I think it’s fair to be more optimistic about Norcros than we have been historically. We have been AMBER/GREEN since last year and I believe that remains the correct call today.
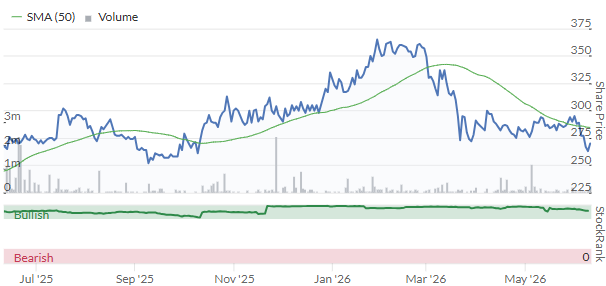
1-year chart:
Mark's Section
RWS Holdings (LON:RWS)
Down 13% at 88p (£381m) - Half-year Financial Report - Mark - AMBER/GREEN ↓
I have to admit to selling out of this still apparently cheap stock on the news that they were paying between £16.5 and £40m for a business that was founded two years ago which turned over £2.5m and lost £1.5m last year. Paying between 6.6 and 16x sales for a start up, just smacked of a certain desperation from management and I started to worry that this was not the behaviour of a company where everything was going well with its core business. In light of that, these figures don’t look to bad (at least on an adjusted basis):
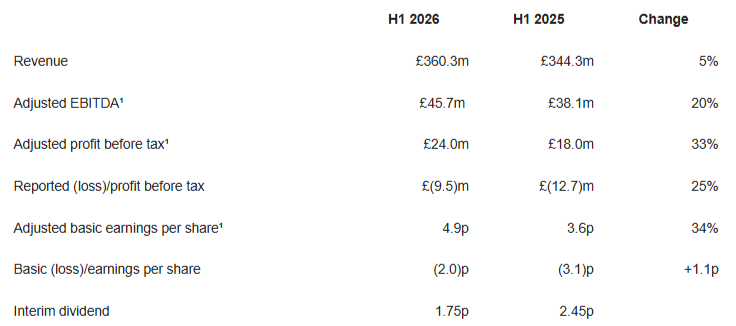
Although they appear to have forgotten how to calculate a percentage when it comes to their declining dividend payout!
Adjustments:
These figures are not a surprise, though, as they already announced £360m revenue and £24m PBT in their HY trading update. How they got there is what is revealed in these results. Here is their description of those adjustments:
Group Transformation Programme - £3.3m - including costs related to transitioning our current on-premises infrastructure to a modern cloud-based environment
Strategic project costs - £0.3m - costs involved in corporate development opportunities.
Restructuring and integration costs - £7.5m - related to severance and termination payments related to the Group's cost reduction plans, and other corporate restructuring initiatives.
These categories aren’t necessarily out of place for many companies’ reporting these days. However, these are mostly cash costs and explain why the cash conversion has dropped from 92% last half year to 67% in this half. The IT costs really should be part of the normal investment a company makes into running their business in my opinion. And I have a natural revulsion towards companies that want us to give them the benefit of cost-cutting but ignore all the costs of doing so. After all, they booked £4.6m of restructuring costs in H1 last year, and £14.2m in H2. These costs are looking less and less exceptional.
In light of all this, it is hard to believe that the adjusted figures represent the economic reality of the business, at least until it is clear that they are through the current restructuring phase of the business.
Segmental Reporting
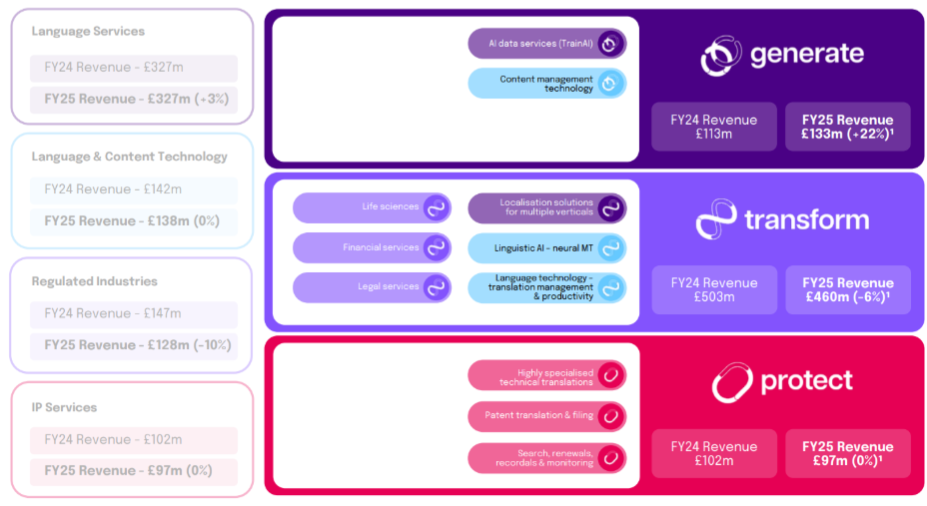
The company recently changed their reporting segments. As a reminder here is how the old structure maps into the new one:
Generate:
This is the stand out performer in this half, although a declining profit margin takes the edge off:
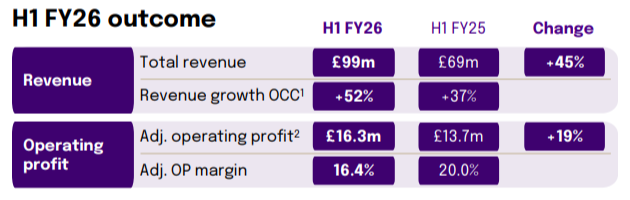
They say this was due to “Exceptional revenue performance driven by TrainAI from programmes with existing clients and initial revenues from a new global technology client.”
Strangely, TrainAI seems to be lower margin than the rest of this segment, and they say that in H2 “TrainAI exceptional H1 revenue will continue to dilute margins.” I’m not sure why providing a lot of training data to LLMs isn't a very high margin business.
Transform
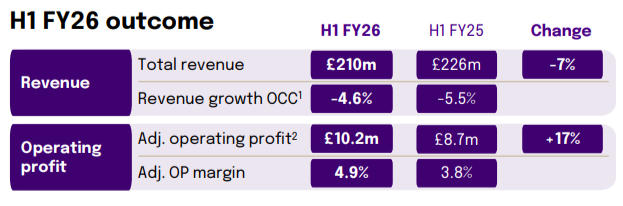
The revenue decline was in line with their previous guidance. This segment contains their own AI translation tool: Language Weaver Pro. This shows what we can expect, clients will pay less for AI translation, but the costs are lower too, driving higher profits on lower revenue.
Protect:
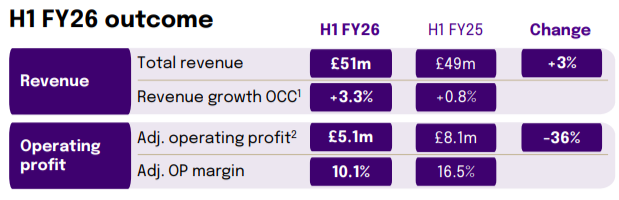
This is the most worrying part with the margin decline said to be due to product mix and an increase in overhead cost. This is where the Obviously acquisition sits and shows signs that one of the key contributors to historical profits is under pressure.
Strategy:
I continue to be worried about trainAI. This may be responsible for a return to revenue growth for the business as a whole. However, management have yet to give a convincing argument to me as to why they aren’t just giving away the crown jewels (a huge database of accurately translated technical documents) to competitors in return for a short-term payment.
Adding the pressure in Protect that appears to have led them to buy a loss-making start up on a high multiple of revenue, this shows that they may face technological competitive pressure throughout the business.
Outlook:
The outlook is said to be in line:
Expect mid-single-digit revenue growth on an OCC³ basis, improving profitability, and continued strong free cash flow conversion for the full year as we benefit from recent client wins, growth in Generate and Protect and our efficiency programme.
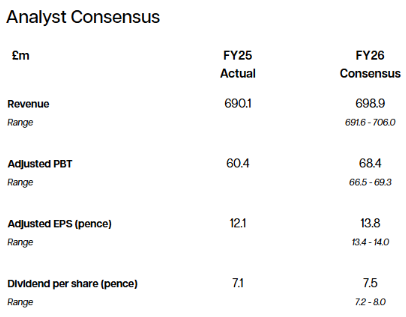
Mid-single digits aligns with the 5% revenue growth in H1, and would actually be above analysts consensus, but I would imagine the organic constant currency bit is doing the damage.
On profitability they add the line:
Current FX rates, after hedging, are expected to have a c.£2m adverse impact on full year PBT, alongside the anticipated £1m in-year impact from the Obviously acquisition which is expected to start contributing during FY27.
It is not wholly clear whether they consider themselves to be trading in line with expectations despite these factors. However, given the scale of the adjustments in these half year results, I wouldn’t be surprised if they are trading in line without these headwinds, i.e. slightly below.
Sadly, mere mortals such as us don’t have access to broker research, so it is hard to say if today’s share price drop is due to cuts to broker numbers, or if shareholders simply didn’t like the narrative.
Dividends:
Having failed to calculate a percentage for us, we fear the worst on the dividend payout. However, the cut to the interim dividend at 29% is less than the cut to the final dividend, which was down 56%:
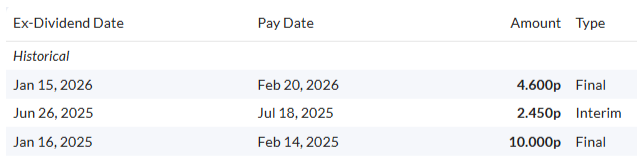
To hit the FY forecast payout the company would need to raise the final dividend to 5.35p, which may be a stretch considering net debt has risen from £25.4m to £32.5m year on year. Post period end, they have spent £16.5m on the Obviously acquisition.
The leverage ratio remains modest at less than 1x EBITDA. However, we are used to this business running with net cash, plus they have cut the dividend and not bought back shares despite the share price dropping to a third of the price they last acquired stock in the market. This suggests that they are comfortable with the current debt levels, but not particularly keen to take on more, given the big shifts happening in their core business.
Mark’s view
On the surface, these are reasonable in line results. However, the more I look into them, the less I like them. Hitting the H1 trading figures required continued significant adjustments for IT projects and redundancy payouts. It seems that hitting full year guidance will need a similarly heroic performance from the accounts department. They are already flagging FX headwinds and the loss from their recently acquired business. The cynic in me thinks they will shortly be asking us to exclude these too.
Then there are the issues of strategy: does it really make sense to be taking (what appears to be low-margin) revenue to train competitors’ LLMs on your proprietary data? Are declining margins in Protect flagging serious competitive pressures?
However, the fact that the strategy here is open to debate, and the company loves its adjustments are not new information. Which makes today’s double-digit fall a bit of a mystery. I can only think that the market may have gotten a little ahead of itself. After all, the strongest Rank here prior to these results was the Momentum one:
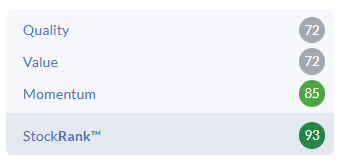
Part of the recent rise appears to be due to the market liking the Obviously acquisition. However, to me paying between 6.6x and 16x sales for a loss-making startup was a sign of desperation rather than strategic brilliance.
Roland upgraded this to GREEN following last year’s final results when the share price was around 80p, citing the recovering fundamentals and mid-single-digit forward P/E. The shares briefly touched 110p, but with them now back below 90p, many of the positive arguments still stand.
However, I think there are also some reasons for caution. That single-digit P/E is based on heavily adjusted figures, and the company already seems to be flagging some extra adjustments required to make current trading in-line with expectations. The dividend also looks like it may come in a little below analysts’ consensus for the full year. With these in mind I think we should take a slightly more cautious view of AMBER/GREEN, at least until the gap between adjusted and statutory figures is narrower and the strategy concerns are shown to be overblown.
PayPoint (LON:PAY)
Up 4% at 580p (£335m) - Final Results - Mark - GREEN =
First up, Paypoint are in my bad books for giving their RNS a promotional title (“Record profits delivered and reorganisation to deliver next stage of growth”) rather than what they are actually releasing (Results for the year ended 31 March 2026). When we look back through the myriad of news flow, it’s easy to miss what these are (although at least they got the classification right):
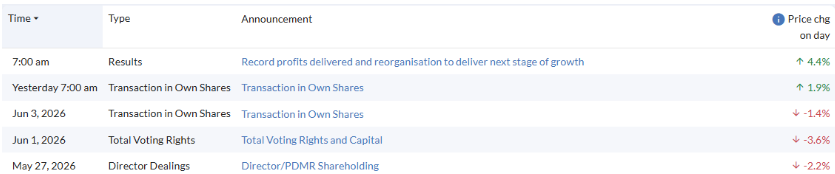
This already makes me wary and suspect they are doing this for Partridge reasons (“Lynn, to the untrained eye this could look rubbish and that I haven’t bounced back.”) Here are the actual figures:
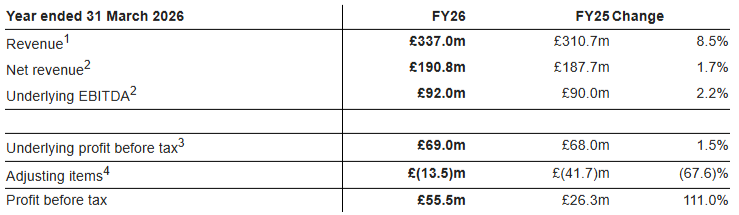
These are indeed record figures, but it is worth bearing in mind that net revenue, u/l EBITDA, and u/l PBT all grew less than the rate of UK inflation which grew by 3.3% in the reporting period.
Adj. EPS comes in at 73.6p, which looks below the 77.2p consensus in Stockopedia. However, it is hard to be certain that this is a miss given our lack of access to broker notes. The consensus appears to have not shifted despite a broadly in line, i.e. slightly below statement in March. What is clear is that this is significantly below the 97p consensus prior to the profits warning in November last year an the market appears to have been right in repricing the stock.
Adjustments:
The good news is that the gap between adjusted and statutory figures has narrowed considerably. Here is the breakdown:
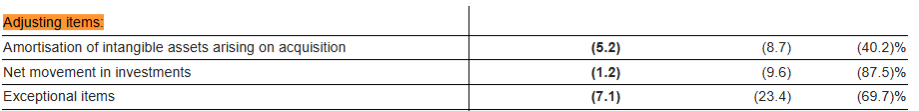
It is normal to exclude amortisation. I wonder if Aperidata is the source of the investment loss, as in the breakdown of Exceptional Items they take a receivable impairment:
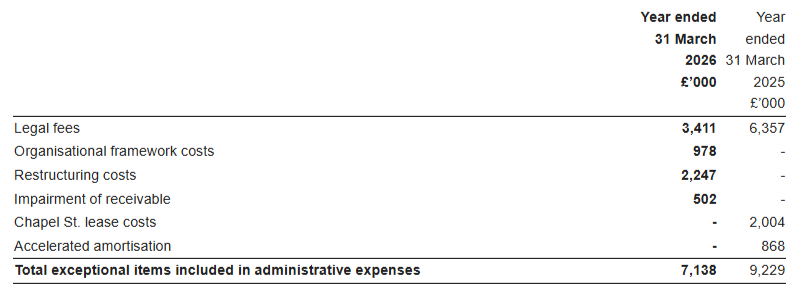
Saying:
The current period cost relates to a balance due to PayPoint Plc from Aperidata Limited, which the Company does not expect to recover. The Company also holds investments in Aperidata, which it has written down to £nil at 31 March 2026
Aperidata doesn’t appear to be insolvent as far as I can see, so presumably PayPoint have written down this receivable but chosen not to try to enforce the debt. At least these write downs appear to be one-off.
What has appeared in the adjustments is a restructuring cost. Again this is a company that wants all the benefits and shareholders to ignore the costs. At least in this case, the number is relatively small compared to the overall PBT. Overall, these are cleaner numbers than in the recent past.
Segmental reporting:
The company has recently changed their reporting segments, but also reports today in the old format. The stand out one is:
E-commerce divisional net revenue decreased by 4.9% to £15.6 million (FY25: £16.4 million)
Collect+ parcel transactions grew by 1.5% to 135.4 million (FY25: 133.4 million), with continued strong momentum from Royal Mail balanced by the impact of the InPost/Yodel commercial reset early in the year
Consolidation of Collect+ network at 14,076 sites (31 March 2025: 14,213) with a focus on service compliance and consumer satisfaction
This looks like one of the previous growth engines Collect+ is operating in a now saturated or low-growth market. The good news is that they appeared to have timed this very well, paying £6m in 2020 to Yodel for Collect+ and getting £43.9m for the 49% they sold to IDS (Royal Mail) last year.
In the new divisional structure, Digital Payments and Open Banking, is the best performing part:
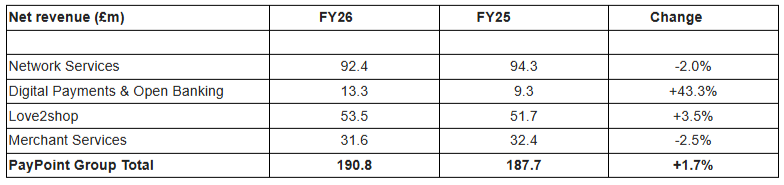
The Digital Payments and Open Banking business provides payment processing, Open Banking connectivity, and AI-driven credit analytics, helping organisations manage transactions, verify customers, and assess lending risk.
This is actually quite an exciting area as Paypoint are part of the UK initiative to cut out Visa & Mastercard from transactions. They say:
In Open Banking, we have made further progress in executing our strategy and leveraging our extensive capabilities. In PayPoint, we are focused on winning business with both new and existing clients delivering Open Banking services and payments channels, all enabled by obconnect and Aperidata, with 26 new client services live in the year, including the Department for Work and Pensions, AccessPay, Gousto and the Insolvency Service for Confirmation of Payee. A recently announced partnership with Raidiam and the Retail Energy Code Company (RECCo) will see the business providing a consent framework for the UK energy industry to securely share smart meter data controlled by the consent of end-customers. In addition, as a founding member of the UK Payments Initiative, PayPoint is closely involved in the rollout of account‑to‑account (A2A) payments in the UK, including exploring how these services can be made available in‑store to support inclusive access for all customers.
It seems a bit strange they namecheck Aperidata seeing as they appear to have been unable to pay money they owe Paypoint. However, the potential here is still large.
Cash flow:
For many investors in Paypoint the big attraction is their history of increasing quarterly dividends. Even without the special dividend that followed the sale of half of Collect+, The yield is impressive at over 7%. A 20p final dividend is declared in two quarterly payments of 10p each over the next few months, which is up 2% versus the previous year.
The combination of the normal dividend and £30m share buyback over the last year has been about half debt-funded, with net debt rising by about £35m:
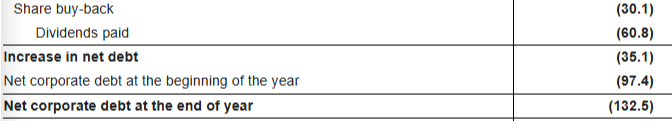
Capex has increased, but there were also one off payments to acquire part of a business, and one of the legal settlements. At least these should be one-off and improve the cash flow going forward. They still have an ongoing buyback:
A continuation of the £30m share buyback over FY27 and FY28 means the business remains on track to deliver a further 10m reduction in shares, representing an overall reduction of shares in issue of c.30% since the commencement of the buyback programme.
This certainly aids EPS. However, it seems likely that there will be a further small increase in net debt to be able to fund the ongoing dividend and buyback. The leverage ratio at 1.45 doesn’t look out of place for this sort of business, possibly placing them at the upper limit of their 1.2-1.5x target.
Outlook:
Although growth for FY26 was pretty lacklustre, the good news is that revenue growth is likely to improve going forward:
FY27 is a year of evolution for the business with the reorganisation now underway driving significant change throughout the Group and strengthening the platform required to deliver a net revenue target growth rate of 5-8% per annum.
They say they expect all four divisions to grow revenue this year. However, it sounds like there may be some more exceptional costs on the way:
Our priorities in the first quarter have been to: implement the announced organisational changes; ensure minimal disruption to the trading momentum in the business; and establish a strong foundation to trading early in the year. Early indications are that we have had a positive start to the year with resilient underlying trading and some encouraging new business wins.
And a H2 weighting is never well received by shareholders:
In terms of profit balance for the current year, we expect a greater weighting towards the second half, reflecting both an accelerating contribution from new business and the positive impact of several of our seasonal businesses.
Given the company warned in March and these results represent that
However, if they are right about being confident of hitting market forecasts, they are on a very modest P/E of around 7, which seems low even adjusting for around a third of the market cap in net corporate debt.
Mark’s view
Graham controversially upgraded this following the second (although this time minor) profits warning in March this year, citing the continued modest rating and high yield. There is also an ongoing share buyback, which suggests that the company continues to view their shares as too cheap compared to the future prospects, a sentiment I agree with, given the return to growth of all four divisions and the potential in Open Banking/Payments.
However, the recent shareholder returns have been at least particularly debt funded and with a H2-weighting guidance, that debt level is likely to rise in the short term, increasing the risk. They also have form for missing expectations recently, and a lack of broker forecasts visible to us, means it is hard to judge if those will be moderated going forward.
Despite these concerns, the valuation wins out, in my opinion and I don't see anything in these results that should change our favourable view. GREEN
Wizz Air Holdings (LON:WIZZ)
Up 6% at 1031p (£1.0bn) - Final Results - Mark - AMBER/RED
When I previewed this in The Week Ahead, I highlighted how Ryanair CEO Michael O'Leary publicly claimed that Wizz Air could face bankruptcy by late 2026 due to soaring global jet fuel prices, and the companies push back against that statement.
These results highlight that the company had been expanding prior to these cost winds. Possibly putting themselves in a uniquely challenging situation:
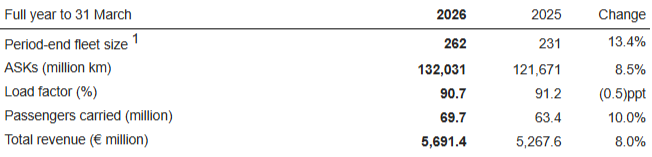
It stands out that a 16% increase in EBITDA leads to mere break-even at a statutory profit level:
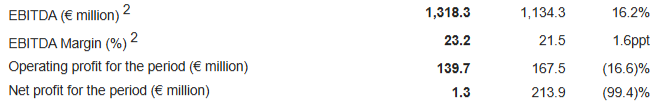
These are the things I said to look out for in these results:
Middle East Profit Hit: The Middle East historically accounts for about 8% of Wizz Air's capacity, so watch how effectively they have redeployed these routes, and whether Summer booking resilience has helped soften the blow.
This is what they say:
Most of this capacity was immediately redeployed to our core CEE markets, improving the existing summer season products to destinations in Spain, Italy, Croatia, Albania and others. We continue to monitor closely the situation on the ground in the Middle East and in Ukraine. On 28 of May we resumed flights to Tel Aviv from most of our CEE bases.
GTF Engine Grounding: The exact number of aircraft out of service and the timeline for their return. Details of any compensation from Pratt & Whitney or insurers.
This is what they say:
As of 31 March 2026, Wizz Air had 30 aircraft grounded due to GTF engine-related inspections; showing an improvement compared with the end of F25 when the grounded fleet comprised 42 aircraft. GTF engine-related groundings expected at the end of F27 are in the range of 15-20 aircraft with this figure reducing to 0 by the end of calendar year 2027.
They say they “continued to receive OEM compensation from Pratt & Whitney related to the GTF engine issues” but the amount doesn’t appear to be specified.
Fuel Hedging for FY2027: The company may be largely protected for FY26, but what about future years? How does this impact forward guidance?
They look to be reasonably well covered for FY27. However, a lack of coverage for FY28 stands out:
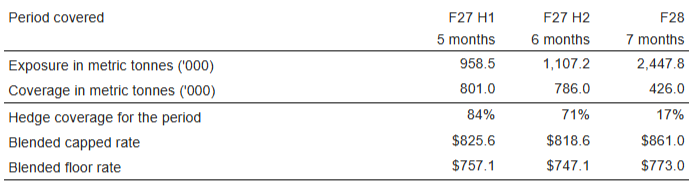
Presumably, this gives them enough time to reflect fuel prices in ticket prices for that period, so may not be an issue.
Forward guidance:
In perhaps a worrying sign, they refuse to give any forward guidance. It is clear that capacity is growing given the fleet growth, and they say that load factor is expected to be flat, which means around 90%. This seems reasonable but we don’t know the pricing they have used to get there.
Balance sheet:
Net debt is significant, but is flat, which actually seems impressive given the fleet growth:
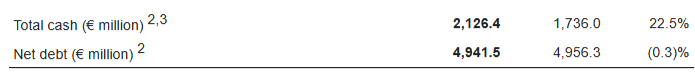
Net cash up significantly gives them a lot of liquidity. However, like all airlines, the model of selling a customer a ticket before the flight tends to lead to significantly negative working capital.
Valuation:
Given the lack of guidance it is hard to consider valuation. Brokers clearly think current events will lead to an EPS loss:
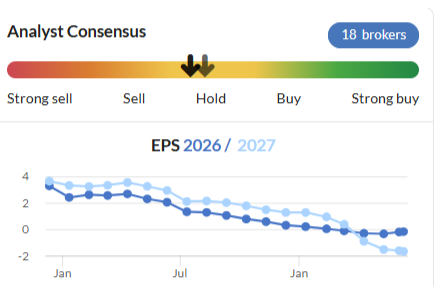
This is a cyclical industry and the company has generated significant profits in the past. However, I have no idea when it may do so again. There isn't an obvious asset play as it trades on a premium to Book Value. I therefore put this in the “too hard” category.
Mark’s view
There doesn’t appear to be signs of the immediate solvency concerns raised by competitors, which is perhaps why the market liked these results. However, with no forward guidance and brokers forecasting EPS losses for the foreseeable future, I struggle to make the investment case here, versus something like Jet2, which is forecast to be profitable and on a lower P/TBV rating. So I feel I need to go AMBER/RED overall.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Space Exploration Technologies (NSQ:SPCX) - love the name and Musk won’t damage it.
I want the “shovels”. Filtronic (LON:FTC) ? Not convinced but will take the punt, can buy it with the coffee budget. Ast Spacemobile (NSQ:ASTS) already in the “space”. Maybe the telecoms cos (a spade is metaphoric).
The biggest debate out there.
Meanwhile in the UK lol.
SSIT ?
Ishares Msci South Korea Etf (PCQ:EWY)
Currently UP 10%!
as SK Hynix (KRX:000660) chairman announces plans to triple wafer capacity by 2034 to meet AI memory demand.
I hold STMicroelectronics NV (NYQ:STM).
All the best
The Space Exploration Technologies (NSQ:SPCX) IPO has received $100+ Billion of orders from retail investors.
SpaceX is looking to raise $75 Billion in the biggest IPO in history.
The biggest IPO in history could be fulfilled by JUST retail investors.
All the best
Norcros (LON:NXR) I think the lack of organic growth needs to be seen in the context of a tough macro and very subdued housing market. Earnings have actually held up better than nearly all the other building supply companies that I track, so I remain fairly positive on this one and would say it looks undervalued after recent share price weakness.
Does anyone know why the sudden fall in Thor Explorations share price?
It isn't sudden, just following gold on the way down (bearing in mind the margins involved). What worries me as a holder is the short life of mine despite drilling for Segilola, no results have been announced and the other holdings are years from production.
Probably more to do with the short life and the prospect mix , going to be a stormy ride
RWS Holdings (LON:RWS) not to brag but I've held this name for a while - it's been quite the tax asset. I'm by no means an expert in the industry but I do think the TrainAI segment is a lot more secure in nature than is being presented here.
the important thing to bear in the mind is that the data being serviced is almost entirely the client's own, and not proprietary RWS data sheets. What RWS brings is a huge number of humans to helps label, annotate and validate the data. these needs are continuous as both client data will expand and model needs will shift. the data will be annotated in a particular way which helps with stickiness here which is high. finally, there are typically large set up costs associated with new clients so the margin profile should improve over time.
Spire Healthcare (LON:SPI) the PUSU extension which expired today has been further extended, but only for 14 days, to 25th June, probably suggesting that the takeover is more likey to happen ?? The market thinks so with the stock up 3% to221p on the news.
Norcros (LON:NXR)
all seems accepotable tickover stuff here - very sensibly run company.
They are probbaly making the best of very anemic marekt conditions - is outperforming markets enough when those markets are growing by inflation ?
anway pretty much nothing of relevance to add here.
points of note
1 they are another year closer to paying materially less into pension which has historically needed funding to the tune of several million pa - but hopefully going forward less of an issue.
2 the pension scheme itself is uber mature and has been closed for many years ref new entrants - so each year their are slight less members in the scheme - the size of the scheme liabilities - which i use as a good proxy for "risk" has been trending downards very nicely over the last 5-10 years - so it may not be every year but the quantified amount they have to pay in the future "all in" peaked many years ago - so each year it derisks itself. The main danger here is that scheme assets may not genrate positive returns necessary to keep up with the liabilities owed out.
3 they are looking to exit south africa - that may short term reduce earnings - but they will be a leaner and more efficient buisness without SA - and Sa has geopolitical issues not faced by some countries
Nore sure how important ROCE is all i do know is i want higher rather than lower and they quote underlying ROCE of 20% - that seems pretty decent for this business type. Being underlying though well they might be stripping out stuf that doesnt help. But i will give them a pass when they are contratulating themselves on these metrics
o Underlying return on capital employed1 (ROCE) up 2.7% to 20.0%
4
debt is temporarily high due to the £45 mill Fibo acquisition last year - they are a cashflow machine normally - so i would expect in a bog standard year they would have £15 mill of cahsflow free after paying dividends. Note they had £7 mill finance costs last year - so scope for paying down debt and the reducing the finance costs. Although with their available facility of £150 they are perhaps looking at next acquisition already. Unlike many they have been a a very safe pair of hands historically re acquisitions they have made. Acquisitions being the key driver of growth - once the debt had been kinda paid down ref purchase (inititially extra debt eats into profits made by acquired unit)
pe currently showing as 6.8 that seems kinda stingy - but this company has most comanded low rating historically - it was at 350p not so long ago. Cheap can get cheaper but if they can keep upping profits and paying down debt i cant see price hgoing much lower than where it is now. Cant argue if the market is slightly worried though about ability for lfl profits to increase without the need for acquisitions - they have deffo bought in most of their growth in profits i think.
I have raised a green button query on this but rarely get a reply so I thought i would ask other subscribers.
When I try to access a single company page I enter the ticker, click on the relevant company in the drop down menu and . . . . nothing happens, this is hopeless, it doesnt happen all the time but is becoming more frequent. I like the Stockopedia format but if I cant access company pages it is worthless to me. Any others get the same experience or anyone from Stockopedia can help.
TIA
I've had occasional issues, but you will get that with any web site. Mostly, Stocko behaves itself and I have been happy with it. Like you, I would be more concerned about the green button service.
Helvellyn - I have had this and have worked out why - if I am on a page that automatically refreshes itself - such as app.stockopedia.com/discussion that I always go in on - when I click on the company page that I want to go to and nothing happens I have noticed a blue line going across the screen above that box - that is the main page automatically refreshing itself and it overrides the call to the company page.
sharw
Thank you for taking the time to help. That makes a lot of sense.
Perhaps you could man the green button in your spare time ;-))
I have noticed the ticker often does not work, l often find l have type, the whole stock name before it appears on the drop-down list. Gave up with green button last year.
RWS Holdings (LON:RWS) "I have to admit to selling out of this still apparently cheap stock on the news that they were paying between £16.5 and £40m for a business that was founded two years ago which turned over £2.5m and lost £1.5m last year."
Hmm. I seem to recall that RWS was highly respected some time ago. I don't know much about it, but from what the other Mark wrote, I'm a bit sceptical, too. Looks like net debt will double over the next few years, maybe. They also seem eager to issue shares (6% pa over the last 5 years).
So, admittedly reading this mostly from cold, I'm getting the impression that they're being too aggressive. I see the acquisition is AI-related, which smacks a little bit of bandwagoning.
If a company like GOOG makes a pig's ear of their AI investment then they can simply write it off, shrug their shoulders, and move onto the next thing. With RWS the impact might be more substantial.
I'm just getting a whiff of overreach.
I sold out on the opening bell. The FCF used to pay divis was my reason to buy in and that story is now diminishing. I'd be a buyer again at lower levels, still made a decent profit but watching from the sidelines now.
AEO...Nice contract win in the US
Aeorema Communications plc, the strategic communications and live experience group, is pleased to announce that its brand experience agency Cheerful Twentyfirst has been awarded a prestigious three-year contract to deliver Climate Week NYC in 2026, 2027, and 2028.
This major contract win solidifies Aeorema's position as a trusted partner for high-impact global conference work and follows a highly successful three-year partnership with Climate Group, the organisation behind Climate Week NYC.
SPCX Not long to go. Everyone have their popcorn ready?
Someone worked out that in order for SPCX to be worth its valuation long term, the revenue growth would put it at something like the entirety of the rest of the US economy. Something like that, anyway.
Even if revenues do get to where they need to be to justify the valuation, then equity raises may well be likely along the way. SPCX is, after all, losing money. That's not something I've seen anyone really discuss.
Like oil, the cream always comes to the top and whilst I love a quick 'brunch and lunch' for the daily bread I still keep firmly to the few that good quality british companies are the foundation of a good portfolio. Added to that there are many good smaller companies that are doing really well. So, I try to avoid being sucked into the hype of Mr Musk, but good luck to him and those who beleive in him, he is the new Messiah, or is he just another naughty boy :)
In the somewhat boring mundane matters of market health - VIX spiked a little yesterday and is just north of 20 - mainly I think due to volatile negotiations in the Middle East. 21 is fragile but not quite banging the buy drum. MOVE on the other hand, actually fell - to a very orderly 74 - remarkable on CPI data day that the bond market could hardly be bothered to look. As far as bonds are concerned there is nothing to see ... which is not quite on message for $ debasement and US funding issues. The trade weighted Dollar didnt do much either but I think investors are caught between what to dislike more, the Dollar or the Euro and can't quite make up their mind - therefore score draw. My conclusion from all this is a little confusion. Oil isn't weakening because the straight isn't opening - equities are a little twitchy but bonds still assume all will be ok. This isn't quite the prefect weather forecast you would like on the eve of the largest IPO in history for a company that makes a gross loss. Movies were made the last time Goldman Sachs were accused of selling investors worthless pieces of paper - it took less than 20 years for the queue to reform - which is impressive.
Can you have a look at RWS Holdings (LON:RWS) please. Everything seems to be fine but you wouldnt know it by the share price reaction.
what about the apparently unplanned costs from the 'acquisition'?
and the unexpected further dividend cut to fund the (very expensive) acquisition.
Halma (LON:HLMA) Revenues up 15%. Nice. Keen-minded readers might recall that this is a company that I thought was good back before 2000, but never bought. It was one of those "one that got away" stock. I was too heavily into Ben Graham at the time. I'm more flexible these days. I think Graham does a lot of damage to more modern readers. It's too rigid,
Stocko's Graham Defensive Investor Screen is up a mere 18% since inception, for example, compared to 95% for the All-Share.
Still, HLMA shares were down 15% at one point today, but now down around 10%. It illustrates the dangers of buying on a fwd PE in the 30's. The Value Score is 5, which is pretty dangerous.
Mind you, the share price was around 3000p five years ago. It has a fwd PE of 44 at the time, and a Value score of 11. It's an example of a company that managed to go up despite the high price.
It's a pretty risky strategy, mind.
Another company reporting today, RWS Holdings (LON:RWS, is down 18%. Ouch. Five years ago the shares were at 600p (now 89p). Fwd PE was 25 and value score was 21. Lots of other companies that were highly-rated five years ago have had dismal performances, too. Many of them Nick Train picks.
Lot of sutff like AUTO (I bought earlier this year), RMV, EXPN, and so on. Down in the smaller caps, FEVR is down from 2500p to 820p over 5 years.
Now I just stick to buying shares with fwd PEs less than 16. It's safer that way.
I guess it's only down to its high a couple of months ago and the thesis is in tact.
I agree though - high multiple does make it more precarious.
What do we think would happen to valuations if Mr Musk fell down the stairs and broke his neck?
There is definitely some 'key man risk' here.
Graham’s summaries at the top of the report every morning are simply superb….. makes fantastic reading!
Maybe this time it’s different! Very tongue in cheek Graham.
Would be interesting to hear the team's view on where NCC goes from here now that the strategic review has concluded without a sale. Chris Mills was bullish on this as a special situation, but will he remain interested now!
The Space X valuation fits in perfectly with the 'mania phase ' of the 18.6 year economic cycle.
Just for fun I will break protocol and let everyone know how IPO subscriptions go. The "bank" rings high profile fund manager and asks if he is interested. The PM feigns interest and asks how much stock he is likely to get....at which point he is told off the record that orders will likely be scaled back 75%.....so PM needs to put in for 4x what he actually wants in order to get the right amount. So everyone puts 3-4x what they want and it all kinda works with +10-15% rise on day one some of these nice chaps decide to lighten the load. This all falls down when occasionally the 3-4x is wrong.... and calls go out the night before and morning to let PMs know they did a little better than expected....and successfully got say 50% or more. Now you have a stock that may only pop 2-3% or down even...and PMs have 2x the stock they want. Colleagues fall around laughing at naivety of PM. In theory it's a bad day for the bank too if the stock falls but they still collect their fee!!! And my point..... over subscribed ?? I would hope so....but don't believe the hype. 10% first move won't be enough with this one - no PM will want to admit losing money on this....price could do anything from +40% to -40% in first day. That's an option not an equity.
Brilliant insight RD! Thank you so much!
Its the price achieved on day 15 that's of interest, This is when the $1.5T in Nasdaq trackers have to load up on the stock. AI reports they can't front run this (which can be done in the UK) so the price of the stock which is of interest is set at the end of day 15.
The fund manager might be tempted to hang on to their allocation to at least day 15 methinks, along with all the hedgies following the same stategy.
In reality, who knows - but its going to fun to watch!?
BTW I was amused to hear that Merin SW had applied.
Great explanation. It all sounds crazy.
Yes, agreed Graham. Whilst Elon Musk is a genius the valuation is plain stupid. Possibly we are very close to the top of this bubble or this will be seen as the top! PayPoint (LON:PAY) results today would be good to cover, albeit always a bit complex with the 4 divisions. This is a real company delivering £122m operating cash flow and with a market cap of only £335m.
For SpaceX it reminds me what Charlie Munger said about Tesla:
To paraphrase
“Not a stock we would get involved in but never bet against Elon”
Somehow I doubt that Graham will ignore PayPoint (LON:PAY) today. I do confess to being slightly underwhelmed by today’s numbers, but perhaps they were flagged well in advance. Market response so far is a resounding ‘meh’.
PayPoint (LON:PAY) Can't grumble with 20p of divis over the next few months
the valuation is plain stupid.
is that a matter of fact or your opinion?
was investing in apple amazon and google stupid when they were on racy ratings - many so called clever people on here said Tesla at $50 bill valuation was the most overated compay even and an outright fraud - well Tesla is now worth 20 times what clueless people thought.
Have you done much research on Space X - or have you just defaulted to valuing in on what its doing now - rather than what it will be doing in 20 years.
i would have perhaps got it if you said my opinion is the valuation is plain stupid but to state it as fact seems to say i am clever and the market is stupid. Its the same stupid argument made by those who thought Telsa wouldnt make it - heck many probably still deny reality that they got it wrong there and marekt got it right.
What would be your conservative valuation for starlink specifically ?
What about the AI side of the business - look at how other AI related stuff is valued now.
what about musk - he has ability to get people top back him with cash - and it that regard he has delivered in spades ref Paypal - tesla and now space x.
i think on the balance opf probabilities its probably overvalued - but i am not that stupid that i wouldnt have any confidence that i wouls be wrong. If AI and starlink deliver thats some serious revenue generating possibilities - without all the added other possibilities.
Nice one rmillaree.
All the best
Oh god…..
Please go somewhere else
All the best
Well I wouldn't call Yiannos a God but he is certainly up there!
I for one, and I would be amazed if there are not others, think that if Yiannos did go somewhere else this platform would be worse for it. Whether you like his communication style or not I feel that he has a lot to offer.
I have been called God in the past for being consistently correct in my stock market predictions.
Much appreciated!
Stay around, you have so much to offer here.
All the best
I think a lot of it is down to those who dislike Musk now due to his politics.
The same people who over the decades lauded him as a business genius and savior of the planet with his EV development. The same people who backed Tesla to the hilt being early adapters etc. Those same people who saw Tesla as a long term bet like Apple, Amazon etc.
Now they claim he has suddenly lost all that business and engineering ability. They can't even give credit to Starlink's impact on Ukraine so they definitely won't allow any positivity to SpaceX. So if it drops Friday they will view it with glee. Simply because of politics.
my personal opinion is that Musk is a knob but can run a top buisness well - so i get it those that dont believe the hype - and i dont think he helps himself (eg calling that caver who he had no evidence was a you know whata you know what) - but i do know he is unlikley to change so if musk is involved well you gotta take the "package" and to me it has an unpleasant element - that probably doesnt help - but ref turning blue sky stuff into reality well he is the man to me.
To be fair, I have had a strong dislike for Musk both when he was a leftie and a rightie, and refused to invest in Tesla at $10 a share, because he seemed like a scumbag and his business seemed less interesting & realistic than other options. Instead, in the same era (~2013) I invested in Google, Meta, Apple and others and I don't really have any regrets tbh.
There are always other ways to make money than doing things that make you unhappy.
Hi rmillaree
For anyone interested in Space X this is a 42 min vid explaining the company and its important developments. This is an X link but I assume it can be accessed from other social media platforms.
https://x.com/elonmusk/status/...
Regards
Howard
Hi Howard,
I am old enough to remember Meta Platforms (NSQ:META) 2012 IPO and the British tabloids and financial experts comments at the time!
Can’t remember the exact newspaper publishing every day about Meta Platforms (NSQ:META) earnings at the time……..
Meta Platforms (NSQ:META) price dipped briefly in the summer 2012 and then quadrupled in three years….and then 20X.
Then, and now, I clearly spot the same wrong argument! Financial experts relying on historical data and past revenues, rather than trying to predict the forward looking business realities of Space Exploration Technologies (NSQ:SPCX).
I am not a genius as Musk and no one posting here is as well!
All the best
Hi yiannos1
Thanks for the comment and history of Meta Platforms (NSQ:META) share price.
As you know one of my holdings is Palantir Technologies (NSQ:PLTR) whose SP dipped to $6/$7, now $130.21 (as of close yesterday). I could easily list other US companies at the forefronts of innovation who have had periods of negative sentiments as well as degraded SP performances but have risen to great hights, Amazon.com (NSQ:AMZN) , being another.
One thing I have noted investing in the US. It is not at all like UK or even European investing.
The market is huge, liquid, thrives on taking risks and has a volatility unlike UK/European indices
I have also noted it pays to look quite deeply inside what these tech/innovation companies actually produce. Quick examples. Look at Tesla (NSQ:TSLA) energy business and its growth rates. Or the growth rate of Space Exploration Technologies (NSQ:SPCX) Starlink business.
Both of these seem to be treated as side issues to the main businesses but each are serious businesses in their own right.
Regards
Howard
Rockets are a side line imo and Mars. Defence (war) internet and AI are more closer to home. The IPO is for gamblers but once the two year cool off over with the onwards and upwards to the stars.
I also remember ceo of Sun Microsystems saying in 2002:
“At 10 times revenues, to give you a 10-year
payback, I have to pay you 100% of revenues
for 10 straight years in dividends. Do you
realize how ridiculous those basic
assumptions are?
What were you thinking?”
Nanoco PLC are trying to delist their company and take it private when it is more than 90% owned by retail shareholders. The market has voted about it by slashing its market cap to less than half its account balance. Nanoco PLC still has a cash balance of £10.1 million as at 19 May 2026. Hargreaves sent a note to its clients yesterday alerting them about this but they didn't tell them about the cash balance so some could have been frightened into selling. Please help us get the word out - if you have a following I would appreciate you tweeting this message.
The board of directors barely hold any stock so retail shareholders can easily block this delisting. In a private company, with limited reporting requirements, nobody outside the company would have a clue what's really going on. It's funded for years on end. Countless ways they could cut costs without going nuclear like this. They could opt for an AIM listing for example which would slash listing costs.
Nanoco’s latest circular says there are 195,543,816 ordinary shares, each carrying one vote, as at 26 May 2026. The delisting/cancellation resolution needs not less than 75% of votes cast to pass. Abstentions/“vote withheld” are not counted in the for/against calculation.
Assuming 50% vote turnout
Total shares: 195,543,816
50% turnout: 97,771,908 votes cast
To pass, the board needs 75% of votes cast:
97,771,908 × 75% = 73,328,931 votes FOR
So the maximum “against” vote they can tolerate is 25%:
97,771,908 × 25% = 24,442,977 votes AGAINST
Therefore, to block the delisting, shareholders need at least:
24,442,978 shares voted AGAINST
That is effectively 12.5% of the entire company plus 1 share, assuming exactly 50% turnout.
Board 1.5% 2.93m
Nanoco Group PLC Employee Benefit Trust 6.7% 13.10m
Combined 8.2% 16.03m
If the board and Nanoco Group PLC Employee Benefit Trust votes are cast FOR, they would represent about 16.03m FOR votes. But that does not change the blocking number under the 50% turnout assumption - you still need 24.44m+ AGAINST because the 75% test is based on total votes cast.
At 50% turnout, around 24.45 million shares voting AGAINST should be enough to block Nanoco’s delisting.
Every “NO” vote matters because abstentions do not count.
Someone check the maths above - with 50% vote turnout we need 24.45 million shares voting AGAINST to block delisting.
THE BIGGEST ENEMY FOR US RETAIL IS PASSIVITY - INACTION - MAKE SURE TO VOTE AGAINST THE RESOLUTIONS SO THE COMPANY IS FORCED NOT TO DELIST. THEY CAN LIST ON AIM IF THEY WANT TO SAVE MONEY.
But maybe this time is different? Love it Graham!
Yep Graham is on the ball with this one. It’s never different despite what the Musk sycophants would have you believe…