Daily Stock Market Report (Thur 11th September 2025) - NXQ (backlog) CAU TRN FEVR TRI DFCH BBSN

Good morning! We are well into earnings results season now, so expect another interesting day.
07:50 Agenda Complete
13:30 Wrapping it up there - report is complete
Spreadsheet accompanying this report: link (last updated to: 5th September).
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
Londonmetric Property (LON:LMP) (£4.21bn) | 5 transactions with NIY of 5.5%, adding £4.6m in rent with WAULT of 23 yr. Includes 5 Premier Inns. | ||
Energean (LON:ENOG) (£1.65bn) | Prod -5% to 138kboepd, PBT +24% to $110m. FY guidance cut to 145-155beopd (prev 155-165k). | ||
Playtech (LON:PTEC) (£1.23bn) | Rev -10%, adj net profit -12% to €16.6m. “Strong H1”, FY25 adj EBITDA to be ahead of exps. | ||
Trainline (LON:TRN) (£1.08bn) | H1 rev +2% w/ ticket sales +8%. FY26 adj EBITDA to be “top end” of +6%-9%. £150m buyback. | AMBER/GREEN (Roland) Trainline shares have been weak this year, despite seemingly strong trading. Today’s update flags up an 8% increase in ticket sales, but revenue growth of just 2% highlights the impact of a 0.5% cut to its UK commission rate in April. More broadly, I think this also emphasises key risks for this business – political and regulatory exposure and new competing ticketing systems. However, Trainline is good at what it does and has minimal competition, in the UK at least. The group’s international and B2B units are providing useful diversification to help offset changing travel habits among UK rail users. Quality metrics are now at levels I’d expect for a software business of this kind. With the stock trading on a P/E of 14, I think the valuation looks reasonable and am happy to maintain our moderately positive view. | |
Fevertree Drinks (LON:FEVR) (£915m) | Rev +2%, adj EBITDA +1% to £18.4m. Cash £130m. On track to deliver FY expectations. | AMBER/RED (Mark) The continued lack of top line growth for a company on this type of valuation has to be a major worry. Some will point to weak consumer sentiment and the transition of the US business to a royalty one. However, I think it is equally likely that the premiumisation trend in mixers has peaked, and any growth from here will have to be driven by expensive marketing campaigns or event sponsorship, rather than a growth in underlying consumer demand. | |
THG (LON:THG) (£415m) | H1 in line: rev -2.6%, gross profit -8.5%, pre-tax loss of £66.7m. Strong Q3, FY exps unchanged. | ||
Kenmare Resources (LON:KMR) (£280m) | Work started to connect two new dredges to WCP A. On track for FY production and cost guidance. | ||
Trifast (LON:TRI) (£119m) | Trading in first four months of FY26 has been in line with exps despite macro headwinds. | AMBER (Mark) [no section below] This is an in line AGM trading statement. Coming just two months after the last update, it is unsurprising that not much has changed. However, the last update was a profits warning, with a negative sounding outlook and brokers reducing EPS low double-digits. It does seem strange, then, that the shares have risen 20% since then, making them look significantly more expensive on near-term forecasts. However, the investment case here is largely based on their transformation program turning things around for later years. While downgraded near-term performance isn’t a great sign for success here, it probably isn’t enough to change our neutral view. | |
Cornish Metals (LON:CUSN) (£90.4m) | Excavation at South Crofty tin project started in August 2025, as planned. | ||
Scancell Holdings (LON:SCLP) (£88.6m) | Operating loss £15.0m (FY24: £18.3m), cash balance £16.9m (FY24: £14.8m) following £11.3m raise. “Cash runway through to the second half of 2026 with further upside opportunities.” | ||
Distribution Finance Capital Holdings (LON:DFCH) (£83.3m) | PBT +20% to £9.0m, Loan Book +21% £728m, cost of risk at 0.63% (30 June 2024: 0.61%), Adj. EPS +27% to 3.8p, Adj. TNAV 70.2p. “As a result of our strong performance, particularly in net interest margin, we expect full year profit to materially exceed current market expectations with an improvement in market expectations for FY26 also anticipated.” Panmure Liberum estimates: | GREEN (Roland) | |
Brave Bison (LON:BBSN) (£61m) | Acquisition: MTM London for initial cash-and-share consideration of £5m cash +£1m shares +£6m contingent consideration over 5 years. Results: H1 Revenue +19% to £12.0m, Adj. EBITDA +6%, Adj EPS -1% to 0.14p. Trading Update: FY25 trading ahead of market expectations and FY26 Board expectations upgraded as a result of the strong trading and the acquisition of MTM. | AMBER/GREEN (Mark) Lots going on here with another acquisition and Adj. EPS upgraded by 7% by their broker, Cavendish, in response. Cavendish also issue FY26 forecasts for the first time with 17% Adj. EPS growth penciled in. This makes the shares look good value on a forward P/E of 10.8, although once we take account of the adjustments made, this may be closer to fair value than their broker would have us believe. However, momentum is behind the company in share price, EPS and deal-making. While that impetus is there, it makes sense to remain broadly positive. | |
Lords Trading (LON:LORD) (£59m) | Revenue +8% to £232m, LFL +7%. Adjusted EBITDA -4% to £12.1m. EPS -14% to 1.32p. Net Debt down £15.4m to £20.9m. Interim dividend held. | ||
Centaur Media (LON:CAU) (£52m) | Sale of The Lawyer for £43m on an enterprise basis, 16x FY24 Operating Profit. Cash on 9th September £24.5m. Sale expected to complete at the start of October. Net proceeds to be returned to shareholders. | AMBER/GREEN (Mark) [no section below] The Lawyer was always the most valuable part of Centaur and 16x operating profit seems a good multiple for this. This means that the company will have £67.5m cash (minus transaction costs) at the start of October compared to a market cap at close of £52m. The bulk of this is likely to be returned to shareholders so there is little reason for the shares to trade at a material discount to this. The remaining titles and business generated £15.5m of revenue in 2024 but it looks like only around £1.5m Adj. EBITDA, so perhaps another £5-10m to come from the sale of these. The downside is the group had £2.7m of central costs in 2024 including significant board pay packets. (There has been £3.4m spent so far in 2025 based on the £8.9m Y/E cash balance, £19m received for MiniMBA and current cash balance.) So, perhaps it will cost around £5m to sell the remaining businesses and close the company. Giving some margin of error, total return between £65-75m with £70m as a central case. So perhaps a further 10% or so upside to come from the current £62.9m market cap at 43p to buy. | |
Rentguarantor Holdings (LON:RGG) (£34m) | Rev +87% to £970k, op loss £443k. Cash £729k. Recently moved to AIM from AQSE. | ||
Tavistock Investments (LON:TAVI) (£25m) | Refocus on those who are no longer being supported by other advisory firms. Acquires 77% of Lifetime Financial Management Intermediaries Limited for £3.7m + £2.25m capital contribution + 4 year earn out capped at £9.9m in total. Lifetime LBT Y/E 31 March was £81k. | ||
Haydale Graphene Industries (LON:HAYD) (£23.6m) | Collaboration with Interfloor to integrate JustHeat heater inserts into their flooring systems. Cost restructuring in line, reducing cost run-rate to below £200k/month, down 70% on last year. Cash £1.92m. | ||
Defence Holdings (LON:ALRT) (£22m) | Project will enter “value realisation" in December. | ||
Petrofac (LON:PFC) (£21m) | Restructuring update: agreement in principle with Samsung & Saipem | Agreement will enable restructuring to proceed, expected to be completed Nov 2025. | |
Zinc Media (LON:ZIN) (£16m) | H1 Revenue +72% to £22.9m, Adj. EBITDA £0.9m (24H1: LBITDA £0.7m), Adj. PBT £0.2m (24H1: loss £1.3m), Net Cash £0.7m (24H1: £0.6m) |
* Market caps at previous trading day’s close
Backlog:
Nexteq (LON:NXQ)
Flat at 80p - Interim Results - Mark - AMBER/RED
These results look pretty poor, with every metric apart from net cash down significantly:
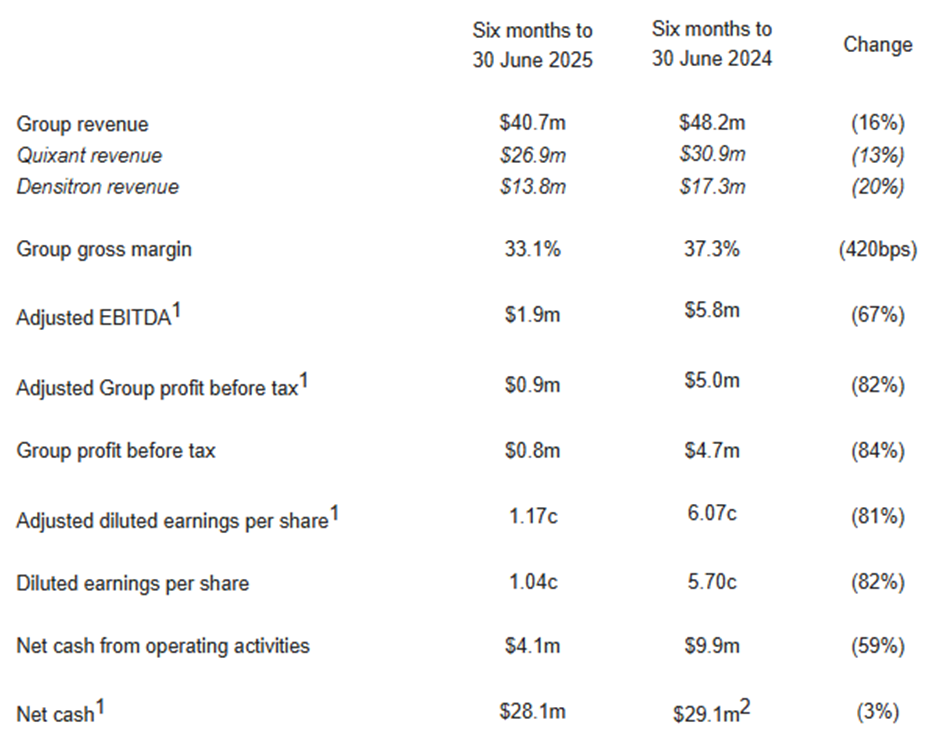
The segmental reporting shows that it is Quixant that has done the damage with operating profit there dropping 40%:
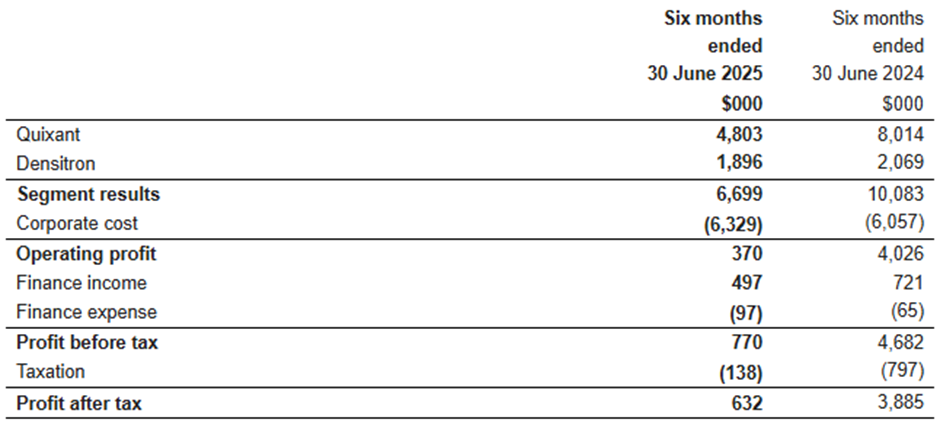
Densitron segmental profit only dropped 8% compared to the 20% drop in revenue. Given the scale of the central costs here, I think a lot of this may be subject to how these are allocated.
Cash flow has been good despite the weak results, with the cash balance only declining slightly despite a $3m dividend paid in the period, and an ongoing buyback. However, working capital moves have been the bulk of that:
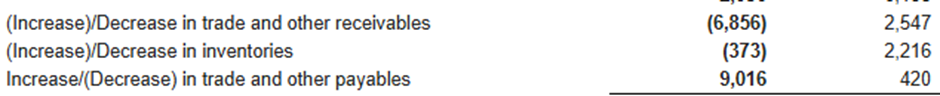
Looking at the balance sheet, this appears to be just a correction to previously unusually low payables, rather than a stretching of working capital:
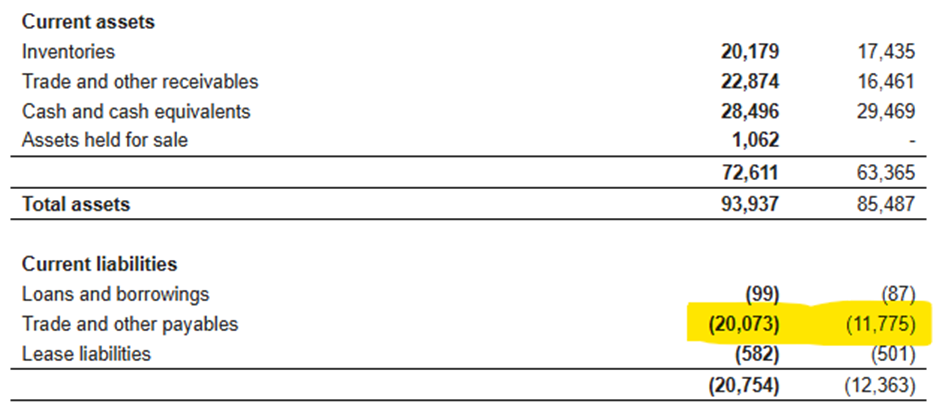
The current ratio suggests that this is still a strong balance sheet.
For the full year, they say:
Revenue and profit before tax for 2025 expected to be in line with expectations as set out in July trading update.
Their broker Cavendish have Revenue of $85.5m and Adj. PBT of $3.6m. This looks quite a stretch for H2, which would have to deliver $44.8m of revenue and $2.7m adj. PBT. With a gross margin in the 30’s they will need to either beat that revenue figure, have a significant improvement in gross margin and/or some cost-cutting to reach that bottom line improvement on H1.
Valuation:
Even if they hit these challenging EPS figure they are on almost 24x forward earnings which seems far too high for this type of business. However, there is the significant cash balance to adjust for. This works out to be 34.8p/share. However, 20% of their earnings are forecast to be net interest in 2025, so the cash adjusted FY25E EPS is 2.67p. This is a more reasonable, but not cheap 16.9x earnings. Cavendish are forecasting a modest recovery in 2026 followed by a much better 2027. 2027E EPS is 6.3p adjusting for interest, making the cash adjusted P/E 7. We really should take forecasts that far out with a pinch of salt, though. As a wise friend once said “every company looks like a buy on brokers forecasts two years out”!
At least the management are doing something with the cash, they say:
The Board remains committed to allocating capital towards diversification of the Group's revenues into new market sectors, consistent with its growth strategy…The Group's capital allocation policy remains unchanged, with a cash generative business model and strong balance sheet with good liquidity allowing it to invest in the business to drive organic growth and take advantage of acquisition opportunities.
And while they don’t have clear opportunities for acquisitions, there is an ongoing buyback. While management will no donut
Mark’s view
Those who believe that forecasts out to 2027 are realistic, or even that the company can return to the heights of 2023, will see this company as cheap. However, far forward broker forecasts typically tend to be far too optimistic, and in the meantime it looks like they have a lot to do in 25H2 to reach even the modest expectations for this year. We’ve not looked at this company on the DSMR for over a year; last time was when it warned and lost both CEO and CFO. The new management team appear to have steadied the ship, but with forecasts lower than after the first profits warning but the shares trading at the same price, and the risk of a third profits warning high, this has to remain AMBER/RED.
Roland’s Section:
Distribution Finance Capital Holdings (LON:DFCH)
Up 8% to 54p (£90m) - Half-year Report - Roland - GREEN
Full year profit expected to materially exceed current market guidance
This specialist lender’s core business is providing inventory financing to dealers and manufacturers in sectors such as caravans/motorhomes, boats and commercial transport. It’s recently also started moving into direct-to-consumer lending on these assets. Graham has been GREEN on this stock for some time now and recent share price performance has rewarded this confidence. Today’s half-year results show good growth in both lending and customer deposits and include a significant upgrade to 2025 expectations, with a more modest upgrade to FY26 as well.
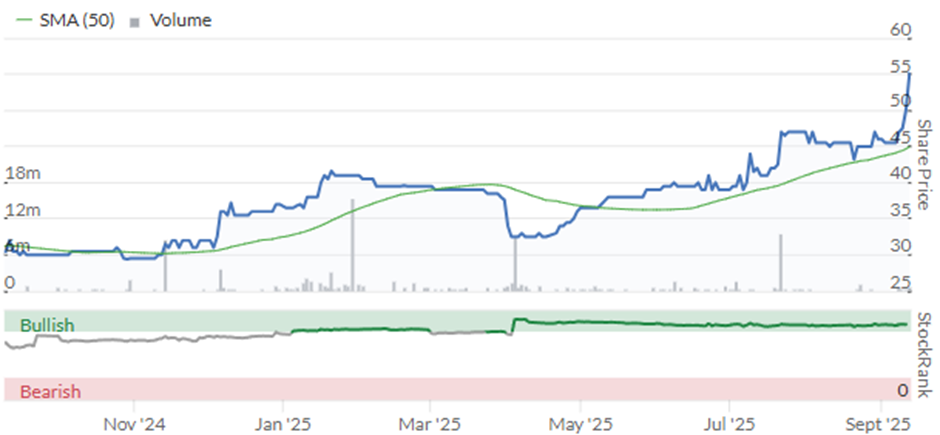
H1 results highlights
Today’s results show most numbers moving in the right direction:
New lending up c.17% to £828m to 1,491 dealers (H1 24: £710m, 1,250)
Loan book +21% YoY to £728m
Adjusted pre-tax profit up 20% to £9.0m
Net interest margin +0.1% to 7.9%
Cost-to-income ratio -1.5% to 57.3%
Return on equity +0.8% to 11.3%
The group has a UK banking licence and funds its lending from customer deposits collected under the DF Capital brand. While consumer interest rates edged lower, the company doesn’t seem to have had any problem attracting additional deposits to support increased lending:
Savings deposits +18.8% to £688m vs prior year
Average customer rate for retail deposits: 4.8% (Dec 24: 5.16%, June 24: 5.10%)
Trading commentary: the company’s largest lending market by value is leisure (Motorhomes & Caravans), where it provides inventory finance for manufacturers and dealers.
Demand for caravans is said to have softened, but motorhome demand remains strong, maintaining the double-digit growth rates seen in recent years. DFCH says it’s the market leader in this segment and has been taking share from competitors. The company is now leveraging this market share and distribution reach to expand into lending directly to consumers who are buying motorhomes/caravans.
Elsewhere in the consumer segment, demand for luxury cars and boats is also said to remain strong.
In the commercial segment, plant and machinery demand has shown good growth, supported by infrastructure spending and manufacturing modernisation. However, agriculture demand has been weaker, due to weather conditions and government policy uncertainty.
To further diversify its loan book, the company has recently entered the renewables sector and is starting to offer loans on solar panels and batteries.
Balance sheet: growth in lending and deposits is reflected in a 2% increase in net assets to £117.6m, compared to December 2024.
However, the company carried out a share buyback during H1, repurchasing 7% of its shares. This means the increase in tangible net assets per share during H1 was much greater, rising by 10% to 70.2p. This nicely demonstrates the value creation that’s possible when a lender or property business buys back shares below book value (assuming it has the surplus capital to do so, as DFCH has done).
The bank’s regulatory Common Equity Tier 1 ratio (CET1) fell to 19.7% during the half year (FY24: 21.6%), which I assume is at least partly due to the buyback. However, this is still a very comfortable and prudent level of coverage, well above regulatory requirements and higher than most other UK lenders.
Credit performance: the number of dealers in arrears remained unchanged at 2.5% during the half year. However, the percentage of the loan book in arrears did increase to 0.9%, from 0.6% at the end of 2024.
The company says this is due to a small number of larger dealers falling behind with repayments. To give a flavour of this, lending to the borrowers who are in arrears accounted for 1.8% of the loan book at the end of June, up from 1.2% at the end of 2024. There’s always a risk the situation will worsen, but I don’t see too much to worry about here. Bad debt levels look manageable and all of the company’s lending is secured.
In his interview with Graham in April, CEO Carl D’Ammassa explained that loans are made at a discount to wholesale value. This means that recovering the loan principal on repossession is not generally an issue. Today’s slide pack confirms this, suggesting lending is typically c.85% of wholesale value:
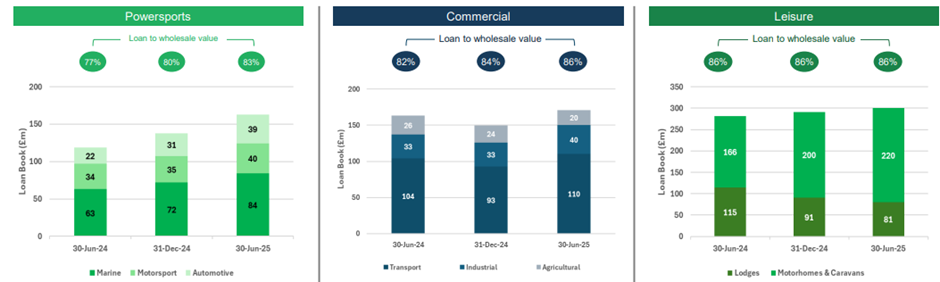
D’Ammassa said the main risk of serious losses is if dealers sell vehicles but don’t use the cash to repay the associated inventory loan. I am not sure how often that happens, but I’d imagine it’s a risk that’s closely monitored.
Profitability & Upgraded expectations
In early July, the company guided that full year results would be in line with expectations. So I’m interested to see what has changed over the summer. Looking at today’s outlook guidance, the expected size of the year-end loan book is unchanged, at £750-800m. What has changed is the expected profitability of this loan book. Lending margins are now expected to be significantly higher than previously thought, with net interest margin (NIM) guidance increased to c.7% over the medium term, from 6% previously. This is a big increase and is the main driver for today’s upgrade.
The feeling I get is that lending interest rates have remained quite firm, despite two recent cuts to the Bank of England base rate. Meanwhile, interest rates on retail savings have edged a little lower. This combination of factors demonstrates DF Capital’s pricing power and is supporting a pretty strong net interest margin.
Outlook & New Estimates
The company’s comment on profit expectations includes the word “materially”, suggesting an increase of at least 10% to FY25 forecasts:
As a result of our strong performance, particularly in net interest margin, we expect full year profit to materially exceed current market expectations with an improvement in market expectations for FY26 also anticipated.
Fortunately we have an updated broker note from Panmure Liberum today that includes revised earnings estimates and confirms this is a very significant upgrade:
FY25E EPS +25.4% to 7.7p (prev. 6.2p)
FY26E EPS +7.6% to 8.6p (prev. 7.9p)
These forecasts leave the stock trading on a FY25E P/E of 7, falling to a P/E of 6.3 for FY26. It’s also worth remembering the stock continues to trade at a >20% discount to its net asset value.
Roland’s view
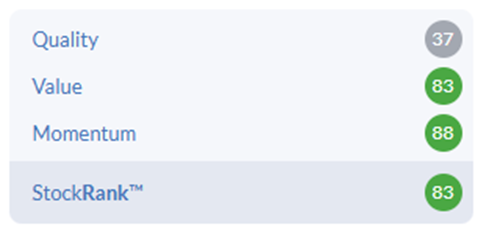
Today’s results look strong to me and suggest DF Capital’s is executing well in markets where it’s competitive and has scope for growth. I’m also encouraged by the improvement in profitability (return on equity), despite a slight increase in bad debt levels. If the company can reach its FY28 target of “mid-teens” ROE, then I think it would be fair to expect the stock to be trading in line with book value, or perhaps even at a small premium. In addition, I would guess that improving profitability should gradually lead to a higher quality score for the stock, complementing its strong value and momentum ranks:
Specialist lenders have the potential to generate attractive returns and strong growth, but as we’ve seen before in recent years they can also run into problems unexpectedly. I think DF Capital looks in good health, with strong growth prospects and a potentially attractive valuation, so I’m going to maintain our GREEN view today. However, I’ll echo Graham’s previous caveat that this is a stock I’d probably restrict to a relatively small position within a portfolio.
Trainline (LON:TRN)
Up 8% to 281p - Trading Statement - Roland - AMBER/GREEN
Robust first half performance, improved profitability guidance and announcement of an enhanced £150 million share buyback programme
Today’s half-year update from the rail ticketing specialist covers the six months to 31 August. They show strong growth in ticket sales (+8%) but rather more modest growth in total revenues (+2%):
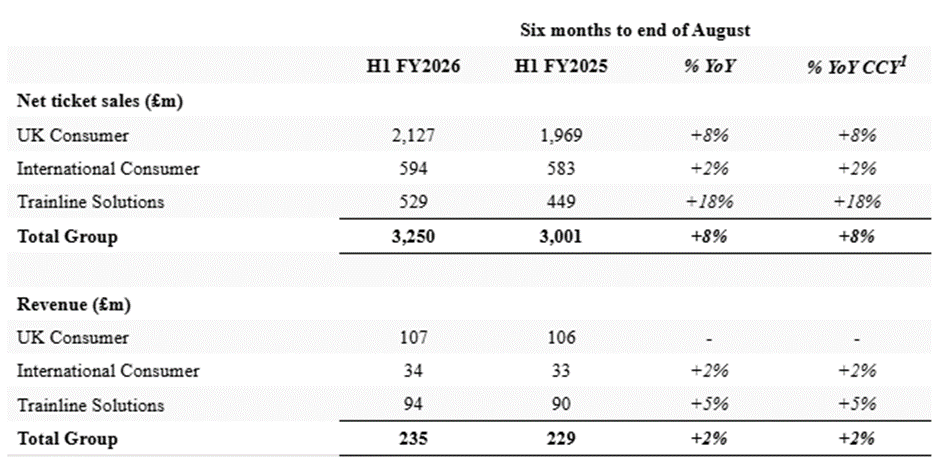
As the management commentary explains, this result is in line with expectations. Reduced revenue growth reflects the reduction in Trainline’s UK headline commission rate from 5% to 4.5%, which took effect in April 2025. Other adverse factors in the UK include the expansion of TfL’s own contactless payment network and a greater shift towards lower-revenue on-the-day travel.
Despite this, both the company’s revenue metrics are trending towards the upper end of management’s FY26 guidance:
Group net ticket sales +8% (guidance: 6%-9%)
Group revenue +2% (guidance: 0%-3%)
In International sales, Google changes and reduced demand from US tourists held back foreign travel sales. This seems to have offset growth in France relating to the expansion of Trenitalia services.
The strongest performing part of the business was actually the B2B Trainline Solutions division, where revenue rose by 5%. This unit supplies ticketing for travel management company clients, mainly for business travel. Ticket sales rose by 18% to £529m, with international B2B sales through the company’s API up by 55% in Europe.
Updated FY26 guidance:
Trainline expects H1 EBITDA growth to be above the full-year guidance range of 6%-9%. As a result, the company now expects full-year adjusted EBITDA growth to be at the top end of this 6%-9% range.
Share buyback:
Trainline has repurchased £71m of shares from its existing £75m buyback programme. When this is complete, the company now plans to launch a new £150m buyback. My sums suggest these buybacks should meet my rule-of-thumb target for an 8% pre-tax return, so I can’t really object, despite my preference for dividends in such situations.
Roland’s view
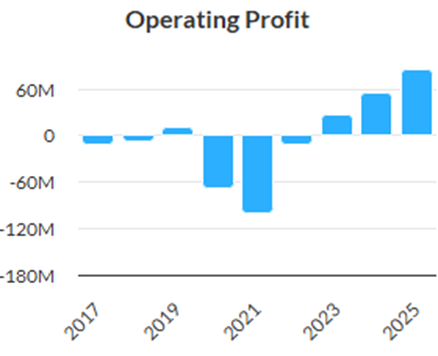
I have been something of a late convert to this stock. While I’ve always felt it was a useful business whose mastery of UK rail ticketing should be lucrative, historic low profitability and poor quality metrics discouraged me:
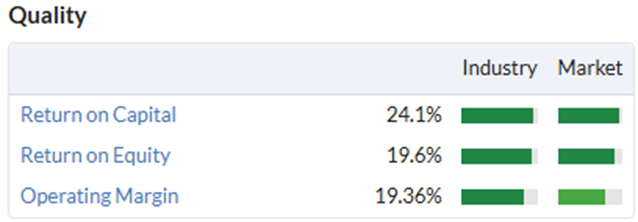
However, progress since the pandemic has been impressive. The group’s quality metrics are now showing the kind of values I would hope to see from a software business of this kind:
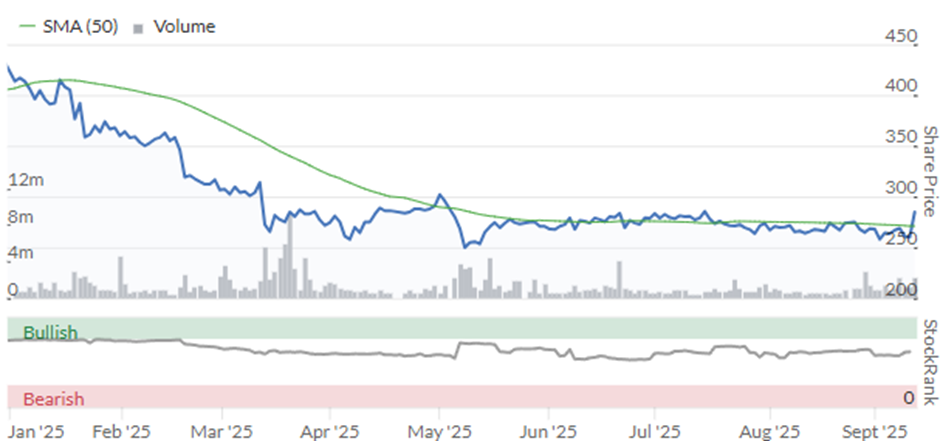
At the same time, the shares have fallen sharply this year despite unchanged forecasts for double-digit earnings growth:
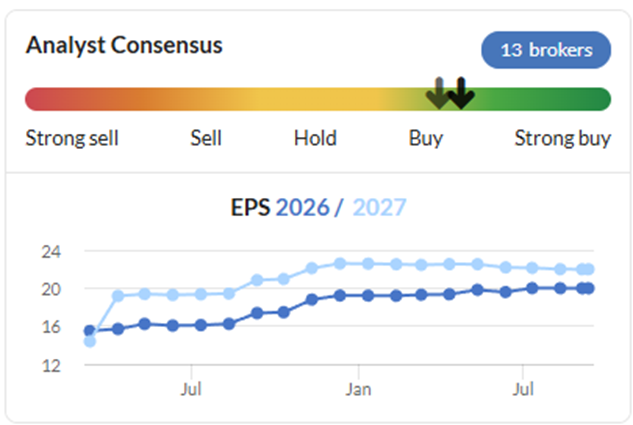
This has left the stock trading on a modest forecast P/E of around 14, with double-digit forecast earnings growth and the scope for further growth in the UK and Europe. This valuation seems very affordable to me – potentially cheap on a long-term view.
The main risk I can see is that regulatory or government intervention of some kind could end up throwing a spanner in the works in some way. We’ve already seen Trainline’s commission rate cut. Other possibilities might include changing ticketing systems, or restricting Trainline’s access to them. Personally, I think this would probably be short-sighted given the evident complexity of these systems. As Fire Juggler points out in the comments today, Trainline has been in business 25 years and has not attracted any serious UK competitors yet. Compare that, for example, to areas such as travel comparison sites, where there’s plenty of competition.
The level of political/regulatory exposure here means I’m reluctant to be fully positive. But I am happy to maintain Graham’s previous view of AMBER/GREEN.
Mark’s Section:
Brave Bison (LON:BBSN)
Up 15% to 75p - Acquisition & Trading Update / Interim Results - Mark - AMBER/GREEN
There’s a lot going on here so let’s start with the Interim Results. These look a little uninspiring:
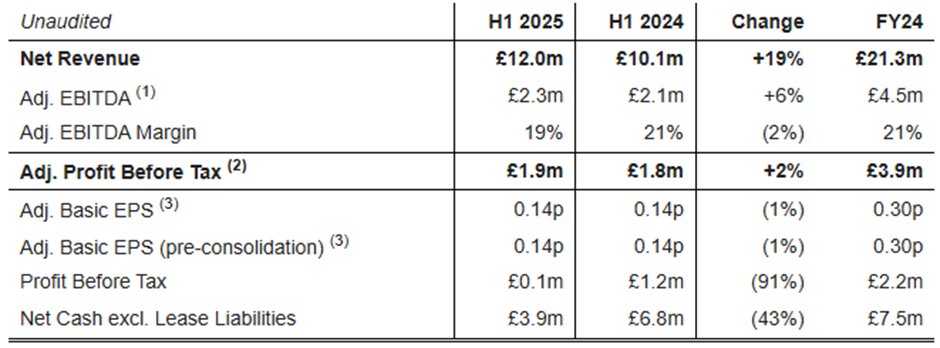
The revenue growth is largely a function of the large acquisitions they have made, although they say their existing business traded better than expected. They do say that:
Adj. EBITDA margin reduced from 21% to 19% year-on-year following the acquisitions of Engage Digital Partners and The Fifth, both of which were loss-making at the time of completion but are expected to contribute positively within 12 months
Which explains why revenue growth hasn’t positively impacted the bottom line. Indeed, they announce that they are trading ahead of expectations:
As a result of stronger than anticipated trading in the second half of 2025 and the acquisition of MTM announced separately today, the Board now expects the Group to exceed current market forecasts for FY25 and increases Board expectations for FY26
This half will now not just include the impact of Builtvisible and The Fifth, but the Mini-MBA acquisition that completed post-period. Today they also announce another acquisition, MTM London:
Initial cash consideration of £5 million and initial share consideration of £1 million. Further cash and share consideration of up to £6 million payable over 5 years and self-funding, subject to continuing employment and business performance. Total maximum consideration of £12 million.
This is said to be earnings enhancing:
Acquisition increases Brave Bison pro-forma adjusted EBITDA to £9.4 million and underlying pro-forma basic EPS by 13%, before cost savings from property and central overheads
However, like previous deals, there is an equity component, which means that the impact on EPS is a little more complicated. Plus they now have net debt, whereas, at the start of the year they had significant net cash:
Net debt at the end of FY25 expected to be £4-5 million, equivalent to 0.5x pro-forma EBITDA
Leverage of this level doesn’t look reckless, even for a people business, where the asset-backing is limited. However, it should adjust our valuation. Here, I turn to their broker, Cavendish to untangle the details. They upgrade their 2025F EPS by 7% and introduce a FY26 forecast. They now have Adj. EPS rising 9% from 6.05p in 2024 to 6.95p in FY25 and then a further 17% to 8.35p in 2026.
This makes them still look pretty cheap on a forward P/E of 10.8 and then around 9 the year after. However, I think some caution is required. Firstly, this sort of business should be cheaply valued. The second is the sheer scale of the adjustments:
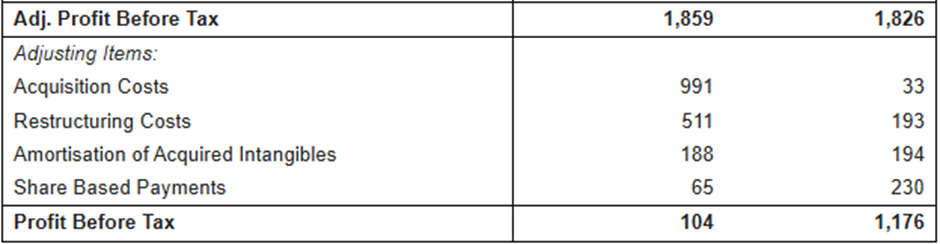
This is understandable in a period where they have made or integrated so many acquisitions, and it is normal to exclude these as one-off. However, you have to question how one-off acquisitions are for this business, given the sheer number completed. In my mind, companies can’t both claim the benefits of acquisitions and expect the market to value them on inorganic growth rates, yet exclude all the costs associated with these. I have previously commented on the Share-Based Payments charge. Management here take a below market salary and make up the difference through options. While this no doubt aligns their interests to wider shareholders, it means that the adjusted profits are flattered by the lower pay. The options are now well in the money as well, given the recent share price strength. At least SBP charge is lower in this half.
Overall, this means that the company trades much closer to what may be considered fair value, than an initial look at the forecasts may suggest. When I looked at this earlier in the year, on release of the FY Results, Cavendish said they found the valuation here “highly compelling given it trades on an FY1 adj P/E of just 8.1x versus peers on 9.3x, whilst retaining significant net cash and growing net revenues by 20% in FY25E.” Now that the company is trading above this level, Cavendish say:
Brave Bison looks highly compelling trading on a basic adj P/E of 7.8x versus peers on 15x.
In today’s note, they provide the list of peers to get to 15x. However, they didn’t seem to provide this list in the note that accompanied the Final Results. It may be that there has been a strong market rally in the marketing sector recently, or perhaps more likely, they have modified the list of peers!
What isn’t included in a simple look at the figures is the ability for the Green brothers to keep doing deals that add value to the business. The Momentum Rank is strong here, and likely to get a further boost when the algorithms process today’s small upgrade in EPS:
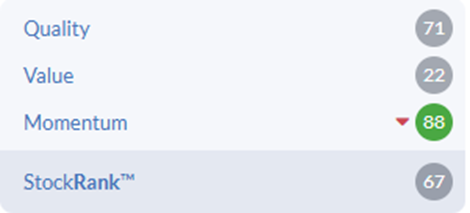
So it makes sense to keep holding while the Momentum remains. Longer term, the history of acquisition-led roll-ups in the marketing space is not good. Although, so far the Green brothers have avoided the debt and generous earn-outs that have proved the undoing of many similar endeavours.
Mark’s view
It’s not as cheap as it was, and questions remain over the valuation trade offs between options and salary, and acquisition-led growth vs acquisition costs. However, Momentum is behind the company in share price, EPS and deal-making. While that impetus is there, it makes sense to remain broadly positive. AMBER/GREEN
Fevertree Drinks (LON:FEVR)
Up 8% to 844p - Interim Results - Mark - AMBER/RED
It is a rather lacklustre half from this former growth stock:
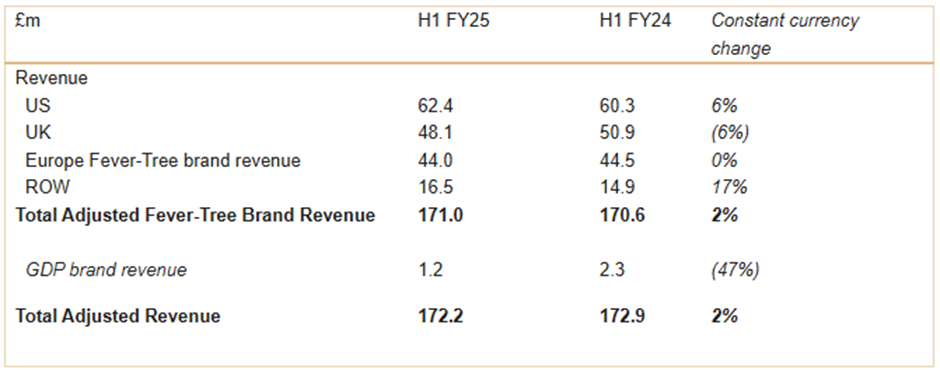
Pretty much all the numbers are flat, although not helped by currency headwinds.
Cash is up, but this largely due to the sale fo the US business in return for a cash consideration and license fee:
QUOTE
As part of the long-term strategic partnership, Molson Coors acquired an 8.5% stake in Fevertree Drinks plc (post-issue) for consideration of £71.0 million. To assist with the transition of operations, Molson Coors acquired the local trading entity Fevertree USA Inc for consideration of $23.9 million in cash.
END QUOTE
Geographically it is the UK business that is struggling. The Rest of World is growing well, although off a lower base:
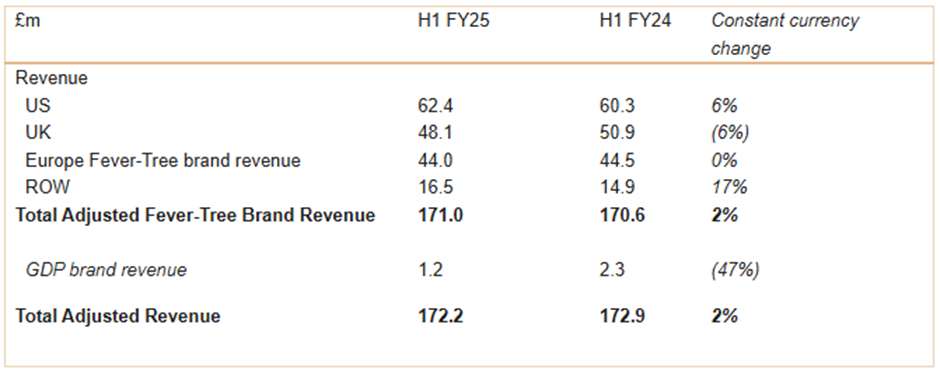
The company seems happy with these figures saying:
The Group has made a good start to the second half of the year across our regions and we remain comfortable with full year market expectations.
However, in line hardly looks challenging, with forecast being for modest revenue growth and declining EPS:
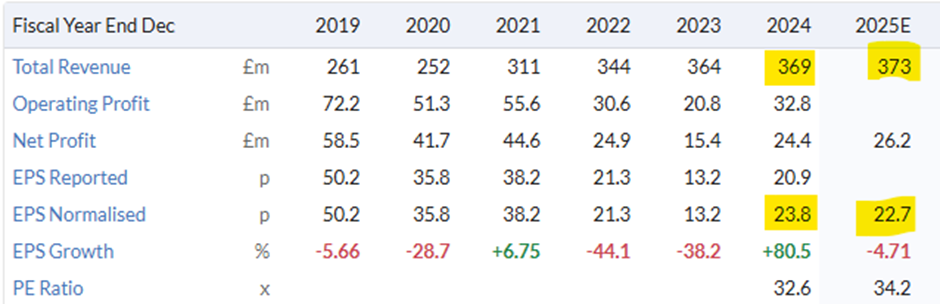
This makes the valuation metrics here look a little bonkers:
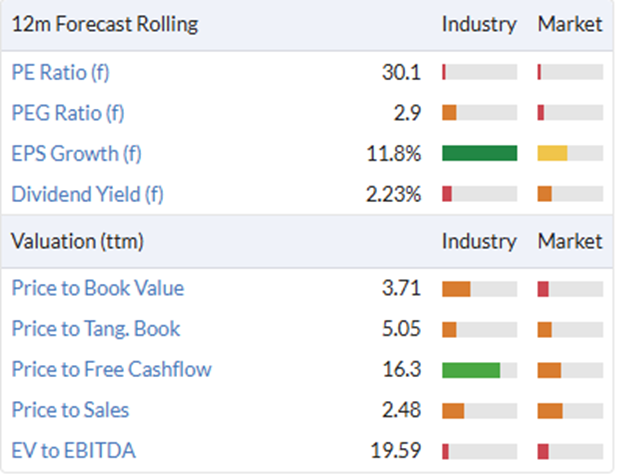
No doubt the bull case is that the brand recognition and Molson Coors deal mean that growth is expected outside the forecast window. However, if they have been unable to deliver this so far, I don’t see why this should now drastically change. Others will take heart that CM have put money into the equity here. However, in my experience large corporates are equally likely to fall for narratives or focus on past glories as investors.
Mark’s view
We were neutral on this when we last reviewed it. However, the continued lack of top line growth for a company on this type of valuation has to be a major worry. Some will point to weak consumer sentiment and the transition of the US business to a royalty one. However, I think it is equally likely that the premiumisation trend in mixers has peaked, and any growth from here will have to be driven by expensive marketing campaigns or event sponsorship, rather than a growth in underlying consumer demand. It’s an AMBER/RED for me on pure valuation/lack of growth concerns.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
THG (LON:THG) from 600p to 30p - good job London Stockmarket.
?
Fevertree Drinks (LON:FEVR)
I used to be a big Fevetree fan back in the day - luckily for me i exited the building when the share commanded a super preimium price and hadnt gone into the later freefall.
I still like the company and believe it will do fine and Dandy long term.
Mark's article comments seem to be someone one sided.
UK is a mature market and they are the main player - so we cant expect growth here.
They are doing newer lines though that are not their main "tonics" - i would agree they dont really seem to be amounting to much .
Overall ref uk is probably a fair cop.
Ref US though i think there is still plenty for this to run - growth this period isnt great - but has likely been clouded by the Molston deal and integration - sales are still up 6% - but i think more is to come.
Ref ROW growth still seems decent - and the world is a big place. To me the main attraction with Fevertree is thatb they can become a true worldwide brand. or at least decnt % of the plant perhaps.
So imho they are now thbe Coca Cola of Tonics and that should deserve a premium.
Ref current woes jamesalastair has summed up the margin woes very nicely - i dont expect a return to teh glory days ref margins - but i think there is deffo scope for improvement once expansion overseas slows.
Ref the US Molsons deal - i dont know how this works - do we have a handle on how much profit they expect from the US next year ? so not sure if they or Moslon have gotten the better part of the deal. Can molsons pass ones costs and still keep 50% - would i trust big boy not to pimp the costs ? hmmmm
Overall i feel like this company easily has the potential to get back to 40-50 mil net profit "cashflow machine" put a 25 * multiple on that and you are decently above the current price.
At present though the company is a fair way off that and even thnen then upside isnt huge - unless they can keep upping the sales and get margin growth back. sales trend is increasing so its not a busted flush imho.
At present though i dont see enough to tempt me back in.
Facts are that the profits are currently still well below 40-50 mill level - non core sales items dont seem to be doing much - so if return to higher profits aint quick i can see then share doing not alot.
I am slightly surprised it hasnt been fully snapped up by one of teh big boys yet - so perhaps the easiest way out for Management is to sell to Molsons as jamesalastair has similarly said.
The fact i havent been tempted back probably sums it up right now - its just not really a compellling buy without havig some faith beyond the current financials being delivered. When many companies are trading at less than 10 X and are reasonably cound - do we want to be paying 25 * curent numbers for some future hope?
Roll on the 1300p bid tomorrow morning :)
B&M European Value Retail SA (LON:BME)
Well you can't accuse the new CEO, Tjeerd Jegen of not backing himself. He bought a further 79,500 shares at 249p on the 9 September, spending close to £200,000.
That adds to the £265,000 his spent on the 3 September buying over 113,000 shares at 234p and the £523,000 purchase of 198,000 shares at 264p on 13 June.
In ball park terms that is close to £1 million for around 391,000 shares.
Mr Jegen is a seasoned operator in retail discount and it is extremely difficult not to interpret his purchases as an indication that the share price does not reflect the performance of the business. Trading update due next month.
I have been adding recently.
Fevertree Drinks (LON:FEVR) Given Mark’ s very negative analysis and today’s 10.5% share price jump (!) perhaps now is the time to jump ship. Alternatively does the market know something Mark has missed? Fevertree Drinks (LON:FEVR) has a very strong brand image in the mixers market. Even so I accept valuation and top line growth are very poor. Perhaps the market is hoping for a full acquisition by Molson Coors Beverage Co (NYQ:TAP) or another player who wants to add a strong brand to its product range . Probably like any other long term holders we live in hope!!
The Fevertree Drinks (LON:FEVR) thesis is, in my view, compelling.
Fevertree's gross margins and ROCE took a hit as its US business expanded as the product was made in the UK and shipped to the US. Then Covid hit and freight rates increased exponentially. In addition, Fevertree got a double hit as the airport and travel market was decimated (half of all mixers are sold in hotels, airports and on aircraft).
The numbers look awful:
In 2019 pre-Covid, Fevertree enjoyed margins of 27.7% and ROCE of 31.8%. This has dropped to margins of 8.9% and ROCE of 12.6%.
The share price responded by falling 75% ... the ultimate fallen angel, and we all lost interest.
Margins remained subdued post Covid, as freight costs remained elevated. Most of the margin destruction can be explained by increased freight costs to the US and the situation worsened ironically as US sales grow. The higher the US sales and the worse was the gross margin mix.
The Molson deal is important. The US market is 4 x the size of the UK market and already represents 35% of group sales. As part of the agreement, Molson Coors will:
• Take over the Fever-Tree drinks production in the US, thus rendering Trump's tariffs a non-issue.
• Distribute Fevertree's product range to its existing relationships with 500,000 retailers and 400 distributors. The Molson distribution network is orders of magnitude larger than Fevertree's existing US distribution arrangements.
• Invest in marketing the brand in the US market.
• The production capital and capacity and working capital in the US market will be provided by Molson.
I believe margins will not only recover as a result of the product being manufactured in the US by Molson, but also Fevertree's working capital requirements, marketing and distribution costs will decrease substantially. Some analysts have bemoaned the fact that Fevertree will have to share US profits 50% with Molson but I do not think they understand the size of the opportunity here. I even know of one fund manager who sold out of his Fevertree position as a direct result of this deal.
As part of the partnership, Molson Coors invested GBP 73m of fresh equity into Fevertree Drinks, giving the US firm a 8.5% equity stake.
How big is this opportunity? I calculate that if US sales targets are met and if margins recover to 34%, the 2028 PE falls to 5.3 excluding cash. I believe the opportunity is substantial and one of the most exciting opportunities on the UK market.
JamesA nicely put case for Fevertree Drinks (LON:FEVR) and perhaps more in line with the jump today than other commentators. Sharing your view that Molson taking on production could be key to making money in the US but not sure about the recovery in margin to 34% if Molson take half the profits. If they were purely a Contract Packer I'd be more comfortable with that but this looks like a proper partnership. Not sure where that leaves the margin. Somewhere round 20/25%? Still a significant uplift from where they are now. And transporting drinks across the pond was never a good idea.
US revenues are consolidated by FeverTree and a minority charge is applied to account for the 50% profit share of the US business of Molson Coors. Fever Tree has guided that they will present pro-forma consolidated business figures for like for-like comparison, although under UK accounting rules the US business will be consolidated by Molson Coors and Fever Tree economics realised through a royalty revenue entry and profit share associate entry.
Ultimately, I suspect Fevertree will be bought by Molson.
US CPI data a little high...a small surprise ID say, but not enough to get too stressed over but obviously not what the rate cutters were looking for. Not much reaction from markets yet.....
M P Evans (LON:MPE) has a StockRank of 99 and recent broker upgrades yet continues to fall, presumably on consumer sentiment fears. Interims soon Maybe scope for a bounce? I hold.
Several of my AIM shares have been drifting down, including M P Evans (LON:MPE) (I hold). Are the smart investors anticipating the Chancellor coming for the other half of business property relief in the budget and getting their sales in early? Specific to M P Evans (LON:MPE) , there is unrest in Indonesia. Or maybe just profit taking after a decent run.
Trainline (LON:TRN) seem to be shrugging off the supposed threat from Great British Rail ticketing including Northern tap and go (I hold) . £350M share buyback in 3 years...
In my experience the only developers who could build a credible ticketing app are....wait for it---the trainline team. It's taken them 25 years to get to this position. A better 'British' app will appear (as my kids say) when dogs learn to scuba dive / or when GTA 6 launches...
There is just no magic pool of developers twiddling their thumbs waiting for a green light to sort out millions of ticket combinations at The Dept of Transport...just as there are not thousands of spare bricklayers anxiously waiting to build 1.5M homes even if planning comes through.
Besides --Europe (remember that place?) beckons...Canny strategy.
No, but....
There are already millions of combinations being dealt with in the South East where pay-as-you-go with your contactless card now spreads well beyond the tube network and TFL across multiple rail companies.
You have the likes of Thameslink and Southeastern involved and you wonder how long it will be till they roll out contactless across their entire networks.
Of course that doesn't deal with advance fares etc, but that wouldn't be impossible. So potential alternatives that could form the foundation of a competitor to Trainline do already exist.
AI Agents is the disruptor for Trainline (LON:TRN) viability going forwards.
Now, with an AI Agent. You could ask the AI to go and buy tickets for you. Just supply the dates and times, types of tickets, etc. And off it goes onto the Train Operator website. Navigating their clunky UI. And voila! Tickets in your email.
Same ticket. Same price (maybe even cheaper!). And even less effort/time spent.
I never found Trainline any better than my train company. I would not trust AI to book tickets, Trainline are more expensive.
What about Uber?
Also the idea that the British government of any colour could actually pull off a tech product better than one made by the private sector seems incredibly unlikely. Unless they are allowed to use their monopoly power once they nationalise the service again.
re. Mark's comments on Nexteq (LON:NXQ). I read somewhere that broker's forecasts are usually about 50% accurate for 1yr forecasts & 20% for 2yr forecasts ! Worth taking broker's forecasts with a pinch of salt.
Mark,
I know Distribution Finance Capital Holdings (LON:DFCH) is a very small outfit but could you cover this today please
Steve
Hi Threepeat,
Yes, Roland is on it as we speak/write!
Distribution Finance Capital Holdings (LON:DFCH) another good candidate for Ed's 'The Setup', with earnings 'materially ahead' of expectations, Stock Rank 83, and up 10% today..... I don't hold, but am almost willing it to avoid the ever-so-common mid-day sell off and sink back to +1.5%....
me too!
Will there be any comments today on Petrofac (LON:PFC) ? I hold as a Loss Leader :-(
Distribution Finance Capital Holdings (LON:DFCH) . Results headline Full year profit expected to materially exceed current market guidance....Say no more....
Distribution Finance Capital Holdings (LON:DFCH) Another nice, neat, noteworthy, Neary knockout! It’s been a GREEN for a while. Well done our Graham!
Brave Bison (LON:BBSN) another acquisition.
Results wise, HY EBITDA up (though margin down), stat profits hit with exceptional acquisition, reststructuring and integration costs. They have made 4 purchases recently (inc the "transformational" purchase of MiniMBA from Centaur). A fifth is announced today.
Outlook is now ahead of Cavendish's expectations for ROY FY24 and FY25. There's a new note on Research Tree. New TP of 150p , was 120p (now 64.75p pre-opening), hope it'ok to paste:
In light of strong trading and the MTM deal, our maiden FY26E represent a 23% uplift to FY25Epf net revenues and 13% uplift to FY25Epf basic adj EPS. We forecast FY26E net revenue of £44.8m (+42% YoY), £9.4m adj. EBITDA (+54% YoY), 8.35p basic adj EPS (20% YoY), and a swing back to net cash of £0.1m with the debt facility almost entirely repaid. These estimates assume no synergies from MTM, leaving scope for further upside following property lease termination and backoffice savings.
Valuation: Brave Bison looks highly compelling trading on a basic adj P/E of 7.8x versus peers on 15x. This is despite FY26E revenue growth CAGR of 45%, versus peers on 4%. We have raised our 12month price target to 150p based on Brave Bison trading in-line the average FY1 peer P/E multiple of 18x, giving over 100% upside.
Thoughts from the team and other readers appreciated! My own view - the Green Bros seems to be on to something, and appear to be delivering. It's early days. Profitable, growing, shareholder alligned/friendly, good balance sheet (net cash becomes small net debt but f/c back to net cash soon), small but hopefully growing dividend. They also seems to be making a habit of announcing "aheads" - good expectation management + under promise, over deliver mindset.