Daily Stock Market Report (Thur 13 Feb 2025) - THRU, TRI, GATC, BATS, RSW, CNC, ONDO, APN, ULVR, AVG

Good morning - today's updates are thankfully more exciting than yesterday's!
1.30pm: we're out of time, thanks for dropping in!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Unilever (LON:ULVR) (£117bn) | Final Results | 2025 outlook: sales growth 3%-5%. Subdued growth in near term, to improve during the year. | AMBER/GREEN (Graham) |
Relx (LON:REL) (£76.4bn) | FY24 Results | 2025 outlook: another year of strong underlying growth in revenue and adj. operating profit. | |
British American Tobacco (LON:BATS) (£74.7bn) | Final Results | 2025: regulatory, fiscal headwinds. Committed to 3-5% rev growth, 4-6% adj. profit growth in 2026. | AMBER/GREEN (Graham - I hold) A large shock in terms of the Canadian class action lawsuit, and competitive pressures. But it still offers amazing cash generation despite its various problems. |
| Barclays (LON:BARC) (£44.3bn) | Final Results | 2025 guidance: RoTE c. 11%, progressive capital returns, £0.5bn efficiency savings, CET1 13-14%. | |
South32 (LON:S32) (£7.8bn) | HY Report | FY25 production guidance unchanged, except for aluminium in Mozambique (civil unrest) | |
Tate & Lyle (LON:TATE) (£2.8bn) | TU | Mild profit warning: rev mid single digit % lower, EBITDA growth at low end of 4%-7%. | |
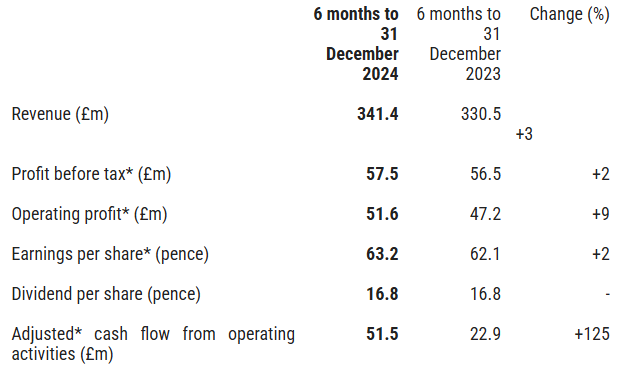
Renishaw (LON:RSW) (£2.6bn) | HY Report | Rev +3%, EPS +2%, dividend flat. FY rev exp. £695-735m, Adj. PBT £105-135m. | AMBER/RED (Mark) |
Applied Nutrition (LON:APN) (£372m) | TU | Rev £47.6m ahead of £46m IPO guidance. EBITDA margin in line. | AMBER/RED (Graham) We have a new sports nutrition stock to look at and today's update is positive, beating revenue expectations set out at the IPO. At this early stage in its life as a listed company, I maintain scepticism. |
| Concurrent Technologies (LON:CNC) (£163m) | Commencement of trading on OTCQX | Trading under the ticker COTGF in the US. Will continue to trade on AIM too. | AMBER (Graham) I like dual-listings and a combined AIM/OTCQX listing for CNC strikes me as a positive step. This ambitious company is enjoying very strong share price momentum, and it has strong business momentum to help back this up. |
Avingtrans (LON:AVG) (£119m) | Contract Win | Booth Industries £4.5m contract win. | AMBER (Mark) |
Trifast (LON:TRI) (£104m) | TU | Expectations unchanged. |
AMBER (Mark) |
Ondo InsurTech (LON:ONDO) (£48m) | TU | Rev +70% to £4.5-5m. EBITDA +ve in FY26H2. | AMBER (MARK) |
Gattaca (LON:GATC) (£22m) | TU | In Line. NFI down 3% to £18.8m. Adj PBT £3m. Net Cash £16.7m. |
GREEN (Mark - I hold) |
Thruvision (LON:THRU) (£8m) | TU & Strategic Update | PW. £5 to £6 m vs prev. guidance of £9 m | RED (Mark) [no section below] |
Graham's Section
British American Tobacco (LON:BATS)
Down 7% to £31.40 (£69.4bn) - Final Results - Graham - AMBER/GREEN
At the time of publication, Graham has a long position in BATS.
The market dislikes these results, let’s try to break them down.
Revenues
Revenue fell 5.2%, “driven by the sale of our businesses in Russia and Belarus in September 2023 and translational FX headwinds”.
Reported revenue of £25.9bn for 2024 is less than the consensus forecast £26.1bn.
Organic revenue growth is 1.3% at constant exchange rates - this is the growth rate I always find to be the most meaningful.
Within this, “New Categories” revenue is up 8.9%.
The traditional “Combustibles” category isn’t really growing but is stable at +0.1%. Lower volumes but higher prices and a more expensive mix of products sold.
Profits
Reported operating profit £2.7bn includes a £6.2bn provision relating to Canada. This seems to have spooked the market the most today - there has been a class action lawsuit going on in Canada for many years, and it is reaching its conclusion.
Adjusted operating profit is much higher than the reported figure, at £11.9bn.
Let’s try to understand the discrepancy between these two numbers a little more.
I’ve found that the PDF for these results is much easier to navigate than the RNS; using the “data lake” at the end of the document I get the following breakdown of adjustments to the profit figure. Here they are ordered by size.
Ongoing litigation in Canada £6.2bn
Amortisation and impairment £2.3bn
Excise assessment in Romania £0.4bn
…. Plus some smaller items.
So apart from the Canadian litigation, and amortisation/impairment, there isn't much else of note.
However, this is the second year in a row when the company has had very large profit adjustments.
In 2023, there was a £23bn charge after it wrote down the value of its US brands.
So if investors want to think of BATS as a company with unclean accounts, I can’t argue against them. However, I still think it’s possible we can get clean accounts again soon.
Balance sheet
With intangible assets on the balance sheet being responsible for the enormous impairment charge in 2023, let’s check the latest state of play for the balance sheet in general.
Total equity: £50bn.
Intangibles: £94bn.
Tangible equity: minus £44bn.
The intangible assets are the largest item by far.
Next up we have borrowings: nearly £33bn of non-current borrowings (these are due in more than one year), plus £4bn of current borrowings.
Net debt (borrowings minus cash) is £31.3bn, down from £34bn a year ago - a nice reduction. Free cash flow was £7.9bn, which enabled the payment of nearly £3bn of dividends and the simultaneous reduction of net debt.
The leverage multiple (net debt to adjusted EBITDA) is 2.75x after taking into account the expected loss of cash in Canada, or 2.44x otherwise.
The company therefore argues that it has reached its target leverage multiple of 2.0-2.5x, but I think the 2.75x number is the correct one and so in my view they do need to keep working on debt reduction.
BATS still has its investment-grade credit ratings, e.g. BBB+ (with a stable outlook) at S&P.
CEO comments with a few snippets on the outlook. Unfortunately it will take another year before the company achieves its medium-term growth guidance:
"We are committed to Building a Smokeless World and becoming a predominantly Smokeless business by 2035…
2024 was an investment year with delivery in line with our guidance…
In 2025, while we expect significant regulatory and fiscal headwinds in Bangladesh and Australia to impact our combustibles performance, I am confident that we will progressively build on our delivery as we shift from investment to deployment and we remain committed to returning to our mid-term guidance of 3-5% revenue and 4-6% adjusted profit from operations* growth on a constant currency in 2026."
Graham’s view
I’ve been holding this one for a long time. I generally don’t invest for income and many of my shares pay no dividend at all, so it has been good to have at least one or two regular payers in the portfolio.
Peak pessimism was reached a year ago:
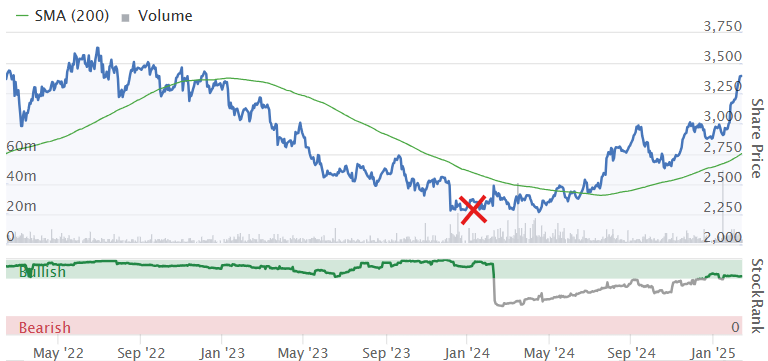
The word “illicit” is used 19 times in today’s results statement, as single-use vapour products remain a big problem for BATS, particularly in the US. Market share of the legal market has fallen but is still huge at 50.2%.
Internationally, vapour market share is 40% in what BATS refers to as the “Top Vapour markets”.
Another problem is that with pressure on consumer spending, there has been a rise in the “deep discounted category” in the US when it comes to cigarettes.
So there is no question at all that BATS is challenged. Not just in terms of regulations and lawsuits but also in terms of competition - from both regulated and unregulated competitors.
But against that, its financial performance remains spectacularly strong, when you look at the raw cash that it continues to generate.
And in the smokeless categories, it does have leadership in next generation products including vapes.
While I admit that I am biased by my status as a long-term shareholder, I think it’s worth having a moderately positive stance on this share, at this valuation:

I think real after-tax profitability is running at c. £8bn - this is in line with free cash flow and does accept the company’s version of adjusted profitability.
The enterprise value is c. £100bn, when we add £31bn of net debt to a £69bn market cap.
So adjusting for debt, the PER is about 12x, with an earnings yield of 8%.
That seems moderately attractive to me. There is just enough growth in new categories to offset the weakness in cigarettes and paint a picture of (very modest) underlying growth. Ethical concerns aside, I think this one adds up to an interesting proposition.
Concurrent Technologies (LON:CNC)
Up 3% to 196p (£168m) - Commencement of trading on OTCQQ - Graham - AMBER
CNC is now dual-listed on AIM in London and the OTCQX in the United States.
OTCQX is an “over-the-counter” marketplace, rather than a traditional exchange such as the NYSE.
It’s comparable to AIM in the sense that it’s driven by market makers.
And similarly in terms of market cap: it contains some companies worth more than $1 billion, but the vast majority are micro-caps.
The company says that this dual listing will help in terms of engaging with US investors/media and will help US-based employees to trade the shares.
The CEO says:
"We believe that having Concurrent's shares trade on both the AIM and OTCQX markets will enhance visibility of the business and expand our global reach. This decision follows an already increased level of interest from U.S. investors, driven by the excellent progress the Company is making across the Systems unit in the U.S."
Graham’s view
I like dual-listings because (in theory) they should help with market efficiency. When more investors are looking at a stock, it should be priced more accurately. It also gives me confidence that the company isn't hiding from exposure to the investing community in a country that it operates in.
From a UK perspective, the valuations given to some US-based tech stocks might seem excessive - of course I have a lot of sympathy with that view. And perhaps with US-based investors now able to trade CNC on their home turf, it will see an increase in valuation, compared to what it might have achieved otherwise..
I don’t see that as a bad thing - if it starts to look overheated, there is always the option for UK-based investors to sell. And any mismatch between the US and UK valuations should be mopped up by arbitrageurs.
CNC shares have been on a fantastic uptrend and made it into Ed’s November review of “The Top 20 clearest trending small caps”.
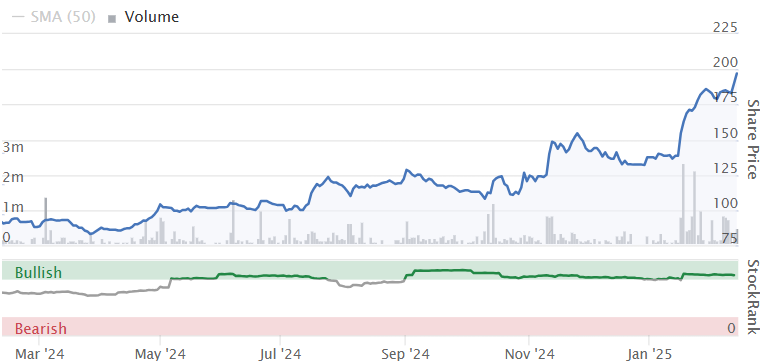
The company has not been shy about posting RNS announcements re: contract wins and other achievements. It is a “designer and manufacturer of leading-edge computer products, systems and mission critical solutions used in high-performance markets by some of the world's major OEMs”.
Serving a wide range of industries, but particularly defence and aerospace, CNC makes single-board computers and related systems and products that can survive harsh environments.
The recent trading update (Jan 16th) revealed that FY24 revenue would be up 25% vs. FY23, and 10% better than market expectations, which were £36m.
PBT would also be 10% better than market expectations, which were £4.7m.
My general impression of CNC is positive but I don’t have enough knowledge about the company to take a strong stance on it. It is expensive in P/E terms but for an ambitious and growing company that is turning a corner in terms of profitability, this might be a fair price to pay.
Applied Nutrition (LON:APN)
Unch. at 148.8p (£372m) - H1 FY25 Trading Update - Graham - AMBER/RED
Applied Nutrition plc, a leading sports nutrition, health and wellness brand, today announces an update on trading for the six months ended 31 January 2025 ("H1 FY25").
This one listed in November and has not been commented on before.
It offers ranges of protein, whey, creatine, etc., under the banners “Applied Nutrition”, “All Black Everything (ABE)”, “Bodyfuel” and “Endurance”.
In theory these could be valuable brands, but after monitoring SIS (NSI:SIS) and its lack of profits for a long time, I’m instinctively wary.
Today’s update from APN says that its revenue is “comfortably ahead of IPO guidance”. Good news but of course a company can easily tee itself up to beat expectations for its first trading update. So I wouldn’t read too much into this.
The Group has made good progress in the first half of the financial year, delivering revenue of £47.6 million, comfortably ahead of guidance provided at the time of the IPO of £46 million, representing a strong underpin for the full year guidance of £100 million. The Group continues to achieve a robust Adjusted EBITDA margin and cash conversion, both in line with market expectations.
Fans of I’m a Celebrity may be interested to know that Coleen Rooney wellness supplements have been added to the Applied Nutrition range. TV ads have been running.
Another tie-up involves a Vimto Isotonic Energy Gel (Vimto being the flagship product at Nichols (LON:NICL)).
A manufacturing extension will allow for future revenues of up to £160m, vs. £100m expected in the current financial year FY July 2025.
CEO comment:
Our successful IPO in October has had the positive impact we hoped for on the profile of Applied Nutrition and our industry recognition. I am pleased to report we have made strong progress in the first half, delivering performance ahead of our IPO guidance. Our growing global customer base highlights our appeal to a wide range of consumers, from everyday health-conscious individuals to professional athletes who rely on trusted sports nutrition products to fuel their performance…
Graham’s view
Experience teaches me to give IPOs a health warning. There is often a problem or a risk that hasn’t been revealed yet. My IPO rule is to assume it's overvalued for at least two years or until there is at least a 50% discount against the IPO price.
Perhaps this is one of the companies that breaks the rule. But Stockopedia isn’t seeing any value yet:
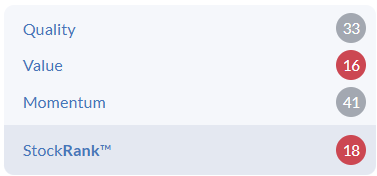
Hopefully they get to £160m of revenues before too long, and prove my scepticism ill-founded.
However, on the basis of the high valuation and the fact that it’s a recent issue, and also my experience with SIS (NSI:SIS), I’m taking a moderately negative stance on this one for now.
Unilever (LON:ULVR)
Down 6% to £44.64 (£110.6bn / €133bn) - Final Results - Graham - AMBER/GREEN
(At the time of publication, I have an indirect interest in ULVR.)
The market has taken a dislike to Q4 underlying sales growth at Unilever of 4.0%, marginally below consensus of 4.1% and dragging on the full-year result (4.2%).
There are contributions from both price and volume, with underlying volume up 2.9%.
Reported turnover for the year was €60.8bn, up 1.9% vs. 2023. The reasons for this lower growth rate (compared to underlying sales growth of 4.2%) are FX headwinds and business disposals.
Ice Cream was responsible for €8.3bn of revenue - it’s the most interesting segment right now because it’s being separated from the rest of the group.
We get an update on this. The former CEO of Heineken, who is currently Chair of Vodafone, Jean-Francois van Boxmeer, will be the Chair of the ice cream company:
The separation of Ice Cream is on track to complete by the end of 2025…
Ice Cream will be separated by way of demerger, through listing of the business in Amsterdam, London and New York, the same three exchanges on which Unilever PLC shares are currently traded. The Ice Cream business will be incorporated in the Netherlands and will continue to be headquartered in Amsterdam.
Amsterdam will be the primary listing, and UK business minister Jonathan Reynolds is quoted as telling reporters in relation to this, that Britain needs to do more to attract listings.
Capital allocation: €5.8 billion was returned to shareholders in 2024 via dividends and buybacks. With a €1.5bn buyback completed, the company announces a new one of the same size.
Net debt: €24.5bn, with a leverage multiple of 1.9x. This should be manageable without great difficulty. The company is only paying net finance costs of about 3% on this, although this is increasing as low-cost debt matures and is replaced by higher-cost debt.
Outlook: this has also hurt sentiment today. I think these bits are worth quoting in full:
We expect underlying sales growth (USG) for full year 2025 to be within our multi-year range of 3% to 5%. Market growth slowed throughout 2024. We anticipate a slower start to 2025 with subdued market growth in the near term. We expect the market and our growth to improve during the year as price increases, reflecting higher commodity costs in 2025. We expect a more balanced split between volume and price.
We anticipate a modest improvement in underlying operating margin for the full year versus 18.4% in 2024. We expect this improvement to be realised in the second half given the very strong first half comparator of 19.6%, which benefitted strongly from the combination of carry-over pricing and input cost deflation.
Graham’s view
When I look at enormous companies like this, I think it’s mostly about taking a view on whether this is the type of stock I want to own, rather than trying to come up with a prediction about its performance.
For me, this is the highest-quality large stock in the UK (vs. the likes of AstraZeneca, Shell, HSBC and Rio Tinto).
This is due to the terrific quality of its brands and its reliability of performance.
I see it as offering lower risk than the average stock, higher quality than the average, and I’m willing to pay for this sort of profile.
It gets a very high StockRank because the computers look at it and come to a similar conclusion as I do: that it’s probably worth this price.
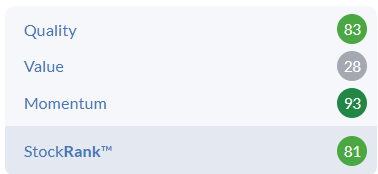
I won’t go fully GREEN on it, as I acknowledge that growth is limited and this is going to put the brakes on returns. But as far as blue-chips go, this is one of my all-time favourites.
Mark's Section
Trifast (LON:TRI)
Up 2% to 76.5p - Trading Update - Mark - AMBER
Trifast is a well-known stock amongst individual investors, perhaps due to the interest of Harwood/Rockwood Strategic. The thesis is that if they can return to historical margins on rising sales, then the earnings will make the company look very cheap. Basically, it's the classic Value turnaround story. It is, therefore, not surprising that this trading update focuses on those ambitions. For example:
With our Recover, Rebuild and Resilience transformation roadmap delivering positive impact, the leadership team remains dedicated to executing its strategy and value proposition which is built around TR's core strengths of quality, service and technical engineering capabilities in selected markets and geographies where it can align both our customer expectations and deliver shareholder value.
However, having resilience as one of the pillars of your “transformation roadmap” shows how tough a market Trifast operates in! This is an update for Q3 trading, and the key line is:
Overall, the Group's performance in the Period and for the financial year to date underpins the Board's optimism that expectations for full year performance remain unchanged.
However, this in itself isn’t particularly impressive. Their broker, Zeus, have 5.8p EPS forecast for FY25, putting them on a forward P/E of 13.3x, with a net debt of £18.1m. The update itself is woefully short of actual figures to judge their progress on this. We are now six-weeks after the period end and I have to assume that if the figures looked great they would have included them in the update. We have to take the broker's forecasts out to FY27, to make them look reasonable value at 7.8x P/E and net cash. A lot can happen between now and 2027!
Mark’s view
While I wouldn’t necessarily bet against Harwood being able to drive the turnaround here, I don’t like the reliance on forecasts out to 2027 or beyond to make the company look reasonable value, and perhaps beyond the forecast window to really look cheap. Paul rated this AMBER in July, and I am minded to keep that rating until there are signs that the turnaround is accelerating and they can beat these modest forecasts rather than simply meeting them.
Gattaca (LON:GATC)
Up 5% to 75p - Trading Update - Mark - GREEN
Recruitment has been an incredibly tough sector for UK investors, and Gattaca is no different with its trading update to 31st January:
Group Net Fee Income1 ("NFI") expected to be £18.8m (H1 242 £19.4m), a decrease of 3% year-on-year ("YoY").
This doesn’t sound great, but they are actually doing well compared to other recruiters. Robert Walters saw NFI down 14% for a similar period. SThree had NFI down 9% in the year to 30 November 2024. Typically, recruitmnet is a scale business, and the larger operators trade on much higher ratings to reflect this. However, in current market conditions, Gattaca’s ability to be more nimble appears to have paid off, and its huge discount to the sector unwarranted.
These trends have been expected, and like many recruiters, they have been reducing costs and headcount:
Total Group headcount reduced by 12% YoY, with sales headcount reduced by 10% as the Group focused on operational efficiency and resource allocation with headcount investment targeted at sectors showing growth opportunities.
This means that PBT remains in line with expectations at around £3m. Cost-cutting is inherently the worst way of maintaining profitability as it is unsustainable. However, it is better than not cutting costs, and one of the factors that have separated the winners and losers in UK small caps this year has been those who saw the risks and have been cutting headcount and those who didn’t. The market has rewarded the former and punished the latter.
Paid-for research provider Equity Development turn this into an adjusted EPS of 6p, which makes the low-teens P/E seem expensive until you realise that a significant proportion of their market cap is in cash. Prior to this update, the company was trading at net cash, so it is slightly disappointing to see this fall in this update:
The Group expects to report statutory net cash as at 31 January 2025 of £16.7m (31 January 2024: net cash of £22.3m). Days sales outstanding (DSO) remains in line with recent reported trends, the decrease in net cash is primarily a reduction in trade creditors.
However, it remains significant, and they have large working capital flows, so this is a normal part of the business. I expect that their overall net tangible assets will remain the same or higher, despite a lower proportion being in cash, making them still look good value on this metric:

For what it’s worth, Equity Development calculates that this trades on an amazing 0.4xEV/EBITDA, falling to 0.2x for FY26. There are reasons for optimism as well as the trend in permanent recruitment. Statement of Work NFI was down due to delays linked to the public sector spending review. When this is finalised, any backlog of work could turn a headwind into a tailwind for Gattaca.
That cash doesn’t do shareholders any good if it simply sits on the balance sheet. The company is forecast to pay a 3p dividend this year but rising to 5.1p next year. The 7% FY26 yield seem reasonable, although I’d personally like them to do a bit more with the cash. Their EBT has a small purchase program in place to offset share dilution. However, the case for more extensive buybacks at this stage is surely a strong one?
Mark’s view
Having watched this company for a while, I had been buying recently as trading at net cash looked too cheap, despite what I thought was the risk of a profits warning. It’s not quite at net cash now, with the cash pile reducing due to lower payables. However, the lack of warning more than makes up for this. Paul rated it GREEN in mid-2024 when the share price was about 90p, on the basis that they were cheap and outperforming their sector. With the shares now trading at 75p, confirmation that the outperformance continues and that they are trading in-line on PBT, they look even better value today. GREEN
Renishaw (LON:RSW)
Down 8% to 3305p (£2.3bn) - Trading Update - Mark - AMBER/RED
These results aren’t particularly impressive:

This makes the rating here a complete mystery:
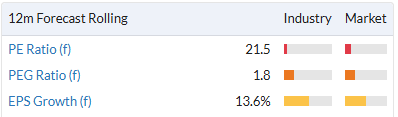
Even with a forecast of a better H2, this is still on PEG of 1.8.
Order intake recently improved, steady revenue growth expected to continue in H2;
There is a decent cash balance:
Strong balance sheet, with cash and cash equivalents and bank deposit balances of £233.2m (30 June 2024: £217.8m).
However, at less than 10% of the market cap, the valuation doesn’t change significantly.
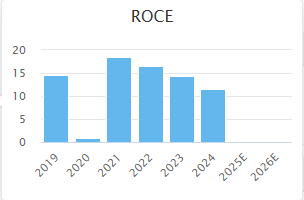
Many investors may like the high gross margin, which suggests they have a good moat. They also have had a reasonable ROCE in the past. However, this has been trending down over time:
And, of course, this only creates shareholder value if they can grow the business. In terms of outlook, they say:
FY2025 revenue range: £695m to £735m; and
FY2025 adjusted profit before tax: £105m to £135m.
The current consensus in Stockopedia is for £725m revenue at the upper end of that range. PAT is a very wide range and works out as £83-107m based on the PBT figures above and their typical tax rate. The Stockopedia consensus is for £113m PAT so this appears to be a warning. The mid-point of the above range is some 16% below the Stockopedia consensus. It also makes those forecast growth rates in Stockopedia look too high and the forward multiple even worse.
Mark’s view
This is obviously a business with a decent moat, but this does shareholders little good unless they can grow the business. Perhaps there are multiple growth opportunities that are outside of the forecast window. However, these results and outlook give little confidence that this is the case. Instead, the most likely outcome is that growth rates will be low going forward, making this stock significantly overvalued. AMBER/RED
Ondo InsurTech (LON:ONDO)
Up 3% to 39p (£49m) - Trading Update - Mark - AMBER
Ondo InsurTech have an interesting sales strategy. Rather than trying to sell their leak detection systems to individuals, they are selling to the people who really bear the cost of leaky pipes: insurance companies. They have some water company customers, too. Although my understanding is that many water meters are capable of detecting leaks, so the drive toward metered water may reduce the demand here. Overall, I don’t think there is anything special about their technology. However, they have a system which is effective and easy to install. This strategy has been pretty successful so far, as the growth rates suggest:
Annualised Revenue Run-Rate: Projected to exceed £7.5m in Q4 FY2025, reflecting c.90% growth compared to Q4 FY2024 (£4.0m).
Full-Year Revenue to 31 March 2025: Estimated at £4.5m-£5m, ~70% growth versus FY 2024 (£2.7m).
This is impressive, but appears to be behind the consensus in Stockopedia:

The fastest growth is in the US:
Registered Customers: 27,000 in the U.S., reflecting 380% year-on-year growth. U.S. accounts for 65% of Registered Customer growth so far H2 FY2025.
But this is only 20% of their total registered customers so far. This is also their biggest opportunity. In terms of financials, they say:
Company remains on track to achieve EBITDA positive trading in H2 FY 2026
This is a year away, and with £6.2m of loan notes at 10% interest, this may not represent cash-positive trading. The good news is that they are receiving advanced payments for initial rollouts, relieving pressure on working capital. However, they will still need to fund the ongoing losses. I don’t see why they wouldn’t be able to raise fresh equity if required, but it remains a risk.
The repayment of the loan notes in January (£0.4m) and due in April (£0.6m) appears to come from the cash flow from the exercise of warrants:
Warrant Exercise: Since September 2024, warrant holders have exercised 10.9m new ordinary shares, generating £2.5m in cash inflows.
Around 900k warrants were exercised by the CEO this month. However, he funded these by selling 700k shares, meaning he likely didn’t put much fresh capital into his holding.
Here’s the full situation as of 31st March 2024:
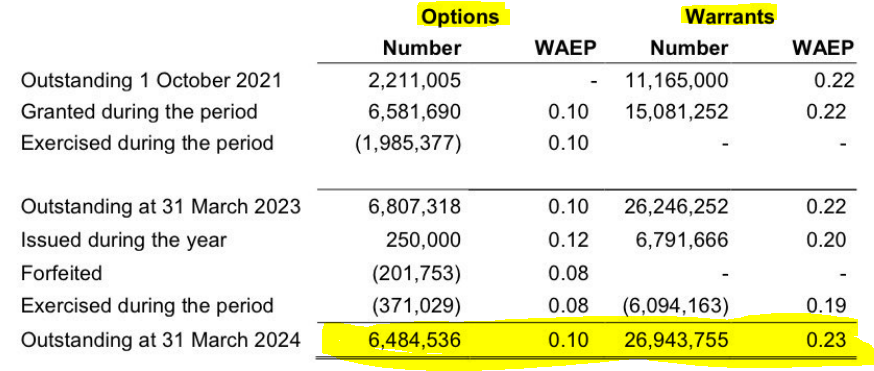
And here is the issued share capital at the interim results in September 2024:
The Company had in issue 116,466,036 ordinary shares at 30 September 2024
So, the company has more capital to keep rolling out its leakbots, but it has come at the cost of dilution. The share count is now 127.4m, and the market cap is £49.7m. Fully diluted (since all options and warrants appear to be in the money), the share count is 149.9m, and the market cap is £58.5m. This is an eye-watering 12x forward sales, or 8x projected annualised revenue run-rate. Investors are paying a high price today for a company that is only projected to be EBITDA positive in a year’s time, even if the addressable market for their leakbots does seem to be huge.
Mark’s view
This looks to be a good revenue growth story based on a decent business model. However, at around 12x forward sales, this isn’t cheap. High forecast growth rates plus cash flow breakeven, likely being over a year away, means that there is a large amount of uncertainty regarding possible outcomes. I remain neutral on whether the growth will catch up with the rating. AMBER
Avingtrans (LON:AVG)
Up 4% to 375p - Contract Win - Mark - AMBER
Seeing this contract win by Booth Industries, I can’t help feeling a pang of regret. My only zero in over 20 years of investing (although several others came close) was Redhall. Avingtrans bought Booth, who makes fire and blast doors, from the administrators in 2019 for £1.8m. I believe far more was going on behind the scenes at Redhall than was ever publicly announced, but the result was that Avingtrans got a bargain. The contract size announced today is not particularly material for the company as a whole:
Booth Industries (Booth), has secured a new £4.5 million contract to supply pressure-rated fire doors for HS2.
That works out as less than 3% of forecast revenue. Nor does it seem material compared to previous orders for HS2-related work:
The contract expands upon Booth Industries' involvement in the HS2 project, following the £36 million contract secured in September 2020 to supply cross passage doors for the London-to-West Midlands segment of the route. Booth will begin mass production of the cross-passage sliding doorsets in its 600m², state-of-the-art production cell during 2025.
However, it highlights that Avingtrans is very good at acquiring niche engineering businesses cheaply and running them better than their previous owners. The problem is that at 25x forward earnings, this is probably in the price. 2026 earnings are forecast to grow significantly, but it really requires a detailed analysis of their order book to see if this is part of a new trend or simply a recovery from the FY25 dip in earnings.
Their broker, Cavendish, makes no changes to forecasts today but says:
Valuation: The shares offer strong intrinsic value as its engineering businesses such as Booth are successfully transformed, while group profitability is masked by the increasing opex investment in the exciting and transformative 3D x-ray and compact MRI systems that offer a huge potential medium-term value opportunity.
They have a 495p target price but without a lot of justification. It is normal for brokers to have a target price at a 30% or so premium to the current share price, so I’m not sure we can read too much into this.
Mark’s view
This contract win highlights what Avingtrans does best: buying niche engineering businesses and running them really well. However, I am neutral on the stock overall due to what appears to be a fairly full valuation. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
Many thanks indeed Graham and team for all your hard work... we're all here to hopefully make decent returns, so my penny's worth would be to align with Ed's articles and concentrate on stocks that are upgrading and ranked Green , with potential to multi bag ... anything that's red or amber red is presumably less likely to need a full section write up ( sell on profit warnings lesson ), unless it's a special case being potentially oversold / very heavily owned ( perhaps a Warpaint London (LON:W7L) ? )...
Yawn
Boring discussion on small cap v large cap .
Im in the small cap camp, maybe stockopedia can offer both in two parts so dont have to read the large cap and US coverage .
As I use the folio on stock to keep a record of trading history and rolling yearly CGT tallies I appear to be stuck with a format that Im no longer finding stimulating, interesting nor more importantly what I signed up for.
Its like being stuck with a once beautiful slim and sexy temperamental sparky lover who is now my wife and changed to boring, overweight and into material wealth .
Hope my missus doesn't read this, its a metaphor only my dear .
So maybe a mistress sexy small cap section for us small cap lovers and a comfortable large cap wife section for others .
Hope this understandable, I do speak in riddles sometimes
See John Gibsons comment below
Why ? I dont agree with that and i just dont want to read about large caps because its pretty much the same analysis i can read anywhere . Doesnt give me a warm feeling and definitely not what i signed up for
I think just a simple separation solves it and should be easy to sort on the side of stocko
Seems it’s not such a boring discussion, for you at least !
Hi Mark. Thanks for the write-up on Avingtrans (LON:AVG). I think bulls of the stock (like me) reckon that the current valuation is justified by the revenue and profit in the engineering businesses. The problem is that these profits are being masked by start-up losses in the small medical imaging business, making it superficially look expensive.
All really comes down to the value in medical imaging. This is a departure from management's usual type of target business as it is much earlier stage. They claim to have quite a bit of management experience in this space and are excited by the technology of their portable MRI scanners which could be revolutionary in both medical and veterinary markets due to their much smaller size and price point than rivals, but it is a gamble and will take time to realise value. Interesting one.
Hi Sparkler
Avingtrans (LON:AVG)
Like you I am an admirier of the company. It is my largest holding having initially bought around 220p. I think Adaptix and the 3D X-ray scanner is more advanced than the Magnetica MRI scanner and at present the most promising for commercialisation.
Whatever I see either scenario as a win for shareholders, Adaptix and/or Magnetica are successful and the share price takes of; doubles I would suggest. The medical division fails to achieve commercialisation and is mothballed. The management (two Steve’s) can focus on the Advanced Engineering Division, which is worth more than the current share price by some margin. The second scenario if it materialised would be similar to Zotefoams (LON:ZTF) and it’s investment in Rezorce.
I am repeatedly amazed by the amount of moaning in the comments, especially from the more obviously professional investors. Strangely, despite their obvious sophistication, they appear unable to spot the glaringly outstanding value a Stocko sub offers to those with 6/7 digit portfolios.
FWIW, I prefer the SCVR roaming around amongst some of my largest holdings, which usually include several FTSE100 companies ...
Agreed. There is ample opportunity to find neglected value in the top division with less volatility. Just look at International Consolidated Airlines SA (LON:IAG)
Agreed I like the mix of big and small caps. There’s are some great (in my opinion) opportunities in the ftse large caps currently that should be reported on to give us members as much info as we want / are willing to consume.
It’s easy enough to scroll past if not of interest or too large for the readers. British American Tobacco (LON:BATS) reported on today for example there aren’t many mega caps with stable revenues and cash flow to support a 7% divi
Hi Graham…please carry on doing exactly the same/something different/a bit of both …as you & the team see fit..whatever you do you’ll be pulled up in the comments section anyway…
Concurrent Technologies (LON:CNC) - Ironic that the coy states re the US market listing - this will assist US based employees to trade the shares. Yet the directors themselves hold such a small number of shares and FWIW I believe that this dual-listing will rescind the (now reduced) IHT tax break for UK holders.
(LON:CNC) It’s not on the list of FCA Recognised overseas investment exchanges. This means that Concurrent will not lose its BPR status.
I agree with other commentators, that it's good to see some coverage of larger cap stocks. The balance of coverage seems about right to me.
On a world scale, many UK FTSE100 and certainly FTSE250 stocks are pretty small. A portfolio of just UK small cap stocks may well offer an "edge", but seen globally it is an obscure corner of world equities. Personally, I follow and invest in some UK small caps, but wouldn't want my retirement relying on them.
To rely on UK small caps means you can never stop working...... on them.
Graham and his team are doing a good job. It is good to have some coverage of larger serious growth companies. You can make a lot of money over time with the larger compounders in the UK. And they have made room for that by cutting coverage of weaker AIM companies which are long term no hopers.
Also they have eliminated emotions from their coverage which is very welcome.
Agreed. Just look at 3i (LON:III) for one. We shouldn’t be elitist when it comes to making a profit on shares.
I thought I would put my pennyworth on what companies should be included in this report.
I would like to see a continuation of summaries on large companies as well as small. I find them useful and when a big beast reports it is likely that small beasts in a similar area will be affected. I want to know how the market in general is doing.
But I would like to see detailed analysis concentrated on the smaller companies simply because we are all searching for the great up and coming company and, as others have said, there is little analysis elsewhere. I suspect the move away from reporting on small companies that others have noticed, is to do with the depressed state of the AIM market. People making money from company analysis are concentrating on the companies they think people are interested in. When AIM picks up (I think it will), the commentators will return to write about it.
That said, I love it when someone comments on a company or an industry they know well - like Megan's report on GSK. For that reason, I suggest the team also includes analysis of any shares they own; they are probably going to do the analysis in any case and I appreciate seeing it.
I have no interest in USA companies - there is enough to do trying to understand UK ones. My fear is that a slump in the US stock market will bring down the rest of the world.
Thanks very much for the comment, chrisgb!
Re: "Concentrating on the companies they think people are interested in", it is true that we use the "Most Viewed" widget to help us decide which stocks to cover. It's not the only factor but it is a big one.
Today, BATS BARC ULVR TATE and RELX are all most viewed on Stockopedia. But if you read the comments on this report, it seems that a lot of people aren't interested in coverage of them. It is tricky to know what people want!
Different people want different things, and the ones who speak are not necessarily representative of the majority every time. We will continue to do our best to figure it out and provide the best mix that we can.
Graham
I, too, would like commentary on the big companies, as a possible spread of my investment allocations by size as well as sector. I made a lot of money from them in the past [eg BDEV, as was, and Persimmon (LON:PSN) and some banks and oil companies] with help from [dare I say it] Motley Fool
Hi Graham -yes its impossible to please everyone -personally, I would cut out all stocks under £25m
Just my quip but cut out under 50 mil most to illiquid, horrible spreads
Please keep up or even increase the coverage of large co's. Many thanks Graham.
"It is tricky to know what people want!"
"If I had asked people what they wanted, they would have said 'faster horses.'" -- Henry Ford
I for one am mostly positive on large cap commentaries where there seems to be big moves or have broader implications.
TATE "Revenue was 4% lower primarily reflecting the pass through of input cost deflation." Hmmm, OK.
I've not been following the story, but in Apr 2022 is reported "Over the last four years we have created a strong platform for growth. As a more focussed business we will enhance the way we serve our customers and accelerate growth through increased investment in R&D, innovation and solutions development." https://www.tateandlyle.com/ne...
As my dad would say, "Still needs a bit more work done to it." I think they sold some of the business around 2022? To be fair, revenues have been rising nicely since then, from £1.2b in 2021 to £1.6b in 2024.
ULVR down 6.6% You can take your pick on your choice of revenue growth statistics they present. -0.1% on GAAP measures, +4.2% on underlying sales growth (+2.9% volume growth), or +1.9%. I sold out of my ULVR shares back in Oct 2024 at 4719p. I bought some in Jul 2020 at 4350p. The had performed very sluggishly, although they are up nicely over 1 year.
I asked myself why I was holding, and came to the conclusion that although they had great returns on capital, they probably couldn't deliver much in the way of growth. Revenues grew at less that 1% pa from 2012 to 2017 and 3%pa from 2018 to 2023. Nothing much to get excited about there, even though Terry Smith and Nick Train speaks of them highly.
I figured that there would be better opportunities elsewhere. A good company for widows and orphans though.
RELX Shares up a tad, but reported a 10% rise in profit. A great quality business, but on a P/FCF of 37 and a PE of 31, that's quite a valuation. Revenue growth has been no great shakes for awhile, going up 4.1%pa from 2018 to 2023. Fantastic returns on capital. Great business. Like ULVR, though, I think there are more exciting companies that are smaller.
Just my 2c anyway. I'm sure that Graham could give much better commentary.
Hi Graham, pleasing everyone is a thankless task!For what is worth my portfolio is made up of US and UK companies, 40% Large Cap, 40% Mid Cap, 18% Small Cap and 2% Micro. Also, I have recently upgraded to Stocko’s European coverage and I am looking forward to more articles and comment on European shares. I am currently in the research stage but there does seem to be a lot of value opportunities and a good mix of growing small caps.
I believe value is value from whatever source. To ignore the top division when you have such gems as International Consolidated Airlines SA (LON:IAG) and 3i (LON:III) is at best silly and at worst snobby.
I was happy to see coverage on BATS - I'm sure plenty of people around here hold it (myself included) given how cheap its been over last year
I'm sure most people only hold genuine small caps as a % of their portfolio
Indeed, but presumably the small cap portion is the under researched, illiquid, actively ( self ) managed part where they feel that they can potentially outperform...
Not necessarily, many of us are buying mid and large caps ourselves actively too - I assume we are all actively buying the best opportunities we can find in the market? For me that means a minimum market cap but I don't have a maximum - it does means a large tilt towards small and mid caps but that is simply because that is often where the value is.
Fair points Boringchess... I just feel that we're more likely to find a frog to kiss under the small cap rocks ( if that's not mixing metaphors too much )... once over £ 2 bn / 5 bn ( pick a number ), information becomes too perfectly disseminated and liquidity too deep to drive prices too far from values ... that's not to say that a large cap can't gap 10% on an unexpected earnings upgrade, but it's much harder to find a ' wrong ' price... many thanks for the reply though...
... once over £ 2 bn / 5 bn ( pick a number ), information becomes too perfectly disseminated and liquidity too deep to drive prices too far from values ...
Are you sure?
You can find similar examples every year.
timarr
Timarr
I'm not going to spend time going back and forth on this ( and I regret getting involved yesterday ), but you've deliberately not included my comment re unexpected news... many of the stories that you mention above include that...
And I was talking about price dislocation versus value... Rolls Royce was a classic example of a turnaround story, but arguably the price was always roughly in line with value , as the improved Metrics filtered through across the year... Stocks like Brave Bison (LON:BBSN) , Oxford Metrics (LON:OMG) , Card Factory (LON:CARD) , Gulf Keystone Petroleum (LON:GKP) which many of us have highlighted , can trade temporarily at ' wrong ' prices, far from intrinsic value , thanks to fund redemptions etc... that extra cushion often feels comforting...
And I didn't say that you can't, but that it's ' much harder ' to find a wrong price in large caps.....
Anyway.... I have always tried to be courteous and supportive on here, but it has become increasingly like ADVFN... many people now seem determined to complain, or be confrontational... I'm convinced that its why so many top drawer posters have left... I definitely wouldn't put myself in that bracket and this is unfortunately a tiny straw on a camel's back, but thats me done too....
Good luck to all in the years ahead...
Hi Cancun
I'm sorry you're leaving, especially if I was the camel breaking straw, but I wasn't being deliberately confrontational (I never am, albeit the written word is an imperfect means of communication).
Anyway, good luck wherever you end up.
timarr
. My fear is that a slump in the US stock market will bring down the rest of the world. My hope is a wall of cash will suddenly discover what value the UK has to offer! Chin up Chris!
Renishaw (LON:RSW) - my notes say "world leader in metrology and spectroscopy. It owns hundreds if not thousands of industrial patents that make its equipment unique and best in class".
Founder David Mc-Murty passed away Dec24 and co-founder David Deer is aged 87. Between own 53% of the stock.
A magazine reported the business may be up for sale. Today £3.45 a share cheaper.
Renishaw (LON:RSW)
The early loss of David McMurty was incredibly sad, but it is a fact that the company would be an enormous asset to many larger groups. When they explored a sale a couple of years ago the price went to over £60. I added a few to my holding today.
What I'd really like, though, is one of these:
timarr
Hi timarr. I ran the rule over Renishaw again this morning. It’s undoubtedly a quality business employing an unusually high proportion of superbly qualified graduates. It’s also in sexy sectors like semiconductors, medical technology and additive manufacturing. What it isn’t doing, however, is growing at anything like the speed that you might expect for the sectors it serves. And its valuation amply reflects the quality without discounting for the mediocre growth. Even 10% cheaper this morning leaves the stock looking expensive. Clearly, there’s a takeout potential here. but shareholders might be relying on that in order to make a decent profit. I’m more comfortable when I’m confident that a company and its profits are going to grow at a solid pace.
Hi BnB
Renishaw (LON:RSW)
I agree with your analysis - it's simply not growing. On the other hand, having followed it for donkey's years, it's never been any good at forecasts and has continually surprised - more often to the upside than the down, and often with one following the other.
But frankly it's a sitting duck. We don't know exactly what the sticking points were previously but McMurty was always protective of his workforce and insistant on high levels of R&D spend. Meanwhile his heirs must be facing a stonking IHT bill ...
Anyway, we'll see. It won't pay for my Spéirling even it does get taken out.
timarr
Whatever happened to this re Tate & Lyle (LON:TATE) and will they come back now share price taken big hit!
Oct 16 (Reuters) - Private equity firm Advent International is preparing a takeover offer for UK-based food and beverage ingredients maker Tate & Lyle TATE.L, the Financial Times reported on Wednesday, citing two people familiar with the discussions.
Shares in Tate & Lyle, which supplies ingredients for Splenda, the sweetener in Diet Coke and other sugar-free drinks, jumped 11.5% to a near eight-year high on the news.
The US-based buyout firm is in the early stages of its bid preparations, according to sources, who cautioned there was no certainty that a firm offer would be made, the report added.
The offer could value Tate & Lyle above its 2.8 billion pounds ($3.65 billion) market capitalization, according to the Financial Times.
Both Tate & Lyle and Advent declined to respond to Reuters' requests for comments
Gattaca (LON:GATC) - TU thanks for covering, Mark, and if anyone wants to read the full ED note and forecasts referred to, it is freely available here: https://www.equitydevelopment....
Not a great day amongst the larger company holdings in my portfolio: British American Tobacco (LON:BATS) , Unilever (LON:ULVR) and Tate & Lyle (LON:TATE) . All down in 6-8% and Shell (LON:SHEL) not far behind. Any views from the DSMR team. No wonder FTSE 100 down - must be because hit ATH earlier in the week!
Ex divi's on any of them pretty sure Shell (LON:SHEL) is ex div today ?
Yes only Shell (LON:SHEL) ex-div. Others poorly received results and trading update. Surprised no review today on Tate & Lyle (LON:TATE) though expect Unilever (LON:ULVR) too big to consider though did have review of British American Tobacco (LON:BATS).
Apologies just seen review of Unilever (LON:ULVR) .
Causing me concern, another Large Cap IG group (LON:IGG, has been buying back it s own shares every day this week yet today it has hit my Stocko 12% Stop Loss figure. I will just have to ignore this.
Hi SM, I had a similar concern IG group (LON:IGG) at the end of January and sold my holding (I had my eye on something else) as it’s had a great run and looked to be topping out post Divi. I still think positively of the company and planned to get ‘back in’ later on if funds and opportunity presented itself.
However If you look at the 12 month chart and read any of Ed’s momentum pieces you’ll know that’s probably a mistake on my part. Throw in a profit beat that was just announced and that’s another massive bull signal? Which is why I’m warily watching the price with large FOMO for a change in sentiment after a little profit taking??
I do wonder why they are doing buybacks at this price thou , are they really that ‘cheap’ intrinsically esp as just recently hit an all time high?
What do u see as a catalyst for future growth ( not that the figure aren’t lovely for IGG). That might take them higher ?
Hi Patrick, the catalyst I see is a rising tide lifting all boats, but I should have sold when I reset my stop loss instead of doing so.
Daft question perhaps (learning how to try and make sense of updates, reports etc). APN - I have always been suspicious of EBITDA, especially when I see "adjusted". This may be a hangover of when I ran my own companies and marvelling constantly at how reality (operationally) never really tallied with such figures (my best friend seemed to solely focus on EBITDA in his role as an acquirer of companies for a Canadian firm). So getting to the question, does the fact that the dip from 2023 to 2024 in the Cash from Operating Activities perhaps be a negative signal? I get it is early days but interested to see what those with much more experience than I think. Cheers.
Maybe FTSE 100 hitting ATHs is not a coincidence as economy grows.
https://x.com/EdConwaySky/status/1889941984615506009?t=8hy619XY98H8eojP2kMgIA&s=19
Now that we are covering mega coys think Barclays (LON:BARC) should be added to the list with their YE results
https://newsfile.refinitiv.com...
Consider it done, bohenie!
Personally I much prefer reports on smaller caps where we may find an edge. There's no shortage of analysis of large cap results....
It is notable for me at least that we seem to have lost a lot of knowledgeable commentators now that the focus has been changed.
And gained some larger cap commentators too.
I generally concur here, investors chronicle has also taken an ill advised swing to covering US mega caps, this lack of coverage is going to further hurt the UK small cap space. IC have notably reduced their coverage on trading updates from mid caps.
There is some action in the Uk large cap space at the moment so it’s interesting, but historically very dull.
We likely all hold trackers dominated by US large caps somewhere in our pensions.
That said I think the quality of coverage has improved, I think the reason for the slow down in comments is due to Paul S being controversial which always starts debate.
The slow down in comments, is because a lot of members, are commenting elsewhere. I note recently, that most of the posts, are not about stocks, that have reported on that day, but others or gold or Reits.
I'm not interested in the large cap reviews, even if l do hold them. By doing large caps, do are reducing small cap coverage. Often only 6 stocks a day are covered.
Furthermore, many of the posts today are about site layout on various devices. Is it possible to start a separate thread on site development?
Investor Chronicle went downhill after Chris Dillow left.
yes, Investors Chronicle is a shadow of its former self. I found the best writer, by far, was Phil Oakley; but they now very rarely seem to use him.
IC wanted to increase my quarterly subscription fee from £50 to £62 next week - I have just sent my cancellation request.
Large or small companies cover
Barclays deserves cover simply because it’s share price doubled last year. I find the short commentary on large caps very helpful in this site. The number of comments by the community is also indicative of interest.
Yadi, didn't Standard Chartered (LON:STAN) double as well? But not before I backed out - however, HSBC Holdings (LON:HSBA) which I do hold is doing pretty well.
UK Banks
Banks of all sort have been excellent investments last year.
Banks, Along with asset managements and housebuilders are predicted to come atop in 2025.
Good points Doctor Dave. As a full time trader for 15 years, I won't touch FTSE 100 as so many have a competitive advantage over me, I am interested in others views of small caps. I meant to cancel my subscription of Investors Chronicle last year as it's coverage of UK small caps is declining, I will be doing so this year. Now we have lost the Small Cap Value Report on Stockopedia, that subscription is less likely to be renewed.
As an x professional it always makes me smile that we think we have an edge in anything. There are minimum 200 professionals looking at every stock, at least 50 with direct access to the company and at least 30 on a six monthly road show. There are no stones left unturned. I welcome all coverage large and small, outsized returns are certainly on offer at the small end, but they come with a lot of risk. The quality of investor comment is why I hang out here, from above and below.
Definately true that someone somewhere knows more about a stock than yourself.
But it is also true that many stocks are mis-priced. Information is ignored because people use emotions and not logic / analysis when buying and especially so when selling.
Hi RDH. Am I right in thinking though that many of those professionals work for institutions rather than for themselves ? And those institutions are not that interested in putting the odd £20,000 into relatively illiquid stocks, whereas I am? DD
Yes but if an institution really wants stock they just ring the company up and get some.. one way or another … just because they aren’t trading doesn’t mean they aren’t influencing price. They ring the broker, tell them their view and where they will transact. The broker shakes the tree and sees if any stock is loose. They certainly don’t sit there working orders on the book … unless they want to send a message. I’m just making the point that everything is being looked at …
And hopefully the said institutions are buying small caps that are on a journey into £ 250 - 500 mio mid caps...
Agree. You can get far deeper coverage of US large cap from Seeking Alpha for example. Seeking Alpha commentary covers zero UK small cap. Stocko's USP is UK small cap ... why dilute your USP?
Yes but the large caps give you a useful steer on what the economy is doing. Personally i like the new format and content.
The large caps could be covered briefly with more depth given to the small caps.
Wish I had kept quiet - Barclays (LON:BARC) now 5% down but at least Bioventix (LON:BVXP) up a tad today having dropped like a stone over the past few weeks.
Im sorely tempted to bail on Bioventix (LON:BVXP) as watching the SP slide ever lower on zero news and zero director buying does not inspire confidence. Fingers crossed that the results announcement on March 24th provides some reason for optimism.
Its now more attractive as an income stock but thats not what I bought it for!
Memo to self: Sell Falling Stars before they come crashing down to Earth.
Anyone else finding the site really glitchy when using in a iphone? I frequently have to close down the app and clear cookies to get it to work again. Only site/app that I’m having this problem with. Contacted support and they blamed Safari and my “old Iphone12”. Don’t really want to have to load another browser.
Yes crashes quite often on my old iPhone and have to restart it
iPhone 14 with Chrome, so two years old phone the site works a treat. The site is complex with all the graphs and charts, maybe stretching the old device?
You can’t put petrol in a horse.
Actually you can put petrol in a horse but performance will suffer!
Neigh
Working fine in Netscape!
Love this
Love it!
I switched over to Google Chrome and have found it so much better, admittedly on a newer iPhone but hopefully will do the trick?
I have iPhone12 mini, with Google chrome as the default browser, and Stocko ‘app’ works fine - I’d try that combo as safari may well be the issue for you. Which unfortunately does mean you’ll need to load another browser…
Works fine in my iPhone XR (10). My days are numbered by the sound of it.
Using iPhone 10 XR via Safari and having no issues.
No problem on an iPhone SE, which I’m told is the iPhone 11 inside
No problems on Android phone. Fraction of the price of an Apple too!
I use an iPad, yes this site is glitchy, it's getting worse. I have problems getting in, l get error messages, some charts don't display etc.
Yes it is only this site. I use Safari.
Think Stockopedia need a properApp.
I use an iPad, yes this site is glitchy, it's getting worse. I have problems getting in, l get error messages, some charts don't display etc.
Yes it is only this site. I use Safari.
Think Stockopedia need a properApp.
Completely agree. The site is a nightmare on my variety of iPads and iPhone, some of which are less than a year old. Presumably, iOS app would solve a lot of the problems.
Works fine on my iPhone or iPad
‘This site is a nightmare on my variety of iPads and iPhone’
What on earth are you people trying to do? I am skiing in France for the season and my iPad works flawlessly.
What on earth are you people trying to do? I am skiing in France for the season and my iPad works flawlessly.
I’m trying to keep in touch with the daily thread on a permanently open tab in Safari without having to log back into the site constantly. I’m kicked out more often than yiannos1 ;-)
I should have replied to this earlier. If you are trying to keep a tab open permanently and you are having problems then that is a problem with the iPad operating system not with the Stockopedia software. I generally only have one tab open in Safari and having once logged in I do not have to log in again when I select Stockopedia from my bookmarks.
Not sure if I'm getting the wrong end of the stick here, but just to say, I have never used the app (fed up with them littering my screens), just have a tab permanently open in Chrome. So two taps take me to website home. Never a problem!