Daily Stock Market Report (Thur 13th August) - COST, RNK, TPX, PBEE, STB

UK GDP has just been released. The economy grew by 0.3% in June and by 0.4% in Q2. This is in line with expectations. The previous quarter had seen growth of 0.6%.
ONS director of economic statistics Liz McKeown:
"Growth slowed in the second quarter of the year, following a strong start to 2026, but remained relatively robust.
"Services were once again the main driver of growth, while production was broadly unchanged and construction also grew."
The pre-open FTSE chart wobbled initially on the news, dropping a few points, before recovering. Slow and unsteady economic growth continues!
Overnight market movements:
The FTSE is up 0.2% at 10,810
S&P 500 is up 0.1% at 7,755
Brent crude (November) is down 0.2% at $86.70/bbl
Gold is down 0.6% at $4,385/oz
Bitcoin is up 0.4% at $63,800
Leaving it there for today, cheers! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Rio Tinto (LON:RIO) (£122bn | SR79) | Tomago Aluminium will enter into a 10-year power purchase agreement for electricity supply to the smelter through to 2038. The PPA will begin following the expiry of the current electricity contract. Tomago Aluminium will support the new agreement with A$1.1 billion (in real terms) of investment in the smelter between now and 2038. | ||
Antofagasta (LON:ANTO) (£39.7bn | SR72) | SP -5% Revenue +18%. PBT +72% ($1,996m). Following severe weather, detailed inspections have identified the need for repairs to certain pipeline platforms and water management systems. Group production for 2026 is expected to be in the range of 625,000-655,000 tonnes (previously 650,000 -700,000 tonnes). | BLACK Copper production guidance lowered. | |
Fermi (LON:FRMI) (£3.59bn | SR1) | Lee McIntire is now CEO. Was previously Partner, Executive Vice President at Bechtel Corporation. | ||
Entain (LON:ENT) (£3.58bn | SR27) | H1 net gaming revenue +5% at constant FX, ahead of expectations. Underlying H1 EBITDA £479m, ahead of expectations. Loss after tax £11.4m. Outlook - reiterates guidance of FY26 Online NGR growth of 5-7% (at constant FX). FY26 Underlying EBITDA guidance range of £910m to £960m, with the midpoint in line with market expectations. | ||
Savills (LON:SVS) (£1.71bn | SR89) | Revenue +9%. Underlying PBT +47%. Expectations for the enlarged Group for 2026 are unchanged. “Continued volatility at a macro level… makes the timing of conversion of our Transactional pipeline difficult to predict.” | ||
Costain (LON:COST) (£579m | SR91) | Revenue +3.4%. Adjusted operating profit +3% (£17.3m). Reported operating profit also £17.3m. Net cash £164.4m. Expects revenue growth in H2 26 compared with H1 26. Forward work position maintained at £7 billion. FY 26 revenue, adjusted operating profit and adjusted operating margin to be in line with the Board's expectations. | AMBER/GREEN ↓ (Mark) | |
Rank (LON:RNK) (£466m | SR59) | FY LFL net gaming revenue +6% to £834.1m, U/L Op Profit +21% to £78.6m, U/L EPS +15% to 10.5p, Net Debt £147.2m (FY25: £154.7m), Dividend +35% to 3.5p. “Made a good start to the new financial year with Group NGR up 8% for the first six weeks…reiterate our ambition to deliver at least £100m underlying operating profit in the medium term.” | AMBER/GREEN ↓ (Graham) I turned GREEN on this in April at a share price of 102p (share price today: 103p). Since then, we’ve had the resignation of Keir Starmer and the installment of a new PM who may favour much higher tax rates on slot machines. There is a thinktank proposal to double Machine Games Duty on high-stakes machines from 20% to 40% - with gaming machines having played an important role in Rank's recent success. I’d be more inclined to stay GREEN on Rank today if the results had been cleaner. Overall, I’m wondering if I allowed myself to get a little bit too enthusiastic about this one. Given all of the risks and the complications involved in running a land-based business in this highly-regulated industry, maybe I should tone down my enthusiasm just a tad. AMBER/GREEN it is. | |
Pensionbee (LON:PBEE) (£346m | SR28) | Customers +14% to 327k, AuA +37% to £8.6bn, H1 Revenue +40% to £26.4m, LBT £2.9m (25H1: £5.1m LBT). Cash £31m (25H1: £34m). Reiterates its existing guidance framework. | AMBER = (Mark) Some decent growth metrics reported for the half year. However, net inflows seems to have been fairly static recently, with market performance being the big driver of AUA growth. With largely passive strategies tied to global market performance, this may be subject to volatility. As well as revenue growing rapidly, so are costs. This is normal for a company pursuing a growth strategy. However, it means that the future profitability is highly uncertain. My modelling suggests they will need cost base growth to moderate going forward or an increase in net flows for this to grow into the current valuation, let alone anything higher.. However, being close to break even and with net cash this gives them time to pursue these aims. So I am happy to keep our previously neutral view. | |
Secure Trust Bank (LON:STB) (£295m | SR91) | H1 Adj PBT +9.4% to £31.3m, Adj. EPS +12.7% to 126.4p. CET1 14.3%. Remains on track to achieve FY 2026 guidance. (+8-10% Net lending, +10bps risk adjusted margins, CET1 c.13.5%). | GREEN = (Graham) | |
Cab Payments Holdings (LON:CABP) (£206m | SR41) | The Cash Offer remains 1.15 US dollars in cash despite declaration of Inaugural Interim Dividend. | TAKEOVER | |
Genel Energy (LON:GENL) (£177m | SR33) | Drilling activities recommenced in April and production at the Tawke field restarted on 28 June and at the Peshkabir field on 11 July. | ||
Tpximpact Holdings (LON:TPX) (£72.6m | SR83) | Previously RNSed possible contract now confirmed. £25m over 3 years for the MoJ to provide probation digital services. No change to forecasts. | AMBER/GREEN = (Mark) While this contract win was effectively announced on Monday and was already in forecasts according to Cavendish, given the low forward valuation, anything that builds confidence in these should be welcomed. Only the relatively short history of trading profitably and the cyclical nature of government procurement mean that I don’t increase our view further. | |
First Tin (LON:1SN) (£67.7m | SR28) | Proved and Probable Ore Reserves +13%) to 45Mt @ 0.12% Sn containing approximately 55,000 tonnes of tin. | ||
tinyBuild (LON:TBLD) (£43.3m | SR60) | “tinyBuild alleges Max failed to pay royalties owed to tinyBuild. Max acknowledged royalties are due, but the parties disagree regarding how to calculate the royalties owed. Difference $1.9m. | ||
Petro Matad (LON:MATD) (£19.5m | SR14) | Further daly in implementing 2026 oil sales agreement, but all issues now resolved. Permits in place for 3D seismic but not starting until they receive oil revenue. Five companies reviewing farmout data. | ||
Light Science Technologies Holdings (LON:LST) (£15.9m | SR4) | H1 Revenue -26% to £3.73m, LBT £0.8m (25H1: £0.16m Loss), Net Cash £2.44m (25H1£1.07m) after £6.6m raise in period. June & July 26 Revenue totalled £2.15m, Order Book £3.09m. “anticipates a more pronounced rebalancing of our divisional revenue contributions as the PFP division scales, in turn driving improved margins and cash generation as we progress into FY 2027” |
Graham's Section
Rank (LON:RNK)
Up 3.5% at 103.3p (£483m) - Final Results Graham - AMBER/GREEN ↓
This casino and bingo hall operator has enjoyed a nice return to profitability after battling with Covid restrictions and then very high cost inflation until c. 2023-2024.
These full-year results for FY June 2026 show the positive trends continuing, as “ongoing cost inflation, increased taxation and regulatory headwinds were addressed through mitigating cost actions and efficiency savings.”
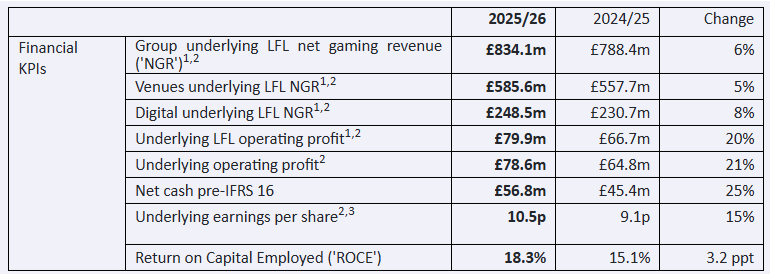
As you can see from the above, there is plenty of positive operating leverage at work when things are going reasonably smoothly. Net gaming revenue increases 6%, and underlying operating profit surges by 20%.
The company’s own calculated ROCE is excellent at 18.3%.
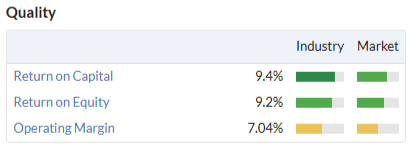
Unfortunately the returns this year aren’t very clean, with £23.3m of "separately disclosed items” (compared to only £5.5m last year). That’s relevant to ROCE, because Stockopedia calculates it based on the statutory numbers, not on the numbers that have been massaged by various adjustments.
So for example, Stockopedia calculated last year’s ROCE as a more average 9.4%
As the “separately disclosed items” have such a big impact on the bottom line and on profitability calculations, let’s see what made them jump higher this year.
It’s complicated, but here’s my summary of the adjustments. From largest to smallest:
£6.7m costs to close some Mecca bingo venues, offset by some credits from venues closed in prior periods. A one-off cost? Arguably yes.
£6.5m loss from a payment fraud incident in Spain. Is this a one-off incident? Arguably yes.
£5m provision from regulatory settlement with the Gambling Commission. There were historical compliance failures at Grosvenor Casino (details not given). A one-off incident? Not sure. It’s the gambling industry, after all.
£3.7m of restructuring and other costs. I definitely wouldn’t ignore this.
£1m impairment.
Ultimately, it’s a matter of opinion as to what you think the real profit figure is (that old saying is correct - profit really is just an opinion).
With £23m of adjustments, I’d assume that about half of them are true instances of bad luck and one-off costs that aren’t reflective of the company’s underlying profitability.
That would leave me with a true underlying profit figure of about £67m.
But this is a capital-intensive business and it’s not easy to convert profit into free cash flow. The net free cash flow result for the year is £25.5m, slightly worse than last year’s £27.7m.
After dividends, the company’s net cash balance does improve, but perhaps not by as much as you’d think: from £45m last year to £57m this year.
Outlook is fine, with remote gaming duty delaying the company’s ambition to achieve £100m of underlying operating profit.
We finished 2025/26 with strong trading momentum and have made a good start to the new financial year with Group NGR up 8% for the first six weeks…
We reiterate our ambition to deliver at least £100m underlying operating profit in the medium term. Digital profitability will inevitably step down in 2026/27, however, due to the annualised impact of RGD at 40%, despite the decisive mitigating actions we have taken in 2025/26…
Remote gaming duty increased on 1st April of this year, and so its effect on FY June 2026 was limited. We’ll see the full effect in FY27.
CEO comment
The CEO makes a nice statement, pointing out that the company paid £225m in taxes and duties during the year (half the market cap!). More positively:
There is material growth runway ahead, most obviously for our Grosvenor casino venues where gaming machines optimisation is an area of sharp focus and significant opportunity.
Graham’s view
I turned GREEN on this in April at a share price of 102p.
Since then, we’ve had the resignation of Keir Starmer and the installment of a new PM who may favour much higher tax rates on slot machines. There is a thinktank proposal to double Machine Games Duty on high-stakes machines from 20% to 40% - with gaming machines having played an important role in Rank's recent success.
Rank’s CEO has made the case against higher taxes today:
Tax increases for clubs like ours, with high levels of supervision and operating on tight margins, will swiftly lead to lower tax receipts as much-loved bingo halls and casinos will be forced to close, impacting customers in local communities. The Government has supported bingo clubs like ours in recent years and any tax increase would have a material impact on commercial viability.
From an investment perspective, I’m inclined to believe him and to view this as a real threat to the commercial viability of venues.
If Machine Games Duty increases, the best-case scenario may be a further delay in Rank’s ambition to achieve £100m of operating profit. But I would expect more venue closures and more exceptional costs.
Speaking of exceptional costs, I’d be more inclined to stay GREEN on Rank today if the results had been cleaner. Overall, I’m wondering if I allowed myself to get a little bit too enthusiastic about this one - although I did acknowledge that it was risky!
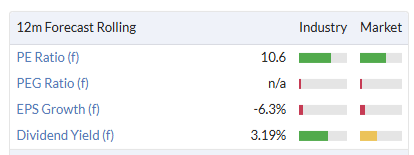
For now, AMBER/GREEN seems to be the more prudent stance. I still think it’s an excellent casino and bingo hall operator, and with some strong online operations, too. And I like the valuation at 10x earnings:
However, given all of the risks and the complications involved in running a land-based business in this highly-regulated industry, maybe I should tone down my enthusiasm just a tad. AMBER/GREEN it is.
Secure Trust Bank (LON:STB)
Up 2% at £16.04 (£301m) - Interim Results - Graham - GREEN =
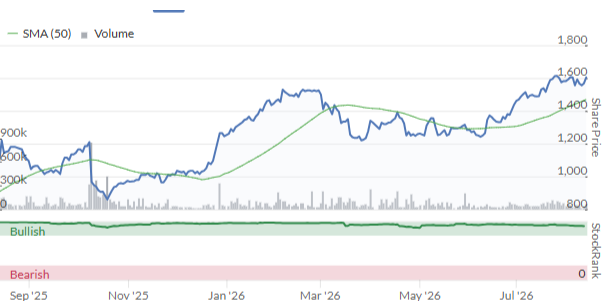
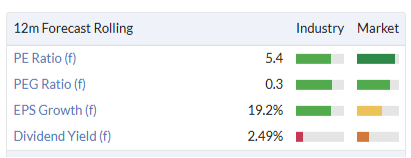
We turned green on this in February on the basis of the stock still being very cheap (trading at 5x earnings) despite having multi-bagged over the prior year:
The financial highlights for H1:
Adjusted PBT +9.4% to £31.3m
Few adjustments are needed; actual PBT comes in at £31.4m or £29.9m if we exclude discontinued operations.
Adjusted return on equity 14.5%, actual return on equity 12.3%.
In terms of safety, the CET1 ratio is 14.3% which by banking standards is considered extremely safe. This has increased after the company exited its Vehicle Finance business.
Guidance unchanged:
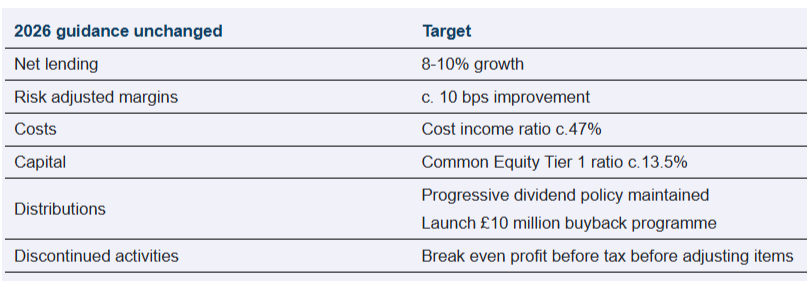
Note that the CET1 ratio is seen falling to 13.5%. Makes sense to me. Keeping it over 14% is likely to be inefficient.
And that 8-10% net lending growth rate looks attractive to me, considering the value on offer here.
Indeed, given the value on offer, I would expect to find more problems and risks for investors here - but they aren’t jumping out at me. For one thing, the growth rate looks perfectly satisfactory to me: there was 4.9% loan book growth in the six-month period. A 10% annual growth rate might be both attractive and realistic.
Dividend: the buyback payout isn’t as large as it could be, but I wouldn’t let that bother me. The interim dividend is 12.4p and the market expects full-year dividends of 37.6p. That pales in comparison to the forecast EPS figure of 246p.
And so it makes sense that the company would also buy back its own shares, given the low dividend payments, the capital released from exiting Vehicle Finance, and the low earnings multiple. A £10m buyback is underway and when it’s completed in September, “a further announcement will be made”. Another buyback, perhaps?
Outlook: very positive, while also warning of a volatile external environment..
Our continued focus on delivering operating leverage is expected to move the cost income ratio towards levels achieved by leading peers over the medium-term, providing a clear pathway to higher returns. The Group is now operating with a lower cost of risk, remains strongly capitalised and is actively returning capital through an ongoing value-accretive share buyback programme.
The first half of 2026 demonstrates clear execution against our strategic priorities and reinforces our confidence in the targets set out earlier in the year. We are laying the foundations to deliver our medium-term targets of c.10% annual net lending growth and return on average equity above 16%, while remaining on track against our 2026 guidance metrics.
Graham’s view
This is now a leaner, more focused business with 650 employees (down from 845 a year ago).
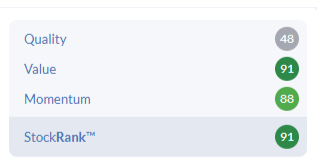
When a P/E multiple of 5-6x is involved, there’s nearly always a “catch”. Apart from the fact that this is a bank and its shares have already multi-bagged for investors, the catch isn’t apparent to me. I’m therefore staying GREEN.
Stockopedia calls it a Turnaround; perhaps it can graduate to Super Stock status as Quality improves over time?
Mark's Section
Costain (LON:COST)
Up 5% at 230p (£580m) - Half-year Financial Results - Mark - AMBER/GREEN ↓
Background:
Costain has been a bit of a smooth trends favourite over the past few years, with the share price delivering 4x returns to holders in that time:
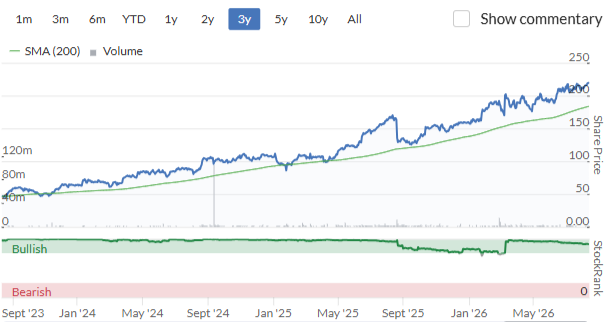
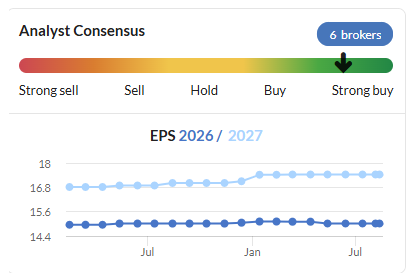
However, this continued share price momentum doesn’t appear to have been driven by significant upgrades in EPS recently:
And the longer-term trend shows flat performance after the initial post-COVID recovery:
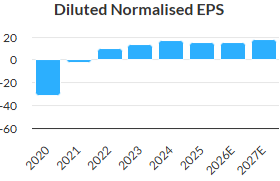
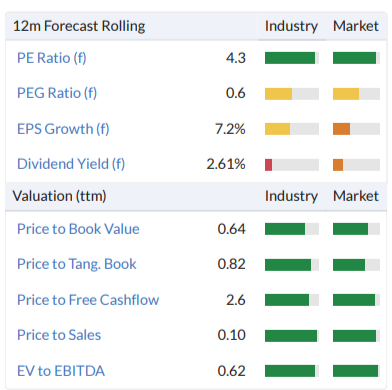
Returns here have been largely driven by a market re-rating, rather than changes in corporate performance. Here are the valuation metrics from three years ago:
And here is today:
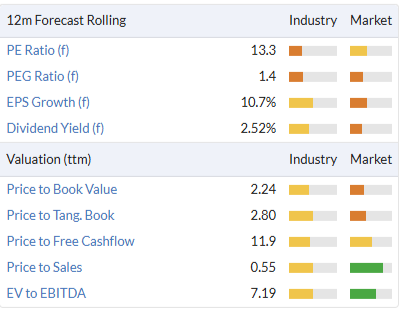
This shows why Value Investing still works. The markets’ perception of companies changes far more significantly than any change in fundamentals, and investors who can take advantage of these swings can generate great returns.
However, three years tends to be a dangerous time for trends, as mean reversion in corporate performance can start to impact outcomes. These results come at a critical time.
Today’s results:
The headlines are uninspiring:
· Revenue up 3.4% to £543.1m…
· Adjusted operating profit up 3.0% to £17.3m…
· Adjusted EPS up 3.6% to 5.7p…
Taken in isolation, these show that the company is trading flat in real terms and without any sign of positive operational gearing; costs are going up slightly faster than inflation.
However, there are also some positive signs. Cash flow from operations was £14.1m, which, combined with working capital timing, led to a net cash position £20m higher than the previous period at £164.4m. The dividend is increased, reflecting a reduced dividend cover target.
Very importantly for companies in this sector, this doesn’t appear to be due to window dressing, as the average cash balances are in line with this figure:
Group's average week-end net cash balance in the period was £177.3m (H1 25: £152.9m, FY 25: £149.2m
This doesn’t mean that all this cash is distributable. Corporate failures in this sector usually result from major projects that go wrong combined with net debt. Customers and suppliers often demand a bullet-proof balance sheet. Trade Payables still exceed Receivables by £64m. This is normal for the company, but that trade credit is largely extended to them because they hold the cash to pay it if needed.
The level of cash balance here makes the balance sheet very strong for the sector.
Divisional Revenue:
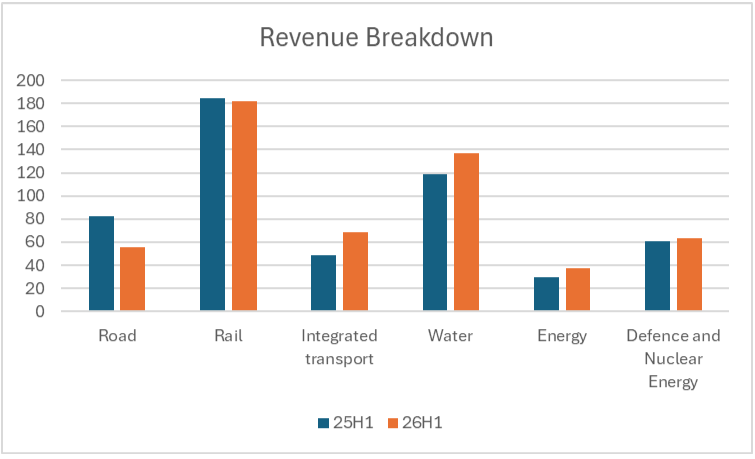
The divisions show dispersion, with Road work down significantly but offset by growth in Integrated Transport, Water and Energy projects:
Order Book:
What is driving positivity about the future for both the company and investors is the size of the forward business:
As at the end of H1 26, our forward work position, which is our combined order book and preferred bidder book, was maintained at a record £7.0bn (FY 25: £7.0bn; H1 25: £5.6bn), an increase of 67% over six years and representing almost seven times our FY 25 revenue. When combined with the revenue delivered in H1 26, it includes £1.1bn of revenue for FY 26 and £1.3bn of revenue for FY 27, equivalent to 91% of consensus forecast revenue in both years.
This forward work position is around half a firm order book, and half as preferred bidder status. They have also had a strategy of diversifying their forward order position away from central government projects, and into private & regulated customers, and devolved government customers, which now make up 48% and 23% of the forward work, respectively.
Forecasts:
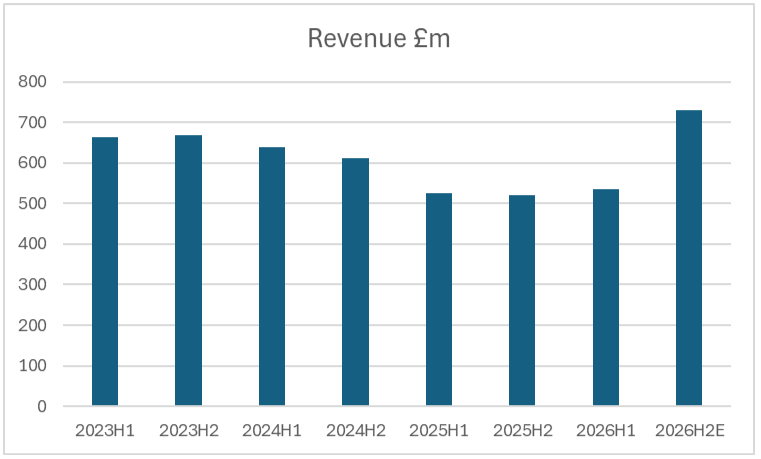
The size and visibility of this forward work position is reflected in the forecast. For example, Cavendish expects revenue to grow to £1.272bn for FY26 as a whole, an increase of 21.6%. This is followed by a further 9.6% rise in revenue for FY27.
However, delivering £1.272bn of FY revenue means that they have to deliver £729m in H2, which is a big jump from H1:
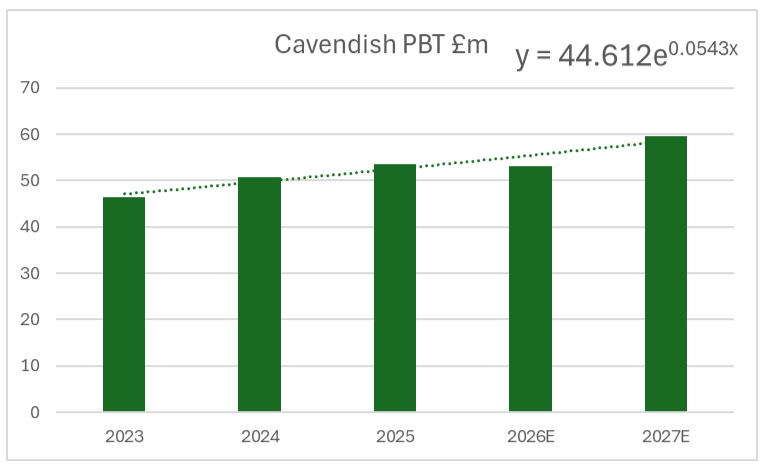
And Cavendish doesn’t forecast this revenue jump being reflected in PBT, which is below trend for FY26:
Panmure Liberum are slightly more pessimistic on revenue and optimistic on PBT, but the overall picture is very similar.
Valuation:
Panmure Liberum raise their target price today to 270p from 245p, and say that “a CY 27 P/E and yield of 11.8x and 3.3% are too cheap.”
Cavendish say:
Our 297p price target implies an 11.0x blended EV/EBIT across FY26/27E, in-line with the FTSE 250 five-year average. We believe Costain's heavier UK infrastructure weighting and balance-sheet-backed shareholder returns support a path to upside and a premium to the FTSE 250.
However, I struggle to get behind these views. The long-term PBT growth rate, including forecasts out to 2027, is around 5% CAGR, or about 2% real.
I’m not convinced this sort of performance deserves a FTSE250 average multiple.
Mark’s view
The market has liked these results this morning, perhaps more for the strength of the forward order book than the numbers themselves. The shares aren’t expensive. However, they also don’t look great value on 15x forward earnings and 13x FY27E EPS, for a business that is growing PBT by around 5% a year nominal.
The cash flow is good, and the company retains significant net cash. However, this is largely used to ensure that the company has the financial resilience to weather any storms, rather than significantly enhance shareholder returns; we would struggle to describe this as an income stock. There is an ongoing share buyback, but so far, this appears to have largely offset management options rather than led to a significant reduction in the share count.
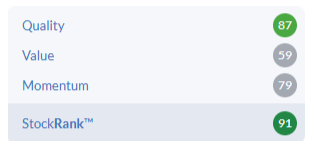
We’ve been GREEN on this company for some time. Given the Super Stock status and solid balance sheet, I think it makes sense to be positive:
However, with a full valuation, a big H2 required to hit the FY revenue number, and rather mediocre PBT growth, it is more of an AMBER/GREEN for me.
Tpximpact Holdings (LON:TPX)
Down 5% at 72p (£73m) - confirms £25m contract with the MoJ - Mark - AMBER/GREEN =
It seems strange for the share price to be down on a £25m contract win. However, the context of this is that the provision win was announced on Monday in response to “market speculation”. Today we get the details:
● Contract Value: £25 million
● Contract Duration: Initial 3-year term from 3 August 2026 to 2 August 2029, with an option to extend for a further 12 months to August 2030 (totalling up to 4 years).
● Framework Procurement: Awarded following a competitive selection process under Lot 2 (Digital Capability and Delivery Partner) of the Digital Outcomes and Specialists 7 (DOS 7) framework.
TPX Impact has been winning a number of government contracts recently, as the push to drive public sector efficiency is increasingly relying on IT solutions.
What may be disappointing to some is that this win appears to have already been in forecasts. Their broker, Cavendish say:
Reiterated guidance incorporates healthy double-digit revenue growth, leading to adj EBITDA margin improvement of +1% pa. Forecasts show +28% FY27E revenue growth and subsequent +10% growth to £110m in FY28E, driving adj EBITDA growth of +37% in FY27E and +19% in FY28E with margin expansion to 13% in FY28E. Net debt expectations remain breakeven by FY27E, an impressive improvement from £17.5m net debt at FY23.
However, forecasts remain the same at £100m revenue for FY27 and £110m for FY28, with £10.7m and £13.3m Adjusted PBT, respectively.
The relationship between forecasts and the share price has been far from linear here recently. Interim results kicked off the current strong performance in December, where an in-line forward statement led to a 40% rise in share price. The market clearly doubted they were trading in line before then!
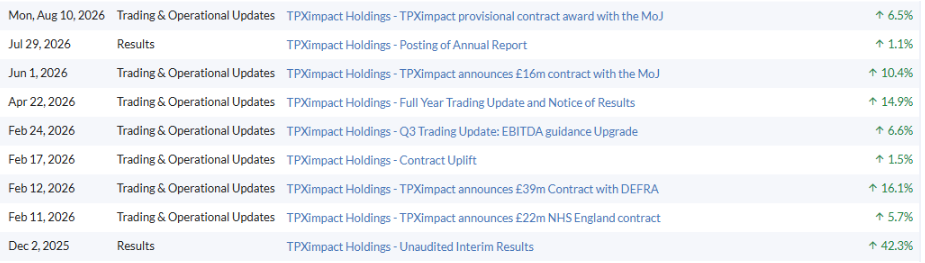
Then a series of large contract wins over the next six months led to the share price doing 5x off the lows, despite the broker mostly saying that these were in forecasts for future years. The market now doubted that they weren't trading ahead. This was backed up by upgrades for FY26, which Roland nicely summarised when we reported on their FY26 trading update in April:
| FY26 guidance (y/e 31 Mar) | Revenue | Adjusted EBITDA | Adj EPS (Cavendish) |
|---|---|---|---|
Previously | £76.2m (consensus) | £6m to £7m | 3.4p |
24 Feb upgrade | £76.2m (consensus) | Not less than £7m | 3.9p |
22 April upgrade | £78.1m | c.£8.6m | 5.0p |
Final results at the end of July led to material upgrades in EPS for forward years, and the market shrugged its shoulders!
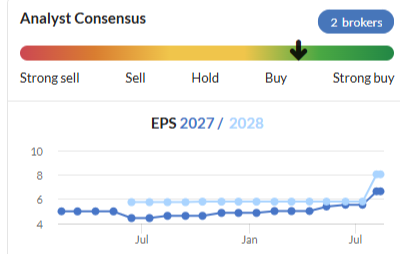
So today’s contract news may well be the start of very similar market behaviour.
Valuation:
Despite the meteoric rise in share price recently, the shares continue to look good value. Cavendish has 10.3p EPS pencilled in for FY28, and it is these types of contract wins that provide visibility over those earnings. They also forecast the company to become net cash positive at the end of this financial year. These metrics make the stock look too cheap, assuming they are delivered.
[Note: I can only see Cavendish research here, so the Stock Report forecast data appears to be a little behind the times.]
Mark’s view
While this contract win was effectively announced on Monday and was already in forecasts according to Cavendish, given the low forward valuation, anything that builds confidence in these should be welcomed.
Only the relatively short history of trading profitably and the cyclical nature of government procurement mean that I keep our AMBER/GREEN view.
Pensionbee (LON:PBEE)
Down 2% at 142p (£346m) - Half-year Financial Report - Mark - AMBER
Some strong growth metrics as a 14% rise in customers, together with net inflows and supportive markets meant that Assets Under Administration rose 37% to £8.6bn.
This fed through to revenue:
Group Revenue increased by 40% to £26.4m for the first half of 2026 (H1 2025: £18.9m), with Group Annual Run Rate ('ARR') Revenue increasing by 40% to £55.8m (H1 2025: £39.8m), reflecting the scalable and predictable nature of the Company's recurring Revenue model.
However, this ends up being another loss-making period, with £3.3m operating loss. This is improved on last year’s £5.6m loss for the same period and looks to be in line with forecasts. This isn’t unusual for a company pursuing growth above all else. However, this is getting on for a long-time for a company not to be profitable:
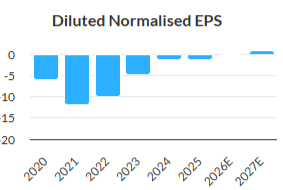
Growth trends:
The good news is that 40% revenue growth looks to be an acceleration from recent trends. The bad news is that the cost base appears to be growing at a similar rate:
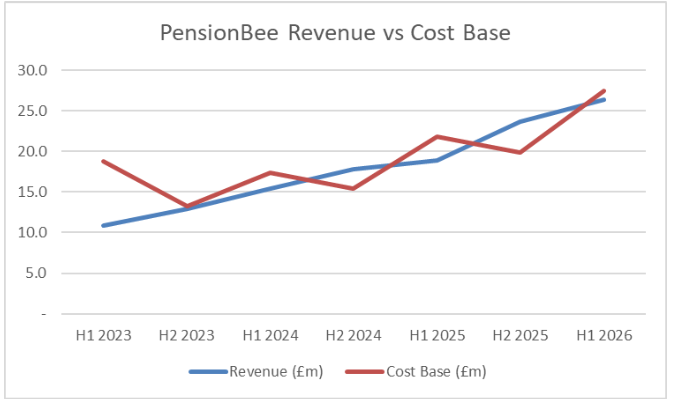
The current trend is for the cost base to rise by about 16% a year. Not too much of an issue if the revenue rises at 40% a year.
Revenue Drivers:
However, it is worth looking at what is driving that revenue growth:
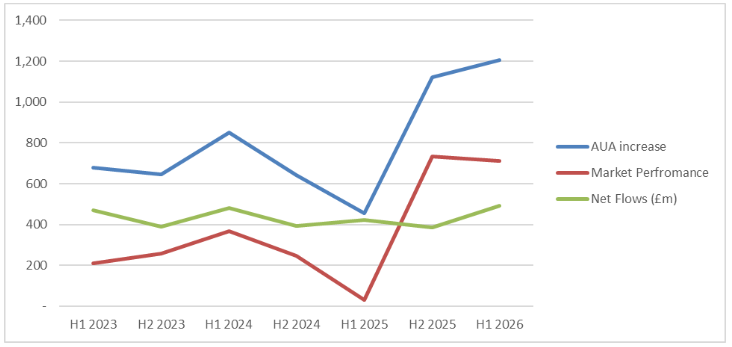
Net flows are actually pretty steady at £400-450m per half. The big driver recently has been market performance. This may not continue.
Modelling:
This all means I can create my own model of where profitability may progress from here, at similar rates of net flows and cost base rises. The big unknown is market performance. Given where we are for valuations, and that PensionBee’s strategies are largely passive and low-cost, perhaps 7% nominal may be reasonable for global equities going forward? Many valuation methodologies put the expected 10-year returns from here at close to zero, but then these have been wrong for a number of years now as passive flows continue to favour megacaps.
Anyway, based on these assumptions, this is what I get:
Year | AUA | Net Flows | Mkt Perf. at 7% CAGR | Revenue | Cost Base at 16% CAGR | Op. Profit | FY Op Profit | EV/EBIT |
|---|---|---|---|---|---|---|---|---|
26H1 | 8,621 |
|
| 26.4 | 27.5 | -1.1 |
|
|
26H2 | 9,674 | 450 | 603 | 29.6 | 29.6 | 0.0 | -1.1 |
|
27H1 | 10,802 | 450 | 677 | 33.1 | 32.0 | 1.1 |
|
|
27H2 | 12,008 | 450 | 756 | 36.8 | 34.4 | 2.3 | 3.4 | 91.2 |
28H1 | 13,298 | 450 | 841 | 40.7 | 37.1 | 3.6 |
|
|
28H2 | 14,679 | 450 | 931 | 45.0 | 40.0 | 4.9 | 8.5 | 36.9 |
29H1 | 16,157 | 450 | 1028 | 49.5 | 43.2 | 6.3 |
|
|
29H2 | 17,738 | 450 | 1131 | 54.3 | 46.5 | 7.8 | 14.1 | 22.2 |
30H1 | 19,429 | 450 | 1242 | 59.5 | 50.2 | 9.3 |
|
|
30H2 | 21,239 | 450 | 1360 | 65.0 | 54.1 | 11.0 | 20.3 | 15.4 |
There is an anomaly between what the company says is their cost base and what their accounts say, but I suspect this is share-based-payments-related. Anyway, my model backs up the idea that the company will break into profitability in 2027. However, this doesn’t look particularly cheap at the current share price, even modelling out to 2030.
The only thing one can guarantee about a model is that it will be wrong. However, it does highlight that the company will need to find a way of either growing net flows faster than they have recently, or increase their cost base much more slowly to really grow into their current valuation, let alone justify a higher one. Their recent move into the US may provide these opportunities, but that is not yet proven, in my opinion.
Mark’s view
This is a decent growth company providing an important service. However, my analysis suggests they have been struggling to grow net flows by more than about £450m per half in the past few years despite client number increases. Unless this accelerates in the future, market performance will increasingly be the driver of their AUA growth, and hence they will be subject to much greater volatility in AUA. Their cost base continues to grow close to the revenue growth rates, and although a widening gap means they will break into profitability soon, it is less clear that they can grow the bottom line at a rate that justifies their current rating without growing net flows or cutting costs.
While this doubt remains, I think we need to maintain our neutral view of AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Thanks for the comments Mark on Costain (LON:COST) today.
I am not sure your comments on the profitability take sufficient account of the strong positive outlook from the company themselves, which you do not draw into your comments and which they have guided on in successive recent statements:
“Costain is now at a key inflection point where the strength of our growing, resilient end markets, strategic positioning with our customers and high-quality forward work position is set to deliver growth in H2 26 and a step change in our financial performance in FY 27 and beyond."
For me, this is a good reason to remain invested while making periodic top-chips to manage position size.
Saying of the week from the replacement Prime Minister - not Andy (he is not my mate!) Yes, he of the less factional politics. He said Water Companies should not treat Customers as blank cheques....
...but as to Govt and Tax payers -we wait with bated breath?
Pensionbee (LON:PBEE)
is the lack of profits not kinda amazon style tactic where they are simply pushing all the extra revenues into funding growth (marketing for pbee) at present so we shouldnt be expecting any better ? imho at present if marketing delivers extra customers it makes 100% sense to me to be maxing that marketing spend as far as you can right here right now,
i dont disagree with viewpoint that normally proof of the pudding is getting into porofits - there can be danger that one marketing spend it knocked back well tyou can go into reverse - i cant think of anything that should be more sticky than pension savings. so personally to me it makes sense they dont have profits yet.
Note marketing spend has increased from £8.3 mill to 11.3 mill - so that has been ramped up materially.
We increased UK marketing investment to £9.4m (H1 2025: £7.6m, up 24%). We deployed a multichannel, data-led approach that centred on brand investment, including partnerships and sports sponsorship to drive customer acquisition. For example, our Channel 4 Weather sponsorship, a highly repetitive format that puts the PensionBee brand in front of consumers multiple times a day, should reinforce both visibility and long-term brand trust.
I am no expect but i would say perhaps 50% of this advertising spend must be discretionary stuff/acquiring future customers - simply to onboard customers quicker - i would guess they could chop marketing 50% and the numbers would still trend forward nicely just not as fast - it just makes sense now to maximise all customers you can get while you can (whatever the cost as they will be uber sticky)
so if i remove 50% of advertsing costs as being "discretionary spending to acclerate income/customer acquisition" - well that would put them nicely into profit.
Am i being too generous here ? Look how many years AO World (LON:AO.) looked a basket case as they made no profits - reality is they were building scale - now they have built scale they have turned that scale into great profits.
So to me based on revenue increases its a green tick - note i dont hold this one at present on valuation grounds alone - but i kinda already give them credit that they are close to being able to make an easy £10 mill a year in 2-3 years time if they chose not to reinvest profits back in even more marketing - reality is they may carry on high marketing spend for many years.
Hi RM
Pensionbee (LON:PBEE) is one i have on the radar but do agree it looks too highly rated at present. Having worked most of my life in Pension Admin I am fully aware of the business and its aims to me do fill a need I have always seen as quintessential, so entirely laudable in a world where pension provision is still far too low profile. Yes I agree more marketing spend ( using the AO model is apposite) is likely given this is all about scale to offset fixed costs and stealing a march on any competitor given the moat is not that huge. As an aside on ' moats' whilst I gather the concept of Rentguarantor Holdings (LON:RGG) ( an old colleague just appointed NED) I have concerns like Pensionbee over the depth of the moat as to me the model could easily be adopted by others
Pensions tend to be more sticky business than other types of investment and aside from tax relief getting its annual kicking in the budget ( hard to see how HRTR stays given the Gov't need for cash to fund more Socalism ) I do see it as a growth area and PB at present near the forefront.....
From a consumer point of view... I'm not sure why anyone would transfer from their workplace pension out to Pensionbee (LON:PBEE) !
Their rates, for their default plan, starts at 0.7% for the first £100k, and then 0.35% for anything over that. That's quite exorbitant.
Most workplace pension providers are charging like 0.3% to 0.5%.
The default fund is a fund managed by Blackrock that "invests in 1000s of global public equities". Seems like the sort of generic fund that is available in any workplace pension.
So are PensionBee targeting money mugs who really are clueless about fees, and attracted to their fancy modern branding? And taking advantage of clueless individuals who don't know they can still keep pensions in their workplace scheme even after they leave? And those that don't bother to shop around for other pension consolidator providers?
If so.... there's definitely a group of customers like that. But don't forget the FCA hates companies that overcharge the "mugs", and retrospectively loves to investigate and slap big fines, always able to find "process deficiencies or customer communications deficiencies".
I definitely think there’s a regulatory risk here - pension transfers which their business model is based on has been synonymous with previous mis-selling. I’ve previously seen comments that people have transferred to Pensionbee (LON:PBEE) without actually knowing they’ve requested to. As you highlight they’re competing for funds with lower cost schemes that have greater economies of scale, more stringent governance requirements and probably lower costs of acquisition
Are they getting advice to transfer to Pensionbee (LON:PBEE) or are they following the AJ Bell (LON:AJB) model where transfers in are client led ?
I believe the bad feedback I saw was execution only. Not sure if they also work with IFAs
On Rank (LON:RNK) - my personal view is that additional taxes on gambling is a very high probability in the upcoming budget. Burnham has now ruled out the big tax levers, sticking to the manifesto. He's also ruled out cuts to the big tax spending areas (triple lock, NHS).
He was a very vocal critic of gambling as mayor of Manchester.
In fact, he's already come out with statements in the past week or two about letting local councils and cities have more control over gambling related premises. So this is still a topic very top of mind for him.
He was also DCMS Minister when the last big changes to the gambling regulations (Gambling Act 2005) were executed. Back then, he was at best neutral in his position on gambling. It also means he is actually quite knowledgeable about the Gambling Act.
What about Healey then? Not had anything public from him on gambling that is substantial, in recent past. Not a key area of focus for him is my guess. However, when he was in the Treasury as a junior, he was working in the team that was responsible for gambling duty. So he is also very familiar with the Gambling Act 2005.
As both of them scramble to put together a tax raising budget for October. They will both definitely be thinking about gambling - given they both are intimately familiar with the taxation regime and regulations. And also the fact that neither are strongly positive towards the industry.
-----
No wonder Rank has really flagged up this in their results today.
Whereas if you go back a year (before the RGD changes) to last year's statements, they barely mentioned that.
A lot more explicit, more fear raising, etc. Reading between the lines, my view is that Rank management view the MGD proposals as potentially more serious and damaging than the RGD changes.
Amaroq (LON:AMRQ) . Q2 Operational and Financial results out today and look pretty good to me. Certainly not a miner that fits the Mark Twain definition. Any chance of a view on this?
All the numbers going forward look promising.
European Green Transition (LON:EGT) (I hold)
Price 11p
Market cap £29.66M
A critical infrastructure and green services company.
It acquires profitable asset-light maintenance businesses, focuses heavily on wind turbine servicing, and targets major repowering pipelines.(concentrating on EBITDA profitable operations rather than speculative green developments).
2026 has been a breakout year for the company following a successful £7.5 million fundraise and a transformative wind energy acquisition.
Instead of owning capital-intensive wind farms or energy assets, European Green Transition (LON:EGT) acquires profitable, asset-light cash-generative businesses that handle operations, engineering, and maintenance.
Following the acquisition of its wind energy services business, European Green Transition (LON:EGT) now maintains and services approximately 1,000 onshore wind turbines across the UK. With many of these assets approaching 10 to 12 years of age, operators are increasingly looking to repower existing sites by replacing older equipment with more efficient technology, rather than developing entirely new projects. That trend is creating, what the company estimates, a £126 million qualified repowering opportunity within its existing customer base alone.
European Green Transition (LON:EGT) has recently guided to achieve £17 million to £18 million in total revenue for 2026, following strong early trading pertormance.
European Green Transition (LON:EGT) still holds legacy assets, such as the Olserum Rare Earth Element (REE) project in Sweden, which it intends to monetise or spin off to focus purely on infrastructure services.
In a recent presentation, the company announced that they are targeting £50M revenues in 2-3 years time and double digit EBITDA margins.
Michael Kearney (Non-Executive Director) has purchased in early June 500,000 shares at 10.2p.
Executive Chairman is Cathal Friel; Amryt Pharma (LON:AMYT^A22) and hVIVO (LON:HVO) were some of his recent successes.
On £50M revenues, European Green Transition (LON:EGT) should be an easy multibagger.
DYOR
All the best
Interesting option to look at for the adventurous. Edmund S's suggestion of Amundi MSCI New Energy ESG Screened UCITS ETF Dist (LON:NRJL) , following the dip, has worked for me too so far. In fact I added this AM!
Agreed. An interesting company. Worth mentioning the Anemos software application they effectively (79%) now own too. The application platform’s growth to 133 contracted turbines and the ambitions beyond wind, and whether condition monitoring work is opening doors to bigger repowering conversations with the same customers.
I hold, but have yet to multi - bag!
Looks a good fit for Renew Holdings (LON:RNWH) (I hold) who acquired Full Cicle Holdings based in the Netherlands with 24/7 monitoring of onshore wind turbines.
Thanks for the recommendation. I do look out for your comments as I value your insight.
UK GDP has just been released. The economy grew by 0.3% in June and by 0.4% in Q2. This is in line with expectations. The previous quarter had seen growth of 0.6%.
So if the population has increased by more than GDP growth, then the per person average has gone down. Why doesn't anyone raise this point? I suspect it would be an inconvenient truth.
It's been so for 20yrs? I thought life in UK was getting worse but I am just back from Sweden and Copenhagen and the good bits of the UK are good.
But not many of them anymore
and the good bits of the UK are good.
nice to here somoene saying something positive about the uk for a change - my area (north east is menat to be most deprived region of england) isnt too bad - went to liverpool the other week for the foo's and the place seemed booming. I dont deny poverty exists and its a struggle to make ends meat at teh bottom - but the masses and media and half a bunch of whingers. I remeber leabing college back in the early 90's - at that time unemploym ent rates in late 80'sa and early 90's are double what they were now with minimum wage - now we have minimum wage that is going up - maxmium forced working hours - less unemployment (compared to back in the day) - plenty of people getting nice inheritances and we are still moaning as a bunch - our forefathers (and ladies) who gave their lives for our freedom - not moanming and bitching would not be impressed with those that only ever moan and gripe - despite day to day life being a million times easier than it was.
i kinda find it ironic that in my neck of the woods on a friday and saturday back in the day it was the young uns out having fun with the old uns at home moaning about life now the old uns are out having fun and the young uns are sat at home moaning that they arent given everything on a plate times have changed.
Happy days growing up in the NE. Good honest hard working people. We lived for the weekends, football and nights out with 80s music as our soundtrack.
Happy days I'm gen x also, fond memories of mega huge nightclubs back in the day (sadly nearly all gone now) and boozing on hot summer nights from Thursday- Saturday.
We didn't have mobiles in the late 80's or early 90's or streaming or broadband so guess it felt we were better off then as less things were classed as monthly essentials.
Mega night clubs long gone in London. I think Ministry of Sound may still be going?? and i think theres something called Drumshed….only if you dare! Don’t forget the Sunday night boozing too. I remember driving a hot hatch and my pal with a brick of a phone and him being called a weirdo!! And The Phoenix we weren’t flooded and pumped with others opinions constantly via media without having time to take a breath and think about what is being said.
thats a good point - i asked chat gpt and it seemed to say theer was two stats that are both 0.4% (perhaps oddly) - gdp and real gdp per head (i havent fact checked chat gpt)
l do you really expect the new intake to be adding much to the economy - thats the issue taking in who we do you cant expect them to be outperformers as things stand kinda the opposite.
Note i am shooting from the hip here perhaps the press have got to me into biased viewpoint - i ssupect the sneaking suspicion is right though.
also well look at who is leaving - if the big earners are leaving well is that gonna help ? someone may take their place perhaps.
Overall its pretty obvious huge net inflow of people who are much more likely to be on benefits and or making lower than average wage - aligned with outflow of high earners give us some headwinds ref the stats.
Be aware that knocking Britain is straight out of the populist playbook: ignore the good points, focus only on the bad points, destroy confidence in politicians and traditional media, claim to have the solution (even though it's simple and won't work) - and get the gullible to vote for you, even though you know it's not in their best interests to do so.
The truth is that the UK has some great companies, world leaders in some spheres, competing well in others. Stockopedia helps to highlight some.
Fact is that whilst there are some great companies in the UK there are many less than there were. Listing here is unappealing for the sort we really need (Revolut, ARM). As Wriston said: 'Capital will go where it is welcome and stay where it is well treated'. The UK, regardless of political preference, could and needs to do better in this as our relative decline to others bears testimony.
i wasn’t going to post this, I chickened out twice! Opening piece in the Spectator Magazine called Labours inheritance (25th July 2026) I found really interesting. The piece talks about when this Labour government took over from the previous government compared to when Thatcher took over from the previous.
It is in the body of the report:
"Real GDP per head is estimated to have increased by 0.4% in Quarter 2
2026 and is up 1.0% compared with the same quarter a year ago."
They don't say on what population that's based upon.
I was wrong, it's based on an estimated population of just under 70M! A figure that is disputed.
Costain (LON:COST) Good results this morning and sp now at post 2019 high. Presentation about to start https://www.costain.com/invest...
Much talk of potential in water market:
They are pushing Capital Markets Day 19/11/26
Only HL could add a feature called "quick trade" which actually slows down the process of trading shares for most of their customers. A creaking tech stack and poor customer insight is not a good look imo.
HL . Sadly they have lost some of my business having been a loyal and previously satisfied customer for many years despite higher-end fees.
Same here.
I closed my accounts with hl and moved to better providers when they raised their charges.
Ive been looking into moving, potentially to T212 and/or IG. Thoughts?
I find T212 really easy, very cheap. They now do SIPP. Need something else for research.
T212 were covered in money mail review recently. broadly positive.
Vastly reduced charges (NIL) on some trades. Don’t have all the European coverage if you trade in Finland, Italy etc but cover is still good. Email communication only but they are swift. Actual platform is a little clumsy & muddling at times but overall I’d say worthwhile, although I do use two other platforms in order to gain access to a wider marketplace.
Yeah I found they are cheap, although they dont use RSP and like you say some stocks are missing (some AIM stocks for instance).
That why I was thinking IG for AIM or less liquid stocks. Then T212 for anything else. As I think IG are also pretty much £0 fees.
Departed to II a few months ago
There is nearly as much to ii as there is to Stocko. Enjoy.
I recently complained to them re them using offer/buy prices to value my ISA pf. Despite me sending them screenshots proving it, they waited until they had corrected their mistake and then told me they didnt and that I was wrong.
Graham, Costain (LON:COST)
Today's H1 2026 interim update appears to deliver a solid, in-line update that validates the ongoing margin transformation with no non-underlying operational surprises. I am heavily moved into Industrials this second half, so would be great to get your thoughts.
Revenue up and H1 marks the transition trough with acceleration expected in H2 with key projects (AMP8 water physical build, M60 works, Heathrow expansion.) Aligns with FY26 consensus run-rate of £1.23bn–£1.27bn.
Adjusted PBT of £19.2m keeps them on track for FY26 consensus PBT of £50.5m–£53.4m, and on track for medium-term margin targets of ~4.0% in FY26 and 5.0% in FY27+
Interim dividend doubled (+100%) to 2.0p. Target dividend cover lowered from 3.0x to 2.5x.
Balance Sheet tracking ahead of consensus year-end trajectories and Order Book remains at at a record £7.0bn, securing 91% visibility for FY26 and FY27 consensus revenues.
No apparent non-underlying adjusting items; reported metrics match adjusted metrics exactly (£17.3m / 5.7p EPS). Brokers model a heavily H2-weighted year (~67% of FY EPS).
Would be good to get a view on H2 Operational Execution and the execution risk of the steep H2 revenue and EPS weighting (~67% of full-year EPS). Also the scalability of the consulting/complex engineering mix required to hit the 4% FY26 and 5% FY27 margin targets ?
Costain (LON:COST)
cheers lumped on - at face value without looking for nasties company looks in a reasonably sweet spot at present - looks like they have avoided any major nasties last few years looking at the numbers on stocky.
If we simplify things down - all we really need is no nasties and confident outlook - with order book that looks healthy - you really want to be partners with people you work for in this sector and it all looks reasonable ref have decent diversified customer types.
Maintained record £7bn forward work, visibility over 91% of FY 26 and FY 27 forecast revenue
Costain continues to secure further significant strategic programme awards and extensions to existing contracts and enjoys good visibility on future work. As at the end of H1 26, our forward work position, which is our combined order book and preferred bidder book, was maintained at a record £7.0bn (FY 25: £7.0bn; H1 25: £5.6bn), an increase of 67% over six years and representing almost seven times our FY 25 revenue. When combined with the revenue delivered in H1 26, it includes £1.1bn of revenue for FY 26 and £1.3bn of revenue for FY 27, equivalent to 91% of consensus forecast revenue in both years. Our order book stood at £3.5bn at period end (FY 25: £3.6bn; H1 25: £3.4bn) and the preferred bidder book stood at £3.5bn at period end (FY 25: £3.4bn; H1 25: £2.2bn).
As a result of our strategy, we have an increasingly diversified forward work position. Private and regulated customers now comprise 48% (FY 23: 30%) of the forward work, 23% (FY 23: 6%) is with devolved government customers, and 29% (FY 23: 64%) is with central government customers. The diversity of our forward work position continues to build, with additions in H1 26 coming from target growth segments such as electricity transmission (National Grid), reservoir programme management work (Thames Water and Anglian Water), devolved authority rail (TfL) and port infrastructure (Port of Dover)
If i have looked at this company before its not jumped out as being great canbdidate to invest in but it seems well run outfit and with close to 10% growth this year and next expected on average based on stocky net profit should be enough to get the job done ref backing up share price rises as reflecting better time. Plus they have cash in the bank (as one should do when one is large contractor as customers need to know you have the finances to deliver long term projects) - for contractor p/e aint cheap on this years earnings at 14.3 - but that drops to 12.7 based on 2027 numbers - we are only 5months away from being into 2027 - so with foward work looking sound if you ignore the h2 weighting all looks pretty tickety boo. Stock ranks in the 90's seem to back up this is a decent outfit working in a tough sector.
Perhaps in this sector at present there isnt as much appetite for bidding low to get volumes as their was back in the day , thats got to be good for tehn companies that are left - i would guess most contracts only want the work if it makes reliable margins - back in the day it seemed to be landgrab for turnover with any potential nasties hidden out of sight for as long as possible (hmm why does vistry spring to mind here ?).
just for interest, I started on Costain (LON:COST) in June this year as part of a rotation away from Consumer Discretionary and into this general area. However this week it came up in my "Coiled Spring" screen ahead of results so I took the plunge and doubled up. So far am happy, but this is a long-run play for me.
The screen works as follows, and you can flex the "Price Chg 1m" in & out to see if you find anything. Give it a spin and let me know what you think - I am also using it on US stocks on my "gambling"side!
Screen Name: Coiled Spring
1. Country: INCLUDES :
2. Primary Listing: EQUAL TO 1
3. Market Capitalisation GBP: GREATER THAN 50m
4. Average Volume 3m: GREATER THAN 50000
5. Stockopedia Quality Rank: GREATER THAN 70
6. Piotroski F-Score TTM: GREATER THAN 6
7. Altman Z-Score TTM: GREATER THAN 1.8
8. Relative Strength 1y: GREATER THAN 0%
9. Absolute Price Change 1m: GREATER THAN -3%
10. Absolute Price Change 1m: LESS THAN 6%
11. Price vs 52w High: GREATER THAN -15%
12. Stockopedia VM Rank: GREATER THAN 75
13. Discount from Broker Price Target: LESS THAN -8%
Love the screen name.
Worth comparing Costain (LON:COST) with Kier (LON:KIE) - both doing very well at the moment and reaching highs for the year also Galliford Try Holdings (LON:GFRD)
And Keller (LON:KLR)
Yes Keller is in a different sector but also doing well - Its ex divi today - down 24p but the divi is 28p. May be worth waiting a day or two to top up ?
US CPI data passed without incident... and was fairly dull which im sure was a relief. Actually I would argue a monthly rise of 0.1% is ok - and annualises well below target - although it does little to reduce the current 12 month number. So bears get to say 12 month inflation remains too high and bulls can argue it's falling, nothing to see. Bond markets didn't move much which suggests the market thinks the Fed can continue to hold...which is better than a forecast rise. That makes two good months and leaves the Fed in an ok position for now. Obviously the market will continue to looks for evidence of pressure building and the most visible symbol of this seems to be oil for now....which isn't doing much... reflecting the stand off in negotiations. At least the last month wasn't strong which would not have gone down well.
Secure Trust Bank (LON:STB)
I originally bought this as a bit of a punt - it was cheap as chips on p/e and seemed to have clarity ref ditching sketchy car financing - and concentrating on much plainer less risky loans - often partnering with retail ers do their customer la can buy products on tick - nothing is no risk but this seems low risk activity - someone with decent credit history is rarely gonna default ok a loan to buy their dream bike.
I can’t really find any negatives in today’s update - if they are there they gave passed me bye - everything seems fine and dandy with their plan of making the quality metrics and efficiency better - whilst maintaining growth seem fully on track.
Warning money lending can be like the wild west with regulators being being able to cause chaos at will - as far as i can see from todays update it all seems fine. Note there is the issue with historic car claims still - at present though the company is sticking to its guns ref current provisions - there could be one off material uplift ref this provisions if final settlements needed are at higher provided levels - anyone thinking of buying would need to dyor ref that item - at present that’s very much peaked awaiting final terms to be set by fca.
I agree with you , good solid results from Secure Trust Bank (LON:STB) . Be keen to hear what Graham etc think of this one.
Its a high holding for me as I feel the risk is low and that mangement time and resourse can now go into creating more profitable growth without that Car Leasing taking up their time and capital. This might not happen for a while though but its in for free.
Good afternoon gentlemen, Secure Trust Bank (LON:STB) I scan read these results early this morning and didn’t see anything immediately alarming. I started building a position this time last year because I wanted a financial in my portfolio. I also began building a poistion in Banco Santander S.A. (LON:BNC) last February last year and both seem to be doing okay. I too look forward to Grahams thoughts as my expertise in analysing financial companies isn’t great!
Secure Trust Bank (LON:STB) basically one can sum up the investment case in this by next years EPS forecast rise of 29%. What they are saying is what a few of us have pointed out and that is without the Car Leasing they can concentrate on other more profitable activities. Note that forecast hasn't been updated for some time.
Financials can be difficult to invest it as they can be complicated to understand (looking forward to Graham helping us out on that all important balance sheet) . Warren buffet famously said don't invest in anything that can't be manged by an idiot, as eventunatly that who will mange it. The advantage though is they can quickly growth if in the right area and manged well. These guys have at least done the hard part and repositioned the Co for growth going forward so they get my vote for now.
All IMHO
(why I have so many of these is the question Im trying not to think about right now!)
Thanks to Graham for covering Secure Trust Bank (LON:STB) . I can't see the catch either.
you're very welcome, oaktree!
Thanks Graham! Secure Trust Bank (LON:STB) your opinion is very much appreciated. Have a good weekend all.