Daily Stock Market Report (Thur 15th Jan 2026) - SRB, PMI, HSW, FOXT, DNLM, BOOM, MPAC, NWT, ABDP, DFCH

Good morning, I'm expecting another large set of updates today!
That will do it for today, cheers!
Spreadsheet accompanying this report: link (updated to 16th December)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Schroders (LON:SDR) (£6.73bn | SR83) | Annual results for 2025 are expected to be ahead of market expectations on adjusted operating profit. AOP of at least £745 million (FY24: £603.1 million). Group AUM of c. £825 billion including joint ventures and associates (FY24: £778.7 billion). | ||
Lion Finance (LON:BGEO) (£4.16bn | SR84) | CFO has decided to step down after 20 years with the company. His successor was CEO of Moldova’s largest bank, maib. | ||
DCC (LON:DCC) (£3.8bn | SR96) | Agreement to acquire UGI International LLC's liquid gas businesses in Poland, Hungary, Czechia and Slovakia. Enterprise value €48m. | ||
Taylor Wimpey (LON:TW.) (£3.68bn | SR83) | UK home completions excluding joint ventures in the middle of guidance range. Revenue £3.8bn (2024: £3.4bn), operating profit c. £420m (2024: £416.2m). Outlook: uncertainty ahead of the late Autumn Budget impacted sales in H2 2025 and order book coming into 2026. “We are experiencing a good level of enquiries consistent with last year.” | ||
Dunelm (LON:DNLM) (£2.36bn | SR83) | H1 PBT expected to be approximately £112m - £114m. FY26 PBT now expected to be at the lower end of consensus expectations (£214 - 227m). | BLACK (AMBER =) (Mark) [no section below] | |
Rathbones (LON:RAT) (£2.18bn | SR74) | Funds under management and administration increased 2.3% in Q4 to £115.6 billion. Net outflows £0.5 billion. | ||
Safestore Holdings (LON:SAFE) (£1.68bn | SR91) | Revenue +5% (constant exchange rates). 3.1% LfL growth. Operating profit down 62.6% to £159.3m due to lower property revaluation gains. Net assets £2.3bn. FY 2026 outlook: cautiously optimistic with a return to earnings growth. | ||
Mitchells & Butlers (LON:MAB) (£1.65bn | SR96) | LfL growth 7.7% over core 3-week festive period. Quarterly LfL sales +4.5%, “well ahead of the market”. “… we remain confident in our ability to manage the c.£130m of year-on-year cost headwinds we expect to face this financial year, driven primarily by increased labour costs and food cost inflation.” | ||
Savills (LON:SVS) (£1.49bn | SR61) | 2025 growth at least in line with expectations. “…While market uncertainty is expected to remain elevated in 2026, the Board believes that strong pipelines and strengthening investor and occupier sentiment will support recovery across our core transactional markets.” | ||
Great Portland Estates (LON:GPE) (£1.33bn | SR27) | Another strong quarter of leasing, with market lettings 9.1% ahead of the March 2025 ERV. “We head into the final quarter with positive momentum… With a robust financial position and best-in-class team, GPE is well placed to drive attractive shareholder returns." | ||
Ashmore (LON:ASHM) (£1.3bn | SR57) | AuM increased by US$3.8 billion (+8%) over the period (Q2), comprising net inflows of US$2.6 billion and positive investment performance of US$1.2 billion. | ||
Oxford Instruments (LON:OXIG) (£1.24bn | SR73) | Reconfirms its full-year outlook, with reported adjusted operating profit anticipated to be in line with market expectations. Consensus for FY26 reported adjusted operating profit ranges from £70.2m to £73.0m, with a mean of £71.8m. Year-to-date book-to-bill ratio 1.2. | ||
Glenveagh Properties (LON:GLV) (£870m | SR79) | 2025 revenue +7%, operating profit +9%. EPS +18% (20 cent). For 2026, the Group is guiding EPS of up to 21 cent, reflecting continued growth in completions, the ongoing contribution from Partnerships and disciplined cost control. Forward order book of approximately €1.1 billion (2024: €0.95 billion). | ||
Raspberry PI Holdings (LON:RPI) (£558m | SR21) | The Raspberry Pi AI HAT+ 2 is an add-on board for Raspberry Pi 5, expanding the Company's on-device AI capabilities. | This is a Reach announcement, i.e. a non-regulatory press release. | |
Advanced Medical Solutions (LON:AMS) (£487m | SR53) | Full year 2025 revenues of approximately £228.5 million (2024: £177.5 million), EBITDA of £49.5 - £50.0 million (2024: £40.2 million), and the Board is confident of meeting market expectations. | ||
Caledonia Mining (LON:CMCL) (£466m | SR83) | $100m notes to be offered in a private placement, plus an optional $20m. Using a capped call to hedge the associated risk. | ||
Fuller Smith & Turner (LON:FSTA) (£381m | SR95) | Trading statement for 41 weeks to 10th Jan 2026. Like for like sales for the year to date up 5.3%. There was “an excellent Christmas trading period”. As the previous buyback programme completes, the Board has approved a buyback for up to an additional one million “A” shares. | ||
DeFi Development UK (LON:DFDV) (£375m | SR4) | Non-Exec Chair and a new CFO have been appointed. | ||
VAALCO Energy (LON:EGY) (£324m | SR89) | 2025 sales 22,100 WI BOEPD, at the top of its guidance range of 20,800 to 22,200 WI BOEPD. Increased cash at bank by nearly $35 million to $58.8 million. | ||
Anglo Asian Mining (LON:AAZ) (£318m | SR56) | Q4 Copper production +94% Q-o-Q to 4,439 tonnes, due to increased production from both Gedabek and Demirli. FY Copper production of 7,915 tonnes was lower than the revised guidance of 8,100 to 9,000 tonnes. Gold production of 25,061 at the lower end of the revised guidance of 25,000 to 28,000oz. Net cash inflow in Q4 2025 of $16.7m. Net cash $2.5m. | ||
Ab Dynamics (LON:ABDP) (£308m | SR54) | Expects to deliver FY26 adjusted operating profit in line with current expectations (of £24.5m). Net cash £35.5m. "Whilst mindful of any short-term macroeconomic disruption driven by geopolitical events, the Board remains confident that the Group will make further financial and strategic progress this year..." | AMBER = (Graham) [no section below] | |
Essentra (LON:ESNT) (£275m | SR39) | FY Revenue flat (+2.5% CCY LFL), expects adj. Op profit for FY25 to be in line with market expectations (of £32.0m to £32.4m). FY25 pre-IFRS 16 net debt leverage guidance is unchanged and is expected to close within the targeted leverage range of <1.5x. | ||
Serabi Gold (LON:SRB) (£261m | SR99) | Q4 production 11,534 ounces, +15% on Q4-2024. Net cash 31 Dec $42.1m (Q3: $33m). Annual production of 44,169 ounces, representing a 18% increase vs FY2024 2026 consolidated production guidance of 53,000 – 57,000 ounces gold. | AMBER/GREEN = (Mark) | |
Brooks Macdonald (LON:BRK) (£257m | SR55) | 26Q2 FUMA +3% to £20.1bn, Net inflows £50m, market performance £0.5bn. | ||
Mkango Resources (LON:MKA) (£190m | SR21) | Official launch of the rare earth magnet facility today at Tyseley Energy Park. | ||
Foxtons (LON:FOXT) (£168m | SR56) | Revenue +5% to £172m, Adj. Op Profit flat at £22m, Net debt £17m (FY24: £12.7m). Acquires Cauldwell, a leading independent agent in Milton Keynes, for a total enterprise value of £6.5m on a cash and debt-free basis. “The Group expects to deliver revenue and profit growth in the year, underpinned by non‑cyclical and recurring Lettings revenue.” | BLACK (AMBER ↓ ) (Graham) The broker note from Panmure Liberum confirms that the FY26 profit forecast has been cut by 3%, and FY27 cut by 14%. I will cautiously take a neutral stance on this stock today. The valuation is not expensive, but I would be nervous if it was. Rather than valuation, the bigger concern here is just the lack of growth and the uncertain outlook for London property. I have an open mind on this one and would be happy to upgrade our stance again in due course. But given that this is a profit warning (although the RNS didn’t explicitly say so), I’m neutral for now. | |
Cab Payments Holdings (LON:CABP) (£168m | SR39) | FY Total Income expected to be c£119 million, Adj. EBITDA expected to be slightly above the range of consensus estimates (of £33.8m). | ||
Hostelworld (LON:HSW) (£145m | SR25) | H2 Revenue +7% (+2% bookings, +5% Average Booking Value). FY Revenue +2% to €93.8m, Adj. EBITDAv€19.9m, in line with market consensus. Net debt €1.6m. | GREEN ↑ (Graham - I hold) I'm upgrading my stance on this as I've had a chance to cool down since the announcement of an acquisition in October. I still think this is a very interesting situation and I'm open to idea of adding to my position. It's rare to find successful online platforms trading so cheaply, in my experience. | |
Audioboom (LON:BOOM) (£137m | SR46) | Revenue +10% to $80.4m, Gross Profit +18% to $17m, Adj. EBITDA +54% to $5.1m, ahead of expectations. Cash $4.2m (FY24: $3.9m). | AMBER/RED = (Mark) [no section below] | |
Savannah Resources (LON:SAV) (£123m | SR30) | “Following approval of the State Grant, Savannah expects the formal signing of the related investment contract to take place before the end of next week.” | ||
Diaceutics (LON:DXRX) (£120m | SR48) | Revenue +20% to £38.5m in line with expectations, Adj. EBITDA expected to exceed analyst consensus estimates. Expects +ve profitability. Expects to deliver 25% revenue growth in FY 2026. | ||
Trufin (LON:TRU) (£116m | SR77) | Adj. PBT to be ahead of previously guided expectations, now expected to be more than £7.4m, (FY24: £0.9m). Adj. EBITDA is expected to be in excess of £11.8m (FY24: £7.6m). Group revenue is expected to be approximately £63.0m (FY24: £55.0m). | ||
Robert Walters (LON:RWA) (£98.8m | SR75) | Net Fee Income -14% YoY, Net cash excl leases £26.2m (30 Sep: £26.6m). | ||
MPAC (LON:MPAC) (£97m | SR22) | FY revenues £170m (FY24: £122.4m), U/L PBT in line with market expectations of £13.5m (FY24: £10.5m), Order Book flat, Net debt excl. leases £47.7m (30 Jun: £43.2m). | AMBER = (Mark) | |
Premier Miton (LON:PMI) (£95.4m | SR69) | AUM -7% to £9.6bn, Net outflows £870m, market performance £103m (+1%). | AMBER ↓ (Mark) | |
Distribution Finance Capital Holdings (LON:DFCH) (£91.7m | SR68) | SP +5% Loan book up 27% on the prior year (FY2024: £666m) and ahead of previously guided range of £750m-£800m. Adjusted pre-tax profit of at least £17.5m, up 22% on prior year. Meduim-term targets for 2030, which are additional to the previously announced 2028 targets: loan book >£1.5bn, cost to income ratio 45%-48%, return on required equity c. 20%. Expects to fund growth internally without needing to raise equity. | GREEN = (Graham) [no section below] We've been consistently postive on this one, even in October when the outlook was merely "in line" for 2026, despite 2025 having previously been upgraded. Panmure are now forecasting underlying PBT of £19.4m for 2026, which is slightly higher than the £19.0m they suggested in October. Although profit growth may have paused in the short-term, the overall size of the business continues to take great leaps forward with the loan book up by an enormous 27% year-on-year. Whenever this translates into operating leverage, we should see very significant earnings growth. In the meantime, the shares are still trading below tangible net assets of 75p (latest share price: 59p). | |
Alumasc (LON:ALU) (£89.4m | SR70) | Pamela Bingham appointed Chief Executive Officer. | ||
Pebble (LON:PEBB) (£66.2m | SR92) | Revenue flat at £125m, Adj. EBITDA -5% to £15.8m. Cash of £9.6m (FY24: £16.5m). In line with expectations. | ||
Likewise (LON:LIKE) (£62.7m | SR51) | FY Revenue -8.6% to £163.8m. “The Group is on track to achieve current market expectations of Profit Before Tax for FY25 with further meaningful growth in profitability anticipated in FY26.” | ||
Agronomics (LON:ANIC) (£58.9m | SR40) | Agronomics will invest the AU$3m (c. £1.5m) in All G via convertible notes, to bring their holding up to c5%. | ||
Abingdon Health (LON:ABDX) (£16.3m | SR9) | H1 Revenue +45% to £4.5m, Cash £2.6m (30 Jun: £1.9m) after £3.2m net raise. Maintaining its revenue guidance for FY26, including grant-funded income, in line with market expectations of £12.6m. | ||
Titon Holdings (LON:TON) (£11m | SR70) | Revenue +2% to £15.8m, U/L EBITDA £811k (FY24: £5k), U/L operating LBT £40k (FY24: £916k). Cash £3.5m (FY24: £2.3m). Trading in the first quarter of FY26 was in line with the Board's expectations. | ||
Newmark Security (LON:NWT) (£10.6m | SR86) | H1 Revenue +13% to £11.6m, Adj. EBITDA +100% to £1.0m, Operating Profit £0.1m (25H1: £0.3m loss). £4.0m net debt (25H1: £3.8m net debt). “H2 FY26 has started strongly and currently expects both divisions to surpass H2 FY25 revenues and operating profits”. | AMBER/RED (Graham) [no section below] I once owned shares in this, a long time ago, but eventually lost interest. As a group it does look interesting with cloud-based workforce security software and a wide range of physical security products. As an investment, however, it has never managed to convert revenues into profits which it could then reinvest for compounded growth. The stock has been listed for over 20 years at this stage, and it has had the same CEO (the founder/Chairman's daughter) since 2013. Today's outlook statement suggests that the company could make a profit this year to surpass last year's £0.7m, but I'm going to take a moderately negative stance to reflect the very long history attached to present management. |
Graham's Section
Hostelworld (LON:HSW)
Up 1% to 118p (£147m) - Trading Statement - Graham - GREEN ↑
(At the time of writing, Graham has a long position in HSW.)
Yesterday Roland covered Nichols (LON:NICL), which is probably the least exciting share on my annual watchlist (its update was in line with expectations).
Hostelworld is a new entrant to my watchlist, and a share that I own personally.
Thankfully, this is also an “in line” update from the online travel platform.
Let’s extract some key points:
H2 revenue +7%
2% increase in number of bookings, 5% increase in average booking value
Average booking value has been trending downwards in recent years, so this is a nice reversal.
Continuing:
Commission rate on bookings has increased to 16.7%, thanks to the “Elevate” tool which lets hostel operators pay more for increased visibility on the site.
Marketing as % of revenue fell from 48% in H2 2024 to 45% in H2 2025.
As for the full-year numbers, they are slightly less impressive than H2:
Net revenue +2% to €93.8m, which I think is below expectations.
1% reduction in number of bookings, 2% increase in average booking value.
Adjusted EBITDA €19.9m, in line with expectations.
I’m happy enough with these results: hopefully the momentum from H2 continues into H1 of 2026.
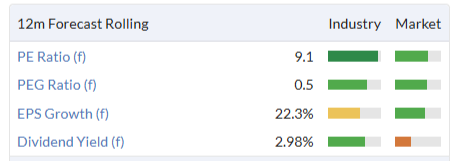
Cash: €12.2m cash, net debt €1.6m. They’ve completed most of their £5m share buyback. I accept that buying back their shares is a little aggressive, but I think they can afford it given their current profitability. The StockReport shows an after-tax net income forecast of €16.1m for 2025, rising to €19m for 2026.
At the current valuation, I do think they are getting good value for their buyback activity!
“Growth roadmap”
They reiterate the rationale for their $12m purchase of OccasionGenius:
The acquisition marks an important evolution of the Group's social travel platform, enabling integrated event discovery with its existing social and accommodation offering.
In other news, they now sell access to their social network even for travellers who haven’t made a booking.
Not sure if that will be able to compete with Facebook or other free options, but I guess it can’t hurt!
And they’ve also expanded to accommodation options beyond just hotels (e.g. budget hotels).
So I don’t think it’s fair to say that management has been standing still - there have been plenty of initiatives over the past year. Let’s hope that a few of them are successful!
Management remains confident that the additional capabilities delivered during 2025 - including social monetisation, budget accommodation, and the OccasionGenius integration - will strengthen the platform and support long-term value creation.
Graham’s view
Obviously I’m bullish on these, seeing as I own it personally and I added it to my watchlist. At the moment the stock is only worth 1% of my portfolio, and I’m wondering if I should add to it.
I just think it’s very rare to find an online “platform” business like this, with a well-defined niche in which it is successful, and a well-known consumer brand, which is available at such a low earnings multiple.
Weaknesses? Well, revenue growth hasn’t been as strong as it perhaps could have been.
The $12m acquisition is still up for debate in my view, as to whether it represents good value. The business they bought only had a few employees, but Hostelworld says that it will speed up their progress significantly (connecting travellers with events).
The balance sheet could be a little stronger, too. It’s a balancing act because I also think that buybacks at this valuation are good for shareholders. Hopefully we will see the cash position improve during 2026.
Overall, I’m still a strong believer in this one. I’m going to upgrade my stance on this to GREEN from AMBER/GREEN, now that I’ve had a chance to reflect and calm down since October!
The share price has made little gains since 2021-2022, but it's a vastly more attractive proposition now than it was then, in my view.
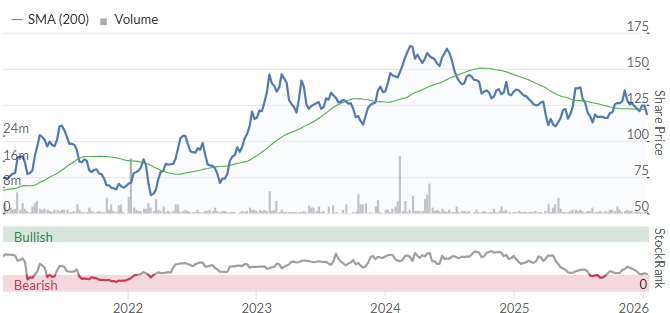
At the end of 2022, the share price was 115p, only a few pence lower than it is today.
- Year-end 2022: revenues €70m, loss making, net debt €13m.
- Forecast 2026: revenues €107m, adjusted net income €17m-€19m, and it's expected to have net cash.
Foxtons (LON:FOXT)
Down 6% to 53.4p (£157m) - Unaudited Year End Trading Update and Acquisition - Graham - BLACK (AMBER ↓)
Foxtons Group plc (LSE: FOXT).. provides an update on trading for the year ended 31 December 2025, together with the acquisition of Cauldwell Property Services Ltd, expanding its presence into the fast-growing commuter town of Milton Keynes and further advancing the Group's growth strategy.
The market was a bit cold on this announcement:
Revenue +5% versus prior year to c. £172m. (this looks like a miss against £174m expected.)
Adjusted operating profit c. £22m seems approximately in line.
Lettings were 64% of revenue.
HQ relocated, bringing £1.5m of cost savings to offset inflationary pressures.
£5.5m of buybacks and £3.6m of dividends - not to be sniffed at with a market cap of only £160m.
Estimates: thanks to Panmure Liberum for commenting on this today.
The note from Panmure confirms that FY25 revenue missed expectations and FY25 profits were in line.
Looking ahead, they have adjusted their forecasts as follows:
FY26 revenues reduced from £185.7m to £180.2m
FY 26 EBIT reduced from £28.5m to £23.1m.
FY27 revenues reduced from £195.3m to £190m
FY 27 EBIT reduced from £31.4m to £27.1m.
Net debt at December 2025 was £17m and it’s expected to be at a similar level at the end of 2026 (£15m, according to Panmure).
This is largely because of the acquisition announced today:
On 7 January 2026, the Group completed the acquisition of Cauldwell, a leading independent agent in Milton Keynes, for a total enterprise value of £6.5m on a cash and debt-free basis, of which £0.8m is deferred for 12 months and contingent on performance targets being met. Cauldwell's unaudited total revenue and operating profit for the 12 months ended 30 November 2025 was £3.1m and £0.8m, respectively. Approximately two-thirds of total revenue is attributable to Lettings.
Outlook: conditions are difficult.
Sales began 2026 with a lower under-offer pipeline than the previous year, as a result of the significant sales market disruption around the Autumn Budget and a very strong comparative period in Q4 2024 (ahead of the March 2025 stamp duty deadline). Due to the lower under-offer pipeline, Q1 2026 Sales revenues will be lower than those recorded in Q1 2025. When the sales market normalises, we expect a more stable market backdrop, with transaction volumes to benefit from recent mortgage rate reductions and the release of pent-up demand.
Graham’s view
I do wish that forecasts could be included plainly in RNS trading updates, rather than in broker notes - there is no law preventing companies from doing that! But this is how most companies operate.
Based on the Panmure broker note, this update is a profit warning.
The FY26 profit forecast has been cut by 3% and the FY27 profit forecast has been cut by 14%.
The Cauldwell acquisition is interesting but is not really the headline here, in my view. The headline is that the sales market around London has been under some pressure, and that the growth forecast has been greatly diminished as a result.
The FY27 forecast, in particular, has been reset at a significantly lower level.
I will cautiously take a neutral stance on this stock today.
The valuation is not expensive, but I would be nervous if it was:
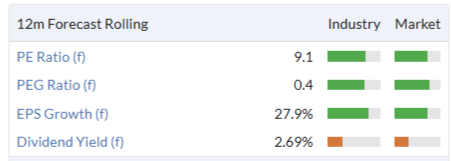
Rather than valuation, the bigger concern here is just the lack of growth and the uncertain outlook for London property. The acquisition announced today, while not making an enormous difference to the overall picture, does slightly increase the risk - perhaps the sellers have read the tea leaves better than Foxtons are?
I have an open mind on this one and would be happy to upgrade our stance again in due course. But given that this is a profit warning (although the RNS didn’t explicitly say so), I’m neutral for now.
Mark's Section
Serabi Gold (LON:SRB)
Down 2% at 338p - Reports Q4-2025 Production - Mark - AMBER/GREEN
I never like it when a company puts a lot of promotional text in the RNS headline, it gives the feeling that they are trying too hard to overcome a weakness somewhere. Last year’s RNS title, “Q4-2024 Production Results and Operational Highlights”, becomes “Reports Q4-2025 Production, Record Annual Production, Production Guidance Achieved & Operational Highlights” this time.
The company is choosing to highlight the record annual production. However, I think shareholders may be a little disappointed with Q4 production. Coringa performed well delivering slightly higher production, but lower grades at Palito meant that production was back to Q1 levels. The net results was that Q4 was below Q3 production, and slightly below recent trends:
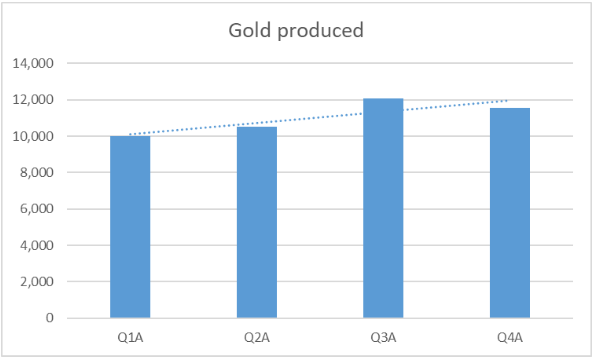
They also highlight that they achieved production guidance, which is true. But at 44,169oz, this is very much at the lower end of the guidance range of 44,000 – 47,000oz that they started the year with.
So when they give us 2026 production guidance of “53,000 – 57,000 ounces gold” my assumption would be that they will deliver closer to the bottom end of that. This is still 20% higher than 2025 production, which is a strong performance, if delivered.
There is also good news on the cash front:
The Company had a net cash balance at the end of Q4-2025 (after interest bearing loans and lease liabilities) of $42.1 million (31 December 2024: net cash $16.2 million).
Plus, shipping delays meant they didn’t receive $5.1m of payments until post-period end. Although this is an ops update and such things are not always mentioned, I would have liked to see some commentary on what they will do with this cash. There is a dividend forecast of 12c for when they release final results. However, gold miners are always always spotting something shiny out of the corner of their eyes which they want to buy rather than return cash to shareholders.
I can model what this production looks like based on the average gold price during the quarter, and keeping costs from Q3 similar:
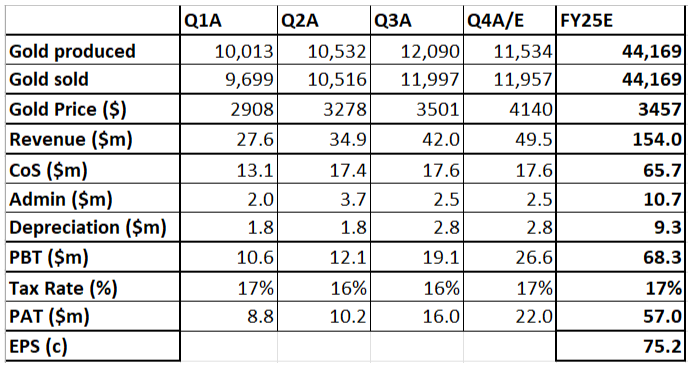
This still looks to be a handy beat on the $147m revenue and 65c EPS forecast in the StockReport. Although, this is almost entirely down to gold price strength rather than operationally exceeding expectations. Tax is a big unknown as they have been paying less than the headline rate and I have assumed similar rates for Q4. Long-term they will likely transition to paying the full rate of 34%, though.
Looking forward, I can model what their production guidance and current spot gold prices mean for future profitability.

Even if I assume they pull the full Brazilian corporate tax rate in FY26 and have a big jump in AISC, then I still get a figure well in excess of the current forecasts:

Mark’s view
I was a little disappointed with these production figures as they came in at the very bottom of the guidance range and were below recent trends. However, quarterly figures can be lumpy and I’m not reading too much into one weaker quarter in an otherwise upward trend for production. Their 2026 production guidance range looks achievable, although I’d personally assume that they came in at the lower end, similar to this year.
Without seeing how costs have evolved in the quarter it is hard to be certain. However, my expectation is that the gold price strength in the quarter will have led to at least a modest beat on expectations. They look on for an even larger beat for FY26 if the gold price remains at current levels.
This also highlights the biggest risk to the company - if the gold price falls significantly, so will their profitability, and planned production increases won’t overcome this. The good news is that this remains a hedgable risk (at least for more sophisticated investors). However, the company is certainly making hay while the sun shines, and while its rays are still glinting off everything gold it makes sense to keep our mostly positive view of AMBER/GREEN.
Premier Miton (LON:PMI)
Down 9% at 53p - Q1 AuM update - Mark - AMBER
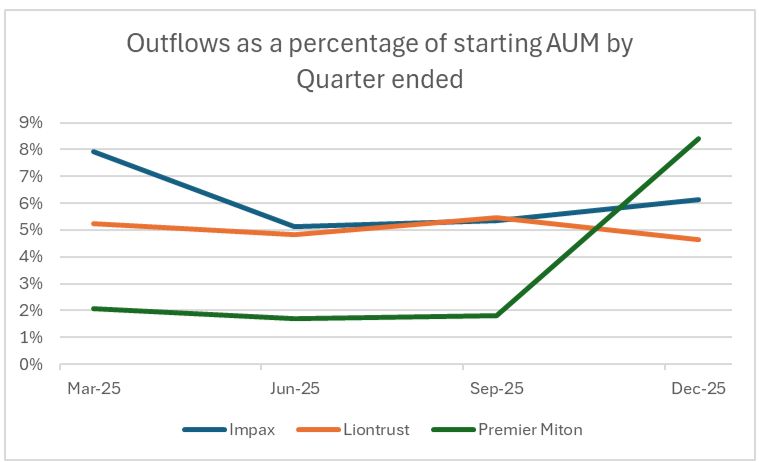
I can see why the market is disappointed with this update this morning. Over the past year, Premier Miton has outperformed a lot of the more UK-focussed asset managers, with around 2% net outflows per quarter. However, in Q4 this jumped to over 8% of their AUM redeemed:
Their recent investment performance has also been nothing to write home about:
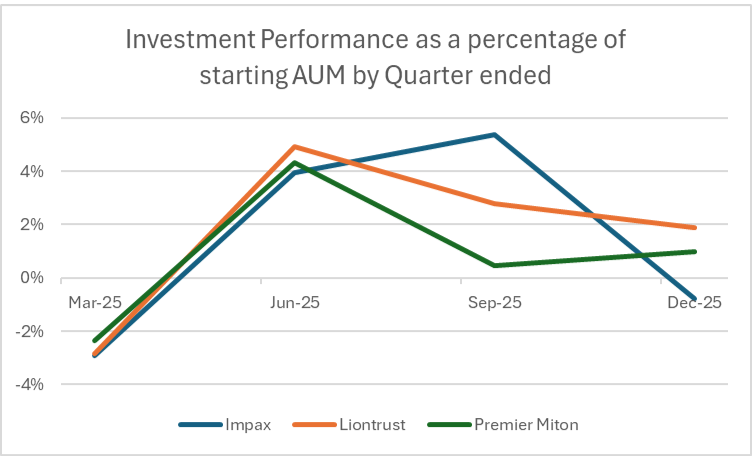
Performance data is noisy and no one apart from the tech and US-focussed Polar Capital has been doing well. However, 1% returns in a period when the FTSE 100 has been performing well struggles to make the case for investors to send their capital their way in the short-term.
I can’t see any update broker coverage today, but similarly to Impax who reported earlier this week, it would seem to take a pretty big turnaround in fortunes for them to now be able to meet market forecasts for the full year. This means that their current forward P/E doesn’t really stand out amongst peers:
- Impax Asset Management (LON:IPX) 7.4x
- Liontrust Asset Management (LON:LIO) 6.0x
- Premier Miton (LON:PMI) 9.4x
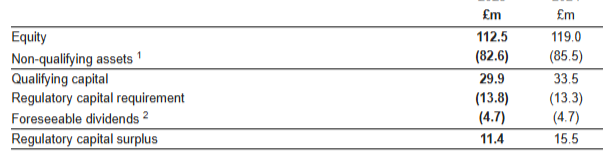
P/E isn’t the only thing, as these companies also have net cash. However, they have to hold that as regulatory capital, making it more like an inventory than distributable capital. I like that Premier Miton clearly tell us what their regulatory surplus is. Something peers don’t always seem as keen to do.
They are forecast to pay a higher dividend yield than the others:
- IPX 8.5%
- LIO 8.3%
- PMI 10.3%
But this is uncovered, so may be at risk of a cut if AUM outflows don’t reverse soon, and that regulatory capital surplus becomes depleted.
The share price has outperformed over the last six months which may also mean that some investors prefer it.
Relative strength:
- IPX -35.3
- LIO -39.2
- PMI -16.5
However, if this isn’t backed up by the underlying business out-performing this may mean it simply hasn’t fallen yet.
Mark’s view
I am sympathetic to the view that the whole sector is cyclical and therefore undervalued on these types of metrics. However, when it comes to Premier Miton specifically, this AUM update worries me. They have seen big outflows in the last quarter and delivered mediocre investment performance. The risk that they miss current EPS forecasts and need to cut back their dividend payout looks to have increased today. However, they still haven’t fallen anywhere near as much as peers recently. Putting all this together means I am going to take a more circumspect view of the near-term outlook here. AMBER
MPAC (LON:MPAC)
Up 2% at 330p - Full Year trading update - Mark - AMBER
The share price has been strangely volatile here on no news, following a big Profits Warning in July:
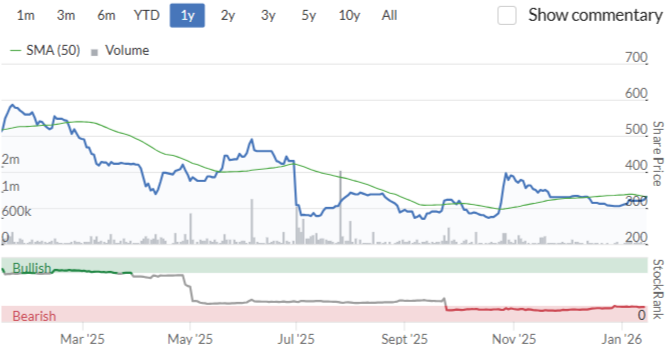
Today, the shares trade at a similar price level as to when I reviewed their half-year results released in September. I concluded that their FY revenue figure looked achievable, despite the weakening order book, since they only had to do £80.3m in H2 versus £84.7m in H1 to hit Shore’s £165m forecast. Today the announce that:
The Group expects that it will report revenues of c£170m
I was less convinced that they would go from £5.0m in adjusted PBT in H1 to £13.5m for the FY as this relied heavily on them making significant cost savings. However, today they confirm that they are also in line with that figure, which is good news. With Mpac the word “adjusted” often does some heavy lifting, and I expect the same when the results are announced in April. There will be cash costs associated with the restructuring as well as asset write-downs.
Looking forward, the order book has stabilised:
The Group closed 2025 with an order book stabilised at c.£92.0m, in line with the position as of 30 June 2025 (HY25 £91.7m). Original Equipment ("OE") order intake improved c25% in the second half of the year against H1 25, following a slow first half as customers deferred capital investments due to market uncertainty in response to US trade tariffs.
However, Shore maintain their FY26 forecasts with just a 1% rise in revenue to £172m. Adjusted PBT and EPS are expected to rise by 12% to £15.1m and 37.5p, respectively. However, again this is due to cost-cutting, rather than business expansion. This puts them on a forward P/E of around 9 which is relatively modest. However, we also need to include the impact of the large net debt:
Deferrals of anticipated orders in Q4 25 resulted in lower customer deposits and consequently resulted in a higher net debt, excluding leases of £47.7m.
This is up from £43.2m on 30 June, and adds to the risk, with the balance sheet already looking weak at the half-year. Shore calculate an EV/EBITDA of 6.3, which looks about right for this type of business.
Mark’s view
While it is pleasing to see that they hit market forecasts, these are still much lower than they were before the July profits warning. They also will rely heavily on cost-cutting and adjustments in order to hit those bottom-line figures. I don’t think it is crazily valued at 6.3x EV/EBITDA. However, all the Stock Ranks are low:
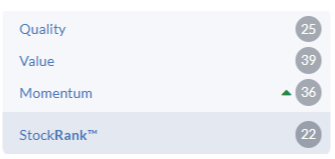
Which means that the algorithms actually rate this a Sucker Stock. That seems a little harsh to me, but I also struggle to see where the upside comes from here. Relatively lack-lustre growth combined with a weak balance sheet, meaning they can’t afford to pay a dividend, is rarely an exciting prospect. Hence, this update doesn’t change my previously neutral view. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Borregard and Robertet are both classified as Materials stocks! But let’s not fall out over it!
Ashmore (LON:ASHM) - a nice volume spike a few days before todays news.
Maybe markets are turning away from the US to the rest of the World (MSCI) or maybe the Powell thing, amongst others.
Ichimoku and MACD if anyone interested. Some people like graphics (powerpoint) and others numbers (clever people like both). Anyway Green cloud Good, Red cloud Bad - works with my stupid brain (when I listen to it - which is a battle in itself).
Big insider trade volume a few day before announcement - so 'someone' knows 'something' and were right.
(Fire away I'm back below the parapet).
Finally, Ashmore (LON:ASHM) gets quarterly inflows into its AuM. I was beginning to wonder if they would catch the EM winds that have been blowing since the start of 2025.
For most of 2025, EM ETFs have been seeing inflows. And international stats have captured institutional inflows into EM bonds and shares. So I've been patiently waiting for Ashmore to declare some inflows into their funds.
Looks like institutional investors are a bit slow moving.... which isn't a surprise... and have now caught up with the EM thinking and allocating more there. Hopefully, this is a 2026 strategic shift, so we might see more institutional flows to Ashmore in Q1.
(I hold in the Boon Fund).
Graham, you make a good case on Hostelworld (LON:HSW) but can you reconcile it to a stock rank of 25 and a sucker stock rating? I can understand that momentum is low but the quality and value scores look harsh.
It's not a conventional value stock, I acknowledge that - definitely a bit riskier than my usual type of selection. Based on historical data, book value and share price momentum, it's a dangerous choice.
Is there somewhere on the website that shows how the Stockrank figure is calculated?
There's a whole eBook on it. Published in 2024 - https://www.stockopedia.com/ac...
Looks like Marstons (LON:MARS) is subject to an activist investor - the company seem to have done well in the last 12 months following selling off brewing arm and paying down debt - will be interesting to see what happens next.
A follow up to my Tuesday posts re 21Shares Bytetree BOLD ETP (LON:BOLD) .The response from HL .
Thanks for getting in touch
Bitcoin is the largest and most widely held cryptocurrency. While longer-term returns of bitcoin have been positive, bitcoin has experienced several periods of extreme losses and is a highly volatile investment - much riskier than stocks or bonds.
The HL Investment view is that bitcoin is not an asset class, and we do not think cryptocurrency has characteristics that mean it should be included in portfolios for growth or income and shouldn’t be relied upon to help clients meet their financial goals.
Performance assumptions are not possible to analyse for crypto, and unlike other alternative asset classes it has no intrinsic value.
HL will offer appropriate clients to trade in crypto ETNs at some point this year following careful development of the client journey and appropriateness assessment.
You can find the full statement from HL regarding cryptocurrency here
Extract from full statement.
“Despite our investment view, we recognise that some clients will wish to speculate with crypto ETNs. The FCA has labelled crypto ETNs as restricted mass market investments (RMMIs). This means that they are considered high risk and are not appropriate for all retail clients, only those that have sufficient knowledge and experience. Clients will have to undertake an appropriateness assessment before being allowed to trade. In some cases, the amount that retail clients can hold in RMMIs will be restricted to 10% of their total portfolio.”
I am becoming increasingly disillusioned with H/L and the unavailability of stocks from overseas markets and their "nanny state" attitude to crypto investments! As well as the paltry interest rate the pay on cash held on account...2.45% on sums over £100K!! They must be getting 4% + on the vast sums held on account!! Rant over :-).
I use ii for overseas stocks, although I think the interest they pay on cash is even worse. But I do agree with the HL investment view on crypto and it seems they are anyway somewhat bound by regulatory restrictions.
No JD, BOLD ( Bitcoin & Gold collective) is now available on the London Market but H/L have not made it available to buy (so far).
Metals Exploration (LON:MTL) released o note this morning, here's the 3rd a nd last paragraph:
The Scheme Document further stated that the Company's Manikbel prospect at the southern end of the Abra tenement was drill-ready, with all approvals in place, and that Metals Exploration intended to undertake an initial 6,000m drilling campaign with the aim of completing such work before the end of Q2 2025, with the objective of compiling an initial mineral resource estimate by Q3 2025. Drilling at the Manikbel prospect has not yet commenced in order to allow for an indigenous peoples' consultation process to take place. Accordingly, the Company now expects to commence such initial 6,000m drilling campaign in H1 2026 with a view to compiling an initial mineral resource estimate by Q4 2026.
I think this is the reseason why there were hold-ups which encouraged Condor Gold to put La India up for sale, also the reason why I sold my Condor investment. I hold Metal Exploration after buying shares without due diligence.
'
There is a Master Investor Show on at Islington Design Centre on 25 April. Book your slot.
On the subject of housebuilding, I live in a small village surrounded by farmland. It is classic green belt but the government has invented the concept of grey belt to define land that can be built on without the protection that green belt enjoyed. Hurrah I hear you say. We need houses to be built. In fact there is a proposal to build 200 houses on a field adjacent to our village. This land once formed part of a landed gentry estate where there were no direct descendants when the owner died so land was inherited by a nephew who lives in London and is more than happy to turn his farmland into cash.
The problem is that our village offers no work opportunities, has no school, no shops, no recreation facilities, no church , no railway or frequent bus service or any transport option except the private car. Even cycling is precluded except for the fittest because all roads into and out of the village have to cope with long steep hills. None of these facilities can be walked to because there are no pavements outside the village itself, there are no street lights and most are miles away. Most existing homes have two cars for obvious reasons.
Some years ago another farmer engaged a company to obtain planning permission for his land which the council refused. An inquiry was held by the Secretary of State into an appeal. The planning inspector refused the appeal and conclude that the site was unsustainable and would leave residents heavily reliant on the car to reach work and other amenities. Nothing has happened since to alter that but we are once again being asked to accept housebuilding which will significantly increase the amount of local traffic, associated pollution and congestion and destroy a useful piece of farmland.
I don't have an answer to the problem of building enough houses but I'm sure building them in the wrong place isn't a good idea.
Speaking as a country lad (bumpkin even) we don't need more houses we need less people. I'll go and hide behind a tree now, if I can find one.
There must be hundreds of farms greyfield-ready, just don't ask the owners at the same time when enquiring about the possibility of helping to control the woodpigoens on their wheat and barley.
Agree. Some other stuff to consider:
Waste disposal / recycling (aka land fill).
Drinking water - ok ED it rains a lot - nothing new here.
Developers are not stupid, just used to doing the same washing machine cycle.
Electricity - so can run the BYD Co (PNK:BYDDY) Geely Automobile Holdings (HKG:175) etc or just call a Uber Technologies (NYQ:UBER).
Maybe Millibund will put a windmill in a field nearby so keeps the "no parking" signs alive. Forget the birds (expendables - nasty flying rats).
A house/accommodation/roof over your head - £200/250k - aspiration or the real story a Government supplied hut.
The biggest challenge is to give Kids (22- 30+ sic) hope they can own some sort of asset to grow their life, have a kid or two and have some money for holidays and old age.
The world seems to be becoming unaffordable until a Universal Social Income arrives with Elons robots giving us a Universal Guaranteed Income (actually a socialist dream).
Apologies - this is an investment website but we need to consider where to put our money so can invest wherever you like.
I could say oil and gas but may incite some negative comments here. Don't care ConocoPhillips (NYQ:COP) Exxon Mobil (NYQ:XOM) started positions and forever holds.
Can anyone point me towards a decent discussion board for European stocks ? Tia.
Lots of good stuff on Substack, but you have to navigate your way around to find it.
Alex is no longer publishing as he has taken a fund manager's role with Fidelity and as a result has had to enter purdah. The material on his substack will consequently time decay, but it still has a lot of value and certainly points you in the right direction. Not exclusively European though: Sweet Stocks | Alex Sweet | Substack
You can find a Substack covering French stocks here: French Focus Investing | Ulrich Dubois | Substack
These group of private investors cover a lot of European stocks (but also US): The Dutch Investors | Substack
This is a group of 4 investment professionals (aren't we all?) who cover some European stocks: Investment theses in Small Caps & Macroeconomic analysis | MORAM Capital | Substack
I have thought about starting a daughter substack covering my Nordic stocks ... we are a British, Swedish, Finnish, German family and consequently are drawn to this part of the investing universe. Half our non commodity stocks are in this part of the World. The commodity stocks I usually write about tend to be UK or Canadian.
European stocks I like and own include:
SWEDEN
Saab Ab (STO:SAAB BTA B)
Investor AB (STO:INVE B)
NORWAY
BORREGAARD ASA (STO:BRGo) listed on Swedish and Norwegian exchanges
Kongsberg Gruppen ASA (STO:KOGo) listed on Swedish and Norwegian exchanges
DENMARK
Alk-Abello A/S (CPH:ALK B)
Genmab A/S (CPH:GMAB)
NKT A/S (CPH:NKT)
ITALY
Prysmian SpA (BIT:PRY)
FRANCE
Robertet SA (EPA:RBT)
GERMANY
United Internet AG (ETR:UTDI)
GEA AG (ETR:G1A)
Non of this is advice of course, but I hope it gives you a starter at least.
Thanks that is a very good response. I will have a free look at one or two of those and see if they seem worthwhile. I only own two Europeans directly - ASML and I very recently bought Viridien. Is there any in your list that you feel most happy about? I like the look of Robertet.
I rate Ulrich and the Dutch fellas, too. Although the latter are OBSESSED with ASML, an admittedly superb company that we’ve held since the last decade. It depends at what scale you’re investing. For large caps I’d suggest Morningstar with it’s proprietary valuation mechanism is the resource of choice.
A lot of materials choice in there, James. I guess you’re focusing on what you understand best? We hold a lot of Nordic industrials, from classic roll-ups (Addtech, Lagercrantz etc) to world class specialists (Atlas Copco, Alfa Laval, Assa Abloy) to smaller niche operators (Norbit, HMS Networks, Epiroc, Mycronic)
To the OP, investigate Swiss mid-caps, optically expensive (Swiss!) but many are family owned and think in generations not decades. Expectations are for them to have a good year. We own several (VAT Group, Kardex, Inficon, Belimo and more)
Happy hunting!
No materials stocks at all actually:
SAAB : aerospace & defence
Investor AB : holding company od the Wallenbergy industrial family. Hold strategic, often controllibg, stakes in ABB, Atlas Copco, Astra Zeneca, Ericsson, Electrolux + private equity arm mistly invested in medical physics and engineering + founder stake in EQT.
Borregaard : Norwegian biorefinery using forestry waste
Kongsberg Gruppen : Norwegian areospace and defence coy 50% owned by Norwegian government.
ALK Abello : Pharma (allergy)
Genmab : antibodies/biotech
NKT : cable manuacturer active in wind farm sector.
Prysmian : World's largest cable and grid component manufscturer. Global manufacturing foot print.
Robertet : family controlled ingredients, flavours and fragrance business.
United Internet : owns 5G mobile network in Germany and controlling stake in Ionos.
GEA : manufacturer of food, biotech, fermentation and pharma production lines
All coys have CREST certification and can be bought for SIPP or ISA. Not a materials company amobg them.
Alastair
Sorry on my phone and my big fat agricultural fingers are not good with this tiny touch pad ... hence the spelling errors. It won't let me go back and fix!
Many thanks, James.
Thank you to the seven subscribers who responded to my post on Tuesday concerning the Money Week article from 2021.
In response to Douglas 1971 about the UK property market there is a road in Torquay where Rightmove say prices have fallen 60% since the 2023 peak.
"In response to Douglas 1971 about the UK property market there is a road in Torquay where Rightmove say prices have fallen 60% since the 2023 peak".
Lies, damned lies and statistics. Rightmove say this is for one postcode - TQ1 4RN Trumlands Rd. Rightmove say "Overall, the historical sold prices in Torquay over the last year were 5% down on the previous year and 12% down on the 2023 peak of £293,325".
This 60% just comes from 2 totally different properties:
In 2023 just one house in that postcode was sold for £818k. It is a large detatched house:
Last year just one house on the same road was sold for £327k - smaller and semi-detatched:
Polite request I follow the Jim Slater portfolio and see that FSG have fallen into this portfolio. Could I ask you to add it to your watch list? Many thanks, Nigel
Morning folks
Copper miners make up around 10% of my portfolio and they have had a good year. There are widely divergent views on when and how large the copper deficit might be going forward. I am pondering whether or not to allocate additional capital to copper: hence the motivation for researching this report to answer the fundamental question: "how large will the copper deficit be and when will it hit us?" In addition, my Lundin Mining (TSE:LUN) position has become a bit oversized, so I am on the hunt for another copper miner to rebalance into.
It is always a conundrum isn't it ... "How far and to what position size do you let your winners run?"
This report might be of interest if you have, or are thinking of, a position in copper:
The Copper Deficit: Why the Timelines Diverge — and Why Friedland Is Still the Outlier Who Might Be Right | By jamesalastair | Stockopedia
You can download a PDF at my substack: The Copper Deficit: Why the Timelines Diverge and Why Friedland Is Still the Outlier Who Might Be Right
I would welcome feedback, criticisms and suggestions. I hope someone somewhere finds some value in it.
Have a nice day.
Alastair
It's brilliant. A fascinating and compelling read over the morning coffee. Highly recommended. I like Atalaya Mining Copper SA (LON:ATYM) , not least because it's based in a relatively stable country. I also have Sprott Pure Play Copper Miners UCITS ETF Acc (LON:COPP) .
Thank you Jolly Biologist (from the Eyeore Chemist!!)
Thanks Alistair - £COPG has done well for me since you pitched copper a few weeks ago.
What thoughts on Serabi Gold (LON:SRB) and their TU today ?
Thank you Bohenie!
Did you see the FT note on this in the week-end edition? If so what was your reaction?
Thanks for the post. I hold ACG Metals (LON:ACG) for copper exposure. It's a new company with a buy and build/consolidation strategy in the copper sector. They currently have one asset, a gold mine in Turkey, that will also start producing 22.5kt copper pa in H2 '26 from a new sulphide plant currently under construction. There are 3 main attractions for me....copper, management & it's a new story that's under the radar. Mgt are impressive imo. The CEO & founder was the no 2 at Rusal to Oleg Deripaska and led their consolidation strategy that led to Rusal becoming a multi billion $ aluminium co. He's now looking to do the same in the copper space. He has big ambitions to become a 200-300ktpa copper producer with mkt cap of $3-5bn. I look for co's/mgt with a track record and ambition to scale and this co certainly has that. There are some serious heavy hitters on the board/advisors. They seem to have v good contacts. It was impressive how they raised $200m bond financing to build the Turkish mine. It's v rare for a new mining co to finance the full construction of their first mine with bonds. I hold so I'm biased but worth a look imo.
Might another Lundin play help here Alistair? Specifically, Lundin Royalties
Hi Charlie
I will have a look Lundin Royalties as I have not heard of it. Do you have the ticker? I know of Lundin Gold (TSE:LUG) but always viewed them as too expensive and too high risk - single asset miner if I recall correctly.
Many thanks Alastair for some excellent posts and reports. I have found them very informative. Like JollyBiologist, I have Atalaya Mining Copper SA (LON:ATYM) as well as Taseko Mines (LON:TKO) . In particular, I think with Florence in the US coming into production this year and the future potential from the Yellowhead project, Taseko Mines (LON:TKO) remains interesting. I also recently opted for a stake in Ivanhoe Mines (TSE:IVN) . Whilst it is in the DRC, and not without risk, it looks like it is far enough away from M23 Rebel activity to only have seismic events and flooding risks to worry about (!) - and I also like the potential of the Platreef project, as a longer term hold. I also have a recent small stake in Bezant Resources (LON:BZT). Here I like the recent purchase of NLZM for the processing plant to help progress the start-up of copper/gold operations in Namibia. It looks like they have started hiring and could have a pathway to commence operations in 2026. However, this is highly speculative, so we will see.
As well as Copper, I have been interested in tin for some time since watching an interview from Vox Markets with Mark Thompson in 2024, discussing the utility of tin and the looming tin deficit. Here I have Metals X (ASX:MLX) and First Tin (LON:1SN). There are not so many investment options for tin mining, and I have avoided Alphamin Resources (CVE:AFM) so far, as again it is based in the DRC and looks just too close to M23 rebels, but I have recently opted for Andrada Mining (LON:ATM) . With the increase in tin prices as a catalyst and production and cost improvements in the pipeline at its Uis mine in Namibia, together with the Lithium Ridge partnership with SQM , things seem to be aligning for Andrada Mining (LON:ATM) to have a good year, but again we will see. Once again, many thanks for your interesting and well researched posts.
Patrick
Holy cow Graham! 43 summaries this morning! Hats off to you! Incredible!
[ could be wrong as I ran out of fingers and toes whilst counting;) ]
early morning companies list
This is my favourite section of the Stocko!
It is a masterpiece of work put together at the shortest of time . Well done to all.
Dunelm (LON:DNLM) at ‘lower end of consensus expectations’ yet share price down 16% when I last looked. Surely an overreaction - be interested to see any analysis from the DSMR team.
Morning All,
Trufin (LON:TRU) looking interesting, historically has done nothing, is this driver a one off or more tangible?
Any updated broker forecasts?
Taylor Wimpey
good summary of the housebuilder status at the current circumstances
https://www.ii.co.uk/analysis-...
The reduction in op margin is a big concern imo and will get worse next year. Are we at the bottom? Who knows, I just remember TW at 4p in 2008! Seem to recall I bought at 8p and sold at 20p. Duhhh!
Useful thread on UK housebuilding:
Noble Francis
"UK brick deliveries are a useful proxy for new house building starts in the absence of monthly starts data. Deliveries in November 2025 were 15.5% lower than in October & 10.2% lower than a year ago, according to the Department for Business & Trade."
"At this stage, it is difficult to see what would drive a strong Spring selling season in 2026 for house building even though the pre-Autumn Budget uncertainty is now over & there was a further an interest rate cut, as the fundamental factors remain the same."
"In areas with high house prices, affordability remains the key constraint. In areas with lower house prices, demand has been sustained but house builders’ site viability is affected by a long (& rising) list of government's additional costs on house building."
3 posts quoted above, but it's worth reading the full thread (20 short posts) here.
There is also a J.P. Morgan note on UK housebuilders here.
Hi Duveteux,
I am a little wary of reading too much into the reductions in brick deliveries in recent years. It is my recent experience in the construction industry that there has been a significant move towards composite timber cladding products and insulated renders in lieu of brick facework. These products are usually more economical and can be installed quickly. (Adverse weather also has a minimal effect on installation times & timing). Although costs are a factor in this change to alternative products, it is also being driven by Designers (Architects) and often LA Planning Departments. Also, throughout my career in the construction industry, (50+ years), there has always been a shortage of bricklayers!! (apart from 2009 to 2012 - global recession). It is noticeable in East Anglia & London that less bricks are being utilized for an average, new-build house.
Thanks, for someone like me, with no connection to or experience of the construction industry, that's a useful insight. Maybe the short to medium term outlook for the housebuilders isn't quite as bad as I feared then - although might not be so good for suppliers like Brickability (LON:BRCK), Michelmersh Brick Holdings (LON:MBH) etc..
That’s a long list!
I’d be interested in your thoughts on the pub/leisure sector. Mitchells & Butlers (LON:MAB) and Marstons (LON:MARS) appear to be managing against headwinds.
Also builders Persimmon (LON:PSN) coping in an equally tight environment due to additional taxes. Are we at the bottom for the construction related stocks?
I read today that new homes are cheaper than older properties for the first time (at least in last 25 years) due to discounts and efficiencies from new bills contractors. Is there a market sentiment indicator there?
Amazing how companies adapt when times are tough. They will boom if conditions improve.
Also builders Persimmon (LON:PSN) coping in an equally tight environment due to additional taxes. Are we at the bottom for the construction related stocks?
I dont think thats a bad shoutout Revs8 - its tricky though as many are not esing any material upswing - it seems like worst may be over for Vistry Taylor Woodrow etc - but i wouldnt be surprised if Vistry brokers have downgraded 2026 expectations. So i woluld be wary of declining forecasts last 6-12 months - but the 2026 or 2027 broker forecasts are are showing that numbers wil be better than current year. Things may be getting beter but not improving over what brokers have pencilled in - and downgrades by brokers aint going to be taken well even if the company has turned the corner and is making more. Perhaps its the best time to take teh plunge though TW. seemed positive budget uncertainty is out of the way now and planning stuff has positive momentum - by the time we get real broker updates the clever money will likely have been in a while. Ref Marstons (LON:MARS) - its all positive tones from them and forecasts are expected to be higher - but brokers havent actually upgraged eps estimates recently.
Hopefully companies have been sensible and getting the basics right in tough times - thats not always terrible focusing on making the most of what you have got - MPAC (LON:MPAC) seem to have gone back to basics in that regard - not that they had any choice to do owt else with sales falling off a cliff.
the powers that be need to doa betetr job though.
I read today that new homes are cheaper than older properties for the first time (at least in last 25 years) due to discounts and efficiencies from new bills contractors. Is there a market sentiment indicator there?
Yes but the average TW new property is 374k - we need to literally build millions of 200-250k houses for the younger people out there - huge mismatch between haves who have been on housing ladder and have nots. I suspect new homes are cheaper as they are less desirable - would you hand your money over to persimmon with their track record?
I doubt that many houses are going to be built by the private sector and and sold below market prices. So the only way that I can see to create millions of affordable houses and keep them affordable is for them to be built by the state and rented with a certainty that there will never be any 'right to buy'.
IMO, the main barrier to affordable housing is the value of land and the fact that the landowner captures the uplift in value when planning permission is granted. If there were a land tax, with a higher rate for undeveloped land with planning permission, it might bring housing costs down, but few owner-occupiers would vote for a significant reduction in the value of their house.
The trouble with a land tax is that landowners will just sit on their land on the basis the next government might reverse it. That said I think its a good idea having worked in the industry for over 30 years and seen landowners make enormous profits
I doubt that many houses are going to be built by the private sector and and sold below market prices
i am not saying sel, below market value
i dont have a full solution - but supply and demand is bound to be an issue ref house prices in general - we have added 10 milion to population without building extra houses.
we need to build millions more houses and labour have promised that - i would like to think that there would be incentives especially if we are using greenbelt - to try and get the mix right - rather than affordable being the runt end of the deal - thats up to the gov. No reason why the gov couldnt say 50% of all fresh planning thats not brownfiled should be "affordable" - ie cap on value as % of top whack nice house.
Its tricky the more we build good quality homes the more that can feed downover so i am not against nice houses. There is most certainly a need though for the young to be able to get on the ladder with something they can afford - and its not ridiculous ref leasehold cost.
if it was me i that was running the country i would buy enough greenbelt land from private landowners at greenbelt values - grant planning en masse so taxpyer gets uplift in value - and then go to open market to build 2 million affordable new homes that are priced for affordibility.
I doubt that many houses are going to be built by the private sector and and sold below market prices
i am not saying they are sold below market price - just get em built for minimum cost - i dont see why en masse billy basic homes cant be done for 200k each on volume - if you are not having to pay top whack for land ! If they need cunning plan ref building in volume to keep prices down - the tech is probably out there to get that sorted.
The nimbies and environmentalists would be up in arms - this would take the froth out of the market too - where prices are being ramped up by supply issues. IMHO it would be vote winner if youngsters start to see afordable new home being built - at present we are sadlkt letting them down.
Note that plan may not be good for current housbuilders if it upsets their dominant position in the chain - they are big enough to look after themselves. We have had enough house prioce inflation over the last 15 years - we could do with period of mild deflation.
Cohort (LON:CHRT) put out an RNS at 7:00am sharp, but the website link says "No documents currently available". I have to wonder whether institutions have been given access ahead of PIs
Wasn't Just me then!
Their interim report was already published last month, so I'm not sure what the point of today's RNS might be. Looking into it. Update: I've deleted Cohort from the table this morning, as today's RNS mirrors an RNS from last year: LINK. They have already published their interim results in December (same as last year), so today's RNS is nothing to worry about.