Daily Stock Market Report (Thur 2 Jan 2025) - TMG, POLB, RCDO

Good morning! Graham here, back after taking some time off. Let's see what companies we have reporting on the first business day of the new year!
Recent articles on Stockopedia:
- SIF Folio 2024 review & changes for 2025 by Roland
- 12 Stocks of Christmas: IG Design by Mark
- 12 Stocks of Christmas: Billington by Mark
11.15am: Roland and Megan have covered a few stories and I think I'll end the report there due to the limited amount of news to cover today. Hopefully we'll have more to cover tomorrow! Cheers.
Spreadsheet accompanying this report: records from 5/11/2024 (format: Google Sheet). Updated to 19/12/2024.
Companies Reporting
Unfortunately there is almost nothing of interest today:
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Mission (LON:TMG) (£22m) | Disposal and capital allocation update | Mission has sold a subsidiary for £17.4m, proceeds will repay debt. | AMBER/RED (Roland) |
Backlog
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Ricardo (LON:RCDO) (£261m) - 17 Dec 24 | Sale of Ricardo Defense & Acquisition of E3 Advisory | The UK engineering consultancy group is exiting defence and doubling down on its focus on the environment and energy transition. | AMBER (Roland) |
Summaries
Mission (LON:TMG) - Up 20% to 29p (£27m) - Disposal and Capital Allocation Update - Roland - AMBER/RED
Mission has sold a US-focused subsidiary for up to £17.4m. This deal should repair the group’s balance sheet and provide some protection for the company’s equity. However, I think there’s a risk the company may have sold one of its more profitable units in order to achieve this goal, so I’d like to see updated guidance from the company before considering a more positive stance.
Ricardo (LON:RCDO) - unch. at 419p (£261m) - Ricardo Defense sale & Acquisition of E3 Advisory - Roland - AMBER
Recent corporate activity will see Ricardo exit the defence sector and expand its focus on the environment and energy transition markets. I take a look at these recent transactions and consider the resulting fall in near-term profit expectations. While the strategy makes sense to me and both deals may turn out to be reasonably priced, I think it makes sense to stay neutral for now.
Short Sections
Poolbeg Pharma (LON:POLB)
Down 34% to 4.7p (£35m) - Reverse merger with US company - Megan - RED
I have been reading some rather depressing statistics this morning about the number of companies that delisted from London’s main market in 2024 - 88 of them in total, compared to just 18 new entrants. This marked the worst year for UK stock market outflows since 2009 in the wake of the financial crisis.
News this morning that Poolbeg Pharma (LON:POLB) is reversing into Nasdaq-listed Hookipa Pharma (NAQ:HOOK), in a deal which seems to value the UK company at about £25m less than its pre-announcement market capitalisation, adds more negativity.
Poolbeg is a spin out of hVIVO (previously Open Orphan) which has had its fair share of ups and downs since it listed on Aim in 2012. Poolbeg was listed as its own entity (with the same chairman as the former parent) in 2021 in the wake of the Covid-19 pandemic, to focus on clinical candidates in the antiviral and vaccine space.
Hookipa is a specialist in immunotherapy with drug candidates in both the oncology and infectious disease space. Like both Poolbeg and its former parent hVIVO all of its drugs and vaccines are in the early stages of human trials. All three companies are aiming to sell their drug candidates to larger pharmaceutical companies before they reach the expensive late stage trial phase.
It’s not a bad model. Big pharma tends to struggle to move quickly enough to take drugs from the pre-clinical stage of development all the way through to commercial launch, while smaller companies don’t have the financing or commercial expertise to take them all the way through to market.
The trouble is that for now Poolbeg hasn’t managed to hook any of those big partners. In September, chief executive Jeremy Skillington commented that the value and attractiveness of one of the company’s drug’s candidates had been “greatly enhanced following the independent confirmation of a potential market opportunity”. But that is definitely more of a hopeful comment than anything concrete.
Megan’s view:
Poolbeg, hVIVO and Hookipa are all ‘wait and see’ kind of investments. They’re high risk because there is no guarantee of any deal coming to fruition, but could be high reward if a clinical candidate does get snapped up by a big pharma group.
They also absorb a lot of capital which is perhaps why the merger with a Nasdaq-listed company is sensible. In September Poolbeg had £10m of cash on its balance sheet and under its new parent, it’s hoping to raise $30m from Nasdaq investors.
Shareholders will definitely suffer some dilution in this deal, but Nasdaq does (for now) seem like a better home for Poolbeg. There are good clinical synergies between the two companies as well. Plus the fact that the US is a better market for pharmaceuticals.
I’m RED on the company as a whole and I don’t like the way Aim-shareholders have been treated in this situation, but I can see why the deal makes sense.
Mission (LON:TMG)
Up 20% to 29p (£27m) - Disposal and Capital Allocation Update - Roland - AMBER/RED
This small-cap marketing group has announced the £17.4m disposal of its April Six subsidiary today – a material amount, given Mission’s £22m market cap (pre-open).
We’ve regularly covered Mission in this daily report, often with mixed feelings. For much of last year we maintained a RED view on Mission due to its weak balance sheet.
In May 2024, Graham discussed a (rejected) bid by rival Brave Bison to buy Mission that might have addressed this issue.
In June, Graham reviewed Mission’s trading and warned that its “large debt balance and slim profitability” could require an equity fundraising.
As it turned out, Mission didn’t carry out an equity raise – and perhaps we now know why. The company has opted instead to sell what appears to be a sizeable subsidiary.
Let’s take a closer look at today’s news.
April Six sale: Mission has agreed to sell its April Six business (April Six Limited & April Six Inc) to US firm Marketbridge Inc for a total gross consideration of up to £17.4m.
This will comprise an initial cash payment of £10.5m and an earnout of up to £4.2m. As these figures only total £14.7m, I guess Marketbridge will also assume some debt/working capital liabilities.
The total consolidation of £17.4m appears to be equivalent to c.1.5x April Six’s revenue, but the company has not provided a 2024 profit-based valuation multiple for the sale. The only clue we have is that the earn-out target is calculated based on a 7x EBITDA multiple.
April Six’s client base is said to be heavily skewed to the US tech sector. As a result its profits slumped in 2023 as tech spending slowed. But we can see from the historical numbers provided today that April Six has generated significant profits in the past.
I’ve highlighted the relevant lines for adjusted revenue (excluding pass-through) and adjusted operating profit:
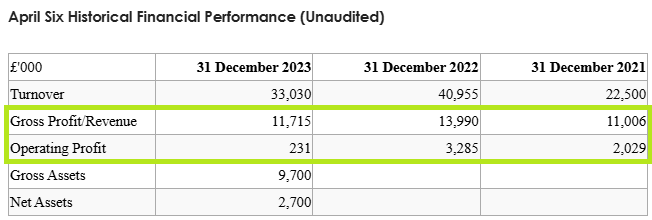
We don’t have 2024 figures, of course. But averaging the three years above gives £1.85m of operating profit on £12.2m of revenue, equivalent to a margin of 15%.
If we view these figures as a normalised level of performance for April Six, then today’s transaction appears to offer the buyer an earnings yield (op profit/EV) of nearly 11%, which does not seem too expensive to me.
One other interesting point from today’s announcement is that the founder and CEO of April Six, Fiona Shephard, seems to have played a key role in arranging this transaction.
Mission says Ms Shephard will remain with April Six and will receive a £360k payment “for sourcing the buyer”, as part of a wider £860k “incentive payment” to members of April Six’s management team.
Impact on TMG balance sheet: initial cash proceeds of £10.5m are expected to reduce net bank debt from £17m on 30 December 204 to £6.5m following receipt of the proceeds.
A further reduction is expected if the earn-out consideration is received.
TMG says the disposal will improve its net debt/EBITDA and interest cover ratios. This is expected to result in improved borrowing terms from lender NatWest.
Looking ahead, Mission’s management are targeting medium-term leverage between net cash and 1x headline EBITDA.
Dividends are expected to return in 2026.
However, the company is sufficiently confident to declare a £1.5m share buyback today, beginning immediately.
Impact on TMG earnings & outlook: The profit figures for April Six in the table above suggest to me that this subsidiary generated around 25% of TMG’s 2021 operating profit, rising to nearly 38% in 2022.
In 2023, TMG’s headline operating profit fell by £2.3m to £6.5m, while April Six’s operating profit fell by c.£3m to just £231k. So it seems that TMG’s profit slump last year was probably caused by April Six, partially offset by gains or savings elsewhere.
House broker Canaccord Genuity has left its 2024 forecasts unchanged today ahead of TMG’s expected FY24 trading update on 20 January 2025.
Current forecasts suggest Mission shares could be trading on c.4.4x 2025 forecast earnings, after this morning’s rise. But I would prefer to have some idea of the likely impact on profits before relying too heavily on these estimates.
£5m cost saving plan completed: the company says that the disposal of April Six means it has now achieved its target of £5m of annualised operating cost savings in 2024.
Of course, it’s easy to reduce operating costs by carving out a big part of the business. The question now is what impact this may have on future earnings.
Roland’s view
Today’s deal seems a reasonable approach to solving Mission’s debt problem. The company has historically generated more than 80% of its operating income in the UK, so selling a US-focused business may be logical.
Assuming that 2025 earnings bear some resemblance to current forecasts, then I think it’s fair to say the overall position has improved for equity investors today.
However, while April Six performed poorly in 2023, its performance in 2021 and 2022 suggests to me that it’s capable of generating high-margin earnings. I wonder if the other parts of Mission’s business are as profitable.
Until we see the 2024 accounts and receive updated guidance on profits and growth expectations, I think it makes sense to retain a cautious view. I’m going to upgrade our view by one notch to AMBER/RED.
Ricardo (LON:RCDO)
Unch. at 419p (£261m) - Ricardo Defense sale & Acquisition of E3 Advisory - Roland - AMBER
This is a backlog piece covering news from 17th Dec 2024. As it’s quiet today, I thought it might be interesting to take a look at this engineering consultancy business, which is currently reshaping its operations.
On 17 December, Ricardo announced the sale of its Defense unit for £67.5m and the acquisition of Australian infrastructure consultancy business, E3 Advisory, for £51m.
The planned sale of Defense had been flagged up in October’s strategy update as part of a move to focus more closely on “engineering consultancy in environmental and energy transition”.
As Graham commented at the time, Defense was a key profit contributor with higher margins than the group’s other operations. So the exit valuation would be important, as would the company’s plans for the proceeds – unlike TMG above, debt levels were not a concern.
Ricardo Defense sale: the sale of the defense business was agreed to a private equity consortium for $85m (£67.5m).
For context, Defense contributed £123.4m of revenue and £23.5m of adjusted operating profit in the 23/24 financial year. Those figures represent 26% of revenue and 60% of underlying operating profit for FY24.
At first glance, the valuation of the sale appears to be very reasonable (for the buyers!) at less than three times trailing operating profit.
However, the picture is complicated slightly by the outlook for a significant drop in sales of a key programme supplying updated Antilock Braking Systems for US Army vehicles. Activity is expected to peak and start falling from 24/25 onwards, meaning future profits could be lower than those seen recently.
The company says this means the timing of the sale is “optimal to maximise the value of Ricardo Defense”.
However, unless the ABS programme is truly exceptional, my feeling is that this valuation also implies a relatively cautious view on future sales. I don’t know whether this might be justified by sector expectations and the Defense order book.
E3 Advisory acquisition: on the same day as the Defense sale, Ricardo announced the acquisition of Australian firm E3 Advisory for £51m (funded entirely with proceeds from the Defense sale).
Given their similar size, shareholders might have expected these transactions to broadly offset one another in terms of profit contribution. But that’s not the case. At least, not initially.
Ricardo’s acquisition price for E3 is 7.7 times the company’s FY24 operating profit of AUD13.2m (£6.6m) – a much higher multiple than the Defense sale.
Management appears to be counting on E3 to continue delivering high-margin growth, in a way that perhaps the Defense business would not.
In fairness, the summary accounting information provided for E3 Advisory does seem to suggest this could be an attractive business. Revenue rose by 15.7% in FY24 and profits were generated with an underlying operating margin of 28.5%.
Updated outlook: the inescapable reality is that Ricardo is selling a business that generated £23.5m of profit last year and replacing it with one that generated less than £7m of profit last year.
The company admits this will be “dilutive to the Group’s earnings per share in the near term”...
With thanks to broker Panmure Liberum, we can get an idea of the scale of this dilution:
FY25 earnings forecasts cut by 47% to 21.4p per share
FY26 earnings forecasts cut by 27% to 33.5p per share
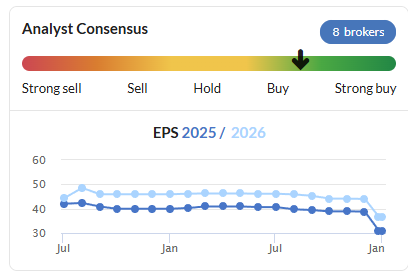
Panmure’s FY25 forecast in particular appears to be more pessimistic than the consensus forecasts shown on the StockReport – this may mean that some of the estimates used to compile consensus have not yet been updated:
Panmure Liberum’s estimates price Ricardo on a FY25 P/E of 19.6, falling to a FY26 P/E of 12.5.
Roland’s view
If E3 Advisory can maintain its recent growth rate and profitability, then I think it’s fair to say that the purchase price may prove reasonable.
Whether the Defense sale price is attractive for Ricardo shareholders is harder to ascertain. Realistically, we are unlikely to have any visibility on the subsequent performance of this business once it is divested.
If profits slump for a few years then Ricardo’s sale may indeed have been “optimal”. Personally, I’m not entirely convinced this will be the case, given the positive macro backdrop for defense spending and Ricardo’s seemingly positive relationship with the US DoD.
For prospective and existing shareholders in Ricardo I think this pair of transactions justifies a fresh look at the business. As Graham commented, a more focused strategy can often be attractive from an investment perspective.
On the other hand, the loss of the Defense unit means this will be a somewhat different business, going forward.
Looking ahead to FY26, my feeling is that a valuation of c.12x earnings would not be unreasonable.
However, my feeling is that the earnings outlook for the next 12-18 months could be somewhat uncertain, until both transactions have completed and we see some evidence of the contribution that’s being made by E3 Advisory.
I’m staying neutral for now - AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Does anyone know what prompted the rise of Serica Energy (LON:SQZ) today?
Most likely due to the rise in gas prices since Ukraine shut off the last pipeline supplying Europe with Russian gas yesterday, as Serica Energy (LON:SQZ) also pumps gas I believe.
Volex (LON:VLX)
Completely unloved! Can’t fathom any reason for the slow downward drift in the share price. On the 12 December the company stated that it was confident in meeting full year expectations, albeit earnings have been adjusted down for this year and next but not significantly.
Possibly the publicised Trump tariffs, given that Volex (LON:VLX) has global manufacturing facilities, including Mexico, which is one of the countries singled out by the unpredictable Trump presidency. The company has a strong relationship with Tesla, which might be seen as a positive.
The shares are very cheap. I hold but not tempted to add until the price stabilises.
Any thoughts?
Quadrise (LON:QED)
I would be grateful if you could give your views on QED – Quadrise which has quadrupled recently, after years in the doldrums.
HNY.
Quadrisen then....
is there any January effect for the UK stock market - particularly small caps - have there been any studies?
Have a look at the 'The Seven Secrets of the UK Stock Market' on Amazon.
Poolbeg Pharma (LON:POLB)
Bit surprised at some of the commentary on here on this one.
Firstly - let's be clear Cathal has done this deal and as an 8% shareholder he is doing it because he sees more value with the two together than on their own and he wants a Nasdaq listing,
Secondly - HOOKIPA have $50m of cash and will raise another $30m (I suspect this has already been done but lets see) so the combined business will have $100m of cash (not the $40m in Megans note above)
Poolbeg Pharma (LON:POLB) shareholders should therefore be left with 40% of something with cash of some $100m and an interesting set of drugs in various stages of development versus a market cap prior to the announcement of $45m so not a million miles away from the 40% fully diluted shareholding.
Cathal is going to be Exec Chairman and the Hookipa CEO (who is new - only appointed in July) will be CEO.
Cathal runs a notoriously tight ship financially whereas Hookipa has been heavily cash burning for a while now (not long ago this was a stock at close to $200 so it has fallen 99%!) so that seems contradictory. My guess is that Cathal has spotted value and there are plans to radically reduce cashburn through synergies and cost reductions to create a business with a strong war chest for a couple of other acquisitions.
This is not a done deal yet so Cathal will not be on the airwaves talking about it until it is agreed. Be interesting to see how Hookipa shareholders view it this morning.
Hi David,
I admire how you can turn a 40% decline in one day into something positive!
Hookipa Pharma (NAQ:HOOK) burns cash and the cash balance is not to be trusted as a long term thing; it has also managed to remain listed amd regained compliance after a reverse stock split1 for 10. Here I must emphasize that last years cash balance was $117.5 million at December 2023. Cash balance was $60 million at the end of September 2024!!
Poolbeg Pharma (LON:POLB) will be a zero in the future.
I believe he is the same guy that sold hVIVO (LON:HVO) at 30p to Institutional investors.
Well done to Megan for labelling this as RED.
All the best
In Cathal’s defence he took hVIVO (LON:HVO) over as Open Orphan at sub 5p, I sold around 30p and got Poolbeg Pharma (LON:POLB) for free.
He is great at turning loss making pharma companies around. I’ll continue to hold to see what he does here.
Microlise (LON:SAAS)
Jonathan Lee, Non-Executive Chairman, purchased 19,417 ordinary shares of 0.1p in the Company at a price of £1.03 per Share.
A buy signal? Board reckons the cyber incident will not have any material impact. Surely customers are not going to be happy?
Well after lots of buying and lots of selling in 2024 I am flat on my UK stocks, what a waste of time and effort.
At least my Tesla (NSQ:TSLA) is up 130% so a good year all in all.
Here's hoping for better picks and less profit warnings for 2025! - Not started so well with Poolbeg Pharma (LON:POLB) - at least they were free shares originally
"Unfortunately there is almost nothing of interest today:"
Not if you're a Poolbeg Pharma (LON:POLB) shareholder, Graham. Very complicated reverse into a NASDAQ company who seem, at first glance, to have all the Aces. Would welcome views on this on a slow day.
I’ve still got some Poolbeg Pharma (LON:POLB) from a dividend in specie from hVIVO (LON:HVO)
On the face of it, looks like they just devalued the shares by 40% but I’m sure Cathal will have a plan, he usually does. I’m going to hold and see.
At 4.2p I think we have no other choice now. I've held from day one and added along the way. Cathal's dream was always to reverse into a NADAQ stock but I don't think anybody expected it to be at what looks like such a heavily discounted value. Cathal should have been on the airways by now and his absence speaks volumes IMO.
Poolbeg Pharma (LON:POLB) Yes, this looks rubbish at first glance! Cathal holds appx 8%. Lets hope he can either negotiate a better deal or block it.
"HOOKIPA shares are issued to investors at HOOKIPA's 60-day volume weighted average price ("VWAP") of $2.81" So far the proposal is that we'll get 1 POLB share for = 0.03 share of HOOKIPA stock. HOOK is currently valued at $2, which is why we are seeing a 40% drop. HOOK also have to fund raise to complete the purchase. If you are thinking of selling,
I'm wondering if its worth waiting for the opening of the NASDAQ, as if HOOK stock price bounces, then the offer will look better.
Not good I think, but I'm no expert. Would love to hear if the merge of these two companies will offer any great advantage. Holding on for now.
Thanks for doing the analysis on Poolbeg Pharma (LON:POLB) this morning Megan. Even though it's RED, you're still more positive than me.
Hi Barry
I believe the entire essence of the set up here at Stockopedia is to steer us all away from investing in dross like Poolbeg Pharma (LON:POLB) . The Stock Rank and classification systems couldn't be clearer and on a normal day this shouldn't even justify comment from the team, imo. Others may take a different view but I regard this as a bonus article probably only getting airtime because of the serial entrepreneur/promoter at the helm and the time of year.
In the meantime the strange false market of the holiday season seems to be quietly positive on first day of trade. Long may it continue! Best of luck for the year ahead. Agree with your rating here.
Agreed. You'll see from my original comment that I only mentioned the company because it was a slow news day and it seemed an interesting structured deal which was difficult to fully understand . If there had been more RNSs to be covered I would not have mentioned it and simply suffered in silence.
Emmerson (LON:EML) on the move. Sorry can’t delete post. Didn’t know was in litigation with Moroccan govt over its potash development. Seems hard to find trust in the Middle East.
Morocco is in North Africa :)
I actually got an o-level in Geography lol. Well at least got lots of 'hits'. Not sure the comment is incorrect though. Jurisdiction risk wherever is a huge investment decision and will only get more serious with natural resource depletions and protectionism. For me a warning that governments can do much as they please - UK and North Sea oil is the case in point. Shell delists 2025 my prediction.
January 2025 Investment trust thread is now here https://www.stockopedia.com/co.... A discussion of Invetment trusts , ideas etc.
Revolution Beauty (LON:REVB)
Jan 2 (Reuters) - Chrysalis Investments Ltd CHRY.L:
UPDATE ON CLAIM AGAINST REVOLUTION BEAUTY GROUP
ENTERS SETTLEMENT AGREEMENT WITH REVOLUTION BEAUTY
REVOLUTION BEAUTY TO PAY NON-MATERIAL SUM TO CHRYSALIS
The claim was for £45m, same as mkt cap, so this removes a big uncertainty now.
Hopefully a large enough sum for Chrysalis Investments (LON:CHRY) to increase their buyback programme a wee bit more.
The announcement states that the amount is a NON MATERIAL SUM; whatever that means. Is it a £1?, £100?, £1000?………or a couple of millions?
All the best
It's less than 1% of Chrysalis Investments (LON:CHRY) mkt cap. So £6m.
https://newsfile.refinitiv.com...
Less than 1% is simply less than 1%.
It’s not 6m!
All the best
Slow day. I'm not sure if the 12 stocks of xmas is supposed to be over, but here's a couple of suggestions for you (one is a catch-up from yesterday).
Bloomsbury Publishing (LON:BMY) 674p Book publisher. It's most famous for Harry Potter and Sarah J Maas' works. It also has a digital division for things like audiobooks, which seems to be doing well. They have recently acquired an educational division, for which they see good growth. Fwd PE 16.6, div yld 2.4%, average ROE over the last 5 years of 10.7%, which is a little disappointing. They have net cash. Growth in EPS has been impressive, going from 12.3p in 2015 to 41.6p in 2024
M P Evans (LON:MPE) 994p. It produces palm oil. It sounds boring, but it has been a nice steady grower. I won't say any more about it as it is mentioned recently by Ed Croft in his top stocks for 2025 (https://www.stockopedia.com/co...) and by Mahad (https://www.stockopedia.com/co...)
I hold both shares.
Hi Mark, thanks for these suggestions.
12 Stocks is still ongoing. Our publishing system is playing up slightly so the articles are appearing int he home page in a weird order. But here are the two latest picks from Mark:
IG Design
Billington
Mark,
Someone on here pointed out around the time of the last results that BMY had become heavily reliant on Sarah J. Maas and that there was little growth elsewhere. So I think you would need to monitor that very carefully.
I also hold Bloomsbury Publishing (LON:BMY). In this current year to 28 Feb 2025 there are no Sarah J. Maas titles which partly explained the drop off in the SP and the reduced revenue forecast. However, I seem to recall that the company will publish 6 of her books in the following financial year and I believe this may not be adequately reflected in the forecasts. I also believe that the impact of the US acquisition announced last May may not have been adequately factored in to this year or next. Add to that excellent, conservative, canny management team, this, for me, is a classic coffee jar hold.
(LON:BMY)
I hold and think you are correct about no S J Maas releases in current financial year but I think 1 or 2 to be published in the year to 02/26 ( not 6) and I believe nothing in financial forecasts at this point to reflect those potential new titles
yes I think I may have misunderstood, Probably there are 6 titles in the pipeline. Not sure anybody would have time to read all 6 titles in a year anyway!
indeed - buy and holder Bloomsbury Publishing (LON:BMY) . There is top draw research on the investor relations website - https://www.bloomsbury-ir.co.u...
As a holder of M P Evans (LON:MPE) , I commend Mahad's excellent post, noted above. It explains the business model and provides very detailed financial analysis which he is generous to share. Since his approach is primarily financial and Ed's inclusion of the share in his 2025 NAPS portfolio is also driven by metrics, I thought I would add a couple of non-financial factors to consider, one negative and one probably positive.
1. Shareholder base.
The company was drawn to my attention about three and a half years ago by the son of a friend. He used to work for them in a fairly senior position. At the time, I was thinking I should have some commodity exposure to counter rising inflation. I've never liked commodity producers because they are generally price takers (world prices) and work on long timescales for projects and with soft commodities there's the weather too, so lots outside their control which can go against them. MPE is no exception. My contact was of the opinion that the company is conservatively managed (including the accounting) so the margin of safety is probably even greater than Mahad and Ed's figures would suggest. It has been in effect controlled by the Hadsley-Chaplin family for several decades. Although the chairman Peter H-C only declares a 4% interest, there are sure to be lots of other family holdings below the threshold for disclosure, including other families whose plantation interests were rolled into MPE. So a prudent approach is understandable and (to me) reassuring.
About 8 years ago, a Malaysian competitor, KLK, launched a takeover at around £6 or £7 a share which failed. The board commissioned a valuation of the plantations which came out nearer £11 a share (cf current share price 8 years later of £10). The much increased dividends also date from that time although they are still well covered by earnings. After the failed bid, KLK kept the holding they had built up and remain the largest holder at about 24%. Interestingly, in the last year, a representative of KLK has joined the board as a NED. KLK's market cap (on Malaysia's bourse) is about 10 times MPE's (although they are more diversified than MPE both horizontally and vertically). So another bid is possible at some point.
Finally on shareholders, MPE recently initiated a share buy back programme which was extended. Operated within European safe haven rules, it mopped up a few thousand shares most days. Just before Xmas, they announced that they would venture outside those rules (but still within their shareholders' authority) to enable them to buy larger holdings. Sure enough, a couple of days later they bought over 600,000 shares (over 1% of the company). Abrdn subsequently announced that their holding had dropped to below 5%. An overhang removed? Or more to come?
2. Political risk
Mahad mentions the risk of laws or international rules changing. I would be more specific about Indonesian risk. As a result of a deliberate strategic decision to focus in recent decades, MPE has reduced its activities to one country, Indonesia, and one commodity, palm oil. (The Malaysian property development joint venture is a hangover from their exit from that country and only has 200 of an original 2000 acres still to develop). A few months after my initial investment, Russia invaded Ukraine (a major producer of rape seed oil, for which palm oil can be substituted in some applications). The palm oil price and the MPE share price shot up and I was feeling quite pleased with myself. Very quickly, the Indonesian government changed the rules to grab most of the super profits and to protect the home market (where palm oil is a staple). This was more or less reversed once prices settled again. The MPE share price went back below my entry price. More drastically, back in history (1960s?) Indonesia nationalised plantations, granting them back on 30 year leases. So in my view political risk is real.
As ever, DYOR and a Happy (and prosperous) New Year to all Stocko staff and subscribers.
An additional thing that I might mention: I remember a year or so ago MPE mentioned that it commissioned an independent NPV valuation of its shares. If they're buying back shares, then it's a sign that they think they're reasonably confident it's undervalued.
.