Daily Stock Market Report (Thur 21 Nov 2024) - $NVDA, JET2, CMCX, PAY, JD., LIO

Good morning!
I hope you've been enjoying the comment notifications rolled out by the team earlier this week.
In other news, Megan and I will be having a chat this evening in an open webinar: Stock Market Sector Trends for 2025. We'll be looking at some of the most topical investment themes and how they are affecting certain sectors as we head into 2025. I look forward to seeing some of you there!
Wrapping it up there (12.15pm). See you at the webinar later if you can make it!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023
Companies Reporting
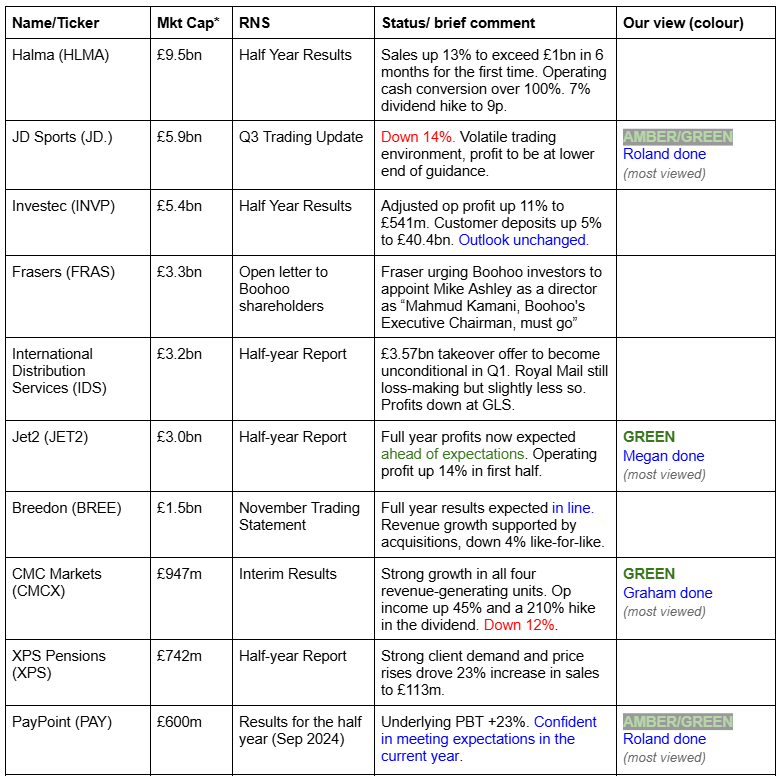
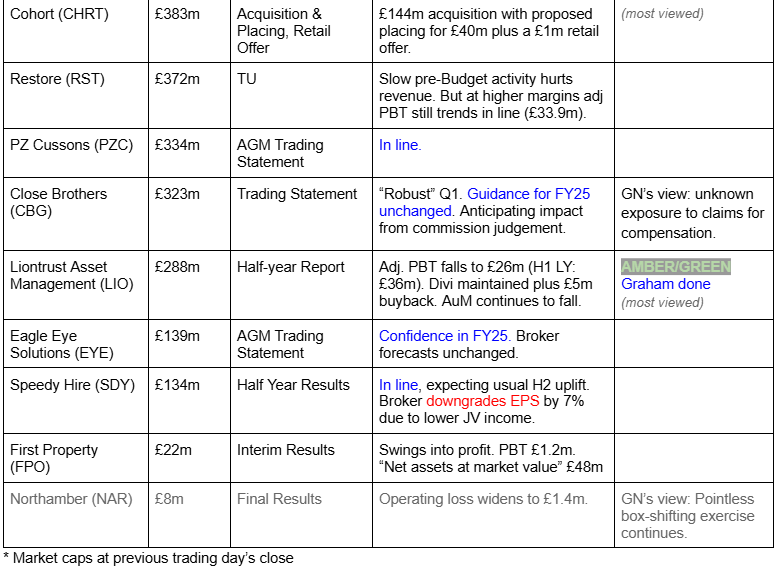
Summaries
Jet2 (LON:JET2) - up 10% to 1557p (£3.34bn) - Half-Year Report - Megan - GREEN
Strong results from the UK’s largest package holiday operator. Strong revenue growth thanks to greater fleet capacity and a slight uptick in prices. Jet2 is also seeing a rapid rise in demand for flight-only tickets, which puts it into interesting competition with easyJet (especially once Jet2 opens its new base in Luton next year). The overhaul of the fleet to the more fuel efficient Airbus planes remains on track and the company is well managed and financed.
CMC Markets (LON:CMCX) - down 12% to 297p (£829m) - Interim Results - Graham - GREEN
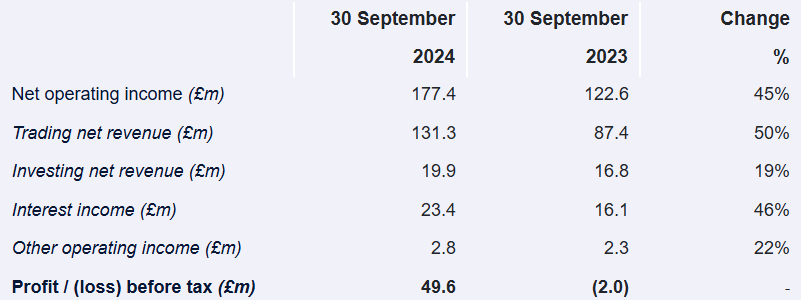
The market seems disappointed that CMCX would not upgrade its full-year expectations given fabulous H1 numbers including nearly £50m of PBT and £177m of net operating income (full-year forecast: £233m). I don’t have a problem with management sticking to conservative forecasts and therefore am happy to keep my positive stance.
PayPoint (LON:PAY) - down 5% to 790p (£570m) - interim results - Roland - AMBER/GREEN
A solid set of results showing progress in most areas and a respectable 23% increase in underlying PBT. Margins remain impressively high, but a slight cut to earnings forecasts by broker Panmure Liberum suggests to me that after a strong run, the share price may be approaching fair value for now.
JD Sports Fashion (LON:JD.) - down 14% to 97p (£5.0bn) - Q3 trading update - Roland - AMBER/GREEN
A seemingly mild profit warning, with full-year results now expected to be at the lower end of expectations. The company blames “volatile” trading from October onwards. While I’m cautious, today’s update doesn’t seem disastrous to me. The modest valuation means I think cautious optimism is still justified here.
CMC Markets (LON:CMCX) - down 12% to 297p (£829m) - Interim Results - Graham - GREEN
The market appears to be disappointed that no upgrade has been communicated by CMCX despite producing net operating income of £177m, vs. full-year expectations of only £333m. As NOI and profits are inherently uncertain, I don’t mind CMCX taking a conservative stance on this and leave my GREEN perspective unchanged.
Short Sections
NVIDIA (NSQ:NVDA)
Down 4% pre-market to $142 ($3.6trn) - Financial Results for Q3 - Megan - AMBER
The world’s largest company has delivered another set of barely-believable quarterly results.
In the three months to the end of October, the company reported just over $35bn of revenue. That’s 17% higher than the previous quarter and 94% up on the revenue reported in the third quarter of 2023.
Reported operating income has also doubled, up to $21.9bn - equivalent to an operating margin of 62%.
Earnings per share of 78¢ came in 8% ahead of analysts’ already lofty expectations. Management has now forecast fourth quarter sales of $37.5bn, which compared to $22.1bn in the same period last year, and typically wide margins.
So why then are the shares likely to open down?
There will be some degree of profit taking. Nvidia’s shares are up almost 200% in the last year - well ahead of its peers in the US tech sector and the wider market.
There are also some concerns that the highly anticipated new chip Blackwell (which has run times more than 30 times faster than its older siblings), is still struggling with overheating problems. The chips have been smoking when they’re loaded onto server racks, which has thrown the Q1 launch into some doubt. There are a lot of large customers which are relying on these chips and won’t be happy with any delays.
The incoming president Donald Trump might also be causing some nervousness. Nvidia already battles with its supply chains to keep up with whopping demand. Increased restrictions on trading with China or mounting geopolitical tension in Taiwan, where one of the company’s largest suppliers TSMC is based, won’t help.
And, there’s the ongoing question of competition. Nvidia has existed in a chip making bubble for most of the last few years. This means it has access to almost the entirety of the market which is reliant on chips to support AI (a phenomenally fast growing market). But surely the dominance can’t last forever. Yesterday we saw management from Sage suggesting that its own AI demands might be diverging - some of its products don’t actually need such super fast performing chips as those Nvidia is seeking to provide. A broadening of demands and an improvement in capabilities of peers could eventually encroach on Nvidia’s growth and margins.
Megan’s view:
For now, there is very little not to like about Nvidia. Sure, if you use traditional valuation ratios, its share price might cause a bit of anxiety, but market dominance and growth like this can’t be measured on traditional ratios.
This is a high quality, momentum play which continues to smash earnings expectations, whilst benefiting from multiple expansion (the two clearest hallmarks of multibaggers).
The only black mark on the horizon is the potential delay in Blackwell, so I would be happy to enjoy watching the ride from the sidelines until there is more clarity on launch dates. AMBER
Graham's Section
CMC Markets (LON:CMCX)
Down 12% to 297p (£829m) - Interim Results - Graham - GREEN
The bull thesis has played out here in spectacular fashion. A loss of £2m in H1 last year becomes a profit of nearly £50m in H1 this year:
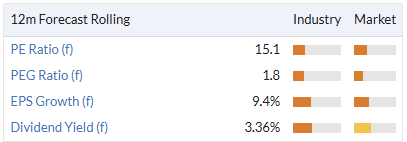
CMC’s share price has trebled from the low it reached last year, as it now trades at a reasonable PER on much higher earnings expectations:
The 50% increase in trading net revenue (to £131m) shows a significant uptick in trading activity. When we read about the constant outflows from UK active fund managers, it’s easy to forget that there is still a great deal of appetite to invest and to trade - just perhaps not always in the way that it was done before.
One key opportunity for CMC is its partnerships: it is providing back-end trading infrastructure for Revolut, and more recently announced a long-term strategic partnership with the Kiwi bank ASB, for whom it will provide its stockbroking technology and execution.
Outlook: much of CMC’s recent financial success has been down to its ruthless cost control. It sounds like this attitude will continue:
Management maintaining pragmatic approach to investment with a focus on profit margin expansion, whilst continuing to explore and invest in opportunities for incremental growth.
Full-year net operating income (NOI) is expected to be in line with external expectations, with the consensus forecast currently £333m.
Note that NOI was £177m in H1 and if this repeated in H2, we’d beat the consensus forecast by £20m+ with £354m.
But it’s a volatile figure as trading activity levels tend to fluctuate unpredictably.
To get operating profit, we deduct operating expenses from net operating income.
So for example let’s suppose net operating income hits the £333m forecast exactly.
H1 operating expenses were £124m. Suppose they rise to £130m in H2.
We would then have:
NOI £333m
Full-year opex £254m
Operating profit is the difference between these two, or £79m.
A few (hopefully small) items are deducted from operating profit, such as finance costs and any impairments of intangibles, to arrive at pre-tax profit (PBT).
Actual H1 operating profit was £53.5m, with actual PBT of nearly £50m.
Graham’s view
This morning’s 12% fall in the share price demands an explanation and the best I can come up with is that the market was hoping for an upgrade that didn’t happen.
As I noted above, a repeat of H1’s NOI in H2 would see NOI beat expectations by £20m+. But CMC have not indicated that they are going to beat expectations, which implies a very conservative (but perhaps realistic?) outlook.
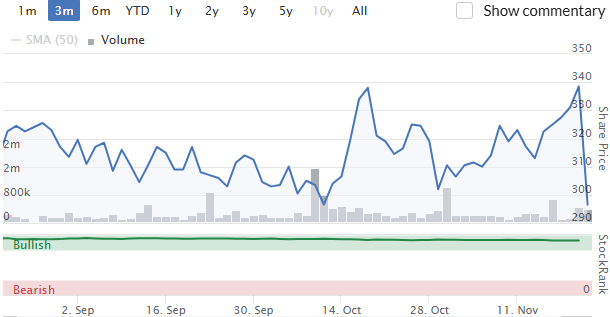
Looking at the chart, today’s fall takes back to the bottom of the range for the past 3 months. Which is perhaps fair enough, as expectations have not been upgraded yet. But with four months left until the end of the financial year, perhaps there is still a good chance of a beat?
I remain a big fan of this one and am happy to stay GREEN. The stock is supported by over £400m of very liquid balance sheet equity.
Disclosure: while I am not a shareholder in CMCX, at the time of writing I do have a long position in a competitor, IGG.
Liontrust Asset Management (LON:LIO)
Up 7% to 447.5p (266m) - Half Year Report - Graham - AMBER/GREEN
Assets under management just keep falling at this fund manager, and profitability is affected, but it continues to look very cheap.
AUM fell by 7% in six months to just shy of £26 billion (Sep 2024), despite some positive market movements.
By mid-November it had fallen further to £25.2 billion.
Adj. PBT falls to £25.8m (H1 last year: £36m)
Divis & Buybacks
The interim dividend is unchanged at 22p. That payment alone is 5% of the current share price.
And this is remarkable:
The Directors intend to target a dividend of at least 72 pence per share for the year ending 31 March 2025.
It’s a yield of 16% on the current share price.
The market had already pencilled it in but now we have it in black and white that LIO are going for 72p per share in dividends.
Based on the current share count, 72p in dividends will cost £46m.
On top of that we have a share buyback for up to £5m.
Can they afford this? Here’s an excerpt from the capital management section:
As at 30 September 2024 the Company had surplus capital after foreseeable dividends of over £45 million
With the following table in the footnotes:
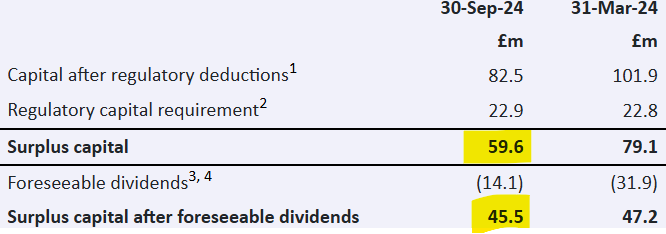
The first interim dividend of 22p is the current “foreseeable dividend”, i.e. £45.5m of surplus capital will be left after paying that dividend.
Or looking at it another way, the entire £51m package is coming out of the £59.6m “Surplus capital” as of Sep 2024.
It’s a brazen move but I think it is affordable - not on an ongoing basis, but on a one-off basis.
The company will pay out most of its surplus capital to shareholders this year and it will be replaced by whatever this year’s profits amount to.
For H1, let’s check the quality of LIO's profits. A reconciliation from adj. PBT to actual PBT:
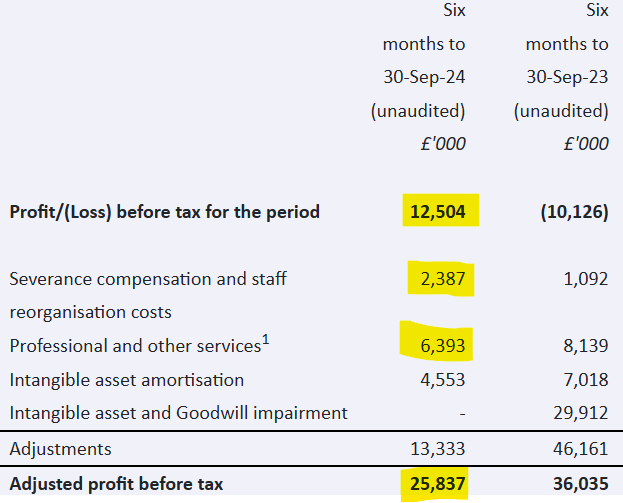
PBT gets inflated to twice its original size with these adjustments, and I’m afraid I’m not on board with most of them. There is an argument to write off intangible asset amortisation but staff reorganisation costs and “professional and other services” seem to me a fairly regular expense.
H1 Adj. EPS is 30p, vs. actual EPS of 14p (rounded figures).
CEO comment excerpt:
"The last six months have continued the challenging period for active managers including Liontrust. There are a number of reasons, however, why we are confident that we are moving into a more positive environment and the outlook is improving…
Our confidence is reflected in the fact that we are targeting the same dividends as last year and have announced a share buyback programme.
He makes some worthwhile points, especially that passive funds have contributed to the outperformance of a “small number of mega cap stocks”, leaving passive funds particularly exposed to concentration risk.
Performance: unfortunately this has not been very good.
Some of the investment strategies at Liontrust have gone through a difficult period for performance. This was notably the case in 2022 for quality growth and UK small and mid-cap equities and that year's performance is still impacting three-year numbers. Shorter term performance for Liontrust's funds, however, has been stronger.
Graham’s view
I’m astonished to see that this share has fallen by another 28% since I covered it last (in July).
Since early July, I have been AMBER/GREEN on it, even though I am GREEN on every other fund manager I can think of.
The problems with LIO:
Its accounts are dirty
Fund performance is generally not impressive in recent years
It has no niche it commands
Management seem to embrace complexity and expansion when (in my opinion) they should be looking for simplicity and acting with caution.
Their aggressive stance on dividends doesn’t change my mind on any of this. In my view, it just means that the company will have less asset backing next year than it does now. I’d have been more impressed by a larger share buyback instead of an unchanged dividend, as that would have really said something about the valuation here.
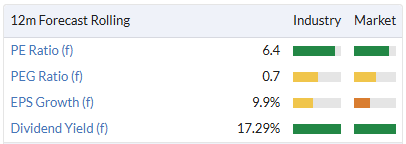
I’m happy to leave my AMBER/GREEN stance unchanged as it does still have a profit margin and it is cheap, but it’s certainly not the first fund management stock I’d be adding to my portfolio.
Megan's Section
Jet2 (LON:JET2)
Up 10% to 1557p (£3.34bn) - Half-Year Report - Megan - GREEN
The UK’s largest package holiday operator seems to be unaffected by any concerns about a possible cost of living squeeze on spending. Sales in the first half of the 2025 financial year rose 15% to £5.1bn thanks to a record number of passengers and higher prices.
The continued investment in the company’s new fleet of Airbus planes has helped to boost capacity. These planes have 20% more seats than the old Boeing fleet and they’re more fuel efficient and quieter, so that seems like it’s a big chunk of money well spent. Capital expenditure rose to £229m in the period as the company paid for two of its new Airbus planes. First half capex is expected to remain at this level for the next few years as the remainder of the 146-strong fleet of planes gets delivered.
In early 2025, Jet2 will open two new UK bases in Luton and Bournemouth airports, adding to the 11 domestic locations it currently operates out of.
In the six months to September, the company reported a slight increase in the average price of a package holiday (to £904), while flight-only prices were marginally lower at £130.81.
Appetite for flight-only tickets was materially higher, which more than offset this slight decline in prices. Management have seen increased demand for last minute flights, which is a trend they expect to continue for the remainder of the winter season. With winter seat capacity 14% higher than last year, continued demand for last minute booking and a material volume of Winter24/25 tickets still to sell, revenue for the full year is now expected to come in ahead of previous forecasts.
The strong increase in operating profits to £702m (up14%) and basic earnings per share (up 21% to 279p) is good news as the company heads into its more cost intensive second half. As is typical, the company is expected to be loss making in the second six months of the financial year as it books fleet, fuel, marketing and staff costs. On an annual basis, the company has reported operating profit CAGR of 16% over the last five years.
Megan’s view:
Jet2 remains the pick of the bunch in an otherwise volatile UK travel sector. It is consistent in its ability to attract customers from other package holiday operators and, increasingly, flight-only companies. The new base in Luton airport puts it into even more direct competition with easyJet (LON:EZJ) and it will be interesting to see how demand takes off.
Shares are trading on a forecast PE ratio of 7.8 times, keeping Jet2 firmly in GARP (growth at a reasonable price) territory.
The balance sheet still looks robust, with a NAV of £1.8bn (only £26.8m of which is in intangible assets), that’s equivalent to a little over half of the market capitalisation. Cash generative with debt headroom so there shouldn’t be any financial dramas in the event of another global travel-related incident. GREEN
Roland's Section
PayPoint (LON:PAY)
Down 5% to 790p (£570m) - interim results - Roland - AMBER/GREEN
This has been a strong half year for PayPoint where we have delivered a positive financial performance and made further progress towards our medium-term target of delivering £100m underlying EBITDA by the end of FY26.
This many-faceted payments business has confirmed that it’s on track to meet full-year expectations in this morning’s half-year results. But investors appear to have expected a little more, with the shares down by around 5% at the time of writing.
I’ve followed this business intermittently for years and have admired its strong profitability and cash generation. But analysing the business and its growth prospects has always been made quite difficult due to the sheer number of moving parts. As PayPoint has made a number of acquisitions in order to reduce its dependency on its legacy cash bill payments business, this complexity has only worsened.
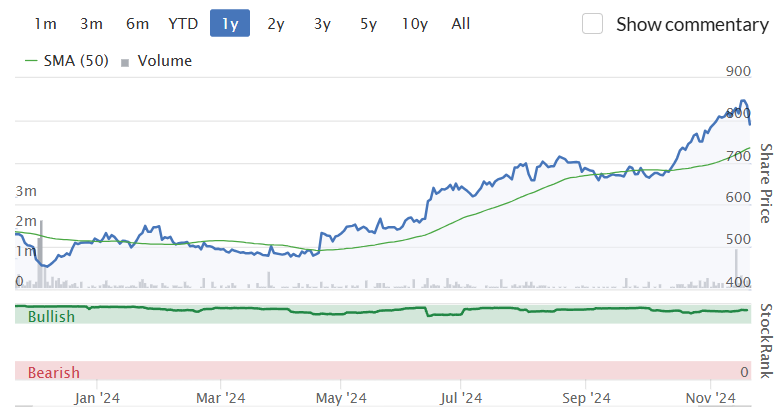
However, over the last year my view has increasingly been that the company’s transformation is (probably) working well. PayPoint’s share price action over the period suggests that other investors have also been taking this view. The stock doesn’t look quite such a bargain to me as it did 12 months ago:
Let’s take a look at today’s results to see what’s new.
Half-year results summary: today’s accounts cover the six months to 30 September 2024 and show revenue up 6.7% to £135m, with net revenue up 6% to £84.6m. Broadly, net revenue excludes commission payments and pass-through revenue such as retail vouchers.
Underlying pre-tax profit rose by a creditable 23.4% to £26.9m.
Underlying earnings per share rose by 24% to 27.4p, while the interim dividend climbs 2.1% to 19.4p per share. That puts PayPoint shares on track to offer a 4.7% dividend yield this year.
Adjustments to these figures don’t look too outrageous to me, although personally I would prefer to see costs such as legal fees (£2.5m) included within ordinary operating expenses. Even so, statutory interim earnings are up by 35% to 23.5p, covering the dividend sufficiently.
Progress seems to have been made in most areas of the business:
Shopping net revenue up 2.5% to £32.9m, with the number of installed PayPoint One/Mini sites up to 19,855 (Mar 24: 19,297). These terminals are typically located in convenience stores and provide the payment infrastructure for most store activities, including Ecommerce and Payments (see below)
E-Commerce (Collect+ parcels) net revenue up 56.9% to £8.0m. This was supported by a 47% increase in parcel transactions to 61.9m, so revenue per parcel improved from 12.1p to 12.9p. The Collect+ network expanded by 14% to 13,421 sites during the half year.
Payments & Banking net revenue down 0.8% to £24.9m. This fall was driven by the cash payments business where revenue fell by 1.3% to £15.2m. This includes the core legacy business of bill payments and top ups, which are generally seen to be in structural decline.
This weakness was offset by continued growth in digital revenue through PayPoint’s MultiPay platform (+3.6% to £2.9m), while digital net revenue delivered underlying growth excluding a £0.3m drag from the cessation of last year’s Energy Bill Support Scheme.
Love2shop net revenue up 7.4% to £8.8m. The company says underlying billings for Love2shop rose by 4.5% to £67m while Park Christmas savings billings are expected to be broadly flat this year, but should benefit from improved technology support in 2025.
There’s also a third arm to this business, gift card operator MBL which apparently supports clients such as Greggs and B&M. Gift card value processed during the half year rose by 38% to £40.9m.
Incidentally, for investors who would like a more in-depth understanding of this business, I would recommend looking at today’s results directly as they include far more detail than I can cover here. Additionally, today’s note from broker Panmure Liberum (available on Research Tree) makes an interesting read, with a useful breakdown of revenue growth in different areas of the business and in-depth commentary.
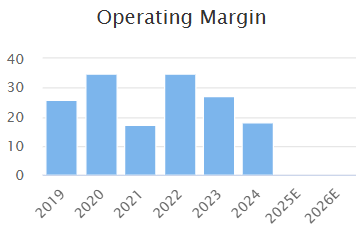
Profitability: at a group level, PayPoint’s profitability remains excellent. My sums show half-year adjusted operating margin improved from 22.2% to 24.8% this year. Assuming a similar result for the full year suggests a result towards the upper end of the range achieved in recent years:
However, the relative profitability of PayPoint’s different activities has never been clear to me. The company only reports its profits under two segments, PayPoint and Love2Shop.
This year’s half-year results tell us that Love2Shop generated a segmental underlying PBT of £2.3m, representing a 12% margin on net revenue or a 4.7% margin on total revenue.
The remaining PayPoint business fared better. Underlying PBT of £24.6m translated into a net revenue margin of 37.4% or a margin on total revenue of 28.7%.
Balance sheet & cash flow: net corporate debt (excluding lease liabilities) rose by £19.3m to £84.6m during the half year. This was due to a £15m investment in parcel operator Yodel and the launch of a £20m share buyback programme in July 2024.
Underlying cash flow appears to have been quite strong. Operating cash flow before movements in working capital rose by 14% to £35.7m in H1.
The current level of debt looks comfortable to me relative to forecast FY25 net profit of £51m.
Outlook: the company says full-year results should meet expectations, but I note that Panmure Liberum has cut its FY25 earnings forecast by 1.4% to 69.0p per share today. That’s slightly lower than the 69.5p consensus shown in Stockopedia prior to today’s results.
Panmure Liberum has also cut FY26 and FY27 EPS estimates by c.3%.
While PayPoint shares still don’t look expensive on 11 times forecast earnings, this more cautious outlook may account for the share price drop today – I guess investors might have been hoping for a modest upgrade.
Roland’s view
PayPoint remains a complicated business to analyse and understand. But my general impression remains that most of the things the company is doing to diversify and grow are probably working well.
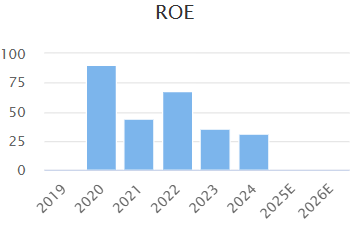
The key risk, I would say, is how much of Paypoint’s profit is still generated from the legacy cash payments business. Not knowing this may help to account for the stock’s relatively modest valuation despite its high returns on equity:
On balance, I think the shares are fairly priced, but not as compellingly cheap as they were a year ago. On this basis, I think it makes sense to moderate our view slightly to AMBER/GREEN.
JD Sports Fashion (LON:JD.)
Down 14% to 97p (£5.0bn) - Q3 trading update - Roland - AMBER/GREEN
The trading environment remains volatile though and, following October trading, we now anticipate full year profit to be at the lower end of our guidance range.
Unfortunately it’s a profit warning this morning from sportswear retailer JD Sports Fashion.
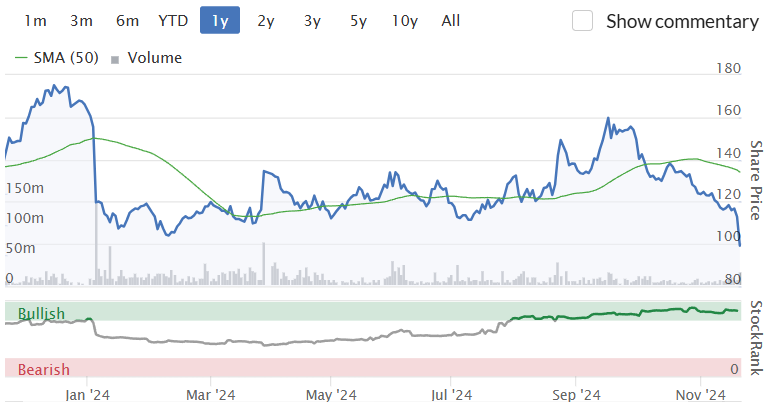
What’s gone wrong? Today’s update covers the 13 weeks to 2 November. The company says that after a strong back-to-school period, trading became more volatile in October, especially in North America and the UK. Like-for-like sales fell by 1.5% and 2.4% respectively in these regions.
JD says it maintained pricing discipline and actually increased its gross margin by 0.3% to 48.1%, while delivering organic sales growth of 5.4%. The company also opened 79 new JD stores during the period.
However, elevated promotional activity (from competitors), mild weather and cautious consumer spending ahead of the US election are said to have held back sales.
Volatile trading conditions have continued and management now expect profits for the full year to be “at the lower end of our guidance range”. This is helpfully stated as £955m–£1,035m.
FX headwinds also appear to have worsened due to USD strength, and are expected to reduce PBT by a further £15m versus the original guidance.
Roland’s view
No updated broker notes are available to me, but today’s share price drop suggests to me the market might be pricing in a 5%-10% cut in earnings per share.
Stockopedia was showing a figure of 13.1p per share ahead of today’s results, so I would guess an updated figure of perhaps 12p per share may be likely.
That would price the stock at around eight times forecast earnings – not obviously expensive for a successful and profitable retailer.
Although I’d personally be wary about buying after today’s profit warning, I think JD’s modest valuation suggests that I can still justify a cautiously optimistic stance ahead of the company’s full-year results. AMBER/GREEN
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

116 comments
Norcros (LON:NXR) - "Steady H1, building for the future" - link to latest note:
https://www.equitydevelopment....
Continuing businesses delivered H125 revenues, in line with last year’s comparator. Underlying profitability was also similar prior to costs taken above the line from a couple of discrete actions in the period. Net debt rose to 1x EBITDA, being in line with H124, and the company’s strong balance sheet position allowed it to absorb short-term working capital movements. Management expectations are unchanged and Norcros remains keenly focused on delivering strategic progress to achieve targets set out in May.
The Norcros share price has substantially out-performed the FTSE All-Share Index YTD. Nevertheless, across our estimate horizon, Norcros still sits on valuation discounts to its peer group averages ranging from 40-50% on a P/E basis and 25-30% for EV/EBITDA whilst offering a 25% dividend yield premium. We believe that sector sentiment will improve and this will support share price progress generally but Norcros offers more than cyclical recovery in our view. As strategic action outcomes become more apparent (e.g. in EBIT margins) we would expect to see further share price outperformance for Norcros.
Under our DCF approach, the current share price is equivalent to ‘steady state’ EBITDA of c£63m; so some progress beyond our FY27E estimate is being factored in but not yet the higher potential levels that we have highlighted previously.
Speedy Hire (LON:SDY) - "Positive start to important H2 trading period"
Market conditions have been challenging but Speedy has delivered resilient metrics in H125 trading and is investing for growth.
All eyes now turn to an expected acceleration of revenue and profit growth in H2 with visible drivers for doing so. The recent share price performance suggests some investor scepticism that this will be achieved, but a c.11% NAV discount and 9.2% prospective dividend yield also catch the eye ahead of further newsflow.
We have retained our 51.1p/ share fair value estimate and evidence of accelerating H2 growth will justify this position. Ahead of that, we note that Speedy is now trading on an 11% discount to its H125 NAV and offers an FY25E dividend yield of 9.2%.
Link to latest research note (freely accessible): https://www.equitydevelopment....
Cohort (LON:CHRT) - SATCOM deal is Group’s largest acquisition - our latest note is freely accessible here: https://www.equitydevelopment....
Cohort has announced a conditional sale and purchase agreement to acquire EM Solutions Pty Ltd from Electro Optic Systems Holdings Ltd, for an enterprise value of AUS$144.0m, c.£75.0m This is Cohort’s largest acquisition to date. The purchase will be funded from Group cash resources, debt facility plus a share placing, and is expected to be EPS-accretive from FY25/26.
EM Solutions offers a range of satellite-based secure communications systems including satellite on-the-move (SOTM) and radio frequency (RF) systems, plus contract manufacturing and design. For Cohort it adds complementary expertise in satellite communications for global naval and defence applications.
We estimate that the acquisition enhances Cohort FY25 revenue by 4% (pro rata for 151 days remaining) and in FY26 by 17%, with an uplift to (adj.) EBIT of 10% and 32% respectively.
Our Fair Value is raised to 1090p/share, indicative of a FY26 E PE of 19.4x and EV/EBITDA of 10.1x. This compares favourably to a market cap weighted average for Cohort’s peer group of: PE, 21.3x and EV/EBITDA of 12.1x - see our research note for more.
Has anyone worked out the cost of the NI for JD Sports Fashion (LON:JD.) when it goes up? They employ 52.5k in the uk.
Pretty sure I read some where back that J D Wetherspoon (LON:JDW) were going to see increases in NI of about £40m and they employ about 32.5k people.
Also, it would be interesting to see how Trump’s import tax may effect JD Sports Fashion (LON:JD.)
I agreed gm - whilst no doubt there was a good company (insomuch that it preyed on the youth wanting the latest gear), I have never been attracted to it. My teenage daughter loves it, I'm sure she does, but she's not the one parting with over £100 for a pair of trainers!
I have slowly shown her that with some time and patience, you can grab same (or at least similar) trainers for £30-£40 quid just waiting for online sales at other retailers. As an example, I managed to score Adidas Campus 00, the 'must have' trainers:
https://www.jdsports.co.uk/pro...
£90 in JD Sports, I found almost identical Adidas Campuc Vulc:
https://www.schuh.co.uk/kids/y...
£25 and I collected for free.
Yes, their not exactly identical, but when wearing the massive baggy jeans so you don't even see the trainers, she genuinely was over the moon and it was like I had presented her with a huge diamond. I'm in her good books for a few days at least.
I too worry about the NI costs, the service in JD is appalling and is run by kids with no work ethic and if Trump does bring in import duties, how will that work for the US market?
To be honest, I could afford the £100 trainers, but that's not the point, and I know others that can't afford them, but will be buying them at Xmas to appease their kids. I keep saying that this can't last forever, but it has seemed up until now a lone voice. Perhaps people are starting to wake up?
You can buy those trainers in Next (LON:NXT) for £50: https://www.next.co.uk/style/s...
l think you can get them from Adidas for £45: https://www.adidas.co.uk/campu...
lt pays to check online for prices.
Unfortunately, these are for small children - I came up against this when searching!
I see, yes it is a problem when searching for prices. Find a really good price but then it is for only large or small sizes.
For companies with a predominantly minimum wage cohort, working between 20 and 40 hours per week, the additional cost is £600-£700 per employee. The hours above 20 count for little. If they work much fewer than 20 each, then proportionately lower.
"Has anyone worked out the cost of the NI for JD Sports Fashion (LON:JD.) when it goes up?"
They mentioned it in the call yesterday; there will be a £30m total impact, split between NI and NMW.
For context UK sales were £3.5b last year, c30% of the total sales.
JD Sports Fashion (LON:JD.)
As a holder my biased opinion is that I don't understand the large drop today.
I think most of my thoughts have been covered on this page already, but to add a few more:
Any benefit from this is currently not included within the guidance range.
With peak season upon us this could add £10m-£20m of PBT (this is my estimate based on Courir's past performance).
So perhaps we'll see an increase in guidance as soon as next week?
The board said this had not happened before, which is why they weren't expecting it.
Hopefully just a blip.
This doesn't seem like a disaster.
This just seems too cheap for such a quality, cash generative company, which is why I still hold.
A
Thanks for this great deep dive. Is a Trump tariff factored in please?
CMC Markets (LON:CMCX) had a closer look this afternoon. Originally thought sell off was overdone and irrational, but think the market might have got it right on this occasion. While at first glance it looked like a huge jump in profits v H1 24, it was actually quite a marked slowdown v H2 24.
Guidance also appears to have slipped a bit in recent months - in June they said they expected operating income to be in the 320-360m range, they are now effectively guiding to 333m. I'm guessing companies hope to hit the top end of the range, so this suggests trading has been a bit on the softer side verus what they were expecting. Therefore, while still performing well overall, momentum has clearly waned over last few months and very different to earlier in the year when it seemed to be a string upgrade.
Perhaps you shouldn't read too much into a couple of months trading - especially given how volatile earnings can be. Nevertheless, I'm not going to be adding just yet (still keeping a small position).
yes if i could be bothered to use it.
Brief thoughts on Liontrust Asset Management (LON:LIO.
They can’t afford to maintain the dividend. That £5 million buyback is a waste of money. What will it achieve?
As I see it the share is so cheap that it might well take a dividend cut or even temporary cancellation in its stride. And because a dividend cut is needed the share price might well see it as good news.
I’ve a portfolio full of current big dividend paying shares and Investment Trusts but all of them, unlike Liontrust Asset Management (LON:LIO) have dividends that look safe or can even be increased. If that changes on bad news I usually sell. It was surely yet another poor update today with yet more outflows and excuses and (unjustified?) Outlook and other optimism.
I hold Liontrust Asset Management (LON:LIO) at a modest loss and small profit with dividends included. I’ll hold on as it’s so cheap with so much bad news priced in, and the chance of that cheapness tempting a bidder.
(Against that a profits warning and worsening outflows along with “sorry but we can’t now pay that 52p dividend’” can’t be ruled out.
The Fund Managers all look at tempting prices (why has been fully explained here already) and sometimes with big and probably sustainable yields, while waiting for significant share price upside. Dream of those outflows becoming inflows again as is already the case with Polar Capital Holdings (LON:POLR).
Liontrust Asset Management (LON:LIO) Directors bought £500,000 of shares today at a price of about 450p
More importantly for investors, business now face the highest energy prices in the developed world. Another wave of deindustrialisation is happening, with Germany leading the way in the EU.
Exporting industry to China, leaving Europe exceptionally weak should they invade Taiwan. 2 internet cable were cut between Germany and Finland recently, wouldn't take more than a few subsea drones to cripple UK energy.
what is comical is that i think one of the leading labour mouthpieces was on not so long ago saying that renewables would be bringing down energy prices medium term !!! - its bad enough going totally ott on renewables but pretending they are the near term solution to prices rises is akin to having mike ashley appointed as owner of your football club then having steve bruce appointed as manager - double kick in the you know whatsits.
"WINTER IS COMING" - well in last couple of days it's here. What happened to global warming - ok warm planet equals ice age. Sorry if I don't understand and suspect 'the science' is a bit clueless as well.
Thinking of electric blankets - Silentnight, Dreamland, - all 'designed' in the UK (aka we need it) but supplied by China of course - but needs must.
Anyways looking to clean the ice off my solar panel tomorrow - let's hope I don't slip and reach my demise before the tax man taketh.
And if you have an electric car would advise buy some good gloves and a hat to extend your range lol - other than to the local Waitrose.
and the same in the style of Jeremy Clarkson :
Right, let’s get into this JD Sports malarkey, shall we? It’s a proper mixed bag of triumph and trouble, like finding a tenner in your pocket but realizing it’s laundry day. On one hand, they’re smashing it with global store openings—181 new stores this year alone, and now they’ve got 4,541 stores worldwide. That’s more locations than the number of times I’ve been late for dinner. Hats off to them for keeping the tills ringing!
But here’s the rub: their like-for-like sales are down in big markets like the UK and North America. That’s a bit like buying a Ferrari, only to find out it won’t start. Sure, they’ve got organic growth ticking along at 5.4%, but it’s mostly because they’re opening new stores faster than a teenager opens TikTok. The real question is, what happens when they run out of places to build these shiny new shops?
Then there’s this weather excuse. Apparently, mild October weather put people off buying winter coats. Come on, folks, the weather’s never been predictable! It’s just a bit of drizzle—deal with it.
And while they’re keeping their gross margins up at 48.1%, there’s a bit of a wobble on their profit outlook, with numbers drifting towards the lower end of their £955–1,035m range. You can almost hear the finance team sweating.
Questions That Beg to Be Asked:
I asked Chat GTP to come up with two questions after analysing the JD Sports Fashion (LON:JD.) statement :
Analysis of the Statement
JD Sports has shown resilience in a challenging market by leveraging its global expansion strategy, improving margins, and maintaining organic sales growth despite headwinds like trading volatility, cautious consumer spending, and unseasonable weather. The standout performance in Europe, coupled with robust store rollouts, underscores the company's ability to execute its growth strategy. However, weaker LFL sales in core markets like the UK and North America raise questions about the sustainability of growth driven by new store openings versus in-store performance.
Two Insightful Questions
Why doesn’t the AI just suggest everyone calm down and wait for a cyclical upturn
Not covered here today are either the Ithaca Energy (LON:ITH) Results or the near 10% special dividend announced today. With another big dividend promised this increases the yield to around 25%.
What’s the catch? Up till now the dividends haven’t covered the relentless share price falls since Ithaca Energy (LON:ITH) was the biggest IPO on the UK market at an inflated 250p in November 2022.
Details about that IPO in this link:-
https://www.reuters.com/market...
Now at just 105p and down about 65% since the IPO Ithaca Energy (LON:ITH) 96 value rating looks justified.
Dividend is paid in dollars but fortunately the shares are traded in £.
The special dividend announced today is $0.1209 which is a bit under 10p at current exchange rate. Ex dividend is next Thursday 28th Nov and pay day Dec 20th.
I bought a half stake too soon on my buy when a quality share or Investment Trust is at a bombed out price tactic, which so often works. But with Ithaca Energy (LON:ITH) it was too soon at 130p. I’ve averaged down today at £1.06p.
At this price and bearing in mind their Results comment today it could be that this is as low as Ithaca Energy (LON:ITH) will go, bar the usual caveat that any share can be hit by unexpected bad news.
https://www.stockopedia.com/sh... for their Results.
There is a total paucity of information on Cohort's acquisition of EM Solutions from ASX-listed AMS. Have I missed something?
I have written to them as the purchase price in the context of ASX's enterprise value seems generous. ASX itself continues to lose money with pre-tax losses last year of Aus$ 40.2 million which is an improvement on the previous year pre-tax losses of Aus$ 62.9 million. Although the AMS balance sheet is liquid (and about to become much more so), accumulated losses amount to Aus$ 241.8 million.
I have pored over AMS last accounts and can find little illumination on the financial performance of EM Solutions, and I can find little information from Cohort on the contribution EM Solutions will make to Cohort's performance next year and the expected impact on EPS.
I have written to Cohort seeking some clarity and will report back.
Bit of a poor show especially when they were seeking partial retail investor support for the few crumbs they threw us.
Our latest note is here, if of interest: https://www.equitydevelopment....
Graham, I would very interested to hear your views on the Phoenix Group , there is a consolidation going on with local council pension funds, this could be a good development for Phoenix?
They usually only comment on updates or news, can't see anything on Phoenix group (LON:PHNX) today.
This is the last article featuring Phoenix group (LON:PHNX): https://www.stockopedia.com/co...
Thanks for this
Interesting thought - I have assumed that it is the investment/fund managers who will benefit, but maybe insurers also - or maybe none of the above.
Cohort (LON:CHRT)
Sale and purchase agreement to acquire the entire issued share capital of Electro Optic Systems Holdings Limited, listed on the Australian Securities Exchange (ASX: EOS) for (c.£75.0 million).
Developer and producer of high-end SATCOM terminals for global naval and defence customers.
EM Solutions will operate as the seventh stand-alone business within the Group, reporting through the Communications and Intelligence Division
Seems a good fit for a very interesting diverse defence contractor.
And what a bonus to those who picked up the placing today at 875p whilst the shares have run up to 950
Apologies Harry, but your statement is not correct.
Electro Optic Systems Holdings (ASX:EOS) remain listed on the ASX. They are disposing of one subsidiary company which they acquired if memory serves me in 2019 called EM Solutions for a consideration of £75m. EM Solutions is regarded as non-core and will enable EOS to focus on its remote firing tech and anti-drone tech.
EM Solutions is a developer of microwave and on-the-move radio and satellite communication products. EM Solutions designs, assembles, tests, and supports high-end, broadband radio transceivers and satellite communications-on-the-move terminals. The solution can be fitted on multiple platforms but is at heart a naval system.
Here is a video on what they do:
EM Solutions - Radio waves at work on Vimeo
Given the information we have at present, it is difficult to see whether Cohort have made a good purchase or not. I don't doubt the strategic fit within the Cohort portfolio, but we do not have operating figures (if someone does, please do share). The Enterprise value of Electro Optic Systems Holdings (ASX:EOS) was £122 million, so £75 million in cash is very material for them. EOS shares have performed abysmally, and I do not hold. I do however hold Cohort (LON:CHRT) . With their buy and build strategy, Cohort are evolving into a Judges Scientific (LON:JDG) , although they buy fewer and larger companies in a different engineering space. I hope the Cohort board are as astute as Judges Scientific were in their glory days, but I worry they have overpaid. With no data, we do not know.
Anyone any idea why Auction Technology (LON:ATG) is down c.7% today on what looks like a fairly sensible NED appointment?
It's a note out from Jeffries rating 'underperform'
A very interesting week for me with Diploma (LON:DPLM) , Halma (LON:HLMA) and Renold (LON:RNO) (I hold all three with Halma and Diploma being my top two holdings).
Watching the analyst presentations from Diploma and Halma have really demonstrated the basics and clear reporting behind quality compounding. Number one requirement is organic revenue growth, disclosed right up front in the report and stressed in the presentations. This together with high operating margins and strong cash conversion, gives the right to acquire businesses on sensible multiples.
That is why it is so disappointing so see Renold leave it out of their report. The market sees right through it and marks the shares down.
Borneo and Indonesia and even Sumba Island
Fascinating to see and hear world views from a diffetent stance .
The Americans are pretty much despised over here for their decades long plundering of resources by colluding with president elect and pocket filling family Soeharto with grossly unfair onesided trade deals .
Roll into town Jokowi a sort of robin hood / equaliser president who rips up unfair trade deals built on corruption, and builds new roads and infrastructure for all across their lands to benefit frpm lets the countries consuming their minerals and resources know there is a new king in town who is not for turning .
Borneo appears to be the worlds coal mine with 40% export to germany 20% to UK
Seemingly the British and Russians are well liked and they “are working together behind the table”
The chinese are buying everything they can .
We burn their open cast coal in huge wuanitotes
They now replant forests on top of the open coal mining something the Americans never did in the soeharto years
Doesnt affect any share prices.
Good to hear we are keeping pour CO2 down by importing coal from half way round the world.
You are absolutely right to be concerned about our carbon emissions and it is, of course, imperative to reduce them. Happily, coal use in the UK is plummeting - we are the first G7 country to end coal generated electricity, and our overall consumption has fallen from 157 million tonnes in 1970 to just 587,000 in 2023. This demand is set to fall even further. It does seem daft to import the little coal we do still use given that the UK is an island sitting on coal, but a government in the 1980s (I can't remember which one) destroyed the UK coal industry for some reason. Still, the good news is that carbon emissions from coal burning are far, far lower than they used to be.
Ending coal burning is good but it has been replaced by biomass which apparently even more polluting than coal. Also it being shipped in from the US and Canada.
Yes, Drax burning wood from Canadian forests to generate electricity (and getting a £6 billion subsidy to do so!) Is no rational way to reduce carbon emissions.
Drax (LON:DRX) has always been essentially a con. Burn wood and pretend it isn't similar to burning coal. Goodness knows how the word "biomass" fooled people into thinking it warranted eco-subsidy.
planetx Good to know we’re ‘in the good books’ somewhere. Hope you’re wrong re share prices as SRT Marine Systems (LON:SRT) are expected to sign a large deal with Indonesia soon – coincidentally the president has just arrived in the UK.
I am heavily invested in Jd Sports and have been for a couple of years. This is a worrying drop. I would appreciate a few words of encouragement from more experienced board members, and maybe a summary from Graham. I really need a pat on the head and someone telling me it will all be OK...in the end!!!!
Check the share price chart history, they have always bounced back from such falls. I don't hold JD Sports Fashion (LON:JD.) at the moment but was sorely tempted at 95p.
Me too. My average is 122 after re buying after the spike. I’m going to keep adding at these levels, in my opinion it’s a steal. However I don’t expect much to be happeneing in the short term. Long term, I believe things are looking good with the growth model on track and consumer confidence will rise 25 with lower interest rates and trump in charge. It is annoying though, as I’m significantly down on this, makes up 25 percent of my portfolio. Anyway, hold tight. Not lost anything until you sell!
Wow - 25% of your money in a sports fashion retailer, eh! You won't be tracking any indices with your portfolio then.
No, got caught off guard a little but im not too worried. I tend to only have 4-5 stocks in my portfolio. I returned just over 50 percent with jd over the last year buying and selling the spikes. I’ll stick with it as it’s inevitable we will see an upturn at some point
Hi Megan,
I agree NVIDIA (NSQ:NVDA) is an extraordinary business but I take issue with you saying: "Sure, if you use traditional valuation ratios, its share price might cause a bit of anxiety, but market dominance and growth like this can’t be measured on traditional ratios." I could understand you saying it might not be as expensive as it first appears, because prolonged growth justifies these high ratios, but ratios do precisely (attempt) to measure the rate and duration of growth. Ratios ultimately condense to present value of future cashflows. It is v.hard to get this right, but ratios are wrong because they over or understimate future earnings not because they can't be measured. I have no view on whether Nvidia is still a buy but think we need to stay grounded in a theoretical financial framework to prevent getting caught up in market emotion.
I've worked in IT all my career and still hold a couple of senior part time decision making roles. My observations are that 1. If you look at Nvidia sales they are nearly all to other "IT services" suppliers - the rest of the mag 7 loom large. 2. At some stage these IT Services Suppliers are going to want to monetise this investment. That means selling AI products and svs to the likes of my firms and even the consumer. I think AI is cool, needs to be on the "we're doing it too" list and has some benefits in places but.... I see nothing like the revenue volumes that can even remotely justify NVDA valuation. Everyone (in IT) I talk to seems to say we're experimenting with it but not getting huge value. When this gets reassessed there will be carnage.
Plus I don’t trust anyone who insists on wearing a crocodile skin black leather jacket. ‘Personal branding’ isn’t working for me.
I also work in the IT industry and I think that part of the problem is that AI is just already integrated into solutions. Office workers will use an ERP like Workday or Oracle with AI integrated, Microsoft office packages will come with copilot, management consultants will be armed with gen AI assistants, designers will use AI infused Adobe tools to make their work easier.
There are lots of use cases of AI providing value to consumers, but because its just been integrated into existing toolsets it has become the base expectation and therefore harder to demand the additional revenue to offset the investments.
I look at it like this ...
Generative AI, for example. i.e. stuff that does art. If one wanted to put a pic on a website, then the AI would have to compete with stock photo sites, which aren't likely to be a licence to print money.
I bought myself a smartphone recently. My first one. A fairly cheap moto, not those expensive iPhones that the hipsters like. I'm actually quite impressed with it. I like how I can speak into it and it will set alarms and reminders for me. That's kinda "AI", but I don't have to pay for it, and its tech that's been around for over a decade.
IMC (Investor Meet Company) do a nice thing where they get AI to summarise RNSs. That was quite nifty, but again, we have to ask ourselves how much someone would be willing to pay for this service.
As I keep saying to my mate Dave over in the States, I am still not convinced what AI is supposed to "do", what problem it is really trying to solve, and how much money it can generate from whatever problem it is that it's allegedly solving.
It's not totally without entertainment value, mind. Occasional amusement comes from recipe ideas like adding glue to pizzas, the recommended daily allowance of rocks we should eat, not to mention how a certain German painter did no wrong.
As I keep saying to my mate Dave over in the States, I am still not convinced what AI is supposed to "do", what problem it is really trying to solve, and how much money it can generate from whatever problem it is that it's allegedly solving.
huh - have you not seen what chat gpt and similar can do - whether that be summarising meeting notes - doing coding - producing reports - checking grammer and the like. surely the options to auomate tasks are easy to spot and clear cut at the basic level . as ai improves that should obviously over time allow us to auomate more and more of the everyday tasks - eg ai is almost non existent right now ref book-keeping but in five years time it wouldnt surprise me if there is some fancy ai that could replace a semi competent book-keeper for 85% of the tasks.
obviously what we dont know is if the ai might hit a roablock soon where it stops improving exponentially - the strides in ai since gpt turned up though are pretty damned imressive to me even if the ai is getting the end results via brute force work rather than using real intelligence - even if its just copying pasting and following rules alot of what can be done is impressive to me.
Can it spell check your posts...?!
8-))
There is a major difference between the open source models that have been trained on the internet (the ones which spout out rubbish like the recipe ideas you mention) and the curated models trained on client specific data. AI will impact most industries and jobs, empowering employees by cutting out monotonous tasks and letting them focus on higher value work.
The entertaining side of AI is pretty much a by-product of the genuinely transformative technology - but unfortunately one of the only experiences the masses have in using gen AI.
Reminded of these type of stories during the dot-com bust. Will no doubt see the same thing with AI during the next sector selloff
at least the daily mail have been consistent with the quality of their stories over the years.
oooh whatever hapened to IF
I am really enjoying these new reports. Great work guys. I would be interested in hearing your thoughts on JD Sports Fashion (LON:JD). It has tanked recently (right after I had a nibble!).
CMC Markets (LON:CMCX) [I hold] getting trashed in early trade, down almost 12% on what seems to be reasonable results, in line with the latest trading update and market expectations. Massive profit taking maybe or did I miss something reading the RNS? Might the market valuing this as earnings decreased compared with H2?
I am struggling to find anything bad in CMC's numbers but suspect some profit-taking and anyway, the dip presents an interesting access point for those who missed this boat previously
CMC Markets (LON:CMCX)
I am struggling to find anything bad in CMC's numbers
I alwasy go straight to they outlook - they say
we are confident in delivering on the guidance set out at the beginning of the year, with net operating income forecast to be in line with external market expectations
Ok this isnt exactly helpful as net operating income is a completely irelevant figure in most expects (dont get me wrong its useful to know and good if that number is higher)
In the absence of anything to the contrary i will presume they are on traget to hitty stocky expectations of £46.9 net profit for the year. H1 they have done £35.3 mill - so that suggests they expect to do £11.6 mill h2.
Does anyone disagree with my maths ?
If there a logical reason for the fact profits are expected to crater h2 if my calcs are correct?
If my calcs are correct i would say their obvious inability to communciate in the outlook section the reasons perhaps may be what has caused the price drop if people dont have time to dig into then detail and presume the worst (probably wrongly)
Having held cmc in the past and knowing how similar stocks work like igg and plus - i am fully aware there is sometimes little visibility as to how they will do in the next 3 or 12 month period. so it makes sense to me that they would hopefully normally be cautious here and hopefully the real good news comes at the end of year trading update when their plans for the worst dont come true and they can beat expectations at that trime.
In summary i think the thing is not to get too carried away when things are going great and perhaps be chilled when they hit a poor patch (i always worry myself when poor patches turn up as it isnt always easy to get out of a rut)
Overall if i was a holder i would simply be looking at overall progress here and say they are doing fine. personally i bottled it with this share and sold out just in case they couldnt continue the good run they had had - when i bought though it was more a punt on the "reasonable" times returning at the lows. It does seem a very well run buisness i must say despite my worry about visibility ref profits (and slight worries over regulation too)
CMC does have wild swings - profits fell sharply a couple of years ago (after the pandemic era boom) and the share price collapsed below a pound. The market doesn't seem to grasp that profits here are cyclical, massively overreacting in both directions - the SP went from 530p in early 2021 to 90p by late 2023, even though nothing fundamental had change about the business.
RE: CMC Markets (LON:CMCX)
It is highly cyclical but the post-pandemic contraction in revenues coincided with significant internal investment in new systems, so the apparent collapse in profits was somewhat overstated. As the commentary today indicates, the peak of that is behind them.
The investment is supposed to decrease dependence on the traditional spreadbetting side, but that remains to be proven.
But a 14% fall on in-line results - that's not the sign of a well functioning market.
timarr
CMC Markets (LON:CMCX)
But a 14% fall on in-line results - that's not the sign of a well functioning market.
what is your explanation for why they are saying h2 net profit will be £11.6 mill when h1 net profit was £35.3 mill. Are my figures wrong or are you glossing over the fact they are telling us h2 will be worse ? to me the market reaction to the expected short term drop in profits is natural ? - the market tends to concentrate on the near term future in absence of anything else useful. Note as long as next year expectations remain intact as they were befroe today that should somewhat calm the market - but as of yet i havent seen any comments ref next year and i suspect the market is more comncentraing on then next 6 months.
To me unless my figures are wrong the drop is an obvious reaction too the fcat they are telling uis h2 is gonna be worse than h1 as the explanation as to why is not obvious (to me at least)
Note i remember selling up igg when they have cautious tone a few years back - the reality was there outlook was over cautous and they delivered great numbers after i had sold. So i am not saying there is something to worry about just that holders should expect droip in price if the near term profiots are takinga hit without clearly explained reasoning.
rmillaree, I completely agree with what you're saying. The thing is that market consensus forecasts for CMCX are not worth the paper they're not printed on, because nobody knows what CMCX's NOI is going to be and CMCX do not have a habit of telling the City to upgrade them in a timely fashion.
In August 2023, the company itself put out a forecast of £250-£280m for FY March 2024.
At last year's interims, they reiterated this guidance. It was mid-November 2023, almost exactly a year ago. They again said NOI would be £250-£280m. There were only 4.5 months left in the financial year.
They did not upgrade until January, when they said it would be £290-£310m.
It turned out to be £333m
G
what is your explanation for why they are saying h2 net profit will be £11.6 mill when h1 net profit was £35.3 mill. Are my figures wrong or are you glossing over the fact they are telling us h2 will be worse ?
Hi rmillaree
RE: CMC Markets (LON:CMCX)
I'm not sure what my motive would be for glossing over anything really. But as you haven't posted your workings I can't comment on your £11.6m figure other than to note I don't understand it.
They did £177.4m net operating income in H1 and confirm expectations of £332.9m for the full year, hence they expect a drop in H2 income to £155.5m. They also predict full year operating costs (minus variable remuneration) of £225m, and with an H1 cost base of £11m that gives H2 operating cost of £114m.
A quick and dirty way of estimating each half profit is to subtract operating costs from net operating income plus variable remuneration - so in H1 that would give us £177m - £111.4m - £12.5m = £53.5m and then there's around £1m of recurring finance costs and what appears to be a one off associate impairment of £2.3m to get us to H1 PBT of £49.6m.
H2, using the same calculations, and assuming the same rate of variable remuneration, gives us £155m (net op profit) - £114m (fixed costs) - £12m (variable remuneration) - £1m (recurring finance costs) = £28m PBT. After tax that's about £21m I think, although I don't normally calculate that.
That's possibly a slight underestimate as variable remuneration costs fall with falling PBT.
Of course, I may have missed something but the net operating income expectation is unchanged, the cost base has dropped as expected and the variable remuneration is a known unknown. So what did the market have to take fright at other than an unchanged forecast?
As a general statement CMC Markets (LON:CMCX) is heavily exposed to short term changes in markets to the point that most forecasts are pointless anyway. A Santa Rally or a Middle East crisis could mean those H2 numbers are wildly out.
timarr
CMC Markets (LON:CMCX) The way I have looked at it is similar:
333m revs - 225 op costs - 25 (12.5 variable x2) - 2.8 (1.4x2 interest) - 2.5 (associate costs) = 77.7m pbt, 55.24 pat (28.9%) / 276m shares is c20p as per stocko.
If h2 revs = h1 then eps may be c 25p
If they match h2 at 210 then eps may be c34p
We don't know if they are expecting any non-recurring costs in H2.
They have changed narrative from 320-360m at Q1 update to now saying in line with external forecasts with consensus being 333m. Not sure we can look too much into that either.
So I'm not surprised they haven't said they are ahead, all down to how it goes in H2 which seems quite volatile.
CMC Markets (LON:CMCX)
But as you haven't posted your workings I can't comment on your £11.6m figure other than to note I don't understand it.
my calcs were as per my earlier 9.30 post - i have defaulted to the bottom line net profit figure as thats the figure thats available on stocky and is the bottom line sum being delivered to shareholders come year end - to me the mismatch betwen teh two sums kinda explains the reaction today to me (perhaps its as someone else said the market was expecting upgrades?)
In the absence of anything to the contrary i will presume they are on traget to hitty stocky expectations of £46.9 net profit for the year. H1 they have done £35.3 mill - so that suggests they expect to do £11.6 mill h2
i think you are looking at the net profit for last year, forecast for this year is 58
CMC Markets (LON:CMCX)
i think you are looking at the net profit for last year, forecast for this year is 58
yes you are correct - what a numpty i am. yes much less wonky split if you add in the extra £11.8 mill profits i missed from h2 by using the 2024 forecasts and not 2025. Apologies to all for pumping out fake numbers. Gotta remember half the time now we are living in 2025 not 2024 !!
RE: CMC Markets (LON:CMCX)
In the absence of anything to the contrary i will presume they are on traget to hitty stocky expectations of £46.9 net profit for the year. H1 they have done £35.3 mill - so that suggests they expect to do £11.6 mill h2
There is evidence to the contrary in the H1 results statement today. The estimates in Stocko are unreliable anyway, I never even look at them, but for a stock like CMC they're equivalent to a drunk, blindfolded monkey throwing darts at a rotating board. Or, as we like to call them, analyst reports.
As it stands we're looking at something around £55m - £56m net profit, possibly a little higher. That's about a 4% miss on those consensus estimates of £58.6m.
We're nearly 3 months into H2 and normally their short term estimates are fairly decent. However, there's a deal of uncertainty around as we near the government transition in the US so I have very little faith in them, one way or the other. Volatility tends to improve profitability though.
The main thing about CMC is that the operational gearing is critical. Even relatively small changes in net operational earnings can have an outsized effect on profits. Investing with CMC is akin to a rollercoaster ride, there's always something around the corner - you only have to look at the dividend record to see that, remembering that their policy is to pay out 50% of profits.
In the end CMC is all about Peter Cruddas, who owns nearly 60% of the stock. However, he's 71 and, although he shows no sign of slowing down, there must come a point when succession plans loom.
timarr
I am clearly smarter than I thought.
With decent holdings in RNO, CMCX, LION, PAY and Jet2 I seem to have devised the perfect market neutral portfolio in recent weeks!
Raspberry PI Holdings (LON:RPI) - FGS - news today (Times radio) that Raspberry circuit boards found on drones in Russia and the shares at top of leaderboard - since dropped down as others have overtaken but still up 2.5%
Jet2 (LON:JET2) (I hold) Another set of excellent results with profits up 20% on last year.
“Winter 2024/25 on sale seat capacity is currently 14% higher than Winter 2023/24 at 5.11m seats.
With a material amount of the Winter 2024/25 season still to sell, we are currently on track to deliver Group profit before FX revaluation and taxation for the year ending 31 March 2025 ahead of market expectations, assuming no material extraneous events in the remainder of the financial year.”
Agree. My investment in Jet2 was made many years ago, after flying with them. I was surprised at the quality of service - many more staff on the group when compared to EasyJet and Ryanair - the whole experience was so much better and continues to be so. Parking their new aircraft on EasyJet’s home base at Luton will be interesting to watch.
Having travelled with Jet2 (LON:JET2) a handful of times, I'm also a big fan. Last trip was in September and everything was miles ahead the likes of Ryanair and Easyjet. The staff are so well trained and friendly, and all the planes I have been in have been brand new and comfortable. I was holding just before covid, but managed to sell before the big fall, and decided to buy in again earlier this year as I'm such a big fan of the company.
My only worry is that the pricing can be quite steep. I would expect to pay more as the product is better, but flights only for a holiday that we are planning in Europe next year for 4 people came to over £3k, which I found a bit crazy. Easyjet was about £2.5k so not that much cheaper, whilst Ryanair was less than £1.5k. Although I tend to avoid Ryanair, which such a big price difference I feel like it's unavoidable! Saying that, when we flew in September Jet2 was about the same price as the competitors when we booked it as a package due to all the discounts that I could apply to the trip!
JD Sports Fashion (LON:JD.) profit warning, shares are down 10% to only 100p.
JD Sports Fashion (LON:JD.) I thought "lower end of guidance" might get a better response than -14%. I see B Ackman has bought Nike (NYQ:NKE) which is no doubt interesting long term but still looked a struggle to me after a read of their last statement yesterday.
JD Sports Fashion (LON:JD.) I thought "lower end of guidance" might get a better response than -14%
Given the falls into earnings I expected it to tick up a couple of ppts on relief things were only so bad as to stay within the estimates band!
Good to see the piece on Nvidia.
It is also worth mentioning the new Taiwan Semiconductor Manufacturing plants in Phoenix Arizona have recently received $6.6 billion of CHIPS act funding for production of a range of semi conductors - incluing AI chips.
The first plant is due to commence in 2025.
There is a catch 22 situation developing as some Republicans are unhappy that such funding is being used to support non US companies even though it is moving critical manufacturing from Taiwan to the US.
I expect that this situation is also weighing on the Nvidia share price. Let us see what January brings...
Breedon (LON:BREE) (I own) read quite well. The first statement this year the LFLs were -9% so they have recovered well to be only -1% in last four months. To my surprise they are talking optimistically about a mkt bottom in the UK ... not reflected in house builder statements. My personal view is Breedon (LON:BREE) is unlikely to be a stock of the year but a well run company in a sector with decent long term tailwinds experiencing cyclical weakness. The latter is in the price but longer term growth is not. Speedy Hire (LON:SDY) also hinting a better times to come and potentially interesting as the Amey contract kicks off IMO.
I hope you can join us next Wednesday at 2pm to hear from the Speedy Hire (LON:SDY) team. https://www.equitydevelopment....
Lots of discussion in today's analyst meeting about the early mobilisation of Amey, the TIC opportunity and turnaround in Trade and Retail.
They were never going to hit 1.5m homes in this parliament and they knew it. There aren't 10s of thousands of spare bricklayers twiddling their thumbs at home waiting for the government to give them the green light.
I would agree.
My forecast would be circa 800,000 homes for the 5 year period.
Gosh busy day today again! PayPoint (LON:PAY) Liontrust Asset Management (LON:LIO) CMC Markets (LON:CMCX) and Jet2 (LON:JET2) all reporting. Some big favourites with the crowd here and I hold all four. Early zip through and all look promising to me despite the pervasive UK gloom. Come on UK!!
I hold all 4 also. Can't believe CMC Markets (LON:CMCX) is down 12%.
Restore (LON:RST) - "Management actions driving profit growth" - new note here: https://www.equitydevelopment....
Restore’s ten-month trading update reiterates profit expectations for both FY24 and FY25. Excellent progress is being made in delivering cost savings and driving profit margins, a clear priority for this management team. This has offset some market softness around the Autumn Budget as well as a £3m headwind for FY25 relating to increases in employer National Insurance Contributions and the National Living Wage. Absent these changes, we believe Restore would have been primed for an earnings upgrade looking into next year.
A recent investor site visit provided a reminder of Restore’s quality, as well as medium term growth ambitions. In our view, this is not yet reflected in an FY25 P/E rating of <14x.
We reiterate our 400p Fair Value estimate with confidence in the Group's growth trajectory.
Hi Graham. You were very positive on PayPoint (LON:PAY) previously. After a strong SP rise over last few months and good results today I’m assuming that opinion hasn’t changed?
Figures are good from PayPoint (LON:PAY) but are they on target to meet the full year forecasts? I hold. I expect a fall today but l will probably be wrong.
Rusty, PayPoint said:
We remain confident in delivering further progress in the current year, meeting expectations and achieving our medium-term financial goals.
The market seems disappointed, shares were down 6%.
Momentum traders exciting on an 'in line'
PayPoint (LON:PAY) Maybe but l think quite a bit to do in second HY, to hit forecasts.
It's now a more seasonal (H2 weighted) business because of the Love2Shop segment - look at last year's results as well.
Just following on from yesterdays discuusion on VIstry and housebuilding in general...
The Telegraph (via MSN) reports that Mathew Pennycock the Planning Minister as saying that the target of building 1.5 million homes over a five year period will be "more difficult" than than the Government thought in opposition.
He is reported as saying that 1.5 million it is still "deliverable" and defends the process of not having annual targets to assess progress.
Apparently most of the housebuilders dont believe that the target to be possible.
It is so easy in opposition, think this Govt. has made a right mess of things already. Upsetting a lot people for little tax gains. Can't see where all the growth is coming from, their policies seem to be doing the opposite. Now we defence cuts, higher inflation, unemployment going up.
They don't get it and never will, far easier to punish those that have sacrificed much, worked hard, saved and invested for the future.
They dont seem to understand that the public sector is being financed by the private sector judging by their policies so far.
Well if they keep going the public sector will be so big that that raises enough extra taxes via them to sort everything out ? heck why not double public sector then taxes from the public sector would double and we would be awash with money. hmmmmm i must be missing something there perhaps ? :).
Throw in 100 billion debt servicing interest repayments a year which eats up 10% of total tax take, about 20% of the workforce economically inactive, inflation busting minimum wage rises, the killer employers ni threshold drop yet to kick in, rising inflation.
I have just had a meeting with one of the best bond managers in the UK and he thinks its difficult to see UK interest rates getting below 4% on a two year view.
I would imagine 25% of my personal social circle who are mostly over 50 are single no kids and zero future interest in work even doing 2-3 days per week part time, they are just living off savings and pension drawdown and spending most of the day in the pub.
Interest rates will go much lower than 4% on a two year view.
All the best
Always value your view Yiannos whats your thinking on this US will force the dollar down and we will have to follow regardless because of currency issues ? or something else ?
Regards
Andy
Hi Andy
You can’t have tariffs and a weak dollar-it does not make any sense as the trading’s partner currency will be sold.
Low growth or no growth will drive rates lower than 4%. A bunch of lunatics governing the US that will eventually create havoc is another reason.
All the best
yiannos1
Suggest you need to be careful Elon & co aren’t monitoring Stocko or your west coast might become Aberystwyth and not SF ………… not that there’s too much difference 8-)
Your way better at this game than me Yiannos utterly agree with the lunatics quote and by the time the purge is over it will be a cabinet full of yes people to follow any dictators handbook.
The only thing I would query is the US economy is doing well and showing no signs of slowing so.
I personally can't see them cutting rates fast unless once they have the inferno raging they decide to add a lorry load of petrol onto it by cutting rates fast into an expanding economy on the basis they are only fussed about the coming four year period possibly ?
The whole Construction Industry doesn't believe the targets are possible.
I didn't want to hold Liontrust Asset Management (LON:LIO) for the trading update today, may have been an error, they haven't cut the divi which is what people seemed to be expecting. £5 million shares buyback too
Re LON:LIO NewInvestor1972 the CEO' s statement makes very interesting reading waving the flag for Active Fund Management and the risks in Passive. We don't hold but I'll be very interested in the team's comments and subscribers if they pick up on this today.
RE: Liontrust Asset Management (LON:LIO)
Undeniably cheap, but objectively a poor set of results, underlying AuM continues to fall.
Maintaining the dividend for the full year will require improved performance as it'll be uncovered as it stands. The share buyback is interesting - clearly the shares are cheap, but £5 million looks more like a gesture than a full on committment.
As the CEO says, short term fund performance has been better, but they've kicked the can down the road for six months.
Also: CMC Markets (LON:CMCX) reporting today - no surprises, they're continuing to prosper. Longer term it'll be interesting to see if the changes they've made remove some of the cyclicality from the business but, as always, on the up-cycle they do extremely well.
Hold both of those and PayPoint (LON:PAY) - fascinating business, but hard to predict in the short term due to the weakness int the UK economy. But 12 months ago it was way too cheap for a business with its entrenched position.
timarr
XPS Pensions (LON:XPS) HY figures look very good and debt has reduced considerably. PayPoint (LON:PAY) also reporting, figures look ok.
Cohort (LON:CHRT) large acquisition, looking to raise £40m.
Morning Graham, one of your 2024 suggestions, CMC Markets (LON:CMCX) smashing it out of the park. Smallest rise in any figures 19%, divi up 210%.
Should be a lot of happy bunnies on here today.
Cheers Bob, I'm glad to see it. G
B please Bob