Daily Stock Market Report (Thur 21st May 2026) - SpaceX, AJB, TRU, SGE, ZIG, BTG, AUTO

Good morning!
The most interesting story overnight has been the IPO plans for SpaceX, giving us a welcome reprieve from looking at the conflict in Iran.
If you’d like to read the original document, it’s available here.
The IPO is being set up to keep Elon Musk firmly in control: there will be Class A shares with 1 vote each, and Class B shares, with 10 votes each. Furthermore, the Class B shares (which are not being offered in the IPO) will have special powers:
Mr. Musk will be able to control the outcome of matters requiring shareholder approval. This includes the election of (i) a majority of our board, through his ownership of Class B shares (as Class B Directors)... and (ii) the remainder of our board, for so long as he holds a majority of the combined voting power of the Class A and Class B common stock… we intend to rely on exemptions from certain corporate governance requirements.
Bearing in mind that I’m a longtime Musk sceptic and former short-seller of Tesla shares, it’s possible that I might be a little biased against this IPO.
But it’s hard not to be, for anyone with value instincts.
The company’s mission: “to build the systems and technologies to make life multiplanetary, to understand the true nature of the universe, and to extend the light of consciousness to the stars”. They can’t be blamed for lacking ambition!
But the financials here are truly mind boggling.
The company is looking to raise $75bn and achieve a $1.75 trillion valuation.
Recent results:
Q1 2026 revenue $4.7 billion
Q1 2026 operating loss $1.9 billion
And for last year:
2025 revenue $18.7 billion
2025 operating loss $2.6 billion
Financially, this looks to me like an even more extreme version of Tesla.
Supporters would argue that Tesla eventually grew into its valuation.
Sceptics like myself would argue that Tesla still hasn’t done that - and that the company was dangerously close to collapse on multiple occasions (which I think Musk himself would agree with).
Like Tesla, it requires investors to accept unusual corporate governance practices that favour Musk.
And like Tesla, SpaceX offers multiple businesses packaged together, some of which have more substance than others.
Whatever the outcome, this IPO will be a landmark event in the markets generally. It will be particularly relevant for investors in certain UK stocks - Seraphim Space Investment Trust (LON:SSIT) and Filtronic (LON:FTC) spring to mind.
Overnight market movements:
The FTSE is set to open down 0.2% at 10,390
S&P 500 is unchanged at 7,430
Brent crude is up $1 at $106
Gold is unchanged at $4,530
Bitcoin is unchanged at $77,850
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BT (LON:BT.A).A (£23bn | SR70) | Reported revenue £19.7bn down 3% and adjusted revenue £19.6bn, down 4%. Reported profit before tax £1.4bn, up 8%. Updated dividend policy. | ||
Sage (LON:SGE) (£8.2bn | SR35) | Underlying total revenue increased by 11% to £1,363m. Sage Business Cloud revenue increased by 15%. Underlying basic EPS increased by 16% to 23.7p. Interim dividend up 8%. Renewal rate by value of 102%, ahead of last year. Now expects organic total revenue growth for FY26 to be above 9%. | AMBER/GREEN = (Ed S) Today’s H1 results from Sage show minimal signs of AI disruption. Revenue is up by a healthy amount and renewal rates have increased. A dividend hike of 8% suggests that management is confident about the future. After a big sell-off this year due to AI concerns, I see the potential for a recovery. | |
Smiths (LON:SMIN) (£7.5bn | SR57) | Organic revenue growth was flat in the third quarter, leading to +0.2% growth for the nine-month period. Now expecting FY2026 organic revenue growth of ~2% versus previous guidance of 3-4% excluding any impact from the conflict in the Middle East. | ||
Investec (LON:INVP) (£5.5bn | SR57) | Operating income up 4% up to £2,281m. Adjusted earnings per share increased by 4.8% to 82.9p. Customer deposits increased by 8.7% to £44.7bn. Dividend increased by 5.5%. | ||
ICG (LON:ICG) (£5.2bn | SR65) | Management fees of £685m, up 13% y-o-y. Performance fee income of £127m (FY25: £86m). Total ordinary dividend per share for FY26 of 87p (FY25: 83p). "Unaffected by challenges being faced by certain evergreen vehicles in the US." | ||
Londonmetric Property (LON:LMP) (£4.4bn | SR46) | Net rental income increased 16.6% to £455.3m. Total property return of 7.1%. EPRA earnings up 13.9% to £305.3m. Dividend up 3.8% to 12.45p. | ||
ConvaTec (LON:CTEC) (£4.2bn | SR31) | YTD organic revenue growth ex-InnovaMatrix of 4.8%. Broad-based growth across categories with product launches performing well and gaining share. FY2026 guidance unchanged. On track to deliver 5-7% organic revenue growth ex-InnovaMatrix for FY2026. Growth expected to increase in H2. | ||
Autotrader (LON:AUTO) (£4.0bn | SR32) | SP -8% Revenue growth for the year was 4%. Revenue growth in H2 was 3% and lower in the fourth quarter, reflecting more difficult trading conditions. Basic earnings per share up 8%. The Board believes the prevailing Autotrader share price does not reflect the Company's fundamentals or long-term prospects and is updating its capital allocation policy. Expects to return over £1bn to shareholders over the course of 2026 and 2027. Outlook: FY 2027 operating profit £395-415m, which is below the prior consensus. | BLACK (AMBER) [Graham] We've not covered this one recently and I'm frankly amazed to see how low the share price is - down by about 50% from the high last year and on a paltry earnings multiple of only 13x (as of last night). Clearly the market views it as ex-growth and perhaps at risk of AI disruption, while also being disappointed by the company missing forecasts and lowering guidance. But £500m of planned buybacks in 2027 is a serious statement of intent - this amount is not covered by earnings and will see the company borrowing more in order to continue buying back their own shares. It's a high-risk strategy and not one that is sustainable but it could work over the next 1-2 years if the business keeps up current performance levels. Also, it's starting from a position of strength with gross borrowings being relatively light at £165m. As someone who always thought this stock was highly attractive, I am tempted to open a small starter position now that its trading at a discount. But it's always risky to trade into EPS downgrades, so I'm putting us on a neutral stance. | |
easyJet (LON:EZJ) (£2.6bn | SR46) | H1 FY26 result was in line with April trading statement. H1 FY26 headline loss before tax of £(552) million. £4.7 billion of liquidity and net cash of £434 million. Passenger growth: +6% YoY. Load factor improved by 2 ppts to 90%. Not seeing any disruption to fuel supply. H2 FY26 Fuel CASK remains uncertain due to price volatility. 72% hedged at $726/MT. | ||
Tate & Lyle (LON:TATE) (£2.3bn | SR36) | Challenging market environment impacted financial performance. Group revenue down 3% reflecting muted market demand. Adjusted profit before tax down 5%. Full-year dividend in-line with prior year. For the year ending 31 March 2027, expects to deliver modest revenue growth and broadly flat EBITDA. | TAKEOVER | |
Qinetiq (LON:QQ.). (£2.3bn | SR45) | Record order intake of £3,573m. Book-to-bill 1.14x. Record year-end backlog of £4.8bn. Revenue increased 1.3% on an organic basis. EPS grew 21% to 31.5p. 24% increase in full year dividend. £200m share buyback extension of £100m p.a. through FY29. Record order intake and backlog provide “clear visibility of sustainable growth and strong multi-year cash flows.” | ||
AJ Bell (LON:AJB) (£2.1bn | SR70) | Revenue up 19% to £183.0m. Underlying profit before tax up 15% to £79.0m. Underlying diluted earnings per share up 18% to 14.61p. Dividend increased by 11%. Further share buyback programme of up to £15 million. Strong growth in customer numbers. Now expects full-year revenue margin, PBT and PBT margin to be higher than previously guided. | GREEN = (Ed S) | |
Hill and Smith (LON:HILS) (£2.1bn | SR86) | Trading in the period was positive and slightly ahead of its expectations, reflecting continuing robust demand for infrastructure solutions in the US. Group revenue was up 5% on an organic constant currency basis. | ||
Mitchells & Butlers (LON:MAB) (£1.5bn | SR93) | Like-for-like sales growth of 3.3% over the first half. Adjusted operating profit of £181m (HY 2025 £181m). Net debt reduced. | ||
Great Portland Estates (LON:GPE) (£1.23bn | SR27) | Executing our growth strategy (FY March 2026 results) | Diluted EPRA EPS of 8.5p vs 5.2p in 2025. Portfolio valuation of £3.0 billion, up 4.3%. FY'27 rental growth guidance of 4.0% to 7.0%. | |
| ZIGUP (LON:ZIG) (£970m | SR97) | Pre-close Trading Update | The FY2026 financial year ended strongly. Now expects the group's financial outturn for the year to be at the top of market expectations. | GREEN ↑ (Graham) |
Close Brothers (LON:CBG) (£693m | SR54) | Q3: “Resilient underlying profitability, benefitting from a robust NIM and modest growth in the core loan book.” “We have delivered a solid performance in the quarter and at this stage (and subject to current macroeconomic developments) remain on track to deliver the 2026 financial year in line with guidance.” | ||
Tungsten West (LON:TUN) (£482m | SR36) | Entered into a binding US$25.0 million bridging loan facility. Key terms: $25m, interest rate c. 8% (benchmark +4.5%), increasing 1% per quarter. Term 366 days. Related party transaction: lender is controlled by a major shareholder. | ||
Young & Cos Brewery (LON:YNGA) (£443m | SR85) | Revenue +4.6%. Adjusted PBT +2.9% (£53.1m). “It has been a good start to the new financial year…. We are very optimistic about the future. The business has strong momentum, like-for-like sales and profit are growing, and our operating margin remains industry leading.” | ||
Ashtead Technology Holdings (LON:AT.). (£432m | SR70) | Q1 was in line. “Whilst the duration and impact of the conflict in the Middle East, and the potential secondary effect on our broader operations and markets, remains hard to predict, the Board is cautiously optimistic in the outturn for the year, and its performance expectations are unchanged.” | ||
Sabre Insurance (LON:SBRE) (£388m | SR89) | Gross written premium +15% to £76.3m. Reiterates guidance given at full-year 2026 results. | ||
Ibstock (LON:IBST) (£382m | SR32) | “Whilst we are mindful of the potential impact of the Middle East conflict, the Board believes recent activity levels support the Group's capability to deliver a full year outturn broadly in line with current market consensus expectations.” Domestic brick volumes down 11% in Q1. | ||
Tharisa (LON:THS) (£372m | SR99) | Revenue +28%. Net profit after tax $46.6m (HY2025: $8.2m). “The past six months have seen Tharisa deliver robust operational and strategic progress, underpinned by the resilience of global commodity markets.” | ||
Yu (LON:YU.). (£290m | SR98) | Extends the structured trading agreement with Shell Energy Europe for additional three years to 2032. The extension includes a significant increase in volume capacity and “ensures Yü Group are well placed to deliver their ambitious stated growth plan to secure a 7-9% market share by 2028.” | ||
Niox (LON:NIOX) (£259m | SR43) | Trading for the year to date has been in line with management expectations. | ||
Capricorn Energy (LON:CNE) (£229m | SR98) | Year-to-date, production is tracking within guidance range of 18,000 - 22,000 boepd. Debt free with cash balance $132m. | ||
Henry Boot (LON:BOOT) (£213m | SR45) | Heavy H2 weighting, consistent with recent years. “...assuming market conditions do not materially deteriorate, we anticipate delivering profit before tax in line with consensus expectations for 2026.” | ||
Cab Payments Holdings (LON:CABP) (£207m | SR42) | Authorised by the Bank of Guyana to establish a permanent representative office in the country. The new office in Georgetown will create a permanent on-the-ground presence for CAB in South America. | ||
BTG Consulting (LON:BTG) (£188m | SR84) | Results for the year to be above the top end of market expectations. Revenue +10%. Adjusted PBT +6% (£25m). Net debt £1m after acquisition payments. Outlook: “A backdrop of increased macroeconomic uncertainty is expected to continue to drive demand for our restructuring and advisory services.” | AMBER/GREEN = (Graham) [no section below] Begbies Traynor is now known as BTG, but the fundamentals haven't changed all that much: restructuring services benefit from macro uncertainty and this is therefore one of those stocks that in theory provides a natural hedge within a portfolio. That alone is a good argument for owning it, but a better one is that it's beating expectations for FY April 2026. Checking the latest note from Equity Development, I see that the FY26 EPS forecast is increased by 3.4% (to 11.1p), and the FY27 EPS forecast is raised by 1.5% (to 11.7p). I considered this stock to be fairly valued the last time I looked at it, and the market cap today is the same as it was then - despite this ahead of expectations update. It therefore seems that the market agrees with my assessment. This is a highly reputable professional services firm, but I wouldn't want to pay much more than 10x earnings for it. | |
Savannah Resources (LON:SAV) (£185m | SR38) | Priorities for the remainder of 2026: “completing the DFS in July, progressing the geotechnical fieldwork… advancing Front End Engineering & Design work, completing the RECAPE submission, and continuing to develop the Barroso Lithium Project's financing and commercial arrangements.” | ||
Helios Underwriting (LON:HUW) (£148m | SR47) | NAV total return 12.3%. NAV per share £2.63. PBT £20.5m (2024: £20.9m). Outlook: “...the insurance cycle is likely to moderate. As markets soften, returns on capital will naturally reduce. Our focus, therefore, is on cycle management…” | ||
Trufin (LON:TRU) (£130m | SR90) | Conditionally agreed to sell Playstack to VantageCo Limited (Integrated Media Company group) for net cash proceeds c. £112.4m. TRU intends to return £70m to shareholders. Proposed price for tender offer of 140p. | AMBER ↓ (Graham) | |
Invinity Energy Systems (LON:IES) (£128m | SR14) | Flexbase has selected Invinity to design a GWh-scale vanadium flow battery for deployment at the Technology Centre Laufenburg. | ||
FDM (Holdings) (LON:FDM) (£115m | SR68) | Trading for the first four months of the year has been in line with the Board's expectations. “While the Board remains mindful of current macroeconomic and political uncertainties, encouraging indicators continue to show… FDM is well placed to deliver improved performance as soon as market conditions permit.” | ||
SDI (LON:SDI) (£84m | SR85) | FY April 2026: full year earnings to be in line with current market expectations. | ||
Braemar (LON:BMS) (£78m | SR53) | FY26 results in line with expectations. Trading in the first two months of the new financial year has been strong. “...confident of further progress and of delivering annual revenue of £200m by FY30.” | ||
Vulcan Two (LON:VUL) (£71m | SR31) | Institutional placing for £40.0 million in March 2026. Then completed the acquisition of three ePharmacy businesses, max consideration £41.7m. “The early signs are encouraging.” | ||
Michelmersh Brick Holdings (LON:MBH) (£68m | SR58) | "Despite the prevailing trading conditions, while we currently expect the Company to deliver performance in line with full-year expectations, we are watchful of the continuing political instability..." | ||
Zephyr Energy (LON:ZPHR) (£65m | SR25) | Further divestment of undeveloped non-core acreage generating US$2.275 million. | ||
Seascape Energy Asia (LON:SEA) (£63m | SR33) | Operating loss £4.4m. Profit for year £5.4m reflecting proceeds from farm down of an asset. Year end cash £6.3m. Outlook: “Progress the Company's Temaris Cluster and DEWA through to FDAP submission during 2026, targeting first gas in 2028 and allowing Seascape to book initial 2P reserves.” | ||
Ilika (LON:IKA) (£60m | SR8) | FY April 2026: revenues of c. £1.1m, including £100k of commercial revenue from Stereax electrode sales (2025: £1.1m), and an EBITDA loss excluding share-based payments of approximately £6.2m (2025: EBITDA loss of £5.2m). Cash £5.3m. | ||
Software Circle (LON:SFT) (£59m | SR16) | New £25m facility with Santander used to refinance the Group's pre-existing facilities with Shawbrook. TU: “another year of strong progress, with revenue growth of 22%, a meaningful step-up in profitability with an 81% growth in Adjusted EBITDA and the continued successful execution of its acquisition strategy.” | ||
Nexteq (LON:NXQ) (£35m | SR93) | “As a result of the continuing uncertainty in the Quixant business, FY26 Group revenue is now expected to be approximately 15% below previous market expectations with a consequential impact on adjusted profit before tax.” | BLACK | |
Works co uk (LON:WRKS) (£34m | SR97) | Revenue +3.2%. LfL sales +3.3%. “...Confidence in achieving recently upgraded FY27 guidance” and medium-term EBITDA goal of at least £22.5m in FY30. | ||
Hardide (LON:HDD) (£30m | SR60) | Revenue +71% (£4.8m). Operating profit £1.3m. “...Well positioned to deliver full year performance in line with recently upgraded expectations.” | ||
Robinson (LON:RBN) (£21m | SR83) | Sales volumes +6%. Total revenue +6%. Underlying operating profit in the first four months of 2026 below the same period in 2025, reflecting the challenging trading environment. Outlook in line. | ||
Zinc Media (LON:ZIN) (£12m | SR15) | Commissioned to produce a major television series in the GCC, with a contract value of $6m. |
Graham's Section
Trufin (LON:TRU)
Down 2% at 135p (£127m) - Proposed Disposal of Playstack - Graham - AMBER ↓
This strikes me as a somewhat disappointing outcome and it ties in with my analysis in January of Trufin’s new management incentive plan.
First, an overview of today’s news:
£125m gross proceeds from the disposal of games publisher PlayStack
Net proceeds of £112.4m, including the repayment of a £15.6m loan.
The £15.6m loan between the parent company Trufin and its subsidiary PlayStack is not something that should show up in the consolidated group accounts. So from a group perspective, I’d expect to see a cash infusion of less than £100m.
This is a “fundamental change of business”, so requires a vote.
But that shouldn’t be a problem: 32.8% of shares are already subject to “irrevocable undertakings” to support the sale, and there is also a letter of intent for another 11.5% of shares. So over 44% of shares are already lined up to vote for this.
The buyer: Integrated Media Company, which is part of TPG (formerly known as Texas Pacific, a US private equity group).
Tender offer: “the company intends to return £70m to shareholders”. The proposal is for a tender offer at 140p, slightly above the current share price (this is perfectly normal). But this is yet to be finalised.
CEO comment:
"We believe the disposal of Playstack represents a milestone for TruFin and a clear demonstration of our disciplined approach to capital allocation and value creation. We've thoroughly enjoyed working with the Playstack team over the last few years and look forward to them achieving future success.
Graham’s view
I should say now why I view this outcome as slightly disappointing.
Going back to my notes in January, there was a broker estimate for the value of Trufin’s PlayStack investment of £150m.
This was lowered to £137m as a result of a new bonus scheme for PlayStack’s management team.
This bonus scheme incentivised a disposal to happen as quickly as possible, as the “Hurdle” above which the options would have value was increasing at 12% per year.
To put it simply: the longer it took for a disposal to occur, the less valuable their options were.
Only four months later, a disposal has been announced and it seems to me to be at a pretty significant discount to the level at which the PlayStack investment had been valued.
On the other hand, several (presumably very well-informed) large shareholders are supportive of the proposal, so perhaps it’s a reasonable outcome.
Trufin will continue to own 85% of Oxygen and 80% of Satago.
Oxygen (early payment provider for the public sector): 2025 revenue £9m, EBITDA £4m.
Satago (cash flow software for businesses): 2025 revenue £1m after losing a major contract.
I’d value Trufin as:
£12m cash at year-end 2025
c. £100m cash infusion from the PlayStack disposal.
Plus whatever you think Oxygen and Satago is worth.
With a current market cap of £127m (pre-tender offer), and perhaps c. £110m in cash, it seems to me that Oxygen and Satago are being valued at less than £20m. That might be fair.
With no further upside from PlayStack investment, I think this becomes a less interesting share, so I’m taking us down to neutral on it.
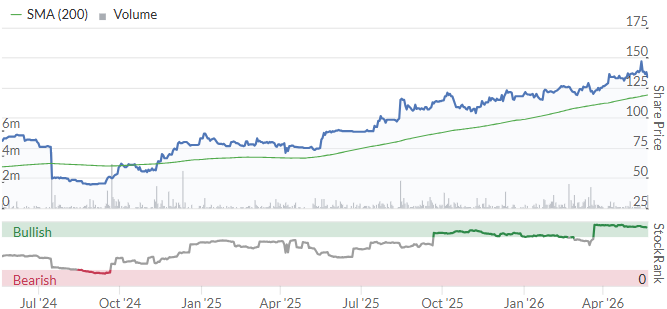
It has been a big winner over the past year and has a StockRank of 90, but I think the company is now effectively cashing in its biggest chips.
ZIGUP (LON:ZIG)
Up 2% at 432.5p (£990m) - Pre-Close Trading Update - Graham - GREEN ↑
This used to have the less exciting name Redde Northgate.
It provides various “mobility solutions” - van rental, accident/claims management, replacement hire and bodyshop repair.
Roland liked the Interim Results published in December, leaving our AMBER/GREEN stance unchanged.
Today’s update is good, too: “we expect the Group's financial outturn for the year to be at the top of market expectations”.
The consensus range is helpfully provided: adjusted PBT of £154.5 - 159.3m.
Leverage is in line with guidance at 1.9x (I’m fine with anything below 3x).
CEO comment:
'Customers are clearly seeing significant value in our service-led offering, and I am very pleased with the contributions from across our divisions this year. Average VoH is up 4.9% for the year and we have secured a number of valued contract wins and renewals, underpinning this good momentum; Steady State Cash generation has stepped up materially and supports our ambition for further growth'.
[VoH = vehicles on hire]
Graham’s view
This one is highly-ranked:
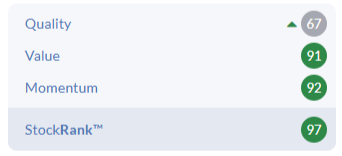
Quality is the only weak point. These metrics are lukewarm:
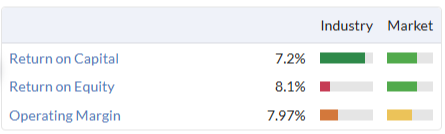
The company argues for having competitive advantages, mostly to do with greater scale, coverage and customer service levels. When it comes to accident management, for example, they say that their customers benefit from “the breadth and quality of services offered through its claims and services platform; the ability to fully connect into insurance partner systems; and efficiencies from scaling automated processes and self-serve portals for policyholders.”
Maybe this is true but as someone who doesn’t specialise in the sector, it doesn’t strike me as the type of business that would be expected to earn sustainably high returns over the long-term. What are the barriers to entry? This is borne out in pretty average ROCE over time:
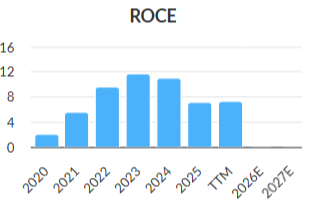
However, at the same time, it has developed a nice track record of maintaining its earnings forecasts:
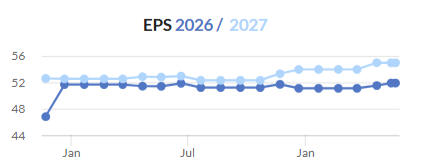
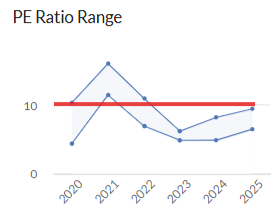
I’ll give this a boost to GREEN today, on the basis of the strong momentum and sturdy performance. I wouldn’t do this if it was already at a P/E of about 10x - and I’ll want to take us back to AMBER/GREEN if it gets there.
Ed S's Section
AJ Bell (LON:AJB)
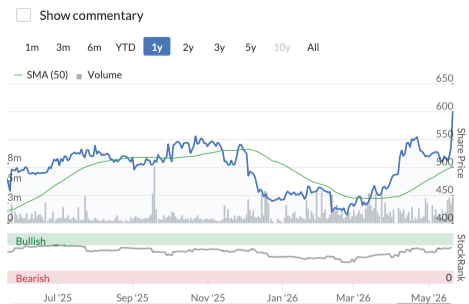
Up 12% at 598p (£2.4bn) - Interim results for the six months ended 31 March 2026 - Ed S - GREEN=
The team has been GREEN on this investment platform company for a while now and they were right to be. Today, we have strong interim results and the share price has popped by around 12% to record highs!
Key numbers:
Revenue up 19% to £183.0 million (HY25: £153.2 million)
Underlying profit before tax (PBT) up 15% to £79.0 million
Underlying PBT margin of 43.2% (HY25: 44.9%) reflecting increased investment in brand and propositions, which drove record business growth
Statutory PBT up 35% to £92.8 million
Statutory diluted earnings per share up 39% to 17.13 pence, reflecting a net exceptional gain of £13.8 million
Underlying diluted earnings per share up 18% to 14.61 pence
Dividends/buyback:
Interim dividend of 5.00 pence per share, up 11% versus prior year
A further share buyback programme of up to £15 million, in addition to the previously announced £50 million programme
Operational highlights:
The platform business added a record 79,000 customers to close at 723,000, up 12%
Platform AUA up 5% in the period to £108.7 billion, driven by record net inflows of £4.2 billion and favourable market movements of £1.2 billion
Investment business AUM increased by 10% in the period to close at £9.8 billion
Outlook:
We now expect full-year revenue margin, PBT and PBT margin to be higher than previously guided. Excellent returns from our investment in brand and marketing give us confidence to invest more than originally planned in the second half of the year, while still expecting to deliver materially higher profitability.
The platform market presents significant long‑term growth opportunities, and our continued business investment positions us well to capitalise on these. We remain confident in the outlook, with strong momentum continuing into the second half of the year.
Ed S’s view:
There’s a lot to like here from an investment perspective. The key theme is scalability. With people continually saving and investing for retirement, and global equity markets continually moving higher, there’s potential for this company to get much bigger over time (could Savvy the Squirrel help?). In its H1 results today, the company points out the UK platform market continues to present “significant structural growth opportunities,” with an estimated £2.4 trillion being held off platform.
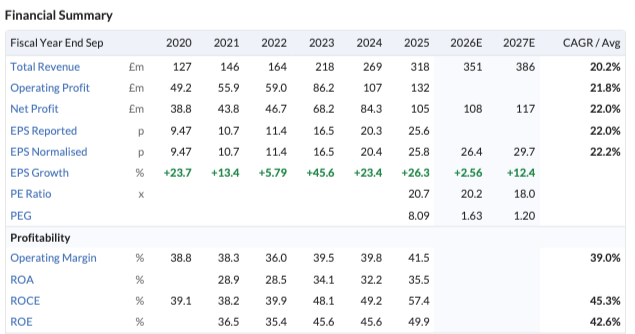
Looking beyond the theme, I like the financials – there’s a lot of quality here (the Stockopedia quality rating is 93). This is a company with a good growth track record and a very high return on capital employed (ROCE). It also has a growing dividend (the yield is close to 3%). The fact that the company has hiked its payout by 11% today suggests that management is confident about the future.
In terms of risks, competition from rivals is one to monitor. I don’t think we need to worry too much about Hargreaves Lansdown for now – I suspect the company is winning customers from them due to Hargreaves’ recent fee changes (which didn’t go down too well with investors). I’m more concerned about the likes of Vanguard (and the rise of passive investing) and the zero-commission trading platforms like Robinhood (disclosure: Ed S has a long position in $HOOD). Some of these newer players are very innovative with their offerings and are very appealing to younger investors.
Is the valuation risky? I’m comfortable with it given the company’s quality, strong track record, and scalability potential. That said, one does need to be prepared for share price volatility with this stock. Over the last five years it has had some big dips.
As for the rating, I’m going to keep it on GREEN given today’s upgrade to guidance. In my view, there’s potential for further gains here in the medium term.
Sage (LON:SGE)
Down 2% at 875p (£8.0bn) - Results for the six months to 31 March 2026 (unaudited) - Ed S - AMBER/GREEN =
Accounting software firm Sage (which I hold) has posted its half-year results today and they look very solid to me. Here are some highlights:
Underlying total revenue increased by 11% to £1,363m, reflecting broad-based growth across the business underpinned by strength in cloud solutions
Underlying annualised recurring revenue (ARR) up 11% to £2,727m, with growth across all regions balanced between new and existing customers
Sage Business Cloud revenue increased by 15% to £1,162m
Renewal rate by value of 102%, ahead of last year (H1 25: 101%), reflecting higher sales to existing customers, including the growing adoption of AI-powered features, supported by strong retention rates
Underlying operating profit grew by 15% to £326m, driving a margin increase of 80 basis points to 23.9%
Statutory operating profit increased by 15% to £293m
Underlying basic EPS increased by 16% to 23.7p, whilst statutory basic EPS increased by 14% to 20.7p
£1.1bn of cash and available liquidity; net debt to underlying EBITDA of 2.0x
Interim dividend up 8% to 8.05p, in line with progressive policy
Outlook:
Building on strong momentum in the first half, we now expect organic total revenue growth for FY26 to be above 9%. We continue to expect operating margins to trend upwards in FY26 and beyond, as we focus on efficiently scaling the Group.
With our trusted scalable platform, growing agent portfolio and strong momentum supported by investment across the business, I am confident in Sage's ability to deliver growth and long term value for all stakeholders.
Ed S’s view:
This tech stock – which I hold – has been dragged into the AI-related SaaS sell-off recently. Year to date, it’s down about 15%.
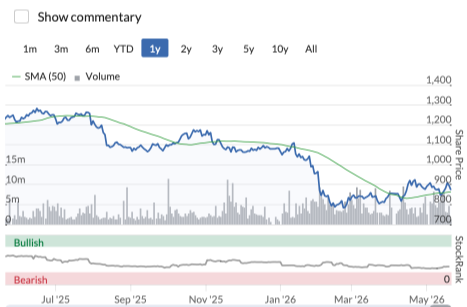
’ve always thought that the heavy selling activity here isn’t really justified. My reasoning is:
Small business owners tend to be really busy running their businesses. Do they have time to sit around ‘vibe coding’ new accounting software?
There’s a lot at stake with accounting software. Get it wrong (as AI often does) and a business could be looking at loss of revenue, fines, reputational damage, and more.
Now obviously, it’s still very early days in terms of the AI disruption story. But today’s results from Sage suggest that the company isn’t seeing much disruption.
One figure that stands out to me is the renewal rate by value of 102%. This was up year on year thanks to higher sales to existing customers and the growing adoption of AI-powered features.
Another is the 15% growth in Sage Business Cloud revenue. This represents an acceleration of growth – last financial year growth here was 13%.
There’s also the increase in the dividend (+8%). This suggests that management is confident about the future.
Small and mid-sized businesses trust Sage to run their mission-critical finance, payroll and HR workflows, where accuracy and compliance are non-negotiable.
It’s worth noting that in the results, CEO Steve Hare talks about how Sage’s AI features are helping customers:
Our intelligent agents are already helping finance teams accelerate cash flows, close the books faster, plan more effectively and turn insight into action, without compromising control or accountability.
By embedding AI directly into our customers' day-to-day work, we are making our solutions more valuable, reinforcing our competitive advantages, and driving efficient, sustainable growth.
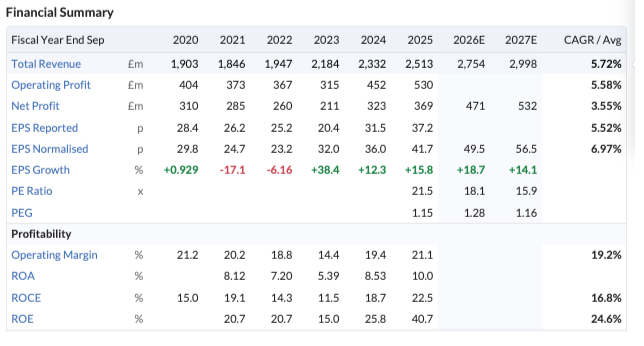
Looking at today’s figures and the commentary from management, I remain relatively bullish on the stock. To my mind, there is upside potential from here given the growth and the valuation.
Note that this morning, analysts at Peel Hunt have upgraded to the stock to Buy from Hold. Their price target is 1,165p (down from 1,187p).
They point to the margin expansion. They believe that this will be a source of earnings upgrades.
Putting this all together, I’m going to leave the stock on AMBER/GREEN. There is obviously some uncertainty around AI disruption but at current levels, I like the risk/reward skew.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
SpaceX
97% of shares are locked up.
Don’t expect this to be going down anytime soon.
Everyone here is talking about the valuation is bonkers without actually saying or most importantly explaining why. I do apologise if someone has actually explained this but have been missed.
Others are talking about the US market going down 30%, although same person has been saying the same thing for years now. If the US market loses 30%, then the UK market will obviously fall more.
SpaceX implying a TAM close to $30T, a figure close to 25% of the world’s GDP, is the most inaccurate and bonkers statement I have ever came across in my 30+ years investing. That’s where the lies about this company can be spotted.
US markets are at the point now where experienced investors can spot multiple pockets of exuberance. But as long as the iShares 20+ Year Treasury Bond ETF (NMQ:TLT) holds above 80, then the bullishness will continue until the mid-terms.
All the best
What's going on with Filtronic (LON:FTC)?
Maybe the impact of the Vox Markets podcast with Richard Staveley where he basically said take profits this is overvalued.
A British growth share?! As it is one of the lesser-known beasts, I don't expect it to feature here, so I'm just putting it out that the Invinity Energy Systems (LON:IES) announcement this morning should be a gamechanger for the company. It's only the engineering design contract at this stage, but the Laufenberg contract envisions GW of flow batteries and validates Invinity as a player in the big league. If they then get a decent chunk of the LODES projects bid for by paertners in the new few weeks, this becomes a business that will scale to many times its current volume. And they have manufacturing partnerships set up to enbale the scale of expansion. Some is/will be in Scotland, but it has to become a multinantional business and now looks on the way. I have been an investor for some years, so I am biased. But I now think the multibagger target is possible over the next two years. Fingers crossed for them; and it's essentially British technology! Comments welcome.
Sage (LON:SGE) US rival Intuit has also reported today. Down 16% pre-market despite decent looking results and raised guidance. Presumably they haven't done enough to persuade the market that they won't suffer in the SAASpocalypse. No director buying yet. I think that if there is a threat it will come from a pure play AI startup that can provide similar functionality at lower cost. It'd be interesting to see how Intuit and Sage are faring in terms of market share.
Is anyone else as baffled as me at how Advanced Medical Solutions (LON:AMS) can announce the end of takeover talks with one party without informing the market that they had been approached by another bidder the previous month and that those discussions were still ongoing? Talk about creating a false market in the shares! Fortunately I still hold the shares and reckon a bid will eventually go through, but I sympathise with anyone who sold out a few days ago.
The Takeover Code demands secrecy during negotiations, whether you agree with that is another matter, it is what it is and its purpose is to avoid a false market, because some people will always have more information than others. Any takeover approach should be initially put to the board (note not shareholders). There are other reasons too - not to disclose every single item of information as it happens, that would become unmanageable. Also for example the bidders may not be aware of each other's existence or intentions. AMS announced the end of talks with TA because it came to the end of the offer period - that period is set by Rule 2.6 (PUSU). That period was started because the TA approach was leaked on X. The talks with HB Fuller were not disclosed because there was no obligation to do so, until today when it was leaked by Betaville. The company (or more likely its advisers) probably got a call from the Takeover Panel this morning because there is now a false market, it's now in the public domain but not everyone knows about it. The point is you have exactly the same information as any other shareholder, and that is the intention of the Code, with the exception of shareholders who have been brought 'over the wall' and they now have dealing restrictions. If your bank holiday is looking unexciting you can swot up here: https://www.thetakeoverpanel.o...
Thanks for this Sparkler...but where was the second announcement?
12 noon yesterday. HB Fuller is in talks now. They are an industry player and so might conceivably get greater synergies than private equity, hence justifying a higher purchase price although the market looks skeptical on the deal so far.
Hi Ed. I also hold Sage (LON:SGE) and like everything about today's numbers except the continuing rise in net debt that is entirely due to the ongoing share buybacks. These buybacks are failing to prevent the share price slide (down 15% over a year as you say) but are increasing financial risk at a time when markets are predicting tougher times for software businesses. I share the company's confidence that AI won't be detrimental to their business, but I don't see the rationale in upping the risk.
Incidentally, the same factor seems to be at play with Future (LON:FUTR) which I don't hold. The company has dramatically upped its dividend AND continues to spend on share buybacks almost as if it is saying "look at my lovely cash flow" just when the market is predicting a slump for the business. In my view both companies would be far better off paying debt down rapidly so that their valuations look more obviously anomalous.
Sage (LON:SGE)
These buybacks are failing to prevent the share price slide (
It shouldnt be about preventing share price slide - imho its whetehr the buybacks make sense and are good value.
On the basics - p/e of 16 is pretty decent value for this company (historically) and they are most certainly expecting higher future earnings.
to me thats exactly then kind of company i would want to be holding a bigger piece of the pie.
are buybacks nota no brainer on that basis alone - one can take the viewpoint that the shares are in the gutter not due to buyback - its clear to me its concerns ref ai.
This the kinds of company where shaebuybacks long term should pay dividends - i own 10% more of the comnpany now that i did in 2020 and i think when buybacks first started price was below where it is now.
If you dont rate future sharepirce prospects well best to sell out - if one is happy this wil take care of itself why worry about current weakness. Imho slight rerate downover for risks ref AI isnt totally unexpected - yet again though thats the issue rather than then act of buying back shares imho - i am more than happy to own more of the company with soem debt - sage is a proper cash generating machine - cant think of many companies less likely to be able to service their debts. Note with higher future profits we are perhaps at inflexion point where debt doesnt need to go up in that regard !
You are not understanding me here, rmillaree. It is one thing to back a company in the belief that it is going to flourish despite what the doomsayers think. It is quite another to increase the financial risk substantially at precisely the time when the market is predicting significant pressure on future cash flows.
If the market is wrong the shares will rise nicely from here and your extra 10% ownership will matter very little. If, however, we are wrong in our thinking then the company has engineered a position that will bring financial distress much more rapidly than should have been the case. Let's face it, nobody really knows what the future impact of AI will be but I don't want my investments betting the house on which way it will go!
Sage (LON:SGE)
It is quite another to increase the financial risk substantially at precisely the time when the market is predicting significant pressure on future cash flows.
sorry but the market simply isnt expecting any pressure on future cashflow at all - then market is expecting cashflow to improve in line withn profits.
where on earth do you get the theroy that the market is expecting cashflow issues - inmho thats crazy suggestion - sage is cashflow machine.
Yes if you expect that in the future profits will be lower than the curent market expects - that would be an issue for you. but the market is expecting profits to rise in the future not decrease - and then trend in that direction is not downward - so i see zero indication ref worries that you are seeing.
imho all that has happened is sage has "derated" with p/e of 16 compared to previosuly 20-25 the market clearly thinks profits are going forward not backwards - they are just ascribing slightly lower rating - thats life.
If, however, we are wrong in our thinking then the company has engineered a position that will bring financial distress much more rapidly than should have been the case.
imho they have a crazy margin of safety here for that not to be the case - profit levels could halve imho with no such worries - other than limiting future buybacks. You are right its somhwhat doubling down on future prospects - thats exactly what you are doing withn buybacks. In that regard take on look at the track record and current expectations
Last year Future (LON:FUTR) generated £188m of free cash flow. Do you really believe that the market thinks that this is sustainable when it values the equity at just £297m and the whole enterprise at only £700m? Of course not.
Sage (LON:SGE) expectations are nowhere near as gloomy and hence it still retains a sensible investment rating. The business generated a healthy £248m in free cash this half year and therefore debt management is not an issue. However, debt has ballooned from £159m in 2020 to over £1.5bn today! A small part of that was a bolt-on acquisition, but the rest was buybacks. How big a cut to future earnings would it take to make servicing that debt an issue? I don't know, but I bet the market would start fretting about it fairly quickly. Let me be absolutely clear, I don't expect to be worrying about downgrades but if I'm wrong I don't want the headache of balance sheet weakness too.
Sage (LON:SGE)
Sage (LON:SGE) expectations are nowhere near as gloomy and hence it still retains a sensible investment rating. The business generated a healthy £248m in free cash this half year and therefore debt management is not an issue. However, debt has ballooned from £159m in 2020 to over £1.5bn today! A small part of that was a bolt-on acquisition, but the rest was buybacks. How big a cut to future earnings would it take to make servicing that debt an issue? I don't know, but I bet the market would start fretting about it fairly quickly. Let me be absolutely clear, I don't expect to be worrying about downgrades but if I'm wrong I don't want the headache of balance sheet weakness too.
It is what it is - if you see this as a risk sell up or give it a swerve if you are not comfortable.
I am 100% comfortable - as per earlier post earning could drop 50% and they would still be able to servioce the debt no porblem. So i am happy gaining bigger % of then compnay now - for that to be done on tick and paid for later -m is fine by me. This is a company growing income by 10% is on track for over £500 mill plus of free cashflow per year - if there is any troubles coming they can easy peasy stop dividends and buybacks before any issues arise - saas revenue aint gonna drfop off a cliff anytime soon. So you are right its doubling down on their confidence for the future - if you dont like that exit stage door left - to me their plan is clear and logical - debt aint always then risk issue it can be for some.
I don't want the headache of balance sheet weakness too.
thats the beauty of Sage - they can run what might appear to you as a weak balance sheet - their future cashflow being SAAS work will be super reliable (few worried about collecting cash from customers)- and if they needed to they could tone to down "investment in the business" to get extra cashflow - sensibly they are activelyt mkaing their products better and fit for purpose.
Each to their own here - with any share sometime you just gotta suck it up or move on.
Note i am normally an avid hater of debt too - so in that regard i am pretty cautious in nature unless i am taking a targetted gamble (I still hold some marstons where the debt really is way to high)
SpaceX - this bit made me laugh "Elon Musk, our founder, Chief Executive Officer, Chief Technical Officer and Chairman of our board"....top notch corporate governance!
Well at least it sounds a bit more professional than 'Techno King' and 'Master of Coin'
Buffett famously said that in the short term the market was a voting machine and in the long term a weighing machine. However, the dominance of passive investing mean that, until there is a recession in the US and flows into passive investments reverse, it will remain in voting mode. The market is dominated by buybacks and passive buys. In those circumstances valuation is meaningless.
The real issue with SpaceX, Anthropic and OpenAi is that they will add $3-4trn to the size of the markets, and as passive scramble to get the right weighting in them they will have to sell everything else, regardless of the relative merits of each investment. It's always worth listening to Mike Green: he's a regular podcast guest who has written the book on the risks of passive.
The fact that these 3 IPO's will go straight into the passive indexes (Nasdaq/S&P) and everyone's pensions with a weighting of $3-4tn is a scandal. Or you can view it as Musk playing a blinder (suckers over paying for his concept company). None of the 3 have a proven business model, or are profitable, nor any chance of being so in the foreseable future. Retail is being sold a pup by private equity. The size of the sale could result in genuine problems for investor returns going forward as the air comes out of the balloon.
Whilst the valuation is ludicrous, I do think that SpaceX does have a proven technology and business model. It is at least profitable before R&D costs.
100% agree with everything that you have written Donald and it wouldn't surprise me at all if these IPO's end up being the top of the market... these founders are much smarter than us after all... but the initial floats from these 3 will probably be between $ 175 - $ 250 bio..... only about 0.3 % of the US Stock market.... so I'm not convinced that there will be a scramble to sell everything
"passive scramble to get the right weighting in them they will have to sell everything else, regardless of the relative merits of each investment"
It is a fear shared by many. I also heard that Musk managed to change the US listing rules to get this IPO underway.
Claude says, "Nasdaq confirmed on March 30 that starting May 1, newly listed large-cap companies can join the Nasdaq-100 index within just 15 trading days of listing. Previously, companies had to wait up to a year. This change came after SpaceX advisers reportedly approached Nasdaq ..."
"The S&P is considering changing the rules for companies it calls "MegaCaps," defined as those with a value placing them within the top 100 largest by market cap. The three proposed changes are: removing the requirement that a company be profitable; eliminating the requirement that a company offer at least 10% of its stock to the public ..."
I don't know how Musk managed to do it, but he did. Maybe these indices considered SpaceX a "sure thing", or something.
Terry Smith quoted a report that said that every $1 invested in the market increases a share by $5 (something like that, anyway). There is a lot of momentum, and surprisingly enough, the effect is more pronounced in the mega-caps. As Prof Damodaran said, "He who lives by momentum dies by momentum."
Update: I suspect that "they" need SpaceX to enter the indices so that passive buy into them and provide liquidity. I bet funds are holding a ton of SpaceX. If they weren't in the index then they couldn't offload. The shares would just tank immediately anyone tried to offload otherwise. BWTFDIK.
SPACEX - its gonna be one heck of a ride!
https://finance.yahoo.com/news...
Looks interesting as to how it will play out but whichever way you slice it, it seems to be another way were the big boys can profit at the expense of individual investors. First by keeping these companies private for much longer than previously. Secondly by having the NASDAQ re-write its rules so there is a structure which seems to guarantee a short term wave of buyers and after 2 / 3 months when the trackers will be forced to buy up stock, (one suspects Hedge funds will also be having fun) and with all these dates including end the compulsory buy in/rebalancing period being known. While small investors can try and manoeuvre around this it will be difficult.
The stock that gets demoted to make way for SpaceX is likely to experience re-entry !
Wonder if NASDAQ will come to regret the "Fast Entry" rule changes.
Thanks Graham - very interesting and the mission makes most companies look like they have no ambition! Elon is a genius rocket man that is for sure. The valuation of SpaceX is truly bonkers though. The US market shows signs of multiple bubbles or even super bubbles. Semiconductor stocks are on bizarre valuations. SpaceX is valued at 100x revenue and loss making after enormous R&D expenditure, but will likely go ballistic on day 1. Nvidia is valued at 6 trillion, but is going to be floored by the Chinese releasing better chips for a quarter of the price, sooner or later. Enjoy the party whilst it lasts but this has all the signs of ending very badly. There will be no place to hide once these bubble collapses. When and where will it end I wonder? I am not sure that I can remember markets like this in my lifetime: US only!
The biggest risk to me appears to be the global debt markets if inflation and spending gets out of control - 10 year rates are close to a breaking point. To think that the FED are still money printing and under pressure to lower rates under these extremely hot conditions is unbelievable.
Totally agree Topvest - I moved to 80% in cash about a month ago, as I just see the downside risks - if they happen - as far greater than the upside, especially in the US, with its lofty valuation. If the US market corrects then it will likely bring everyone down with it.
I am not trying to time the market but as you mention, I keep looking at the markets and some sectors within them - largely in the US - with increasing disbelief and felt I wanted to take a lot of risk off the table. Fortunately, I don't have a mandate to be fully invested at all times - like many fund managers - and view this as one of the advantages we private investors have at our disposal.
In a past life I worked on the dealing and execution side of things for a stockbroker in London during the dotcom bubble and the feeling I get from some of the current markets reverberates similary with me, with investors FOMO leading them to chase momentum in all sorts of areas and chasing up valuations parabolically and, in my, view unsustainably.
I am also concerned about the bond markets as you describe, inflation increasing around the world as the strait of Hormuz remains effectively closed and any peace deal seems increasingly difficult to achieve, and the valuation and narrow concentration of the US market.
On an anecdotal front I live in an affluent part of southern England where I have heard shoppers in various outlets bemoaning the high cost of things and we are now seeing cold callers knocking on doors again, which suggest to me a squeeze on the consumer, as prices have gone through the roof - from food to fuel. Can companies continue to pass on their cost increases to a consumer already under pressure, or will many - as we are doing in my household - say "I'm just not willing to pay that!". This, in turn, has to hit company growth and earnings.
To my simplistic mind something has to give somewhere - by how much and how soon I have no idea - but at least I personally feel comfortable at the moment with my very defensive positioning. I know 3% interest on the cash in my SIPP is not my ideal level of return, but at least it is something, and if the markets do turn downwards I am sure I will be very content with it.
(Personal opinions only - the crystal ball broke the other year!)
Interested in what fellow investors use for none specific company news sources especially relating to foreign based operational entities.
Yesterday like many others I suspect were caught out by the Indonesian Governments proposed regulations on Palm oil producers (AEP and MP Evans particularly)
Not been aware of the news report on this until mid morning the shares were already down by 20% but the news was out at 5:17AM in the morning
https://www.reuters.com/world/asia-pacific/indonesia-plans-centralise-commodity-exports-through-state-agency-sources-say-2026-05-20/
Anecdotally if I had seen the news report I could have closed the positions at the open and potentially mitigated some of the losses.
Stocko is a godsend for company specific news but I need a news source that would pick up foreign notifications such as the above to not be blindsided in future.
Any advice would be much appreciated
Cheers
El
I set Google Alerts that send me stuff to inbox. It's not perfect, it's manual (ie you need to know what are the key risks for a company and set them all up as alerts individually).
For example I've got one tracking our Culture and Sports minister anytime she mentions gambling. For any gambling related shares, as they are very sensitive to regulation.
Agentic AI will be a solution eventually. You set it up to track hundreds of potential risks for a company, to run daily at 6am and give you a daily debrief before 8am. The big institutional investors are probably already using, I'd say it is cost prohibitive for individual investors at this point.
Thanks Boon Fund, The AI idea does sound intriguing, and sounds brilliant once economically available. Will look into Google alerts meanwhile, cheers
I received the AEP news from Investegate in my inbox at 1142 yesterday. Not as early as Reuters but better than nothing.
Yes GN100 I received the same, but this was I believe the company notification after the event. Stocko picks these up but not the actual news story that broke before the market opened unfortunately that drove the drop.
Has Trump just tweeted again to send oil up and the markets down?
I was speaking to my mate Dave across the Atlantic the other day. He was in an Uber with a driver who was a MAGA supporter. He was quite in agreement with Trump. He said that he noticed that Americans are much more politically unaware compared to the British.
I have come to the conclusion that there's no level of insanity that the American public won't tolerate.
well after 5 years of Trump they dont have much choice do they they have to suck it up.
- i must admit trump seems to have gone totally off the rails this term - i suspect many who voted him in are kinda annoyed that he seems to be causing mass carnage for stuff that makes no sense - he himself said he wasnt a president to go to war needlessley - then he goes to war needlessley with iran half way through active peace talks.
Trump seems to have got a touch of the Biden syndrome..
I would argue that there's not much difference with US and UK voters, how else do you explain Labour in Govt or current popularity of the Greens?
Most people don't see the damaged done. The British are fed up with politicians, as is most of Europe. The problem in Britain is there is no good party. Labour are useless, The Greens life on another planet, Reform could well be worse than both under Farage. As for the Conservatives, they deserved to be kicked out and are still very much divided, though they could be the best of a bad bunch. The UK and Europe are sadly very much like the US, actually being run by the elitists. And they call this Democracy. Imo, the Elitists are the ones that need kicking out before we end up in an actual war with Russia instead of a proxy war.
Well said!
A brief look at the history Stack BTC (OFEX:STAK) and one understands the integrity of our elected representatives.
From Kwasi to Farage; the cartel of greedy politicians exploiting public office for personal gains is so obvious.
All the best
The real question is, how do we take back control from the Elitists when they control everything?
you do what Musk did - setup in business and made some money - that option is available to everyone - and ref the elite - well their forbears will mostly have done the same - ok some of that may have been earned through dodgy activites back in the day.
Where we are stupid is that we allow people and companies to divert "uk plc" hard earned cash out of tehn county - often paying little vat or corporation tax or employee taxes. So rather than pile the taxes on small buisness owners - they should very much be taking % of revenue the likes of indeed / facebook / google /adobe / uber etc are diverting out of the country having paid little to nothing - ditto with any uk citizens having earned a wad in uk and not paying tax - hey ho silly does as silly does - if labour dont want to tax the elite "fairly" well i doubt there is much hope for any "poper party" doing that.
Yes the Space X valuation is crazy but opportunities will be missed by betting against Musk, you can disagree with his methods and politics but his vision and ability to get there is 2nd to none.
Neuralink has the potential to completely change lives for the better.
The only reason you can now go out and buy a decent VW, BMW, Renault or Ford electric car is because Tesla made a good one and made them wake up, and they are still playing catchup.
Space is completely untapped and perhaps essential in meeting our energy requirements for AI and the future. What space x have achieved already in 20 or so years is mind blowing and I doubt we can even guess at what the future will hold but I would guarantee that space x and musk will be at the forefront.
Before he went MAGA the exact people in America who now hate him were lauding him as a business/engineering genius/savior.
Yes his politics have changed or at least came more blatant but the rest of it seems pretty much the same.
Guess the only problem is if his political enemies get into the WH and punish him via spaceX.
SPSY - Spectra up about 9% today. Has been trading very strangely recently. I don't understand uncrossing trades but there has been a fair bit of late action before the close - only for it to almost always reverse the next day - this has been happening quite a bit recently.
Stock ranks 99 and 88 for Quality and Value. Momentum is only 45 but may re-rate soon as its up about 40% from the lows in just under 2 months (Overall stock rank of 95 - hasn't been this strong for about 2 years).
Some of the strange price action makes it seem like something might be happening, would be good to get some positive news as it has been quiet recently on the news front, usually on no news I would expect it to bumble along, strange the stock has been moving so much recently.
I'm a long term holder, but have been getting a bit impatient with the lack of contract wins / growth. I would also like to see them go after the authentication market more aggressively - not sure if that's possible but feels like they will lose out if they stand still.
Spectra Systems (LON:SPSY)
its an illiquid smallercap (sub 75 mill) company - not sure what your expectations are ref the norm. I fully expect the shareprice for this company to move perhaps 10-20% based on not alot. Might there be some reason - who knows you have to add in some people if the know wil know much more than us.
to me my main take here is that the price was 161.5 on 21/4 and is 162p today - so overall there is didly squat going on of note on the last 30 days - thats the reality. Perhaps something might be brewing - so a presumption that good news might be on the way might be right. I hold this share too and i am most ceetainly not trying to overthink daily volume of minor movements - what matters is what the company say when they update the market.
We are at a huge disavantage with smaller caps like this if there is "bad news coming" and we are often the last to know when that is the case - good news takes care of itself - but the clever money often exist before bad news - thats the risk we take holding companies like this - where the cancellation or a problem with a contract could materially affect thne valuation.
I'm a long term holder, but have been getting a bit impatient with the lack of contract wins / growth.
Yes - as things stand they are saying next year they will make didly squat - that will only not reflect badly in shareprice if they are promising better for 2028 - or can give hope those estimates are too conservative and will likely be updgraded.
I have given them credit for past deliverance before i bought in as they looked like company that could make £5 mill in a bad year - i as things stand if stocky forecasts are correct not sure exactly why 2027 is expected to be so bad. any company can have one bad year - and that might be an expectation it costs to get future years sales.
ref their outlook statemnt per ye accounts release - its not exactly over promising ref the near term when they say - coming years - well that could be 4-5 years in then future could it not be.
The combination of these prospects will allow the Company to accelerate its revenue and earnings growth over the coming years.
does anyone who has more insight than me know why 2027 is expected to be so bad ? and if there is an expectation they wil be back to £5 mill profit pa in a not so good year.
MELLO 2026 on 2nd & 3rd June
Another 11 companies have just been announced and this will guaranteed be the biggest two day investor show since the pandemic so come on down. If you have never been to a face2face Mello before then you are entitled to a taster ticket at a very low price of just £29 per day. Just enter the code NEWBIE when registering
https://www.melloevents.com/mello2026
Sceptics like myself would argue that Tesla still hasn’t done that - and that the company was dangerously close to collapse on multiple occasions (which I think Musk himself would agree with).
Musk likes to live in his alternative world - where he takes delight in saying we were running close to ruin (his living on the edge narrative) . Thats just ridiculous nonsense at that specific time Teslsa was still valued in the tens of billions of dollars and could esaily have raised money by issuing more shares - its nonsense to suggest it was close to collapse.
It might have been logical to presume company was overvalued - but its nonsense to suggest the compaany was near ruin - must was just telling porkies. Have you ever seen a company valued in tne tens of billions of dollars not ben able to raise funds to cover cashflow.
Most of the lies were spread by the shorters here saying that Tesla wasnt proper buisnes was a fraud and couldnt make decent profits and or have decent cahflow. In thgat regard Tesla is still going - and has provded when in sweet spot it can make decent money. My worry here is more to do withn competition and the like.
imho unles you can convince me Tesla couldnt simply have raised cash by issuing more paper - i simply dont believe it was near to failure in 2017-18 time.
Note perhaps there might have ben another agenda - he might have been happy for lower shareprice if that would have benefitted from that secanrio. anyway not having it that company valued at $30 billion couldnt have raised $5 bill cash to sort its cashflow - it could and would have had it needed to.
As predicted after my sale of M P Evans (LON:MPE) yesterday it is up 10% today and no doubt will go higher!
Don't worry - I did the same.
Me too. As the saying goes, 'A zen master's life is one continuous mistake.'
and me
Still below my sale price but the original investment thesis has gone unless the impact can be quantified. I can make other "bets" with better information than we have here at present. Or re-enter when things are clearer.
Doesn't make you wrong.
SpaceX Corporate governance is a something that Prof Aswath Damodaran talks about in his lectures. It's an important topic. Aswath talks about how, at one time, Sidney Potier was on the board of directors of Disney, citing it as an example of weak governance.
Turning to Musk, the class structure is sure to create lapdog directors that will rubber stamp whatever he wants.
Musk has already tried the $55b pay deal thing.
As I said to my mate Dave, SpaceX is a sign of a (US) market top. (I give myself a year's latitude on that). Let's see if I'm right.
You need to read John Authers today for a more optimistic data view
I suspect SpaceX will mark the top of this melt up.
This time next year US markets down 30%.
Seems 'rational' but very hard to fade unreality though
Excellent Results from Londonmetric Property (LON:LMP) today, including another dividend increase to give 7% yield. There are also a lot of other high yielding Property REITs that get coverage on the Investment Trust threads, for any interested in having a high yield portfolio.
Note the section below from the Londonmetric Property (LON:LMP) update today including this bit:-
“We are grounded in the belief that income compounding is one of the true wonders of investing - the essential ingredient and rocket fuel of long term wealth creation.”
That’s my investment approach and it works.
Andrew Jones, Chief Executive of LondonMetric, commented:
"Our results today reflect the progress that we have made over the last few years to create the UK's largest and most efficient NNN REIT. Despite macro uncertainty, our relentless focus on income and ongoing rental growth, has again delivered.
"Our investment activity through further M&A and direct transactions has maintained our strategy of owning high quality assets in winning sectors. This has helped to propel our rental income to a new record which has allowed us to progress our dividend for the eleventh consecutive year and put us a step closer to dividend aristocracy. We are grounded in the belief that income compounding is one of the true wonders of investing - the essential ingredient and rocket fuel of long term wealth creation.
"As owners of the business, our interests are fully aligned with our investors and we remain focused on our mission to operate, execute and allocate capital with discipline, experience and ruthless efficiency. We believe this represents the right way to invest. In today's environment, scale and efficiency are essential, and our relentless expansion has put us in a strong position with every reason to be optimistic. After all market uncertainty will undoubtedly throw up new opportunities."
A shed load of up dates and results this morning. Plenty for Graham and the team to choose from.
House building remains stuck in the slow lane judging by the announcements from Ibstock (LON:IBST) and Michelmersh Brick Holdings (LON:MBH) . It really does need something to kick start the industry. Over to Messrs Burnham or Streeting perhaps, who knows?
On a more positive note there are three portfolio companies reporting this morning.
Young & Cos Brewery (LON:YNGA) I have rarely read a more upbeat set of prelims. Like for like sales continue to increase along with revenue, helped by the recent acquisition of Cubitt House London Pubs. Operating margins remain impressive at 14% , net debt is coming down, two times, excluding IFRS 16. The shares trade at a significant discount to NAV and there is a reasonable yield, especially on the non voting shares. Much to like in my view. Together with Fuller Smith & Turner (LON:FSTA) it is one of the two pub groups in the portfolio.
ZIGUP (LON:ZIG) A short but sweet update. Trading at the top end of expectations. Continues to look too cheap in my view.
Sabre Insurance (LON:SBRE) Trading in line with a great dividend. At some point I expect it to be acquired.
As for SpaceX I will leave it to those with more money and a very different approach to investing than me.
All the best.
Lots of announcements today, but is there any chance you could add Northern Bear (LON:NTBR) to the list please? A rather brief 'in line' trading update, but given the expectation of a wet winter this might be a positive. Thank you!
SpaceX is an exceptional company with truly breakthrough technology, no question. But Musk adds an element of unpredictability, and the valuation is bonkers, you’re effectively paying upfront for decades of growth and perfect execution. That means taking on a lot of long‑duration risk today, with limited margin for error. At these levels, it feels disconnected from fundamentals, I’ll pass for now.
Yeah.... A bit like AI. If Space captures the retail sector's attention and it already has to a degree, we will see some overvaluation. The trend is your friend
I think we shoould be thankful to Musk - he has given us a massive warning not to get involved by creating a two tier voting structure!
"Bonkers" describes it perfectly.
Let not man's reach exceed his grasp.
SDI (LON:SDI) trading update sounded alright to me but the market does not like something, shares down 11%.
SDI (LON:SDI) still have pretty high debt. I recall the investor video in which the then CEO did not seem to have considered the effect of rising interest rates on profitablity. At one time they funded their acquisitions from profits.
Recovered a bit. Didn't think update shot the lights out, but solidly in line decent
Please add to the list ZIGUP (LON:ZIG) StockRank 98 with a pre-close trading update saying "FY2026 performance at top of market expectations".
will do, cheers Michael!
Hi Graham
Thanks for your thoughts on Autotrader (LON:AUTO).
I've recently caught the falling knife here and also topped up after today's fall.
This is one company that I've wanted to hold for years and I'm amazed how far it's fallen.
Having worked for the company many years ago (and with the current CEO on a few occasions) I'm hopeful that the share price will eventually recover.
I'm a big fan of the huge shareholder return strategy announced today.
---
On another note if it's quiet tomorrow it would be interesting to hear your thoughts on the Integrafin Holdings (LON:IHP) 's results earlier this week.
I've been tracking it for a while, but never bought. The SP seems to have gone nowhere for years and it looks seriously undervalued, even more so after interim results this week.
I'm keen to buy, but I'm wondering what a catalyst for a re-rating might be.
----
Finally thanks to you + the team for all the insights this week. I don't get much time to comment these days, but I still read all the reports and reader comments, which are always a useful addition to my own analysis.
Cheers
A
Cheers Abtan. Very interesting to hear you re: AUTO. I'm prompted to start researching it properly now! Roland is writing tomorrow's report and if it's quiet hopefully he'll have a chance for a look at the backlog. All the best. G
I assume Scottish Mortgage Investment Trust (LON:SMT) will be a big winner when SpaceX launches. 20% of Scottish Mortgage Investment Trust (LON:SMT) is SpaceX, circa 3bn, which they paid less than 200m for.
Scottish Mortgage Investment Trust (LON:SMT) has been my preferred way of accessing the SpaceX IPO.
Scottish Mortgage Investment Trust (LON:SMT) has gone from a discount to NAV of -8% at the start of 2026 to a premium of +5% now. The question is whether that change in its discount/premium fully takes into account the likely uplift to its NAV after the SpaceX IPO.
BTG Consulting (LON:BTG) ahead of expectations with a strong outlook. P/e of just 10 with a 4% yield. Too cheap. Ric Traynor took a step back to Chairman (albeit executive) last September. This was followed by the rebrand from Begbies Traynor to BTG. Ric still owns 17%. Reading the tea leaves, BTG is probably ‘in play’. One of my favourite quality UK small caps.
Genuine question - what leads you to believe that BTG Consulting (LON:BTG) is in play?
(I hold)
I listened to a podcast with Ric (think it was ‘The Business Case’) last summer and he was asked about a potential sale and he said something that peaked my spider senses (can’t remember exactly what!). This was followed up by replacing himself as CEO and then the rebrand to remove reference to his surname. Just a hunch!
Yes BTG certainly looks good value, although I note that FRP is even cheaper. Would quite like to own one of these but can't quite make my mind up. Growth metrics looks fairly similar too.
BTG is a better counter cyclical play - more insolvency and administration exposure. I’m very negative on the UK economy and domestic facing companies, under this govt - tax regime and energy policy and so this BTG was my choice
I would say on the insolvency/administration side, Frp Advisory (LON:FRP) is my choice.
But BTG Consulting (LON:BTG) are diversified. They have a strong property advisory and auction atm now.
So it's kinda what you would prefer, in terms of exposure.
I hold BTG as a counter-cyclical hedge. Will go to 140-150p if signs of recession/stagflation start worrying investors.
(I hold BTG)
BTG & FRP - They both look too cheap to me. But Stocko has educated me to be sceptical of certain kinds of professional services companies. Are we confident that this is being run for the benefit of shareholders instead of mainly for the benefit of management? I don't know the answer, but this is keeping me on the side-lines, a pet hate of mine is a well performing business whose share price goes nowhere while the management take the majority of the financial benefit. Anyone have a good idea of the remunerations structures and whether this is a fair concern to have?
Yes this is what is keeping me on the sidelines although I agree they are cheap. As people businesses with very specialist, in-demand employees there will always be a lot of pressure to distribute profits towards staff rather than shareholders. There also seems to be little in the way of operational gearing as they grow - generally if they want to take on new business they'll need to employ more staff, so costs will tend to rise at least as quickly as revenues.