Daily Stock Market Report (Thur 23 Jan 2025) - GETB, IGG, RBN, GKP, LUCE, WJG, ABF, MAB1, KOO

Good morning! We have another mammoth set of updates to digest.
Spreadsheet accompanying this report (updated to 17/1/2025)
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Associated British Foods (LON:ABF) (£14.1bn) | TU | Revenue warning: Primark now targeting low-single digit growth in 2025 (prev: mid-single digit). | AMBER/GREEN (Graham) Profit forecasts are unchanged and Primark is growing internationally. Interesting at PER below 10x. |
| IG group (LON:IGG) (£3.8bn) | Interim Results | Adj. PBT +30% to £267m. Extends buyback. Confident of meeting consensus rev & PBT for FY25.. | GREEN (Graham holds) Very impressive numbers even if only in line. New management team are interesting. |
Spectris (LON:SXS) (£2.7bn) | TU | Adj. op profit above consensus (£197m) at upper end of the range (£183.3 - 201m). | |
MITIE (LON:MTO) (£1.4bn) | Q3 TU | Good Q3 performance “underpins confidence” in FY adj, op profit of £225m, FCF at least £100m. | |
CMC Markets (LON:CMCX) (£746m) | TU | NOI in line with previous guidance, costs in line. | AMBER/GREEN (Mark) |
THG (LON:THG) (£582m) | Q4 TU | FY 2024 in-line with expectations, Gross Debt £550m | |
Boku (LON:BOKU) (£566m) | TU | Rev +20%, adj. EBITDA +22% | |
Ashtead Technology Holdings (LON:AT.) (£444m) | TU | Full-year revenues c. £168m, adj. EBITDA ahead of consensus. Growth to continue in 2025 in line. | |
Gulf Keystone Petroleum (LON:GKP) (£352m) | Ops Update | 2025 YTD gross production 47.9kbopd, 40-45kbopd guidance for 2025. Cash $102m. | AMBER (Mark) |
Team17 (LON:TM17) (£350m) | TU & Change of Name | Rev & adj. EBITDA slightly ahead of exps. New name “everyplay”, new ticker EVPL. | |
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£368m) | TU | Rev +11%, adj. PBT +31% to £30.3m, ahead of consensus (£29.2m). Pent-up demand. | GREEN (Graham) Profits have beaten consensus with adj. PBT of £30.5m in a bad year. Mortgage applications are now rising at a solid rate (+15%) and I'm excited to see how MAB1 can perform in better market conditions. |
Forterra (LON:FORT) (£344m) | TU | Adj. EBITDA £50m, in line. Net debt lower than expected at £85m. Outlook: uncertain recovery. | |
Fonix (LON:FNX) (£202m) | TU | H1 adj. EBITDA in line. 3p special divi. O/look: stronger H2 weighting, confident in meeting exps. | |
Luceco (LON:LUCE) (£201m) | TU | Ahead of expectations. Rev +15%, Adj. Op Profit +20%. | GREEN (Mark - I hold) This beat highlights that this is a great business at a very reasonable price. |
Animalcare (LON:ANCR) (£165m) | TU | Rev +4.9%, underlying EBITDA in line with market expectations & prior year | |
Netcall (LON:NET) (£164m) | TU | Rev +22%, Adj. EBITDA +18%, in line with expecations | |
Zotefoams (LON:ZTF) (£143m) | TU | Rev. slightly ahead of current market expectations, Adj. PBT £15.6m ahead of expectations. | |
Iqe (LON:IQE) (£120m) | TU | Rev & Adj. EBITDA ahead of expectations. | |
Pharos Energy (LON:PHAR) (£107m) | TU & Ops Update | 2024 prodn 5,801 boepd, in line with guidance. 2025 guidance 5,000 - 6,200 boepd. | (Mark) |
Chapel Down (LON:CDGP) (£63m) | TU | Net sales -5%, in line with guidance, net debt £9.2m | |
Kooth (LON:KOO) (£63m) | TU | 2024 Rev in line, Adj. EBITDA ahead of expectations. | AMBER (Mark) |
| Watkin Jones (LON:WJG) (£51m) | Full Year Results | Revenue falls but adj. op profit improves to £10.6m. Medium term outlook remains strong. | AMBER/GREEN (Graham) Still no estimates for 2025. I leave my stance unchanged purely on the basis of balance sheet equity. Provisions might stabilise from here? |
Revolution Beauty (LON:REVB) (£46m) | TU | FY25 sales to decline 25%, high single digit £m underlying adj. EBITDA, net debt £26m | |
Iofina (LON:IOF) (£42m) | Corp Update | Prodn +13.4% within forecast range, strong spot prices, shipment delays mean adj. EBITDA $7.5m, below expectations. | (Mark) |
Angle (LON:AGL) (£42m) | TU | “Strong progress”. Rev +3%, ARR +6%. Net cash £1.1m, “sufficiently funded to execute its strategy”. | |
Getbusy (LON:GETB) (£27m) | TU | “Strong progress”. Rev +3%, ARR +6%. Net cash £1.1m, “sufficiently funded to execute its strategy”. | AMBER/RED (Mark) |
Skillcast (LON:SKL) (£37m) | TU | Rev +18%, ARR +25%, EBITDA in line at £0.5m, net cash £9.1m. | |
Robinson (LON:RBN) (£18m) | TU | Rev +14%, op. profit moderately ahead of current market expectations | AMBER (Mark) |
Smarttech247 (LON:S247) (£11m) | Final Results | Rev +8.2%, Adj. EBITDA -50%, Cash €3.34m down from €6.06m |
Graham's Section
IG group (LON:IGG)
Unch. at £10.71 (£3.8bn) - Interim Results - Graham holds - GREEN
At the time of publication, Graham has a long position in IGG.
We covered IG’s acquisition of FreeTrade last week. Today we have interim results with an in line outlook statement.
The headlines:
Revenue up 11% to £522.5m
Net trading revenue up 12% to £452m thanks to higher revenue per client. The number of active clients was down fractionally on the prior year.
Net interest income flat at £71m: higher client money balances, lower rates.
The result: adj. PBT up 30% to £267m. IG is less operationally geared than CMC Markets (LON:CMCX) but even IG in this case has enjoyed a very nice increase in profitability against a relatively modest increase in revenues.
In simple terms, IG’s trading revenue increased by nearly £50m, its operating costs fell by a few million, and there was a clean conversion into £60m+ of higher PBT.
And the accounts are fairly clean, with fewer adjustments than we saw in H1 last year. £266.8m of adjusted PBT becomes £249.3m of actual PBT.
H1 earnings per share, boosted by the above factors and by share buybacks, have risen by a remarkable 55% year-on-year (from 33p to nearly 52p).
Shareholder returns: the interim dividend gets a small increase to 13.86p (total value £49m) and the current buyback programme is extended by £50m to £200m.
CEO comment:
First half performance reflected more supportive market conditions, but we have work to do to grow active customers which will be necessary to deliver sustainably stronger growth…
Current trading has been satisfactory, and we remain confident of meeting consensus revenue and profit before tax expectations in FY25.
The new CFO gets a pleasant introduction to his new job, reporting positive news to shareholders. He says:
It is clear to me that IG has many strengths, including solid positions in large and growing addressable markets, geographically well diversified revenue, high margins and strong capital generation. However, we are competing against many new and highly capable players and there are many things we must improve to take market share.
Explaining the high revenue levels, he notes that "volatility normalised to long-term averages from unusually low levels in the prior year”.
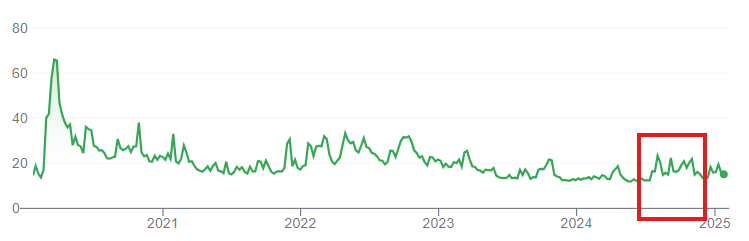
Here is the 1-year chart for the VIX Index, and I’ve put a red box over IG’s H1 period to help to demonstrate that yes, this was a period of much volatility:

Looking at this, you might think that H1 was an outlier with exceptionally high volatility. While its true that the spike in the VIX on 5th August was exceptional, I don’t think that the six-month period as a whole was particularly volatile. Here’s a 5-year chart for context:
Even so, there is a little bit of caution that volatility could revert back to lower levels, with an implication that IG would like to have a smoother revenue profile where it does not need supportive market conditions to do well:
Performance in the period was a good demonstration of IG's ability to capture cyclical upside, but our focus is on delivering sustainably stronger growth from more diverse revenue streams.
Revenue streams: I’m pleased to see continued growth from the “Stock trading and investments” segment, but it remains a minnow in comparison to the others:
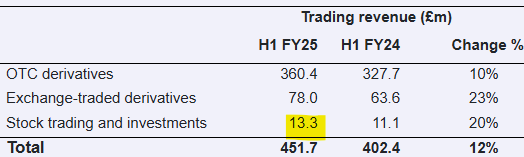
Revenue per client in “Stock trading and investments” was only £157 in H1, vs. £2,523 in OTC derivatives (i.e. spread betting). It is far, far more lucrative to sign up a new spread betting client than it is to sign up a simple buyer and seller of stocks.
But it was a particularly busy six months for OTC derivatives clients, who had generated only £3,800 of revenue each during the previous financial year. And now they have generated more than £2,500 each in just six months.
Graham’s view
I’m GREEN on this again, for reasons mentioned before.
IG’s new CEO is the former high-profile CEO of Paddy Power Betfair which I think provides a useful background.
The new CFO has been hired directly from Virgin Money and has many years of experience as CFO at financial organisations.
I am pleased that they aren’t resting on their laurels on the back of this strong H1 performance, and are thinking about how to grow active clients.
On a broader point, I’m reassured by the company’s exposure to different risk factors. IG can benefit if any of the following things are true: interest rates are higher (the company benefits from higher interest on client balances), volatility is higher (so there is more trading activity), or markets are performing strongly (so that clients have more cash available to put on deposit). It seems to me that it’s a pleasant combination of factors where there should always be at least one positive driver of performance.
For a big company’s also a market leader, its progress in recent years has been staggered but very good:
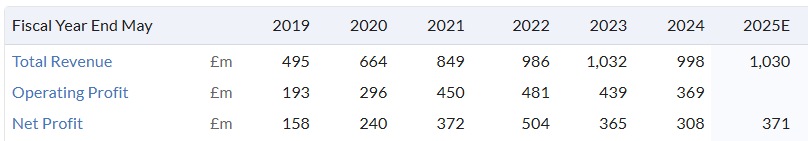
Overall, I remain very happy to have this in my portfolio as it trades on a P/E ratio of about 10x.
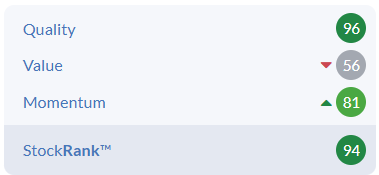
The StockRanks share my positive assessment:
Watkin Jones (LON:WJG)
Up 21% to 24p (£62m) - Graham - AMBER/GREEN
Thanks to JASVFS for requesting this one.
I was AMBER/GREEN (at 36p) on the day of the profit warning last August.
The company builds homes for rental, with a particular focus on affordable and student accommodation.
Today’s adjusted full-year results show an improvement on last year:
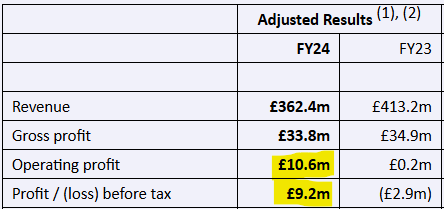
Watch out though - there are important exceptional charges. £7m of remedial costs for building safety, and £2.5m to reflect the passing of time as the building safety provision is measured at its present value rather than at the actual value that the company expects to pay.
The improved profitability (before exceptional charges) reflects the sale of two schemes and the successful completion of six schemes.
Estimates: the profit result has beaten the £7m estimate at Progressive, although revenue is a huge miss. There are still no estimates for 2025.
Dividend: there has been no dividend since 2023, as the Board prioritises financial flexibility.
This is necessary because of…
Provision for building safety works: there is now a net provision of £48m, down by nearly £7m year-on-year.
£16m was paid out in remediation works, in line with expectations.
However, £7m was added to cover new properties and to change the scope on properties that had already been provided for.
Outlook: they seem more confident in the medium-term than they are in the short-term.
Investment market gradually showing signs of recovery, though pace is likely linked to further reductions in gilt and interest rates.
Medium term outlook remains strong with excellent sector fundamentals continuing to drive investor sentiment and allocations.
Along similar lines, the CEO says that the investment market “has continued to be challenging”.
They want to do more forward sales, but it seems that it is difficult to get deals over the line in this interest rate environment, forcing WJG to develop “new approaches” and considering “differing types of transaction”.
The CEO continues:
We will continue to keep an open mind when exploring the funding options available to us, in order to provide a robust business in the long-term interests of our stakeholders.
Graham’s view: I’m afraid that higher rates have, for now, broken the business model as forward funding liquidity is not available in the amounts needed.
I don’t expect this situation to last forever, and so it makes sense to me that the company would be more confident in the medium-term than it is in the short-term.
A big worry for the short-term is building safety provisions currently standing at £48m (after £55.6m of total provisions are netted against agreed customer contributions to the works of £7.6m).
The company has a net cash position at year-end of £42.6m, and it acknowledges that this is a seasonal high as cash peaks around year-end.
That cash position will be needed to fund the remedial works. An important point is that the works are being carried out gradually, with an expected cash outflow of £10.6m to fund them in FY25.
That being the case, WJG should be able to use its generally strong balance sheet (and perhaps some future profits) to help pay for works over time.
Balance sheet equity is £133m of which its tangible value is £122m.
An important question is around the reliability of the provision for remedial works.
Here’s an excerpt from the footnotes:
The amount provided for these works has been estimated by reference to recent industry experience and external quotes for similar work identified. The investigation of the works required at many of the buildings is at an early stage and therefore it is possible that these estimates may change over time or if government legislation and regulation further evolves. If further buildings are identified this could also increase the required provision, but the potential quantity of this change cannot be readily determined in the absence of such identification through further claims or investigative work.
Unfortunately this reads in a very open-ended way, in terms of the potential cost.
Later in the footnote, WJG says that if an additional property is identified which requires remedial works for which they are liable, a reasonable estimate of the cost would be £0.9m. That at least puts some kind of limit on possible increases in the provision.
Despite the difficulties with the business model and the potential for rising provisions, I’d like to keep this at AMBER/GREEN, the same stance I had when the shares were at 36p.
The biggest risk is that the company’s cash position starts to get tight. WJG has a £50m borrowing facility which is only supposed to be used for land acquisitions and development, which I guess excludes remediation. At least they aren’t paying any dividends for now - almost certainly the correct call.
I keep coming back to that £122m tangible value on the balance sheet. Perhaps WJG should start to think about crystallising some of that value? Even if they don’t particularly want to, it could ward off any concerns that investors may have around financial stress.
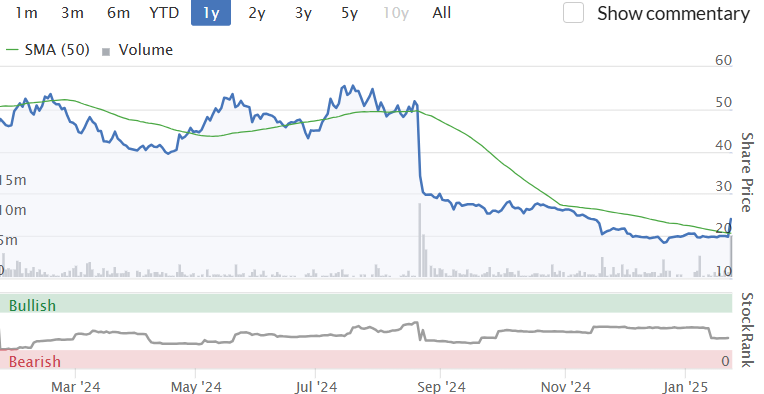
Associated British Foods (LON:ABF)
Down 3% to £18.77 (£13.7bn) - Trading Update - Graham - AMBER/GREEN
There is a tempering of expectations at Primark with only 2% sales growth over the 16 weeks to early Jan, including a 6% decline in like-for-like sales in the UK/Ireland.
The main disappointment was in womenswear which saw weaker sales in cold-weather and seasonal clothing.
All other regions - Spain, Portugal, France, Italy, Northern Europe, Central & Eastern Europe and the United States - all saw varying levels of growth.
Central & Eastern Europe and the United States, the two smallest regions, are currently being boosted by new store openings.
Grocery - revenue up 1%. Twinings and Ovaltine saw good growth, weakness in other brands.
Ingredients - revenue up 4%.
Sugar, Agriculture - small declines in both of these.
Outlook - Primark is now only targeting low-single digit sales growth in 2025, where it previously targeted mid-single digit sales growth.
Growth will come from store rollouts in international growth markets, offset by the weaker like-for-likes seen in the UK/Ireland in Autumn.
Fortunately the profit position shouldn’t change too much:
We continue to expect Primark's adjusted operating profit margin to remain broadly in line with last year's level, as gross margins have continued to improve and good cost management offsets inflation and the step-up in investment.
Graham’s view
I don’t have a strong view on this one but I’m happy to leave the AMBER/GREEN expressed by Megan in November unchanged.
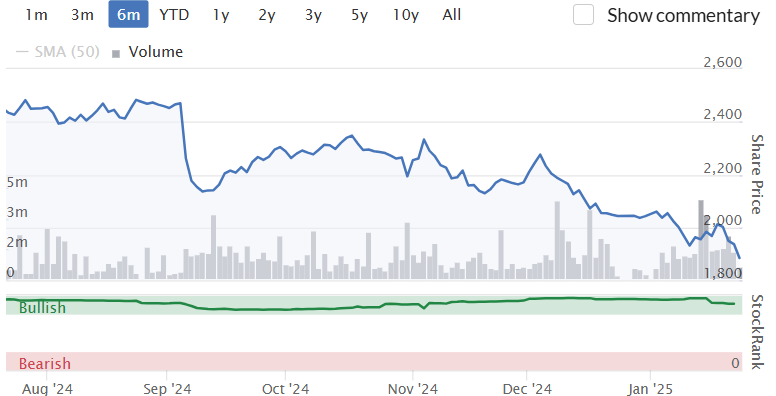
The shares have been very weak in recent months:
But EPS forecasts have been holding up:
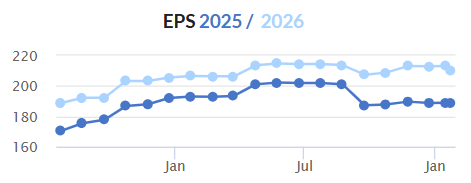
With the PER nudging just below 10x, I think this FTSE-100 member is not a bad candidate for investment.
Worth noting that it has official net debt of £2.0 billion, but this includes £3.1 billion of leases.
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Up 9% to 688p (£399m) - Trading Update - Graham - GREEN
I left this network of mortgage advisers on my watchlist for 2025 and am pleased to see a brief but positive full-year update today.
Key points:
Revenues in 2024 rose 11% to £266m, much faster than the 4% growth in overall UK gross lending.
Adj. PBT is up 31% to £30.5m, better than the consensus estimate of £29.2m.
The number of advisors across the MAB1 network grew very modestly, but their productivity improved by 12%.
Outlook:
Clear signs of pent-up demand were evidenced by the increase in mortgage applications in Q4 2024 (+15% compared to Q4 2023) and we expect this positive momentum to be maintained. UK Finance forecasts gross new lending to rise 11% in 2025 in £235bn, which we believe is a realistic estimate.
In addition, the delivery of new technology enhancements and lead generation initiatives are expected to drive further growth this year, with many AR firms expecting to see adviser numbers increase, alongside a continued focus on increasing profitability through rising productivity.
Graham’s view
I’ve had this one on my watchlist because I’ve been so impressed with the company’s financial performance during a period (c. two years) in which mortgage volumes have been depressed or lethargic.
If the company is able to perform like this in stagnant conditions, I’m excited to see what it might do when conditions are more favourable.
We might get to see that this year, with new lending forecast to rise at an impressive rate.
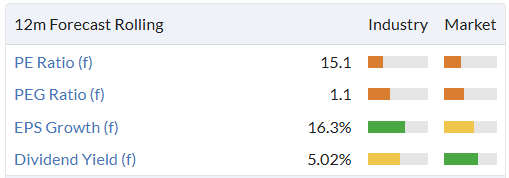
I don’t see the shares as expensive here, given its underlying quality as a successful franchising business:
Mark's Section
Getbusy (LON:GETB)
Up 2% to 55p - Trading Update - Mark - AMBER/RED
The irony of calling this provider of productivity software for professional and financial services Getbusy is that they haven’t been very busy, nor productive:
Annualised Recurring Revenue (ARR) grew by 6% at constant currency to £21.6m with reported recurring revenue up 4% at constant currency to £20.8m. Total revenue was up 3% for the Year, at constant currency, to £21.4m.
This is barely in line with inflation. The good news is that they managed to increase adjusted EBITDA by 40% and now say that this was…
…the first year that the Group has broadly broken even at the Adjusted Profit level.
With the lack of top line growth, this presumably means that they have been cost-cutting. On one level, this means they have a good grasp of where they find themselves but this hardly reinforces the case for future growth. The other problem is that EBITDA is a poor metric for a company such as this that capitalises more internal development costs than it amortises. We need to focus on cash flow. Here they say:
Net cash at 31 December 2024 was £1.1m with available cash funds of £3.1m.
This has improved since the half year, where net cash was just £178k. However, it is still down on the previous year’s value of £1.9m. It is also a function of timing on how they get paid upfront for their software. Current liabilities exceeded current assets by £6.7m. While growing software companies can maintain this position almost indefinitely, any slip-up here will start to consume cash. So, while it is good that the company say:
The board considers the Group to be sufficiently funded to execute its strategy.
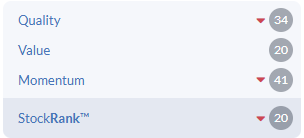
That they have to say this at all means that it isn’t necessarily a given. Despite these worries, the market cap remains a heady £27m. It looks like the StockRanks have got the measure of the investment opportunity here:
Mark’s view
It can be hard to value growth stocks that are just breaking into profitability. The problem here is that this company isn’t growing anywhere near rapidly enough to justify its current rating. It's an AMBER/RED for me.
Robinson (LON:RBN)
Up 11% to 119p - Trading Statement - Mark - AMBER
A return to growth for this plastic packaging manufacturer comes as some relief, as the trends towards avoiding plastics continue. This is driven mainly by volume, which is good news:
Revenue for 2024 is anticipated to be £56.5m, which is 14% ahead of the prior year. After adjusting for price changes and foreign exchange, sales volumes are also 14% higher than in 2023.
There is even better news on the profitability front:
The Company is pleased to report that 2024 operating profit before exceptional items and amortisation of intangible assets is expected to be significantly ahead of 2023, and moderately ahead of current market expectations.
House Broker Cavendish provide the details; upgrading Adj. EPS from 9.3p to 10.9p, a 17% uplift. This is a larger increase than the EBITDA increase, suggesting that progress on net debt is leading to lower interest costs too:
Net debt at 31 December 2024 is expected to be £5.9m (31/12/2023: £6.3m) following substantial capital expenditure in the year.
Cavendish say this is some £2.4m better than their previous expectations of £8.3m, driven by the uplift in profitability and better working capital management. Perhaps equally importantly, Cavendish upgraded FY25 EPS by a similar amount to 11.5p. This makes the forward P/E a very reasonable 10.3, even after today’s rise. Dividends are expected to be maintained at 5.5p for a 4.6% yield at today’s share price.
There is a chance that debt may be reduced further by excess property sales. However, these have always been pretty lumpy and plagued by delays over the years, so it may be too soon to count this chicken. The debt remains a significant part of the capital structure, and when I adjust for this, the forward P/E comes out closer to 14.
Mark’s view
The new CEO appointed in August is clearly doing things well here, with volumes up, costs controlled and good working capital management. However, the backdrop remains difficult, with plastic packaging increasingly being replaced with cardboard where possible. There will always be the need for some single-use plastics, but environmental pressures will constrain growth. As such, a debt-adjusted P/E of around 14 seems to be up with events, and I am neutral on the prospects here. AMBER
Gulf Keystone Petroleum (LON:GKP)
Down 1% to 160p - Ops Update - Mark -AMBER
Good news on the production front, as the company manages to produce and sell significant quantities of oil into the local market at the moment:
2025 year to 21 January gross average production of c.47,900 bopd
Guidance for the full year is a little below this level, but perhaps up a bit on 2024
2024 gross average production of 40,689 bopd, an 86% increase versus the prior year (2023: 21,891 bopd)....
Should local market demand persist at current levels, 2025 gross average production is expected to be in the range of 40,000 to 45,000 bopd
Being a rather simple business, we can work out what this would mean for future financials, taking the midpoint of the production guidance and 24H2 oil price received, and their net entitlement is 36%:
42,500 x $27.5 x 36% x 365 = $154m net revenue.
The other key figures are also given as:
Estimated 2025 net capex of $25-$30 million, reflecting disciplined and flexible work programme focused on safety, reliability and maintaining the capacity of existing wells…
Stable low costs, with expected operating costs of $50-$55 million and other G&A below $10 million in 2025
This works out to be around $90-95m of free cash flow. The current market cap is around $430m and EV around $330m. So the EV/FCF is just 3.6. This makes the company look very cheap, with a potential upside if their export pipeline ever gets approval to start again. The downside is that they operate in an extremely unstable part of the world, and that local demand for their oil can be very variable. Thier reserves should support production for many years. However, at some point, they may need to invest more into capex to maintain their infrastructure rather than just returning capital to shareholders.
Mark’s view
I think a strong argument can be made that the company is currently undervalued even on the current local production for which they receive low prices. However, the payment terms are very good here, with them receiving cash on delivery for every barrel. This has enabled them to pay good dividends and buyback shares. However, this remains incredibly risky, given the region in which the company operates and will only be suitable for the most risk-tolerant investors. As such, an AMBER rating feels like the right balance.
Luceco (LON:LUCE)
Up 9% to 136p - Full Year Trading Update - Mark (I hold) - GREEN
Good news at this supplier of electrical products:
The Group expects to report a full year 2024 performance ahead of market expectations*, with revenue in the region of £240m (2023: £209m) and Adjusted Operating Profit in the region of £28.5m - £29.0m (2023: £24.0m).
Helpfully, they provide the consensus:
Company compiled analyst consensus as at 22 January 2025 is for full year 2024 revenue of £234.2m (Analyst Range of £232.8m - £234.6m) and Adjusted Operating Profit of £26.5m (Analyst Range £26.0m - £27.2m)
This works out to be a 2.5% revenue beat, and an 8.5% Operating Profit beat underlying the operational levergae that this business has. The only updated research I can see is from Longspur, who don’t appear to have updated their block model to reflect the revenue figures the company has given today, so I am ignoring that. In the absence of better information, I would assume that EPS rises by a similar amount to the operating profit beat, which would be around 12.3p based on the previous consensus.
It seems that the trends that have seen many building products suppliers have a good 2024 are also having an effect here:
The strong order book from Q3, combined with increased trade and retail orders, led to impressive sales growth at the end of the year in the Group's Residential RMI divisions.
Plus, their move into EV charging is proving to be a good one:
Our Residential EV Charger division also continued to outperform, with quarterly year-on-year growth of c.50%, reflecting both a strengthening market and successful new product launches.
Not all of their 15% sales growth is organic, though. They delivered 5% organic growth. However, they continue to describe their markets as challenging so this can be expected to improve as market conditions do.
The market occasionally gets worried about the debt levels here, as the company are happy to make acquisitions via debt. They say:
The Group's balance sheet remains robust with Bank Net Debt at 1.7x EBITDA (within our target range of 1.0 - 2.0x) despite increased working capital requirements commensurate to the strong trading in Q4.
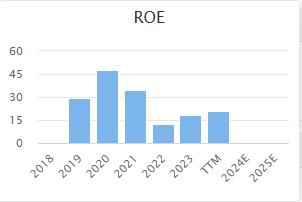
This may well be why the shares here have been weak recently. While debt levels may worry some, they have a history of paying down acquisition debt rapidly from internal cash flow. The leverage also gives the company great returns on equity:
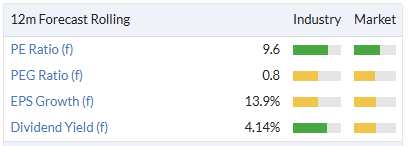
The downside is that the multiples that look pretty cheap on the surface, are not as impressive if you adjust them for the net debt:
Mark’s view
This update highlights what we already know - that this is an incredibly well-run business with the ability to grow faster than its end markets via acquisition. Its operational leverage, combined with strong returns on equity, means that this strategy generates strong EPS growth over the long term. I don’t see why the company won’t be able to compound EPS at reasonable rates well into the future. While the rating isn’t incredibly cheap once you adjust for the debt, it is not expensive either. This is a great business at a very reasonable price, so I retain the GREEN rating.
CMC Markets (LON:CMCX)
Down 14% to 227p - Trading Update - Mark - AMBER/GREEN
As commenters have pointed out this is very short statement here, which is in line with the guidance they had previously given:
The Group remains on track to achieve annual net operating income in line with previous guidance.
In their interim results, they said they were in line with market consensus, which they gave as:
External market consensus for year ending 31 March 2025 is net operating income of £332.9 million.
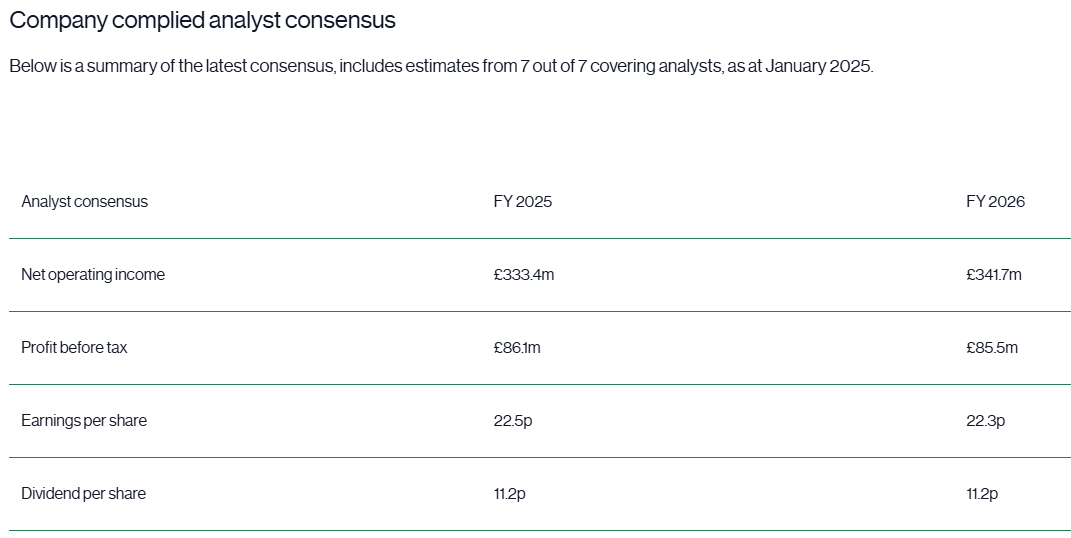
They also publish a consensus on their website that can be useful:
The other side of the equation is costs, where they say:
Management also remains confident in meeting its cost guidance of approximately £225 million, excluding variable remuneration and non-recurring charges.
It’s a shame to get no guidance on the variable remuneration, but perhaps they simply don’t know this until year end close. Here’s how the variable remuneration stacked up in H1:
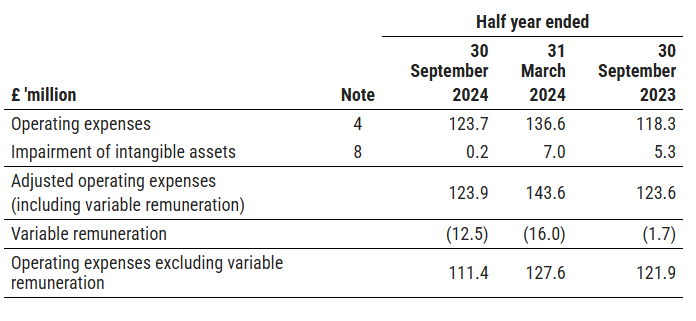
So, backing out the analysts' consensus, this means £22.3m for variable costs for the full year, or £9.8m for H2.
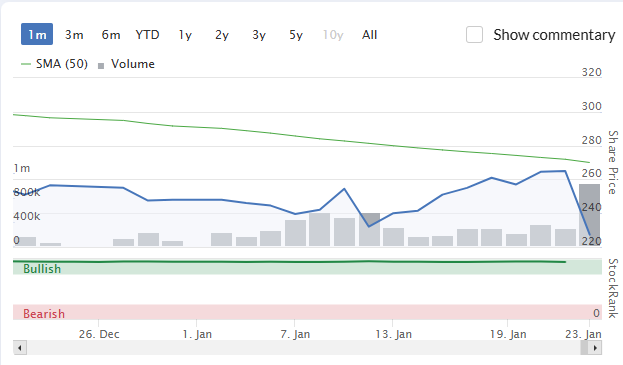
The share price has fallen 14% today. This may be the market doubting that the variable remuneration will be this low, or it may be that the market was expecting them to beat expectations. The share price was strong in the run-up to this trading statement:
After all, forecast valuation metrics prior to today’s fall had them at a premium to the sector:
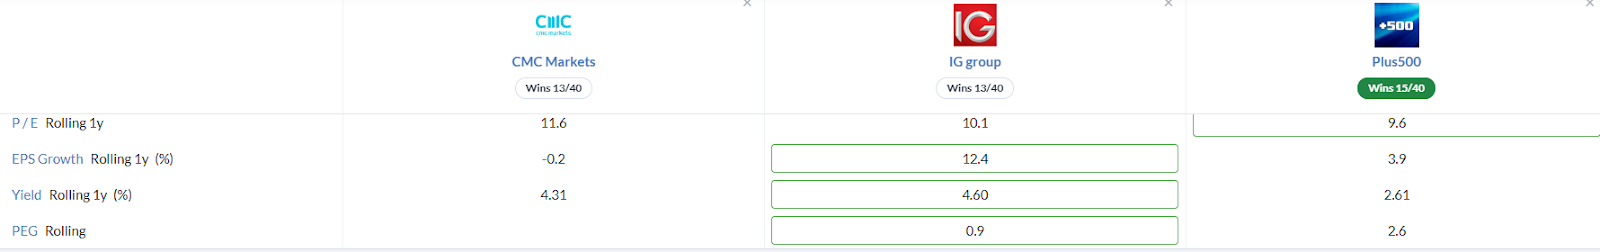
Things look better when net cash is taken into account, though:

Balancing this, investors who enjoy being entertained should read the Glassdoor reviews on the company and CEO:
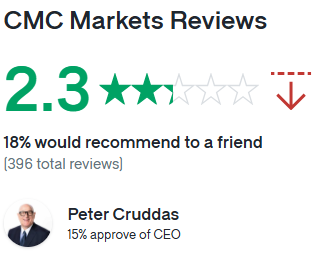
This hasn’t stopped them making money for shareholders in the past, of whom Cruddas is the largest, but perhaps means the risk here is higher than the sector.
Mark’s view
While there was nothing wrong with today’s in line update, the market was clearly expecting better. A relatively terse statement probably doesn’t build confidence. However, with the shares now trading at a similar P/E to peers, and cheaper on an EV/EBITDA basis, this is starting to look good value again. The share price is highly volatile, which means there will be a time to buy this again, I’m just not convinced that time is now. AMBER/GREEN for me.
Kooth (LON:KOO)
Down 2% to 170p - Trading Update - Mark - AMBER
Revenue is in line, showing some phenomenal growth rates here:
2024 revenues are anticipated to be in line with consensus market expectations of £65.8m (2023: £33.3m).
EBITDA growth is even better, and beats expectations:
Adjusted EBITDA is expected to be at or ahead of the top of the range of analyst forecasts of £12.7m (2023: £2.3m), helped by certain items which are not expected to recur in the current year.
However, it's this last line, which shows that the beat is likely a one-off, which is why the shares are actually down today in response.
I’m not sure I trust the broker consensus here, so doing some simple maths, at the half year, they said:
● Adjusted EBITDA to £7.8m (2023: £0.0m)
● Profit after tax of £3.9m (2023: £0.5m loss)
This gives H2 EBITDA of £4.9m. D&A in H1 was £2.6m, giving PBT of £2.3m and £1.7m PAT on a standard tax charge. That’s £5.6m PAT for the FY or 15.4p EPS. The P/E of 11, then, is potentially not that expensive for a company with their growth track record.
The problem is that their product, which is a mental health platform for teens, has faced some significant pushback in the US. The perceived issue is that parents do not have sight of the support given. My own view is that without something in place, there will be an increasing crisis in teen mental health, and the benefits outweigh the risks in this regard. However, logic rarely wins out in such emotive issues. The good news is that they keep winning pilot projects, although these won’t move the needle unless they become more than a pilot:
As announced in December 2024, Kooth has agreed terms for a new pilot contract with the State of New Jersey valued at $1.45m. Under the terms of the Contract, Kooth is providing mental health support via its Soluna platform to school districts within New Jersey, reaching 50,000 students aged 13 to 18. This pilot went live on 7 January. The Company continues to hold negotiations, which are expected to be concluded in Q1, regarding a second pilot contract in the US.
Mark’s view
This is a potentially interesting growth company, having a positive social impact and on a relatively modest valuation if my maths is correct. The problem is that the political risk in their key market of the US is almost impossible to quantify or mitigate. So it's an AMBER for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
"Revenue streams: I’m pleased to see continued growth from the “Stock
trading and investments” segment, but it remains a minnow in comparison
to the others:"
Graham, personally I'm not convinced there's any growth in Stock trading and investments, outside of net interest income. Looking at the HY figures, it looks to me as though trading revenue has flatlined since 2021, with client numbers in gentle decline since 2022. It's a shame, since back in 2021/22 I was hoping they could really take off as a stock trading provider in order to de-risk the leveraged side somewhat, but that doesn't seem to have happened. On the other hand, one could regard the Tasty Trade acquisition as de-risking the traditional leveraged side, since it's unlikely to be exposed to the same regulation as UK SB and CFDs for example.
IG group (LON:IGG) down over 6% after revenues up 30% in line with expectations. Does anyone have any idea why?
IG group (LON:IGG)
I thought today's results were excellent and I was impressed with management during today's call.
I particular liked how they called out areas where they were not doing well and indicated what they will focus on going forward. Fingers crossed their actions from this drive the business forward.
2 things in particular that I found interesting in the detail:
1 - previously adjusted costs are now being expensed as normal operating expenditure:
"In H1 FY25 our approach to cost adjustments was reviewed, and as a result we have not made any adjustments in the period for one-off restructuring costs. Costs incurred in the period, including the costs of the Spectrum closure, have been included as BAU costs."
Hopefully this implies elevated operating expenses this year that won't make an appearance next year.
2 - This slide in the invstor presentation.
As probably the only person who thought that the TastyTrade acquisition was a good one (albeit luckily, due to unexpected interest income over the last few years) I thought the 65% growth in open customer positions over the last 12 months has been excellent ($2.3b ---> $3.8b.)
Angle (LON:AGL) Yes, I still hold !
Broker paper today from Trinity Delta gives a good description of the current situation.
https://www.voxmarkets.co.uk/a...
My thoughts on Kooth (LON:KOO) and the New America president is he and RFK especially are looking to cut ppl's reliance on medication for metal health issues so they may well push the kooth approach more.
Who knows tho.
Luceco (LON:LUCE) Does its success in residential EV charging have any read across to Volex (LON:VLX) ?
Just a thought.
I wouldn't think so they're quite different companies supplying different sectors. On the other hand Pod Point group (LON:PODP) , which exist solely for ev chargers have done badly recently
Hi Graham,
Can we have your thoughts on Mortgage Advice Bureau (Holdings) (LON:MAB1) and its wider relationship with the real economy
Sorry its a bit late in the morning
thanks
MAB1 is in the report, Threepeat! Cheers. G
A new Jerusalem
Dividend increases and share buybacks are good news for UK equities according to our analysts - who think those dark Satanic mills could deliver world-beating total returns...
https://www.trustintelligence....
Gulf Keystone Petroleum (LON:GKP)
The AMBER colour given by Mark has surprised me, shocked to be precise.
I feel that the team should evaluate the companies covered (for us the subscribers) based on their balance sheet, FCF generation, future returns to their shareholders and not based on personal likes/dislikes.
You cannot give a GRREN/AMBER on Goldplat (LON:GDP) (stated that you hold) that operate in South Africa and Ghana! and then suggest that Gulf Keystone Petroleum (LON:GKP) operates in a risky region. Goldplat (LON:GDP) share price has done nothing the last 3 years and this is after one of the most bullish gold price period we have experienced in history.
I took my money off the table on Gulf Keystone Petroleum (LON:GKP) and bought Afentra (LON:AET) simply on opportunity cost basis. i do still hold a good amount of shares.
Gulf Keystone Petroleum (LON:GKP) is one of the best UK listed stocks and is GREEN as it can get, with or without a pipeline restart. Perhaps the price will fall back to 130p on no imminent pipeline restart but it trades very cheap on current and future multiples.
All the best
IGG owns Freetrade. Anyone have any opinion on it as a platform?
Do you mean IG group (LON:IGG) ?
If so, l use it. It is ok, cheap dealing on UK shares £3, but the support service is rubbish but is improving. Do have some issues trading, especially small caps, often no prices available. Even Relx (LON:REL) the other day, l could not sell. On profit warnings shares are often suspended at market opening, so unable to sell.
They are good for US shares, only 0.5% forex, no transaction fees (as long as 3 trades, on any shares, in prior month).
But poor for Europe, even French shares are not available. Fees quite high also.
No stop losses.
Hi I notice Record has a trading update tomorrow, any views/news?
Mark mentions Gulf Keystone Petroleum (LON:GKP) is on an EV/FCF of just 3.6 & is cheap. I'd recommend Valeura Energy (TSE:VLE) on a forecast EV/FCF of @ 1. Now that's cheap imo.
Watches of Switzerland (LON:WOSG)
Revenues and EBIT will have a big boost if the £/$ exchange rate stays at these levels.
All the best
Associated British Foods (LON:ABF)
One of my 2025 stocks, not a promising update.
The question is, does this count as a profit warning? Better to sell and cut losses?
As they always say, maybe it is not a good idea to attempt to catch falling knives. But the stock rank was 95 when I invested...
What does everyone think?
Primark with low single digit growth increases my opinion that it will struggle to compete with competitors like Shien. Which now do cheap 'ethically questionable' clothing like Primark but delivered.
Good point. I am not so familiar with Shein, will take a look at it.
What I like about Primark is
1. cheap clothes (and for example these days with cost of living increases etc I thought this would have appeal)
and 2. the in store aspect. I do not believe that Shein have stores. For those who like shopping days out, Primark has a presence in most shopping centres throughout the UK (although I am aware that does not automatically mean the share price should perform well).
I am considering cutting my losses on this one. But I can't help but also think based on the chart as my low entry point compared to the share price of the previous year, it could surely rally up at some stage...hmmm.
I guess there are those who like a shopping day out. But there are the opposite as well, how many of Primark's customers who like cheap clothing would prefer it to be online? Which they don't offer and Shien do
PI's sentiment towards the high street is very poor at the mo. Card Factory (LON:CARD) , B&M European Value Retail SA (LON:BME) , Shoe Zone (LON:SHOE) - all SP's are languishing.
Gosh JD Sports Fashion (LON:JD.) too - down 3.3% as we speak. Very cheap but cheap can get cheaper. Couldn't resist though!
Numerous reports in the press today about a report from the British Retail Consortium.
Consumer expectations for the economy have declined from -27 in December to -34 in January.
Helen Dickinson, British Retail Consortium
“With retailers’ tight margins leaving little scope to absorb more costs, many are warning of price rises and job cuts in the coming months.
Having said that these 3 shares are a bit different I would rate CARD as a reasonable prospect. I think that B&M is being squeezed and I don't really rate Shoezone.
Most of my perceptions are from a customer perspective.
Its trading at a support level last found at the end of 2023, with some relatively high volume selling at each downturn. Personally I'd put a stop loss in around 1800 to give it a little room to bounce but to cut my losses if needed.
Associated British Foods (LON:ABF) Considering some of the price drops we have seen of late, the drop in SP today is less than2% I'll stay in - but of course would have been better to sell months ago!
Too many moving parts at Associated British Foods (LON:ABF), as the TU confirms.
Retail
3,362
-0.4%
+1.9%
Grocery
1,389
-1.8%
+0.8%
Ingredients
687
-1.6%
+3.5%
Sugar
751
-6.0%
-2.1%
One day, this ungainly conglomerate will be split up, but don't hold your breath.
Inchcape (LON:INCH) down 10% on no news - scoured the web for any information but nothing found
JPM have cut from overweight to neutral today
CMC Markets (LON:CMCX)
Updates like the one we had today (basically saying nothing) is worrying.
All the best
Hi Yiannos,
As an alternative view, Games Workshop (LON:GAW) have made numerous curt updates like this and it's worked out quite well (admittedly a sample size of 1!)
Random guess, but there's a possibility that Peter Cruddas (51% owner) is thoroughly pis@ed off with the current valuation in the UK market (he's moaned about this previously) and may well have thrown a bit of a strop with this statement. Backfired spectacularly if that is the case. I hope so as I've just bought back in at 234. They did 12.8p EPS in H1, and have c£200m in cash so 300 looks more reasonable to me
CMC Markets (LON:CMCX)
Random guess, but there's a possibility that Peter Cruddas (51% owner) is thoroughly pisConsolidated Edison (NYQ:ED) off with the current valuation in the UK market (he's moaned about this previously) and may well have thrown a bit of a strop with this statement.
If you want to get company valued at max and are doing well you provide more inforamtion not less - he may be hissed off but if he choses to provide minimilistic info when company is doing well he is shooting himself in the foot if he wants shareprice to be higher - and he will known that is the case (i presume)
best bet whe stuff like this happens is email company express what youithink they could have done better.
one issue they do have is high variability in what they do - so holders needs to understand know the future is not as easy to predict as it is for some other companies. i sold out a while back but i am slightly surprised at price dip bearing in mind they are still churning out decent numbers. I sold simply more for caution than anything else - i think this is one of those shares its quite tricky ref timing as we dont what is around the corner
CMC Markets (LON:CMCX)
If you want to get company valued at max and are doing well you provide more inforamtion not less - he may be hissed off but if he choses to provide minimilistic info when company is doing well he is shooting himself in the foot if he wants shareprice to be higher - and he will known that is the case (i presume)
That's a very investor-led viewpoint. I don't think Peter Cruddas cares a fig about maximising the share price, he's just getting on with running the business. He doesn't need to raise new capital and with over 50% of the company he doesn't have to care about what anyone else thinks. He's obviously not interested in selling any time soon.
Of course if he was ego driven that might be a concern. However, as far as I can see, just he's focused on improving the company, investing in the future and driving costs down like any good owner manager. It's just a very volatile business, albeit they're trying to find ways of reducing that volatility.
Quite why the market has thrown its toys out of its pram today is a mystery, given they've simply reiterated what they said in the interims. Everyone wants an upgrade, I guess. Investors, eh?
Anyway he's 72 now, so one day the business will be sold. In the meantime I'm happy to tag along.
timarr
CMC Markets (LON:CMCX) Wise words indeed Tim! I'm with you on this one. SP is very volatile and whilst more detail would have been welcome does this not just show the fragile minds of a lot of investors at the moment? I'm not saying I blame them but the past few years have been very trying for even the strongest of constitutions! I'm staying glass half full on this one.....
Hi N'n'G
Meanwhile Ashtead Technology Holdings (LON:AT.) announces vaguely that "full year adjusted EBITA expected to be ahead of consensus" and the share price goes up 12%.
I ignore daily movements and work out my own expectations. Sometimes you have to take the long view. Although in some cases I'm wondering whether value will out before I die ...
timarr
I think there is a lot to be said for Ed’s NAPS strategy Tim. The annual rebalancing gets rid of those stocks which you are certain are undervalued but never reach their potential.
I think there is a lot to be said for Ed’s NAPS strategy Tim. The annual rebalancing gets rid of those stocks which you are certain are undervalued but never reach their potential.
Hi john2
That's true if capital gain / protection is your main aim. As I approach retirement persistance of income is a critical consideration, especially as I don't wish to be forced into selling shares for income at inconvenient times.
Income is less volatile than share prices so you can see significant variation in capital values over a portfolio while income streams are stable.
In terms of capital appreciation I think NAPS has shown its worth. Mentally there's a huge step to move from an active approach to a passive one, but it's now hard to argue with Ed's numbers which have been tested over a range of market conditions, and while the UK markets have been in the doldrums.
timarr
I have been retired for 15 years. My investments are currently approx one third in safe shares with a high dividend e.g. Legal & General (LON:LGEN) and Aviva (LON:AV.) , one third in NAPS and one third in American tech. Don’t forget that many of the NAPS stocks pay a dividend.
I have been retired for 15 years. My investments are currently approx one third in safe shares with a high dividend e.g. Legal & General (LON:LGEN) and Aviva (LON:AV.) , one third in NAPS and one third in American tech. Don’t forget that many of the NAPS stocks pay a dividend.
Interesting.
I certainly don't include Legal & General (LON:LGEN)'s dividend in the safe shares bucket. Aviva (LON:AV.) looks good value, especially if the Direct Line Insurance (LON:DLG) deal goes through.
American technology shares come in all sizes and shapes, but there's clearly a bubble in kit form in some parts of the market. I hold a fair range of these, but it's like picking my way through a minefield. I am uncomfortably reminded of 1998-1999. I also remind myself that I sat on the sidelines then because I knew many of the companies being pumped to the skies from the inside while friends made fortunes (they all lost them, too, but that's another story). While the music plays ...
NAPS - yes but dividends are incidental to the approach, not central. However, it's under consideration.
timarr
I well remember the dot com crash. I wish I had gone into the US earlier, but it’s still where the big gains can be made. Yiannos has been very helpful. As for L&G, it gives a better return than bank account interest.
LGEN And av.
i think timarrs' point is that these insurance type companies can be complicated blck box type investments where there can be many unknown unknowns at play and if they ever get it wrong ref their risk taking then .......
so what you may view as a safe dependable plodder - other may view as being akin to a ship like the titanic setting sail on its maiden voyage - i am sure everyone on board the titanic would have been highly confident they may have been on one of the safest ships on the seas.
I have shares in l&g and have invested in Aviva in the last - and i have alwasy viewed them as punt type investments due to the fact i dont have clue whats beneath the bonnet and how safe it is. pe look cheap and propsects look cheap but the reality is i know i know didly squat aref eberything that matters ref valuing this company.
would like to think we have learned our lessons over time and these may be fairly low risk nowadays - i suspect though at some stage sometime then theer will be another wave of finacials getting hammered due to some random future event.
l&g seem to mostly have positive outlook but looking at net prfoit at 2022 and 2023 the profits are waay lower than i would have expected - if they should be delivering £1.5 billion per year profits - why is the final result so poor for these years ?
I though l&g looked better long temr prospect than Aviva so soel Aviva and kept l&g - that decision doesnt look great sigh
I also hold a few of the life insurers as you say no real idea how to value them, remember when dear old Liz nearly brought them down through their ldi debacles, well I met one of the best strategic bond managers in the sector who works for one of the big insurance houses and even he completely missed ldi as a possible issue so you kind of think if best in class who work for these firms miss these things we have no chance.
One problem that Legal & General (LON:LGEN) had was that they invested a substantial amount of money in a factory which built pre-assembled houses. The idea was that the plumbing pipes and electrical cables would be installed in the factory and it would be a simple job to assemble the house on site. This lost them a lot of money because the demand was not there, whether because people wanted bespoke houses or because mortgages were not available.
Strewth - how much of my money did they lose on that hair brained scheme ? - sounds like some sucker sold em that good and proper.
Nice rise for Gulf Marine Services (LON:GMS) today on no news
Very nice indeed Brad! maybe an overhang was cleared in yesterday's big volume? or maybe it's a read across from Ashtead Technology Holdings (LON:AT.) or Hunting (LON:HTG) or any business in oil an gas services who all seem to be thriving...
Either way very welcomed and now hoping it rubs off on James Fisher And Sons (LON:FSJ) as well!
Would be interested to hear your views on Fonix (LON:FNX) following their trading update.
They announced a special dividend of 3p per share and a “higher than expectation” H2 even though H1 was broadly in line with expectations. There is a pipeline for securing more contracts which I understand are very sticky and seeing positive results since entering the Portuguese market.
Not cheap but a quality outfit
This is a buy and hold for me Fonix (LON:FNX) as they continue to deliver and most of it ends up as cash dividends. The exciting comments about exploring several other European countries is also exciting.
The bear case is that the technology gets superseded or something or someone looks for another way to do it cheaper and eat into their margins.
Fonix (LON:FNX) A very lean business with only around 70 employees.
Fonix (LON:FNX) has 49 employees. A capital light business so easy to make money. Also management have a history of beating expectations which is no accident.
Share price performance been held back:
1. by a strong H1 24 comparator as H124 got a boost from the sad death of the Queen , however reported H1 25 adj. EBITDA up over 6%. Means H126 comparator will be kinder.
2. Overdone concerns regarding Irish gambling rules which are very unlikely to affect Fonix
3. Pre-AGM statement the plan was to "launch in Portugal for the lucrative Xmas period." AGM statement in November said "ready for launch in early 2025."
If Portugal had launched pre Xmas as planned, there would have been a beat. I think it is likely that these transitory/ temporary setbacks are now behind Fonix and the future looks appealing.
I hold
Gulf Keystone Petroleum (LON:GKP) gave an operational update this morning - didn't come through in my feed for some reason.
Local sales have remained strong since our previous market update in December 2024, with 2025 year to date gross average production of c.47,900 bopd. If current demand persists in the local market, our disciplined and flexible work programme, combined with our stable low costs, should enable us to deliver gross average production in the range of 40,000 to 45,000 bopd in 2025 and generate material free cash flow, underpinning our ongoing commitment to return excess cash to shareholders. At the same time, we continue to proactively engage with government stakeholders to unlock an exports restart solution.”
Good results which show excellent local production & sales generating FCF leading to both decent dividends and a share buyback programme. So even without the pipeline restarting they are able to provide good returns. A decent operator.
I hold and thanks to Yiannos for highlighting this again - I had been a previous holder sometime back but had sold out after the pipeline closed.
Hi Kevin,
For transparency, I have recently took my money off the table on Gulf Keystone Petroleum (LON:GKP) and only hold the profit made in them. The reason is that I have lost my patience on the Iraqi’s government and the tactics on NOT restarting the pipeline. Still the FCF from local sales (not really local just sold to Iran and then from there to……) are about $8.5m per month. This figure allows Gulf Keystone Petroleum (LON:GKP) to return about 25p-30p to its shareholders per annum.
Afentra (LON:AET) is where the money from the sale were deployed. Same story with a forward EV/FCF of 2.5! Too cheap to ignore with an experienced management that have previously done well in the same region. Further acquisitions on the horizon.
All the best
Thanks Yiannos - much appreciated.
Another interesting O&G play - I have finally lost patience with Serica Energy (LON:SQZ) and the UK Govt's strategy for wrecking our O&G industry (still hold a small amount but bailed a lot of the holding). Will do some more research on Afentra (LON:AET) and a few other options to see if there is anything worth looking at.
I like to have a small % in O&G as part of a balanced PF but nothing too significant as it can be volatile.
I lost patience with the UK O&G sector 18 months ago and invested the lot in various Vaca Muerta plays - $YPG, $PAM, $VIST.
I think Canadian O&G is a no brainer as well despite Trump's tariff threats. I like TSX: ARC, TSX:TOU and TSX: PEY.
There is always jurisdictional risk with energy and commodities. Try prospecting for U in Northern BC, or O&G in the North Sea, or U and Au in West Africa. Mali have arrested mining executives in Mali, the junta in Burkina Faso is threatening to strip permits from existing operators and the nutters in Niger have seized French U assets
Give me Javier Milei or the likely new conservative government in Canada now Trudeau has departed than Reeves or some dodgy West African "country". The jurisdictional risk in Argentina is less than the UK in my view. The undoubted jurisdictional risk with Gulf Keystone Petroleum (LON:GKP) is arguably in the price, but a bit too risky for me, but probably less of a jurisdicitonal risk than say Serica Energy (LON:SQZ) (and I am not risk averse).
Oddly KevinS1 I disagree on Serica Energy (LON:SQZ) - I’m actually more inclined to buy them at these levels than I was previously. Their $60 hedges have rolled off and now the only hedges they have left on are at around $92 so making a lot on oil. For gas prices up at 125p therm and not looking likely to recede given current policy they will be throwing off cash but at the same time have loads of losses available to be utilised. Apparently they are in active discussions with the government about current policy so it will only take a small tweak to have a material impact.
Anyway can’t argue with Afentra (LON:AET) or Gulf Keystone Petroleum (LON:GKP) either to be honest which both generate prodigious cashflows. Personally I hold neither but do have Petrotal (LON:PTAL) which also generates me c. 15% dividend/buy back returns. I don’t really buy the high/low country risk arguments - In the O&G space I think they are more or less equal. You only have to look at the UK governments approach - would you rather invest in the North Sea or Kurdistan? I’d say Kurdistan is marginally lower risk given how important Oil is to them and how cheap it is to extract versus a government that is prone to taxing industries out of sight.
KevinS1
fwiw I’m very happy continuing to hold prodigious dividend payer Serica Energy (LON:SQZ) including for reasons covered here today.
I took the profit on Harbour Energy (LON:HBR) which I’ve held for about 3 years after their trading update today which saw a 15p share price fall. Tucked away in an otherwise bullish update was this short section which might mean dividend cut ahead:-
”Anticipated to be broadly free cash flow neutral in 2024, excluding one-off acquisition related costs and distributions. This reflects a material negative working capital movement and an unplanned outage at East Irish Sea in the UK in Q4”
I also hold Ithaca Energy (LON:ITH) and averaged down ahead of the recent ex dividend date at 116p. The share rose to 140p recently but fell again today. Buying the dips for the likes of Ithaca Energy (LON:ITH) , Serica Energy (LON:SQZ) and Gulf Keystone Petroleum (LON:GKP) coukd work very well.
As for Gulf Keystone Petroleum (LON:GKP) despite agreeing with yiannos that it might be ages before the pipeline reopens, GKP is managing very well despite that. So a surprise opening of the pipeline would probably see a big share price gain. And without that happening just look at the dividend history including in 2024.
2021. 33p which gave 14% yield.
2022. 80p! 30.5% yield.
2023. Just 9.6p reflecting the pipeline closure. 7% yield.
2024. 12.45p and 8.4% yield, despite the pipeline still being closed.
Finally and in case anyone hasn’t seen it, this superb article by Ed Croft on trading updates/profits warnings/better than expected updates is a must read:-
https://www.stockopedia.com/co...
Mortgage Advice Bureau (Holdings) (LON:MAB1) provided a YE TU today - sounds positive.
Group revenue for year ended 31 December 2024 increased by 11% to c.£266m (2023: £239.5m), which is significantly higher than the estimated 4% growth (1) in UK gross lending for the same period.
Adjusted PBT for the year of c. 31% to c. £30.5m (2023: £23.2m) 4% ahead of consensus
MAB's number of mainstream advisers grew modestly in the second half, increasing to 1,941 at the year-end (2023: 1918). However, lower than expected growth in adviser numbers was more than offset by a significant rise in productivity.
Current trading and outlook
Clear signs of pent-up demand were evidenced by the increase in mortgage applications in Q4 2024 (+15% compared to Q4 2023) and we expect this positive momentum to be maintained. UK Finance forecasts (1) gross new lending to rise 11% in 2025 in £235bn, which we believe is a realistic estimate.
I am a holder, and bought on the expectation of a turnaround. These numbers are pleasing, but I do find the volatility on a lot of days unsettling, but hopefully we can now see the improvement in numbers and the forecasted growth over the next three years also looks positive. Just need to hope that the mortgage market starts to grow if the predicted housing recovery/build programme starts to kick-off.
Good morning Graham, I am reluctant to add to an already heavy workload but if you find a few minutes to glance at Watkin Jones results and make a short comment I'd appreciate it. Institutions reneging on agreements during the pandemic, then building remediation linked to cladding changed a good investment into a bad one. My mistake again to hang on and buy more but is another dog in our portfolio reviving?
Net cash of 83 million, not losing money and a market cap of 50 million (at last close).
Not expecting it to get back to ATH any time soon but I just don't get why it is so lowly rated now
This peaked my interest ... im not an expert but I suspect the £83m flatters them somewhat .... not least since £48m Building safety provision needs to run off.... and cash position is approx half at the half year reflecting seasonal cashflow. finally passing the dividend also improved the annual position by £15m. No view on the stock but I doubt it's a negative EV as suggested.
This was just a very quick glance on the table and agree with your points. Thanks for highlighting them.
Looked a bit deeper, the 8 million costs of remedial works was covered by cash generation this year. This years predicted remedial costs are predicted as 2 million higher (circa 10 million), it is not an unachievable target for this to also be covered by cash generation this year. Its an 'if', but if they manage to maintain covering the costs of remedials while posting a small profit the cash position look strong. This is also before you include any other assets. With a recovering market (as suggested by them today and read across form the Mortgage Advice Bureau (Holdings) (LON:MAB1) update) this doesn't seem unreasonable.
But yes, no expert, I also hope graham or his team covers this for some better insight.
Watkin Jones
(LON:WJG) There are future provisions not included and I have my doubts that this will survive.
I hope it does.
all the best
Had a look at this for you, JASVFS! Cheers.
Good morning Graham, I’m a little surprised not to see interims from IG group (LON:IGG) in today’s table as I thought you were a fellow holder. It would be interesting to get your take on the numbers and commentary.
I’m a little surprised not to see interims from IG group (LON:IGG) in today’s table as I thought you were a fellow holder.
Damn that AI.
Just going through them, they look all right - better than alright, to be fair. Net trading revenue up 12% and a slight reduction in costs. Adjusted eps up 42%. All volatile as hell, of course.
Dividend only up a measly 2%, which seems a bit stingy. Buyback continues, they've now repurchased 18% of the shares since the tastytrade blowout. On the other hand the most recent batch haven't been cancelled, but are being held in Treasury, so that's something to keep an eye on ...
Will be interested in Graham's take, too.
timarr
I sold my IG group (LON:IGG) badly - looks like it is finding its feet again to me. Institutions like Breon and outlook in a volatile world must be quite good. I think on 10x you don't have to make it too complicated which is good because I can never make head or tail of their trading statements. Current trading satisfactory and confident of meeting forecasts sounds a bit hmmm so Im going to say it is them being conservative.
Tim could you elaborate on "held in treasury something to keep an eye on" I'm presuming that shares held in treasury is usually done so that they can reissue them again in the future if needed at lower cost than say organizing a rights issue ?
Or is it some other possible future sleight of hand your highlighting here ?
Thanks
Andy
Not a fan of share buybacks, but if they at least cancel them, your EPS has grown. If they hold them in treasury, what have I as a shareholder gained? Suspect the worry is, the directors can then award them to themselves later on. Didn't Renold (LON:RNO) play this sleight of hand last year?
Hi Bob,
Shares held in treasury do enhance EPS as well as they are used in future non dilutive ways; for acquisition purposes and for directors and employees bonuses.
All the best
Thanks Yiannos should have read on a bit further stand down Bob.
Thanks Bob so if they hold them in treasury eps doesn't grow, but if they are truly cancelled it does grow eps ?
Hi TP
Shares that are cancelled are gone for good. Shares that are held in Treasury aren't active, and don't count for eps, but can be reissued at the discretion of the board. This is often used to reward directors and to boost option schemes. However, they can also be used as currency for acquistions.
So far there's nothing amiss at IG group (LON:IGG) - a few shares have been re-issued to fulfil existing option schemes - but the sudden and unexplained switch from cancelling to holding fuels the worry that either the board are going to find a way of rewarding themselves or are thinking about another large share-based acquistion.
They're using shareholders' money to repurchase the shares, instead of returning the cash to shareholders as dividends, so if they're not cancelling them we have to ask why.
timarr
Thanks as always Tim
That was rectified, Brilliant Leader! Yes, I'm a holder and I expect to cover it today. G
Spectris (LON:SXS) also ahead...shares also been weak.. I don't hold. Not sure on this one, a long term buy but relies on a decent economy. Currency may well have helped ( $ strength).
Zotefoams (LON:ZTF) (I hold) "ahead of current mkt expectations" will do I think against the backdrop of a weak share price as the ReZorce partner search proved unsuccessful. It remains unclear how much of the £4.7m loss will be excluded from 2025 results. A capital markets day on March 18 should make things clearer. Current 2025 forecasts look conservative to me... but after such a stellar year in footwear maybe there is a pause in growth.
I think it's worth giving them the benefit of the doubt for now as a GARP contender.
CMC Markets (LON:CMCX)
Trading update - The Group remains on track to achieve annual net operating income in line with previous guidance.
Management also remains confident in meeting its cost guidance of approximately £225 million, excluding variable remuneration and non-recurring charges.
Anyone else a bit worried by how brief this is? Does anyone have access to any broker notes?
Worrying update! Very strangely worded too. 'Net operating income' and costs 'excluding variable remuneration and non-recurring charges' - leaves open a lot of accounting jiggery pokery
CMC Markets (LON:CMCX)
'Net operating income' and costs 'excluding variable remuneration and non-recurring charges' - leaves open a lot of accounting jiggery pokery
It's an exact repeat of what was stated in the interims:
Operating cost guidance for FY 2025 remains unchanged at £225 million, excluding variable
remuneration and non-recurring charges.
Or - nothing has changed since then (or most of the previous trading and result statements I can remember).
Given Peter Cruddas owns over 50% of the company it's very unlikely there'll be any mystery in the results. CMC's earnings are highly volatile, although recent investments ought to serve to reduce that a bit. The company tends to plough on doing what it does regardless of market conditions, shareholders are simply along for the ride.
One day Cruddas will sell up, wouldn't want to miss that.
timarr
CMC Markets (LON:CMCX) Shows total disdain for shareholders. No broker notes either. Market forecasts looked low so was hoping for a beat. Sold first thing - amazed I got out with share price marginally up. Would expect it to fall back today, but we'll see.
Bouden54, I did the exact same, somehow was allowed to sell at the open for 269p. Glad I did!!
CMC Markets (LON:CMCX)
I don’t hold but in the absence of any specific bad news I wouldn’t have been worrying personally , that’s not to say they couldn’t have added slightly more to reassure shareholder. This company has been fairly consistent in not hiding bad news as far as can recollect.