Daily Stock Market Report (Thur 23rd July 2026) - SRB, TMG, MAB1, WRKS, HVO

Red Sea: the price of oil continues to climb as the Houthis in Yemen say they attacked oil tankers in the Red Sea. The Red Sea provides a crucial alternative to the Strait of Hormuz for the export of Saudi oil.
This attack comes as US bombing of Iran has continued for a 12th successive night.
The US Secretary of State says that the US is “open” to negotiations. But unfortunately there is no positive progress to report at this stage.
Alphabet: the owner of Google has made headlines for announcing increases to its planned capex this year to c. $200 billion, up from $190 billion.
This level of spending is totally unprecedented and highlights the AI arms race that is happening in Big Tech. Amazon, Alphabet, Microsoft and Meta are collectively planning to spend well over $700 billion this year alone on capex, as they each strive to achieve dominance in AI-related capabilities.
For context, total capex spending by these four companies in 2025 was just $380 billion.The prior year, it was $230 billion.
The obvious danger is that if this enormous spending fails to generate the expected returns, it will have to force a rapid change in the market’s assessment of what these companies are worth.
Overnight market movements:
The FTSE is down 0.2% at 10,700
S&P 500 is down 0.1% at 7,490
Brent crude (October) is up 1.5% at $91.50/bbl
Gold is unchanged at $4,125/oz
Bitcoin is down 0.3% at $65,700
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£217bn | SR67) | AstraZeneca's Etcamah (camizestrant) has been approved in the EU for the treatment of adults with breast cancer. | ||
Relx (LON:REL) (£43bn | SR44) | H1 underlying revenue growth 7%. Underlying adjusted operating profit growth 9%. “We continue to see positive momentum across the group, and we expect another year of strong underlying growth in revenue and adjusted operating profit, as well as strong growth in adjusted earnings per share on a constant currency basis.” | ||
Anglo American (LON:AAL) (£41.6bn | SR65) | “We have delivered another strong quarter across both Copper and Premium Iron Ore, with performance tracking well to plan… Our merger with Teck is on track to form a copper-focused global metals and minerals champion, with the expected completion window of September 2026 to March 2027 unchanged.” | ||
3i (LON:III) (£25.8bn | SR52) | Total return of 3% for the three months to 30 June 2026, after a negative foreign exchange translation impact of £276 million, or 27 pence. NAV per share increases to 3,131p. | ||
BT (LON:BT.A) (£19.5bn | SR79) | Revenue £4.3bn, flat year-on-year. Adjusted EBTIDA £2bn, down 1% year-on-year. Reported PBT £505m, down 4%. “We remain on track to deliver our targets, including cash flow of c £2.0bn this year and c £3.0bn by the end of the decade.” | ||
Airtel Africa (LON:AAF) (£12.7bn | SR84) | Total customer base up 11.6%. 56.3% increase in data traffic across the network. Revenue up 31% (constant currency growth 21.1% plus currency appreciation). Profit after tax $198m ($156m in the prior period). | ||
| SEGRO (LON:SGRO) (£12.1bn | SR78) | Statement re Possible Offer and Extension of PUSU | Fourth Proposal: 0.0920 new Prologis shares for each SEGRO share. Partial cash alternative. Based on Prologis's closing share price of $149.94 and a GBP:USD exchange rate of 1.3371, it values each SEGRO share at 1,031.7p. Including dividend, value is 1,054.3 pence. The Board of SEGRO has unanimously concluded that the financial terms of the Fourth Proposal are at a level that it would be minded to recommend to SEGRO shareholders. | TAKEOVER |
Centrica (LON:CNA) (£8.31bn | SR52) | EBITDA falls from £900m to £737m. Adjusted operating profit falls from £549m to £497m. Outlook: Retail to be towards the lower end of £500m-£800m adjusted EBITDA guidance range. Earnings weighted to H1. | ||
easyJet (LON:EZJ) (£4.44bn | SR51) | FY26 ASK capacity expected to grow c.6% YoY with seats expected to grow c.3% YoY. Load factor is 2ppts below the prior year, improving from 3ppts below at the time of the HY results in May. Strong late bookings continue… albeit still needing some price stimulation. | TAKEOVER | |
Howden Joinery (LON:HWDN) (£4.25bn | SR85) | Sales +3.3%. Underlying PBT +4.3%. “Trading to date has been in line with our expectations. We are well prepared for Autumn peak trading and our full-year outlook is unchanged.” | ||
AJ Bell (LON:AJB) (£2.43bn | SR87) | Assets under administration up 12% in the quarter, 26% over the last year. Investment business AUM up 16% in the quarter, 41% over the last year. Net inflows £0.8 billion. | ||
Morgan Sindall (LON:MGNS) (£2.39bn | SR77) | Revenue +8%. Adjusted operating profit +21%. “Despite the challenging housing backdrop, the strength and breadth of our diverse operations, together with the visibility provided by our high-quality order book for the remainder of the year, we remain confident that our full year performance will be in line with our current expectations.” | ||
Mitchells & Butlers (LON:MAB) (£1.65bn | SR84) | Year-to-date like-for-like sales +2.2%. “Cost inflation expectations remain unchanged at c.£120m this financial year, reflecting the challenge facing the whole sector. However, the actions taken across the business, together with the benefits of our Ignite programme and investment strategy, provide confidence in our ability to deliver a full-year outturn for the current year in line with consensus expectations.” | ||
Great Portland Estates (LON:GPE) (£1.4bn | SR34) | Completed four new leases at 16 Dufour's Place, W1, one of its prime West End Fully Managed buildings. | ||
Volution (LON:FAN) (£1.26bn | SR47) | Adjusted EPS expected to be above the current range of market forecasts; driven by broad-based margin expansion, resilient organic growth and earnings accretive acquisitions. Total revenue growth c. 15%. Organic growth c. 3% at constant currencies. | ||
Serica Energy (LON:SQZ) (£976m | SR91) | New six-year, senior secured Reserves Based Lending facilities totalling $750 million, comprising a $500 million secured revolving loan facility and a $250 million secured revolving letter of credit facility. | ||
CVS (LON:CVSG) (£895m | SR51) | FY26 Adjusted EBITDA in line with market consensus. Revenue growth 5.9%. Like-for-like sales +2.1%. | ||
Jupiter Fund Management (LON:JUP) (£849m | SR91) | £0.7bn net new business. After CCLA acquisition, 36% increase in AUM to £73.7bn. Underlying PBT up 67% to £50.7m. Statutory PBT up 29% to £35.4m. | ||
Auction Technology (LON:ATG) (£523m | SR53) | Pro forma constant currency revenue growth 7.8%, with pro forma growth (actual rates) of 7.7%. Slight upgrade to revenue growth guidance to 5.5%-6.5% on a pro forma constant currency basis. Adjusted EBITDA margin range unchanged (“We continue to expect the outcome to be at the bottom end of this range.”) | ||
Mortgage Advice Bureau (Holdings) (LON:MAB1) (£312m | SR56) | H1 revenue +8%. Adjusted PBT c. £14.6m, in line with H1 last year. Reduction in margin “principally driven by a significant shift in mortgage mix, slower growth in protection policy volumes and the timing of benefits from integrating subsidiaries acquired in late 2025.” The Board expects full-year results to be in line with expectations. | AMBER/GREEN ↓ (Graham) I calculate that they need H2 adj. PBT growth of about 33% (from £22m to £29m) in order to hit full-year expectations. I’ve been very positive on MAB1 but I will moderate my stance slightly today, to AMBER/GREEN, as I now perceive that there is a heightened risk of an earnings miss. That’s just a short-term call, however - I’m still a big fan of the business long-term, and I’ll happily go back to GREEN as soon as I'm more confident in the 2026 result. I don’t think it’s excessively valued at all, considering that it’s a high-quality franchised business model. | |
Judges Scientific (LON:JDG) (£308m | SR48) | Order intake -11% (Q2 broadly in line with prior year). Revenue -21% to £70.2m. The lower volumes during the period were only partially offset by the management actions taken to reduce costs and consequently adjusted earnings per share in the first half is expected to be in the range of 38p-42p. The Board anticipates delivering Adjusted earnings per share in line with current market expectations (202.8p). Geotek coring expedition now scheduled no earlier than 2028 (previously expected to be 2026H2 into 2027). | ||
Caledonia Investments (LON:CLDN) (£269m | SR56) | Results demonstrate the presence of significant near surface gold mineralisation in a previously unknown mineralized horizon. Include 23m at 2.61g/t from the surface. | ||
City of London Investment (LON:CLIG) (£246m | SR96) | FuM +13.9% to $12.3bn, Outflows $1.3bn ($483m in H2). Investment performance +$2.8bn.Expects the final dividend to be in line with the previous year. | ||
SRT Marine Systems (LON:SRT) (£223m | SR29) | Revenue +49% to £116m, Adj. PBT +105% to £10.0m. New financial year: we are confident of existing market expectations. | ||
Serabi Gold (LON:SRB) (£211m | SR95) | Q2 gold production of 11,007 ounces, +5% on Q2-2025. Net Cash $65.7 million vs $64.4m Q1. Based on the assumption that the Coringa full mining license will be awarded by Q4-2026, the Company remains on track to deliver FY2026 consolidated production in excess of a record 53,000 ounces gold. | AMBER/GREEN (Mark - I hold) | |
Eco (Atlantic) Oil & Gas (LON:ECO) (£206m | SR31) | Operating Loss $7.0m (FY25: $2.3m loss), Net Cash $10.7m following $10m raise in the period. | ||
VP (LON:VP.). (£188m | SR41) | “Trading during the first quarter has been resilient…continues to expect performance for the year to be in line with market expectations.” | ||
Videndum (LON:VID) (£163m | SR19) | Jan Peter Tewes joins Videndum from Villeroy and Boch as CEO. H1 Revenue to be in line with the prior year on a like-for-like basis, and adjusted EBITDA to be modestly ahead of the same period in 2025. Net debt was £39m (including finance leases of £24m). | ||
Fonix (LON:FNX) (£159m | SR63) | Total payment volume +8.0% to £303.3m. FY26 Adjusted EBITDA slightly ahead of market expectations at +11% to £16.2m. "Fonix enters FY27 with positive momentum across its core UK and Ireland markets." | ||
Mercia Asset Management (LON:MERC) (£111m | SR38) | Entered into a three-year facilities agreement with Metro Bank for a term loan facility of £13.0million and a £25.0million revolving loan facility, at SONIA +3.99% and +3.5%, respectively. | ||
Somero Enterprises (LON:SOM) (£108m | SR91) | Buyback extended from US$6.0m to US$12.0m. | ||
Motorpoint (LON:MOTR) (£102m | SR47) | Q1 retail volumes +11.1%. Profitability has improved strongly year on year, supported by continued excellent metal margins and cost discipline. | ||
Eleco (LON:ELCO) (£97m | SR44) | ARR +16% to £35.5m, Net Cash £15.4m (31 Dec: £16.3m). Remains confident in delivering full year 2026 results in line with market expectations. | ||
Spectra Systems (LON:SPSY) (£89.6m | SR99) | Following the successful completion of a pilot programme, Swiss Post has confirmed that it will transition its stamp programme to hybrid stamps with data-matrix codes. Expected to result in an approximate 40% increase in revenue ($1.6m) over the 5-year contract period, which commenced in 2024 and which has an additional one-year option. | ||
Record (LON:REC) (£86.4m | SR78) | Q1 AUM +6% to $122bn. Net flows $2.3bn, Asset Movement $5.4bn. “Performance across the Group continues to support expectations for the current financial year.” | ||
Victoria (LON:VCP) (£72.8m | SR50) | Confirmation that holders of over 90% of 2028 SSNs support the transaction, reducing the cost of implementation which will now be done via consent solicitation. | ||
Creo Medical (LON:CREO) (£62.3m | SR21) | More than 100 clinical cases have now been completed using its MicroBlate™ Flex microwave ablation product. | ||
Software Circle (LON:SFT) (£61.4m | SR17) | Revenue +225 to £22.3m, Adj. EBITDA +81% to £5.8m, (organic +23%), Statutory Op Profit flat. Net debt £11.4m (FY25:£2.2m). Current year trading is in line with internal expectations and the acquisition pipeline remains healthy. | ||
Works co uk (LON:WRKS) (£49.4m | SR98) | Revenue +3.1% to £260m, Pre-IFRS16 Adj. EBITDA +47% to £14.0m, Adj. PBT +44% to £7.2m, Statutory excl. discontinued operations PBT -28% to £6.8m. Positive momentum has continued into the new financial year, generating +8.8% LFL sales growth during the first 11 weeks of FY27 to 19 July 2026. Maintaining its recently upgraded FY27 guidance for pre-IFRS 16Adjusted EBITDA of £15.0m. | AMBER/GREEN = (Mark) | |
Naked Wines (LON:WINE) (£47.7m | SR88) | Adjusted EBITDA of £7.6m, slightly ahead of guidance (£5.5 - £7.5m) Net cash excluding lease liabilities of £33.4m up £3.3m on prior year (FY25: £30.1m). Statutory loss before tax of £6.3m (FY25: loss of £4.9m). FY27 Guidance: Revenue: £158m to £175m. Adjusted EBITDA: £7.6m to £9.0m. Net cash: £34m to £42m | ||
hVIVO (LON:HVO) (£46.5m | SR38) | H1 revenue -33% to £16.3m. Adjusted EBITDA for H1 2026 is expected to be negative mid-single digit. H2 positive EBITDA. Expects 2026 full-year revenue to be broadly in line with expectations of high single-digit revenue growth. Orderbook increasing significantly to £65 million, compared with £30 million at the start of 2026. | BLACK(Revenue broadly in line, -ve H1 EBITDA) | |
Enwell Energy (LON:ENW) (£40.9m | SR26) | Under Arbitration Tribunal's Procedural Order No 3 of 26 June 2026, the parties are obliged to notify the Tribunal and the other party by way of four days written notice of any new proceedings or any material change in any existing proceedings which might affect the Company's rights in relation to its Group companies or the integrity of the arbitration. | ||
Oriole Resources (LON:ORR) (£17.4m | SR29) | Updated JORC Mineral Resource Estimate for the MB01-S deposit at its 50% owned Mbe orogenic gold project in Cameroon shows 1.66moz contained gold with a mean grade of 1.02g/t. | ||
Inspiration Healthcare (LON:IHC) (£16.6m | SR68) | “Momentum in the core business has continued into FY27 and the Board is encouraged by trading for the first part of the year. Our order book, opportunity pipeline and strengthened operational foundations provide us with confidence in the Group's future prospects.” | ||
Mission (LON:TMG) (£14.3m | SR65) | H1 2026 performance was in line with the Board's expectations. H1 revenue -4.7% to £32.5m, adj. Op Profit +10% to £2.4m, adj. PBT +27% to £1.4m. Net debt £11.0m (£9.0m 31 Dec) .On track to meet full year market expectations. | AMBER/RED = (Mark) | |
Airea (LON:AIEA) (£10.8m | SR83) |
Q2 Sales +10.2% to £10.81m, volumes +7.45%. UK & ROI sales +10.2%, International +9.9%. New manufacturing facility now complete. The third quarter has started well with a strong order book for July. | ||
Richmond Hill Resources (LON:RHR) (£10.3m | SR6) | The drilling permit for the Martello Project has been approved and issued by the Ontario Ministry of Energy and Mines |
Graham's Section
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Unchanged at 540p (£311m) - Trading Update - Graham - AMBER/GREEN ↓
Mortgage Advice Bureau (Holdings) plc (LSE: MAB1), a leading technology-driven UK property finance service, today issues a trading update for the six months ended 30 June 2026, ahead of publishing its interim results on 22 September 2026.
To summarise:
Revenue +8%
H1 adj. PBT c. £14.6m, only slightly higher than H1 last year (£14.5m).
We get an explanation for adj. PBT not growing very fast:
The reduction in margin was principally driven by a significant shift in mortgage mix, slower growth in protection policy volumes and the timing of benefits from integrating subsidiaries acquired in late 2025.
The mortgage mix this year was more heavily weighted towards refinancings (rather than purchase lending). This means lower margins and fewer protection policy sales.
On top of that, “volatility in mortgage pricing also required advisers to devote additional time to secure the best outcome for customers, impacting productivity.”
Outlook: The Board expects full-year results to be in line with expectations.
There have been some big changes in activity levels already this year: mortgage applications were up by 15% year-on-year as of mid-May, but they are down 13% since then. The overall year-to-date figure is +7%. It must be tricky to make forecasts with this sort of volatility in demand.
CEO comment:
Management is taking targeted action to improve adviser productivity and profit conversion, with a particular focus on customer retention, protection performance, the delivery of acquisition synergies and continued cost discipline. These actions, together with the opportunities ahead, mean that I remain confident in the Group's outlook for the full year.
Graham’s view
This is an important point:
The Group is not assuming an improvement in housing transactions while heightened geopolitical and domestic policy uncertainty persists.
On that basis, I’d hope that full-year expectations aren’t overly optimistic. Although they do say this year will be “more heavily weighted towards H2 than in prior years”.
That’s certainly the case. The full-year adj. PBT forecast for 2026 is about £43.5m, nearly 20% higher than last year’s result.
But adj. PBT barely grew at all in H1.
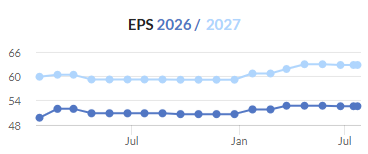
As a result, I calculate that they need H2 adj. PBT growth of about 33% (from £22m to £29m) in order to hit full-year expectations.
They will have a bunch of recent acquisitions to help them do better in H2, and they do say that H1 was held back by “the timing of benefits from integrating subsidiaries acquired in late 2025” - I read this to mean that there were integration costs in H1 which they haven’t fully benefited from yet.
I’ve been very positive on MAB1 but I will moderate my stance slightly today, to AMBER/GREEN, as I perceive that there is a heightened risk of an earnings miss this year.
That’s just a short-term call, however - I’m still a big fan of the business long-term, and I’ll happily go back to GREEN as soon as I'm more confident in the 2026 result. I don’t think it’s excessively valued at all, considering that it’s a high-quality franchised business model:
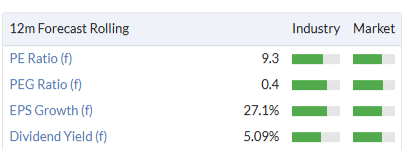
EPS forecasts have held firm so far, but there’s a lot to do in H2:
Mark's Section
Serabi Gold (LON:SRB)
Down 5% at 262p (£211m) - Reports Q2-2026 Production & Operational Highlights - Mark (I hold) - AMBER/GREEN
[At the time of writing, I have a LONG position in this stock.]
The market appears to have been a bit apprehensive about these production figures. The gold price has risen around 3% so far this month and bounced off the psychologically important $4k/oz, yet the Serabi share price is down around 3% over the same period.
I think the market had reasons to be cautious. Although today they report gold production of 11,007 ounces, a 5% increase from Q2-2025, this is below the 12,042oz they produced in Q2.
Palito:
The issue is at their core Palito mine, where despite increasing horizontal development 4% to 1,963m in Q2 and mined ore by 3% to 25.845kt, a drop in grade from 5.88 to 4.55g/t meant that gold production from Palito was 1,123oz lower.
Coringa:
Coringa continued to perform well, increasing mined ore by 12%, although slightly lower grades meant that produced ounces only increased by 1%.
This brings us to the second market worry, that Coringa will not get its full mining license and the temporary license will expire. They provide some detail on this:
- Coringa Mine currently operates under a 3-year GUIA licence which expires on January 29, 2027.
Discussions are ongoing with the Agência Nacional de Mineração (“ANM”), regarding the possible extension of the current GUIA.
- For the full mining licence (“LI”) at Coringa, the Company requires a change of land use approval from the Instituto Nacional de Colonização e Reforma Agrária (“INCRA”) as well as the approval of the Estudo de Componente Indígena (“ECI”) from FUNAI, which are both progressing well.
Successful site visit by the local Indigenous communities to Coringa occurred on July 17, 2026.
Change of land use is in the final stage, requiring approvals by INCRA at the state and federal levels.
As an external party, it is almost impossible to judge the likelihood of the various outcomes. Although it is worth noting that when I asked ChatGPT to compare this situation to others, it thought that not getting some kind of license was highly unlikely. It seems the company is covering all its bases by applying for the full license, while also requesting an extension to the temporary one.
Production guidance:
Q2 was described as “broadly in line with budget” but the company maintain their production guidance:
Based on the assumption that the LI will be awarded by Q4-2026, the Company remains on track to deliver FY2026 consolidated production in excess of a record 53,000 ounces gold.
However, it is worth noting that this is a subtle shift from Q1 where they said that they expected “production profile for the year will see each quarter sequentially increasing production” which has clearly turned out to be not the case for Q2. And the guidance has moved from “53,000 ounces to 57,000 ounces” to “in excess of 53,000 ounces”.
I had always assumed they would come in around the bottom of that range, so there is no impact on my modelling. However, this is also the first time they mention that the guidance is based on the full mining license at Coringa being approved in Q4. I’m not entirely sure why this matters, as it would surely be too late to make mining investments (which may be held back until full approval) that would impact that quarter’s production. It may be that the company is getting their excuses in early!
Modelling:
Without seeing the Q2 financial results, there is a good deal of guesswork in my figures. Unknowns include when inventory sales from Q1 will catch up with production, the cost of Sales progression, future gold prices and tax rates. However, here is my best guess, assuming they do actually pull it out of the bag on FY production:
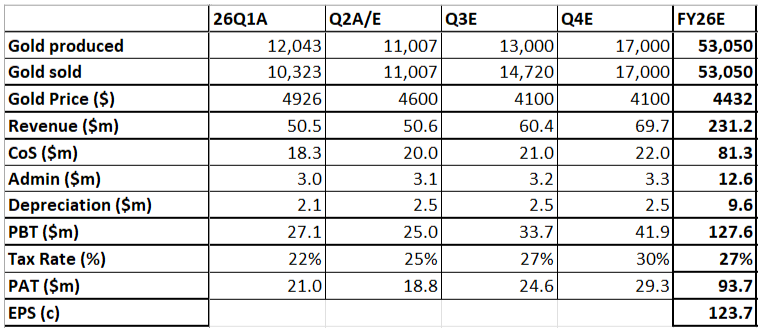
Note that the EPS figures here are below the 138c forecast in the Stock Report. However, this is a case of brokers being slow to update their models for changes in the gold price:
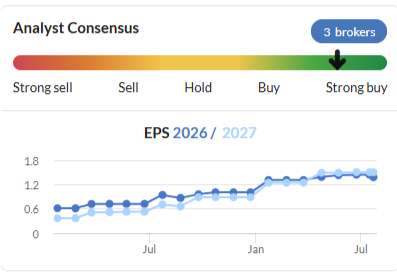
This is one of the many reasons it is worth maintaining your own models for commodity producers.
Despite these headwinds, Q2 should have produced around $19m of PAT, which makes it a bit of a mystery why net cash is effectively flat at $65.7m vs $64.4m at the end of Q1. The only explanation we get is:
…[the] development of the Galena and Serra South zone at Coringa and approximately $4 million of one-time G&A and tax charges…
I think we can also include spending on the new $5m ball mill, and increased exploration costs. Plus there could be further inventory build, due to the timing of sales. However, it would be nice to get an explanation of this.
Broker forecasts:
The only updated note I can see today is from Tamesis Partners. They say the Q2 numbers are a 21% miss on their production estimate for the quarter, driven by a 13% lower than expected grade. The cash is $8.5m lower than where they modelled it.
However, they don’t provide an updated block model to see if they are modelling any full-year impact.
For what it's worth, in my model, EPS would fall further in FY27 based on some conservative cost assumptions and their production aims:
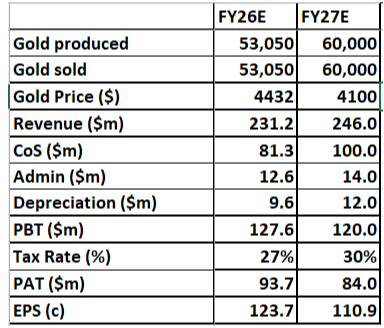
Valuation:
With what appears to be three minor disappointments (Q2 production, FY guidance, and cash), it is tempting to be more negative about the company's prospects. However, even if I take my 2027 estimates, they would do around 83p of EPS, and say $80m net cash, or around 80p/share.
Adjusting for cash, the forward P/E is around 2.2. This is incredibly low for a company with credible ambitions to further increase production in the coming years. These depend on obtaining the licenses for Coringa to continue operating and growing. However, I think that it is unlikely that these will not be granted.
Other risks include the gold price continuing to fall, costs rising, or grades at Palito continuing to disappoint. One quarter’s weak production is too soon to conclude that this is a permanent shift in prospects.
Mark’s view
I won’t pretend that today’s production results weren’t a disappointment to me. The company had previously guided that production would increase incrementally from Q1, but that has not been the case. They must be a disappointment to the company as well, as they have subtly increased the conservatism in the language of their production guidance.
However, on a forward P/E of around 2 (adjusting for net cash), the market is either pricing in permanently lower grades at Palito, a much lower gold price in the future, or no Coringa license being issued. Possibly, all three. While recognising that each of these risks remain, the chances of one of these looks low, let alone a combination of these.
Despite weakening momentum, the company remains a Super Stock, as its incredible profitability at current gold prices gives it high Quality and Momentum scores:
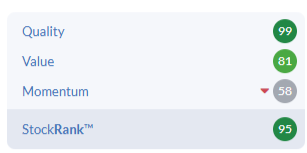
As such, I don’t see enough to change our previously broadly positive view of AMBER/GREEN, nor my personal holding.
Mission (LON:TMG)
Up 29% at 20p (£14.3m) - Half Year Trading Update - Mark - AMBER/RED =
I took a look at this marketing group following an inline AGM statement last month, when the market seemed to take heart from the lack of further profit warnings in their outlook. The market’s reaction today has been very similar, up 29% to 20p, as that outcome has been reiterated:
As a result, while market conditions remain uncertain, the Board remains confident in delivering profitable growth across all business segments, with the Group on track to meet full year market expectations
Helpfully, these are given as:
The Group believes market expectations for the year ended 31 December 2026 to be revenues of £70.0m and headline operating profit of £8.1m (2025: £5.1m).
However, looking at today’s H1 trading update, I am a little sceptical. H1 revenue is actually down 4.7%, and while headline Op profit and PBT are showing reasonable percentage increases, following a period of cost-cutting, these are very small numbers:
…headline operating profit before adjustments expected to be up 10% at £2.4m …Headline profit before tax is expected to be 27% higher at £1.4m (30 June 2025: £1.1m).
This leaves a huge amount to do to go from a headline operating profit of £2.4m for H1 to £8.1m for the full year.
Adjustments:
Adding to the concerns is the scale of the adjustments. Last year, headline operating profit was £5.1m, but this required £21.7m of adjustments, including restructuring costs of £1.9m and Acquisition and disposal related costs of £2.4m. While we don’t get to see the H1 details until the results are released, I expect these sorts of costs to continue to be reported in FY26.
Balance sheet:
They headline this section as “Robust balance sheet”. However, with net bank debt up £2m since the end of the year to £11m, and £0.6m of acquisition obligations still to be made in Q3 this year, and virtually no tangible assets, this looks anything but robust to me.
Outlook:
While some may take comfort from the in-line statement today, Last year in the same update, they said they were on track to “at least to meet full-year headline operating profit and margin expectations”, of £8.5m. Despite a period of very high adjustments, they only delivered £5.1m of headline operating profit. They left it until January this year, 13 days after the period ended, to break the news that they weren’t going to make the numbers.
Assuming history rhymes, they will probably do around 2p of heavily adjusted EPS again this year, which puts them on a P/E of around 10. Not hugely expensive, but then this is a heavily indebted people business with a shrinking top line.
Mark’s view
Given the big improvement in headline operating profit required in H2 to hit their numbers and the recent history of telling the market they are in line until after the reporting period ends, I put almost no faith in today’s in-line statement.
Looking at the actual numbers released today, we have improved profitability despite declining revenue through cost-cutting, but only if we exclude the costs of making staff redundant. Plus, increasing net debt. In reality, there seems little to be enthusiastic about in today’s update, and I keep our mostly negative view of AMBER/RED.
Works co uk (LON:WRKS)
Down 4% at 76p (£49.4m) - Preliminary Results - Mark - AMBER/GREEN =
I like The Works. In a world where there is increasing evidence that extensive exposure to screens is damaging children’s health, a business that provides cheap non-screen activities on the high street seems like a public good.
The market has liked the recovery story, too. With the share price rising from around 20p in April last year to almost touching 80p:
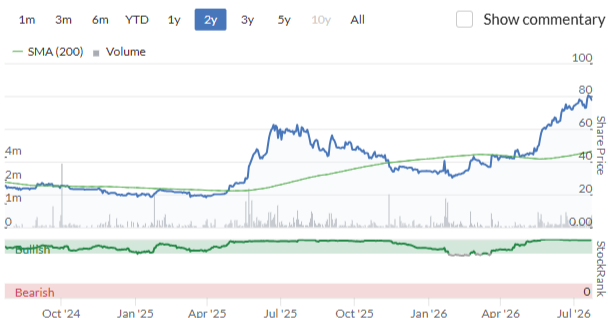
hose who backed the recovery have made exceptional returns.
However, I have been a little sceptical. When I looked at their FY25 trading statement in May 2025, I commented that the reported beat was driven by pre-IFRS 16 Adjusted EBITDA expectations being raised from £8.5m to £9.5m, excluding exceptional fulfilment costs of £1.2m and exceptional restructuring costs of £0.6m. Basically, they were ahead if you ignored everything that had gone wrong in the year.
Their trading update in May this year was again ahead of expectations:
Reflecting the revenue growth, improvements in product margin and cost reduction programme, pre-IFRS 16 Adjusted EBITDA is expected to be approximately £14.0m (FY25: £9.5m), a 47% increase year on year and ahead of current market expectations of £13.5m.
This has been responsible for the share price almost doubling since then.
Today’s results are in line with this EBITDA figure, which turns into a handy rise in Adj. PBT & Adj. EPS:
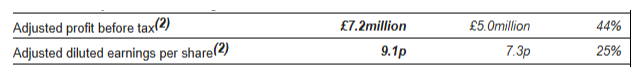
This becomes a statutory PBT of £6.8m, which doesn’t seem too bad until I realised they were excluding the impact of the closure of their online retail operations. Statutory profit after tax actually comes in at just £1.4m overall.
Name change:
I find this rather amusing:
Reflecting the Group's focus on screen free activities and its store based operating model, the Group intends to table a resolution at its forthcoming annual general meeting ("AGM") to change the Company's name from 'TheWorks.co.uk plc' to 'TheWorks plc'. Further information on this resolution will be provided in the Group's AGM circular, to be published in due course.
They presumably changed the name originally because they thought including .co.uk would lead to a higher share price rating. Having failed to make online retail work at all, they now have to bin that part of the name!
Outlook:
The reality is that having closed the online operations, they can only fail at this (and adjust out the failure) once rather than continuously as appeared to be the previous scenario.
Hence, when they say:
The Board is encouraged by the Group's strong trading performance in FY27 to date, while remaining mindful of the continuing macroeconomic uncertainty. With the key back-to-school and Christmas trading periods still ahead, the Board is maintaining its recently upgraded FY27 guidance for pre-IFRS 16Adjusted EBITDA of £15.0m
These figures may not be as clean as I’d like, but they will be much better than in the past. Current trading is much better than I would have expected, so I feel there may be room for further upgrades during the year:
The Group's positive momentum has continued into the new financial year, generating +8.8% LFL sales growth during the first 11 weeks of FY27 to 19 July 2026 (FY26 first 11 weeks: +7%). This strong performance reflects sales growth across all product categories driven by further delivery of key strategic initiatives.
Balance sheet:
There is a modest net cash balance of £3.6m and no bank debt, but it is worth bearing in mind that this is a seasonal business where working capital will be much higher at its peak. Also, there are considerable lease liabilities, which have gone up from £75m last year to £82m this year. There’s a £5.5m interest charge, of which £4.1m is notional lease interest.
Lease assets are just £68m up from £62m, which suggests there is still a tail of stores that are not performing as well as expected. I’d expected the gap here to decline over time as underperforming stores are closed/moved/on renegotiated leases, so I’m disappointed that it remains. I tried to quiz the FD on this when they were at Mello. However, they failed to grasp what I was getting at (possibly a bad sign!)
Overall, I don’t see any issues with the balance sheet, which is typical for a brick-and-mortar retailer. Things can get tricky for such a business if revenue were to decline continuously. However, with FY27 so far showing strong growth, such issues look unlikely any time soon.
Broker forecasts/Valuation:
I can’t see an update note from Singer this morning, but with guidance reiterated and only one broker covering the company, we can use the Stock Report numbers:
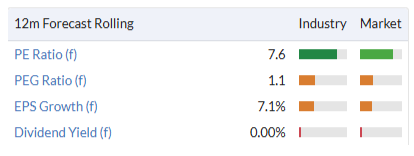
This is still on a pretty cheap multiple, despite the recent share price rise. However, there is little in the way of revenue growth so far, and volumes will decline with the loss of the online retail. We should probably be wary of paying a high multiple for such a business, even if profitability has been much improved through cost-cutting and the closure of online operations.
If current sales trends can be maintained during the year without sacrificing margins, this could well look very cheap again on an earnings multiple basis. However, to make it a buy at the current price, one has to believe this is the start of a multi-year trend towards higher sales with better business execution, rather than a one-off benefit from the closure of loss-making operations.
There is no dividend, but they are flagging the possibility of one for the first time since 2023.
Mark’s view
Roland upgraded this to AMBER/GREEN following the announcement that they would close their online operations. While it may seem strange that a failure of execution makes them a better business, the reality is that they should be a cleaner, more profitable company without this.
Given the positive sales momentum so far this year and modest rating, I see no reason to change that view.
hVIVO (LON:HVO)
Down 1% at 6.7p (£46.5m) - H1 2026 Trading Update - Mark - BLACK/AMBER/RED ↑
We tend to view companies that fail to generate positive EBITDA pretty negatively on the DSMR. It would seem a fairly low hurdle for sustainable businesses to meet.
Hence, this is a slightly worrying statement:
The Group expects to report a negative mid-single digit adjusted EBITDA for H1 2026 (H1 2025: adjusted EBITDA of £3.0 million) driven by the impact of the lower H1 revenue base. However, the significantly higher revenues in the second half of the year are expected to deliver a positive adjusted EBITDA in H2 2026.
Mid-single digit is presumably £4-6m, so that is a £7-9m swing versus the previous year. FY25 was itself a weak year where revenue fell to £46.8m from £62.7m and adjusted EBITDA to £1.4m from £16.4m.
These excluded £1.4m of exceptional items including £450k of acquisition transaction cost and £960k of reorganisation costs, making EBITDA zero overall last year. Today, they appear to guide that FY26 will not have an exceptionals, so that is one positive.
They say 26H2 is expected to deliver a positive adjusted EBITDA. However, they don’t say that for the full year, making a rather obvious omission, which we should probably infer that the FY will be negative on adj.EBITDA overall.
There is a small warning overall on revenue:
The Company expects 2026 full-year revenue to be broadly in line with expectations of high single-digit revenue growth
So it is a bit of a mystery why Cavendish doesn’t choose to adjust their forecasts today and maintain a full-year EBITDA number of £1.2m. Surely they are just setting the company up for a later warning?
However, in the longer term, there are some signs of optimism:
The Group has demonstrated strong commercial momentum, with the orderbook increasing significantly to £65 million, compared with £30 million at the start of 2026, providing much improved revenue visibility for the remainder of 2026 and into 2027 and 2028.
The problem is that even if they had perfect visibility out to 2028, the Cavendish forecasts put them on a forward P/E of 25.
Another positive is that they have no debt, which gives them the financial flexibility to trade through recent problems:
hVIVO's cash position was £13 million as at 30 June 2026 (31 December 2025: £14.3 million). This reflects positive working capital inflows from recent contract wins, with the Group retaining the financial flexibility to support ongoing investment in growth initiatives across the business.
Cavendish forecasts that this will drop to £8.8m by the year end, which may be optimistic given their FY EBITDA forecast now looks challenging. However, cash is expected to start to build again from a low point at the end of this year, and their solvency does not look in immediate danger.
Mark’s view
A much strengthened order book and sufficient cash to see them through the current weak trading suggest there may be some optimism about a potential recovery. However, with their broker forecasting a positive full-year EBITDA figure and the company only willing to commit to a positive H2 number, the chances of a further near-term warning look high.
In addition, even if they hit all their future numbers, they will be on a forward P/E of 25 for FY28, which seems far too high for a company with such a patchy profitability record. They have shown in the past their ability to grow revenue and profits and generate shareholder excitement by upgrading expectations. They may end up doing likewise again. However, it would be a brave move to expect this in the near term, given the H1 numbers.
Graham rated this RED following their huge profits warning in May last year, and we haven't looked at it since (probably for good reason!) I still see much to be negative about here, not least a negative EBITDA figure for H1. However, it seems that the cash burn may be coming to an end and that revenue will start growing modestly from here, hence they will probably survive. As such, I tend to reserve RED for companies that have no revenue, or an unsustainable business model, or who are insolvent, or are in clear need of additional equity finance. None of these is immediately of concern here, hence I think an AMBER/RED view probably more accurately reflects the clear overvaluation, but without an immediate insolvency risk.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
re removal of quote based system on IG. I have seen a few people complaining about this now. I have sent a complaint to them, but doubt they will see sense until enough people jump ship. Any good ISA providers out there to be recommended (or any to avoid?). The new IG system is insane, particularly for thinly traded shares where the quote can be wildly different depending on the amounts traded.
IBKR if you want access to the US or other foreign exchanges...
I use A J Bell. I find them superb and very good value
I've spent quite a bit of time on this question in the last day or two, as want to move my ISA away from IG.
As I mainly trade small and mid caps, I wanted two things. The ability to get a Quote. And the ability to get Level 2 data (at a reasonable price) to see the order book and actual spreads and volumes available.
I've settled on:
IBKR is probably the best option. However, I already have quite a bit of assets there... so no-go for me in terms of diversification.... also has a Level 2 data add-on.
Hargreaves Lansdown. It appears they probably have the most integrations with market makers and exchanges, so their Quote should be superior. But the fees are high here. Also, I already have some assets parked here....
AJ Bell. Quotes yes. But I found in the past that often there was none for small caps. And execution of limit orders is terrible, worse than IG. So not sure why I'd jump here.
Interactive Investor. Pretty decent choice from what I can see?
The rest I dismissed for one reason or the other... Barclays, Halifax, iWeb, etc...
I'm still getting quotes on IG group (LON:IGG). I agree live quotes is a good thing. I use limited trades, which is useful to get lower buying prices or higher selling prices.
Have moved most of my ISA from HL, not keen to go back there.
ii, not that keen on their platform and the fees are much higher than IG.
May try IBKR but are they any good on smaller UK stocks?
The issue is the removal of the direct connection to the RSP system which most investors prefer in smaller stocks. It is caused by IG migrating to IBKR for the back end for non-professional clients, so a move to IBKR doesn't help in this regard.
HL, AJB, Barclays, and ii are pretty much the only choice for those who value the RSP connection (where you get a quote and 15 secods to decide whether to take it). If you only use limit orders in more liquid stocks, then keeping IG with the IBKR back-end likely won't be an issue.
Companies reporting today
WHAT A LIST!
Well done team for preparing this.
Having read just the summary, I am having tomorrow off!
planning to spend well over $700 billion this year alone
A manager from the Brunner Investment Trust put a little context on this recently. The total capital (I don't recall if it was individually or combined, I think combined) required to create Google, Apple, Facebook and Microsoft was less than $1t.
Cumulative spending on AI by 2031 could exceed $3t.
Something to contemplate.
I did see a pic of an Amazon datacentre under construction recently. The scale of it was truly impressive (absolutely no way you're going to put something like that up in space).
Just to look at it, you have to figure that these guys must really have done their sums to commit to such a huge investment.
I remain a sceptic, but still. I don't own any AI shares (although Computacenter (LON:CCC) is a beneficiary right now).
surely as backup plan though they can earn money from hiring out the "grunt" to others
it just makes no sense to me that long term this money is going to ve completely wasted bearning in mind "grunt" has value - and we are not ghoing to be short of companies wanting grunt - at most basic level most workers probably still haev desktip compuer or pc doing the grunt - worst case scenario they can move into hosting stuff.
Yes could buisnes model shift and company fail heck yes - is this capital spend alone going to be what breaks the company or destroys value - hell no.
all imho thats just my viewpoint.
An alternative way of viewing things is that A.I. is a technology advance that has invisibly wiped off hundreds of billions of intangable value from the likes of Google, Microsoft etc. Much as the advent of the steam engine and trains permanently undermined the value of the canal transport network. Viewed like this, investing these enormous capital sums into A.I. is about survival for the tech companies - a least bad- but essential- measure.
The obvious danger is that if this enormous spending fails to generate the expected returns, it will have to force a rapid change in the market’s assessment of what these companies are worth.
I simply dont get this logic - capex is very much their bread and butter - its flippin obvious to me that "more processing power will be needed long term" - surely bringing forward investment or taking some risk ref investing for growth isnt going to alter then future trajectory of the company value - its not as if you cant simply rent out the capacity to someone else if you have it spare.
To me the danger is very much not investing and losing out on market share
I am not sure what the expected future procesing needs are in 10 years time - but makes sense that might easily be 10 X what it is today if thats the case we need to be investing now clearll
I get the logic that if they need to spend more capital - well that is drain on margins and freecashflow and may not have future payback - surely then flipside is that if they dont find teh "use for the pcessing power" well they then need to spend less later and if "now is peak growth phase ref AI " well now is teh time to invest most and that should subside later as exponential growth stops - which it will likley do at soem stage
You may argue this is a race to the bottom - but i see it that there is this huge need and want for more AI - we are probbaly at the peak of that AI expansion - it seems nonsensical to be worying about extra investment now for that future.
In general if you have agood compoany and they waste one or 2 years profits on some fancy side project - but everything else delivers as normal - surely the market will look back at core other stuff and say - well thats just doing fine and dandy.
We clearly need more infrastructure to deliver AI. However, the key question is whether a $700 billion investment—which represents just one year of spending, with the total easily stretching into trillions—can generate a sufficient return on capital to justify it.
In my opinion, the 80-20 rule applies here: while some will profit, the majority will lose money. This mirrors every other technology boom throughout history, from railways to the internet.
"can generate a sufficient return on capital to justify it."
if we take the worst case and its a one off sunken cost surely the makret is going to look to the future anyway many companies have bad spells where investment dont pay off and thats glossed over
In my opinion, the 80-20 rule applies here: while some will profit, the majority will lose money. This mirrors every other technology boom throughout history, from railways to the internet.
I agree this is a tricky sector to predict the future - and AI is kind of a new era - look at what hapened to nokia after the new era of the smartphone. I agree with those worries.
surely google though is pretty stongly placed - over the years the big american tech titans have shown great ability to deal withn everything thrown at them so thne ones that have made it "already" have nowhere near 80% chance of crashing and burning - its pretty easy for them to gobble up anything that might become competition - of there are the some new entrants - but imho AI will clearly being new income streams if we say AI will trend to "SAAS" down the line.
I am skeptical that all big tech companies will be able to generate adequate returns on their AI capital expenditure. Too much duplication. While it is difficult to predict the ultimate winners, I agree that Alphabet is well-positioned to succeed, particularly given their interesting work in quantum computing which accelerate AI.
Also lets not forget the billions currently being invested in AI startups, it seems likely that most of these companies will not survive once the current funding cycle dries up.
One area of concern is the circular financing by Nvidia as highlighted by Dr Burry. One giant high-rise of cards?
Just food for thought..
To add to this, Chinese AI has proved adept at matching US progress at a fraction of the cost... and making theirs more broadly available too.
It may be more about doubting their ability to match the build-out to align with demand. Tech moves so fast these days that the infrastructure can become less desirable quickly and so that could mean write downs. Build-out too slowly and they won't be able to meet demand and lose market share. It's always been a really hard balancing act for IT companies and I think it's only going to get harder.
Is the risk the investment becomes obsolete quickly where there is a possibility other companies maybe able to provide the IT infrastructure cheaper and quicker in the future. Also how much quicker do things need to be most thinks I go on are more or less instant now. Lastly this feels like a tech arms race between the US and China.
The telco sector has suffered for 25 years after investing too much money in 3G... so I think it's valid to ponder if all this investment is worthwhile. The data centre network virtually went bankrupt after 2000 and it took 10 years before the likes of Telecity managed to reinvent themselves.
The telco sector has suffered for 25 years after investing too much money in 3G... so I think it's valid to ponder if all this investment is worthwhile.
Agreed - i dont disagree in theory and i dont blame anyone for swerving the entire sector
If we dig into the detail though aref Alphabet (staying on point) are you not making nonsensical comparisons?
I think now vodafone still has like £20 billion pound of debt and only makes profit after tax of £1.5 billion - thats a ridiculously sketchy business model and always has been
copilot suggests Alphabet only has long term debt of $49 billion - and pat of $132
if the above stats are correct and comparsions not just nonsensical as there is no similar debt issue ?
i would also say vodafone needs to scrap around to find customers in competitive market - if you have extra "computing grunt" - surely you have the whole world at your feet ref customer base if you need to pass the costs on.
I get the worry and stuff but to me $200 bill investment for Alphabet is rump change as far as i can see. and that investment could generate pretty easy income.
Well I wasn't comparing business models - I was comparing investing a lot of money in the hope of return that may or may not materialise. $200bn isn't rump change to anyone - even Alphabet - but if that's your approach - I wish you luck and move on.
Well I wasn't comparing business models
sorry but when you said the following surely this is a comparison of sorts - i am pointing out the factual nonsense of your comparison - you are comparing situations where companies loaded up on debt compared to profits ( 10 X!!) and that debt has created the future drag - against the discussion i would having about Alphabet where there appears to be little meaningful debt compared to profits - its the debt compared to profits that creates the drag - if vodafone didnt have the debt it would be making great profits.
The telco sector has suffered for 25 years after investing too much money in 3G... so I think it's valid to ponder if all this investment is worthwhile.
"$200bn isn't rump change to anyone - even Alphabet"
the nonsensical point some are trying to make is that this direct investment puts Alphabet at some financial risk - practicably speaking if Graham or any of the other expert commentators actually went to the trouble of detailing the balance sheet of Alphabet - they would give it a massive green tick with it being uber conservative historically. To compare debt laiden telcos to a hugely conservatively financial company that very much has the firepower to unleash this investment when it so chooses is silly and simplyn lazy - if that investement fails it aint gonna over impact the business fundamentals - so rump change it is with raged to "main future prospects"
- i have hopefully adequately explain too that if they have $200billion of extra "computing capacity" - its uber easy to sell that capacity to others and earn back some or all of the wonga irf they were to charge that capacity out to others.
i dont normally trust AI but here is what AI says about Alphabets balance sheet.
Alphabet (Google) Balance Sheet Summary
(Fiscal year ended 31 Dec 2025)
Total Assets: $595.3 billion [finance.yahoo.com], [stockanalysis.com]
Total Liabilities: $180.0 billion [finance.yahoo.com], [stockanalysis.com]
Shareholders' Equity: $415.3 billion [finance.yahoo.com], [stockanalysis.com]
Cash & Short-Term Investments: $126.8 billion [stockanalysis.com]
Total Debt: $67.0 billion [stockanalysis.com]
Net Cash Position: approximately $59.8 billion (cash and short-term investments less debt) [stockanalysis.com]
What Stands Out?
✅ Massive liquidity
Alphabet holds over $126 billion in cash and highly liquid investments, giving it enormous financial flexibility for AI infrastructure, acquisitions, and share buybacks. [stockanalysis.com]
✅ Conservative leverage
With only about $67 billion of debt and a net cash position near $60 billion, Alphabet is far less leveraged than many large technology peers. [stockanalysis.com]
✅ Strong equity base
Shareholders' equity of $415 billion means roughly 70% of assets are financed by equity rather than liabilities, reflecting a very robust balance sheet. [finance.yahoo.com], [stockanalysis.com]
Not sure what has ruffled your feathers so much but the debate is rather simple - is the money been spent wisely or not ?- I don't think anyone other than you is mentioning financial viability of Alphabet. This doesn't mean the investment is good and its perfectly reasonable to debate. I don't need a lecture on financial analysis thank you .... perhaps you do though.
best to draw this one to a conclusion happy to agree to disagree on finer points - it was you who cross referenced heavily indebted telecos and mentioned bankruptcy - with huge debts many of those companies are living very much on the edge - even when they can service their debts. that wsas my main thrust Alphabet is nowt like that - hopefully we can both agree on that point that Alphabet has none of the issues that those telecos had.
Serica Energy (LON:SQZ) have they got a large acquisition in mind?
$750m of new bank facilities agreed….
Probably 100 free cash flow generation in June.
SEGRO (LON:SGRO) - I have changed my mind and sold today, recycling into TR Property Investment Trust (LON:TRY) instead. This investment trust at a discount and c5% yield remains about the best property play in my view.
Topvest- I am thinking of selling SGRO. But not sure about TRY. Held it for a couple of years , did little. Performances says it all- over 1 year -1.4%, 3 years +23.7%, 5 Years -16.3% and 10 years =59.3%. Marcus Phayre-Mudge talks the talk, their marketing is excellent. Sadly the key thing-performance lets them down. (Figures from AIC). I have done far better with a small portfolio of UK property companies and an ETF iShares UK Property UCITS ETF GBP (Dist) (LON:IUKP) which is up 11% since I bought in March and April 26.
Investor Meet Company this afternoon TR PROPERTY INVESTMENT TRUST PLC will shortly be holding the meeting Annual General Meeting at 2:30pm.
I think you mean Caledonia Mining (LON:CMCL) not Caledonia Investments (LON:CLDN). I may be one of the few investors who hold both of these!
There was an after hours RNS yesterday from Capricorn Energy (LON:CNE) announcing a rival bid, at 381p per share, in case anyone missed it. The current offer on the table is about 356 per share.
Morning all,
Today I'd welcome any thoughts on Videndum (LON:VID) and hVIVO (LON:HVO).I hold the latter (for recovery clearly!) and noted at last Mello the enthusiasm that Rochard Stavely/Harwood had for Videndum (LON:VID) ("a double from 380p" per my notes). Todays TA was in line but the tone of the outlook must be the cause of todays sunstantial drop. A buying opportunity or a value trap?
Worth noting that Jupiter Fund Management (LON:JUP) has beaten half year EPS expectations by 20% according to a note just now from Cavendish. I hold.
So what is it the market doesn't like? Assets still leaving?
Yet the shares were down 4.5%?
Yes strange isn't it. It could be because Q2 had outflows whereas Q1 had inflows, and the company itself didn't talk about beating expectations.
However, I wouldn't be surprised to see a bounceback during the day post their analyst call and once broker numbers get updated.
Looking interesting again after today's dip. Worth noting that the previous year benefitted from some large performance fees which weren't repeated this time (as expected). Not sure if there is scope for future performance fees which aren't currently in the forcasts?
SRT Marine Systems (LON:SRT) I hold Lots
I have long believed that the day would come when investors would realise that SRT is no longer a jam tomorrow stock. I think that day has arrived with this end of year update.
Multiple active contracts and a significant pipeline of future ones is testament to the efforts made to develop a trusted sovereign partner relationship with countries that need to protect their marine environment and their land borders from a range of threats. Working with Kuwait has been transformative in expanding the range of capabilities SRT now offers for all aspects of civil as opposed to military defence.
SRT now offers the ability to fuse multiple data sources, from AIS, radar, cameras, satellites, surface and undersea sensors and to give system operators actionable alerts derived from data analysis. The data resides in territory, on equipment owned by the customer and not controlled by another country. This unique advantage is especially appreciated now that the world can see that it can no longer rely on the USA for protection.
Simon Tucker has a stated ambition to grow SRT into a £1bn company in five years, today is a good start. I hope the team will find time to comment.
SRT Marine Systems (LON:SRT)
I have long believed that the day would come when investors would realise that SRT is no longer a jam tomorrow stock. I think that day has arrived with this end of year update.
Simon Tucker has a stated ambition to grow SRT into a £1bn company in five years, today is a good start. I hope the team will find time to comment.
well with profits of £10 mill year just finished and new year a bit more its perhaps not been a jam tomorrow stock for 12 months i would say.
i think the problem here is the company has over many years failed to convert itself into a £1 billion company - Tucker may want it and may publicise it - but the real world is going to look at what you are delivering now.
we currently have a p/e of 21 - so the market is giving the company some credit here - it aint cheap.
if we look at forecasts for the next 12 months - well sales up 6% and profit up 10% - dopes that suggest company is fgoing to be worth 5 times its current value based on those numbers - not on your nelly. Mr Tucker if you think your company is worth £1 billion give investors some proper notes showing concrete income and profit increases to back it up.
Looks like earnings forecasts have coem down over last 12 months rather than gone up.
Does the outlook narrative today say to me we are uber conbfident ref this years prospects ?
Hmmm well the text below doesnt inspire confidence in me - when they say pending what definition so they use ? i read it as three things that might go wrong this year and be excuse for later profit warning - oh i am such a cynic
Looking forward to the new financial year we are confident of existing market expectations which we expect to achieve through a combination of existing contract execution and commencement of new pending contracts and/or additional conversions from our growing £1.8bn pipeline may also occur during the period, however due to the challenge of precisely determining dates and timescales of new projects we will provide further market guidance once these become known.
I get the potential here - as does the market with p/e of 20 - but how "in the bag" is future sales that would be needed to get his £1billion vision. Its tricky one perhaps if they are gonna sign some chomping contracts in next 24 months - well if you wait for the proof the boat will have sailed with price spikes when the contracts are in the bag.
Really positive update from Fonix (FNX:LN)
- Some large contracts have been renewed
- International expansion seems to be moving at pace
- Gross profit and EBITDA increased by double digits with FY expectations to be slightly exceeded
- A 6% yield and a commitment to grow this plus a £2M share buyback
All looks good on a rerasonable p/e of around 13. A nice stock to tuck away and let it play out.
Grossly undervalued a return to 200p plus should be on the cards
yes hold will add
Foreign expansion seems to be a bit lacking. Nonetheless, the stock seems to be priced right now for a steady grower with good divis.
Not sure I understand that comment. Portugal has launched in Sept 2025, Switzerland is in pilot phase, France has been registered as a legal entity and another unnamed country is in the pipeline. I think that is more than enough overseas expansion for now! Execution risk is probably a bigger concern than international growth opportunities.
However, we must be missing something on Fonix (LON:FNX) because the shares remain stubbornly cheap whilst apparently delivering good numbers, paying a decent dividend and looking set for exciting future growth prospects. I hold.
Good Morning Graham!
Can you add Airtel Africa (LON:AAF) and Works co uk (LON:WRKS) to your analysis for today please?
Works co uk (LON:WRKS) some hard-to-understand accounting but looks overall like continued progress. Could continue to be a big beneficiary of parental momentum away from screens?
There's a lot going on there but it sounds like they're making positive changes and their positioning as a provider of screen-free activities is a savvy move as long as they can get that message to parents and kids.
Would welcome thoughts on Fonix (LON:FNX) and Mortgage Advice Bureau (Holdings) (LON:MAB1) if you have time - appreciate it’s a busy day with a large number of company updates
Fonix (LON:FNX) good Mortgage Advice Bureau (Holdings) (LON:MAB1) not so good.
Hold both
Question is do I sell MAB on the bell...
Look forward to comment on the accepted bid for SEGRO, a long-term holding of mine. Seems underwhelming to me, apart from being part of a slow-motion car crash of the London market.
SEGRO (LON:SGRO) - yes, very disappointing if we lose this massive REIT to the Americans. A decent profit to be made, but its a unique portfolio. I will wait to see what TR Property Investment Trust (LON:TRY) say about the deal, but I don't want overvalued shares in Prologis so will likely sell out and purchase Tritax Big Box REIT (LON:BBOX) instead.