Daily Stock Market Report (Thur 28 Nov 2024) - TPX, LGRS, THS, MACF, CRL, LTHM

Good morning! And thank you to Roland for editing yesterday's report while I was struck down with flu.
Please give a warm welcome to Mark Simpson as he rejoins us today. Mark does take an interest in commodity stocks and wrote an article about how to gain an edge in this sector yesterday - see here.
I saw there was a huge amount of comment yesterday about the market caps of the stocks we cover in this report. My expectation is that we are carrying on with mostly the same coverage as always, but with some changes on the margin as each member of the writing team naturally has their own particular areas of interest and expertise.
Megan has created a survey where you can vote on the market segments you want to read about (or don't want to read about). Please take a minute to vote if you can, dragging the segment you are most interested in up to the top of the list and then continuing by order of preference. Thank you!
12.50pm: that's all we've got time for today, cheers!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day. We usually avoid the smallest, and most speculative companies, although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We have a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Add your own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing. Links:
Daily Stock Market Report: records from 5/11/2024 (format: Google Sheet).
Companies Reporting
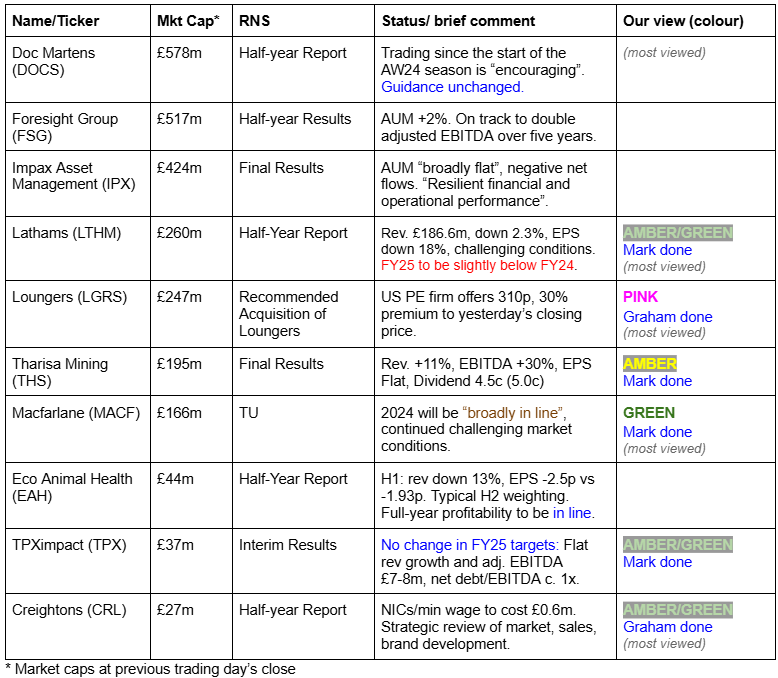
Summaries
Loungers (LON:LGRS) - Recommended acquisition of Loungers - Graham - PINK (takeover)
A cash offer comes in from US private equity at 310p and 40% of the shareholder base are already committed to it. Based on my own calculations of prospective earnings at LGRS and my cautious attitude to café/bar/restaurant shares, it seems like a reasonable exit price to me.
Tpximpact Holdings (LON:TPX) - down 4.5% to 38.2p (£37m) - Interim Results - Mark - AMBER/GREEN
The shares remain on a modest rating if forecasts are to be believed. The H1 results show significant improvement at the bottom line, but much to do in H2. The company seems confident in performing well in H2 and beyond and these results give some measure of increasing confidence in that. Some caution is required since the adjusted figures exclude restructuring costs that have been all too common recently. The balance sheet looks okay, although it has no tangible asset backing to fall back on. Overall, I retain my AMBER/GREEN rating.
Tharisa (LON:THS) - up 2% to 65.5p (£195m) - FY Results - Mark - AMBER
It is hard to be negative on a company with a forward P/E of around 3. However, in this case, all their operating cash flow and then some is due to go on developing the Karo PGM mine in Zimbabwe. It is certainly possible that this is a great investment that will come on stream just in time for a new PGM boom. However, in the meantime, the forecast move to significant net debt significantly ups the risk. Cautious investors may want to adopt a wait-and-see approach. Hence the AMBER rating.
James Latham (LON:LTHM) - Down 10% to 1167p - Half-Year Results - Mark - AMBER/GREEN
While I can’t see updated forecasts, the outlook here reads like a minor profits warning, and the market has taken it as such. A number of factors mean that an expected improvement in H2 now looks unlikely. A P/E of 11 isn’t expensive, but it isn’t cheap either for a distributor that has no near-term growth prospects. However, those who believe this is just a dip and the long-term growth will continue from a well-run business will see this as a buying opportunity.
Short Sections
Macfarlane (LON:MACF)
Down 1% to 103p (£166m) - Trading Update - GREEN
The Board anticipates the Group's performance for 2024 will be broadly in line with its full year expectations.
Broadly is market code for slightly below, of course. This is a strong business operationally, but they can’t escape their end markets, which are described as “challenging.” This means revenue to date is down 4%. Note that this is an acquisitive company, so like-for-like figures will be worse. However, they appear to be able to largely mitigate the effect of the revenue decline. Their broker, Shore, only takes 2% out of their EPS forecasts for FY24. FY25 & 26 EPS is reduced by 4%, but this is due to the impact of NI increases, where the company says:
The increase in employers' national insurance rates and National Minimum Wage announced in the UK Government Budget on 30 October 2024 will increase the Group's costs by c£1.5m annually from April 2025. Mitigation actions are currently being reviewed to minimise the impact.
Even making these adjustments, the company is pretty cheaply rated:
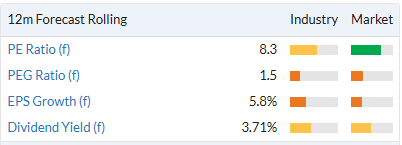
The yellow here is more about how cheap the sector is than any objective valuation concerns.
Mark’s view
When Paul last looked at this in August, he said:
I’m comfortable to stick at GREEN on the good long-term fundamentals. A slightly soft patch in current trading doesn’t alter the big picture that this is a good business, at a reasonable price.
Since then, we’ve had a minor downgrade, but the share price is down too. Although the potential upside from stronger trading appears to have moved further into the future, I see little reason to change this as a long-term view.
Graham's Section
Loungers (LON:LGRS)
Up 28% to 304.5p (£317m) - Recommended acquisition of Loungers - Graham - PINK (takeover)
Loungers have published their interim results along with the news of this recommended takeover.
Paul covered the H1 trading update here.
Takeover offer: 310p in cash, offered by the US firm Fortress Investment Group.
The proposed 30% premium to the prevailing share price is around the bare minimum I look for.
LGRS shareholders are also offered the choice to accept “Rollover Units” in the new holding company, but these units will be “unlisted and non-transferable (except in very limited circumstances)” which does not sound very appealing.
Comment by the Chairman of LGRS:
"We remain very confident about Loungers' future prospects and the half year results that we announced separately today clearly demonstrate the strong momentum that we have in the business…
We are more ambitious than ever and we see Fortress as being an ideal partner to help us take Loungers into the next phase of its growth journey. We believe that the Acquisition represents a compelling proposition for all of our stakeholders and will allow us to execute our ambitious growth plans even more decisively and effectively."
The MD at Fortress highlights his company’s experience in UK consumer businesses, as Fortress previously bought Majestic Wines and Punch Pubs.
The bid: fair value?
While I tend to think bars and restaurants should trade cheaply, I still think that shareholders should be paid a very full price if they are going to agree to a takeover offer. Today’s offer is worth £338m.
The announcement describes the valuation as 8.1x FY April 2024 adj. EBITDA (before site pre-opening costs).
Since I don’t trust EBITDA for capital-intensive businesses like this, I would be more inclined to value it based on actual earnings, but I am willing to exclude site pre-opening costs as they are purely investment in growth.
For FY 2024, PBT was £11.4m and pre-opening costs were £4.2m, so I would be willing to use a PBT figure of £15.6m and apply tax on this to get adjusted net income of £11.7m (up from £8m the previous year, applying the same calculation).
Looking at today’s interim results, there is continued strong growth (revenue +19%) and I calculate that adjusted net income over the six month period was £6m (H1 last year: £4.3m).
Based on the growth trajectory, it therefore looks to me as if the company might be on track to generate an adjusted net income figure this year of £16m+.
The current-year adjusted PER for the offer from Fortress is therefore in the region of 21x (£338m divided by £16m).
Graham’s view
Personally I would view this as a fair offer for a company in this sector.
The analyst at Singers Capital Markets does not agree, and has come out with a research note headlined “low cash bid which should be rejected”, arguing that the bid is “on the low for a business with an excellent track record, a differentiated offer and a significant growth runway”.
However, I calculate that according to their forecast for adj. EPS (FY April 2025), the PER for today’s bid is over 25x. Based on anticipated growth, this falls to 17x by FY 2027. Again, my personal view is that the price is fair.
40% of LGRS shares are already committed to vote in favour of the deal, including the shares owned by Lion Capital and the Chairman Alex Reilley:
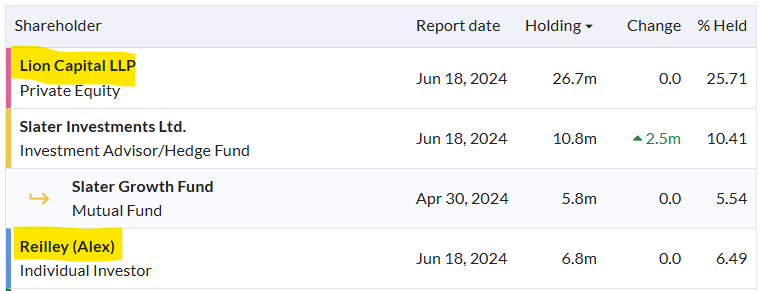
With 40% already committed, I think it’s more likely than not to go through, although there is still a chance for it to be held up. I wonder where Slater stand on it - I presume they are included in the 40%, but they aren’t mentioned in today’s announcement.
Creightons (LON:CRL)
Down 7% to 36.75p (£23m) - Half-year Report - Graham - AMBER/GREEN
Roland covered the H1 trading update from Creightons here.
Today’s interims see the share price giving back some of its recent gains, but it’s still slightly higher than it was when the H1 trading update was released.
There is no analyst coverage of this company available anywhere:
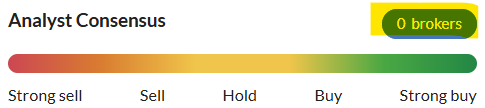
Let’s take a look at some of the key elements of this report.
Revenues fell year-on-year by £0.5m to £27.1m.
Gross margin improved to 44% (from 42.2%) “as a result of cost reduction and SKU rationalisation” (SKUs = distinct products).
Adj. operating profit improved to £1.7m (from £0.5m).
Checking the income statement, I see that the increase in operating profit was driven by 1) a nearly £500k decrease in distribution costs, and 2) a greater than £400k reduction in administrative expenses.
Distribution costs fell “as a result of the decision to exit the majority of third-party logistics providers and bringing picking and packing of finished goods in house”.
The reduction in administrative expenses seems mostly attributable to spending cuts at subsidiary Emma Hardie, now fully integrated, as Creightons “re-evaluates its strategy for the brand”.
Net cash is £1.5m, vs. net debt of £1.7m a year ago. A dividend for £0.3m was paid during H1 (in September).
Strategy: Creightons has three revenue streams: Branded (its own brands), Private Label (creating products for brands owned by retailers/supermarkets), and Contract Manufacturing.
Looking back at last year’s report, I see that the company has been diverting resources away from Contract.
Creightons says today: “Contract sales continue to be challenged through contract customers being overstocked and the inability to obtain credit insurance.”
Private Label and Branded revenues are the key revenue streams now, and Private Label is the main source of growth:
Private label has seen significant growth as a result of new customer wins, and our dominance in the market of being highly innovative, increasing pace of NPD delivery and exceptional quality and strength of service.
Branded revenue remains in retreat due to the cull in SKUs - probably good for the company long-term, but it holds up the numbers in the short-term.
P/E multiple
Roland ran some numbers earlier this month and came up with an FY25e P/E multiple of 10x.
I can update this for 1) the improved cash position, and 2) operating profit of £1.7m was higher than the lower bound suggested by the trading update.
I’ll use an upgraded net income forecast of £2.5m, and I’ll deduct £1.5m of net cash from the market cap. On that basis I get a cash-adjusted PER estimate of 9x (Roland got 10x).
Graham’s view
This is part-manufacturer, part-brand owner. I primarily think of it as a manufacturer.
As manufacturers normally (and rightly) trade at cheap multiples, I’m not sure if I’d be comfortable upgrading this one to GREEN today. By all accounts the new CEO (since March) is excellent and worth backing. But as someone who previously owned CRL shares, I’m also keenly away that the market can get carried away with this one:
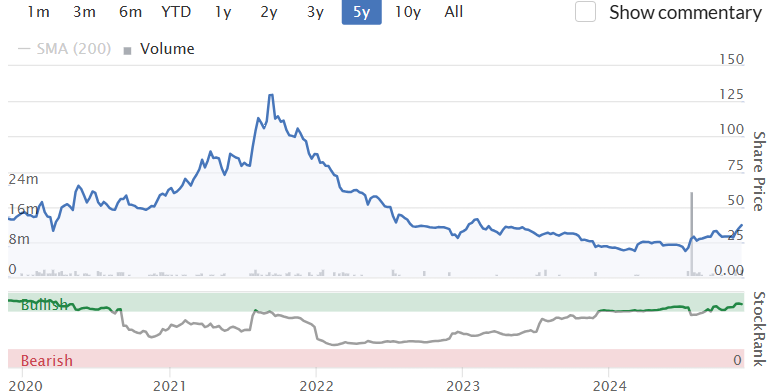
Tangible assets are £15m and the purchased intangible assets should have some value, too, consistent with a market cap of £23m.
I’m therefore happy to leave this one where it was, at AMBER/GREEN.
Mark's Section
Tpximpact Holdings (LON:TPX)
Down 4.5% to 38.2p (£37m) - Interim Results - Mark - AMBER/GREEN
Coincidentally, I reviewed this company when I was last on the DSMR following its Trading Update for the period reported today. This means the headlines are already known:
Revenue of £37.8m (H1 2024: £41.6m), a decrease of 9.2% reflecting market headwinds; Adjusted EBITDA2 up over 15% to £2.3m (H1 2024: £2.0m)
This means that profitability is up significantly in H1 versus last year:
Adjusted diluted earnings per share up strongly to 1.2p (H1 2024: 0.5p)
However, there is a big gap between the adjusted and statutory figures:
Reported diluted loss per share improved to (3.6)p (H1 2024: (10.2)p)
So, it is worth checking if these adjustments seem reasonable. Here, note 7 gives us the breakdown:
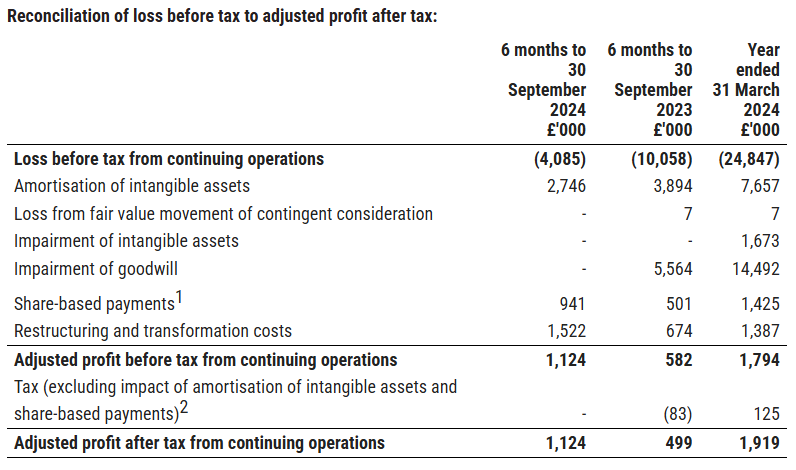
Excluding the amortisation of intangibles is fairly normal these days, and I think this is acceptable as long as the company isn’t capitalising significant amounts of intangibles. This figure is zero for these six months and negligible in previous periods so that seems ok. Share-based payments is a huge debate. Many companies exclude them, but they are a real cost to shareholders. They are just not necessarily a cash cost equal to what the option pricing models suggest they are for accounting purposes. Perhaps the best solution is for shareholders to exclude them for profits but always use the fully diluted share count for EPS.
I have less patience for companies excluding restructuring costs when they seem to restructure every year. Indeed, in some companies, such as consolidators in declining industries, restructuring is their core business! That isn’t the case here. However, these costs are material and appear to be recurring in nature. Shareholders will want to quiz management about the exact nature of these costs and when they will end, in any management calls. TPX will be presenting on InvestorMeetCompany at 11:30 today.
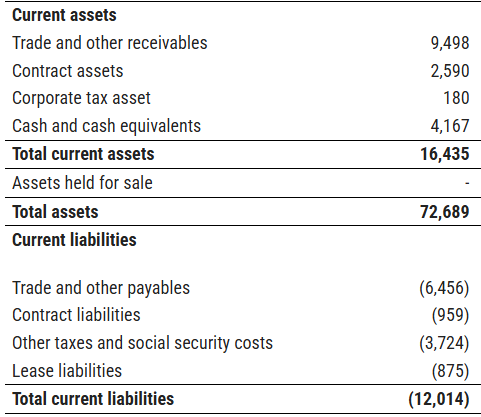
With these results, we also get to look at the balance sheet. Here the current ratio looks reasonable at 1.37:
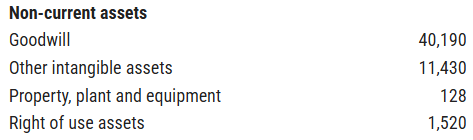
There is little in the way of tangible asset backing, and almost all the assets are intangible:
However, net debt is down, and it appears without them playing games with working capital:
Net debt (excluding lease liabilities) as at 30 September 2024 of £7.9m (31 March 2024: £7.1m; 30 September 2023: £12.8m)
This is good news, but it is also worth bearing in mind that they have a lot to do in H2 to meet forecasts:
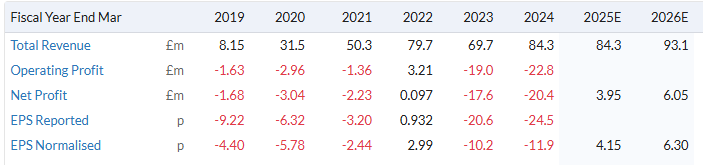
That works out to be £46.5m revenue and c.3p of EPS. However, they re-iterate what they said in the last trading statement:
No change in FY25 targets: flat revenue growth for the year and Adjusted EBITDA in the range of £7-£8 million, and net debt of around 1x EBITDA
FY26 target of like-for-like revenue growth of 10-15% reaffirmed
Mark’s view
The shares have bounced following the last trading statement as confidence has built in their ability to deliver in line with expectations. Despite this, the shares are still trading on a very modest rating. Having now seen the balance sheet and cash flow statement, I don’t see anything to be concerned about. However, investors need to interrogate those restructuring costs, as the value here is in the company's ability to generate high earnings and cash flow and it is no good if these continually go out in below-the-line costs. Overall, I retain my AMBER/GREEN rating, though.
Tharisa (LON:THS)
Up 2% to 65.5p (£195m) - FY Results - Mark - AMBER
Tharisa was recently covered by Keelan in his review of the PGM commodity sector. I also showed how companies such as this could be modelled by investors, here.
Being dual-listed on the JSE, Tharisa tends to include only a summary of its results in the RNS and then guide us to its website to see the full picture. These are a tale of two commodities. It was the best of times, it was the worst of times. Chrome production increased, as did pricing. But PGM production was flat, with a significant drop in the average price received:
Chrome production at 1 702.6 kt (FY2023: 1 580.1 kt)
o Average metallurgical grade chrome concentrate prices up 13.7% at US$299/t (FY2023: US$263/t)
PGM production at 145.1 koz (FY2023: 144.7 koz)
o Average PGM basket price retreated by 28.1% with average prices received at US$1 362/oz (FY2023: US$1 893/oz)
The net result isn’t bad, increasing revenue and significantly higher EBITDA:
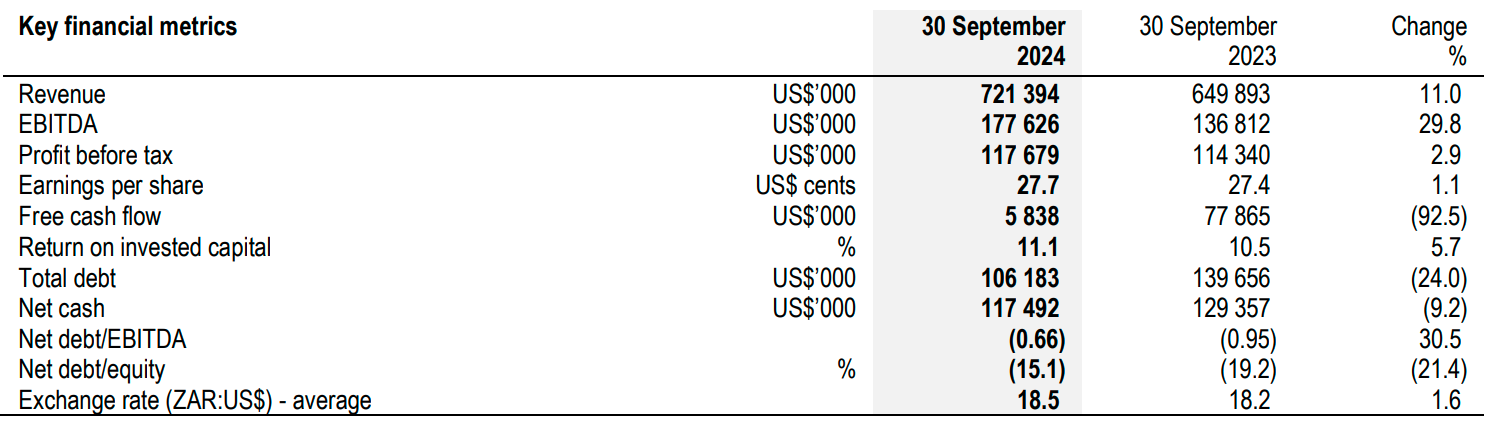
However, that increase disappears as we go down the income statement, as increasing net interest costs and taxes bite. However, this was expected and EPS is in line with consensus forecasts:
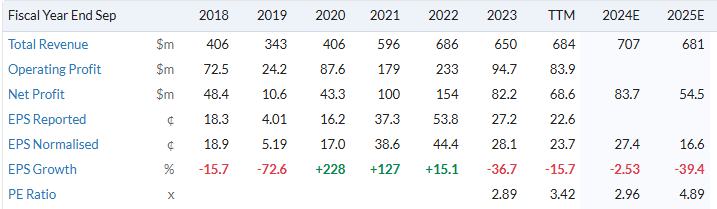
This gives a very low P/E of just 3. On top of this, there is net cash. However, this is something investors don’t like to see:
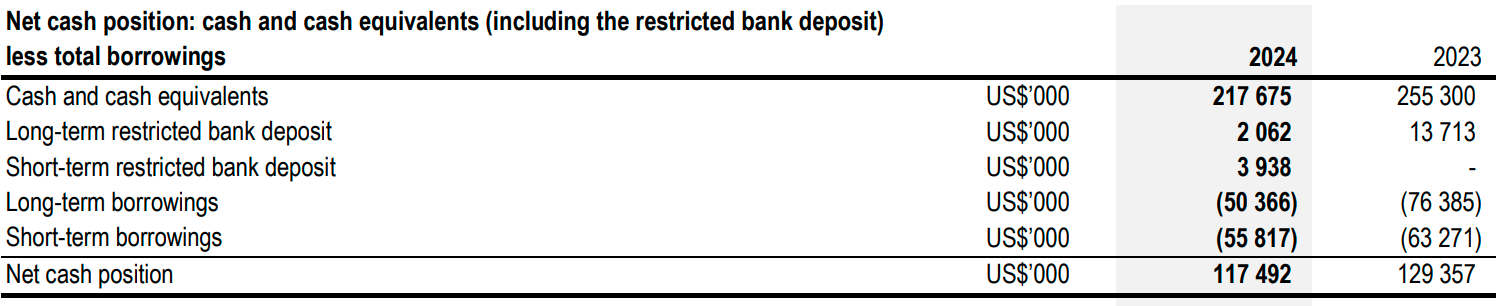
Assuming there are no audit problems, a company having a large debt with an even larger cash position suggests one of three things:
There are large working capital flows, and the balance sheet date is unrepresentative of the rest of the year.
The cash is restricted in some way, perhaps by capital controls.
The cash is committed elsewhere.
There may well be a bit of 1. and 2. but 3. is the major factor. While competitor Sylvania Platinum (LON:SLP) is realising the benefit of chrome production and developing a JV to produce that, Tharisa is doubling down on PGMs and developing a large mine in Zimbabwe called Karo. This means capex for the year came in at a whopping $195m. This is despite Tharisa slowing the Karo development in response to continued low PGM prices:
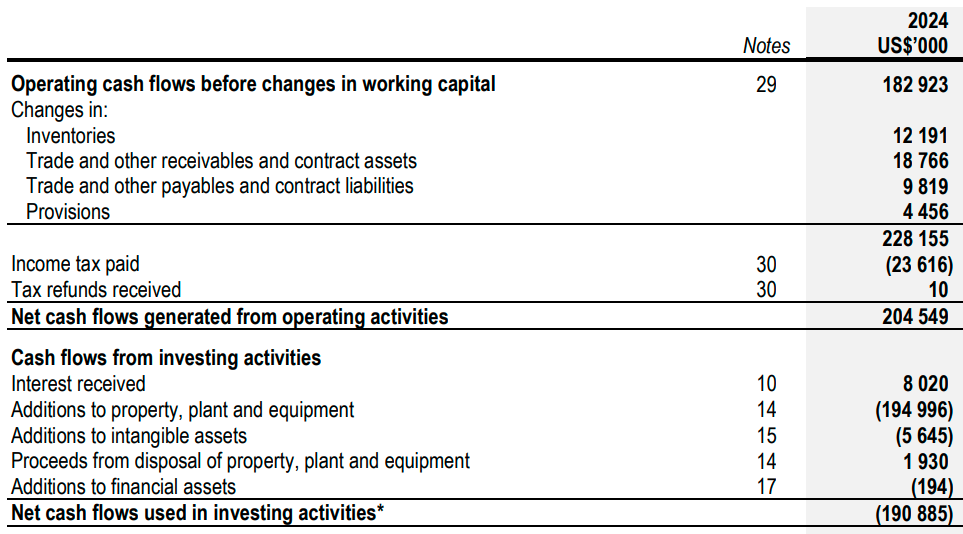
This dwarfs the dividend payment of c.$11m, and investors will feel disappointed that this has been moderated in response to these continued capex demands to 4.5c versus 5c the previous year.
Looking forward, committed capex is much less:
Total capital commitment at the financial year end totalled US$46.9 million (Karo Platinum: US$22.6 million): Contracted for property, plant, and equipment – US$46.1 million Authorised but not contracted for property, plant, and equipment – US$0.8 million.
However, I expect that they will spend far more than the current commitments. Broker Tamesis, are forecasting a whopping $325m spent on capex in FY25. Production also has the ability to increase slightly in FY25:
Production guidance for FY2025 is set between 140 koz and 160 koz PGMs (6E basis) and 1.65 Mt to 1.8 Mt of chrome concentrates
The midpoint of those ranges is above FY24 actual production. Chrome prices have moderated slightly but remain at reasonable levels:
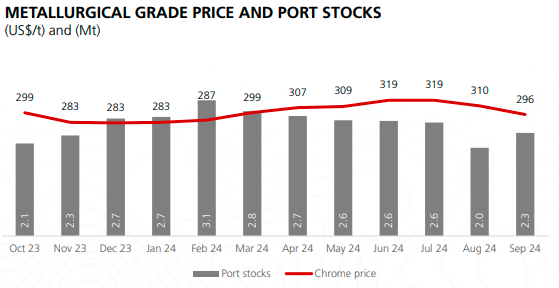
There is little sign of a recovery in PGM prices, but they don’t need to for Tharisa to generate significant operating cash flow. Broker Tamesis hasn’t updated their model following these results, but after the Q3 production, they had 34c of EPS pencilled in for FY25, which means the Stockopedia consensus for a drop in EPS may now be stale. The problem is that Tamesis also forecast net debt to balloon to $178m due to the capex spend, making this much riskier than in the past.
One final thing to be careful with when it comes to miners is how long they have left. In this case, 17 years is a reasonable life-of-mine at Tharisa, especially when the P/E is 3.
The Tharisa Mine’s (South Africa) remaining useful life of mine and infrastructure based on the remaining open pit life of mine and excluding future potential underground development, is currently estimated to be 17 (2023: 18 years) years.
Mark’s view
It is hard to be negative on a company with a P/E of less than 3 which generates significant operational cash flow. However, the capex forecast by the broker Tamesis is so huge that it eats that cash flow and more. This makes them particularly high risk, as they will be in a net debt position and have operations in challenging jurisdictions. I can’t help feeling that if the company simply mothballed the Karo mine and returned the cash earmarked for capex in dividends, the share price would be significantly higher. From this point of view, the most sensible course of action may be to wait to see how that development pans out. Hence, I think this only gets an AMBER rating at the moment. The risks of a waiting strategy are that PGM prices take off and transform the Karo business case or that the business gets taken over. Tamesis point out that:
The share price is trading on PE multiples of 2.6x and 2.4x FY24 and 25 and EV/EBITDAs of 0.7x and 0.7x using a static net cash figure. These are based on essentially spot PGM and Chrome price so believe are conservative. If the market doesn’t react soon and rerate the stock, then we would expect industry to further consolidate.
However, I can’t help but think any potential acquirer would take the same approach as me and wait to see how the Karo development goes, risking paying a bit more for much greater certainty of outcome.
James Latham (LON:LTHM)
Down 10% to 1167p - Half-Year Results - Mark - AMBER/GREEN
I can’t see any updated forecasts from broker, SP Angel,, but it is clear from the market reaction and momentum Rank that many expected better:
As a distributor, they are at the mercy of market prices. So, while volumes are actually up 4.1%, revenue declines
Revenue for the six months ended 30 September 2024 was £186.6m, down 2.3% on £190.9m for the same period last year. Cost prices on both timber and panels have remained stable throughout the first half of the year but there are signs of price weakness in some of our commodity products.
Margins are impacted by EU regulation shifting hardwood supply to the UK:
Gross profit percentage, which includes warehouse costs, for the six-month period ended 30 September 2024 was 16.3% compared with 16.8% in the comparative six months.
50bps doesn’t sound a lot but for a distributor whose overall gross margin is low, this can have a big effect:
Operating profit was £11.3m, down £3.2m compared with £14.5m operating profit for the same period last year. Profit before tax was £13.6m compared with £16.4m for the same period last year. The tax charge of £3.4m represents an effective rate of 25.3%, reflecting the UK basic rate of corporation tax. Earnings per ordinary share were 50.5p compared with 61.5 p for the same period last year.
With distributors, it is always worth checking the cash flow as price changes either way can exaggerate profit changes due to FIFO accounting (First In, First Out). In this case, the operating cash flow paints a similar story:
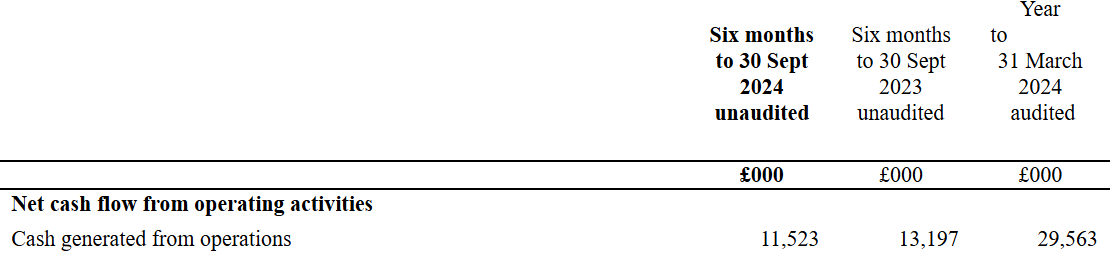
Things don’t appear to show any sign of near-term improvement either:
The second half of 2024/25 has started with similar volumes to the previous six-month period to 30 September 2024, with similar margins. We were expecting the market to show signs of improvement in the second half of this year but so far this has not materialised. We have seen considerable challenges in our marketplace, including a significant competitor going into administration and others looking to quickly turn inventories into cash, which has affected short-term margins in some product groups.
Simply doubling EPS would see full-year numbers of 101p, a miss on forecasts, but a slight one. It is tempting to think that a 10% share price fall represents an opportunity. However, this still puts them on a P/E of 11. While not expensive, it isn’t cheap for a company without any sign of near-term growth.
Mark’s view
When Paul reviewed this in August, he rated it GREEN due to the long term performance of the business. I’m torn about this one. While I agree this is a quality business, it is also a distributor and is not immune to market forces. Hence, the outlook has undoubtedly soured since Paul last looked at it. Hence I am going for GREEN/AMBER to reflect that greater short-term uncertainty.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
Impax Asset Management (LON:IPX) - video recording - Investor Presentation (FY Results) - November 2024
?si=gDrw241Odwz2kQar
Ian Simm (CEO) and Karen Cockburn (CFO) of Impax Asset Management plc hosted a live Investor Presentation reviewing their results for the 12 month period ended 30 September 2024. The company reported broadly flat Assets under Management at £37.2 billion, with resilient financial and operational performance for the period. Management highlighted the expansion of distribution and listed equities product range, with two Fixed Income acquisitions and further development of investment processes. The team ran viewers through business highlights and KPIs from the past year, shared their insights on the outlook, and answered a range of questions submitted by viewers. The full video is available to watch at the link, divided into chapters.
I was expecting some chat about Sylvania Platinum (LON:SLP) but could only see Tharisa (LON:THS) . What have I missed?
Sylvania Platinum (LON:SLP) was only mentioned under Tharisa (LON:THS), "While competitor Sylvania Platinum (LON:SLP) is realising the benefit of chrome production and developing a JV to produce that,"
l don't know why it is tagged on here. I think only stocks that are reviewed should be tagged. It makes searching a lot more difficult.
Noted. I’ll have a chat to the DSMR team to agree a best practice on this.
Avation (LON:AVAP) 5% new shares created from warrants at nice prices. Thanks for the dilution guys!! Will this happen every year?? I expect I should know, as a holder, but I don't.
Yes and they have invited comments, so I have, asking them to justify their actions.
Creightons (LON:CRL) thanks for write-up. Has good Wolfie-Cockney bowl
Supreme (LON:SUP) - Yes, awful Typhoo Tea numbers, but easy game for Supreme. £8.5m distribution and admin expenses and £24m of write-down's and provisions. All irrelevant, as most of these costs will simply disappear. They will use part of their new facility, no doubt so the key numbers will be expected sales and gross margin. They won't be taking on the factory I suspect. Adding £20-50m of sales in the medium term would be neat and they could use this base to do wellness teas. Typhoo is in B&M I believe which is already a customer.
Thanks Mark, great coverage of Tharisa. As I said in a previous post it is good to see small cap miners being covered.
Why nothing on Sylvania Platinum?
Sylvania Platinum (LON:SLP) They didn't report today, it was mentioned in connection with Tharisa (LON:THS), which did report.
One of my best performers YTD.
LTHM ?
James Latham (LON:LTHM) Mark don't forget the net cash balance c 26%. Looks cheap to me taking that into account. Especially as a main competitor has gone bust. They've been around since 1757 so one to tuck away and forget about, enjoying the income whilst you wait for market conditions to improve.
RE: James Latham (LON:LTHM) )
They've been around since 1757 so one to tuck away and forget about, enjoying the income whilst you wait for market conditions to improve.
Precisely. I first bought in 2005, since when the share price has gone up eight times and I've received over double my original investment in dividends. To the best of my recollection in all those years they have never issued or bought back a single share.
It's not an exciting business but it is a very good one.
timarr
Depends when you buy and sell it. I sold in 2017 at 849p, since then in over 7 years, it has gone up about 40%. Not that exciting.
RE: James Latham (LON:LTHM)
Depends when you buy and sell it.
Indeed.
But a CAGR of over 10% over nearly 20 years, not taking into account the compounding effect of reinvesting dividends will do me fine, thank you.
This lady's not for timing.
timarr
Yes l get that but for those who bought James Latham (LON:LTHM) more recently it is not such a good investment. 30% share price over 7 years is no great shakes.
James Latham (LON:LTHM)
I think then point is that thats how shares work sometimes - long term aint short term. and performance short term is much more likely to be random that it is long term - hopefully the more savvy investors buy good companies on the dip rather tyhan bad companies being lucky enough to hit a purple patch.
Long term holders dont have the problem of timing the market. one could possibly have said the same in 2009 or 20198 that short term perfomance had been poor - anyone buying at the "wrong time" a couple of years prior to then has still had very decent outcome despite perhaps having timed the market wrong.
anyway past performance does not decide the future anyway so perhaps slightly pointles discussion. James Latham (LON:LTHM) does look decent value to me - if we take the viewpoing that the current dumping of stuff to uk is going to be short term ? does anyone have any clues as to whether the eu issue is one off or whether its likely to carry on. one oher question - do they have fixed agreements to get their stock perhaps at set prices ? or do they have flexibility to take advantage of lower prices that may be avaialble. There doesnt seem to be much to go on in thatyregard ref todays update.
I would not call 7 years short term.
Hi Rusty2
James Latham (LON:LTHM)
Even after today's 10% fall and allowing for your self selected sell price they've managed a 66% TSR since 2017 as opposed to a max 10% on the FTSE All Share, roughly a 9% CAGR.
What kind of return are you targeting and how do you go about achieving it?
timarr
Tim, are you including dividends and compounding it all up on the FTSE All Share index?
James Latham (LON:LTHM)
Hi Rusty2
I was genuinely curious by the maths here.
I've made a few assumptions about your sell date based on your sell price (c.7.5 years ago), assumed that all James Latham dividends have been reinvested since then and came up with the following figures:
https://uk.investing.com/indic...
I certainly see your point about an 8% CAGR being "unexciting" but it's not too shabby either.
On a personal note, I recently bought some James Latham (LON:LTHM) as I thought it was too cheap relative to the asset backing and cash generation.
A
Hi abtan
Frankly rusty's figures are pointless anyway.
Calculating James Latham's (LON:LTHM) TSR and CAGR are critically dependent on your starting point. You could have bought as high as £9.06 in 2017 and as low as £5.83 in 2018 - or £5.45 on the day of the Covid panic.
Basically I can manipulate the CAGR to anything between 6% and 20% simply by giving myself the flexibility to choose the start date and price.
I'm not suggest rusty is cherrypicking his start date, but he doesn't seem to understand that a single price in time is an anecdote, not data. That is - unless he can show he has a method that makes this type of decision repeatable - which so far he's declined to do.
timarr
Thanks, I had missed that. However, I do wonder if that cash is available for distribution. It has grown with sales growth, perhaps suggesting that it is actually used to fund working capital for a portion of the year. Still, it gives them a lot of financial strength, which is nice, and anything above the current level seems to get paid out as a special dividend. But this again suggests that they at least partially see that cash as a buffer to manage working capital changes rather than distributable.
I don't think it would have to fall that much further for me to consider it a buy, even in small cap markets where some companies are incredibly cheap. I always have in my mind that this is a but at TBV, which is somewhere around £10, excluding the pension surplus, which isn't realisable for the company.
Hi Graham Just wanted to thank you for the review of the Creightons (LON:CRL) half-year results. I hold, and share your positive view of the CEO. As I see it, revenues have not shown much growth over the past five years, there was massive disruption from COVID which was masked by a temporary boost from bottling lots of handwash. They have always wanted to develop the own brand side of the business, and I will be watching to see how this goes.
Tharisa (LON:THS) presnted on Investor Meet this morning, while in a bit of a rush I gained the impression that chrome figured largely in its plans. A recording will be available soon for holders like myself to go over.
Avation (LON:AVAP) Anyone have an idea who sold 3.5m shares in AVAP today ? Went through at 150p, which I assume explains the price fall.
Wasnt me
Looks like it was a sale of rights granted at between 105 and 110.
There was a company announcement at 2.10 pm about the issue of a large amount of warrants. I have contacted the company as it looks like a huge dilution. I am no expert though and have asked for an explanation. Shares down 7% at one stage.
They were warrants issued in 2020 and 2021. They cost £105 and £110 so the company is getting capital of £4.69m. Increased the share capital by 4.94 % and given 40% below current share price my ready reckoner says a dilution of 2.5% But I am no accountant and my sums could be wrong.
Please excuse my ignorance but I would like to understand why Volex (LON:VLX) who have made a bid for another company have put out so many RNSs with forms 8.5? Thanks
That's's standard practice for companies bid on and the bidder. Holders are required to update the market on their positions more regularly.
Supreme (LON:SUP)
There was a lot of discussion here on Tuesday when results were released. A recording of the presentation is now available and the Q&A in particular has drawn out some interesting detail - for example a venture in Spain.
#SUP
Looks as though entrepreneurial CEO Sandy Chadha might be interested in acquiring UK heritage brand Typhoo Tea from the administrators.
You only get an "OO" with Supreme's portfoliooo.....
Interesting opportunity. No commercial details mentioned
Supreme (LON:SUP) - this could be a fantastic deal for them. Second drinks deal if it goes ahead. They can push a great old brand (founded in 1903) through their distribution network at low cost to the discounters. I did exit here, ahead of the Budget, but back in again on this news and the wonderful half year results. EV is x5 the EBITDA. Its very cheap for such a class outfit.
Typhoo Tea sales were over £80m per annum a decade ago and now are only c£20-30m. Could generate £4m gross margin at 20% margin and £20m sales. Hopefully the price is for the business and assets, so maybe less than £5m to buy. Let's see. Buying brands from the administrator is a lucrative business if you have the overhead cost already in place. Ultimate Products Ultimate Products (LON:ULTP) do it well also.
Supreme (LON:SUP)
Typhoo Tea - ahhh us older ones will all remember their adverts from back in the day.
does anyone know how much Typhoo turned over pa.
I would agree would sem right up their street nice brand name that they can run "efficiently" and should be able to make margin on as long as sales are at decent level. Perhaps i am living in a different era Mcewans best Scotch deffo isnt the one most people come back to nowadays !
Supreme (LON:SUP) Typhoo had sales of £23.5 million and loss of £38 million last year. Sandy is canny so I'm confident he has a cunning plan to make money from purchase....
Supreme (LON:SUP)
ouchies not surprised they had to call in the liquidators with those numbers !
Ooo, whaaa-SUP.
Sorry, could not resist :-)
Renewi (LON:RWI) shares rocketed on Thursday after the waste management company said it was minded to recommend a £700m takeover proposal from Australian investment firm Macquarie Asset Management, should a firm offer be made.
Responding to earlier press speculation, Renewi said Macquarie had offered 870p per share in cash. This is a premium of 57% to the closing share price on Wednesday.
Zegona (LON:ZEG) I hold - I would encourage people to take a close look at this share. ZEG is a listed investment vehicle originally set up by 2 shrewd ex Virgin Media operators. They acquired Telecable in Spain in 2015 selling it in 2021 to MasMovil for a return of ~90%. In 2023, ZEG acquired Vodafone Spain (3rd largest operator) for €5B (5.3x EBITDA), the lowest multiple paid for a Spanish scale telco asset in the past decade. €900M of the required financing was provided by Vodafone Group to ZEG via an SPV in the form of preference shares accruing at 5% p.a., which the SPV used to subscribe for Ordinary Shares resulting in Vodafone indirectly owning ~70% of ZEG. ZEG has now entered into 2 JVs with Telefonica (#1 operator) and MasOrange (#2 operator), respectively, where each organization has contributed their Spanish fixed network assets. Each of these JVs is currently in the process of selling a 30-40% stake to an infrastructure investor with closing expected during H1 2025. Historically, similar assets have attracted mid-to-high teens EBITDA multiples from infrastructure investors. Mgmt has stated Telefonica JV’s EBITDA would be ~€125M in FY26 and MasOrange JV EBITDA is estimated at €400-500M. Let’s go with the lower figure for a combined EBITDA of €525M assuming a 15x EBITDA for total EV of €7.9B. ZEG owns 37% in the Telefonica JV and ~30% in the MasOrange JV and has announced that it wants to keep a 10% stake in both. Hence, ZEG would sell between 20%-27% in each JV, which would result in proceeds of €1.6-2.1B for ZEG. This would be sufficient to repay ~€750M of debt at ZEG to stay within leverage covenants post transaction (given lower EBITDA of ZEG post disposal) and redeem all the pref shares owned by Vodafone thereby cancelling their ownership in ZEG. ZEG’s outstanding shares would reduce from 759M today to 181M. ZEG’s post-transaction EBITDA is estimated to be ~€100M lower and assuming it continues to trade at the same uninspiring multiple as today (as the transaction was effectively just a sale-&-leaseback of its network), the SP could triple . On top of that, the CEO who joined last year has bought shares for £1.3M in Jul-25 at a SP of 265p and the wider Mgmt/Board has rolled their entire 2021 LTIP of ~£200M into ZEG shares in Oct-24 at a SP of £357p and now own 7.5% of the company. I’m very bullish on this stock, but please do your own research and calcs. Graham, if you have time pre Xmas, would appreciate if you can take a look at ZEG - cheers!
Back in October Simoan suggested that I moderate my enthusiasm for EnSilica (LON:ENSI) given the boom and bust nature of the ASIC market and the lack of positive cash flow (and the Stock rating of "sucker stock" does not offer encouragement!). Today's announcement is "in line" and therefore has not prompted comment, but for this company an in line statement is exactly what the doctor ordered, since it needs to establish credibility and further distance itself from the Sondrel and Sirata "excitements". With a recent increase in its borrowing approved and an apparent mountain of backlog orders still being garnered and added to, it is getting harder not to give in to enthusiasm and slightly increase my small position.
Slightly larger than the usual companies discussed on here, but if anyone is interested in Halma (LON:HLMA) following another set of high quality results last week then why not attend the webinar with the impressive Charles King, Head of IR and Melanie Horton, Deputy Head of IR at 12pm today. You can register here
Halma has delivered a 10 year CAGR of 12% for both revenues and EBIT - a level not matched by many companies.
Extraordinary moves in Aviva (LON:AV.) and Direct Line Insurance (LON:DLG) this morning after Direct Line rejected Aviva's takeover offer. As of now Aviva is down 3% and Direct Line is up 39%.
Normally when a takeover bid is rejected the price moves for the bidder and the target are in the opposite directions. Presumably the market is expecting a larger bid from Aviva.
Well it did not with Volex (LON:VLX) /TT electronics (LON:TTG). Vlx went down and TTG went up.
Crazy - why have AV made such a generous offer and why have DLG rejected it. Would be interested to hear the rationale on this from Megan and others...
Normally when a takeover bid is rejected the price moves for the bidder and the target are in the opposite directions. Presumably the market is expecting a larger bid from Aviva.
I think you are getting confused here john2 - feel free to correct me with worked examples if you have any.
there are two separate situations that shouldnt really be confused.
example 1
the case here is where bid comes out of nowhere and is rebuffed - i would 99% expect price reaction to be jump in price for company being bid for - probably to something matching bid even if bid is being rejected. ref acxuirer i am slightly more neutral but a drop in price seems natural. The only execption perhaps if bid is below current price and suggestions are that company is in strife.
Practicably speaking todays news is almost as good as a bid imho - not quite so but much better than a bid falling through due to no agreement being made when there was a previous expectation of deal being done.
example 2
the second case is where there has previously been formal bid news and price has already risen and that "likely deal is cancelled" if that were the case i would expect the reaction you are expecting.
to me todays news is much more like an agreed bid rather than something that was likely to happen but has now fallen through and deffo wont.
so price movement here is exactly as i would have expected today.
So the first announcement of a bid was yesterday at 17:35. The bid was actually made on November 19, and represented a 60% premium to the Direct Line closing price on November 18. Direct Line are currently up 40% - substantially less than the Aviva offer price.
As I said, the market is presumably expecting a higher bid, but a 60% premium seems pretty generous to me.
it's ridiculous IMO that this news has not been shared until now, it's basically been a false market in Direct Line shares for the past week. I'm not saying every single intimation of possible bid interest should be disclosed immediately but an actual proposal (albeit non-binding) at a 60% premium should. I'd be pretty furious if I'd sold any DLG shares in the interim.
Direct Line Insurance (LON:DLG) is a company that has been promising little over the years I've been watching (and avoiding), perhaps its true value is coming to the fore now.
A holiday in the US and month end feels appropriate to review where we are. Two fed cuts... a clean sweep to Trump... a deluge of commentary regarding a hot or not US economy. Ignoring any views we have, the market has hardly moved....
T2Y yield is 4.24%... risen since the Fed cuts, 50bps, not moved since Trump.
T10Y yield 4.26% ...risen since Fed, the emerging term pm has disappeared since Trump.
T30Y yield is 4.43% ... up the least since Fed, down since Trump... term premium nearly disappeared.
The Druckenmiller steepener has yet to gather pace, in fact it's weakened. Bonds have been mildly in favour not out of favour. Bonds strengthen quietly and fall noisily at the moment. Their strength is a non story for now. The MOVE index has fallen to 97 since the election and inflation expectations remain anchored at 2.2%.
So far all the above suggests the mkt is braced for muddling on, not too hot not too cold. The data in November did nothing at all for the too hot camp - inflationists.
Perhaps the biggest surprise recently has been the strength of the Dollar since the fed started cutting. Is this Dollar strength or Euro and Yen weakness? ...hard to say but the 6% appreciation in the Dollar is never positive for the broadening out trade, that benefits the UK, Europe and Asia. Hopefully it starts to weaken but is likely to remain volatile with the new government and all the news flow. A little cash buffer probably makes sleeping at night easier.
Good luck all.
Hi RDHowarth,
In connection with your review it might be worth mentioning that the US SmallCap market has moved recently, perhaps in response to the Fed cuts you mention, or an expectation of further Fed cuts in the future or of tariffs in the future. I expect more to come and have been holding US SmallCap funds for a while. In case anyone is interested I reckon the following are worth a look: De Lisle American (virtually unknown but with an excellent track record), Artemis US Smaller Companies, IFSL Marlborough Global Small Cap (most holdings in US/Canada and fund size only £6M) and the SPDR MSCI USA Smallcap Value Weighted ETF (US MSCI SmallCap index seems the best one to track). All these have strong momentum. Sentiment for small caps is so much better in the US compared to the UK but like alot of Stockopedia subscribers I also hold plenty of individual smallcap companies in the UK and USA.
Direct Line Insurance (LON:DLG) has rejected a cash & shares bid from Aviva (LON:AV.). Bid valued at £2.50 at last night's prices.
https://newsfile.refinitiv.com...
I hold both and am inclined to sell up my DLG and draw a (Direct) line under this woeful investment. Gift Horse and all that.
DLG Rejected a bid from Ageas SA (EBR:AGS) earlier this year and they could conceivably come back too & currently are valued higher than they were in Feb. Decisions....
IG Design (LON:IGR) - Market Cap of £105m - interesting update yesterday - reduced profitability, challenging markets but roadmap to improved margins, and focus on cash management and expectation of "a strong net cash position" at year end.
In such regard, a very seasonal business with material increases in Working Capital in H1 but historically a reversal of such in H2, IF such repeats in H2 FY25 the Group will end the year with a significant amount of its Market Cap in Cash balances:
Apparently an updated broker note from Canaccord Genuity left full-year forecasts for adjusted earnings of $0.21 per share unchanged, a PE of c.6.5* with a yield of c.4.2%.
Potential recovery play?
I've been quite sceptical about IG Design (LON:IGR) in the past, so much of the value appeared to be in the hope of a future recovery in trading. However, I think that there are reasons to think they have improved the operational position sufficiently and that those improvements will flow through to the bottom line over the next few years. I asked some "difficult" questions on the PI world presentation and management answered them very well. Such that the drop yesterday appears like a buying opportunity to me. The investment case is actually pretty simple. They trade at 0.5 TBV, where the majority of those assets are in inventory. This means that capital is relatively unproductive at the moment; any changes that make it sustainably productive will cause the share price to be significantly higher. With them now having net cash at all times apart from perhaps Oct/Nov, then the risk of insolvency has pretty much disappeared now, which was the other reason I avoided them in the past.
Serabi Gold (LON:SRB) reports almost 4x EPS increase for 9 months this year compared to last. Now just shy of $0.24. SP currently 89p. I know that miners don’t get reviewed often on here but the changes in EPS and cash flow at Serabi Gold (LON:SRB) look impressive. They also forecast increased production in Q4 due to new processing facility. Any thoughts from the team wood be welcome. I hold.
This is my third biggest holding Serabi Gold (LON:SRB) so obviously I am a cheerleader for this one, but the value here is compelling, even for a gold miner in Brazil.
Current p/e of less than 3, next years p/e less than 2. Production is ramping up, not tailing off and exploration is continuing.
Cash on the balance sheet is up to $20m, and the visibility is clear for making their expectation of 39c EPS for this year.
They also issue quarterly production and financial reports so it easy to keep track of.
Important to realise this is not just a play on the gold pricing rising, there is more going on than that.
David
And yet I don’t think it’s ever been covered in the SVCR (as was)!
Miners did not used to be reviewed on the SVCR.
Quite so. It does look however as though that has changed post Paul’s departure as Tharisa Mining is on the list of daily companies to be reviewed above.
There are things that Paul Scott won't touch with a barge pole and small miners one of them. It's the width of the Sectors that is the problem, can't focus on everything. I've had just as much fun and games with small gold miners as Paul with his consumer cyclicals and consumer defensives. I hold Serabi Gold (LON:SRB.
Re: Serabi
I would also be interested in future coverage of Serabi Gold. I hold a small position like others here - as a leveraged gold play. It is probably the riskiest share in the portfolio.
The mining sector is large - but it can be whittled down by stripping out non producing exploration companies etc - and Serabi has had consistently high stockrank for a good while now. This should justify some coverage on Stockopedia.
Didnt know that so many fellow subscribers held Serabi.
The most recent riskiest was Hummingbird Gold, I held.
Question for an aficionado. What caused the share price to reach £100 in 2006?
Thanks Revs8. You beat me to it. Interesting that post these results net cash at Serabi Gold (LON:SRB) is now about 16% of market cap. I am as sceptical as anyone when it comes to mining shares and fully get the fact that mines have finite lives, but this does look decent value, especially when you consider the increase in the gold price since the average realised price of $2,338 in the 9 month reporting period. I hold.
Very operationally geared play on the Gold price... which has had a strong year... Serabi Gold (LON:SRB) however have, like most companies in the space, completely missed their long term production targets. Delays in permission haven't helped but when I started following this ...short term target of 50k and longer term 100k, remain targets that appear no closer to being met. My feeling at the time was that these targets should offset any gold price weakness. This didn't come to pass in the last cycle. Therefore for me it is likely to follow the gold price...im not a bear of gold but wouldn't be chasing here either. I sold my position extremely badly when mining rights were being disputed... which seems to rear its head at the most inopportune times.
Serabi Gold (LON:SRB) breakout is ticking several boxes. Needs to survive a retest to confirm.
Sorry, this comment passed me buy. I've got to admit that I've mentally crossed Serabi off my investing list. I invested in it back in 2009-10 during the last gold price boom, but lost money on it because they failed to perform operationally. Still, 15 years is a long time to hold a grudge, and I imagine that management and even assets may well be completely different, as is the gold price environment. I'll take a look, but given that I am largely starting from scratch here, it won't be for the backlog tomorrow!
Hi Mark. Thanks for looking at the figures. They have just started a new processing plant which will improve output. The AISC looks high but so is the price of gold at the moment.
James Latham (LON:LTHM) - Worth reading this half year TU even if not a holder just to see the challenges and opportunities of trading in today's environment. Timber rejected by EU due new legislation dumped on the UK - Buyers trading down to cheaper products and new opportunities following collapse of a major competitor - its all there...
Just a reminder on Impax Asset Management (LON:IPX) that we are hosting an Investor Presentation webinar with management this afternoon at 3pm - you can register to sign up here: https://www.equitydevelopment....
Creightons (LON:CRL) update positive though perhaps not quite what the market was anticipating with this week's strong rally up to the results?
Creightons (LON:CRL) was broadly what I expected and I think that the move towards cheaper own brand product is welcome - I see this very much like another holding Supreme (LON:SUP) which benefits from cost of living. I sat down last night with my daughter and wife who looked at the offerings online and much preferred the in house rather than branded products. But still, dipping their toes into premium territory with Emma Hardie who is in M&S. It's a decent turnaround and I have held it since March I think, so I did actually sell yesterday and bought back in at 34p. I'm confident longer term, as you say there has been a substantial move in recent weeks so profit taken was to be expected, especially given the announcement last week. The Christmas period will be fairly crucial, so will be keeping an eye on discounts and I will be doing my best to gift the women in my life some Emma Hardie bundles!
Impax Asset Management (LON:IPX) - Solid FY24 results, triggers to reignite growth visible - new research available here: https://www.equitydevelopment....
AUM was down a touch by 0.5% in FY24 (1 Oct 23 - 30 Sep 24) to £37.2bn. Net outflows totalled £5.8bn, largely offset by a positive investment performance of +£5.3bn and a contribution of +£0.3bn from the acquisition of fixed-income specialist Absalon Capital Management in Q4.
With average AUM also slightly down, revenue fell 4.7% to £170.1m. Adjusted operating costs were firmly under control and decreased by 2% from £120.3m to £117.4m, helped also by Impax’s incentive-based remuneration model. Adjusted operating profit fell 9.3% to £52.7m, a still-solid operating margin of 31.0% (FY23: 32.6%) and slightly higher than forecast (£52.2m).
Impax generated £49.2m of cash from operations (FY23: £36.7m) with a strong balance sheet and robust cash reserves of £90.8m (FY23: £87.7m), despite paying £36m in dividends. It has no debt. The full-year dividend is unchanged at 27.6p, a yield of 8.6% on the prior closing share price.
It has been a tough two years re flows for sustainable funds, active funds, and for Impax, with its growth trajectory flattening during this period (although AUM is still 146% higher than five years ago: £37.2bn v £15.1bn at the of FY19). However, we think there are pending triggers for inflows to return.
We reduce our fundamental valuation to 700p per share (from 750p) but note this is still more than double the closing share price.
Recommended acquisition of Loungers (LON:LGRS) by FORTRESS INVESTMENT GROUP at 310p representing 30% premium from last night's close.
https://www.investegate.co.uk/...
Shame (I hold) growing nicely, but from comments the CEO made early this year was obvious not happy with AIM share price/Aim market valuations in general.
Who is?!!!!!
Loungers (LON:LGRS)
dang never quite got round to buying this one - well done to holders here.
seems a bit cheap the big based on where price was most of this year - i suspect directors have been better greased up than a greco roman wrestler to make them so enthusiastic.
ECO Animal Health (LON:EAH) - "FY25 interims point to a stronger second half" - new research note here: https://www.equitydevelopment....
For the six months to 30 September 2024 ECO Animal Health reported revenue of £33.2m, -13%YoY and (adj.) EBITDA of £0.45m (H1 23: £0.7m). The gross margin remained firm at 40.3% compared to 40.8% a year earlier. In the October Trading Update (Equity Development report ‘Trading update: headwinds in China’) the Group reported that the combination of a lower incidence of disease and reduced Aivlosin® demand in China and SE Asia markets meant that FY25 (adj.) EBITDA would be c.£7.2m. Into H2 the Group has seen “demand accelerate” to the extent that 82% of market consensus revenue is now covered by year-to-date revenue combined with orders and run rate across operations worldwide. Consequently, the (adj.) EBITDA outlook is reiterated.
Following the Trading Update, and in light of Interim results, our Fair Value range is revised to 97p – 102p based on an updated comparative review of EAH peers. We note that this valuation includes only the initial (R&D etc.) costs but not the full potential contribution from next-generation products under development.
With no particular view on the stock itself, I smiled at the first line of the ECO Animal Health (LON:EAH) interim results statement which described the company as "a rapidly growing global animal health company". About four lines later under 'highlights' we get "Group Revenue decreased 13% to £33.2 million!"
Good morning all.
Trading update look ok for Macfarlane (LON:MACF) . In line still, positive look about latest acquisition. N.I. will hit company from next April for £1.5m. So that’s about £1350 extra per employee. This government has really tried to kill our economy. I see a lot of jobs disappearing in the next 6 months as companies try to reduce tax bill. Well I hope the sp drops a bit more because I fancy a few below a pound!
'Broadly in line' always implies a slight miss to me
The problem with "broadly" is that it immediately tells you that the company is trying to make it look like it is. Disappointing because it seems quite unlike Macfarlane 's (LON:MACF) (I hold) usual practice.
Macfarlane (LON:MACF)
i have sympathy for many listed companies reporting now - seems fairly clear that the hopes that "things could only get better" after the election are not working out as planned. the whole point is that close to year end expectations are normallya bit narrower so i will tend to accept that explanation as long as its not part of "yet another excuse" - ie i would agree Macfarlane have been very reliable last few years.
infact fair play to mangement for saying its possibly not quite up to expectations - i supect many companies may have asked brokers to quietly reduce forecasts a month or two back then hit those lowered forecasts.
Lowering the threshold alone is £615 per employee.
Govt trying to induce productivity growth through labour saving cap ex. Clumsy but so needed? Omelette and eggs.
I suspect this was an unintended consequence rather than planned!
Yes, it is possible that lowering the NIC starting point was partly to encourage higher productivity. The left leaning Resolution foundation frequently referred to the UK's low productivity problem. Its fromer head, Torsten Bell, is now a Labour MP so it would not be surprising if he had a bit of budget influence.
How about making a silk purse out of a sow's ear?
the risk here must be increasing likelihood of a recession, and reduced consumer spending anticipated, of which MACF are fully dependent.
James Latham (LON:LTHM) also appear to corroborate your views. A salient reminder of how hard investing is however efficient the company may be. Diversification and thinking about the longer term springs to mind.