Daily Stock Market Report (Thur 28th May 2026) - PPH, ULTP, TPFG, IQE, SALT, DPP

The stalemate in the Strait of Hormuz continues for now, with the ceasefire itself on shaky ground but with President Trump thought to be very keen to find a politically acceptable deal.
Elsewhere, Bloomberg reports that a merger between SpaceX and Tesla is “inevitable and only a question of timing”, according to influential SpaceX investor Peter Diamandis.
The motivation for this, according to Peter Diamandis, would be to give Musk voting control over Tesla, which he currently lacks but which he will retain at SpaceX. Musk currently owns 11% of Tesla.
Thinking more broadly about the SpaceX IPO, and the $2 trillion valuation (which I consider to be absurd), I do have to admire Musk. He has always been remarkably successful when it comes to monetising investor demand.
He’s an engineer, an entrepreneur and a product designer, yes. But I think what makes him stand out above all of these is his ability to sell a dream to his investors - at Zip2, PayPal, Tesla, Solar City and now SpaceX. I don’t think I’m reaching when I say that nobody else in the history of capitalism has been more successful than him, when it comes to motivating investors to hand him their hard-earned cash.
And in a world where US tech valuations are high and where passive money flows are constantly streaming into the US markets, he does what is financially logical: he gives these money flows something else to invest in.
Overnight market movements:
The FTSE is set to open down 0.6% at 10,430
S&P 500 is down 0.1% at 7,510
Brent crude (July delivery) is up 3% at $97.10
Gold is down 1% at $4,400
Bitcoin is down 3% at $73,000
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
SSE (LON:SSE) (£29.5bn | SR66) | Revenue approx. unchanged at £10.2 billion. Adjusted operating profit down 8% at £2.2 billion. Adjusted Earnings Per Share of 153.5p, down 5% year-on-year but towards the upper end of guidance. Earnings targets of between 168 - 193 pence for 2026/27 (adjusted for equity issuance) and between 225 - 250 pence for 2029/30 remain unchanged. | ||
Computacenter (LON:CCC) (£4.48bn | SR90) | Buys Government Acquisitions Inc, a Value-Added Reseller focused on the US federal government market, for an enterprise value of up to $92m. | ||
Johnson Matthey (LON:JMAT) (£3.66bn | SR53) | Revenue +14%, sales excluding precious metals down 10%. FY26 underlying operating profit +14% and in line with previously upgraded guidance. FY27 outlook: low to mid single digit percentage growth in underlying operating profit (at constant FX and metal prices). | ||
Harbourvest Global Private Equity (LON:HVPE) (£2.33bn | SR87) | Net Assets of $4.3bn (2025: $4.0bn). NAV per Share Return ($) +9.7%. Discount to NAV (£) reduced from 35% to 26%. At least $500m to be distributed to shareholders during 2026. Further investment commitments paused for the remainder of the year. | ||
Sirius Real Estate (LON:SRE) (£1.57bn | SR69) | SRE has notarised the acquisition of a light-industrial business park in Fulda, north east of Frankfurt, for €49.8m. | ||
Vesuvius (LON:VSVS) (£1.17bn | SR89) | Revenue and trading profit in the first four months of year slightly ahead of last year on a constant currency basis. “We confirm our guidance for FY26, with H2 trading expected to be stronger than H1.” | ||
PPHE Hotel (LON:PPH) (£675m | SR36) | Possible cash offer at £22 per share, a 47% premium to share price on 13th Nov (prior to investor meetings being held to discuss options). [Note by Graham: it’s a 36% premium to last night’s close]. From PPHE last night: “The Board… has evaluated the Proposal and determined that the Proposal represents fair value.” | TAKEOVER (Graham) Against PPHE's official asset value, this offer does not appear all that generous: it’s a 20% discount to the company's December 2025 EPRA NRV (real estate's equivalent to NAV). On the other hand, it could be argued that nobody believed that figure anyway. If you go back to last November, the share price was trading at a discount of ~50%. If we measure the offer against earnings, it looks better. The lesson, if there is one, is to not have blind faith in real estate NRVs - but also to get interested when there is a 50% discount and a clear catalyst. In this case, the catalyst came in the form of major shareholders looking for an exit. Congratulations to everyone who has made money out of this share. | |
Iqe (LON:IQE) (£497m | SR29) | Revenue down 17.6%. Adjusted EBITDA £3.2m (FY24: £8.1m). Reported loss before tax £37m. Raised £81m in 2026. Outlook: Q1 trading in line. Revenue for FY 2026 is expected to exceed 20% growth year-on-year, with strong order book visibility into H2. This is expected to result in a high-single digit to low double-digit adjusted EBITDA position. [Graham: unusual phrasing!] | RED = (Mark) Poor results highlight that all of the current excitement about this company is based on future expectations of growth from AI data centres, for which there is little sign in current numbers. The recent placing at a 58% discount removes the immediate financial distress in the business. However, it makes the current proforma EV of around £640m look daft compared to a forward EBITDA of less than £12m. Investors can own the world’s best semiconductor fabs for less than half the rating IQE is on. I can’t help feeling a sense of déjà vu, where a decade ago a very similar excitement around a new use for IQE’s semiconductor fabrication led to the share price 10-bagging and the company raising money at the top, only to see years of ongoing losses leading to the shares losing 97% of their value. I’m not saying exactly the same is going to happen this time. However, there is enough of a similarity for me to keep our firmly negative view. | |
Property Franchise (LON:TPFG) (£304m | SR83) | Continues to trade in line with the Board's expectations. Renters' Rights Act in May 2026 creates a meaningful opportunity for professionally managed operators such as TPFG. “The Board remains confident in the Group's long-term positioning and its ability to deliver on strategic opportunities, whilst continuing to adopt a measured and disciplined approach in light of the broader macroeconomic environment.” | GREEN = (Graham)
This has performed well since my last review , so it's a little more expensive now. The ValueRank of 50 doesn’t see a compelling opportunity. Despite this, I’m going to leave our GREEN stance unchanged. After all, this is a quality, capital-light business with a faultless financial performance and that recently upgraded expectations. As I think a positive re-rating is possible from current levels, I’m happy to stay the course. | |
Pulsar Helium (LON:PLSR) (£150m | SR27) | Minnesota's new helium-specific rulemaking guidelines create a clearer pathway toward responsible helium production at Pulsar's flagship Topaz Project. | ||
GreenX Metals (LON:GRX) (£141m | SR9) | Exploration Target demonstrates potential for globally significant copper endowment at Tannenberg Copper Project, Germany. | ||
Roadside Real Estate (LON:ROAD) (£110m | SR19) | Delayed completion of the acquisition of DAR to the end of June due to the death of the major shareholder of the target. | ||
DP Poland (LON:DPP) (£70.8m | SR20) | SP -5% Revenue +15% to £61.7m, Adj. EBITDA +29% to £6.2m (Pre-IFRS16 EBITDA £2.6m), Loss £4.3m (FY24: 0.5m loss) mainly due to increased impairment charges. Net cash (excl. leases) £.1.4m (FY24: £10.7m) after £5.8m acquisition. “expect double-digit system sales growth in 2026”. | AMBER = (Graham) [no section below] The loss for the period of £4.3m is after a £4.1m impairment, but I think it says something that the company barely made any money even if we leave this out. Depreciation (£4.7m) is a real cost, whether we are talking about the lease costs now included within it, or the ordinary depreciation of PPE. Share-based payments (£0.4m) are a real cost, too. So I don't believe that the adjusted EBITDA figures are useful in this instance. Personally, I'd be ok with looking past the impairment and saying that this is trading somewhere around breakeven. It has a long history of pretty average financial performance and so I think a neutral stance remains fair. | |
Ultimate Products (LON:ULTP) (£44m | SR93) | Q3 Revenue £34.8m flat on last year. Branded sales +3%. Currently expects the flat trading trends seen in Q3 to continue throughout the balance of the year, which would be slightly ahead of expectations. Profitability remaining in line with consensus, reflecting the change in sales mix. | AMBER ↑ (Mark) A lot has happened since we last reviewed this company following a series of profits warnings. In light of this, guidance for a small FY sales beat is well-received, even if the sales mix means that profitability stays the same. Also well-received by shareholders was the recent announcement of a new CEO, who comes from a much larger company. However, I’m not convinced that this in itself marks a turnaround in prospects, especially as the two previously key people are moved to non-exec positions. Still, with several in-line statements in a row now building confidence that forecasts are achievable, despite a difficult consumer backdrop, I feel we should take a more neutral stance. | |
MicroSalt (LON:SALT) (£26.9m | SR2) | Revenue +180% to $2.1m, Net Loss $3.2m (FY24: $5.8m), Net Debt $0.96m (FY24: £$2.49m) after £5.7m fundraise in period. Outlook: updating FY26 sales guidance to US$4.5m, (down from $7.0m guided in January) due to production timing associated with the 2027 launch schedule. | BLACK (RED) (Graham) [no section below] This company says that it can improve the flavour of salt, meaning that less consumption is required for the same effect. We’ve been RED on it and I believe that we should remain so after these full-year results. Recall that there was a 2025 revenue warning last August, when I listed seven reasons for caution. Looking back on those reasons today, one change has been the introduction of financial forecasts from the Nomad, Zeus. These forecasts get slashed today with 2026 revenues cut by 36% to £4.5m, and a larger loss is now expected. The company says that the downgrade is purely due to production timing issues, and is not demand-related. Meanwhile, it finished 2025 with a cash balance of $1.9m after raising $5.7m in new equity. While I do think that this story could get exciting as they gain traction, the risk of another equity raise keeps me on the sidelines and in the RED. | |
Skinbiotherapeutics (LON:SBTX) (£25.3m | SR-) | Investigation into, inter alia, the financial statements for the year ended 30 June 2025 is complete, but interims slightly delayed. Investigation findings and actions to be published with interims. Appointed Saffrey LLP as the Company's independent auditor. | ||
Touchstone Exploration (TSE:TXP) (£23.6m | SR69) | The FR-1835 and FR-1836 development wells on the WD-8 block were successfully completed and placed on production in mid-May 2026, averaging 175 bopd, in line with expectations. | ||
Petro Matad (LON:MATD) (£23m | SR15) | Production from Heron-1 and Gazelle-1 continues in line with forecasts (126 + 123 bopd, respectively.) | ||
Great Western Mining (LON:GWMO) (£17.3m | SR27) | Option Agreement signed with global copper producer KGHM whereby KGHM may earn a 100% interest through staged payments and a minimum exploration commitment of US$5m over 6 years. | ||
Prospex Energy (LON:PXEN) (£13.7m | SR21) | Loss £2.8m (2024:£46k loss) after £2.5m investment write-down. 31 Dec: Cash £39k after £1.2m placing. £2m CLN raised post-period-end. | ||
FIRST CLASS METALS (LON:FCM) (£10.7m | SR11) | Has completed the final cash payment and has now secured 100% ownership of the Kerrs Gold Project in northeastern Ontario | ||
GreenRoc Strategic Materials (LON:GROC) (£10.6m | SR35) | Mobilisation of drill contractors and Company personnel is scheduled for the second half of June 2026. |
Graham's Section
PPHE Hotel (LON:PPH)
Up 25% to £20.10 (£841m) - Update on Strategic Review and Formal Sale Process - Graham - TAKEOVER
We had an RNS from PPHE last night, at 5.10pm, and there is another this morning at 7am.
Last night’s announcement:
Following the announcement on 21 November regarding the commencement of the Strategic Review and Formal Sale Process… the Board of PPH… announces that it has received an indicative proposal from Fattal Hotel Group… regarding a possible cash offer for the Company at a price of £22 per share.
Importantly, “the Board, together with its Rule 3 adviser, has evaluated the Proposal and determined that the Proposal represents fair value.”
The Board intends to engage with the Company's major shareholders regarding the Proposal in order to assess its deliverability
This morning’s announcement from Fattal
Some background: Fattal is Israel's largest hotel group and it already owns 4% of PPHE.
Fattal says:
“As part of the Proposal, the Company announced that it is interested in discussing with the Board of Directors of PPHE and its representatives potential structures for such transaction. The Company announced it is willing to maintain the proposal for a limited period to allow for a constructive engagement with PPHE Board and its advisors, with a view towards announcing a firm offer within the next 4 weeks.”
The reference to “potential structures” presumably refers to the potential for a scheme of arrangement, takeover offer, etc, and not to the potential for any non-cash elements to be introduced. The proposal itself is pretty clear: £22 in cash for each PPHE share.
Premium: £22 is a 36.5% premium to last night’s close.
It’s also a 47% premium to the share price last November, when we learned that the Founder (owning 33%) and President/Co-CEO (owning 11%) were intending to hold meetings to discuss various options, that could include “a potential partial monetisation of their stakes in PPHE”. A formal sale process involving the entire PLC board started shortly thereafter.
Graham’s view
I treat real estate takeovers differently. For a normal business, I expect at least a 25-30% premium against the prevailing share price. That has been achieved here. But in real estate, I mostly think about the premium/discount to asset value that has been achieved.
And against PPHE's official asset value, this offer does not appear all that generous: it’s a 20% discount to the company's December 2025 EPRA NRV (real estate's equivalent to NAV).
That NAV figure was £27.40 per share.
Moreover, the Board of PPHE are now on record saying that £22 represents fair value, which further undermines the notion that the shares were worth £27.40.
On the other hand, it could be argued that nobody believed that figure anyway. if you go back to last November, the share price was trading at a discount of ~50%. This, in hindsight, was too extreme.
If we measure the offer against earnings, it looks better. PPHE has earned 125p of EPRA (real estate) adjusted earnings per share in each of the last two financial years. £22 is a multiple of nearly 18x against that. Forecasts suggest it will earn 111p of EPS in 2026 and then 127p in 2027.
The proposed buyer is credible and makes sense given the Israeli connections at PPHE. I would assume the takeover has a strong likelihood of going ahead.
The lesson, if there is one, is to not have blind faith in real estate NRVs - but also to get interested when there is a 50% discount and a clear catalyst. In this case, the catalyst came in the form of major shareholders looking for an exit. Congratulations to everyoneone who has made money out of this share.
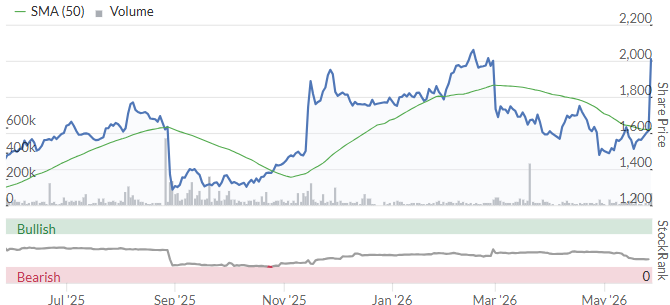
Property Franchise (LON:TPFG)
Unch. at 478p (£305m) - AGM Trading Update - Graham - GREEN =
I went GREEN on this in March, at 434.6p, thinking that an earnings multiple of 10x might not be a bad entry point. Earnings forecasts had just been upgraded, and I’ve been a long-term fan of this business.
Today’s AGM statement is in line:
TPFG continues to trade in line with the Board's expectations, with the Group benefiting from a resilient, highly cash generative business model underpinned by substantial recurring revenues across both its franchise and licensing divisions. This strong level of recurring income provides good visibility over future earnings and helps mitigate the impact of shorter-term cyclical movements in the housing market.
A few other points made in the statement:
The Renters' Rights Act came into effect this month and will increase the burden on self-managed landlords, thereby creating an opportunity for operators such as TPFG. They are “already seeing encouraging levels of enquiries from self-managed landlords seeking support with compliance and property management”.
Two investments were made this year (the acquisition of a mortgage broker and the purchase of a 25% stake in the parent company of Legal & General Surveying Services. These represent “strategic progress” against TPFG’s “platform development strategy”.
Estimates
No change to forecasts at Cavendish today:
2026 revenue £91.4m, adj. EPS 42.3p
2027 revenue £96.4m, adj. EPS 45.6p
2028 revenue £100.8m, adj. EPS 48.4p
The forecast earnings multiple is now 11.3x for 2026, falling to 10.5x for 2027.
Graham’s view
This has performed well since my last review , so it's a little more expensive now.
The ValueRank of 50 doesn’t see a compelling opportunity:
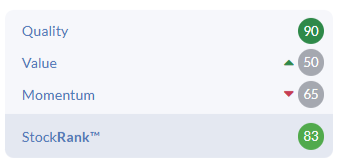
Despite this, I’m going to leave our GREEN stance unchanged. After all, this is a quality, capital-light business with a faultless financial performance and that recently upgraded expectations.
Here’s a chart of the historical earnings multiple range, most of this being prior to the Belvoir merger in 2024. It has achieved a much higher rating from time to time:
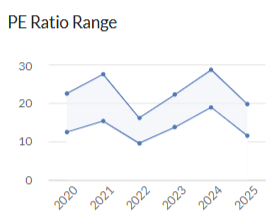
As I think a positive re-rating is possible from current levels, I’m happy to stay the course.
Mark's Section
Ultimate Products (LON:ULTP)
Up 2% at 51p (£44m) - Q3 2026 Trading Update - Mark - AMBER ↑
Here’s the headline:
Unaudited Group revenues during Q3 were £34.8m, in line with the prior year (£34.8m), reflecting continued subdued consumer demand for general merchandise and the planned reduction in non-core third-party clearance sales.
Flat sales in an inflationary environment doesn’t sound great. However, given that H1 sales were down 6.3%, this is a modest recovery. For the full year, they say:
Notwithstanding the subdued macroeconomic backdrop and the unpredictable geopolitical environment, the Board currently expects the flat trading trends seen in Q3 to continue throughout the balance of the year. This means that, while the general merchandise market remains soft, particularly in the UK, Group sales are expected to be marginally ahead of market expectations, with profitability remaining in line with consensus, reflecting the change in sales mix.
25H1 revenue was £79.5m, and the FY £150.1, so if 25Q3 was £34.8m then 25Q4 was £35.8m. If they do the same in 26Q4 then we get £145m, compared to the previous consensus:
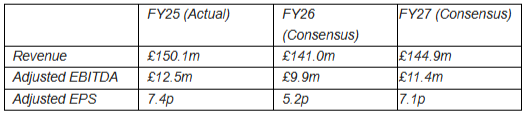
Unusually for such a small company they have four brokers, who have all done similar maths and come up with similar results. All the brokers have increased their FY27 sales estimates by a similar amount to the FY26 increase, but kept EPS forecasts the same. Sales mix is blamed for the difference. To understand this I think we need to delve into the recent management history.
History:
There’s been quite a lot going on behind the scenes since we last reviewed this on the DSMR. Cavendish helpfully summarises this in their latest note:
Earlier this week Ultimate Products announced the appointment of a new CEO, Simon Harrison. Simon is currently the CEO of Princes Group PLC (LSE: PRN), the international food and drink company, and he will join Ultimate Products as CEO designate on 5 September 2026 before replacing Andrew Gossage on 26 October 2026. After a short sabbatical, Andrew will continue as a non-executive director from 1 May 2027. Simon Showman will also move to a NED role with effect from 1 June 2026, while continuing as President and Founder. In February 2024 Andrew moved to CEO from MD while Simon Showman moved from CEO to Chief Commercial Officer. In August 2024, Simon moved to the role of President and Founder and the operating board was restructured, with five management changes announced, to allow the team to play to their strengths.
It won’t have escaped investors attention that even prior to these management changes, it was Andy Gossage who almost always presented the company to investors. The history of the company was as a third-party clearance business. It is widely thought that founder, Simon Showman, was the key figure in sourcing this stock. This part of the business has always been profitable, but very variable, and not really able to grow consistently. So as a listed company looking to scale, it makes sense for this part to shrink, and Showman’s role in the business with it. With the company increasingly moving towards branded products, and clearance described as non-core, it made sense that Gossage took the CEO title.
However, things have not worked out well during that period. In February 2024, the share price was 150p, today it is around 50p. A series of profits warnings meant that FY26 EPS dropped by 70%:
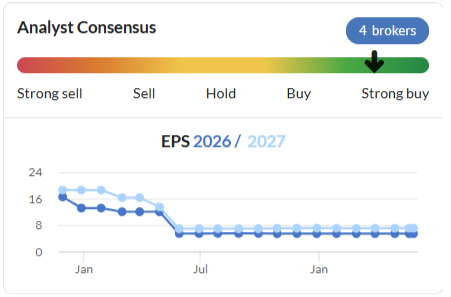
When you consider that the company also has net debt, the share price managed to drop by over 60% and still became more expensive during this time.
I don’t think this is entirely Gossage’s fault. These have been difficult consumer markets in their key geographies, and this sort of business with typically single digit operating margins is very sensitive to changes in sales.
They also benefited significantly from the boom in air fryer sales in 2022, as rising energy costs and inflation drove consumers to seek cost-effective cooking alternatives. Management didn’t foresee the impact a reversion to more normal air fryer sales would have, though, as they kept buying back shares at levels that now look very elevated. [Although it is possible that a post-IPO Management Incentive Plan (now expired) that would have seen them awarded 6.25% of the company if they got the share price above a certain level may have contributed to that enthusiasm!]
New CEO
The recent bounce in the share price has been due to the announcement of a new CEO. This seems slightly harsh on Gossage, but perhaps the larger shareholders made it clear that something had to change. The new appointment is a relatively big-hitter:
Simon is currently the CEO of Princes Group PLC (LSE: PRN), the FTSE 250 international food and drink company
For a CEO to leave a £500m market cap company for a £44m market company means he must see a lot of potential. However, there are a couple of potential pitfalls:
He doesn’t appear to have direct experience of branded sales of the types of products Ultimate produce. Going from a company with £2bn turnover and 7k+ employees to a much smaller business can be a culture shock.
His salary at Princes was £500k. While Showman and Gossage were not badly paid on £300-400k each base salary, if the company matched his current package, this could add to costs. (They could offset these costs by halving the number of brokers that cover the company, though!)
Incoming CEO’s tend to do a thorough review of prospects and re-base targets. There may be a final “kitchen-sinking” to come.
Valuation:
All of the brokers are keen to point out the low valuation, perhaps keen to be the ones to avoid a possible upcoming broker cull! For example, Cavendish say:
Our 85p target price remains based on 9.4x EV/EBITDA and 3.0% FCF yield (adj.) for FY26E. The 5.5% FY26E dividend yield is attractive.
Certainly if one is confident of them hitting FY27 forecasts, this is looking good value:
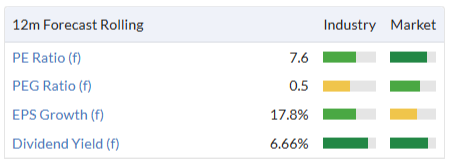
However, we can’t completely ignore the debt, which is forecast to be around £14m at year end, and Cavendish’s price target of 9.4x EV/EBITDA looks punchy to me. After all, this is a relatively low margin business, which designs and distributes Chinese-made goods, with a very volatile performance, as products go in and out of fashion. Apart from occasional periods of irrational exuberance, this has never been a highly rated stock. And while that exuberance may return, I’m not sure anyone should be investing on that basis.
Mark’s view
Last time we reviewed the company on the DSMR it was after one of the profit warnings and we rated it AMBER/RED. We were right to be cautious, as the share price declined pretty much constantly since then:
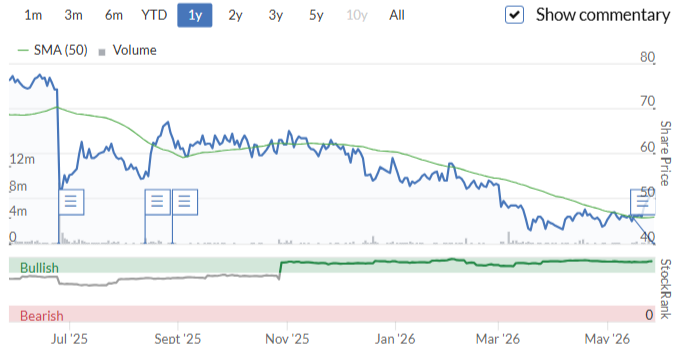
I’m not sure simply appointing a new CEO, even one from a much larger company, suddenly changes the prospects here. There is much to prove, including whether he chooses to “kitchen-sink” the numbers, or completely exit the clearance part of the business, when he finally gets his feet under the table. However, they have now had a few in-line statements in a row and they appear to be weathering the poor consumer backdrop well (or at least slashed forecasts enough that this is now the baseline). At this stage, I think a more neutral view of AMBER would be more appropriate.
Iqe (LON:IQE)
Down 6% at 47.7p (£467m) - FY 2025 Financial Results - Mark - RED =
IQE is a fascinating stock. A British tech company operating in the global semiconductor industry. Perhaps today’s results are best-placed to be understood in the context of some history.
A long, long time ago….
I have bittersweet memories of investing in IQE in the past. It was a decade ago, the share price was 18p, the market cap was £125m and the metrics looked like this:
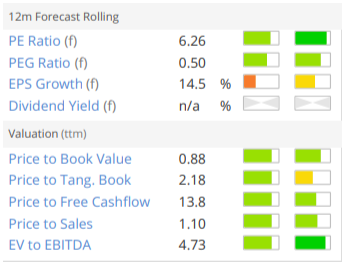
I actually ummed and aahed for quite some time before investing. The reason being that the global semiconductor business is highly cyclical, and it was certainly very possible that I was buying into a value trap. So it was with great delight that I sold less than a year later having trebled my money. The smug look was quickly wiped off my face as the shares continued to 3x again, peaking at around 150p.
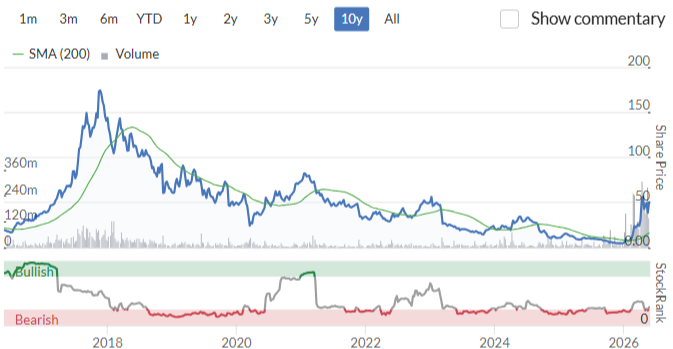
The story that generated such great excitement at the time was that Apple were using IQE’s products. The company was quick to take advantage of the sudden exuberance for their equity and raised fresh capital. This mostly marked the peak in the share price, and the company fell into losses for close to the next decade, raising more money along the way to keep them going:
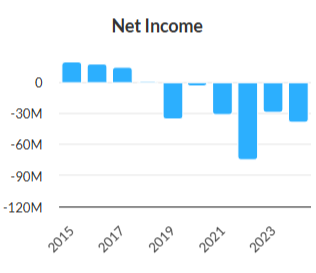
Perhaps rarely has a UK share promised so much but delivered so little.
Bring us up to date…
Fast forward a decade, and their Interim Results to 30th June 2025, showed that they needed covenant waivers:
The Directors remain in discussion with the Group's bankers, HSBC Bank plc, to secure the banks continuing support for the Group and have obtained formal waiver of the 30 September 2025 minimum EBITDA financial covenant test.
The going concern statement revealed that if they grew revenue by 31% yoy in 2026, they will still breach their liquidity covenant and that as things stood, both the sale of IQE Taiwan sale and continued forbearance from HSBC was required to keep them going:
Whilst the Directors are confident that the divestment of either the whole Group or IQE Taiwan is progressing as planned and will realise sufficient cash, they acknowledge that either a decision by HSBC Bank plc to withdraw its on-going support of the Group, or a delayed outcome of the potential sale of the whole Group or IQE Taiwan could impact the availability of sufficient funding for the Group's needs in the going concern period from 31 December 2025 onwards.
In light of this, it is perhaps unsurprising that the shares bottomed at less than 5p, giving a market cap of less than £50m. They say that history doesn’t repeat itself, but does rhyme, so perhaps I should have been less surprised that a sudden interest in the idea of photonics being used in AI data centres and space applications led to the shares in the close to insolvent business being bid up as high as 70p for a £700m market cap.
At this point, the management did what any business finding itself with net debt at 10x Adj. EBITDA, and a soaring share price would do and conducted a large equity raise. The price was at a 58% discount:
The Issue Price represents a discount of approximately 10.1% to the 12 month VWAP ending on 24 April 2026, being the latest practicable date prior to the publication of this announcement, and a discount of approximately 58.4% to the closing mid-market price of 47.6 pence per Ordinary Share on 24 April 2026, being the latest practicable date prior to the publication of this announcement.
Strangely the scale of the discount doesn’t appear to have dampened enthusiasm for the stock. One of the possible reasons for optimism is that MACOM Technology Solutions contributed £30 million in equity and £15 million in convertible loan notes, giving them a 11.5% stake as part of the placing. MACOM and IQE work together on epitaxial services across multiple compound semiconductor technologies. Under their partnership and long-term supply agreements, IQE acts as a critical foundry supplier, manufacturing advanced wafer materials that MACOM uses to build hardware for the AI data centre, telecommunications, and aerospace/defence markets. While this may be a vote of confidence in IQE, given that MACOM have a $22.7bn market cap, they may well have seen this as a price to pay to keep their supply agreements in place.
FY25 Results
After all the context, it is again unsurprising that we have some pretty poor results:
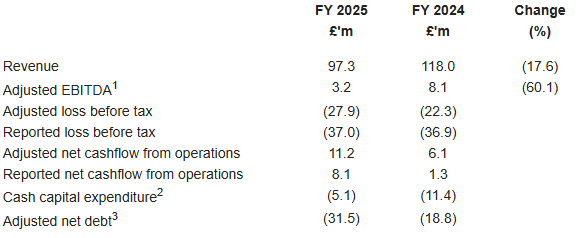
The Photonics part of the business that the market is currently excited about, is doing ok, growing by 15% but more than offset by a large decline in Wireless:
Wireless revenue of £40.1m (FY 2024: £67.3m) decreased 40% year-on-year reflecting uncertain macroeconomic conditions in the first half of the year and softness in mobile handset demand with some end customer requirements met from existing inventory.
Outlook:
This is the key line:
Revenue for FY 2026 is expected to exceed 20% growth year-on-year, with strong order book visibility into H2. This is expected to result in a high-single digit to low double-digit adjusted EBITDA position.
+20% revenue gives £117m, roughly where they were in 2024. The EBITDA margin sounds a lot like 10%, so that’s about £11.7m EBITDA. Up nicely on both FY24 and FY25. However, there has typically been around £30m between Adj. EBITDA and Adjusted Profits, so this is likely to remain heavily loss making.
Valuation:
I can’t see Peel Hunt’s forecasts, nor any update from Panmure Liberum, so it is hard to make assumptions about future years. After all, this is a highly cyclical industry, where trends are difficult to forecast. Using my FY26 forecast numbers, and assuming EBITDA is an appropriate measure for a capital intensive business, we have £11.7m EBITDA and a current market cap of around £650m post dilution. Net cash is around £11m, giving an EV of roughly £639m and a valuation metric of roughly 55x EV/EBITDA.
Frankly, this seems bonkers to me. To be fair, it doesn’t seem out of place to some of the US-listed AI data centre plays. However, those companies don’t come with decades of failure to profitably exploit their technology.
Mark’s view
Perhaps I’m jaded, given my history with the company and this time really is different. However, the company’s track record of losses give little confidence that the current enthusiasm for the stock will not be dashed on the rocks of cyclical reality in a few years time. The recent raise may solve the going concern issues for the moment, and the support of MACOM suggests that their partnerships are real and valuable to them. However, that doesn’t mean that there is an obvious pathway for IQE to grow into its current valuation, and as such I think we have to keep our negative RED view.
Investors who are excited about the positive impact that AI data centres will have on global semiconductor volumes and pricing can invest in Taiwan Semiconductor Manufacturing Co (NYQ:TSM) or GLOBALFOUNDRIES (NSQ:GFS) for less than half the valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Clearly there are some here who have drank the Musk Kool Aid - it's a free world and you're entitled to your own views.
In my view (yeah I'm not a scientist) it's the biggest fraud in the history of the world - makes Enron look like a rounding error - both Tesla and SpaceX. And if - when they merge - all those inter-company sales flattering Tesla's sales will disappear.
As for Musk being a genius, nope, he's just exceptionally good at manipulating human greed levers.
In my view (yeah I'm not a scientist) it's the biggest fraud in the history of the world
Lol - did you even read the factual infromation yiannos1 provided confiming otherwise - why not drill down to facts and make an argumenmt rather than just post nonsense without any facts - to me musk is a genius - the companies are very much real and often leading in their fields - i would say Musk to a proper d***head. It seems many that agree he is a d***head simply refuse to accept the reality that he is actually damn good at running a business - you can try and deny it but if you checked your facts you would see it. Look at someone like Sandy Munro - he is a no nonsense auto engineer - who doesnt fall for bullshit - all day he srtrips down cars and compares them - go and have alok at his older vidoes comparing Tesla to ten competition at the time and you will see Musk is the real deal - and the Idiots running other us car companies are often clueless idiots.
Hi rmillaree
Sorry I was so busy to respond earlier.
Unfortunately you have correctly summarised everything (as always).
Will add that as long as management accepts and allows these trolls to continue harassing hard working knowledgeable individuals, that have offered and offer so much to this forum, then this issue will never be resolved.
All the best
All the best everyone
Especially to you!
All the best
I have actually urged Graham to concentrate on what he is actually very good at; that’s analysing UK companies and have congratulated him on many occasions.
Should take more and read carefully on what we post, in case others come back to me teaching me how or what to post.
US market has reported on average around 14-15% increase in Q1 EPS, while the market is up only 10%. It’s not rocket science, the US market will continue going higher until the mid terms. So reading about US crashes all the time, especially from stockopedia employees/commentators is absurd to me.
All the best
Hi Yiannos,
I don't know if you were replying to me... perhaps.... In any case, I would like to reply to your post. Mainly out of respect for your views - which I like because even if they are abrupt, I believe them to be sincere, which is a rare commodity.
So that you know, my holdings are mostly US companies, just because the majority of my portfolio is in ETFs (my largest holding however is Invesco ChiNext 50 UCITS Acc ETF (LON:CHNX) .. which says something about my outlook.
My views on the US ? - I am a bull, but I think that is a much more nuanced discussion than you are making out. There are many ways of looking at this, but it probably comes down to the fact that if the 'West' is going to make headway in the future, it comes down to the innovation & drive that is the US tech / industrial sectors. We can argue back & forth about whether PE ratios are above the Shiller historical average, or whether private credit is correctly marked to market, or whether the current political climate is healthy or not - but it matters not at all. After four decades of giving away our IP for free whilst getting fat & lazy - Europe & the US have to start working - and the US is leading the way at the moment.
I do agree with you that the Stockopedia website tends to promote UK companies more than should be representative in a portfolio, perhaps this is due to a geographical bias - most of the subscribers I guess are UK based, perhaps it is a little inertia (momentum perhaps you could say). I dont subscribe to the US region - but dare I hazard that the Stockopedia algorithms are less successful in the US market ? I would guess that AQR & Rennaisance already have this edge honed sharp.
For new members - I would caution against ignoring other markets - there will be plenty of bulls for the UK market here - and there are good companies at great prices - but there may well be bigger tailwinds elsewhere. As investors I think that we often fall prey to Aesops sour grapes (one of your great thinkers if I am not wrong) - other companies / markets that are doing better than the ones we hold don't taste as good as they should do - because of whatever reason we make up to ourselves.
My thanks to Graham were open and sincere and not aimed at any comments here today. I think it is easy to forget that this daily coverage is done every day that the market is open - and always interesting. Let him have his view on Musk - we can always disagree. He even offered to cover a US company the other day -- come on -- take him up on that !!
Excellent back & forth commentary today
I’d simply note there is a tendency to fallaciously equate U.K. listed companies with U.K. focused companies …many of the finest U.K. listed companies are deriving the vast bulk of their business from overseas markets…and we get to own their equity at a discount because a U.K. discount is applied at the checkout.
PS Elon is a genius…batsh*t crazy …but a genius
It felt to me that the comments section was turning into an episode of The Office... ;-)
I wish all comments coming back were all like yours. Agree/Disagree-this is not the issue.
You have provided a comment worth reading rather than the rather idiotic comment someone else has provided: ‘all the best everyone!’
Many see yiannos1 and do not even make the effort to properly read my comment. Again, I have urged Graham to concentrate on what he is good at and understands most, and that’s the UK market. If Graham does not understand the fact the US EPS have grown 15% in Q1 but at the same time the SP500 grew by only10%, this is not my fault. Also, if he wants to write every week that the US market is a bubble, then again this is not my fault that the market keeps going up. A reasonable financial analyst/person should sit down and search on why the US market is flying and what exactly he is missing.
Has Graham ever researched from where all this power needed for AI is coming from and what’s the next Bloom Energy (NYQ:BE)?
Power play is the next big theme on WS!
Remember that I have posted here about the data centres, the AI play, the quantum theme, about 2-3 years ago when no one was mentioning them……
Many forget and do not appreciate the fact that I have analysed and shared my analysis here on so many UK companies that went on to be multibaggers McBride (LON:MCB) Most importantly they forget on how many more I have urged people to be very careful in the past, for example Boohoo (LON:DEBS).
Yes he can have any opinion he wants on EM and so does everyone else.
And yes bang on target on Aesop and the sour grapes, but we still regard him as a myth rather than a real person.
All the best
I recently watched a Tom Lee video in which he listed three reasons for the USA's superior economic growth over the rest of the world -
The working age population is increasing not declining
The US is an energy exporter not an energy importer
The US is the world leader in high tech products
Yes John agreed, and nice to see there are still people around willing to offer value to this forum.
These are just some, but the most important for me is the talented educated people they attract from all over the world-just the opposite of what happened here after Brexit.
Brief history of the top CEO’s confirms that.
All the best
Thanks Graham for all your hard work :o)
MicroSalt (LON:SALT)
The company says that the downgrade is purely due to production timing issues, and is not demand-related.
Unbelievable that the company have been waiting all this time for for sales to ramp up to higher levels - its not as if they didnt know they were going to turn up before now they are baked inte forecasts - now we get to the date when they need to think about delivering these orders - how the f*** can they not be ready in time for delivery this year. did they not think about the practicalities of production when they put sales in their forecasts - not great ref customers if customers want it now and the company cant deliver - thats beyond incompetence. Just seems like nonsense excuse or incompetence - neither of which is great. Not sure what our regular MicroSalt (LON:SALT) fanperson makes of this if they are still about.
When you understand that MicroSalt (LON:SALT) is one of only 4 investments held by nano-cap IP promoter Tekcapital (LON:TEK) it helps clarify things. Tekcapital (LON:TEK) reported yesterday and earlier in the week announced a project worthy of Elon's ambition - geothermal powered data centres with low earth orbit (LEO) satellite communication, rather than cable/fibre.
I'll stick with my holding of IP (LON:IPO), for this market niche.
Frontier Developments (LON:FDEV)
Part of our Deep Dives portfolio at a much lower price than current levels.
Announcement about the launch of Planet Zoo 2 in October 2026 will further enhance EPS and generate more FCF.
Still very cheap indeed.
All the best
Finsbury Growth & Income Trust (LON:FGT) I'm a fan of Nick Train, although fortunately I haven't put my money where my mouth is. Half-year report is in, 6 m to 31.3.26. NAV was down 15.5% over that period. FTSE 100 up 7.7% over the same period.
Hmmm.
NAV was 780 ps. At 30.4.2026 is was 819p. Share price 748p. That's a discount of 8.7%. Over 5 years (to end April), NAV was up 0.7% whilst All-Share up 67%. So, massive underperformance.
The problem is, I think, that Nick had a bunch of quality shares (in terms of returns of capital, not necessarily growth) that were highly rated. Several of them have had hiccups (Burberry and Diageo the most notable). His "digital winners" (like RELX, Experian, Rightmove) succumbed to fears of AI disruption. So valuations have come down and/or the businesses themselves have hit road bumps.
Could his fortunes turn around? Meh, it's feasible. RMV trades on a fwd PE of 13.3, in stark contrast to around 29 five years ago. So lots of valuation risk there. ULVR is now on a fwd PE of 15.2, which is reasonable. The problem is that their revenues and operating profits have gone nowhere in 5 years. It's difficult to get excited about that, isn't it?
DGE has been growing its revenues OK, even if not that exciting. Fwd PE is 13.5. Might make a good contrarian bet.
And so on and so forth.
Some interesting comments over on ADVFN: "Last roll of the dice? Taking gearing up to the max £100m because everything's so "cheap", yet also upping the divi 50% - which one is it? ... Rather than "..Once in a decade opportunity..", I'd suggest "Cheaper than at any point during the bond proxy era". Those aren't the same thing."
We shall see.
Mark - I reckon if his fortunes were going to turn round - they would have done so by now. No - he is stuck in the past same as Terry Smith, Mark Slater and Evenlode to name a few.
You could be right. The argument is that Smith and Train were "long bond" trades (something that Smith told us after the fact, it should be noted), which worked well during the period of historical low interest rates. There was a double-whammy of interest rates reverting coupled with high valuations for quality stocks. Lots of Nick's picks had their own issues, too.
I don't think that Smith had many in the way of investing disasters. Novo Nordisk A/S (NYQ:NVO) sticks out, mind. $141 at the peak, now $45. Picking, or holding, highly-rated shares is inherently dangerous. NVO has a PE of 10 at the moment. I strongly suspect it well do well from here.
I asked Grok, ""hat are the chances that buying quality stocks will do well over the next five years?" Grok responded "High chances—likely 70-85% or better—that a diversified basket of quality stocks will do well (positive real returns, and often outperform the broader market) over the next five years." ... "Over 10-year periods, it's often near 100% outperformance vs. the market."
I also heard that Ackman thought quality companies was a good choice at he moment compared to value.
0
I think Graham’s comments are the least disrespectful to what Elon Musk has achieved and the gains/free money he has offered to investors that have followed him over the years.
Also, Graham has been calling about a crash in the US market for a long time now but he is missing the point that we had FOUR in the last 6 years and it’s inevitable that many more will happen in the future. Is a stock market something new? Is it so bad for investors? Every time one happens, another great opportunity emerges for wealth creation.
Because Graham has lost money on shorting Tesla (NSQ:TSLA) it doesn’t mean that Musk is not a great entrepreneur. Gnome2 has commented on Musk’s achievements in a post further down that has covered all.
It’s my humble opinion that when you don’t understand a market or a business, then it’s better not to comment about it and just concentrate on what you are good at.
Yes SpaceX is overrated, overvalued or whatever you want to call it. The suggested TAM is bonkers. But it will be eligible for fast track inclusion 15 trading days after the IPO in the Nasdaq 100, and only 5 days into the Russell.…….and only 3% of its shares will actually be traded…..
My only concern about the US market is the interest payments on the debt. That’s worrying indeed.
All the best
PS I believe Graham has mentioned that he has shorted Tesla (NSQ:TSLA) in the past. If not, I apologise for my mistake.
Hi Yiannos
When you say interest on the debt are you referring to the US itself or Musk's collection of business's ?
Regards
Andy
US interest payments on the debt are about 65% of the Social Security number and climbing…….
Nothing to do with Musk.
All the best
Thanks any thoughts on how it will all end ? I thought it would blow up 10-15 years ago but they seem great at kicking the can all be it I think its now getting much harder for them to do so given no party seems to have any interest in trying to balance the annual spending deficit.
As always they will find the way to get over it!
But I do expect this time a crisis before it is resolved.
All the best
I’d say Graham is being kind to Musk. Yes he’s a visionary and a genius in many ways but he’s also a megalomaniac who treats people like dirt. His behaviour at DOGE was disgusting - and shows how people are treated in Tesla. He’s not a CEO but claims to be. His share payments are out of all proportion. And for me, Space X is uninvestible because of its two classes of shares.
That’s exactly why SpadeX is indeed investable, because of its two classes of shares. I don’t expect you to understand how the US market actually works……
No he has been very disrespectful to a great entrepreneur that has offered so much to humanity just because he has been short on Tesla (NSQ:TSLA) in the past and lost money.
Imagine the narrative if he was long and made money…….
Read Gnome2 and Bohenie posts about what Musk has offered to us.
All the best
Different opinions are precisely what make markets.
Some people see Musk as an extraordinary entrepreneur worth backing despite behaviour and governance concerns. Others think the governance risks, behaviour and shareholder structure matter.
Reasonable people can differ without implying the other side “doesn’t understand markets”.
Yes correct
But when there is a continuation negativity about the US market then this obviously becomes unreasonable and gives the impression of an agenda!
Reminding everyone that the US indices have outperformed the UK indices over the last twenty years and will continue to do so.
Despite the underperformance, the UK still market offers some great opportunities for the ones that have the patience and knowledge to dig into financial accounts.
All the best
I think when looking at Real Estate it is important to remember the pricing of the various parts. Direct Real Estate and Pooled funds investing in direct real estate are priced via valuation which often relies on looking at similar property being sold in the area or rebuild. REITs are a very different beast. They are valued in the market real time. Following the 2008 global meltdown, REITs fell 60/70% in real time. Direct Real Estate was edged down by 5/10% a quarter. The claim that REITs are reflective of real estate isn't entirely true, for long periods it correlates closely with equities. So anyone relying on NAVs and saying a price at 50% of NAV is a bargain needs to consider how the valuation is being decided upon and the REIT price cycle. The issue in 2008 was nothing was selling, so direct was hard to value accurately.
As an aside I remember talking to large pension fund manager, who explained that whilst he recognised that the underlying asset in both was real estate and therefore they should over the longer term reflect the performance of real estate in the short medium term the pricing of the direct real estate was extremely helpful given the dire situation across equities at that time. He totally understood this was simply a pricing anomaly.
Good to get the views of a large manager.
In addition to looking at NAV to value REITs I also like to look at the earnings yield (inverse of PE ratio) which is arguably an even better measure of value. In fact thats how they are generally valued in the US. There are a number of REITs which are on 40-50% discounts but don't look particularly attractive on an earnings yield/PE basis - a good exmaple is Grainger which I think is on a PE of about 16 (or earnings yield just over 6%). Not sure that is especially attractive even if it is on a 50% discount to NAV.
I do this too; so many REITs on "bargain" discount to NAV.
But when you look at the net earnings yield to share price, its low.
Then the question comes - how are they going to be able to increase it massively? Do they have a strategy in place for transforming the properties to drive more rents? Or is there a structural rent increase situation in the 1-3 years to come? Usually its neither, so it makes a poor investment.
Graham,
It feels like you're looking to provoke a reaction with your Elon Musk comments, so I'll stick my head above the parapet and pen a rebuttal.
I've been a subscriber to Stockopedia long enough to know that you're not the biggest fan of Musk or his companies but to suggest that his stand-out ability is selling his latest funding round is more than a little disingenuous. Let's just review a few of his achievements thus far:-
I could go on about human robots and chip fabs but that's for the future. The point is, Elon Musk has a track record of innovation and vision that he's made real. That is the reason he's able to raise capital. He's not selling snake oil, he has a record of turning science fiction into reality. I know this is not going to land well with this readership. It's a group of investors who make decisions on the basis of valuation and I respect that. It's very difficult to put a valuation on some of the blue sky stuff and you can't use traditional valuation metrics. I don't expect anyone to completely pivot their portfolio to the latest tech IPO, but I think all of us should be making ourselves aware of what the future may hold. I hate to say “this time it's different,” but A.I. Is like nothing we've ever seen before, that's for certain. Is there an argument that, whatever your view, we should all have some exposure to Big Tech? Not necessarily because you believe in it, but as a hedge. A hedge against the possibility that you could be wrong.
Thanks Gnome2 for this - Yes it may be painful for many to acknowledge, but EM is a genius of sorts. Take just one venture from above - Starlink. There are already over 10 million subscribers worldwide - and predicted to reach 100m in a few years. Growth is coming from all corners - not just emerging countries. As has been reported recently, our own government is embarking on a programme to provide wifi on the entire UK rail network, thanks to Starlink. And this is probably peanuts, compared to his other ventures - especially Space.
SpaceX has been on a journey - prior to its acquisition of XAI it would have been a more pure play Space co. Now its a mixed Space and AI venture with increased capex as a result. The valuation has also changed as a result. Note this only completed 6 May 2026 ! As an investor I would have been more favourable on the pre merger SpaceX.
Re Tesla - SpaceX has purchased about $131M of CyberTrucks and also $667M of massive grid-scale Tesla Megapacks for power. Or about $890M worth since 2023. Would be much easier to keep this sort of thing going in a merged entity.
Just five days to go until the doors for the best investor event of the year open again.
There is still time to secure your final release ticket and use code Stockopedia25 for a 25% saving. The schedule is LIVE and on the Mello website so you can start to plan your day(s).
50 companies, keynotes, educational talks, stock picking panels and more. Most of all, Mello will have 350+ investors who are welcoming and like-minded individuals... Many will be fellow Stockopedia users too. There is no better place for the investor community to come together.
Schedule, tickets & more: https://www.melloevents.com/mello2026
Warpaint London (LON:W7L) Cambridge Cognition Holdings (LON:COG) Capital Gearing Trust (LON:CGT) ECO Animal Health (LON:EAH) WAG Payment Solutions (LON:EWG) have all recently joined the event.
There is a really interesting very new podcast worth a listen about Space X and the way that the Index compilers are massaging the rules so as to include the company. https://podcasts.apple.com/gb/...
As an aside I highly recommend following the podcast since they discuss wider general investing matters rather than specific companies.
Stockopedia's Ed Croft has been on previous episodes of the Many Happy Returns podcast at least a couple of times.
They have some good content on their website and YouTube too.
Given that 'Necessity is the mother of invention' maybe the fact that the sky hasn't fallen in (yet) over Hormuz suggests that there are alternatives and in the long run the Straits will lose some importance.
My heavily defence skewed defence portfolio isn't looking a sick as in recent months today. Babcock International (LON:BAB) continues a recent climb after months of doom and gloom. Can't wait for the defence investment plan on Monday (I think) to see how they plan to invest in all the wrong stuff again!
Can't wait for the defence investment plan on Monday (I think) to see how they plan to invest in all the wrong stuff again!
Surely not. There I was thinking the delay in publishing the Defence Investment Plan was because Treasury had sent a man from Southampton with a smart phone to see what the enemy are planning.
Thanks for the heads up on expected date. I have built a basket of mid-cap defence cos so will be keen to see how much flexibility the plan offers as we see cyber, unmanned and asymetric campaigns move up the agenda
The Treasury does not have a man in Southampton. He is working from home in Dubai because at least he can get a half decent wifi signal.
Currently I can still pick up PPHE Hotel (LON:PPH) shares at £2 this morning versus the potential offer price of £2.20. Decent risk reward given the company's major shareholders have pushed for a sale and the indicative offer is attractive.
Dear Tortoise Investor
You have the decimal point in the wrong place as the share price of PPHE is currently just over £20 versus a putative offer of £22.
Kind regards
Phillip
Apologies!
Free shares in SPACE X for Graham
I think Elon Musk should offer Graham a few free shares after reading the above flamboyant description !
I like the macro introduction which has started appearing at the top. Decent bit of narrative to start the day.
Was thinking just the same thing. Really helpful.
Insightful stuff from Graham regarding Musk's skills at 'selling a dream' to the markets. For me, such commentary is most welcome.
RE your comments on Elon Musk. The BBC series is worth watching and E4 was quite revealing.
Re Musk series, E4. It was indeed. He appears to be helping with the population growth.