Daily Stock Market Report (Thur 4th June 2026) - PMP, FLO, SPR, CMCX, AET

AI boom: Alphabet (NSQ:GOOGL) has increased the amount it is raising to spend on AI, from $80 billion to nearly $85 billion.
In total, it’s planning to spend up to $190 billion on capex this year, more than double what it spent in 2025. It plans to spend even more in 2027.
Billionaire Ray Dalio, commenting on the AI boom and the rush to sell AI-related shares, was philosophical in an interview yesterday with Bloomberg:
“All great technology changes produce bubbles. The reason they produce bubbles is that nobody can get it exactly right. You have to either spend a ton of money to capture your market share and don’t worry about whether it’s too much or not, or you don’t spend enough money and you lose your market share…”
Noting that “bubbles burst when wealth needs to be converted into money", he said that the indicators for a bubble were currently close to the levels seen in 2000 and also in 1929!
Overnight market movements:
The FTSE is set to open down 0.5% at 10,290
S&P 500 is down 0.4% at 7,530
Brent crude is down 1% at $96.35
Gold is up 0.8% at $4,470
Bitcoin is down 1.6% at $64,000
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
MITIE (LON:MTO) (£2.27bn | SR70) | Revenue +10.5%, or +5.3% organically. Operating profit before Other items up 13% to £264m. Actual operating profit £151.4m (FY25: £161.6m). Share buyback programme for FY27 of £100m. “Entering FY27 with confidence in delivering our FY25-FY27 Strategic Plan and continuing growth and margin expansion…” | ||
Great Portland Estates (LON:GPE) (£1.24bn | SR28) | GPE has secured three further lettings at City Tower, EC2, taking leasing of the recently refurbished space to 69%. | ||
CMC Markets (LON:CMCX) (£1.03bn | SR94) | Net operating income +15%. PBT +20% (£101.3m). Positive start to FY2927. Expects FY2027 net operating income to increase by at least 17% year-on-year to £460m - £480m. | AMBER/GREEN (Mark) The bottom line results look like a miss due to higher than expected costs. However, that is dwarfed by the scale of the upgrade in guidance for FY27. My calculations suggest that this is a 30%+ EPS boost. The impact of this is likely to improve both the Value and Momentum Ranks, keeping this firmly as a SuperStock. Despite this positive trend, I still see some risks around volatility normalising and unexpected cost increases. This company has a long history of large cyclical swings in response to changes in NOI and costs, and I don’t see that changing. Hence, I keep our positive view moderated by the obvious risks of investing in a highly cyclical business. | |
Guardian Metal Resources (LON:GMET) (£511m | SR29) | The Tremor Zone is a newly discovered tungsten-skarn zone at one of the Pilot Mountain Tungsten Project's priority exploration targets. The initial discovery drillhole intersected five distinct zones of tungsten-rich skarn mineralisation. | ||
Halo Minerals (LON:HALO) (£301m | SR7) | IPO completed March 2026, raising £5m. Competent Person’s Report led to an NPV10 of US$154.1 million and an IRR of 50.9% (after tax). Outlook: Focus on optimising the DFS, securing ancillary permits and progressing towards Final Investment Decision. | ||
S4 Capital (LON:SFOR) (£290m | SR96) | Full year LfL net revenue is expected to be within the current consensus range of £632m - £663m, down low single digits year-on-year. Like-for-like operational EBITDA margin targeted to increase by at least 100bps. Plans to recommend total dividends of 2.2p for 2026. | ||
Afentra (LON:AET) (£160m | SR54) | Has raised gross proceeds of $40m via a placing. The new shares represent 19.6% of existing share capital. Retail offer to be carried out separately. | AMBER/GREEN (Mark) I am a little surprised by this placing but it is well supported, at a minimal discount and with a retail offer, so I don’t judge it too harshly. | |
Springfield Properties (LON:SPR) (£112m | SR94) | Expects to report revenue of £245m and adjusted PBT in line with market expectations Net cash £1m, (significantly ahead of market expectations). | GREEN ↑ (Graham)
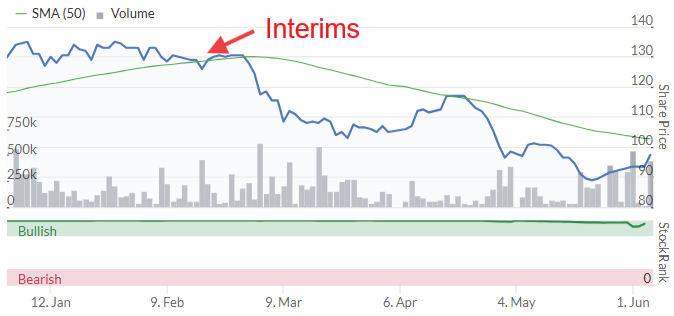
Springfield's share price has come back quite a long way since the interims, down over 20%. And yet earnings forecasts have been stable. The discount to tangible book is now over 30%. So I think this is worth an upgrade to fully GREEN today. I don’t have total conviction in the EPS forecasts, but I think the balance sheet argument is good enough at this stage. | |
Gateley (Holdings) (LON:GTLY) (£91.1m | SR50) | FY26 Revenue +7% to c.£193m. u/l Op Profit £21-22m, in line with consensus. “Whilst our Q4 experienced longer than anticipated transactional cycles as a result of the macro backdrop, we enter FY 27 with good activity levels across transactional and contentious workstreams, and we continue to see attractive mandated and pipeline opportunities across the Group's Platforms.” | ||
Jubilee Metals (LON:JLP) (£90.3m | SR28) | Roan annual maintenance shutdown completed during May 2026, with operations successfully resumed at full capacity targeting run-of-mine throughput of 30ktpm. | ||
Ondine Biomedical (LON:OBI) (£81.4m | SR14) | Revenue +29% to $2.6m, Operating Loss $30.0m (2024: $19.4m), Cash $10.6m (FY24: $9.9m) after $24m fundraise in period. Further $9.2m gross raised after period end. | ||
Aurrigo International (LON:AURR) (£66.1m | SR24) | Revenue -10% to £8.0m, Adj. LBITDA £3.0m (FY24: £1.6m LBITDA), Net Cash £11.5m (FY24: £3.1m) after £13.8m net raise in the period. “While it is early, we are seeing initial signs of stabilisation as performance improves and our actions take effect.” | ||
Premier Miton (LON:PMI) | AuM -13% over 6mo to £9.0bn. Adj. PBT -44% to £3.0m. Interim dividend -50% to 1.5p. Reg Cap Surplus £11.4m (30 Sep 2025: £11.4m). “While it is early, we are seeing initial signs of stabilisation as performance improves and our actions take effect.” | ||
Helium One Global (LON:HE1) (£54.9m | SR35) | The Operator has entered an initial 3mo helium offtake agreement with a major US industrial gases purchaser, covering early production output from the Pinon Canyon Plant. Pricing reflects current US spot markets. | ||
Flowtech Fluidpower (LON:FLO) (£41.9m | SR54) | £0.4m for Helipebs, an award-winning British market leader in the manufacture of hydraulic cylinders and hydraulic technology solutions, paid in cash. | AMBER/RED = (Mark) This deal seems just too good to be true. My suspicion is that some liabilities of the acquired company to its former holdco remain, or it is in severe financial distress, but in reality, we have no idea. In my opinion, management owes shareholders an explanation as to why this looks such a good deal. With this deal creating more questions than an initial look suggests and a significant downgrade in EPS less than 6 months ago, I am in no rush to change our broadly negative view. | |
Neo Energy Metals (LON:NEO) (£23.4m | SR23) | South African Minister of Mineral and Petroleum Resources has not yet granted approval for Phase 1 approvals. Deadlines extended by 6mo. | ||
Switch Metals (LON:SWT) (£16.4m | SR20) | Two high priority hard rock drill targets defined at Issia | ||
Portmeirion (LON:PMP) (£13m | SR50) | £17m gross raised at 50p, almost 50% discount to previous close. New shares will represent 70.8% of the enlarged share capital. “ significant confidence in the medium- and long-term prospects for the Company to create substantial value for our shareholders.” | AMBER ↑ (Mark- I hold) | |
Pennant International (LON:PEN) (£11.2m | SR23) | Auxilium Phase 3 delivers enhanced security and a better user experience. | ||
Altona Rare Earths (LON:REE) (£10.1m | SR14) | All assay results now received from the 2025 drilling campaign. Wide significant intercepts have been observed, with up to 30m at 2,677ppm HREO, and HREO/TREO ratios ranging from 21% to 77%, confirming HREE enrichment is widespread across the Fluorite Zone. |
Graham's Section
Springfield Properties (LON:SPR)
Up 4% at 97.3p (£116m) - Trading Update - Graham - GREEN ↑
This Scottish housebuilder issues a full-year update for FY May 2026.
Key points:
Revenue (£245m) and adjusted PBT in line with expectations.
Net cash £1m, significantly ahead of expectations for year-end net bank debt of £10m.
Checking my notes from February (we were AMBER/GREEN), the expectations at the time included a very large H2 weighting, with 56% of full-year revenues and 65% of full-year EBIT expected in the second half. So it’s nice to see that these forecasts were hit. They are even slightly ahead of the revenue forecast I quoted then.
As for the cash position, I personally wouldn’t read too much into this, as I expect that it’s a volatile figure from month to month. Even so, beating expectations by £11m is not a bad thing, and they’ve made enormous progress on this front: net debt was £93m in November 2023, and £40m at the interims.
SSEN Transmission: we’ve touched on this last time; Springfield has agreed to build and rent 300 homes to SSEN Transmission employees in the North of Scotland. My understanding is that these homes will later be sold.
The outlook for housing in the North of Scotland and in Scotland generally are good:
The Board remains very excited about Springfield's prospects in the North of Scotland. Forecasts for expected housing demand in the region are substantial, which the Group is well-placed to meet thanks to its strong land bank and established position as a housebuilder of scale in the area. The Group is receiving increasing interest from major infrastructure providers who are looking for solutions to their worker accommodation requirements…
Alongside this, the fundamentals of the housing market in Scotland remain strong. There is a critical undersupply of housing across all tenures and the newly formed Scottish Government has reinforced housing as a priority with £4.9bn of investment for affordable housing and £10,000 interest-free shared equity loans to First Time Buyers over the Parliamentary term.
CEO comment: he is “delighted” to have eliminated net bank debt and concludes:
"Our underlying business remains strong, with the achievement of year-on-year growth in private and affordable housing. We also continue to hold significant landholdings in areas of high demand. Accordingly, we continue to believe Springfield is well positioned for the future and we look forward to reporting on our progress."
Estimates
Many thanks to Equity Development for covering this. They have left FY27 and FY28 forecasts unchanged:
FY May 2027: revenue £220.7m, adj. PBT £13.4m
FY May 2028: revenue £206m, adj. PBT £19m
So revenue is expected to decline year-on-year, while adj. PBT continues to rise.
Graham’s view
I think the strongest argument for this share remains centred on the balance sheet. It’s not that I don’t think the earnings numbers are realistic; it’s more that they are far less certain than numbers in hand. Springfield reported tangible net assets of £167m at the interims.
The share price has come back quite a long way since then, down over 20%:
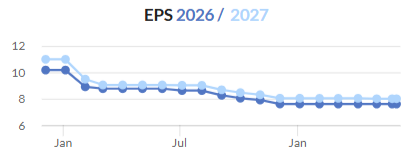
And yet earnings forecasts have been stable:
The discount to tangible book is now over 30%.
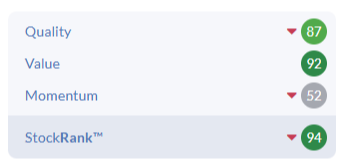
In StockRank terms, Springfield is a Super Stock that looks increasingly contrarian (i.e. weak Momentum):
Putting it all together, I think this is worth an upgrade to fully GREEN today.
I don’t have total conviction in the EPS forecasts, but I think the balance sheet argument is good enough at this stage.
Mark's Section
Portmeirion (LON:PMP)
Down 37% at 57p (£13m) - Placing - Mark (I hold) - AMBER ↑
(At the time of writing, Mark has a long position in PMP.)
When I last looked at this company, I viewed it as AMBER/RED, saying:
Perhaps most worryingly net debt is up, they say this is due to order timing (presumably customers trying to beat tariffs) but it reveals that the seasonal peak in debt will typically be after the 30 June balance sheet date here. This has required a revised RCF and that has come at the cost of higher interest, making short-term profitability a further challenge.
However, I recently bought a small position. My thesis was that it would be embarrassing for the Government to announce a package of support measures for the UK ceramics industry and then have one of the most iconic names go bust. However, I was very clear that insolvency was one of the possible outcomes, hence my position size was very small.
So while today/last night’s announcement is better than insolvency, the scale of the raise needed to rebuild the balance sheet means that the company (or probably more likely, their banks) were not willing to wait around for the details of any government support:
…it has conditionally raised gross proceeds of £17.0 million (before fees and expenses) by way of a placing of 34,000,000 ordinary shares… at a price of 50 pence…
It is clear that with a company with a market cap of £13m raising £17m (up from an initial planned £15m) would be a huge dilution. On top of this we have a £2m open offer for existing shareholders (another reason why it was worth risking a small position), making it a £19m raise.
Net debt at 31 Dec was £17.5m and we can normally expect the seasonal peak in debt to be a few £m higher. Fees on a raise of this size are typically around 5% of the amount raised, meaning the net amount is closer to £18m (assuming the open offer is fully subscribed). So we can perhaps still expect a few £m net debt after this raise.
This is what the Chair has to say about the prospects going forward:
We have an experienced senior leadership team in place led by CEO Michael Scheepers, an exciting growth plan for 2027 and beyond, a substantially strengthened financial position and a portfolio of exceptional homeware brands. This gives the Board significant confidence in the medium- and long-term prospects for the Company to create substantial value for our shareholders.
Valuation:
One of the attractions here was the asset backing, with significant inventories on the balance sheet at cost. The company doesn’t reveal their gross margin (presumably to avoid giving customers a target to aim for) so if those inventories are not obsolete, there is considerable value. Part of the failure of previous management has been being unable to reduce those inventories in the face of a downturn in demand and they took an inventory provision in the FY results.
NTAV was £36.1m excluding a probably inaccessible pension surplus, and this will be increased by the net amount of cash raised, say £18m to give a NTAV of around £54m.
There are an additional 38m shares in issue (assuming full take up of the open offer) and there was 14m prior to the raise giving 52m shares in issue. At 60p to buy the proforma market cap is £31.2m, meaning the company still trades at 0.58xTBV. Not quite as good as the 0.33x TBV pre-raise but still showing some potential value.
NTAV is meaningless unless those assets can be made productive. Current forecasts have been suspended so we can’t rely on the figures in the StockReport. However, looking at longer term history, this is a business that can deliver £5-6m PAT in the good years:
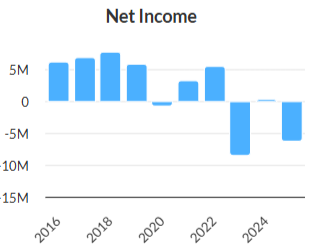
This would put the company on a P/E of 5-6, if the current Board’s “significant confidence in the medium- and long-term prospects” is not misplaced.
Mark’s view
This placing rebuilds the balance sheet, and while it comes at the cost of huge dilution, a large discount to TBV remains. The recovery may still take some time, and it would be naive to assume that they will immediately return to prior highs of profitability. However, it remains a strong brand with a long heritage and has received considerable support from new and existing shareholders in the placing. Given that the risk of short-term insolvency has been removed, and there is a potential upside if the new management can return the business to more normal profitability, I think we can risk taking a more neutral view today. AMBER
Flowtech Fluidpower (LON:FLO)
Up 8.5% at 56p (£41.9m) - Acquisition of Helipebs Controls Ltd - Mark - AMBER/RED =
This seems an exceptional deal. This is what they are getting:
Helipebs is an award-winning British market leader in the manufacture of hydraulic cylinders and hydraulic technology solutions, serving some of the world's most technically demanding industries, including energy, aerospace & defence, nuclear and industrial manufacturing….Alongside its UK-based manufacturing capabilities, Helipebs has significant engineering expertise in delivering high-quality engineered solutions to customers globally across sectors including oil & gas, sub-sea, marine, research, green energy, and defence.
And this is what they are paying:
The £0.4m consideration for the Acquisition has been financed from the Group's own cash resources. It is expected that this cost will be fully recouped from customer receipts before the end of FY26. The Acquisition is likely to lead to a bargain purchase gain for the Group, which will be reported as an exceptional item in the current financial period.
Even better:
In the remaining six months of FY26 Flowtech expects the Acquisition to contribute turnover of c.£1.5m and modest positive EBITDA to the Group. For FY27 the Acquisition is expected to deliver turnover of c.£4m and EBITDA of c.£0.5m.
Even if the numbers are relatively small at around 3% of Flowtech’s revenue, paying 0.1x Sales and less than 1xEBITDA just seems too low to me and there must be more going on.
While it is hard to be certain, a quick look at HELIPEBS CONTROLS LIMITED on companies house, shows that at 31 March 2025 they owed group undertakings £2.7m:
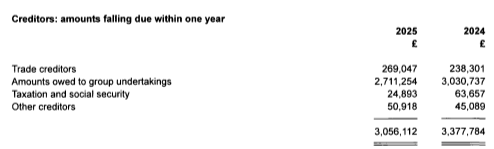
Presumably, this is HELIPEBS (HOLDINGS) LIMITED. And while we don’t have up to date accounts, it is clear that Flowtech are buying the subsidiary and not the (former) parent HoldCo and hence they may have agreed to take on some of these liabilities.
If the current financial position is similar, they are still acquiring £700k of inventories and up to £1m of net working capital. However, this just looks like too good a deal for there not to be a further element to it. No one sells a 150 year old high-tech manufacturing business with a great management team for less than 1xEBITDA and 0.1x Sales unless it is in severe financial distress, or the acquirer agrees to take on certain liabilities. In my opinion, management owes shareholders a further explanation on this, either to have given the consideration on a debt-free, cash-free basis, or explain why the seller was willing to virtually give this away.
If my suspicions are correct about there also being some former HoldCo liabilities remaining after acquisition, this turns an exceptional deal into a largely unknown deal. If Helipebs Controls Ltd still owes Helipebs (holdings) Limited £2.7m then the consideration is more like £3.1m or 6.2x EV/EBITDA.
We do know that Flowtech are paying less than Book Value as this will be a bargain purchase gain, and the acquired business had -£400k of equity at 31 March 2025, so perhaps I am completely wrong about still owing the HoldCo. But they could still owe say £1.8m to the HoldCo, and be buying £500k of TBV for £400k with a £100k bargain purchase gain.
Net off £400k cash and in this example, they would be paying a 3.6x multiple, which seems reasonable but not as amazing a deal. The reality is it could be any figure, and if they really are getting this for £0.4m on a cash-free, debt-free basis because it is in severe financial distress, why are they bigging up the management that ran it so close to insolvency?! It just raises more questions than answers.
The market liked this announcement this morning with the share price rising 8.5%. This may just be that shareholders appreciate the activity. However, I can’t help feeling that part of the rise is due to the view that the company has got an amazing deal, and the jury is still out, in my opinion. If it turns out that Flowtech has not paid just £0.4m on a cash-free, debt-free basis, this speaks to management credibility, as I start to wonder what other details are they omitting from statements?
Mark’s view
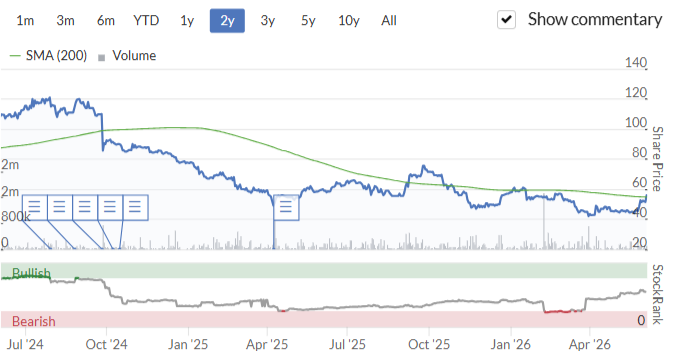
It’s been a while since we reviewed this company. Just over a year ago, Graham downgraded it to AMBER/RED as the wait for a recovery seemed interminable. Since then the share price has largely gone nowhere, although there has been a modest bounce in the last month:
In January this year, there was a placing, partly to make an acquisition and partly to rebuild the balance sheet. Combined with a warning, this led to a significant downgrade in EPS:
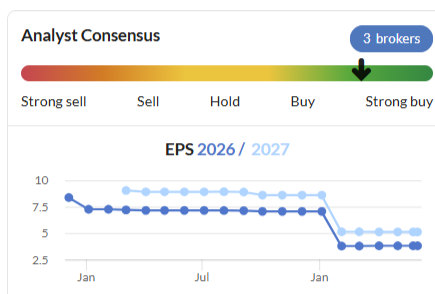
This means they don’t look particularly cheap, especially on an enterprise basis. As such, I’d want them to be exceeding expectations in their next trading update, scheduled for late July, before being willing to upgrade our view. We may even have to wait until half year results are released in September before we get the full story on this acquisition and can take a further judgment on management credibility.
CMC Markets (LON:CMCX)
Up 16% at 428p (£1.03bn) - Preliminary Results - Mark - AMBER/GREEN =
When I wrote a StockPitch article on CMC markets in March this year, I concluded that:
The FY26 setup looks compelling. Record client cash, dynamic hedging, and 24/7 trading mean CMC can capture volatility-related upside better than ever. The macro backdrop - geopolitics, policy uncertainty, AI swings - all suggest that elevated volatility will persist for some time. A largely fixed cost base means that any increase in net operating income will drop straight to the bottom line and drive significant upside beyond current guidance.
The share price at the time was 323p, so it is pleasing to see the market react positively to today’s results, taking the stock up almost 30% since I wrote the article.
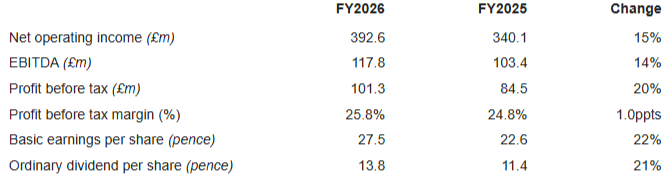
These look strong, with a significant increase in net operating income. We can’t access the broker coverage here. However, the rest of the numbers look like a miss to me. Here is the company’s own consensus from their website:
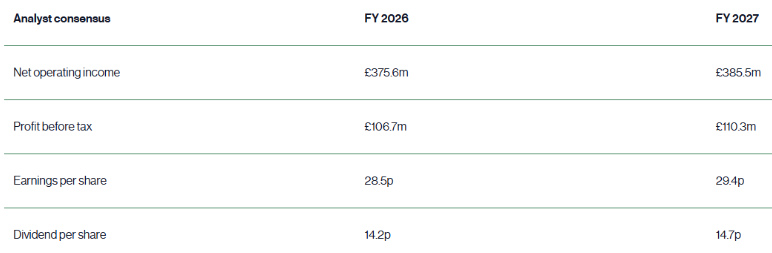
They don’t appear to have updated this since April, which means it may be somewhat stale. However, the StockReport has 28.1p EPS and 14.7p EPS in for FY26, and these results are slightly behind these.
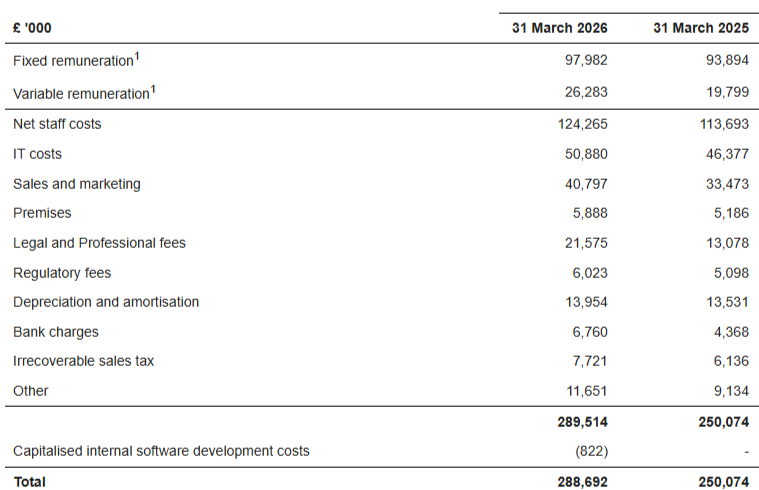
The difference will be due to higher costs, with almost every category seeing some kind of rise:
Outlook:
The market is forward looking, though, and the rise today appears to be due to a big upgrade in forward guidance:
· The Group has made a positive start to FY2027, with net operating income supported by continued momentum across institutional and B2B partnerships, an increasingly diversified product offering and sustained client activity.
· As a result, the Group expects FY2027 net operating income to increase by at least 17% year-on-year to between £460 million and £480 million, with operating costs (excluding variable remuneration) of approximately £280 million.
Net operating income guidance is 15% ahead of the current consensus on the StockReport. If we guessed that variable remuneration came in at around £30m then this would imply £310m total operating costs and £160m operating profit at the mid-point. Interest income is counted with NOI, so with finance costs of around £3m, I would estimate £157m PBT, and £116m PAT on normalised UK tax rates. This is 36% ahead of the consensus on the StockReport. You can see why the market has liked this update today.
Valuation:
If we take my £116m PAT estimate this works out to be around 42p of EPS, meaning that the company is on a relatively modest 10x forward earnings. They would normally pay out half that as dividends for a 5% forward yield. On top of this cash and cash equivalents has increased to around £276m, of which £76m is blocked, meaning that there is up to £200m of unencumbered cash on top of this. In reality, financial firms won’t run the business anywhere close the their regulatory capital limits. However, even if we assume half of this is available for distribution, this makes the P/E look even better.
Caution:
There are some reasons to remain cautious:
The current guidance will presumably be based on continued volatility and risk appetite amongst investors. This tends to be cyclical, and at some point will moderate.
The word salad continues with phrases like Web3 and Defi featuring heavily in their narrative.
IT spend may accelerate. They continue with their “SuperApp” development and the company has a slightly chequered past of delivering large IT projects. A few years ago the company increased costs significantly to develop a non-leveraged trading platform, which as far as I can tell, never delivered any usable product, at least in the UK.
News stories suggest that the company has signed a £30m deal with Everton to be their shirt sponsor, and may do a similar deal with Fullham. It is not clear how long such deals will be for and therefore the yearly cost. However, it seems that marketing spend is due to increase overall going forward.
Overall, given the above, and that they appear to have missed FY26 numbers due to higher than expected costs, I would take the guidance for declining operating costs in FY27 with a pinch of salt.
Mark’s view
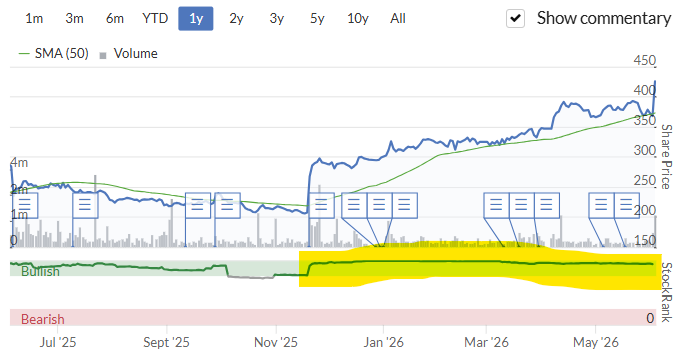
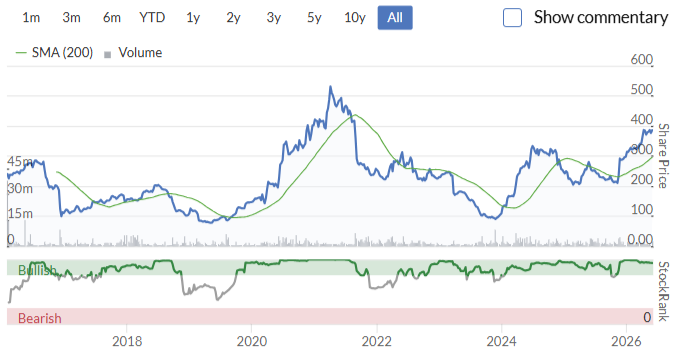
We’ve written extensively on the company on Stockopedia over the last year. However, it was last reviewed on the DSMR in November last year when I upgraded our view to AMBER/GREEN. Since then it has remained a Super Stock and has rewarded investors who have hung on for the ride:
While it remained highly-ranked overall, the lower Value Rank and declining Momentum Rank were perhaps flashing some warning signs:
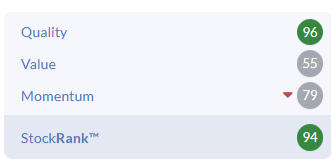
However, I expect today’s large upgrade and associated share price reaction to rejuvenate these Ranks, and confirm that we should remain positive about the prospects here. Given the scale of the upgrade, it is tempting to go fully GREEN here. However, it remains at the riskier end of investments since any reduction in volatility, or if we saw recent speculative behaviour regarding space and AI stocks abating, we would likely see NOI moderate. Combined with the possibility of increasing costs, this would mean the current positive operation gearing would go into reverse. The company has a history of facing many of these cycles in its past:
So while I don’t see signs of that moderation in the short term, I feel that our rating should still reflect that cyclical risk that will always be present. AMBER/GREEN.
Afentra (LON:AET)
Down 1% at 70p - Equity Fundraising & Retail Offer - Mark - AMBER/GREEN
I am a little surprised by this placing. When I was asked to write up a StockPitch on one of the African oil producers, I chose Afrenta, as it appears to be the pick of the bunch; cheap on current production, and with material development potential. When I wrote the article, I pointed out that they had recently refinanced their debt, saying:
Favourable refinancing: In May 2026, Afentra secured a new US$125m pre-payment facility with commodities trader Gunvor, replacing its existing Reserve-Based Lending and working capital facilities. The new facility extends the maturity profile to 2030 and pays interest at SOFR+6% (improved from SOFR+8%). It also carries a 12-month repayment grace period, giving the company the financial flexibility to fund its drilling campaign.
This is clearly a well-supported raise, with shares representing roughly 20% of the enlarged share capital issued at 67p, just a 5% discount to last night’s close. With $40m gross raised from institutions there is also a £2m retail offer which seems a reasonable compromise, to allow individual investors to avoid excessive dilution. This level is still some 50% above where they started the year.
The reason for the placing is given in the announcement yesterday evening, which is “to accelerate these growth activities and enhance strategic flexibility.” These are how they summarise those activities:
Afentra has a much larger opportunity set within its portfolio that can be accelerated to deliver growth and value accretion for its shareholders, including follow up drilling activity and workovers on Block 3/05, drilling, near-field developments and exploration on Blocks 3/05A and 3/24, and short-cycle production and significant exploration on the Company's material onshore Kwanza basin acreage;
I’m surprised that they have the ability to accelerate what already looks like a fairly tight drilling schedule, so I do wonder if they have their sights on acquiring some further assets and need the flexibility to move quickly.
Mark’s view
We’ve not reviewed this on the DSMR before. When I wrote my Stock pitch article I came away with a broadly positive view of the company. If the oil price remains around current levels, the company should be highly cash generative, and they have some great opportunities to double their WI production over the next few years. However, there are quite a few risks, from operating in Africa to the impact on the company should oil prices fall. Perhaps I should have been a little less surprised that they chose to re-inforce their balance sheet ahead of some material drilling campaigns.
Adding to the concerns, the StockRanks look middling in all respects and have been getting weaker:
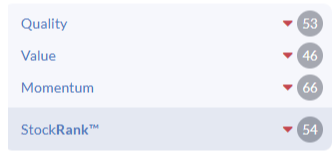
However, I think it is worth bearing in mind that if the company gets anywhere close to FY26 forecasts, all of these ranks will be materially higher. Hence, I will go for AMBER/GREEN overall, at least on a relative sector view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
It's the high cost of imported gas that has hurt the pottery industry. The more renewable generation we have, the less dependent we are on imports. We're absolutely correct to be expanding renewables as fast as we can. Both Trump and Putin have made it very clear they would like us to do otherwise. It's been a tough period for companies like Portmeirion, but ultimately the benefits of electrification to our own green energy are huge. In Spain electricity is almost free in the middle of the day now.
Just to clarify that Q1 2026 US EPS growth rate is currently at 28.5%, the highest rate since 2021. Analysts now at all major US investment banks project 2027 SP500 earnings around $400!
I do not understand why Graham Neary constantly criticises the stability of the greatest stock market in the world, or what his underlying motive is.
Haven’t we seen a 10%+ correction about two months ago?
What was the outcome of this? The US market has gone to new highs but the UK (no growth market) is still, and as always trying to catch up…….still analysing teapots…….
I believe a financial analyst/writer should be neutral, fair and well informed, providing the best possible information to his subscribers.
After all, why is Graham Neary not taking the correct steps and approach to protect his subscribers, given that a US market crash/collapse would this time completely finish off the UK market ?
All the best
Ref us - i think its fairly clear US is not a top speciality of commentators here as things stand - you might not like it but the writers here can have their own opinions all we ask is if they have an interest in a share that it is disclosed closed. I do get your point but reality is we cant dictate what the team do here - overall Graham does a fantastic job so where i disagree i choose to do so politely rather than demand he be a different person.
I dont think this is a site that is trying to guide people down any particular path too - its a site to provide infromation for people top judge - note most of the main popular mechanical portfolios using the tools here sem to outperform their sector segment too.
thats why comments section slike this exist - and are uber userful here - if soemone has even slightly jaundiced viewpoint here - good news is that normally someone wil come along and add some comment.
On numerous occasions I have emphasised that Graham analyses UK stocks in an extreme thorough but most importantly honest way and urged him to concentrate on what he is doing best.
He can have any opinion he wants, like everyone else does. This is not the point. I have given numbers and have explained my concerns. Read them again if you have time and the numbers I have provided.
He keeps talking about a US crash, mentioning 1929 and 2000……..so he believes that the UK market will be destroyed as well!
Read again please my thoughts and don’t just write things like I am demanding Graham to be a different person???
And yes I do believe that there is an agenda here. No need to continue this conversation.
All the best
happy to disagree here - it did come across to me as if you were actively wanting Graham to say something different to what he belives - apologies if i got the wrong end of the stick there. As ever with online posts its easy to read something in amanner that it was not intended to be.
ref agenda - i well i dont believe there is here - if nothing else compare to most other sites on the net i have always found the comments by paid for contributors to be free of any ulterior motives or agenda - who knows though.
Thanks and yes most of the times online posts are misinterpreted.
All the best
Castings (LON:CGS) up 20% on no news - seems to have come out the blue with no known cause?
Castings (LON:CGS) FY numbers due on 17/6 but looking at the volume today it is more likely to be a bid rumour, unfortunately I missed this one :-(( . Good spot Ben.
Reading down a list of reduced percentages in my daily investment list today, while only missing a couple thousand £ from yesterday's total invested figure, made me very grateful indeed for the quality of the recent daily reports I have read encouraging me to hold on SRB and an excellent article which introduced and encouraged me to take a good position in CMC markets a couple of months ago. With accurate analysis like these available it is obvious to me as an existing customer that my best investment each year starts with my Stockopedia subscription. Great work, much appreciated.
Just noticed the price of Portmeirion (LON:PMP)!
I will never forget the post from BnB, probably about 2 years ago, on Portmeirion (LON:PMP) that was covered all the time: ‘The world is experiencing a global shift towards AI and data centres and we are still talking about teapots!’
Something on those lines……
All the best
Seraphim Space Investment Trust (LON:SSIT) what is happening with this, the share price is down to 180p now.
Also Filtronic (LON:FTC) has fallen back considerably.
They announced results this week. From memory the NAV is up 34% to 177p. It was trading at a massive premium and the price has reverted to NAV.
Time to top up
Hmmmm... I added a final line to that message saying that 'I hold SSIT', but it doesn't appear to have made it to the final cut...
Seraphim Space Investment Trust (LON:SSIT) better to travel than arrive. SpaceX IPO - just had the invite to invest £500 to £1m. I can't believe retail investors are allowed to invest £1m. No thank you. Great company. Hot air valuation!
Capital Gearing Trust (LON:CGT) final results today. A fantastic investment trust for wealth preservation if anyone is interested. Good for cCPI+2% long-term in my view with very low volatility. Better than holding gilts or cash for the safe part of your portfolio. Quite attractive as inflation surges again!
thanks Topvest, sort of thing I'm looking at for a proportion of my ISA
Anyone any idea why Volex (LON:VLX) is down nearly 6% on no apparent news?
I hold.
Richard
No obvious reason or news why VLX is down sharply today, but I'm not that surprised. It's risen sharply over the recent past, still up around 50% on 3 months ago, partly encouraged by the planned move to the main market, and hopes of more institutional interest, including from the US. I considered top slicing at around 700, as a pull back seemed likely, but I didn't, and remain happy overall. a lot of shareholders must be sitting on useful gains here, and profit taking seems unsurprising. My money remains on it moving up further, though recent rates of rise are clearly unsustainable.
Volex (LON:VLX)
share price is exactly where is was 2-3 weeks ago on no news - if there has been no news should you not be questioning why is spiked up in price in teh fisrt place rather than why it is back where it was on the same news?
If you my a guess then i would say natural variability - its uber common for share to trend upwards - then when that trend stops it gives back some or all of the gains. If its a common stop loss level below recentnhighs then perhaps its market makers making an easy buck timing them out - that perhaps me getting into territory of conspiracy theories that are perhaps best ignored.
The US AI stocks took a hammering yesterday. May be linked to that.
Slightly surprised by the market response to S4 Capital (LON:SFOR) results. I read them as reasonable, and expected the announced dividend to be price-supportive.
S4 Capital (LON:SFOR)
i have always thought this one had the potential to bounceback - there must have ben some logic to the high historical valuations existing.
At face value the trend in forecasts and what the company says about net debt looks uber promising.
Perhaps itys what they havent said that matters - are any broker updates likely to be adjusted downwards rather than upwards ?
the reuters tidbit mentions slwo revenue growth - ref sales they said they are on target.
ref 2027 at least there has been reecnt uptick ref expectations after constant lowering - so if there are no broker nasties today perhaps the kneejerk reaction here is just random movement - sell on the update perhaps if they were expecting more chipper news ?
I rather agree rmillareethans (re: S4 Capital (LON:SFOR) and think the fall after today's trading update is likely to represent shorter-term traders getting out, having hoped for better.
Portmeirion (LON:PMP) They had a big fund raising in 2020. How many years until the next one ? It looks like the shareholders are keeping the lights on.
Portmeirion (LON:PMP) - It would make a lot of sense if they can purchase the assets of Denby. Is this connected with the fundraising I wonder?
Denby's been bought out by Home Bargains.
In terms of style, the two are not quite competitors, even though they aim for the same mid-upper class.
Denby is probably going to ditch their UK manufacturing, outsource everything to China, and the brand equity is going to be milked for all its worth selling Chinese-made dinnerware but with a heritage English brand label still on.
Nothing wrong with the quality of Chinese-made dinnerware btw.... the Chinese themselves use loads of it domestically, and they supply the world with it too.
Portmeirion (LON:PMP) - Home Bargains are only 1 of the bidders...let's see who wins!
Crazy how cheap acquisitions can be in the industrial sector.
Flowtech Fluidpower (LON:FLO) announces a bolt-on acquisition. £400k acquisition cost. Net assets worth more than that they are implying, so they'll realise and exceptional gain in the P&L this year. AND expect £500k EBITDA profits on £4m revenues run-rate going forwards.
The cynical view is... the leader (who is probably majority shareholder) is staying on. Maybe she's getting a huge package. So her total "return" from the sale might be much higher, when you add her golden handcuffs comp for the next few years.
(I hold in the Boon Fund)
Flowtech Fluidpower (LON:FLO)
The Boon Fund - be careful who you slander - check facts first. FLO is taking on the business and assets of Helipebs Controls Ltd. That company is 100% owned by Helipebs Holdings Ltd. which at the last report (10/9/25) had 57 shareholders none of which was Mrs. Victoria Hayward.
I stand corrected! Good sleuthing.
Not a big fan of Ray Dalio, hes been predicting market crashes for decades and got it right once, watched a you tube video about him a few days ago, he was shown in a very poor light.
Dalio got a huge call on the GFC crash right which made his name then just grew rich on fees while delivering unremarkable investment returns. Yet another big name who got lucky rather than consistent outperformance over decades.
In nigh over 25 investing in the markets I don't think I've seen one single headline/video with him saying "now's a great time to buy"
Sounds like "Crispin Odey’s hedge fund career was defined by extreme volatility. While he correctly predicted the 2008 financial crash and made massive profits, his flagship fund suffered prolonged underperformance for years, driven by dogged bearish bets against global equities and poorly timed market calls."
There are not many, if any, who get both 'bearish' and 'bullish' calls correct, especially those that have made big money from a bearish call. They are always looking FOR the downside rather than THROUGH it.
This site is still playing up, in fact, it is worse today, can hardly read any posts, before it jumps to top of the page.
No site problems for me using my iPhone
Just not me then, using Android phone.
I'm using an iPad.
HgCapital Trust (LON:HGT)HgCapital Trust plc has announced that its manager, Hg, intends to increase its ownership stake in HGT from about 6% to more than 15% by buying shares in the market. This is a very confident move and I will be adding as a result of this announcement.
It looks good value, they have consistently been saying AI is an opportunity for portfolio companies not a problem. But the market appears to think software companies are going to suffer. I hold and have bought more over the last few months.
I'm in the industrial computing industry and used to think AI was a bit of nonsense for generating text and fake videos. Yesterday, we were missing the package we normally use for converting a text file from a system into a usable excel database. (its was left at home). My colleague described what we wanted into copilot and within 5mins we had powershell script that worked perfectly...terrifying. Admittingly, the task was relatively simple and the description of the requirements was comprehensive - you needed understanding to write into co-pilot but definatly job threatening...
Could be job threatening- though I recall over they years many innovations were job threatening. What happened to the typist pool, printer's blocks etc. But HGT argue not threatening to software companies.
I think the type of software company is key - AI will be good for more generic software, but HGT say they focus on mission-critical, deeply-embedded software that would be very difficult for AI to replicate. It would require in-depth knowledge of a specific industry and vast proprietary data - AI tools simply wouldn't have access to this.
It's the portfolio companies applying AI to the proprietary d/bs to improve the value of their products.
Definitely a threat. But so was the industrial revolution. Jobs will be lost but new jobs will be created. Gen Z and Gen Alpha will figure it out.
I see CMC Markets (LON:CMCX) are currently up 14% after excellent results.
lovely dividend increase as well!
The forward guidance is well above consensus.
As CMC Markets (LON:CMCX) is one of the biggest movers of the day today, any chance that we could get some expanded thoughts from the Stocko team ?
We opened a starter position in Springfield Properties in March after Roland highlighted them, we increased our holding this morning after reading their TU when I saw it on today's agenda and look forward to comments from the team and subscribers. As previous Portmeirion holders I note Lord Gnome's comment and as a bottom fisher wondering about diving in.
Hi JASVFS - I too was tempted earlier in the year - on the face of it a good story for growth but the financial complexities of their business is complicated and I held back - so will be interested to hear Graham / Roland's update
I almost thought of selling CMC Markets (LON:CMCX) after this mornings update as on here its showing the price is marginally down ..until i checked my trading account and saw its up 16% this morning. why are stocko prices not being updated? this was at 8.29am. this really isnt good enough. i just refreshed and is showing now so appears to be some delay
Hi Shark
Do not rely on prices on here (especially at the open). They are 30 min delayed I believe. Use Trading view if you want up to the minute prices (costs £6 per month per market on top of subscription).
All indicators for CMC Markets (LON:CMCX) are looking positive and it featured as one of Stocko's top prospects for the year. If they deliver then CMC Markets (LON:CMCX) is heading to a new ATH IMO. I added on the recent consolidation and is my largest holding at present.
thanks for the advice Revs8. Trading view looks good. will look into it. yeah i bought cmcx in january. prospects are looking good and looking to topup when the price settles
Looks like an inverted head and shoulders and has broken the yellow neckline recently which suggests more upside target being the measurement from the neckline to the head projected to the upside over a similar time frame.
Indeed. The dotted line at the top.
Anewfn also free up to date prices
I use IG Index Charts
I have raised the possibility of getting real time pricing on here before - my understanding is that it is expensive and would require a much higher subscription price. Basically don't look at the prices on here till at least 8.30. Google still seems to use real time pricing so that's the easiest source for me.
Big fundraising from Portmeirion (LON:PMP) announced today. Sorting out their horrendous balance sheet . The government is finally waking up to the terminal damage done to the British pottery industry by Milliband’s net zero fanaticism and has announced a package of measures to support it. This fundraising is well timed and probably no coincidence. I’m interested, having lived and worked in the area. I’d be interested to get your take, Graham.
Portmeirion (LON:PMP)
thats how to destroy the cash of loyal long serving shareholders - piss all the money you have up the wall and when the shareprice is in the gutter issue a boatload of new shares.
I have some sympathy for the company with the industry they are in a must admit - but its basic comon sense that if you are selling £80 mill per year very year - you really need to ensure your cashflow is positive not negative. Perhaps those that stump up the cash will reap the rewards - but the upside is hugely more limited now - and current holders have been completely shafted by the way they have gone about it - presumbaly they couldnt get any funds at anything like market price.
Its probbaly even more a slap in the face doing it directly after the government has announced funding. Hey ho any sensible shareholder should probably have departed the building a long time ago. It is uber frustrating with shares that can make decent profits in good year - but ihjn bad year they seem to have zero control over cashflow.
At Mello yesterday, Lord Lee revealed that he has taken part in the placing.
Very shocking though that the placing price at Portmeirion (LON:PMP) was at 50p, compared to the 90p+ it was trading at. But then again, the new shares are going to make up 70% of the total shares after admission.... so a very hugely dilutive placing.
Portmeirion (LON:PMP)
Very shocking though that the placing price at Portmeirion (LON:PMP) was at 50p, compared to the 90p+ it was trading at. But then again, the new shares are going to make up 70% of the total shares after admission.... so a very hugely dilutive placing.
this is the core danger of holding onto shares that are sliding down on price - and teh bad news its quite up with the share price slide - if they could only geta deal done at 50% of te curent value the reality is that might have been a "good deal" the alternative might have been shareholder wipout. As soon as theer are any issues ref solvency then it kinda turns into a binary bet and people need to be prepared to have their pants pulled down if they are holding. Note sometimes taking ten risk can pay off - card factory back in the day played harball ref refinancing their debt and avoided mass dilution - saga seemed to have dodged a bullet with a dramatic rise in sharepirce to the extent riaising funds to pay down debt perhaps even makes sense. So being in it can bring multiple x rewards when the issues go away - but the plain facts are as market cap drops dilution can destroy existing investments and prior holders can be royally shafted compared to those who sold the day before and buy back in immediately after the bad news is released.
So imho i think theer was perhaps scope for current situation being avoided here - but there was alwasy a chance it would be thus so - often directors dont care one jot about other shareholders - when a deal like this is a done deal well its probably impossible for shareholders to rejeect it even if they wanted to (perhaps they had enough approval to rubber stamp)
If you dont want to lose your shirt staying away from companies like this is the obvious route - howver i suspect here many may already have lost most of their shirt anyway with this company.
Portmeirion (LON:PMP) another lost cause me thinks. Trying to compete with made in China household consumer goods is a sure fire way to lose money. Chinese consumers are no longer easily impressed by western brands and increasing buying their own unless it is genuinely high luxury.
Congratulations to all at Cordiant Digital Infrastructure (LON:CORD) today on their inclusion in the FTSE250 index. A great achievement and a great growth story. I hold.
In stark contrast to the other play in the sector Digital 9 Infrastructure (LON:DGI9) !!
Thanks for the current AI commentary, Graham. It's all very interesting.
I wonder if the mega-caps themselves have FOMO wrt AI. Quite possibly they will overbuild.
Here's the thing: will AI ever be a reliable technology? In the past, we've had planes, trains, semiconductors and the internet. These things actually worked. There was a "right" and "wrong" answer. Even with rockets, there's a definitive answer to whether they work or not. But with AI, who's to say?
In the past, we've had planes, trains, semiconductors and the internet. These things actually worked. There was a "right" and "wrong" answer.
While they were being developed there were horrendous failures with all of those. No new technology comes out of the box fully formed.
timarr
So true Timarr.
Exactly.
For an example.... does anyone remember betamax and zip drives? They did work and have benefits. But were soon superseded by other technologies.
Both were seen as the leading standard for storage at their respective times.... I remember zip drives (was the company called Omega?) saw their shareprice surge to highs.
We're all assuming that the current type of AI, called Generative Pre-Transformer (GPT) will be the dominant AI technology. But there are other (current theoretical) ways to "do" AI.
Anyone remember an old investor fave Torotrak that was going to revolutionize gearbox transmission.
remember it well ...
All too well!
While they were being developed there were horrendous failures with all of those. No new technology comes out of the box fully formed.
I'm aware of that. Let me restate. Rockets are a hard science, we can measure them objectively. AI is in the realm of a soft science, the answers they give are (mostly) subjective.
I wonder if the mega-caps themselves have FOMO wrt AI. Quite possibly they will overbuild.
i think they have been between a rock and a hardplace at present - if others are throwing the kitchen sink and more with regard to "new ways of doing everything" - can you stand aside and say - well we think thats likely to be wasted money ? not sure why nokia didnt do excat copy of the ihone as soon as it was released - saying they would probably be ok probably ended their business model.
Perhaps reality is starting to dawn perhaps though that once the money has ben spent - they do need to show that ongoing spend is paying for itself - i read at tehn weekened (on ticktock so could be false) - that companies like microsoft were limiting token spend on ai as staff were spending more than their annual salary - clearly if you need to spend same on ai as you are paying staff member they need to produce multiples of prior output.
I kinda guess it will slightly die down - and we will be left with ten current trend that AI is gradually taking over many tasks - timelines perhaps are accelerated compared to but imho very similar to personal computers and the internet - one just has to adjust to teh new way of how it will be in the future.
These things actually worked. There was a "right" and "wrong" answer. Even with rockets, there's a definitive answer to whether they work or not. But with AI, who's to say?
AI is in its infancy - one thing is over time AI shoudl be decently positioned to fact check stuff - the reality here is that us plebs piggybacking on free or cheap chat gpt or copilot - are probably getting a fraction of what you could get if you allocated resources to your problem. At worst AI should in time be able to give a yes no grey area. Those expecting the correct answer when they are not paying for it - and its still in its infancy are missing the reality of where we are - that very much doesnt mean its not coming. AI does have agood rationale argument at times based on limited data - it probably does a better job than our trainees who have been on the job for 2-3 years. Yes it gets stupid stuff wrong - but on complex areass it can put up som real useful info for me to digest (and fact check)
AI is in the early stages, however, I probably use it everyday.
I used to wait days/weeks for a programmer to write me some code, now I have it written within minutes, and "working together" with AI, within a couple of hours we have ironed all the bugs out of it.
Whether they can monetise it enough to make a profit is another question.
I have found AI very useful in my work. I use paid-for versions of three AI programs, ChatGPT, Claude and Gemini. They each have their strengths and weaknesses, and sometimes each makes mistakes, but using one AI to check the answers of another is a good way to spot mistakes.
I think we are in a bubble. There is massive infrastructure spend to support the requirements of today’s LLMs. Nvidia is lending money to companies to buy their product. But technology always gets smaller and cheaper. At some point LLMs will require less power. Remember DeepSeek. The promise of LLM on a laptop. Nvidia dropped 17% on one press release. Seeing large companies bounce up to 20% in a week and looking at parabolic share price graphs, it does have the feel of Wile Coyote running over the cliff, arms and legs still pumping. When does he look down? I don’t know when, but there is always a when.
But it's not the Dotcom bubble. The path to monetisation has already been shown. Tokens. Slowly free use of LLMs will disappear and we’ll have to pay. This will introduce the adverts, airline style pricing, surge pricing, middlemen offering cheap tokens, offers to switch AI provider with a special deal and eventually the government implementing a token cost cap to help “hardworking British families”.
I’m 15% in Tech and 15% in cash. 70% in “normal” stuff, Investment Trusts, ETFs, UK stocks. The ultimate barbell? One thing that really resonated with me is the advice from Ken Mitchell, of this parish, who says buy good companies at low prices. It sounds simple but I find that hard to do. So during the next panic it will be good quality, dividend paying companies with a decent StockRank for me. No AIM shiny shiny story stocks… Well maybe just the one. That can’t hurt can it?