Daily Stock Market Report (Thur 6 Feb 2025) - WOSG, TPX, W7L, TBLD, SRC, BBGI, ANX, BAB, CPG

Good morning!
12.45pm: that's all for today, thanks!
Spreadsheet accompanying this report (last updated to: 23rd Jan 2025)
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| AstraZeneca (LON:AZN) (£173bn) | Final Results | Rev +18%, Core EPS +13%. FY25 guidance: Rev + high single-digit %, Core EPS + low double-digit %. | |
Compass (LON:CPG) (£47.4bn) | TU | Q1 organic rev +9.2%. Organic growth drivers in line with exps. 2025 guidance unchanged. | AMBER/RED (Graham) I don't think it makes sense to pay a PER of 25x for a caterer even if it is performing well and expected to grow profits at c. 10% p.a. for the next few years. |
Anglo American (LON:AAL) (£28.3bn) | Production Report Q4 | Production guidance delivered. Forward guidance is unchanged in copper, reduced for diamonds. | |
Babcock International (LON:BAB) (£2.7bn) | Q3 TU | Revenue & underlying operating profit to exceed top end of the range. Revenue c. £4.9bn. | AMBER (Graham) A very pleasant trading update and it's not due to success in just one area but in multiple areas, which makes it even better. I think BAB is fairly valued here. |
Watches of Switzerland (LON:WOSG) (£1.3bn) | Q3 TU | In line. Confident in delivering guidance. Refinanced term loan in December, new £150m facility. | AMBER/GREEN (Graham) |
| BBGI Global Infrastructure SA (LON:BBGI) (£870m) | Rec. Cash Offer | 147.5p in cash, 21% Premium | PINK (Mark) |
Sigmaroc (LON:SRC) (£785m) | Secondary Placing | 15.4% of shares sold via bookbuild at 67p | AMBER (Mark) |
Warpaint London (LON:W7L) (£425m) | TU | FY 24 Rev +14% to £102m, PBT +33% to £24m. January Rev +15% | AMBER/GREEN (Mark) |
| Spectra Systems (LON:SPSY) (£104m) | New Security Printing Postal Contract | 5-year contract to produce postage stamps for a new EU customer. $3- $4m value. | Graham's view: This is a “Reach” announcement, so it’s not material. |
Anexo (LON:ANX) (£77m) | TU | In line. Potential settlement of claims against vehicle manufacturers to enhance profits. | RED (Mark) |
Tpximpact Holdings (LON:TPX) (£30m) | Q3 TU | Q3 In line. FY warning: Rev. down 8-10% vs FY24, adj. EBITDA slightly up on FY24. |
AMBER (Mark) |
tinyBuild (LON:TBLD) (£25m) | TU | Rev, adj. EBITDA “broadly in line”. Current trading remains difficult. Cash to trough in summer. | RED (Graham) Tough conditions in the video game industry, and TBLD hasn't helped itself by running its cash balance low for the second time in two years. |
Graham's Section
Watches of Switzerland (LON:WOSG)
Up 1% to 562.5p (£1.35bn) - Q3 FY25 Trading Update - Graham - AMBER/GREEN
The market was very pleased with the “in line” update issued by WOSG in December.
Today we have another in line update that leaves guidance unchanged.
Market conditions are supportive:
Over the period, we have seen further stabilisation of the UK market in both luxury watches and jewellery, while the US market has seen continued momentum
Watch revenue was down 2% in H1, so hopefully we’ll see something better than that for the full year?
The company has made some acquisitions which are boosting total revenues. As usual, I’ll place more emphasis on organic numbers when we get more details.
In store news, a new flagship Rolex boutique is set to open in March in Old Bond Street, London.
Refinancing: a $115m term loan (set up to fund the acquisition of Roberto Coin in the United States) has been replaced by a £150m facility.
Outlook: “confident in delivering our FY25 guidance”.
Graham’s view
I’ve been moderately positive on this one for a while - the best part of a year. It’s a stock that makes me nervous, as I worry about the fundamental quality of a retailer that doesn’t own any of the IP it sells. Let’s call this the Currys (LON:CURY) of the jewellery industry.
However, like Currys, WOSG also appears to have its house in order. It has US-based growth opportunities, solid backing from lenders in relation to the acquisition of Roberto Coin, and a valuation at c. 560p that isn’t overly stretching.
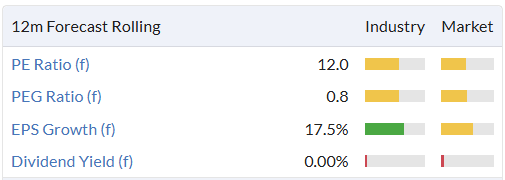
It’s not the highest-quality business that we cover in this report, nor the most exciting, but I think I can leave my moderately positive stance unchanged.
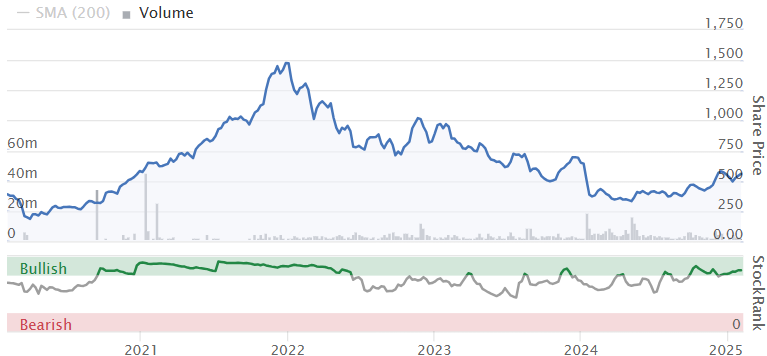
It has survived a boom and bust in the secondary watch market, and is forecast to generate almost as much profit this year (c. £96m) as it did in FY2022 (£101m). The share price is still only about half the price now as it was back then:
tinyBuild (LON:TBLD)
Unch. at 6p (£25m) - Pre-Close Trading Update - Graham - RED
tinyBuild (AIM:TBLD), a premium video games publisher and developer with global operations, is pleased to provide a trading update for the twelve months ended 31 December 2024 ("FY 2024").
This is not quite in line, but it’s close - “broadly in line” for 2024.
According to a note published by Progressive in December, they estimated revenues of £35.3m and adj. EBITDA of minus £4.4m for FY Dec 2024.
These were downgraded expectations on the basis of delays to game publication by TBLD but I note that there was no official RNS from TBLD in December. I'm quite amazed by that actually - let me reiterate that there were very large downgrades at Progressive (who are paid by TBLD to cover them), but there was no accompanying RNS from the company. Profit forecasts for 2024 were reduced by nearly £5m.
Turning back to the present, the cash position doesn’t sound very good: “Cash and cash equivalents of low single digit millions at the end of December 2024”, with this expected to reach a trough in the summer of 2025 and improve thereafter following the launch of certain new games.
For context, the last time I covered TBLD was in Dec 2023 when it issued a profit warning after it had burned through nearly $50m of cash in two years. Shortly afterwards, it raised $11m (net) in a placing.
By the time it raised money in that placing, its cash balance had fallen to $2.5m (as of Dec 2023), and perhaps fell lower again before the funds from the placing were received.
And now here we are a year later, with cash back in the low single digit millions. There is a pattern of TBLD running on fumes when it comes to its cash balance, but hoping to fill up again when games are published.
I understand that game development has to be paid for first, before any revenues can be generated. I just think it’s very unfortunate that the company started with such a cash-rich position a few years ago, and then ended up having to dilute shareholders. TBLD’s share count nearly doubled last year, which might have been avoided if the company hadn’t spent so aggressively during the previous two years.
And how can we rest assured that further dilution won’t be necessary?
This appears to suggest that IP could be sold off to avoid further equity dilution:
The cash position will be carefully managed as the Company invests in upcoming game releases in a disciplined manner. The Company has no borrowings and it continues to assess its IP portfolio for strategic opportunities.
Pipeline: some game launches are coming up, with the potential to convert into revenue. One of them is in the top 20 on the Steam platform, in terms of user wishlists.
Outlook: in line for 2025.
Again turning to that note published by Progressive, for 2025 they forecasted revenues of £36.8m, adj. EBITDA of 2.2m, and an adjusted pre-tax loss of £3.3m.
Graham’s view
It might be harsh but I’m inclined to leave this on RED, as I did back in Dec 2023.
The limited cash balance, the delays affecting game publication (and associated downgrades to estimates), and the warning that cash will not trough until Summer 2025 - these do not fill me with confidence.
Yes, the shares are very cheap when measured using something like Price/Sales. Video games companies should trade at a strong P/S multiple, not at less than 1x as TBLD does. But TBLD burned through its cash when it was cash-rich (under existing management), and now I think investors might need to worry about the potential for another fundraising, if things don’t go as planned in 2025.
Checking the most recent balance sheet (June 2024), I note that the company said it had a “significant net asset position” of $70m and that there was no problem in terms of the going concern assumption.
However, $70m was its gross asset position, not its net asset position. Its net asset position was $53m, and of that $49m was intangibles. This figure is largely made up of money that has been spent on game development relating to future title launches. So really, this balance sheet is not as solid as the company made it out to be - it is built on the hope of future success.
I wish the company well and I note that the founder-CEO is well-aligned with a 20% shareholding. But I view this share as excessively risky and not offering a solid investment opportunity.
Babcock International (LON:BAB)
Up 10% to 598.9p (£3.03bn) - Q3 trading update - Graham - AMBER
This engineering services group issues a positive update that’s ahead of expectations. Q3 is now over and the company’s financial year-end is approaching in March.
The majority of revenue for the year is now under contract and, having reviewed the delivery forecast for the remainder of the year, the Board now expects both revenue and underlying operating profit to exceed the top end of the range of analyst expectations. Accordingly, we are upgrading our expectations for FY25 to c.£4.9 billion of revenue, with the expected overperformance due to double-digit organic growth in Nuclear and strong growth in Marine.
Prior analyst expectations are given as £4.51 - 4.78bn of revenue and £327.1 - 339.7m of underlying operating profit.
So this is a very pleasant beat: revenues are 2.5% higher than the highest estimate that was published by analysts, and nearly 9% higher than the lowest estimate.
The strong performance is attributed to various factors, from increased nuclear submarine support activity, to the ramp-up of Skynet (the MOD’s military satellite communications system).
The CEO says “our engineering skills and know-how are in ever greater demand”.
A new contract is mentioned: a 17-year, up to €800m agreement to provide military air training for France (the Air and Space Force, and the Navy). It is described as “a significant expansion of our military activity in France, one of our focus countries”.
If the contract reaches its full potential of €800m and was spread evenly over 17 years, that would amount to €47m of additional revenue p.a. But hopefully there is some front loading to these revenues?
Graham’s view - I think this is fairly valued here. It looks to be trading at around 11x underlying earnings, if you calculate earnings by applying a tax rate to a new, higher underlying operating profit estimate (e.g. apply 25% tax to a profit estimate of c. £350m, to get a rough idea).
The StockReport calculates a PER of 11x based on the date prior to this update:
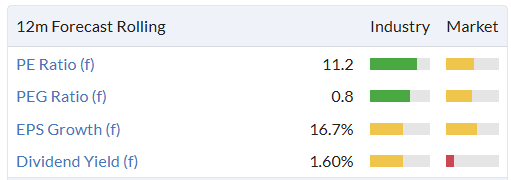
And on that basis, the StockReport finds a ValueRank of 40, i.e. below-average value.
I agree that it’s perhaps a little expensive, but BAB can probably justify that based on its strong trading momentum and its association with landmark projects such as Skynet. My guess is that a neutral stance is fair.
Compass (LON:CPG)
Down 1% to £27.62 ($58bn) - Trading Statement - Graham - AMBER/RED
Another brief trading update from an even larger company. Compass is in the top 15 companies listed in London, according to market cap.
Its year-end is in September, so this is a Q1 trading update for Dec 2024.
Guidance for 2025 is unchanged:
The Group delivered strong organic revenue growth of 9.2% in the first quarter. All regions and sectors performed well, with positive outsourcing trends continuing to underpin our growth momentum. Organic growth drivers were in line with our expectations, with net new business supported by strong client retention, and pricing and volumes trending as anticipated.
Growth was led by North America:
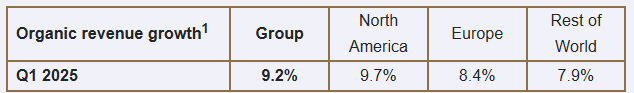
Expected organic revenue growth for the year is “above 7.5%”, and CPG has beaten that with some room to spare in Q1.
Similarly, underlying operating profits are expected to grow at “high single digit” rates. That will be growth vs. last year’s result of $3.0bn. So this metric should get to somewhere in the region of $3.2bn this year.
FX headwind: expected revenues for 2025 are some $45 billion, so investors will look past the current FX headwind of $558m.
Graham’s view
I’m afraid I don’t understand this valuation.
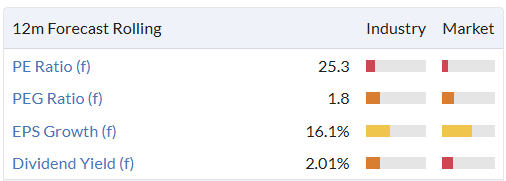
There is a trend of office workers gradually returning to work, perhaps that is the play here?
Even so, I can’t get behind paying 25x earnings for a caterer.
Forecasts for the next few years are positive (up to c. 10% profit growth for the next few years) but even so, there must be much better opportunities than this.
And there is no net cash position to fall back on to help support the valuation; it has a leverage multiple of about 1.3x.
I think I must lean towards a negative view on this one, consistent with the StockRank:
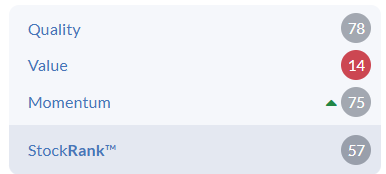
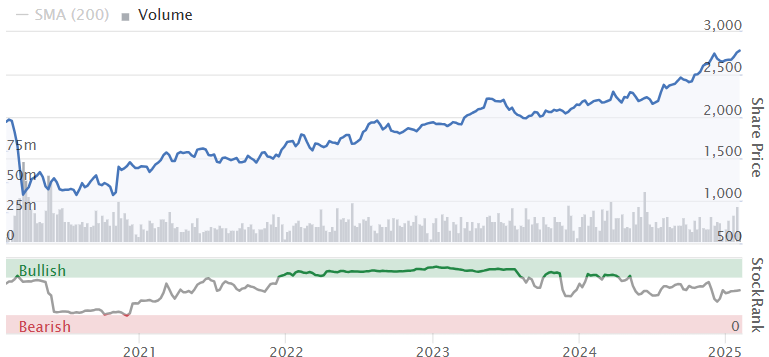
The stock’s positive momentum has been amazing in recent years - and I fear it has been overcooked.
Mark's Section
Tpximpact Holdings (LON:TPX)
Down 19% to 26p - Q3 Trading Update & Revised Outlook - Mark - AMBER
When I last looked at TPX following their Interim Results, they said
No change in FY25 targets: flat revenue growth for the year and Adjusted EBITDA in the range of £7-£8 million, and net debt of around 1x EBITDA
So it is good news that Q3 trading is said to be in line here:
The Board confirms that Q3 trading met management expectations, with profitability and margins aligning with the Company's forecasts. In the first nine months of the year, new business secured totalled approximately £65 million, including approximately £30 million in Q3.
However, the inclusion of the words “revised outlook” in the RNS title reveals that this isn’t, in fact, going to be good news for the outlook:
Management's expectations are that revenues for FY25 will decline 8-10% on the prior year.
Revenues were forecast to be flat year-on-year, so this is a reasonably large miss this late in the year. Blame is put on delays in procurement of large government digital transformation programmes due to a delayed spending review. There is some mitigation on margins:
Adjusted EBITDA margins for the Group are expected to improve by 1-2% year-on-year, as a result of reorganisation actions taken earlier in FY25, and should result in an improvement in Adjusted EBITDA compared to the prior year.
This is also not a one-off, with 2026 also coming in below previous expectations:
We anticipate our final budget will show revenue growth at the lower end of our previous guidance of 10-15% growth in FY26. We also anticipate continued year-on-year Adjusted EBITDA margin progression of 1-3%, noting the 1% headwind of increased employer National Insurance Contribution rates may lead us to the lower end of this range.
This gives me enough detail to calculate the likely impact of these guidance changes on Adj. EBITDA:
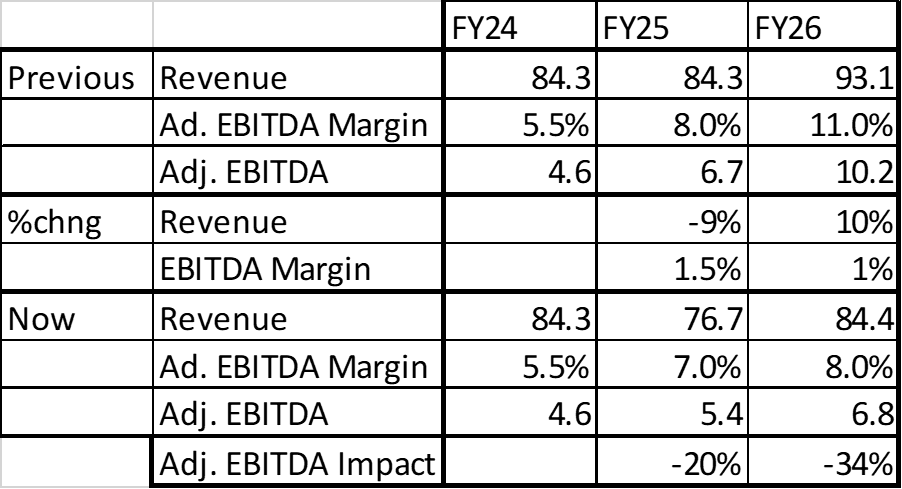
So, this is a major impact, especially on FY26 numbers. I can also estimate EV/EBITDA, taking the midpoint of their leverage guidance, which works out to be £9m net debt:
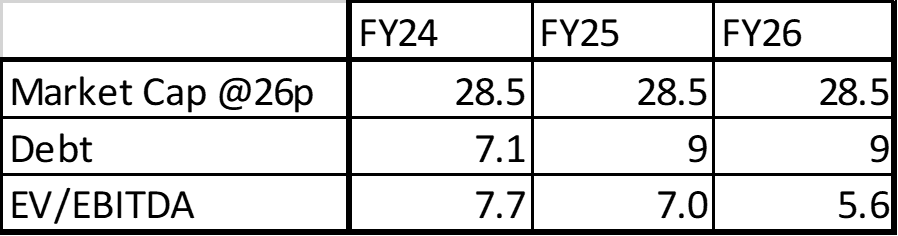
So, what looked like a cheaply rated stock on the previous forecasts…
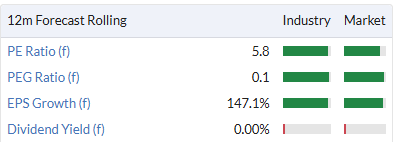
…now looks fairly priced, at best.
Mark’s view
While the reasons for the miss here are largely out of the company’s control, this update highlights that this isn’t the highest-quality business. They have less control over their destiny than I’d like to see in a business. This isn’t ridiculously expensive, but it no longer looks cheap on the forward numbers despite an almost 20% fall in price today. So, I am downgrading this to AMBER.
Warpaint London (LON:W7L)
Down 4% to 510p - Trading Update - Mark - AMBER/GREEN
A short update on FY24 trading:
Revenue for the year ended 31 December 2024 is expected to be approximately £102 million (2023: £89.6 million) and profit before tax to be approximately £24 million (2023: £18.1 million).
Again, these are showing great operational gearing. Revenue is up 14% but PBT rises a wonderful +33%. These growth rates are in line with the medium term trends here:
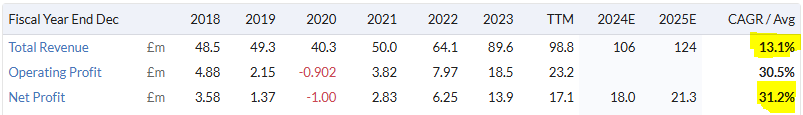
It is this ability to grow earnings faster than revenue that has made this a multi-bagger over the last few years despite a fairly lacklustre first five years of being a listed entity.
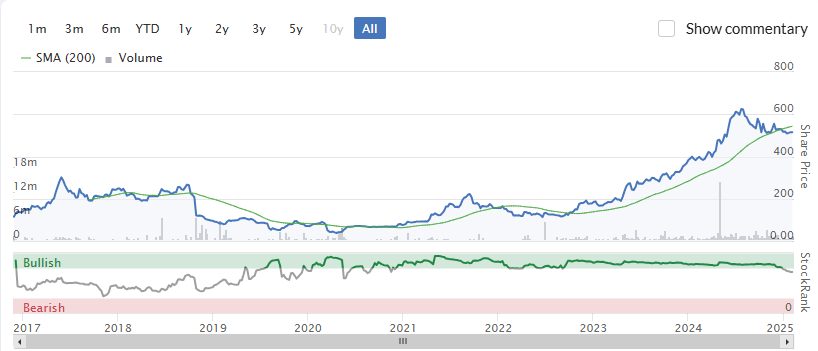
It is hard to work out exactly how these compare to broker expectations because forecasts are suspended due to Warpaint taking over Brand Architekts. However, the last Shore note from September had £105m revenue and £24.5m adj. PBT. The stockopedia consensus was for £106m in revenue. So compared to these forecasts, the actual results appear to be a few per cent miss on revenue and PBT.
The good news is that 2025 has started well:
The strong trading performance has continued into January 2025, with revenue approximately 15% ahead of January 2024, at an improved margin.
Shore had £116.6m revenue forecast for FY25, so this year appears to be tracking in line with this. However, this is tracking behind the £124m consensus that is in Stockopedia, but this may now be out of date given the pause in coverage. The forward EPS consensus of 26.6p may prove conservative if the margin improvements continue to drive operational gearing. If this is the case, then the current forward P/E of 20 will be lower and look good value again.
Mark’s view
This is a mixed update. While the growth rates and operational gearing continue to be impressive, the numbers themselves appear to be slightly behind the consensus. Could this be the start of a trend for the company missing forecasts rather than exceeding them? Still, the 2025 EPS looks like it may be conservative, even if the revenue consensus isn’t. When I last looked at this in December, I thought the management looked a little keen to issue equity at these levels and rated it AMBER/GREEN until there were tangible signs that the FY25 forecasts would be beaten. Today’s update doesn’t yet provide enough confidence that this is the case, so I will retain the same rating.
Sigmaroc (LON:SRC)
Up 5% to 75p - Secondary Placing - Mark - AMBER
These types of announcements often confuse those who haven’t seen them before. Here is what the company said last night:
CRH announces its intention to sell up to 171,578,948 ordinary shares in SigmaRoc. The Placing Shares represent approximately 15.4% of the Company's issued share capital.
The Placing Shares are being offered by way of an accelerated bookbuild, which will be launched immediately following this announcement.
CRH received these shares as part payment for the lime assets that SigmaRoc acquired from them in November 2023. So the placing here is not the company raising money but major holder CRH wanting to sell their holding. However, the holding is so large that they can’t just sell in the market. Hence, they have asked brokers to place the shares with other interested investors. This morning, we get the result:
…it has sold in aggregate 171,578,948 ordinary shares at the price of 67 pence per share, raising aggregate gross proceeds of approximately £115 million.
Following completion of the Placing, CRH will have exited its interest in SigmaRoc in full.
So they have managed to sell their entire holding but had to take a discount to get them away, much the same as a company placing. The discount is relatively slight, and this is a good sign that there was reasonable demand for the shares at that price, especially when many UK asset managers are facing outflows at the moment. The market has taken this as a positive sign, and the price has risen 5% this morning. The buyers in the bookbuild are locked in for 60 days. This means they can’t immediately sell their shares to lock in a risk-free profit. However, they may well start to sell if the share price remains at these levels in 60-days’ time.
Mark’s view
Roland rated this AMBER following their Trading Update on Monday. While this overhang clearing is good news, CRH had to accept a discount to get it away, and it doesn’t change the fundamentals of the company itself, so I keep the same rating.
BBGI Global Infrastructure SA (LON:BBGI)
Up 17% to 142p - Recommended cash offer - Mark - PINK
This PFI infrastructure fund receives a takeover offer from Canadian infrastructure giant BCI. The offer is relatively modest:
147.5p in cash…represents a premium of approximately…21.1 per cent. to the Closing Price per BBGI Share of 121.8 pence on 5 February 2025 (being the last Business Day prior to the date of this Announcement)
This is a relatively modest premium, but then the discount to NAV was modest, and this offer is effectively at NAV (1/0.83 = 1.205)
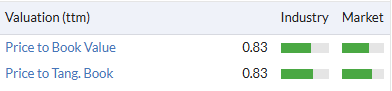
This is why the deal is recommended by the board and looks fair, and a done deal.
Mark’s view
This is obviously good news in the short term for holders who get an exit at NAV. However, this also highlights why I don’t tend to invest in listed funds unless the discount to NAV is very large. The near-term upside from an offer such as this tends to give small premiums. Whereas the downside from the ones that go wrong tends to be quite large. Just look at the long-term share chart of Digital 9 Infrastructure, for example. Obviously, the failures are rare. However, the risk-reward seems skewed the wrong way for me to be an equity holder in similar funds.
Anexo (LON:ANX)
Flat at 65p - Trading Update - Mark - RED
This stock regularly comes up on some of my bargain screens as it trades at a discount to its Net Current Asset Value. Today, they confirm they are trading in line:
The Group is pleased to announce that trading in FY2024 was in line with the Board's expectations.
So, what could possibly go wrong? Well, lots as it happens. To my mind, this is a terrible business model. They appear to be billing “customers” who simply don’t want their services, or at least to pay for them. So they don’t pay or at least delay payment as long as possible. Hence, the booked revenue stacks up on the balance sheet as huge receivables:
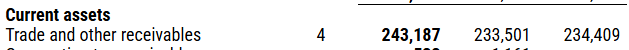
At the half year, this reresepents 1.7x TTM revenues or 632 days on average to get paid. These receivables are funded by around £55m of net bank borrowings. It was this dynamic that caused similar businesses, such as Accident Exchange, to fail.
In today’s update, they are keen to point out that:
Housing Disrepair and serious injury work continue to make an increasing contribution to the Group's overall performance against the backdrop of a solid performance across all Group divisions.
But the H1 revenue breakdown shows an increasing reliance on credit hire:
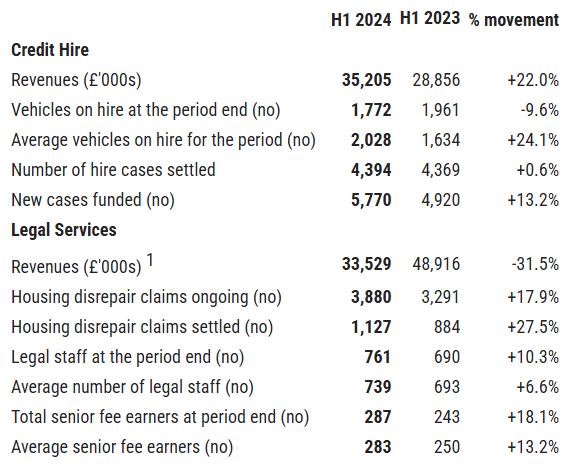
The update also includes details of a refinancing. They say that “The new agreements have resulted in significant savings in interest costs throughout the lifetime of the facilities.” However, the upfront costs of doing so come to a not insignificant amount of £2m.
Mark’s view
In my opinion, this is such a poor business model that it makes it completely uninvestable for me. Paul agreed and rated it RED. I see nothing in this update that causes me to change that view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Hi Jonno. I've posted another comment further down (or up?!) to try and explain a bit more. I'm talking about the short-term crowding effect rather then the long-term. On a long-term basis I completely agree it's fundamentals that matter.
Vertu Motors (LON:VTU) I hold
Profit warning just out
Vertu Motors (LON:VTU) I hold
Profit warning just out
“Profits will be substantially below expectations” and shares barely budge from 55 when they should be down in the low 40s. Warpaint misses by less than 1% and shares fall 20%. Gotta love the market. No need for anyone to explain why so perverse. I already know. Although that doesn’t mean I agree.
Absolutely ridiculous!
Cheeky middle of the day announcement from Vertu Motors (LON:VTU) - did they think no one would notice?
Bad form to put it out in the middle of the day. I must admit I gave up on Vertu Motors (LON:VTU) as gave up waiting for the elusive bid, and also found it too difficult to read the new/used car market, which seems to be very unpredictable. Wondering if any read across to ZIGUP (LON:ZIG) (I hold) which has recently been impacted by falling second hand van prices. The dislocation highlighted today seems to be more in the new car market so hopefully not.
BBGI Global Infrastructure SA (LON:BBGI) has returned c8.5% total NAV return per annum since launch over a decade ago. Not too shabby for a low risk placeholder income stock.
Warpaint London (LON:W7L): I have wondered recently if the popularity of a stock on this thread is becoming a contrary indicator.
Card Factory (LON:CARD) is another which seems to have a huge private investor following (and popular among a fair few fund managers too), but it has continued to languish below 100p.
For the record I hold Warpaint and this isn't a knock on the expertise of this community in any way... but once a stock is so widely held, where is the next set of buyers coming from? The marginal trade is more likely to be a sell. Anyway, just an observation! I think I'll continue to hold Warpaint and trust in the longer term growth story, for now. All compounders have large drawdowns at some point.
Warpaint London (LON:W7L): I have wondered recently if the popularity of a stock on this thread is becoming a contrary indicator.
huh you have lost me - warpaint shareprice is up 300% in 3 years - is that not the opposite of contrary indicator?
oh and card factory shareprice has also shown good gains in last 3 years.
shareprice may go up and shareprices may go down - comparing to "peak bubble price" for any share is not perhaps too meaningful i suggest - if you look at any share its likely that most are down from their all time highs or not at even near their all time high for last 18 months - thats probably 80% of all shares (my random guess)
Hi rmillaree. Yes Card Factory (LON:CARD) had a big jump from October 2022 to January 2023. But it has been broadly flat for the past two years (ex-divs).
My feeling is that it has become one of the most popular stocks in the Stockopedia community over the past 6-12 months. It wasn't so popular a few years ago, which was actually the best time to buy.
Using the "discuss" tab on the CARD page, it has been mentioned in 20 articles over the last year or so. The 5 Dec and 14 Jan daily blogs covered lots of company updates, but Card Factory attracted the most comments, about 10-12 each time. It has a busier 2024 discussion tab than 98% of stocks on the UK database, I'd venture.
In 2022 it was only mentioned in 8 articles (all SCVRs) and half of those articles attract no comments on it at all.
Warpaint London (LON:W7L) is similar - I'd say one of the most popular stocks right now, alongside Card. Look at the "Discuss" page for W7L and the 2024 entries are endless! 2020-2022 was much quieter. But when was the best time to buy? W7L is now broadly flat over the past year.
It's just the old short-term sentiment check. When everyone is talking about something (in an overwhelmingly positive way / as holders) then all the good news is likely in the price already. The buyers have already bought and the rate of change in public opinion (and buy/sell decisions) can only tilt negative. Like it has over recent weeks with Warpaint.
Journeo (LON:JNEO) springs to mind too. No community interest before. Big rise in 2023. Huge community interest in 2024. And now flat over the last year. Good luck to holders though - I have no view on its fundamentals.
Of course, long-term, share prices are inextricably linked to EPS. Like others have mentioned.
Bit of a ramble, sorry - knackered after a long day!
Hi Chris, not sure if I agree with your 'logic'. I hold Card Factory (LON:CARD) having sold on the way down from the high around 116p and bought back in around 94p once the exit stampede had abated and I had got a better handle on the interims and watched the management presentation.
Unfortunately I missed investing in Warpaint London (LON:W7L) having seen them at Mello in Chiswick, two years or so ago and before the shares took off. I also saw Filtronic (LON:FTC) at Mello when the shares were 17p and again failed to invest on the basis that I didn't fully understand the technology. So well done to those more perceptive than me and there will be many.
Excuse my rambling. My observation is that if a company consistently trades well, the share price will ultimately follow. You can bet your shirt that if a company makes a habit of issuing positive trading updates, there will be buyers, private investors and institutions.
Nothing goes up ad infinitum and at some point something is likely to upset the applecart either the price becomes too rich and/or something comes out of left field, for example competition, real or perceived, Nvidia being a recent example or closer to home Funding Circle Holdings (LON:FCH) where questions have been raised about the legal 'water-tightness' of their loan agreements. I don't follow Warpaint so am unable to comment as to why today's update was poorly received by the market
Just my view and some will see it differently.
All the best
Potentially / hopefully both right Jonno ...
Chris in the short term / voting machine
You in the medium + long term / weighing machine...
Future looks bright, says Liberum
Future (LON:FUTR) remains Liberum’s top pick in media and technology, following a trading update that confirmed its medium-term potential.
Analyst Johnathan Barrett retained his ‘buy’ recommendation and target price of £19.50 on the publisher, which was trading up 0.59% at 941p on Wednesday. Its shares are up 33% over the past 12 months.
A trading update for the first four months up to the end of January confirmed it remained on track to hit market expectations, with ‘high margin US advertising performing well’. Barrett noted the owner of titles Marie Claire and Homes & Gardens is benefiting from a positive backdrop and optimisation strategy that is working.
GoCo – the parent group of the GoCompare comparison site bought by Future in 2021 – is seeing some volatility in car comparison ‘as expected’ but other areas appeared to be growing well.
‘Our “buy” case gains further support from [the] update with the highest potential medium-term upside element – US advertising – looking very strong,’ said Barrett.
‘We reiterate our view and note the stock is our most preferred stock in media and technology.’
Triple Point Energy Transition (LON:TENT) , are one of several investment trusts and REITs either in wind down or considering it. (I hold this and abrdn European Logistics Income (LON:ASLI) )
In advance of their liquidation vote, TENT have highlighted the fact that once delisted the shares will no longer qualify for ISA or SIPPs.
This seems like an oversight when drafting the regulations, and I hope that platform managers are making the relevant representations to the Treasury to get this addressed. I shudder to think how much more complicated for those managing a probate portfolio.
"Triple Point Energy Transition plc has announced its intention to cancel its listing of Ordinary shares from trading on the LSE, and to place the company into a Member's Voluntary Liquidation, subject to shareholder approval at a general meeting on 24th February 2025. If approved, this is expected to become effective on 25th February 2025.
As the shares will no longer be trading on a supported stock exchange you may choose to sell your holding prior to our last day of trading listed above or transfer your holding to another broker.
If the liquidation is approved, the company intend to make an initial distribution to shareholders of approximately GBP0.4299 per share. The payment is expected to be made by 10th March 2025.
Please note the company is also conducting a Tender Offer, details for which can be found on your account. If the Liquidation is approved at the General Meeting, the Tender Offer will not proceed.
ISA Customers
Due to restrictions imposed on ISA accounts, unlisted shares are not considered an ISA-qualifying investment. Following the stock becoming ISA ineligible, we will arrange to move your shares to a linked trading account, opening one on your behalf if you do not already have one.
SIPP, Pension Trading Account, and Junior ISA customers
Unlisted shares are not considered a qualifying investment for these accounts and withdrawals are not permitted from these products. Consequently, holders may wish to liquidate any holdings prior to a delisting becoming effective."
Does anyone have any views on Chemring (LON:CHG) ? It's drifted gently since the results. PE now 15. Maybe a persistent seller?
Mark,
Not sure the catastrophe that is unfolding at Digital 9 Infrastructure (LON:DGI9) is any indication of a typical situation for decent yielding infrastructure Investment Trusts (see my comments on the IT thread!). BBGI Global Infrastructure SA (LON:BBGI), as a few comments on this thread indicate, is seen as generally seen as a relatively low risk income play in the alternatives space. It depends on ones attitude to risk/stage in life and the associated decisions on asset allocation as to whether you go all in for individual equities or look for a balance of income & growth from a broader range of holdings.
ACounsell, that is absolutely correct in my opinion. Comparing a low risk traditional infrastructure trust BBGI Global Infrastructure SA (LON:BBGI) with the cowboy antics of the managers Digital 9 Infrastructure (LON:DGI9) is not the best analysis I've seen on this Board. BBGI Global Infrastructure SA (LON:BBGI) has been badly impacted by the interest rate cycle.
Iweb not accepting debit card payments at the moment. Owned by a UK bank so may be Halifax affected too. No message sent. You have to wait 15 mins on the phone to be told. Time to move to Interactive Brokers or IG instead of just owning shares in them?
FTSE 100 new high. Nothing in the UK media though!
To be fair the FTSE 100 is often inversely correlated with the performance of the UK company. Interest rates are being cut because demand is collapsing in the UK , the pound is falling and the largely overseas earnings of the FTSE 100 will be worth more in sterling. So not sure it's a moment to blow the trumpets for the UK!
Ra International (LON:RAI) down 90% on proposed delisting. Given the extremely high insider ownership I would imagine that this will be a formality.
She, you know who of Ra International (LON:RAI) , is about to walk off mission accomplished. I dropped out last August at 7.2 pence, lost me thousands and was left disgusted at the way investors were coaxed along. Jam tomorrow, huh!
GlobalData (LON:DATA) up 12% on news of a proposed move from AIM to main market. What usually happens here, are proposed moves typically confirmed? Assuming would get bought in much higher volume if moved to main market.
GlobalData (LON:DATA) .... extra £ 50 mio share buyback too please JS ... Not sure how much weight to give to each of the 2 effects though ...
One of Megan's suggestions
To buy shares that might be moving to the main market?
No, she wrote about its Compounding potential, UK tech etc
Sigmaroc (LON:SRC)
Overnight, CRH placed all of the shares it received when SigmaRoc bought its Limestone interests. The share price of SRC has risen in response.
SigmaRoc is one of my largest holdings and a high conviction stock because it has the following attributes:
Experienced and capable management
Clear strategy
Environmentally sustainable business
Essential product
The necessary scale to succeed
Paul Scott once wrote that he didn’t know enough about lime to evaluate the company. Whilst limestone is a remarkable mineral with plentiful uses that we require in our daily lives, it isn’t necessary to have a very detailed knowledge. Limestone itself is a construction material that we are all familiar with. Lime, derived from limestone is a key material in the making of iron and steel, sugar, paint, plastics, glass, paper, aluminium, asphalt and plaster. It is used in agriculture and soil stabilisation. It is also a key ingredient in purifying water and flue gasses.
In short, the modern world is highly dependent on lime. SigmaRoc seeks to create value by purchasing assets in fragmented materials markets and extracting efficiencies through active management and by forming the assets into larger groups. It seeks to de-risk its investments through the selection of projects with strong asset backing.
Lime and limestone are key resources in the transition to a more sustainable economy. New applications for lime and limestone products as part of a drive for sustainability include the production and recycling of lithium batteries, the decarbonisation of construction including through substitution of cementitious material and new building materials, and environmental applications including lake liming, air pollution and direct air capture.
To understand why this is an unappreciated company I suggest you need to focus on the business model instead of how its products are used. Think of SRC as a producer that has cornered the market in a product that is in finite supply and cannot be substituted. This, in effect is what SRC did when they bought all the limestone quarries owned by CRH. This deal gave SRC the scale to dominate the market in western Europe and the UK and Ireland. There are many economies of scale to be extracted and little competition on price given the costs of distribution over long distances so margins should remain healthy.
Yes they have sizeable debt but in my view it was a price worth paying for a once in a lifetime opportunity to acquire an awful lot of limestone in the ground. The company has a clear vision of where it is going and how to get there. They are also very entrepreneurial in seeking ways to be carbon neutral or even negative. The management team are experienced and highly capable. We cannot live without limestone so it is only a matter of time before demand returns to a more normal level. Lower interest rates will add a tailwind. Forget about it being a natural resources business and focus on how it can exploit its dominance.
This is an excellent primer from the company web site for anyone who wants to gain a better understanding of SRC.
https://www.sigmaroc.com/lime-...
thanks for this - Like perhaps many - I don't know the coy but am interested especially as their MktCap and revenue are more or less equal- so silly Q maybe but why did CRH sell their limestone quarries - surely thats all part of their business - indeed they could have easily bought out SRC ?
Sigmaroc (LON:SRC)
Thanks for asking, I think CRH is more focussed on the USA and on construction materials. It's listed on the NYSE and is a much bigger outfit than SRC. It looks like they thought the European assets were too small and peripheral to their longer term ambitions. That's my view anyway.
CRH (NYQ:CRH) was itself acquisitive a few years back, it bought a lot of the old Tarmac quarries back in the day, which had before that been acquired from Wimpey all part of Sir Joe Dwyer strategy of becoming a pure housebuilder that is now Taylor Wimpey (LON:TW.) and Sir Neville Simms creating Carrillion...
I don't know enough about the cement production and ready mixed concrete world and ownership thereof, so there feels a sense of vertical integration too within the process somewhere. Do you own one piece and specialize within it or do you own parts of the whole value chain?
I do not follow this area enough as I work it in rather than invest in it...
Tommy
Very interesting, would be helpful to understand pricing and competition since limestone itself is in plentiful supply
Sigmaroc (LON:SRC) , correct John LA, limestone is abundant so it's not likely to be exhausted for very long time. But being heavy, the more it costs to transport it to buyers, the less profitable it is. I believe SRC have established enough sources in Western Europe and the UK to be able to deliver finished product economically. They have also been keen to find ways of developing novel aspects to their production such as carbon recovery and low carbon building products. I'm certainly no expert here and there is a strong case for DYOR to establish a well informed opinion. The company web site is a mine of information as are some previous RNS.
Appreciate your reply, I will check out their website, I certainly agree its an interesting company worthy of more research. I guess they supply end markets and its not seen as a commodity
Until the Q3 TS, Warpaint London (LON:W7L) TSs and results detailed strong growth supported by optimistic, upbeat text. The growth essentially disappeared in Q3 and Q4 but we are still being BS'd about "continued growth" when that was non-existent
Personally, I would much prefer an honest explanation about why H2 was pretty dreadful combined with details of how they will improve sales and profit growth going forward.
P.S. Obviously 15% growth in January '25 is helpful but its not clear its quite what's needed to deliver the FY25 broker sales forecast.
Warpaint London (LON:W7L)
FY 24 Rev +14% to £102m, PBT +33% to £24m. January Rev +15%
Sounds terrible. What an awful year they had.
Warpaint London (LON:W7L) Yes, shares down over 14% now.
Its no good looking at a great H124 for £W7L...
Warpaint London (LON:W7L) were ex-growth in H2 and haven't provided a decent explanation for this. At their rating they needed to get beyond generally positive BS and provide something a bit more meaningful.
It currently feels to me like a management team who are open and honest... ...when things are going well.
At this point I have no real idea why growth disappeared in H2 and so am struggling to extrapolate into FY25 and FY26. Some frankness from management would be really helpful.
For context, I held them from Jun-23 (circa £2.60) until it was clear they were not going to issue an ahead TS for FY24, whilst thankfully buying and selling profitably around my core position a number of times.
I complete missed selling at the top albeit I sold some around £5.80. In retrospect I should have sold out completely following the interim results when Q3 was ex-growth... ...without a great explanation. I wasn't having that happen to me again... and therefore thankfully avoided today's farce where we again have minimal growth and no justification.
Selling all at 550-560 now looks a decent sell
What do you mean by ex-growth?
According to Stocko Warpaint London (LON:W7L) delivered top-line £52.9m in H2-23. In H1-24 they delivered £45.8m. FY24 is £102m in total, so £56.2m H2 and c.6% growth.
"What do you mean by ex-growth?
According to Stocko Warpaint London (LON:W7L) delivered top-line £52.9m in H2-23. In H1-24 they delivered £45.8m. FY24 is £102m in total, so £56.2m H2 and c.6% growth."
6% is barely keeping above inflation and is pretty shoddy for a company that grew annual revenues from £50m in 2021 to £89.3m in 2023.
To stay on a growth P/E, there needs to be some growth somewhere. Hence the hammering the SP has taken today
Warpaint London (LON:W7L) ... my sense is that you're both correct... but, as someone said on another platform, ' 20% down is akin to a bad profit warning '... I missed out on this one originally, so have taken a starter position just now... a quality management team , astutely picking up Brand Architekts (LON:BAR) on the cheap... I think that this could be a long term compounder, even if it doesn't have the rocket performance of the last couple of years....
Hi Cancun - The problem with Warpaint London (LON:W7L) today is the PER rather than it being ex-growth. It is unusual for a retailer of this type to trade on a PER of 20+ so the only reason for that rating to be maintained is anticipated excess growth - a FY25 eps growth rate of 30% would bring it back to a more in-line 14* PER so for the shares to rise from here now you need confidence there is an anticipated 20-30% eps rise in FY26..
As others mention H2 doesn’t look great against those lofty expectations so there is clearly a view amongst investors that this sort of EPS growth may not prove attainable hence the sell off.
At this level Brand Architekts (LON:BAR) holders will take the cash rather than share offer so that probably removes any potential overhang of investors trying to arb the differential though so that’s probably a positive.
I don’t own though I’ve watched Warpaint London (LON:W7L) for some time and been reluctant to buy until I saw good H2 results. Trading update didn’t inspire. I suspect the purchase of skinny tan could act as quite a boon for them longer term but I suspect a period of consolidation is now in order whilst the market watches growth rates.
You're much better at this than me David, but I suppose that it will come down to margins ... if the 2025 EPS forecast of 26.6 proves to be correct, then after today's fall that's a PER of 16 ... if they can continue on some kind of growth strategy, I'm hoping that will prove decent value ...
A 1/3 fall in share price just feels overdone for a relatively unchanged story... many thanks as ever though:)
Sorry... I meant 1/3 from the high / 20 % today obviously...
I think that’s a very good summary David. The Warpaint London (LON:W7L) shares were on a PER of I think 24 when trading opened, which could only have been justified by revenue well ahead of forecasts, not slightly below.
Ah I see. I wouldn't describe Warpaint London (LON:W7L) as ex-growth - they had a quieter H2 where growth slowed. That's disappointing and we'd benefit from clarity on why that was the case. I suspect they waited until Feb for the trading update so they could confirm growth is continuing (15% YoY at a higher margin isn't ex-growth.)
Warpaint sells internationally, so judging their trading against inflation is a bit tricky. I think it's more appropriate to benchmark against the sector. Elf Beauty is a similar brand / competitor. I believe they're releasing a trading update today. It's been reported that YoY sales are falling due to the 'cosmetics category struggling.' Growth - albeit at a lower level - suggests W7 may be winning market share against competitors, which I think is more relevant than comparing sales against inflation data.
Finally, margin continuing to improve suggests to me they continue to be a well run/managed business. I hold, so may be biased.
Ah I see. I wouldn't describe Warpaint London (LON:W7L) as ex-growth - they had a quieter H2 where growth slowed.
I'm usually trying to identify the negatives in stocks I hold, but I don't really need to do that with W7L today ...
The reaction seems over the top for what wasn't a full blown profit warning (in fact not a profit warning at all). However, this type of reaction is quite common for small cap stocks that have multibagged. Private investors tend to get nervous about their gains and can be hair-trigger on selling at the slightest sign of trouble. This can get accentuated when the stock is also a bulletin board favourite and sellers communicate their fears to other nervous holders.
I can only see the volume on Stockpedia but it looks like about 2 million shares have been traded today out of 77 million. That's a lot more than normal but isn't huge. Probably around 70% of Warpaint is held by insiders or institutions, so that's maybe 10% of the available shares - enough to make a difference, but not an indication of any big moves.
That said, I'd never criticise investors taking a profit, but it's very hard to find the portfolio defining multibaggers if you sell at the wrong time. But it'll be interesting to see the FY results in April - if the outlook there is poor I'd imagine we'd see another hit to the share price.
Tricky stuff, investing.
timarr
But missed numbers, for now. No visibility of any "ahead" for time being
Yes, I would be really wary of this this one now. These small cosmetics companies all appear to fly for a while but eventually crash to earth (look at Creightons (LON:CRL) and Brand Architekts (LON:BAR) themselves). This is a tough industry with many big players with large advertising budgets. I held Brand Architekts (LON:BAR) back in its Swallowfield days and lost money as it changed strategy to become a branded player and bought the disastrous InnovaDerma business. Warpaint London (LON:W7L) have their work cut out to make money out of the acquisition at a time when their own sales might be struggling a little. All pretty risky when you are valued at 4x sales.
Thanks for all the comments about Warpaint London (LON:W7L) this morning.
I understand the disappointment/confusion because the information in the TU is a bit thin. A lot is going on in the company with the Brand Architekts (LON:BAR) takeover, and the expansion in the US team.
would also refresh memories about what was said about the US situation where the company is making the (tough?) transition for the discounters to the main players. They also said if I remember correctly that the main targetted retail players change their programmes less frequently - annually? - and so developments would be slower. They also commented that their target would be to get on the 'back wall' of companies like Walmart and this was a bigger ask. So, yes, I think that they are moving from regular 'beat'TUs of 12-18 months ago to a more leisurely pace. I do have confidence in the management, though I will be interested to see what they can make of the Brand Architekts (LON:BAR) acquisition.
All in all they have a lot going on; change of strategy in the US; heavier focus on the bigger US market; integration of the Brand Architekts (LON:BAR) acquisition; and not forgetting the solid base in the UK and the very productive performance in EU markets.
I sold out my whole holding of many years some months ago but I have dipped my toes in the water again in the 430s. I have that much confidence in the very shrewd - well I hope they maintain that descriptor - management team. I/we may just have to be rather more patient. I trust this TU is designed to give a little reassurance - apparently from the market this morning, not that successfully - and we wil get a fuller picture in the coming months.
Interesting that they must have had the finance team working at full tilt ( presumably including all over the last weekend) since the jan period end ( fri 31 st ? ) . Only three ish working days to get an accurate fix on gross margins for the month .
Wonder how accurate those numbers will be - thats not a normal turnaround time and wont be subject to any audit scrutiny at all ?
Warpaint London (LON:W7L) reports FY2024 Revenue of £102m, Profit before tax of approximately £24m versus consensus (3 analysts) of £105.2m and £24.3m respectively.
January revenue growth of 15% versus FY25 forecast of 17.7%, albeit its very early in the year.
So ‘small’ top and bottom line miss and maybe some catching up to do on the FY25 outlook.
It’s a short trading update touching on a ‘strong start’ to FY25 and the upcoming Brand Architekts acquisition (perhaps pointing to increased reliance on inorganic as opposed to organic growth).
We need to wait another 2 months for the full ‘meat and potatoes’.
Back at the interims the CEO said he was ‘delighted’ with performance and ‘continuing strong growth’ referring to ‘significant opportunities for growth’ with ‘existing’ and ‘additional’ retailers. Today he reports a strong start to FY25 but then refers to ‘consumer headwinds’ and mention of growth from large retail contracts is missing.
The mood music seems to have changed.
Spectra Systems (LON:SPSY) small contract win for them today. A lot of downward drift, don't know why but it's good little company that is growing. Earnings not until next month, but I would like to see this double from here.
Spectra Systems (LON:SPSY) I agree curious drift, presumably through lack of visibility. EPS next year would put in on a PE of 5. For a precision provider with state of the art technology that seems harsh!! I am biased though.
Spectra Systems (LON:SPSY)
thanks for flagging up spectra everyone - then p/e does seem very tempting based on 2025 numbers per stocky.
Have forecasts for next year - ie 2026 (bearing in mind 2025 is current year) been published yet ? if they have can anyone advise what those forecasts are.
General question ref how stocky works if 2026 forecasts are published now should we expect they only show up on stocky once 2024 numbers have been finalised ? at present both 2024 and 2025 have not been formalised yet - not sure if stock restricts itself to 2 years data not finals ? - or whetehr it would show 2026 data for all companies right now if it existed.
If 2026 forecasts do exist and stocky is choosing not to publish data - can i request that stocky would be rejigged to that tehn next yuears data is always brought in if it exists -even if thats greyed out memo total or needs checkbox to flag up - cheers
I always think if companies doent enter the "new year" with forecasts already in place for next year - they should expect the market to be unimpressed and not apply a "premium rating" - i know its possibly hard for smaller companies - but i damn well know mangement will have plans for next year and i most certainly want to know what their thoughts are rather than having a complete information void - and then having to do the hard work of manually checking if for example "2025 is exceptional year" and we should expect 2026 earnings to materially drop. Sometimes though perhaps for us nimble investors a void might give us teh opportunity to invest now - presuming we can trust mangement not to screw us over by hiding poorer data to come.
I have bren impressed from what i have seen from this company up to now - so even if 2026 forecasts do show decline now that might not put me off taking a position - they seem to be reasonably conservative ref their promises - i am aware its easy to be conservative when things are trending "up" not so easy when things are trending down.
one standout stat here is that the growth in sales from$12 mill to $50 plus mill has aligned with reduction in shares in issue in the same period !!! - thats a pretty spectacular acheivement when you factor in the decent trend ref increaisng profits too (easy to get extra sales if you make no profit on said extra sales) so top banana respect to mangement here - note i have only checked stocky front page - i havent checked recent stuff to see if there may have been any recent changes in share count!??
BBGI Global Infrastructure SA (LON:BBGI) - this is an interesting development in the alternatives space. It's my biggest holding in this sector and its being taken out at a 3.4% premium to net asset value, or about book value if the dividend is factored in. Although this is definitely top-end in quality, this will have an impact on the share price of other infrastructure investment trusts on very wide discounts. BBGI was trading at about 115p a few days back which was a totally stupid price. Unfortunately, my average entry price was 128.5p. Still a good return though. I will need to re-invest the takeover cash in another discounted high yield alternatives investment trust I suppose as I want to retain a 10-15% alternatives exposure.
I am also a holder and wasn't expecting this. Will have to see what the share price does at the open but what to replace it with? That's quite a decent yield to loose.
BBGI Global Infrastructure SA (LON:BBGI)
I have sold into the market about £1.45, similar the entry price of ~£1.30 was not a huge premium, but happy to have collected the dividends and made a profit for once in my life :)
Memorandum to myself, it is possible not to sell at a loss!
With it being cash and recommended I am not close or clever enough to work out whether there might be a counter offer and bidding war, but with a small premium I do not feel given everything else I have going on in life that it is worth waiting for, so taken the money on offer.
As for DutchShulz, I have a list of good income offering alternatives in my ideas folio, just got to spend some time tonight going back through these and make a couple of decisions as I also have the cash from the Blackstone Loan Financing (LON:BGLF^A25) shares come in yesterday. So that is two things that have left mum's and my portfolio's this month.
If you are interested in income, then I would suggest Charles' discussion thread is a starting point as often thought provoking and some things I had never thought about or heard on there
Stockopedia | Investment Trust- Thoughts (February 2025) | By Charles Mitchell
Good luck
Tommy
Hi Tommy. Thank you. I also sold at £1.45 this morning and am leaning towards 3i Infrastructure (LON:3IN) as a replacement. Lower yield but forecast to grow. Total return performance has also clearly been much better. Have been following Charles' excellent IT thread since he launched it. I'd be interested in what you opt for in the end and wish you good luck too.
Yep, also took the profit this morning. I liked BBGI as it had no debt. So also holding HICL Infrastructure (LON:HICL) which although no debt has low gearing, wide discount and good divi Keplar research here https://tinyurl.com/532nzpwj
All of the infrastructure ITs are trading on wide discounts - doesn't make sense since the underlying assets are frequently being purchased at premiums. Hopefully today's news will drive a re-rating. I hold 3i Infrastructure (LON:3IN) and Pantheon Infrastructure (LON:PINT) but there are several others which look good value.
There is a strong trading update from Warpaint London (LON:W7L) reporting higher income with an improved profit margin. Let’s hope that the high P/E ratio does not prevent an increase in the share price.
Revenue was a slight miss against 106m estimates. Is this in "in line" statement, I'm guessing so ?
A miss on revenue BUT a beat on profit. However I'm intrigued by the start to the year vs 2025 forecasts. Stocko has revenue at £124m, so does anyone know if this includes revenue from the BAR acquisition? Assuming 15% growth continues, this extrapolates out to £117m, add on £17m revenues from BAR that they did in 2024, then you get £134m, a nice uplift to what stocko is showing currently, plus improving margins, looks good!