Daily Stock Market Report (Thur 6th November 2025) - BoE, WOSG, FDEV, DGE, WISE, ITV, VCP, SBRY, FTC, TATE, AFC

Good morning!
The Bank of England announces its interest rate decision at 12 noon today, with most economists predicting there will be no change to Bank Rate (4%), although there is an outside chance of an early rate cut.
Decision: rates are left unchanged but four of the nine members of the MPC wanted at 0.25% rate cut. In a surprising and new development, the summary and minutes of the meeting includes statements from every individual member of the committee. It sounds like there were some strong views, and everyone wanted to make sure they were heard!
The consensus is as follows:
CPI inflation is judged to have peaked. Progress on underlying disinflation continues, supported by the still restrictive stance of monetary policy. This is reflected in an easing of pay growth and services price inflation. Underlying disinflation is being underpinned by subdued economic growth and building slack in the labour market...
...The risk from greater inflation persistence has become less pronounced recently, and the risk to medium-term inflation from weaker demand more apparent, such that overall the risks are now more balanced. But more evidence is needed on both.
With inflation peaking, that sets the stage for a rate cut in December or February.
Today's report is finished - have a good evening.
Spreadsheet accompanying this report: link (last updated to: 31st October).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£193bn | SR75) | Reiterates Total Revenue and Core EPS guidance for FY 2025 at CER. 9-month product revenue +11% at CER, 9M EPS +42% at CER. | ||
National Grid (LON:NG.) (£57.1bn | SR76) | Underlying EPS 29.8p, up 6%. FY26: “we expect strong operational performance… with underlying EPS expected to be in line with the 6-8% CAGR range from the 2024/25 baseline.” | ||
Diageo (LON:DGE) (£40bn | SR54) | Outlook: “Organic operating profit growth is expected to be low to mid-single digit, including the impacts of Chinese white spirits and a weaker US consumer environment” (and tariffs). | BLACK (AMBER/RED) (Mark) | |
BT (LON:BT.A).A (£17.9bn | SR72) | "We remain on track to deliver our financial outlook for this year, our cash flow inflection to c.£2.0bn in FY27 and c.£3.0bn by the end of the decade.” | ||
Smith & Nephew (LON:SN.) (£11.8bn | SR77) | Revenue (5% growth) and profit margin (19-20%) guidance unchanged; free cash flow guidance raised to around $750m (previously >$600m). | ||
Wise (LON:WISE) (£11.8bn | SR78) | SP -5% Continues to expect to move towards underlying PBT margin of c.16% for FY26, excluding one-off costs. This is the top end of medium-term guidance of 13-16%. Active customers +18%, revenue +11%, underlying operating profit down 15% (£132.8m). Underlying PBT down 17% (£122m). | AMBER/GREEN (Graham) [no section below] Please check out David Wordsworth in the comments section for a very helpful analysis of this one, which is far bigger than the typical mid-cap financial that I study. It has a grand vision: to become “the” network to move and manage the world’s money. I noticed an interesting debate in the comments section below about the threat of “stablecoins” (crypto assets backed by fiat). Wise refers to this threat in today’s report but personally I must admit that I don’t understand it: crypto, in my view, failed to ever deliver on its original promise of instant payments, while fiat currencies surprisingly did deliver instant payments, years ago. Wise’s infrastructure makes instant payments increasingly possible and in that sense it seems to be fulfilling what crypto coins were originally supposed to do. As for the investment merits of WISE stock right now, I’m happy to upgrade our view today having noticed the company’s very high quality metrics and the growth in the overall size of the business (18% customer growth year-on-year, with revenue approximately doubling over the past three years), which seems more important to me than short-term profit numbers. A US listing next year is likely to put upward pressure on the valuation too, as US investors tend to be more growth-oriented - and US growth stocks are in very punchy territory these days. | |
J Sainsbury (LON:SBRY) (£7.73bn | SR95) | SP +5% H1 sales and profit ahead of expectations and H1 profit after tax from continuing operations is £185m. Now expects Retail underlying operating profit of more than £1 billion for the year. Previous guidance: “around £1 billion”. £400m to be returned to shareholders following bank disposal: a £250m special dividend plus £150m additional buyback (split over FY26 and FY27). | GREEN (Graham) [no section below] We’ve been moderately positive on this one and I’m pleased to see that this has been rewarded with an “ahead of expectations” outlook. Retail sales are up 4.8% and like-for-like retail sales are up 4.5%, which means that retail underlying operating profit can stand still at just over £500m. In order to be consistent with our method, I’ll upgrade our stance on this to fully GREEN given that this is a Super Stock that has just delivered an “ahead” update. The stock is currently trading at around 14x earnings and it has traded higher than this before, although not significantly and not for very long. So I would assume that further gains will rely mostly on earnings growth over multiple expansion. Market share has been pretty stable around 15% for the last five years, putting SBRY in second place only to Tesco and materially ahead of each of the discounters. It seems to understand its place in the market well, and continues to execute. | |
Auto Trader (LON:AUTO) (£6.68bn | SR54) | Revenue +5%, operating profit +6% (£200.1m). H1 is in line with expectations, and the full year outlook remains unchanged. | ||
IMI (LON:IMI) (£5.93bn | SR73) | Q3 organic revenue +12%.Full year guidance reconfirmed. | ||
ConvaTec (LON:CTEC) (£4.81bn | SR49) | CFO promoted to CEO. Group Financial Controller promoted to CFO. | ||
Howden Joinery (LON:HWDN) (£4.7bn | SR87) | YTD sales +3%. On track with the outlook for 2025, PBT to be in line with current market expectations. | ||
Hiscox (LON:HSX) (£4.55bn | SR60) | Written premiums +5.9%. Claims experience well within expectations. Change programme on track. | ||
Hikma Pharmaceuticals (LON:HIK) (£3.93bn | SR78) | Continues to expect revenue growth of 4% to 6%. Tightens core operating profit range to $730m - $750m, (previous range $730m - 770 million). | ||
Harbour Energy (LON:HBR) (£3.28bn | SR78) | Free cash flow outlook “reinforced”, production guidance upgraded. | ||
RS (LON:RS1) (£2.62bn | SR78) | H1 “as expected”, full year outlook unchanged. H1 revenue down 1% like-for-like, operating profit +3%. | ||
ITV (LON:ITV) (£2.57bn | SR82) | Performance for the 9 months to the end of September was better than market expectations. YTD Revenue+2% (+4% external revenue). £45m of total Group permanent non-content savings in 2025 as previously guided, £35m of additional savings. Net debt £508m (30 Jun: £586m). | AMBER (Mark) [no section below] | |
TBC Bank (LON:TBCG) (£2.4bn | SR64) | 3Q 2025 profit of GEL 368 million, up by 6% YoY, with ROE at 24.4%. Net Interest Margin flat Q-on-Q at 7.1%. Georgia CET1 16.7%, Uzbekistan CET1 18.5%. | ||
Vistry (LON:VTY) (£2.02bn | SR73) | Expectations for the year remain unchanged. Sales rate since 1 July is up 11% compared to the same period last year at 0.81 (2024: 0.73). Forward order book remains stable at £4.3bn (2024: £4.8bn). Build cost inflation for FY25 remains in line with expectations, tracking at low single digits. Expect to deliver a year-on-year reduction in the Group's net debt position as at 31 December 2025. | ||
Derwent London (LON:DLN) (£1.97bn | SR66) | Open market leases signed 10% ahead of ERV; £17.5m of new rent completed YTD (including renewals/regears), EPRA vacancy rate at 3.7%, £200m of disposals completed YTD, with a further £14m contracted. | ||
Osb (LON:OSB) (£1.88bn | SR93) | Net loan book +2% to £25.6bn, in line with guidance, 3m+ arrears reverted to 1.7% from 1.8% as at 30 Jun, in line with the previous trend. Common Equity Tier 1 capital ratio remained robust at 15.8%. On track for 2025 guidance. | ||
Tate & Lyle (LON:TATE) (£1.68bn | SR23) | Revenue -3% to £1.02bn, Adj. EBITDA -6% to £215m, Adj. PBT - 10% to £126m, Adj. EPS 21.3p, Net debt £952m (31 Mar: £961m). Outlook for the full 2026 financial year is unchanged. | AMBER/RED (Mark) [no section below] A forward P/E of 9 initially looks interesting for this household name in what should be a fairly defensive sector. However, they have £952m in debt, partly taken on to acquire ingredients manufacturer CP Kelco. This makes the rating far less attractive on a EV basis. Today’s results are adjusted to take account of that acquisition, but are uninspiring, and all key metrics down for the half-year. The outlook is in line, but this was cut (together with our view) following a profits warning at the start of October. I see no signs in these results that this isn’t a plodder on not that cheap a rating once debt is accounted for, so I maintain that broadly negative view, given the StockRank of just 23. | |
Helios Towers (LON:HTWS) (£1.63bn | SR78) | Q3 Revenue +1% to $216m, Op Profit +38% to $78.1m, Net debt flat at $1.72bn. | ||
Watches of Switzerland (LON:WOSG) (£910m | SR69) | H1 Revenue +10% CCY to £845m (US +20% CCY). Reiterating FY26 guidance provided in July. | AMBER (Mark) | |
Workspace (LON:WKP) (£779m | SR26) | Workspace to acquire a minority equity stake in Qube for £3m which will largely be reinvested into The Old Dairy fit-out in Shoreditch. | ||
Ocean Wilsons Holdings (LON:OCN) (£318m | SR75) | NAV was US$812.4 million (£604.0 million) US$28.72 (£21.35) per share. Investment portfolio valued at US$355.5 million, which represents US$12.57 (£9.34) per share, with the balance of US$456.9 million held in cash, reflecting the proceeds from the Wilson Sons disposal. | PINK | |
Filtronic (LON:FTC) (£297m | SR61) | Secured a contract with a leading European aerospace manufacturer, to supply RF assemblies for integration into a major Low Earth Orbit satellite constellation programme, valued in excess of €7 million over three years. | AMBER (Mark) [no section below] Another decent contract win, showing their expertise is in demand, but at around £2m revenue pa (assuming smooth revenue booking), it is only around 3% of forecast revenues each year, meaning it doesn't move the needle much. It remains a great business, but it is expensive and the Momentum Rank continues to fall, so our previous caution remains warranted in my opinion. | |
Intuitive Investments (LON:IIG) (£218m | SR37) | “…has delivered further growth in its performance metrics since September and continues to anticipate further progress in the period to December 2025 with connected Lucky World shops increasing to c.9,000 and UGO UnionPay POS Terminals to more than 1,000…” | ||
Frontier Developments (LON:FDEV) (£190m | SR96) | “At just over two weeks after release, base game sales have now exceeded 500,000 units, with higher revenue than was achieved by Jurassic World Evolution 2 (Nov'21) in an equivalent period.” | GREEN (Graham) Despite the lack of visibility compared to many other companies I cover, and despite how expensively rated the stock is now, I think that Frontier does deserve a high rating given the success it has achieved by returning to its original strategy. The next Planet Zoo could reboot its financials once again, and there is every chance that Jurassic World could also continue to surprise positively. | |
ASA International (LON:ASAI) (£180m | SR80) | Geert Embrechts as Chief Financial Officer, joining from Rabobank where he currently serves as Chief Financial Officer of the Wholesale & Rural business unit. | ||
S4 Capital (LON:SFOR) (£139m | SR52) | Q3 billings +2% to £491m, Revenue -3% to £192m, Net revenue - 7% to £167m, “2025 like-for-like operational EBITDA target remains unchanged, broadly similar to 2024”. Month end average net debt for the third quarter £154 million versus £184 million last year. | ||
AFC Energy (LON:AFC) (£101m | SR4) | FY Revenue £107k (FY24:£4m), Cash £25.3m (FY24: £15.4m) after £25m fundraise in period. | RED (Mark) [no section below] You’d think that £170k of revenue this year compared to £4m last year and £1.3m forecast would cause some embarrassment amongst the board. However, I don’t sense a lot of contrition, perhaps because the CEO is relatively new. While he may be new to the job he appears to have retained AFC’s core technology: raising money from shareholders. Given that they raised £25m and have £25m, that means they burnt through about £15m in the year. They say that the business “has been fundamentally restructured…” , leading to “an annualised saving of c. £1.5m in FY26.” However this would only appear to lengthen the cash runway by a month or so in this Sucker Stock. | |
Victoria (LON:VCP) (£62.9m | SR27) | H1 revenue -7% (Q1-11%, Q2 -2%) in line with previous guidance. U/L EBITDA +6% to £53m. Revenue for FY26 is expected to be slightly below FY25. Cost savings of £20m complete. | RED (Mark) [no section below] Things remain tough in this sector, although there are signs of an improving trend. Underlying EBITDA is up, but I can’t help feeling I am going to disagree with those adjustments when I see them. They highlight that “Group liquidity remains sufficient” but without giving us the overall net debt figure. To give some idea of scale, they recently refinanced their 2026 notes with “near-term senior debt maturities with €612million (£528 million) of 9.875% Senior Secured Notes due July 2029, and a new £130 million super senior credit facility maturing in January 2030.” They recently tried to refinance their €166.6m of outstanding 2028 3¾% Senior Secured Notes for 2031 notes with a 12% 2031 PIK note. That the 2028 holders refused, presumably shows that they would prefer some (slim) chance of being paid first or leading the restructuring rather than accept a much higher interest rate but no payment until 2031. All of this simply highlights that the equity here is at best an option, and if I wouldn’t be willing to take the risk of holding the debt here, why would I risk holding the equity? | |
Hercules (LON:HERC) (£31m | SR83) | Academy on course to train 2,000 students in the 2025 calendar year. | ||
Rockfire Resources (LON:ROCK) (£11m | SR27) | First drill hole complete. Five portable XRF spot samples have been taken, which average 6.7% Zn, 2.5% Pb and 42g/t Ag. |
Graham's Section
Frontier Developments (LON:FDEV)
Up 9% to 562p (£208m) - A STRONG LAUNCH FOR JWE3 & A SEQUEL FOR PLANET ZOO - Graham - GREEN
Frontier Developments plc…, a leading developer and publisher of video games based in Cambridge, UK, is pleased to provide updates on two of its flagship franchises: Jurassic World Evolution and Planet Zoo.
We’ve been reasonably positive on this one - see my coverage in June and then Mark in September.
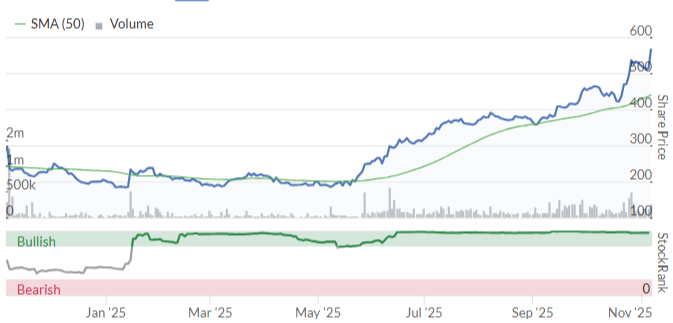
So far, the bull thesis is playing out with Jurassic World Evolution 3 having launched successfully:
Excellent player engagement and critic reviews following its release on 21 October 2025 has delivered stronger-than-expected sales for Jurassic World Evolution 3, the third instalment in Frontier's biggest-selling game franchise, Jurassic World Evolution. At just over two weeks after release, base game sales have now exceeded 500,000 units, with higher revenue than was achieved by Jurassic World Evolution 2 (Nov'21) in an equivalent period.
This follows a pivot by Frontier back to its original strategy of focusing on grand “CMS” games (creative management simulation). This means the player building and managing a theme park, a zoo, or a dinosaur park. One of these might be entirely fictional, but it’s not hard to imagine how there might be commonalities between them all!
Here’s the trailer for the new edition of the fictional game that’s doing so well:
Review aggregation site Metacritic gives JWE3 a “Metascore” of 81/100 (based on critic reviews).
On Steam, the game scores 92% out of 2,447 reviews.
Let’s compare that to F1 Manager, the discontinued Formula One simulator series that is generally considered to be a flop and that played a big part in the collapse of the FDEV share price in 2022 and 2023.
On Metacritic, the F1 Manager games (2022, 2023 and 2024) all received scores of 79 to 81, the same as Jurassic World Evolution 3.
However, on Steam, F1 Manager 2022 received “mixed” user reviews: 65% positive feedback. The subsequent titles improved this to 77% and 79%.
A couple of things I’d take from this information:
Maybe it’s best to ignore Metacritic when it comes to predicting commercial success? I’m sure the critics have good reasons for their views, but they rated all of these games similarly.
Similarly, I’m going to put more weight on reviews at Steam (the digital distribution platform) from now on, as it’s far more reflective of the public mood - which makes sense, seeing as games enjoy thousands of reviews on there.
These review ratings help to confirm that FDEV did learn from the initial failure with the first F1 game, and the follow-up F1 titles were a big improvement.
But the main takeaway from today is the FDEV is succeeding by doing what it knows best: grand CMS games in large open areas. Focusing on its niche is working.
And in that regard, we have more news today:
Frontier is excited to reveal that the CMS game scheduled for release in financial year 2027 (1 June 2026 - 31 May 2027) is a sequel to Planet Zoo, Frontier's biggest selling game to date. Released in 2019, Planet Zoo has sold over 5.5 million units worldwide and generated over £145 million in revenue as of 31 October 2025.
Graham’s view
I’m going to take our view on this back up to fully GREEN.
Yes, there is no denying that it’s expensive now:
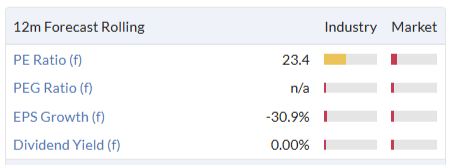
Let me reiterate my standard warning that it’s not without risk: there is always the potential for its next release to flop, just like F1 Manager did.
However, that risk is mitigated by the company focusing on sequels to titles that have a large fanbase and where FDEV has particular development strengths (CMS).
Also, shareholders must accept the annual revenue figure isn’t smooth: it depends on which games are released in particular years, and this will change every time.
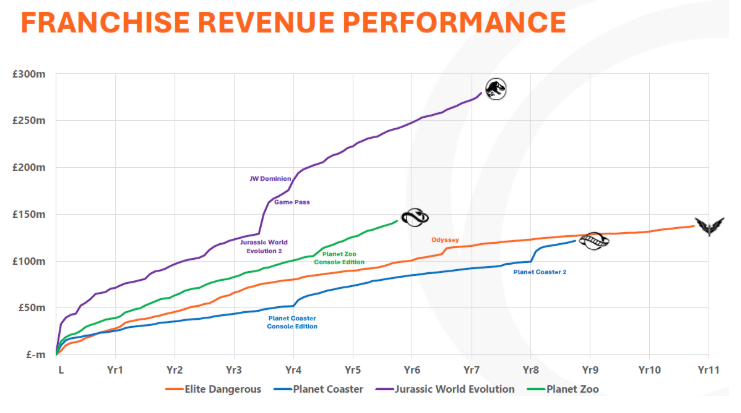
Here’s an interesting chart from last year’s results presentation which is very helpful for us to visualise this. It shows spikes in franchise revenue when there are new releases. The success of each financial year basically depends on how many of these spikes happen to occur in a 12-month period, and how steep they are:
Upgraded forecasts: we have new estimates from Panmure Gordon (many thanks) which I should share here:
FY26 revenue £93.9m (previous estimate £91.1m)
FY26 EBIT £9.5m (previous £7.6m)
They also make small positive adjustments to FY27 and FY28.
Adjusted operating profit - a figure similar to EBIT - was £13.2m in FY25. Therefore, even with these upgrades, the company is not currently expected to match FY25’s profitability in FY26. EBIT is not expected to get back to £13m+ until FY28.
There is no way to invest in FDEV without being comfortable with this ebb and flow, and with the inherent uncertainty of profit forecasts.
Despite the lack of visibility compared to many other companies I cover, and despite how expensively rated the stock is now, I think that Frontier does deserve a high rating given the success it has achieved by returning to its original strategy. The next Planet Zoo could reboot its financials once again, and there is every chance that Jurassic World could also continue to surprise positively. I’m excited to see what this can achieve next!
Mark's Section
Watches of Switzerland (LON:WOSG)
Up 6% at 415p - H1 FY26 Trading Update - Mark - AMBER
The headline of +10% revenue for the half versus last year hides a tale of two regions:
US revenue £409 million, +20% at constant currency, +15% at reported rates vs prior year…
UK revenue £436 million, +2% vs prior year, +5% adjusting for showroom closures
Claiming the UK would be +5% adjusting for showroom closures seems a bit of selective reporting as they also are keen to point out:
We continue to make good progress with our showroom development programme, with several flagship refurbishments and new boutiques completed in H1 FY26, and further high-profile openings planned for H2 FY26.
And then go on to list a series of expansions or relocations, including in the UK. Overall, this is just a continuation of recent trends, with the UK revenue flat and the US expanding quickly:
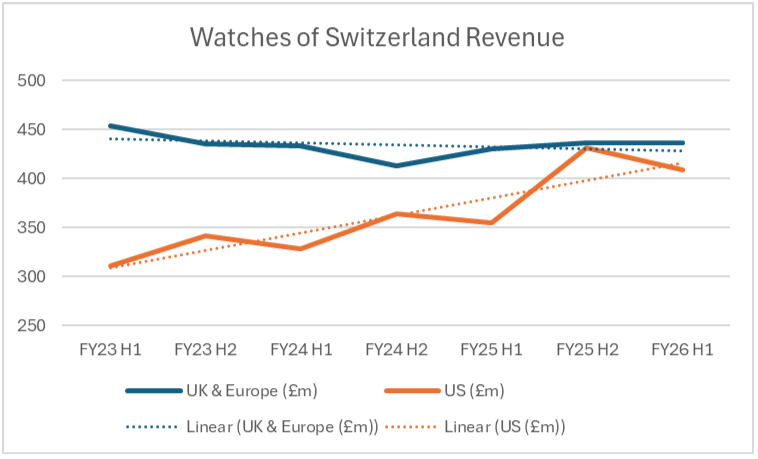
This half revenue is actually below H2 last year, but there appears to be a strong seasonality in the US business, so shouldn’t be particularly worrying. What is worrying when they have such a large exposure to the US is tariffs. Here they say:
Additional 39% tariff in place since 7 August 2025 on landed cost of Swiss imports. We understand negotiations between governments are still taking place. We are closely monitoring tariff developments and brand responses. To date we have not seen any significant change to consumer behaviour.
This scale of tariff is no doubt why the shares have been weak since the summer:
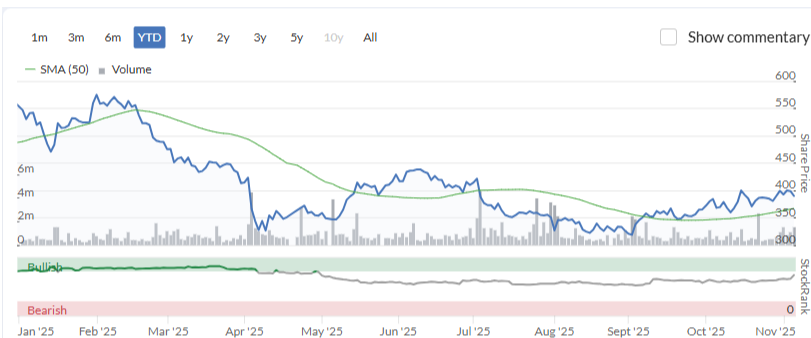
They say there is no significant change to consumer behaviour, but this could be due to many reasons:
Inventory: It will have made sense to build up inventory in the U.S. ahead of the tariff effective date, which may delay how quickly retail price increases hit consumers.
Buying behaviour: we may be seeing consumers buy ahead of perceived upcoming price rises.
Lower price rises: the tariff is paid on the import cost not the RRP, so overall prices may only rise 15-20% if the full tariff was passed on.
Margin share: it is not clear who will absorb the tariff - brands, WOS, or customers. In reality this may be shared.
Luxury: watches are a luxury good which are largely sold on the wealth that they signify to those who observe the wearer. Having a more expensive good may actually increase this signalling and make them more desirable.
Only the last point is really positive, with all of the other signalling pain delayed rather than cancelled. Balancing any impact on new watch prices, used watch prices may strengthen, as they look comparatively better value, but this remains a modest part of the overall business.
Valuation:
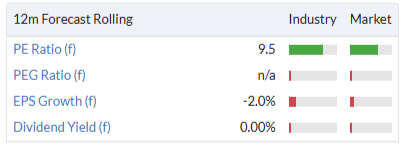
The current sub-10x P/E makes the company look reasonable value for a luxury retailer (although this is not a brand owner so shouldn’t be compared directly to luxury brands):
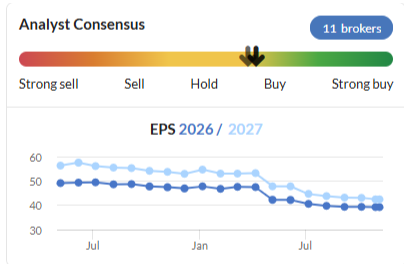
While the overall EPS growth rates may be unimpressive, when I separate out the US from the UK, there is no doubt that the US remains a growth business. Costs are an issue though, and the overall EPS trend is not particularly encouraging:
The biggest issue is the unknown impact of the tariff situation. The company helpfully provides current consensus on their website:
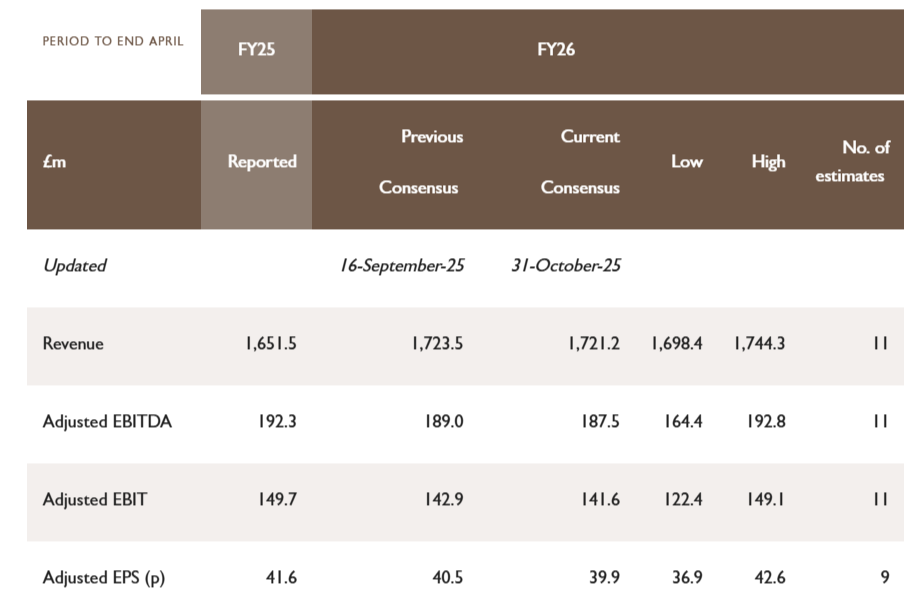
The current consensus is for a 8.23% EBIT margin. Therefore, any impact on gross margin from tariffs would have an outsized impact on EBIT and EPS, as this would drop straight through to EBIT.
Based on current trends, the US will be about half of revenue this year. We don’t get a breakdown of the product split by region but 84% of overall sales in H1 were in the watch segment:
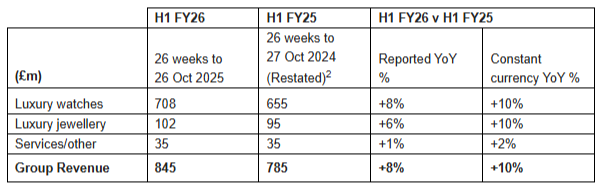
We also don’t know the split between new and used. However, their five-year plan presentation said they believe that by FY28 the second hand watch business will grow to the point where it represents 20% of the value of new Rolex sales in the US. This is one brand, but their major one. I think we can guesstimate that it is probably about 15% used watches by revenue this year.
So my guesstimate for US new watch sales in FY26 is £1,721m x 50% region x 84% watches x 85% new = £614m. Each 1% tariff related gross margin impact would impact EBIT by £6.14m. If we assume say 5% GM impact this would take £30.7m out of EBIT, which would drop EBIT and presumably EPS by around 22%. Of course, not all of this will impact FY26 as we are already half-way through. Plus presumably analysts may have included some of this impact as part of the recent decline in EPS consensus. The scope for a large miss in FY27 remains even if recent revenue growth trends in the US continue.
The market has liked this update this morning with the share rising 7%, presumably buoyed by the statement that they haven’t seen any significant change to consumer behaviour in the US. It seems to me that they aren’t out of the woods yet on this, and they probably have the choice between eating a significant gross margin hit or raising prices that will have an unknown impact on consumer behaviour.
Mark’s view
When Graham reviewed this in September he was hovering between AMBER and AMBER/GREEN, due to the lack of clean accounts, brand ownership or quality metrics. Only the P/E of around 8 kept him interested. However, with the share price now almost 25% higher, the analysts consensus lower, and a potentially large future tariff impacted as yet unaccounted for, it is probably best to moderate our view back to AMBER.
Diageo (LON:DGE)
Down 5% at 1715p - FY26 Q1 trading statement - Mark - BLACK/AMBER/RED
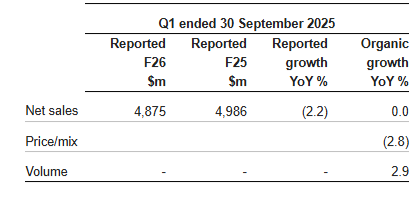
Overall revenue is down due to disposals, and flat organically as weaker pricing offsets all of the volume increase:
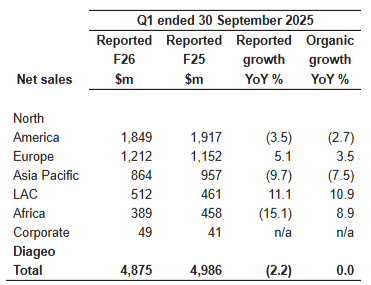
It is the US and China that are weak:
The overall impact appears to be a modest profits warning, although it would be nice if they quantified this further, given the organic aspect:
Organic net sales growth - we expect to be flat to slightly down including the adverse impact from Chinese white spirits and a weaker US consumer environment than originally planned for.
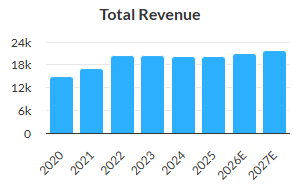
Overall, it looks like this will be the fourth year of flat revenue, which in an inflationary period for the world is poor:
Like many companies their answer is cost-cutting and they say that their “cost savings guidance of c.$625m over the next 3 years fully on track.” However, this isn’t enough to avoid a decline in earnings, even more so after today’s trading update makes it into the consensus:
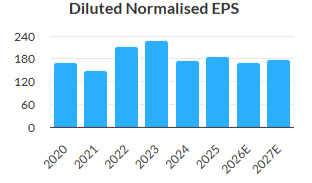
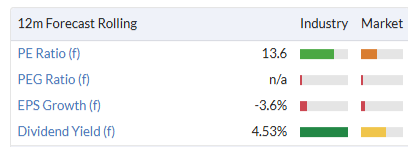
Many investors view this sort of company as a stable business throughout all market conditions. The P/E of around 13 seems high for a company with so many years of no growth, but this is why it is green against its industry but not thE overall Uk market:
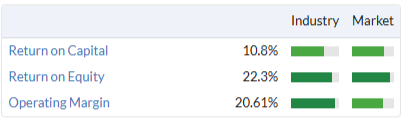
As a brand owner it should be able to continue to generate reasonable operating margins which are typically above 20%. However, its decent Returns on Capital mean nothing if it can’t deploy additional capital to grow sales and EPS:
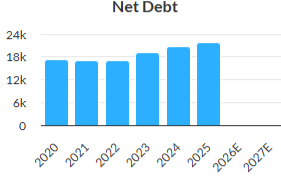
The dividend yield is reasonable, but not stand-out and given that net debt has been increasing, this is at least partially, debt-funded:
On cash flow they say:
We remain committed to delivering c.$3bn free cash flow in fiscal 26 and returning to well within our target leverage ratio range of 2.5 - 3.0x no later than fiscal 28. This will be supported by appropriate and selective disposals over the coming years, with plans progressing well.
Selling assets in order to pay down debt and maintain a dividend may be the right thing to do, but it hardly inspires confidence in a growing future. I think there are some structural/ethical headwinds too:
Problem drinking
A UK study into alcohol consumption in 2018 found that:
Drinkers consuming more than the government’s low-risk guideline of 14 units (around one and a half bottles of wine or six pints of beer) per week make up 25% of the population, but provide 68% of industry revenue.
The 4% of the population drinking at levels identified as ‘harmful’ (over 35 units a week for women, over 50 units a week for men) account for almost a quarter (23%) of alcohol sales revenue.
I don’t think I can be too critical as I both drink alcohol and some of Diageo’s products. There may also be some significant cultural differences around the world. However, with harmful drinkers making up around a quarter of alcohol sales, this makes me a little bit uncomfortable with Diageo as an investment due to both the ethics and risks of further regulation.
Demographic differences
The US is a key market for Diageo and here, at the start of this year Time Magazine reports that:
…research from the National Institute on Drug Abuse shows that lifetime drinking, past month drinking, and past year drinking among young people began to decline around the year 2000. That means that such declines have especially impacted Generation Z, defined as anyone born from 1997 to 2012, and some Millennials, born between 1981 and 1996. A 2023 survey from Gallup found that the share of adults under age 35 who say they ever drink dropped ten percentage points in two decades, to 62% in 2021-2023 from 72% in 2001-2003.
Overall, US alcohol consumption was still up, but similar trends hold across many developed countries - young people are drinking less. This may act as a demographic headwind for producers.
Weight-loss jabs
The Guardian reported earlier this year that:
…the first clinical trial of its kind has found that semaglutide, distributed under the brand name Wegovy, cut the amount of alcohol people drank by about 40% and dramatically reduced people’s desire to drink. Researchers said the study backed up anecdotal evidence from patients and doctors that semaglutide can lead to a sudden loss of longing for alcoholic drinks.
Recent studies suggest about 12% of US adults are currently taking weight-loss jabs, so while the absolute numbers may not be a significant impact for Diageo on their own, there appears to be a correlation between problem drinking and obesity. Combining these factors I can easily see a 5% revenue risk to Diageo in developed countries from these treatments.
Alcohol-free products
Offsetting these trends is the tendency for companies to produce alcohol-free versions of popular drinks. While the idea of an alcohol-free spirit seems pointless to me (at least while it is priced at a premium to cordials), high-quality alcohol free beers are increasingly popular. Diageo may well benefit from this trend for their Guiness brand (especially if margins are higher due to the lack of alcohol duty). However, they will not benefit as much as some other brewers who have more beer and less spirit offerings.
Mark’s view
Roland rated this AMBER at the start of August. The share price is a bit lower today but then so is the broker consensus:
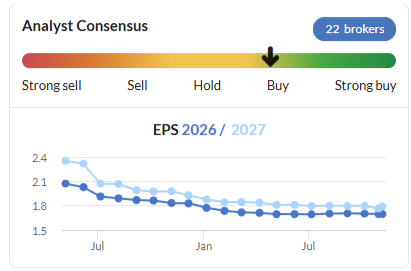
This will take a further tumble when today’s update is digested into the StockReport. The StockRank is likely to fall further in the short term too:
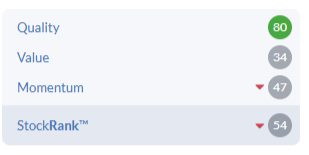
Without the headwinds I mentioned then I would agree that the quality metrics that Roland mentioned would warrant a neutral view. However, a high historical Return on Capital does nothing for shareholders unless the company can re-invest capital at similar rates to generate growth. Instead the message from the company is one of selling off assets in order to pay down the debt and maintain the dividend. I am also much more negative on the potential impact from the trends towards lower alcohol consumption on the company, hence it’s an AMBER/RED for me, until there are clear signs that they can grow their sales above inflation over an extended period of time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Hi Jimbob — glad the research has been useful.
Wise looks simple on the surface, but it’s essentially a modern, regulated version of the old Hawala concept: money rarely crosses borders, Wise does. To make that work globally, they’ve spent a decade building their own “rails” — banking licences, local accounts, liquidity buffers, instant-payment integrations and compliance infrastructure. That’s the bit that’s hard to copy.
As for the share price drift since September, it’s mostly sentiment rather than fundamentals. There was a wave of “stable coin” and blockchain-payment noise around late summer, some profit-taking after a strong run, and slightly softer global FX volumes. None of that changes the long-term story.
In fact, the last fortnight has been very positive. Wise has just issued its first corporate bond — £250m, unsecured — and it was more than 3× oversubscribed by JPMorgan, Goldman Sachs, Bank of America and HSBC. These are extremely conservative lenders, so it’s a strong vote of confidence in Wise’s model, leadership and long-term durability. Over time, that kind of relationship can also open the door to deeper institutional partnerships.
If you want another balanced view, Alyx Wood (Mello speaker) did a good segment here:
https://open.spotify.com/episode/5WHovGNgbT5DKNbNa0kq2Y?si=nI-zrsPCTMK7yMCpKkT8lQ
Happy to chat more if useful.
Fantastic thought-provoking write up on Diageo (LON:DGE) Mark. I'd love to see a head-to-head at Mello where you and Nick Train debate the merits of Diageo, and then compare your respective track records!
I have just read that Sky owner Comcast is in talks to buy ITV (LON:ITV) I would appreciate anyone's thoughts on this as I hold.
ITV (LON:ITV) A part of its business (I believe)
Not the whole company.
All the best
Frontier Developments (LON:FDEV) If you follow rns statement tr1 holdings
jp morgan put £10 million quid into Frontier Developments (LON:FDEV) just days before a trading announcement today. Almost like they had information ? They made a cool 1 million on todays news when their rns tr1 form holding was realeased yesterday.
Maybe they had inside knowledge, though I do think the information was already out there, and investment was derisked after JWE3 launch. It just wasn't RNS released information.
A few examples:
And that's just all I could think up myself.
e.g. here's SteamDBinfo https://steamdb.info/charts/?c...
I should write an article on this as actually it's a good "sleuthing" case study that can create alpha.
10 million pounds is lot to put on the table, especially as this wasnt a pre set date for a trading release , so yes fishy,
I follow TR1 form buys and sells rns statements based on timing days to trading dates release and half or full results. The results can be interesting. Im basically looking for insider info . I found a pattern for certain shares where 10-13 days before results, amounts bought above £20 million produced a win
I have also seen certain banks constantly buy and sell large amount reducing same amount each day and then buying back the next. I avoid this like the plaque, Trending my industry, stock rank, pe ,peg and stockopedia type,country of holder, if its in takeover talks and 8.3 form s have been lodged.
Its taken ages to have 1 years worth of data as I have to calculate (and recalculate business days to results as stockopedia or others dont have definite full year results in some cases .
To scrape out from the tr1 form and work out the previous holding versus current then the date of buy and the share price on that day will give you the amount.
Im only taking where there was 0% previous holding to 5% or more so not interested in the buys and sells unless its dumped all 5%
I need more data points so i can stick tableau over my excel sheet and analyse properly
Adding in certain metrics later to the sheet are not historically available in stockopedia so its a work in progress
My real portfolio is fairy large £ but looking for a tweak on it .
The pattern can be interesting out of 170 stocks (many are still awaiting result dates
So far stockopedia type for 31 winners
5 are super stock rating
6 are high fliers
13 are neutral
1 turnaround
3 falling stars
2 sucker stocks
1 n/a as its a trust/ jp morgan fund
Wise (LON:WISE)
Sharing a few bullet points from my notes today for any interested:
Negatives:
Admin costs to hit £1b, far higher than last guided (still +ve FCF and profitable.)
Are they spending to get the margin down to 16%?
Positives:
Exactly 2 years ago it was 0.54%
Is anyone else cheaper in the SME world?
Highest growth since end of 2022.
Highest # onboards ever (in FY22 they did 3.2m in the whole year.)
Nothing really to do with investing - unless you own shares in Thales and maybe some insurers.
If you ever wanted to own rare artworks, it might be easier than you think.
https://www.independent.co.uk/...
Wise (LON:WISE) , steady as she goes...
Latest quarter in red. no. 1 == Q1 2021. Not all info was available back then, hence the gaps.
Wise (LON:WISE)
Hi IsaAllowance
Nice charts, thank you for sharing.
One thing I would probably add to the Customer Balances chart is cash held in Wise Assets.
These are held off-balance sheet, but they still generate an income for the company.
For context balances here were £100m back in 2022 (so just before your timeframe starts), but they have climbed to £5.6b today.
A
BOE keeps rates unchanged although a 5-4 decision.
Big mistake!
Can they see what the Cable is telling them?
All the best
But central bankers hate being told what to do! I’m guessing they consider the budget to be a vital datapoint that needs absorbing before they act. Setting the national minimum wage increase anywhere near the ludicrous 6.7% set last week for the national living wage would have huge significance for the BoE. Not to mention the potential impact on Gilts of a poorly received budget.
If a central banker has a reason to wait before acting, they’ll invariably do just that!
Cable has spoken the last four weeks……. and they are not listening.
Take it from someone that also spends hours looking for opportunities in the property market (besides the US stock market)
the UK market desperately needs rate cuts.
All the best
Of course it does. But take it from someone who is often (including today) short or long cable futures, recent moves are about the budget - so the bankers will always choose to wait and see
Thought you lost a lot on your US portfolio cause you don’t hedge.
Remember you have posted this sometime this year.
The UK market desperately needs a rate cut and this has nothing to do with the budget as many rate cuts in the past (or even rate hikes) have occurred just before the budget.
Anyway……..take it from someone that actually trades (sometimes) the cable and publishes his trades before or at the time of execution.
All the best
I did and I’ve switched back to hedging on recent weakness in cable. Is that allowed?
Of course!
Is cable a buy or a sell now?
For the next 3 months
It’s a simple yes/no answer.
All the best
If I were a currency trader, I’d be short both really and it’s a question of which has more room to weaken. Next 1-2 months: short GBP (I am currently 80% long USD relative to exposure). 2-12 months I’d expect to short a higher proportion of USD especially if we head towards 1.26. I reserve the option to reverse the medium term view following the inevitable moves after budget day, however.
Thanks BnB
From only the political UK scene (current and future muppet show) I believe it is a long term short.
Also the continuous growth of stablecoins will create more demand for the USD, something that it is in its infant stage.
All the best
I agree GBP is a long-term short - and for the reasons you state. It’s the short to medium term where USD is expected to resume its fall that I’m concerned about. Trump and Bessent seem determined to achieve a much lower USD and the actions of market participants hedging in anticipation may continue to have a profound effect.
Growth of stablecoins will gradually increase the value of the dollar.
All the best
WOSG - in reply to your pondering on who takes the hit from the tariff, Graham, the experience across the whole US economy since April has been that importers, ie WOSG, eat 70% and the consumer 25%. The exporter barely notices. But luxury watches is a category uniquely produced in Switzerland, so the consumer has no recourse to goods from other nations. All competing goods have risen in unison. And the product is used to signal wealth, meaning that a price rise actually adds to its appeal on one level. Consequently, there is huge scope for the importer to protect margins. Finally, the tariff negotiations between US and CH are still ongoing and there is every reason to imagine a rate could be agreed nearer the 15% struck with EU nations.
All that said, it’s something to keep a wary eye on.
If there is time it would be great to know your thoughts on Helios Towers (LON:HTWS). The market certainly likes the Q3 update today with a share buyback announced, expectations adjusted upwards and a rise in operating profit. I've been tracking this for a few days now after being inspired by Phil Hoffer's webinar on Quality Momentum stocks. I don't think this matches all his criteria but it definitely has strong QM characteristics. Revenue is reported on Stocko has having a 15.4% CAGR and profits growing rapidly. I managed to get some at the open so I hold. Clearly I'm bullish on this overall but would also like your thoughts about why they are planning to return so much capital to shareholders when they are in "structurally high-growth markets" and they have some debt they could pay down.
I like the look of it and think it fits Ed Crofts 'ahead of expectations' setup criteria:
https://www.stockopedia.com/co...
BT (LON:BT.A) (I hold) Just about good enough I think but shares often get hit on results day...sticking to forecasts and long term targets but emphasis here I think suggests they think the share price hinges on these sticking. So let's hope these don't slip.... I read over Diageo (LON:DGE) but don't see much evidence that the slide in earnings is over. They are caught between tariff pain and inflation ... a pull back in markets could further hit the consumer and mean this isn't defensive this time...stays a not really sure for me for now.
I actually ended up selling my BT shares recently. After trying to cancel my BT contract, it turned into a long, unnecessary, and expensive process time wise, which made me think something’s not quite right at a deeper level within the company. Then, when I see smaller players like Gigaclear expanding into new areas (like mine) and taking customers from BT, it’s hard to see how that doesn’t eventually show up in BT’s bottom line, regardless of the forecasts.
I agree that exiting any contract is somewhat painful...but wouldn't hold it against BT (LON:BT.A) . If pricing holds and they are allowed a decent return then the cashflow should accrue .... so im a little more relaxed. In an inflationary world costs of laying fibre are rising all the time which also helps them out competitively.
A strong update today from Frontier Developments (LON:FDEV) for their new Jurassic World Evolution 3 game. I have run the unit sales numbers to date though AI and hope its hallucination ability is under control. Upgrades ahead? I hold
....JWE3 exceeded 500,000 units at 16 days (vs. model ~496,000) and has higher revenue/engagement, its trajectory is ~10% stronger than JWE2 early on. Scaling the model proportionally yields ~1.24 million at 72 days. Factoring in the stronger momentum and upcoming holiday boost (as with JWE2), sales could reach 1.2-1.4 million by January 1, 2026
Google Search Trends have had JWE3 15% higher like for like vs JWE2 release. Panmure Liberum have upgraded eps by 24% this morning.
Yes Ed, The previous broker JWE3 sales forecast was modest, so I am not surprised to see a +24% EPS catch up attempt today. Operational gearing here will be substantial.
Add the EPS upgrade to a >10% SP Jump today, a SR of 96, together with past Earning Surprises, a 3Y Bowl showing Trend Clarity and new sequential 52Wk Highs. Frontier Developments (LON:FDEV) has a lot of Momentum anomalies going for it!
A bit more detail on the above - I've been tracking the Google Trends closely - in the first 3 weeks JWE3 had been 15% up on JWE2 in terms of search traffic like for like, and all the reviews were better than the previous game. So it's unsurprising that FDEV have pushed out a rather excited RNS.
I've never seen a company use the words "hits it out of the park" in an RNS before.
Ask jp morgan
Tan Delta Systems (LON:TAND) I hold
I've commented before on the potential of this small company but it's unlikely to register as important enough to be included in coverage by DMSR. However, the RNS this morning should awaken some interest amongst fellow investors. A Phase 2 trial with a global retailer (Amazon???) is definitely interesting to me.
Chris Greenwood, Tan Delta CEO said:
"This customer has tens of thousands of critical gearboxes across its distribution estate, all of which rely upon oil for lubrication and reliable operation. Continuous monitoring will enable them to plan and co-ordinate maintenance to minimise distribution centre disruption. Phase 1 proved to them that our sensor system does what it says and Phase 2 is seeking to validate this further as well as targeting the evaluation of the practicalities of a wider deployment and integration into their existing maintenance systems which are already very significant. Whilst the timing of this opportunity progressing into a wider rollout is currently unknown it is progressing steadily, is another very significant future opportunity for us and it is notable that the customer is paying us for the Phase 2 trial."
This is a small company in Sheffield that has developed a technology that is capable of saving large amounts of money in unnecessary maintenance costs or unplanned downtime. The latest news comes just weeks after announcing a trial with Shell Marine Products.
"About Tan Delta Systems
Tan Delta Systems is a UK-based technology leader in real-time oil condition monitoring. Our patented sensor technology and predictive analytics help businesses across sectors - including power generation, marine, manufacturing, and transportation - reduce downtime, prevent equipment failure, and optimise maintenance. With thousands of systems in operation globally, Tan Delta's solutions are trusted by OEMs and end-users alike to improve performance and lower environmental impact."
Tan Delta Systems (LON:TAND)
cheers rwh3ue
are the broker forecasts on stocky outdated ? ie have broker forecasts been removed?
the narrative per the interims was that its taking longer than expected for sales to be booked after trials - so the narrative within then outlook doesnt seem to align with 5 mill sales this year - i did only skim read i must admit.
so based on the narrative that sales are not picking up - and aligned wikth the factb they are down to £2 million cash - it doesnt look like they are at the point i would like a company to be at - would be nice if they were past the point that they investors had to experience additional delays compared to prior hopes. thats so uber common with companies on teh cusp of possible big things - that last hurdle of selling stuff on scale to make profit is the hardest.
i am not negative here they seem to have plenty of fingers in any pies - but if their stuff is so good with so many potential customers it would be nice if it simply sold itself - i understand that may take long periods of time to show products are working - if the system doesnt trigger any warnings for many months.
are sales expected to be £5 mill this year ? if not what are expected losses ?
Tan Delta Systems (LON:TAND)
rmillaree, I wish I knew but it looks as if there is no analyst coverage or broker forecasts that I can find. Zeus is the house broker but I don't have access to their research. Stocko clearly is in no better position.
Yes, they only have £2m in cash but there is no debt at the moment so I presume they could raise funds either through the banks or by issuing stock. They attracted a number of well healed private investors at the IPO so it's also possible that they may be prepared to support any future funding to protect their own investment.
It's clear they are focusing on some key opportunities despite having a great deal of interest from other potential customers. The technology has been thoroughly independently reviewed (by TUV) and found to be accurate and to do what it claims. You ask why it doesn't simply "sell itself" but that is exactly what it does. There is no marketing other than their website which features a number of case studies showing how cost effective previous sales have proved to be. Given how their devices need to be thoroughly integrated with the customers machines, it is understandable that timelines are extended. The fact that a customer is taking the time to evaluate beyond the first phase is very significant as it strongly suggests they expect to buy a lot of product. It's good to know they are paying TAND as well..
I am just a small investor with no access to information outside what is in the public domain. However, I think I can spot a promising niche technology when I see it and I follow closely any news that becomes available. The risk of failure exists with any company, even the big boys that attract a lot of comment here. I am of the view that taking an early stake allows me to gain the material upside for an affordable loss if it doesn't work out.
Tan Delta Systems (LON:TAND) I wish them well and I really hope they succeed. The UK needs more successful engineering companies.
However, what do they do that Poseidon https://www.poseidonsys.com/gu... , Gastops https://www.gastops.com/produc... , Argo Hytos https://www.argo-hytos.com/pro... and the newer Chinese competition such as Inzoc https://www.inzocint.com/ don't do? They are entering a competitive field, and they are going to have to be good to survive as a newcomer. For me, it's one to keep an eye on, but way too early to consider investing in at this stage.
ISAallowance, thanks for your input. I will do some more research into competition. Maybe TAND have something that the competition don't have that gets it through the door of companies like this "Global retailer" aka Amazon I believe. I'll try to find out.
Looks like Rangeley Capital are finally out of Avation (LON:AVAP), having finally sold their last few percent of the company. Hopefully this will reverse the recent slide in the share price now the overhang has cleared.
Wise (LON:WISE)
Wise PLC – HY FY26 (H1 to 30 Sep 2025)
Strong half; classic “invest-to-grow” execution.
• Active customers +18 % → 13.4 m
• Cross-border volume +24 % ( +26 % ccy ) → £84.9 bn
• 74 % of transfers instant; 8 direct domestic rails (Pix live, Zengin imminent)
• Take rate 52 bps (-10 bps YoY) = strategic price cut
• Underlying income £749.5 m (+13 % YoY)
• Underlying PBT margin 16.3 % (top of 13–16 % range)
• Customer holdings £25.3 bn (+37 %); non-cross-border rev 41 % of total
• Wise Platform ≈ 5 % of volume → 10 % MT, 50 % LT
• Guidance reiterated: +15–20 % underlying income, ~16 % margin FY26
• Dual listing (Q2 2026) on track; stablecoins optional only — Wise remains fiat-native.
Overall: volumes, instant share and rails all up; profits reinvested for scale.
Long-term story intact — Wise is quietly building the infrastructure others promise.
I read it slightly differently, underlying profit was down due to a large increase in admin expenses. I'd guess these were more like utility, rent, salary etc so don't see it as 'invest to grow'.
Interesting to hear if they explain where these costs came from.
That’s how I read it too. The overall report looks very interesting but I was struggling to find any commentary on my phone as to why operating expenses for the first half of the year were up 27% and profit before tax down 17% on 2024.
Thanks both — good questions. The RNS breaks the “admin expense” increase down fairly clearly (see CFO section). Total admin was +27 % YoY but +24 % excluding one-off dual-listing costs (£11.5 m) — exactly in line with last year’s growth.
Within that:
So the step-up is deliberate investment, not runaway overhead. Management reiterated the 16 % underlying PBT margin target and guided to ~£1 bn FY admin spend, which includes these growth areas.
Jamie Ward’s Wonder Stocks note this morning framed it neatly: Wise is intentionally reinvesting margin to widen the moat— marketing + price cuts now for scale later. (I’ll leave the detail behind his paywall.)
In short, costs rose because they’re adding rails, licences, staff and brand reach — all consistent with the long-term “infrastructure dominance” strategy, not an erosion of efficiency.
Fully agree. Market reaction looks short-sighted. Goody buying opportunity on any medium-term outlook, IMHO. (I hold).
Indeed, have been watching the recent pull back on price with interest over last months and was waiting for the update before deciding what to do, spent some time today combing through the report and am now of the view that its as good a moment as any, so have just gone straight in with a decent sized position at ~900p.
One thing I'll say for WISE is they have an eye for talent, they have poached some of my best staff over the years!
You’ve come in a fair bit lower than me; I’m ~£10.70 so congratulations
Thanks for this I'll watch this one for the time being but it does look like a share with significant growth potential.
Wise (LON:WISE) I held this until stablecoin started being touted as a risk. Up until then i had been intending to hold for years. Be interested to hear thoughts although I already jumped ship.
Really thoughtful point, Dr Dave — and one that’s been raised a few times since SWIFT and others started experimenting with stablecoins.
From our side, we see very little genuine threat to Wise here. Stablecoins are, in essence, another way of moving value — but they still need to clear regulatory, banking-rail, and liquidity hurdles. Wise already owns the key advantage: a regulated, fiat-native global network where ~65 % of transfers land in < 20 seconds, at a cost traditional banks still can’t touch.
Kristo has been explicit on this — he’s said Wise isn’t interested in “chasing crypto fashion.” Their goal is to make fiat transfers instant and cheap without compromising compliance or user trust. In his words: “If a better technology arrives that makes things faster and cheaper within regulation, we’ll use it — until then, the Wise network is the benchmark.”
Jamie Ward’s broad take (publicly shared) aligns: stablecoins are more of a headline risk than a structural one. They’ll coexist for niche use-cases, but they don’t fix the underlying frictions — onboarding, AML, FX conversion, or regulatory acceptance. Wise’s rails already integrate directly with Tier 1 banking infrastructure; crypto projects are still trying to build those relationships.
So my lens is:
Wise (LON:WISE) great answer thank you. I got spooked. Hope it continues strongly for you.
Wise (LON:WISE) I held this until stablecoin started being touted as a risk. Up until then i had been intending to hold for years. Be interested to hear thoughts although I already jumped ship.
Yeah, but what is stablecoin?
Basically it's a cryptographic token that's pegged to one or more currencies. The pegging may be direct (i.e. the service provider actually holds the underlying currency) or algorithmic (i.e. there's some complicated derivative management process going on that's supposed to underpin the pegging). Neither are perfect, both have lost their pegs at various times. If it happens customers will lose money.
To send money from (say) the UK to Dubai we have to:
Now probably what I'm doing is converting from sterling to USD and then USD to Dirham. The stablecoin transfer is near instantaneous, which is why the peg should hold (but it isn't guaranteed). The transfer itself may be near zero cost but the currency conversions on either side aren't. Stablecoin providers often make most of their money from interest on reserves - i.e. customer funds.
So, stablecoins may be an option for cross-border payments but:
So yeah, it's a threat, but no more than the multitude of other options out there. There are no free lunches and once onboarded and happy with costs people don't tend to shift.
If stablecoin really goes mainstream then there'll need to be some network providers that offer end to end services, including the onboarding and cash-in / cash-out processes, backed by a recognised, trusted and regulated brand. Basically Paypal and ... Wise.
timarr
Also a great answer thanks Tim. Definitely didn't want to lose my shirt AND my pegs. So I exited reluctantly. But good luck to you (Wise (LON:WISE)
Check what Revolut recently announced about stablecoins and easy crypto-fiat conversions - it's frictionless and low-fee, and they won't be the only ones.
Fair point — Revolut’s announcement made headlines, but it’s worth separating speculative rails from regulated infrastructure.
Revolut’s stablecoin layer still sits on top of third-party crypto networks — great for quick intra-Revolut transfers, but it doesn’t replace the banking connectivity, local clearing access, or global compliance that Wise already has in-house.
Wise’s system moves fiat directly between 40+ countries via its own licensed entities — instant, transparent, and legally recognised everywhere it operates. Stablecoin models still face regulatory uncertainty, FX spread costs, and conversion friction at the on/off-ramps.
In short: Revolut’s experimenting; Wise is already executing at scale. One’s building a bridge to the future, the other is the bridge.
Wise (LON:WISE)
"Revolut recently announced about stablecoins and easy crypto-fiat conversions"
I've only had a brief look just now, but I think the announcement refers to USD fiat to USD crypto and vice versa.
This still doesn't get around the issue of USD fiat to, for example, EUR fiat.
Someone somewhere is still going to be charging to provide the liquidity when a stablecoin needs to be withdrawn in the fiat world.
A
Check what Revolut recently announced about stablecoins and easy crypto-fiat conversions - it's frictionless and low-fee, and they won't be the only ones.
Revolut are absorbing the costs and don't hold the liquidity. Transactions are on network only.
timarr
Wise (LON:WISE)
Interesting to hear if they explain where these costs came from.
It's broken down in the report - there's no excessive growth in overheads and the underlying message is the same, they're sacrificing profit and margin now for future market share. Not something the Chablis swilling masses in the City of London like but far more palatable in New York.
They also mention the threat of stablecoins, which is a more realistic concern. For cross border transactions there's still a conversion cost but it'll be interesting to see if Visa's efforts in this area actually lead to anything concrete. Everything else they've tried cross-border has failed due to their unwillingness to take any risk.
timarr
EDIT: David Wordsworth's post breaks the numbers down from the report and expresses the business approach better than I've done here.
Thanks, Timarr — really appreciate that.
I’ve been slowly building something I call The Purfleet Method over the past couple of years — a structured, evidence-based framework for identifying and holding genuine multibaggers (Wise being one of our core case studies).
It owes a lot to Ed’s multibagger research — the entire original foundations — and quality thinking from Jamie Ward’s Wonderstocks work, which has been invaluable in deepening my understanding of flywheels and durable growth.
It’s not my full-time job — just a labour of curiosity and discipline — but the results so far have been encouraging.
Happy to chat more or swap ideas at Mello Chiswick (if I can actually sneak away from work!).
Always enjoy seeing proper discussion rather than noise.”
Hi David
Happy to chat more or swap ideas at Mello Chiswick (if I can actually sneak away from work!).
I should be there both days. Probably near the bar ... :-)
timarr
What an excellent string of informed comment ... saved me a lot of work this morning. This is where the value of Stocko really shines.
Thank you!
If we look at Wise through an analytical lens, it’s easy to see why it’s performed so strongly.
My framework looks for enduring flywheels — businesses that convert efficiency, trust and data into self-reinforcing growth.
Wise scores exceptionally across three pillars:
1️⃣ Economic Flywheel: Each new user lowers marginal costs and improves liquidity in its network — a true compounding loop.
2️⃣ Cultural Velocity: Management are operators, not storytellers. Their transparency and engineering discipline mean execution risk stays low.
3️⃣ Financial Quality: High ROCE, negative working capital, and real free cash generation make it self-funding — a rare trait for fintechs.
As I said my model borrows heavily from Ed Croft’s multibagger framework and Jamie Ward’s Wonderstocks insights, blending quantitative quality with qualitative endurance.
The result is a company that compounds not just profit, but trust. That’s why price volatility matters less than process integrity.
I’m simply a retail investor building structured conviction — but the method’s held up well so far for someone with an investment horizon of a number of years/decades ☺️.
Just out of interest as I listened to a podcast with some crypto bros discussing Western Union Co (NYQ:WU) - what is preventing others copying Wise (LON:WISE) ? stupid Q alert no doubt.
In a nutshell a decade of rails, infrastructure, and its organisational memory to work in 70 different countries.
Then you add Kristo’s obsession with being the ‘Costco of currency transfer’, B shares reasoning, and the fact he’s never sold a share yet.
Ok thank you, feels like the 6% SWIFT costs to banks helps them out a fair bit as long as it lasts ....
What caught my eye with Wise (LON:WISE) was the list of large international banks that use Wise behind their platforms to conduct their international transfers for their customers. They just can't do it as cheaply or quickly themselves. That and my sister saying how swift her transfers are (lives in Oz).
We need a means of identifying fellow ‘Stocko’ travellers! See you at the bar ;)
Thank you for sharing this. Just interested to know how you value it? Is there a PE ratio you consider “fair”? At circa 25, it’s up there with some MAG7 types. Thanks again.
That’s the rub I think, Jimbob — and one that even the professionals wrestle with.
Wise is unusually hard to pin down on a traditional P/E basis because it straddles tech efficiency and regulated finance. I think the “E” in that ratio still carries a lot of float-related interest income and heavy reinvestment into infrastructure, so it doesn’t yet reflect the true steady-state economics.
For context, Jamie Ward discussed this earlier in the year: rather than treating Wise as a short-term profit machine, I value it as a compounding network — a platform that grows volumes, lowers unit costs, and widens its moat every quarter. On that lens, today’s mid-20s P/E isn’t demanding. If you normalise for growth (~20 % underlying income CAGR) and capital-light scalability, the stock sits nearer a PEG of ~1.2 – 1.4, which is fair for a durable compounder.
In my own framework I don’t anchor on a single “fair” multiple; I look for compounding visibility + reinvestment runway. Wise’s combination of 50 %+ ROCE, rising customer float, and self-funded growth justifies a premium multiple — not because it’s a MAG7 clone, but because it has a self-reinforcing flywheel that's still early in its global rollout.
So yes, c. 25× looks full if you view it like a bank — but entirely reasonable if you view it like a network still doubling throughput every few years.
So sorry, I’m not sure that’s definitively answered your question but hopefully pointed you in the right direction!
VBW
D
Agreed, Wise (LON:WISE) (I hold) should be viewed (and valued) as a platform business, not a bank.
But... this only works in the long term for investors if the founder (who has just quietly slipped through an additional 10 years of control along with the US listing vote) actually wants to build a valuable platform business. What if he doesn't actually care about becoming rich, and just wants to make FX free for the World?
Possibly unlikely, but it must be a non-neglible risk. You can find his historical personal blog here: http://kaarmann.com/
There's some great content from bike riding, Ironman, snowboarding, though to more and more FX and business stuff.
<snip...>
That’s a really interesting angle — and I don’t think any of us outside the company can claim particular insight into Kristo’s inner ideology.
It’s clear Wise has always operated with a slightly different philosophical base to most fintechs. Kristo’s early writing (“National currencies are a UX disaster”) shows a genuine frustration with how inefficient the world’s money plumbing is — but not a desire to replace it with something speculative. The goal was, and still is, to fix it.
Profit at Wise isn’t treated as an end in itself; it’s the by-product of scale efficiency. Each corridor, customer, or partner added to the network makes the next transaction cheaper and faster — the classic compounding flywheel. That’s a very Visa/Mastercard-like model, just applied to currencies rather than cards.
So while the mission can sound ideological — “money without borders” — it’s actually deeply commercial: make transfers instant, convenient and (eventually) free because that’s the only sustainable way to dominate global payments infrastructure.
It’s a rare mix of principle and pragmatism, and probably one reason Wise feels so different to most listed fintechs.
Thanks again for your insights David - I have researched and started putting a few quid into WISE. Hard to believe their main product is so simple and not been done before. It does look like a good long term growth prospect - scaling to build a dominant position etc. And a potential cash cow when going well. There is a lot to like. Any thoughts on why it has been falling since early Sept 2025?