Daily Stock Market Report (Thur 8th Jan 2026) - TTG, DIA, CAML, ABF, MKS, GRG, TSCO

Good morning!
Today's Agenda is complete. Spreadsheet accompanying this report: link (updated to 16th Decembeer).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Shell (LON:SHEL) (£152bn | SR63) | Shell narrowed its projected range for fourth-quarter liquefied natural gas production to between 7.5 million metric tons and 7.9 million (Reuters). | ||
Experian (LON:EXPN) (£31.6bn | SR67) | “After a highly successful tenure as Chair”, Mike Rogers intends to retire at the AGM in July. Was on the Board for nine years, seven as Chair. | ||
Tesco (LON:TSCO) (£28.9bn | SR78) | Like-for-like sales: Q3 +3.1%, Christmas +2.4%. Total 19-week period: +2.9%. “Outperformed market on both value and volume basis”. Now expects FY26 adj. operating profit at upper end of the £2.9bn to £3.1bn guidance range. | AMBER/GREEN = (Mark) [no section below] There is a theory in food retail that if you win Christmas, you win the rest of the year, as customers tend to stick with a particular retailer into the New Year. While we haven’t seen all the supermarkets report, the figures here look pretty strong and potentially mark Tesco out as a Christmas winner. It doesn’t seem to be just sales either as they are now guiding profits at the upper end of guidance. However, the share price is off 6% today. It seems to be an issue of expectations management. The market actually expected UK Christmas sales to be stronger than they were, and the lacklustre performance of wholesaler Bookers may be giving some investors pause for thought. It is also worth bearing in mind that the rating on a number of valuation metrics looks a little higher than rivals such as Sainsbury’s and M&S. Historically, Tesco has generated higher returns on capital, so perhaps deserves a premium rating in the sector. Plus, this is the second minor upgrade in a row, meaning that it makes sense to stay broadly positive. | |
Associated British Foods (LON:ABF) (£15.3bn | SR86) | Primark has had a challenging start to the financial year, with a mixed performance. Food businesses also mixed. 16 week period: group revenue +1%. “We now expect Group adjusted operating profit and adjusted EPS to be below last year”. | BLACK (AMBER/RED ↓) (Mark) | |
Marks and Spencer (LON:MKS) (£6.76bn | SR52) | LfL food sales +5.6%, Fashion, Home & Beauty sales minus 2.9%. Food sales were strong while Fashion, Home & Beauty is “getting back on track”. Full-year guidance remains unchanged. | AMBER = (Mark) [no section below] This is another strong food sales number. Although, it is only a 2.3% increase by volume, as continued food price inflation plays its part in these figures. The rest of the business wasn't so great, seeing declines in LFL sales. Full year guidance being unchanged isn’t perhaps as impressive as it sounds, since it means a 20% fall in EPS. The good news is that the issues surrounding the cyber-attack seem to be in the past. If the company can deliver on the FY27 forecasts then this is going to start to look too cheap again. However, it feels a little early to upgrade our previously neutral view, given that it would be a big jump in EPS from FY26 to FY27, and Home & Beauty remains weak. | |
Computacenter (LON:CCC) (£3.28bn | SR87) | Buys a professional services business focused on the US enterprise market for up to $120m. | ||
Greggs (LON:GRG) (£1.81bn | SR70) | Q4 like-for-like sales +2.9%, total sales +7.4%. Full year like-for-like sales +2.4%, total sales +6.8%. Conditions remain challenging; gains in market share. Anticipates full year outcome in line with previous expectations. | AMBER = (Mark) [no section below] | |
Hilton Food (LON:HFG) (£445m | SR70) | NED becomes COO of the West region. APAC CEO becomes COO of the East region. New full-time Director of Investor Relations. | ||
Cerillion (LON:CER) (£363m | SR35) | Major new contract with Oman Telecommunications worth £42.5m, Cerillion’s largest contract win to date. “Helps to underpin existing market forecasts for FY26 and beyond.” | ||
Central Asia Metals (LON:CAML) (£345m | SR98) | Copper production of 13,311 tonnes. Zinc-in-concentrate production of 17,881 tonnes. Lead-in-concentrate production of 25,156 tonnes. Cash $80m. | AMBER/GREEN = (Mark) [no section below] | |
Beauty Tech (LON:TBTG) (£323m | SR-) | Continued to perform strongly through November and December. Anticipates that revenue and adjusted EBITDA for 2025 will be ahead of current market expectations (Will now be no less than £136.0 million and £35.5 million, respectively.) Remains confident in its outlook for the new financial year | ||
TT electronics (LON:TTG) (£197m | SR48) | “As only 51.77% of shareholders by value voted in favour of the Scheme, the TT Board notes that the Acquisition will not now proceed.” | AMBER = (Mark) [no section below] This is another company where shareholders have voted down a bid from a trade buyer that was recommended by the board. The chances of it passing did look slim after 24.5% holder DBAY publicly said that they didn’t support the bid. The plot thickened after the Board revealed that DBAY themselves had tabled an inferior bid. However, the details of the vote released yesterday afternoon show that DBAY weren’t alone in opposing the 150p Cicor offer, and preferring that the company remained independent. In reporting this news, the company also included a trading update. “At least in line” is good news. However, it is worth noting that since I reviewed the company’s H1 results (when I said FY numbers looked a stretch), the broker EPS consensus for both forward years has been cut by a mid-teens percentage. So while shareholders rejecting a 150p bid suggests that there is still long-term value, the near-term rating isn’t inspiring, and there is much work still to do for the management to turnaround the business. So with a middling StockRank of 48, I’m sticking with our previously neutral view for the moment. | |
Dialight (LON:DIA) (£145m | SR81) | Now expects to exceed market expectations for Adjusted Operating Profit (prior consensus $8.6m EBITA) for the year ending 31 March 2026 and beyond. Non-Underlying costs for the year to be approximately $4m. Net debt closed at $10.3m on 31 December 2025 (30 Sep: $10.2m). | AMBER/RED = (Mark) | |
Kistos Holdings (LON:KIST) (£143m | SR55) | Production for 2025 averaged 9,000 boepd at the top end of guidance. 2025 proforma exit production rate was 22.7k boepd. FY26 proforma production guidance remains at 19-21kboepd. Adjusted net debt $81m. | ||
Quartix Technologies (LON:QTX) (£138m | SR80) | Revenue and adjusted EBITDA (under current accounting policies) are expected to be ahead of current market expectations. ARR +14% to £37m, FCF £5.1m, Cash £5.6m, Final Dividend 7.5p. | ||
Orosur Mining (LON:OMI) (£92.6m | SR29) | Infill hole results: o PEP072B - 47.60m @ 3.43g/t Au from surface o PEP073 - 104.45m @ 5.96g/t Au from surface o PEP074 - 71.35m @ 6.46g/t Au from surface Drilling restarts at Anzá after Christmas break. | ||
Rentguarantor Holdings (LON:RGG) (£45m | SR18) | FY Revenue +88% to £2.4m (£2.2m consensus). Adjusted operating loss £280k higher than expected (£416k prior consensus) due to accelerated marketing costs. | BLACK | |
Cobra Resources (LON:COBR) (£44.8m | SR19) | IP Survey defines two additional large scale chargeability targets. | ||
Palace Capital (LON:PCA) (£42.1m | SR54) | Palace Capital confirms it received a valid requisition notice seeking to appoint Christian Kappelhoff-Wulff and Valentin Pierburg to the Board and remove the current Executive Chairman Steven Owen with immediate effect. Company views Lakestreet’s comments about Steven Owen's remuneration as “inaccurate and misleading”. | ||
Mobile Streams (LON:MOS) (£39.7m | SR12) | The Acquisitions of Estadio Gana and Capital Media Sports will complete immediately on admission to trading on AIM which is expected at 8.00 a.m. today. Change of Name to Gana Media Group plc. | ||
Medpal AI (LON:MPAL) (£26.3m | SR7) | “MedPal app's AI now analyses aggregated user health data, including body mass index ("BMI"), to identify individuals who may benefit from clinically supervised weight management and GLP-1 treatments or other supplements or medicines that can be obtained via the Company's online MedPal Clinic.” |
Mark's Section
Dialight (LON:DIA)
Flat at 360p - Third Quarter Trading Update - Mark - AMBER/RED
The market reaction to the newsflow here is a mystery to me, with the shares having trebled since the Summer:
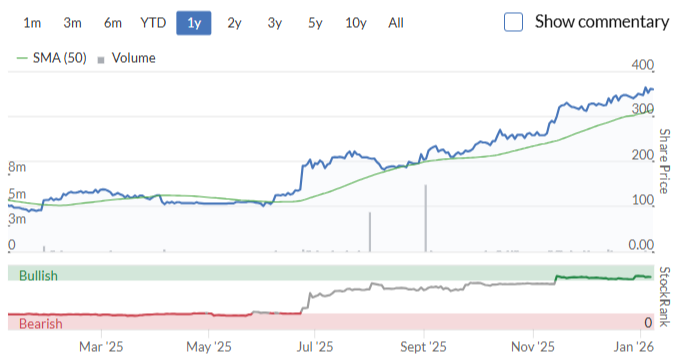
It kicked off with a 20% jump in share price in response to FY25 results, which in itself looked a little strange. While cost-cutting had got them back into profitability on an adjusted basis, there was still a huge statutory loss and the going concern statement said that:
…“the Directors have identified circumstances which give rise to a material uncertainty which may cast significant doubt on the entity's ability to continue as a going concern, meaning it may be unable to realise it assets and discharge its liabilities in the normal course of business.
When Graham reviewed their trading statement on 1st September, he continued to highlight the lack of balance sheet strength, although at that point the company said they were “confident of meeting current market expectations”. But it was all a bit confusing. They said:
Year-to-date adjusted operating profit at the end of August 2025 is expected to be strongly ahead of both the six months to 30 September 2024 ($0.9m) and the six months to 31 March 2025 ($3.2m).
But why not just quote the higher figure of the last H2, and why report an in-line TS for 5 months when you could wait a month and have the HY numbers? It seems that their adjusted figures appear to include a couple of one-off gains, and it was not clear that they had adjusted these out:
This result includes the benefit of a one-off Covid credit from the US Internal Revenue Service of $1.4m, as disclosed with the Preliminary Results in July 2025. The current year result has further benefitted from foreign exchange gains of circa $0.8m.
By the time the expected HY trading statement arrived, they said
Demand trends and operating conditions in the Group's end markets have remained soft with sales marginally down on the prior year as a result of tariff uncertainty, the softer macro-economic climate and the impact of this on the Group's hazardous end market sectors. The Group remains cautious on the sales outlook for the full financial year to 31 March 2026 due to this continuing uncertainty.
But cost-cutting rode to the rescue:
The continued benefits of the delivery of the Transformation Plan are that the Group now expects to significantly exceed the market expectation for Adjusted Operating Profit for the year ending 31 March 2026.
But they were clear at this point that this excluded the one-off gains.
Adding to the mystery, the broker consensus didn’t change:
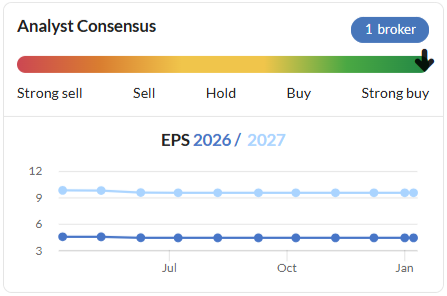
Although we did get an Edison note at this point forecasting 17c of EPS for FY, which works out at around 12.6p. This suggests that, what I presume is research from Investec but we are unable to view, either isn’t being updated, or is not being captured by Refinitiv (Stockopedia’s data provider). Edison so far seems unwilling to commit to a FY27 forecast, meaning that this FY26 figure is all we really have to go on.
The results themselves added little new information, although the directors did consider that there is no longer a material uncertainty, which was good news.
Today’s trading update reveals a similar pattern, with ongoing sales weakness (not quantified) offset by better-than-expected cost-cutting, leading to:
The continued benefits of the delivery of the Transformation Plan means that the Group now expects to exceed market expectation* for Adjusted Operating Profit for the year ending 31 March 2026 and beyond.
They seem to be quoting EBITA here as the footnote says “Market expectation $8.6m EBITA (Earnings before Interest, tax and amortisation)”. Although this figure isn’t in the Edison note, they do forecast $17.1m EBITDA and depreciation is running at around $5.4m annualised including IFRS16. Meaning Edison were forecasting around $11.7m EBITA. Even with the company now saying they will beat the $8.6m EBITA figure, this looks a miss versus Edison’s figure. I can’t see any updated coverage to be sure. Presumably, their Broker and Financial Advisor, Investec, had a much lower figure in their research.
On top of this, EBITA is not Operating Profit. At the half-year, the company amortised $1.4m of intangibles, but capitalised $2m of intangible development. I’m going to be generous and assume they are now doing $10m EBITA, which means we have:
- $2.8m annualised Amortisation
- $2.6m annualised interest charge
- $1.8m annualised tax
= $2.8m adj. PAT
With a market cap of $194m, they look to be on a forward P/E of around 70. Plus H1 PAT was $2.7m, implying that H2 will be barely profitable, even on an adjusted basis.
These also adjusted numbers and exclude non-underlying costs, where they say:
We expect Non-Underlying costs for the year to be approximately $4m (prior period: $21.6m) consisting almost entirely of transformation related activity, which will contribute to ongoing upgraded financial performance.
Given that the adjustments were a positive $0.4m in H1, this means that they have spent $4.4m on cost-savings in H2, in order to broadly break even, if my calculations are in the right ballpark.
Mark’s view
I know that I should be broadly positive on a High Flyer with this sort of StockRank:
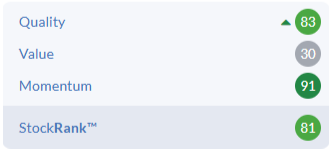
Especially, as the material uncertainty, which has been one of the major sources of our negativity, appears to have gone away.
However, there is so much uncertainty here, with different figures being quoted by the company, a lack of broker coverage (at least viewable by us), quoting EBITA while capitalising development costs, and the sudden reappearance of material adjustments. None of this builds my confidence that this is a company that has put a difficult past behind it. Combined with what looks like an incredibly high P/E, at least if my attempt to make sense of the mess of figures is right, I can’t help but keep our negative view of AMBER/RED.
Associated British Foods (LON:ABF)
Down 12% at 1890p - Trading Update - Mark - BLACK (AMBER/RED ↓ )
This doesn’t sound the worst profit warning, given that previous consensus was for only a 1% rise in EPS:
We now expect Group adjusted operating profit and adjusted EPS to be below last year, reflecting the guidance by segment set out above.
However, the new guidance means that revenue is now forecast to be £19.3bn versus the £19.9bn in the StockReport:
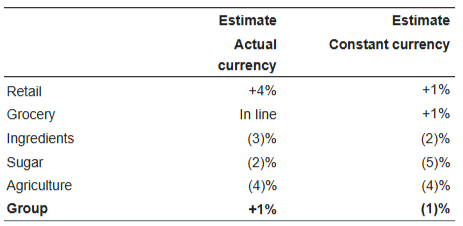
Partly this seems to be currency effects, but also specific weaknesses. Sugar and agriculture were already expected to be weak, but they are joined on the naughty step by the ingredients business:
In the US, we had expected ongoing consumer weakness to lead to lower sales. In our cooking oils and bakery ingredients businesses this year, the impact has been more acute than anticipated and we are more cautious on the outlook. As a result, we now expect both our Grocery and Ingredients segments to deliver adjusted operating profit for the full year that is moderately below last year.
The weakness in Primark is a little worrying, as you would expect that their value-orientated offering would resonate with the cash-strapped consumer in difficult market conditions. They claim that in the UK they have gained market share, despite LFL sales growth of just 1.7%. We have to be a little careful, as companies can always choose their comparatives, but if this is the case there must be a significant number of clothing retail losers out there yet to report Christmas trading. This also may be a worrying number for Shoezone investors, as this company tends to lactate their stores close to Primark in order to generate price-conscious footfall. Brokers are forecasting a 5% recovery in revenue there for their FY , and virtually flat Primark LFL sales over the key Christmas trading period might not help them achieve this.
The real damage in Primark is said to be in Europe where LFL sales were down 5.7%. The response was higher clearance sales in order to reduce stock, impacting profitability. They do say:
We have a broad range of initiatives in place and planned for the coming months, which we expect to drive improved sales and profitability, particularly in Europe. However, if Primark's current sales trends were to continue in the second half, we would expect the adjusted operating profit margin for the full year to be approximately 10%, similar to the first half, as we continue to invest in growth. It should be noted that in the first half of 2025 we had a non-recurring benefit to profit of £20m.
Without them really revealing what has gone wrong in Europe, it is really hard to judge whether their initiatives will have the desired impact.
Mark’s view
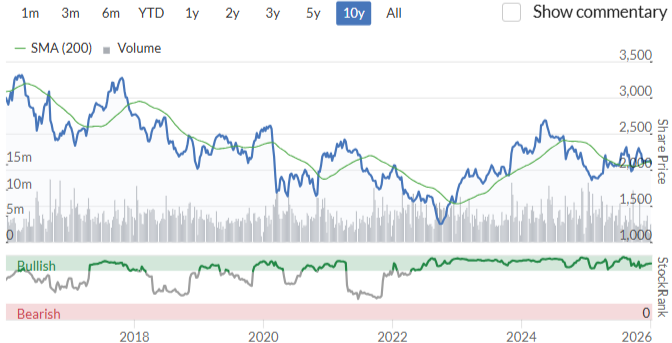
We’ve held a neutral view here in the past, as family controlled firms, such as this, tend to be good at taking decisions that deliver long-term shareholder value rather than looking for short-term market-pleasing headlines. However, looking at the chart, this has gone nowhere for a decade, and the 3% yield doesn’t exactly offset the capital loss:
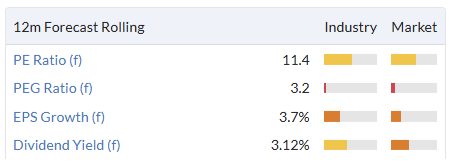
The forward rating isn’t crazy. However it doesn’t stand out in either the market nor its sector:
The algorithms actually rate this a Super Stock as it scores well on all three factors:
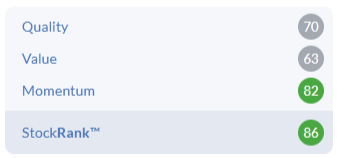
However, I think there are reasons to think that this will be short-lived. FY26 results being lower than FY25 will see Piotroski score fall, impacting the Quality Rank. The Momentum rank will also react to this, plus today’s share price fall. The Value Rank may not be as severely hit as the others as the declining EPS will be offset by the lower share price. However, the net effect will be a much lower StockRank.
This is clearly not a terrible company, but I struggle to see where the shareholder returns will come from from here. It is a combination of mature food businesses that generate pretty low returns on capital, together with a retail operator that appears to be struggling to resonate with its customers, at a time where being good value should give it an edge. While the profits warning may not be the most severe type, in keeping with the Stockopedia research in this area, I’m reducing our view to AMBER/RED to reflect the near-term outlook.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
CEO Andrew Walters has clearly built up and manages a very well-run company in what is no doubt a very competitive market. However, with the one exception about which he is very candid, he continues to manage the key elements that make up a very successful business. Frankly I wish I had picked the turnaround up earlier as a recovery stock when he returned after the German investment debacle. My increasing holdings would have been worth so much more in a relatively short space of time!
He and his current team should be complimented on many aspects.They balance charges, value, service, costs and therefore profitability exceptionally well. Perhaps they could have increased prices further, but I’m sure he weighed his decisions very carefully! Their overall approach has a great deal of similarity with the kaizen approach to operations, which I came upon as a consultant many years ago - always seeking to improve and recognizing there really is no limit, whether it be product, customer service, team performance!
They offer a superb piece of engineering which they are constantly trying to improve. Currently they have found ways simultaneously to cut the cost and generate better performance from new models.
It must be frustrating that the majority of their customers focus on only a fraction of the offerings the kit provides. However, they are working on simplifying the graphics so that presumably users will make fuller use of its capabilities and generate even greater savings from its use.
At the same time, they are broadening your offering e.g. with the dash cams which they have introduced in the UK only currently, which has already generated a significant sum to the bottom line (mentioned in the latest TU). Presumably, this will be offered more widely in future where practicable and relevant
They have a flexible model of professional-fit or self-fit, giving full recognition to the benefit of the former with their outsourced team of engineers. It takes time, but no doubt they will be aiming to increase the proportion of the former (professional fit)) whilst still keeping the latter (self fit) relatively simple.
Given their SAAS model and costs of recruitment, they appreciate that their levels of churn are more a reflection of their up-front credit control than dissatisfaction with their product or service per se. They are giving more focus to that, and it seems to be working well.
Their potential for growth seems to us to be almost limitless, though managing their presence in other markets probably needs more care and the costs of mistakes e.g. their previous Board’s error in Germany, much greater. However, they have identified the need for fuller use of the 4 routes to growth they mentioned in both the presentations to Mello Monday this year as the key routes where they can develop in the so far 4 ‘smaller’ countries. North America, particularly the US, must offer huge potential and I note that, though small, this could be a fast-growing market for them. Presumably as a service industry they will be are unaffected by the huge disruption of Trump tariffs and can move forward at a pace determined only by the resources they choose to apply to it.
I have examined in detail their success stories both in the UK/ROI and their smaller French presence (their two biggest markets) and they reflect the wide coverage their cost-effective solutions can reach and satisfy.
They talk about the clear difference between their target audience of e.g. plumbers and electricians and the massive essentially transit fleets of the Tesco’s and Sainsbury’s where say, Microlise have a large share. On the other hand, they have some ‘large fleets’ in their successes too. Although there is still a clear difference, they clearly don’t miss an opportunity when it arises.
They have built a very experienced team, and they have been with the company for some years, another reflection of a good and -in this case we sense - an inspiring employer. We also sense they do not have too big a core team to become impersonal.
It is clear from their success stories that Quartix appreciates the critical importance of outstanding customer service. Working at distance with a highly technical operation can lead to problems very quickly. They are clearly on top of both the technical and the personal side.
Finally, in my experience many private investors seem to take the stance that it is not up to us to act on say climate change, or health issues. It is not an easy question. However, where possible I am attracted to companies which do well and are also making a positive impact. I noted that of the 6 uses of services valued by customers, two are shared positives from my standpoint – reduce (fossil) fuel consumption and minimise carbon footprint. Also, despite the presidential team’s denial on climate change, I was pleasantly surprised to see on the Quartix US website a blog feature on emissions( https://www.quartix.com/blog/calculate-your-fleets-emissions/). Hydrocarbons and dangerous emissions will be with us for many decades to come and reducing them is a positive wherever we find it.
The CEO, Andrew Walters as the largest shareholder and with fellow founders holding around 50% of the shares seem to be very much in control of their own destiny in all key respects
The recent trading update from Microlise indicates that this is not an easy thing to do, and the results can be punishing Although the current PER is quite high at around 20x, I believe that the company is underrated. If the CEO and his team push forward with their very high potential on all the fronts they have identified, I believe that the growth rate and profitability are significantly underrated. Of course, the SP movement in 2026 will not replicate that in 2025 when they were still in recovery after the German debacle when Mr Walters stepped away from the running of the business. On the other hand, if they want to grow on all fronts, and that is by no means certain, then this could be a very worthwhile investment.
Superb post - thank you.
Quartix Technologies (LON:QTX)
For those following the construction and housebuilding sector, the S&P Global UK Construction PMI for December was released yesterday..
https://www.pmi.spglobal.com/P...
Reaction to the report....
https://www.buildersmerchantsn...
Very similar to November,subdued activity with reduced input costs.
cheers intuitive619
this is a very damning reflection with regard to the new government.
It seems plainly obvious too me that the one simple wthing to do is get the housebuldingn and contruction activity ramped up - and ramped up quite quickly - via whatever means is needed. If that be direct suport for construction firms to take on trainees hire staff - or for new projects to be started (heck provide advance fundiong to legit buisness needing a hand)
Perhaps i am being over harsh - policies take time to fed through but i dont think anyone doubts that ensuring activity takes place has huge assoicated benefits on the economy.
imho based on their pledge ref housebuilding when they came into power - it seems reasonably obvious that they have done f all which is super annoying. Ok they may say planning has improved - but if actual building of houses isnt ramping up its clear they will fail. They should have has laser focus on ensuring the building process starts
Hey ho perhaps there is hope that stuff might pick up soon if there is a time lag - i suspect we are all equally fed up with little light at the end of the tunnel - there seems more optimism than pessmism but i suspect thats due to them being battered so far down tehy now hope it cant get much worse.
Despite all their protestations everything they are doing is anti growth and inflationary.
Greggs (LON:GRG)
Despite all their protestations everything they are doing is anti growth and inflationary.
in what respects ?
Can't win them all. Yesterday's dabble in PayPoint (LON:PAY) could not have been timed worse if I had tried. From the moment I hit the buy button it has been one way traffic down. As Graham said, 'don't try this at home'.
It trading in a range for now. Difficult to know if its accumulation or distribution. Good luck.
I bought because it looked to be breaking out of the range - failed! I would much rather have bought at the bottom of the range than the top.
So often the case. I often get over excited and do the same.
Regarding Refinitive. Have you considered switching to Bloomberg or someone else ? Online reviews for the Refinitive service are not great.
The issues that have bugged Refinitiv, chiefly occasional outages and general high latency of the interface, are only a problem for professional traders at investment banks. For the buy and hold investor, or even day traders, it is a good alternative to Bloomberg at a much lower cost. We take the Refinitiv Eikon feed for about £1.5k pa.
Hi, I read that Stockapedia use Thomson Reuters Business Classification Schema (TRBC) for share sectors, but don't have Real Estate as a sector that Reuters list but have Telecoms instead. Any idea why this is?
I find the sectors classification barmy. I noticed in the NAPS portfolio that the Industrial choice was Gattaca (LON:GATC) thus putting a cyclical service company it in the same bucket as BAE Systems (LON:BA.). I think at the very least there should be four top level divisions - defensive services, defensive manufacturing, cyclical services and cyclical manufacturing. I also find that there are a bunch of other categories that you need different kinds of analysis like banks, miners, and trusts.
The RNS today for Ariana Resources (LON:AAU) indicates that Hong Kong Zinai Mining Services has gained one seat on the board of directors. My holding's share price stood at 158 pence this time in 2019, now at 152. Dividends stopped being paid in October 2022 in the Covid aftermath along with those of many other companies, it's one of my poorer choices I should say, and hopefully China's cash and Director will give Ariana a right kick up the rear.
Ariana should not have paid dividends. They needed the money to further develop their projects. Dividends don't come for free -anything paid out is reduced from the company's balance sheet and this is adjusted in the stock price immediately. If Ariana had retained that money it would be better placed now. Having said that I think Ariana is great value at present levels.
Given the interest in Seraphim Space Investment Trust (LON:SSIT) here is a link to their latest Space newsletter https://newsfile.refinitiv.com...
Odd to see that Mike Rogers is "retiring" as Experian Chair, he's actually leaving to take up the chairmanship of Nationwide BS
Seraphim Space Investment Trust (LON:SSIT) - Down over 10% this morning - Is this just the profit takers pushing it down ?
I think so. The discount has narrowed to almost nothing, or even a small premium following the ICEYE/Rheinmetall deal. Funnily enough I wrote about the trust this morning: Seraphim Space Takes Off - Alastair Kendall
I expect this to be a long term hold for me.
According to The AIC website the premium is almost 13%.
Seraphim Space Investment Trust | The AIC
Apologies but this is meaningless. The AIC premium calculation uses the last published NAV, which for SSIT is 119.55p as of 30 September 2025.
But since then ICEYE signed a major strategic deal with Rheinmetall (December 2025) which is a material uplift event for SSIT’s largest holding; listed comps in defence/space have rerated sharply globally.
SSIT’s share price has moved rapidly, but the NAV has not been updated to reflect any of this.
Hope this helps put your mind at ease. It could even be that the discount is even greater.
ICEYE valued at €2.4bn after €1.7bn German military contract and €150m Series E funding
Rheinmetall ICEYE Space Solutions, the joint venture between Rheinmetall and ICEYE, has been awarded a €1.7bn ($1.9bn) contract by the German Armed Forces to provide space-based reconnaissance. The agreement, running from late 2025 to late 2030 with options to extend, gives the German Armed Forces exclusive access to a dedicated satellite constellation for continuous, all-weather, day-and-night monitoring. [Read more]
SSIT was below 40p early 2025 on a hugs discount to then then NAV as I recall of 90p
Gemini AI calculates SSIT NAV as follows.
Please note this is an AI estimate based on latest announcements from SSIT
Thx ... So the discount has narrowed to between 3.1 and 7.9%.
Yes. I have been talking about SSIT for quite a while on the Investment Trust monthly Discuss board-as have others. If IPO floats- which is a possibility- the next question will be how do SSIT recycle the funds once they sell. They will probably need to as such a large % now and doubt they want- or shareholders would- it to become another 3i (LON:III) with one main holding like Action. I bought in 54p May25 and sold a few days ago at £1.24. Before the buy in May or so at 54p traded it on and off for a while as it was prone to dip in and out of favour. I am pleased the discount has narrowed- but for me at the moment it had run its course and other things beckon. I would not be adverse to buying back in, even at a higher price once there is more clarity.
Greggs (LON:GRG) Shares down 2.2% so far (I hold). I'm disappointed by the reaction. Sales up 7.4%. L4L were fine, too, at +2.9%. Plus they gained market share and said they had a strong pipeline of new opportunities. I guess the market didn't like the inline statement, or ongoing challenging conditions.
BAE Systems (LON:BA.) Shares up 6.3%. I'm thinking of top-slicing here.
Computacenter (LON:CCC) Shares up 4.3% (I hold). Looks like the market approves of the acquisition of $120m for $120m in sales, $14m in adj EBITDA.
TECHNICAL SUPPORT PLEASE: Are you sure the alerts are triggering correctly? I seem to be getting emails for price triggerings, but not fundamentals like Stock or Value ranks. Are they triggered only daily, or something?
Re. Greggs (LON:GRG), I think the negative reaction was to their forecast for 2026 - "...in the year ahead we expect to deliver profits at a similar underlying level to 2025, with any year-on-year improvement contingent on a recovery in the consumer backdrop."
In other words, profits will be flat which constitutes a mild warning against broker consensus.
Personally, I remain sanguine because it looks reasonably good value, the dividend is decent enough, it's a stalwart company with incredible brand recognition and consumer affiliation, it appears to be taking market share, the heavy Capex investment cycle is coming to an end - "capital expenditure will reduce significantly in 2026 and further again in 2027", it has net cash and they "expect to revert from net cash consumption to net cash generation."
It remains the most heavily shorted stock in the UK which baffles me somewhat for such an admired brand with a strong balance sheet coming to the end of an investment cycle but I suppose with flat profits into 2026, the p part of p/e might come under pressure.
I'm positive for the medium and long term investment case here but the market disagrees for now.
Thanks for that.
It remains the most heavily shorted stock in the UK which baffles me
somewhat for such an admired brand with a strong balance sheet
Yes, that's a bit of a puzzle to me, too. It's a good quality company on a reasonable valuation that isn't in any danger, making it an odd shorting candidate.
Greggs (LON:GRG)
I would agree with your assessment johnsmith - stocky has £6 million uplift in net profit for 2026 - ok we dont know what the different between underlying numbers and bottom line will be - but all things being equal thats mostly likely £6 mill lowering of expectations imho so we cant take any positives out of that.
As you i aint blmaing Greggs here not much they can do with consumer footfall and spending being low and the gov ramping up costs.
I'm positive for the medium and long term investment case here but the market disagrees for now.
To be fair to the market its simply adjusting to the fact there have been continual material dowgrades in expectations AND actual earnings in the last 12 month - thats at a time when greggs is ramping up the levels of debt it has - it should be easier to up profits when you are adding many new stores. The market is reflecting the fact that as things stand its not as rosy a picture as it looked when price was higher.
Greggs has always had good times and lean times over its history - i dont think they are doing much wrong at present - i have bought in aminor holding not so long back and personally i will not be upset if it drifts back to around the 1500p level as i could quite happily buy some more - if the specific news doesnt get worse in the meantime. Thankfully although this is clearly another downgrade - its manageable amount that has imho reasons beyond their doing.
I think one problem for Greggs is that no matter how good a company it is in many ways, it just isn't a growth stock any longer and will be rated accordingly going forward.
Greggs (LON:GRG)
I think one problem for Greggs is that no matter how good a company it is in many ways, it just isn't a growth stock any longer and will be rated accordingly going forward.
hmmmmmm
At a basic level imho i would completely disagree - greggs is cleary going through a phase of higher costs that are hitting margins - but its nonsense to suggest they are not a growing business when they clearly are - they have opened 121 net new shops in 2025 and are expecting to open 120 net new shops in 2026 - thats factually growth is it not ?
imho its common sense though that if you hit tough times and make less that will affect the shareprice - that has imho didly squat to do with long term growth plans.
You can argue the past better margins might not come back and that the profits might continue to struggle to increase but they are mostly certainly growing the business - thats a matter of fact !! - its also sensible to presume that the headwinds they have now wont always be there - they have been in similar spots in the past and bounced back. What clearly isnt helping is the general setup that the powers that be oversee that are the root cause of their problems - they are no alone in struggling as a high streeet chain at present.
Note greggs could perhaps have taken the easy option and gone into its shell and not invested - perhaps if they had know how tough it is they might have toned down growth plans - not sure if they could get better elase deals now that they have signed - its pretty simple formula though - if most stores make a profit the more you have the more profit you shoudl make - in that regard they are seasoned operators even if they may currently have a bit of egg sarnie on their face.
Note imho as pe of 10-12 - even if greggs did decide to stop expanding - and concentrated on returning cashflow to shareholders that wouldnt be a bad place as long as they run the buisness well and long term keepm increasing profits in line with inflation (they are clealry failing at present) - they also have easy other options - eg franchising the brand similar to spoons perhaps abroad / non uk airports etc - ok supply chain issues would make that tricky but you could have scaled down core menu with some local fare without too many problems imho
Another problem for Greggs (LON:GRG), and a reason I will not invest, is the blatant thieving that must impact their profitability. Example here in Greggs Coventry. This never used to happen when I was growing up.
https://www.youtube.com/shorts...
Outrageous video!
I did see the opposite though in a branch of Greggs at London Bridge station where staff blocked the entrance and exit when a group of youths wearing hoodies came in apparently intent on stealing.
Greggs (LON:GRG)
thieving is real and known and factored into current forecasts. Its already that poorly policed that i doubt its going to get materially worse. If anything i would suggest that at soem stage soem party might come into power that clamps down soemhwat oin theft - or police may do better job.
so comparisons with past mean nothing as this is known its already factored in imho . Do you think theft will get materially worse in next 24 months above the current trends the company would factor in ?
it most certainly happened when i grew up - my mates (not me honest guv) would brazenly steal sweets and other items from the local cornershop by asking teh owner to get soemthing from under the counter - they would also jump over his back wall and take teh bottles that paid money to return (that they had previously retuen too) - i would accept - probaably not as blatant - but back then there was no cctv to aid stuff.
If its homeless people stealing food so subsist hopefully greggs whilst not encouraging them realise that it is what it is. the person in the linked video deffo should have an asbo from that town centre or be arrested for sure.
From a far right YouTube account - no agenda there then?
They might be opening up new stores, but if they've already reached saturation point then these new stores won't necessarily be particularly profitable (and might even canibalise sales from nearby stores). Ultimately growth needs to come from increasing demand for their products, not just from increasing the supply through new store openings. For me it is starting to feel an ex-growth business and probably priced about right.
I agree - there is saturation, and the nostalgic love of the sausage roll is being cannibalised by a generation that see their rapidly growing range of products and mischievous “customers”.
Rather than sickening us with too many more stores and pasty-R&D, they need to fix their existing stores and reinforce the nostalgic brand.
Greggs (LON:GRG)
They might be opening up new stores, but if they've already reached saturation point then these new stores won't necessarily be particularly profitable (and might even canibalise sales from nearby stores).
do you really think that is the case ? so you think they are so stupid they cant take data freom existing estate and suss out the score ? that viewpoint makes no sense. Yes stores many partly cannabile sales - they have had like 26 stores ikn newcastle for years and they will know if those eat into each other sales.
. Ultimately growth needs to come from increasing demand for their products, not just from increasing the supply through new store openings.
- stores will have limit to what they can sell and they will alwys have and always will try and max out sales per outlet there is only so far you can take each outlet
Yes they will always try and get more from each outlet - but practicably spoeaking there is a ceiling - its probably been the same for mcdonalds locations for like the last 20 years. dontb you think they have been trying to eke out more from less for the last 25 years that only works so far - unless you get something really cunning.
. For me it is starting to feel an ex-growth business and probably priced about right.
I am not saying its screaming value here - i only picked up a few myself at a level below the current price and that was before todays downgrade. without evidence that things are picking up they may get worse. imho though its clear that its the whole market that is struggling - they say they are increasing market share - i would concede they may pick favourable stat here.
Total sales for FY25 were £2,151 million, an increase of 6.8% compared with 2024, with like-for-like sales in company-managed shops 2.4% higher than those seen in 2024. Fourth quarter total sales were 7.4% higher than in 2024, with like-for-like sales in company-managed shops growing by 2.9%. Subdued consumer confidence continued to impact the food-to-go market, as did weather extremes earlier in the year. Against this backdrop, Greggs increased its market share of visits, including at breakfast and in the evening (Source: Circana, 12 months to September 2025).
Hey ho the future will tell us whetehr they are ex growth but with hundreds of new stores being added such talk is imho madness plain and simple.
In terms of new stores, yes they will undoubtedly have all the data and make the calculation that the new store will generate some additional profit, but my point is the level of additional profit is probably nowhere near what is was in the past - so some incremental growth from new stores but no longer a growth business.
I've been in a number of towns and quite shocked to see 2 Greggs literally within 2 minutes walk of each other - there's no way that can't have at least some impact on sales.
Greggs (LON:GRG)
I've been in a number of towns and quite shocked to see 2 Greggs literally within 2 minutes walk of each other - there's no way that can't have at least some impact on sales.
None of this is new and its been like that for decades to a lesser or greater extent and they have managed decent growth in profits throughout most of this time. I most certainly get your point that it could be an issue and it will always have been an isue to a minor degree but greggs are clearly happy to open outlets and they have delivered the bacon of profits - note there might be more subtle reasons here - if one wants to negotiate better lease renewal with landlords haveing nearby shops aint a bad barganing tool - historically landlords have called the blufff of tenants they might be less likley to do that with greggs. So it might be the easiest thing to do is get new lease with generous terms and fit out from scratch they dont sem adverse to closing outlets.
anyway to me the numbers are all out in the open and the reasons why they and many other retailers are struggling is out in the open - and thats due to the general issues at play - less football tough time ref spending and increasing costs - ref footfall they seem to be holding their head above water though compared to others.
we will have to wait and se if they return to profit growth matching the store growth
You make some good points but I suspect the company's ROIC on new openings is not what it used to be given higher fit-out, labour, ingredient, property and utility costs, none of which are likely to ease. So just opening new stores doesn't guarantee earnings' growth. The low-hanging fruit has been picked by now I think.
I think they will turn-off the new investment taps and become a cash-generative income stock over the next couple of years which is fine, but this will obviously be reflected in a permanent re-rating.
Hmm, re BAE Systems (LON:BA.) Mark, I look back to last March when I top-sliced it at 1610p with a wry smile. Give it more time?
https://open.substack.com/pub/...
is something wrong with stockopedia - why doesn't the market cap on Galantas Gold move (update) after the huge rally? Why is the market cap still displaying as £16.33m - that's the same market cap it was displaying a couple of days ago. We are paying for this service and we need accurate up-to-date data to be able to act on it!? If the market data displayed is wrong some investors might be wrongly led to think the company is a bargain still now? (i'm not saying it isn't but why doesn't the data update on the fly so to speak?)
Galantas Gold (LON:GAL) Blimey - Ive just looked on HL and it shows MC of £117m
I always check prices elsewhere, especially for smaller stocks Stocko just doesn't keep up.
I'd be wary about this one. 680m shares fully diluted according to their website. That's a mkt cap of @ £157m. Pre-production, new Chilean mines will require start-up financing so further dilution likely. Co & mgt have questionable history. Related party transaction. Having said that, 7moz + gold resource is certainly an eye catching headline.
This is just the tip of the iceberg on Stockopedia. I'm a mathematician by background and I've been really shocked at how bad their underlying data analysis is. I don't think they understand basic concepts, like what a time-series database is or even how to perform simple calculations. Some of their workarounds for things like consolidations of shares are just wrong.
My portfolio has ADDED UP THE NUMBERS INCORRECTLY many times. Literally, simple "what is the sum of this column" type things. I was so amazed I exported it into Excel to check. I've had to send them screenshots and Excel files explaining why the totals are wrong on things like the realised and unrealised gains. I've kept screenshots and files of all this, not that it makes any difference mind you, but I wanted evidence that their figures on something as simple as adding up a portfolio were wrong! It makes me really question what they're doing on the Stockranks - I can't believe they've got that right either!
I would hope that Stockopedia would publish a reply to this, please
Hi I also sent them a note a while agoabout the adding up of columns. For example the cost column is incorrect on many shares that I have bought and sold more than once. I dont think they really understood it and they dismissed what I was saying. I was super busy at the time and just let it go.
Exact same thing happened to me as well, Fegger. And yes, my cost columns aren't right either. I just don't think the portfolio side of their product is designed to work if you're dealing in and out of shares.
Yes all relating to this needs looked at. When the cost is wrong, the gain and % gain are wrong and if you dont realise this. it is very misleading.
Also in the transactions section, the cumulative balance is wrong/meaningless
Let me know what they reply and if it helps, I will send a chaser message myself.
Another good set of results from Coral Products (LON:CRU) this morning.
Underlying H1 EPS of 0.74p from -0.48p last year, so a strong favourable trend and accompanied by a positive outlook statement.
Double the EPS for a FY 1.48p EPS puts the business on a PE ratio well below x6 at yesterday's closing price of 8.25p.
Cashflow still weak and net debt high, but progress of sorts at Coral Products (LON:CRU) I suppose. I had to smile at the "outlook positively unchanged" comment. Now that's a 'glass half full' comment if ever I heard one!
Fair points. However, Coral Products (LON:CRU) operating cash flow before working capital movements is +£1.8m. Working capital movements take the operating cash flow down to -£0.5m but there is a strong history of unfavourable H1 working capital movements and favourable H2. If working capital stabilises (and I do concede the credit risk here), operating cash flows will tend to materially exceed operating profits. They have also made substantial investments, which have affected cash flows but should pay off in future revenues and margins.
The excessive net debt is the biggest issue here. With (normalised) healthy cash flows, this can be paid down quite rapidly. I just hope, with Joe Grimond gone now, the obession wuth divdidends is also gone and they focus their cash flows on sorting out the balance sheet.
Would be interested in a view on Central Asia Metals (LON:CAML) update if possible.
I very much hope you'll have time to take a look at the trading update from Quartix Technologies (Quartix Technologies (LON:QTX). i frequently mis-interpret RNSs and can be unpleasantly surprised by share price drops following what I'd thought to be positive news (hence the immeasurable value to me of the DSMR!), but I'll go out on a limb here and suggest that this trading update seems quite, um, good....?
Broker has upgraded Quartix Technologies (LON:QTX) this morning for 2025 and 2026.