Daily Stock Market Report (Tue 10 June 2025) - BPM, FTC, HOC, GBG, SXS, BWY

Good morning!
Congrats to shareholders in Spectris (LON:SXS) - news emerged yesterday afternoon of a possible cash offer at £37.35 (a premium of over 80%!).
Spreadsheet that accompanies this report: link.
We ran out of time for today, cheers!
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Frasers (LON:FRAS) (£3.3bn) | Frasers confirms it is considering a possible offer for Revolution Beauty (LON:REVB), which would be all cash if it is made. | ||
Spectris (LON:SXS) (£3.2bn) | Possible cash offer from private equity at £37.35 plus £0.28 interim dividend. Due diligence ongoing. | PINK (Graham) [no section below] | |
Bellway (LON:BWY) (£3.2bn) | Fully sold for y/e 31 July 25, FY units 8,600-8,700, “on track” to deliver FY volume and profit growth. Average selling price exp £315k (FY24: £308k). Forward order book +7.7% at 5,759 homes, expect further increase before year end. | AMBER (Roland) [no section below] Today’s update from the housebuilder supports the view that housing demand may be recovering, with management guiding for cumulative volume growth of 20% in the two years to 31 July 2026. As far as I can see, profit expectations are unchanged today. These suggest to me Bellway’s return on equity will remain in mid-single digits in both FY25 and FY26. The company is promising an update on its capital allocation plans later this year which may alter this view. But for now, I’d argue this level of profitability means the shares could be fairly valued at a slight discount to book value. Bellway’s share price has risen by 17% since I covered it in February, so I’m edging down our view to neutral. | |
Hochschild Mining (LON:HOC) (£1.6bn) | SP -22% to 236p | BLACK (AMBER/RED) (Roland) [no section below] Problems at the Mara Rosa gold mine mean that FY production is now expected to be well below previous guidance. This mine was previously expected to contribute c. 25% of group production this year. Based on the YTD run rate, I estimate today’s news could imply a c.10% reduction in FY production guidance for the group. Following the COO’s recent departure, HOC’s CEO has taken charge of this situation directly. An update on progress and revised FY guidance are promised in due course. HOC shares were trading on a modest P/E of 9 prior to today, but this relies on a stable gold price and hitting production targets – at least one of these now seems unlikely. I think it’s sensible to expect earnings forecasts to be downgraded based on today’s news, so I’m taking a cautious view until there’s more clarity. | |
Safestore Holdings (LON:SAFE) (£1.4bn) | Rev +4%, adj EBITDA -1.5% to £66.1m. LFL occupancy +0.6% to 78.2%. NTAVps +11.3% to 1,117p. | ||
Firstgroup (LON:FGP) (£1.1bn) | Rev +7.5%, adj op profit +9% to £222.8m. FY26: outlook in line with exps, adj EPS flat or better. | ||
Oxford Instruments (LON:OXIG) (£1.1bn) | FY25 results delayed due to audit request; remain in line with exps. NanoScience unit sold for £60m. | ||
GB (LON:GBG). (£675m) | FY25 in line with exps w/ rev +3%, adj EPS +14.9% to 17.4p. FY26 outlook unchanged. | AMBER/GREEN (Roland) The main weakness of these results seems to be limited top-line growth and weak profitability. However, free cash flow was strong and for investors who are willing to look past the bloated goodwill line on the balance sheet, I think underlying profitability could be attractive at the current valuation. I’m leaving our moderately positive view unchanged and will continue to watch GB’s turnaround with interest. | |
Tatton Asset Management (LON:TAM) (£363m) | Rev +23%, PBT +29% to £21.6m. Record net inflows of £3.7bn, AUM +24% to £21.8bn. Outlook unch. | ||
Filtronic (LON:FTC) (£285m) | Received follow-on SSPA order worth $32.5m for FY26. Confident will exceed FY26 rev exps. | AMBER/GREEN (Roland) | |
| Gulf Marine Services (LON:GMS) (£246m) | General Meeting | Shareholder GM request proposing board changes & dividend found to be invalid, again. | |
B.P. Marsh & Partners (LON:BPM) (£233m) | PBT +140% to £104.7m. NAV +42.4% to £326.4m (890pps). Outlook: “robust pipeline”. | GREEN (Graham) Looking at some data points, I think the current share price offers a discount to NAV that is fairly normal for BPM. While there is some risk that scaling up their investment strategy will bring challenges, I think they are highly credible. | |
Quadrise (LON:QED) (£90m) | Updates on various trials. Has momentum but some are taking “longer than originally anticipated” | ||
Vianet (LON:VNET) (£22m) | Rev £15.3m, PBT £0.9m (FY24: £0.8m). Confident for earnings growth in FY26 and beyond. | ||
Powerhouse Energy (LON:PHE) (£22m) | Very late results. Rev £0.5m, op loss £4.7m. Focus on marketing its feedstock testing unit in 2025. | ||
Surface Transforms (LON:SCE) (£17m) | Rev +13% (£8.2m). Loss after tax £22m. Outlook: continued growth. Material uncertainty. | ||
Zinc Media (LON:ZIN) (£16m) | Further Middle East Growth [contract award] | Seven figure commission in the UAE. No reference to any change in expectations. | |
Diales (LON:DIAL) (£13m) | H1 revenue flat (£21.6m), adj. op profit falls to £700k. Outlook in line. Higher enquiries in Q2/Q3. | ||
IXICO (LON:IXI) (£11m) | Imaging analysis via IXICO’s AI-driven platform supported FDA clearance for a new blood test. |
Graham's Section
B.P. Marsh & Partners (LON:BPM)
Up 4% to 650p (£241m) - Final Results - Graham - GREEN
B.P. Marsh & Partners Plc (AIM: BPM), the specialist private equity investor in early-stage financial services businesses, announces its audited Group Final Results for the year ended 31 January 2025.
I tend to be positive on this one due to its tremendous track record as an investor in its specialist niche - startup financial companies, mostly in the insurance sector.
Today’s results for FY January 2025 are excellent:
PBT £104.7m (previous year: £43.6m).
NAV increases by 42% or £97m to £326m.
NAV per share 890p or 847p fully diluted for shares in the employee benefit trust.
The extraordinary profits were helped by two large disposals during the year, so cannot be expected to repeat on a regular basis.
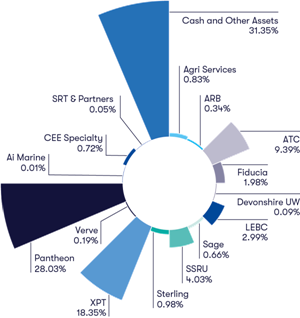
Here’s a visual breakdown of the company’s NAV. Overall diversification seems quite good to me, given that BPM is still only worth c. £300m:
Comment by Chairman Brian Marsh:
"I am pleased to report a year of exceptional performance, realisations, new investments, and cash returns to shareholders. B.P. Marsh creates real value, and, with a robust and diversified portfolio, we will continue to identify opportunities, support entrepreneurial teams and exit only when it is appropriate.
BPM finished the year ending Jan 2025 with a cash balance of £74m. The focus remains on new investments, but it has also enlarged its shareholder rewards:
Dividends: £8m is being paid out for the current year (including a £3m special dividend), and then £5m in each of the next two years. That’s 21.64p per share followed by 13.56p per share (twice).
Buybacks: under its current policy, BPM can buy back its own shares when they trade at a greater than 10% discount to their most recently announced NAV per share. As their most recently announced NAV is now 890p, I guess this means the company can buy back shares below 801p.
With a share price of only 650p today, I have to think they’ll buy back shares here. However, there’s an important limitation: the Chairman already owns 38% and the company doesn’t want to trigger mandatory bid obligations for him, or to increase his stake to over 42.5% (this was decided at a general meeting recently). So in practice, any buybacks are likely to be modest in size.
New investments: following the successful exits last year, BPM has also been reinvesting in the new financial year (FY Jan 2026). In both April 2025 and June 2025, it made new £10m investments.
Outlook sounds good, with good prospects for more deals:
We continue to demonstrate our ability to create long-term value and deliver strong returns. Deal origination remains active, particularly in the underwriting and broking sectors, and the new investments made during the year reflect the Company's proven capability in identifying well-positioned and compelling opportunities.
The Group remains committed to supporting its portfolio companies, not only with follow-on capital where appropriate, but also through strategic input aimed at unlocking further growth. With a robust pipeline of prospective investments in both the UK and international markets, supported by a strong cash position, the Group is well placed to act decisively where it sees exceptional potential.
Market commentary: for those who track the insurance sector, BPM informs us that premiums continue to soften, due to competition among insurers. Global insurance rates declined 3% in Q1.
Graham’s view
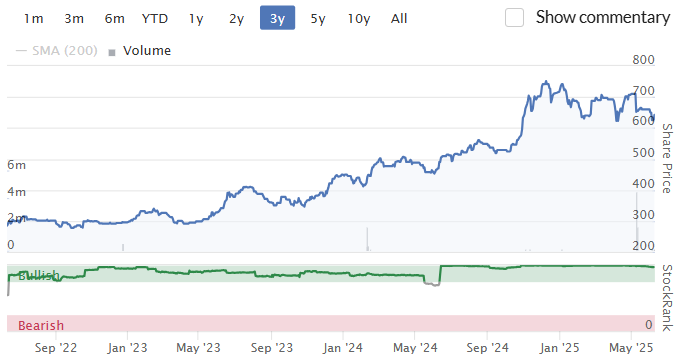
BPM is a class act and I regret not owning it currently - I have owned it in the past. Probably I should try to pick up a few while it’s still trading at this discount to NAV. Although it’s always a little tricky to buy when the chart looks like this!
I’ve gone back over the last five years and checked where the company’s share price was trading at the end of May each year, vs. the book value it published for January that year.
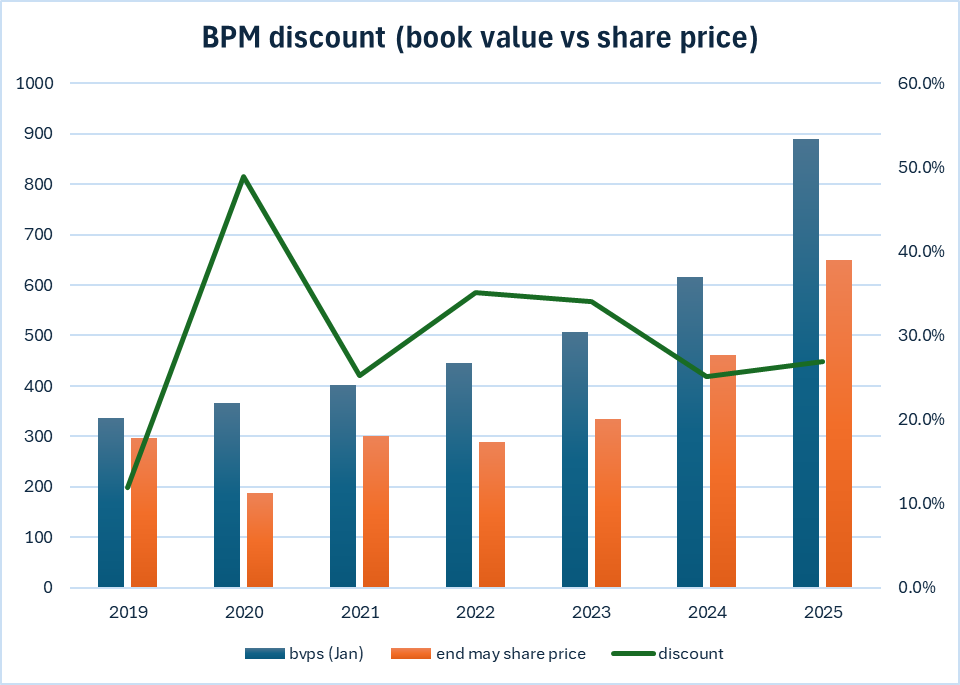
For the current year I’ve used today’s share price. While these are only a few data points, it seems to me that the current discount to NAV (27%) is pretty normal for BPM. It has been higher than this, but it has sometimes traded a little lower. Given its track record, I'm inclined to think the risk/reward is attractive!
Brian Marsh is 84 years old and has taken a step back for many years, with the company being run by a very loyal MD and Chief Investment Officer.
While I try not to get into the weeds of BPM’s specific investments - that’s the job of the company - I have noticed that one of their recent investments is quite unusual. They’ve invested outside of the insurance sector in a “buy-and-build” opportunity in the alternative finance space, called iO partners.
This obscure new venture has just bought a stock funding outfit called Seneca and a probate lender called Provira. I’m intrigued to see whether it will succeed - as I’ve just said, it’s an unusual investment for BPM to be involved in! The global investment giant Janus Henderson is a co-investor.
Overall, I’m very happy to stay GREEN on this. It’s a stock that I would not mind owning again.
Roland's Section
Filtronic (LON:FTC)
Up 8% to 140p (£307m) - Largest contract award to date with SpaceX - Roland - AMBER/GREENE
the Board is now confident the Company will exceed current revenue expectations for FY2026
Filtronic has secured a significant follow-on order from SpaceX valued at $32.5m (£24m). This is the largest order to date from the US satellite company.
The order is for Filtronic’s “market-leading E-band Cerus 32 Solid State Power Amplifier” (SSPA) – this product is used in SpaceX’s Starlink ground stations. This is the product line that has driven the high volume of orders from SpaceX over the last year or so.
Filtronic expects to deliver the majority of the order in the FY26 financial year, which runs to 31 May 2026.
The company also confirms today that Filtronic has exercised all of the 10.9m warrants it was entitled to under the agreements satisfied to date. This is equivalent to 5% of the company. I believe these warrants were exercised at 92.8p, somewhat below the current share price.
SpaceX has also previously exercised warrants relating to a further 4.96% of the company, taking the total to date to 9.96%.
Seeing as there is no trace of SpaceX in the shareholder register, I wonder if the US firm has immediately flipped its Filtronic shares.
Assuming the latest 10.9m tranche of shares were sold at 130p, that might have generated a c.£4m profit for SpaceX – effectively a c.15% rebate on the value of this latest order.
Updated Estimates: ahead of today, consensus forecasts were for revenue of £50m in FY26.
Today’s order is for nearly half this amount (c.£24m), so intuitively we might expect today’s order to have a material impact on expectations for the year.
However, as I’ve mentioned previously, FY26 broker forecasts were already pricing in a certain volume of new orders still to be received. This is normal for many industrial businesses, but unfortunately Filtronic doesn’t report order/revenue coverage for the year ahead in the way that some companies do.
This means that we have had no way of knowing how much of the forecast revenue for FY26 was already underwritten by committed orders.
Fortunately, house broker Cavendish has provided an updated note today including new forecasts and providing some insight into this situation – many thanks for making this coverage available.
The change to Cavendish’s revenue forecast for the current year is surprisingly modest, in my view, and profit forecasts have been left unchanged:
FY25E revenue £55m / EPS 5.9p (unchanged)
FY26E revenue +8% to £54m (previously £50m)
FY26E adj PBT unchanged at £8.3m
FY26E EPS unchanged at 3.2p
These update forecasts seem to suggest that once again, much of today’s new order intake win was already priced into expectations.
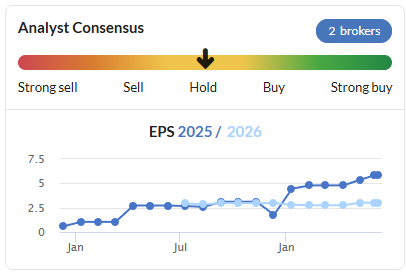
These numbers also mean that the overall shape of profit expectations shown on the StockReport remains unchanged, with earnings expected to fall by 45% in FY26:
Cavendish says it has left profit forecasts unchanged today because it expects Filtronic to experience additional upfront costs relating to recent new business wins (e.g. ESA, Leonardo and Airbus).
Further cash investment “in support of growth” is also expected, meaning that net cash forecasts have also been reduced for the current year.
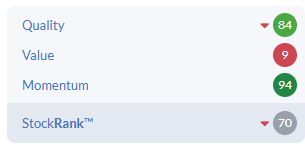
Filtronic shares are up by nearly 10% as I write. When paired with today’s unchanged earnings forecasts, this means that the shares are now trading on 44x FY26 forecast earnings. This valuation is reflected in the StockRanks’ very low value score:
No forecasts are yet available for FY27. I assume these will be initiated when Filtronic publishes its FY25 results, probably in late July/early August. In the meantime, this lack of visibility is a potential concern, in my view.
Roland’s view
I recognise that I’m at risk of sounding like a stale bear on Filtronic. This isn’t the case at all. I think the company’s achievements with SpaceX have been impressive and I’m very happy to see what could be another British engineering champion emerging.
However, based on current expectations, I think it’s fair to say the shares are expensive. I also think it’s fair to assume from today’s update and previous orders that at least 50% of FY26 revenue is currently expected to come from SpaceX, potentially from a single product type.
This kind of customer concentration is always a risk, especially as there seems to be a growing lack of visibility on future revenue beyond the current year.
Filtronic reiterated today that sales under the next phase of the SpaceX agreement are “subject to meeting certain criteria in relation to new technology”.
I don’t think management has provided much insight for outside investors on progress or timings relating to this new technology.
However, what’s clear is that Filtronic has been scaling up its cost base significantly – headcount rose by 16% in H1 25 and its manufacturing facilities have been expanded.
While recent contract wins with other non-SpaceX clients sound encouraging and should help to diversify the group’s revenue base, they haven’t moved the needle on forecasts. They also appear to require additional upfront investment.
My concern is that for some reason – political, commercial, or technological – the torrent of revenue from SpaceX could reduce to a trickle at some point, leaving Filtronic with a bloated cost base and too much capacity.
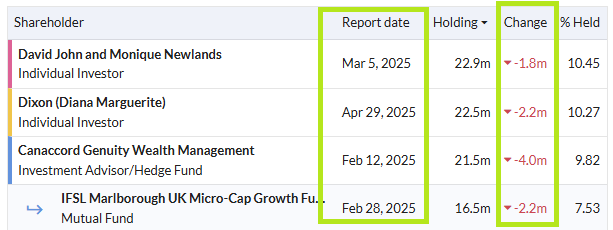
I would be more reassured if SpaceX had become a strategic shareholder with a near-10% stake, but this doesn’t seem to have happened. Instead, I’ve noticed that all of the company’s largest shareholders have been using this year’s strength to trim their holdings:
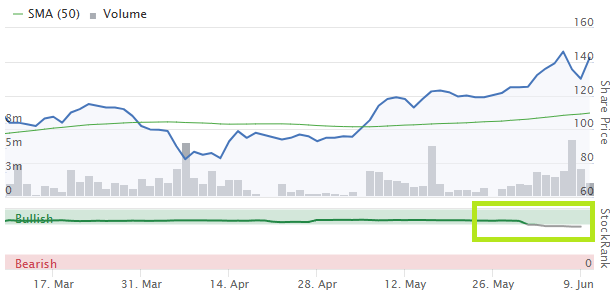
While Filtronic’s High Flyer styling remains unchanged, the StockRank has also started to fall recently, perhaps reflecting the stretched valuation:
Of course, I could be completely wrong. I think it’s fair to assume the underlying growth of the LEO satellite market will continue for some time yet, especially as European operators are increasingly planning rival systems to Starlink.
If demand for Filtronic’s SSPA type products remains strong and the company launches planned new products successfully, then the company’s growth could remain very strong for some time yet.
As I’ve stressed before, investors need to form their own view on this situation and decide how to proceed.
Personally, the combination of Filtronic’s valuation and the lack of any next-year forecasts means that I’m struggling to remain positive.
However, given the scale of today’s contract win and the stock’s continuing strong momentum, I feel objectively that it’s appropriate to remain moderately positive. My view remains unchanged ahead of the company’s year-end update and full-year results. AMBER/GREEN.
GB (LON:GBG)
Down 7% to 251p (£625m) - Final Results - Roland - AMBER/GREEN
Today, GBG, a global identity technology business enabling safe and rewarding digital lives, announces its audited results for the financial year ended 31 March 2025. These results are in line with the trading update published on 24 April 2025.
This digital identity verification specialist is a company I’ve seen as a potential turnaround and have been keeping an eye on.
Today’s results are billed as in line with guidance provided in April and expectations for the year ahead are said to be unchanged.
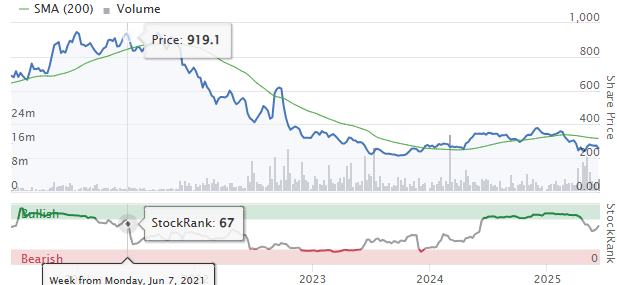
However, the market doesn’t seem impressed and the shares are down by 9% as I type, continuing a decline that’s seen the stock fall by over 70% in four years:
Let’s take a look to see what’s been happening.
2024/25 results summary: the company launched its GBG Go platform last year, which management says is an important step in the unification of its various services into a single global platform. Using GBG Go will allow users to “instantly verify identities and detect fraud”.
The group operates in three segments, two of which delivered revenue growth last year on a constant currency basis:
Identity +3.1%
Location +6.2%
Fraud -4.0%
In Identity and Location, net revenue retention improved to 101.1% (FY24: 99%), suggesting the firm’s products are fairly sticky and maintained their pricing power last year.
The fall in Fraud revenue was said to be due to the timing of licence renewals, with annual recurring revenue up by 5%.
This operating performance seems reasonable, although revenue growth seems pretty weak to me when inflation is taken into consideration.
This top-line weakness is reflected in GB’s group revenue, but profitability does seem to have improved last year:
Revenue +3% to £282.7m (constant currency)
Adjusted operating profit +9.5% to £67m
Adjusted EPS +14.9% to 17.4p per share
Net debt -40% to £48.5m
The numbers above translate into an adjusted operating margin of 23.7% (FY24: 22.1%), but this relies on a heavily adjusted profit figure.
Reported operating profit is markedly lower at just £22.7m, giving an 8% operating margin.
The vast majority of this adjustment relates to a £34.8m charge for the amortisation of acquired intangible assets. Rather than getting bogged down in a debate over the merits of this approach (which I dislike), I’ve turned to the free cash flow statement to see how much surplus cash GB actually generated last year.
The news is quite good, in my view. Free cash flow drops out at £41.6m by my calculations, midway between the group’s reported and adjusted measures of profit. This explains last year’s big reduction in net debt and gives rise to some potentially attractive metrics, in my view:
FCF margin (vs revenue): 14.7%
FCF yield (vs share price): 6.8%
The main weakness here for me is that GB does not seem to be generating very attractive profits relative to the assets on its balance sheet.
My sums give the following return metrics for last year (adjusted/reported):
Return on equity: 7.3% / 1.4%
Return on capital employed: 9.5% / 3.2%
These measures are similar to the quality metrics shown on the StockReport:
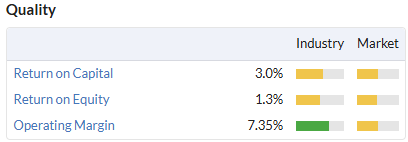
Even using adjusted profit, these profitability measures do not seem very high for a software group that claims a strong competitive positioning and boasts numerous high-profile customers for its identify and location services:
Outlook: management guidance unchanged, but there is expected to be an H2 bias to growth to reflect the strong performance in H1 last year:
The new financial year has begun as expected and our outlook for the full year is consistent with current market expectations. Given the relative strength of the first half of FY25, our FY26 growth in constant currency terms will naturally be second half weighted.
Exchange rates are also expected to be a headwind this year, albeit the company says the majority of this impact is already reflected in market expectations.
I don’t have access to any updated broker notes for GB.
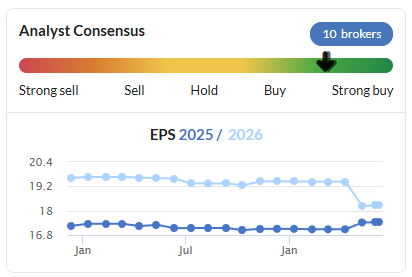
However, Stockopedia’s consensus figures ahead of today’s results suggested that adjusted earnings could rise by 5% to 18.3 per share this year. Assuming this consensus remains unchanged, this puts GB on a forward P/E of 13.5 after this morning’s drop.
One point worth noting is that expected growth this year narrowed sharply following April’s trading statement – analysts appear to have raised forecasts for FY25 but cut them for FY26:
Roland’s view
I would not be entirely surprised if consensus expectations edged slightly lower after today’s results. But I think the broad picture here could still be of interest.
My reading of the low returns being generated by this business is that they result from past acquisitions, perhaps in particular the £305m acquisition of Acuant in 2021. As a result of this and other deals, the balance sheet carries £550m of goodwill.
I’m not sure that current profits justify the past spending implied by this level of goodwill. However, this is in the past now. If management can resist any further expensive acquisitions, I think GB’s underlying profitability could potentially be attractive at the current valuation.
In my view, the missing ingredient that would be needed to support a share price recovery is stronger revenue growth. Consensus forecasts seem to suggest the top line will remain broadly flat again this year, unfortunately.
Without stronger evidence of momentum, I can’t take a fully positive view. But I’m going to maintain Graham’s previous AMBER/GREEN view today and will continue to watch GB’s progress with interest.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

81 comments
Companies on the RNS list.
Seven are under £100k - have no interest whatsoever - get a SR or 50 then will have a look but before then not interested.
I'm not some seed capital private funder wanting a way out.
Yes Rolls Royce after billions of years can now produce a Small Modular Reactor (SMR) or is it a Small Nuclear Reactor (SNR) - whatever presume Not In My Back Yard - understandably methinks (not the tech but the 10 years of concrete mixer trucks etc tearing up the highways).
I'm investing in UK Uranium mining companies.
Hi
Inward investments into Europe and UK .... data centres and real estate. A large investment site for data centre in Newcastle ...
Regards
Howard
B.P. Marsh & Partners (LON:BPM) - Hi Graham and agree your analysis today - Also watched the Investormeetcompany webinar this morning Interestingly, they now have a well known Fund involved - Wellington and a seller PSC which has been bought by a hedge fund. My question - will they now think of moving to the main market - or is there attraction in IHT relief esp for Brian Marsh - if indeed it qualifies ?
I doubt it will qualify for IHT relief as surely it counts as an investment company?
Spectris (LON:SXS) - potential 18% uplift to current SP too tempting for me.
Proposal price of 3763p is most recent in a series of proposals which shows Advent are keen. BoD minded to recommend if bid materialises at stated price. DD unlikely to reveal anything catastrophic in a FTSE 250 company. Another bidder not completely out of the question. Obviously, the downside is significant if Advent walks away but probably not back to 2000p - more like 2500p. Looks like one of the more likely deals to go through.
I hold from lower and bought more today.
Spectris (LON:SXS) - just seen your suggestion that regulatory hurdles likely account for the large potential mark-up on offer here. Grok thinks the closest analogy is Spirent Communications (LON:SPT) and that Advent will need to obtain similar (if not identical) clearances. The Spirent clearances have been ongoing since the bid was announced on 28th March 2024 but that bid did run into some regulatory issues and Spirent also announced weak trading which may have delayed closure. Obviously, the same could apply to Spectris.
However, according to a (rather lazy), Grok which refused to provide me with an average daily discount to bid price for Spirent, the average discount using the few closing prices it was prepared to use, suggested that the discount there has been much less than 18%. I'll continue to hold for a few months to see how this pans out as I would be happy enough to get 18% per annum on this from funds diverted from Supermarket REIT where I doubt there's a further 18% upside in the next year.
Hi Graham. The ticker on the first stock is for an ASX stock, not the LON listed BP.
BPM not 'BP'. Damn auto correct!
Fixed it, thanks!
Ouch - provisional HMRC PAYE data suggest that payroll employment fell by 109,000 in May
https://x.com/julianHjessop/st...
No surprise as both wages and NI have increased, from April. Companies have warned jobs will be cut.
Mara Rosa isn't the only gold mine that Hochschild Mining (LON:HOC) owns, is the 25 percent fall in the share price today justified?
Hi Silver Moon,
We'll be adding a brief comment on Hochschild Mining (LON:HOC) shortly, with an estimate of impact on overall production.
Roland
Hi Roland
Thanks, it will be much appreciated.
Morning All,
Costain (LON:COST) on the move?
Pension fund valuation news?
I hold.
Morning all just noticed Aberdeen (LON:ABDN) up a tad over 8% this morning anyone know why broker upgrade or such like ?
JP Morgan upgrade
Thanks Chris
Also tipped in the Times Tempus column, which can sometimes give a boost to share price.
Yes, broker upgrade although current consensus apparently remains ‘Hold’ on average, with a PT lower than current SP.
Noted in IC that short interesting also reducing.
** J.P.Morgan upgrades to "overweight" from "neutral"; raises PT to 218p from 164p
Aberdeen (LON:ABDN) - recommendation of the day in todays Times - which incidentally points out that of several brokers, 7 recommend sell.
I bought Aberdeen (LON:ABDN) after considering Graham's recommendation at the end of April. Currently I'm up 31.7%, and of course there is a substantial dividend on top.
Having lots of brokers with sell ratings can actually be a good contrarian indicator - lots of scope for upgrades as brokers take a more positive stance.
GB (LON:GBG) forward p/e of 13... surely a US PE takeover is now on the horizon
A forward p/e of 13......but only if you accept their heavily 'adjusted' earnings figure. I agree that the valuation looks compelling, but I shall be interested to see how happy the team is with the adjustments at GB (LON:GBG) . Also, the lack of organic growth for a business that should be sitting right in the 'sweet spot' of fraud prevention etc is a major concern.
Forward earnings aren't adjusted
No, maybe not - fair point. However this years' are and next year Stocko has only a very small rise in revenue forecast. Interest costs will be a bit lower but I'm not sure what else will drive underlying earnings significantly higher?
I think there will be adjustments made to forward earnings, given the amount of goodwill on the balance sheet. Lowiah growth too but for a tech company with a p/e of 13, that is all more than priced in. This is a rerating/takoever play ...
Lowish*
GB (LON:GBG) forward p/e of 13... surely a US PE takeover is now on the horizon
On the subject of valuations in the UK market. I am involved in an AI start up. I spoke a couple of weeks ago to a business that provides AI stock modelling for institutions. It uses tens of millions of data points to try to identify which stocks will outperform over a given timescale. They can show their track record adds 3-4% to performance a year. They sell to hedge funds, who generally look at stocks that will outperform over the next day to week, and institutions who may have a 3-6 month window.
The interesting thing is that UK listed stocks never appear on their screener, for the simple reason that over any period below 6 months, stamp duty makes them statistically likely to underperform. Nobody wants to buy something that will underperform for 6 months, and so nobody buys UK stocks. As more and more people rely on these objective tools (and Stockopedia is itself an example of an objective tool) the cycle becomes self-fulfilling.
I would add that morally, I think it outrageous that a UK government could seek to force UK pension funds to invest in UK shares at a time when the government levies the highest rate of stamp duty on shares of any large developed market. People should not be forced to pay for high tax products.
Surprised constituents of the AIM market with no stamp duty don’t occasionally make the cut.
Donald I am not so sure that I would agree it is anything to do with morals. I am not sure investment full stop has anything to do with morals. But I wouldn't argue with you that a rebalancing is overdue. However it is also worth mentioning that central government is there to provide service to us all and that has to be funded. At the moment all one hears is how to avoid and reduce taxes because that is appealing to individuals. At some point we have to make the decision do we support our country or ourselves. With defence required to draw more on public finances, no solution to our NHS problem in sight, energy recalibration in process, we need to find ways to invest in our country, in my humble opinion. Therefore expecting Pension Funds to invest in the UK holds water. The issue we need to address is how do we increase the competitiveness of UK companies and get UK companies on the screeners. The British people are known for ingenuity and creativeness it will be much needed in the coming years. Just my view from the bridge.
Hi Camtab i personally think we need to find a way to get the nigh on 9 million economically inactive back to work even 10% would surely make some form of a dent. I think the problem you have is the average working middle ranking Jo is thinking I pay 20/40% income tax , 8% national insurance, 2.5k average council tax from net income, car tax, insurance tax, fuel tax, vat on car parts and repairs, cgt allowance reduced to 3k that they feel they are paying in more than their fair share already.
You are correct we have virtually no army and no one seems to want to sign up to the army either these days.
Bellway (LON:BWY) - What is meant by the phrase ' fully sold'
Morning bohenie,
Re. Bellway (LON:BWY) and other housebuilders - I believe "fully sold" means the company has sold all the properties it expects to be able to build in the current financial year.
Roland
Thanks Roland - I should have guessed but it does seem it bit odd - with their year ending in just a few weeks but at least we can appreciate they are selling properties before finish of build - a bit like hot cakes maybe!
Hi Roland ,slightly off Bellway , but my daughter is FD for a Devon builder ,and reservations sound steady ,and I myself have 4 acres in Cranbrook [new town near Exeter]. They are getting to the end of the first phase of Cranbrook , and are literally working alongside my boundary. For reference they start at 7AM ,till 5pm Mon to SAT. I have taken a small position in BRCK after recent results ,and what is happening in my back yard. Tony
Morning Tony,
Thank you for your comment. It's very interesting to hear feedback from someone who is much closer to the ground than the RNS feed!
Roland
Bellway (LON:BWY) . I think it means that they have reservations for all sales in the budget.
Bellway (LON:BWY) They have all reservations to convert to sales to hit their volume target
Rolls-Royce Holdings (LON:RR.)
"Rolls-Royce SMR has been successful in the Great British Nuclear (GBN) competition to select a provider of small modular reactor (SMR) technology, in a boost to economic growth and exports that will create significant long-term value for Rolls-Royce (LSE: RR., ADR: RYCEY)."
https://www.rolls-royce.com/me...
TBH this one was probably a foregone conclusion given RR status, but good to see any uncertainty removed.
Yes I agree, and share price only up about 2% so fully factored in
Needs fuel, which of course is provided by Kazakistan and processed in Russia - not Scunthorpe.
Bit like rare earth minerals and magnets - again not processed in er Tunbridge Wells.
The premium is so high because Spectris (LON:SXS) was woefully undervalued both in absolute terms and in relative terms to international comparitors. There's a finite chance of a competing offer for what is an excellent business. I'm certainly not selling at these levels, and will be more than happy if the bid fails for some reason.
The valuations across UK markets are ridiculous, partly because of the gravitational attraction of US markets which has been sucking capital and listings away from other jurisdictions (Singapore, for example, has a similar problem) and partly because Brexit and the political instability thereafter led to a redirection of capital. The partial reversal of this in recent months may be due to the changes in both of those issues, or may simply reflect the fact that valuations at these levels aren't sustainable.
Just yesterday we also saw Alphawave IP (LON:AWE) being taken over from the US as well as the UK quantum computing startup Oxford Ionics, sold for £1.1 billion. Others will follow.
There's not much the government can do to stem the flow, although stopping giving UK investors a tax break to invest in overseas shares through ISAs is an obvious measure, albeit one that might not be very popular among the investing classes.
timarr
I agree tax breaks on SIPP and ISA to grow businesses abroad are a blight there should be a forced UK weighting to compensate for the tax break of investing in the UK.
That would be a far better way to drive tax returns thru higher corp tax than taxing pension contributions which is what I suspect we’ll see in the autumn.
Higher corp tax due to higher levels of investment in UK PLC but that requires long term thinking and hard work from Reeves so it won’t happen.
My recollection is that was the original point of PEPs (predecessor of ISAs) way back in the 1980s
Hi Timarr
Can't help but agree with your assessment The majority of UK companies of any quality are woefully undervalued by the market, albeit valuations have started to pick up over the last month or so, but in many cases remain some way off fair value.
Hi jonno
I seem to remember BnB trying to start a discussion on possible targets recently, but you'd think Oxford Instruments (LON:OXIG) and Treatt (LON:TET) would be vulnerable to a bid. Possibly Tracsis (LON:TRCS). I also wonder about the speciality chemicals companies, the likes of Croda International (LON:CRDA) and Victrex (LON:VCT).
Anyone else have any thoughts?
timarr
Maybe add in GBG?
Maybe add in GB (LON:GBG)?
Yeah, and also Renishaw (LON:RSW) where the founder David McMurty's untimely death leaves a 36% stake in play.
timarr
Why GB (LON:GBG) ?
Why GB (LON:GBG)?
Well, it wasn't my idea but I don't think it's a bad call. GB would be an interesting addition to any number of identity management companies, and they've been the subject of bid interest before, back in 2022. Probably only the economic downturn stopped that going through.
timarr
Oxford Instruments (LON:OXIG) - should we read anything into the delayed results ?
Oxford Instruments (LON:OXIG) - should we read anything into the delayed results ?
Probably not, there've been a few instances of this where auditors have struggled to finish their work for results day. At the very least it seems unlikely there's a bid behind the delay.
timarr
Timarr, some possible bid targets from my view. I hold all, so have a tendency to be biased, who knows?
MPAC (LON:MPAC)
Michelmersh Brick Holdings (LON:MBH)
Journeo (LON:JNEO)
Premier Miton (LON:PMI)
Sabre Insurance (LON:SBRE)
Van Elle Holdings (LON:VANL)
Restore (LON:RST)
Ramsdens Holdings (LON:RFX)
Bit of an eclectic mix, but all have their attractions.
My concern with Croda is they have lost a lot of their pricing power which I see in the market (as well as farming, I am a chemist). Their falling margins bear testament to this.
Victrex was an interesting one product company which has seen better days. They made hay after they were spun out of the old ICI business. These days, their PEEK product is being successfully challenged by better products, including Ducoya, produced by a subsidiary company (Duvelco) of Goodwin (LON:GDWN). The Vixtrex polymer is also facing stiff competition from St Dupont SA (EPA:DPT) product Vespel. The margins of Vixtrex have fallen by nearly 50% over 5 years which tells you everything you need to know about the competitive space for high-temperature polymers. My money is on Goodwin (LON:GDWN) .
One final point: Energy costs have a significant impact on the margins of the chemistry business and here in the UK we enjoy the highest energy prices in Europe, which Mllibrain's policies will only exacerbate.
It will be interesting where all this positions Victrex (LON:VCT) as a takeover target. Why buy something you are out competing and which has the misfortune to operate in the highest energy cost market in Europe?
Hi James
re Goodwin (LON:GDWN) product Ducoya vs Victrex (LON:VCT) product PEEK there is no comparison…Ducoya competes against Vespel from DuPont de Nemours (NYQ:DD) at a price point at least 10 to 20 times higher than the average PEEK selling price. Ducoya itself is chemically identical to Vespel but produced using a v different patent pending process which gives it attributes considerably in excess of those of Vespel which is why they are confident it will be a major business in the not too distant future https://www.aero-mag.com/raisi...
I should obviously add that I hold a non trivial portfolio % of Goodwin (LON:GDWN) shares
Hi jamesalastair
My concern with Croda is they have lost a lot of their pricing power which I see in the market (as well as farming, I am a chemist). Their falling margins bear testament to this.
Can't disagree with that. Alex Sweet gave a really excellent overview of the history here: https://sweetstocks.substack.c...
To summarise - they exploited their customers and it's eventually cost them. Not necessarily unrecoverable but not easy.
On Victrex (LON:VCT) I don't think Goodwin (LON:GDWN) (which I hold) is a competitor. They're in different parts of the market. Victrex's problem is that it's found it hard work to develop new markets for PEEK.
In both cases the valuations are, if not compelling, at least interesting but I'll happily concede that these probably aren't the cheapest stocks around ...
... oh, and the point on energy costs is well made. Croda have international factories so less of a problem, but Victrex don't. I don't see how the UK ever competes with cheap hydro-electric from the likes of Norway and Iceland, but at least if we didn't have the current stupid price setting mechanism where everyone pays at the marginal rate, there would be room for some regional price reductions.
Of course, the politics of that are difficult - persuading the heavily populated South East to pay more for energy than other parts of the country is tough, but maybe it would concentrate minds a bit more ...
Off topic. Time to move on.
timarr
Hi Tim I'm far from an expert or clued up on this but as far as I understand it UK's electricity is based on the price of gas even though we have as far as I'm aware stacks or windmills and solar.
As such what is stopping the Government from basing it say on the price of UK wind electricity (assuming its cheaper) ?
Hi Phoenix,
It is because the half hourly wholesale price is set using the most expensive form of generation required to balance the market. In short, marginal cost pricing. In the UK this is gas generation. Renewable are cheaper, not the reason prices are high.
If you google 'why are electricity prices based on gas' there is a pretty good AI answer.
David
Thanks David
Hi TP
DaveMcCabe is absolutely correct.
Roughly gas prices set the electricity price 98% of the time, while gas only produces 40% of our electricity. Renewables are far cheaper but consumers don't get the benefits of this investment and we end up with politicians arguing that we need more fossil fuels when this is unlikely to make a damn bit of difference to the prices we pay. If all of our electricity was produced by gas we'd pay exactly the same.
Battery storage solutions are part of the answer - situations where energy prices are set by gas making up a tiny percentage of the overall electricity output are not uncommon - but ultimately we need nuclear to take up the slack. And that's a decade away, at best. Oh, and improving the distribution network is essential, but try telling that to people who don't want nasty metal towers in their neighbourhood.
Energy pricing has to be reformed, and one solution is to regionalise. So if you have a lot of renewables in your area then you get the benefit of that. Trouble is, most of the voters live in SE England and don't have access to renewables - and don't want the nasty windmill things near them.
It's a massive issue and if we really want to get to net zero - and let's face it, it's not a question of if, but when - we need to address it now. Given this government's ability to dodge the difficult questions I can't say I'm confident, although they're doing better than the last lot who simply ignored the issue. Sizewell C, etc, will help but it will take way longer than people will tolerate.
But of course, Farage claims that more oil from the North Sea (a decade away, the wrong sort of oil and not enough of it) and restarting coal mining in Wales (let's see Gen X going down t'pit - he'll need a lot of willing immigrants to make that work) will solve the problem.
It's delusional, start to finish. Change is needed, and now, not later.
timarr
Thanks as always Tim.
Hi Timarr
Going through my portfolio I'd hope that at least one of the following (UK-listed companies) is on someone's takeover radar:
I'm aware that the latter x2 are not favourites on this site, but I remain a big fan of both.
With Everyman Media (LON:EMAN) UK cinema admissions are well ahead of last year.
The CEO has been highlighting how underlying cash generation excluding capex is good - I agree and hope that more positive figures will shine through soon as capex costs finally start receding after years of aggressive expansion.
A major shareholder has been increasing its stake over the last year.
When it comes to GYM (LON:GYM) you only need to look at the Annual Report of its main UK competitor Pure Gym, which itself was acquired a few years ago, to see the potential here.
Again, I believe underlying cash generation (excluding expansion capex) is excellent with an inflection point coming in the next few years.
A
Hi abtan
Under normal circumstances I'd consider the debt levels at GYM (LON:GYM), Everyman Media (LON:EMAN) and Avation (LON:AVAP) to be avoided. I've a very simple process - avoid excessive levels of debt, even if the assets look like they cover them. But if you think the cashflow warrants a look, I should probably do so. Certainly my local Pure Gym is always full these days whenever I can drag my sorry soul to it ...
LSL Property Services (LON:LSL), Gamma Communications (LON:GAMA) and Wise (LON:WISE) I hold. The former (I think) was after you pointed the board in its direction. It continues to look interesting. I also note that the vaguely similar Property Franchise (LON:TPFG), which I hold in volume, has taken off for no particular reason.
Gamma Communications (LON:GAMA) is cheap, but the sector needs consolidation. It'll be interesting to see which side of the equation they end up on.
And as for Wise (LON:WISE) - well, I've said enough. I don't need to further boost my confirmation bias ...
I'm wondering when we'll start to see bid action in the fund managers. They're all horribly undervalued due to market conditions, although the pick of the bunch (IMO) Tatton Asset Management (LON:TAM), reported excellent figures today.
Of course, Trump could wake up tomorrow and decide to annex Mongolia or make Trumpcoin the official US currency or replace Jay Powell with Jim Cramer or, well, pretty much anything. Best to enjoy the good times while they roll ...
timarr
Hi Timarr
Interestingly enough I totally agree with you on not investing in companies with too much debt. I definitely prefer companies with a net cash position.
However, for indebted companies if I see:
the contrarian in me always likes to take a deeper look.
---
AVATION
I don't think I'll change many minds on Avation (LON:AVAP), but perhaps these guys will:
https://east72.com.au/wp-conte...
Pages 4-24 (it's long!) explain why there could be value here.
---
EVERYMAN MEDIA
On Everyman Media (LON:EMAN) I personally think that the debt will be paid down rapidly now that expansion has slowed.
x2 new venues are expected to open this year, down from x3 last year and x6 in 2023.
I think that it's also worth noting that with H1 almost done, UK box office admission (£) and # YTD figures are +20% and +11% higher respectively vs last year.
This +11% figures excludes May, which should be an excellent month, as I'm still waiting for official figures to be published.
---
GYM
On GYM (LON:GYM) non-lease debt is indeed very high as you point out.
However, interest payments are mostly covered by cashflow and I believe (or rather hope!) that the company is at an inflection point whereby all costs will be comfortably covered by cash flow and debt will start to reduce materially.
I've included Pure Gym's trajectory over the last 4 years for reference.
This is their UK business only.
For context The Gym Group's Revenue and PBT for 2024 were £216.3m and £4.4m respectively.
Here's hoping things progress as I hope they will.
Abtan, thanks for posting that piece on Avation, very informative.
Just topped up opening position in HSS Hire (LON:HSS) .
PE of 6 with 8% yield. Should be beneficiary of government infrastructure projects.
We have the stupid position where our pension contributions are not being invested in British companies and jobs! Under-valuation is inevitably
Completely agree with timarr's comments re Spectris (LON:SXS. The price only looks good against the low valuation of manufacturing companies in this country, arising from a toxic mixture of an overvalued currency, costs for exporting companies being steadily inflated by government actions, and government discrimination against investment. Against international norms for a company of this calibre the buyer has got a bargain. It is a company I have held in the past, though not for some time.
A big order win for Filtronic (LON:FTC)
Just out of interest - Why an 80% premium? Seems rather excessive!
I guess the buyer saw value at that level, from memory if you look back in the chart it’s been valued above the purchase price in the past.
Sounds like the suitor had one K. Starmer negociating on their behalf!
That’s absolutely amazing, good pun.
B.P. Marsh & Partners (LON:BPM) - rather stunning set of results here - well done to management. Note normally I expect this share to be a bit of a plodder as the banking of gains will always be exceptionally lumpy in nature and there is potential for company to toodle along without much progress most years - so most certainly not results we can expect to repeat anytime soon. Looking at their current investments seems like their strategy is fine and dandy (despite some stuff new perhaps straying away from core competence) - overall their tried and tested plan of being insurance business funder-mentors particularly with startups seems to be a most excellent niche way of making decent returns for shareholders. My only slight annoyance here is at myself for top slicing some a while back.
Be happy I pulled out completely at about 500. Resigned to the fact if I ever want to get back in it’ll be substantially higher now. #BPM should in effect be a but and hold