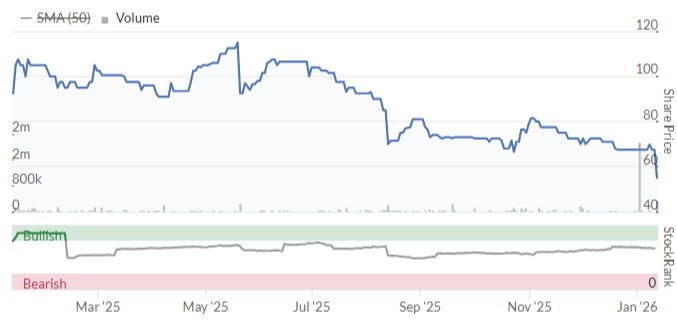
Daily Stock Market Report (Tue 13th Jan 2026) - PSN, SHOE, GAW, GAMA, RPI, HTG, TRST, PAGE, TMG, SAG

Good morning!
The avalanche of year-end trading updates has landed.
Wrapping it up there for now! Thank you.
Spreadsheet accompanying this report: link (updated to 16th December).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
Rentokil Initial (LON:RTO) (£12.0bn | SR69) | Mike Duffy is appointed CEO from March. The outgoing CEO is thanked for his “enormous contributions”. | ||
Games Workshop (LON:GAW) (£6.2bn | SR78) | Core revenue +17% (£316m), licensing revenue £16m (H1 last year: £30m). Core operating profit +28.5% (£126.1m). £1.10 dividend declared bringing the total so far in FY26 to £4.85. | GREEN = (Roland) Licensing revenue dropped in H1 and the receivables pipeline for the year ahead suggests a weaker performance is expected in H2 as well. However, the core retail business continues to grow and profitability remains exceptional, with margins above 40%. A 110p dividend declared today is a reminder of the group’s cash-generative quality and transparent policy on shareholder returns. While the stock might not be obviously cheap, I think the quality of this business justifies a stronger valuation than most others. On a medium-long term basis, I’m happy to maintain a positive view today. | |
Persimmon (LON:PSN) (£4.5bn | SR94) | New home completions +12% (11,905). Full-year underlying PBT for 2025 at upper end of market expectations. On track to achieve current market expectations for 2026 (underlying PBT £461 - 487m). | AMBER/GREEN ↑ (Roland) This solid update nudges profit guidance higher for 2025, but suggests the recovery in volumes seen in 2025 could slow in 2026. However, I’m more interested to see that forecasts suggest profitability could improve modestly in 2026. Pairing this with today’s upgrade and recent evidence of improving momentum has convinced me to move my view one notch higher today, despite feeling that the valuation is already at a level I’d view as fair. | |
Whitbread (LON:WTB) (£4.4bn | SR22) | Will deliver a higher level of efficiencies in FY26 than previously expected (£75-80m vs. £65-70m expected). Q3 total group sales +2% (£781m) (Q3 finished around the end of November). Current trading for six weeks to Jan 2026: UK accommodation sales and RevPAR both up 4%. Germany accommodation sales +11%. | ||
Primary Health Properties (LON:PHP) (£2.7bn | SR82) | Combination between PHP and Assura successfully delivered, creating £6 billion healthcare REIT. 60% of total annualised synergies of £9 million already delivered. | ||
Grafton (LON:GFTU) (£1.76bn | SR91) | Full year adjusted operating profit expected to be in line with expectations. Revenue for the year was £2.52 billion (2024: £2.28 billion), up 10.4%. | ||
Integrafin Holdings (LON:IHP) (£1.16bn | SR63) | Strong Q1 FY26 net inflows to the Transact platform of £1.0bn, up 11% year-on-year. Reiterates cost guidance from December 2025. “In a strong position to accelerate profit growth in the coming years.” | ||
Gamma Communications (LON:GAMA) (£814m | SR54) | FY 2025 in line with market expectations. Consensus for FY25: Adjusted EBITDA £140.0m - £143.0m, adjusted EPS 93.6p - 95.4p. Buyback for £42.5m. | AMBER ↓ (Roland) [no section below] Gamma shares have continued to sink since I last covered the stock in September. Today’s update highlights strong performance from recent acquisition in Germany and good cash generation in 2025. My sums suggest the shares may now offer a trailing free cash flow yield of more than 8%. I see that as good value, as is the trailing EBIT/EV yield of c.10%. However, there seems to be some uncertainty about prospects for 2026 and perhaps 2027. Earnings forecasts for 2026 have drifted steadily lower for this year and are now broadly level with 2025. The company reiterates UK market headwinds today in addition to the structural headwind that will be caused by the switch-off of traditional PSTN (copper wire) telephone services from 2027, which I believe will affect demand/pricing for some of Gamma’s telephony services. I’m also a little discouraged by today’s decision to freeze the dividend for the next two years while diverting up to £85m into buybacks. It feels to me like management may be digging in for a difficult period. The StockRanks style this as a Contrarian stock which feels about right to me. But I’m also wary about the very low MomentumRank of 18. I wonder if it might be too soon to take a positive view here? I’m going to revert to a neutral view until more clarity emerges. | |
THG (LON:THG) (£794m | SR64) | Record H2 revenue performance (+6.7%), c.14% ahead of the top end of guidance (guidance was +3.9% to +5.9%). FY25 adjusted EBITDA expectations unchanged and in line. High confidence in THG Beauty and THG Nutrition trading momentum into Q1 2026, following c.8% revenue growth over November and December. | ||
Trustpilot (LON:TRST) (£742m | SR36) | Bookings +18% (constant currencies), ARR +19% (cc), revenue +20% (CC). Adjusted EBITDA projected to be ahead of market expectations. Extending buyback by up to £10m. | AMBER/GREEN ↑ (Graham) I acknowledge that this might be an unpopular stance and that Trustpilot is a controversial company. Bear raiders have been attacking it and I agree that the valuation is hot according to traditional metrics. But on a multiple of ARR, it's not expensive, if we are willing to value it as a quality software business. With an "ahead of expectations" update today, I think I can justify raising our stance on this by one notch. | |
Pagegroup (LON:PAGE) (£734m | SR48) | Gross profit -4.6% (cc), -3.1% (actual currency rates). 2025 operating profit to be broadly in line with current market consensus of £21.1m. "While the market outlook remains uncertain due to the unpredictable economic environment, we will continue to control the controllables and we remain confident in the execution of our strategy, given our highly diversified and adaptable business model, strong balance sheet and our cost base that is under continuous review." Net cash £31m. | AMBER/RED = (Graham) We were AMBER/RED on this last year and a cautious stance in relation to the recruitment sector continues to look prudent. The quarterly decline in gross profit for Q4 was better than expected, according to Reuters, but the “broadly in line” description of full-year profitability does not inspire. EMEA and the UK have both posted double digit declines in gross profit for the full year, with the group as a whole seeing gross profits down 7.8% vs. 2024. Even temporary recruitment declined in Q4, and the outlook statement does not suggest there is any light visible at the end of the tunnel yet for the recruitment sector, and I maintain my concern that the old way of doing business in this sector might have been fundamentally broken by technology. | |
Hunting (LON:HTG) (£621m | SR90) | Group EBITDA of c.$135 million, up 7% year-on-year. Guidance: 2026 EBITDA to be c. $145 million - $155 million, “representing an additional year of good organic growth, despite wider market volatility.” Zeus 2026 EPS forecast unchanged at 40.2 cents. Canaccord Genuity 2026 EPS forecasts cut by 20% to 45 cents. | AMBER = (Roland) [no section below] 2026 guidance suggests Hunting could generate c.£55m of free cash flow in 2026, giving a possible 9% free cash flow yield. While cyclical and geopolitical downside is always a risk in the oil and gas business, this seems a potentially attractive valuation to me, especially as the company ended the year with a strong net cash position. However, checking today’s EBITDA guidance against previous expectations suggests to me that it may be at the lower end of the range of previous forecasts – today’s update has prompted a material cut to 2026 forecasts by CG (see left). Drilling into the business, Hunting appears to have scaled up its medium-term growth ambitions for its Subsea division. My reading of this is that it should support growth on longer-cycle offshore projects and reduce the group’s dependence on the somewhat unpredictable and short-cycle US onshore (shale) business. My overall impression is that a stronger recovery in earnings has been pushed back slightly today. While I’m encouraged that the company has met its revised 2025 EBITDA guidance, I don’t think Hunting can completely escape its exposure to (weakening) oil prices. I’m going to leave Mark’s October view of neutral unchanged today. | |
Raspberry PI Holdings (LON:RPI) (£561m | SR21) | Adjusted FY2025 EBITDA to be ahead of market consensus forecasts, at not less than $45m. The Board is confident that H1 2026 unit shipments will grow versus H1 2025, with profitability in the period in line with Board expectations. Visibility beyond H1 2026 is limited. | AMBER/RED = (Roland) [no section below] Booming demand for hardware for AI data centres is starting to affect the PC market due to memory shortages. Raspberry Pi says this situation means that both pricing and availability of a key type of memory chip is becoming challenging. While mitigating actions are being taken, this situation translates to very limited visibility on volumes or profitability beyond the first half of 2026. I’m not sure if today’s update will translate into a broker downgrade, but I think there’s clearly a material risk of a cut to 2026 forecasts at some point. This is an interesting business that floated to great fanfare in 2024. However, the shares have fallen by c.50% over the last year and are now trading below their IPO level. Despite this, RPI stock is still trading on c.30x forward earnings. The StockRanks view this as a Falling Star and both the ValueRank and MomentumRank are under 20. While I hope to see this innovative British tech business succeed, I am not inclined to get involved at current levels. I’m going to leave our previous AMBER/RED view unchanged today. | |
Thor Explorations (LON:THX) (£476m | SR99) | Q4 gold poured of 23,719 ounces. FY 2025 gold poured totalled 91,910oz. Q4 cash balance of US$137m. FY 2026 production guidance range set at 75,000 to 85,000 oz of gold, All-in Sustaining Cost ("AISC") guidance range set at US$1,000 to US$1,200 per ounce. | ||
Picton Property Income (LON:PCTN) (£399m | SR60) | “Whilst the Company is in a strong financial and operational position, the Board believes it is important to be proactive and has initiated this process, which will take into account the views of shareholders and other key stakeholders.” “Continues to trade at a material discount to EPRA net tangible assets…” | ||
Tharisa (LON:THS) (£360m | SR99) | CEO: “While output was softer at the start of the year, leading indicators across the business are trending positively, particularly in mining, where recoveries have begun to improve following weather and sequencing-related impacts experienced during the quarter.” | ||
GYM (LON:GYM) (£280m | SR55) | Full year results slightly above the top end of current analysts' forecasts. Revenue +8%, LfL revenue +3%. 16 new sites, taking the total to 260. £10m buyback planned. FY26 Group Adjusted EBITDA Less Normalised Rent also expected to be slightly above the top end of the range of estimates, currently £55.2-59.3m. | ||
SRT Marine Systems (LON:SRT) (£242m | SR45) | H1 revenue +95% to £51.1m, pre-tax profit +47% to £3.1m. Gross cash +85% to £41.5m. H1 performance in line with exps. Expect continued progress in H2. | ||
Science (LON:SAG) (£236m | SR97) | Expect record adj op profit for 2025, ahead of expectations. Net cash £61.2m at 31 Dec. Expect to continue buybacks in 2026 at similar level to 2025. | GREEN = (Graham) [no section below] I've learned my lesson with this "international services and systems company", I hope. After undue caution in the past, I'm happy to give it the GREEN light for now, until it puts a foot wrong. Our last coverage was in October. Today's update shows the company overcoming "volatile market conditions" with an adjusted operating profit result that should be ahead of the £22.2m forecast in the market. Reported gains will be higher again, reflecting the successful (and surprisingly short-term) investment in Ricardo. That investment leaves with company with net funds of £61.2m as of year-end, giving it plenty of flexibility for future ideas. They provide a table to illustrate their long-term share price performance, something which the vast majority of AIM companies will never do, for entirely logical reasons! But they still think they are undervalued, and so buyback activity will continue. While I don't have a strong view on the underlying quality of the businesses within SAG, they clearly have a motivated and entrepreneurial Chair in the form of Martyn Ratcliffe, who owns nearly 19% of the company. I wouldn't bet against him, so I'll leave our stance on this GREEN for now. | |
Petrotal (LON:PTAL) (£191m | SR78) | Production averaged 15,258 bopd in Q4 and 19,473 bopd in 2025. $112.4m of unrestricted cash. Work underway to address production issues. | ||
Rainbow Rare Earths (LON:RBW) (£120m | SR35) | Pilot plant will operate through H1 2026, producing data to contribute to DFS and project financing efforts. | ||
SIG (LON:SHI) (£114m | SR50) | LFL sales flat w/ revenue of £2.6bn. Adj op profit c.£32m, in line with expectations. Leverage c.4.7x at year end. | ||
Afentra (LON:AET) (£95m | SR75) | Total 2C WI contingent resources across Blocks 3/05, 5A and 24 now 87.3 mmboe, up from 20.9 mmboe previously. | ||
Eagle Eye Solutions (LON:EYE) (£84m | SR51) | Won contract with US supermarket co-op Wakefern. Expected to go live mid-2026, with “a material contribution to Group ARR”, supporting the Board’s FY26 expectations (forecasts unchanged). | ||
Brave Bison (LON:BBSN) (£71m | SR42) | FY25 trading ahead of expectations, with net revenue +57% to £33.5m, adj pre-tax profit +41% to £5.5m. Board is comfortable with FY26 expectations. | ||
Petra Diamonds (LON:PDL) (£57m | SR22) | Recovery of 41.82 carat Type IIb blue diamond at Cullinan Mine | A diamond of “seemingly exceptional quality”. Company is analysing stone and determining the best method of sale. | |
Iofina (LON:IOF) (£50m | SR81) | FY25 ahead of expectations, with revenue >$65m w/ EBITDA >$11m. 2025 crystalline iodine production rose by 17.2% to 743.2MT. | ||
Shoe Zone (LON:SHOE) (£31m | SR63) | FY25 revenue -7.6% to £149.1m, pre-tax profit 67% to £3.3m. Net cash £5.9m. FY26 outlook “challenging”, expect FY26 PBT of £1.0m (Zeus previous f’cast £4.5m). | BLACK (RED ↓) Downgrading to a wholly negative view after yet another profit warning. I do see positives that could bode well in a recovery, particularly around cash conservation measures, so in my view this is far from a lost cause. But the timing of any potential recovery is uncertain and profitability is likely to be marginal for the foreseeable future. | |
Sosandar (LON:SOS) (£19m | SR64) | Q3 revenue +10% to £13.4m, gross margin 66% (FY24: 64.7%). Net cash £9.7m. On track to meet FY26 expectations. | ||
Lexington Gold (LON:LEX) (£19m | SR19) | £1.19m Equity Fundraise & Conversion of Loans & JORC Mineral Resource Estimates for JKL Project | 53% increase in contained gold for the combined JKL Project. Total Inferred Resource of 12.90 Mt at 0.78g/t Au for 323,500oz of contained gold. Raised £1.19m in new equity at 4p per share. Converted £350k of loans into equity, also at 4p per share. | |
Mission (LON:TMG) (£17m | SR72) | SP -12% PW: Completion of some projects delayed into H1 26. FY25 revenue now to be £68m w/ adj op profit £5.1m (CG previous f’cast £73m & £8.5m). Year-end date being moved to 30 Sept; next year end is 30/09/26. | BLACK (AMBER ↓) (Graham) [no section below] I tentatively upgraded this to AMBER/GREEN last year, in a move that now appears to have been misplaced. TMG is a people business: a group of collective agencies, and I must always be taught the lesson to be cautious with this category of business! Macro uncertainty is blamed for some project delays. which is fair enough, but the lumpiness of revenues is highlighted by the large gap between the expected and annual numbers (both revenues and profits), especially given that this is an update for FY December 2025! Net debt is £9m, which doesn't strike me as being all that comfortable for a business of this size, but at least it's moving in the right direction. A new CEO is attempting to achive annualised cost savings of £1.5-2m. | |
Itaconix (LON:ITX) (£15m | SR19) | Navitas has signed a MOU to acquire 65% working interest in JHI’s PL001 licence, which is adjacent to Sea Lion. No financial details provided. | ||
Westmount Energy (LON:WTE) (£11m | SR62) | Navitas has signed a MOU to acquire 65% working interest in JHI’s PL001 licence, which is adjacent to Sea Lion. No financial details provided. |
Graham's Section
Shoe Zone (LON:SHOE)
Down 18% to 55.1p (£25m) - Final Results - Graham - BLACK (RED ↓)
We already had three profit warnings here in recent memory, and today brings yet another.
First, let’s review FY September 2025.
Revenue £149.1m (FY24: £161.3m)
Digital revenue up slightly, store revenue down.
PBT £3.3m (FY24: £10.1m)
Adjusted PBT £2.4m (FY24: £10m).
This PBT result is in line with expectations.
Net cash has increased year-on-year to £5.9m.
The store count has reduced from 297 to 269 and its composition has also evolved with only 68 original stores left from 112 last year. These have been replaced with new larger format stores, relocations, refits, etc.
Outlook:
Trading conditions remain challenging due to macro-economic pressure and higher wages, with expected profit before tax of approximately £1.0m for the year ending 3 October 2026.
Forecasting the next ten months must be difficult, so I wouldn’t bet on this £1m PBT estimate being too accurate.
However, it’s still a major downgrade from the £3.4m forecast for after-tax income that’s currently in the market..
Management commentary
This is one of those stocks that can easily and with some justification point to the challenged consumer as the explanation for its poor trading:
This was a challenging year, particularly in the second half, as consumer confidence declined further following the Government's October 2024 budget, and highly adverse fiscal policies. Persistent inflation, higher interest rates, and reduced disposable income contributed to negative economic and consumer sentiment in the UK. Sales were good when there was a reason to buy, such as the warm summer and the Back-To-School period, however, discretionary spending remained subdued as consumers exercised greater caution in what they were spending money on.
Leases: lease length is only 2.6 years, which is excellent and helps to reduce the risk for shareholders. And rents aren’t increasing.
Product margin reduces from 62.8% to 61%. I’m surprised it’s even as high as this!
Cash: it sounds like Shoe Zone has been running a tight ship. Inventory fell £5.4m as the number of stores reduced, and capex also collapsed to only £3.3m (FY £11.5m). They cancelled their profit share scheme. They also paid no dividend, and haven’t declared one today.
The result is that the cash balance was protected, and grew from £3.6m to £5.9m.
Outlook is appropriately downbeat:
Trading conditions remained challenging in the first quarter of the new financial year, with revenue down on forecast, reflecting ongoing macro-economic pressures that continue to weigh on consumer confidence resulting in lower footfall on the UK High Street, alongside the highly adverse Government fiscal policies. The Government's November 2025 budget included an additional increase in the National Living Wage, raising our cost base further, with broader measures not materially improving consumer sentiment. In light of these conditions, we expect a profit before tax of approximately £1.0m for the financial year ended 3 October 2026.
Graham’s view
I’ve been AMBER/RED on this, and I’m going to downgrade it further today, to an entirely negative view.
I would like to quality this with some positives:
Management has acted very prudently to conserve cash with a wide range of cash-saving measures.
This has resulted in a positive net cash position, before considering leases.
Lease liabilities on the balance sheet are some £34.5m but they could have been much larger, if the average lease length was longer.
Given the low average lease length (2.6 years), Shoe Zone has the flexibility to continue closing stores as necessary.
Those are the positives. The negatives are pretty clear: they sell a commoditised product, and external conditions play a huge role in deciding whether or not it’s possible for them to make a profit. For now, these conditions are not conducive to success.
So I’m RED, but this is very much a temporary view. I’m open to the idea that this could become an interesting turnaround at some point. But personally I wouldn’t go near it for now.
Trustpilot (LON:TRST)
Up 11% to 208p (£819m / $1,103m) - Trading update for the twelve months ended 31 December 2025 - Graham - AMBER/GREEN ↑
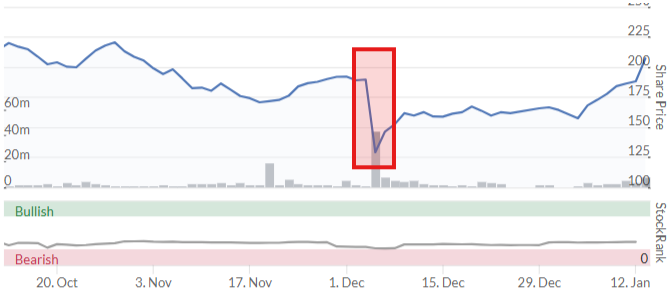
This is a controversial one. Many readers have expressed some form of disgust over Trustpilot’s business model, and the stock has attracted the attention of professional short-sellers (Grizzly Research in particular).
But the share price is now higher than it was when Grizzly raided it:
Today’s full-year update shows excellent growth for FY December 2025:
Bookings +18% (at constant currency)
Annual recurring revenue +19% (cc)
Revenue +20% (cc)
Adjusted EBITDA is projected to be ahead of expectations.
Cash: $48m, after buying back $72m of shares.
Buyback: extended by up to £10m/$13m.
Interesting little snippet: “Importance of Trustpilot in AI answer engine optimisation helping drive growth”.
In a rejoinder to short-sellers and sceptics who describe it as a sewer of fake reviews, they claim to have removed 7.8 million fake reviews.
CEO comment:
"2025 was a year of excellent strategic and financial progress, with growth accelerating in H2. Answer Engine Optimisation drove particularly strong growth in enterprise new business. This, combined with product innovation and improved gross dollar retention, positions us strongly for 2026. We reinforced our core commitment to trust, implementing new AI-enabled fraud detection technology, ensuring that both consumers and the 1.3 million businesses using Trustpilot can continue to build trust with confidence."
“Answer Engine Optimisation” is similar to SEO (search engine optimisation), but for AI bots:
People are increasingly asking AI tools for recommendations instead of relying solely on traditional search engines. Answer Engine Optimization (AEO) helps your business appear in those AI responses.
AEO works a lot like traditional SEO, but instead of optimizing for search engines, you’re optimizing for the AI systems people now use to find and evaluate businesses.
I’d never thought about this before, but it obviously makes sense. Traditional SEO is going to have to evolve for ChatGPT, Grok, etc.!
Graham’s view
I’m a huge admirer of Trustpilot’s market position, and my view hasn’t really changed in the light of the bear raids. I still think Trustpilot has very little direct competition, and has the potential to be an extremely successful business in the long-term.
For me, the question is more around whether the share price can be justified on valuation grounds.
In recent time, we've been neutral:
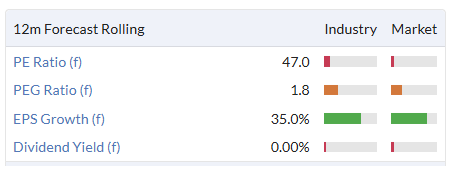
I’m actually more comfortable valuing this on a multiple of sales or on a multiple of ARR, rather than on a multiple of earnings. I think it makes sense to treat Trustpilot in the same way we should treat other high-quality software businesses with interesting long-term prospects.
Given the latest ARR of $296m, Trustpilot is today trading on a multiple of 3.7x ARR.
This is a little low, in my book. If we put it in a US context, it's normal for software companies to trade around 6-8x ARR.
Since Trustpilot is profitable, is trading at a modest ARR multiple, and has just informed us that 2025 was ahead of expectations, I’m going to revert back to AMBER/GREEN on this. I acknowledge this might be an unpopular stance! But I think there are enough reasons to justify it.
Roland's Section
Persimmon (LON:PSN)
Up 0.5% at 1,421p (£4.5bn) - Trading Statement - Roland - AMBER/GREEN ↑
Today’s update flags up a strong recovery in volumes for 2025 and good progress on building safety remediation at this large housebuilder.
Profit upgrade: underlying pre-tax profit for 2025 is now expected to be at the upper end of expectations.
The company has helpfully included details of consensus forecasts in today’s update:
2025E underlying pre-tax profit of £428m (£415 - 440m)
Based on today’s guidance for PBT to be at the upper end of expectations, I think we can now expect a result between £428m and £440m for 2025.
Checking last year’s results, the equivalent figure for 2024 was £395.1m. So it looks like profits may have risen by around 10% in 2025. That’s not a bad result, in my view and suggests the group’s pre-tax margin may have risen from 12.3% to 12.9% last year. A useful increase.
Improved operating metrics: the increase in profit seems to have been driven by higher volumes rather than any improvement in profitability.
New home completions rose by 12% to 11,905, while the average selling price also edged higher.
Although private sales per outlet were unchanged, Persimmon also managed to end the year with a slight increase in its order book:
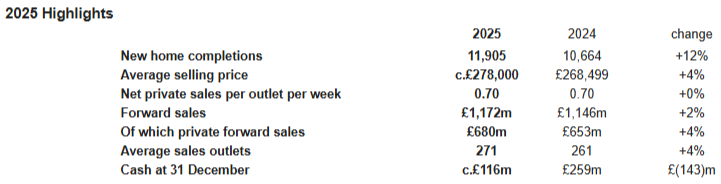
I think one thing that’s interesting about these figures is that they mask an improvement in private sales (to individual homebuyers) last year.
Like most housebuilders Persimmon now generates substantial sales from built to rent (bulk sales) as well as private sales. In its commentary, the company reports a number of positive metrics for private sales:
Private selling price up 5% to c.£301k;
Incentives stable at c.4-5%
Sales rate excluding bulk sales rose by 4% to 0.59;
Private sales in forward order book +4% to £680m
While Persimmon is still having to offer fairly material incentives (such as kitchen upgrades, etc) to complete sales, these figures are slightly more positive than the overall figures listed above.
The difference between the two is explained by softer bulk sales during the final quarter of the year. Persimmon attributes this to uncertainty ahead of November’s Budget.
On balance, I think it’s probably positive to see these tentative signs of strength in the core private sales business. Perhaps falling mortgage rates are helping to encourage transactions and liquidity in the housing market.
2026 outlook
Persimmon’s management isn’t pricing in too much optimism for 2026, but they echo my comments above about private buyer activity:
While we are not expecting any material improvement in market conditions this year, early indications from our Boxing Day marketing campaign are encouraging. Recent reductions in mortgage rates are helpful for our private customers although we remain mindful of continued affordability constraints.
However, sales elsewhere may remain weaker:
In addition, fewer bulk sales in the order book, and continued challenges in the registered provider market, are likely to slow our growth in these markets in 2026.
The end result is that volumes are expected to rise by less than 2% to 12,043 in 2026.
However, the company says its “unique level” of vertical integration should help the group manage continued cost growth.
Consensus forecasts for underlying pre-tax profit lie in a range of £461 - 487m. Based on the mid-point of this range, I estimate the group’s pre-tax profit could rise by c.9% in 2026.
Roland’s view
I’ve been neutral on this business for a while, purely on valuation terms.
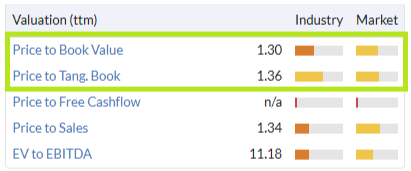
Persimmon has been trading at a premium to its book value:
… but only generating a c.7%-8% return on equity:
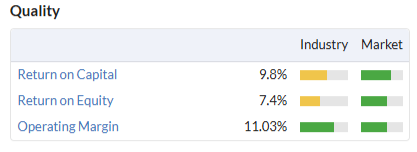
For a property company that simply buys land, builds houses on it and then sells them, this valuation looks relatively full to me. To justify paying a premium to book value for a housebuilder, I’d want to see it earning a 10%+ return on equity.
However, today’s mild upgrade and 2026 outlook suggest to me that we could see a modest improvement in profitability in 2026. In addition, today’s positive update is itself a positive sign – our research has shown that one upgrade often follows another as expectations gradually edge higher.
Although earnings forecasts for Persimmon have drifted lower over the last year:
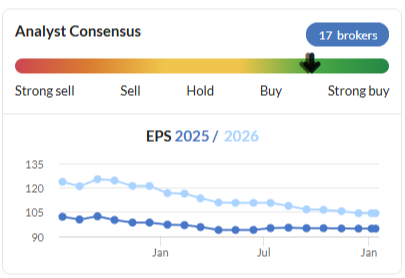
… more recently, the StockRanks have measured improving momentum:
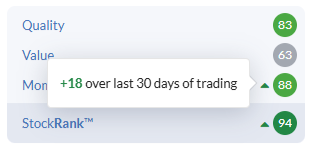
In addition, our algorithms are now styling Persimmon as a Super Stock.
With this combination of trading and quantitative improvements, I’ve decided to move my view up by one notch to AMBER/GREEN today.
Games Workshop (LON:GAW)
Down 2.5% at 18,390p (£6.1bn) - Half-Yearly Report - Roland - GREEN
Today’s update from Games Workshop hasn’t set the market on fire – the shares are down slightly as I write, but as usual with this business I am struggling to find any serious concerns in today’s results.
I’ll review the results in a moment, but first take a look at todays’ second RNS update – a dividend.
Dividend: rather than paying dividends on a fixed schedule, Games Workshop declares dividends when it has “truly surplus cash”.
The Board has today declared a dividend of £1.10 per share taking dividends declared so far in 2025/26 to £4.85 per share (2024/25: £4.20).
Last year’s total payout was 520p per share. Last year saw payouts in January and March, so I suspect we’ll see one more dividend this year. On that basis, it seems reasonably likely that the FY26 dividend could exceed last year’s payout.
Having said that, consensus forecasts shown on the StockReport are more conservative than this:
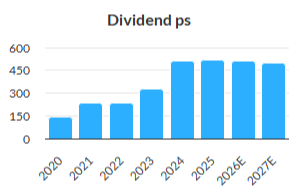
Based on these forecasts, the stock offers a yield of around 2.7%. Games Workshop’s share price growth means it’s no longer an attractive yield play, although it could still deliver strong income growth over time.
Half-year results summary
Moving on, today’s half-year results show a respectable increase in the group’s top-level numbers:
Revenue up 10.9% to £332.1m
Operating profit up 11.3% to £140.4m
Operating margin: 42.3% (H1 25: 42.1%)
Trailing 12-month return on equity: 64.7%
Drilling down one level reveals growth in the core retail business during H1, but a reduction in licensing revenue:
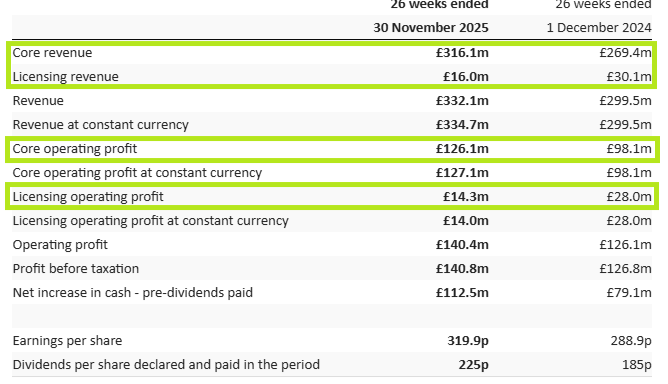
Licensing: this fall may explain today’s share price reaction – licensing revenue is almost pure profit and has helped to juice earnings growth in recent years.
However, the near-term pipeline of licensing revenue seems weaker than last year. Licensing revenue fell by 47% to £16m in H1, while the pipeline of licensing receivables due in the year ahead is just £12.5m (FY25: £30.0m).
86% of the royalty income generated in H1 came from PC and console game licences. Timing on future payments from the Amazon deal that has so excited investors remains harder to predict, as the company admits with its usual admirable transparency:
Our live action endeavour is still in development with our partners: Amazon MGM Studios, Henry Cavill and Vertigo. It is the nature of these things to take several years, and while we wish we could tie down a release the way we can with our core business, the reality is that, as with any licensing deal, delivery is not in our control. We leave it to our partners to manage their own businesses.
However, work is said to be “almost complete” on a standalone Warhammer Age of Sigmar episode for Prime Video.
Outlook: Games Workshop doesn’t provide forward guidance, but there are some consensus forecasts in the market. If correct, this estimates suggest earnings could dip slightly this year:
FY25 actual: 594.9p per share
FY26E: 563p per share
FY27E: 611p per share
However, today’s H1 earnings of 319.2p per share represent 57% of current full-year forecasts. I don’t think it would be a massive surprise if the group’s full-year earnings were slightly ahead of these forecasts.
Roland’s view
Earnings forecasts were upgraded in November after a strong update which Graham covered here.
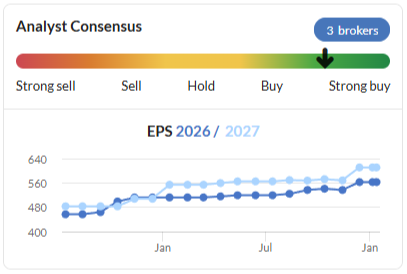
The shares rose sharply at the time but have drifted lower since:
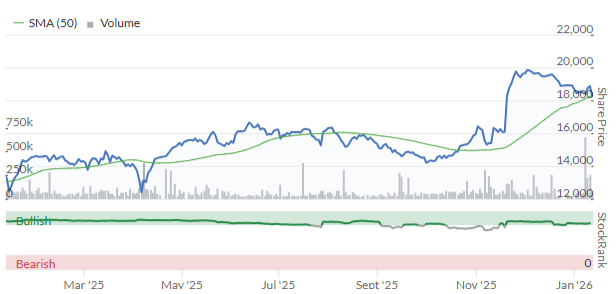
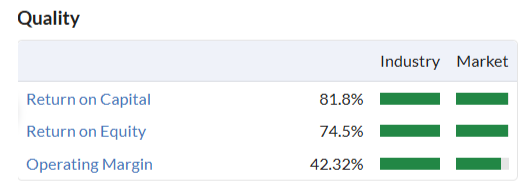
On conventional measures the shares hardly look cheap on a P/E of 32. However, Games Workshop is hardly a conventional business. The group benefits from a differentiated product that appears to have both growth potential and pricing power, excellent management and superb high-quality financials:
While I wouldn’t buy the shares as a short-term trade at current levels, I don’t see any reason why they cannot continue to justify their valuation over the medium-long term.
The core business is continuing to grow and the company’s television and film efforts appear to have strong backers and are being developed methodically. I am confident they should eventually bear fruit.
The StockRanks also remain impressed, despite a low ValueRank:
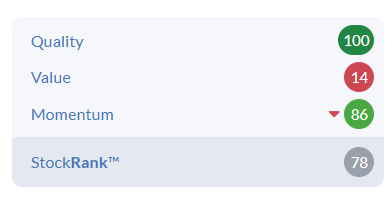
With only slight trepidation, I’m going to leave Graham’s GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
US CPI data for December is out and the snap reaction is not much to see here. Headline up 0.3% and core 0.2% is playing ball with everything we know....dare I say it's a little goldilocks for now...since employment data isn't accelerating but inflation muted. The fast reaction (not always right) from the bond market is positive ie yields down. Looking through the data there are less positives actually since plenty of data is actually stronger than the headline which is held back by fuel and energy. Hmmm it is what it is and we take a good (ish) number and hope these numbers maintain their current trajectory into Q1....this would result in lower inflation expectations. I do remember last year though and obviously Jan-Mar is a good time to try and get a price rise through so let's not get carried away. AND those prices need to stick...ie not affect demand.
In summary - the picture for Q1 2026 looks favourable until future employment and inflation data. Employment data reacts much more quickly and more likely to show weakness ( or strength ) early. So the employment numbers I expect will become the media focus over the next month or two.
Regarding Games Workshop (LON:GAW) , the market reaction is slightly surprising but I guess when the price is already for perfection, then simply more perfection just isn't good enough. I thought this was a nice update and I'm pleased to see that the new IT systems are seemingly coming together at last. This is essential but mundane stuff for what is a truly global, vertically integrated business.
One thing that I look for is evidence of growing interest in the hobby and once again subscriber numbers for Warmhammer+ (the subscription service for Warhammer fans) were impressively up at 248,000 versus 207,000 a year ago. Equally "My Warhammer" active users continued on an upward trajectory to 790,000 from 695,000) a year ago. Email subscriber numbers were 720,000 versus 629,000 a year ago.
I find this engagement really encouraging as it's evidence of a widening interest in the hobby which is needed to sustain the growth.
I also like to track the revenue growth by market and particularly the trade revenue (+25.2%) which is around 60% of total core revenue and this continues to grow across all markets at an impressive clip.
I suspect that some of the tepid market reaction was due to lower licensing revenue but this, by its very nature, will always be lumpy and it remains a marginal part of the business. It's clear that it's increasingly a focus of management effort and I have no doubt that when the Amazon / Henry Cavill media content is finally released , it will generate even greater interest in the hobby and perhaps presage some wider licensing deals.
Considering the macro picture and the fact that they have brushed off the impact of trade tariffs, I see these results as tremendously positive and the potential catalysts for further growth acceleration seem to be present.
It is so worth reading this report from top to bottom because everything in it is testament to the quality of the management and the culture within the business - "... a senior team that is ego free managing a team of people that is also focused on delivering the best outcomes for Games Workshop rather than themselves, is essential" - how refreshing.
I'm surprised by the 2026 estimates shown on Stocko as 563p (versus 616p last year) when they have already done 319.9p in this first half to November 2025 and the second half will include the Christmas period. This appears to be an anomaly unless I've missed something but anyway, even if the share price takes a breather for a while, this remains a core long term holding for me.
F’casts at Games Workshop (LON:GAW) are basically works of fiction…
I asked Grok about GAW. I deleted the reply, but it mentioned entry into China as a potential source of revenue (imagine the potential there) and some other developing markets.
It did say that it thought GAW would go sideways, though. Perhaps it was the way I phrased the question, though.
Grok is brilliant. And maybe the others. This is a game changer for investor information. Don't let the social side detract - its an investment resource of huge impact. DYOR duh! Dumb does dumb - don't blame the tech.
And its a bit cold for bikinis.
GYM (LON:GYM) Ah, now here's a share I haven't dissed for a long time.
Hmm, net gearing 289%, which is too high, and interest cover 1.3, which is too low.
Revenues have been compounding at a rate of 8%, but operating profits are pretty flat. It even made operating losses for 3 of the last 5 years, which is not good.
It has been issuing shares at a rate of 6% pa, which is too high for me. It's returns on capital are low (a negative average, but the highest they achieve was only 4.5%).
The upshot being that the company can only increase revenues by issuing shares, and earn low returns on capital in the process. What's the point of that?
GYM (LON:GYM)
Hi Mark
Thanks for insights.
You're right, it's looking a tad high. I don't think there are any plans to bring it down either. Based on expansion plans published today (+75 new gyms) I have a feeling that debt will actually go up in the next 2-3 years, although the company says that these will be funded using free cash flow only.
On the Stock Report it looks like the average number of shares increased a lot in 2024 (179m ---> 185m.)
I don't recognise this 185m figure at all and I can't see it further down the Stock Report (see screenshot below), on the Balance Sheet page (see screenshot below) or in the Annual Report.
I therefore have no idea what this 185m is referring to, but it looks like it could be an error.
After 2021, therefore, I don't think the share dilution has been anything to worry about.
I'll forgive them for the share issue that happened during covid.
https://oxycapital.com/wp-cont...
Cheers
A
My worry for GYM (LON:GYM) may sound counterintuitive but younger generations are getting more and more into health. You would think this is a positive for GYM, but as people get more into fitness they spend more on better memberships and leave behind the cheap tier options.
If you go into a GYM youll find it extremely busy and predominantly full of students and young professionals, if these start to venture towards the david Lloyd's of the world then there could be issues. Perhaps just anecdotal insight and my own experience, but worth considering.
GYM (LON:GYM)
Hi JSchoffer
Thanks for your comment.
I actually think there could be some truth to what you've highlighted. Indeed the average number of members at GYM (LON:GYM) today vs 2018 (3,842 vs 4,582) is the only row that's highlighted red in my own spreadsheets.
However, it's hard to see if this has been driven by:
3 counter arguments to the above:
Within this the % of members using low costs gyms has risen from 14.9% to 28.3%.
The covid years aside, this is a % that has only ever increased within this 10 year time period, however, it's definitely a metric that I plan to keep an eye on going forward.
Thanks again for the thought-provoking response.
A
Agreed my youngest son who is 17 and his mates live in the local pure gym in Norwich, the place barely has any staff and you get in and out by using a code they are all skint students but with the bodies of middleweight boxers.
They spend no other money in the place other than the monthly membership fees. He tells me Jan is busy with all the newbies but its still 90% other students and youngsters.
It might just be me but when I was in my teens/early 20's late 80's early 90's all young people wanted to do was go to the pubs and then the nightclubs but both of my son's have minimal interest in pubs or social drinking and it seems the same goes for most of their friends, as for nightclubs incredibly they have gone the way of the dodo yet back in the 90's thousands would turn up at the weekends for them.
Morning,
Will Gamma Communications (LON:GAMA) be looked at?
Many thanks
GAMA was looked at, cheers John!
For info: BOLD - the 21Shares Bitcoin and Gold ETP listed on the London Stock Exchange this morning. It is unlikely to be available immediately on all platforms but anyone interested should nudge their brokers. See https://www.bytetree.com/bold/ for more details.
I did this with HL a couple of months back, but they said they had no intention of offering it.
They weren't offering Metlen Energy & Metals (LON:MTLN) recently but are being pushed into it. I'll be pushing them shortly on 21Shares Bytetree BOLD ETP (LON:BOLD) .
Lots of interesting things going on today.
Games Workshop (LON:GAW) Great results, as usual. Shares down 3%, though. Mr Market is presumably thinking "great company, shame about the valuation". Perhaps the shares will trade sideways for awhile. I don't hold (alas).
Gamma Communications (LON:GAMA) "Inline". Germany good, UK tough. Shares up 6%. Good quality company with good growth. Fwd PE of 9.3, and FCF yield around 8%. So it's a question of "how much cheaper are you expecting this to get?" I hold (but underwater).
Raspberry PI Holdings (LON:RPI) Shares down 8.7%. Ouch. I hold. Fortunately a very small position. It was my "daft wee laddie bet". Value score 18 (so valuation risk!). Momentum 7.
RPI still finds things to innovate. One problem, I think, is I'm not sure what their value proposition is. Their latest models are quite pricey. So they're not cheap enough that you can chalk frying your board up to experience. The price is pushing into low-end PC territory, but not as well specced.
To put it context, a couple of years ago I decided I needed a new PC. I bought a Beelink, a PC in a dinky little case. I paid £260 IIRC (from Amazon. I actually feel ripped off because I am pretty sure I could have gotten it materially cheaper if I shopped around).
I installed Debian Linux on it - ousting Windows (boo, hiss) - and it works great. Nice, fits my needs just fine. It probably would have run like molasses if I had kept Windows on it.
If I had gone the Raspberry Pi route, then I could have gotten things cheaper, but it's a bit "bitty". A case is extra. Not really a proper power brick either (I think Pis should consider moving to power jacks given how much power they now require, rather than the sill USB).
In other words, if you want a PC, then just buy one.
Maybe RPI will address this issue, I dunno.
Anyway, I might consider a top-up of RPI (a small one) if the valuation score becomes more reasonable (say above 25). That's not a "recommendation" though, it's a fanboy view who thinks the company is innovative in making commercial products.
Its ironic that the main reason for the fall today is the statement from the company that costs of memory are increasing as sellers divert supplies to firms developing AI
Last May I bought some RAM for £180. Now the same RAM costs £600. I suppose this can put many people off from upgrading or replacing their PCs.
But to run a lot of new software which uses AI, you often need to upgrade your computer. The minimum requirements have increased substantially. I had to get a much better graphics card and more RAM.
That's true, as the fact that Windows 11 requires more RAM than 10. However, I don't think many people run AI locally. Also, basic PC users, which use the PC just for Office or browsing, may be OK with what they already have. Gamers with systems with 16 or 32 GB of DDR4 RAM might just postpone upgrading. I haven't read the TU from Raspberry PI Holdings (LON:RPI) but in my view those are not systems for AI and the RAM cost is going to be huge compared to the rest. Furthermore, the SSD prices are up as well, so the situation is not ideal to by a new PC. I'm trying to understand if this is going to affect companies like Softcat (LON:SCT) and Computacenter (LON:CCC) as they sell to businesses.
I downloaded some photo editing software which uses AI, it wrecked my old computer. I bought a new computer but that kept crashing, so l returned that one and got a more powerful one, which does work alright. My old computer could run massive size photos in Photoshop but could not handle AI software. Even my new one is at low end of what is required. But graphics cards are so expensive now. SSD were not too bad.
Prices increased considerably a few years ago, graphics cards more than doubled, partly due to a shortage. I don't do gaming, but there are reports that some cards are not up to it. When l looked NVIDIA (NSQ:NVDA) were said to be the best.
Micron Technology (NSQ:MU)
A monthly chart repeat monthly ..
The $1trn Question is where on from here.
They have sold out all production for 2026 and likely most of 2027.
This is a new investment universe which is upturning all prior.
Sorry. I'm guessing all this stuff needs basics - water, energy, minerals - I can't guess the next disruptor stock.
I should have sold the house, car, wife, kids and pension and gone full Micron Technology (NSQ:MU) :).
But Micron is just paper money so he ho.
On 3rd September 2021 Merryn Somerset Webb published an Interview with Jeremy Grantham an esteemed Market Commentator in the USA in Money Week Magazine when he said "the US is in one of the greatest bubbles in Financial History."
I kept the Article to see what happened. Today the S & P 500 is 6,977 compared to 4,474 in Sept 2021 an increase of 56%.
He also said the UK Housing Market was overpriced and when the crash came it would be a humdinger.
I would welcome some views on the above from those subscribers far wiser than me.
"Esteemed' by MSW? Isn't increased debt keeping the plates spinning?
Being too early is indistinguishable from being wrong?
There's a reason why newspapers/magazines are put into the industry category of "Media & Entertainment".
The incentive of MSW is not to give the best financial advice / future prediction.
It is to generate views/reads/watches/listens which then either generates subscription revenues or ad revenues.
".... one of the greatest bubbles in financial history" is a good clickbait headline to generate said revenues.
I'd take the article for what it is on face-value.... a way to generate clicks, eyeballs, and therefore subscription/ad revenue. Nothing more.
I don't know why "experts" spend so much time calling out bubbles...by definition prices have reached irrational levels in a bubble, and therefore events that trigger a reverse are hard to predict. There are plenty of choices not in bubble territory to look at, although when bubbles collapse everything suffers. Jeremy I like a lot but he got a lot attention re 2021 etc and nothing has popped yet although emerging markets that were the other side of his call have picked up significantly. So money is moving towards better returns, as you would expect.
I must have read that article. It spooked me at the time when Jeremy Grantham warned of the coming super bubble crash of 2022 and what might be the signal to pop it. I have since learned that he is something of a permabear. Funnily enough there is a snippet in the current Money Week magazine where he is still saying "we are due a setback" and that "the investment bubble is extreme in the US". He will be right one of these days.
Hi Portugull, unfortunately I am not one of those wise subscribers but what I will say about the housing market in the area which I live in London which is east it appears housing sells are extremely difficult or almost nonexistent. Estate agents are struggling to find buyers for the houses on their books. I myself have put on hold a move closer to my sons new senior school which as a family we can manage for now but I notice the talk amongst friends about moving bigger properties etc as stopped.
I think i read that article.
What he said was right, it was in a bubble in 2021 and more so now. Did he actually forecast when the bubble would pop?
Overall I think using a running stop loss would be a partial solution. Stay invested but if the market falls get out in stages.
However of course no one can time the market....this is not news. Have a reasonable diversification over equity, bonds, propert, gold and silver.
USCPI data today.... for the last three years Dec data has been quite weak compared to the rest of the year and in particular Q1 ...Jan-Apl has had a habit of producing high (ish) numbers that shake the rate cut thesis, ie inflation not dead. This year, 2026... as usual we have nice high numbers dropping away at the back. If data stumbles along in 0.2-0.3% range this is positive....and higher numbers tend to scare the market. My total guess is today will be a nothing number...ie on trend ...therefore 0.0-0.2% ... telling us very little. A big negative would be a surprise... -0.2 - -0.3% ....Looking forward however 0.6% 0.4% 0.25% in 2025 for Q1 fall away which does open the door for a positive result. Employment data suggests some weakness so as we move through Q1 in 2026 ...its possible confidence in rate cutting grows...should the numbers play ball. This helps soften the blow today if the number is a little high say 0.4%....since we could well recover those losses as strong comps fall away.
Net net I don't expect the number today matters too much.... ( humble pie coming my way) but we see.... and the outlook for this data point seems favourable for now. Good luck all.
Science (LON:SAG) results look very good but no one biting this morning. Must be frustrating for the Board. Record profit expected, ahead of expectations, buybacks continue - market response nothing!
Agreed, really could/should be a 300-350M MCAP company!
Maybe P.E will see the value here...
Science (LON:SAG) results look very good but no one biting this morning. Must be frustrating for the Board. Record profit expected, ahead of expectations, buybacks continue - market response nothing!
The board's habit of holding the shares in treasury rather than cancelling them reduces the impact of the buyback as the market anticipates they'll come back on the market at some point. Now over 3 million shares, so around 8% of the share count, which is a significant overhang.
Obviously this gives the board flexibility to use shares to fund any acquisitions or share options without requiring pesky shareholders to agree, but the market likes to see jam today, rather than tomorrow.
timarr
Science (LON:SAG) ah thanks Tim I hadn't spotted that. One of the reasons to be wary of buybacks. That's cheeky.
Many companies especially AIM have an ongoing authorisation to raise 10% anyway....is an 8% overhang really holding back a stock? Less convinced it's that personally.
Hi Tim, it would have been nice if the Board put some numbers in the announcement,
"The resilient operating performance was further enhanced by the return on investment related to the H1 corporate activity. As a result, reported profit before tax and earnings per share will be substantially higher than the prior year, reflecting the investment gain."
How does one interpret 'substantially higher'? 15% perhaps?
All the best
Thanks for that Tim I did always wonder why some firms hiked the bought back shares into treasury rather than cancelling them and the answer re future share options and not needing shareholder approval to reissue makes sense, it would seem from that full cancellation is a more positive sign than slight of hand that says "they are gone, but they aren't really".
Science (LON:SAG) Shares were up quite a bit but have fallen right back now. Yes results do look good and one of higher rated Stocko stocks.
Gamma Communications (LON:GAMA) please.
This share has fallen consistently throughout 2025 and has de-rated to a PE of around 9.5 times. Despite very strong growth over recent years and confirmation of full year 2025 estimates within a tight range. Will buy back another 5% of their shares in the coming months.
Looking very interesting now, was priced for a warning, buyback positive too
Gamma Communications (LON:GAMA) What is it with this share? Does the market simply not like the company?
Gamma Communications (LON:GAMA) What is it with this share? Does the market simply not like the company?
It's ex-growth in the UK and reliant on a relatively untested geography (Germany) to reignite expansion. It's in a dull sector - telecoms. Growth investors have sexier stuff to covet and income investors have plenty of alternatives with longer runways.
c.10x PER doesn't seem far wrong even if cashflows are decent.
Gamma Communications (LON:GAMA) Thanks for your thoughts BnB.
Just for info. after doing a routine software update on a MacBook all my google finance watchlists disappeared except my actual portfolio. This morning, day 3, they have miraculously returned. My enquiries everywhere didn't really reveal a magic trick apart from the usual " clear history, cashe etc and reboot" .... all of which I did but this morning - all back to normal. A good ending but without a clear solution nor explanation. The last advice I received was to rebuild them... no easy task with 16 lists with 10-20 stocks a list! anyway if anyone else struggles the message is they do simply return at some point... hopefully at little personal cost.
Quite a big drop on ZigUp yesterday today. Any news please?
Not aware of anything. Its been up a bit recently and not unusual for it to start slipping when people get bored in between updates.
ZIGUP (LON:ZIG) I can't see any big drop today? What prices are you looking at?
Cnbc live price watchlist
No news for ZIGUP (LON:ZIG)
Remember the dividend paid on 9 Jan 26 will have been reinvested on a lot of portfolios since they were paid, many Thursday or Friday, so might just be a part of profit taking and less automated buyers today?
I hold in my AJBell SIPP and obviously they bought this morning just before they dropped!
Good luck
Tommy
Quite a list today so well done Graham. Games Workshop (LON:GAW) report today well worth a read - no bullshit just honest write up of progress in the business.
Primary Health Properties (LON:PHP) records an increased dividend. That's the 30th consecutive annual increase and at the current SP represents just over 7%. I'm a long term holder in 2 portfolios - one down on capital but level pegging thanks to divis and one a more recent buy showing a healthy capital gain too. With Assura merger now complete I'm happy to hold / top up.
SRT Marine Systems (LON:SRT) I hold
Excellent trading update showing strong 95% growth in revenue, PBT up 47% and an 85% growth in cash balance. The latest broker note highlights a £1.8bn pipeline of visible contract opportunities with a near term £200m Kenya contract being finalised. Also anticipates further strong profit growth for full year 26 and 27. Broker target sp 122p
Simon Tucker, SRT CEO said: "I am very happy with our H1 results which are in line with our expectations. As reflected by our £300m active-contract book and £1.8bn new contract opportunity pipeline we are experiencing strong and sustained global interest in our solutions underpinned by a new and evolving understanding of the importance of the marine domain. I expect to see SRT continue to gather pace and deliver strong growth this financial year and many years to come."
Looks like an opportunity today to 'buy on the dip' with the shares down 6%. Another example of the Mkt reaction to good results
Good results from Thor Explorations (LON:THX; I hold) and SRT Marine Systems (LON:SRT; I keep thinking of holding but never do). Would be very interested in commentary. The bullion bandwagon still looking unstoppable!!
Thor Explorations (LON:THX)
Results/forecast production for 2026 look very good to me.
Canaccord have raised their TP from 89p to 106p, the main factor is the raise in forecasts for 2026 - EPS now forecast at 38.7c up from 18.2 c.
A
Hunting (LON:HTG) flagging forthcoming acquisition(s) of subsea technology companies. Ashtead Technology Holdings (LON:AT.) anyone????! The HTG pipeline of subsea work and desire to grow its subsea business is very interesting. Must be a strong read across to AT. today.
Hunting (LON:HTG)
I have been following somewhat passively but am surprised having read the statement that forecasts were up with today or slightly higher even. That is not how it read... which puts me off a little. They are very keen to talk it up.
Ashtead Technology Holdings one to watch. Director purchase of £90k on 5th Jan.
Ashtead Technology Holdings plc (AT.), a leading subsea technology solutions provider to the global offshore energy sector, announces that Mr Tony Durrant, Senior Independent Non-Executive Director, has purchased 30,000 Ordinary Shares in the capital of the Company.
Trading update Monday 19th Jan. Good purchase and shows confidence.
I wouldn't spill your tea at £90k.. Tony Durrant is the ex CEO of Premier Oil for many years where he would have consistently taken him +£1m pa. A drop in the ocean.
Look at Kraken Robotics (CVE:PNG) supplying the kit for deep sea searching for MH370 on a no win no fee basis (I hold). I can't buy Anduril but would if could. Also look to Norway have some great subsea companies.
The search for natural resources and the North Atlantic undersea war all growth factors.
Sorry to say it's not Kraken Robotics, it's Ocean Infinity that's searching for MH370.
https://www.bbc.co.uk/news/art...
Exploration firm Ocean Infinity is leading the current search under a "no find, no fee" arrangement. It will receive $70m (£56m) if the wreckage is found, Transport Minister Loke Siew Fook earlier said.