Daily Stock Market Report (Tue 16th June 2026) - GMS, W7L, RAT, TAM, IHC, STEM, IGR, EMAN

Iran: there’s been genuine progress, although it remains difficult to quantify as the text of the US-Iran agreement has not been published yet. A key provision is that the Strait of Hormuz will be open for 60 days, allowing negotiations and the fragile ceasefire to continue. The Strait is not currently open for business.
Early last week, Brent crude oil (for August delivery) reached a high of $98. As I type this, it’s below $83. There’s still a gap to fill, to reach pre-war levels of $60-70, but it’s progress.
Japan: I note that the famous “widow-maker” Japan trade, which involves shorting their government bonds (JGBs), continues to perform well.
Here’s the Japanese bond yield. A rising yield means that the value of the underlying bonds is falling:
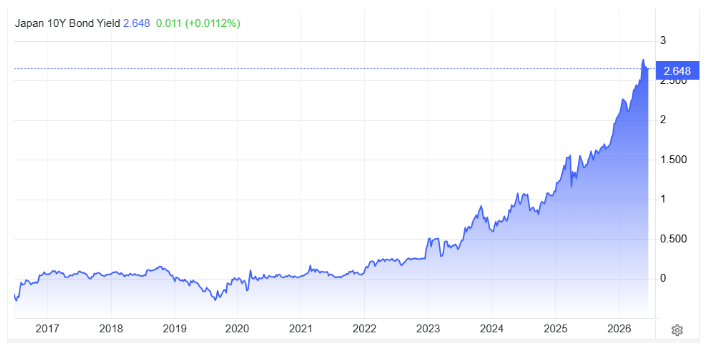
This is even a trade that I temporarily sat in, about ten years ago. Unfortunately, its reputation as a widow-maker was not without justification: JGBs were remarkably resilient for a remarkably long time.
But that technical fact didn’t stop thousands of traders from betting that JGBs would collapse. Their (or perhaps I should say “our”, as I was one of them) reasoning was impeccable. Japanese rates were close to zero or even negative. Their debt to GBP ratio was over 200%. Their population was shrinking. Logically, it didn’t make sense that rates could stay at that level.
However, the irrationality of markets outlasted our exuberance, and many traders who attempted to short JGBs have been retired by the markets by now. The Bank of Japan has just raised its benchmark rate to 1%, the highest level in over 30 years, and JGB yields are finally at normal levels. A timely reminder that whether we are looking at stocks or bonds, we can never assume that financial prices will return to “normal” within a reasonable timeframe.
Overnight market movements:
The FTSE is set to open up 0.7% at 10,542
S&P 500 is set to open up 1.3% at 7,524
Brent crude is down 4.4% at $83.50/bbl
Gold is up 1.7% at $4,288/oz
Bitcoin is up up 2.1% at $65,698
Calling it a day there, thank you!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Zegona Communications (LON:ZEG) (£4.0bn | SR61) | Broadband lines up 29k to 2,591k. Vodafone Spain revenue flat at €3,628m. Returned €1.6bn to shareholders, including €1.4bn special dividend. Year end net debt €3.2bn. | ||
Rathbones (LON:RAT) (£2.1bn | SR59) | Skilled Person Review following engagement with the FCA. Areas for improvement identified in UK wealth management re: the implementation of Consumer Duty and certain aspects of compliance, oversight and assurance. Voluntary pause on certain activities with clients that require Enhanced Due Diligence. | BLACK (AMBER) (Graham) I’m willing to look past the £60m of short-term costs. However, what’s really important is the effect that this review could have on long-term profitability. There could be a general overhaul of fees. Wealth managers such as Rathbones aren’t cheap and while some of their clients are financially sophisticated, many will not be. In the current regulatory environment, this puts the onus on Rathbones to deliver the best possible outcomes to them. I’d suggest that we could be looking at a 10-20% reduction in long-term profitability. The earnings multiple isn’t expensive but economic returns here have been average and I tend to think of it as a people business. I’m therefore inclined to take a neutral stance on it today. | |
International Workplace (LON:IWG) (£1.75bn | SR30) | Founder and current CEO becomes Exec Chair. Chief Transformation Officer becomes CEO. Non-Exec Chair becomes Deputy Chair. | ||
Hilton Food (LON:HFG) (£471m | SR69) | New independent non-Exec Chair. The current Exec Chair to become CEO. | ||
Tatton Asset Management (LON:TAM) (£369m | SR46) | AUM +11% to £24.2bn. Revenue +20.1%. Adjusted operating profit +24.1% to £28.5m. Adjusted EPS +22.3% to 35.05p. All of these figures are ahead of expectations. | AMBER/GREEN = (Roland) This is a fairly strong set of figures. Market tailwinds and continued net inflows allowed Tatton to deliver double-digit AUM growth last year, despite the impact of a one-off £3.3bn outflow. The group’s ambition to increase AUM to £30bn by March 2029 implies a 7.4% CAGR and seems reasonable to me, assuming we avoid a market crash in the meantime. There’s no certainty of this, of course, and I think it’s probably prudent for investors to consider how the market might view the valuation of this business if growth slowed. I remain positive, but given the wider macro and market context, I think a moderately positive view is fair here. | |
Boohoo (LON:DEBS) (£349m | SR38) | GMV down 21.6%. Adjusted EBITDA +35% to £53.3m. Pre-tax loss £109m. FY26 net debt £93m. Leverage multiple 1.75x, targeting <1x for FY27. Outlook: expecting GMV to return to growth. FY27 adj. EBITDA to grow at double digits. Operating costs to reduce further. | ||
Optima Health (LON:OPT) (£211m | SR61) | Revenue +15%. FY26 adj. EBITDA to be c. 10% ahead of previous expectations, as previously announced. Net debt £94m. | ||
Gulf Marine Services (LON:GMS) (£208m | SR71) | All vessels temporarily evacuated from one of the countries in the Gulf due to the prevailing geopolitical situation have now successfully returned to hire on the same contracts. Maintaining adj. EBITDA guidance for 2026 in the range of $105-115m but continues to assess the final financial impact of this disruption through ongoing discussions with clients. | AMBER = (Roland) [no section below] It looks like GMS hopes to secure at least partial payments from clients for the period when four of its vessels were out of action, although I don’t know how likely they are to succeed. As things stand, full-year guidance is unchanged. Broker Zeus also confirms its EBITDA forecasts are unchanged, while noting that Zeus’s $105m EBITDA estimate is at the bottom end of guidance. Looking ahead, the recent expansion of the fleet could support a stronger year of earnings in 2027, assuming normal market conditions. However, there’s no guarantee of the latter and the risk remains that management will overpay for fleet expansion to the detriment of shareholder returns. The current share puts GMS on a FY26E P/E of 10, which seems about right to me. I’m going to leave my previous neutral view unchanged today – a position also reflected by the StockRanks. | |
SThree (LON:STEM) (£206m | SR91) | Net fees down 7%. Rate of decline moderated through the half. Strong growth in USA. Performance for FY26 expected to be in line with the previously announced c.£10 million PBT guidance. | AMBER = (Graham) [no section below] These shares are cheap if you think the problems facing the rectruitment sector are cyclical rather than structural in nature. SThree's strong 14% growth in the United States suggests that economic factors, which vary by geography, are playing a role - and therefore that the current overall weakness may be temporary. I haven't quite managed to make up my mind but the ongoing downward trend in net fees is sufficient to keep me on the sidelines. I note in passing that Contract net fees (down 8%) are underperforming Permanent net fees (down 5%), which is not what you'd expect in a downturn - Contract fees should be more stable than Permanent net fees. It's a puzzle but my conclusion for now is that recruitment remains a dangerous sector for investors. SThree does still maintain a strong balance sheet with cash of £43m and about £12m of shares left to repurchase under its buyback programme. | |
Accsys Technologies (LON:AXS) (£187m | SR44) | LfL revenue +20%. Adjusted EBITDA +96% (€21.2m). Statutory loss before tax €0.6m. "This strong set of results reflects disciplined execution of our FOCUS strategy in a challenging macroeconomic environment.” Trading in line with the Board's expectations for FY27. | ||
Warpaint London (LON:W7L) (£174m | SR73) | Trading conditions continue to be difficult, but Q2 has been more encouraging than Q1 so far. FY expectations remain unchanged. | AMBER ↑ (Roland) An H2 weighting is expected this year, as improved margins and growth initiatives contribute later in the year. It’s too soon to be certain that the run of profit warnings seen over the last year has ended, but I think there’s enough here to justify upgrading to a neutral view. In my view, this business has a number of attractive qualities. If the company can deliver on forecasts this year, the P/E of 11 and 6% yield suggest to me the shares could offer value at current levels. The steady rise in Warpaint’s StockRank over the last three months is also encouraging, in my view. | |
Galantas Gold (LON:GAL) (£135m | SR28) | Voted to approve the acquisition of Sol de Oro Mining and in favour of the Company’s omnibus equity incentive plan”. A new non-board CFO has also been appointed. | ||
Smarter Web (LON:SWC) (£131m | SR20) | Oliver Hewett has been promoted to CFO. He was previously Group Financial Controller. He will not be appointed to the Board. | ||
IG Design (LON:IGR) (£87m | SR71) | SP -7% Revenue -3% reflecting tariffs, pricing and softer UK demand. Adj operating profit -40% to £9.6m, adj EPS -28% to 7.2p. Outlook: guidance remains unchanged, expect 0-5% adj op margin of 4-5% and c.£5m free cash generation. | AMBER/GREEN = (Graham) [no section below] Net cash of £55m is the standout figure considering the market cap of only about £80 million after today's 7% fall. Investors don't trust this share after the disappointments of recent years, but short-term news flow is encouraging given recent EPS upgrades, a bolt-on acquisition, the recommencement of dividends and a buyback of up to 10% of its outstanding shares. With the disposal of the American business last year this is now a much simpler proposition and on the basis of today's outlook statement, I think we have to remain moderately positive here. It offers the potential for modest cash generation (£5m) on top of an already impressive cash balance, relative to the market cap. A new CEO begins next month, bringing fresh eyes to the company's challenges. If investors can also bring fresh eyes to this share, and try to forget the past, they may find that it's worthy of a second look. | |
Tpximpact Holdings (LON:TPX) (£59m | SR87) | Revenue +1%, with H2 revenue +16% vs H1. Adj EBITDA +54% to £8.6m with op profit of £0.8m and adj EPS of 5.4p (FY25: 3.0p). Completed three-year turnaround and halved net debt to £4.2m. FY27 outlook: expect double-digit revenue growth with adj EBITDA of not less than £12m. | ||
Alternative Income REIT (LON:AIRE) (£56m | SR50) | Responding to Friday’s offer of 70p per share: “There are many reasons why the Independent Board is not currently in a position to recommend the Glenstone Offer to shareholders, with the principal one being that Glenstone's Offer represents a 17 per cent. discount to AIRE's latest published net asset value of 84.4 pence per share as at 31 March 2026”. | TAKEOVER | |
Poolbeg Pharma (LON:POLB) (£53m | SR27) | Received notice of decision to grant for its POLB 001 cancer immunotherapy-induced Cytokine Release Syndrome ("CRS") patent. “... this grant increases the commercial value of POLB 001 to potential partners”. Trial data is expected over the summer. | ||
Gelion (LON:GELN) (£42m | SR5) | A subsidiary has signed an exclusive commercial licence agreement with the Max-Planck-Innovation GmbH for intellectual property covering nano-encapsulated sulfur cathode technology and novel nano-confined anode materials. This concludes an agreement announced in March 2025. Payment terms not disclosed. | ||
Christie (LON:CTG) (£36m | SR94) | “Robust levels of demand” so far this year with agency pipelines +19% in deal volumes. H2 weighting expected due to “slightly extended deal times”. Outlook: expect full year performance in line with expectations. | ||
Everyman Media (LON:EMAN) (£32m | SR50) | 3 board members controlling 45.6% would like to delist the company. They believe they have the support of shareholders representing a further 11% of the stock. Stakeholder discussions are underway. At this stage, the board believes it is likely that Everyman will proceed with proposing a delisting. Trading: admissions +23.1% YTD (to 28 May 26), with revenue +26.5% and adj EBITDA +45.2% to £9.4m. FY26 Outlook: uncertain due to economic environment and dependence on Q4 trading. | RED = (Graham) [no section below] I'm glad that I stayed consistently RED on this as the company's time as a listed entity now appears to be approaching its end. With more than 50% of shares already likely to vote in favour of a delisting, that appears to be a probable outcome and not an illogical one considering the company's lack of progress as a listed company and c. £30m market cap. Net debt is reported as £17.6m which is at least down year-on-year, as the company has halted expansionary capex. The trading update offers an uncertain outlook but I would argue that the main practical uncertainty is now the potential for a delisting and the impact that this will have on liquidity for small shareholders. | |
Gana Media (LON:GANA) (£30m | SR2) | Raising £750,000 through the issue of 375m new shares at 0.2p per share. Directors participated. Company reports new registrations and wagering volumes at Estadio Gana in Mexico are “up significantly” in Q2. | ||
Inspiration Healthcare (LON:IHC) (£23m | SR57) | Revenue +24% to £47.5m, gross profit +27% to £20.8m and adj operating profit of £0.8m (FY25 £(1.9)m. Net debt reduced to £5.1m. FY27 Outlook: currently trading in line and confident of meeting full-year expectations. | AMBER/RED (Graham) | |
Great Southern Copper (LON:GSCU) (£21m | SR3) | Scout reverse circulation ("RC") drilling commences at Artemisa South prospect, targeting old mine workings where structurally-controlled vein and disseminated type Cu-Au mineralisation occurs in granodiorite south of the La Colorada lithocap. | ||
Cizzle Biotechnology Holdings (LON:CIZ) (£13m | SR14) | CIZ1B biomarker (early stage lung cancer) test successfully accredited for clinical use in the U.S. under CLIA. Enables licensed U.S. healthcare providers to order the test signifying commercial launch. | ||
Galileo Resources (LON:GLR) (£12m | SR15) | Has entered into an agreement with a subsidiary of Sandfire Resources for the sale of Botswana prospecting licences PL039/2018 and PL040/2018. There will be an upfront consideration of $3m on completion, with a possible one-off success payment of $20-80m, subject to levels of contained copper. |
Graham's Section
Rathbones (LON:RAT)
Down 16.5% at £16.29 (£1.49bn) - Regulatory Update - Graham - AMBER
This is a grim update:
Rathbones Group Plc… announces that it has undertaken a Skilled Person Review following engagement with the Financial Conduct Authority… The review has identified areas for improvement within the Group's UK Wealth Management business regarding the implementation and embedding of Consumer Duty, as well as certain aspects of its compliance, oversight and assurance arrangements.
The words “Skilled Person Review” sends shivers down my spine.
This is when the FCA mandates a review of a company’s processes. We’ve seen it before with the likes of Jarvis Investment Management and S&U. They tend to be long and very expensive episodes and the outcomes can sometimes be very serious for the organisation.
Rathbones announces that it’s taking the following actions:
A programme of work addressing the recommendations from the review, which is expected to be conducted over a two-year period.
A two-year period - see what I mean about these reviews taking a long time? These reviews tend to hang over a company and its valuation for years.
Continuing:
A targeted review of a portion of our clients to assess whether they have received good outcomes.
The FCA’s Consumer Duty requires firms to act to deliver good outcomes for retail customers. That might sound somewhat subjective - because it is. If a review is happening, that says that the FCA wants some questions answered.
For a period of up to twelve months, a voluntary pause to the onboarding of new clients that require Enhanced Due Diligence ('EDD clients') whilst the Group focuses on implementing changes to its procedures and controls. In the last twelve months, relevant gross inflows from EDD clients totalled approximately £370 million.
A voluntary pause to the acceptance of inflows into general investment accounts from some existing EDD clients…
Let’s try to put the flow figure into context. In 2025, total gross inflows were £11.2 billion, while total gross outflows were £13.3 billion.
So £370m would not have been a huge percentage of total inflows, but it would have been significant in terms of its impact on net flows, if it had been paused last year (net outflows were £2.1 billion).
Due diligence has been a hot topic at financial firms for many years as governments have attempted to crack down on money laundering and tax evasion. So it’s a significant misstep if Rathbones’ procedures have not been up to scratch - the type of thing that can lead to serious but avoidable fines.
Costs: these actions are expected to cost £60m over the next two years. Rathbones will nevertheless continue with its £20m buyback as planned.
Fees on cash balances: underlying PBT will take a £9m hit in 2026 from ceasing to charge fees on cash balances in discretionary portfolios. This will be implemented from 1st July, so that’s a c. £18m hit if it’s annualised and if it becomes a permanent change. This is part of the company “reviewing certain aspects of its pricing as part of its ongoing commitment to delivering fair value for clients.”
Graham’s view
We don’t usually cover this stock but it looks like this story will be worth following.
I’m willing to look past the £60m of short-term costs. However, what’s really important is the effect that this review could have on long-term profitability.
According to market forecasts, Rathbones’ PBT was supposed to progress from c. £260m to c. £300m over the next few years.
It sounds like the FCA might take a dim view when it comes to charging investment management fees on customers’ cash balances in portfolios that are being managed by Rathbones. I’ve annualised the cost to £18m and while Rathbones might be able to mitigate that figure, I think it’s reasonable to assume that this change will be made permanent and most of it will not be mitigated.
After that, there might be a more general overhaul of fees. Wealth managers such as Rathbones aren’t cheap and while some of their clients are financially sophisticated, many will not be. In the current regulatory environment, this puts the onus on Rathbones to deliver the best possible outcomes to them.
So I would consider Rathbones’ earnings forecasts to be highly fragile now, even after we cut them by £20m to reflect the change to fees on cash balances. I’d suggest that we could be looking at a 10-20% reduction in long-term profitability, plus the short-term impact from one-off costs. The initial £60m estimate in that regard should be taken with a pinch of salt.
In conclusion: the 16% fall in the share price this morning seems approximately right to me, although I personally might have marked it down by 20%+.
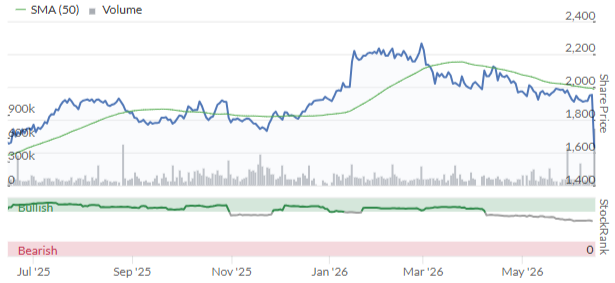
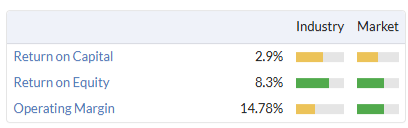
The earnings multiple isn’t expensive: perhaps still in the region of 10x, depending on what happens to EPS forecasts after this announcement. But economic returns here have been average and I tend to think of it as a people business. I’m therefore inclined to take a neutral stance on it today.
The QualityRank is 47:
Inspiration Healthcare (LON:IHC)
Up 7% at 27.9p (£25m) - Final Results - Graham - AMBER/RED
Inspiration Healthcare Group plc (AIM: IHC), the global medical technology company, pioneering, specialist neonatal intensive care medical devices, announces its final results for the year ended 31 January 2026 ("FY26").
These are pleasant results and the outlook statement is in line with expectations.
In more detail:
FY January 2026 revenue +24% to £47.5m
Adj. EBITDA £2.8m (2025: £0.2m)
Adjusted operating profit £0.8m (2025: loss of £1.9m)
While the turnaround from losses to profitability is impressive, it must be said that on a statutory basis, the result is still a loss of £0.1m (effectively breakeven).
There were “non-recurring items” of £0.8m, namely “restructuring costs resulting from employee severance payments, and increased provision for dilapidations at the Group's old site in Croydon where the leases were formally exited during the year.”
I don’t know if I trust that FY27 will see a cleaner result than this - it might be safer to assume that some non-recurring costs will be a regular feature here? But this FY26 result is still a mammoth improvement on FY25, which saw far higher non-recurring costs (£12.8m).
Net debt reduces from £8m to £5m.
Balance sheet: tangible equity is about £9m, mostly in the form of working capital (inventories and receivables). In practical terms it seems that most of the cash generation and debt reduction in FY26 was achieved through the 33% reduction in inventories (from over £13m to less than £9m).
Infusion: in the new financial year, IHC has agreed to give up the right to transfer infusion pumps made by the Greek company Micrel. There will be a transition period until January 2027.
Infusion products were responsible for about £10m of revenues in FY26, so this will shrink IHC’s revenue base over the next few years.
Estimates: accordingly, the latest forecasts from Cavendish are as follows.
FY27 revenue £40m, adj. loss before tax £1.2m.
FY28 revenue £33.1m, adj. loss before tax £1.9m.
Outlook statement:
Current trading is in line with the Board's expectations, and the Group has an increasing orderbook and an improving pipeline of opportunities for FY27. We have already secured some notable orders from European distributors which has been a strategic priority under the back-to-basics campaign.
The announcement that the infusion product rights will return to Micrel after 31 January 2027, allows the Group to focus on its core business of neonatology and neonatal ventilation in particular which are the markets where we have the most growth potential.
Graham’s view
The market hasn’t reacted much to the Micrel news - first announced at the beginning of this month - probably because the downside of losing the business is offset by the upside of reducing expenses and receiving a compensation payment (about £1m).
In other words: the Micrel distribution rights weren’t very profitable anyway.
As for my overall view on IHC, the lack of profitability in the forecasts, even out to 2028, is obviously going to be a problem for me. I’m a simple investor at heart: I like to see regular profits. IHC isn’t offering that for the foreseeable future.
More positively, the company does have plenty of working capital and the debt position is expected to be stable. Cavendish are forecasting that net debt will stay around the £5m mark for the next few years.
I’m going AMBER/RED for the simple reason that IHC is a small company that is both financially indebted and unprofitable. But hopefully they will figure out how to get into the black over the next few years. There couldn’t be a more worthy mission than improving neonatal care.
Roland's Section
Warpaint London (LON:W7L)
Up 1% at 220p (£178m) - AGM Statement - Roland - AMBER ↑
Today’s AGM Statement takes a fairly measured tone on trading, but leaves full-year expectations unchanged. If management can deliver on this, it could mark an end to the run of profit warnings we’ve seen over the last 10 months:
Key points:
The [challenging] trading conditions seen in 2025 continued into Q1.
Trading remains difficult, but Q2 sales from 1 April - 31 May are ahead of the same period last year.
Overall group sales are at “an improved margin” compared to 2025.
The group has “significant planned expansion opportunities” for later in 2026 and expects further margin improvement.
Expectations for the full year remain unchanged.
Inevitably this commentary means that an H2-weighting is expected this year:
… sales in 2026 are expected to be more second half weighted than prior years due to the timing of certain larger orders and planned customer rollouts.
Warpaint’s management flag up growth opportunities in Germany and the US:
Germany: launched a capsule range of W7 products into 2,200 Dirk Rossmann stores in May, “early sales are encouraging”.
US: “significantly improved Christmas order received from Walmart”. Warpaint will also be launching an online Christmas gift range with Ulta Beauty, “the largest specialty beauty retailer in the US”. This could lead to further opportunities in 2027.
Balance sheet: the company confirms that the balance sheet remains debt free, with cash of £20.6m at 31 May 2026 (May 2025: £15.0m).
Ward & Hagon: the company is in talks to renew a management consulting contract with Ward & Hagon for a further 24 months. The renewal is expected to include “additional sales responsibilities and increased time commitments” to reflect the expansion of the Warpaint business since the previous renewal on 1 February 2024.
The partnership with Ward & Hagon is a longstanding arrangement (since 2020) which has previously seen Ward & Hagon representative Paul Hagon serve as an executive director of Warpaint. As part of this renewal, Hagon will step down from the board.
Terms haven’t yet been finalised for the renewal, but the previous contract was priced at £225k per year. Further details of the renewal will be provided in due course.
Broker estimates
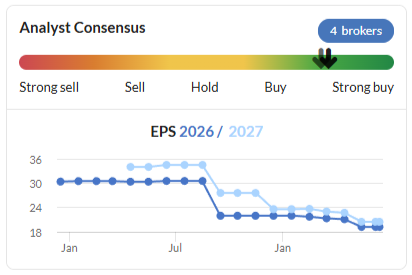
Forecasts from both Cavendish and Shore Capital are unchanged today and largely reflect the consensus estimates in the StockReport:
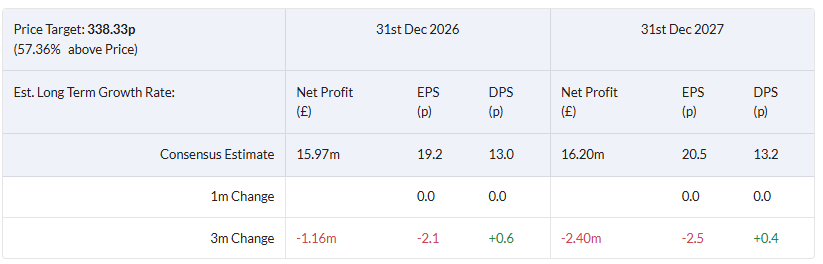
Roland’s view
I took a cautious view on Warpaint in April when the company issued a profit warning with its full year results. But I also noted at the time that “some value may be emerging” and suggested it could be worth watching for signs that the outlook had stabilised.
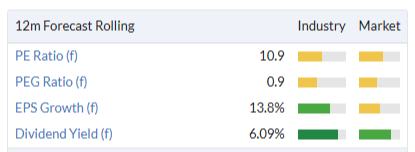
It’s too soon to be certain given the expected H2 weighting, but my feeling is that we may now have reached that point. The current valuation looks undemanding to me, with a P/E of 11 and PEG ratio of 0.9x, below the traditional value threshold of 1.0x:
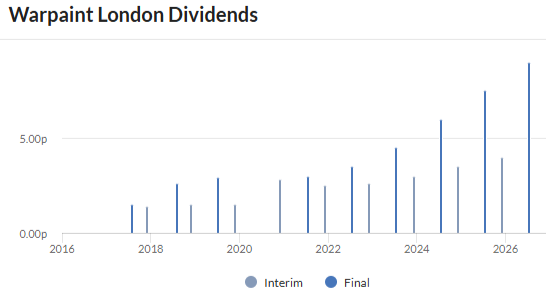
The 6% dividend yield – covered by earnings and net cash – is an additional attraction in my view. Except for a pause during the pandemic, Warpaint’s payout has not been cut since the company’s IPO in 2016 – a typical characteristic of companies with owner management:
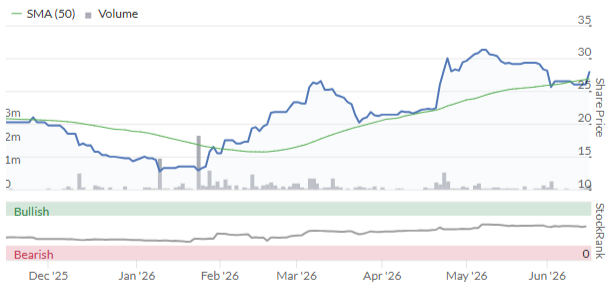
Taking a quantitative view, Warpaint shares have consolidated at the current level for more than six months and the StockRank has been rising steadily:
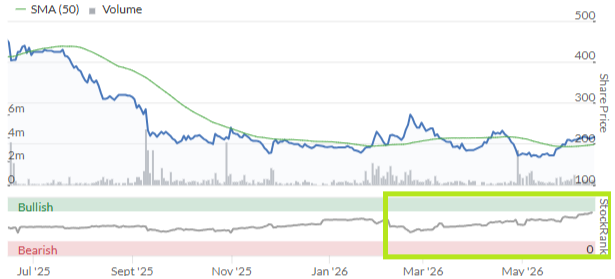
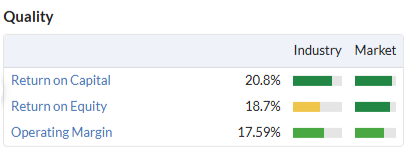
Finally, quality metrics for this capital-light business remain excellent, highlighting Warpaint’s ability to self-fund its growth while still generating attractive shareholder returns:
I am going to move our view to neutral today, with a view to turning more positive if guidance remains unchanged later this year. AMBER
Tatton Asset Management (LON:TAM)
Up 16% at 698p (£428m) - Title - Roland - AMBER/GREEN =
Today’s full-year results are ahead of consensus forecasts and have prompted broker upgrades for both FY27 and FY28.
Key points (y/e 31 March 2026):
Revenue up 20.1% to £54.4m
Pre-tax profit up 17.2% to £25.3m
Adjusted EPS up 22.3% to 35.05p (+6.8% vs Stockopedia consensus of 32.8p)
Total dividend up 42% to 27.0p (+16.9% vs Stockopedia consensus of 23.1p)
Cash of £33.9m (FY25: £32.1m)
These figures support excellent quality metrics and cash generation, as usual with this business:
Operating margin: 44.5% (FY25: 45.7%)
Return on Equity: 34.0% (FY25: 34.4%)
Free cash flow: c.£18.5m, giving 100% conversion from net profit
Surplus cash generated by the business covered the dividend and buybacks last year.
Operational performance: Overall AUM growth for the year was held back by a planned one-off £3.3bn outflow relating to the loss of a specific contract. However, today’s results show good underlying investment growth and solid new business performance, with net inflows replacing the majority of the lost assets:
Total AUM up 11% to £24.2bn
Total net outflows of £0.52bn
Underlying net inflows of £2.81bn, excluding the £3.3bn
IFA firms increased by 9.7% to 1,218 (FY25: 1,110), with client accounts up 2.6% to 157,850 (FY25: 153,915)
Paradigm Mortgages “participated in mortgage completions totalling £18.0bn” (FY25: £14.2bn)
Investment performance - beating the market? Tatton’s asset management business is built around a range of managed portfolios. Financial advisers can access these on popular platforms in order to invest their clients’ cash. This allows the adviser to maintain the client relationship, while outsourcing investment management to Tatton and avoiding the regulatory and risk burden of investment selection.
Tatton’s portfolios appear to be competitively priced, but the other question that matters when it comes to fees is whether strategies perform well.
To its credit, Tatton provides clear details of the annual investment returns for its six core model portfolio strategies. These have varying equity components – the Global Equity line is the most relevant for our purposes, I think, as I believe these strategies have a 98% equity allocation:
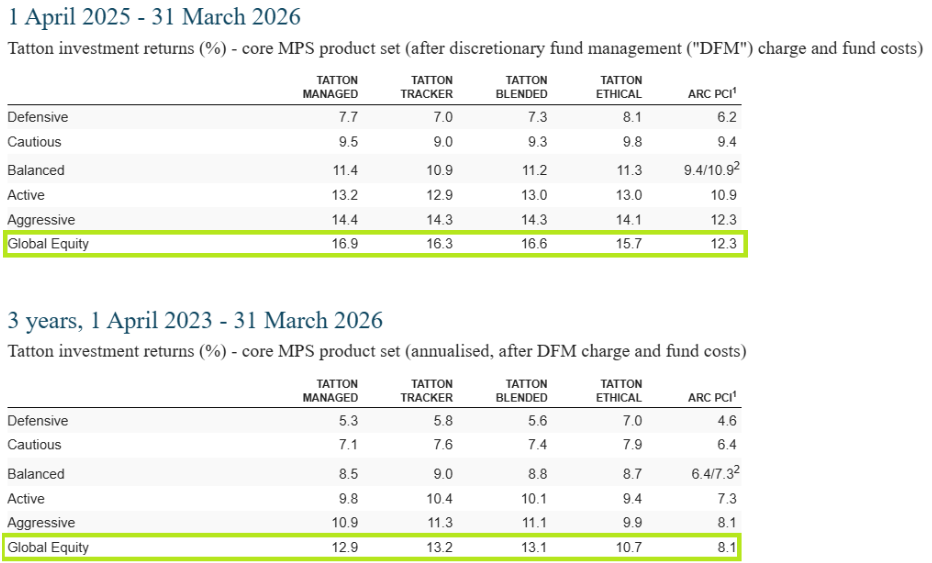
For some context, here are the returns from various key equity indices over the same period::
FTSE 100 total return: 21.9% (3yr annualised: 14.2%)
S&P 500 total return: 17.4% (3yr annualised: 18.3%)
FTSE All-World: 16.6% (3yr annualised: 14.5%)
The performance of Tatton’s lowest-cost Tracker strategy last year was similar to the FTSE All-World index. This is also true on a three-year view, according to the tables above, which are included in today’s results.
However, given the similarity of results from the company’s actively-managed strategies, it’s not clear to me that the additional fees levied on these portfolios are delivering results for investors. Of course, the last three years has been a notoriously difficult time for active managers to beat the market, especially in the US.
Outlook & Updated Estimates
Clearly, many of Tatton’s IFA customers are happy with its services and are choosing to continue to add their clients’ cash to its portfolio offerings.
This momentum is not expected to slow anytime soon. Today’s outlook commentary from founder-CEO Paul Hogarth acknowledges macro risks, but sounds a confident note:
Tatton Asset Management enters FY27 with strong underlying momentum and a clear sense of strategic direction. The core business has delivered another year of excellent organic growth. Our adviser network has expanded, our margins have improved, and our investment proposition continues to attract recognition across the market.
Tatton has maintained its growth target for AUM of £30bn by the end of FY29 (March 2029).
Broker Zeus has translated this commentary into upgraded FY27 and FY28 forecasts:
FY27E adj EPS: 41.0p (+8.9% vs 37.7p previously)
FY28E adj EPS: 45.8p (+10.9% vs 41.3p previously)
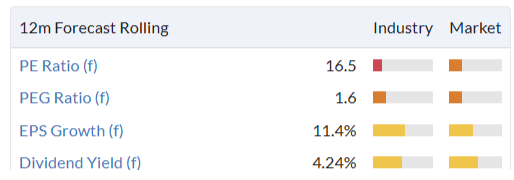
These estimates put Tatton on a FY26E P/E of 16.5x, in line with the valuation on the StockReport prior to today’s upgrades (and share price gains):
Roland’s view
As I commented in The Week Ahead on Friday, this has been one of the most successful AIM IPOs I can remember in recent years. Today’s results don’t really change that view.
The company’s growth is being supported by a structural trend towards on-platform discretionary fund management, as an increasing number of IFAs choose to outsource their investment decisions to asset managers:
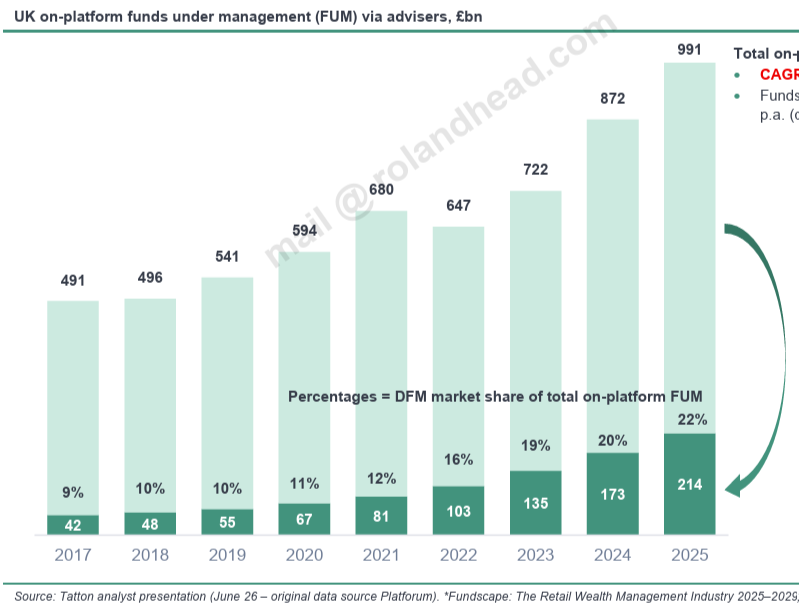
Source: Equity Development
I have no idea when or if this trend will slow, but I would imagine it’s likely to continue for some time yet. If more IFAs are outsourcing their investment management, then I would guess that progressively fewer will become willing to risk their reputations (and finances) by making their own decisions.
Today’s results leave the company’s target of reaching £30bn of AUM by March 2029 unchanged. Meeting this goal would imply annualised AUM growth of 7.4% over the next three years – below the 11% level seen last year.
Of course, last year’s result was aided by fairly strong investment returns, as has been the case for several years. If the market enters a prolonged slump, achieving AUM growth could become more difficult.
In such a scenario, Tatton’s premium valuation could come under pressure as investors priced in a period of stagnation.
Predicting the timing of stock market crashes is beyond my paygrade, but there’s clearly a narrative at the moment which suggests we could be closer to the top than the bottom of the current cycle. This may help to explain why Tatton’s share price has eased in recent months despite multiple earnings upgrades:
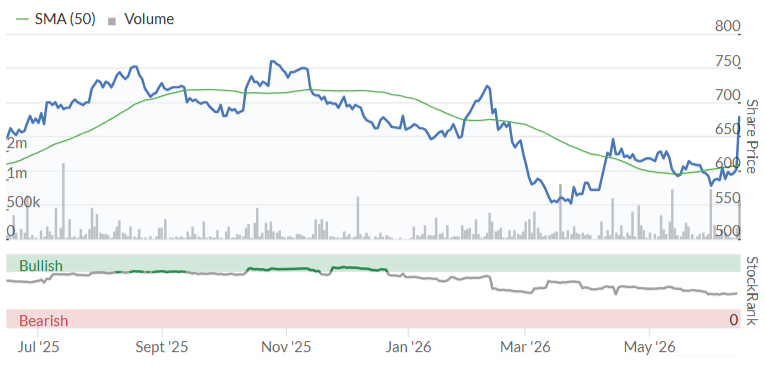
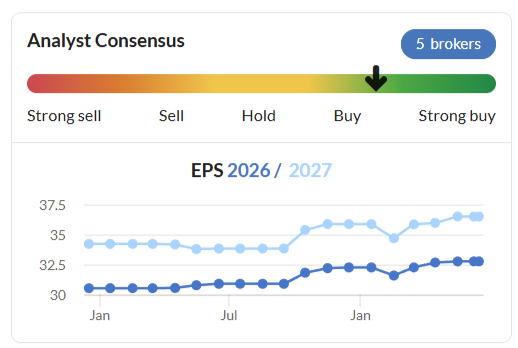
Graham was AMBER/GREEN on Tatton in November 2025, noting the quality of the business and the appeal of founder management. On balance, I don’t see any reason to change that view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Space Exploration Technologies (NSQ:SPCX) appears to be valued based on the infinite size of space itself. Congrats to holders!
On a day when there are more important matters around eg Rathbones, etc nevertheless Warpaint London (LON:W7L) slipped out an AGM review and our esteemed experts here deemed to give it a full report and a mildly positive push. I beg to differ.
I am skeptical about what Warpaint can achieve in the USA in particular. My research indicates that it is collecting the crumbs of the business, and it will make little or no progress as a branded company. Here is a summary of my research.
Warpaint London’s entry into Ulta Beauty in the US with its W7-led Christmas gift range is a low-risk, high-hurdle test case that faces extreme headwinds in the US mass-market cosmetics sector.
While Warpaint is a highly profitable, debt-free, and well-managed company in the UK and continental Europe, the US has historically been a challenging region for them. It is a fact that US revenue actually declined 21% to £6.9 million (accounting for just 9% of their total business).
An analysis of why my doubts are structurally correct highlights the massive challenges Warpaint faces in converting an online holiday trial into permanent, high-volume shelf space at Ulta:
1. The "Online-Only Gifting" Safe Bet
Ulta's decision to launch Warpaint's holiday range online-only is a classic retail strategy to mitigate risk.
2. The e.l.f. Beauty Monolith (The Market Share Wall) The primary obstacle to W7 expanding into standard everyday lines at Ulta is e.l.f. Beauty, alongside competitors like NYX and Wet n Wild.
3. The Digital Marketing Disadvantage
Ulta is an algorithm- and data-driven retailer. To succeed on Ulta.com against dominant US brands, a brand requires a massive digital marketing engine.
Despite these steep hurdles, Warpaint is not without a strategic playbook. If they do manage to achieve surprise volume, it will likely come from a successful Xmas trial, hopefully - stressing hopefully - to an everyday roll out next year with a high margin range.
Yes, The Value-Seeking Consumer Shift: the US consumers are currently experiencing intense inflationary fatigue. If American shoppers flock to Ulta looking for sub-$10 holiday gifts, W7’s price-to-quality ratio could trigger strong impulse buys online.
Yes The Walmart/CVS Blueprint: Warpaint is not entirely green in the US market. They already supply Five Below, CVS and Walmart. They understand US logistics and supply chains. If they can cross-promote their Ulta launch to their existing US retail footprint, they might generate the necessary initial momentum.
But The Bottom Line I think that caution is the name of the game. Significant volume and deep penetration are unlikely in the short term. This Ulta online launch is a low-stakes experiment for both parties. Expect W7 to experience a moderate, profitable seasonal bump from the holiday range, but breaking into Ulta's permanent in-store everyday lines next year will require a highly expensive, uphill marketing battle against e.l.f. and Amazon replenishment trends. Not Warpaint’s style or capacity.
Thank you for your in depth alternative view. Having been previously invested in Warpaint London (LON:W7L) i am inclined to lean towards your view.
Glad to be of help. Generally use other people's expertise. Good to be able to contribute though sad about my findings. I think that Warpaint London (LON:W7L) will be around for a long time, but they will be playing a fringe if still profitable position. Dreams of US success? Well they are among much bigger bed fellows - Tesco and Sainsbury among them - who have tried and failed in the US. They should think very hard about balancing their scarce resources between the two sides of the Atlantic. They have always been stronger in Europe, even than the UK, and may have to fight to retain that. e.l.f. are on the WARpath in Warpaint London (LON:W7L) territory - geographical and quality/price points, reach in target market groups ttoo..
Tpximpact Holdings (LON:TPX)
Good results this morning. Cavendish has increased target price from 80 to 120 (it was 45 at the interims) and adj. eps to 3/27 from 6.1 to 8.3 with 10.3 to 3/28 introduced. The latter is for a p/e of 6.4 at today's 12m high of 66p. This one was picked up in Ed's uptrends screen a month ago https://www.stockopedia.com/co... Roland - still Amber/Green for you?
Edit - iwright7 - you beat me to it!
Another decent "Jump" today from Tpximpact Holdings (LON:TPX) making it a 12M clean sweep....
Tpximpact Holdings (LON:TPX) also qualified last month in Ed's R2: "Didn't buy Serabi Gold? Why clear uptrends are the best uptrends and 20 stocks to consider now". I continue to hold.
Rathbones (LON:RAT) - not good news today. Maybe share price reaction a bit exaggerated as probably been going on for well over a year. I think they have been re-working some of the AML checks for existing clients, possibly Investec related. Fees are generally quite competitive, from what I have seen, at 0.7% on average with the upper end very competitive. Consumer duty issues are probably at the lower end where closer to 1%. I expect the FCA want to make a point by selecting the market leader. I think others have had issues as well. It's nothing like St Jamess Place (LON:STJ) which charges much higher fees with entry and exit charges, in my view!
I think market reaction about right Section 166 always cost about 100% more than estimated and similarly take longer than expected. Consumer Duty is particularly nebulous as it is standard practice for FCA to go after firms if they think after execution that the implementation is incorrect, despite it being for the business to decide on the execution. Consumer duty may hide ' suitability' issues as well which would add to the burden of correction
I am not aware how much of RAT business is impacted but it can hardly be great that they have accepted not to take new funds from these clients
Would appreciate your thoughts on SDCL Efficiency Income Trust (LON:SEIT) announcement today
re SDCL Efficiency Income Trust (LON:SEIT), the big question is why the sharp markdown, when the likelihood of the wind-down, and the troubles at Onyx, have been known for some time.
Hi ST my view ( I hold in my ISA !) is that Mr Market does not like the dividend being passed and lack of a clear indication that any payment wil be forthcoming
I concur. The tone of the announcement was very downbeat and the news of the div suspension hardly encouraging. Onyx seems the major cause here. I think Market reaction is unsurprising unclear what is the level of involvement of Jefferies and Saba
Good morning Graham,
could we have your views on the FY results from Tatton Asset Management (LON:TAM) out this morning. SP has been sliding for a while (don't know why) and as a result PE has down to 16. I am late to this party (only yesterday) but the results and yield tempt me to stay.
I hold
Tatton Asset Management (LON:TAM) yes great results. Their net inflows shown as underlying is a bit sneaky given the large specific outflow, but more than happy to ride this one up! Its about half the fee margin of Rathbones so is a very low cost option.
Thanks Roland. very useful
Rathbones (LON:RAT) if anybody can add colour to this poor announcement - all gladly received. Im more interested in what hey have not being doing with EDD clients ? than the charging on cash issue which is actually complicated and simply not charging may well have adverse effects. Reading the statement though - short on detail and not consistent with Rathbones (LON:RAT IMO.
Rathbones (LON:RAT)
its the same old same old here - when the FCA steps in well it can get very messy. They themselves say its gonna cost £60 mill to sort out this mess. Its huge risk of any companies within thne regulated sector at present that what you did last week or last month - may not be judged good enough this month and next month - and worse still what you have done historically is judged to have been not fit for purpose. I think us small holders will have an impossible job ascertaining whether this is blip - update perhaps doesnt sound as bad as it could have done perhaps - or whether there is going to be onbgoing impact with regard to teh wonga they can make going forward. If its as bad as a combo of failing mlr stuff and also shafting their customers ref fees - well i suspect they easy money they may have been making may not be so easy to make going forwad. I know nothing about this company though so my comments are perhaps mostly genric here rather than with any specific company insight.
Its perhaps no surprise thats shareprice had been trending downwards from prior highs - as ever small shareholders last to know.
top marks yet again for the ability of the stocky alogorithims to downgrade the rankings in advance of the bad news - yet again top notch spidy senses at play here by the stocky algo.
To be honest if they charge high fees to customers should holders be surprised they are being hauled over the coals ? regulators have taken St James place to task for sketchy tactics - i have no idea if its possibly similar here but if it is holders should not be surprised (they can be annoyed) - the fca cant be much clearer with their messages "though must be holier than holy" - and when it comes to making quick buck by maximinisng what you charge customers who want to pay minimum in fees well its always potential to make it opaque how "you make your buck from client" if you are making uber fat margins that really eat into returns being made - do you want to lay that out in transparent fashion to your customers - obviously not.
SJP, Quilter and many others have had the FCA looking at their DD on how they do business. It all boils down to how the advisers are compensated. As the old saying goes. Show me the comp structure, and I will show you the behaviour,.
Interesting take : I worked in private client for 7 years in the 90s and was a decent Rathbones (LON:RAT) shareholder institutionally after : its not my experience that the FCA actually behaves how they are perceived, especially to a business like Rathbones (LON:RAT. They give a lot of advanced notice re enquiries before launching an investigation - which you really want to avoid. So somethings gone wrong here and most likely tied to the acquisition I guess..... but I need to try and learn more....as the current price reaction is extremely attractive IMO.
Rathbones (LON:RAT) are probably now a target with no share price gains for about a decade and a merger that has caused a few issues. They are a quality wealth manager. This is yet another example of the FCA over regulating a perfectly good UK business. We have 350 quangos in this country, all of which try their best to kill UK business through over regulation and box ticking. A tad different to the US!
Anyway, Rathbones will now have a couple of issues to work through. Its very different to Jarvis Securities (LON:JIM) which were too small to deal with the regulator. I wonder how many other wealth managers also charge fees on cash balances? Most I suspect. End result will likely be slightly lower interest charges on cash balances held.
Last call for AGAINST voters: Nanoco PLC (NANO).
Proxy Voting Deadline: Wednesday, 17 June 2026, at 10:30 a.m. BST (This is the final deadline to submit electronic proxy appointments or Forms of Proxy).
Folks I know I've made a few of these posts but this one might be the most important of all.
We really are looking at the final opportunity to vote now. HL have a voting deadline of later on today. Other brokers will be similar. Whether you have 10,000 shares or many more than that it all counts. Collectively we have real power here.
We know we are rapidly closing in on the GM day now. HL shareholders alone hold 21% of the shares here. Imagine the difference that makes to the outcome. We can easily defeat this. To vote with HL, just go to Investor Inbox or this link when logged in https://online.hl.co.uk/my-accounts/investor-mailbox If anyone isn't sure about how to vote with their own broker, please ask I'm sure somebody can help.
VOTE AGAINST TO STOP THIS HEIST AND KEEP THESE SHARES LISTED.
Nanoco PLC are trying to delist their company and take it private when it is more than 90% owned by retail shareholders. The market has voted about it by slashing its market cap to less than half its account balance. Nanoco PLC still has a cash balance of £10.1 million as at 19 May 2026. Hargreaves sent a note to its clients yesterday alerting them about this but they didn't tell them about the cash balance so some could have been frightened into selling. Please help us get the word out - if you have a following I would appreciate you tweeting this message.
IF YOU HAVE SHARES IN NANOCO YOU ONLY HAVE A FEW MORE DAYS TO VOTE. DON'T MISS THE DEADLINE. THE DELIST PROPOSAL ALONE HAS WIPED TWO THIRDS OFF THE MARKET CAP. IT'S ALREADY PROVEN TO BE ONE OF THE MOST CAPITAL DESTRUCTIVE THINGS THEY COULD HAVE DONE. It benefits no shareholder to hold an illiquid private instrument without accountability. For insiders on the other hand, the benefits are many. No interim accounts. Massive lag between reporting periods. Zero visibility on admin costs breakdown.
The board of directors barely hold any stock so retail shareholders can easily block this delisting. In a private company, with limited reporting requirements, nobody outside the company would have a clue what's really going on. It's funded for years on end. Countless ways they could cut costs without going nuclear like this. They could opt for an AIM listing for example which would slash listing costs.
Nanoco’s latest circular says there are 195,543,816 ordinary shares, each carrying one vote, as at 26 May 2026. The delisting/cancellation resolution needs not less than 75% of votes cast to pass. Abstentions/“vote withheld” are not counted in the for/against calculation.
Assuming 50% vote turnout
Total shares: 195,543,816
50% turnout: 97,771,908 votes cast
To pass, the board needs 75% of votes cast:
97,771,908 × 75% = 73,328,931 votes FOR
So the maximum “against” vote they can tolerate is 25%:
97,771,908 × 25% = 24,442,977 votes AGAINST
Therefore, to block the delisting, shareholders need at least:
24,442,978 shares voted AGAINST
That is effectively 12.5% of the entire company plus 1 share, assuming exactly 50% turnout.
Board 1.5% 2.93m
Nanoco Group PLC Employee Benefit Trust 6.7% 13.10m
Combined 8.2% 16.03m
If the board and Nanoco Group PLC Employee Benefit Trust votes are cast FOR, they would represent about 16.03m FOR votes. But that does not change the blocking number under the 50% turnout assumption - you still need 24.44m+ AGAINST because the 75% test is based on total votes cast.
At 50% turnout, around 24.45 million shares voting AGAINST should be enough to block Nanoco’s delisting.
Every “NO” vote matters because abstentions do not count.
Someone check the maths above - with 50% vote turnout we need 24.45 million shares voting AGAINST to block delisting.
THE BIGGEST ENEMY FOR US RETAIL IS PASSIVITY - INACTION - MAKE SURE TO VOTE AGAINST THE RESOLUTIONS SO THE COMPANY IS FORCED NOT TO DELIST. THEY CAN LIST ON AIM IF THEY WANT TO SAVE MONEY.
Inspiration Healthcare (LON:IHC) turnaround looks to be continuing and now focused on the high margin part of the business. Will be interesting to see how the market reacts. Your opinions would be welcome.
I second that request for IHC in which I have a small holding.
Greeting from Doha, Qatar. Thank you for all of your hard work. Looking forward to today’s analysis.
Greetings James! Good luck against Canada on Thursday!