The Week Ahead (15-19 June): SpaceX, UK & US rates + Tatton Asset Mgt, Castings, Oxford Metrics

Welcome back to The Week Ahead. Shortly after this article is published, shares in the world’s biggest IPO, SpaceX, will begin trading.
The flotation at $135 per share will raise $75bn. This will give the satellite, AI and rocket group a market cap of $1.78tn, reflecting the fact that less than 5% of its equity is being sold.
This IPO has attracted unprecedented interest from private investors who have reportedly been prioritised. They’re expected to receive 20% to 25% of the SpaceX shares being sold, an unusually high proportion for a major flotation.
Ed has covered this story in depth, reviewing SpaceX through the lens of the StockRanks. Perhaps predictably, he warns that based on the numbers “SpaceX looks like a textbook Momentum Trap”.
This doesn’t mean the shares won’t climb higher when trading starts, of course. Sentiment aside, there could be solid buying support from institutions and private investors whose orders didn’t get filled in the IPO.
More broadly, SpaceX is expected to be added to the Nasdaq 100 after just 15 days of trading. This could mean that index tracking funds will have no choice but to buy heavily in the coming weeks.
SpaceX is the (eagle-sized) canary in the coal mine for the next phase of the AI boom. But further mega IPOs for Anthropic and OpenAI are expected to follow. Meanwhile, Google-owner Alphabet (NSQ:GOOGL) is in the process of executing an $85bn equity raise, the largest in history.
It’s not yet clear if the market can absorb this tidal wave of new equity without triggering volatility elsewhere. The week ahead will provide our first taste of what may lie ahead. But I suspect it will be a little longer before investors start to focus on individual companies’ prospects and valuations, rather than the overall direction of travel.
Economic news
Oil prices have fallen below $90 for the first time since the start of the Middle East conflict. Trump is promising that a deal is close, but we’ve heard this before. I would not be surprised if continued uncertainty caused further flip-flopping for oil prices next week.
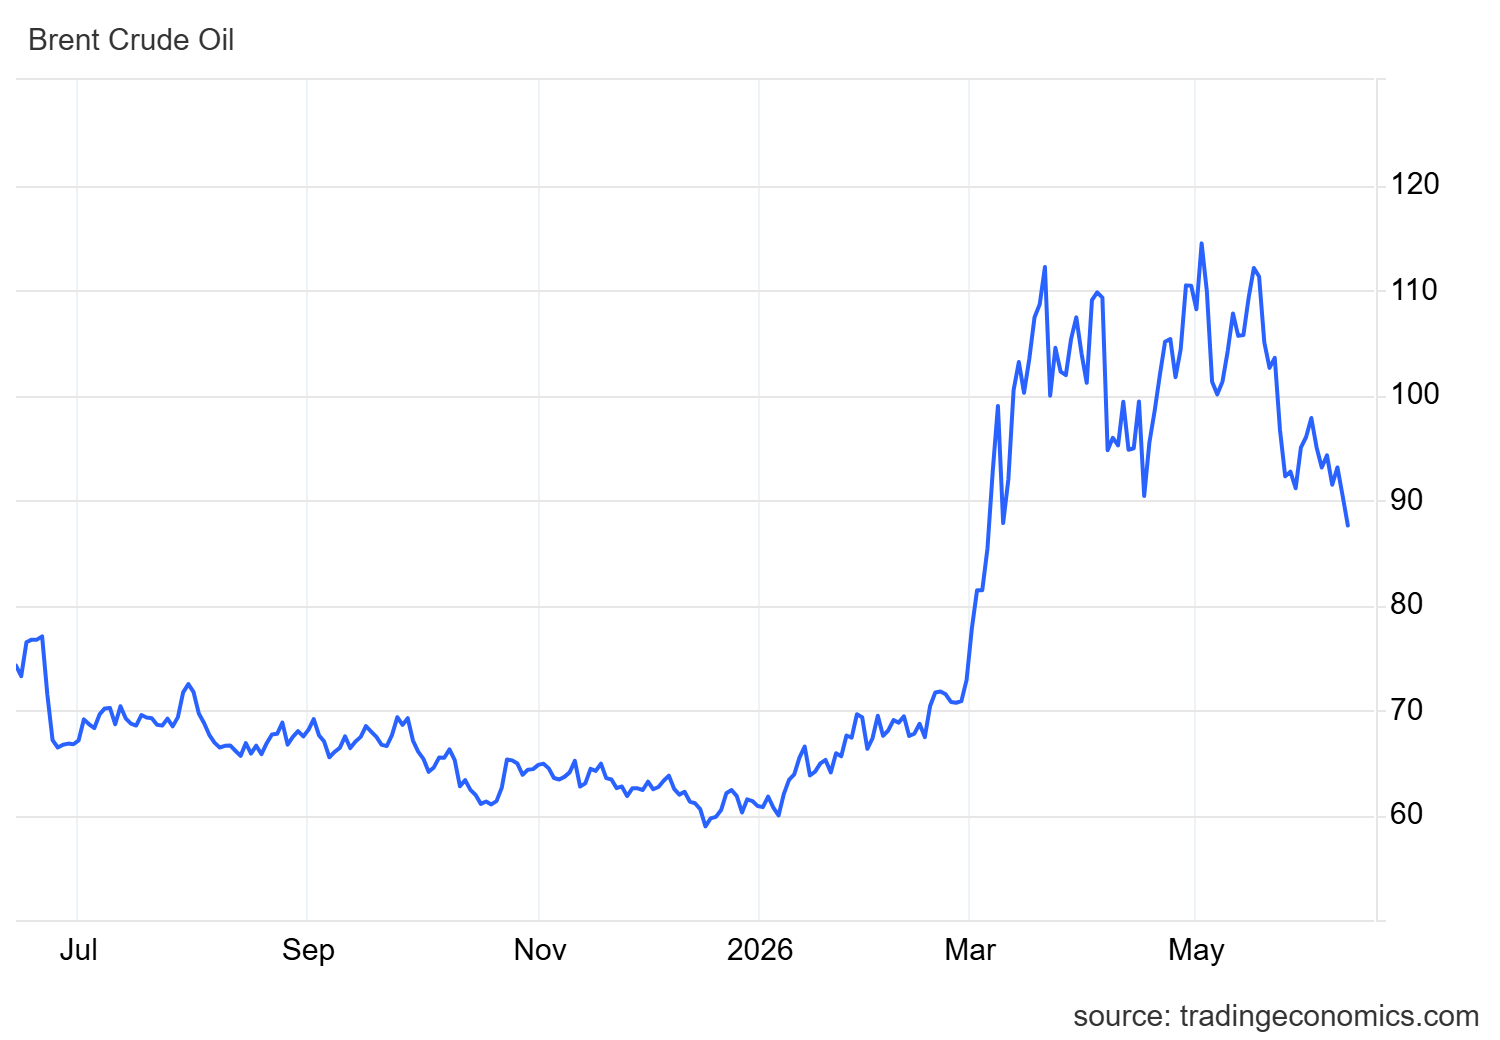
Fears are growing that crude inventories – particularly in the US – are falling towards critical lows. Oil inventory data due from API and the EIA next week could be worth watching.
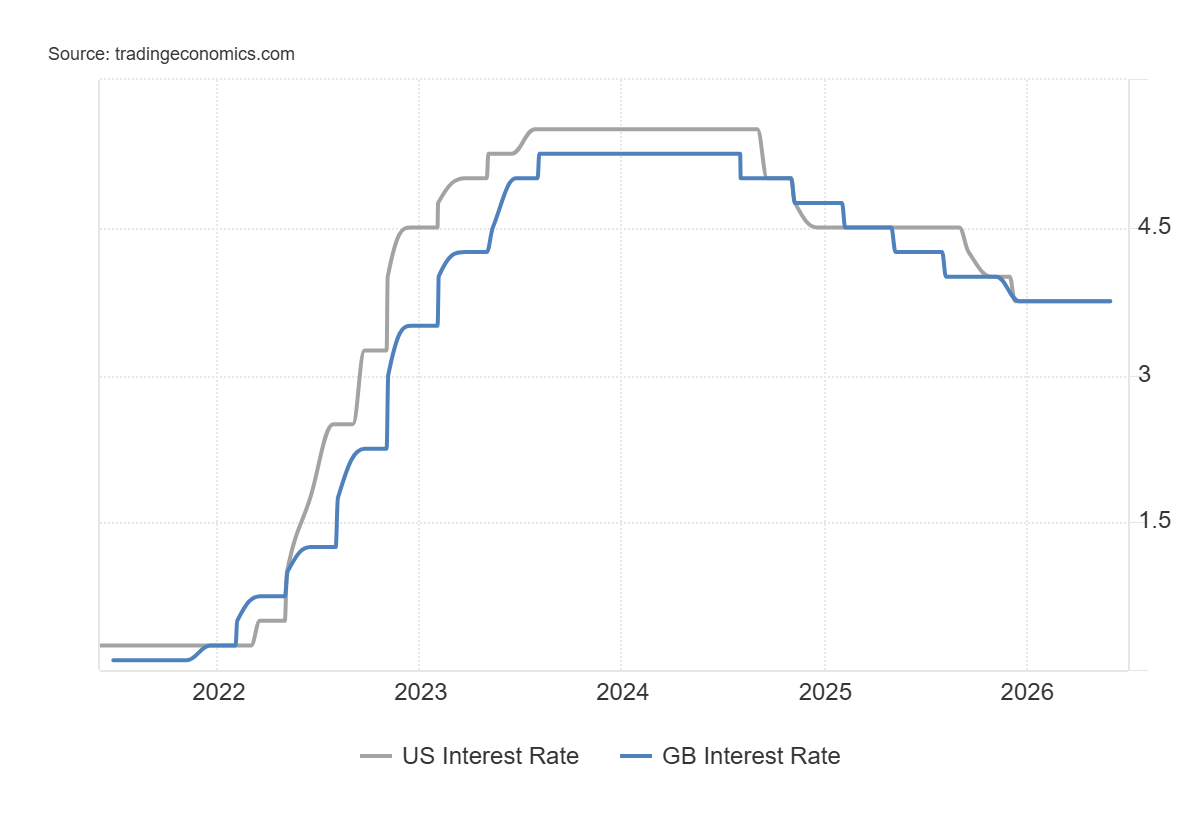
Interest rates could also make headlines. Both the US Federal Reserve and the Bank of England are due to announce interest rate decisions mid-week. While the European Central Bank raised its benchmark deposit rate to 2.25% this week, both the Fed and the BoE are expected to leave their headline rates on hold at 3.75%:
Company news
The UK earnings calendar remains thin next week. AGM season is in full swing and could prompt some interesting trading updates. But company results are likely to be limited to a handful of smaller firms.
Here is a selection of those that have caught my eye.
Castings (LON:CGS)
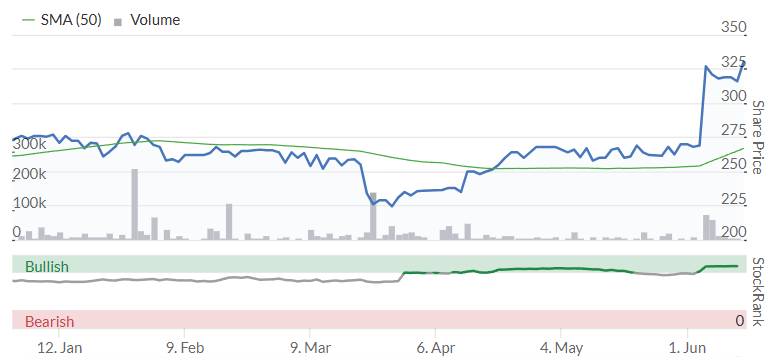
One company that could attract some interest is engineering group Castings, whose results are due on Wednesday. Castings’ share price recently spiked 20% higher on no news:
This foundry business specialises in parts for heavy trucks and has a reputation as a reliable high yield stock. However, profitability is average, at best. Recent results have come under pressure from high costs and subdued cyclical demand from truck makers.
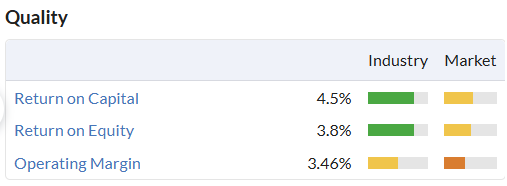
Forecasts suggest FY26 may have been a turning point:
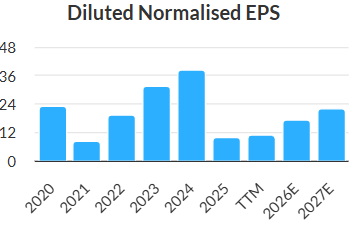
However, with the stock now trading on a mid-teens P/E, I suspect the market will need some reassurance to prevent a retracement.
Oxford Metrics (LON:OMG)
Tech group Oxford Metrics is still cash rich after having sold one half of its business a few years ago. The remaining business is motion capture specialist Vicon. This unit has seen profits come under pressure from cuts to US academic spending, but has been expanding into Smart Manufacturing with apparent success.
While earnings forecasts have been cut over the last year or so, Mark felt confident enough to upgrade our view to AMBER/GREEN when he covered last year’s results in December.
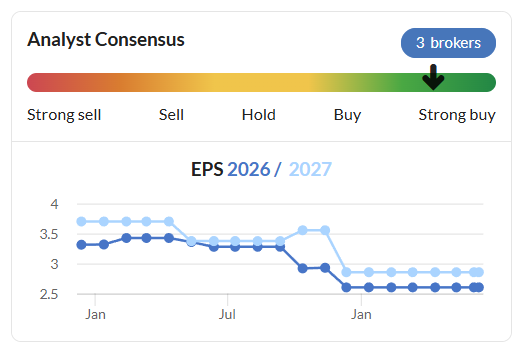
Oxford Metrics' 7% dividend yield isn’t backed by earnings, but it is well-supported by surplus cash. I’ll be interested to see if there are any signs of recovering profitability in next week's interim results. That could open the door to restoring dividend cover and a potential re-rating.
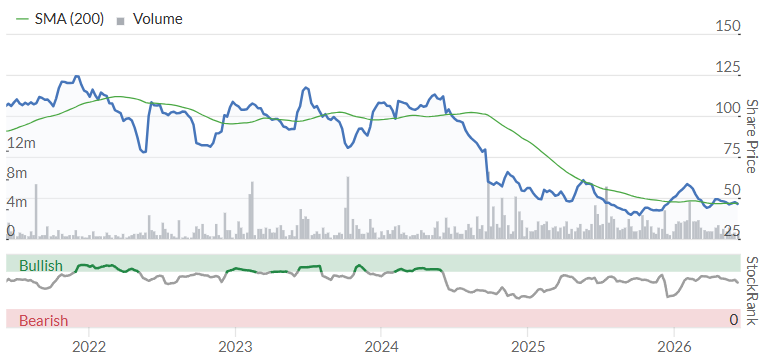
The stock continues to trade a long way below its historic highs:
Tatton Asset Management (LON:TAM)
One company I see as a likely indirect beneficiary of the US stock market boom is AIM-listed asset manager and IFA support services group Tatton Asset Management.
This founder-led business floated on AIM in 2017 and has been one of the more successful UK IPOs of the last decade. While traditional asset managers have struggled, Tatton’s on-platform discretionary approach (essentially built around model portfolios) has proved to be a winning proposition.
Assets under management (AUM) have risen from £4bn in 2017 to c.£23bn at the end of March 2026, while profits have risen 10-fold over the same period.
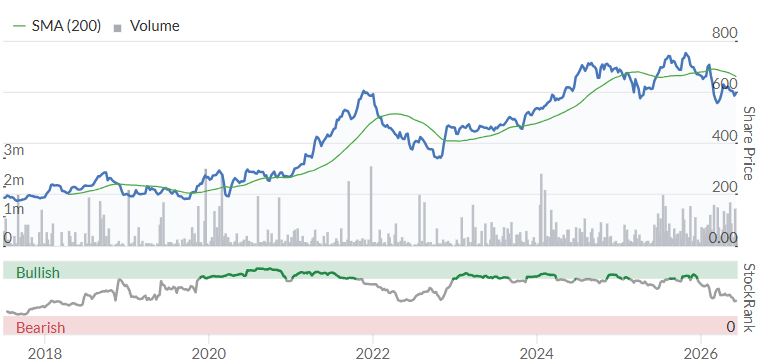
Tatton’s share price has tripled since its flotation and shareholders have also enjoyed an impressive stream of dividends:
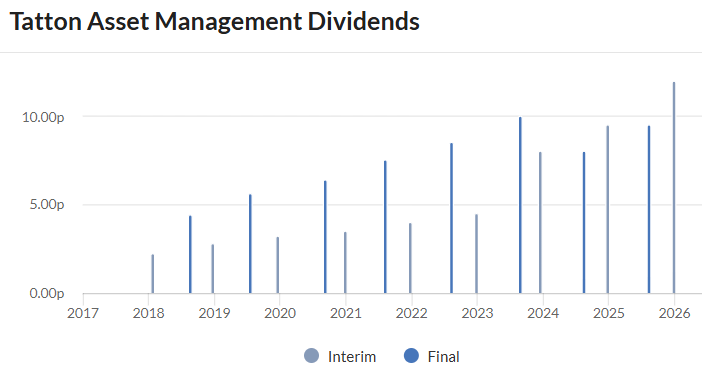
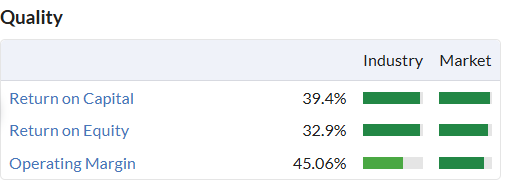
These payouts have been supported comfortably supported by the group’s super profitability and cash generation – net cash currently accounts for around 10% of the market cap:
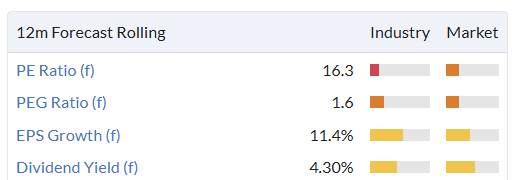
The valuation still looks fairly reasonable to me for a business of this quality and supports a near-4% dividend yield:
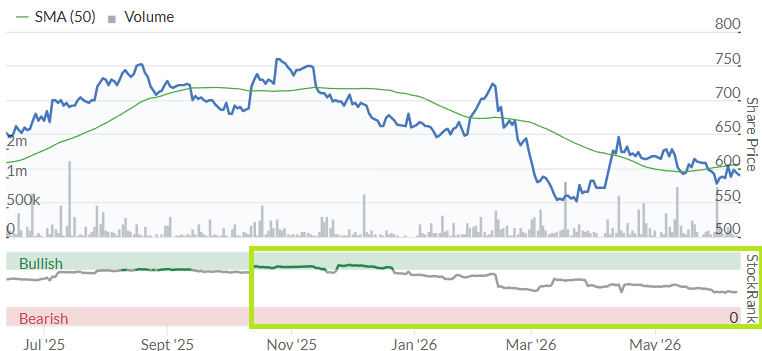
However, I can’t help noting that Tatton’s StockRank has fallen steadily over the last year, despite several earnings upgrades:
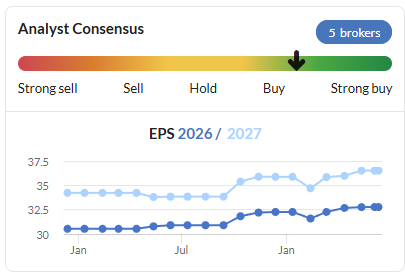
More broadly, I would speculate that part of Tatton’s rapid AUM growth has reflected the company’s low-cost ability to help its clients ride the coat tails of the US stock market boom. It might be interesting to know how much of the group’s AUM is ultimately invested in UK equities, and how much is in US index funds.
I suspect there’s little risk of this momentum slowing down just yet, but it might be something to keep an eye on.
Tatton is due to report its interim results on Tuesday.
Here's a summary of what’s expected next week.
Economic Calendar
Date / Time (BST) | Country | Event |
15 June | ||
10:00 | EU | Industrial Production |
14:15 | US | Industrial Production |
16 June | ||
00:01 | UK | Rightmove House Price Index |
03:00 | China | Retail Sales |
03:00 | China | Industrial Production |
04:00 | Japan | BoJ Interest Rate Decision |
10:00 | EU | ZEW Economic Sentiment Index |
13:15 | US | ADP Weekly Employment Change |
13:30 | US | Housing Starts |
21:30 | US | API Crude Oil Stock Change |
17 June | ||
07:00 | UK | Inflation |
07:00 | EU | Inflation |
13:30 | US | Retail Sales |
15:00 | US | Pending Home Sales |
15:30 | US | EIA Crude Oil inventories |
19:00 | US | Federal Reserve Interest Rate Decision |
18 June | ||
07:00 | UK | Unemployment Rate |
12:00 | UK | BoE Interest Rate Decision |
13:30 | US | Initial Jobless Claims |
18:00 | US | Baker Hughes Rig Count |
19 June | ||
US | Public Holiday | |
00:01 | UK | GfK Consumer Confidence |
07:00 | UK | Retail Sales |
Companies Reporting
Disclosure: Roland owned shares in Castings at the time of publication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Cordiant Digital Infrastructure (LON:CORD) finals due out on Friday. This one has had a very strong run recently and still has much further to go. Looking for a modest increase in dividend as well. I hold.
Outdated technology... Listen to this...podcast by the renowned Ross Coulthart. https://youtu.be/ueVqtCQEZ-E?is=Un7t3u6sM0AOoW10
Looked at Record (LON:REC) a number of times but never bought. Yield is appealing but the StockReport says not fully covered. Dynamic AUM must generate higher margins than Passive AUM but doesn't seem to meaningfully increase in size.
Pantheon Infrastructure NAV keeps increasing but not one of the higher yielding trusts in the sector.
Morning Roland, a few omissions insofar as my portfolio is concerned.
Prelims from Halfords (LON:HFD) and Volex (LON:VLX) on Thursday, plus a trading update from Avingtrans (LON:AVG) based on previous announcements.
Apologies Roland got my weeks wrong, running ahead of myself!