Daily Stock Market Report (Tue 18 Feb 2025) - AGR, SQZ, CGS, SLP, PLUS, BOWL, ELIX, TRT

Good morning! The Agenda is complete now.
12.30pm: all done for now, thank you.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BHP (LON:BHP) (£104.9bn) | Interim Results | HY25 rev -8% to $25.3bn, adj profit -23% to $5.1bn. $2.5bn interim dividend. | |
Anglo American (LON:AAL) (£33.1bn) | Sale of Nickel business | Anglo has agreed to sell its Brazil-based nickel operations for “up to $500m”. | |
Antofagasta (LON:ANTO) (£18.1bn) | Final Results | 2024 rev +5% to $6.6bn, PBT +5% to $2.1bn. 2025 guidance unchanged. | |
Intercontinental Hotels (LON:IHG) (£17.0bn) | Final Results | 2024 rev +6% to $4.9bn, adj op profit +10% to $1.1bn. RevPAR +3.0%. Confident outlook. | |
Plus500 (LON:PLUS) (£2.1bn) | Preliminary Results | Rev +6%, EBITDA +1% ($342m). $110m buyback & $90m in divis. “Extremely well positioned”. | GREEN (Graham) Investors are being asked to trust the strategy of spending big on customer acquisition, with the view that it will pay off in future periods. Additionally, 2025 looks like it could be a quieter financial year, with less trading activity. But the long-term picture is one of tremendous growth and expansion and that continues today most notably in the United States, UAE and Japan. More than 1/3 of the market cap is covered by cash and PLUS continues to buy back its own shares. |
Assura (LON:AGR) (£1.4bn) | Statement re. Possible offer from KKR | The board believes KKR’s offer “materially undervalued the company” and thus rejected it. | AMBER/GREEN (Graham) No change to my view expressed yesterday with the shares offering both a discount to NAV and an attractive yield. Deleveraging could help to boost investor confidence. |
Serica Energy (LON:SQZ) (£562m) | Update on Triton FPSO | Triton production suspended due to Storm Éowyn damage. FY guidance under review. | AMBER/GREEN (Roland - I hold) |
Hollywood Bowl (LON:BOWL) (£470m) | Share Buyback | £10m buyback, “to reduce the share capital of the company”. | AMBER/GREEN (Graham) [no section below] BOWL matches last year’s share buyback, despite very high capex spending which saw net cash fall to £29m as of Sep 2024 (Sep 2023: £52.5m). However, it chose not to propose a special dividend this year, saving about £5m. Interesting that it chose to cancel its special divi rather than its buyback. PER is 12x so it earns a yield of about 8% on buybacks here. |
Foresight Solar Fund (LON:FSFL) (£436m) | Corporate update | Mgt fees reduced, NED board refresh and shareholder discussions re. strategy. | |
Elixirr International (LON:ELIX) (£374m) | TU | FY24 results above market expectations. Revenue >£111m. Momentum continues into 2025. | AMBER/GREEN (Roland) |
Castings (LON:CGS) (£129m) | TU | Profit warning - substantially below expectations. Demand for heavy trucks fell further in Q3. | BLACK (PW) / AMBER/GREEN (Roland - I hold) |
| Sylvania Platinum (LON:SLP) (£120m) | Interim Results | Net profit +132% due to higher prod and PGM basket price. FY prod exp 75-78koz (prev 73-76k) | AMBER (Roland) [no section below] Sylvania has increased its FY production guidance, helped by improved mining grades. Profit growth was as expected and broker Panmure Liberum has left FY25 estimates largely unchanged. SLP remains debt free and at a discount to NAV, but is exposed to cyclical and country risks. Perhaps a recovery in PGM prices and automotive demand can drive a re-rating. |
Transense Technologies (LON:TRT) (£23m) | Interim Results | Trading remains in line (FY June 2025). Trading since period end is strong. Net cash £1.9m in January. | AMBER (Graham) [no section below] Shares down 10%+ despite "in line" trading. Revenue +36% to £2.5m, EBITDA unchanged (<£1m). I noted previously that TRT's sensor technology/measurement businesses were very early-stage, and thus difficult to value. Broker Cavendish says that 70% growth is required in H2 vs H1 to meet full-year forecasts. Those forecasts are unchanged but surely there is a high risk of an official profit warning at some point in H2. They are targeting £15m in sales and £5m of EBIT by 2030, which is when they will stop receiving royalty income under a deal with Bridgestone. Net cash improved to £1.9m in January, but there are plans for £2.5m of capex spending over the next 12-18 months. This business is just so small and early-stage. Very difficult to value and its margin for error seems slim given the size of the cash balance. |
Inspiration Healthcare (LON:IHC) (£12.1m) | Trading Update | FY rev £38.3m, return to +ve EBITDA. Results below exps due to delay, but improved momentum. |
Graham's Section
Assura (LON:AGR)
Unch. at 42.4p (£1.4bn) - Statement re Possible Offer from KKR - Graham - AMBER/GREEN
We have independent confirmation from Assura that they rejected the 48p cash proposal from KKR.
The Board confirms that it considered the Proposal carefully with its advisers and concluded that it materially undervalued the Company and its prospects and therefore rejected it unanimously. No further proposal from KKR has been received.
Graham’s view: many thanks to Ken Mitchell in the comments who pointed out that it’s not unusual for REITs to accept takeover offers below their net asset value.
Tritax Eurobox (EBOX) was an example: the Canadian investment company Brookfield bought EBOX in late 2024 at a 12% discount to its March 2024 NAV.
Each case is different, however, and the Board of Assura clearly thinks that their company is worth its last-published NAV or more - the offer from KKR is 48p, while Assura’s last-published NAV is 49.4p.
Some general factors that come to mind:
Date of measurement: the last-published NAV might be out of date. The Directors might have a sense of what the next-published NAV is going to be, e.g. if there have been acquisitions, disposals, or changed valuations.
Quality of portfolio: different industries (healthcare, retail, residential, etc.) and their changing outlooks over time might justify a premium or a discount to NAV, depending on the outlook for demand and for rent collection.
Investor sentiment: if a REIT’s shares have been trading at a large discount for a long time, and/or if most shareholders are happy to move on, then accepting a discounted takeover might be a lot more palatable.
Personally I’d always want to ensure that buyers paid full price for any REIT that I was involved with - especially when it comes to the most financially sophisticated buyers, such as KKR.
I do accept that there are circumstances when a discounted offer will be accepted. A REIT can be worth more or less than its NAV, and if it's worth less than NAV, then it might make sense to accept a discounted offer. But as things stand, Assura does not appear to be one of these cases.
Plus500 (LON:PLUS)
Down 5% to £27.14 (£2.01bn / $2.53bn) - Preliminary Results - Graham - GREEN
Plus500, a global multi-asset fintech group operating proprietary technology-based trading platforms, announces today its preliminary unaudited results for the year ended 31 December 2024.
The headlines for these results were already disclosed in a year-end trading update last month: revenue up 6% to $768m, and EBITDA up 1% to $342m.
The cash balance at the end of 2024 was $890m, slightly lower than where it finished 2023.
As we discussed in January, the question investors need to decide is whether they trust the strategy to spend big on customer acquisition.
As the CEO says in his first paragraph today:
We leveraged our proprietary marketing technology to significantly increase our customer acquisition by 30% year-on-year and by 46% in Q4 2024 versus Q3. Our commitment to continued strategic investment has established the foundations for growth in future years.
Customer churn at PLUS remains my main concern, as it has done for some time, despite my overall positive view on the shares.
The table below shows that the number of new customers recruited during FY 2024 (118k) was much higher than the number of new customers recruited during FY 2023 (91k). But the number of active customers increased by only 21k.
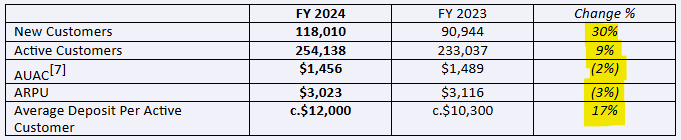
If my sums add up correctly, it seems to me that nearly 100k customers must have become inactive in 2024, in order for the above table to make sense. That’s about 43% of the active customers in 2023 who became inactive in 2024.
With the average life of a customer being so short, PLUS has to constantly pump its marketing machine in order to keep new ones coming in the front door.
It has consistently demonstrated an ability to do this, so I’m not changing my positive stance. I’m just highlighting an important feature of the company.
Despite the rapid churning of many customers, PLUS notes that 67% of its OTC (over-the-counter) revenue is generated by customers who have been trading with the Group for more than three years.
This percentage has increased over time and it is undoubtedly a positive. Note that trading platforms are like casinos in the sense that a small number of high rollers tend to generate the large majority of revenues. So my interpretation of the 67% number is that PLUS’ high rollers are becoming more mature customers of the company. Which is not a bad thing.
The table also shows small declines in both user acquisition cost and in average revenue per user - I guess it makes sense that these might rise and fall together, reflecting industry trends.
Finally, the 17% increase in the size of the average deposit shows that PLUS is, on average, finding larger customers than it did previously. Another positive sign.
Outlook: they are “confident about the Group’s future prospects and strategic direction…”
Profits and shareholder returns
EPS rose 13% to $3.57 despite net income being virtually unchanged. The share count continues to fall, thanks to the company’s propensity to buy back its shares, boosting EPS.
On that point, today the company has announced a new $110m buyback, to begin when the existing $110m buyback completes. There will also be $90m of dividend payments.
Estimates: thanks to Panmure for covering PLUS. Their forecasts for FY25 are unchanged with a revenue forecast of $704m (below consensus $727m) and EBITDA of $343m (above consensus $336m). Lighter revenues are based on an expectation of calmer markets, but the “very lean, flexible cost base” should allow EBITDA to remain firm.
Graham’s view
The market is a little disappointed this morning, which I guess might have something to do with the dawning realisation and acceptance that 2025 could be a relatively quiet year for PLUS in terms of growth.
However, nothing has really changed. The company continues to expand both geographically and in terms of its licenses. It's increasingly active in the US with a thriving futures business and a B2B business for introducing brokers. It has a new licence in the UAE and a new localised trading platform in Japan.
Quantitatively, it’s almost impossible to argue against:
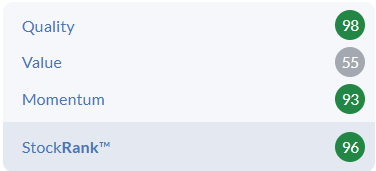
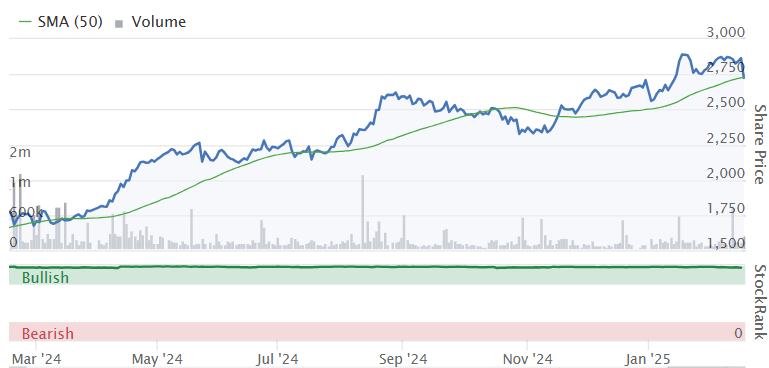
So I have no alternative but to maintain my positive stance. This trades on a PER of less than 10x and that’s before allowing for the cash balance which covers more than a third of the market cap. As the share count continues to reduce, and the company continues along its path of long-term growth, I can only assume that the path of least resistance is higher.
Roland's Section
Serica Energy (LON:SQZ)
Down 11% to 127p (£501m) - Update on Triton FPSO - Roland (I hold) - AMBER/GREEN
At the time of publication, Roland has a long position in SQZ.
We have more bad news from North Sea oil and gas producer Serica today, relating to the ageing Triton FPSO (Floating Production Storage & Offloading) vessel.
Serica Energy plc (AIM: SQZ) announces that, as a result of issues resulting from Storm Éowyn, production from the Triton FPSO has been suspended.
Safety critical fault: the company says that sea spray during Storm Éowyn triggered Triton’s fire and gas detection system, causing an automatic shutdown.
After an initially successful restart, storm damage was noticed to one of the cargo tanks. While preparing to repair the tank, operator Dana Petroleum discovered a further, safety-critical issue:
While preparing to conduct the necessary repairs, Dana Petroleum ('Dana') identified an integrity issue with a coupling in the inert gas line required for purging the tanks prior to carrying out the repairs. Triton has remained offline subsequently pending identification of the root cause of the issue and the best means of resolving it.
Triton is operated by Dana Petroleum but Serica says it is supporting Dana, including with the secondment of a member of staff. The implication of this would seem to be that the problem is not straightforward to fix (or that Serica has limited confidence in Dana’s technical team).
Expected restart date: Serica currently expects production to resume “in mid-to-late March”. Summer maintenance plans – currently scheduled for 40 days – are also under review. My reading of this is that this maintenance period may need to be extended.
Impact on FY production: Serica’s 2025 production guidance has been placed under review and will be restarted or revised when the timeline for repair of Triton is clarified.
When compared to previous guidance, the numbers provided by the company today and the extent of the shutdown suggest to me that a downgrade to guidance is likely, if not inevitable:
7 Jan 25: production net to Serica running at 46,400 boepd
21 Jan 25: FY25 production guidance for “around 40,000 boepd”, reflecting planned maintenance
18 Feb 25: January 2025: averaged 37,000 boepd, February 2025: “averaging 27kboepd to date”
I’m not able to model the timing and impact of new production expected to come onstream this year. But my rough estimates suggest that production could be much closer to last year’s level of 34.6kboepd than previously expected.
Estimates: how much financial impact will any production shortfall have on current forecasts? This is not easy to model as it’s dependent on commodity prices through the year. But gas prices have been strong so far this year:
This has included strong production from the Bruce Hub into a robust gas market, with February NBP prices averaging 134p/therm, as well as solid contributions from our other assets.
Auctus Advisors have published a note on Research Tree this morning - many thanks. They suggest that the financial impact of an extra Triton outage is not as great as it might have been, as gas prices have been above their modelled level so far this year.
Auctus estimates that the dividend might still be supportable, assuming gas prices remain favourable.
Triton FPSO life extension: Serica also uses today’s update to inform us that the company has recently received a draft of a third-party study into the work required to extend the life of the Triton FPSO. This is necessary as production through the FPSO is expected to continue potentially to 2040.
The report has confirmed that, subject to the continuation of the programme of maintenance and upgrades, the FPSO has the potential to continue producing well into the next decade.
Internet research suggests that construction started on Triton in 1997, with production starting in 2000. So by 2040, it will have spent more than 40 years floating in the North Sea. I suspect maintenance requirements may remain fairly high.
Roland’s view
Serica CEO Chris Cox sounds a little frustrated by today’s news. I think his comments are worth reproducing in full:
"Given that the Triton FPSO was recovering strongly from the operational issues of 2024, with material production from new wells, the impact of Storm Éowyn is deeply frustrating. Safety is of course always the number one priority, and we fully support the operator's actions in ensuring that this supersedes other considerations.
Recent drilling results illustrate the significant value of proven hydrocarbons in the Triton area. We will continue working with the operator and discussing with them at the highest level all options to secure a lasting improvement in the operating performance of the FPSO."
Serica has featured several times in the report recently. Both Mark and I have covered the stock, taking an AMBER/GREEN view due to the apparent value on offer and high expected free cash flow.
However, I’ve also mentioned my growing concerns about the age of Serica’s assets and the risk they may be more prone to reliability issues.
Today’s update makes me think I may have underestimated this risk, especially in relation to the Triton hub, which is not operated by Serica.
I’m tempted to downgrade to AMBER today, but I’m going to maintain my view at AMBER/GREEN as I think Serica does remain both cheap and cash generative.
Castings (LON:CGS)
Down 14% to 246p (£110m) - Trading Statement - Roland (I hold) - BLACK (AMBER/GREEN)
At the time of publication, Roland has a long position in CGS.
Castings’ RNS style is clean and concise. Unfortunately this clear style of communication has been used by this morning to report a significant profit warning:
it is the board's expectation that the company's result will be substantially below market expectations in the current year.
Around 75% of Castings’ revenue comes from supplying parts to European heavy truck manufacturers. The company has previously reported a slowdown in demand after a busy period, but says that volumes dropped further than expected during the company’s third quarter (Oct-Dec 24).
As a result, the underlying profitability of the foundry and machining businesses has fallen below expectations.
The slowdown in demand was such that Castings has actually had to pay penalties to its electricity supplier for not using enough of its contracted supply.
However, it’s not all bad news. Demand appears to be starting to recover:
Our major customers have recently reported increasing sales orders which are expected to positively impact Castings sales volumes early in the next financial year.
Estimates: with thanks to both Zeus and Canaccord Genuity we have updated estimates this morning. The company’s comments on FY26 initially suggested to me that existing forecasts for the next financial year might be unchanged, but both brokers have trimmed their estimates.
Zeus has cut its FY25 earnings estimate by 45% to 9.4p per share. FY26 forecasts have been cut by 20.2% to 17.2p per share.
Canaccord has a slightly more positive stance, cutting FY25E by 40% to 10.3p per share and FY26E by 17% to 17.3p per share.
Both brokers expect the ordinary dividend to be held at c.18.4p this year, supported by an expected year-end net cash position of £10m+. After this morning’s fall, that gives Castings a possible 7.3% dividend yield.
Roland’s view
Graham covered Castings’ interim results (and a previous profit warning) in November, taking a neutral view.
The key attractions for me are the company’s market leadership in its niche and strong balance sheet. Offsetting this are the cyclical risks (as we’re seeing) and the capital intensity of this business, which limits profitability.
Arguably, growth potential in the company’s core truck market is also limited, although management is trying to expand into areas such as renewables to access new growth opportunities.
Both brokers seem confident that Castings’ will maintain its longstanding net cash position and be able to sustain the ordinary dividend, which hasn’t been cut for more than 30 years:
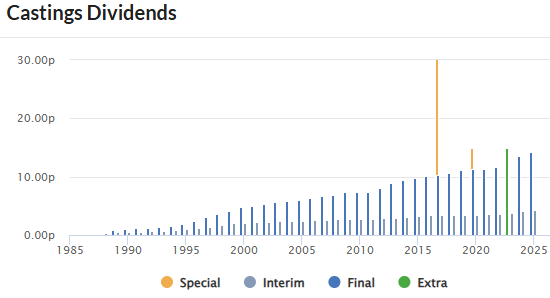
Based on the last-reported book value of 294p per share, Casting shares may now be trading below book value. Although historic return on equity has only averaged just over 8% in recent years, I think the opportunity to invest below NAV and gain a 7%+ dividend yield suggests the stock may now offer attractive value.
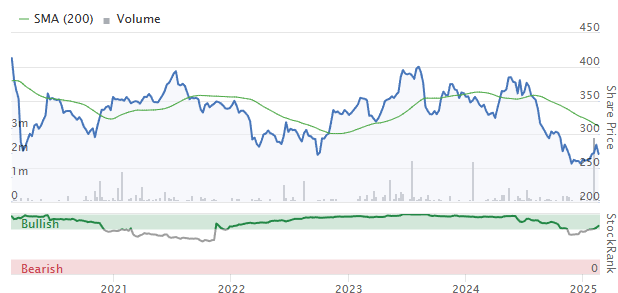
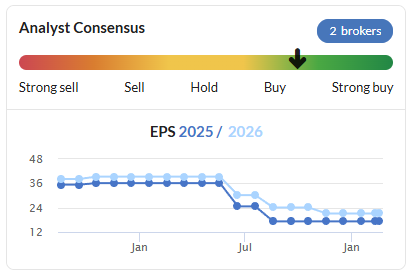
I also wonder if today’s profit warning will be the last of this cycle. Stockopedia’s consensus trend chart suggests this is the third material downgrade in the last year:
As a value proposition, this won’t appeal to everyone.
However, given the continued strength of Castings’ balance sheet and the seemingly improving outlook, I think a more positive stance makes sense.
As a shareholder, I’m more inclined to buy more than sell following today’s announcement. AMBER/GREEN.
Elixirr International (LON:ELIX)
Up 6% to 819p (£395m) - Trading Update - Roland - AMBER/GREEN
The Board of Elixirr International plc (AIM: ELIX) ("Elixirr", the "Company") the established, global, award-winning, challenger consultancy, is pleased to provide an update on trading.
I’ve not looked at this consultancy business before and we haven’t covered it here since 2023, so I thought it might be useful to put a marker in our coverage ahead of April’s full-year results.
Today’s update from Elixirr is ahead of expectations, albeit only slightly:
Subject to audit, FY 24 results are expected to be above market expectations with:
The company is now guiding for revenue “greater than £111m”, versus a guidance range of £108-£111m. This represents an increase of 29% on the 2023 figure of £85.9m.
Adjusted EBITDA is expected to be “approximately £31 million”, versus a previous estimate from broker Cavendish of £30.4m. EBITDA margins are in line with expectations at 28% (guidance “27-29%”).
The company expects to end the year with net cash of £7.5m, having fully repaid debt drawn to fund the initial cash consideration of $28.9m for the acquisition of Hypothesis Group in October 2024. From what I can see, up to $7.6m in further consideration will be due in FY25 and FY26.
Trading commentary: Elixirr has not provided any detail on 2024 trading in today’s results, except to comment that the year ended “strongly”.
2025 trading to date is said to have been strong, with “record revenue for January”.
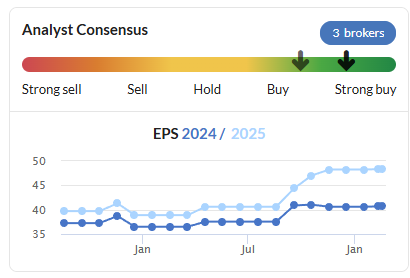
Estimates: broker Cavendish has increased its FY24 adjusted EPS estimate from 40.8p to 41.4p (an increase of 1.5%.
There’s no change to FY25 estimates at this point, but these have previously been upgraded to increase the rate of expected growth versus 2024:
Roland’s view
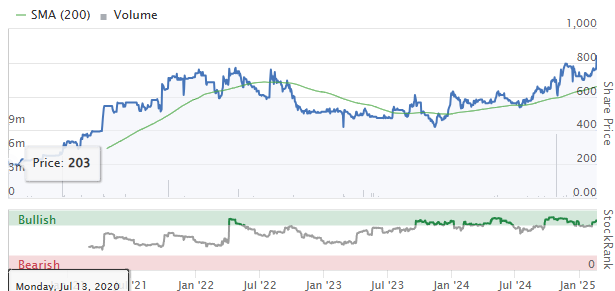
Elixirr floated on AIM in July 2020 and has four bagged since then. The stock has hit a new record high this morning:
As I commented yesterday in relation to FRP, professional services businesses such as this can be vulnerable to external conditions and the risk that key people will leave.
I’m always slightly sceptical about companies with misspelt names, but Elixirr certainly has lived up to its name so far.
Profitability and cash generation have been consistently strong since listing, supporting excellent quality metrics.
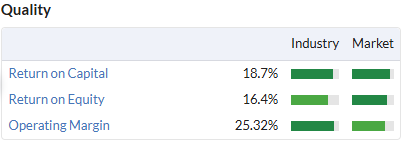
Revenue has grown at a compound average rate of 38% since 2018, while operating profit has grown at a CAGR of 30.9% over the same period.
Cavendish describes Elixirr as a possible ‘rule of 40’ stock in today’s note. This appears to be a term for (mainly) software companies targeting a combination of annual revenue growth and EBITDA margin in excess of 40% each year (Bain & Co have a useful introduction to this topic here).
I can certainly see the logic of this kind of metric - if a company has sufficient underlying quality, slowing revenue growth should be offset by higher margins, supporting continued high returns.
Stockopedia classes this stock as a High Flyer with strong quality and momentum. The StockRanks reflect this:
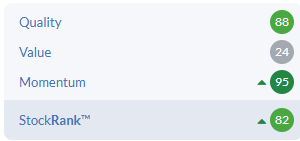
After today’s gains, I estimate Elixirr is trading on a FY24E P/E of 20, falling to a forecast P/E of 17 for FY25.
A certain amount of growth is baked into the valuation here. But if momentum can be maintained, I think Elixirr shares could have further upside on a medium-term view. AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
On Assura (LON:AGR) I supect that the DCF valuation may exceed the EPRA valuation. Some medical property REITS used to disclose a DCF valuation as well which historically supported a premium to NAV. They don't seem to disclose it anymore. MedicX Fund which was rolled into Assura always used to disclose this and it was materially higher. Higher discount rates will have reduced the valuation, but it may still be above the NAV disclosed. That may explain the material difference the board are mentioning.
SQZ. Check Directors’ dealings between February and September 2024. They filled their boots at a SP mostly higher than today’s. It strongly suggests that they thought that there is money to be made. Of course, they could not anticipate FPSO problems. I bought SQZ simply for the divi, thinking that I couldn’t lose much, given the low SP. From now on, I will check directors’ dealings daily. If one of them sells so much as a single share, I’m sold. Till then, I’ll hang on.
Thanks Graham for the further Assura (LON:AGR) update and for referencing my reply to your analysis yesterday. I hold several REITs but hadn’t previously looked at Assura (LON:AGR) . Wish I had now as there was a 15 year multi year low buy opportunity at just 35p recently, so bearing in mind the discount then, no wonder a potential bidder pounced.
Also they have high quality assets, so much so that a bidder was (unlike with EBOX ) prepared to pay near to the full NAV. But the share price is now well below 48p suggesting that there won’t be a higher bid.
Assura (LON:AGR) LTV is high at 49%, but asset disposals are bringing that down. The recent trading update and previous Results were overall bullish……again explaining why KKR bid.
Other REITS could well be bid targets. The problem is guessing which ones. Good quality REITS on big discounts could be the likeliest targets and if the bid is anywhere near NAV give the most upside for holders.
I saw on Monday that Paul Scott is a sudden convert to the REIT attractions and holds 5, with his choices influenced by shrewd Investor Wasim Shakoor. One of his choices is Social Housing REIT (LON:SOHO) which is on a huge 52% discount and 9.1% dividend and LTV looks fine at 37%. I hadn’t looked as for vague reason put off because they invest in social housing, but that discount and yield makes it well worth checking out. Social Housing REIT (LON:SOHO) has bounced to 59p from recent 55p low.
Of the several I hold Supermarket Income REIT (LON:SUPR) with J Sainsbury (LON:SBRY) and Tesco (LON:TSCO) accounting for over 50% of their tenants and the other major supermarkets being their other renters means almost certain 100% rent payments along with annual rent increases and, obviously it doesn’t get much higher quality tenant wise than those! Supermarket Income REIT (LON:SUPR) at 72p has just bounced from recent 66p all time low. Discount is 22% despite that high tenant quality, and dividend 8.6%. And LTV is fine at 37%.
Warehouse Reit (LON:WHR) which I bought at 76p all time low recently (and covered on the Investment Trust thread here then) is still at a bargain 82p price. Discount is 35% and dividend 7.6%. LTV is 34%. Warehouses are in demand ….and that 35% discount looks way over the top. Top bid candidate?
I also,hold Schroder European Real Estate Investment Trust (LON:SERE) now 67p and up from recent 60p low. Discount is too wide at 35% and dividend 7.5%. LTV is low at 25%. It’s in the same Commercial Property Europe sector as EBOX which I held and at one point the discount went to around 50% before the bid.
The Commercial Property Sector looks over the worst with several reporting small NAV increases after a while of lower NAV updates. As the Assura (LON:AGR) news this week hints at too, it’s a sector well worth checking out while discounts are still wide.
Thanks for this Ken - Is it worth trying to get some of the tax on divis refunded - when held in a SIPP or ISA - or is it just not worth the effort. Ditto Irish shares...?
Do you mean outside of a SIPP or ISA? There is no tax on dividends when held in these
It's more complicated with REITS and Irish stocks as some tax is automatically taken at source. Look it up...
bohenie.
JSchoffer is right. Dividends in our ISA’s are all tax free and our investments in ISA’s are free of capital gains tax as well. Obviously that includes REITS. I’m wondering why you thought they were taxed?
Hi Ken, my SUPR divis are subject to tax at 20% initially inside my ISA, which is then reclaimed by my broker and credited 60 ish days later. Bit of a faff but could explain the perception of tax being deducted.
Any idea why the tax treatment is different to other shares?
I'm not sure why, but something to do with REITS - the blurb on the broker factsheet states 'Property income distributions (PIDs) are subject to 20% withholding tax. PIDs paid in to ISAs are tax exempt. The withholding tax will be reclaimed and distributed to ISA holders approx 30-60 days after the PID is paid'
Tim.
I’ve checked all our REIT dividends in our ISAs with H/L and ii this morning and every one was paid in full on dividend pay day as imo they should be. Until the posts here yesterday I had never heard of Commercial Property REIT dividends being treated differently to all other dividends in our ISAs.
£SUPR. See link below - scroll down to the bottom of page to read the blurb. Similar situation applies to Irish companies (i.e. all Irish not just reits)
https://supermarketincomereit....
I have REITs with AJB and HL in SIPPs and I've also never had any tax withheld from PIDs. Maybe the large online platforms just take the hit for the 30-60 days until they can reclaim it because it's cheaper than fielding messages from disgruntled clients?
News just in from Beeks Financial Cloud (LON:BKS). And good news too (strange that it's released at this time of the day), but another exchange contract won with Grupo Bolsa Mexicana.
We await tomorrow's share price action in anticipation... I hold
Regards,
Jon
I can't see how to edit, but in fact the market is still open for around an hour. Getting my time zones mixed up...
There was no value assigned the announcement, just a comment it reinforces the 2025 outlook and revenue recognition will be in 2025. So perhaps there won't be any big moves. Currently around 3% down for the day...
Beeks Financial Cloud (LON:BKS) it is up 6.6% at the moment.
Now 8.3%.
Yep, it's a happy evening!
Possibly timed with an announcement at the exchange in Mexico? No value given as product isn’t sold but will be made available to customers.
Reading between the lines, CEO comment seemingly bullish on the prospect of other contracts.
(I hold).
Thank you for your comments on Castings Roland, reading their TU was a poor start to the day for us too as long term holders. We'll add when the share price settles in anticipation of dividends being paid. I note Mark's observation on that, but I expect them to maintain their payments reliabilty.
Plus500 (LON:PLUS) Constantly amazed that they manage to recruit 100,000 customers each year, which they then lose the following year.
Are there really that many mugs around that will happily sign up to losing their money?
Plus500 (LON:PLUS) graham says
"The market is a little disappointed this morning, which I guess might have something to do with the dawning realisation and acceptance that 2025 could be a relatively quiet year for PLUS in terms of growth."
I had understood, perhaps wrongly, that market volatility had a big impact on the company. Indeed, Zruia said at the end of todays presentation that 2024 had suffered from a low VIX. With the state of the world's economy, trading, and AI competition, I am expecting things to be dramatically volatile this year.
What are your thoughts, Graham?
acdoug, we may see volatility this year, nobody knows! In 2024 there were some events that nudged VIX higher, to a lesser extent the US election and to a greater extent the short-lived panic in early August.
Compared to many other years it was a quiet one, but so far there has been nothing to spike volatility in 2025 and there are no known events - e.g. elections or other scheduled political events - that could be predicted to increase it. So the analysts covering PLUS are talking about 2025 being a year of calmer markets. Maybe this is a good thing? If volatility does pick up, it might be quite easy for PLUS to beat these forecasts. G
Thanks Graham
The market in UK small caps appears completely dislocated at the present, says he in exasperation. I am more or less holding my own being down a little over 1% since the start of the year and using dividends to add to the odd holding.
On which note I couldn't resist adding a few more Premier Miton (LON:PMI) at a little under 51p. Unless the wheels have come off since last months trading update the shares look, like many small caps, bonkers cheap. The company is paying a covered dividend, currently in excess of 11% and has over £30m cash on he balance sheet, which is more than 30% of market cap. The forward PE is 8.25% giving an earnings yield of around 12%. According to Mark's review of last month's trading update, UK equities account for around 17% of AUM, although in fairness I have yet to confirm this myself. Is this the low for the shares, who knows?
At this price the fund environment only needs to be better than dire for the shares to recover. If tough times continue surely industry consolidation will happen, either from other listed companies or an overseas buyer. You can buy a readymade retail platform with £10bn AUM for £50m. Seems completely the wrong price.
A good update from Elixirr International (LON:ELIX) today shows strong growth momentum in both revenue and profits. ... and a ROCE comfortably above 15 indicates a successful bolt on M&A strategy.
However, as a relatively new ‘challenger’ consultancy, it’s the ‘deal making’ senior employees as opposed to the ‘brand name above the door' driving growth. These talented folks require regular feeding with high salaries and share options diluting shareholder upside…. a slug of Revenue growth doesn’t flow to PAT growth and a slug of PAT growth doesn’t flow through to EPS growth.
Shareholders are missing out on operating leverage. Why pay 19x for the cheap seats?
Forecasts
FY24
FY25
FY26
Revenue
27.5%
27.0%
9.48%
Profit after tax growth
16.4%
21.5%
11.1%
EPS growth
9.36%
18.8%
9.65%
I’ve held Castings (LON:CGS) before, attracted by its valuation, superb financial management and a juicy dividend. However it’s a bet on how soon you believe its products will become obsolete as the transition to EVs continues. Interestingly it has been said that shift towards electrically powered vehicles will happen more slowly in the truck market than for cars which could aid the firm in the short term.
Sold my Serica shares last week because Russian gas could flood Europe
Do you think its realistic that EU would start buying Russian gas again in the near future? I would have thought that would be an extremely long term outcome.
Aren't all the pipelines now busted and slow, expensive and hard to reopen?
Countries have secured other gas supplies now and I would have thought Russia would have to make pretty extreme compromises to get let back in to the EU economy in that kind of way - hard to imagine they would agree to the sort of demands that would no doubt be demanded by the EU
I would have thought all of the risk here is medium/long term risk - still, Serica very good value even considering such things.
Russia is the 2nd largest supplier of gas to Europe. But instead of Europe buying cheap piped gas, it now pays 4x the price for Russian LNG. It will probably take a changing of the guard in the EU for them to swallow their pride and allow the pipelines to be switched back on. But you never know, sense might prevail.
One of the Nordstream pipelines is still intact, as are the overland pipelines, however Ukraine has refused to allow the transit of the gas to fellow Eastern European countries via those pipelines.
So apart from political will, it's entirely possible to get most of the pipelines working again fairly quickly.
And you're right, Russia won't be compromising with the EU anytime soon.
Re - EU Buying Russian gas again? and associated look across to gas prices
I'm no gas production engineering expert, but I don't believe you can quickly turn on supply by opening an export pipeline - How much Western supplied proprietary oil and gas field equipment has been sanctioned since Russia invaded Ukraine and how easy it is to get that supply re instated and installed quickly
Being a realist I wonder if re supplying that equipment and service by Western companies is part of the mindset behind the US "Push" for a free market solution to the conflict and "Drill Baby Drill"
Its not just the E&P gas and oil producers in the mix here but surely also the likes of Halliburton Co (NYQ:HAL) and Baker Hughes Co (NSQ:BKR) who presumably would like to return to trading in Russia? https://fortune.com/europe/202...
I believe the position of the various parties regarding the pipelines is :
Russia is very keen to export hydrocarbons without sanctions as part of any peace deal
Ukraine would also profit from reopening their pipeline ,would be happy to reopen but not a deal breaker.
Europe is very divided on whether they should accept Russian gas again with some arguing the economic case is indisputable and others arguing it makes us hostage to Russia again/enviromental considerations
Trump is pushing to keep the pipelines closed as they are doing very well out of exporting expensive LNG to Europe, and reopening the pipelines certainly wouldn't help the trade deficit Trump is so keen to eradicate
On 24 March 2020 Stockopedia published an article entitled "Shares that as are as cheap as they`ve ever been" I took a copy to look at in 5 years time. I set out below seven examples in order of growth from 64 companies listed. I failed to copy page 5 of the list.
IHG 2754p now 10,435p plus 7681p 279%
IMI 681p now 1929p plus 1248p i83%
HMSO 103p now 290p plus 187p 181%
DLAR 50p now 118.5p plus 68.5p 137%
AV. 232p now 508p plus 276p 119%
This is not representative as obviously some stocks have fallen and a number have been taken over. However the above examples are interesting particularly IHG which has reported today.
Nice! Thanks for posting.
Some interesting stuff. I had considered IMI attractive (even now), as it has good returns on capital and is reasonably priced.
DLAR: a good example of how the sun even shines on a dog's arse sometimes. Despite not paying a dividend in the last few years and sinking into net loss, the shares have done really well. There's another smaller company in a similar line of business (can't remember its name) that's doing great guns.
AV: Who'd have thought you could double your money out of that one? I can't find the reference, but I remember Ben Hodson (??) wrote an article on Cornerstone Value years back. I followed the result. I estimated that if you had bought that portfolio and held for 10 years - yes 10 years - you would have earned a total return of about 10% pa. AV was one of the holdings. That chunky dividend from AV sure did help.
I am leery of trusting AV. I held their preference share until, in March 2018, they announced, out of the blue,
“For 2018, we have outlined our intent to repay approximately £900 million of expensive hybrid debt”
We have the ability to cancel preference shares at par value7 through a reduction of capital, subject to shareholder vote and court approval. The preference shares carry high coupons that are not tax-deductible and they will not count as regulatory capital from 2026."
Preference shares had been trading at a significant premium until then, and I, and a lot of institutional and retail investors sold out for whatever they could get. In the face of "strong feedback and criticism" Aviva did a U-turn, and the shares surged 23%, but those who had acted quickly on Aviva's statement, were not allowed to recover their loss.
The ordinary shares fell 20% in the next 2 years, then plummeted a further 30% when covid started, and have since recovered to their 2018 price. Well done to anyone who benefitted from that, and the dividends of course.
As far as I can see, all the directors in 2018 have lost their jobs.
I hope that investors will be able to trust the new Board; they do look reliable enough to turn AV around. Good luck
I hope that investors will be able to trust the new Board; they do look reliable enough to turn Aviva (LON:AV.) around. Good luck
Too late for that, the turnaround has already happened. Amanda Blanc has sold off most of the overseas businesses, consolidated the core business, stripped costs out and has returned over £9 billion to shareholders since 2021 (on a business currently worth £13 billion), including over 220p in dividends (i.e almost equal to the share price back in 2020). If you include shareholder returns the company is trading at an all time high, despite its market cap having halved from its peak.
She and Aviva are now moving into the growth stage with the bid for Direct Line Insurance (LON:DLG). Lots of different considerations now apply, although I think once DLI is integrated they're likely to be able to resume significant shareholder returns, possibly from 2026 assuming the transaction goes through relatively smoothly.
I too was far from impressed by the company's attempt to redeem the prefs on the cheap, but that's ancient history these days.
timarr
Thanks guys. It has always rankled with me, and I took the opportunity to get it off my chest. You're right, it is history, and the new Board looks good.
They HAVE returned the share price to what it was in 2018, although the PE is up 50% and the price and CAGR Book Value/share lie well down in the Insurance sector, but, as you say, their dividends have paid for a 2020 investment.
I have Helios Underwriting (LON:HUW) on my watch list [having invested just before the LA fires and sold] and think there may be other companies worth looking at in the sector. Good fortune go with you
crikey acdoug! The Aviva (LON:AV.) recovery began years ago. The share price bottomed in 2020 at just 230p and has since more than doubled. Isn’t your post looking at distant and now largely irrelevant history?
Hi Roland. I also own Serica and as both a retired engineer and living less than 100 miles from the platform (Shetland), fully concur with your thoughts on the ageing infrastructure. However, I also think that the company is phenomenal value. For me I'm going to give it the benefit of the doubt and stick with it, at least for the time being.
Hi Chris, thanks for your comment. I am also planning to stick with Serica Energy (LON:SQZ) for now, at least, for the same reasons.
I envy you living in Shetland, we've visited several times over the years and love the islands (even in winter!).
Roland
When I saw the comments about investment required to maintain production through to 2040 it made me think about the parallel with the decision to hold onto a much loved car as garage visits and bills rise, or head for the dealership and trade it in for something newer, shinier and (hopefully) more reliable.
I am tempted to add for a recovery trade, although as I already have a full position in Serica Energy (LON:SQZ) the recovery profit would be recycled into Ithaca Energy (LON:ITH), where I currently have a starter position. Both are offering patient holders forecast dividends of over 15%
The consultancy group Elixirr International (LON:ELIX) have issued a “Ahead” trading update reminding us that it has that it has passed the "Rule of 40" every year since its IPO. The Rule of 40 is usually applied to successful SAAS companies where the % Sales growth + %EBITDA = >40.
But in the latest edition of the We Study Billionaires podcast the Canadian managers suggest using the Rule of 40 to identify great investing opportunities across all sectors . They suggest that because of the compounding potential of a Rule of 40 company, a PE of 25x is reasonable. Pre-update Elixirr International (LON:ELIX) sat on a PE of just 16x (and a PEG =1), which seems far too cheap for such sustained sales and margin growth.
https://www.theinvestorspodcast.com/episodes/unlocking-high-growth-investments-w-jason-donville-and-jesse-gamble
I hold.
Big fan of the we study billionaires podcast, the spin off 'the intrinsic value' is also a good watch as they analyse specific companies but usually US focused
Thanks, interesting read. It also popped up on the Jim Slater screen middle of last year - shame I didn’t buy any!
Elixirr International (LON:ELIX)
Good update this morning. Results ahead of market expectations (but not a lot - Cavendish previously had revenue £109.5m and adj. EBITDA £30.4m - now "greater than £111m" and "approximately £31m".
Net cash with debt to finance acquisition repaid.
Market reaction has taken the SP to an all time high.
I have not come across the "Rule of 40" before. Does anyone here find it helpful?
In every year since Elixirr's IPO, the sum of its revenue growth and Adjusted EBITDA margin have exceeded 40%.
I think you can only truly be a 'Rule of 40' company if you are achieving the growth organically, still growth has been impressive here even if its been assisted by using cash on the balance sheet
You dont often hear of the Rule of 40 . The other UK one I can think of who aspires to it is £SYS1 Anyone know of others?
SAGE!
What are the rules?
Filtronic (LON:FTC) ?
Any chance of a current view on Hollywood Bowl (LON:BOWL) chaps , decent covered dividend, seems to consistently churn out profits but are they now ex growth and more of an income stock moving forward ?
Castings (LON:CGS) down 16% today for reasons others have noted. It's a company that appears on my radar from time-to-time. I think its basic problem is that it can't seem to get anywhere as a company. Its EPS in 2015 was 31.8p, pretty much where it stood in 2024 at 38.3p.
It dividend cover has been been stretched in the past. Analysts estimate a dividend cover of 0.9 for 2025 and 1.1 for 2026. Given today's announcement the dividend looks like it might be under threat, possibly.
Serica Energy (LON:SQZ) Equivalent of a profit warning today as production halted in Triton and estimates for the year "under review". I've sold this morning. Should recover in time but may take quite a hit again.
Are they still planning to pay out that dividend? I never trusted the huge amounts on offer especially when they were arguing about UK production...
No word on that...I expect so, would really hammer the price if the dividend is reduced. Serica Energy (LON:SQZ)
Serica Energy (LON:SQZ) Yes, more Triton issues - this is a frequently told story now, which is getting tiresome (although the latest is storm damage, which to be fair is somewhat out of their control). Thus I also sold this morning (so watch the price rebound now!!).
I also sold first thing this morning for a 10% loss excluding dividends. It’s one shut down too many. This section from Roland’s commentary in January reflects the risks that problems like this could well continue to happen.
“It’s not a pretty picture and it may be worth remembering that Serica’s assets are fairly mature. I can’t be sure, but I wonder if they may be more prone to reliability issues than more recent developments, especially as operators are likely to manage capex tightly to reflect limited production lifespans.”
Dividend cut coming too?
Agreed Ken looks cheap as chips on the numbers but to many constant banana skins makes me wary of getting involved at this level.
I thought the whole point of Serica was that they took over ageing assets with the aim of operating them more efficiently than the bureacratic oil majors could. They're obviously very profitable doing that, but glitches like the current one should be considered par for the course.
JCPr
I agree that the plus case for Serica Energy (LON:SQZ) is strong and also agree with Chris860 that the share looks “phenomenal value.” But I’ve weighed that against their ageing assets being so prone to problems and the risk that these could well continue or get even worse. And what if the gas price, a current Serica Energy (LON:SQZ) headwind falls if Russian gas supplies increase again after an Ukraine peace deal/sell out?
I also have a “sell on bad news” rule that works very well, but up to now have ignored it for Serica Energy (LON:SQZ) on previous shutdown or similar news because the share is otherwise so cheap. The market reaction today is negative. If that continues and Serica Energy (LON:SQZ) falls to around £1.10 I might well buy some again, not least because at a bonkers low price it might just tempt a bidder.
Yes, more bad news from Serica Energy (LON:SQZ) today and an understandable hit to the share price.
I still hold (I might even be in love it's such a long term hold for me!!).
A few things strike me about this update, while the storm is clearly out of their hands, the initial 4 days it took to recover, I find excessive. Was the F&G system damaged in some way? If not, 4 hours would seem a more appropriate time frame for a re-start of production.
And then a faulty fitting is found in the inert gas system used to purge the tanks. Is it also storm damage (along with the tank)? The inert gas system is generally in use full-time.
And finally, 4 to 6 weeks repair period? Very disappointing. I wonder if any sort of gap analysis exists of where the Triton vulnerabilities lie?
FWIW, the placement of a Serica person in the Dana team, doesn't strike me as unusual. And I would expect that the review of the planned summer maintenance shutdown will likely focus on work that could be done now (unlikely) and work that can be differed until later, shortening the shutdown period.
But in all of this, I have to say, while I do like Serica and the apparent value on offer, patience is wearing thin...
Regards,
Jon
Castings (LON:CGS) - As well as the significant profit warning for the foundry business for the current year, the muted recovery in heavy truck demand, I think is also signalling a downgrade to FY26 numbers, so I'd expect a significant fall in the shares today