Daily Stock Market Report (Tue 25th August 2026) - VLX, VTY, CSN, TUN, GKP

There has been a remarkable surge in the price of bitcoin since the beginning of last week: from around $63,000 to over $80,000. The rise this morning alone is some 2%.
It really started flying on Wednesday 19th, when US Treasury Secretary Scott Bessent announced an intention to massively increase the buyback of long-term US Treasury bonds (10- to 30- year bonds). The Treasury said it was “increasing, by at least double, the size of liquidity support buyback operations”.
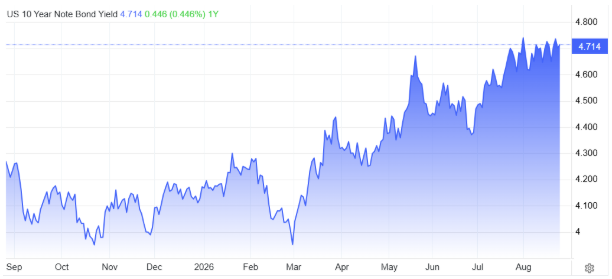
The 10-year US yield has been increasing over the past year, approaching 5%:
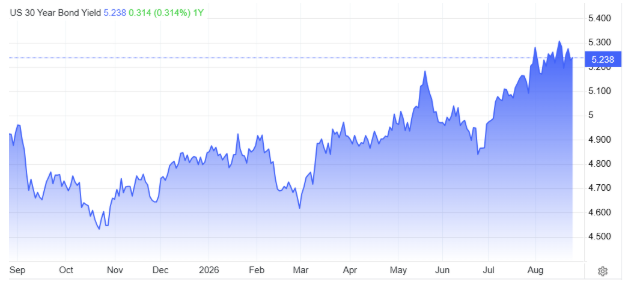
The 30-year yield is over 5%:
The US government famously has a tendency to borrow short-term rather than long-term, but with the federal debt load officially crossing over the $40 trillion mark this month, interest rates are becoming a sensitive subject whether at the short end or the long end of the curve.
Gold has also been a beneficiary of bond buyback talk, up $300 an ounce (or 7%) since August 19th. But Bitcoin has put it in the shade, increasing by around 25% over that timeframe.
Roland Head joins me today.
Leaving it there for now, thanks! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author |
|---|---|---|---|
Melrose Industries (LON:MRO) (£5.8bn | SR16) | Re: chemical leak at GKN Aerospace Garden Grove. A claims programme will be launched to provide up to $100 million for eligible residents and businesses. GKN is targeting 28 September 2026 to resume full manufacturing operations. | ||
easyJet (LON:EZJ) (£5.1bn | SR63) | “In order to facilitate continuing constructive engagement with the relevant aviation regulators following the summer period and prior to publishing the Scheme Document, the boards of easyJet and Bidco have agreed an extension to the deadline for publishing the Scheme Document…” Acquisition is still expected to complete by the end of the first calendar quarter of 2027. | TAKEOVER | |
Volex (LON:VLX) (£976m | SR88) | A very strong start to the new financial year. 28.0% constant currency organic revenue growth (in the prior year, new Data Centre programmes were ramping up). Headline growth rate to normalise over the remainder of the year. FY2027 underlying operating profit to be ahead of current market expectations (consensus is $138.3 million, with a range of $135.3 million to $141.3 million). | AMBER/GREEN ↑ (Roland) While there are clearly some cyclical risks here relating to the Data Centre boom, there’s no sign of a slowdown yet. Today’s update from Volex suggests the group’s growth and profitability will take a further step forward this year. I don’t have access to updated broker forecasts this morning, but my number crunching suggests we could see a c.10% increase to profit estimates based on today’s upgraded guidance. It looks like I turned neutral too soon in June, so I’m moving back up to a moderately-positive view today. | |
| Vistry (LON:VTY) (£854m | SR72) | SAHP Funding Award | Vistry has secured a “significant direct grant award” under the first allocation of funding from the government’s Social and Affordable Homes Programme. The initial funding for Vistry is £350m, “the largest award possible in this phase” and will support the delivery of over 3,000 affordable homes. | AMBER/RED = (Roland) Today’s news is evidently positive, but it’s not clear to me how much of this was already reflected in the company’s own H2 guidance. Vestry hasn’t commented on guidance today and I don’t have access to any updated broker notes. We’ll learn more with the H1 results and CEO Review that are due in late September. In the meantime, recent press reports of cuts to the group’s credit insurance cover and other company-specific risks we’ve discussed previously mean that I’m going to leave our cautious view unchanged today. |
Chesnara (LON:CSN) (£765m | SR39) | Adjusted Operating Profit of £31m, up 46%. Assets under Administration of £21bn, up 38%. Operating Capital Generation £96m. HSBC Life (UK) acquisition completed in January. “...we continue to see attractive opportunities to grow the business, underpinned by a healthy M&A pipeline…” | AMBER/GREEN = (Graham) | |
Tungsten West (LON:TUN) (£538m | SR35) | SP +18% Agreed terms National Wealth Fund regarding a proposed investment of up to £71m, completing the funding package for the restart of Hemerdon to full production. Chancellor John Healey: “We are tapping into one of the largest deposits of tungsten in the world, right here in the UK.” NWF to buy 100 million new shares at 36p (last night’s close: 43.1p). | AMBER ↑ (Roland) [no section below] The UK NWF will invest £36m in new Tungsten equity at a discount of 16.5% to last night’s close. The NWF will also provide facilities for up to £35m of debt. In addition, the UK government will have the opportunity to arrange an offtake agreement for up to 50% of expected tungsten production, potentially providing an anchor buyer (for TUN) and a domestic source of this strategic metal (for the UK/EU). This deal is expected to support a production ramp-up starting later this year. However, gauging the value on offer here is beyond my paygrade. From what I understand, European demand for tungsten has risen sharply this year (e.g. due to defence) while Chinese supply has fallen. This has created a situation where there’s a significant price difference between EU and China prices, with both markets well above historic norms. Brokers covering the stock have target prices north of 60p, but I would be wary of the risk that this is a situation where a pre-production miner is already priced for near-perfection. I’m going to adopt a neutral view on the basis that the business appears to be on track, but the valuation requires further research. | |
Gulf Keystone Petroleum (LON:GKP) (£399m | SR58) | Gross average production of 14,600 bopd in H1 2026 (H1 2025: 44,100 bopd) “reflects impact of precautionary shut-in between 28 February and 23 June 2026 due to regional security issues”. A second precautionary shut-in took place between 19 July and 15 August 2026. Shaikan Field production restarted on 16 August 2026, with gross volumes currently approaching 40,000 bopd. $10 million interim dividend. | AMBER ↑ (Roland) [no section below] Shaikan has always been a large, low-cost field with huge cash generation potential. Anyone who has followed this Kurdistan oiler for long enough will be familiar with the cycles of regional instability, payment issues and periodic halcyon periods that have characterised this business. I don’t see that changing. Right now, the balance sheet looks strong, with net cash of $63.5m. This position could improve if the company can achieve both agreement on and payment for exports at full international prices (local market prices are much lower). On the other hand, the risk of conflict or further political headwinds cannot be discounted. With the stock trading close to book value and offering a cash-backed dividend yield, GKP could be cheap. But investors need to form their own view on whether the stock is cheap enough to discount the perennial risks facing this business. I’m not sure. But I think it’s fair to follow the StockRanks and take a neutral view given the production restart, balance sheet strength and interim dividend. | |
Eco (Atlantic) Oil & Gas (LON:ECO) (£172m | SR25) | Navitas (subject to completion of its acquisition of PL001) intends to drill a multi-target exploration well on PL001 during its development drilling campaign in the North Falkland Basin, with part of the Sea Lion Project (NDA1) drilling campaign expected to commence at the beginning of 2027. The first chosen drilling target on PL001 holds a 2U prospective resource of 640m barrels of oil, of which Eco’s share would be c.225 MMbbl. | ||
Savannah Energy (LON:SAVE) (£115m | SR n/a) | Group average gross daily production was 16.3 kboepd for 7M 2026 (FY25: 18.8 kboepd). With Uquo 13 now on stream, average gross daily production is expected to exceed 20 kboepd for the rest of the year, with FY26 average gross daily production expected to be 18-20 kboepd. 7M 2026 cash revenue +10% to $160.6m, with cash collections +13% to $247.9m. Net debt was $672m at 31 July 2026. | Shares currently suspended. | |
Windar Photonics (LON:WPHO) (£26m | SR n/a) | £4m placing (yesterday) & £0.2m retail Offer | The company raised £4.055m through a placing of 81.1m new shares at 5p on Monday afternoon. It has now launched a retail offer aiming to raise up to £200k at 5p. This is a discount of approximately 81.1% to the closing mid-market price of 26.5p on 17 June 26, prior to the shares’ suspension. Windar hopes to publish its FY25 accounts by 26 August to enable the shares to resume trading from the 27 onwards. | Shares currently suspended. |
Emmerson (LON:EML) (£23m | SR9) | Following the rejection of Morocco’s application for bifurcation of the case in July, the next steps in the process will be: - Morocco’s Counter-Memorial (due Jan 27) - Emmerson’s reply to Counter-Memorial (due Oct 27) - Morocco’s Rejoinder (due Jan 28) - The Tribunal hearing will take place from 17-26 July 2028. Emmerson is seeking $1.215bn of compensation for alleged breaches by Morocco. | ||
Tialis Essential IT (LON:TIA) (£19m | SR31) | H1 revenue -13.6% to £7.6m with adj EBITDA -40% to £0.6m. Outlook: “encouraged by the visibility of the Group’s second-half revenue pipeline”, which has an approximate contract value of c.£8m. Agreement JV partner AI Auxesis has been formalised so that AI Auxesis will receive an annual cash fee of £192k on a 12-month contract. Other potential fees may apply in the future. This is a related party transaction. | ||
Southern Energy (LON:SOUC) (£15m | SR30) | Sales +4% to $4.2m in Q2, with net loss reduced slightly to $407k. Q2 production averaged 10,460 Mcfe/d, a 7% decrease from the prior year period due to a transport dispute. Net debt of $16m on 30 June. |
Graham's Section
Chesnara (LON:CSN)
Up 4% at 343.5p (£796m) - Half-Year Financial Report - Graham - AMBER/GREEN =
This is not an exciting business: it buys up old insurance books and extracts the profit from them as they gradually expire.
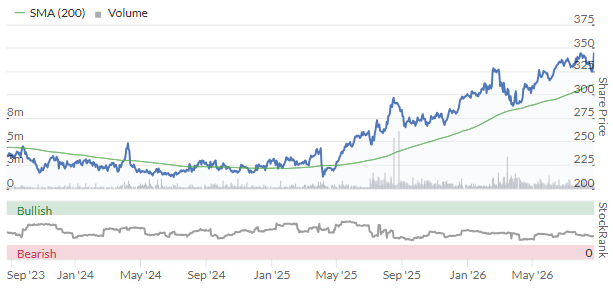
For its shareholders, it has paid a nice dividend of 20p+ annually, increasing over time. There’s also been some decent share price growth in recent years:
These interim results read very well:
Adjusted Operating Profit (AOP) of £31m, up 46%
Assets under Administration (AuA) of £21bn, up 38%
(Assets under Administration in this case is a balance sheet number - it’s different to the number reported by fund managers/trading platforms.)
The headline numbers are:
Operating Capital Generation (OCG) of £96m, up 79%
Cash Remittances of £73m, up 31%
I don’t trust these numbers quite as much as I do the profit numbers. For example, “cash remittances” is measuring how much cash has been sent to Chesnara from all of its various business units during the period. I’d expect that to be a lumpy figure that doesn’t represent underlying profits.
OCG, too, doesn’t seem to represent cash generation that’s sustainable. Today’s notes say that OCG “was supported by £51m of acquisition-related impacts and capital optimisation activities relating to Chesnara Life UK…” Sounds to me like this is non-recurring in nature.
For me, AOP of £31m is the number I trust the most, to measure underlying profitability that might be repeatable.
HSBC Life/Chesnara Life: HSBC withdrew from selling protection policies, selling HSBC Life (UK) Limited to Chesnara in a deal that completed in February this year. This was Chesnara’s 15th and largest acquisition.
The price for HSBC Life was £260m, of which £140m was raised in a rights issue.
So it’s very important to consider that dilution when looking at today’s numbers. The number of shares outstanding has increased from 151 million (June 2025) to 230 million (June 2026).
Thankfully, the acquisition appears to have gone very well so far. Another big acquisition is planned, too: €110m for Scottish Widows Europe, a closed life insurance book based in Luxembourg and owned by Lloyds Banking (LON:LLOY). This one will be paid with Chesnara’s existing cash resources (no need for an equity raise).
CEO comment today, summing up the interim results:
"Chesnara has delivered a very strong financial performance in the first half of 2026 with Operating Capital Generation up 79% and a 6% increase in the interim dividend. The integration of Chesnara Life UK, our largest acquisition to date, continues at pace with strong capital generation already delivered from our first five months of ownership. The regulatory Change in Control for the proposed acquisition of Scottish Widows Europe SA is anticipated around the end of 2026, and we continue to see attractive opportunities to grow the business, underpinned by a healthy M&A pipeline and disciplined execution across the Group."
Outlook excerpt: “We have made strong progress against the priorities set out for 2026. In the second half of the year, our focus will remain on delivering our strategic priorities.”
Graham’s view
In some ways, I’d treat this like I treat many of the High Street banks: these are respectable blue-chip stocks where it’s often difficult to understand the full nature of the risks taken on by shareholders.
Thankfully, there are some metrics that do help out.
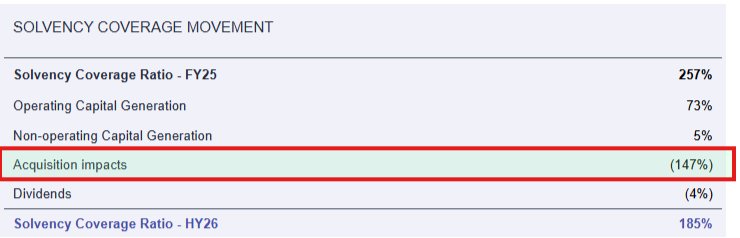
The Solvency Coverage Ratio (185%) tells us that the company still has plenty of regulatory capital, although it spent a huge chunk of it on the HSBC acquisition:
The balance sheet shows the leverage that’s inherent in running a major insurance operation: £21 billion of assets are supported by equity of little over £500m.
In March, looking at the full-year results, I was AMBER/GREEN. I was willing to look past the heavy adjustments to the profit figures and come out with a moderately positive view.
Looking at it today, the share price is up by 50p and the adjustments are still very heavy. On a statutory basis, the net income result on today’s income statement is only around breakeven. To get £31m of adjusted operating profit, you have to add back £23m of integration/restructuring costs and a few other small items.
So this is far from straightforward. I could justifiably move back to a neutral stance, I think. But I’m inclined to trust their acquisition process, on the basis of their track record, and therefore I’d have some degree of confidence that the statutory numbers will be looking much better in a few years, when HSBC Life (and Scottish Widows Europe) have been bedded in. So let’s leave it AMBER/GREEN for today.
Roland's Section
Volex (LON:VLX)
Up 19% at 634p (£982m) - AGM Statement - Roland - AMBER/GREEN ↑
One of the key points Ed highlighted in last week’s webinar was how earnings-driven momentum can continue for longer than expected.
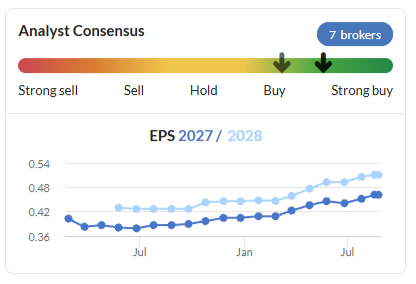
Volex appears to be a case in point – today’s AGM update includes an upgrade to FY27 profit expectations. This continues a run of upgrades that have already added 20% to FY27 EPS estimates over the last 12 months:
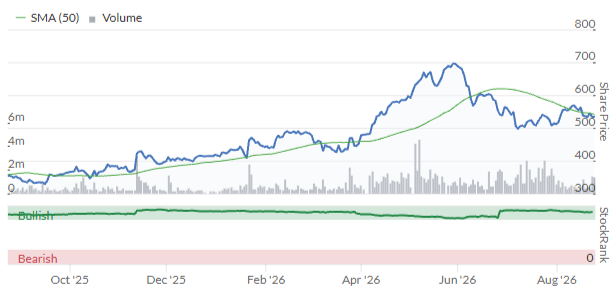
Volex’s share price has risen by 50% over the same period:
For anyone new to this stock, Volex is an industrial firm producing a wide range of wiring products for markets including data centres, automotive OEMs and consumer goods companies. Growth over the last year or two has been turbocharged by the AI boom, which has accelerated demand for the company’s data centre solutions. These are also among its highest-margin products.
AGM update: “very strong start to FY2027”
Volex has started the year at a good pace, with 28% organic revenue growth at constant currency compared to the same period last year. Growth is still being driven by Data Centre demand, but performance also appears to have improved in the company’s other divisions:
Complex Industrial Technology (data centres): “customer demand has been sustained at the elevated exit rate of FY2026”.
EV & Electrification: “increased demand” supported by electrification trends and customer focus on energy efficiency.
Consumer Electricals, Off-Highway and Medical all saw “good growth”.
In a welcome dose of transparency, Volex’s management cautions that the impressive H1 revenue growth rate reflects the ramp-up of Data Centre demand during FY26. Growth rates are “expected to normalise” during the current year and we are told that a more meaningful sequential growth rate versus H2 FY26 is 8%:
Sequential trading is the better guide to underlying momentum, with average monthly revenue in the first four months of the year running 8% higher than the monthly average for the second half of FY2026.
KST Acquisition
In July, Volex announced that it was acquiring the remaining 64% of KST Signaltek for $89m, a medical technology business in which it was a founding shareholder.
KST generated revenue of $51.8m during the year ended 31 March 2026 and is expected to accretive to group margins:
The Acquisition is expected to be immediately earnings enhancing, and to improve the Group's underlying operating margin, with KST's EBIT margin ahead of the Group's underlying operating margin
The return on capital employed from the Acquisition is expected to exceed 15% within two years of completion
Broker forecasts updated following the acquisition suggest KST will add c.4% to earnings in the first full year of completion (FY28).
Outlook: “ahead of current market expectations”
As a result of the strength of trading in the opening months and the operating leverage inherent within the business model, the Board now expects FY2027 underlying operating profit to be ahead of current market expectations.
I can’t see any updated broker forecasts today, but Volex does provide details of current consensus expectations:
Revenue $1,338m ($1,327m to $1,347m)
Underlying operating profit: $138.3m ($135.3m to $141.3m)
Roland’s view
I’m not sure how big today’s upgrade really is – there are no qualifying words such as material or significantly to suggest a major upgrade.
However, there are a few clues I can work with:
Revenue: YTD revenue is said to be 8% ahead of H2 FY26. Annualising this suggests FY27 revenue could be c.$1,425m, assuming no further growth. That’s about 6% ahead of previous consensus.
Underlying operating profit: today’s update mentions positive operating leverage and cost control. This suggests to me that Volex’s underlying operating margin will be higher than FY26 (10.2%) and higher than the previous consensus view of 10.3%. I’m going to stick a finger in the air here and suggest an improved margin of 10.7% after factoring in the expected contribution from KST. On that basis, I estimate underlying operating profit could be c. $153m – around 10% ahead of current consensus.
Underlying EPS: applying a c.10% increase to current consensus gives me a figure of perhaps $0.51 per share, putting Volex on a forward P/E of 17.
Was I wrong to turn neutral? I reviewed Volex’s results in June and moved our view down to AMBER, noting customer concentration in data centres and declining sales in two of the group’s five divisions.
It now looks like I was wrong, or at least premature, to take this position.
While I would argue that risks remain relating to the buildup of working capital and exposure to a small number of large Data Centre customers, underlying momentum still seems positive.
At some point I expect the Data Centre boom to slow, but I have no idea when this will be – the pipeline of projects under construction still appears to be quite large.
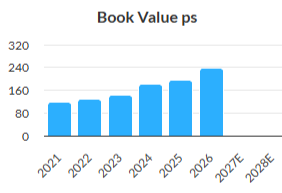
Perhaps I should have put more weighting on Volex’s improving quality metrics:
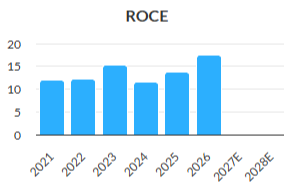
A combination of stable/rising ROCE and rising book value suggests Volex is generating genuine economic value for its shareholders, over and above its cost of capital:
The StockRanks also have a broadly positive view of Volex, styling the stock as a High Flyer, with weak value but strong quality and momentum:
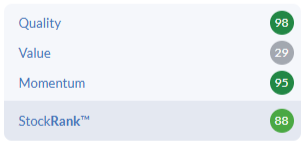
While momentum and profitability remain positive, Volex could continue to make progress and does not look overvalued to me.
To reflect this, I am moving my view back up to AMBER/GREEN today.
Vistry (LON:VTY)
Up 17% at 314p (£998m) - SAHP Funding Award - Roland - AMBER/RED =
One of the question marks hanging over Vistry this year has been the size and timing of the award it would receive as part of the government’s Social and Affordable Housing Programme (SAHP). This aims to provide £39bn of funding for social housing over the next 10 years.
Today we’ve learned the answer – Vistry has received an initial tranche of funding of £350m, which it says is “the largest award possible in this phase” of the programme. The market has reacted very favourably, although the shares remain extremely depressed on a medium-term view:
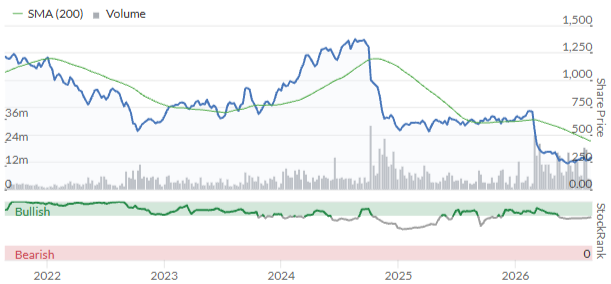
One apparent positive in today’s announcement is the company expects the SAHP funding to have a material impact during the current financial year:
The funding “will enable the delivery of over 3,000 affordable homes”
Vistry has as “an established pipeline” and has “identified immediate opportunities to deploy its own grant funding […] within the current year”
Vistry has long experience in this sector, working with partners such as housing associations to complete new housing schemes. As a result, the company has the advantage of having existing relationships with many of the other relevant parties needed to move developments to completion:
The group has “longstanding relationships with 29 of the 32 other strategic partners announced this morning” and operates “within all of the Mayoral Strategic Authorities” including in today’s announcement.
Vistry has received direct grant funding awards under successive affordable homes programmes for nearly twenty years.
CEO Adam Daniels is also keen to highlight that today’s funding is a step up in size from any previous programmes:
Vistry’s total funding under the 21-26 Affordable Homes Programme was £278m, with an initial award in 2021 of £83m.
Roland’s view
We have commented on Vistry’s operational and financial problems a number of times this year, most recently in May and July. I won’t repeat all of that here, except to highlight that prior to today the stock was trading at a near-75% discount to its last-reported book value:
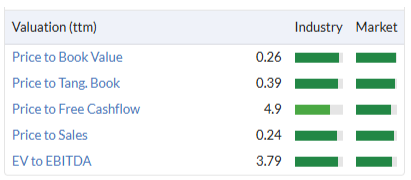
As Mark and I have both commented, it seems likely that there is a value opportunity here, if the company can get its balance sheet and profits moving in the right direction.
Sadly there is no commentary today on whether this SAHP award is in line with expectations, or how it might affect profit expectations for the current year. I don’t have access to any recent broker notes for Vistry, either.
As a result, I can’t be sure how many of the 3,000 homes mentioned today were already included in guidance for the full year. After all, an SAHP award has been expected for some time and was explicitly included in July’s H2 guidance:
Higher weighting of volumes in H2 in both Open Market and Partner Funded, as seen in prior years
The benefit of confirmation of the SAHP allocations improving Partner Funded transaction activity
I am fairly confident that today’s news should underpin existing FY26 guidance, but it’s not clear to me if there is any net positive impact that wasn’t previously included.
My decision: Vistry is due to report its half-year results on 24 September, together with the results of a review by the group’s new CEO. We should learn more then about both forward guidance and the likely impact of today’s news.
In the meantime, I have to choose whether to retain our AMBER/RED view today or revert to a neutral (AMBER) view.
The StockRanks support either choice, styling Vistry as Contrarian, with strong quality and value scores and very weak momentum:
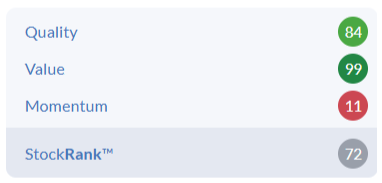
In general, my feeling is that the tide may be turning for some listed housebuilders, potentially including Vistry.
However, while I do think Vistry could be an interesting special situation, I think there are some company-specific risks worth noting.
One concern is that recent press reports have suggested that insurer Allianz has cut the level of credit insurance it provides for suppliers to Vistry, potentially putting further pressure on the group’s cash flow.
From an equity perspective, this kind of issue is always a warning flag that’s worth considering. For this reason, I’m going to leave our AMBER/RED view unchanged for now.
We’ll take a fresh look at the situation in September, when the half-year accounts should provide greater clarity on the group’s financial situation and trading outlook.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Volex (LON:VLX) Thank you Roland for your very helpful analysis. I originally bought these shares when they were at the c£2.50 level and sold my total holding, albeit making a good profit, too early. Bought back in again in June, added in July and August against a leap in the SR highlighted by the team in June.
Whilst there is always the prospect of a slowing down in data centre builds, my view is that there is still a reasonable timeframe for the momentum to continue, coupled with more electrification of goods and services to satisfy continuing worldwide demand. Volex now has several strings to its business and I believe that it will continue to make good progress for several years to come.
The directors continue to buy in-Nathan Rothschild has a 26%+ holding and whilst the PEG ratio is a little on the high side, the P/E ratio looks reasonable for this sector I would suggest. Quality rank at 98 suggests that there will be more gradual gains until the next set of results are announced as outlined in Ed’s analysis of SR jumpers.
FTSE shake-up. The regular shake up is due any day now. Does anyone have a list of the contenders. I'm thinking Keller (LON:KLR) may be uplifted to the 250 which might help it climb back up ?
Announcement should be made on Sept 2nd. Very likely Volex (LON:VLX) will be added to FTSE 250
Keller (LON:KLR) is already in the 250
And so is Volex (LON:VLX) , which I hold - it seems to be unstoppable.
Vistry (LON:VTY) Not to put too fine a point on it but where else would the Government offer a contract for these builds? One wonders if the bounce in the share price is down to some shorters closing positions. I would be surprised if the margin on this business is anything like housebuilders have enjoyed in recent years. Are Vistry actually able to deliver these homes ?
Huge risk all round, gov.t should have taken equity share like the tungsten firm oak bloke just highlighted?
This is what Vistry (LON:VTY) have to say on their ability to deliver:
The Group has an established pipeline and has identified immediate opportunities to deploy its own grant funding to deliver much needed affordable housing schemes within the current year. Alongside this, Vistry will deliver additional homes at pace by working in partnership with other Strategic Partners, Established Mayoral Strategic Authorities and Councils as they commit funding to their programmes as part of the initial £9.58bn of allocations. The Group already has longstanding relationships with 29 of the 32 other strategic partners announced this morning, and operates within all of the Mayoral Strategic Authorities referenced in the announcement.
You could argue "they would say that, wouldn't they?" For me, there is enough substance there to be convincing. Vistry does have a substantial track record in this market.
Re Vistry
I think that the main problem is the recent press coverage that a trade insurer has cut Vistry's credit by up to 70%. This was discussed on this board a couple of weeks ago, but additional link below.
https://www.constructionenquir...
Various reports suggested that Bovis was having to discount completions to bring in cash. Not a great position from which to increase the number of builds.
I think that Vistry must be a decent trading stock for those who know what they are doing. I personally don't see it as a viable investment.
Vistry (LON:VTY)
i am not particularly impressed by management here.
i wasnt going to mention rumours i had heard that Visty was very slow at paying suppliers - i cant verify those rumours - but the fact the CFO is leaving (thrown in the towel) and their credit insurance has been cut by up to 70% - with no comment from company themselves. Its got red flags left right and centre unfotunately.
I get pimping out suppliers if you can use cashflow to pay down debt - but that should only be done with constent and full agreement of suppliers. Perhaps its just natural lag that credit checks go of the now rather than the 6 months time. But perosnally i have little confidence that managment wont chcuk in an additional stinker at some stage - they previously tried to blame one specific area when my opinion was that "necessary central checks" must have been non existent - imho toip brass should have ben rinsed then. its all too easy with companies like this to get suckered into playing with the numbers - rather than delivering simple reliable clean consistent profits from clearly conservative acounting perspective. For my sins i do have a minor holding here i havent got round to ditching yet as its a company with a boatload of very mixed signals - in theory company making £100 mill plus per year - paying down debt and trading at below book value shouldnt be having more questions than answers.
Im have to preume todays news is good though - albeit i am kinda guessing it was kinda expected it would turn up.
Pleasingly I have avoided Vistry, even when it was the sector darling which does seem an age ago. Given this sector of the market ( note Gleeson comments) seems to be the only one where activity is at a reaonable level ( mortgage affordability seems bad enough given cost of living for many is going up yet again even before taxes rise in the Budget to pay for more Socialist largesse) I previously commented there was an opportunity to ' bottom fish' housebuilders but this may have gone given recent relative strength. I am sure without further 1st time buyer incentives the sector will remain in the doldrums. Round where I live it is a building free for all but most are not selling and developers holding onto the land they have pending ' better times' This is to me a question of building with a low margin; nobody seems to know if these homes are to be built to the same standards as other new including such as Heat pumps and solar panels etc ..............
i think you have hit the nail on the head with low margins - i think its good if there is little to no real terms house price inflation , clearly hosues are too dam expensive - that and leasehold changes will make it harder for homebuilders to eak out a profit.
Note it must get to apoint though where if it costs 300k to build a home are they pricing most out of teh market - however its done affordable homes for the younger ones should be top priority of this government.
Perhaps sensible middle ground would be for youngsters to build up some credit history and then perhaps be given some support for long term loans fixed at inflation type rates - so they could be lent the money and only have to "inititially" pay say the rate of inflation. explain to people that the gov will help if they are grown up and take their finances seriously.
would be huge helps for young uns if say 50k to 100k could be lent so they only pay interest each month for up to first ten years of ownership (plus whatever they can afford on top at token level) - orerpayments perhaps encouraged or demanded based on ability to pay. it would be clear that its done on the basis that when they get a mortgage they are expecting that there would be no further advances and mortgage debt would be falling s- so very much help for those with real need to get a propertry - rather than something for middle classes to pimp out and get a home with an extra room or allow them to remortgage to gain from uplift in value whilst getting this freebie support. would help massively if this would make it eassier to get mortgage and get home where people could pretty much afford monthly payments but cant get on the ladder at present . this needs to be done in conjunction with new homes being built in the millions. It could be done in conjunction with proper financial training - send someone on a financial course and they would need to evidence sensible spending to pass and qualify. Ideally at future points the debt would just be moved over from this facility to part of their standard mortgage - one would hope someone paying down mortgage - and with wages going up in line with inflation - in 5 years hopefully that loan deposit amount could be switched over onto formal mortgage at renewal. Note this advance would be noted on mortgage systems as being part of calc but could be ignored for affordibility purposes if its bog standard remortgage.
Back on point ref vistry £100 mill plusprofits pa aint to be sniffed at - is it real and proper though with no real nasties under the hood - the market has doubts and must admit i have doubts.
You make a lot of very sound points and in truth unless there are young first time buyer incentives the idea of building all these homes will just fall over. The idea of including in the chain a huge number of housing associatons where I have bad memories of poor financial control and general incompetence does not exactly fill one with confidence
I think many builders ( i was told here that small builders are struggling to sell 1 a month) face dramatically lower margins if they want to shift houses in volumes on top of having to offer incentives to buyers. I have no idea of the margin Vistry expects on the building but given their issues a more sanguine view may suggest that cost inflation etc will bite harder
Just a view and I am not at all clear that the sector is yet ripe. Of course the Budget could easily bring FTB incentives
and in truth unless there are young first time buyer incentives the idea of building all these homes will just fall over.
well it shouldnt - its an express policy of AB to build these new homes - there is i think politically no scope for the building of new homes in teh millions to be anything but one of his 3 main pledges as PM if he wants to keep teh job past teh next election he will need to show progress even if they fall short of election promises i think he has the will to up mateerially from levels of past governments and KS- it may take time but the new homes need to be built. Note even if thats at a higher than basic level - it can take heat out of the market if it allows those that cant currently afford to move into something bigger to do so - so that would free up lower level stock. its plain fact an 2 mill extra homes existing pronto would Indubitably help keep house prices down all other things being equal.
I think many builders ( i was told here that small builders are struggling to sell 1 a month) face dramatically lower margins if they want to shift houses in volumes on top of having to offer incentives to buyers.
i think thats a likely fact of life - we cant expect them to work for no margin though - so some solution may be needed - presumbaly update yesterday is a starter for 10 - even if 10 wont gety you anything like the 180 points you may need to win.
If we need to get uber cheap no nonsense mass produced stuff done so be it - just ensure basic standards exist.
Cheers I share your view that these homes are critical and my doubts surround actual delivery from the builder completing to the new 'owner'/tenant. Yes they should be basic design rather than meeting the complete new build standards which are a drag on the sector... I will await comments from Vistry next month before, potentially harbouring a view that less pessimism is in order . I live in Shropshire and the Council has a redundant ( so brownfield site) Town Hall which they cannot afford to run ( will cost 700K a year to keep ticking over, we are told!)Just seems too easy to knock it down and build a significant number of new affordable homes you would think given Shrewsbury (has a signifcant number of homeless as well) has a dearth of affordable accommodation and seen locally as one of the 2 areas where new housing is in peak demand' Duh if only life and planning was that simple...
Vistry
The most shorted share in the UK market . Almost 20% of its market cap!
Maybe buying the most shorted share is the ultimate in contrarian trade.
It’s up more than 12% after a contract win from the government 39b funds for social housing.
"The most shorted share in the UK market . Almost 20% of its market cap!"
I suspect that press comment re Nationalisation does not help.
Up 13%
Today's Volex (LON:VLX) AGM statement is the first in 4 years to break Volex's "in line with expectations" AGM narrative. Now we have, “very strong start to FY2027 with profit expected to be ahead of market expectations”
AGM
Q1
Framing
27 Jul 2023
+6.5%
"in line with management expectations"
1 Aug 2024
+9.0%
"remained in line with management's expectations"
7 Aug 2025
+10.4%
"in line with management's expectations"
Bodes well for the rest of this year?
Why only focus on AGM statements? Volex said they were ahead on 21st January and 25th March this year so to me this is what Ed Croft refers to as repeated beating expectations.
Yes but like Made its a jagged chart and time of buy is important?
I personally think Volex chart is a little false, as there were many forced sellers (for inheritance tax reasons) when it moved from AIM to the main market. Hopefully now this event is over the chart should be smoother.
Wag Dog:
The Volex (LON:VLX) AGM statement is the focus simply because it's today's new information, and the narrative shift against the last 3 years of AGM language is a notable part of it. A fresh full-year and/or H1 signifigant beat would be the stronger read, but neither RNS is due at this point in the year.
I agree: Volex (LON:VLX) have tended to guide conservatively earlier in the year. Today is an interesting break with that recent history and perhaps there is still some left in the tank for further upgrades later this year.
Volex (LON:VLX)
A very positive market reaction to the ahead statement - up almost 19% (at 09 16). The icing on the cake will be that with MCap £1.16 bn. at the current price the recent move from AIM means that it should move into the 250 at the quarterly review next Wednesday (changes take effect from Mon, 21 September). Tracker funds will then be buying.
Melrose
Dreadful stocko rankings but classed as Neutral.
Yadi - I'm not sure what you mean by neutral - the stock rank is in red! - Do we know if Melrose has any insurance cover for these losses ?
Melrose Industries (LON:MRO) Depends if you have the Rankings set to global, regional or local. On global and local it is ranked as neutral, but on regional it is sucker stock!!
I know nothing about bitcoin or how to value, but do hold and have recently added to Volex (LON:VLX).
I was expecting data centre growth to remain strong but am pleasantly surprised that the other divisions also appear to be trading well. Would appreciate the thoughts of Graham and the team.
Morning all,
Impressive headline interim numbers out from Chesnara (LON:CSN) this morning (I hold) but as always interpretation is key. More moving parts than usual so I would welcome expert opinion.
Stocko doesn’t seem to like CSN for some reason. A stock rank of just 39 is scant reward for an impressive track record. What’s the problem?
Life insurers are not the easiest to comprehend - the balance sheets are so complicated. If you look at Standard Life (LON:SDLF) it's more than 10 times bigger. According to Stocko - Chesnara suffered net losses of 10.4m last year, Standard lost £100m and it has a stock rank of 93
Yes this was covered recently in the comments section - life insurers have very different accounts to conventional companies and as a result the stock ranks don't really work for this sector (particularly the Quality rank which always seem excessively low)
Not sure how significant it may be, but bitcoin does seem to be respecting a long term upwards channel with this latest bounce.