Daily Stock Market Report (Tue 27 May 2025) - INSE, MWE, REAT, BOY, ELM, OPG, SAA, ENQ, SRT, AVCT, 4BB

Good morning - I hope you're feeling refreshed after the long weekend!
The Agenda is complete.
12pm: wrapping it up there. It was a rather strange collection of announcements, as might be expected on the first day back after a Bank Holiday. We should get a more normal set of updates tomorrow! Cheers.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Bodycote (LON:BOY) (£940m) | SP +4% For the recent 4-month period, “core” revenues are down 5% organically. Total revenues down 6%. “Supply chains improving in Civil Aerospace; conditions remain weak in Automotive and Industrial markets.” Full year outlook in line with an H2 profit weighting. No material direct exposure to tariffs. Net debt £90m. | AMBER (Graham) [no section below] This issued a profit warning last month, prompting me to downgrade my stance to neutral. Today’s update reassures that the outlook has not deteriorated any further, with the share price reaction suggesting investor relief. The company’s ongoing “Optimise” programme targets savings and benefits of £12-14m p.a., and the company is exploring the potential to expand this. At a modest earnings multiple (and a neutral StockRank) I remain comfortable with my neutral stance. This is a reputable company with a strong heritage but in the short-term I would be a little cautious around the potential for another profit warning - especially given the expected H2 weighting for adjusted profits. | |
Elementis (LON:ELM) (£770m) | Enterprise value of sale $121m, net cash proceeds c. $55m. $50m buyback. Outlook unchanged. Disposal is expected to improve adj op margin by +2.4%. | AMBER (Roland) [no section below] The Talc business has been sold after a difficult year for a multiple of 15x 2024 operating profit. The new CEO will now try to improve the performance of the remainder of the business. This could be an interesting turnaround, but revenue has only risen by an average of 1% per year over the last decade and profitability has been variable. Further research would be needed for me to form a view on this situation, although perhaps Elementis will benefit from a wider chemical sector recovery. For now, I will give the new and highly-experienced CEO the benefit of the doubt and upgrade our view to neutral. | |
Enquest (LON:ENQ) (£212m) | Production efficiency >90%. Q1 production 42k boepd. Net debt $405m. 2025 guidance unchanged. | AMBER (Roland) [no section below] Like most peers in this sector, this independent O&G producer looks superficially cheap and offers a potentially tempting dividend yield. Deleveraging has reduced equity risk and the acquisition of Harbour Energy’s Vietnam assets may be a logical addition to Enquest’s existing SE Asia assets. | |
M&C Saatchi (LON:SAA) (£204m) | Agrees to buy a sports agency in Dubai and Abu Dhabi. Price not given. Funded by cash on the balance sheet (net cash was £18m as of December 2024). | AMBER (Graham) [no section below] When no price is given for an acquisition, we know that the cost must not be material - otherwise the company would be obliged to tell us what it is! The small size of the deal is backed up by its description as a “bolt-on” and the low staff count: its 40 employees join the M+C Saatchi Group family of over 2,400. Megan was neutral on this stock last month and I’m inclined to agree with her; in general, advertising, marketing and PR companies shouldn’t trade at rich earnings multiples and with modest like-for-like growth in 2024 I don’t see why this one should trade much more highly than it does already. PER is 8x on the StockReport and the StockRank style is Neutral. | |
4Basebio (LON:4BB) (£174m) | Revenues £933k (2023: £506k). LBT £12.7m (2023: £8.4m). “Transformational year of growth.” | AMBER/RED (Graham) [no section below] Given the £174m market cap, this is effectively pre-revenue with turnover of less than £1m in 2024. I note in passing that these are results for FY December 2024: companies reporting last year's results in late May are leaving shareholders in the dark for far too long, in my view. As for the results themselves, a key number is the cash balance (£34m following an equity raise in November) which should give the company a runway of a few years, based on historic and forecast losses. On that basis I can leave this at AMBER/RED rather than straight RED. | |
SRT Marine Systems (LON:SRT) (£147m) | SP +4% €167m Indonesia project has commenced. Implementation for 2 years, then 8 years of services. The half-year report to Dec 2024 showed H1 revenues improving to £26.2m and a PBT of £2.1m, after their Kuwait project commenced delivery. £320m of systems were said to be under contract. Estimates: still not estimates. Cavendish expects to reinstate forecasts late June/early July. | AMBER (Graham) [no section below] I was AMBER/RED on this in February on the back of allegations of irregularity (denied by the company) in the Philippines. I had previously been neutral, waiting to see if long-promised revenues from major contracts would at last materialise. Today’s update confirms that the Indonesia contract is now live and I’m happy to go back to neutral, bearing in mind that the half-year report in March showed revenues accelerating and the company moving into profitability. If only the company hadn’t promised success so many times before, I would be more inclined to trust the bull thesis today! It will be fascinating to see how how quickly the company can turn £320m of contracted systems revenue into profits and cash. | |
Inspired (LON:INSE) (£113m) | PE makes a possible cash offer of 81p per share, minus final dividend (if not withdrawn). | PINK (Graham) | |
Avacta (LON:AVCT) AVCT (£106m) | Results due 29 May 25 are delayed to 4 June 2025 due to audit delays. No impact on cash. | RED (Graham) [no section below] I wish this company every possible success with its mission to eliminate cancer. Quantitatively speaking, the stock is a RED - the StockRank is only 3, but the sea of red on the income statement (including the financial forecasts), along with the rising share count would lead me to a similar conclusion. Today we get a red flag to go along with all the red on the income statement: the company's audit isn't finished yet, and so it is unable to publish its results by May 29th as originally planned. Instead, it looks to publish them on June 4th. These are results for FY December 2024 - so they are already very late! | |
Software Circle (LON:SFT) (£109m) | £427k recovered in full. Incident isolated to a single unit. No evidence of breach of systems. | ||
MOH Nippon (LON:MOH) (£78m) | Expect FY25 loss of JPY1,151m. No H2 revenue due to project delays halting crowdfunding. | ||
MTI Wireless Edge (LON:MWE) (£38m) | Rev +7%, net profit +9% to $1.02m. EPS +12%, net cash $8.05m. Confident FY outlook. | AMBER/GREEN (Roland) This AIM technology group has a solid track record and benefits from exposure to several structural growth markets. However, growth is steady rather than rapid and I believe there are some additional risks for UK investors. On balance, I think a moderately positive view is appropriate. | |
Prospex Energy (LON:PXEN) (£20m) | FY loss of £46.8k, NAV +19.5% to £24.6m. Net cash £1.2m, no debt. Now has 3 producing gas assets. | ||
OPG Power Ventures (LON:OPG) (£20m) | FY25 generation flat at 2.3bn units. Revenue & EBITDA are expected to be in line with expectations. Cavendish forecasts (published in Dec 24): FY25E revenue £161m (FY24: £156m); FY25E adj PBT £5.1m (FY24: £8.0m). | AMBER (Roland) [no section below] OPG looks perennially cheap and trades at a near-90% discount to book value. But this may be justified by the sub-3% returns on equity. Shareholders have suffered a massive destruction of value over the last decade from this owner of Indian power stations. Forecasts are unchanged today, but suggest flat revenues and a lower pre-tax profit than last year. The algorithms style this as a contrarian stock and I can see this argument. But I think there’s also a risk that OPG is a value trap; I’d view this as a special situation requiring very careful research before taking a strong view. I can’t get higher than neutral. | |
Conygar Investment Co (LON:CIC) (£17m) | NAV +4.4% to £63.8m (107.5pps). H1 profit of £2.7m. A loan due Mar 25 has been extended to Dec 25. | ||
React (LON:REAT) (£17m) | H1 rev +14%, adj EBITDA +12% to £1.4m. Loss of 1.18pps. FY25 now to be below expectations. | AMBER/RED (Roland) [no section below] Today’s half-year results look poor to me. Last year’s debt-funded acquisition of drainage contractor Aquaflow has pushed the business to an H1 loss and the company now warns of sluggish order conversion, warning on full-year profits. React has a patchy record of profitability. While its collection of operating subsidiaries may include some attractive businesses, management empire building has delivered very little for shareholders – the share count has tripled since 2019, but the share price has fallen. I don’t see any reason to invest at this time. | |
Goldplat (LON:GDP) (£11m) | Ghana and SA achieved a combined Q3 PBT of £769k, including £90k of FX gains. |
Graham's Section
Inspired (LON:INSE)
Up 10% to 77.75p (£124m) - Potential Offer - Graham - PINK
This is a business advisor, helping companies to buy and optimise how they use energy.
It’s not one that we’ve covered very often. I see that I was RED on it back in Sep 2023, blaming its “balance sheet, debt, acquisition strategy and the presentation of its barely profitable results”.
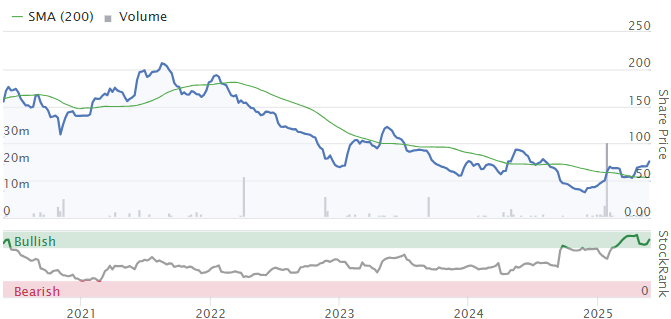
The share price at the time was 85p; I’m relieved to see that today’s takeover offer is below that level!
Its two largest shareholders control most of its shares:
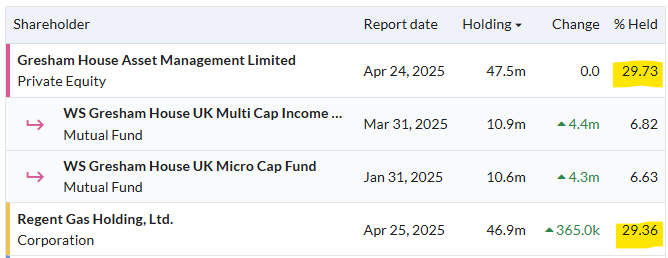
One of these - Regent - made a bid for the entire company last month at 68.5p, which was roundly rejected by the company and by the other major shareholder, Gresham.
Today the company announces that it has found a private equity buyer who is willing to make a possible cash offer of 81p.
They also say that the takeover would be structured so that it could go ahead without needing Regent to accept it.
The potential buyer is an American mid-market PE firm, HGGC.
Graham’s view - my assumption is that this deal will go through, perhaps unless Regent is willing to make a better offer.
Checking the recent full-year results for 2024, I see that the company is carrying significant debts (£59m) vs. its profitability (adj. PBT £12m).
In a situation like this, a takeover offer is often warmly received by small shareholders, so long as it is not viewed as being overly opportunistic. The new potential offer is 18% higher than Regent’s. As I’ve historically not been enamoured of this share, I would take the money and run.
Roland's Section
MTI Wireless Edge (LON:MWE)
Up 6.6% to 46p (£39m) - Q1 Results - Roland - AMBER/GREEN
MTI Wireless Edge Ltd (AIM: MWE), the technology group focused on comprehensive communication and radio frequency solutions across multiple sectors, is pleased to announce its financial results for the three-month period ended 31 March 2025.
Today’s first-quarter results from this Israeli technology group look fairly positive to me:
Revenue up 7% to $12m
Operating profit up 6% to $1.25m (10.4% margin)
Earnings per share +12% to 1.18 US cents
Net cash of $8.05m (31 Dec 24: $5.96m)
MTI’s operations are structured in three divisions, providing exposure to three industrial sectors that all appear to be benefiting from structural growth at the moment:
Defence;
5G mobile telecoms;
Water management.
Here’s what the company has to say about trading in each of its divisions.
Antennas: this business is described as a “one-stop shop for off-the-shelf flat and parabolic antennas”. It also produces custom designs.
Performance was strong in Q1:
Revenue up 22% to $4.04m
Segmental profit up 205% to $342k (8.5% margin)
These antennas are used for 5G mobile backhaul and for military use. 5G is seen as a big long-term growth opportunity in this business and MTI has a factory in India to target its large domestic market.
However, my impression is that the recent growth has been driven by increased military deliveries (mainly to the Israeli government), not the hoped-for surge in volume orders from 5G operators. Unfortunately we aren’t given a sales split between these two markets to provide extra clarity.
Water Control & Management: this business provides wireless systems under the Mottech brand for agriculture and municipal purposes (e.g. irrigation and fountains respectively). These solutions help users to save water and improve crop yields.
Sales rose in Q1, but profits fell due to a weighting to lower-margin projects. The company says the existing project pipeline should deliver improved profitability over the remainder of the year:
Revenue up 11% to $4.21m
Segmental profit down 23% to $446k (10.6% margin)
Distribution & Professional Consulting Services: this distribution business sells RF and microwave components to the defence sector and other industrial customers in Israel. Some products are later exported, so it’s hard to be sure how much revenue is derived from Israeli end users.
Q1 performance was weak as the PSK subsidiary (acquired in 2022) continued to drag on results:
Revenue down 7% to $4.02m
Segmental profit down 9% to $284k (7.1% margin)
PSK makes communication systems for defence and government clients and has required some additional support since its acquisition. But in another recent update, MTI indicated that the outlook could be improving:
[…] the Board believes that PSK has now resolved the issues it encountered in 2024 and has begun 2025 with a very healthy order backlog and a long pipeline of opportunities driven by Governments seeking to increase their investment in defence.
This view is reiterated in today’s Q1 results:
Overall backlog and pipeline of opportunities in both the traditional representation business and PSK is very strong which bodes well for the remainder of 2025.
Outlook & Estimates: CEO Moni Borovitz (whose family controls c.33% of the stock) sounds confident about prospects for the remainder of the year:
Overall MTI is in a good position, Q2 is progressing well with three material contracts wins announced so far and as a Board we are confident about the outlook for the year.
This view appears to translate into an outlook that’s in line with expectations.
With thanks to house broker Shore Capital, I can see that full-year forecasts are unchanged today, suggesting FY25 earnings of 5.1 cents per share.
Roland’s view
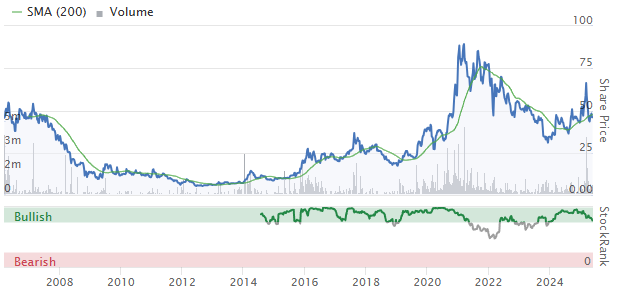
MTI has been a steady performer on AIM for many years:
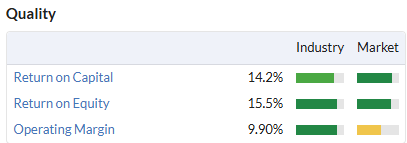
Quality metrics are also very respectable:
… and the dividend has proved very reliable, backed by a strong balance sheet and (perhaps) strong support due to family ownership:
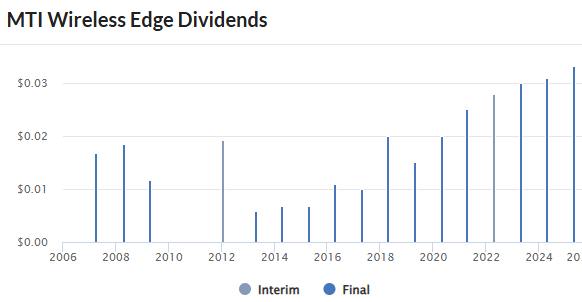
On the face of it, the stock’s forecast P/E of 12 and 5.5% dividend yield don’t look demanding. However, recent years’ growth has only been in single digits. I would also argue that the company’s foreign ownership, family control, and heavy single-country exposure may justify a modest valuation discount.
Stockopedia’s algorithms view MTI as a Super Stock, but the StockRanks have been falling recently and are starting to look less compelling to me.
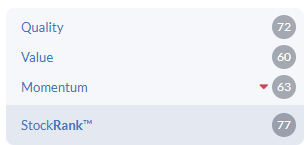
On balance, I’m going to leave my previous AMBER/GREEN view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
I hold Churchill China (LON:CHH) noticed a very significant 8.11% rise today any ideas as to what might be be the reason behind the jump in price?
Could be the “100 days Trump Plate” but unfortunately a bit costly to export to its followers.
Spectra Systems (LON:SPSY)
Rather intriguing after hours RNS announcing the appointment of a new Finance Director (non Board position).
Previos incumbent, Edward Spies, was in situ for 2 years. The new FD 'is replacing Mr Spies pursuant to his separation from the company'.
Sounds rather like the FD was sacked. Can't see any previous commentary suggesting that the FD might be leaving. Looks a rather unsatisfactory explanation.
Perhaps he will end up at MI6.
Goodness my Value Momentum portfolio is finally getting some real Momentum and realising some Value today!
Cavendish (LON:CAV) seems to be moving up quite rapidly over the last week. No news that i can see and no update planned until mid July. Is it just moving up with a general improvement in sentiment in small caps of have i missed a broker upgrade. Any views greatly appreciated. I'm a patient holder
I'm a holder of Cavendish (LON:CAV) - sentiment is changing in relation to small caps and also UK - we are hopefully coming out of a long term bear market in AIM and therefore the IPO market should pick up. It is a geared play on UK small caps similar to the the fund managers. I bought because I thought we had reached a nadir in the markets and sentiment should improve at some point. It also has a decent balance sheet.
Informative article in the Telegraph today about wind theft - the growing problem with the development of numerous offshore windfarms. Scientifically described as "the wake effect", it occurs when one wind farm interferes with the production capability of another.
The Telegraph reports that around 20 gigawatts of wind projects are now under dispute with the issue seeming to be mainly in the North Sea with some additional problems in the Irish Sea.
I recall that Orsted had recently discontinued its Hornsea 4 project as the project was becoming economically questionable which begs the question how far wind can continue to be part of a cheap energy strategy.
It's not a sector I am familiar with but would guess that there is probably some read across to renewables at some stage.
WAY off topic but I remember discussing a similar issue about humans extracting energy from the tides, with a physicist. Obviously there's no such thing as free energy, wind and tidal energy comes from somewhere. Winds are created from the heat of the sun and tides from the earth/moons gravity.
My query at the the time was, isnt the daily moving 'F'ing LARGE oceans going to require a fair chunk of energy - which must impact the moon big time? Turns out the earths oceans tide has more of a pendulum effect, and so fairly energy efficient in moving it to and fro and not impacting our moon too much. (although it does mean we spin 17micro seconds a year slower, while the moon drifts off 4cm).
So my predication is the Card Factory (LON:CARD) share price will reach fair value once the moon is but a dot in the sky...
This is very well known science and I'd be absolutely shocked if wind farm designers didn't already know all about it It is known as 'dirty air' in sailing circles and wake turbulence in aviation. It's why you could always tell when Concorde was coming in to land at Heathrow because there'd be no other planes on approach to the airport in advance of its arrival. Giving it a stupid name lke 'wind theft' is just typical of the green lobby.
The UK has considerable natural resources including in the form of wind and marine. From energy resilience (security of supply, long term price, and balancing the grid) and net zero perspectives, diversification is likely to be really important. Over reliance on any one energy source is therefore likely a risk and will increase volatility in price and supply. As one sector, in this case wind, has increased quite significantly in recent years, we should probably also be considering how we balance it with other generation sources. There are useful websites, eg Drax (LON:DRX) Electric Insights (I don't hold), that gives a recent (last 30 minutes) snapshot of UK energy generation if you want to see where are electrons are currently coming from. Its fairly peak time in the evening as I write this, and wind and gas are currently contributing the most, both at 30% of our generation capacity. Solar (PV) is interesting because it is the closest of any renewable to following Moore's law (its based on silicon), and we will need biomass for chemical feedstocks and for broader decarbonisation of fossil fuels (which are just ancient biomass). Marine, given the size of our coastline, seems to currently be a missed opportunity, although its a challenging environment. So probably in terms of investing in, as well as building, energy and renewables, diversification is an appropriate strategy, but these themes will likely take a long time to fully play out.
SRT Marine Systems (LON:SRT) I hold
Following on from my earlier post, this note is worth a read. It makes the point that SRT currently have 5 active projects (for anyone who thinks this is a one off).
"Today’s announcement means the company is delivering on five active projects worth £334m with consummate revenue and cash receipt over the next 12-36 months, with further significant upside in the medium to long term, underpinned by management confidence in conversion of the £1.2bn validated sales pipeline from both new and existing customers over the next financial year.
https://www.sqcresearch.com/po...
Some photos from SRT web site
https://srt-marine.com/about/g...
Spike continues in Jupiter Fund Management JUP - up 8% to 88.5p this morning, despite no fresh news - marking s 50%+ rebound since April.
Jupiter Fund Management (LON:JUP)
I thought the RNS announcement on 22 May about £15 million of annualised cost savings was very interesting. Seemed like the board was trying to get its retaliation in first !
This is the trend for many investment vehicles, atm.Impax Asset Management (LON:IPX) Aberdeen (LON:ABDN) , Liontrust Asset Management (LON:LIO) long may it continue…
Any AstraZeneca (LON:AZN) holders here should be aware of what the Times reported on Saturday: the company is not exactly holding the moral high ground, it's swimming in the swamp. https://www.thetimes.com/artic...
I think companies trading in Russia stink. Wish the government would do more to clamp down on this. Astra had sales of £29 billion in Russia last year.
I think the problem is that exiting writedowns, penalties and heavily discounted property sales = big hit to profits and therefore, the share price, so they are trying to protect shareholder value. I’m sure they had wished that the invasion of Ukraine would have ceased yonks ago or they might have taken a different stance but now its a b it late and they are just praying an end comes quickly from here. From a moral point of view its indefensible from an investor protection strategy I can see where they’re coming from.
Total sales for Astra of $58 billion in 2025, clearly they don't have sales of £29 billion in Russia. There is at least a reasonable debate to be had about whether denying patients life saving cancer treatment to apply pressure on Russia is the right thing to do
£29 billion?
I don’t think so
All the best
It also does a lot of business in another country that is daily killing women and children, how does that smell to you ?
SRT Marine Systems (LON:SRT) I hold, in spades
The 167 m Euro Indonesian project has started not only validating SRT's system but also the faith of its shareholders. I believe there is no comparable system yet in existence and isn't it wonderful to see a minnow based in Somerset succeeding in selling a nationally critical system to a foreign government.
SRT says:
"This project delivers a sovereign national capability owned and operated by the government of Indonesia that enables them to build up a massive national dataset within a system they own, control and operate that has highly configurable functionalities to provide deep insight. Furthermore, the flexible AI powered architecture of the SRT-MDA System enables them to continue to grow and evolve the system in the future alongside their ever-changing operational needs and scale."
Over the years many have called SRT a jam tomorrow company - well tomorrow has just arrived!
Could be, and definitely an interesting company, but really they need to get themselves a new scriptwriter. SRT Marine Systems (LON:SRT)
The jam is certainly getting closer, but I'm not sure its a home run just yet. How about the execution risks on delivering this project? Not to mention potential cost overruns, unforeseen delays, risk of onerous contracts etc, etc. SRT Marine Systems (LON:SRT) is the most 'overpromised' and 'underdelivered' sock I have ever encountered in the UK market so I shall cross my fingers for you that this time is different!
Q1 earnings release tomorrow. Obviously eagerly awaited as could be catalyst for rerating of shares, as they are very cheap.
There isn't any news on Serabi today I'm missing, is there?! It's interesting that this is currently the #1 most viewed stock on the website this morning - despite apparently having no news.
As far as I am aware there is no news but for all the reasons detailed by Caulkhead the investment case for Serabi Gold (LON:SRB) is hard to ignore.
Morning SCI20,
Re. Serabi Gold (LON:SRB) - just to amplify Caulkhead's comments below, I believe the report he has posted is AI-generated, not the outcome of his personal analysis (or the work of another human analyst).
Regards,
Roland
Understood but valuable non the less. The report does highlight both bull and bear points and appears to cover all known angles.
That’s right Roland.
No news! I just thought it was an interesting exercise and of course the best time to investigate is when it’s not on everyone’s radar.
And it has a Stockrank of 100!
I would be careful with the below analysis which isn’t much more than interpretation of current numbers. Obviously they are strong after the rise in gold but what catches you out in stocks like Serabi Gold (LON:SRB) are disputes over mining rights. These have reared their head normally when shares are under pressure. I would be careful - historically they miss all their somewhat wild production targets.
Hi Graham, it appears from Sockopedia that results are tomorrow, hence the interest. Plus with it having such a high ranking and low PER its coming up on many people seives (I hold) :
Wednesday, May 28th 2025
Q1 2025 Serabi Gold PLC Earnings Release
Thanks for that, Oaktreee. I am not trying to police what people talk about here - just curious!
Serabi Gold (LON:SRB) I asked AI to write a detailed report on Serabi from the perspective of a cynical mining analyst with fifty years experience. It’s a bit long but I thought it was interesting.
Serabi Gold: A Sceptical Assessment of a Brazilian Gold Miner’s Prospects
After five decades of watching gold miners come and go, promise the moon and deliver fool’s pyrite, I’ve approached Serabi Gold plc with the appropriate level of cynicism that only comes from seeing too many “next big things” turn into the next big disappointments. However, the confluence of factors surrounding this Brazilian-focused gold producer presents an intriguing, if complex, investment proposition that merits serious examination. The company’s recent financial performance, combined with an extraordinarily bullish gold price environment and Brazil’s evolving mining landscape, creates both compelling opportunities and significant risks that demand careful analysis.
Current Financial Performance and Operational Metrics
Serabi’s 2024 audited results demonstrate the kind of operational momentum that makes an old cynic sit up and take notice. Revenue jumped 48% to $94.5 million from $63.7 million in 2023, driven by both increased production and higher realized gold prices averaging $2,407 per ounce compared to $1,945 in the prior year. More impressively, EBITDA surged 160% to $35.9 million, while post-tax profit rocketed 321% to $27.8 million. These aren’t the marginal improvements typical of struggling miners—this represents genuine operational leverage.
The company’s production profile shows steady growth, with 37,520 ounces produced in 2024 versus 33,153 ounces in 2023. Cash costs remained relatively stable at $1,326 per ounce compared to $1,300 previously, while all-in sustaining costs (AISC) increased modestly to $1,700 per ounce from $1,635. For 2025, management guides for 44,000-47,000 ounces with ambitious targets of 60,000 ounces by 2026. The balance sheet strengthened considerably, with cash holdings increasing to $22.2 million from $11.6 million, resulting in net cash of $16.2 million.
What’s particularly encouraging from a cash generation perspective is the company’s announcement of a new shareholder return policy targeting 20-30% of free cash flow for dividends or buybacks. After years of zero dividend payments, the company projects dividend payments beginning in 2025. However, seasoned analysts know that dividend promises from junior miners often evaporate faster than morning dew when operational challenges arise.
The Golden Backdrop: Extraordinary Price Forecasts
The gold price environment presents perhaps the most compelling aspect of Serabi’s investment thesis. Major financial institutions have issued forecasts that would have been considered fantasy just a few years ago. Goldman Sachs predicts gold reaching $3,700 per ounce by end-2025, up from their previous $3,300 target. JPMorgan sees gold hitting $4,000 per ounce by Q2 2026, supported by continued central bank buying averaging 710 tonnes quarterly. UBS has revised their forecast to $3,500, while some analysts predict gold could reach $5,155 by 2030.
These aren’t isolated predictions from perennial gold bugs. The forecasts are driven by fundamental factors including persistent inflation concerns, central bank diversification away from US assets, geopolitical tensions, and the anticipation of Federal Reserve rate cuts. With gold already breaking through $3,000 per ounce and achieving 28 new all-time highs in 2025, these targets appear increasingly achievable.
For Serabi, operating with cash costs around $1,326 per ounce, even conservative gold price scenarios of $3,000-3,500 per ounce would generate substantial free cash flow. At $3,500 gold, the company would achieve operating margins exceeding 60%, transforming cash generation capabilities dramatically. However, experienced analysts know that high gold prices can also inflate costs industry-wide, as suppliers, contractors, and workers demand their share of the windfall.
Brazilian Political and Economic Landscape
Brazil’s political and economic environment presents the most significant risk factor for Serabi’s operations. The country faces substantial macroeconomic challenges heading into 2025, with inflation expectations drifting above target and the central bank raising rates to combat overheating. The Brazilian real depreciated 22% in 2024, contributing to inflationary pressures that forced the central bank into defensive monetary policy.
President Lula’s administration struggles with fiscal credibility, as mounting debt concerns and expansionary fiscal policy have undermined market confidence. Brazil’s debt-to-GDP ratio stands at 78%, with a fiscal deficit approaching 8% of GDP. The SELIC rate could peak at 14.75% by May 2025, creating the highest real interest rates in 20 years. These conditions typically create headwinds for commodity investments and foreign capital.
However, Brazil’s mining sector benefits from several mitigating factors. The country ranks among the world’s top five mineral producers, with a diversified resource base including significant gold reserves. The government recognizes mining’s strategic importance for export revenues and has implemented measures to support the sector, including streamlined licensing for strategic minerals projects. Brazil’s environmental regulations, while strict following the Brumadinho and Mariana disasters, have positioned the country as a leader in sustainable mining practices.
From a geopolitical perspective, Brazil’s relatively lower exposure to US trade tensions compared to other emerging markets provides some insulation. Exports to the US represent only 1.5% of GDP, with an effective tariff rate of just 8.7% after exemptions. This positions Brazil better than many countries amid escalating global trade tensions.
Operational Risks and Sector Challenges
Despite strong recent performance, Serabi faces typical challenges confronting mid-tier gold miners in Brazil. The company operates the Palito Mining Complex and the Coringa Project, both underground operations in Para state. Underground mining carries inherent operational risks including ground conditions, water management, and ventilation challenges that can quickly impact production and costs.
The company’s production guidance of 44,000-47,000 ounces for 2025 represents meaningful growth from 2024’s 37,520 ounces, requiring successful execution of development programs at both operations. Capital expenditure requirements for achieving the targeted 60,000 ounces by 2026 will test management’s ability to deploy capital efficiently while maintaining cost discipline.
Brazil’s regulatory environment, while improved, remains complex. The National Mining Agency (ANM) oversight requires ongoing compliance with environmental and operational standards. Local community relations, environmental permitting, and infrastructure limitations represent ongoing operational challenges that can impact production timelines and costs.
Labor costs in Brazil have been rising, supported by minimum wage adjustments and tight labor market conditions. Energy costs, logistics expenses, and taxation levels remain elevated compared to other mining jurisdictions, potentially constraining margin expansion even in a high gold price environment.
Financial Structure and Capital Allocation
Serabi’s balance sheet transformation deserves recognition, moving from marginal cash generation to robust free cash flow. The company’s net cash position provides financial flexibility rare among junior miners, enabling continued development investment without immediate refinancing needs. However, the ambitious production targets will require sustained capital investment, particularly for underground development and processing infrastructure.
The announced dividend policy represents a positive development, signaling management confidence in sustainable cash generation. However, mining companies’ dividend track records often disappoint when operational challenges arise or commodity prices decline. The company’s historical zero dividend payments through 2024 reflect the challenges of maintaining consistent cash generation in the mining sector.
Working capital requirements will likely increase with higher production volumes, while inflationary pressures in Brazil could impact both operating and capital costs. Currency exposure remains a consideration, as operations generate revenue in US dollars while incurring significant costs in Brazilian reais. The real’s volatility adds complexity to cost forecasting and margin projections.
Market Valuation and Investment Considerations
Current analyst consensus suggests a price target of $3.07, representing approximately 50% upside from recent trading levels. With three brokers covering the stock and an analyst consensus leaning toward “Hold,” institutional attention remains limited. This lack of coverage often characterizes mid-tier miners but can also represent opportunity for investors willing to conduct independent analysis.
The company’s enterprise value relative to production and reserves appears reasonable compared to peer companies, particularly considering the operational momentum and improving financial metrics. However, valuation multiples for gold miners can compress quickly when operational issues arise or gold price expectations moderate.
Liquidity considerations warrant attention, as the stock trades with relatively modest daily volumes that could impact position sizing for larger investors. The company’s dual listing on AIM and TSX provides some diversification of investor base, though neither exchange typically generates substantial institutional liquidity for smaller miners.
Conclusion and Risk Assessment
After decades of analyzing mining companies, Serabi Gold presents an unusually compelling combination of operational momentum, favorable commodity backdrop, and reasonable valuation. The company’s demonstrated ability to generate substantial cash flow improvements, combined with extraordinary gold price forecasts from major financial institutions, creates significant potential for returns.
However, the investment requires accepting Brazil’s political and economic volatility, operational execution risks inherent in underground mining, and the perpetual uncertainty surrounding commodity price movements. The company’s success depends heavily on management’s ability to achieve ambitious production targets while maintaining cost discipline in an inflationary environment.
For investors with appropriate risk tolerance and portfolio diversification, Serabi offers leveraged exposure to what could be an extraordinary gold price environment over the next several years. The key risks—Brazilian political instability, operational execution, and potential gold price moderation—are identifiable and can be monitored. The key opportunities—dramatic margin expansion in a higher gold price environment—are substantial and increasingly probable based on current market dynamics.
The cynical analyst in me remains cautious about any mining company’s promises, but the current confluence of factors suggests Serabi deserves serious consideration despite the inherent risks of Brazilian mining exposure.
Thank you Caulkhead. This level of detailed analysis is the reason why Stockopedia and its contributors is such an essential investing tool. “For investors with appropriate risk tolerance and portfolio diversification, Serabi offers leveraged exposure to what could be an extraordinary gold price environment over the next several years.” For these very reasons Serabi Gold (LON:SRB) is my largest holding
its just a cut and paste job from chatgpt, not sure i would call this "detailed analysis"
Does Mr AI "hold" be good to know .
Detailed yes but the analysis anyone could do. Now, how about one for Hochschild Mining (LON:HOC) which I also hold. One thing speculators might like to keep in mind is the AISCs of producing gold miners, they seem to be smaller in African mining to me. Perhaps I'll ask ChatGPT to check that out.
Would personally prefer this board not cluttered up with very long AI generated posts - people can easily run their own AI queries if they're interested in that, but no need to post them here.
Although this is a very interesting article, it would interesting to have this AI generated analysis fact checked from which the results are reproduced here at Stockopedia.
I did a very similar exercise on Filtronic (LON:FTC) using Deepseak. Although incredibly detailed after several in depth questions, I did question where some of the facts came from as I could not prove the existence of them in the public domain. It almost felt a smattering of insider knowledge.
Would be interested to hear in what other investors experiences have been especially on their fact checking results.
I ran a chatGPT query on the possible connection between Michael Carvill and the OIA re Kenmare Resources (LON:KMR) . In the response chatGPT said that Carvill and Oryx had dropped their proposed bid for Kenmare. There being no RNS stating this, I questioned chatGPT on its source for this statement. It confessed that it had none and complimented me for my persistence on fact-checking! Caveat emptor.