Daily Stock Market Report (Tue 29th Sep 2026) - CARD, ZIG, SUS, BMS, SNWS, BAG

Good morning! No major overnight news to report; the big story yesterday was the new Your First Home Scheme (essentially the new version of Help to Buy).
Scores on the doors at the end of yesterday:
Persimmon (LON:PSN) up 14.7%
Barratt Redrow (LON:BTRW) up 11.7%
Taylor Wimpey (LON:TW.). up 11.5%
Crest Nicholson Holdings (LON:CRST) up 11.0%
Vistry (LON:VTY) up 10.7%
We won’t get full details on the scheme until Budget Day on October 28th. The main points are that it applies to England only, that only a 2.5% deposit will be required, and that the government will also put in a 20% loan, so that the remaining mortgage will be for just 77.5%.
Asking home buyers for just a 2.5% deposit on a starter home sounds risky to me, but from an investment point of view this is clearly going to make life a bit easier for housebuilders - it’s a more generous scheme than Help to Buy, and (as with Help to Buy), any losses on these loans will be shared with the taxpayer!
Overnight market movements:
The FTSE is up 0.2% at 10,725
S&P 500 is down 0.1% at 7,675
Brent crude (December) is up 1.7% at $99.50/bbl
Gold is up 0.7% at $4,145/oz
Bitcoin is up 0.4% at $83,800
The Agenda is complete - update 10.30: added details of Vesuvius takeover situation.
All finished for today! Cheers.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£194bn | SR56) | AstraZeneca announces equity investments in Summit | AstraZeneca has entered into an agreement to invest $2 billion in newly issued equity in Summit Therapeutics Inc. to accelerate the development of ivonescimab, a first-in-class bispecific antibody targeting PD-1 and VEGF, in combination with antibody drug conjugates (ADCs) across tumour types. | |
ZIGUP (LON:ZIG) (£991m | SR88) | Performed well over the first four months of the financial year …we expect our adjusted PBT for the year to be at the top of the current range of market expectations of £163.2 - £170.0m. | GREEN = (Roland) Zigup appears to have nudged full-year profit guidance slightly higher today, so I’m maintaining my positive view despite my feeling that this business should be relatively cheap. Growth in the Spanish business remains strong and I’m encouraged by the growth of the UK incident management operation. With a 6%+ yield and single-digit P/E, I think it’s fair to remain positive. | |
| Vesuvius (LON:VSVS) (£929m | SR71) | Response to Media Speculation | The company confirms that since September 2025 it has received a series of unsolicited and non-binding indicative takeover proposals from RHI Magnesita (LON:RHIM) . The latest of these is valued at 551p, comprising 470p per share in cash and 0.28 new RHIM shares for every 10 VSVS shares. | TAKEOVER |
A.G. Barr (LON:BAG) (£671m | SR54) | Growth ahead of the soft drinks market driven by core brand performance. On track to meet full year market expectations. | AMBER/GREEN ↓ (Graham) | |
Close Brothers (LON:CBG) (£582m | SR35) | CEO remains “fully committed to returning the group to double-digit returns by FY 2028, rising thereafter." FY26 operating loss £60m. Adjusted operating profit £120m (FY25: £144m). | ||
Acceler8 Ventures (LON:AC8) (£512m | SR20) | Sports Lottery+ approved by Jiangxi Sports Lottery to launch within China Mobile business halls and shops in Jiangxi Province. | ||
PayPoint (LON:PAY) (£371m | SR96) | Capital Markets Day sets out growth drivers underpinning medium-term ambition | Trading has continued in line with expectations. | |
Newriver Reit (LON:NRR) (£335m | SR83) | New retail park capital partnership with affiliates of Soilbuild and United Engineers (two Singapore-based real estate investors). First acquisition: The Springs retail park in Leeds, for £73.5m from Legal & General. NewRiver holds a 25% interest in the Capital Partnership, resulting in a net equity investment of £9.3m following completion of a loan facility. | ||
Niox (LON:NIOX) (£276m | SR51) | Revenue £24m (H1 2025: £25.2m). Adjusted EBITDA £8.3m (H1 2025: £9.2m). “The Board remains confident of delivering full-year revenue and adjusted EBITDA in line with current consensus market expectations.” | ||
Altyngold (LON:ALTN) (£272m | SR75) | Revenue up 64.6% to $115.2m. Average realised gold price up 50.3%. EPS up 58.4% to 156.38 US cents. The Company remains on track to meet its full-year production guidance of 52-55Koz. | ||
Card Factory (LON:CARD) (£240m | SR88) | Revenue +5.3%. Adjusted PBT down 3.8% (£12.7m). Net debt excluding leases £87.4m. "We are confident of delivering full-year expectations…” | AMBER/GREEN = (Roland) A solid set of H1 results leave this retailer in line to meet full-year expectations. Encouragingly, LFL store sales have turned positive so far in H2, potentially positioning the business for a decent festive period. The caveat to this is that more than 75% of earnings need to be generated in H2, so visibility is by definition quite limited. On balance, I think these risks are reflected in the low valuation and high dividend yield, so I’m quite comfortable with our moderately-positive view. | |
S&U (LON:SUS) (£239m | SR67) | Revenue: £57.3m (H1 2025: £51.8m). PBT £15.7m (H1 2025: £15.6m). “St Paul’s letter to the Galatians reminds us that as we sow, so shall we reap.” | GREEN = (Graham)
I’ve been a fan of this business for a long time and I’m very much inclined to stay GREEN on it today. The major attractions remain, namely, a cheap earnings multiple and a discount to book value, for a family-owned business with many decades of heritage and continuing family involvement. Looking forward, the company remains hugely ambitious to grow. The new £600m securitisation deal will allow for massive additional scale which should prove to be a helpful tailwind for their ROE. | |
Wilmington (LON:WIL) (£228m | SR66) | Ongoing revenue +37%. Ongoing adjusted PBT +15% (£30.1m). Statutory continuing PBT +11% (£18.2m). “Early Group trading in FY27 has seen a continuation of the momentum built in FY26… we are well positioned for continued growth and on track to achieve market expectations." | ||
Tribal (LON:TRB) (£214m | SR84) | Jenzabar announces a possible cash offer of 111p per Tribal share. This represents a 5.7% premium over the c.105p per share offer currently being recommended by the board. | TAKEOVER | |
CLS Holdings (LON:CLI) (£180m | SR25) | Unconditional exchange of Fangdieckstrasse 75, 75a and 75b in Hamburg for €25.35 million, 9% below the latest valuation. “...we consider this the right time to dispose of the asset, further focusing our German portfolio and reducing debt.” | ||
Smiths News (LON:SNWS) (£167m | SR95) | Demand for collectables stronger than expected in H2, plus record contribution from the World Cup of over £3m. FY2026 results now expected to exceed market expectations. Expectations were for adjusted operating profit of £37.2m. Trading has started positively in FY27. | GREEN = (Graham)
I was GREEN on SNWS already: they have just announced they are beating forecasts for FY26, and the valuation remains very undemanding. So clearly, I’m staying GREEN on this today. The dividend per share (5.5p) is well-covered by earnings per share of over 10p, and cash flow generation has been excellent. The company has recently been reporting net cash balances, having previously been in net debt. | |
Helios Underwriting (LON:HUW) (£159m | SR62) | Net asset value total return for H1 is 17p per share (6.5% increase), including a 10p dividend (7p base / 3p special). NAV at half year of £2.70. PBT £11m (H1 2025: £4.4m), driven by improvement in estimated syndicate profits. The outlook for the Lloyd’s market for 2026 remains positive. | ||
KEFI Gold and Copper (LON:KEFI) (£85m | SR8) | On 4 September 2026, a serious security incident at the Tulu Kapi Gold Project resulted in multiple fatalities, including a Company employee. During H1, full development of the Project was launched. The comprehensive loss in H1 was £4.6m, reflecting an increase in administration expenses. | ||
Venture Life (LON:VLG) (£81m | SR61) | Final results for 17 month period. Revenue £50m. Adjusted EBITDA £7.9m. Loss per share 2.98p. CEO intends to retire from 31 Dec 2026. Will be succeeded by the current CFO. | ||
Made Tech (LON:MTEC) (£75m | SR69) | Revenue +27% to £58.9m with pre-tax profit +141% to £4.7m. Adj EPS +72.5% to 2.38p. Outlook: contracted backlog has increased to £115m at 31 July, from £83.5m at 31 May (y/e). Expects FY27 adj EBITDA of £6.3m to £6.6m. | ||
Braemar (LON:BMS) (£74m | SR78) | H1 revenue +16% to £74.3m with underlying operating profit +7% to £6.0m. Results supported by “a strong rate environment”. Forward order book stable at $73.4m (FY26: $72.5m). Outlook: confident of delivering in line with market expectations for the full year. | AMBER ↑ (Roland) Shipping brokers are enjoying strong market conditions at the moment, thanks to the situation in the Middle East. Against this backdrop, this H1 update looks relatively subdued to me. Certainly performance is lagging far behind that of sector leader Clarkson (disc: I hold). I wonder if Braemar lacks the scale or market presence that’s needed right now. While earnings are expected to be substantially higher next year, I’m a little disappointed by this H1 outturn. A low valuation means there is still some opportunity here if performance improves, but I share the StockRanks’ neutral view of this business. | |
Billington Holdings (LON:BILN) (£61m | SR83) | H1 revenue +29% to £54m with pre-tax profit +70% to £2.84m. EPS +66% to 16.3p. Cash of £12.6m at 30 June 26. Outlook: record order book “providing excellent visibility into 2027”. Full-year results to be in line with expectations. CEO will retire on 1 Jan 27, to be replaced by the current COO. | ||
Poolbeg Pharma (LON:POLB) (£56m | SR26) | H1 net loss of £1.9m with cash of £4.8m and a further £3.5m raised post period end. TOPICAL trial initiated following MHRA authorisation, with eight of c.30 participants dosed to date. | ||
Ondine Biomedical (LON:OBI) (£55m | SR7) | Mela Solutions will customise its data platform (used in 90% of NHS ICUs) to allow hospitals to “rapidly evaluate Steriwave nasal photodisinfection” against their own baseline metrics. Targeting 6-10 hospitals in the first year. | ||
Vulcan Two (LON:VUL) (£53m | SR18) | Revenue of £10m from acquisitions in March. Gross profit for the period of £2.2m with H1 adj EBITDA loss of £(0.6)m. Changing company name to Molecule Group. | ||
Ariana Resources (LON:AAU) (£40m | SR26) | H1 pre-tax profit of £6.248m (H1 25: £0.151m), with partial sale of the Company’s interest in Zenit for $19.5m. Revised Dokwe PFS demonstrates a long-life, low capital cost, high margin gold production occurring in two phases. | ||
Zanaga Iron Ore (LON:ZIOC) (£36m | SR28) | H1 net loss of $4.2m with cash of $5.4m. Project development work continues. | ||
Amigo Resources (LON:AMGO) (£36m | SR76) | High-grade potassium and associated rare earth enrichment confirmed by first-pass surface sampling at the Musensi Hill block, south-west Tanzania. | ||
Jersey Oil and Gas (LON:JOG) (£33m | SR23) | H1 net loss of £827k, with cash reserves of £10.1m and no debt. Work underway to submit GBA licence extension requests later this year. | ||
Kendrick Resources (LON:KEN) (£30m | SR17) | A total of 90 drill holes have been completed to date, 38 diamond and 52 reverse circulation ("RC") drill holes. Continuous LREO grade and combined mineralised width intercepts include 5.08% over 20m, 4.85% over 23m, 4.30% over 15m, 4.28% over 26m, 3.37% over 40m, 3.36% over 48m and 3.27% over 46m. | ||
Tortilla Mexican Grill (LON:MEX) (£28m | SR59) | H1 revenue +5.9% to £38.5m with systems sales of £100.9m on a trailing 12-month basis. UK LFL sales +13.9% in H1. Adj EBITDA of £502k with pre-tax loss reduced to £(1,605,000). | ||
Atome (LON:ATOM) (£28m | SR n/a) | The delayed FY25 and H1 26 accounts previously due to be published on 30 Sept 26 are now expected to be published on 2 Oct 26. | Shares are currently suspended. | |
Energypathways (LON:EPP) (£19m | SR n/a) | H1 net loss of £2.0m with cash of £840k at the end of H1. The future of the company “is dependent on the development of the MESH project” [a UK energy storage project]. Recent funding arrangements (£5m debt/£10m equity) are expected to support operations for 12 months but there is a material uncertainty about going concern status beyond this – further fundraising will be needed. | Shares are currently suspended. | |
Eden Research (LON:EDEN) (£18m | SR16) | “Since the beginning of 2025, Eden has continued to build on the momentum established and has made further progress in strengthening its position as an emerging leader in biological crop protection.” | ||
Tekmar (LON:TGP) (£17m | SR59) | Expects FY26 revenue to be “more than 20%” ahead of FY25. However, H2 growth has been slower than expected, with delays to some work. Full-year profits are now expected to be below previous expectations. Cavendish cuts FY26E adj EPS to -1.4p (prev. -0.08p). | ||
Petro Matad (LON:MATD) (£16m | SR11) | Net loss of $0.59m for H1 2026, with outstanding net receivables of $2.16m and cash of $2.76m. Production from Heron-1 and Gazelle-1 averaged 241 bopd in H1 with 41,941 barrels sold. | ||
Zoo Digital (LON:ZOO) (£16m | SR73) | The company is seeing “an increased demand for our tech-enabled services as well as new emerging opportunities for our business.” Outlook: H1 27 revenue to be at least $23m, ahead of H1 and H2 FY26 and in line with expectations. | ||
Pennant International (LON:PEN) (£14m | SR46) | Secured new Auxilium contracts in the US defence sector through its Siemens partnership. These are expected to generate aggregate revenue of >$300k/yr. ARR is now £3.1m, exceeding the £3.0m ARR target for 2026 provided in January. | ||
Ebiquity (LON:EBQ) (£14m | SR45) | Revenue -5% to £36.1m with adj pre-tax profit +334% to £1.8m. Adj EPS +212% to 0.45p. Outlook: currently on track to meet or exceed market expectations for full-year profit. | ||
Airea (LON:AIEA) (£12m | SR81) | H1 revenue +10.2% to £10.8m with pre-tax profit of £0.2m (H1 25: £0.04m loss). Sales volumes +7.4%. Outlook: expects current trading to continue through the remainder of the year. |
Graham's Section
S&U (LON:SUS)
Down 2% to £19.30 (£235m) - Interim Results - Graham - GREEN =
The chart here has been remarkably stable. I last looked at it in August, at the Q2 trading statement.
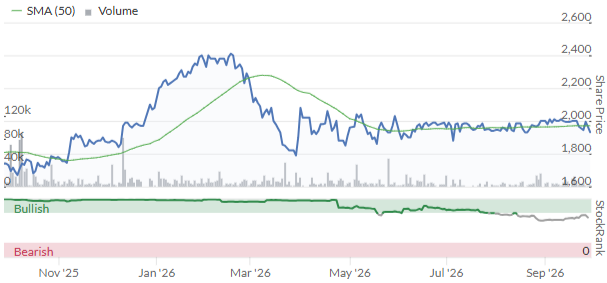
The Q2 statement assured us that things were going well, but today’s H1 results give us the details:
Revenue up 11% to £57.3m
PBT flat at £15.7m
Net receivables up 27% to £541m
Impairment charge flat at £8.2m.
I’ve emphasised the receivables line to show the enormous growth that the company has achieved over the past 12 months.
This is confirmed when we look at the company’s two divisions individually:
Advantage Finance (Motor Finance): advances to customers (£105m) are up by an enormous 49% compared to H1 last year. This reflects the changed regulatory situation, with the company now free to grow its business as usual.
Also worth highlighting that the impairment charge here (£7.5m) is lower than last year’s, and that live monthly repayments (92%) are also better than last year (90%).
Aspen Bridging (Property Bridging): although there has been no regulatory disruption here, conditions in the property market have not been helpful and S&U has been acting cautiously. Advances to customer (£102.8m) are down by a few percentage points compared to last year, and PBT falls from £5m to £4m. There is a slight rise in the impairment charge, from £0.2m to £0.6m.
Balance sheet equity has nudged slightly higher to £251m, a fully tangible figure, as post-tax profit of nearly £12m was offset by dividend payments of nearly £10m. It’s worth noting that this is higher than the market cap.
The first interim dividend will be 36p per share (last year: 35p).
Outlook: At the last update, Chairman Anthony Coombs quoted Abraham Lincoln. Today, he quotes St Paul.
St Paul’s letter to the Galatians reminds us that as we sow, so shall we reap. S&U’s recent trading and results reflect our determination to make the necessary investment at the right returns to maximise our rewards in the future. The economic and political backdrop remains uncertain, but S&U is well placed to navigate it. Current trends indicate our ability to do just that, to the benefit of our customers and shareholders.
Funding: S&U has borrowings of £285m out of total facilities of £330m, and needs access to a bigger facility to keep growing - “a possible additional requirement of up to £300m in the next three years”.
We are told just a little more about this today:
S&U has embarked upon a securitisation programme with two banking partners who together, will provide up to £600m of facilities at an improved rate over the next 3 years.
The combined deal will provide flexible and scalable funding in line with our credit appetite and methods of operation. It will also give certainty over the credit cycle and do so at a cost saving on S&U’s existing facilities. Over time, the deal should lead to an improved valuation of the Group’s loan book and its earnings.
Graham’s view
I’ve been a fan of this business for a long time and I’m very much inclined to stay GREEN on it today.
The major attractions remain, namely, a cheap earnings multiple and a discount to book value, for a family-owned business with many decades of heritage and continuing family involvement.
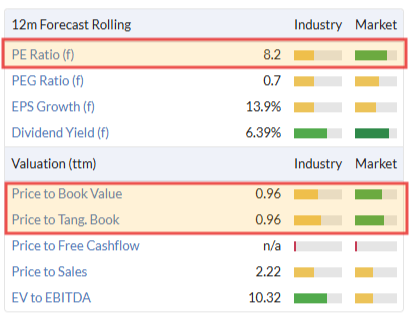
Returns have been suppressed in the last few years, in large part due to the FCA and broader market concerns around motor finance.
But looking forward, the company remains hugely ambitious to grow. This £600m securitisation deal will allow for massive additional scale which should prove to be a helpful tailwind for their ROE. So I continue to like the story here.
Smiths News (LON:SNWS)
Up 4% at 70.2p (£174m) - Post Year-End Trading Update - Graham - GREEN =
This cigar butt stock has evolved into what looks to me like it could become an interesting growth opportunity, but the share price doesn’t reflect it yet:
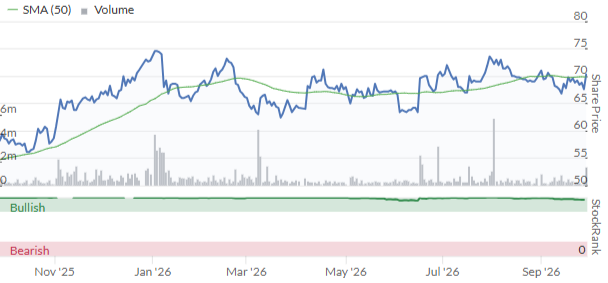
As a recap, this magazine/newspaper announced in recent months that far from shrinking, it’s expanding its distribution network to a fully national scale, having won several big contracts from major newspaper houses.
Today’s trading update continues the excellent news flow:
Smiths News (LSE: SNWS), the UK's largest news wholesaler and a leading provider of early morning end-to-end supply chain solutions, is pleased to report that it expects to deliver results for the 52-week period ended 29 August 2026… ahead of market expectations*.
Smiths distributes Premier League stickers, Match Attax cards, and the like. These high-margin products are highly profitable products for everyone who gets to touch them along their route to the customer. Demand for them was “stronger than expected” in H2.
On top of that, the World Cup boosted performance; every second year gets a boost to news and magazines from the World Cup or the Euros, so we can expect a slightly quieter summer next year.
The company helpfully tells us that market expectations were for adjusted operating profit of £37.2m.
Looking ahead:
Moving into FY2027, trading has started positively and the Company has begun its transformational programme to establish a national distribution footprint to service the new contract wins announced in H2 FY2026, ahead of the first go-live in July 2027.
Estimates
Thanks to Canaccord Genuity for publishing on Smiths News today. They’ve raised pre-tax profit estimates for FY August 26 by about £1m (the new adj. EBIT forecast is £38.6m, previously £37.5m).
Canaccord have cut their FY27 forecasts, but say they are doing that merely to bring their forecasts in line with consensus. Their new adj. EBIT forecast for FY27 is £36.1m.
Unfortunately, there is as yet no visible impact of the new contract wins on forecasts. These contracts will start to go-live in July 2027, in time for FY August 2028, but the adj. EBIT forecast for FY28 is unchanged at £35.9m.
Graham’s view
I was GREEN on SNWS already: they have just announced they are beating forecasts for FY26, and the share price hasn’t moved much. So clearly, I’m staying GREEN on this today!
The StockRanks love what they see:
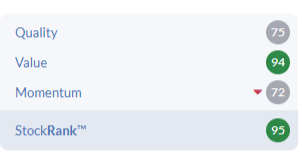
On the StockReport, the dividend yield (7.6%) is shown as higher than the P/E ratio (6.5x). Those numbers will adjust slightly based on today’s share price, but I just want to highlight that a dividend yield higher than a P/E ratio is a traditional sign of a very cheap stock.
The dividend per share (5.5p) is well-covered by earnings per share of over 10p, and cash flow generation has been excellent. The company has recently been reporting net cash balances, having previously been in net debt. So this is a strong GREEN from me.
A.G. Barr (LON:BAG)
Down 2.7% at 583p (£653m) - Interim Results - Graham - AMBER/GREEN ↓
A.G. BARR, the multi-beverage business with a broad portfolio of market-leading UK brands including core brands IRN-BRU, Rubicon and Boost, today announces its Interim Results for the 26 weeks ended 1 August 2026 (H1 26/27).
Euan Sutherland’s interesting CEO career has brought him to this company. It continues to do well:
Revenue +8.5% to £247m
Adjusted PBT +2.6% to £36.1m
I’m glad to see that statutory PBT is £33.0m, so once again, the results are quite clean. There were one-off costs associated with integrating one of the acquisitions, and the slight decline in statutory PBT is attributed to them.
It’s probably nothing to worry about, but the company’s cash position has crashed from £41m net cash a year ago, to £47m of net debt today. This is after they spent £53m buying Fentimans and Frobishers, while also spending big on capex. They seem relaxed:
Through the strongly cash generative nature of our business we expect to close the financial year in a small net-debt position.
They previously said that they’d be fine with a leverage multiple of up to 2.5x.
Annoyingly, the word “organic” can’t be found in today’s report. They made these two acquisitions in early 2026, and the report covers the six months to the end of July/early August. So an organic growth rate would be really helpful. They say they are growing ahead of the market, but I don’t trust this without a clear delineation of how much revenue was generated from the pre-existing business versus the acquired businesses.
Checking footnotes and the broker note, I see that Fentimans alone contributed £15m of revenue to these results. That seems to account for most of the revenue growth achieved by the company in the period. I really think this should be much clearer.
CEO Comment:
Looking ahead, we remain confident in the significant opportunities for the business and our ability to build on this momentum in the second half. With our acquisitions now fully integrated and our investment programme progressing well, we remain on track to deliver full year performance in line with market expectations. We will continue to focus on delivering above-market growth and creating sustainable long-term value for our shareholders.
These expectations are for 48p of adjusted EPS (source: ShoreCap).
Graham’s view
There have been a few wrinkles to performance here lately. The company has suffered from supply chain issues (now resolved) and seen its cash balances dwindle and reverse into debt. I can forgive these as temporary issues. But I can’t help the nagging feeling that the underlying growth here is not as good as you might think, especially considering the amount that has been spent on acquisitions and the company’s claim that it’s growing faster than the wider drinks market.
The good news is that they are still guiding for a ROCE of about 19%, which is fine.
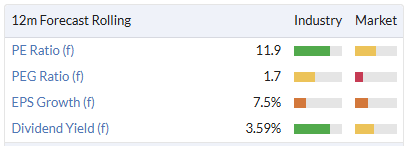
As I’m a little uninspired by these results, I’ll put us on AMBER/GREEN today. Hopefully I can put it back to GREEN again soon. I still think the shares offer pretty decent value:
Roland's Section
Card Factory (LON:CARD)
Up 3.7% at 75p (£247m) - Half-Year Financial Report - Roland - AMBER/GREEN =
This well-known high street retailer warned on profits late in 2025 due to lower high street footfall, but it’s not warned again since then and has been an interesting case study in StockRank recovery:
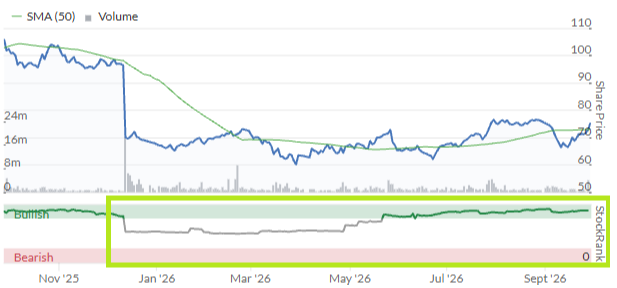
So far, Card Factory’s share price recovery has not really reflected the rise in its StockRank. But today’s results are in line with expectations and suggest the company could be well positioned ahead of the key festive trading period. Let’s take a look.
Half-year results summary
These accounts cover the six months to 31 July 2027. Any analysis of these figures has to carry the caveat that Card Factory’s profits are always heavily weighted to the second half of the year, for obvious reasons.
With that said, these numbers look fairly reasonable to me, if a little subdued:
Revenue up 5.3% to £582.7m, aided by the acquisition of Funky Pigeon
Store sales -0.7%, like-for-like store sales -2.0%
Adjusted pre-tax profit down 3.8% to £12.7m
Adjusted EPS up 1.6% to 2.9p
Interim dividend up 7.7% at 1.4p
While the decline in like-for-like (LFL) store sales seems a little disappointing, the company believes that changes made during the first half are now starting to deliver results, with LFL now positive:
We have been encouraged by trading since the half year, with UK store Like-for-likes improving from H1 levels and returning to positive growth in recent weeks. While it is still early in the period, this provides encouraging evidence that the actions implemented at the end of the period and beginning of H2, are gaining traction.
Wholesale was another positive in H1, with sales to retailers such as Aldi up by 13.6% during the period.
Card Factory’s model also appears to be working well in the Republic of Ireland, where total store sales rose by 24.3% and LFL sales were up 5.6%.
Cash flow and Balance sheet: we’ve had concerns about debt in the past, but although debt levels rose slightly during the first half, leverage remains acceptable (if not ideal):
Net debt up 10.8% to £87.4m vs H1 25
Covenant leverage (exc leases) of 1.1x EBITDA (H1 25: 1.0x)
The increase in debt reflects cash outflows on last year’s final dividend and the current share buyback programme. However, the majority of free cash flow is generated in H2 and forecasts suggest this should net out over the full year to deliver a reduction in year-end net debt.
Outlook
CEO Darcy Willson-Rymer sounds confident ahead of the key ‘golden quarter’:
We have strong Golden Quarter plans in place, supported by significant product newness, targeted value investment and an increased focus on driving customer traffic.
But not too confident! This is an in line outlook statement, with the usual risk that profits could be hit by a bad Christmas, as happened last year:
[…] the Board remain confident in expectations for Adjusted PBT in FY273, with performance weighted to H2 and the key Christmas trading period, as usual and as expected.
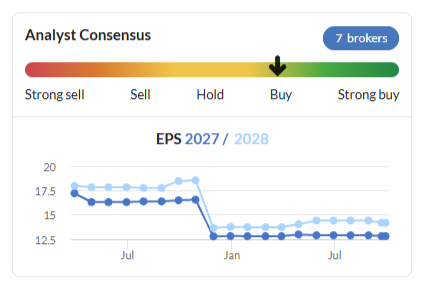
I can’t see any updated broker notes today, but consensus figures on the StockReport suggest full-year earnings of 12.8p, giving a similar 77% H2 weighting as last year.
Roland’s view
These results aren’t exactly sparkling and suggest trading conditions on Britain’s high streets remain challenging. However, Card Factory’s current valuation isn’t exactly sparkling either and suggests investors also remain quite cautious.
Against this backdrop, I think Card Factory’s valuation looks quite interesting:
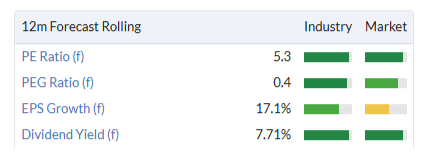
I am not surprised the StockRanks view this as a Contrarian play:
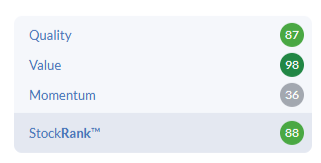
Although I think there’s still some risk that peak trading will disappoint, as it did last year, I am inclined to think Card Factory offers value at this level.
The company’s quality metrics look acceptable and my sums suggest the 7%+ dividend yield should be covered this year.
Growth isn’t strong enough for me to be fully positive, but I’m quite comfortable leaving our AMBER/GREEN view unchanged today.
ZIGUP (LON:ZIG)
Up 5% at 458p (£1.04bn) - AGM Statement - Roland - GREEN =
Shares in this van hire, fleet solutions and accident repair group are up by 5% today after a positive outlook statement in today’s AGM update:
[...] we expect our adjusted PBT for the year to be at the top of the current range of market expectations of £163.2 - £170.0m.
The main driver for this seems to be continued growth in the company’s Spanish business, continuing a theme I discussed in July’s full-year results:
Average vehicles on hire “more than 5%” ahead of last year;
Spanish fleet is now “in excess of 80,000 vehicles” (FY26: 78,000).
FMG (UK incident management) volumes are also said to be strong, aided by the recent renewal of a Motability contract “by one of our largest insurance partners”.
The UK & Ireland hire business (Northgate) saw revenue fall by 5% last year and my reading of today’s update suggests growth remains more challenging in Zigup’s home market – the company notes that “simplification actions are continuing at pace” in UK&I.
Roland’s view
I was positive on Zigup in July. Although my inclination would be to take an AMBER/GREEN view here, I am going to stay GREEN for now to reflect today’s positive nudge to guidance and the quite reasonable valuation:
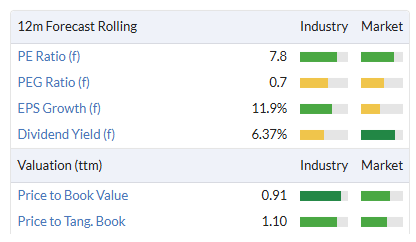
The StockRanks also support a fairly positive view, although they do reflect the somewhat average quality metrics of this capital-intensive business.
Braemar (LON:BMS)
Up 5.8% at 238p (£79m) - HY27 Trading Update - Roland - AMBER ↑
The last time we looked at this shipbroking business was in May 2025, when Braemar warned on profits. Much has changed since then, given the situation in the Middle East, so I think it’s probably time we updated our view on this business.
Braemar has a 28 February year end, so today’s update covers the six months to 31 August 2026,
Key points are positive, as I would expect given the impact of the situation in the Middle East:
Revenue up 16% to £74.3m, “driven by a strong rate environment”
Underlying operating profit up 7% to £6.0m, “after making £1.4m of strategic investments to drive future growth”
Net debt reduced to zero at 31 August 2026 (H1 26: £5.6m)
Strong forward order book of $73.4m (FY26: $72.5m)
Outlook - this is an in line update:
The board remains confident that the Group will deliver in line with market expectations for the full year. Increased volatility across shipping and energy markets has lifted average rates in our chartering business and underpins strong demand for our advisory and risk management services. We expect the strategic investments made in the first half, including senior hires and the establishment of our power desk, to convert to profitable growth in the second half.
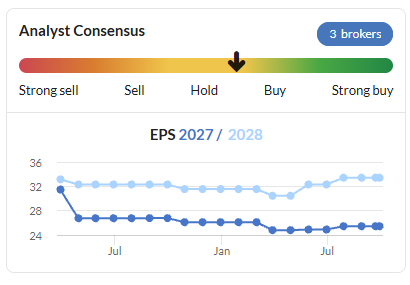
Broker forecasts have also reset somewhat since last year’s profit warning and appear to support the view that trading is expected to improve as a result of recent changes:
Roland’s view
The valuation looks undemanding for a business that’s returning to growth:
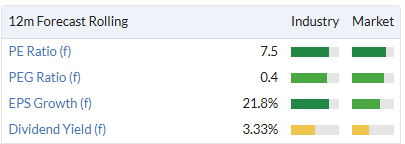
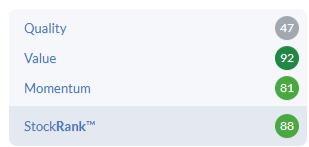
The catch is that quality and momentum are relatively weak:
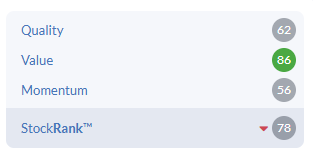
In reality, my concern with these half-year results is that they aren’t stronger. For comparison, sector leader Clarkson (LON:CKN) (disc: I hold) recently reported H1 revenue growth of 39% and a 48% increase in pre-tax profit.
Braemar’s profit margins appear to have weakened in H1, with (adjusted) profit growth of 7% failing to keep pace with revenue growth.
I wonder if Braemar isn’t big enough to reap the full rewards from the current situation, or if it simply doesn’t have the right market presence.
Whatever the explanation, Braemar’s relatively subdued performance is unfortunate for shareholders – tanker markets are said to be truly exceptional (£) at the moment. Big profits in boom markets help to offset inevitable periods of cyclical weakness.
Another concern for me is that Braemar’s quality metrics are also rather average. I wonder if this is a reflection of its cost base - this is a business that depends on highly-incentivised brokers:
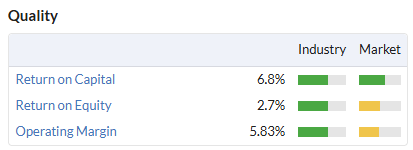
It’s possible that profitability will improve over time. Forecasts suggest much stronger profit growth next year, with FY28E EPS expected to be up by 31%. Based on the current balance sheet, this suggests return on equity could improve to double digits, closer to that of Clarkson.
Personally, I think Braemar’s recent performance and mixed track record justifies a more modest valuation until we see evidence the company’s quality metrics and/or growth rate are improving.
After all, the company’s shares are still lower than they were 10 years ago:
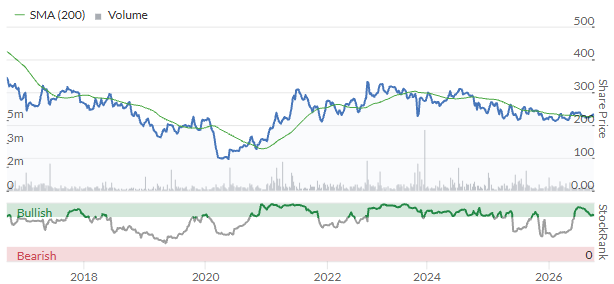
I’m going to move our view up to AMBER (neutral) today to reflect my mix of views on this business.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
RM (LON:RM.)
Excellent move/selling its TTS business.
All the best
I am really looking forward to the Results from Saga (LON:SAGA) tomorrow in the hope that the share will lose its Momentum Trap ranking on Stockopedia. I am of course biased as it is currently my largest position.
The SP is up 29p today nearly 5%.
Guess you may have bought my 666 shares (a dangerous number in itself!) at 117p in January 2025!! A 5.5 x multi bagger in less than 2 years for those brave enough to believe in a turnaround (the Stockopedia style at the time) opportunity when faced with a business with some pretty dire metrics:
As mentioned yesterday with reference to Keller (LON:KLR) my crystal ball let me down on this one too! Perhaps a failure to see through the bad statistics and believe in the power of the 'grey pound' spending on cruises and the insurance business deal.
Perhaps of today’s results from Carnival (NYQ:CCL) currently up 12.58%.
All the best
Thank you, Roland, for your views on BMS. In 2013, I had a financial adviser who put me in at 541p in 2013 and 515p in 2014! Yes, the opportunity cost has been huge! They made a number of very weak decisions, including acquisitions in those days. The saving grace was a high div. Whilst it is turning itself around, focusing on growth, it is still enduring significant set-up costs to achieve this, plus paying, as you say, highly incentivised brokers. At the same time, the div has been cut to aid cash etc. It must be a fantastic company to work for - shareholders are yet to be rewarded! I will still hold, having bought more at lower levels, to see if the turnaround gathers pace. Thankfully it's a smallish investment. I am rather more pleased with others such as VSVS!
Card Factory (LON:CARD) lfl store sales down 2%, sales to Aldi up 13.6%. Need some numbers but margins on Aldi sales must be order of magnitude lower. How much of the retail market will Aldi take from CARD? Puts the latter in barge pole territory for me.
LfL store says down -2% is having a huge negative impact on profit margins on a per-store level at Card Factory (LON:CARD) when you take into account upward rent rises, inflationary fixed costs (labour, utilities, etc) of running stores.
Plus if they've been putting up card prices to combat COGS inflation (eg cost of card, production increases, transport increases) then it points towards a volume sold contraction of worse than -2%....!
Thanks for the excellent summary Graham, looking fwd. to comments on S & U a company I have long admired. I'm in accord with your comments in regard to the "alleged" help to buy scheme, this is yet again a monumental abuse of tax payers money from successive governments. Every well intentioned policy interference from the powers that be has unintended consequences, this will only push house prices up and line the pockets of the directors of the house builders. Every time there is a temporary reduction in stamp duty prices rise, previous help to buy schemes have always been abused by family members clubbing together and buying multiple properties in their children's names, no doubt many of these greedy people are now realising that property prices do not always rise and can be are a very expensive, illiquid asset to fund during recessions. A more cost effective way to get the market moving and recoup more tax revenue would be to lower stamp duty for good and stop all these ridiculous "mansion tax" charges, if only the boneheaded dinasours who think they are born to rule would just butt out for once. Property cycles (from high to low) generally last c18 years this current one was predicted to bottom out next year. As a long retired Quantity Surveyor and new build property developer I have experience in this field.
Hi Carla
I agree with your summary, this is yet again a scheme where the heart of it is massaging the volume of houses built given Labour is going to fall woefully short of its ' manifesto' promise backed up by the words that first time buyers will benefit because they can buy a home. The latter is of course hugely worthy but it is a sad indictment that Housebuilders and the market in their present guise can only prosper if tax payers money is used to prime the pump. Successive Governments have seen whatever incentive as a measure to stimulate the economy but lack the nouse to understand the longer term unintended consequences. Still maybe continued higher house prices adds to the IHT collected in due course......
I agree that help to buy pushes up house prices (at the lower end), but wouldn't reducing stamp duty do the same thing?
It's a failure of council tax that it's proportionally cheaper on more expensive properties - the 'mansion tax' on properties above £2m goes a modest way towards addressing that imbalance.
I agree that help to buy pushes up house prices (at the lower end), but wouldn't reducing stamp duty do the same thing?
its tricky but i am not as convinced that stamp duty decreases would make a material difference - remember first time buyers dont pay stamp duty up to 300k and the stamp duty on a 300k home isnt going to be a hige difference of a difference.
You might be right that it does a tad but i kinda see high stamp duty as simply being something that blocks people changing homes when they need to which isnt great. Even with no stamp duty if one is selling up and moving home thats an expensive excerise which will cost a wad on estate agents fees etc - so my impression is that those that would like to move but its to expensive arent going to be foooled into paying to whack prices - as first time buyers may be.
hey ho small steps today with it becoming easier for councile to bring back into use empty homes - even if they do fail miserable ref targets ref new houses it does seem that Burnham is at leaqst going to try to get stuff done more than Stamer who was alseep at the wheel from the moment he came in.
Property is the cheapest it’s been in real terms for years.
Long may that continue whilst price crashes can really screw the economy - below inflation increases or trending nowhere is what is needed for the young to be able to get more affordable housing in real terms - plus we need a boat load of new homes being built.
Hi pj8
I appreciate your reply thank you.
A more cost effective way to get the market moving and recoup more tax revenue would be to lower stamp duty for good and stop all these ridiculous "mansion tax" charges,
In today's prop. market there is currently very low turnover, in a vibrant mkt a reduction in stamp duty probably would be positive for prices.
With the current glut of unsold houses I would be amazed if prices were to increase with a sensible stimulus as per my note in italics. I really believe it would generate an increase in revenue for the treasury without the massive risk & cost of help to buy schemes etc.
Billington Holdings (LON:BILN) seems good results, any reason results haven't popped the price. Looks like it could be coming out of a bowl? Severfield has had decent momentum of late.
Tpximpact Holdings (LON:TPX) down 8%, why? Looks a great entry point
Strange drop. No news and modest volume. Yes, could be a good entry point.
Still not difficult to buy, yet, maybe some spooked by Made Tech (LON:MTEC) not rising?!
Now 11% down!!
Large sell order being worked maybe, is quite illiquid
Looks like profit taking after its extended rally over the last year. Possibly on lower volumes as no new contract win announcements. Fundamentals still very positive.
I can't see any obvious news. I was wondering if something had come out of Labour conference but then surely that would affect all the companies in the sector.
It looks very good value especially versus peer Made Tech (LON:MTEC) that reported positively today.
i cant see anything wrong with the story and have taken the opportunity to top up after having previously bought at 56p. i can only assume its profit taking and see it as a buying opportunity.
Another day, another bid approach. This time its Vesuvius (LON:VSVS). I would be grateful if the team could add this to the list and cover it today.
Vesuvius (LON:VSVS)
No mention yet of the bid announcement. Issued in response to "media speculation" having kept it quiet from them and the market "since September 2025" when the bidder first made an offer!!
With a national distribution network that they will end up with, it has HUGE potential!
As expected Smiths News burning the rubber and their distribution strategy is working. Must be time for rerating?
Sorry used wrong box - see comment above.
We hold Braemar and Card Factory, I agree with rmillaree and GloucesterBob's comments but I'd appreciate comments on both companies if you have time Graham, we're slightly below break even on those two holdings although the dividends help!
A.G. Barr (LON:BAG) interims in line and there should be some relief that supply chain issues have been resolved in H2. Outlook positive.
Niox (LON:NIOX) and Helios Underwriting (LON:HUW) Two companies both announcing a Tender Offer today. Would be interested to hear views on this. Presumably a clever way to avoid some tax for the benefit of both shareholders and the company - and help drive up the share price. Note in the case of Helios it is in addition to a conventional share buyback already in place,
It's hotting up over at Tribal (LON:TRB) !!
Will Main Capital match Jenzabar's 111p or will we get a bit more? Hand me the popcorn!
Tribal (LON:TRB)
Closed at 101p. Anyone any idea why everyone is not buying at this price for a short term profit?
+10p a share profit on the table and with possibly more to come if the alternative bid(s) come to fruition.
Tribal (LON:TRB)
There was a further announcement at midday by the company.
All the best
The Altyn gold results were very encouraging this morning. I would welcome your comments.
Cheers
Nick
ZIGUP (LON:ZIG) and Smiths News (LON:SNWS) both raising forecasts?
ZIGUP (LON:ZIG)
Short and sweet update - note it’s just towards the high end of a pretty narrow range ref profits - so kinda still within expected range - better to be near top end than bottom tho !! and with no real need for them to have said near upper end today that gives comfort for remainder of the year that they are firmly on track and might even owehais have further good news?
They should be in a sweet spot now with profits increasing back towards prior highs and a much improved cash flow profile - they have needed to load up on debt last few years with higher vehicle fleet values - with them having reached inflection point about now ref debt that’s some nice tailwinds rather than headwinds they should have next 18 months.
As ever they seem to be operationally on point - management continue to do a very good job here.
Smiths News (LON:SNWS) ahead of market expectations due to World cup (nice divi to boot) always nice to wake up to.
Card Factory (LON:CARD) mixed bag, Revenue up mainly from Funky Pigeon, Store sales decline...what do the experts make of it.
Card Factory (LON:CARD)
No real surprises here as with many in retail they are having to work hard to stand still - so profits down despite new stores coming on tap.
They have said they are currently on target though this this year so as of now no further deterioration since the profit warning from last December - that’s the third in line update since then. Sales are hugely loaded towards the end of the year - so facts are if there was going to be profit warning it was unlikely to be now anyway albeit on track is ok.
They still have a lot of hard work to though to deliver ref this year end but at least they are expecting profits to trend back up this year and next.
Overall it’s probably as expected really - key for them is not to get caught out with their pants down in key year end trading period as they did last year - in that regard you would like to hope they learned lessons from last year - only time will tell though.
Nice half year results from Altyn Gold https://www.londonstockexchange.com/news-article/ALTN/half-year-financial-report/17809251
Strong results from Made Tech (LON:MTEC) this morning.
be great to have the teams views on this
Yep, market doesn't agree...had a strong run tbf
It will be interesting to see if Made Tech (LON:MTEC) results take it into 'Jumper' territory when the Stock Report is updated (probably next week) By my calculations the Operating Margin % has just doubled. What will the results take the Quality ranking to and overall Stock Rank => 90? Would be good if we had the teams review on theses results and expected Rank updates.
+1 for the team's perspectives. Ive just seen some research go live on it