Daily Stock Market Report (Wed 8th July 2026) - ZIG, SYS1, IGG, GYM, VTY, JET2

Iran conflict: hostilities resumed between the US and Iran last night, threatening peace negotiations and sending the price of Brent crude oil up $4.
US forces struck 80 military targets, most of them small boats in and near the Strait of Hormuz, with the following justification:
Iran recently attacked three commercial vessels transiting the strait... The unwarranted aggression by Iranian forces is a clear and dangerous violation of the ceasefire and undermines freedom of navigation.
The US also cancelled a waiver that allowed Iran to sell crude for 60 days without fear of sanctions.
In response, the Iranian Revolutionary Guards say that they struck US bases in Kuwait and Bahrain.
Both sides are still officially committed to the ceasefire and to the creation of a long-term peace agreement.
System1 (LON:SYS1): I'll be speaking to SYS1 this morning, let me know if you have any questions you'd like me to ask them!
Overnight market movements:
The FTSE is down 0.1% at 10,670
S&P 500 is down 0.1% at 7,495
Brent crude (September delivery) is up 3.2% at $76.60/bbl
Gold is up 0.5% at $4,128/oz
Bitcoin is down 1.6% at $66,650
Wrapping it up there, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
| SEGRO (LON:SGRO) (£11.9bn | SR74) | Trading Update | Significant increase in new headline rent secured during H1 2026 to £53 million, versus £31 million in H1 2025. “SEGRO has had a very encouraging start to the year, with strong occupier momentum through the first two quarters of 2026… we now have a record level of projects in our current and near-term development pipeline." | |
IG group (LON:IGG) (£6.2bn | SR92) | Plans to create a new group holding company in Jersey. Will not change listing or tax rates. Carrying out internal restructuring aimed at “streamlining” operating model. H1 revenue +18% with active customers +66% (+13% organic). FY26 trading in line with expectations. | GREEN = (Graham) There’s no bombshell announcement here. We’ll have to wait until the Strategy Update in the Autumn to find out the conclusions of the Strategic Review. In the end, they may decide to do nothing - but I doubt it. This review has been trundling along for some time, and I suspect that Breon Corcoran is interested in another mega-deal. For my part, I’m relaxed. IG will approach any merger ideas from a position of strength. I just hope that management don’t get too distracted by M&A so that they end up neglecting the core business. But that doesn’t seem to be the case. Organic growth remains very impressive (helped naturally by the geopolitical tensions that have been problematic for so many other businesses). | |
Unite (LON:UTG) (£2.7bn | SR52) | 86% of beds reserved for 26/27 (25/26: 85%). On track for 0-2% LFL income growth in 26/27 academic year. Expects property valuations to fall by 6.0-6.5% in H1 due to increased yields. Reiterates guidance for FY26 adj EPS of 41.5-43.0p. | ||
Jet2 (LON:JET2) (£2.6bn | SR72) | Final Results & Launch of Share Buyback Programme of up to £250m | Results in line with expectations. Revenue +4%, pre-tax profit -7% to £551m, with EPS -1% to 211.2p. Net cash of £2.0bn. Launching further £250m buyback. Outlook: summer ‘26 capacity is 7.7% ahead of last summer with booked-to-date passengers +7.1%. Strong momentum in recent weeks. | AMBER/GREEN = (Roland) [no section below] I think my decision to remain broadly positive following April’s profit warning is justified by today’s results. In my view, Jet2 is an excellent business that’s performing relatively well in difficult circumstances. The group’s strong balance sheet means it’s now able to underpin future shareholder returns by buying back a significant proportion of its shares at what I estimate to be a very attractive valuation. Today’s outlook appears to be in line, based on the minimal change to broker forecasts. However, it’s worth noting profits are expected to fall by c. 40% this year before recovering in FY28. I think there’s value here on a medium-term view, but the near-term outlook is perhaps a little weaker. I’m going to leave my previous AMBER/GREEN view unchanged for now. |
Hammerson (LON:HMSO) (£1.98bn | SR55) | Sale of multiple holdings in Dublin “and a further non-core investment”. Total non-core divestment YTD now £75m, at “a substantial premium to book value”. Proceeds contributed to purchase of additional interest in Ilac. | ||
Senior (LON:SNR) (£1.21bn | SR73) | Continuing to see positive momentum in the business, with both Aerospace and Flexonics divisions contributing to the improved trading. Now expects full year trading to be ahead of the Board's expectations set out in our April trading update. | TAKEOVER (under offer) | |
ZIGUP (LON:ZIG) (£1.06bn | SR98) | Revenue +2.6%, adj pre-tax profit -4.1% to £160.1m. Adj EPS -9.2% to 53.1p. FY27 outlook in line with expectations. | GREEN = (Roland) I don’t see too much wrong with today's results from this van hire and mobility group. While leverage crept up slightly last year and underlying dividend support was tight, I think cash performance should improve somewhat now that fleet age has normalised. The valuation looks slightly cheap to me but I do respect the run of earnings upgrades seen over the last year – on recent form, profitability is improving. | |
Vistry (LON:VTY) (£802m | SR71) | Completions down c.12% in H1 to c.6,100, with average discount on private sales of 7.1% (H1 25: 1.4%). Expect H1 adj pre-tax profit of c.£20m. H1 net debt was £470m, in line. Vistry continues to forecast net cash of >£100m at the end of 2026. FY26 outlook in line with consensus (adj PBT of £200m). | AMBER/RED = (Roland) While the company appears to be making reasonable progress at liquidating its inventory of unsold land and homes in order to reduce the pressure on its balance sheet, the medium-term outlook seems more uncertain to me. Difficult housing market conditions are adding to the uncertainty, as is the current lack of clarity about the likely pipeline of work under the SAHP scheme. While the deep discount to book value means there is some potential value on offer here, risks remain. I think the stock’s Contrarian style and low MomentumRank are a fair reflection of the situation and am leaving our AMBER/RED view unchanged today. | |
GCP Infrastructure Investments (LON:GCP) (£664m | SR92) | Sale of AD project in Northern Ireland for c.£3m by a borrower, with proceeds used to reduce money owed. Disposal value in line with 31 March 26 NAV. Following recent solar debt financing, RCF has been fully repaid. | ||
Galliford Try Holdings (LON:GFRD) (£552m | SR85) | Appointed to £1.5bn YORbuild Major Works 2 regional framework for 4-year period. | ||
Partners Private Equity (LON:PEY) (£426m | SR44) | NAV -0.7% to €11.84 per share (€801.71m). Declared first interim dividend of €0.325 per share. | ||
Boku (LON:BOKU) (£407m | SR37) | Revenue +c.11%, reflecting various delays and one-off changes. H1 adj EBITDA to be c.$19.3m. Now expects FY26 performance to be below expectations, with revenue of $135-142m and adj EBITDA of $38-42m (previously: $157m and c.$50m). | BLACK | |
GYM (LON:GYM) (£382m | SR68) | H1 revenue +10%, including +3% LFL. Average members +5% with average monthly revenue per member +5%. Ended H1 with 991k members (Dec 25: 923k). Opened four new gyms in H1, net debt £58m. Confident in full-year outlook. | AMBER ↑ (Graham) [no section below] It's been a while since I looked at this one and I need to update my stance after a very strong share price performance as the company has finally started generating real profits. Full-year results to March 2026 showed the company generating an adjusted PBT of £10.6m and a statutory PBT of £7.4m. Site growth continues but at a more measured pace, with 75 new gyms planned over the next three years (260 total gyms as of Dec 2025). The net debt picture is manageable against EBITDA of almost £100m - in a worst-case scenario, the business could probably be run for short-term cash in order to pay down debt. In big picture terms it's an impressive story with 1 million members having been reached, but I think that our stance here shouldn't be any higher than neutral, given the capital intensive and highly competitive nature of the industry. There is some low price at which I would agree that it offered value, but I didn't think that was true at a £250m market cap last year. With the market cap now approaching £400m, having generated £38m of free cash cash flow in 2025, I can put my hands up and admit that I was too slow to revise my negative stance here. But I still don't see a whole lot of value on offer. The company is buying back its own shares instead of paying a dividend, a decision which I think may turn out to be foolhardy. | |
Guardian Metal Resources (LON:GMET) (£380m | SR26) | Entered partnership with Montana Mining Association to collaborate on a tungsten mining and recovery pilot program supporting domestic defence applications. Will supply c.250-400t of stockpiled legacy ore from Tempiute to the partnership. | ||
Capita (LON:CPI) (£340m | SR21) | Statement - Smart DCC Procurement Practice Investigation Outcome | Ofgem reviewed five contracts and found that one was awarded “through non-competitive process”, with a further one to DCC’s parent company. No consumer detriment was found. Smart DCC will pay £200k into Ofgem’s Voluntary Redress Fund and improve its procurement process. | |
Next 15 (LON:NFG) (£265m | SR64) | Trading is in line with expectations, with a particularly strong performance in Digital Transformation where the group is engaged on a multi-year project for DEFRA. FY expectations unchanged. | ||
Central Asia Metals (LON:CAML) (£230m | SR75) | Production for H1 2026 ahead of the corresponding period in 2025 in all three metals. Kounrad copper production of 6,304 tonnes. Sasa zinc-in-concentrate production of 9,094 tonnes. Sasa lead-in-concentrate production of 13,312 tonnes. Production guidance for FY2026 reiterated. | ||
Sovereign Metals (LON:SVML) (£191m | SR15) | Rio Tinto has notified Sovereign that it will not exercise its right to elect to become operator of Sovereign's Kasiya Rutile-Graphite Project. “Rio's decision does not reflect any change in the fundamentals, economics or strategic importance of Kasiya…” | ||
Galantas Gold (LON:GAL) (£184m | SR27) | Chairman resigns, effective immediately, to move to a senior role in private equity. | ||
Pulsar Helium (LON:PLSR) (£148m | SR29) | Due to strong investor demand, increased gross proceeds to c. $25m (£18.7m). $0.5m (£0.4m) from the Retail Offer. The additional proceeds from the Fundraise are intended to be applied towards Topaz Project contingency and corporate working capital. | ||
Quartix Technologies (LON:QTX) (£109m | SR64) | H1 revenue £19.4m (H1 2025: £17.3m). EBITDA £6.9m (H1 2025: £6.2m). The Company is confident of achieving market expectations for the year for revenue, Adjusted EBIT and free cashflow. | ||
Brave Bison (LON:BBSN) (£106m | SR34) | H1 net revenue +97%, adj. EBITDA +87% (£4.2m). “Profitability in the first half was in line with budget and Board expectations for the full year remain in line with previous guidance.” | ||
Avation (LON:AVAP) (£81m | SR43) | Long-term leases for two ART 72-600 aircraft. Six-year leases to start in July 2026 and September 2026. “In general the Company believes that there is a noticeable uptick in the regional aircraft market and second hand ATR72-600 demand.” | ||
Alternative Income REIT (LON:AIRE) (£56m | SR47) | Increased cash offer of 71.4p from Glenstone: AIRE says this is only 70p after deduction for 1.4p target dividend. The offer “represents a negligible premium based on the closing undisturbed share price of 69.7 pence on 14 May 2026”, and a discount of c. 17% to last stated NAV per share. “The Board is considering the offer document and will publish its response document shortly.” | TAKEOVER | |
Caspian Sunrise (LON:CASP) (£45m | SR n/a) | The first of three new deep wells at the Yelemes Deep structure on the BNG Contract Area has been spudded. Chairman and NED to leave in Dec 2026, “in accordance with the Company’s succession plans”. | Shares have been suspended since 1 July 2026. | |
System1 (LON:SYS1) (£40m | SR90) | Revenue -1%. PBT -60% (£2.1m). Fall in revenue “reflected planned additional investment and macro-driven revenue softness in H1 FY26.”. Year-end cash £12.4m. FY27 to date has seen continued strong new business activity. | AMBER/GREEN = (Graham) We’ve been moderately positive on System1 and I’m comfortable leaving that stance unchanged today. The bullish argument I could make is that enterprise value is only £26m and that if it hits forecasts, the cash-adjusted P/E multiple is only about 9x. A cash-adjusted P/E multiple of 9x would be modest for a business that is still early in its potential growth journey. If it does scale up from here and see operational leverage working in its favour, then it is far too cheap at current levels. What holds me back from taking a more positive stance is some lingering uncertainty around its growth prospects. | |
European Metals Holdings (LON:EMH) (£32m | SR21) | Preliminary results for testwork and design of a tunnel kiln for the Cinovec Project. Estimated to materially reduce capex by approximately US$112m and opex by US$10m per annum. Not expected to impact Project timeline. | ||
Quadrise (LON:QED) (£27m | SR5) | Results of Placing and Subscription & Retail Offer to raise up to £1.2m | Conditionally raised £1.2m at 1p (last night’s close 1.37p) from Placing and Subscription. Retail offer also for £1.2m at 1p. | |
SysGroup (LON:SYS) (£17m | SR78) | Revenue +8%. Adjusted EBITDA +26% (£1.2m). Operating loss £1.9m. CFO leaving to pursue a new opportunity. Expects to exceed market expectations for FY27. | ||
Aptamer (LON:APTA) (£16m | SR10) | Aptamer has commenced development of Optimer® binders for a potential rapid diagnostic test for the highly infectious Bundibugyo strain of the Ebola virus. | ||
Fulcrum Metals (LON:FMET) (£12m | SR16) | Updated Mineral Resource Estimate announced by Loyalist Exploration Limited (CSE:PNGC). The updated MRE exceeds the threshold associated with additional contractual consideration (15,000,000 additional Loyalist shares) payable to Fulcrum. Loyalist Exploration share price: 3.5 Canadian cents (about 1.8p). |
Graham's Section
System1 (LON:SYS1)
Down 4% at 300p (£38m) - Final Results - Graham - AMBER/GREEN =
Investor Meet Company - System 1 will be presenting on IMC today at 2pm, if you’d like to hear management speak!
I was given the chance to speak with them this morning, so I asked some broad questions about the profile of the business. Many thanks to CEO James Gregory and CFO Chris Willford.
The headlines from today’s final results had already been provided in an April trading update that I discussed here.
System1 is a “marketing decision-making platform”. The company was previously known as Brainjuicer. It was founded by John Kearon who is still on the Board and is a major shareholder.
For a small company that has been around for a long time, I think it’s fair to say that it has become a source of frustration for small shareholders:
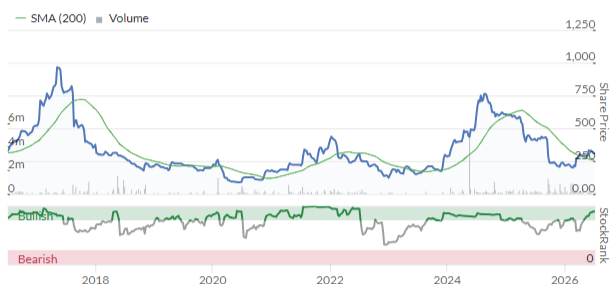
Last year proved to be disappointing as growth projections had to be rolled back after US companies cut their marketing budgets.
Let me remind you of the headlines from these full-year results to March 2026:
Revenue down 1%
PBT down 60% to £2.1m
Net cash at year-end £12.4m.
I started my management call asking them to explain how this is a scalable business. The answer was straightforward: they enjoy very high margins of 87% on their “Data” product (e.g. “Test Your Ad”).
Management’s point of view, which is backed up by performance in prior years, is that incremental Data revenues can drop through to profits very efficiently.
However, as things stand, operational leverage has worked against them in FY26.
I asked them to explain how £37m of revenues results in just £2.1m of pre-tax profit, if this is a scalable, profitable data product.
The answer is that they are simply not big enough yet: they are close, but need another £10-20m of revenues to demonstrate strong profitability.
Thanks to CFO Chris Willford who pointed me in the direction of Note 16 of their accounts:
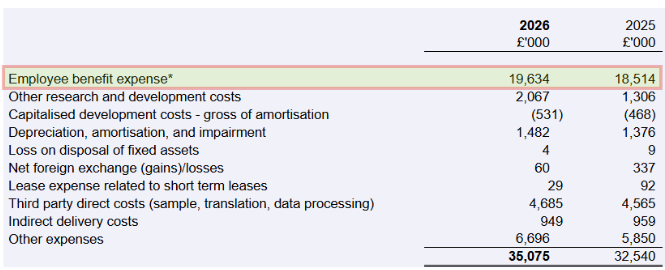
As you can see, there is nearly £20m of employee benefit expense.
For every extra £1m of Data sales that they make from here, they would expect to make very strong profit margins on that. As I’ve mentioned already, the gross profit margin is 87%. Most of the costs in the table above are fixed. Even within employee benefit expense, many of those costs are fixed.
So in order to get from here to a more profitable future, they need to grow - grow in the US especially, and grow their share of the world’s largest advertisers.
They mentioned Covid, tariffs and Iran - geopolitical issues that have hurt sentiment among their customers at various stages of their journey.
Competitive advantage? I asked how they can compete given that many US rivals would probably like to offer a similar product. Their response was that they have an enormous database that derives from constantly testing thousands of ads. This database can apparently train their future products, and gives them a depth of understanding that can’t be replicated purely by software.
Today’s results
Let’s switch over to today’s results and give you the latest outlook statement. With emphasis added by me:
We have entered FY27 with momentum and confidence.
The investments made over recent years, combined with the cost efficiency actions taken during FY26, have created a stronger and more focused business, positioning us to improve profit margins. We have a growing customer base, deeper relationships with major brands and encouraging progress across our strategic priorities.
Our focus for the year ahead remains clear: continue to grow in the USA, further strengthen relationships with the world's largest brands, continue developing our Innovation and AI capabilities, and continue improving operational efficiency to scale seamlessly… we believe the long-term opportunity for System1 remains significant and we enter FY27 well positioned for further growth.
As you can see, there is a lot of focus on margin and on scaling the business (goals that go together hand-in-hand).
Estimates
There is no change to forecasts at Singers. They see adjusted earnings per share almost doubling to 21.2p this year on the back of a modest increase in revenues to £38.4m. Adjusted PBT is seen almost doubling to £3.9m.
Graham’s view
We’ve been moderately positive on System1 and I’m comfortable leaving that stance unchanged today.
The bullish argument I could make is that enterprise value is only £26m and that if it hits forecasts, the cash-adjusted P/E multiple is only about 9x.
(Without making that adjustment, Stockopedia sees a multiple of about 14x.)
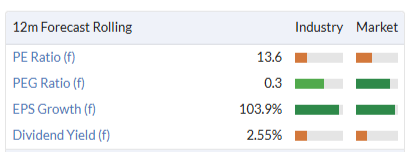
A cash-adjusted P/E multiple of 9x would be modest for a business that is still early in its potential growth journey. If it does scale up from here and see operational leverage working in its favour, then it is far too cheap at current levels.
What holds me back from taking a more positive stance is some lingering uncertainty around its growth prospects. While I acknowledge that their customer spending is volatile and that they’ve had some difficult macro events as a backdrop, it remains the case that their “Platform” Revenue hasn’t moved far in the short-term:
FY25 £34.5m (up strongly by 39% compared to the prior year).
FY26 £35.5m
FY27: total revenue is seen growing by 4% (Singers).
In short, I just don’t have much conviction, and I don’t think the numbers encourage conviction, in an imminent high-growth story.
And if revenues only grow by modest single-digits, that makes it harder for positive operating leverage to kick in against inevitable cost base inflation.
I still think that a moderately positive stance makes sense, given the cheap valuation. I’d just need more evidence and clarity around the strength of its growth prospects before upgrading our view here.
IG group (LON:IGG)
Down 2% at 1825p - New holding Company proposal and trading update - Graham - GREEN =
(At the time of writing, Graham has a long position in IGG.)
I’ve been looking forward to an update on the Strategic Review at IG Group.
We have an important proposal:
As part of the strategic review, IG today announces a proposal to establish a new Group holding company ("New HoldCo"), incorporated in Jersey, subject to shareholder and regulatory approval.
The new structure will give the Group greater financial and strategic flexibility and better reflect its international footprint, with around two-thirds of revenue now generated outside the UK. It will not change IG’s listing, tax residence or London operations:
Now I’m not entirely sure how IG might wish to use this flexibility. But it could be to do with dividends/buybacks, mergers or acquisitions.
On its own, this isn’t a very exciting announcement. But it could set IG up nicely for future exciting announcements.
Indeed: “the strategic review is evaluating other routes to maximise shareholder value, including acquisitions to accelerate growth, the Group's listing venues, and potential combinations of parts of the Group with other industry participants.”
Organisational model: three regional divisions along with Freetrade are being merged into “IG Consumer”. North America and Institutional will remain separate divisions. Sounds logical.
H1 trading update:
The Group expects to report H1 2026 total revenue of approximately £643 million, up around 18% on the prior year, and organic total revenue of approximately £624 million, up around 16%. First trades increased approximately 107% on a reported basis and 74% organically, and active customers increased approximately 66% on a reported basis and 13% organically, in each case on the prior year.
I’m not unhappy with these organic growth rates!
Guidance is reiterated for 2026:
Organic revenue up 10-15% year-on-year.
EBITDA margins in the mid-40s percentage range, as previously guided.
Beyond 2026, the Board remains confident the Group can compound organic total revenue at least 10% per annum on the 2025 base, with EBITDA margins sustained in a mid-40s per cent range.
Graham’s view
There’s no bombshell announcement here. We’ll have to wait until the Strategy Update in the Autumn to find out the conclusions of the Strategic Review.
In the end, they may decide to do nothing - but I doubt it. This review has been trundling along for some time, and I suspect that Breon Corcoran is interested in another mega-deal.
For my part, I’m relaxed. IG will approach any merger ideas from a position of strength. I just hope that management don’t get too distracted by M&A so that they end up neglecting the core business. But that doesn’t seem to be the case. Organic growth remains very impressive (helped naturally by the geopolitical tensions that have been problematic for so many other businesses).
I’m staying GREEN on IG as nothing fundamental has changed, and it’s important to stay positive on ideas that are working. This is an important personal holding for me that I’ve held for many years and as things stand, I intend to continue holding it.
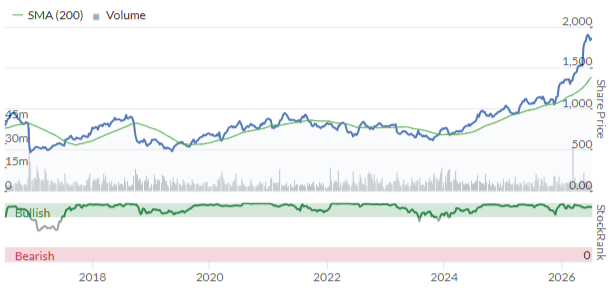
The StockRanks love it but I should acknowledge that they see limited value on offer at this level: momentum is carrying it higher.
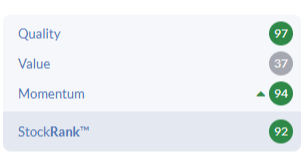
It’s expensive compared to other financial stocks, but personally I see it as offering much higher quality than other financials:
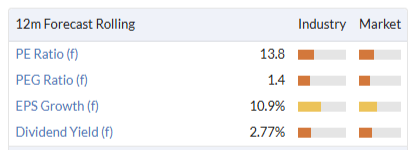
Interactive Brokers (NSQ:IBKR), for example, has a P/E multiple of 35x and has always been very highly-rated. One simple thing that IG could do after their Strategic Review is to list in the United States.
I know I’m dreaming, but if IG Group was listed in the US, why wouldn’t it get a P/E multiple that’s much closer to 35x than to its current 14x? I don’t think it’s obvious that it’s a worse business than Interactive Brokers. So that’s my free advice to the IG board of directors: get dual-listed!
Roland's Section
ZIGUP (LON:ZIG)
Down % at p (£m) - Title - Roland - GREEN =
Graham upgraded our view on “integrated mobility solutions provider” ZIGUP to GREEN in May.
A StockRank of 98 ahead of today’s results also suggests this business could offer a tempting combination of quality, value and momentum.
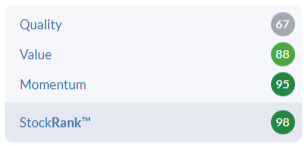
ZIGUP owns the Northgate van hire/fleet management business in the UK, a similar business in Spain and the former Redde accident and claims management operation.
Do today’s results justify such optimism? The numbers are not without complexity, but I believe the overall picture they reflect is a) broadly positive and b) in line with expectations.
FY26 results summary
Here are some key numbers from ZIGUP’s results for the year to 30 April 2026:
Revenue up 2.6% to £1,858.9m
Underlying pre-tax profit down 4.1% to £160.1m
Reported pre-tax profit up 0.5% to £102.0m
Underlying earnings per share down 9.2% to 53.1p
Dividend up 2.3% to 27.0p per share
Net debt up 19.4% to £999m
The decline in underlying profit requires some explanation. In short, profits from the sale of ex-rental vehicles are falling from exceptional levels triggered by supply shortages during the pandemic to more normal levels:
The used vehicle market has been relatively stable over the past 12-18 months after a period of significant supply/demand imbalance, with disposal profits moderating as expected. These are likely to continue to moderate as the historic lack of new supply in 2021-23 reduces defleet volumes for a period, before the market readjusts as a greater number of used vehicles appear on the market.
Selling ex-rental vehicles is an integral part of the vehicle hire business model, but the decline in disposal profits is masking continued growth in the core rental business.
In an effort to illustrate this, ZIGUP has provided two versions of revenue and three versions of EBIT today:
Revenue: £1858.9m (+2.6% YoY)
Revenue ex-vehicle disposals: £1,636.3m (+5.2% YoY)
Stripping out disposal revenue showcases a stronger rise in revenue from the group’s other operations.
However, ZIGUP generated £223m in revenue from used vehicle sales last year. These made a notable contribution to profits:
Underlying EBIT: £200.5m (-0.7% YoY)
Underlying EBIT ex-disposal profits: £164.0m (+9.7% YoY)
Reported EBIT: £142.4m (+4.3% YoY)
Disposal profits fell from £52.5m to £36.5m last year, a reduction of 30.4%. Even after this decline, the EBIT margin of 16.4% on these used sales is still well above the broader group EBIT margin of 12.3%.
I don’t know where used margins are likely to level out, but I am not sure I agree with treating disposal profits as an adjusting item to the core business. Proceeds from disposals have always been and will likely remain a material contributor to group profits.
There will naturally be some ebb and flow in the profitability of different elements of the rental business, but in my view it makes sense to focus on overall returns on capital and cash flow – topics I’ll return to shortly.
First of all, I want to summarise the performance of the group’s three operating segments:
UK & Ireland Rental
Revenue -5.4% to £542m
Hire revenue +5.2%
Disposal revenue -28.4%
Underlying EBIT down 13.4% to £78.2m
ROCE down 3.1% to 9.4%
Average Vehicles on Hire (VOH) down 1.5% to 43.3k
Average utilisation: 91% (unchanged)
UK profits were clearly hit hard by the declining value of disposals. However, underlying rental performance and demand appears to have been stable or moderately positive and the fleet age has now normalised:
Rental profits rose 7.3% and rental margins reflected strong performance in every rental business, especially in higher margin channels, cost control across the underlying rental businesses and high utilisation levels. The average fleet age of 25.0 months is now well within our operating range, enabling fleet recycling activities to normalise.
I don’t see too much to worry about here, except perhaps for somewhat sluggish underlying growth.
Spain Rental
The picture was quite different in Spain. Disposal proceeds improved and demand also appears to have been much stronger, supporting fleet expansion:
Revenue up 15.4% to £433.4m
Hire revenue +16.2%
Disposal revenue +12.1%
Underlying EBIT up 12.1% to £91.6m
ROCE down 0.7% to 11.6%
Average VOH up 9.5% to 66.8k
Average utilisation: 91% (unchanged)
Spain was the largest contributor to profit last year, thanks to a fleet size c.50% greater than the group’s UK operations. Profitability is also stronger, with Spain maintaining double-digit ROCE and an underlying EBIT margin of 26.3% (vs 19.0% in the UK).
ZIGUP is the market leader in Spain and enjoyed “strong” contract growth last year, including a rail maintenance provider with 700 vehicles on rent by the year end.
Claims & Services
This part of the business operates a network of bodyshops and provides related services such as recovery and replacement vehicle provision. It’s low margin but generates higher returns on capital than the core rental business.
Revenue up 0.2% to £935.2m
Underlying EBIT up 7.0% to £41.0m
EBIT margin up 0.3% to 4.6%
ROCE up 6.6% to 24.25
The quality of this business was also improved last year – in my view – by ZIGUP’s decision to exit the personal injury market. The company’s remaining PI claims book has now been outsourced.
Balance sheet & cash flow
ZIGUP helpfully provides details of both replacement capex and growth capex. Few companies do this, but it can be useful when helping to estimate free cash flow generation from the underlying business.
Free cash flow is another metric where ZIGUP likes to provide a more favourable alternative metric – in this case, “steady state cash generation”. This is a pre-tax measure that excludes growth capex and working capital movements.
Steady state cash generation £95.7m (FY25: £16.7m)
Growth capex: £132.4m (FY25: £65.1m)
Company-calculated free cash flow: £(74.7)m (FY25: £(58.1)m)
Stripping out growth capex gives me an underlying FY26 free cash flow estimate of £58m (FY25: £7m).
Looked at this way, dividend payments of c.£59m in each of the last two years have perhaps been a little too generous, as in real terms they are likely to have required some support from borrowed cash.
ZIGUP’s net debt levels have certainly been rising, as it has funded fleet growth with its balance sheet:
FY24 net debt: £742.2m (1.5x EBITDA)
FY25 net debt: £836.7m (1.8x EBITDA)
FY26 net debt: £999.3m (1.9x EBITDA)
This level of borrowing remains under the company’s target maximum of 2.0x, although it’s slightly above my preferred limit of 50% of fleet assets, which ended last year at £1.8bn. I don’t think there’s too much to worry about though.
Overall net assets were stable last year, ending the year at 477p (FY25: 474p).
Profitability
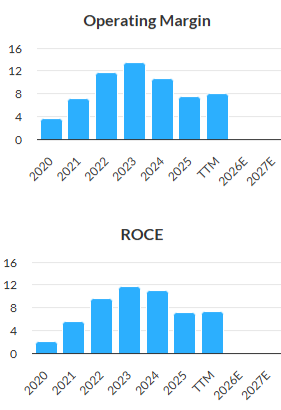
This is a capital-intensive business in a competitive market, so I’d only really expect to see fairly average levels of profitability. Last year’s results support this view:
Operating margin: 7.6%
ROCE: 7.1%
These figures are also in line with the group’s medium-term record:
Outlook
We don’t have access to any updated broker notes for ZIGUP today, but today’s FY27 guidance is for a result that’s in line with expectations for adjusted pre-tax profit of £162.9 - £170.0m).
Consensus forecasts on Stockopedia suggest this will translate to FY27 adjusted earnings of 55.1p per share, putting ZIGUP on a forward P/E of 8.1x with a dividend yield of 5.9%.
The company also says that it’s tracking towards its target of generating more than £200m of steady state cash from FY28. That seems encouraging, but as we’ve seen earlier this measure doesn’t necessarily map onto free cash flow due to additional outflows for growth. For this reason, I’d be wary about using the £200m figure as the basis for a valuation estimate.
Roland’s view
Today’s results seem fine to me and I’ve no reason to doubt the company’s guidance for another year of progress. While I’d like to see slightly stronger free cash flow support for the dividend and moderating leverage, I don’t think either factor should become a problem.
The decline in disposal profits doesn’t concern me as I can see that it’s a natural function of normalising vehicle supply chains since the pandemic.
I can see some potential for capex to moderate slightly now the fleet age has normalised, supporting improved cash generation. I can also see that cost control efforts are improving margins (slightly).
In terms of valuation, the shares currently trade slightly above their tangible book value of 428p. I’d argue that this is about right for a business generating a c.8% return on equity. However, I do respect the improving trend of earnings forecasts over the last year:
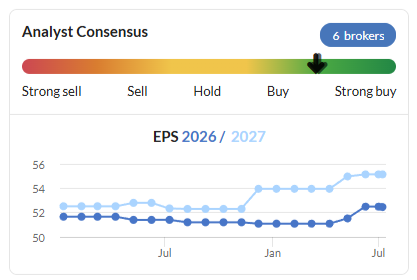
ZIGUP’s near-6% dividend yield is also an attraction.
To avoid too much flip-flopping, I’m going to leave our previous GREEN view unchanged today, with the caveat that I think fair value for the shares is somewhere around the 500p level.
Vistry (LON:VTY)
Down 6% at 237p (£750m) - Trading Update - Roland - AMBER/RED =
Unusually for a housebuilder, Vistry doesn’t try to sugarcoat its recent discounting with talk of incentives. The company is simply cutting prices to shift stock more quickly. This appears to be having a positive effect, too.
Vistry says it reduced inventories of unsold private homes from c.£600m to under £300m in H1, while also starting to exit its part exchange offer, which has historically tied up c.£50m of debt. However, the average discount of 7.1% is quite high and of course implies some properties may have been discounted by more than this.
These measures give us an idea of the financial pressure the group is under, but liquidating assets can be a very effective way of generating cash inflows to reduce leverage.
Today’s guidance on debt is mixed: while the company still expects to achieve net cash of at least £100m at the year end, H2 average daily debt is only expected to be “below £650m”, compared to £799m in H1.
To me, this suggests a substantial window-dressing effort will be required to achieve the year-end net cash figure – I prefer to focus on the average daily figure as being more representative of a builders’ financial state.
Outlook: the company expects to meet consensus forecasts for 2026:
As a result, the Board expects that adjusted profit before tax for FY 2026 will be in line with the current market consensus (Company compiled analyst consensus for 2026 is adjusted PBT of £200m). This forecast excludes any impact from the ongoing CEO Review, the findings of which will be detailed on 24 September 2026 in the Half Year results.
However, I think it makes sense to look beyond this single headline (and heavily adjusted) figure.
Liquidating assets can be an effective strategy to reduce balance sheet pressure. But it needs to be followed by a return to suitable volumes of profitable new-build work in order to put the business on a sustainable footing.
Commentary today on the forward outlook seems mixed to me.
On a relatively positive note, the forward order book stood at £3.9bn at the end of H1 and Vistry says it’s 80% forward sold for FY26 – I assume this is relative to consensus revenue forecasts.
Build cost inflation is stabilising at 3-4% after a more challenging H1 and the company expects “materially improved H2 profit performance” as volumes rise and overhead costs fall.
There will also be additional profit from land sales “as we reshape the landbank”.
I think the short term impact from all of this should be positive. What’s less clear to me is the outlook for the next 12-18 months. Several potential headwinds are highlighted:
“Open Market [private sale] conditions deteriorated in the second quarter [...] we are not anticipating a significant change in Open Market conditions in H2 or early 2027”.
While Vistry remains committed to the partnership building model, “we have renegotiated several deals with partners that did not meet our commercial requirements”. This has resulted in delays to the completion of some deals, while the company has opted not to proceed with some transactions.
While the government’s Strategic Affordable Housing Programme (SAHP) continues to offer potential, progress so far has been limited and remains uncertain. The initial grant allocation process is expected to complete in September, when the picture may become clearer.
Roland’s view
Vistry shares are trading at a discount of c.75% to book value after an 80%+ decline over the last two years:
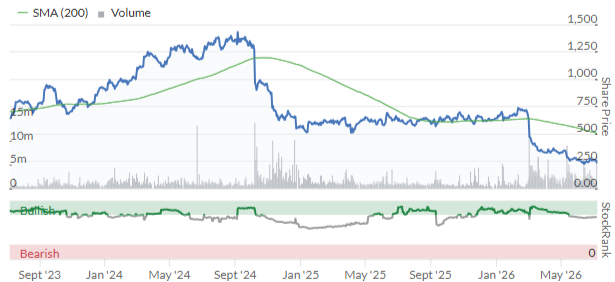
Such a deep discount normally implies a measure of distress. In this case, the risk is that the company may need to raise new equity to reduce debt to sustainable levels.
Based on today’s evidence, I would suggest that this remains a risk, although not a certainty.
We should learn more about the outlook when new CEO Adam Daniels provides a strategy update in September.
At this stage I am going to maintain Mark’s previous AMBER/RED view. While there could be significant upside here if Vistry can deleverage without raising equity, I don’t think we can be sure of the eventual outcome yet.
Difficult housing market conditions are adding to the uncertainty, as is the current lack of clarity about the likely pipeline of work under the SAHP scheme. I think the stock’s Contrarian style and low MomentumRank are a fair reflection of the situation:
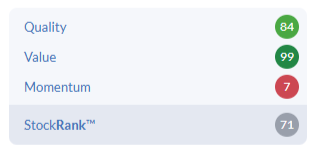
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
Hey Revs8. So here’s my take: this report shows solid underlying performance masked by near-term cost rises. But longer term, I’m bullish. I understand that the capex figure will jump over the next few years as the neos come online. However, the company has an amazing track record when it comes to capital discipline. I haven’t run the maths for a while, but it typically trades at a significant discount to peers when net cash (not including deferred revenue) is included. As we move towards the end of the decade, the neo transition should be largely digested, the new bases maturing, and the fleet efficiency gains dropping through to margins. It’s probably due a re rating .
I think there’s also an interesting narrative around overcapacity. Airline cyclicality was never just demand — it was overcapacity. Every good year triggered an ordering binge that crushed fares three years later. Right now that mechanism is broken: Boeing and Airbus can’t ramp production, backlogs run close to a decade, etc.
SK HYNIX'S US LISTING IS NOW MORE THAN 7 TIMES OVERSUBSCRIBED, WITH PRICING SET FOR TOMORROW.
All the best
On System1 (LON:SYS1), I wonder if the brokers are being too conservative with the +4% revenue growth for FY27.
If I look at the "Platform Revenue", which is mostly the subscription recurring revenue. H2 was a £38.6m/yr run-rate, higher than the £35.5m total for FY26. That's +8% run-rate into FY27 already.
And then there's the 87% gross margin.
So if I take this H2 exit run-rate into FY27, and assuming ZERO extra growth in new subscriptions (which is very conservative as they are guiding growth here).... that's an extra £3.1m gross profit.
They should be able to keep a lid on "costs", especially employees, as they scaled up last year for growth and they are implying this year is higher margin due to controlling costs. Employee costs last year £19.6m. Assume maybe 5% inflation so £1m extra this year.
So around £2m will fall to the operating profit. Don't think D&A, net interest will change much.
So FY26 PBT of £2.1m doubling to £4.1m looks conservative, so brokers rough doubling of EPS looks OK too, to around 20.5p EPS lets say.
So yeah - broker forecasts do look a bit conservative here. Any amount of extra revenue growth, given the 87% gross margin, even a few percentage points, will mean a beat against expectations. And as Graham mentioned, 9-10x PE adjusting for cash.
I'll be digging deeper in the results later this week, but I think these results have validated my conviction that these should be easily worth over 400p, and the current 300p has a very strong fundamental support, especially with Brave Bison lurking in the background.
System1 (LON:SYS1) results presentation on Investor Meet Company worth a listen for the following three things:
Penguin Solutions (NSQ:PENG)
After these results, it is clear enough that the AI theme is not overvalued, but still at its initial stage and will provide investors with some amazing opportunities for wealth creation.
All the best
GYM (LON:GYM)
Hi Graham
Thanks for your commentary on GYM (LON:GYM)
I remain a fan, but I appreciate why some do not like it.
As a point of reference below are figures for Pure Gym, the larger PE-owned competitor. It seems that 1m members was a PBT inflection point, albeit one that capitalised on the post-covid boom.
If GYM (LON:GYM) follows a similar PBT trajectory then perhaps the current share buyback programme will end up being a good decision?
SOUTH KOREA’S KOSPI HAS ENTERED A BEAR MARKET, FALLING 20% FROM ITS JUNE 19 HIGH.
All the best
US SK Hynix ADR might have problems?
No it’s oversubscribed multiple times. Price based on wherever its stock happens to be trading on July 9-:)
Amazing how these US investment banks are ahead of everyone else in the field.
Depends now on TACO timing, probably sometime over the weekend……
All the best
Time to adopt the brace position with the latest news on the Middle East crisis
Think the Iran conflict will blow hot and cold for some time to come - both sides don’t seem to negotiate in good faith.
"The FTSE is down 0.1%"
I wish!
Graham, please will you add the tags so that we get the complete Securities Mentioned column?
FREng, do you mean all stocks in the table?
Graham, Yes, that would be really useful during the period when we only have the agenda table not yet poulated with your summaries, as it gives the quickest way to see price movements and other details.
Apologies if that seems a daft suggestion or burdensome
Hi FREng, that's fine. If most people prefer it that way. we can do that. It doesn't actually cost any time for me, as it's pre-populated anyway.
Better, perhaps, would be to make the share names in the table generate a popup when hovvered over, like the names in portfolios do.
Clearly, I could click and generate separate tabs but that's slower and generates many tabs and requires more bandwidth and compute at both ends.
Or have I missed a trick?
Hi. Would there be a way to ask about the relationship between Brave Bison (LON:BBSN) and System1 (LON:SYS1) ? Thanks
Hi bsharman, I did mention it to them but I acknowledged that they wouldn't be able to give me any information that wasn't already public. There is a shareholder relationship agreement that's been outlined in an RNS between BBSN and SYS1. Speaking personally, I think it makes sense for a company like SYS1 to merge or get bought out, if it can't grow quickly on its own. I think that the SYS1 management can see this logic but they want to grow independently for now and in any case they don't have control over BBSN or any other potential buyer. G
Hi Graham, would you be able to give your thoughts on Victoria (LON:VCP) refinancing and trading update if you have any time. Thank you
IG group (LON:IGG) proposed establishing a new group holding company in Jersey as the online trading platform presses ahead with a strategic overhaul. Quite a big change.
London-listed financial firms have increasingly sought structural flexibility to pursue growth in fast-moving global markets reshaped by new trading technologies (Reuters). Not sure what this means - UK tax changes on ISAs, spread-betting, CFDs etc and general increase in regulation being prepared for. Staying listed and taxed in UK.
18% year-on-year jump in first-half revenue, with active customers increasing about 66% on a reported basis.
Those Jet2 figures look strong on first glance, given the Gatwick costs and jet fuel spike --- I had expected worse.
Initial market reaction was very positive. Many traders taking profits (possibly because of news from Iran). Opinion of the team would be appreciated.
ZIGUP (LON:ZIG)
As far as I can decipher the results have come in more or less as expected, possibly a little better, but the prelims take some unravelling. The shares have been in the value bucket for as long as I can remember but on balance I think that they are worth more than the market is currently willing to pay.
Any help from Graham or Roland would be welcome.
ZIGUP (LON:ZIG)
i am a contented holder - at present the accounts are very messy and the bottom line numbers arent nearly as good as the underlying numbers - so some may take a more conservative viewpoint ref where the business is at.
The main plus point here is that core trading seems to be "adequate" - looks like Spain is the star performer (could they ever get no brainer offer for Spain?).
They have had to work extremely hard here to make progress - with normalisation of second hand prices the easy money aint there - and the adjust they had to do slowing deprecation a couple of years backs makes comparisons with prior years look less good as those adjusts on lfl basis pimped up the prior years at the expense of the now.
Chunky costs closing the legal side of things - its for the best though if they concentrate on core stuff that has best payback.
You can perhaps take two viewpoints here - you could say they have had to work much harder for profits to not really progress much - upping debt massively (they do have matching increase in fleet value !) and with that upping any potental issues if for example they need to up depreciaton levels. Or you can take the viewpoint there is enough demand out there that they need to splash the cash - and debt issue now will partly/mostly unwind over the next 4-5 years. At present the increased finance costs are certainly eating into ability to generate profits. The key here is the next 24 months now that they have reached inflexion point of having invested to get the future rewards.
Key metric here to me is the progress steady state cash generation - this very much sugests the"heavy lifting" is now all done
That was £17 mill 2025 - £96 mill this year - and is trending towards £200 million in 2028 - so it seems like the hard work of piling on the debt is over - they now just need to hire out the vehicles and make expected margins - they seem fully on course in that regard.
Thats what we want to see meaningful amount of profits flowing through to free cashflow and paying this that and the other.
They have targetted pbt of £163 to £170 mill for 2027
if we take 75% of that number and add multiple of 10 that gives us market cap of £1.25 billion - thats a nice round £5 per share.
all looks fairly decent - share has done fairly well (450p) thn last 12 months so deffo not the bargain it was at sub 350p - with chunky dividend yield of 6% i am more than happy at present to continue holding espcially as the cashflow profile going forward should be much better than up to now.
SEGRO (LON:SGRO) I hold
trading update " SEGRO plc reported a strong first half of 2026, securing £53 million in new headline rent, a significant increase from £31 million in the prior year, driven by £24 million in new pre-lets and a record development pipeline." can you add to coverage please?
done!
PLSR. Stock rank of 290! I'm in.