Daily Stock Market Report (Tue 4 Mar 2025) - GRG, SNX, WHR, KLR, ABDN, KITW, RCH

Good morning all, the Agenda is there now!
1pm: we're all done for today.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Ashtead (LON:AHT) (£20.1bn) | 9M Results | Q3 rev -3%, adj. PBT -6%. Nine-month figures more positive. Full year results to be in line. | |
Intertek (LON:ITRK) (£8.3bn) | Final Results | Rev +6.6% at constant FX. 2025: mid-single digit growth, margin to grow to 18.5%+ (2024: 17.4%). | |
Beazley (LON:BEZ) (£5.7bn) | Final Results | PBT +13% to $1,423m. Net tangible assets per share 545.9p. Share buyback for $500m. | |
Fresnillo (LON:FRES) (£5.6bn) | Final Results | Rev +26.9% ($3.6bn). $550m divi. 2025 production might be lower: 49-56 moz silver, gold 525-580koz. | |
Direct Line Insurance (LON:DLG) (£3.6bn) | Final Results | Ongoing operating profit £205m (2023: loss £190m). | PINK. Under offer. |
Abrdn (LON:ABDN) (£3.0bn) | Final Results | New 2026 targets: adj. operating profit >£300m (2024: £255m), net capital generation >£300m. | GREEN (Graham) Lovely news that they are changing their name back to the pleasant "Aberdeen". The 2026 targets are also encouraging, as are the improved net flows. Adjusted profits for 2024 have slightly beaten expectations. Shareholders can look forward to a constant dividend payout for now, until it's coverage has improved. All in all, it's a picture of improving health and positivity. |
Inchcape (LON:INCH) (£2.7bn) | Final Results | New med-term CAGR targets (compound growth rates). EPS >10% p.a. Volume +3%-5% p.a. | |
Greggs (LON:GRG) (£2.1bn) | Final Results | Sales +11.3%, adj. PBT +13.2%. LfL sales +1.7% in first nine weeks of 2025. Challenging Jan weather. | AMBER/GREEN (Graham) This is a risky decision but I'm leaving our stance unchanged despite another sharp fall on the back of declining short-term sales growth. Management assert that their expectations for the year are unchanged and still plan to hit their long-term sales growth next year. |
International Workplace (LON:IWG) (£2.0bn) | Final Results | Outlook: cautious. FY25 EBITDA $580-620m. Leverage to fall, BBB credit rating to be maintained. | |
Spirent Communications (LON:SPT) (£1.1bn) | Final Results | Rev -3%. Challenging market conditions, but a growing orderbook. Well-placed for 2025. | PINK. Under offer. |
Keller (LON:KLR) (£940m) | Final Results | Rev +4%, adj. op profit +22% at constant FX. Significant deleveraging. Multi-year buyback. | AMBER/GREEN [no section below] (Roland) |
Bakkavor (LON:BAKK) (£895m) | Final Results | LfL revenue +5.1%, adj. op profit +20.5%. 2025 rev to be “broadly” in line, adj. op profit to be in line. | |
Supermarket Income REIT (LON:SUPR) (£869m) | Proposed Mgt Internalisation | Using sale proceeds to insource mgt team for £19.7m. Exp £4m ann. savings; 19% yield on cost. | |
Apax Global Alpha (LON:APAX) (£660m) | Final Results | NAV -4.6% to €1.23bn/208pps. Decrease mainly due to PE portfolio. €69m of s’holder returns. | |
Johnson Service (LON:JSG) (£547m) | Final Results | FY24 in line. Outlook: £30m buyback, improved margins in FY25. Possible Main Market move. | AMBER/GREEN (Graham) [no section below] |
| Warehouse Reit (LON:WHR) (£360m) | Stmt re Possible Offer | Blackstone offered 110.5pps for WHR, its 4th proposal. Board has rejected. Sept ‘24 NAV 127.5p. | PINK (AMBER/GREEN) [no section below] (Roland) |
Reach (LON:RCH) (£275m) | Final Results | Rev -5%, but adj op profit +6% ahead of exps. Digital returned to growth. FY25 outlook in line. | GREEN (Graham) [no section below] This cigar butt stock keeps puffing out impressive profits (£102m adj. op profit, +6%) and cash flow (£107m adj. op cash flow). The dividend is maintained with a yield of over 8%. I also note £59m of contributions into pension schemes - these contributions “will materially step down… to around £15m in 2028”. My estimate of c. £200m of future pension contributions still seems about right (see January report). Non-pension net debt is only £14m. Total enterprise value including pension commitments is c. £500m or 5x adj. op profit. Like-for-like group revenue fell by a modest 4.2% in 2024. This continues to intrigue. |
Origin Enterprises (LON:OGN) (£261m) | Interim Results | H1 op profit +2.2% to €14.9m. Net debt €270.1m. “Too early to issue guidance for the full year”. | |
Kitwave (LON:KITW) (£223m) | Final Results | FY24 in line with exp. Rev +10% to £664m, adj op profit +6.3% to £34m. FY25 “started well” | AMBER/GREEN (Roland) |
Aquis Exchange (LON:AQX) (£194m) | FY24 TU | Profit warning. Heightened credit risk in respect of two clients. FY24 to be £3.7m below exps. | PINK. Takeover remains expected to complete in Q2. |
Synectics (LON:SNX) (£64m) | Final Results | FY24 results ahead of exps with adj PBT of £4.7m versus exp of £4.3m. FY25 estimates upgraded. | AMBER/GREEN (Roland - I hold) |
PCI- PAL (LON:PCIP) (£44m) | Interim Results | H1 revenue +26% to £10.6m. ARR +21% to £16.8m. H1 adj PBT of £0.2m in line with mgt exps. | |
Blackbird (LON:BIRD) (£23m) | Final Results | Rev -17% to £1.6m with adj EBITDA of £492k. Cash outflow of £3.8m. Net cash of £3.8m. | |
Tekmar (LON:TGP) (£9m) | Final Results | FY24 results in line with exps. FY25 EBITDA to be “consistent with FY24”, with H2 weighting. |
Graham's Section
Greggs (LON:GRG)
Down 11% to 1844p (£1.9bn) - Preliminary Results - Graham - AMBER/GREEN
Before getting into the bad news, we have very nice headline growth rates from Greggs this morning, for 2024:
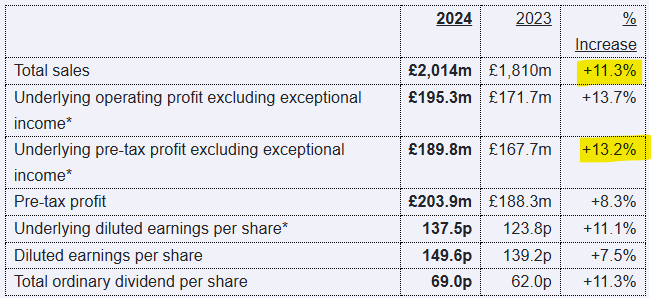
The company points out - with evidence, if it was needed - that consumer confidence in 2024 was low, and that the food-to-go market wasn’t growing.
Despite the difficult circumstances, they can point to various growth achievements during the year:
Estate: the estate has increased to 2,618 shops with a net 145 openings during the year. Similar net openings are targeted in the current year, as they “continue to see clear opportunity for significantly more than 3,000 UK shops over longer term”.
App: The Greggs App scanned 20% of their company-managed shop transactions (up from 12.5% in 2023).
Delivery: delivery sales grew by 30%+ in 2024, from a low base.
Evening trade: post-4pm is the fastest-growing part of the day and is now 9% of company-managed shop sales.
We also have a trading update and this is where the shine starts to come off the announcement:
Like-for-like sales in company-managed shops increased by 1.7% year-on-year in the first nine weeks of 2025. Challenging weather conditions in January followed by improved trading in February
Confident that Greggs can manage inflationary headwinds and deliver another year of progress in 2025
The CEO’s report says that management expectations for 2025 are unchanged despite the above.
Roisin Currie elaborates on the outlook; I’ve tried to pick out the key points here.
Looking ahead to 2025, the macroeconomic landscape remains tough. Inflation remains elevated, and many of our customers continue to worry about the cost of living…
Despite a challenging food-to-go market, Greggs has demonstrated its ability to make positive progress and we remain confident that Greggs can and will continue to grow. The five-year strategic plan that we set out in 2021 is proving successful…
Increases in employment taxes will significantly increase our wage bill, and that of other retailers, in 2025, but we have dealt with significant cost inflation effectively over recent years and remain confident in our ability to manage the impact of cost inflation on the business. We are relentlessly focused on improving efficiencies which supports our position as a value-led brand. To the extent that we cannot mitigate cost inflation through savings, we recover it through careful pricing activity, which we strive to keep to an absolute minimum to ensure that we protect our reputation for offering great value.
I note that under the 5-year plan, the company planned to double sales by 2026, which I think means hitting £2.4bn. Consensus forecasts suggest that this will be achieved (£2.0bn in 2024, £2.2bn in 2025, and then £2.4bn in 2026).
Graham’s view
It’s clear that the slow growth figure for early 2025 has rattled confidence this morning.
I note that Megan covered this in January and reported on a clear, declining trend in like-for-like sales: from 7.4% growth in H1 2024, to 5% in Q3, to 2.5% in Q4.
And now it’s just 1.7% in early 2025.
It appears that Greggs is not immune to the economic climate, even if it does offer better value than most of its competitors. The entire food-to-go sector has slowed down and brought Greggs with it.
Perhaps I should downgrade our stance on this from Megan’s AMBER/GREEN. It’s a tough call as we haven’t had a clear profit warning today - management expectations for 2025 are unchanged, officially.
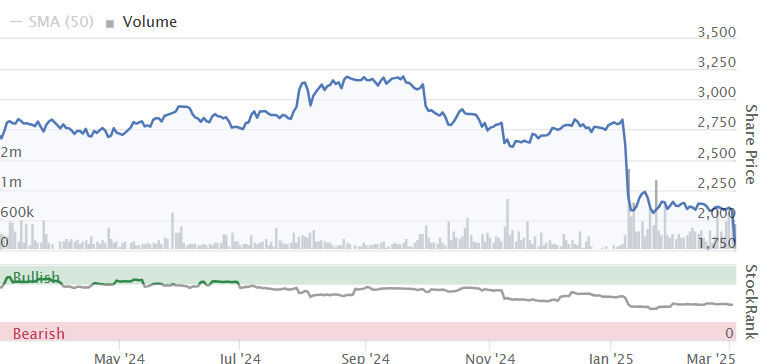
However, we have had a noteworthy drop in the share price this morning, and this follows another sharp fall in January. Don’t they say profit warnings come in threes?
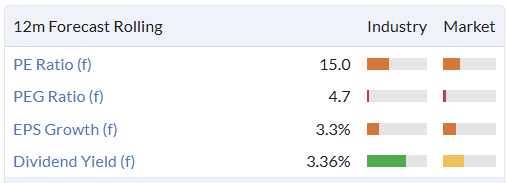
Valuation has been moderate, which makes it easy to take a positive stance on it as one of the most likely long-term High Street winners.
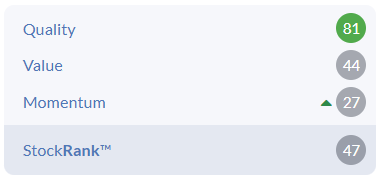
But the StockRank is neutral, mostly due to the weak momentum offsetting its high quality:
I’m unsure but on balance I’d like to leave our AMBER/GREEN stance unchanged. If you scroll out, the share price is back below the levels it first reached in 2019-2020. Sales were only £1.2bn in 2019, and the company could well double that figure next year.
Another point in its favour is £125m of net cash (before leases)..
The accounts are clean with few adjustments.
Quality metrics are very attractive, as reflected in the StockRank above.
I am therefore going to leave the AMBER/GREEN stance unchanged, while acknowledging that negative momentum could continue to hurt the share price in the short-term. We’ve had two sharp falls on RNS statements now, and the trend in terms of sales growth is negative. Hopefully we can see this turn around before too long!
Abrdn (LON:ABDN)
Up 11% to 179.4p (£3.3bn) - Final Results - Graham - GREEN
Abrdn have published a 7-part RNS with far too much detail for me to cover. But let’s just get a helicopter view of this investment giant - to help inform us when we might look at the smaller ones.
The big picture is that AUMA (assets under management and administration) are down by 6%, and adjusted net operating revenue is similarly down by 6%.
More positively, the net flows in 2024 were much better than in 2023. Net outflows were only £1.1bn, which is almost a rounding error when you have over £500 billion in AUMA (admittedly some of the improvement for the year relates to flows into low-margin liquidity funds).
Another positive is that the company made a small improvement (+2%) in adj. operating profit, despite lower revenues. It’s no surprise that cost management played a role: “This was driven by cost discipline, better markets and a strong performance by interactive investor.”
And the accounts are clean, with £251m in statutory pre-tax profit, almost matching the adjusted operating profit figure (£255m).
According to Refinitiv the consensus forecast was for £249m of adj. operating profit, so the company has beaten forecasts today.
But the best news is that they are changing their name! This must be why the share price is up over 10%, as they will no longer be a target of ridicule in the City:
"This is a Group to be proud of, with a promising future. We will deliver by looking forward with confidence and removing distractions. To that end, we are changing our name to aberdeen group plc. This is a pragmatic decision marking a new phase for the organisation, as we focus on delivering for our customers, people and shareholders."
Unfortunately, I doubt that they will get a refund from brand consultancy Wolff Olins.
And it’s a sharp U-turn by CEO Jason Windsor who said only in January, as we reported here, “the name (Abrdn) is the name and we will be continuing with it”.
Outlook: falling interest rates will reduce cash margins at Interactive Investor and in the Advisor side of the business. But cash balances and trading activity are expected to grow, offsetting that.
In the Investments division, there will be “a slight reduction in revenue margins”.
It’s a measured statement:
Looking beyond 2025, we continue to see long-term structural growth in the UK savings and wealth industry, which we are well-positioned to capture. In addition, while market conditions are expected to remain challenging for active asset managers generally, we see a number of areas of attractive opportunities that our Investments business is well-placed to serve.
New targets: for FY26 they are targeting adjusted operating profit of £300m and net capital generation of the same amounts.
Graham’s view
I was GREEN on this last time and I am GREEN on nearly all fund managers.
With the name fiasco getting put behind it and with flows having improved significantly, I’m very happy to stay GREEN on this today.
The StockRank is close to perfect:
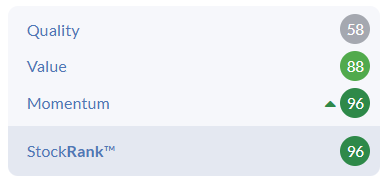
And it offers an incredible yield:
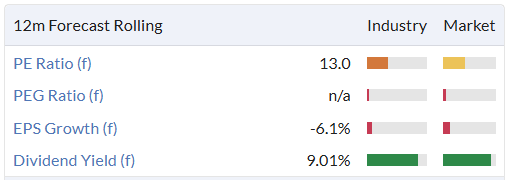
The full-year dividend for 2024 is 14.6p, vs. adjusted diluted earnings per share of 15p. It’s not easy for them to pay this level of dividend and so their intention is to leave it at this level until it is covered 1.5x by the capital they generate. It’s currently covered 1.2x.
Can we read across from this to other fund managers, that their performance should also be expected to start improving soon? I think we might be able to start to think more optimistically about the sector.
At Aberdeen’s Investments division, net outflows were only £4bn, vs. £19bn the prior year.
£4bn is only around 1% of the AUM in this division.
Let’s see if the smaller fund managers can follow suit with less dramatic outflows.
Roland's Section
Synectics (LON:SNX)
Down 7% to 335p (£60m) - Final Results - Roland - AMBER/GREEN
At the time of publication, Roland has a long position in SNX.
Synectics plc (AIM: SNX), a leader in advanced security and surveillance solutions, announces its audited final results for the year ended 30 November 2024 ("FY24").
Synectics’s full-year adjusted profits have beaten market expectations today, but the shares are still trading lower at the time of writing.
This stock is a member of my Stock in Focus portfolio and my personal holdings. So I’m keen to see if today’s results suggest recent momentum can be maintained – or if the rate of growth may be slowing.
2024 results summary: at face value these results seem excellent, with adjusted pre-tax profit of £4.7m coming in comfortably ahead of the £4.3m consensus estimate:
Revenue up 14% to £55.8m
Adj pre-tax profit up 59% to £4.7m
Reported pre-tax profit up 57% to £4.2m
Adj earnings up 52% to 21.6p per share
Net cash of £9.6m (FY23: £4.6m)
Order book at 30 Nov 24: £38.5m (Nov 23: £29.2m)
Full-year dividend up 50% to 4.5p per share
Drilling down a little further into the numbers, I can see evidence of improved profitability – a point I’ve flagged up previously. These figures are still fairly average in my view (using reported profits), but are moving in the right direction:
Op margin 7.6% (FY23: 5.6%)
ROCE 9.6% (FY23: 6.5%)
Cash generation has been skewed by some big movements in working capital. An updated note from Shore Capital today suggests Synectics has received cash upfront for revenue not yet booked, boosting its cash position.
Stripping out working capital movements gives me an underlying free cash flow estimate of £3.4m. This represents an excellent 107% conversion from reported net profit of £3.2m.
I don’t have any concerns about Synectics’ finances. Let’s see what the company has to say about trading.
Trading commentary: Synectics reports its results under two segments, reflecting its split between solutions that are sold through systems integrators and partners (Synectics Systems) and those it sells directly (Ocular).
Synectics Systems: this part of the business generates the majority of profit, selling software and hardware solutions (primarily) to the gaming and oil and gas markets.
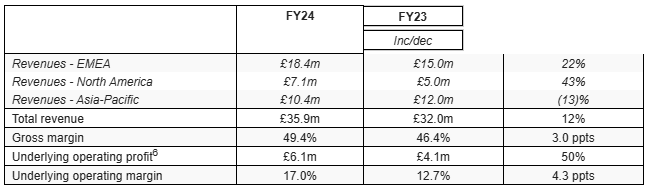
Synectics has a long heritage of providing surveillance systems to Casinos and this remains one of the most important parts of the business.
Although Asia-Pacific revenue fell last year, the company also won a $13.2m contract during the year in this region:
the upgrade and expansion of one of the world's most successful and highest-profile gaming resorts in South-East Asia. Synectic Systems has been working with this customer since 2014,
Elsewhere, the company won a series of contracts in North American casinos and said it’s starting to target the tribal gaming market – casinos located on reservation land.
In oil and gas, the company reported a 5% increase in revenue and noted the dependence on economic conditions and geopolitical factors.
The final part of this market includes public spaces and infrastructure. Client wins last year included “a major UK utility provider”.
New opportunities flagged up include the UAE market, data centres and UK critical infrastructure.
Ocular: this business sells Synectics solutions and support directly to customers in the UK and Ireland. Key sectors are public spaces and transport infrastructure. It was previously known as Synectics Security but was rebranded in November to a name with no obvious meaning. Or as the company describes it:
This rebranding signifies a broader transformation programme designed to sharpen Ocular's focus on delivering cutting-edge security solutions and innovations across identifiable sectors, including public space, transport, and critical national infrastructure.
In any case, performance was solid last year, albeit at much lower margins than the channel business, perhaps reflecting the greater cost base required to work directly with end users:
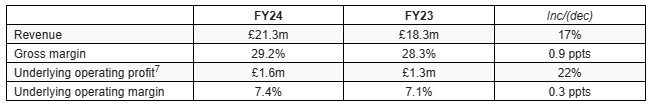
The company says it’s “refining and developing Ocular’s go-to-market strategy”. with a “targeted approach to key sectors” where the company has a proven ability to deliver. A new Sales Director has been appointed and the company is investing in its sales team.
Operationally, growth was driven by “increased traction in transport sales”, while “security sales remained broadly flat”.
Transport growth is being driven by investment in infrastructure and a shift to the electrification of fleets (e.g. buses).
An ongoing framework agreement with National Grid delivered £6m of contracts during the year and Synectics now supports 32 NG sites.
Outlook & Estimates: 2025 trading is said to be in line with expectations, so far:
Following a good start to FY25, trading to date is in line with the Board's expectations, with our strong order book underpinning confidence in FY25 and beyond.
FY25 estimates from Synectics’ house broker Shore Capital have been upgraded today to bring them into line with the more positive outturn from FY24. Our thanks go for making this coverage available on Research Tree – without this it would be very difficult to track changing expectations:
FY25E revenue +5.3% to £65m
FY25E adj EPS +4.2% to 24.9p
For FY26, shore has edged up its revenue forecasts but left adj PBT unchanged to reflect higher spending on business development.
Roland’s view
Today’s upgraded FY25 estimates leave Synectics trading on a forecast P/E of 13.5 for the current year. That’s significantly below the level seen prior to today’s results and share price drop:
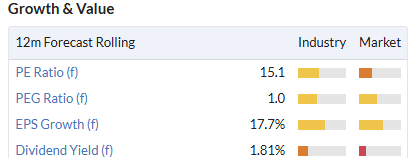
My impression from today’s results is that the business is performing well, but is investing more in business development in an effort to reach new markets to support further growth.
The year-end order book is equivalent to around seven months’ revenue, based on FY25 forecasts. This seems to provide decent support for FY25 trading at this stage in the year, but clearly still leaves some gaps to fill.
Optimistic investors will point to the opportunity to outperform during the year with new contract wins – and that’s certainly true.
However, I’d also want to consider the opposite risk – failure to secure a few more big wins could leave the outlook for FY25/26 looking a little weak.
On balance, I’m reassured by improving profitability and the strong balance sheet. I think it makes sense to maintain a cautiously positive view, while noting that the big gains may be in the price for now:
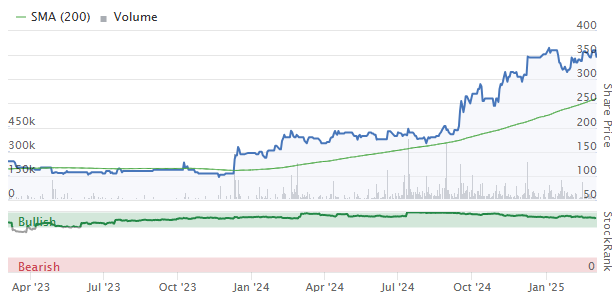
I’m going to maintain my previous view of AMBER/GREEN.
Investors can see a live presentation from Synectics on Investor Meet Company this morning at 11am.
Kitwave (LON:KITW)
Down 3% to 267p (£216m) - Final Results - Roland - AMBER/GREEN
Graham last commented on this food wholesaler and distributor in November, coming away with a positive impression. I’ve also been impressed by this business since its 2021 IPO.
Let’s see if today’s 2024 results support a continued positive stance – the market has taken a slightly negative view, but in the current climate that’s not necessarily very significant!
The Company is pleased to announce financial results in line with market expectations.
The headline numbers suggest to me that Kitwave has delivered another solid year of progress:
Revenue up 10.2% to £663.7m
Adj operating profit up 6.3% to £34.0m
Reported operating profit down 2% to £28.8m
Earnings per share down 13% to 23.5p
Total dividend up 1% to 11.3p per share
The drop in earnings partly reflects some dilution from a £31.5m fundraising used to fund an acquisition in September. A more positive picture is expected to emerge when the new business makes a full-year contribution to profits.
Profitability/leverage: The reason for the limited dividend growth becomes apparent when we consider the sharp increase in leverage over the last year. This was required to fund three acquisitions, including September’s £70m deal:
Return on invested capital: 11% (FY23: 19%)
Return on net assets: 22% (FY23: 30%)
Leverage inc leases: 2.8x EBITDA (FY23: 1.4x)
Leverage exc leases: 1.9x EBITDA (FY23: 0.8x)
Net bank debt of £63.7m (FY23: £25.7m)
While I give full credit to Kitwave for actually reporting a return on capital KPI, these figures clearly require some explanation.
The company makes this comment on profitability, from which I infer ROIC and ROA should improve in 2025:
The discharging of acquisition consideration has increased the investment capital and net assets in the relevant measure, but the contribution from the related acquisition has only been taken into account effective from the date of the acquisitions. This calculation is the principal reason for the reduction in the return on capital measures compared to the prior year.
Similarly, with leverage, Kitwave says:
Accounting for an estimated full year run rate effect of the acquisitions made during the year, the Group's leverage (inc IFRS 16 debt) would be below our stated target of 2.5x.
The company says it remained in compliance with relevant bank covenants at 31 October 2024, but the fact this was mentioned makes me wonder if the safety margin may have been slimmer than usual.
Balance sheet: for me, the picture painted by today’s accounts is of leverage at the upper limit of my comfort zone for a business of this type.
While Kitwave has a track record of generating attractive returns on capital, it’s a low margin business that relies on managing c.£100m of payables and receivables to generate attractive returns. This model can work well, but in my view it’s better achieved with the flexibility provided by a strong balance sheet.
I’d hope to see the company focus on deleveraging over the current year, rather than further large acquisitions.
Outlook & Estimates: CEO Ben Maxted makes a fairly vague statement on the outlook for FY25, which started on 1 November 24:
Despite the implications of the UK Government's Budget as previously disclosed in the November 2024 trading update, the Group has started the new financial year well.
Fortunately we have updated estimates from house broker Canaccord Genuity to fill in the blanks:
FY25E EPS 32.5p (previously 33.0p)
FY26E EPS 34.5p (previously 37.6p)
Canaccord says its estimates are essentially unchanged, except for some minor changes to revenue and cost assumptions based on FY24 results.
The broker notes that Kitwave has made 15 acquisitions since 2011 and is “well-placed to drive further organic growth in FY25 and extract scale synergies from recent acquisitions.”
Roland’s view
These forecasts are broadly in line with consensus estimates on Stockopedia and put Kitwave on a potentially reasonable valuation:
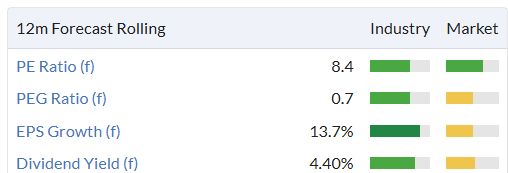
Kitwave has been a rare success story from the doomed 2021 IPO crop:
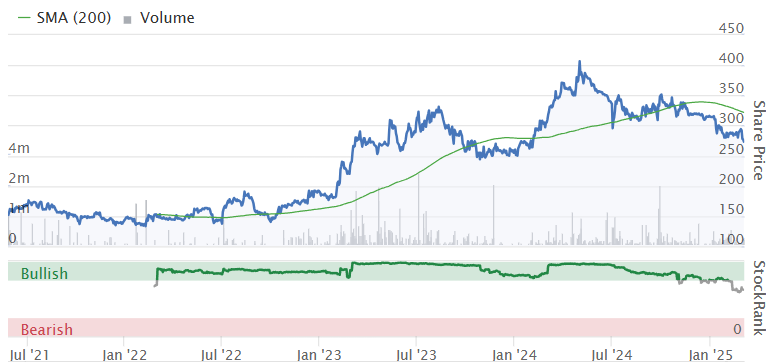
I remain a fan of this business, which has generated strong quality metrics in the past:
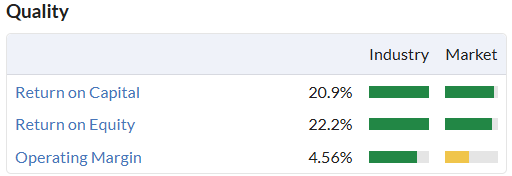
However, I would argue that today’s results highlight not just the opportunity, but the need for a period of consolidation and deleveraging.
Assuming trading remains on track, my guess is that there could be some scope for broker upgrades over the coming year, as was the case last year:
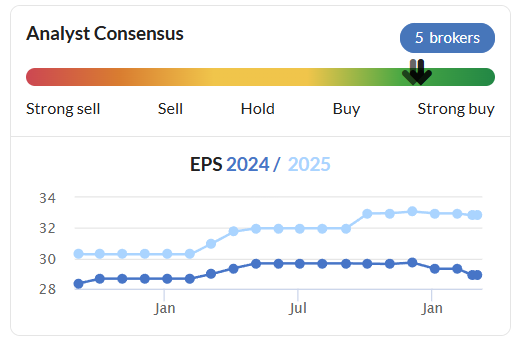
My sums point to an EBIT/EV yield of nearly 10% following today’s results. I think the shares could be attractively priced at this point, but I’ll hope to see some improvement in the balance sheet as the year progresses.
I’m going to maintain Graham’s AMBER/GREEN view at this point, based on Kitwave’s valuation and the strength of its track record to date.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
I also hold Card, and Jd Sports...and Renold! So I am seriously reevaluating my future as an investor. If I had put it all into a World tracker fund, I would be 50% up by now...but what's life without a bit of jeopardy???
See Ed Shing's ETF article two weeks back Bruce seems to be the way to go in my opinion, I think one problem investors have is unless you can do this pretty much full time you get caught out when we have times like the last week when everything dives and your either to busy with work or looking after children to react.
By the time you have caught up your in that "bugger its to late to sell now" mindset then chances are another 10-15% is going to come off the topline also.
I've got about 25-30 positions open at any one time and when stuff is going up its easy as doesn't really require much time maintaining the portfolio I still plough on with research 15-20 hours per week when I probably should just be reviewing holdings every evening at the first sign of possible wobbles.
We are all in search of the elusive grail of investment strategy but I just feel maybe 5-6 ETF'S as per Ed's article would be the way forward this would give diversification across bonds, global stocks, cash and gold.
I put portfolios together for clients and even something relatively low risk would have made 45% over last 5 years but in my personal portfolio I would be lucky if I have made 20% primarily because I have been in the wrong area in my Sipp UK small/mid caps.
No easy answers but I guess a lot of people on here are starting to feel like me in that despite 20 odd years in the market, meeting fund managers and the likes of J P Morgan monthly I still can't get above average returns.
Someone once said its probably easier to train and get into the olympics than reach the top 1% of traders.
The only thing I will say is if you stick with it we are fortunate some of the top 1% are on this board and are happy to share their knowledge.
Many thanks for taking the time to reply , Phoenix, your thoughts are very much appreciated.
Renold (LON:RNO) now at out near very strong support IMO. No bad news that I know. Hold IMO.
Yes, if you buy a long-term linker and then sell before maturity (but after a big change in real yields), you can lose your shirt. Holding to maturity is what they're designed for.
Thanks Graham
#ETL (Mrkcap €1bn)
Shares in European GEO-LEO satellite operator Eutelsat Group literally shot to the moon today (up +74%).
On the back of investor hopes that its services might be used to replace Elon musk's Starlink constellation in the defence of Ukraine.
The company (owner of OneWeb) adding earlier that it was “actively collaborating with European institutions and business partners” and had equipment that could be “deployed swiftly in Ukraine”.
Seems odd that the London listing Eutelsat Communications SA (LON:ETL) is down 17.7%.
I wonder if US listed Ast Spacemobile (NSQ:ASTS) could do similarly.That is if Trump 'allowed' them.What a disaster that person is.But not necessarily really bad for Europe if they can come to some common agreements quickly and step in and work together.
Why was there so much volume in Warehouse REIT 2 days ago. Its almost as though someone knew about the bid. Is anyone going to investigate this?
Well another stop hit. Had a few nibbles since new year, virtually all I have exited or stopped out.
And all dropped lower. Telling me nows not the time to put cash pile to use. Yet. Could be very wrong mind!
Every time I look at my portfolio it gets worse and worse :/
It's proper grim, just about to 10% down since start of Jan, trying to hold my nerve.
There's an easy fix for that... don't look!
Seriously though, investing is much less stressful if you do the gardening / hiking / skydiving (insert your favourite hobby here) during corrections, and re-engage when the tide turns (which it always does).
Yes, it's hard to look at portfolio values on days like today. Corrections will always hit your investing journey, many times I'm sure. The bigger the correction the more of an opportunity they present - just look at the charts during Covid.
Just wait until the news/social media is filled with stock negativity, doom and gloom (well, more so than usual!) and then invest some more or even better continually invest more.
Card Factory (LON:CARD) seems to be on a bit of a slide last couple of days, any news? Or just a big seller getting out?
I think you find that 99% of small caps are on something of 'a slide'. From my portfolio Jet2 (LON:JET2) Kitwave (LON:KITW) Sigmaroc (LON:SRC) WH Smith (LON:SMWH) and Card Factory (LON:CARD) all down over 5% closely followed by Bloomsbury Publishing (LON:BMY) down 4%.
Time for some gardening or a visit to the gym or allotment to paraphrase ISAallowance.
Roland, thanks for your comments on Keller (LON:KLR) but why not put them in a section below, it will be far easier to read? On my screen your comments are 35 lines long, some with just word on them.
That's unfortunate Rusty, are you on a tablet/phone? Perhaps check it in landscape mode?
I'm on an iPad Air, in landscape mode.
So Warehouse Reit (LON:WHR) might fall to a bid from Blackstone at 110p we learn today, and also that investors have been kept in the dark about the 3 previous approaches. Isn’t it scandalous that this is allowed? It’s nice work if you can get it for those in the know. Time surely for the rules to be tightened so that any bid approach has to be reported to the market? Also even today with the bid news out, so far Warehouse Reit (LON:WHR) haven’t issued a news update.
I hold a lot of REITS and the sector still looks bombed out, with so many on big discounts and paying big covered dividends. And bidders are taking advantage with several already falling to bids including EPIC and EBOX which I held at the time. I bought Warehouse Reit (LON:WHR) in January on the extreme multi year fall to just 76p compared with NAV of 128p!
If only more investors and some of those posting here about their investment despair would realise that there are bargains galore in the Investment Trust sector. And plenty more elsewhere too.
Anyway to the Warehouse Reit (LON:WHR) bid. It’s well short of the bidder price of 110p suggesting doubts that it will go through. NAV is 128p, A bidder won’t want to pay much more than 115p, so if Blackstone nudge it up a bid, that might do the trick.
Other REITS on big discounts that could be targets include CLS Holdings (LON:CLI) which I’ve bought today on a huge 55% discount. A negative is the too high 50% or so LTV which has put me off up till now. But the discount is so wide that a bidder might be tempted.
Custodian Property Income Reit 73p (LON:CREI) 28% discount.73p.
Schroder Real Estate Investment Trust (LON:SREI) 23% discount 50p
Supermarket Income REIT (LON:SUPR) 22% discount 70p. . There are plus and minus points to the news today with one post so far on this on the March Investment Trust thread:-
https://www.stockopedia.com/co...
(REITS get a lot of coverage on the Investment Trust threads including posts from timarr and others on another tempting one, Tritax Big Box )
Schroder European Real Estate Investment Trust (LON:SERE) 35% discount 66p.
Social Housing REIT (LON:SOHO) 54% discount. 57p,
A must go to site for all Investment Trusts is the AIC site (AIC are the trade body for Investment Trusts). The link below is for the UK Commercial Property sector. Clicking on each Trust then brings up loads of must know facts and figures on each one:-
https://www.theaic.co.uk/aic/f...
This is very useful insight Ken. You mentioned this a few weeks ago and specifically called out WHR I think as a potential takeover target.
I agree that it's a shame, as you said, that we only find out on the 4th bid as shareholders in the company (not even from the company itself) - something definitely needs to change there.... although unlikely.
Thanks for your useful post Ken.
Thought I should do a little research on REITS.
One REIT I wanted to reasearch was Primary Health Properties (LON:PHP) but I can't find it on the AIC website. Any idea why it isn't listed there? Any thoughts on Primary Health Properties (LON:PHP) ?
Thanks
I don’t know why (and if anyone does then please post to explain) why a few Investment Trust REITS aren’t officially classed as Investment Trusts and so are not included on the AIC Investment Trust website. These include CLS Holdings (LON:CLI) and Newriver Reit (LON:NRR) which I hold and also Primary Health Properties (LON:PHP) .
Thanks Ken
Glad it wasn't just me being dumb.
Snazzy
It might be something simple - that they are not members of the AIC.
I'd imagine that it's pretty difficult for a Board , like Warehouse Reit (LON:WHR) , to recommend a bid that's below NAV. Doesn't it amount to the Board admitting that the NAV is incorrect? What does history tell us in these circumstances ?
I answered your point last month about bids for REITS being too low if below NAV and have pasted that short post below. For Warehouse Reit (LON:WHR) where (as the The Hitman has just posted) I highlighted this bid chance last month, with NAV at 128p, a 110p bid is a a bit of a cheek and if they want to succeed they might have to up a bit. But with REITS if they pay the full NAV what’s in it for that bidder? Other REIT bids have succeeded below NAV.
Here’s that paste:-
Graham.
Have you taken in to account that Assura (LON:AGR) is a real estate investment Trust where NAV is a crucial factor, and not a Company where NAV isn’t?
Your comments about “no good reason for a Board to agree to give a company to PE at a discounted price,” would make total sense for a share (e.g a housebuilder trading at less than NAV) but doesn’t for an Investment Trust.
See topvest’s post to see that there might be another 2p or so if KKR are prepared to go that high. Note that other successful bids for Real Estate Investment Trusts have been successful at a small discount to NAV. e.g the EBOX example in my post earlier today.
Can you explain please why you think Assura (LON:AGR) is an exception and deserves to be sold for more than it is worth, and what would be in it for any bidder for any REIT prepared to pay more than NAV?
61 Reply
Thanks Ken, I always read your ongoing IT thread and have been educated doing so, good luck to you and congratulations on your Warehouse Reit (LON:WHR) result! I’m amazed the sector hasn’t rerated more this am, but great for investors! I guess it’s a much overlooked sector well away from the Mag7 spotlight!
Is there any evidence of recent property sales on the books and how what they achieved compared to asset value on the books? Curious how realistic the NAV is.
Can't remember if it was Warehouse or Tritax but when I looked into their books before, whenever they were selling off bits of the portfolio they were achieving 100% of NAV or higher
If the NAV is quite realistic, there is no way they'll take a bid like this. Might as well just sell their whole property portfolio on the open market. No way the costs of that would be as big as a giant % discount on NAV
Or just, y'know, continue running the business which is doing just fine and has no need to sell up?
I reckon Warehouse Reit (LON:WHR) is a sitting duck now, but agreeing to a deal at this price would be wrong - it's not just the discount but NAV is rising and interest rates are heading down. But if the board can't get a better deal then they need to go into wind-down - the company is probably worth 30% more than today's market cap.
FWIW I think if every company disclosed every approach then we'd be swamped with the things. Also as soon as the bid is disclosed then the bid timetable starts - if the board is trying to extract the best price for the company then disclosing the first bid wouldn't be in shareholders' best interests. Judging when to go public is tricky - but at this level I would hope the board would have been playing hardball, hoping to extract a better price.
timarr
Hi ken
I've been taking a good look at CLS Holdings (LON:CLI) but I was waiting on the Spring Mews deal, due any day now. If it comes in then it helps derisk and adds to confidence in the valuation. If it doesn't - well a billion in debt on a market cap of £250m looks a bit painful, albeit the interest cover looks fine. But there's a lot riding on their ability to make disposals.
Of course, the valuation reflects the risk.
timarr
Hi timarr
Re CLS Holdings (LON:CLI) . I hope I’m right to be optimistic based on this short bit in their last Results update:-
“Sales process for Spring Mews Student is progressing well and has generated significant interest with several bids received from experienced and well-funded PBSA owners.”
It’s the debt that has been a key reason I didn’t buy until today.
As for Warehouse Reit (LON:WHR) not having notified investors of the previous 3 bid attempts, your take on it was thought provoking, especially so your point about the bid timetable.
I agree too that with NAV rising now, and rising for other REITS too, there’s a strong case for wind-down to extract the full value. The snag with that is the time it can take. A bid even if it’s at a bit too cheap a price means investors can quickly sell and put some or all of the proceeds in to another REIT with a good chance it will be bid for.
The key point readers of the REIT posts can take on board is that the sector is cheap and full of quality choices on far too wide discounts, and a lot yielding 8% or even a bit more.
Supermarket Income REIT (LON:SUPR) looks a possible win win, in that it might see a bid and anyway with top notch Supermarkets their tenants, and almost guaranteed to pay the rent, the recent 66p multi year low and only 70p now seems bonkers and so it’s an obvious bargain anyway.
Tim i remember you flagging Abrdn (LON:ABDN) last summer I have just seen today the db pension by all counts is 800 mil in surplus so hopefully another asset within it that can be unlocked at some point.
Hi TP
Not had a chance to look in detail yet, but the update today provides some comfort that the new CEO is getting to grips with things. Hoping this will turn into another Aviva (LON:AV.) - new management doing sensible things to create value rather than destroying it.
A bright spot on an otherwise chaotic day ... :-)
timarr
Out of interest Tim some are predicting first quarter US gdp could be negative somewhere between -2-3% do you think that's now factored into prices or not ?
Out of interest Tim some are predicting first quarter US gdp could be negative somewhere between -2-3% do you think that's now factored into prices or not ?
Hi TP
I don't worry about that kind of detailed macro stuff. No one ever gets it right, other than by luck and even if they do predicting the direction of markets is a fool's game - they're usually moving six months ahead of events.
All I'm trying to do at the moment is figure out what to sell in order to buy more Abrdn (LON:ABDN) and REITs :-)
timarr
Abrdn (LON:ABDN)
Hi Phoenix
I too recall Tim flagging this one last year and after some research I bought some (thanks Tim!)
In response to your point the value behind the pension surplus is being unlocked. If you read the Annual Report and search for "£35m" you will see the commentary around this (spoiler alert: it's £35m pa.)
The benefit will start to flow through from July 2025.
A
Thanks Abtan plus they have a stake in Phoenix group (LON:PHNX) that was worth several hundred million.
Savannah Energy (LON:SAVE) , not a pretty sight today, is a company investing in Africa - say no more? I invested in 2019, things were looking good then there were problems and the shares were suspended in December 2022 until today. Meanwhile a Fundraisng occurred, to which small investors like myself were apparently uninvited, seeminly benefitting CEO Andrew Knott the most. Note that Stocko's performance graph doesn't show the missing years. They say that patience is rewared but in my case it was not, I remain suspended.
Silver Moon: I am in the same boat as you. Is there a light at the end of the tunnel or have they blocked off the tunnel completely?
I have not heard any news on this stock since 2022.
Does anyone here have any news on this company?
Graham , anyone?
Hi Goodfella, there has been quite a number of statements made by that company over the last 3 years mostly of promises. For me, it looks like being another Ra International (LON:RAI) and another Hummingbird.
Better Results at last from Abrdn (LON:ABDN) today, along with discarding the stupid ABRDN name for the obvious; Aberdeen.
This is one of so many examples where the £multi million buyback programme started 6 years ago at £5 and continued every year since, favoured those who sold (and big investors had that willing buyer in ABDN) and not those who stayed invested.
I held at £5 and remember groaning on that buyback news. As the share price fell steadily, as daily they announced big buybacks, I sold around £4. 40. I bought back again (too early as it happens) at 160p a couple of years ago. The share fell to £1.30 in January and aside from the near 10% dividend it has been a duff buy for those 2 years. BUT investors who saw the buybacks as one of the plus points, and who stayed invested all the way down from £5, were down nearly 80%. Those who sold early and bought back much lower missed that huge share price fall.
Now there’s a very good chance that Abrdn (LON:ABDN) will make further gains. They will be real gains for those who sold and bought back much lower. They will be losses at last being recovered for those who stayed invested. And it would need the share price to nearly quadruple from that £1.30 low to get back to £5 again.
One big plus for new buyers from the buybacks is a 40% decrease in the share count. The dividend has been held throughout and there are now far fewer shares to pay out the dividend. And it’s 1.5 times covered. Good chance of dividend increases ahead if the improved figures today and new Management optimism prove justified. Again though, it’s those who sold who benefit most from these buyback plus points and the fewer shares in issue to share eps on.
Market reaction to Abrdn (LON:ABDN) Results is positive so far with the share up 12% to 182p,
Another torrid day. About 70% in cash now. If trailing stops/stops keep getting hit I will be holding nothing shortly!!
Same on mine too thank you Mr Trump…… a bit of fear in the market. Even oil and gold shares are getting clobbered today
Good price is up, 2 gold miners l hold are both up, Serabi Gold (LON:SRB) and Pan African Resources (LON:PAF). Oil price is down.
Pan African Resources (LON:PAF) yet to get back to where it's been, still a buy? I hold both companies mentioned.
Not sure about Pan African Resources (LON:PAF) a lot depends, of course, on the gold price. It has not performed as well as Serabi Gold (LON:SRB) but downside maybe more limited. I'm holding on for now.
Hello JohnDoe. your quandary seems to match mine and I was interested in your thoughts. I appreciate that what I am about to say is contrary to this site i.e. we just discuss small companies but in the end those companies those companies will only thrive in an encouraging environment so Macro must be important. It seems to me that for Capitalism to work well then you must have a functioning Democracy. I am not sure this is the case in the worlds largest economy anymore. Certainly the law which supports good capitalism has been much diminished. So is holding cash such a bad thing? We all covet diversification so perhaps the discussion is how much cash and how safe is sterling now. Gold? Did you know in 1933 the US made it illegal for an individual to hold Gold. They paid around $20 an ounce and then devalued the dollar by over 50%. Bitcoin is something I shy away from and yet I am starting to see the value of an asset no Govt can fleece. Bonds? Tariffs etc are not deflationary despite some ridiculous arguments I have read to the contrary. I don't want Bonds in inflationary times. Real Estate, well then starts a debate about where, the UK? If anyone else reads this I am interested in their views too. I am not interested in arguing about politics or what Trump is doing (in my view he is Russifying the US) but how we can all ringfenc eand perhaps protect some of the wealth we have accumulated over a life time of work. A bit left field but I thought it may begin an interesting discussion of more value than whether UK small caps are fairly valued because I think we all know the answer to that.
Pretty much agree with all of that, but it might be worth learning about US inflation protected bonds (tips).
I need to put some time to study these as some of the shrewder defensive minded fund managers I meet are all over this asset class at the moment.
Maybe someone who has a decent understanding might chip in, my own thoughts were that inflation linked bonds are the most volatile of all so you wouldn't want to buy them until you are sure (as you can be that inflation has peaked).
However as I say people who are smarter and with greater resources than me are buying and seem to remember Ed Shing was positive on them recently.
RD if your reading this maybe you have a view or anyone else who understands this area of the market would very much like to hear your input.
Regards
Andy
Hi Andy, I used to buy UK linkers in a former life. I thought they were the most boring of all investments. You weren't betting on a business, or a country, or a commodity, or even RPI! You locked in a real yield (pretty sure it was negative at the time) and that was it. If inflation rose, you were protected. If inflation fell, it would cost you but you would still earn the same real yield.
Despite finding them very boring on a personal level, I can't deny their economic importance and their usefulness. They are wonderful in a defensive portfolio. They are inherently hedged, by design. They protect purchasing power. They insulate a bond portfolio from one of its key risks. And they even allow speculation on real yields, which can be useful for some people.
Thanks Graham my understanding though is that rising yields is bad for bond prices and the longer the duration the more extreme this gets so although your income/yield in linkers would be protected against inflation would the capital value of the bonds not take a big hit ?
Yes long-dated linkers are very sensitive to rates and can be extremely volatile in the short-term. I think 10-year US TIPS look interesting though - you're getting a positive real yield and not too much duration risk - a pretty good safe haven investment if inflation takes off again.
Thanks Bouden
Well, Trump won't be able to seize American citizens gold and then devalue the dollar this time round.
Checks portfolio ... what a mess. Nearly 2% down. It's seems a very bipolar market right now. The market is handing out both double-digit gains and double-digit losses. It all seems a lucky dip.
GRG Down 11% despite showing sales up 11%. It's on a fwd PE of 15, which is a level you don't often see. I don't hold, but we've had situations in the past where sentiment is negative and it has proven to be a buying opportunity. We shall see.
Apparently stocks go up as well as down.
If I was an XP Power (LON:XPP) holder right now I think I would consider ditching it. The share price is sitting at today's placing level despite pretty terrible numbers and the dreaded 'half 2 weighting' for this year. They also lost a court case in January that is costing quite a lot. Surely this would be down considerably more than 5% in normal circumstances. Looks to me like a placing at the wrong price and the company's broker desperately trying to hold the shares at that level to keep placees happy. What do others think?
I ditched it
Such a difficult market to navigate. Impossible at present I would say.
I don't hold and haven't read the RNS in full but at first glance I thought that Greggs (LON:GRG) results were pretty good, yet the shares are down 10% or thereabouts .
Kitwave (LON:KITW) I hold and an initial skim of the prelims and outlook read well. I have little doubt the the share price will head south despite the current miserly rating, like many good quality small caps.
On the subject of AiM, In the long term I don't think it matters that a company is AiM listed. If it executes well with good management and capital allocation and treats employees and shareholders fairly, it will ultimately prosper.
Kitwave (LON:KITW) difficult year but FY 25 "started well". Of course drops!
Hard luck to Team Internet (LON:TIG) holders. Possible bid talks ended and a profit warning. Ouch! Another of the 'share buyback' brigade that always had too much debt for the market's liking but chose buybacks over debt reduction. Not for me.
Reach (LON:RCH) results look decent!
Good morning. Hope you find time to review Synectics (LON:SNX) today. It would be greatly appreciated.
After a quick read of the results I am struggling to find any negative comments within the report.
Mk cap £60m
Cash of £9.6m No debt
Profits increased by 56%
EPS up to 21.6p
Dividend up 50%
Strong order book. R&D continues. Looks promising for growth as critical structures such as data centres and power stations need upgrading of security. Gaming world (Casinos) starting to recover.
The company has a lot going on and while they see double digit growth to continue they see fruition to really happen 2-3 years time.
Only downside I am seeing is II, Whitehall has been selling in recent months. I see that though as only temporary and the share price did need some consolidation time. It is also a good thing that Whitehall have reduced which I see as increasing liquidity as SNX does not have too many shares on the market.
Shore capital have released a good detailed report for Synectics (LON:SNX. Suggests that while the sp has done well, there is plenty of scope for it to go further suggesting a DCF price of 486p.
Synectics (LON:SNX) shares were up initially but are now falling, can buy for 340p.
Yep noticed that. Whitehall selling I’m guessing. Unless there is something I’ve missed.
Synectics (LON:SNX) I have topped up, at 338.5p, shares are rising now.
Yep market killing everything at the moment. Not sure what more they wanted from SNX results.
Synectics (LON:SNX) I hold. Thanks for message gmtrader. I was eagerly awaiting these results and this is encouraging. I plan to slowly reduce my AIM exposure and also tidy my portfolio overall but hopeful Synectics is a keeper. I also hold two other companies announcing this week Hunting (LON:HTG) and Lancashire Holdings (LON:LRE)
Another “Materially Ahead” announcement from Synectics (LON:SNX) (Sept, Dec and Today). Outlook is confident and the order book is +24% ahead of last year.
Synectics have recently launched market leading casino AI software which includes face recognition and risk surveillance, with known/unknown human behaviour video analytics to follow soon.
Synectics (LON:SNX) are helping casinos ensure the winning odds stay in their favour! See https://synecticsglobal.com/resources/ai-casino-trends-2025
Fresnillo (LON:FRES) No doubt I was sleeping at the wheel but the special dividend is a welcome surprise to me. Generally speaking I am braced for bad news on results day from mining companies. And then the commodity price bails you out. So when the stocks are out of favour but the commodity isn't .... special dividends are a nice way of saying we are making lots more money than we need at the moment. Let's face it, mining companies normally have a raft of silly ideas to waste excess money on....and shareholders are at the back of the queue. Even those at the back reach the front eventually and so fingers crossed......maybe these unpopular shares can gain more favour. In the meantime thanks for the divi.
Origin Enterprises Plc (Origin Enterprises (LON:OGN)) is showing signs of a cautious recovery this morning in their interim results highlighting strong EPS growth (+38%) and a 17% rise in operating profit, driven by a recovery in agriculture volumes and continued strength in its Living Landscapes division. While group revenue dipped slightly (-2.7%) due to lower global feed and fertiliser prices, the company is diversifying into environmental solutions through Living Landscapes, expanding its exposure beyond traditional agriculture. The new sustainability linked credit facility and ongoing share buyback add confidence. I have been invested here for a while, but I think that this is one to watch for those seeking an under the radar agri-environmental play. Anyone else watching this?
Tremendous results from SNX with it seems exceptional performance across all aspects of their business.
Really feel this could be a takeover target this year.
Statement re Possible Offer Warehouse Reit (LON:WHR)
https://www.investegate.co.uk/...
.
The collapse in the Atlanta Fed's Q1'25 GDPNow forecast (see below link for graphic) is certainly something for investors to watch.
Sure there's a degree of normalisation after the +2.3% Q4'24 reading, which was artificially boosted by the stocking of imported goods (say from China) ahead of Trump's new tariffs.
Yet nonetheless, the estimated steep decline in US output to -2.8% (yes, minus 2.8%) does imply the economy may have hit a mini brick wall.
Plus at 1.30pm on Friday, will see any DOGE impact wrt the US' February non-farm payrolls (est +156k net new jobs created and 4% unemployment) – this is a lagging indicator.
>>Yet nonetheless, the estimated steep decline in US output to -2.8% ...>>
Is that 2.8% an annualised figure, so that if the GDPNow forecast is correct GDP would reduce by 0.7% in Q1?
Unlikely to see any impact on the payrolls yet. Most of those cut by DOGE are on deals where the continue to get paid for at least 3 months so will still appear to be 'on the payroll' for a good while yet - these 'ghost jobs' will only drop out later in the year.
Stonking dividend increase out of Beazley (LON:BEZ) today, who have had an excellent year and a good outlook to come. I have a modest holding, sadly.
20% increase in operating profit for Bakkavor (LON:BAKK) .
In a sign that the new CEO is rapidly getting to grips with the problems Abrdn (LON:ABDN) has faced since it changed its name from Aberdeen Group:
We are announcing today that we will change the Company's name to aberdeen group plc
At first blush the results look OK too, with operating profit up and some ambitious targets. Complicated as ever, mind, will take some unpicking. Dividend maintained.
timarr
I wonder how much that cost and wasted on the old name? Couldn’t fathom what real benefits the abstract name offered.
A consultant probably pitched that he had an amazing plan to change the name to make the company look windswept and interesting, and convinced the management that it would be a good idea. 'Oh chaps, we have some money in the marketing budget, we haven't spent this year. I know let's change our name'.....The consultant walked away with a large fee and is on the next poor target.... probably Jaguar but I don't want to come across as cynical at all.....
Decent looking results from Greggs (LON:GRG) if you get chance to cover please!
Sorry when I said decent I actually meant shocking - down 10.5% and counting
This market seems impossible atm
That's done, JSchoffer! Cheers. G