Daily Stock Market Report (Tue 5 Nov 2024) - SNWS, ASC, TCAP, SDR, VOD, MGAM

Good morning and welcome to the Daily Stock Market Report! This is the new name for our daily report, previously known as the Small Cap Value Report. Don’t worry, we’ll still be covering all the small company stories that matter to you. But we’re also aiming to expand the breadth of our coverage - you can read more about the incoming upgrades to our content and analysis here.
This morning we have Graham, Megan and Roland helping to cover today’s news.
Graham writes: we're hanging up our collective pen now (2pm). Thanks for reading!
Explanatory notes
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices).
My video explaining/reviewing it.My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
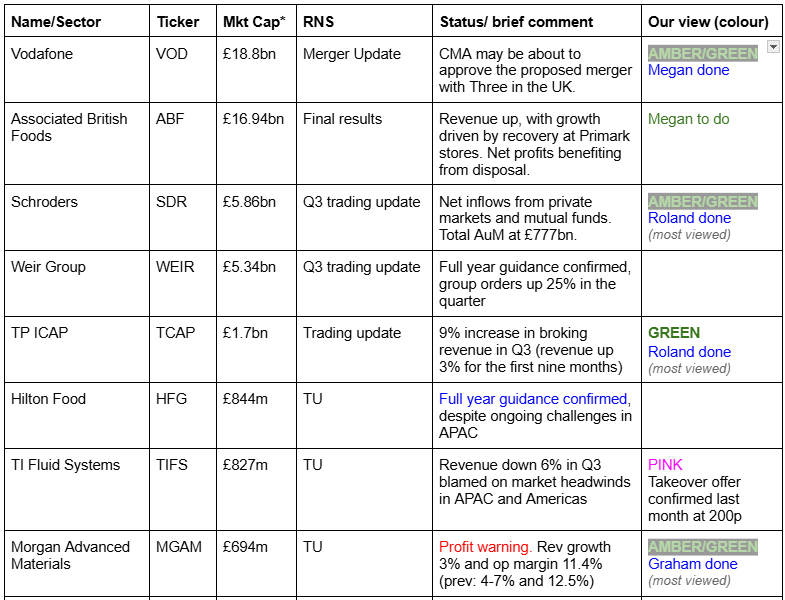
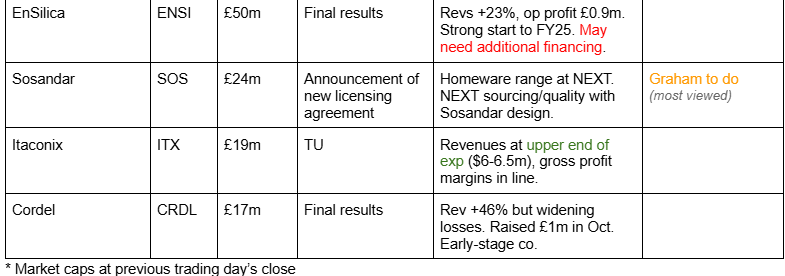
Summaries
Smiths News (LON:SNWS) - up 7% to 61p ( £151m) - Final Results - Graham - GREEN
Results come in ahead of expectations (we already knew that they would be “at least in line”). Operating profit is £39.1m and the company declares a special dividend of 2p due to being under-leveraged. The outlook for the new year is in line and I continue to like this one at a PER of only 5.4x.
Morgan Advanced Materials (LON:MGAM) - unch. at 245p (£699m) - Trading Update - Graham - AMBER/GREEN
Officially this is a profit warning but I think the market was expecting it after a woolly outlook statement a few months ago and given the declining share price since then. More interestingly, the company has announced a £40m buyback and an expanded cost-cutting programme. Could be worth a closer look.
Asos (LON:ASC) - down 8% to 346.7p (£414m) - Final Results - Megan - AMBER/RED
Sales are down 16% like-for-like, below expectations, and the company remains loss-making. It is now trying to increase order sizes by invoking a £40 threshold for free returns. I see little to like here from a quality perspective and it’s probably still too soon to make a value argument for the shares either.
Vodafone (LON:VOD) - up 1.4% to 73p (£18.8bn) - Merger Update - Megan - AMBER/GREEN
The Companies and Markets Authority (CMA) has revealed it might give the go-ahead to Vodafone’s plans to merge its UK operators with Three. The two telecoms companies announced their merger proposal in June last year, but the deal has been held up by concerns from the regulator that the two companies might drive up prices. News that the deal could get the green light when the CMA makes its final decision in December has been well received.
TP Icap (LON:TCAP) - up 3% to 234p ( £1.8bn) - Trading Statement - Roland (I hold) - GREEN
A solid Q3 update from this FTSE 250 broking and data group which suggests to me that the business remains on track after a strong Q2. The shares have risen this year but remain attractively valued, in my view.
Schroders (LON:SDR) - down 14% to 314p (£5.1bn) - Q3 2024 update - Roland - AMBER/GREEN
Assets under management rose thanks to positive market movements in Q3, but there were net outflows. Management have warned that Q4 could see further significant outflows before a more positive period in 2025. I argue that the company needs tighter control on its cost base and perhaps more focus, but could be attractively valued after a multi-year decline.
Graham's Section
Smiths News (LON:SNWS)
Up 7% to 61p ( £151m) - Final Results - Graham - GREEN
We covered the full-year trading statement from SNWS here, when it confirmed that full-year adjusted operating profit would be “at least in line” with expectations of £38.2m.
That number comes in today at £39.1m (slightly higher than last year, and ahead of expectations) on revenues of £1.1 billion (up 1%).
Here are the headline numbers from the UK’s largest wholesaler of newspapers and magazines:
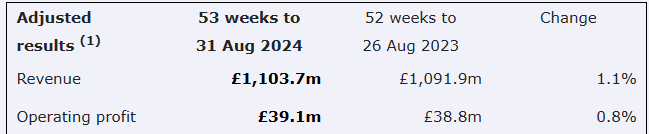
FY24 had 53 weeks, while FY23 only had 52 - something to bear in mind when there are only marginal differences between the two financial years.
Average net debt did see a meaningful reduction: it more than halved to less than £12m (from £25m).
The adjustments are minimal. In fact the statutory (what I call “actual”) operating profit of £40m is higher than the adjusted operating profit.
91% of revenues are set to renew under long-term agreements, either in the form of signed contracts or Heads of Terms, until 2029, suggesting excellent visibility (74% of revenues will repeat under signed contracts, with an additional 17% under Heads of Terms).
Outlook: in line with expectations, and there has been a start to the new financial year.
CEO comment snippet:
"Our performance over FY 2024 reflects the resilience of our news and magazines business and impact of our cost efficiency initiatives. The refinancing agreement announced in May removes restrictions on shareholder returns and also enables internal investment to support both our news and magazines business and our growth plans…
Smiths News is well placed to continue to deliver a resilient performance over the medium term.
Refinancing/dividend: back in May, SNWS received a new £40m RCF with better terms than the previous facility. The old facility only allowed a max of £10m to be paid to shareholders annually. With that cap out of the way, SNWS announces a 2p special dividend in addition to a final ordinary dividend of 3.4p.
Including an interim dividend that has already been paid, they are distributing an impressive £17m to shareholders for the year. They can afford to do this as their leverage ratio (net debt/EBITDA) ended the year at only 0.3x, far below their self-imposed limit of 1.0x (the bank will allow up to 2.5x).
Graham’s view
I see no reason to change my view from what I said in October: this is an interesting value stock that I'm happy to give the thumbs up.
It trades at a pitiful earnings multiple:
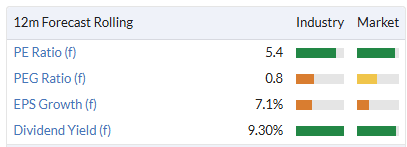
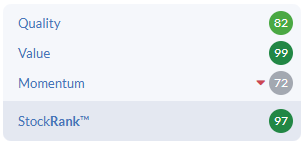
And it gets a perfect Value Rank of 99, while still offering some Quality according to the algorithms:
Probably in truth it is a melting ice cube, as newspapers and magazines are in long-term decline. But of course everyone knows this, and it has been true for many years.
According to the Press Gazette, the year-on-year decline in newspaper circulation is currently running up to 20% (Sunday People), with only a couple of the free newspapers (Metro and City AM) bucking the trend.
So when SNWS says that up to 91% of revenue is set to renew until 2029, maybe we should assume that this is a best-case scenario.
However, at a PER of a little over 5x, and with the company doing a great job of finding cost savings, perhaps the gloomy industry outlook is priced in?
Personally, I’m inclined to think that print circulations could stabilise at some point in the next few years - could there be a point where everyone who wants to read the news online is already doing so?
It might be a risky call but I continue to like the risk:reward here, and will keep giving it the thumbs up.
Morgan Advanced Materials (LON:MGAM)
Unch. at 245p (£699m) - Trading Update - Graham - AMBER/GREEN
Morgan Advanced Materials plc, the global manufacturer of advanced carbon and ceramic materials for technically demanding applications, announces today a trading update for the first nine months to 30 September 2024.
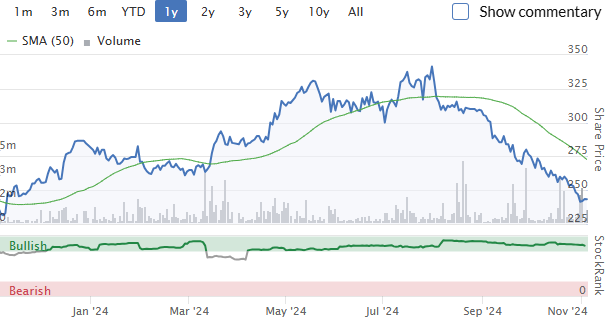
MGAM hasn’t made it into this report before. The stock has taken a dive in recent months:
Roland has covered it in his SIF Portfolio, most recently here when he noted a vague outlook statement at the interim results and declining earnings estimates.
Given that the share price has barely moved today, I think we can safely say that the market priced in the bad news the company has published.
Outlook/Profit warning:
Market conditions have weakened during the second half and we are now seeing a further deterioration in our outlook for the fourth quarter. Our outlook for constant currency revenue growth for the full financial year is now around 3%. Together with additional FX headwinds, we now expect an adjusted operating profit margin for the year of c.11.4%.
The half-year guidance was for full-year revenue growth towards the top end of the range of 4-7%, and an adj, operating profit margin of around 12.5%.
But sales for the first nine months are only up by 3.8%, and Q4 is shaping up poorly.
Simplification programme: the company is looking for even more cost reductions than it was before.
Previously: £10m of annualised savings were targeted, with a one-off cost of £20m.
Now: it wants a total of £22m in annual savings with a one-off cost of £45m.
This cost-cutting programme is set to complete by mid-2026 and the money to pay for its implementation will be at the expense of spending on increased capacity. So there is no doubt that this is a very defensive move by the company, but should hopefully set it up to achieve a position of strength from 2026.
Share buyback programme: the announcement of a £40m buyback is not what you’d normally expect to hear from a company that is defensively cutting costs. But if you scroll back to the interim results, its leverage multiple as of June 2024 was only 1.3x (excluding leases), within its target range for quiet periods without any major M&A.
As it seems that there are no major M&A deals coming up in the short-term, the company is happy to plough cash flow into a buyback instead.
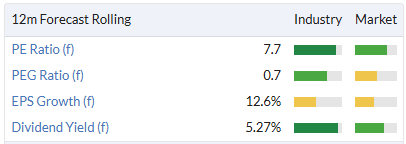
It’s a little unusual but it does make sense to me. I know that buybacks can be controversial, especially when it seems that companies are overpaying for their own shares. But the valuation on offer here doesn’t seem excessive, even if forecast earnings need to be adjusted slightly lower:
CEO comment:
"We are seeing a weaker trading environment in the near term and are expanding our simplification programme, continuing our track record of self-help. We remain focused on delivering enhanced returns to shareholders and are pleased to be able to support this in the near term with the additional cost savings and share buy-back programme, both announced today. Our business is well positioned with leading market positions, a strong balance sheet, and attractive opportunities in both faster growth and core markets as markets recover."
Graham’s view
I’m inclined to go AMBER/GREEN on this, as the combination of cost-cutting, share buybacks and a low-ish earnings multiple all appeal to me, even if the company is lowering expectations today.
The share price is down by about 25% from where it traded earlier this year, which at first glance seems harsh in comparison to declining EPS estimates (they are down, but not yet by 25%):
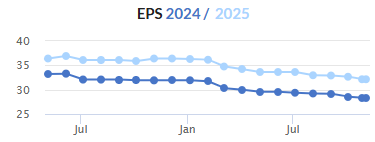
And if the company buys back £40m of stock, that could reduce the share count by over 5% and provide a nice little tailwind for future EPS.
So this one strikes me as being worthy of further research. It’s not high conviction for me but I’m satisfied with AMBER/GREEN.
Megan's Section
Asos (LON:ASC)
Down 8% to 346.7p (£414m) - Final Results - Megan - AMBER/RED
The recent share price spike which followed the news that Asos had secured additional financing following the part sale of its Top Shop family of brands, did not stick. The share price is back below 400p and has fallen further following this morning’s final results announcement.
Revenue continues to slide owing largely to a 16% decline in the number of active customers on the site (from 23.3m in the year to September 2023 to 19.6m in the 2024 financial year). A slight uptick in the average basket value (from £40.33 to £41.07) failed to offset the decline in customers and their frequency of orders.
Declining customer numbers is a problem that Asos will struggle to deal with. The market for online shopping has shifted in recent years, putting extreme pressure on the model that Asos pioneered in the UK in the early 2000s. Today, young shoppers are far more likely to buy cheap goods from Chinese competitors than they are from the UK. While a surge in environmental consciousness is turning yet more chunks of Asos’ former stalwart customers from their site.
Marketing costs rose from 5.5% of sales to 6.6% in these numbers, but marketing alone is not going to rescue the company’s dwindling sales.
Growth therefore must come from increased order sizes and Asos seems to be attempting to secure that by invoking a threshold for free returns. Now, customers will have to keep £40 worth of goods ordered to qualify for free returns.
I am dubious that this move will have the impact that Asos hopes it will. The company risks alienating its core customers even further. Sales this year were down 16% on a like-for-like basis (below expectations).
Gross margins have fallen further to 40%; they averaged over 50% before the pandemic.
Inventory levels have come down 50% over the last two years and are now at a more manageable £520m. Management says this improves “newness for customers” (not a great use of the English language), but more significantly for shareholders it improves the financial flexibility of the business. Fresher inventory should also help improve average selling prices and contribute to lower discounting (positive for margins in the long run).
Better balance sheet health has also had a positive impact on operating cash inflows in the 2024 financial year. The cash cost of payables (short-term debts owed by the company to its vendors) was almost £300m lower this year, allowing the company to report operating cash inflows of £217m.
These results don’t reflect the refinancing, completed after the period end, which should support the weakening balance sheet. But (as Paul commented in our last coverage of Asos), at what cost? Asos has ceded control of one of its higher quality brands and stomached a material loss on the investment it made in Top Man during the pandemic.
Megan’s view
Recent momentum, from the news of the joint venture, did not last long.
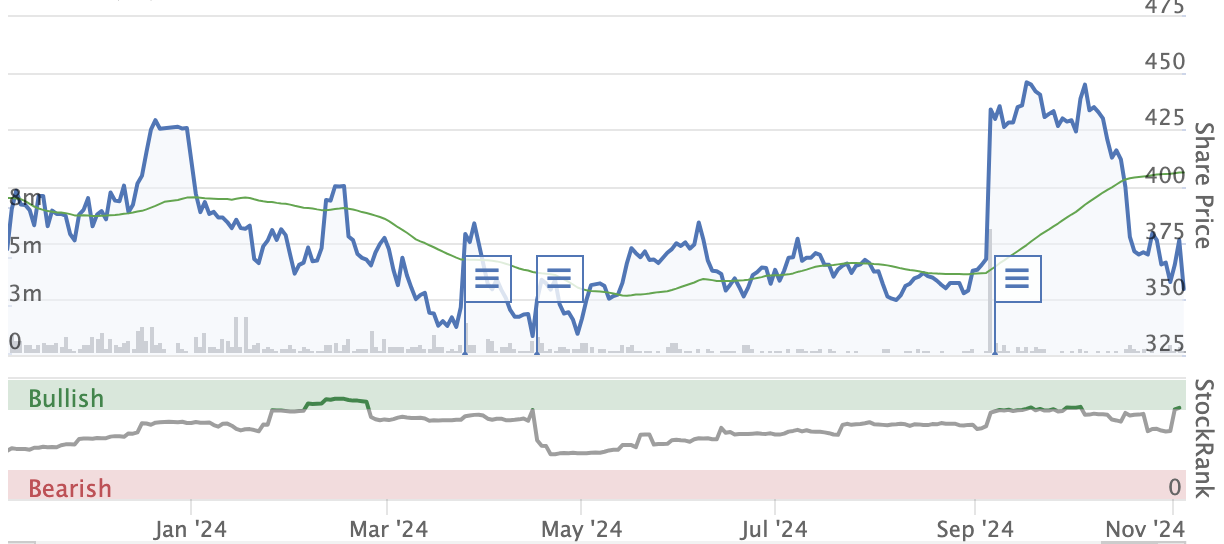
The company’s share price has underperformed the market by more than 14% in the last month and its momentum rank is now falling.
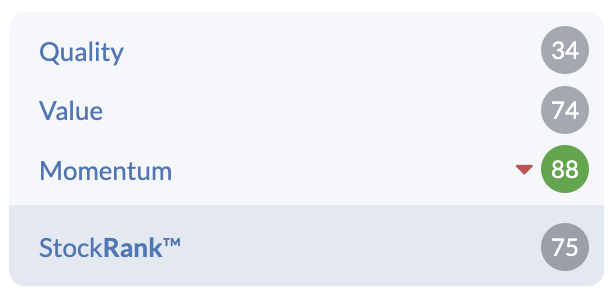
There is very little to like from a quality perspective. Margins are waning and the company has been loss-making at the operating level for three consecutive years.
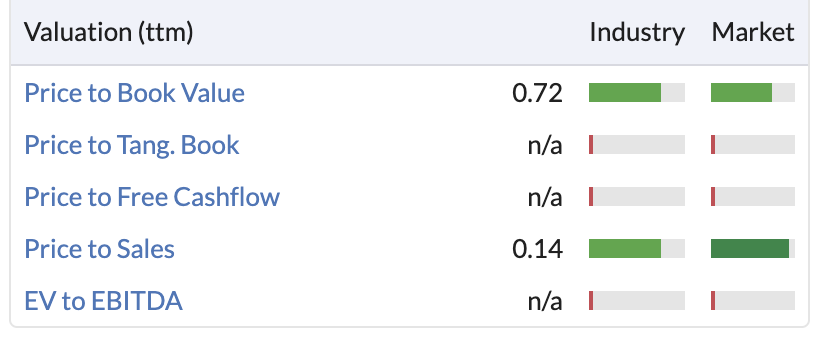
Without profits, it’s hard to make a value argument either. Shares trade on just 0.14 times sales, but revenue continues to decline, meaning price/sales is not a great metric on which to base a valuation argument.
I have recently been familiarising myself with the deep value approach to investing (you can watch the webinar that Mark and I hosted recently here) and there could potentially be an argument to make about Asos heading towards deep value territory.
The company has a net current asset value of £95m (before the recent joint venture) so if the market cap keeps heading towards £100m, this might become one for the deep value investors. For now though, I am sticking with Paul’s Amber/Red rating.
Vodafone (LON:VOD)
Up 1.4% to 73p (£18.8bn) - Merger Update - Megan - AMBER/GREEN
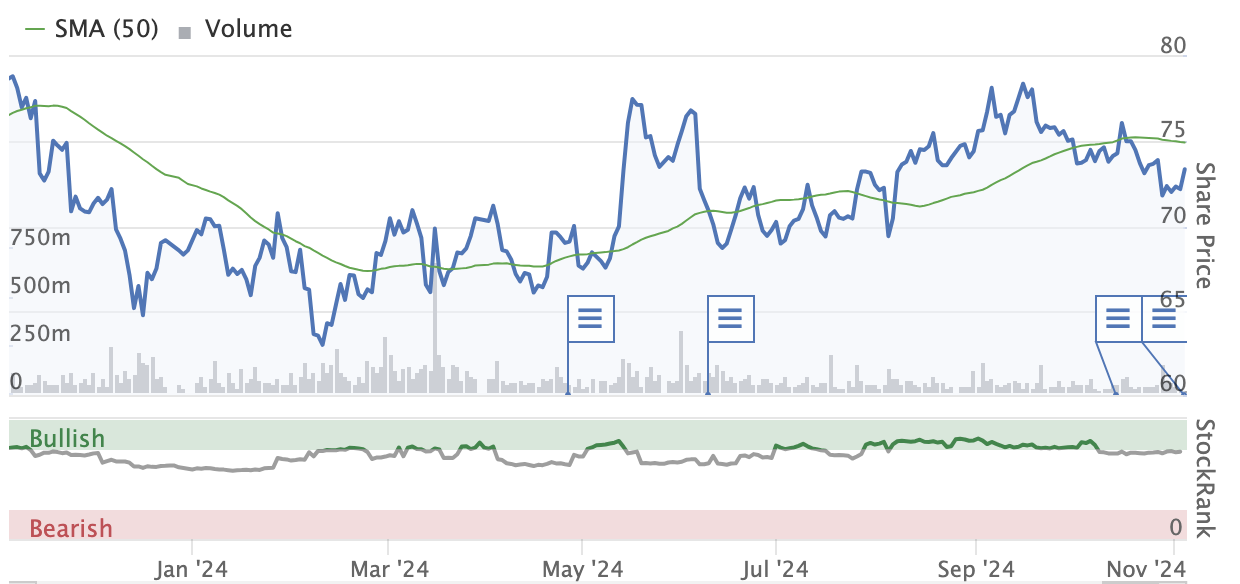
For retail investors, the main draw of a holding in Vodafone is its dividend. In May, these shareholders were forced to stomach the disappointment of a major dividend cut (from 9¢ a share in 2023 to 4.5¢ a share this year) after the company revealed it could not afford to keep paying out such high amounts of cash to its shareholders given the volume of debt and anaemic growth.
It’s the second blow to Vodafone’s income investors in recent times. In 2019, the company slashed its final dividend to 3.7p (from 9.1p the previous year). For the last special payout, you’d have to look back to 2012.
But sometimes dividend cuts are the healthy thing to do and in Vodafone’s case, this is certainly true. The share price has dropped significantly since 2019 to reflect the cuts to the payout and shares are now yielding 6.07%. That’s certainly tempting, but the crucial question is: is the dividend safe at current levels?
The 2024 dividend, (the second chunk of which was paid in August) was not covered by earnings, but the dividend forecast to be paid in 2025 is covered by forecast earnings.
Today’s announcement that the UK business could be merged with Three will also be a relief to shareholders. Growth in the UK division of Vodafone has been sluggish as the company has struggled to invest in its domestic infrastructure. Merging with Three into a joint venture which would be 51% owned by Vodafone and 49% owned by Three’s UK owner, CK Hutchison Holdings, would allow for greater investment in a resilient 5G network.
Megan’s view
Vodafone has long been an income stalwart for UK investors and remains so, despite the major dividend cuts of the last few years.
The strategic direction of the company, which includes chopping out the cash draining chunks and implementing mergers (like the proposed merger with Three) to allow for more investment seems sensible.
This definitely isn’t a growth stock. But while the dividend looks safe and comes with a decent yield, I am pretty positive about Vodafone for income investors.
Roland's Section
TP Icap (LON:TCAP)
Up 3% to 234p ( £1.8bn) - Trading Statement - Roland (I hold) - GREEN
The Board is comfortable with FY 2024 market expectations for adjusted EBIT
I hold shares in this FTSE 250 interdealer broker group in the SIF model portfolio and my personal holdings. It’s also a stock that’s caught my eye for its high and apparently well covered dividend yield.
As I see it, the investment case has two core elements that could drive a re-rating from the current modest P/E:
Improved performance from the broking and exchange businesses after a period of reshaping and M&A
Potential for significant value to be released by a partial spinout of the high-margin Parameta Solutions data business
Today’s trading statement is fairly brief but seems broadly reassuring to me. Let’s take a look at the main points (all figures in constant currency):
Record Q3 group revenue up 10%to £557m - a new record for the business.
Global broking revenue up 9% - this division arranges transactions between financial institutions in areas such as FX and interest rates. Rates is the largest and most profitable asset class – Rates revenue rose by 14% in Q3, although I wonder if this masks weaker results in some other asset classes.
Liquidnet - this is an equity trading venue providing block trading and other liquidity services for institutional investors. Reports strong trading in Q3 with revenue up 28%.
Energy & Commodities broking revenue rose by 3% against a tough comparator in Q3 2023.
Parameta Solutions - revenue up 9%. This is a data analytics service specialising in OTC markets such as those served by TP ICAP’s other operating units. Parameta has an adjusted operating margin of c.40% and is seen by many investors as undervalued within TP ICAP, when compared to some rival data businesses.
I share this view, although I am struck by the relatively slow rate of revenue growth in this business. Nine-month revenue growth for Parameta is only 10% and FY23 revenue growth was only 8%. I wonder if this slow growth could act as a constraint on the value that can be released in a possible spinout.
Business update: a strategy update will be provided with the FY24 results in March. For now, the company confirms it's continuing to investigate “strategic options” in relation to Parameta Solutions, including a possible IPO. This might be in the US, although nothing has been decided yet.
Roland’s view
TP ICAP’s performance appears to have gained momentum this year:
H1 revenue +3%
9 month revenue +5%
Q3 revenue +10%
This appears to support management’s claim that strong Q2 momentum continued into Q3.
The reality is that some elements of this business, notably the broking business, are somewhat mature and will always be exposed to external market conditions. But I’m comfortable that this group is performing well, probably better than for some years.
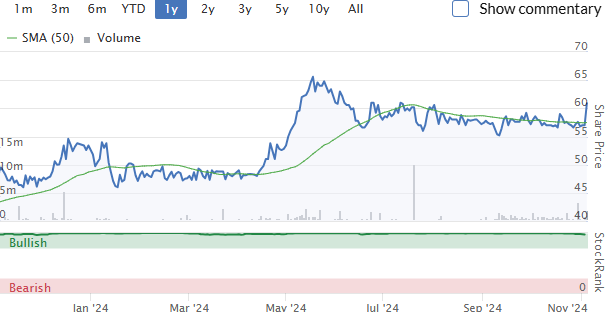
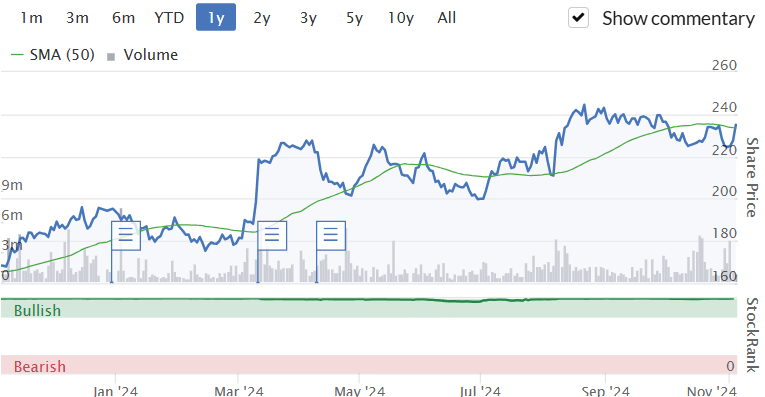
The shares have also done well over the last year, gaining around 40% and remaining highly ranked:
One point worth making may be that while TP ICAP is cash generative, historical profitability has been somewhat average:
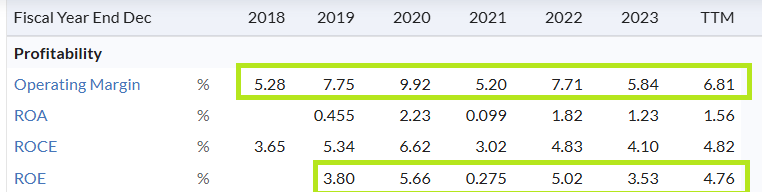
Low profitability might help explain the low valuation and supports the argument that Parameta could be more valuable if spun out.
However, consensus estimates suggest to me that TP ICAP’s adjusted operating margin could rise to a low-teens level in 2024, with a corresponding increase in return on equity. This might help to support a higher valuation, in my view.
Outlook: Today’s update confirms FY24 adjusted EBIT guidance, subject to any outsized FX movements (TP ICAP is heavily exposed to the USD).
Broker notes aren’t available to me, but I’d imagine it’s reasonable to continue relying on Stockopedia’s consensus earnings estimate of 29.5p per share. This prices the stock on a FY24 P/E of 8 with a 6.5% dividend yield – still very modest, in my view.
While the shares aren’t quite as cheap as they were, TP ICAP still appears to be on a positive trajectory. I remain positive about the outlook here.
Schroders (LON:SDR)
Down 14% to 314p (£5.1bn) - Q3 2024 update - Roland - AMBER/GREEN
Total assets under management (AUM) reached a new high of £777.4 billion and the Group's net flows for the nine months to 30 September 2024 totalled £1.6 billion.
This morning’s third-quarter update from FTSE 100 asset manager Schroders has triggered a moderate sell off. Shares in this family-controlled business are down by 14% as I write, extending a multi–year decline that’s seen the stock fall by nearly 50%:
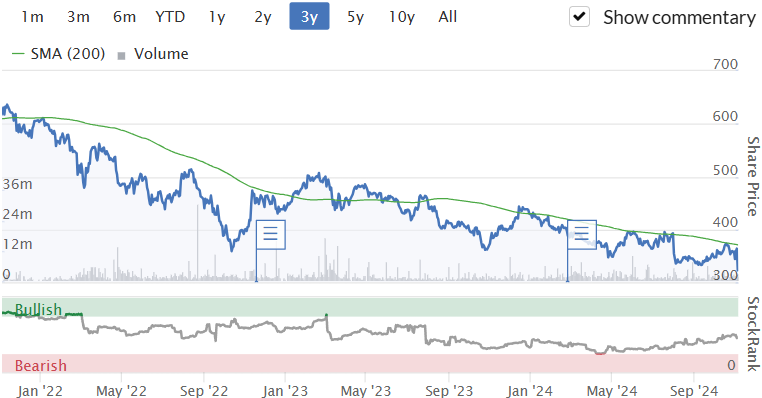
Let’s take a look at the news that has prompted this slump.
AUM: Total assets under management rose by £3.7bn (0.5%) to £777.4bn during the third quarter, but this was driven by market movements (+£6bn) offsetting net outflows (-£2.3bn). I’ve pasted in the table showing AUM movements below to highlight the scale and complexity of this business:
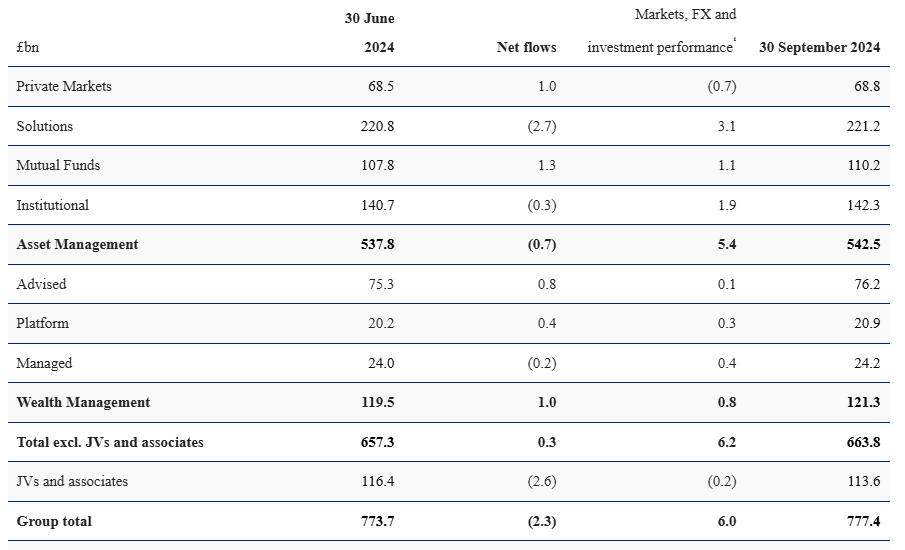
While I’m reassured to see positive market performance, ultimately net inflows are required to drive a recovery in profitability.
Unfortunately, the company’s comments suggest that Q4 2024 could be a dire period for outflows:
£2bn of losses from three institutional clients
£8bn of outflows on the legacy Scottish Widows mandate (although this will see regular outflows by its nature)
The company expects to report more positive progress in 2025, when management says “there are good mandates funding across Asset Management”.
Time will tell. But I would argue that today’s news is only more of the same from Schroders, highlighting a persistent underperformance and erosion of profitability.
We can see this readily using the data presented on the StockReport. Profitability has declined steadily for years, as revenue growth has failed to keep pace with cost growth and acquisition spending.
Since 2018, revenue has risen at a compound average rate of 2.3% per year, while operating profit has fallen by 7% per year:
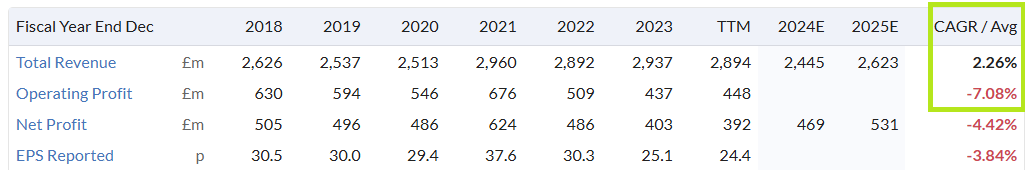
The increase in costs can be seen explicitly by clicking through to the Accounts/Income Statement tab.
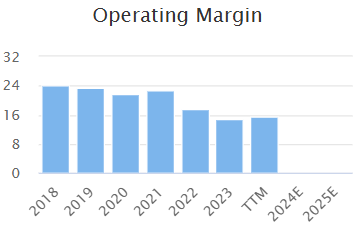
This process has resulted in a steady decline in Schroders’ operating margins (and a corresponding decline in return on equity to under 10%):
Roland’s view
Schroders is not the only asset manager to be suffering from declining profitability and a hefty cost base. I covered rival Abrdn (LON:ABDN) in a piece last week, for example.
However, as with Abrdn, the recent promotion of the CFO into the CEO position suggests to me that Schroders may start to pay closer attention to its cost base.
I’d hope that CEO Richard Oldfield will also use this period to take a closer look at the group’s (broad) range of activities. Could the focus be tightened on areas where Schroders has more well-defined competitive advantages?
Having said this, I think Schroders’ valuation may have come down to a level where it’s starting to look reasonably priced. Assuming consensus remains broadly unchanged, the shares are now trading on less than 11 times forecast earnings with a 6% dividend yield.
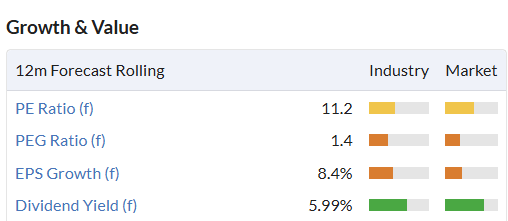
Although dividend cover has thinned in recent years, this payout has not been cut for over 30 years. I don't think there's much risk of a cut as things stand today.
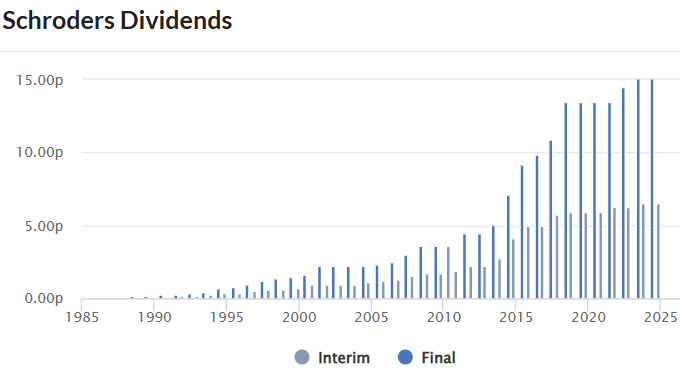
On balance, I feel broadly positive about Schroders’ business and current valuation. However, I do think a measure of caution is prudent to reflect near-term risks, so I’ve opted for AMBER/GREEN here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

160 comments
Deleted (wrong board)
I joined the online Mello yesterday and saw the Smiths News (LON:SNWS) presentation and asked the CEO about his disposal. He got divorced last year and that was part of the agreement that he had to sell these shares. Otherwise he had no intention and is fully committed.
Other takeaways were that the move to recycling seems a good idea. They deliver newspapers and then pick up recycling at the same time. They are 'better' than current local authority or private conntractors as the rule generally is that this needs to be cleared from the pavements by 8am. Generally, they are out before 6am so works well for them.
They are trying to get new customers (who don't already have deliveries made to them) to take up their recycling offer. They believe the profit of the addressable market is £160 million, so whilst they haven't given figures of how much they are after, this could be material if executed properly.
I asked whether there was a danger of productivity of deliveries dropping, i.e. if they are picking up recycling, will deliveries suffer. I was impressed with their response, they monitor every single delivery run every day to ensure KPI;s are met. Not only do they not have an 'AM/PM' delivery slot they narrow it down to 15 mins (as a former newsagent who was up every morning at 3am, I can vouch for this), they stated if they felt deliveries were slowing down, simply they would get the drivers to pick up the recycling on the way back after their deliveries as they basically have to get back to the depot by and large the same route they took as they had to return the unread newspapers from the day before.
Also, they confirmed that they charge for picking up recycling and then when these are processed, they are a commodity which can be sold, albeit like all commodities prices change.
The figures were repeated which we knew last week - debt dropping, FCF increasing, divis have a massive runway ahead of them, but interestingly, they do see themselves as a growing business. Whilst the core business of deliveries wan't expand, they are seeing uptake of the recylcing and are also looking for new opportunites.
I was more than confident that this is a business with more to give rather than the opposite and with the huge divi on offer, it's one of those that the price needs to catch up with events. Even without the special divi, if the price doubles from here, it still puts the yield above 4%? Happy holder.
What happened to Associated British Foods (LON:ABF), not sure there much interest in Vodafone (LON:VOD), don't think that is adding any value to the content.
My view on Asos (LON:ASC) is that it is probably only a matter of time before they merge with Boohoo (LON:BOO) . Both companies are struggling to be profitable, and the operations have a high degree of overlap, so there is lots of cost synergies that can be extracted.
Once that happens, and if the EU and UK government gets their act together and tighten the screws on de minimis parcel shipments, then they probably have a sustainable business model.
There is also an outside chance that Temu and Shein clothing is banned after a public health scandal; bound to be some sort of "baby poisoned and dies wearing baby clothes from Temu that were contaminated with [x]". Its a ticking time bomb just waiting to happen, given that these are marketplaces without rigorous whole supply chain checks and assurances.
I am so sorry to see that Paul has left Stockopedia. I am a silent member who reads this report every morning without fail but contributes infrequently. The report has been a great learning experience for me.
I would like to wish you all the best Paul and to Thankyou for your tireless volume of quality reports over the years.
I find Stockopedia a great platform. But it will be poorer without Paul. I shall be following Paul’s Substack together with Paul Hills very informative interviews and other investor substacks. I shall continue with Stockopedia. The combination of all these sources of ideas and information will be the basis for my decisions.
Planetx - is as always "considerably richer than yauuughw"
Fantastic comment Sparkly , absolutely spot on
I would just like to echo the comments of planetx. Paul will be missed for his often prodigious output and excellent grasp of accounts. His enthusiasm for the subject also shone through. However, he won't be missed for some of the behaviour towards paying subscribers nor the plethora of dubious calls in his supposed areas of expertise, namely retail and leisure stocks. Nevertheless I thank you and wish you well in your new endeavours, Paul.
However, the departure of a leading light can often lead to unexpected improvements in a service as new ideas and personalities emerge. I am looking forward to the reincarnation of SCVR and let's not forget the high quality comments of the subscribers on this site. They are a valuable resource that I enjoy reading each day in their own right. Onwards and upwards!
Come on Graham and team, "the king is dead long live the king!"
Smiths News (LON:SNWS) I am a holder and listened to their investor presentation this morning and was very impressed. Graham calls them a melting ice cube and I hold them mainly for their excellent dividend as I'm sure many do, however they have some very positive growth plans in recycling and other areas and may well return to growth imo.
Smiths News (LON:SNWS) a director, CEO, has just sold over a million shares. You may want to reconsider your holding.
Where did you get that information Rusty?
RNS: https://www.stockopedia.com/sh...
Thanks I hadn't seen that. That's getting on for half his holding.
Considering he has been in and around the company since 1994 and been CEO since 2020 (when the price tanked) this would represent his first sale and I wouldn't be overly concerned.
I was quite shocked when I read of Paul's departure. He has been my morning read for the past goodness knows how many years and I learned a lot from him. I wish him well.
I only really have one comment which is that we in this community should not underestimate the contribution many of us make to this forum. I always religiously read the whole sermon right to the end and I have also learned a lot from my fellow contributors. There are a lot of smart people on this forum and it is, at least partly, up to us to maintain the quality.
Have a nice evening folks.
xxx
Spot on James, as mentioned by me before there are some real top table posters on this site worth the subscription price alone, as you say its up to us to maintain the high standards set over the last decade.
I've learnt shedloads from the posters on here and i work in wealth management, Wolf's thread is pure gold and I always look out for RD's macro comments plus many others who are batting at a different level to me.
Our other Paul is an emerging talent as well, and the folks that used to work in fund management and I would also give a shout out to our resident entrepreneurs like PlanetX and the folks that have sat on the Boards of major companies.
Paul Scott
I had a couple on instances in my career where what was perceived as a key man left suddenly and in retrospect these times often give the chance to improve things dramatically .
So good luck to Graham and his team for having the opportunity to show us what they can do .
Paul Scott had a clearly prodigious work ethic but at times a somewhat spicy (or poor) attitude that was quite often pretty disrespectful to paying subscribers so maybe we dont need to blow too much smoke where the sum isnt shining anymore .
Equally lets hope Paul freed from the shackles of employment at stocko can do something very soecial in his new incarnation .
These situations tend to drive each party onto bigger and better things that they would not have been able to achieve together .
That definitely happened in my case notably with David Hanney ny CEO going off to form Alpkit.
Might be a touch controversial post for some as stocko had pretty much become the Paul Scott show .
How unpleasant.
I suspect that you are in an incredibly small minority if you genuinely believe that Paul had at times a poor and disrespectful attitude. He was just blunt speaking and didn't suffer fools gladly. Good for him.
He liked people who agreed with him.
As someone who is just blunt speaking and dont suffer fools gladly i know how difficult it is to work within the constraints of traditional. employment .
Definitely not unpleasant in my opinion and speaking the unspeakable is allowed on a forum of opinions .
I think a good few on here know what i am talking about .
I could not agree more and am pleased that somebody has had the temerity to say the unsayable.
Paul could dish it out when it suited him but, typically, took great offense when his own position was mildly questioned by a non-acolyte. He sucked up the applause but did not take kindly to questioning.
Paul's work rate is prodigious and his ability to analyse company accounts quickly and incisively is astonishing. He offered less, however, when it came to projecting future performance or analysing strategic positioning.
I think the future matters quite a bit in the business of investing and ... so far ... I have made more money avoiding Paul's favourites than I have from following his (non)-advice.
Anyway, I wish Paul all the best. I am sure he is going to succeed.
No more incessant ramping of pub chains and loss making fashion retailers lol
Well over two hundred people, probably most also Stocko subscribers, have signed up to Paul's new venture in less than twelve hours.
As opposed to the rather bitter half a dozen who have taken the opportunity to have a go at him after he has left and cannot answer back. None of whom were prepared to do the same when he was here, with the notable exception of Yiannos according to his recent post.
Hi Planetx,
Although on my holidays , I would like to wish Paul all the best and happiness in whatever he chooses in his life.
About three years ago , I have expressed with my usual direct response , that most of Paul’s holdings were heading south (Boohoo (LON:BOO) Joules (LON:JOUL^L22) and many others the likes of Sosandar (LON:SOS) etc, etc, etc.
The words he has expressed towards me were not the words you expect from an educated person working for a big corporation with a big audience. That I blame the management of Stockopedia as well.
From that day onwards every time I have disagreed regarding holdings or opinions of Paul’s were attacked by him in a very uncomfortable way, the last being Plexus Holdings (LON:POS) when at 22p.
That specific response gave others courage to add to the nonsense.
All my views were explained in detail with facts and figures and my opinions on many stocks are there for everyone to read and the people that follow me here know what I mean.
The sad thing is that 95% I have agreed with his views!
Lately I have realised that this forum became as you have rightly said the Paul Scott show and everyone who has agreed was his friend and everyone that has disagreed was not welcomed to be a subscriber!
On numerous occasions other posters were abused at midnight and even later on with very bad words and embarrassing behaviour. Again I feel this is an issue that had to be sorted out long time ago by the management.
I have managed today to only read Megan’s view and report on Asos (LON:ASC) and that was excellent as it has also provided an opinion on future events.
Good luck to Graham , Megan and Roland on this new project that I believe will be a massive success. After all it is these big caps that make money!
All the best
PS. The Iraqi government has finally gave in and there is an agreement for the restart of oil exports from the Kurdish region Gulf Keystone Petroleum (LON:GKP) !!
ShaMaran Petroleum (CVE:SNM) up 20% now!
Carefully with this numbers, very illiquid share with 10%ish spread!
Big hat tip to yiannos1 re Gulf Keystone Petroleum (LON:GKP) and the potential of an SP bump up if there was news of the opening up of the Kurdish oil exports.
Up 8% on the news this morning.
Paul’s a decent guy but this place will survive and no doubt prosper. People are acting like he’s died. He’s just stopped uploading his shares blog on here!
Just wandering back through these screens and I came across your post and felt inclined to air my own recollection:
I made a post one morning requesting an SCVR and I got this reply from PS
"What a boring comment. I'm happy to stand down if you think someone else
can do a better job. But am I going to waste my time writing about
rubbish/boring companies? No. find someone else to do that."
I was shocked at the rude reponse and commented that Robbie Burns informs us that boring companies are often the best winners. PS went on that day to extol the virtues of RBG Holdings (LON:RBGP) at 20p, one of those rubbish companies he doesn't want to waste time on
I have never forgotten that comment
I don't think politeness and/or tolerance were among Paul's principal virtues. I think he enjoyed having a strong and loyal band of personal followers and, maybe, came to believe that this gave him licence to be somewhat rude and disdainful towards people who questioned his approach and priorities.
It doesn't matter whether you think Paul was right or wrong regarding the merits of the company you requested he looked at. You are his customer and should be treated with respect.
On such a momentous day, I thought I'd lighten the mood by sharing my latest purchase, an opening position in Software Circle (LON:SFT)
As well as good SP momentum (up over 100% in 12 months) and clear signs that the turnaround is progressing, I couldn't resist the opportunity to receive their updates, when I was reminded of Paul as I read through recent reports, which featured comments such as
Outgoing chairman:
"This will be my last AGM as chairman. Tough reality for a fish and chips connoisseur!"
and the CEO commented:
"Ned Bishay founded the business in 1990. Thankfully, a year of number 1 tracks like NKOTB's 'Hangin' Tough' and 'Vanilla Ice's 'Ice Ice Baby' did not prove too distracting for him. Ned remains with the business."
adding in the AGM statement
"We are immensely grateful to Jan and Conrad for their invaluable contributions and leadership over the years. They have both been instrumental in guiding the Company through significant change and strategic milestones.
We will miss Jan's vision, notorious German directness and surprising penchant for a fish and chip supper. Maybe there'll be more menu options at future board get-togethers as Matthias takes on the Chairman's role.
Conrad's fair minded, well rounded approach and sartorial flair added a certain style to Board meetings that we will find difficult to replace. Of course, we look forward to seeing both Jan and Conrad regularly at future shareholder meetings.
While Paul can never be replaced can I just say that if the quality of the daily reports remain the same as todays my subscription is safe.
I hope Paul is still able to do his Podcast on the basis that it was his own idea and venture rather than Stockopedia's. I think many on here, actually everybody on here will miss him, his thoughtful analysis, insights, honesty and humour plus the odd gaffe and hangover. Stocko, in law, will not be able to restrict his ability to make a living and a podcast, even a video podcast on a subscription basis, I'm sure would do well and would be followed by many. Thanks Paul. I will miss you.
ps. if you pop up at SharePad, I'll see you there.
Vodafone (LON:VOD)
This definitely isn’t a growth stock. But while the dividend looks safe and comes with a decent yield, I am pretty positive about Vodafone for income investors.
Based on the £45 Billion of debt Vodafone has i dont see how anyone can say the dividend looks safe. Yes i understand that they are loathe to cut it and one would like to think that when they do cut they would do so on the basis the cut is conservative. I would suggest though that any higher cut would have been trending down closer to nil - so to me it looks like they have simply done the minimum cut they could save face with. Obviously with market cap below half the level of the debt any rights issue would potentially be evry dilutive if they wanted to take a hatchet job to debt. So whilst i have no indications cashflow wont be perfectly fine to pay lower level and perhaps increase - i for one would not be presuming its all tickety boo. The lack of mention of the huge debt here seems to leave the commentary lacking some balance. With regard to the company being an income stalwart - it looks very much to me that the dividends have not exceeded the annual drop in shareprice recently - that generally suggests that a company is not in fine enough fettle to have paid said dividends from risk persective - trending down shareprice and huge debt that needs serving can end up a terrible combo if their is a liquidity/funding issue at some stage. Over the years sen plenty of companies go down the swanny due to a presumption that huge liabilities could be "paid off from later cashflow" - similar to te numpties that run our country borroing from the next generation who havent started paying tax yet - oh and probably their kids too.
A little harsh as the net debt figure is lower 33bn Euros ... and the co guiding to the lower of range - taking account of leases. Also they are currently buying back stock to the tune of 500m which suggests no significant current pressure following the cuts referenced. I guess the point is the merger would be attractive for UK Telco stocks due to a reduction in competition .... results this week from BT (LON:BT.A). All eyes on FCF... and a possible divi increase? ( I own BT (LON:BT.A) - no Vodafone (LON:VOD) ).
Vodafone (LON:VOD)
A little harsh as the net debt figure is lower 33bn Euros ... and the co guiding to the lower of range - taking account of leases.
Aplogies for that - i was lazily using the most recent stocky figure - that is quite a bit lower for sure - albeit still material enough for everyone to be slapped in the fact with.
Ref mergers - i would agree its possibility about as no brainer as you can get particualrly if you get one less large competitor out of the equation - not saying that this might not be a good investment just that the debt is material here.
Megan,
I am not sure which company's chart you have added to your piece on Vodafone (LON:VOD) but it certainly isn't theirs.
Apologies, that is now corrected. Thanks for spotting that.
Megan lovely piece on Vodafone (LON:VOD) the chart you displayed does not look right? wish it was 200+ today
Thank you for spotting that. Chart is now updated to the correct one.
Sad to see Paul go but I will absolutely keep my Stockopedia subscription going. What's even better is that Paul is already on Substack so we get 2 fantastic resources for a few quid more. Graham and team wishing you all well and keep up the great work!
He's own his own now. Will be there be guest writers if he's incapacitated in some way and can't write for a few days? After all subscribers do expect uninterrupted service.
Paul ... incapacitated??? Perish the thought!
I'm happy with the decision to broaden out this Daily Stock Market Report as it is more suited to my wider and more diversified portfolio as I am an old fashioned dividend investor. It makes perfect sense to me. Paul will be missed, but no doubt he will blog post personally somewhere and many of us will continue to listen as he is great fun. Stockopedia is still worth every penny with the great content and, most importantly, the fantastic Stockreports that Ed has developed. Without these we would all need to do a lot more work, so keep-up the fantastic work Ed and the team!
I'm with you, Topvest, as I have grown older and less interested in shooting for the stars with small stocks. Inverstment Trusts need nurturing before they die! And thoughts on larger financials like M&G (LON:MNG) , Legal & General (LON:LGEN) , etc. I still have a very few nil dividend 'lottery' stocks, but I know so few make it, that I sleep nights because of an average 9% yield, many of which buys I think may never be repeated in my lifetime.
Absolutely nothing wrong with a diversified portfolio raggedtp and I hold both the names that you mention... Graham et al can certainly analyse eloquently such financial large caps, but it will be impossible for him to look under the hood sufficiently... having had the misfortune of working for my whole career on a trading floor, I never had a clue what the guy in the row next to me was up to ..... impossible for an outside analyst ( even as good as Graham ) to pre-empt every possible accident... an analyst can certainly add colour, but there's too much black box stuff going on... hence why, IMHO, the small cap universe is potentially a richer risk reward arena to analyse
Zotefoams (LON:ZTF) BenHazz -looking forward to hearing about the feedback you get from your email to the company :)
Re TI Fluid Systems (LON:TIFS) in the summary table above .... unless I have missed something, wasn't the original takeover offer upped from the original £ 1.76 to £ 2.00 please ? And no worries, if it needs editing, there's an awful lot ( of comment in particular) going on today... very best of luck to Graham, Roland and Megan.... and could I possibly add my voice to the small cap crowd... its certainly easier to find alpha and greater volatility / mis-pricing in that sphere....
Thanks for spotting that Cancun - fixed! And yes I note that you'd like to keep the small-cap focus. I think it will remain but with more options to cover larger companies when we have the writers available and when there are interesting stories to cover from them.
Maybe a poll on minimum market cap to weed out the chaff. And perhaps in profit or at least has revenue. Min SR?
Also trending sectors like energy, metals, defence or current in the news.
Or what’s pulled up in the Screen of Screens.
Interesting suggestions HH! For now we have the £10m minimum market cap and we do try to avoid spending too much time on obvious no-hopers. G
Times that by 5 imo.
Best wishes Graham to you and the new team on the morning RNS news. Paul will be missed but I have no doubt that you, Megan and colleagues will continue the excellent morning output.
Cheers jonno! Appreciate that. G
Cordel (LON:CRDL)
‘Rev +46% but widening
losses. Raised £1m in Oct.
Early-stage co.’
This seems unduly cursory and IMO doesn’t reflect the potential, assuming we are still looking to uncover small cap value here? They are operating close to cash breakeven despite expensing all R&D, and expect to breakeven this year (to June 25). They reported a net loss but have approx £2.5m net cash, strong revenue visibility and a very strong pipeline with a clear path to £10m revenue in the next two years (expected to generate ~£2m of EBITDA, with minimal A since they don’t have large capitalised dev’ costs). I would argue they are not an ‘early stage Co’ but have clearly demonstrated product market fit, growing demand, expanding use cases and shown good traction with 8 large clients (doubled this year) on largely multi-year contracts with very high gross margins and strong operating leverage. There’s a useful Cavendish note out today.
I’m happy to keep accumulating at what I see as bargain levels given this is totally overlooked high margin SAS business operating in a large and growing market with significant competitive advantage and regulatory tailwinds.
I agree and bought an opening position earlier this year Cordel (LON:CRDL)
The market is massive and having spoken to some friends who work on the rails, they echo that the kit anecdotally is excellent and provides great assistance, especially at night when they're working. Together with building up the data analysis side of things, I do worry a bit if they will need to dilute, but again, IMO it's not jam tomorrow.
Hi PastPerformance, yes that was just a very cursory overview of what I saw in the statement and how I view the company. I fleshed things out a bit more here. Best of luck with CRDL! G
Can someone point me to Paul’s Substack report? I can’t find him there.
https://substack.com/@paulypilot
Regarding TP Icap (LON:TCAP) and the slow rate of revenue growth in their Parameta division. They are entering a market suppling market data such as OTC derivative prices to market participants. S&P Global (NYQ:SPGI) currently dominates services in this area and I'm not surprised that it is taking time to build momentum. The opportunity is big but it's not a forgone conclusion that it will all work out as hoped.
Just as an aside ( and I bring this up strictly for ICAP relevance and not political issues ).... 150 of ICAP's top brokers are apparently relocating to the Middle East in the next few weeks .... whether that means that they are a greater flight risk from the company, or changes the business model for ICAP in any way, I'll leave others to decide...
In the words of Douglas Adams,
So Long And Thanks For All The Fish.
Best wishes and thanks Paul.
Ed, thank you for building an awesome platform without which I would struggle to invest confidently!
Good luck to the new daily team in keeping the plates spinning but in all honesty, whilst the SCVR has been the “location” Maitre D’d by Paul, I have learnt mostly from fellow subscribers, some of whom are prolific posters (I’m sure you know who you are!) with incredible knowledge and insight into many aspects of macro, investing and life!
Thank you all for sharing! The sun will come up again tomorrow ;)
Neil
There has been so many nice things said about Paul today so please sign up to his new report now on substack
https://substack.com/@paulypilot
Hi alexdonnelly, Please can you explain how we do that, I very much want to follow Paul's work
this is his substack link
https://substack.com/@paulypilot
Thank you alexdonnelly, I am all signed up now with Paul on substack
Thank you!!!
Wise (LON:WISE) Interim results tomorrow, up 7% today, it would be good if you could cover these results tomorrow. I hold.
Wise (LON:WISE)
Hi Dazza64
Wise is up today due to a deal signed with Standard Chartered:
https://www.cityam.com/wise-sh...
A
As a new user I haven’t been following Paul’s posts for long. That said I’ve found them both useful and fun. The bite sized ones point analysis was a draw. I wish him well and all the best going forwards.
Stockopedia continues to provide me with food for thought and considerable enjoyment and has certainly improved my investing, The stock reports, data driven approach, webinars and so forth have made a huge difference and I look forward to seeing how this piece of the picture transforms as changes due to the new people working on it percolate through. The variety of opinions and approaches due to the differences brought should strengthen things. Diversity usually does.
Best wishes to Paul and best wishes also to the new team in the transformation.
Paul's started his Substack. Won't paste a link here but anyone can find it if you look
On the macro front - China's fiscal stimulus plans are expected by markets to be announced after their 4-8th Nov meeting this week. So it sounds like that will be our Friday morning. This could have a large positive or negative effect on basic materials and energy stocks, or perhaps no effect at all. Worth thinking about if you're holding these stocks or thinking of buying any.
Thanks Andrew, will do my best! G
Paul has been a mainstay of my investing intelligence throughout my Stockopedia journey. I realise that for many his presence stretches back much further, in fact decades to the Motley Fool era. It’s a huge shock for sure, but anyone who has followed Paul’s mercurial talent should not be too surprised - it was obvious that this day would eventually come and frankly, I never expected that such a temperamental genius would continue for as long he has. Thank you Paul for all of your invaluable insight, analysis and output throughout the years - I will certainly be looking to continue reading your analysis wherever it next appears.
As sad as Paul’s departure is, I for one will not be cancelling my Stockopedia subscription. Paul’s contributions provided great colour but my own personal out-performance has been driven by the incredible depth and breadth of the tools that make Stockopedia the unique resource that it is. The Stock Ranks, Styles and Stock Reports have saved me from many disasters and have driven my portfolio to performance levels that I would never have been able to achieve otherwise as an amateur investor.
I think that some of the comments regarding Paul’s departure are lacking balance and recognition of the monumental workload (and passion of Ed Croft) that has driven the incremental advances in the quality and usefulness of the platform. Paul has been amazing but so have the developers and behind the scenes staff at Stocko.
Onwards and upwards into a new era.
John - that is a lovely comment, and I'll be sure to reflect that to the team.
I was trying to write something similar but this nails it. So I echo all of this.
Paul thanks for everything. When you get your new venture up I'm sure many here will add that subscription to their stocko one.
Stockopedia team, keep up the amazing work, it's so very unique and valuable to investors.
I wish Paul good luck with his new venture and he will be missed here.
I also welcome a new dawn in this space where the commentary is not restricted to the small caps.
At the risk of being accused of political commentary, and not knowing what may have happened behind the scenes at Stocko HR, Paul’s sudden departure without (seemingly!) having an opportunity to message the community himself is quite shocking.
I’ve been through denial, anger, and I’m sure that’ll subside into depression and acceptance once I’ve got my head around it.
Thanks to Paul for such excellent analysis over the years and all the best for whatever comes next.
I appreciate Ed, Graham, Megan, Roland and the other writers too and hope you are able to maintain something near the level of commentary that Paul epitomised ….I must say the announcement today sounded rather like a profit warning with promises of ‘profitable growth’, but I won’t be cancelling just yet.
I suspect there might be more money in full time Podcaster. Whatever, best of luck Paul and thanks for your (not) tips that have been so valuable the last few years!
well if harry and megan can get 60 million from spotify the sky's the limit for paul.
I have a medium-sized position in Smiths News (LON:SNWS) and will hope to join the IMC presentation later. I'm hoping to hear more about their projection of the volume of the old core titles. Nano-scale comment: at our village shop, the volume of papers sold seems to have stabilised. Is this like books? There are still too many older subscribers, but there have been a handful of sign-ups. I'd be interested if any other subscribers have local knowledge of news and magazine sales.
Thanks for the comment raddedtp, and for your nano-scale anecdote! In simple terms, print newspapers and magazines are either going to disappear or they are going to stabilise. Surely there is a point at which they stabilise... G
Graham. I don't think that print volume will stabilise. I believe that volumes will continue to fall until such a point is reached that readers will not be willing to pay the high cover price required, and advertisers will conclude that the price to place adverts will be too high when considering the small number of readers. So it's really about WHEN the end comes, rather than IF the end will come.
A scary thought, WarrantStar! But of course you may be right. How long will it take...?
Smiths News (LON:SNWS) The survival of the company is a temporary situation. I predict that this situation will continue for a length of time somewhere between a nano second and a millennium. That is unfortunately about as precise as I can get on the subject!
Have just listened to the presentation. Naturally they are fired up about the new initiatives, which are currently small but growing. I think it will take a year to see how the reality of the opportunities, using their current expertise, begins to make real traction. The areas of focus are: recycling paper, soft plastic and bulky card: complementary deliveries of books and some greetings cards just starting: and increasing categories of 'ambient' goods to small supermarkets and independents alike between 2 and 10am. Could be as much again, given market sizes, but it's too early to say whether there's a new cigar to be lit.
For me, Stockopedia just a chunk of value. Others will use Stocko differently but most of my daily usage was around the Small Cap Value Report, and reading analysis from someone I trusted. I'm less interested in mid caps and financials.
Could this move be related to the range of intiatives just launched by ii? (Trading Signals data and community app). Stocko needs to value its community. It is a 'remote" business to most of its subscribers.
What an irreplaceable loss triggered by Paul's sudden exit(ing) . . . . his insights, experience, instincts, as well as ready humour will be irreplaceable.
It's all so unnaturally sudden, so unexpected, and accompanied by such a sanitised PR response (of the kind Paul was so vocal in disliking when included in RNSs deflecting unwelcome news).
There's clearly been some sudden/dramatic events resulting in the use of the emergency exit door.
While none of the readers, so far, know the full story, on the basis there's no smoke without fire, it seems a raging inferno swept through the corridors of Stocko HQ yesterday.
As with other commenters I won't be rushing into giving up my subscription.
I heard he had opened an XJS dealership in Bournemouth
Graham, good luck with the new role. I look forward to more of your excellent insight.
The Ant & Dec partnership of Graham and Paul has been just amazing. Both are brilliant in their own ways. I am going to miss Paul. Do we know where he is going next?
I remain a very satisfied subscriber and especially after the news today from #tpac and #snws
I second that and also welcome Megan to her new role, you are off to a great start and I'm sure you will grow into it over time, best of luck.
Still in shock at the news about Paul this morning - always better to reflect than make rash decisions…. But also an opportune time to thank Graham for his excellent work - will be interesting to see if this means an increase to the “12 hours per week” and if it includes Fridays now. Interesting piece on Smiths News (LON:SNWS) so thanks for that to kick off the new era to review later. Good luck Graham
Paul was/is superb and I enjoyed reading his thoughts every day, his Podcast was fantsastic and something I looked forward to every week . A sad day for Stockopedia (which i'm sure they are well aware) and a sad day for us, Stocko's loss will be someone else's gain and his loyal followers here will keep a close eye on where he pops up next, good luck to him in whatever he chooses.
Why would anyone stop subscribing to Stockopedia?
Because Graham traditionally has stuck to a narrow range of companies with a perfectly understandable bias towards financials, and Megan, to date I would stress, has focused on giant corporations with perfectly good analysis but not anything unique. I do like Mark’s detailed coverage of smaller caps but I wonder how that will translate to the rapid fire of the daily forum.
That said, I’m not rushing to cancel my subscription because I value the community here extremely highly and believe we need to give the site the benefit of the doubt. And I expect Stocko will revise its format to address some of the weaknesses I’ve highlighted. I actually welcome the inclusion of more mid-caps and, if that is at the expense of all the blue sky, jam tomorrow crap on AIM, then I applaud the shift in emphasis. But if the membership were to follow Paul to a new site, it would be an existential threat to Stocko that I would need to heed.
But if the membership were to follow Paul to a new site, it would be an existential threat to Stocko that I would need to heed.
Doubt Paul would be able to replicate the vast amount of information and data available here. He might start another SVCR elsewhere but to say Stocko's time might be up is a GREAT exaggeration!
Doubt Paul would be able to replicate the vast amount of information and data available here
He simply has to move to Sharepad to prove it is a simple matter. In fact I hope he does, as the data and chart formats there are much more to my liking. I appreciate others may differ.
Hi BnB, not a Sharepad user so please do me a favour and let me know if and when Paul shows up there.
Totally agree on this. I find stocko's metrics extremely frustrating, far better to use real life data from Sharepad's vast library.
Paul please let us know how to keep up with your daily thoughts in the future, you are that good
I have never commented on here before but feel I must write something to thank Paul for all that he has done. I read his reports every day and have so much to thank him for. His personality and humour helped spur me on in my investment journey and I can't imagine not reading his wonderfully detailed insights every day. Paul, please do let us know how we can continue to access your invaluable work.
I note Plexus has fallen 6% on the news!! I do hope we don't get too far away from small cap coverage here, that's where the alpha is for little guys like us.
Plexus Holdings (LON:POS) being a huge loss for some but Paul's SCVR is a huge loss for all Stocko subscribers.
Smiths News (LON:SNWS) looks fairly positive overall. I must admit I was slightly worried this might be impacted by the rise in the minimum wage and employee NI, given that fairly low paid staff must make up a large part of their costs. Doesn't seem to be mentioned in today's update - not sure if there is a mechanism to pass on any increased costs?
I don't suppose there is anything much to be won in future capital gains and the return in dividends is a shadow of what it used to be. I've held Smiths News (LON:SNWS) since 2011 and will see how things are looking next January before making a decision.
I bought in around 2020 and have topped up since, my buy in is on average 40p, so have done well on both capital returns and divis. I'm happy with the size, I expect further returns and this should be held for a decent yield. Similar to Reach (LON:RCH) as a former newsagent I know the businesses quite well and in my town at least, everyone buys papers and magazines - the oldies don't want digital, especially for the crosswords and sudoku!
Viz, I bought on numerous occaisions, even up to the price of 160 pence and selling just the once to bed and ISA in one portfolio, at a loss. I'm underwater still, it was the Tuffnells purchase that spoilt Smiths News.
I don’t think we’re going to see 160 anytime soon. Actually my average buy in is actually 30 as the highest I paid was 40 so I’m doing slightly better than thought (sorry I know that won’t come as much help to you).
If I remember correctly, whilst the Tuffnels purchase seemed to make sense, intergration was always going to be key, especially bringing in a company with massive overheads and slim margins. Poorly executed although management made money for sure.
The chart I have thought looked like it needed some news recently and there we have it. It should move from here, upto 100? Some decent TUs and looking at (ironically) more logistics work would continue to push it further but I hadn’t factored in the increased NICs….
Thank you Paul for your massive contribution to my finances over the last few years.
Good luck Graham! I enjoy reading your views and analysis and will remain a Stocko customer for the foreseeable.
Jim
Cheers Jim! G
Why would anyone stop subscribing to Stockopedia? There's so much analytical data and screens to help in investment decision making. I have found it invaluable.
SCVR was a starting point for in-depth investigation into small caps, but if you blindly followed him then you take the consequences that come with it. DYOR
Paul's contribution will be greatly missed for sure but the show goes on imo.
Exactly
I am sure that Paul more than anyone would not want anyone t blindly follow him. So agree anyone who does that with anyone should take the consequences. But at the same time if Stocko think that is peoples concerns they are missing the point. Which for me the big concerns would be:
1. Paul covered a huge amount of companies in depth. No new writers are announced, just others doing more. If this was an RNS then you would read this as a cost cutting exercise….
2. We will at least be able to track the companies covered before and after given the trackers (not clarified who will pick those up) but the proof of the pudding will be in the eating
3. The move to a daily report is a concern. I have no interest in reading about larger cos / large mid caps. I cant get to the detail required in those and for me those are covered through trackers. The selling point for Stocko is the small caps
4. Breadth of coverage - I love Grahams writing as much as Pauls but it largely financial services etc so a move to a much broader sector will be a challenge but hope he can rise to it
Good luck to all - I would hope I speak for most in wishing Paul and the Stocko team equal luck. As I say the proof of the pudding will be in the eating……
Hi Investment4Adam, thanks very much for those points, I'd like to address one or two of them if I may...
1. I will be here for longer every day, and will be covering more companies.
3. The SCVR always did cover big caps from time to time, and I don't think there is going to be any huge change from that point of view. Small caps will remain very well covered, but with the name change I guess we are explicitly giving ourselves permission to look at interesting news from larger companies.
4. Of course I don't have Paul's expertise when it comes to the retail sector, but I'll try to pleasantly surprise you with my coverage of a broad range of sectors! And at the end of the day I'm just one of the contributors here.
All the best
Graham
I have from time to time been mildly frustrated that the SCVR did not cover noteworthy announcements from the rest of the market just because their market cap was a bit higher, so I welcome the extended coverage in this regard.
I am very sorry to see you go Paul. You have been a big part of my knowledge of investing and also your podcasts are not only informative but entertaining. Thank you and good luck whatever you do.
I must say I did always slightly wonder why Paul was a salaried employee. I had assumed it was to give him some income stability perhaps. Maybe now he is going to lead his own venture. It's very sad that he is leaving, and it will change the value of this forum, but we will find him and we will follow him!!
Its not all doom and gloom,
I dont think this is the last we will hear from Paul
Thanks Paul, really enjoyed your reports and comments. Sorry to see you go so suddenly.
All the best for the future and will carry on listening to your podcasts.
I’ve bot some J D Wetherspoon (LON:JDW) this morning partly as I think the NI worries are overdone , partly because Paul might be spending more time in the Mary Shelley recording podcasts, but MAINLY because the threatened smoking ban has been scrapped. A quality business underloved temporarily. Best wishes to Paul! Whatever he does will be a great success.
Lots more "Cheese" to come then!
I have been a subscriber since 2013 and very rarely post. My gratitude to Paul is immense and without his posting I would not be anywhere near as successful. Hopefully I will see you at Mello and thank you in person.
I wish you all the best whichever direction you follow.
Any chance of your comments on Associated British Foods (LON:ABF) Megan?
"Don’t worry, we’ll still be covering all the small company stories *that matter to you*."
I fear dilution. The beauty of SCVR is that it did not just focus on company stpries and not just on companoes *that mattered to us* (whatever that means).
What you are doing is a bit like trying to turn a podcast like Rest is Politics into a general news bulletin. None of what Paul did was factor analysis droven, simply does not mesh and will not produce any alpha beyond wjat's in the stokko data already.
Here's a better idea: keep the small caps report, and generate the general market report separately by training an AI on dynamic stokko data.
To Paul: hurry and open that substack already
Let's hope it is announced where Paul Scott is moving too, or Paul finds a way of letting us all know where to find him, no one can match his output, thank you Paul
I doubt very much that we wont be able to find Paul wherever he has gone too :)
Rumour on the Street is that Paul has taken a staring role in the next series of 'Industry'
Pretty raunchy show
Isn't 'Industry' where Edmund (Market Musings) moonlights
Sorry, but no one can compete with Paul Scott's work ethic no matter how many people replace him.
So. Farewell then SCVR.
Keith's Mum said that
You were too good
For this world.
DYOR, that was your catchphrase.
E J Thribb (age 17.5)
SCVR was a unique resource thanks to the combination of Paul and Graham's diligent and soundly reasoned analysis with the often expert and well informed comments of experienced and knowledgeable subscribers. IMHO, it will not work once it is widened into a general market commentary of the type widely available elsewhere. It is among the small caps that private investors have the best chance to outperform and I personally would prefer that to remain the focus.
Here is Ed's article that should answer questions re: Paul Scott.
The end of an era: thank you Paul Scott
Hi Graham,
I’m afraid it doesn’t really answer questions around Paul. Naturally the sudden departure raises concerns when here on a Monday gone on a Tuesday without word.
I dont need to say this but I will, this is a defining moment for stockopedia as for many the SCVR is Stockopedia. Get this wrong moving forward and I feel you will lose a lot of subscribers.
I think you owe it to your customers to give a bit more of an explanation as long as that is Paul wishes. Many of your subscribers have been very loyal to yourselves over the last decade I feel we deserve a more through answer.
That’s my feelings anyway on the matter.
For the record I enjoy your analysis as well Graham and good luck in the new format but you cannot afford to get this wrong.
hi Daz
yes for me you have expressed it well.
I welcome all the new SOP features.
I can fully understand if the SOP business doesn't want to be overly emphahised UK small cap (remember it provides international data etc as well)
hopefully the change has very obviously been handled terribly.
and then the explanation of the change seems disrespectful to me as a customer. the community generally seems to appreciate honesty - not perfection, but honesty.
it would seem an obvious solution to just keep a part of SOP for small caps, so there must have been an UNEXPECTED bust up. we don't know the full story yet but we do know that it will come out.
it's defo a shock and a change. let's hope we all look out for EVERYONE in coping through the change.
I'd assume Graham (and all the others in the Stocko team) will be contractually prohibited from commenting. I'd also expect Paul will also have his hands tied from commenting (if the Stocko legal team is doing their job).
The recent survey about editorial content makes more sense now. I asked for no changes. Why is it every time something works, people want to change it. I can't see any advantage to large cap coverage.
I'm going to miss Paul. Not just his small cap coverage, but his wider coverage of mothers, Jags and mystery shopping at Weatherspoons. Good luck Paul, wherever you are. You are missed.
Different strokes for different folks.
One problem is that SCVR has to all intents and purposes 'become' Stocko for what seems to be a significant proportion of subscribers. It has come to dominate the platform. But -- objectively--it is actually only a very small part of it.
I have been hugely frustrated by the extent of Stocko's apparent concentration--evidenced by the high profile given to SCVR--on small stocks. It makes no sense for me as a careful but not wholly risk-averse investor seeking to build and benefit from a broad portfolio. I am positive about the prospect of a more broadly focused Stocko going forward.
With respect to Paul's--remarkably sudden, if not truly unexpected--departure, I am sure there is more to this than we currently see. Something very significant has happened behind the scenes. We shouldn't presume to assign blame in the way most commentators seem to be doing.
More generally, I am underwhelmed by the prominent 'wailing and gnashing of teeth'. Paul is clearly a very genuine person who, perhaps, wears his heart too evidently on his sleeve. That doesn't mean the rest of us also have to let our emotions get the better of us.
Hi Daz,
Fair comment and I accept that a longer explanation would be much more satisfying but I'm afraid that this is not up to me. This is between Paul and Stockopedia and I don't have any right to act as a news source on their relationship. I appreciate that this may be frustrating for loyal readers. My best suggestion is that you head over to Ed's article to express your views on it further, if you wish.
Thanks for your kind wishes,
Graham
My own personal opinion is that nobody can spend an hour looking at a FTSE 100 company and come up with an opinion that's worth much. They're large and complex businesses that are heavily researched and analysed. To get any actionable insight you'd need to spend weeks or months studying them, preferably with a horde of analysts, industry experts and alternative data sources backing you up. Small cap prices, on the other hand, detach from reality all the time and often interesting opportunities pop up from a quick rummage around by an analytical mind, as Paul and Graham have done so many times
Cordel (LON:CRDL)
Great results. Doubling of customers and strong deal pipeline.
- Revenue as expected +46% to £4.44m.
- Operating at cash breakeven before strategic expansion investments
- Expecting revenue build towards £10m over next 24 months. At £10m revenue the CEO expects EBITDA in the region of £2m with strong operating leverage
- Increased confidence in demand for and pricing potential of additional use cases.
- ~£2.5m net cash gives plenty of runway for accelerated development and no need for further dilution.
‘Based on a 46% revenue growth in FY24, a high level of contracted income in our next financial year and a very strong deal pipeline heading into FY25, we remain very optimistic about Cordel's future. ’
update: there is a further announcement from {LON:SCVR).
CEO thanked - albeit in a note that includes much marketing to promote the companies new products. seems to me like these announcements were issued in the wrong order.
obviously there is more detail behind the sudden change of direction in (LON:SCVR) that might come out in the weekend papers.
maybe i've become too cynical but as we all prepare for an intense covering of the US election, was it deliberate that this change of direction was issued on a day when investors attention will be distracted?
hi team
I hope you will cover in depth the surprise announcement from (LON:SCVR).
it is my largest holding and I've held for many years.
it seems the CEO is no longer involved and has not been thanked.
the announcement seems to have been written by the corporate PR team with survey feedback ratios of only 35%-40% skin to 'adjusted EBITDA' being quoted and ignoring the obvious REAL LOSS being implied for future periods.
We'll have to wait for the notes to the report to see if they have also closed the Mr Contrarian subsidiary which was a good offering connected to their brand.
I think the loyal customers of (LON:SCVR) will be quite shocked at this unexpected news and I'm sure will take to social media to vent frustration at the move to a broader product.
disc: I hold
Didn't even get a profit warning, straight to insolvency.
Good day to bury bad news! This is very sad and next weekends podcast could be interesting.
Unbelievable…..I’m literally lost for words. Feelings of concern and abandonment. Hope Paul is ok and that we get to hear about the new venture asap.
Only matched by the finesse of the country's PM announcing plans for re-election without an umbrella, with the vote called on a less than auspicious date, when he could have left it until the autumn when a stronger set of numbers were expected.
Smiths News (LON:SNWS) Final Div of 3.4p plus 2p Special Div both to be paid on 6 Feb 2025 means Total Dividends paid up 72% on prior year.
The Company is presenting on Investor Meet at 12 noon today. I hold.
I have to say I am massively disappointed to hear that Paul has gone. I had assumed that the introduction of Megan and Roland was to give Paul the extra help and resources he craved
Hi NfG, you’ve changed what you originally wrote, yes?
Edit: just seen the Paul news, which explains it. I remembered giving a thumbs-up to different text!
Hi Indie
Sorry, yes you're right. I initially thought this was good news. Paul has been asking for (and deserving of) more resources to cover more companies. I had naively assumed that with the intro of Roland and Megan he was now getting a bigger team to help with the SCVR.
Note to Ed - Has this really been thought through? You sent a survey out to subscribers recently, was the main thrust of the responses to change the SCVR and drop Paul Scott? I would bet my house that it wasn't......
Looking forward to this new format and wider coverage - hope it goes well.
Welcome your views on the TP Icap (LON:TCAP) update which seems a bit "revenue" heavy but contains a mildly concerning "subject to the impact of FX movements" statement related to $ based revenues. No concrete update / anything new on either buyback or Parameta. It's a Top 10 holding for me, and continued revenue growth gives a bit of comfort for now...
Smiths News (LON:SNWS)
Surprisingly good figures from Smiths News this morning. A brief read so far but the increased div plus the special mean it is yielding 12.5% at yesterday’s closing price. Worth a closer look ?
Morning Graham
Apologies for asking but - alongside yourself, Megan & Roland - is Paul Scott is still going to be contributing to the Daily Stock Market Report?
His comments & sense of humour are brilliant .
Could this be Stockopedia taking a leaf out of the PR people's book and treating us like mushrooms? If so, the subscription numbers may take a hit here
Morning Paul,
Any chance you could locate and interview poste haste PaulyPilot about, well Everything ?
I am sure he would have flagged this had he been able and would welcome hearing his take on it all and where next?
Thanks also for your contribution to my knowledge
Hi Paul. Completely agree re PS and I am following him on Substack.
Someone told me you also publish through a Substack account - what is your username please? Thanks
Could I request a look at Smiths News (LON:SNWS) and TP Icap (LON:TCAP) please. Positive statements out today. I hold both.
Your request is noted, Revs8!