Daily Stock Market Report (Tue 6th Jan 2026) - GSK, SEE, CAU, RNK, NXT

Good morning! As noted in The Week Ahead, the post-Christmas updates from retailers are expected to kick off today. Update: Next (LON:NXT) came through with an update, we'll have to wait a little longer for the others.
We are done for today, see you in the morning! Graham.
Spreadsheet accompanying this report: link (updated to 16th December).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our View (Author) |
|---|---|---|---|
GSK (LON:GSK) (£74bn | SR92) | Exdensur approved by Japan’s Ministry of Health for severe asthma and chronic rhinosinusitis with nasal polyps. | AMBER/GREEN = (Roland - I hold) [no section below] Exdensur (depemokimab) is reportedly one of the top new biologic drugs in GSK’s pipeline, with peak sales potential of up to £3bn. This new treatment has the potential to provide long-acting treatment for severe asthma and certain other respiratory conditions through twice-yearly injections – an industry first. Today’s approval in Japan follows recent approvals in the US, UK and EU, suggesting this could be a new blockbuster product for the company. As I commented yesterday, I believe GSK is in good shape currently, with a promising portfolio and reasonable valuation. My moderately positive view remains unchanged today. | |
Next (LON:NXT) (£16.6bn | SR64) | In the nine weeks to 27 December, full price sales were up +10.6%, vs. guidance for the quarter of +7.0%. Increases guidance for full year profit before tax by +£15m to £1,150m. PBT up 13.7% vs last year, EPS up 16.1%. | AMBER/GREEN = (Graham holds) As I trust Next's capital allocation skills, I am happy to mimic their buyback policy: if the share price is at a level where they would be happy to repurchase shares, then I'll probably be fully GREEN. Above that level, as they are now, I can be AMBER/GREEN at best, as the shares are unlikely to be dramatically undervalued. This update sets a very high bar for other retailers to follow in the coming days. | |
Rank (LON:RNK) (£450m | SR64) | Following discussions with the Board, the CEO intends to retire from 29th Jan 2026. The current CFO will be interim CEO. | AMBER ↓ (Roland) [no section below] Today’s news comes at a potentially challenging time for this bingo and casino group. The company suffered a €7.1m payment fraud in December, shortly after warning that changes to gaming duty in November’s Budget could result in additional annualised costs of c.£40m from April 2026, before mitigation. For context, house broker Shore Capital was previously forecasting pre-tax profit of £74.1m for FY27 (y/e June 27), but placed its estimates under review following the Budget. While I’m sure some mitigation will be possible, I expect an impact. For this reason my assumption is that current consensus forecasts are probably stale, with FY27 in particular likely to see significant revisions. Rank is expected to issue interim results on 29th January, when the interim CEO (and full-time CFO) will hopefully provide some more clarity on expectations. Until then, I think it’s difficult to take a conviction stance on this stock so I am going to downgrade our view to neutral, mirroring the StockRanks. | |
Caledonia Mining (LON:CMCL) (£387m | SR85) | The enacted provisions of Zimbabwe’s 2026 annual budget confirm the position outlined in Caledonia’s previous announcement. A higher royalty rate of 10% will only apply if the gold price is over $5,000 and other proposed changes have been withdrawn. | ||
Seeing Machines (LON:SEE) (£300m | SR27) | Seeing Machines will receive an accelerated lump sum royalty payment of c. US$14.1 million from a customer under an existing Automotive Program Guarantee. The company “expects to deliver improved positive cash flow in early 2026”. | RED = (Roland) It looks like this long-running and loss-making growth story may be nearing profitability. But after digesting today’s RNS, I can’t help wondering if this accelerated royalty payment (for cash previously expected over the next four years!) could be a bailout in disguise. Perhaps I’m being too cynical. But on current forecasts, Seeing Machines shares are trading on 15x FY28 forecast EBITDA. With another year of losses expected in FY26 and a major debt refinancing deadline looming, I think this is too expensive. The StockRanks view this as a Momentum Trap and I agree, so am leaving our negative view unchanged today. | |
KEFI Gold and Copper (LON:KEFI) (£134m | SR36) | Tulu Kapi project: contracting packages for capex and 50% of opex have been achieved, and the lead design and construction contractor has begun work. Various other milestones. The schedule remains for commissioning in late 2027 and full production in 2028. | ||
Jubilee Metals (LON:JLP) (£107m | SR24) | Received second instalment of $10m from Chrome One following sale of South African Chrome and PGM operations. Deferred payments of up to $50m and a minimum royalty payment of $12m are due at various future dates. | ||
Centaur Media (LON:CAU) (£66m | SR63) | Net cash £67m, planning to return £64m to shareholders at 48p per share. Has now completed plan to downsize cost base to support the remaining single trading business (Influencer Intelligence Limited). | AMBER/GREEN = (Roland) [no section below] The shares are trading at 44p today and a quick check with my online broker confirms that in small parcels, at least, they can be purchased at 44p. In theory, this means there’s an arbitrage opportunity here, given Centaur’s intention of carrying out a tender offer at 48p per share. In practice, I’m not sure if it’s worth pursuing, given the potential difficulty of buying in sufficient size to make the trade worthwhile and the risk that not all shares tendered will be repurchased. Once the tender offer is complete, my sums suggest around 12% of the current sharecount will remain, giving a market cap of c.£7m. With the remainder of the trading business now contained in a single (newly-formed) limited company, assessing valuation is difficult. A delisting also seems likely, as Mark commented in September. I’m going to leave our AMBER/GREEN view unchanged due to the theoretical value on offer. However, from my perspective, Centaur is now a special situation stock and is no longer something I’d consider buying for a regular share portfolio. | |
Zanaga Iron Ore (LON:ZIOC) (£64m | SR32) | Completed work that could deliver an additional $11bn in revenue over 30 years, while offering significant potential capex savings | ||
Windar Photonics (LON:WPHO) (£44m | SR8) | CEO steps down with immediate effect - his decision. He is “the founder and creative force behind Windar”, but “the Board believes there will be no change to the trading position of the business.” | ||
Kelso group (LON:KLSO) (£13m | SR36) | Opened a new holding in Saga. Purchased 400k shares at an average price of 386.5p in January 2026. Believe undervalued with strong prospects. | (Graham) [no section below] Saga is quite a popular idea in the UK share investing community, and not a new one - Kernow Asset Management talked about this at length at a Mello presentation in November! | |
Prospex Energy (LON:PXEN) (£12m | SR15) | CEO Mark Routh is retiring. He will be replaced by external hire Tom Reynolds “no later than 1 February”. Mr Reynolds has previously been CEO of a number of other energy businesses. | ||
essensys (LON:ESYS) (£9.4m | SR25) | Revenue -21%, adj EBITDA £1.3m (FY24:£(0.9)m). Net cash £1.8m. Data centre decommissioning project has delivered £1.5m in savings, Q1 FY26 “broadly in line” with expectations. Remain in discussions re. possible offer. |
Graham's Section
Next (LON:NXT)
Up 2.5% to £139.30 (£17.1bn) - Trading Statement - Graham - AMBER/GREEN =
(At the time of writing, Graham has a long position in NXT.)
It’s an ahead-of-expectations update, which is typical for Next.
Key points:
9 weeks to 27 December: full price sales +10.6%, vs. guidance for the quarter of 7%
Within that, international sales were up 38% (this has been a remarkable source of growth in recent periods).
Adjusted PBT guidance for the year (FY January 2026) increases by £15m to £1,150m.
The new PBT guidance represents year-on-year growth of 13.7%.
Earnings per share is anticipated to grow slightly faster, at 16.1%, to 738.8p (previous guidance: 729.4p).
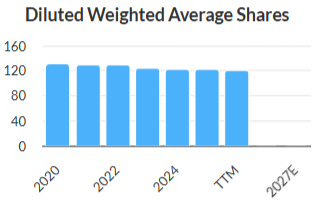
The share count has declined a little, boosting EPS, even though buybacks have not been prioritised recently:
Initial Guidance for FY January 2027:
Full price sales forecast +4.5%
PBT forecast also +4.5% to £1,202m
£768m of cash expected to be available for distribution to shareholders, assuming no acquisitions. Next points out this is 4.8% of their market cap.
Next also points out that combining these cash distributions with EPS growth of 4.3% would lead to a total shareholder return of 9.1%, assuming their P/E multiple is unchanged.
How many other UK companies provide such clarity? I can’t think of any!
The guidance above is for 52 weeks, but FY27 will have 53 weeks and so will be a little better than what is shown above (an extra £22m of PBT - Next makes £3m of PBT each day, on average!).
The rest of today’s statement provides lots more detail on everything - FY January 2026 performance, and FY January 2027 guidance.
Trying to pick out the most interesting bits from the review of FY Jan 2026:
Online UK full price sales growth has been quite good at 8.8% (year-to-date), and retail stores are holding their own 3.5%.
Online international sales are very impressive at 33% (year-to-date), and accelerated in Q4.
Finance income stable.
As we’ve noted previously in this report, Next has discovered how to spend very successfully on international marketing:
We were able to increase profitable marketing expenditure by more than anticipated.
Sales through our main European aggregator, Zalando, were better than anticipated following our transition to ZEOS's platform in August. This change improved stock availability by allowing the same stock-holding to serve both the Zalando and NEXT websites across Europe.
Balance sheet: it’s fair to say that Next runs an "optimised" balance sheet, increasing net debt as it becomes more profitable.
They are looking to maintain a constant net debt to EBIT ratio, at 0.63x.
I view this as a very conservative debt level, so it doesn’t concern me. This leverage multiple based on EBIT, not EBITDA, so it’s more cautious than a typical company would use. Many companies run a net debt/EBITDA multiple of 1-3x.
Instead, Next only allows itself to have a net debt to EBIT multiple of 1x.
This is the right thing to do, because after all it’s a retailer with significant lease liabilities which are considered separately (but most retailers don’t act like this).
Given the anticipated growth in profitability this year, they expect to increase net debt by £38m, which means more surplus cash available.
Graham’s view
This sets a high bar for the retailers that are about to follow with their own post-Christmas updates in the coming days - including Marks and Spencer (LON:MKS) and the supermarkets.
I’m obviously delighted with the performance of my Next shares - which are a two-bagger for me at this stage, not including dividends.
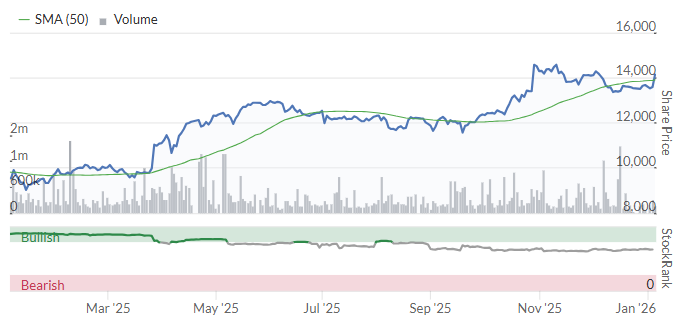
However, I’ve not been fully GREEN on the company as the valuation is now rather high, and I’m not expecting any buybacks in the foreseeable future, unless there is rapid earnings growth or a collapse in the share price.
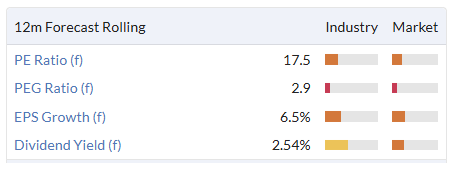
At this valuation, being fully GREEN would not be prudent. I believe that Next are master capital allocators and if they aren’t buying their own shares at any significant scale, it’s a great sign (in my view) that the shares are not undervalued.
If I may quote from the most recent interim report:
Any share buybacks are subject to achieving a minimum 8% equivalent rate of return (ERR). As a reminder, ERR is calculated by dividing (1) anticipated NEXT Group pre-tax profits by (2) the current market capitalisation. Our latest guidance of pre-tax profits of £1,105m results in a buyback limit of circa £118 per share.
The new PBT guidance for FY 2027 is £1,202m. So in order to get an 8% return, the market cap would have to be less than £15.0 billion.
This actually makes my life very simple, if I follow Next’s view on their share price: below £15 billion, I’d (probably) be fully GREEN, as Next’s buyback policy would help to accelerate EPS growth from that level.
At the current £17bn market cap, I’ll stay AMBER/GREEN as I still like the company very much, but it’s probably not undervalued here, or if it is, it’s unlikely to be undervalued by all that much.
Indeed, if I didn’t have capital gains tax issues, I’d probably want to take profits here, at least with some portion of my holding. However, I’m locked in for the moment! So I hope they continue to show what best-in-class UK (and increasingly, international) retailing looks like. Poor consumer sentiment, economic challenges and higher taxes - Next does not need to reach for any of these explanations for their performance.
Roland's Section
Seeing Machines (LON:SEE)
Down 2.7% at 5.9p (£292m) - Agreement - Roland - RED =
Today’s RNS from this “advanced computer vision company” appears to be good news, but on closer inspection I think it also flags up a potential area of concern for equity investors.
Here’s a summary of the main headlines from today’s RNS.
Accelerated royalty payment
Seeing Machines will receive an “accelerated lump sum royalty payment of approximately US$14.1m” from an existing customer, described as a Tier 1 automotive customer (i.e. a supplier of major systems to automotive OEMs).
The company says this accelerated payment has been made possible as a result of a “material change” to a production program.
However, today’s RNS also makes it clear that this is not new money. This payment represents royalties that were already guaranteed and are simply being brought forward into a lump sum payment, having previously been expected over the next four years. Obviously we don’t know the full story here, but this seems a remarkable contraction of the previously expected payment timeline.
Trading update
There’s also a brief trading update in today’s RNS.
Automotive royalty revenues are expected to “increase materially over the next two quarters” driven by the rollout of General Safety Regulations across Europe. These regulations mandate increased fitment of driver monitoring technology in new vehicles. Seeing Machines expects to benefit from increased demand for its “proven” products.
Management is also confident in the continued growth of the Guardian Aftermraket solution, with quarterly sales expected to exceed 6,000 units by Q3 FY26 (Jan-Mar 2026). In November, the company said Q2 FY26 Guardian sales had “surpassed 2,600 units”, suggesting a rapid ramp up of sales may be underway.
Outlook
Today’s guidance suggests long-suffering shareholders can be hopeful that Seeing Machines is at last nearing profitability:
The accelerated cash generated from this payment and associated revenue recognised will further increase profitability and cash generation in the second half of FY2026. The third quarter of FY2026 represents a significant financial milestone for the Company as it will be the first quarter of generating positive earnings and cash.
However, the obvious question for me is whether the business would have been profitable and cash generative in Q3 if the royalty payment schedule had remained unchanged. This isn’t made explicitly clear, but my guess is that it might not have been.
Debt refinancing risk
Today’s RNS also highlights a second potential concern for investors. CEO Paul McGlone’s comment reminds investors that Seeing Machines has $47.5m of convertible notes that may need refinancing by October 2026:
We are now well positioned to continue executing our strategy, build cash reserves, and progress a range of options to meet our convertible note obligations in October 2026.
Checking last year’s annual report I see that the conversion price of these notes is 9.95p, or around 50% above the current share price:
If the shares reach the conversion price then they will be converted into new shares. This would result in the issue of up to 386.4m new shares, or around 8% of the current share count.
Dilution is never ideal, but this is fairly modest and doesn’t seem a big worry to me. If I was a shareholder, I would be much more concerned about what might happen if the share price doesn’t rise far enough to trigger conversion. This looks more likely to me and in this scenario, Seeing Machines will have to refinance or repay these notes.
The lender, Magna International, is a major car parts manufacturer so may have an interest in remaining invested in Seeing Machines. However, debt is always senior to equity and the terms of any refinancing would be likely to favour Magna over existing equity investors.
Equally, Magna might not want to remain invested in SEE, in which case the company may need to secure refinancing elsewhere.
Roland’s view
I am only speculating, but my guess would be that today’s announcement is all about debt refinancing. Consider the facts:
Seeing Machines is receiving an accelerated royalty payment that would previously have been earned over four years
The royalty payment is coming from an unnamed “Tier 1 automotive customer”
Seeing Machines also has $47.5m convertible notes that are owed to a Tier 1 automotive customer (Magna International)
There may be no connection between the royalty payment and the convertible notes, of course. This could just be a fortunate coincidence.
It’s also worth noting that the company’s share price could yet reach the 9.95p level required to convert the debt to shares, in which case the liability could disappear.
Personally, I’m not convinced conversion is likely, at least not based on fundamentals.
Seeing Machines helpfully provides analyst consensus forecasts on its website for the next three financial years:
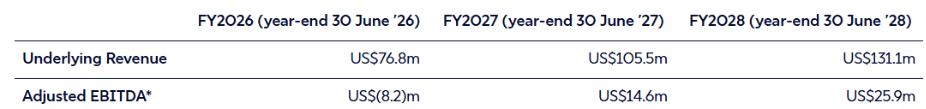
Based on the current market cap of c.£300m, Seeing Machines is trading at around 15 times FY28 forecast adjusted EBITDA.
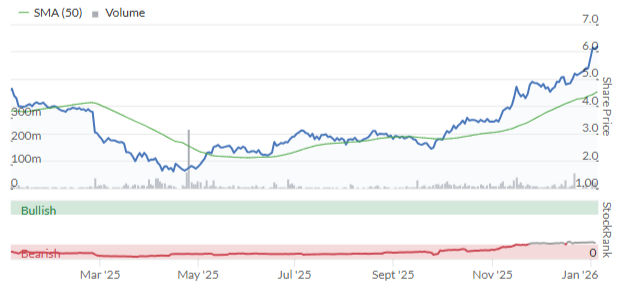
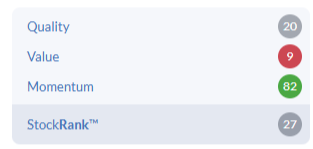
That seems a pretty full valuation to me, without much fundamental support. This is a view also reflected by the StockRanks and SEE’s Momentum Trap styling:
With revenue approaching $100m a year, Seeing Machines seems to have become a substantial business. I’m excited to see this long-running growth story may be nearing profitability and success. This company has been a jam tomorrow stock for as long as I’ve been investing in shares.
However, with a debt refinancing deadline looming and at least one more year of losses expected, I think there’s a risk that further borrowing or fundraising could be needed on terms that might not be very attractive for current shareholders.
Seeing Machines shares would have to be a lot cheaper for me to become interested. I’m going to leave our RED view unchanged today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Regarding the discussion on Prostate Cancer yesterday, I strongly recommend any male over 45 going to your doctor for a PSA, even though they might be reluctant. 6 years ago I had an appointment to have my Cholesterol checked & I asked the Nurse if she could do a PSA. She was reluctant but did one & the next day my Dr phoned to say my PSA was 21. So I had my Prostate removed & the 1st thing the surgeon said when i came round was i wouldn't have lasted more than 9 months if I hadn't asked for a PSA. I had some radiotherapy too to deal with cancer cells in my lymphnodes.
Does anyone know what AdvancedAdvT (LON:ADVT) paid for the AI business, MatchingCore they bought today and what the turnover of the business is? Thanks
WAG Payment Solutions (LON:EWG) broke out yesterday on high volume, back down again today. Let's hope 110 holds
Any news on Goodwin to cause price rise
It is on Cockney Rebel top 7 tips for 2026.
What are the others please?
Zotefoams (LON:ZTF) Carclo (LON:CAR) Saga (LON:SAGA) Marstons (LON:MARS) Dialight (LON:DIA) Marshalls (LON:MSLH)
An uninspiring bunch.
Thanks!
They often do look uninspiring. He had 2 out of 7, double last year. Some this of this years he has held for a while, like Goodwin (LON:GDWN) and Saga (LON:SAGA).
I would not underestimate him.
He also had Card Factory (LON:CARD) (-31%), IG Design (LON:IGR) (-66%) and Liontrust Asset Management (LON:LIO) (-44%). Buyer beware.
Its quite handy though if you want to sell out of what he is tipping. I took advantage when Creightons (LON:CRL) was heavily pumped.
Yes, still made 23% ex dividends. Did he double his money in his folio, last year? I know he was getting fairly close a few months ago.. He had 3 multi baggers and 6 single baggers, last year.
Am I reading this correct. You can buy centaur media for 43.5p and receive 48p from them per share? Seems too good to be true
I suspect it is nuanced. You are unlikely to get a full fill on the tender which is for c90% of the equity i.e. you are likely retain a stub. Although there will a small business left, and c£3.0m of cash, there is also a cash based value creation scheme with a max pay-out of c£2.5m. So it could be that the 10% uplift on the tender is then offset by any reduction in the share price of the stub compared to your in-price. Of course all will be ok if 1) the tender fill is somewhat higher, or 2) the stub can be exited at a reasonable valuation. I would also note that the the pro-forma cash of £71m stated in the 25th Sept statement has fallen to £67.0m, which I assume is largely driven by the necessary down-sizing restructuring costs.
So Chris it was indeed too good to be true! Largely played out as expected i.e. c90% fill leaving a rump which you can currently sell at 12p if you don't fancy holding a private investment i.e. the original investment has moved from 43.5p to c44.4p so basically a 2% return. That said the return is better than cash and it has also avoided the market mayhem.
Any idea why Liontrust are down -yet again- today?
Deutsche cut to Sell with a price target of 175p
Meantime Jupiter Fund Management (LON:JUP) up near 5% and Polar Capital Holdings (LON:POLR) up 2.4%. Pity Artemis is not quoted they seem to be top of the game atm.
EMG
up 7% today
I just wanted to express my sincere thanks to the 8 subscribers who responded to my post yesterday.
It was very gratifying to get 143 thumbs up for my post and a further 185 thumbs up for the responses. I thought long and hard whether I should post on such a delicate subject as Prostate Cancer but given the response I am so glad I did.
Good on you for opening up on the topic. Prostate cancer can be a lonely journey if none of your immediate circle is affected.
I think you are very brave and many of us are of an age where these things start to become a part of our lives.
Naturally I felt for you portugal, old age does not come alone and the younget generation has a need to listen up. In my case I've had a stoma bag changed daily for almost 13 years ("of all the things I've lost it's the ring I miss the most") and have had a permanent catheter (changed every 12 weeks) due to a benign prostate for two years next month. Some troubles never seem to go away, a blood test last week indicated a high PSA and I'm in for a repeat test tomoorow.. I have always taken the view that in reaching old age one has to be either very poor or very wealthy to cope with what one is to be faced with. With the help of Stocko, it's contributors and commenters I've achieved that second objective, I thank you all and am now working for our two grandsons.
Keep Buggering On. KBO
God bless Silver Moon. My German brother-in-law has just had a stoma fitted. Older age can be tough for sure.
Your post prompted me to book a PSA test - thanks for the reminder portugull.
I had a PSA test last year after walking into the GP and asking. It’s hard to talk about at times but we must take care of ourselves gentlemen.
portugull - I would echo what many have said that the post was appreciated and if only stirred one reader into action will have done good. However, what got me about your post was the mention of Torbay Hospital. That is where I was born multiple decades ago. It has been rebuilt about three times since, but still in Shiphay.
Next (LON:NXT) Mighty fine results.
I seem to recall selling these shares a number of years ago because I was a little disappointed with the results. Urgh.
Return on capital has averaged nearly 30% over 5 years.
I don't think you're alone in flagellating yourself with thorns every quarter that £NXT reports!
Thankfully bought in when they briefly dipped below £50 in November 2022… unfortunately only took a small position with intent to build on any dips… still waiting for the dips.
Next (LON:NXT)
I seem to recall selling these shares a number of years ago because I was a little disappointed with the results. Urgh.
similar i sold out on valuation grounds (i dont remember company commanding a premium rating back in the day) and perhaps slight worries that at the time they were making too much from the credit side of their business (not sure if that is still the case?) - i thought it would very much be a plodder if i held on - infact i seem to remember being quite happy i got over 7000p when i sold. Hey ho the future is hard to predict thats for sure - what is not in doubt is that this is very well run business i think we can universally agree on that fact that probably the secret sauce here.
Me too ... one of my many mistakes.
For once Next (LON:NXT) is one I have got right! I did exit back in late 2019/early 2020 (Covid panic) at around £50 per share. Fortunately took the plunge and got back in at c. £49 in September 2022. There is little doubt that their management and financial controls and reporting are best in class. The retirement of the previous CFO appears to have made no difference to the quality of reporting which must reflect well on Next (LON:NXT) succession planning. Let's hope the same applies when Simon Wolfson calls it a day!
What a contrast with that the today's news item from GSK (LON:GSK). I first bought this share at £23.27 (!!) in November 1999. Foolishly I held it for 25 years with some dividend reinvestment from 2019 onwards (all but 2 transactions at prices above the current level) but finally decided to throw in the towel in January 2025. The result a 37% increase in the share price during 2025! There were some decent dividends along the way but my total shareholder return wasn't great even allowing for that.
All in all two very contrasting decisions but I guess that is the name of the game!
Also you got Haleon stock with the demerger…
Indeed but a very small compensation and HALEON (LON:HLN) stock hasn’t done much since though I continue to hold in the hope of it being acquired!
Next (LON:NXT) was range bound for a long time. I sold at the top of the range . Good decision on the facts at the time . I suppose the lesson is as with Goodwin that it can take a number of years but quality will break out in the end .
Followers of Hansa Investment (LON:HAN) or Avation (LON:AVAP) may find the following insightful:
https://east72.com.au/wp-conte...
cheers abtan
do you have any opinions with regard to Avation (LON:AVAP) - currently. The shareprice performance seems so be going nowhere despite the ntav being more than double the shareprice.
I suspect it perhaps doesnt help that broker forecasts are for modest profit levels the next 2 years - interets on the loan notes i think isn 8.5% so their financing aint massively cheap. and the equity compared to value of assets and debt is quite low which is perhaps always a slightly risky situation eg if they needed to issue shares to raise finance (something they have done well to avoid). I suspect for companies like this you either wind your neck in in and develerage or do the exact opposite (in for a penny in for a pound). So perhaps just so many moving parts that the market sees too much risk despite them being a reasonably well run company?
Avation (LON:AVAP)
Hi rmillaree
I'm not overly hopeful of a material re-rating anytime soon, even with the shares trading at such a large discount to NAV (and even excluding the aircraft purchase rights.)
My initial hope was that a larger acquirer would come along and see an opportunity to either buy the company below NAV or buy it at NAV, but refinance Avation's debt.
In my mind 1 of 3 things needed to happen:
This didn't happen.
This didn't happen - in fact the 2025 refinancing was at a higher rate (8.5% vs 8.25%) and for 5 years.
The CEO has consistently stated that he has no plans to sell below NAV.
For me, this make an acquisition unlikely for a few years until a refinancing event comes around again, unless the CEO has a change of heart and decides to sell below NAV.
Having said all that the company seems to be doing everything right; buying and cancelling shares below NAV, paying back debt, growing the fleet, etc...
I've held a small position to feed the FOMO, but I'm less convinced that there will be a re-rating any time soon.
A
Thanks abtan for your very helpful comments on Avation (LON:AVAP) and the link you provided. I had penned a response just now but seem to have lost it, so this is a second attempt .
I was saying that I'm a holder too and that I had earmarked this one as a sell, although so far have held on for similar reasons as yours ie FOMO. Your shrewdly given reasons for a takeover being unlikely may help me in my decision to sell - possibly - perhaps on a day when the sp is up - last few weeks seem to be up&down in a range 136-141p.
I'll see but thank you again.
Avation (LON:AVAP)
cheers - most appreciated. yep its a tricky one here - are they better buying back shares rather than paying debt down. It will probably only be with be benfit of hindsight whether that particular plan is cunning or not. Its perhaps a shame that the main owner isnt a bit more realistic ref exit terms - eg with the debt and high financing costs they have is it realistic to expect expect above book value sale - perhaps it might be if acquirer can pay half the interets rates AVAP are paying - but if the market is valuing at 40% of book value i think one would need a bidding war for someone to offer over 100% of book value - or perhaps get lucky if acquirer really liked the fleet profile - so to me some discount to book value would still give decent payday that is sorely lacking at present. I have always had the nagging suspicion that this might end decently for anyone who buys in at around 40% of book value - just never had the courage of my convictions to take a stake - imho any company paying 8.5% on their debt is clealry seen as a risk from lenders point of view - and lenders rank ahead of us if anything does go wrong (not that i think it will)