Daily Stock Market Report (Tue 7 Jan 2025) - SQZ, NXT, CNS, ARB

Good morning! The RNS remains quiet for now - it appears that many City workers and company management teams have taken full advantage of the chance to take a break over Christmas. I did think we would have a few more updates than this on January 7th!
11.50pm: we are all done for today, see you tomorrow!
Spreadsheet accompanying this report (updated to 3/1/2025).
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Next (LON:NXT) (£11.9bn) | TU | Full-price sales ahead of exps; pre-tax profit exps increased by £5m to £1,010m. FY EPS +11.4%. | AMBER/GREEN (Graham) |
Serica Energy (LON:SQZ) (£593m) | Production update | FY prod 34,600 boepd, below Q3 guidance. Most issues resolved, output currently 46,400 boepd. | AMBER/GREEN (Roland) |
Corero Network Security (LON:CNS) (£100m) | TU | “Broadly” in line for 2024. Looks like a probable miss for 2024. Confident in 2025 expectations. | AMBER/GREEN (Roland) |
Argo Blockchain (LON:ARB) | Dec Operational Update | Their hosting agreement ended; they are evaluating alternative sites to rehost their machines. | RED (Graham) |
Summaries
Serica Energy (LON:SQZ) - Down 1.7% to 148p (£582m) - Update on production - Roland (I hold) - AMBER/GREEN
Today’s update reveals that Serica’s 2024 production of 34,600 boepd fell below even its 5 December guidance. However, various technical issues now appear to be resolved and reliability is expected to improve in 2025. With current production running at over 46k boepd, I expect strong cash generation and believe the 15% dividend yield remains sustainable.
Next (LON:NXT) - up 3% to £98.32 (£12.2bn) - Trading Statement - Graham (I hold) - AMBER/GREEN
Full price sales in the pre-Christmas period were up 5.7%, vs. prior guidance of 3.5%. This slightly increases the full-year PBT estimate for FY January 2025 to £1,010m. Looking ahead, the company anticipates 3.5% growth in full-price sales for January 2026, and a similarly modest increase in PBT. Next remains impressively robust to my eyes and it will need to rely on this robustness if its pessimism re: the UK economy is well-grounded.
Corero Network Security (LON:CNS) - Down 2.5% to 19p (£98m) - Trading Update - Roland - AMBER
Today’s full-year trading update reveals Corero has missed 2024 revenue and EBITDA expectations slightly, but trading performance has remained positive and the growth outlook for 2025 is unchanged. I think there could be an interesting story here, but the low profitability and full valuation mean I’m neutral for now
Short Sections
Argo Blockchain (LON:ARB) - down 7.4% to 4.9p (£35m) - December operational update - Graham - RED
This crypto miner issues its normal monthly update. Revenues are up to $3.9m thanks to the rising bitcoin price, but there is a sting in the tail:
As previously announced, the Company's hosting agreement with Galaxy ended on December 28, 2024. The 23,619 S19J Pros at the Galaxy site will be refurbished so they can be used in an air cooled facility. The Company is currently evaluating alternative sites to rehost the machines.
Galaxy is the company that rode in and saved Argo back in 2022, buying its Texas mining facility for $65m and also lending it $35m. That loan has since been repaid but now Argo is without a facility, as Galaxy are not interested in keeping Argo as a tenant.
I could hazard a guess as to why Galaxy might have have made this decision. Interim results for Argo to June 2024 showed that it had a negative balance sheet value of minus $20m, and to add insult to injury it was loss-making at the operating level. The cash balance was only $4m; it has since raised £6.5m in fresh equity (July) to help it finish repaying the Galaxy loan, and then another £4.2m (December). Shareholders have suffered dilution of c. 20% so far this year.
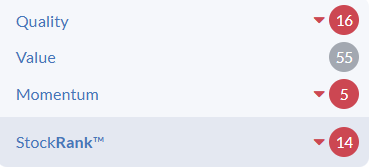
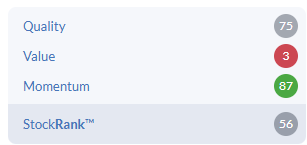
I’ve never been a fan of this stock and it remains an automatic RED for me after today’s update. At least the class action lawsuit by some of Argo’s US-based investors has been dismissed. With the company’s crypto mining machines now in need of being relocated or sold, they are exploring new ventures in high-performance computing. I’m afraid I don’t view this as a serious investment opportunity, and the StockRanks are on my side:
Graham's Section
Next (LON:NXT)
Up 3% to £98.32 (£12.2bn) - Trading Statement - Graham (I hold) - AMBER/GREEN
It’s pleasant news for NXT shareholders such as myself, as we get yet another ahead of expectations trading update.
This remarkable management team continues to under-promise and over-deliver. It’s amazing how the simple act of keeping expectations low, and then consistently beating them, even by small amounts, can generate such goodwill among shareholders like me.
The headlines:
Full-price sales in the six weeks to 28 December are up 5.7% year-on-year, after adjusting for the timing of Christmas this year compared to last year.
The full-year PBT forecast for FY Jan 2025 increases by £5m to £1,010m.
This PBT estimate is 10% higher year-on-year, with pre-tax EPS up 11.4%. That controversial topic of buybacks is relevant here: NXT’s share count continues to gradually decline, which helps to put upward pressure on earnings per share.
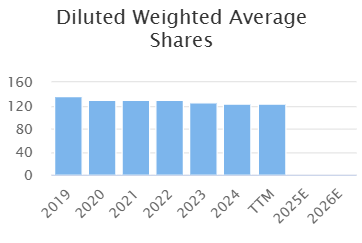
The share count is expected to reduce by nearly 3% this year. As the stock currently trades at a moderate PER of about 14x, I don’t think they need to be any more aggressive than this when it comes to buying back their shares.
Trading performance
For the financial year to 28th December, we have the familiar pattern of UK online sales growing (+5.2%) faster than UK retail sales (minus 1.1%). Overall UK growth is modest at 2.5%.
Overseas sales unexpectedly accelerated in the pre-Christmas period (31.4%) and now have a growth rate of nearly 24% year-to-date.
Cash flow and net debt plans
The company’s planned use of its £670m of surplus cash generated this year is clearly explained. There’s a nice mix of dividends and buybacks to keep fans of both happy, plus a small reduction in net debt from £700m to £625m.
There is £250m bond maturing in August 2025, so Next wants to have some extra cash available:
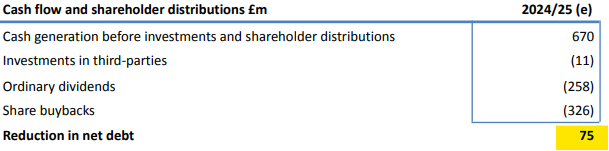
Next’s intention has been to repay this bond using its own resources. However, “subject to market conditions, we may choose to issue a new bond in 2025 which would allow us to distribute more surplus cash to shareholders.” So there could be a nice boost to the dividend, or more buybacks, if the company thinks it can borrow cheaply again in August.
With full-year PBT significantly higher than net debt, I do think that Next can afford to use more leverage, but I’m relaxed about whatever option it chooses as August approaches.
Guidance for FY January 2026
Not much growth is baked into these forecasts:
Full-price sales growth 3.5%
PBT up 3.6%
Pre-tax earnings per share up 6.7% after the effect of share buybacks.
Next say they are being cautious on the UK, where they expect only 1.4% sales growth, due to employer tax increases, i.e. higher National Insurance. These tax increases will “filter through into the economy”, impacting prices and employment.
Internationally they are only forecasting 14% sales growth, vs. 24% in the current year. They say that the current year saw a step change in overseas marketing expenditure, and they don’t think they can profitably increase marketing spend at the same rate in the current year.
£67m increase in wage costs: this figure is estimated from “normal” inflation of 2%, plus the change in the national living wage, plus higher NICs, plus the cost of wage inflation at NXT’s suppliers. The change in the national insurance threshold alone creates a 6.5% increase in the cost of hiring a part-time low-wage employee.
How the company will mitigate this: firstly, by increasing prices by 1% (but NXT’s prices will still rise by less than 2%). Secondly, by operational cost savings, primarily new mechanisation at warehouses. It seems that about half of the increased wage costs can be offset in these ways.
Graham’s view
In my view, NXT remains the absolute gold standard when it comes to UK company reporting. The clarity, transparency and (I hope) honesty are second to none.
As for the company’s actual trading performance, I have no complaints. Of course growth could always be stronger, but this is a mature business and moderate growth comes with the territory.
It does trade at a higher PER than its industry peers:
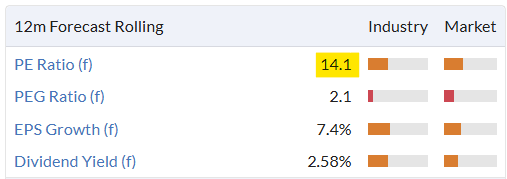
However, even at this PER, its buyback activity (paid for out of ongoing cash generation) helps to juice its EPS growth in a noticeable way.
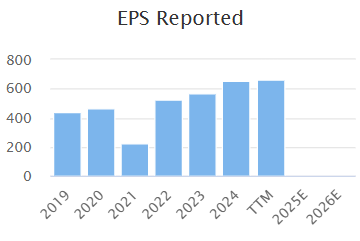
Stockopedia reports net profit growing at a CAGR of 6% since 2019, while reported EPS has grown at a CAGR of 8.3%:
See my update in October when I gave a big-picture summary of Next’s attractions.
Does the company face significant risks? Of course. I am extremely selective when it comes to retailers, and there are probably only a handful that I would even consider buying. This is a low-quality sector where economic winds often decide the face of mediocre businesses.
I think that Next is different: that it has a management team who are uniquely logical and sensible.
One of the major concerns facing the sector right now is of course employment costs and taxes, but Next has an in-built cushion in the form of a chunky operating margin (19% according to the StockReport). It doesn’t need to panic about profits evaporating overnight.
As for my current stance, I’m inclined to leave my AMBER/GREEN unchanged here. I was AMBER/GREEN in October at a share price of £102. At a share price of £98 and in the wake of another upgrade to earnings expectations, there is little reason to change my view.
The outlook for 2025 is indeed very cautious but that is probably appropriate in the circumstances and in any case Next are known for their caution, so there is really no surprise on that front.
Roland's Section
Serica Energy (LON:SQZ)
Down 1.7% to 148p (£582m) - Update on production - Roland (I hold) - AMBER/GREEN
The title of today’s RNS sounded slightly ominous to me – and so it proved. After warning of further issues with the Triton FPSO in December, the company today admits it did not meet even December’s reduced production guidance.
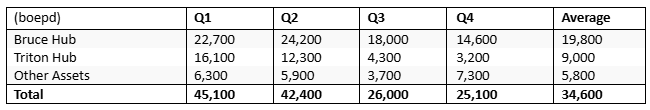
Serica now confirms full-year 2024 production of 34,600 boepd, slightly below 5 Dec guidance of 35,000 to 36,000 boepd. This quarterly table provides a useful breakdown, showing that overall production did not recover as previously hoped in Q4:
The issues: the Q4 shortfall is primarily blamed on the Triton restart being “at the longer end of expectations”.
Production shut down on 5 December and gas exports did not resume until 29 December, when the export gas compressor was restarted “following extensive root cause analysis and remedial work”.
Unfortunately, Serica’s owned and operated Bruce field also experienced a period of unscheduled downtime during December. This was said to relate “primarily” to a subsea intervention to improve production reliability on the neighbouring Rhum field.
I assume the impact of this downtime is reflected in the lower Q4 production from the Bruce Hub versus Q3. The big drop off in Q3 reflected scheduled annual maintenance.
2025 production: it may be that these issues are now in the past. Overall production net to Serica was running at 46,400 boepd on 5 Jan.
This figure is expected to increase as the phased restart of Triton completes and the newly-completed Gannet GE05 well is brought online.
Other drilling is also underway that could contribute to H1 2025 production, while Triton reliability is expected to improve when the FPSO resumes operations with two compressors later in Q1.
Roland’s view
In his comments on 5 December (when the latest Triton problems were announced), Mark documented the decline in Serica’s 2024 production guidance during H2 2024:
H1 actual - 43,700 boepd
2nd Oct FY guidance - towards the bottom of the 41,000 to 46,000 boepd range
29th Oct FY guidance - expected to be slightly below this previous guidance (41,000 boepd)
Today's FY guidance - 35,000-36,0000
It’s not a pretty picture and it may be worth remembering that Serica’s assets are fairly mature. I can’t be sure, but I wonder if they may be more prone to reliability issues than more recent developments, especially as operators are likely to manage capex tightly to reflect limited production lifespans.
However, Serica is a respected operator with a good reputation. Today’s update suggests to me that recent issues are now largely resolved.
This view is supported by updated broker commentary from Auctus Advisors forecasting total production of c.41k in 2025 – many thanks.
The investment case for Serica – and the reason I hold the shares – is based on the company’s strong cash generation. In its H1 2024 presentation, the company said it expected to generate surplus cash equal to its then market cap (c.£500m) between now and 2028.
This should underpin the stock’s current 15% dividend yield, which continues to look safe to me.
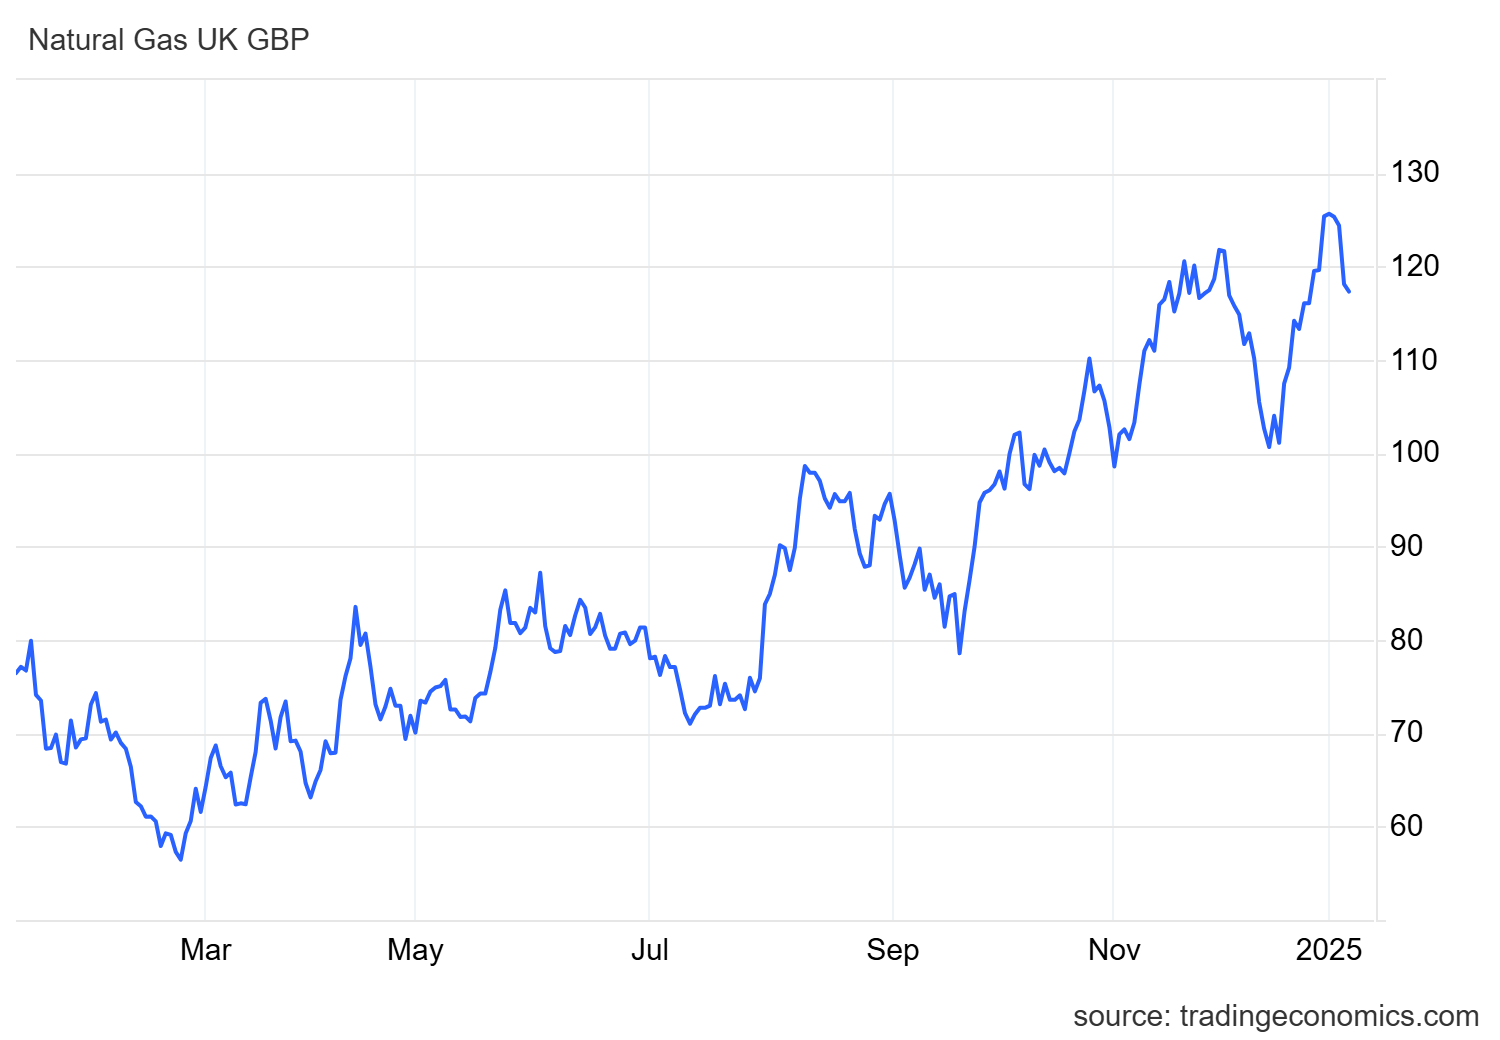
The rising gas price trend should also be positive for Serica, whose production is roughly 60% gas, 40% liquids:
I remain happy to continue holding and believe the shares offer value at current levels. However, I may turn more cautious if 2025 turns out to be as problematic as 2024. For now, I’m maintaining our previous view of AMBER/GREEN.
Corero Network Security (LON:CNS)
Down 2.5% to 19p (£98m) - Trading Update - Roland - AMBER
Trading across FY 2024 is expected, subject to audit, to be broadly in line with market expectations.
Corero Network Security provides security software (SmartWall) to protect against denial of service attacks.
The shares have doubled over the last year. While today’s update appears to be a slight miss against expectations, the muted market reaction suggests to me investors remain comfortable with the outlook.
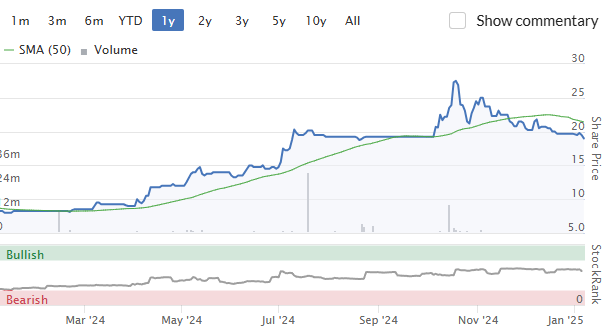
Interestingly, the sloping line at the bottom of the chart above shows us that Corero’s StockRank has improved and become much more respectable over the last year. The shares now boast a high quality-momentum score, typical of High Flyers in the Stockopedia style rating.
If growth remains strong, this suggests to me the shares could potentially continue to perform well:
Let’s take a closer look at today’s update.
FY24 trading: operationally, 2024 seems to have been a decent year for Corero.
In line with industry trends, the company aims to sell its software on a subscription basis as well as through upfront licence sales. The subscription service is described as “DDoS Protection as-a-Service (DDPaas)”.
Reflecting this model, annualised recurring revenue (ARR) rose by 16% to $19.5m last year, while order intake increased 13% to $28.2m.
Corero’s interim results showed ARR up 12% to $17.2m and order intake up 10% to $14.2m, so H1 performance appears to have been maintained during the second half of the year.
Profit miss: as Mark commented before Christmas, use of the world “broadly” generally indicates results below expectations. That seems to be the case here.
Corero’s full-year revenue rose by 10% to $24.6m, slightly below Stockopedia’s consensus forecast of $25.6m. Updated notes from Canaccord Genuity and Zeus Capital today both confirm this slight miss.
In terms of profit, adjusted EBITDA is expected to be between $2.2m and $2.5m (FY23: $1.8m), versus broker forecasts of $2.6m to $2.7m.
I’m not a fan of adjusted EBITDA as it excludes too many costs for my liking. This is reflected in sharply downgraded earnings forecasts from broker Zeus today - many thanks.
Zeus has used the low end of Corero’s EBITDA guidance to update its forecasts. As a result, the broker believes Corero will only achieve a breakeven result at the bottom line this year:
FY24 EPS (previous): 0.1 cents
FY24 EPS (latest): 0.0 cents
Margins remain low: I’m surprised Corero is providing such a wide EBITDA guidance range, given that 2024 has now ended. I wonder if there are some accounting questions to iron out.
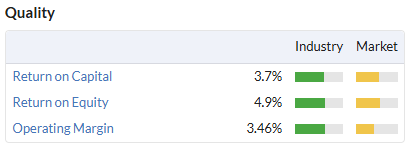
Regardless, these numbers highlight the continuing poor profitability of this business. Using the midpoint of today’s EBITDA range gives me an FY24 EBITDA margin of just 9.5%.
That doesn’t seem all that exciting to me – ID security group Intercede (LON:IGP) is of a similar size, for example, and reported a 21% EBITDA margin in its last set of accounts.
I understand Corero has been scaling up its sales team and I would hope to see evidence that operating leverage will improve margins with further growth. At present, profitability remains uncomfortably low, for me:
2025 outlook: the company sounds confident about the year ahead:
Management is encouraged by the FY 2024 exit rate of ARR and new Orders and remains confident that 2025 market expectations will be achieved.
The group’s $5.3m year-end cash position is also expected to improve early in Q1, as $4.8m of cash for orders invoiced in Q4 is expected imminently.
Forecasts for 2025 have been left unchanged today, with Zeus estimating earnings of 0.4 cents per share, slightly ahead of Stockopedia’s consensus figure of 0.3 cents per share.
This leaves Corero shares trading on a hefty forward P/E of between 60 and 80, depending on which estimate you choose.
Roland’s view
I don’t have any insight into the quality or scalability of Corero’s product. I’m not sure who the end users are – smaller companies or large enterprises? What’s the realistic addressable market? Who are the competitors?
It would be very interesting to hear from any industry insiders (or investors) who are more familiar with this sector in the comments.
From a financial perspective, Corero seems to be making progress at building a growing base of recurring revenue. I’m also encouraged by the 97% customer retention rate. This seems to suggest the product is both sticky and reasonably useful.
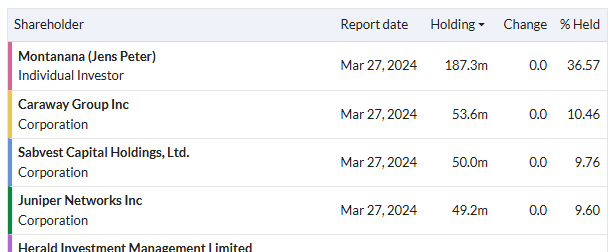
Looking at the shareholder register, I don’t recognise many of the names, but the presence of network equipment provider Juniper Networks (NYQ:JNPR) seems positive. I understand Juniper resells Corero’s SmartWall product to its customers, potentially providing access to a sizeable market.
On balance, I’m going to take a neutral view here. Corero’s net cash position and growing scale suggest to me it should be able to self-fund continued growth.
On the other hand, profitability is lower than I’d like to see for a £100m company, and I think the valuation already prices in significant further growth. AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
I thought that was a really good and helpful write-up on Next- thank you.
Regards
Andrew
please keep this thread to SVCR topics
What’s SVCR?
Small Crap Value Report - RIP
Thanks Harry
Perhaps hdavies2 is still in Christmas overhang mode!
All the best
Sorry but 3 years reading it religiously and going nowhere has dented my confidence, plus Mr Markets ludicrous IPO's killing all the 'golden gooses' it could lay its hands on.
Going full contrarian - read it in the news, do the opposite.
Haha. Experience comes at a cruel price.
Sorry bud, as from nov5 it is now The Daily Stock Market Report covering a wider area of subject material. If you've just got back from the Space Station you can read about it here. Feel free to select what you read.
Thank you Roland for your views on Serica Energy (LON:SQZ) this morning which is my 2nd largest holding. I have 2 holdings one in my SIPP bought in 2023 which is 43% down and one in my SIPP Drawdown which is 15% up.
In the last 2 years I have received £7,250 in Dividends and at the current SP 149p I do feel there is value here particularly with Gas Prices rising.
SQZ are holding a Meeting with Investor Meet on Jan 21st at 9am which will bring investors up to date and will hopefully provide more guidance on 2025 Production.
Its just a thought, there are a large number of posters here who are interested in the future of EVs and companies which might benefit from further EV take up.
Would it be worth Stocko giving EVs a thread of its own?
Create one on the Discuss board. Interested in a solid state batteries that are quicker and cheaper to charge apparently. Tech will maybe catch up with politicians aspirations - but my interest is it contains silver, as do a lot of 'green' tech - now that's an investment.
Corero Network Security (LON:CNS) is another of those software companies where the transition to SaaS from upfront contracts is perhaps concealing their underlying progress. In the last 2 years, ARR is up 38% vs revenues up 22%. Profitability is negligible as they've invested in new product launches and doubling the salesforce but they are cashflow positive even so. As Roland says, their EBITDA margin is only 9% but that should be the low point due to investment with the corporate broker forecasting it increasing to 14% next year and 16% the year after due to operational gearing.
The DDoS TAM is over $4 billion and growing in double digits, particularly as AI makes DDoS attacks much easier and cheaper to execute and Canaccord reckon Corero Network Security (LON:CNS) market share has increased by over 40% in the last 3 years vs the competitors they track with the technology seemingly good enough to displace incumbents.
They've also started going down the partner route. Juniper has been a partner for a while but they've recently added GTT and Akamai.
I view them a bit like PCI- PAL (LON:PCIP) where it's more about the growth (as long as it's cashflow positive) rather than the PE ratio at this point in their development.
I hold both.
Team Internet (LON:TIG) Low ball offer today. At least there may be further upside from the indicated 125p, if the two prospective bidders engage in a bidding war.
Hi
To add a broader perspective into the thread beyond the UK.
At last nights CES conference NVIDIA (NSQ:NVDA) keynote speech, Jensen touched on several important trends in the AI, compute, robotics, autonomous AI space. Outlining the speed and strength of technological innovation.
These trends are coming thick and fast so I think it useful for any investors to consider as these changes will (eventually) impact even the UK markets.
For those interested this X tweet is a good summary (from a well known US tech analyst Gene Munster) ...
https://x.com/munster_gene/sta...
For the more enthusiastic tech investors or US investors see the CES Keynote on You Tube vid on Nvidia's channel (or other super cuts).
Sadly UK nor Europe has anything close to these sort of investment opportunities.
The Stocko team might like to analyse some of these innovations in one of their postings.
I hold NVIDIA (NSQ:NVDA) indeed most of my portfolio is US invested.
Regards
Howard
On the subject of EV's.
The AA are bringing out a service tailored for owners of small battery powered cars, it will marketed as triple A according to Jack Dee.
To kick the tyres so to speak I test drove a Tesla (NSQ:TSLA) Model 3 last year, if you get time and there is a center near by do it, it was all remote, you get the car for an hour - no big sales pitch, just a pre and post drive call to see how it went.
It is a fantastic car, if they bring out a smaller model I'll get one. Incredible car, getting back in my ICE vehicle was like stepping back in time.
Tesla (NSQ:TSLA) as an investment faces serious challenges - Musk is called a chief executive, but he's not. He got a shareholder vote in June promising to devote himself to the company and has spent his time since campaigning for Trump and down to be DOGE. He's also the chief executive of four private companies (including X) so how can he devote enough time to any of them?
His outrageous option, which would give him another eighth of the company (to add to his existing eighth) has been blocked so far in Delaware. And he's diverted AI resources and chips destined for Tesla to his private company (xAI).
To make matters worse, Tesla's other directors don't seem to know what they're doing and the share price is grossly overvalued! That's why I won't invest in Tesla nor any UK fund or investment trust (such as Scottish Mortgage) that owns its shares.
But still +150% on my 2024 position - Mustn't grumble Tesla (NSQ:TSLA)
I don't agree with his politics but the company is superb. Watch out for the affordable model and semi this year , never mind FSD which is now Full AI and getting better than a human.
Still, time will tell if Elon implodes or not.
But still +150% on my 2024 position - Mustn't grumble Tesla (NSQ:TSLA)
indeedy - plus those held from the date the future options were announced did ridiculously well - not sure of the exact numbers but Musk delivered something like 10 x return for shareholders since options were announced - and anyone buying later on knew what the deal was - so future costs/dilution were a known factor fro anyone buying from 2018 onwards.
I think any shareholders who can be promised 10 x return and chance to exit at that time before payout is made have not got a bad deal in any respect.
I would be pretty happy to sign off on similar deal for any company i hold shares in without exception !!!!
His outrageous option,
What was outrageous ref his options ??- i thaught he delivered in bundles for shraeholders and was rewarded based on the fact he delivered fantastic returns for shareholders.
Incredible car, getting back in my ICE vehicle was like stepping back in time.
It depends what you are comparing it to. I had a day in a Porsche Macan Electric - which is considerably nicer than a characterless Tesla - and it was very good and quieter than the ICE version (or my BMW petrol estate) but not more modern and unquestionably less enjoyable to drive enthusiastically on account of the huge increase in weight. Good in traffic though with superior NVH and would definitely strongly consider going electric for the calmer cabin.
I'm talking about the software as much as the hard ware, has to be tried to truly appreciate it.
Just dipped into Pony AI (NSQ:PONY) - already running autonomous taxis in 5 major Chinese Cities and license their software to Toyota and other OEMs. Maybe regulation will reduce under Trump 2.0 but unlikely imo.
Liontrust Asset Management (LON:LIO) funds up their holding in Impax Asset Management (LON:IPX) to 13%.
I was a holder but let them go some time ago due to the exit of assets but it would be interesting to see if they have bottomed out. Profitability and cash flow remain positive and dividend is now very good and affordable. Will keep watching...
Some short squeeze in Victoria (LON:VCP) ! Up 30% this morning
NXT Want a laugh at my expense? I bought NXT in Nov 2015 at 8013p and sold out in Dec 2016 at 4933p when its stockrank was 45 and I kicked it out "by rotation". I should have done it the other way around, of course.
In Nov 2015 the fwd PE was 17 and it was trading on a P/FCF of 22 (I'm using Stocko's archived PDFs, which you access via "Print"). Momentum score was 89.
In Dec 2016 the PE was 11 and P/FCF was 15. In retrospect that was cheap. The share price had a torrid year. Momentum score was 29. Paul wrote in Sep 2016 that it was a high-quality business. "Next describes current trading as 'challenging and volatile'. It is adding lots of new space, and with such good ROCE and short payback times, this makes a lot of sense. ... There are a number of headwinds though ... For these reasons I'm reluctant to buy shares in Next, although on a PER
of about 10-11, it's very tempting. The trouble is, it's difficult to see much future upside on profits." https://www.stockopedia.com/co...
Never easy, is it?
My own view? NXT is probably "fairly priced" PE is fine and I don't think investors will go far wrong. One thing I like to look at is the 10-year diluted normalised EPS that Stocko has on its income section. It went from 413p in 2015 to 662p in 2024. I like to see it double if I'm thinking about a company as a long-term quality buy. NXT falls short on that score, so it's difficult for me to get too excited about it.
Hi Mark,
Another Next (NXT) story - at my expense this time.
In a past life I worked for Lloyds Bank and recall the late 1980's when I was responsible for stock and sharedealing customer transactions in one of their high street branches.
I remember looking at Next shares at about 20p and thinking to myself that I should buy a few as I recognised I had switched from buying M&S suits and shirts for work to sourcing them from Next instead.
Unfortunately, I had just bought my first house and didn't have any spare cash so didn't make the purchase - it has 500 bagged since that time!!!
That really was a big one that got away!!
Richard
We all have ones that get away.
And one more Next story.
A friend, genuinely not me, bought 100,000 right at the bottom in 1990(?) at 7p.
They bounced so strongly the he sold them at 10p in the afternoon.
A genius trade, so he thought.
20 years later, at £70, he could have retired!
True story!
I remember this well. David Jones took over I believe and brought the company back from almost the point of no return.
Next (LON:NXT) (I hold)
Brilliantly clear reporting with a detailed profit and cash guidance for next financial year. I don't understand why other good companies don't do this to demonstrate the strength of their business model.
Superb performance in their Online Overseas (ytd: +24%) with potential to carry on growing. Also clear ramifications (fewer jobs and increased selling prices) of the budget increase in Employers' National Insurance, particularly highlighting the 13% cost increase of employing people on a part-time basis.
Raspberry PI Holdings (LON:RPI) down 7.5% to 550p this morning What a roller coaster - Up and now down as HSBC raise their target price to 500p. Another sign of the crazy market out there.
Graham, I hold Serica Energy (LON:SQZ) and am one quarter underwater seemingly having added shares in the ups rather than the downs. I'm happy with the returns in dividends but "This should underpin the stock’s current 15% dividend yield, which continues to look safe to me" does not ring true in my opinion as while the share price recovers, which it will in spite of the super windfall tax, the dividend will correspondingly fall. Time now for me to add again, methinks.
Thanks for the comment Silver Moon. Roland wrote that section - he's the expert today on SQZ, not me!
I assume Roland meant the ability to generate enough cash to pay the dividends will be there, rather than the yield % .
Hi Silver Moon,
What I meant about the dividend at Serica Energy (LON:SQZ) is that the cash value of the payout continues to look like it should be affordable, to me. (Assuming management don't change course and make a huge acquisition...)
A rising share price will reduce the yield, but as a shareholder that's a problem I would be happy to have!
Roland
re Serica Energy (LON:SQZ) im also an underwater holder but I would argue that given the tax backdrop and the weak gas price there was nothing to lose by scheduling maintenance early. This is a hopeful interpretation after an accident prone year. I would actually welcome acquisitions and the key reason I continue to hold is the belief that Mercuria will steadily pass more assets through to the listing which should be accretive.
Serica is not incurring super windfall tax because of carry forward capital losses, hence the strong cash flow generation and high dividends. It is a well managed company being attacked by net zero policies of clueless miliband who would rather import fossil energy than support British Oil Companies operating in the North Sea
GlobalData (LON:DATA) .... I hold... completes the acquisition of Deallus... GlobalData (LON:DATA) CEO mentions in statement ' poised to drive remarkable growth and deliver exceptional value to our stakeholders '...
Trading update next week...
Hi Cancun
There was a hint in today’s purchase statement that said something along the lines of they are looking forward to giving investors an update on the positive impact the previous acquisitions have seen.
I could be wrong but feels to me like they are warming up for a strong trading update.
Journeo (LON:JNEO) announced a £1.4m contract from Stoke City Council for the provision of real-time bus information.
Charge-point surge heralds UK ‘electric car revolution’
More than 120 planning applications for plug-in stations for EVs have been approved
The UK is on the “cusp of an electric car charging point revolution” with the number of plug-in stations set to increase considerably in the next two years.
More than 120 planning applications for plug points, worth more than £500 million, have been granted in the last 18 months by local authorities, equating to hundreds of thousands of new points
https://archive.ph/Yvw9w
Volex (LON:VLX) Pod Point group (LON:PODP)
And anyone forced to use them will be paying an arm and leg plus 20%VAT - Reminds me of the article in the Times recently that long distance travel by EVcar is just as if not more expensive than petrol.
71% of journeys are under 5 miles apparently...
Few of mine are. I cycle for short journeys. Over 50% of mine are long, over 3 hours, some 6-7 hours. Old EVs just not good as over about 100 mile range. Waiting 30-40 minutes to recharge every 1.5 hours, is not on. Note range on motorways is less as at higher speeds and less braking.
71% of journeys are under 5 miles apparently...
Which I think is all modes of transport, including walking and cycling.
However, the basic principle applies - the average car journey length in the UK is around 8 miles which is perfectly achievable with an EV even as half a return trip but is too far to walk unless you have half a day to spare.
We use petrol for long distances, although I hardly do any of those now, and electric for everything else.
timarr
That is the problem, EVs are fine for short journeys, but those can easily be done by train or bus in an urban environment. Not so good for longer journeys, so you are forced to run two cars.
That is the problem, EVs are fine for short journeys, but those can easily be done by train or bus in an urban environment.
Ah, but as noted previously, people don't use public transport, they drive. If you can figure out how to change that then the problem goes away, anyway.timarr
30% of uk properties don’t have driveways so will need to charge elsewhere.
motorway chargers are most expensive, like petrol on motorways but they are still about 40% cheaper than petrol, plus you can charge at origin and destination usually
As a long-term EV driver, I agree that the most expensive, fastest charging, public chargers will take you all the way up to about equal with petrol. But most people can charge at home for a third of the cost (or a quarter if they have smart meter), and the build-out of slower street chargers, at-work chargers etc. is gathering speed too. It's worth remembering that the up-front cost of these is not negligible, and there's a real chicken-an-egg problem between, having chargers and there being the cars to use them. As the electric fleet grows and they get used more, the prices will start to come down. It'll be interesting to see where they are in 3 years.
Well the government is fixing the playing field to ban petrol/hybrid cars the result is inevitable. The real crunch of course is EV are not good for the environment and their production and ongoing maintenance is not CO2 neutral as the propaganda might promote.
Plus I don't much go for their heating systems(car fires)
I believe the myth about EV car fires is dealth with in https://www.faircharge.co.uk/l...
I understand that insurance on EVs is very much more costly than on an equivalent ICE vehicle. That cost alone surely negates any annual savings made on electricity charge vs diesel costs? So in practice they are more costly, less convenient (for long trips) and have little or no benefit regarding CO2 reductions (when the extra, and ongoing, manufacturing and sourcing of lithium, nickel, cobalt etc are factored in). If we all swopped to EVs then there would have to be a corresponding carbon cost to construct additional charging points and to supply the additional power. Oh, and they cause far more tyre particles than ICE cars due to the instant torque. My last diesel did over 65mpg and was still going strong at over 165k miles when I sold it at 10 years old. It'll stick with my present LEZ compliant diesel as long as I can thanks.
Savings on driving an EV versus an ICE car isn't something that can be generalised as true or false. It very much depends on a whole range of variables. Principally it depends on mileage driven, range of the EV, cost of the vehicle, cost of charging, cost of petrol or diesel, insurance and road tax. Any one of these can easily turn the argument on its head.
I drive two EV's, have solar panels and a home charger. Octopus supply my electricity and allow 5 hours of cheap electricity at night. This works out at less than 2.5p per mile for me. If you drive an ICE vehicle that does 50 to the gallon, the cost is roughly 12p a mile. One of my EV's has a limited range which means it tends to be used for shorter journeys although it did once travel 180 slowly driven miles before recharging. The other EV can do nearly 300 miles on a single charge. Neither is a Tesla. Both are a joy to drive, quiet, responsive and economical.
The stupidity of Government imposing a hefty road tax on higher originally priced EV's is a disincentive to owning one. It makes little sense when you claim you don't want people to buy ICE vehicles as is any additional taxation compared to ICE ownership.
I've enjoyed ICE vehicles in the past including a V8 BMW convertible that required its own oil well. Times have changed and clinging to the past and stating dubious opinions as facts doesn't help.
electric cars are pretty niche items at present - as pretty new (mass market) tech - it aint going to have price parity at present with diesel/petrol and that shouldnt be expected at present.
Other arguments are your cherry picked personal viewpoints
Eg ev vehicles are perfect items to use overnight electricity when demand is lower and there may be a decent surplus on the grid plus we are moving towards a more renewable source of power anyway.
You mention tyre wear but ignore the fact there are less parts that will need maintenance - not an expert on particulates but i woudl guess extra tyre particulates are nothing like the problem of equivalnet diesel/petrol car particualtes that are being removed.
I think your average tesla can be expected to do well over 300k miles without much issues being expected so from what i have seena decent electric car should be able to match a diesel on average (some will obviously be unlucky)
So whilst some of your points definately are valid you seem to be taking anything other than balanced viewpoint ref the future of ev's . Hopefully over time some of the negatives you highlight will partly dissipate as they become less niche (prinicpally battery prices should be expected to reduce over time).
Although this data is from 2022 - and it appeared in The Guardian - the company doing the analysis was quoted as saying that particulates from exhausts are so low on new cars that if we started now it would not be worth tracking them
Tyres produce far more particles than exhausts in modern carsMilligrams of particles per kilometre of driving: New tyres 73.0, Used tyres 36.5, Exhaust legal limit 4.5, Exhaust - real world 0.02. . Source: Emissions Analytics
would be interested in accurate stats for sure - without doing a deep dive a quick search near the top of google has the following article from the rac. not sure is thats disagreeing with the guardian piece or not - but it does loks like some of the press releases quoting sismilar may not have been of the "unbiased variety" - thats so often the case with renewables that its not uncommon for nonsense to be trotted out as fact (that can happen on both sides of the dividing line i would say)
thanks for supplyinmg info though - it is an interesting stat If the guardian article is right
https://www.rac.co.uk/drive/el....
As a recent EV user I spent a lot of Xmas travelling to relatives & out visiting. I have a home charger that is 9p per unit of electricity at nighttime vs normal charge of approx 22p. I can therefore charge my car at home for about £7-9 which will do me 300+ miles. I got a few all-day Sunday charges free through EDF in Nov & Dec which also helped.
However, using public chargers I was paying between 70p-90p per unit and a full charge was about £75-80.
The price of the car was ridiculous compared to equivalent gas guzzlers, but it is very nice. Don't buy new as they lose about 40-50% depreciation in year 1.
All-in-all if you can avoid public charging largely, don't mind the initial cost (I view it as a present to myself) and are happy having a 30minute break every 2-4hours on a long journey then it is OK. I am sure the whole life costs don't add up and if purely looking on it as a business decision then it doesn't work out. But I am viewing it as a 2 year test and can hand it back at the end of the lease and then see how I feel (having enjoyed a nice car and trialled the pros & cons).
The charging infrastructure is getting better, but the Govt need to help incentivise car companies & users - bringing back the road tax is not going to help in April.
90% of the time and I charge up at home and that costs me £17 for 220 miles range. My wife’s petrol car costs £45 for the same distance. When I do have to charge en route, my EV manufacturer provides a RDIF card that gets me 50% discount on 350,000 chargers all across the UK and Europe. I just don’t get all the negative comments about EV charging costs, they are just not factually correct. However, the additional cost to purchase an EV I do get, but hopefully for new buyers, there are plenty of discounts around. So far, I’m mildly positive on the EV experience but who knows where this journey will take us, with tax and government intervention, supply chain issues, energy costs etc.
'More than 120 planning applications for plug points, worth more than £500 million, have been granted in the last 18 months by local authorities, equating to hundreds of thousands of new points'
I really don't understand this. If 120 planning applications result in hundreds of thousands of new points, each new charging site would contain thousands of points.
Each 'planning application' would contain thousands of points.
Hydrogen is a dead duck unfortunately, the billions that has been spent and there is still not a commercially viable company - I used to believe, IEH - AFC Energy (LON:AFC) Powerhouse Energy (LON:PHE) all dogs
When is ITM Power (LON:ITM) due to make a profit?
A very short sighted personal opinion which bears no relation to the facts. ITM Power (LON:ITM) is doing very nicely, plenty of cash to see it through, plenty of sales of their equipment, backed by Linde, the German industrial gases giant and Lord Bamford of JCB fame and no fool with his money. A very good thread with many links is on ADVFN for anyone who wants to do research. Zeus have coverage for anyone who cares to register. Alternatively be like NewInvetor1972 and wait for it to make a profit.
I am a little more interested in who eventually controls these charging points and what price they are allowed to charge when the EV target is reached.
I think we can safely assume that cost of public charging today will be a lot more expensive when there is captive market
In London car ownership is genuinely optional as there is a good public transport network.
Outside london the service is between unreliable and ****.
At some point someone will work out that getting people from their home to a work reliably will be a big boost to productivity and the economy.
Electric cars cost too much.
So *Buses*. Lots of buses.
I did chuckle when you said buses the odd times I go on my local one at peak times it's like that scene out of the original Star Wars cantina.
This is a bit off topic, but anyone who holds Investment Trusts should be aware of this:
https://www.theguardian.com/bu...
Our investment trust sector needs our support. If it disappears, so will more liquidity and support for UK companies, which will in turn reduce returns for people like us. Keep an eye on your holdings and make sure that you vote in any AGMs. For the record, the majority of personal wealth is held in such trusts, which have been decent if not exceptional long term investments, and which provide almost all of my income.
The last thing that we need is an offshore hedge fund plundering our savings assets for short term gain, enabled by the fact that private shareholders tend not to vote. This can easily allow a minority shareholder to take over a trust.
Apologies for being off topic.....
Sounds like a charity appeal ad!
All the best
It's in the hand of the pension funds to start reinvesting in UK Limited, after all it our pension funds and none of us want the UK market to disappear
That is dangerously close to talking common sense there John LA