Daily Stock Market Report (Tue 8th September 2026) - CCC, DNLM, SOM, JSG, XSG, G4M

Canada’s “counter-tariffs” against the US have gone into effect, matching US tariffs “dollar for dollar”. Hundreds of different types of goods are included (if you’re interested, the full list can be viewed here).
Closer to home, John Healey’s “Growth Speech” yesterday didn’t seem terribly newsworthy. One snippet that stood out was a commitment to “reducing the burden of business regulation by 25% by the end of this Parliament.” It doesn’t sound plausible to me, but it’s a nice idea!
Right, on with today’s company news…
Overnight market movements:
The FTSE is down 0.3% at 10,780
S&P 500 is unchanged at 7700
Brent crude (November) is up 1.1% at $98.40/bbl
Gold is up 0.2% at $4,415/oz
Bitcoin is down 0.9% at $78,500
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Computacenter (LON:CCC) (£6.0bn | SR83) | Revenue +73.3% at constant currency. Adjusted operating profit +87.6% (£153.1m). “Following a strong start to the second half and a further increase in our committed product order backlog, we now expect adjusted PBT for full-year 2026 to be significantly ahead of current market expectations and to be no less than £380m." | AMBER ↓ (Roland - I hold) Timing the peak of a boom is impossible, but a number of details in today’s results make me wonder if growth in AI data centre spending may be levelling out – at least for good quality, credit-worthy customers. I also need to consider Computacenter’s valuation, which is well above historic norms. While I think this is an excellent and well-run business, I can’t help feeling that the good news is now priced in. The decline in StockRank since March also supports this view, in my opinion. I would be unlikely to buy more shares at current levels, so I’m turning neutral (while recognising that this could be premature). | |
Old Mutual (LON:OMU) (£2.5bn | SR64) | Value of new business up 32%. Adjusted headline earnings down 30% to R 2,951m. “The gradually improving fiscal position and sovereign credit rating trajectory in South Africa supports a positive macro backdrop… our strong first half sales volumes do include some large non-recurring gains such that sales growth is likely to moderate over the second half of 2026.” | ||
Dunelm (LON:DNLM) (£1.79bn | SR74) | Preliminary Results & Strategy Update: Winning Hearts & Homes | Sales up 3.1%. PBT flat at £211m. “As a result of the extended period of unusually hot weather… we saw significantly softer trading in first six weeks of FY27. Strong online conversion and increasing store footfall give confidence in our current proposition, and we have seen better trading following cooler weather.” | PROFIT WARNING (AMBER ↓) (Roland - I hold) Hot weather may (or may not) be a fair excuse for softer sales, but I think it’s clear there are some deeper weaknesses here that CEO Clo Moriarty must address over the next couple of years. The strategic update detailed today seems reasonable to me and consistent with the group’s traditional business model. However, after three profit warnings I think it’s prudent to take a cautious view, so I’m moving down to neutral despite the potential value that might be on offer over the medium term. |
Uniphar (LON:UPR) (£930m | SR60) | Revenue up 7.4%. Operating profit up 8.8% (both at constant currency).Well positioned to deliver on Adjusted EPS expectations for the full year. | ||
Funding Circle Holdings (LON:FCH) (£682m | SR48) | CEO intends to step down by no later than September 2027. Upgrading full year 2026 guidance to more than £255m (previously c.£235m) in revenue and more than £40m (previously at least £35m) in PBT. | ||
Johnson Service (LON:JSG) (£519m | SR77) | SP -8% Revenue +0.2%. Adjusted operating profit +3.8% (£29.8m). “The seasonal uplift in HORECA over the summer months was more modest than originally anticipated and we expect that softer trading will persist throughout the remainder of the year….” Expects to achieve its targeted adjusted operating margin of at least 14.0% in 2026. | PROFIT WARNING (AMBER/RED ↓) (Graham) [no section below] I don't really like this outlook statement: it justifiably focuses on the company hitting its operating margin target, but it doesn't help much in terms of understanding how much of a revenue hit has been suffered in the summer months. Last time I looked at JSG, I described it as "solid if unexceptional", but unfortunately it's looking a little less solid today. I'm also disappointed to see that it launched a £55m share buyback programme in May, so it has been buying its shares at higher levels. Today's results show net debt of £136m, excluding leases, up from £112m at Dec 2025 - I think the company has been a little aggressive with its buyback activity. Overall, therefore, I'm downgrading our stance to AMBER/RED in light of today's profit warning and a couple of other misgivings. | |
Bloomsbury Publishing (LON:BMY) (£513m | SR86) | Nigel Newton, Bloomsbury's Founder and Chief Executive, becomes Executive Chairman today. New CEO to be appointed in two years. | ||
Fuller Smith & Turner (LON:FSTA) (£382m | SR89) | Exchanged contracts to purchase 10 pubs via a transaction with pub operator, Stonegate Group and a simultaneous separate transaction with an institutional property investment company. Price is £35.25m representing a multiple of 8.4 times acquired site EBITDA. | ||
James Fisher And Sons (LON:FSJ) (£230m | SR57) | Revenue up 2.1%. Underlying operating profit up 27.9% to £14.2m. “Assuming no worsening disruption in the Energy market, the Board's overall expectations for the full year remain unchanged.” | ||
Ferrexpo (LON:FXPO) (£175m | SR61) | Loan agreement with the Company's largest shareholder: unsecured loan facility for US$15 million. Interest charged at the rate of 9.75%, maturing 12 months after the date of the Loan. | ||
Regional REIT (LON:RGL) (£153m | SR59) | Portfolio valuation down 5% after disposals. Like-for-like portfolio valuation down 1.3%. EPRA NTA down 3% to £305.8m. “...a resilient operational performance in the first half of 2026, securing 26 new market lettings providing £1.9m of rental income, marginally ahead of the £1.8m of breaks and expiries.” | ||
Mobico (LON:MCG) (£144m | SR80) | Revenue up 5% in Q2, “reflecting continued strong momentum in Alsa and the ongoing recovery in German Rail”. Guidance for the year remains unchanged. | ||
Somero Enterprises (LON:SOM) (£124m | SR94) | H1 revenue up 22%. PBT +86% ($9.1m). Interim dividend increased 25% and share buyback doubled to $12m. FY26 guidance increased: revenue for the full year now expected c. $ 95m, with adjusted EBITDA of c. $ 19.5m and year-end net cash expected c. US$ 29m. | GREEN ↑ (Graham) | |
Trifast (LON:TRI) (£118m | SR78) | Trading in line with market expectations (FY March 2027 revenue £214m, adjusted EBIT £18.6m). | ||
Journeo (LON:JNEO) (£97m | SR63) | H1 revenue +53% to £37.6m with adj pre-tax profit +10% to £3.0m. Adj EPS +9% to 13.6p. “Sales opportunity pipeline increased to £200m (H1 2025: £80m)”. Outlook: on track to deliver full-year results in line with expectations. | ||
Pebble (LON:PEBB) (£83m | SR98) | H1 revenue +4% to £60.7m with adj operating profit -4% to £2.6m. FY26 outlook: the Board expects 2026 results to be in line with market expectations. | ||
Gaming Realms (LON:GMR) (£81m | SR52) | Revenue -3% to £15.5m due to a 71% drop in brand licensing revenue as a result of a large deal in the prior year period. Pre-tax profit -21% to £3.4m, or +47% to £2.7m excluding brand licensing. FY26 outlook: the Board remains confident that the group will deliver full year results in line with market expectations. | ||
Gear4music (HOLDINGS) (LON:G4M) (£59m | SR97) | SP -6% Trading for the year to date has been in line with the Board’s expectations, with April-Aug sales +7.3% year-on-year. (FY27 expectations are for revenue of £200m and pre-tax profit of £6.0m.) | GREEN = (Graham) [no section below] The market got very accustomed to upgrades from G4M, and it hasn't provided another one for its followers today. This is important because, as Roland pointed out in April, profits are expected to fall in the current financial year, FY March 2027. Today's update says that "sales growth moderated during July and August amid an unusually prolonged period of hot weather, and against the very strong growth achieved in the corresponding period of FY26", but that growth in the first five months of the year was still +7.3%. That's better than the full-year growth rate currently pencilled in for FY27 as a whole, and I'd expect some normal Autumn weather to kick in soon. So in summary, I don't think today's update changes anything. As such, I'm going to leave our GREEN stance unchanged. PBT of £6m, if it's achieved this year, is a very reasonable number for a decent-quality company with a sub-£60m market cap and a modest net debt figure (£5m at the full-year results). | |
Flowtech Fluidpower (LON:FLO) (£55m | SR71) | Revenue +23.8%, with LFL revenue +13.3%. Underlying operating profit +44% to £2.3m. Sales order book was more than 20% higher at the end of H1 than at the start of 2026. Outlook: the group continues to trade in line with market expectations for 2026. | ||
STV (LON:STVG) (£52m | SR61) | H1 revenue -27% to £66.1m with adjusted operating profit -12% to £5.9m. Adj EPS flat at 7.1p. Advertising revenue +5% to $8.1m, slightly ahead of guidance. Studios revenue of £15.5m, down 63% year-on-year. £25m impairment charge against Studios, reflecting weaker commissioning. Outlook: Q3 advertising revenue to be down c.5%, Studios profit subject to “positive decisions on a small number of material commissions”. Cavendish cuts FY26E adj EPS to 10.2p (prev. 13.6p). | PROFIT WARNING | |
80 Mile (LON:80M) (£42m | SR5) | All-share acquisition of 80 Mile by Greenland Energy: 0.01108 new Greenland Energy shares for each 80 Mile ordinary share. Transaction values 80 Mile at £61.48m (1.1p per share) based on Greenland’s closing price of $1.37 on 4 Sept 26. | TAKEOVER | |
Novacyt SA (LON:NCYT) (£30m | SR33) | Has launched the In Vitro Diagnostic Regulation-certified Yourgene® Insight DPYD assay, enabling the detection of 19 clinically-relevant variants in the DPYD gene, supporting the identification of patients at increased risk of severe toxicity from fluoropyrimidine-based chemotherapy. | ||
Itaconix (LON:ITX) (£28m | SR32) | H1 revenue +72% to $8.3m with pre-tax loss reduced to $(0.3)m (H1 25: $(0.4)m). Growth driven by strong reorder volumes and two new detergent customers in EMEA and NAm. Outlook: confident in recently upgraded guidance for FY26 revenue of >$14.8m and “small positive EBITDA”. | ||
Checkit (LON:CKT) (£23m | SR33) | Has engaged with potential acquirers and received “several non-binding indicative proposals”. These have all been at “substantial premiums” to the share price prior to the FSP. The Board has previously determined it would not consider proposals below 30p and is now seeking to bring the FSP to a conclusion, with a focus on determining whether any remaining party can deliver a proposal that can be recommended to shareholders. | TAKEOVER | |
Proservice Building Services Marketplace (LON:PRO) (£20m | SR32) | FY26 revenue -6.8% to £248m on a pro forma basis. Underlying operating loss of £2.5m (FY25 pro forma: +£9.3m). Transformation into a “pure-play marketplace” is now complete, with refinancing carried out after the year end. Outlook: management reiterates previous guidance for FY27 adj EBITDA of £9m to £12m. Continues to consider a potential equity fundraise. | ||
Inspiration Healthcare (LON:IHC) (£17m | SR46) | H1 revenue -8.3% to £22m, reflecting “significant one-off contract revenues of £6.5 million” in H1 last year. Underlying growth was “strong” led by the SLE product portfolio. Outlook: expect to close the financial year “slightly ahead of market expectations”. | ||
Manolete Partners (LON:MANO) (£16m | SR48) | YTD trading performance has been “positive and in-line with the Board’s expectations for FY27”. | ||
Genflow Biosciences (LON:GENF) (£14m | SR11) | The SLAB (Sarcopenia and Longevity in Aged Beagles) clinical trial met its primary endpoint of reduction in biological age measured by the GRIM methylation clock. Treated animals demonstrated a clear signal of improvement relative to control animals. | ||
Fulcrum Metals (LON:FMET) (£12m | SR8) | Shares have started trading on the US OTCQB market under the ticker FULMF. AIM listing unchanged. | ||
Xeros Technology (LON:XSG) (£12m | SR12) | H1 revenue of £0.1m with adj EBITDA loss of £1.6m (unch). Net cash outflow of £2.1m with net cash of £3.5m at the end of June. Outlook: “... pressure from lower cost competition impacting US and European OEMs are extending programme timelines beyond our control and likely to push early revenues anticipated in H2 of the current year into H1 2027”. Cavendish cuts FY26 forecasts. | PROFIT WARNING (RED=) (Graham) [no section below] Another profit warning from a blue-sky company that has disappointed previously. Revenues have slipped into FY27, but I remain to be convinced that the company is on the verge of financial success. With an operating loss of £1.7m in six months, there was a cash outflow of £2.1m, leaving the company with a cash balance of £3.5m at the end of H1. This reduced further to £2.8m at the end of August. The only thing reliably increasing is the share count. |
Graham's Section
Somero Enterprises (LON:SOM)
Up 7% at 258p (£133m) - Interim Results - Graham - GREEN ↑
Kudos to Roland for turning moderately positive on this in July, at 211p, after it upgraded expectations for FY26.
The positive momentum continues at today’s interim results:
FY26 guidance increased: revenue for the full year now expected to be approximately US$ 95m, with adjusted EBITDA of approximately US$ 19.5m and year-end net cash expected to be approximately US$ 29m, assuming the additional US$ 6m share repurchase authorization is fully executed prior to year end
Let’s check in with house broker Cavendish to get their new forecasts:
The new $95m revenue forecast is nearly 5% higher than the previous forecast.
The new $16.9m adj. EBIT forecast is 6% higher.
The new 22.3 cent EPS forecast is 7.8% higher.
This confirms that the company is headed for attractive year-on-year growth: FY25 revenue was $88.9m, with EPS of 20 cent.
Under “strategic and operational highlights”, we read the following explanation of the company’s recent success:
New customer growth: contribution increased to 28% of total direct machine revenue (H1 2025: 21%)
Strong traction from recent products launched: Hammerhead Ride-on and S-15EZ Boomed screed launched in H2 2025 and S-22EZ+ Boomed screed and Viper Walk-Behind launched in H1 2026, contributing meaningful revenue
While the “continued stabilisation of our core markets” gets a mention from the CEO, it reads to me that the new products are an important part of the story here, particularly “Hammerhead”. In other words, this is not just a case of a favourable economy providing a tailwind. In the main US region, sales to new customers have increased as a percentage of the total (28% vs. 19% in H1 last year).
Net cash has improved year-on-year to $29.6m, but it was $33.2m at December 2025, so it has fallen over the six-month period. That’s understandable given that the company spent over $9m on dividends and buybacks. A new $6m buyback was announced in July and should begin shortly.
Outlook
New data centers and other AI-related infrastructure is boosting performance
U.S. private non-residential construction has continued to stabilize, with AI-driven digital infrastructure and related utility investment supporting activity, alongside a slowing pace of decline in other end markets including warehousing, manufacturing and retail. Customers continue to report healthy activity levels and strong backlogs extending into 2027.
Somero enters the second half with positive momentum and remains well positioned to benefit from improving market conditions, supported by its market-leading product portfolio, strong customer relationships and flexible cost model. The Board nevertheless remains mindful of continued macroeconomic and geopolitical uncertainty, including tariffs, elevated interest rates and immigration policy.
Graham’s view
This company used to generate very strong ROE, and current performance demonstrates a recovery in the direction of its historic form.
Let’s do a quick calculation: average equity in H1 was £81.1m, and the company generated a clean after-tax net income of £6.7m. If I annualise that across H2, I get a strong ROE in the region of 16-17%. So it looks like these metrics are going to rise nicely this year:
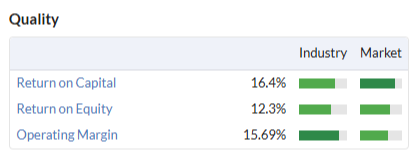
It seems to me that the company has got its mojo back: I’m sure this is partly to do with the AI boom and the moderately strong US economy, but credit should also go to the new CEO, who has overseen a rejuvenation of the product set.
Let’s go fully GREEN on this Super Stock after strong consecutive upgrades to forecasts. The boom times are back?
Roland's Section
Computacenter (LON:CCC)
Down 3.8% at 5,385p (£6.2bn) - Half Year Results - Roland - AMBER ↓
(Disclosure: at the time of writing, Roland has a long position in CCC.)
In July, Mark commented that “the scale of the increase in H1 PBT” suggested there could be more to come. Today we get another upgrade to full-year guidance for this value-added IT reseller, which specialises in supporting larger customers and is benefiting from the data centre boom.
Following a strong start to the second half and a further increase in our committed product order backlog, we now expect adjusted PBT for full-year 2026 to be significantly ahead of current market expectations and to be no less than £380m.
The growth in these half-year figures is exceptional, especially for a FTSE 100 company:
Revenue up 71.6% to £6,845.2m
Gross profit up 30.5% to £657.9m
Pre-tax profit up 94.8% to £142.6m
Adjusted earnings up 94.1% to 101.9p per share
Adjusted net funds up 11% to £308.7m vs H1 25 (FY25: £606m)
Product order backlog at 30 June of £9.2bn (+323% vs June 25, +29.5% vs Dec 25)
There’s no secret about where this growth is coming from. While Computacenter’s higher-margin Services business saw revenue rise by 15.6% to £935m, the engine driving the business at the moment is Technology Sourcing, where revenue rose by 86% to £5.9bn as the company fits out new AI data centres with volumes of high-value equipment:
Technology Sourcing revenue increased by 88.8% in constant currency, principally driven by North America, where networking and data center volumes grew with hyperscale, neocloud and enterprise customers. The UK also delivered strong growth, particularly with neocloud customers. Our targeted growth with high-volume customers is driving significant gross profit momentum while reducing our gross margin percentage.
(neocloud: specialist data centre operators that rent out compute capacity to AI clients.)
Computacenter’s ability to meet this surge of demand hasn’t arisen by chance. The company has a longstanding policy of focusing on large enterprise and public sector customers and has invested in the infrastructure and skills needed to meet such demand over many years.
This is continuing, with a new integration centre under construction in Atlanta and the addition of a liquid cooling facility to its Hatfield site.
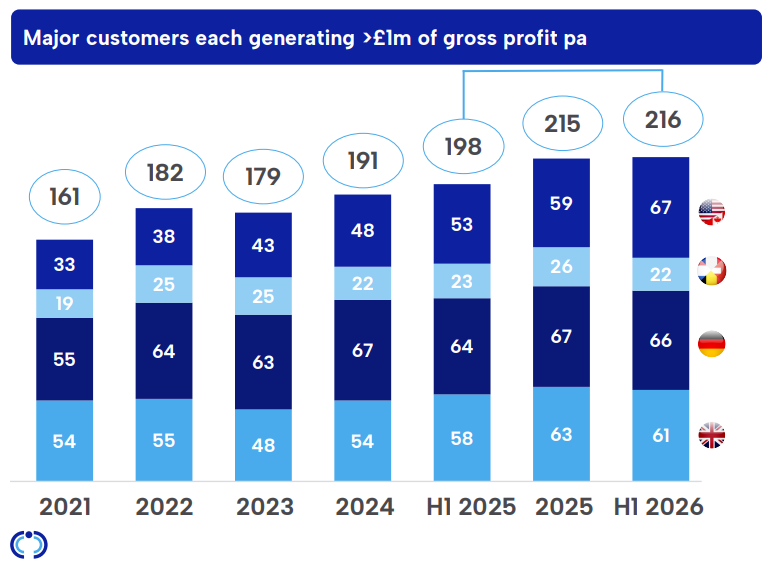
One key performance metric is “major customers” – those who have generated at least £1m of gross profit over the last 12 months. Encouragingly, this figure is still rising. The group ended the half year with 216 major customers. That’s a net increase of 18 over the last 12 months, although only one of these appears to have been added during H1:
Source: Computacenter H1 2026 presentation
North America & Acquisitions: the half-year growth in major customers includes eight major customers added through the acquisitions of AgreeYa and GAI in North America. These businesses were acquired for a total of c.$210m earlier this year. AgreeYa is a US professional services business, while GAI is a value-added reseller focused on the US federal government market – “a new growth opportunity”.
Both of these deals look well judged to me. They should support the group’s need to develop a sustainable service-led business in the US and find new opportunities for when AI-led growth eases.
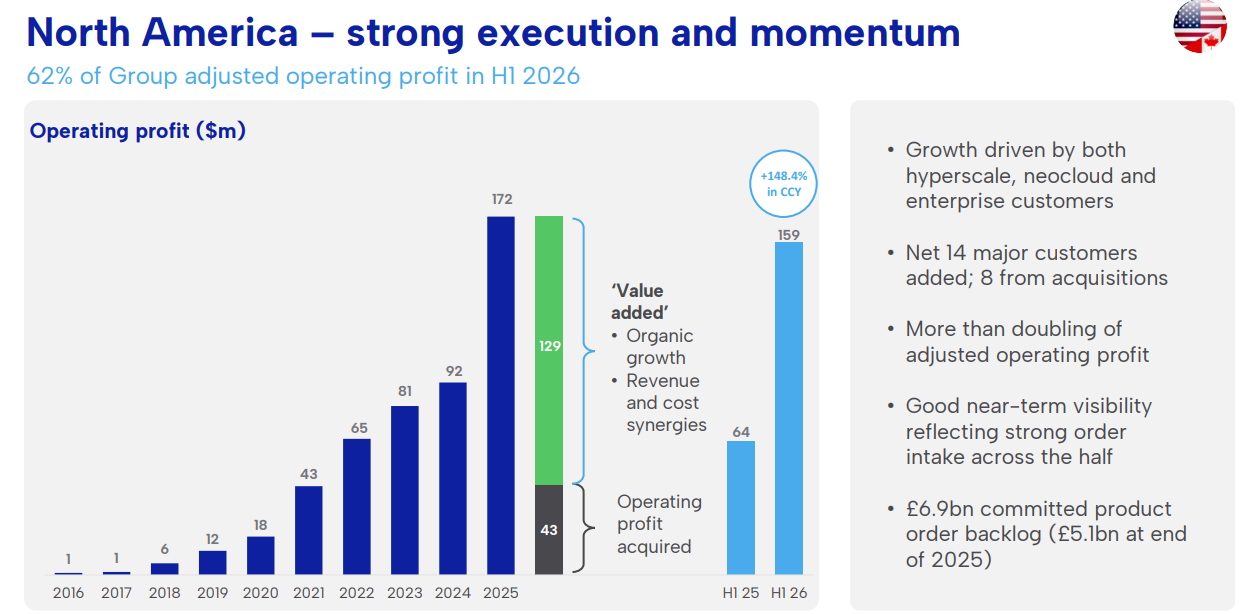
Computacenter has operated in North America since 2005, but only began expanding more aggressively through acquisitions in 2018. This timing has proved very well-judged so far. North America now generates the majority of group profit:
Source: Computacenter H1 2026 presentation
UK & Europe: it wasn’t so long ago that Germany was Computacenter’s largest market by profit contribution. However, the group’s business in the EU’s largest economy is more dependent on services revenue and public sector spending, both of which have flagged somewhat.
H1 growth in Germany was not sufficient to offset higher operating expenses, resulting in a fall in profit.
Fortunately, performance in the UK was much stronger, with a 91% increase in Technology Sourcing revenue and a 7% increase in services revenue.
The laggard of the group remains the Western Europe division, where Computacenter reported another half-year loss:
Germany: operating profit down 10.6% to £43.0m;
UK: operating profit up 52.6% to £26.4m;
Western Europe: operating loss reduced to £(4.9)m (H1 25: £(8.9)m).
I’ve included these figures to highlight how much the group’s valuation has come to depend on AI-led momentum in North America.
Outlook & updated profit guidance
As I commented in the Week Ahead, ultimately the AI boom will slow down when lenders and investors become unwilling to fund further spending. While I don’t know when this will happen, I am fairly confident that it will happen at some point.
Fortunately for shareholders, today’s upgraded guidance suggests this isn’t going to happen in 2026:
2026 adjusted pre-tax profit is now expected to be “no less than £380m”
Previous consensus is given as £340.9m (£332m to £354m range)
Today’s upgrade represents an 11.4% increase from previous consensus.
I don’t have access to broker forecasts for an updated EPS estimate, but based on the tax rate guidance included in today’s results I estimate Computacenter’s adjusted net profit for the year could be around £268m, or perhaps c.250p per share.
That’s a 13% increase from the prior consensus shown on the StockReport of 221.3p per share.
All of this makes it interesting that Computacenter’s share price has actually fallen this morning:
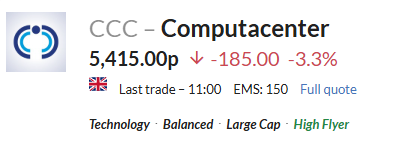
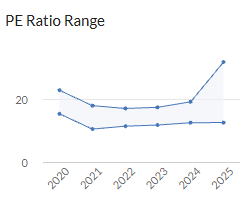
One reason for this may be valuation. As we’ve flagged previously, this stock has re-rated hugely over the last year and now trades on a P/E rating that’s significantly above historic norms:
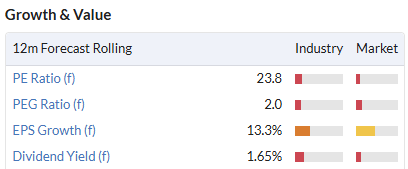
The StockReport valuation graphics are flagging up the company’s steep rating versus the wider market, too. I don’t think these metrics will change all that much after today’s upgrade:
Roland’s view
Computacenter is now one of my largest personal holdings, so I should preface this section by highlighting my obvious bias as a shareholder.
CEO Mike Norris has been in charge since 1994 and has a close relationship with founders Sir Peter Ogden and Philip Hulme. Collectively the founders still control more than half the stock through personal shareholdings and trusts.
As a shareholder, this rare situation (for a FTSE 100 company) gives me an unusually high level of confidence and trust in management.
I also take some comfort from the group’s long track record and excellent quality metrics:
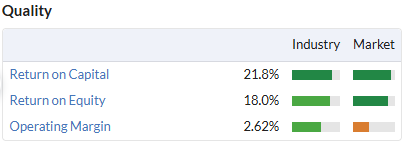
Despite these positive factors, there’s no doubt in my mind that the valuation is becoming quite demanding.
I think the slowdown in the growth of the order backlog could also be significant. The company’s product order backlog was £9.3bn on 30 June 2026, 323% higher than one year earlier.
However, this backlog has only risen by 29.5% so far in 2026. Although there has been further growth in the order backlog since the end of June, it looks like demand is growing at a much lower rate than seen during the second half of 2025.
This is especially true as the impact of price inflation on many IT products means volume growth is likely to be lower than the increase in the value of the order backlog.
Is the tidal wave of AI-led spending approaching a peak? Maybe not yet, but I wonder if the endgame might be coming into view in the distance.
One potential warning flag for me is Computacenter’s increased monetisation of its receivables.
Today’s results highlight both the sale of receivables to support longer customer credit periods and the increased use of invoice financing to “manage working capital demands of specific customer projects or engagements”:
Benefit of sale of receivables to cash position: £43.4m (June 25: £48.3m)
Invoice financing amount outstanding: £140.5m (June 25: £50.9m, Dec 25: £38.8m)
In fairness, the increase in invoice financing may simply represent the unprecedented scale of the Technology Sourcing projects currently underway. In any case, I’m confident Computacenter will take a disciplined approach to both pricing and customer creditworthiness, so I’m not too worried by this situation.
Even so, I can’t help wondering if the company’s greater monetisation of its receivables may also reflect the increasingly convoluted investment flows that are being used to fund new AI data centres.
Verdict: I am pretty confident Computacenter will remain a well-run and market-leading business in this sector and I’m encouraged by recent US acquisitions.
However, I am also pretty confident that at some point we will see earnings growth slow, which could trigger a de-rating of the shares.
While timing the top is impossible, I’m always wary when I see a company’s shares fall following an upgrade. This tells me either that the upgrade was already priced in, or that the market is looking beyond the current year and guessing at a weaker future. There was no mention of 2027 guidance today.
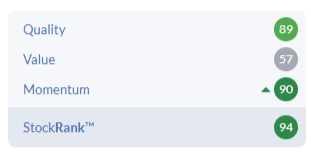
As usual, the StockRanks tell the story here, with high Quality and Momentum scores but a very low ValueRank:
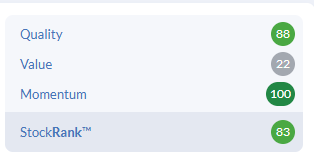
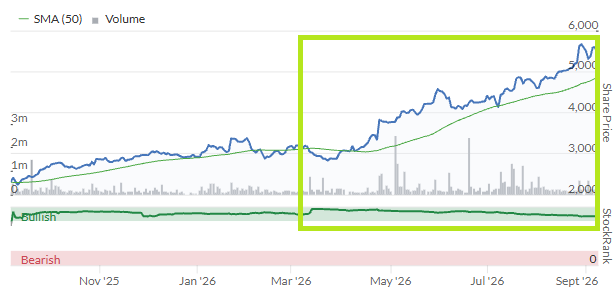
The current valuation is only being driven by momentum, in my view, so any sign that this is slowing could prompt a reversal. While the share price has risen by around 75% since the 2025 results were published in March, the StockRank has been falling steadily:
Personally, I wouldn’t feel comfortable buying more shares at the current price, as I think the downside risks are starting to mount up. To reflect this, I’m going to move our view down by one notch to neutral today.
Dunelm (LON:DNLM)
Down 12.6% at 775p (£1.59bn) - Preliminary Results & Strategy Update - Roland - AMBER ↓
(Disclosure: at the time of writing, Roland has a long position in DNLM.)
The old market adage is that profit warnings come in threes. More scientifically, our research here at Stockopedia has found that an extended period of weakness very often follows an initial warning.
Dunelm appears to be staying true to this playbook today. The homeware retailer’s full-year profits include its third profit warning since the start of 2026:
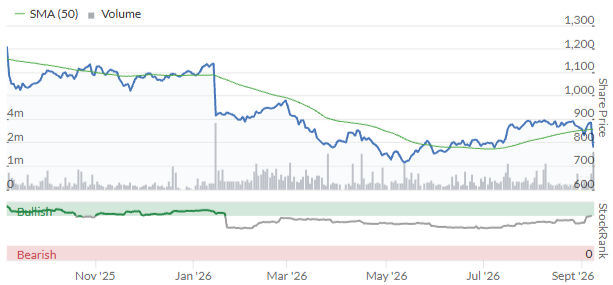
Let’s see what’s caused the damage.
FY26 results summary
Dunelm has a 52-week financial year and today’s numbers cover the period to 27 June 2026:
Revenue up 3.1% to £1,825.6m
Store-enabled LFL sales +0.8%
Digital % total sales: 42% (FY25: 40%)
Gross margin up 0.1% to 52.5%
Pre-tax profit unchanged at £211.0m
Earnings per share unchanged at 76.8p, in line with consensus
Ordinary dividend up 2.2% to 45.5p
Special dividend of 25.0p (FY25: 35.0p)
These backward-looking numbers are not terrible. The company has protected its gross margin and managed to deliver level profits in a tough consumer market. Market share is said to have risen by 0.1% to 7.9% (for combined homewares and furniture).
As usual for this business, the quality of these profits was high:
Free cash flow: £154.8m (100% of after-tax profit)
Operating margin: 12.3% (FY25: 12.5%)
Return on Capital Employed (ROCE): 46.8% (FY25: 47.7%)
Prior to this morning, the stock was trading on c.11x FY26 earnings, with an 8% dividend yield. Clearly, the reason for today’s share price fall doesn’t lie with last year’s results or with the historic valuation.
This must mean that the issue lies with the outlook for the year(s) ahead.
FY27 Outlook & Strategy Update
I know many investors have mixed views about retailers who blame the weather for poor sales, especially as the reverse is rarely true. Unfortunately, that’s what has happened here:
As a result of the extended period of unusually hot weather, however, we saw significantly softer trading in first six weeks of FY27
In fairness, I can imagine that people may have been less focused on buying products such as bedding, rugs, lighting and cushions during a period when the need for these items has been much lower than usual.
The company does say that “we have seen better trading following cooler weather”.
However, newish CEO Clo Moriarty’s in-depth comments suggest to me that she has identified other issues within the business that need addressing:
Over the last year, we have taken a deep and honest look at our business and the opportunities ahead to better serve our customers and drive the Group's performance. This work has given us confidence that the opportunity in front of Dunelm is larger than we previously understood, but also that we need to evolve. The strength of our business and balance sheet means we are well placed to invest for the future and accelerate our growth trajectory
FY27 guidance has been provided in a separate strategy update RNS today. I’ll return to the strategy comments shortly, but the financial guidance for the current year suggests to me that real profits and free cash flow are likely to fall this year:
Inflation of c.3% on FY26 operating cost base
Cost savings of £25-30m, reinvested for growth
Adjusted pre-tax profit “broadly in line with FY26”
Capital expenditure of c.£60-70m (FY26: £43m), with up to 10 new store openings and c.30 refits/renewals
Net debt to remain within target range of 0.2x - 0.6x EBITDA
I don’t have access to any broker forecasts, but my feeling from reading this is that adjusted profits will be slightly lower, while reported profits (and free cash flow) may be more materially lower. We will see.
FY27 consensus estimates prior to today were for earnings to rise by 2.5% to 78.6p in FY27, so this won’t necessarily result in a big downgrade. Even so, the negative trend seen since January is likely to be extended:
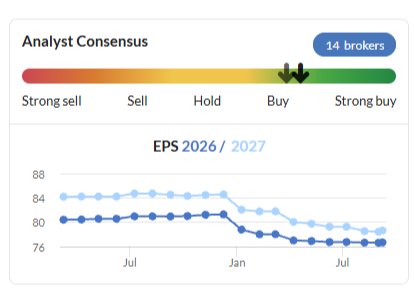
Strategy Update
Historically, this has been a market-leading business in its sector, with good profitability and generous cash-backed dividends. The group’s ownership by the founding Adderley family remains unchanged, so I would hope that the focus on dividends will also remain unchanged.
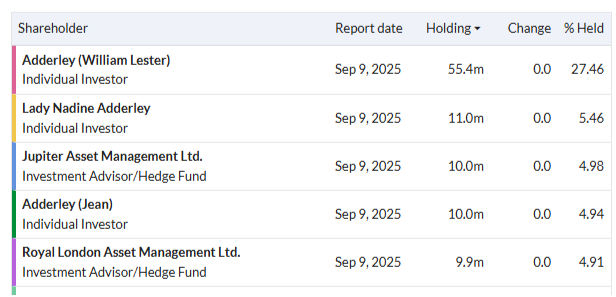
Today’s strategy update covers themes that Ms Moriarty has already flagged up previously:
Opportunity for range simplification: in selected areas, the company believes it can remove up to 40% of the store range “with limited impact on sales”, releasing space for higher-productivity categories.
Improval of store layout, promotional activity and digital presence
Leverage customer loyalty and target a greater share of wallet: 85% of the UK population doesn’t shop with Dunelm frequently and “even our most loyal customers” only spend around 20% of their home spend at Dunelm.
Improve customer satisfaction, particularly with home delivery services.
These changes seem logical enough to me and are consistent with the group’s traditional value & volume-focused business model. Moriarty has an extensive retail background at Sainsbury’s, so hopefully has the ability to deliver on these promises.
Roland’s view
Anecdotally, my nearest Dunelm always feels a little tired and cluttered inside. Some changes to presentation and stocking could definitely improve the feel of the store.
It looks like shareholders will have to endure a couple of years of increased spending before the results of Moriarty’s revised strategy become apparent. I would guess that special dividends may also be off the table during this period, at least unless consumer spending becomes stronger.
Based on today’s guidance, I estimate a forward P/E of 10-11x. On balance, I think this is potentially attractive for a business that’s historically generated very high returns on equity. In my view, the fundamental attractions of this business have not necessarily changed much.
However, it’s disappointing to see a further profit warning today. It’s probably also worth considering the risk that consumer spending will remain subdued.
Overall, I think it’s prudent to take a more cautious view of the business until some signs of positive momentum occur.
I was AMBER/GREEN on Dunelm previously, so I’m going to move down by one notch to take a neutral view today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Classy to to the end…All the best
Hopefully you have a better day tomorrow!
All the best
Goodwin (LON:GDWN)
You have been warned.
All the best
Update on AJB rebrand: Just received a call from Richard at AJB to thank me for raising the issue and to say that all comments have been fed back to product development. He admitted the new design was poor. Expect a remedy soon.
Thanks for the update. Fingers crossed then!!
Goodwin (LON:GDWN) a 20% swing in price action today for Goodwin Plc. Presumably to do with this reported by the FT. Now down by 14% on the day.
Goodwin (LON:GDWN) sale of mechanical engineering division. That reported price of £1 mn implies no premium to the market price. It is not looking to be a very good deal for shareholders. I hold.
Richard
Goodwin (LON:GDWN) I am fairly sure that £1 B would be a discount, certainly not a premium, for the division, however the report says " approximately" so could be more, OR could be less.
I understand Roland's caution on Computacenter (LON:CCC) but on balance think the succession of positive updates outweighs the risks. Mindful of Stocko's recent research on the positive impact 'earnings surprises' I decided to add to my position today. (Though with Computacenter (LON:CCC) it's not that much of a 'surprise' !)
Trends usually run for longer and faster than vestors expect and - specifically for the A.I. boom - there is a big slug of future capex baked into the system from recent funding rounds. Enormous sums were raised and these are surely unsustainable over the longer term. The trick will be to leave the party while the guests are merry and before things turn ugly.
I'll cross fingers with you then Richard, having added to my already large holding in CCC this morning after glancing at the initial results, but before reading Roland's summary later in the day and feeling the pain of the freefall in the shareprice, short though it probably will be, ever since. (:-)
Computacenter CCC is also my largest single holding now despite a recent sale - but I have held for 10 years. Worth mentioning that several analysts have been raising their target prices in the past month or so. They have possibly felt company confidence and will have helped with the final leg of this strong uptick that has taken the price from 3k in May to 5k plus. The company is in the FTSE 100 but its index weight is (I think) 0.1% which reflects the very narrow float. I just think that some traders will have taken positions and are now taking profits, nothing more. The returns continue to be outsanding (RoE, RoCE etc) and I personally do not think the share is expensive at circa x20 PE. It should be at a premium to our market here, and a big one. But I also accept that a REVERSAL in the profits trend would be damaging and none of us know when that will happen.
Computacenter (LON:CCC) I'm not so surprised at the price fall today. Very good results but high valuation. So some will exit on results day. But Roland is talking his holding down rather. Stocks usually rise beyond sensible limits and fall below sensible limits so I'm holding on for further growth here.
I have to say I agree re AJB website. I can read it but find it more difficult. It's like I have to strain to focus in a way I wouldn't expect to. The app seems unchanged though?
It appears the website redesign prioritised design over usability.
Nationwide did exactly the same recently Their new online format is so much more difficult to use.
Sadly, that seems to be the case pretty much everywhere: new shiny beats usability every time :-(
More teams/companies need UX experts to guide them properly.
TP Icap (LON:TCAP) still not trading that well despite ok results - maybe they should have been better as investment banks were quite hot but ... even though headline volatility measures are quiet in bonds and equities.... currency action and commodities are picking up. Bonds are actually moving and so the niggle in the back of my mind is trading could well be quietly picking up and a source of positive surprise. Sort of an each way bet as if markets do head south volatility will inevitably pick up.....but happy to be proved wrong if anyone has a negative view...
I have a decent sized holding in TCAP, and will be happy to add to it. I believe that the share price is being held back because there is a view in the market that TCAP is looking for further acquisitions, and some past ones have been over priced. My view is that another technology driven acquisition for a modest price would be fine - if you can find one. I support the company's wish to move away from voice trading and towards being seamless technology-based plumbing of the financial system.
I have messaged AJB re exactly this issue. The lack of contrast is a real issue. Maybe all AJB users could message them.
Yes ideed, I sent a comment along this line yesterday lets hope their product team check it out!
App looks ok. Bright blue and bright red. I’m sure they will adjust the web pages following so much feedback.
Yes the colour saturation on the app is fine. Looks exactly the same as the old branding.
I always prefer dark sites, so if no dark site offered natively, I turn on Dark Reader - sorted.
Have to say I looked at AJB this morning without Dark Reader and it is rather bright.
I note that AJ Bell (LON:AJB) have pointlessly changed their colour palette on their website "re-brand"
Dark blue, dark red and black are now used for numerals on portfolio pages.
These colours are problematic due to insufficient contrast. People with colour blindness
will struggle to differentiate the colours.
This is difficult for me to see (my eyesight isn't that bad).
The Website probably violates accessibility standards. Wonder if anyone checked?
It's like when Coca Cola changed their recipe....
As someone who works in PR, I know most reputable branding agencies have quite sophisticated systems for checking for the different types of colour blindness and accessibility. Given the scale of AJ Bell I would be surprised if they hadn't used a reputable agency and tested their concepts, but maybe worth dropping them a line to give the feedback.
One of the key elements of any persons visual acuity is contrast sensitivity (the ability to distinguish an object from its background) which is quite separate from colour blindness. I have a good standard of vision but find the contrast on the numerals problematic. Given the age profile of AJB clients visual contrast is essential.
I find it much improved , look feel and speed especially and a much cleaner crisper font. I do agree that the hue discrimination between shades of red and black may well be an issue for some.
I'm particularly pleased they got rid of those cartoonish images of "weird things to do with bells" .. some of those were borderline disturbing.
I agree on the colour changes. I also find it problematic (and am not colour blind) and the font is also more difficult to read. Lastly if you choose live prices the width of price colomns moves about, making you feel slightly unwell after a few minutes. Hopefully teething problems?
On the plus side the site speed is much better. Trade data and contract notes arrive much faster, and navigation is faster. Also price info seems to be updated faster. e.g. Gilts prices which were 1 day delayed, are now up to date at eod. So overall an improvement.
Journeo (LON:JNEO) morning all, to a novice, Excellent revenue growth here, not translated in to EPS growth?
Margin I believe, reading down the report
Weak profit growth if you examine the P&L
Its a low margin business now, GP in the Info Systems business collapsed from 48% to 38% ( although they expect margins to improve in H2)
Almost half of the total group revenue growth in H1 came from the acquisition from last year which, although having a reasonable GP of 45% , only made underlying profit of 5.9% in H1 26.
Suggests a competitive marketplace and little if any moat. Plus very high overheads in the new Infrastructure Protection business.
Interesting replies, thank you
Journeo (LON:JNEO)
must admit i have exited the building today on valuation grounds - i have been lucky enough to more than double my initial stake here so what was a bog standard holding had become one of my larger ones due to excllent progress made.
I think there is enough in the update to give everyone the takeaway they want here - so i wont argue with anyone who is buuying holding or selling
My main reasons for exiting now are.
(1) oversized position great gain it would be nice to bank and p/e seems up with events
(2) 2027 current expected profit growth is only 5%
(3) as has been commented operational gearing is pretty much non existent -at present. So any issues with large contracts coudl unduly affect bottom line.
(4) i was hoping that there may be a beat here - i think beat was more likely than downgrade.
(5) i suspect acquisition may have flattered these figures compared to last year.
it was close ref whether to fully sell up or not - plus points
(1) up to now the seem to have been reasonably cautious and delivered as promised - so perhaps i should not have expected upgrades here right now - it kinda makes sense for them to wait till closer to year end if they are being cautious and might have scope for beat - there is potential here for any cherry on the cake to be really nice if they can get "extra stuff at good margin"
(2) it kinda makes sense with so much going on that they may be investing behind the scenes now and that profits may come later - with sales ramping up and new contracts this that and the other sometimes the easy profits turn up later rather than earlier - they seem to be doing everything right ref trend in profits.
(3) rock sold balance sheet - they can easily afford acquisitions cash that could reduce pe materially overnight.
(4) they are proving they can deliver profits at materially higher level than they did a couple of years ago - one would hope that they could carry on doing that. gotta respect management who are getting profits to trend in right direction ove the medium term
Good comments rm , I would have done the same in your position , I’m going to watch the IMC and decide what to do.
I would appreciate you elaborating on your initial point 5 please, that’s beyond my pay grade !
Journeo (LON:JNEO)
I would appreciate you elaborating on your initial point 5 please, that’s beyond my pay grade !
(5) i suspect acquisition may have flattered these figures compared to last year.
Happy to provide some further info Lochinver - they only acquired the Infrastructure Protection buisnes in H2 this year - this generated £4.8 mill gross profit H1 - as this unit was acquired in H2 last year i am presuming (not 100% sure) that this segment simply wasnt present last year - note although it made £4.8 mill gross profit it would have added to overheads.
Per interims update
Infrastructure Protection, which joined the group during H2 2025, produced revenue of £10.6m. Gross margin was strong at 45%, delivering a gross profit of £4.8m.
Note when they acquired company they said
With 4 months of FY25 remaining, it is expected that the Acquisition will add £4m revenue and £0.4m PBT to current FY25 market expectations
So my rough and ready calcs would have this group potentially brining in £500k ish profit first 6 months of this year - note adjusted profit before tax was only up £200k - so if my basic calcs are right they might be down £200k ish plus on last yet line on true "lfl adjusted profits .
I dont want to be over negative hear - they confirmed they are on track to make forecasts so its not as ifn they arent on track to deliver what they promised - simply that it all looks slightly anaemic at present - that could simply be them investing now though to make good money later on - its not obvious whetehr that is the case or if they are simpoly struggling to make good margins. Managment have been reliable since i bought and have not over egged things so on track now aint terrible.
IG group (LON:IGG) for those that missed the announcement.
Notice of Underdog investor seminar
IG Group Holdings plc ("IG") today announces that it will host a virtual seminar for institutional investors and analysts on Thursday 8 October 2026, from 2.00pm to 3.15pm (BST). The seminar will focus on Underdog, the US daily fantasy sports and prediction markets business that IG agreed to acquire on 30 July 2026, subject to regulatory approvals.
The seminar provides an opportunity to hear directly from Underdog co-founder and Chief Executive Officer Jeremy Levine on the business's product offering, operations and strategy. Jeremy will be joined by IG Chief Executive Officer Breon Corcoran and IG Chief Financial Officer Clifford Abrahams, with a Q&A to follow.
Somero Enterprises (LON:SOM) coming back to life, Mobico (LON:MCG) looking towards recovery and Computacenter (LON:CCC) motoring into the distance. Will be interested in a review of all three held stocks.
Gear4music (HOLDINGS) (LON:G4M) 7.3% revenue growth represents a slowdown compared with the “double‑digit percentage revenue growth FY27 year‑to‑date against tough prior‑year comparatives” they highlighted in June. Their explanation that sales moderated due to unusually hot weather in July and August is plausible. However, another important factor is that their former competitor, PMT, went into administration June 2025. So July and August are the first full trading months where their year‑on‑year comparatives reflect a period without PMT in the market. PMT had an annual turnover of £43m so not an insignificant competitor.
7.3% revenue growth is still above broker estimates for the full year but it would have been interesting to know exactly what the growth was in July and August versus the prior months.
On a busy news day with Computacenter (LON:CCC) & Funding Circle Holdings (LON:FCH) posting strong results, Itaconix (LON:ITX) looks kind of interesting with +72% revenue growth, break even at the EBITDA level, and a potential to beat expectations for the full year perhaps given the strength of the HY results versus FY expectations.
It's not a company I've looked at before but from an initial glance it looks like the type of share that might have potential to be a multi-bagger so would welcome any views - Graham and team or readers!
Well, Tortoise, I have been a holder, bought Computacenter (LON:CCC) at 1686 pence/share and sold fairly recently at 3230 pence/share, the grass over the fence being greener. I look at it and kick myself, doh!
You made a good return, be happy :-)
I got in around 3300 and now have an average price of 3566. I'm up 50% and will keep holding until I see a significant change in market sentiment
Tortoise Inv - question, as you say Funding Circle Holdings (LON:FCH) posting strong results, yet sp down (by as much as 7.6%. Why?? Is it linked to the announcement of the CEO retiring? Thoughts anyone?
Yep, there will be those who followed FCH due to the CEO. I'm taking the view it will recover if they announce a credible replacement.
Somero Enterprises (LON:SOM) revenue grew by 22%.
Yes growth spread across all their regions which is nice to see. Their recently introduced new screed products seems to have assisted this upsurge, together with the demand from existing and new customers. Be nice to see a commensurate uptick in the share price. I live in hope!
Me too!